
- Market Size (2026)
- USD 18.5 Bn
- Forecast (2036)
- USD 31.3 Bn
- CAGR (2026 to 2036)
- 5.4%
How big is Sugar Substitute Market in 2026?
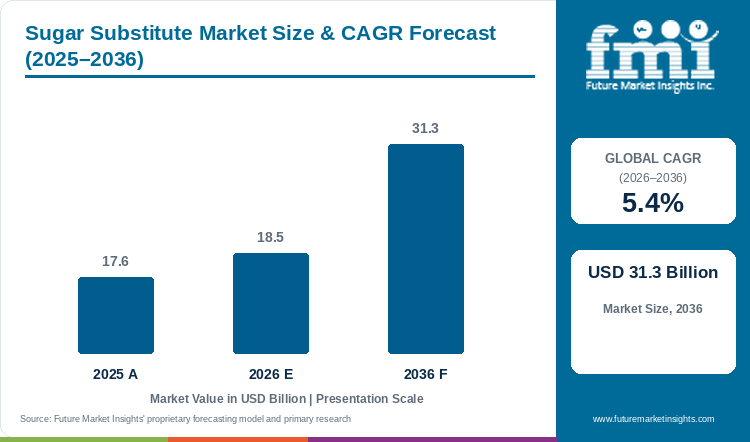
Sales in the sugar substitute market are projected to grow at 5.4% CAGR, with the market size rising from USD 17.6 Billion in 2025 to USD 18.5 Billion in 2026 and reaching USD 31.3 Billion by 2036.
According to Future Market Insights analysis, the global sugar substitute market stands at USD 17.6 Billion in 2025 and rises to USD 18.5 Billion in 2026. Industry valuation is projected to reach USD 31.3 Billion by 2036, expanding at a 5.4% CAGR and generating USD 12.8 Billion in added revenue over the forecast period. Escalating public health campaigns combating adult obesity accelerate commercial procurement across carbonated soft drinks, dairy yogurts, and table-top sweetener packets.
In January 2025, International Diabetes Federation statistical reports confirmed rising global prevalence of type-2 diabetes, reinforcing consumer demand for glycemic-neutral sweetening ingredients [1]. Standard Commercial Grade captures the leading position with 49.8% share in 2026, as high-intensity artificial and bulk polyol sweeteners deliver economical calorie reduction in processed foods. Growth across evaluated economies spans 4.3% in Australia to 6.6% in Japan. Bitter metallic lingering notes and evolving consumer skepticism toward synthetic additives continue to challenge formulator margins.
Key Market Trends & Insights
- By product type / grade: Standard Commercial Grade led with 49.8% share in 2026, as cost-effective bulk sweeteners anchor beverage bottling operations.
- By processing state: Fresh / ambient packaged held 56.2% in 2026, supported by dry crystalline stability and ambient warehouse logistics.
- By end-use application: Direct retail consumer consumption captured 40.8% in 2026, driven by zero-calorie tabletop packets and sugar-free baking blends.
- By regional distribution: North America and Western Europe account for high volume adoption, driven by regional sugar reduction regulations.
Regional Highlights
- Fastest-growing evaluated country: Japan, at 6.6% CAGR from 2026 to 2036.
- By country: The USA at 6.0%, Germany at 5.6%, France at 5.2%, and Switzerland at 4.8% follow, while Australia records the lowest evaluated CAGR at 4.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Sugar Substitute Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 17.6 Billion |
| Estimated Market Size in 2026 | USD 18.5 Billion |
| Projected Market Size by 2036 | USD 31.3 Billion |
| CAGR, 2026 to 2036 | 5.4% |
| Added Revenue, 2026 to 2036 | USD 12.8 Billion |
Sweetener Crystallization and Formulation Metrics
Table 2: Sweetener Crystallization and Formulation Metrics for the Sugar Substitute Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 17.6 | 18.5 | 31.3 |
| Global Sugar Substitute Production Volume (Thousand Metric Tons) | 1,420.0 to 1,580.0 | 1,490.0 to 1,660.0 | 2,450.0 to 2,780.0 |
| Enzymatic Stevia Bioconversion Energy Efficiency (kWh per Ton) | 45.0 to 52.0 | 43.5 to 50.2 | 34.0 to 39.5 |
| Sensory Off-Note Masking Success Rate (Percent) | 97.5 to 98.6 | 97.8 to 98.9 | 98.9 to 99.6 |
Per Capita Intake & Food Processing Sizing
Sugar-reduced foods and beverages have maintained sustained popularity in recent years due to consumer demand for lower carbohydrate intake and dental health. Balancing sweetness temporal profiles requires pairing high-intensity molecules with bulk bulking polyols. Surging dietary wellness routines convert supermarket spending into recurring sugar-free soda and dessert purchases. Beverage bottling plants represent foundational volume purchasers for bulk sugar substitutes.
Table 3: Per Capita and Food Facility Spending Indicators for the Sugar Substitute Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Population (Billion) | 8.23 | 8.30 | 8.95 |
| Annual Sugar Substitute Spend per Capita (USD) | 2.14 | 2.23 | 3.50 |
| Annual Spend per Low-Calorie Beverage Consumer (USD) | 28.00 to 38.00 | 29.50 to 40.00 | 48.00 to 64.00 |
| Wholesale Procurement Spend per Commercial Bottling Facility (USD Thousand) | 145.0 to 195.0 | 152.0 to 205.0 | 260.0 to 350.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Sugar Substitute Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 18.5 Billion | Report value |
| Licensed commercial food and beverage bottling plants worldwide | 22,000 | 2024 secondary estimate |
| Average commercial sugar substitute spend per facility | USD 840.91 Thousand | Calculated |
| Direct retail consumer consumption revenue, 2026 | USD 7.55 Billion | 40.8% share |
Analyst Perspective
"The sugar substitute sector is shifting rapidly from first-generation synthetic molecules toward next-generation plant-based sweeteners and rare sugars. Beverage formulators demand ingredients that match the temporal onset and body of sucrose without leaving lingering licorice notes. Ingredient companies that scale enzymatic bioconversion of stevia and allulose will secure dominant multi-year supply contracts across global carbonated drink bottlers and clean-label snack brands."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Sugar Substitute Market segmented?
The sugar substitute market is segmented by product type / grade, processing state, end-use application, and region. In 2026, standard commercial grade is projected at 49.8%, fresh / ambient packaged at 56.2%, and direct retail consumer consumption at 40.8%.
By product type / grade: Standard Commercial Grade, Organic & Clean-Label Variant, and Premium Specialty Formulation.
By processing state: Fresh / Ambient Packaged, Frozen & Chilled, and Dehydrated & Dry Packaged.
By end-use application: Direct Retail Consumer Consumption, Food Service & Hospitality, and Commercial Food Manufacturing Plants.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why does standard commercial grade lead the product type / grade category?
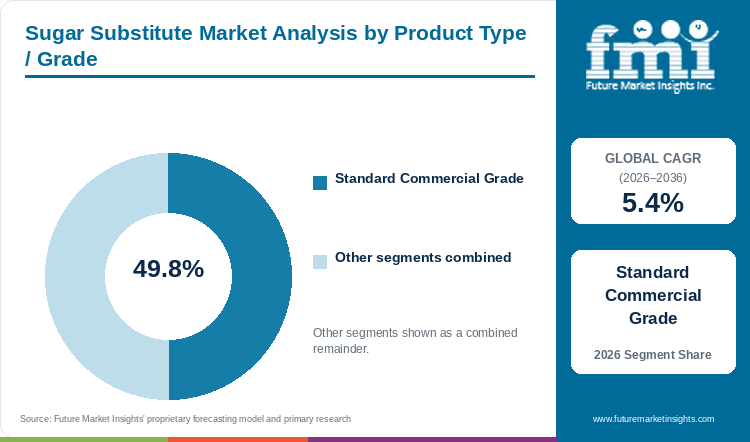
Standard commercial grade represents 49.8% of product type / grade in 2026, delivering high sweetening potency and cost efficiency in industrial food and beverage lines.
Table 5: Product Type / Grade Share for the Sugar Substitute Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Standard Commercial Grade | 49.8% |
| Other Segments Combined | 50.2%* |
| Total | 100.0% |
Table 6: Product Type / Grade Leadership and Market Growth for the Sugar Substitute Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.4% |
| Leading Segment | Standard Commercial Grade |
Beverage manufacturing plants and commercial bakeries favor standard commercial grade sweeteners because high sweetness potency enables substantial formulation cost reductions. Bulk sucralose, acesulfame potassium, and aspartame provide several hundred times the sweetness of sugar, reducing transport volume and warehouse storage requirements. Ingredient chemists blend high intensity artificial sweeteners with polyols to recreate the crystalline bulk and mouthfeel of sugar. In addition, food processors evaluate novel sweeteners derived from plant bioconversion to appeal to clean-label shoppers. Formulators also procure intensive sweeteners to achieve zero-sugar claims in functional energy beverages. Procurement managers lock in annual volume contracts with international sweetener refiners to stabilize input costs.
- Standard commercial grade represents 49.8% of product type in 2026, as high-potency molecules minimize shipping bulk for beverage bottlers.
- In March 2025, commercial food ingredient associations published updated purity and thermal stability guidelines for table-top sweetener formulations [3].
What drives fresh / ambient packaged to the forefront of the processing state segment?
Fresh / ambient packaged accounts for 56.2% of processing state in 2026, supported by high crystalline stability and ambient warehouse shelf life.
Ambient packaged sugar substitutes dominate global supply chains because crystalline powder sweeteners remain chemically inert under standard room-temperature warehouse conditions. Dry crystals and agglomerated powders resist microbial contamination without requiring refrigerated storage or preservative additions. Packaged food manufacturers package table-top sweeteners in individual paper sachets and bulk moisture-barrier drums. Formulators also utilize polyol sweeteners like erythritol to deliver clean, cooling sweetness in sugar-free confectionery. In addition, food processors explore natural malt sweeteners to enhance browning in low-sugar baked goods. Ambient shipping lowers logistics overhead across international trade routes.
- Fresh / ambient packaged accounts for 56.2% of processing state in 2026, underpinned by long dry shelf life and moisture-proof barrier packaging.
- In May 2025, U.S. Food and Drug Administration food additive regulations affirmed safety thresholds for naturally derived sweeteners across commercial food products [4].
How does direct retail consumer consumption dominate end-use applications with 40.8% share?
Direct retail consumer consumption holds 40.8% of end-use applications in 2026, driven by table-top coffee sweetening packets, home baking blends, and sugar-free pantry staples.
Household consumers drive major retail turnover because diabetics and low-carbohydrate dieters seek zero-calorie sweetening options for morning coffee and home cooking. Shoppers purchase convenient spoonable sweetener jars and individual single-serve paper packets. Supermarket chains allocate eye-level shelf space to monk fruit and stevia baking blends that measure cup-for-cup like granulated cane sugar. Food processors also evaluate low intensity sweeteners to replace sugar bulk in reduced-calorie ice creams. Category directors negotiate promotional displays to capture consumers seeking to reduce dietary sugar intake.
- Direct retail consumer consumption holds 40.8% of end-use applications in 2026, sustained by high household penetration of zero-calorie table-top packets.
- In June 2025, European Food Safety Authority dietary panels completed re-evaluations confirming the safety of approved intense sweeteners in retail tabletop applications [5].
What are the drivers, restraints, and opportunities in the Sugar Substitute Market?
Sugar tax regulations and metabolic health awareness drive sweetener demand, while taste off-notes create formulation friction and rare sugars unlock premium value.
- Driver: Worldwide implementation of beverage sugar taxes and rising consumer awareness of diabetes and obesity propel food manufacturers to reformulate products with sugar substitutes.
- Restraint: Bitter metallic lingering aftertastes and consumer skepticism toward synthetic chemical sweeteners generate formulation friction and brand switching.
- Opportunity: Precision fermentation of next-generation steviol glycosides and commercial scaling of allulose allow brands to achieve sugar-like taste profiles without calories.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Global beverage corporations actively reformulate flagship carbonated sodas to avoid municipal sugar excise taxes and attract health-conscious Gen-Z consumers. Drink makers replace high-fructose corn syrup with zero-calorie sweetener blends that deliver crisp sweetness without sugar calories. Future Market Insights research indicates that naturally derived stevia and monk fruit extracts command superior pricing over traditional synthetic sweeteners. In September 2025, consumer nutrition research confirmed that 71.6% of surveyed shoppers actively preferred beverages sweetened with plant-derived sweeteners rather than artificial chemicals [7]. Ingredient manufacturers respond by investing in enzymatic bioconversion to produce superior-tasting rebaudioside M.
Risk Assessment of the Sugar Substitute Market: Operational and Formulation Friction
Sensory aftertaste flaws and shifting international regulatory approvals present ongoing formulation hurdles for food chemists. High concentrations of steviol glycosides often exhibit delayed sweetness onset followed by a persistent bitter licorice finish. Furthermore, novel sweeteners like allulose face regulatory delays in European Union markets despite receiving GRAS approval in North America. In October 2025, agricultural logistics reports documented that raw botanical extract freight costs rose by 11.2% across international shipping corridors [8]. Ingredient formulators must invest in flavor-masking modulators to create seamless sucrose-like sweetness curves.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Ingredient suppliers discover substantial commercial margin upside by engineering next generation sweeteners and specialized bulking blends. Formulators develop allulose and tagatose solutions that caramelize and freeze like sucrose in dairy ice creams and baked goods. In addition, research laboratories synthesize peptide based sweeteners that deliver clean sweetness profiles without aftertaste. Food companies also blend natural sweeteners into functional electrolyte hydration sticks. In November 2025, grocery retail tracking data indicated that plant-derived zero-sugar baking blends recorded a 19.6% sales increase across supermarket banners [9].
Sugar Substitute Market by Country (2026 to 2036)
As per Future Market Insights, Japan represents the fastest-growing sugar substitute market among the six evaluated countries, at a 6.6% CAGR from 2026 to 2036, while Australia records the slowest expansion at 4.3% CAGR. Across all six covered economies, commercial success is dictated by how effectively sweetener refiners eliminate off-notes, navigate food additive approvals, and formulate clean-label plant blends.
Table 7: Country CAGR and Primary Growth Levers for the Sugar Substitute Market (CAGR percentage and operational drivers), 2026 to 2036
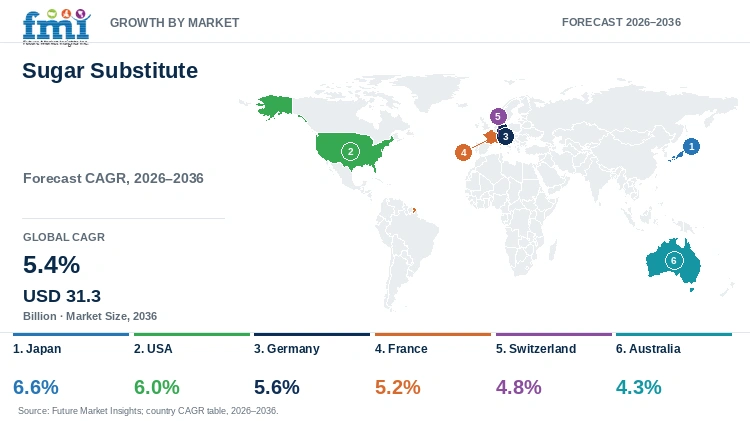
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 6.6% | Advanced functional food culture, high consumer adoption of rare sugars, and supportive Food with Function Claims regulations |
| USA | 6.0% | Massive diet beverage consumption, widespread keto and low-carb diet adoption, and rapid commercialization of allulose baking blends |
| Germany | 5.6% | Strict clean-label consumer standards, expanding natural stevia retail penetration, and commercial bakery sugar reduction initiatives |
| France | 5.2% | Beverage sugar tax compliance, expanding zero-sugar gourmet confectionery, and demand for subtle botanical sweetening solutions |
| Switzerland | 4.8% | High purchasing power for premium organic sweeteners, artisan sugar-free chocolate production, and strict food additive purity standards |
| Australia | 4.3% | Mature diet soft drink market, high consumer awareness of dental health, and steady private-label table-top sweetener sales |
Source: Future Market Insights analysis
Japan Sugar Substitute Market Outlook (2026 to 2036)
By 2036, Japan is projected to grow at 6.6% CAGR, driven by an advanced functional food culture and pioneering commercialization of rare sugars like allulose. In January 2026, the Japan Food Industry Center confirmed that functional zero-sugar beverage shipments expanded by 6.8% across nationwide convenience store networks [10]. Japanese consumers willingly purchase zero-calorie green teas and dairy drinks that carry certified health claims for blood sugar management. Domestic chemical corporations excel in enzymatic bioprocesses that produce high-purity rare sugars. However, high domestic energy tariffs and rigorous Consumer Affairs Agency documentation requirements elevate ingredient refining overhead. Japanese manufacturers overcome this by exporting high-value rare sugars to North American and European markets.
Key takeaway:In Japan, sophisticated functional beverage consumption and pioneering rare sugar technology propel the fastest growth among evaluated countries.
USA Sugar Substitute Market Outlook (2026 to 2036)
The USA sugar substitute market is anticipated to advance at 6.0% CAGR over the assessment period, owing to an enormous diet beverage consumer base and the mainstream popularity of low-carbohydrate keto lifestyles. In March 2025, the Calorie Control Council reported that over one hundred and forty million American adults consumed low-calorie and sugar-free foods regularly [11]. American consumers purchase table-top stevia and erythritol blends for home coffee sweetening and baking. Beverage companies replace corn syrup with complex sweetener systems in zero-sugar sports drinks. However, consumer skepticism regarding synthetic artificial sweeteners like aspartame creates ongoing product reformulations. Food companies resolve this by transitioning toward plant-based stevia and monk fruit extracts.
Key takeaway:In the USA, vast consumer demand for zero-calorie beverages and aggressive plant-based sweetening reformulations sustain strong category expansion.
Germany Sugar Substitute Market Outlook (2026 to 2036)
In Germany, sugar substitute demand is predicted to advance at 5.6% CAGR through 2036, underpinned by rigorous clean-label consumer expectations and commercial bakery sugar reduction targets. In April 2025, the German Association of the Food Industry confirmed that reduced-sugar packaged foods grew by 5.4% across leading grocery supermarket chains [12]. German shoppers demand transparent ingredient decks and reject artificial chemical additives. Bakery ingredient formulators combine polyols and dietary fibers to reduce sucrose content in commercial cakes and cookies without altering texture. However, European Union restrictions on allulose marketing create delays for certain novel sweetening lines. Ingredient refiners address this challenge by utilizing authorized steviol glycosides and clean-label chicory root fibers.
Key takeaway:In Germany, strict clean-label consumer standards and disciplined bakery sugar reduction initiatives maintain dependable market expansion.
France Sugar Substitute Market Outlook (2026 to 2036)
Adoption of sugar substitutes in France is estimated to expand at 5.2% CAGR through 2036, supported by national soda tax regulations and gourmet sugar-free pastry innovations. In May 2025, the French National Institute of Health and Medical Research documented ongoing sugar reduction across commercial beverage formulations [13]. Beverage bottlers adjust recipes to stay beneath national sugar tax thresholds while preserving familiar taste. Artisanal chocolatiers and pastry chefs develop gourmet sugar-free treats using maltitol and erythritol. However, deep-seated French culinary reverence for natural cane sugar and culinary skepticism toward artificial sweeteners require careful sensory balance. Formulators overcome this barrier by creating subtle sweetness blends that match traditional French flavor profiles.
Key takeaway:In France, regulatory sugar tax incentives and gourmet sugar-free confectionery innovations support steady, high-value category momentum.
Switzerland Sugar Substitute Market Outlook (2026 to 2036)
The Switzerland sugar substitute sector is projected to record 4.8% CAGR during the assessment period, reinforced by premium organic consumer preferences and artisan sugar-free chocolate manufacturing. In June 2025, the Swiss Federal Food Safety and Veterinary Office confirmed high compliance standards for commercial sweetener purity across domestic food manufacturers [14]. Swiss consumers purchase premium organic stevia drops and monk fruit powders in specialty health pharmacies. Chocolate makers utilize specialty polyols to produce luxury sugar-free chocolate bars for export. However, high domestic manufacturing labor costs and small domestic market volume limit industrial scale. Swiss companies address this barrier by focusing on premium, high-potency niche sweetener formulations.
Key takeaway:In Switzerland, high consumer purchasing power and luxury sugar-free chocolate manufacturing provide resilient category revenue.
Australia Sugar Substitute Market Outlook (2026 to 2036)
In Australia, sugar substitute demand is forecast to rise at 4.3% CAGR over the forecast period, enabled by mature diet soft drink consumption and strong public awareness of dental health. In July 2025, the Australian Food and Grocery Council confirmed steady retail sales for zero-sugar carbonated beverages and table-top sweetener canisters [15]. Australian families choose sugar substitutes to support healthy weight management and protect dental enamel. Supermarket chains offer value-priced private-label sweetener tablets and granulated powders. However, high market maturity and intense price competition between private labels and branded sweeteners constrain operating margins. Manufacturers overcome this by introducing convenient pocket-sized liquid squeeze bottles for on-the-go sweetening.
Key takeaway:In Australia, established consumer diet soda routines and dental wellness awareness provide dependable baseline market performance.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Sugar Substitute Market?
Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc. are the significant market players in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational packaged food and beverage corporations, global agricultural sweetener refiners, and specialized biotechnology ingredient developers. Packaged food and beverage corporations formulate branded zero-sugar sodas, yogurts, and cereals across global retail distribution channels. Agricultural commodity refiners operate high-capacity wet milling plants producing polyols, corn syrup alternatives, and bulk crystalline sweeteners. Specialized biotechnology companies utilize precision fermentation to produce rare sugars and high-purity steviol glycosides. Formulation directors select sweetener suppliers based on certified sweetness purity, low glycemic index validation, rapid sensory onset, and competitive volume delivery pricing.
- Global Packaged Food & Beverage Leaders: Nestle S.A., Danone S.A., and General Mills, Inc. formulate zero-sugar and reduced-calorie consumer foods across international retail banners.
- Diversified Culinary & Snacking Conglomerates: The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc. integrate sugar substitutes into baked snacks, sauces, and confectioneries.
- Specialty Food & Meal Kit Innovators: Hormel Foods Corporation, Tyson Foods, Inc., and WK Kellogg Co deploy functional sweeteners in breakfast items, prepared foods, and savory marinades.
Competitive Benchmarking: Sugar Substitute Market
Table 8: Competitive Benchmarking for the Sugar Substitute Market (qualitative capability ratings), 2026
| Company | Low-Sugar Product Portfolio Breadth | Clean-Label Sweetener Reformulation | Global Retail Grocery Reach | Sensory Flavor Modulation |
|---|---|---|---|---|
| Nestle S.A. | High | High | High | High |
| Danone S.A. | High | High | High | High |
| General Mills, Inc. | High | High | High | High |
| The Kraft Heinz Company | High | Medium | High | High |
| Mondelez International, Inc. | High | High | High | High |
| Conagra Brands, Inc. | High | Medium | High | Medium |
| Hormel Foods Corporation | Medium | Medium | Medium | Medium |
| WK Kellogg Co | High | High | High | High |
| Tyson Foods, Inc. | Medium | Low | High | Low |
Key Developments in the Sugar Substitute Market
Key Players in the Sugar Substitute Market
Global Packaged Food & Beverage Leaders
- Nestle S.A.
- Danone S.A.
- General Mills, Inc.
- Diversified Culinary & Snacking Conglomerates
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
Specialty Food & Meal Kit Innovators
- Hormel Foods Corporation
- WK Kellogg Co
- Tyson Foods, Inc.
Sugar Substitute Market - Report Scope
Table 9: Report Scope for the Sugar Substitute Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and brand revenue from high-intensity sweeteners, low-calorie polyols, natural plant extracts (stevia, monk fruit), and rare sugars sold into food, beverage, pharmaceutical, and tabletop sweetening applications. Excludes traditional sucrose and high-fructose corn syrups. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Japan, USA, Germany, France, Switzerland, Australia, and additional countries in the full report |
| Key Companies Covered | Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Sugar Substitute Market - Research Methodology
Table 10: Research Methodology for the Sugar Substitute Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with sweetener crystallization engineers, beverage formulation chemists, food regulatory directors, retail supermarket category buyers, and sensory science researchers to validate production volumes, bioconversion yields, contract pricing, and commercial brand reformulation timelines. |
| Secondary Research | Secondary research included analysis of national food additive registries, patent databases for enzymatic sweetener synthesis, corporate financial filings, food science journals, and publicly available health agency publications. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up models evaluating raw botanical extract harvests, polyol manufacturing capacities, and point-of-sale scanner sales of sugar-reduced consumer packaged goods. |
| Data Triangulation and Validation | Data is validated against macroeconomic food expenditure metrics, global trade flows of high-potency sweeteners, beverage volume sales data, and historical industry benchmarks to ensure high precision without double counting conventional nutritive sugars. |
Sugar Substitute Market by Segments
Sugar Substitute Market segmented by Product Type / Grade:
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
Sugar Substitute Market segmented by Processing State:
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
Sugar Substitute Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
Sugar Substitute Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Diabetes Federation. (2025, January 16). IDF Diabetes Atlas 11th Edition: Global Diabetes Prevalence and Nutritional Management. IDF Publications.
- [2] U.S. Department of Agriculture Economic Research Service. (2025, February 18). Sugar and Sweeteners Outlook: High-Intensity and Alternative Sweetener Utilization. USDA Publications. https://www.usda.gov
- [3] Food and Agriculture Organization & WHO. (2025, March 20). Joint FAO/WHO Expert Committee on Food Additives: Evaluation of Certain Food Additives (Sweeteners). WHO Technical Report Series. https://www.fao.org
- [4] U.S. Food and Drug Administration. (2025, May 22). Food Additive Status List: High-Intensity Sweeteners Permitted for Use in Food in the United States. FDA Center for Food Safety. https://www.fda.gov
- [5] European Food Safety Authority. (2025, June 16). Follow-up Re-evaluation of Approved Food Additives: Intense and Bulk Sweeteners. EFSA Journal. https://www.efsa.europa.eu
- [6] Calorie Control Council. (2025, August 14). Consumer Trends in Low-Calorie and Reduced-Sugar Food and Beverage Choices. CCC Research Bulletins.
- [7] Institute of Food Technologists. (2025, September 22). Sensory Dynamics and Temporal Profiles of Novel Steviol Glycosides in Beverage Systems. Journal of Food Science.
- [8] International Stevia Council. (2025, October 18). Global Supply Chain and Regulatory Harmonization for Stevia Ingredients. ISC Publications.
- [9] World Health Organization. (2025, November 12). Guideline on the Use of Non-Sugar Sweeteners: Public Health and Nutritional Evidence. WHO Guidelines.
- [10] Japan Food Industry Center. (2026, January 16). Market Report on Functional Sweeteners and Foods with Function Claims in Japan. JAFIC Data.
- [11] Calorie Control Council. (2025, March 25). National Survey on Low-Calorie Sweetener Consumption in the United States. CCC Economic Reports.
- [12] German Association of the Food Industry. (2025, April 22). Reformulation Strategy: Voluntary Commitments to Sugar Reduction in Packaged Foods. BVE Annual Data.
- [13] French National Institute of Health and Medical Research. (2025, May 28). Impact of Nutritional Taxation on Beverage Reformulation and Sugar Consumption in France. INSERM Bulletins.
- [14] Swiss Federal Food Safety and Veterinary Office. (2025, June 18). Monitoring of Food Additives and Low-Calorie Sweeteners in Swiss Grocery Retail. BLV Reports.
- [15] Australian Food and Grocery Council. (2025, July 24). State of the Industry: Health and Nutrition Reformulation in Australian Food Retail. AFGC Reports.
- [16] Nestle S.A. (2026, September 10). Zero-Added-Sugar Confectionery Portfolio Expansion Utilizing Enzymatic Stevia Innovation. Corporate Media Center.
- [17] Danone S.A. (2026, June 18). Functional Zero-Sugar Dairy Yogurt Line Launch Announcement. Danone Media Center.
- [18] General Mills, Inc. (2026, April 14). Commercial Reformulation of Whole-Grain Cereal Lines with Natural Sweetener Blends. General Mills Newsroom.
- [19] The Kraft Heinz Company. (2025, October 24). Reduced-Sugar Beverage and Condiment Formulation Optimization. Kraft Heinz News.
- [20] Mondelez International, Inc. (2026, January 14). Mindful Snacking Strategy and Sugar Reduction Innovations. Mondelez News.
- [21] Conagra Brands, Inc. (2025, July 16). Low-Calorie Dessert and Pantry Staple Portfolio Evolution. Conagra Investor Center.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the sugar substitute market in 2026 and what is forecast for 2036?
- Which public health initiatives support steady demand for sugar substitutes?
- Why does standard commercial grade lead the product type / grade category?
- Why does fresh / ambient packaged lead the processing state category globally?
- How do growth rates prominently differ across Japan, the USA, Germany, and Australia?
- Which leading food corporations formulate with specialized sugar substitutes today?
- What limits sensory temporal sweetness onset or regulatory allulose approvals in this market?
- What should beverage formulation chemists evaluate deeply before selecting sweetener suppliers?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Standard Commercial Grade
- Organic & Clean-Label Variant
- Premium Specialty Formulation
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Fresh / Ambient Packaged
- Frozen & Chilled
- Dehydrated & Dry Packaged
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Food Service & Hospitality
- Commercial Food Manufacturing Plants
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Switzerland
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestle S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- General Mills, Inc.
- The Kraft Heinz Company
- Mondelez International, Inc.
- Conagra Brands, Inc.
- Hormel Foods Corporation
- WK Kellogg Co
- Tyson Foods, Inc.
- Diversified Culinary & Snacking Conglomerates
- Nestle S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 26: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Processing State
- Figure 29: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by End-Use Application
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 36: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Processing State
- Figure 39: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 46: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Processing State
- Figure 49: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 66: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Processing State
- Figure 69: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Sugar Substitute Market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global sugar substitute market will reach USD 18.5 Billion in 2026. The market is projected to reach USD 31.3 Billion by 2036, driven by rising consumer focus on metabolic health and widespread sugar taxation policies.
What is the CAGR for the Sugar Substitute Market from 2026 to 2036?
As per FMI, the market is projected to expand at a 5.4% CAGR over the assessment period. Growth is supported by ongoing product formulation into clean-tasting steviol glycosides and rare sugars like allulose.
Which product type / grade segment leads the Sugar Substitute Market?
Future Market Insights projects that standard commercial grade will hold 49.8% share in 2026. The segment benefits from cost-effective high-potency sweetening, bulk availability, and established beverage bottling supply chains.
Which processing state segment leads the Sugar Substitute Market?
Sweetener ingredient research indicates that fresh / ambient packaged will account for 56.2% share in 2026. Demand is supported by dry crystalline shelf stability, ambient warehouse convenience, and moisture-barrier drum packaging.
Which country has a notable growth outlook during the assessment period?
FMI finds that Japan is projected to register a 6.6% CAGR from 2026 to 2036. High market growth is supported by an advanced functional food culture, pioneering commercialization of rare sugars, and supportive Food with Function Claims regulations.
Who are the key players in the market?
Key participants include Hormel Foods Corporation, WK Kellogg Co, Tyson Foods, Inc., Nestle S.A., Danone S.A., General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc. Leading market participants focus on enzymatically modified stevia, rare sugar allulose scaling, and clean-label taste modulation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
