

- Market Size (2026)
- USD 14.2 Bn
- Forecast (2036)
- USD 23.6 Bn
- CAGR (2026 to 2036)
- 5.2%
How big is Agriculture Packaging Market in 2026?
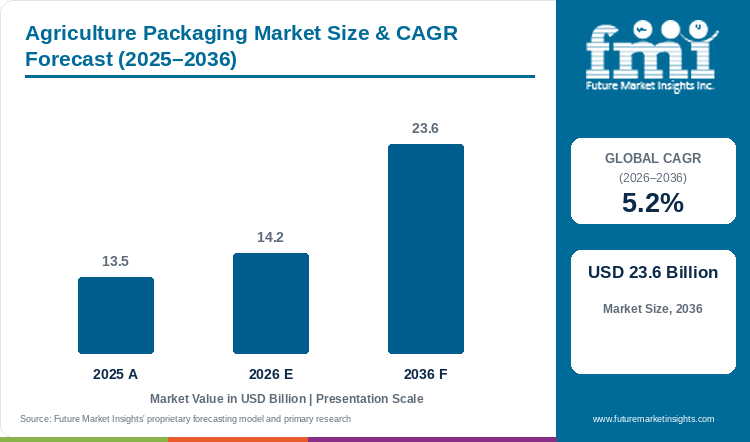
Sales of agriculture packaging are estimated to rise at 5.2% CAGR through 2036. Market valuation increases from USD 13.5 billion in 2025 to USD 14.2 billion in 2026 and is estimated to reach USD 23.6 billion by 2036.
Post-harvest spoilage across long-haul fruit corridors and solvent permeation in liquid crop-protection chemicals force farm cooperatives to replace wooden field crates with engineered containment, lifting global turnover from USD 13.5 billion in 2025 to USD 14.2 billion in 2026. Future Market Insights projects that mechanized packhouse upgrades will carry sector valuation to USD 23.6 billion by 2036 at a 5.2% CAGR as container suppliers capture USD 9.4 billion in new orders over the decade. Rigid Containers & Bottles hold 43.1% of packaging format demand in 2026 because foliar herbicides require fluorinated barrier jerrycans with closed-transfer valves. Food and Agriculture Organization analysts estimated global cereal production at a record 2,911 million tonnes in June 2025 [1], and moving that harvest volume compels grain elevators to lock in multi-season bulk bag and drum allocations ahead of planting.
Key Market Trends & Insights
- By packaging format: Liquid crop-protection chemicals and chelated micronutrients place Rigid Containers & Bottles at 43.1% of 2026 demand through widespread use of fluorinated polyethylene drums.
- By material substrate: Orchard packhouses switching from expanded polystyrene crates to moisture-resistant kraft punnets give Recycled Paperboard a 31.2% revenue share in 2026.
- By end-use sector: Continuous procurement of ventilated berry clamshells and hermetic grain sacks puts Food & Beverage at 37.6% of 2026 sector sales.
Regional Highlights
- Fastest-growing evaluated country: Protected-horticulture export demand places Mexico ahead of all profiled markets with a 6.3% annual growth rate through 2036.
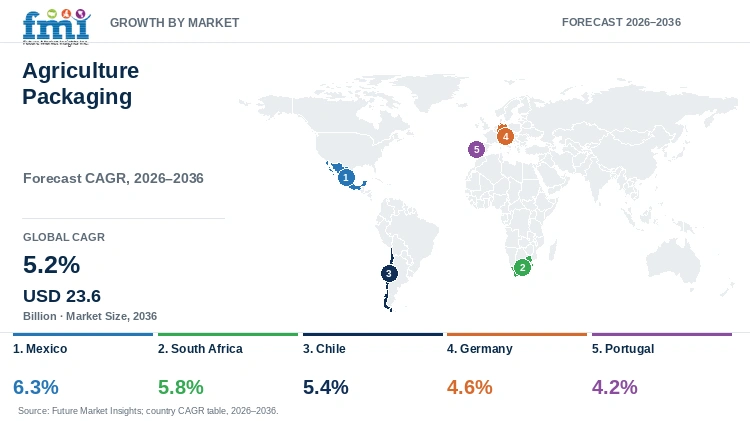
- By country: South Africa (5.8%) and Chile (5.4%) track behind Mexico while Germany (4.6%) and Portugal (4.2%) expand at a steadier pace.
Market Size & Forecast
Table 1: Market Size and Forecast for the Agriculture Packaging Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 13.5 billion |
| Estimated Market Size in 2026 | USD 14.2 billion |
| Projected Market Size by 2036 | USD 23.6 billion |
| CAGR, 2026 to 2036 | 5.2% |
| Added Revenue, 2026 to 2036 | USD 9.4 billion |
Counter-seasonal fruit export basins in Latin America and southern Africa expand faster than mature European farming districts because transoceanic reefer voyages require humidity-resistant cartons and modified-atmosphere liners. Packhouse engineers in these export hubs specify corrugated and folding carton designs bonded with wet-strength resin adhesives that prevent box buckling at 90% relative humidity. European growers simultaneously face binding plastic-reduction rules after Regulation (EU) 2025/40 took effect in August 2026 to restrict single-use plastic wraps on fresh produce loads under 1.5 kilograms [2]. That regulatory divergence steers European cooperatives into fiber punnets while Southern Hemisphere exporters purchase breathable polyethylene liner bags.
Crop Output and Packaging Requirement Sizing
Table 2: Crop Tonnage and Packaging Volume Indicators for the Agriculture Packaging Market (USD billion and million tonnes), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 (Base Year) | 2026 (Estimated) | 2036 (Modeled Forecast) |
|---|---|---|---|
| Market size (USD billion) | 13.5 | 14.2 | 23.6 |
| Global cereal & horticultural packed output (million tonnes) | 3,420 to 3,550 | 3,490 to 3,620 | 4,150 to 4,380 |
| Commercial rigid & bulk units deployed (billion units) | 18.4 to 19.8 | 19.3 to 20.8 | 31.2 to 33.8 |
| Average packaging spend per packed tonne (USD) | 3.80 to 3.95 | 3.92 to 4.07 | 5.39 to 5.69 |
Operational note: Base-year 2025 packed output synthesizes FAOSTAT cereal (2,911 million tonnes) and commercial horticultural trade volumes moving through mechanical grading and chemical-input channels; 2026 and 2036 figures represent FMI modeled scenario ranges across 20-liter agrochemical jerrycans and 1,000-kilogram woven bulk bags alongside 15-kilogram ventilated produce cartons.
Per Capita & Packhouse Facility Sizing
Engineered farm containment has gained steady traction among commercial growers because bruising and moisture loss during field-to-retail transit directly erode farm-gate margins. Balancing airflow slots with vertical stacking strength requires calibrated flute geometry in fresh produce containers. Year-round procurement from cold-storage hubs and seed-treatment plants turns seasonal harvest spikes into predictable annual supply schedules. Commercial packhouses and agrochemical blenders represent the primary volume buyers for certified agricultural containers.
Table 3: Per Capita and Arable Hectare Spending Indicators for the Agriculture Packaging Market (USD and billion), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 (Base Year) | 2026 (Estimated) | 2036 (Modeled Forecast) |
|---|---|---|---|
| World population, UN medium variant (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 1.64 | 1.71 | 2.64 |
| Spend per 1,000 people (USD) | 1,640.34 | 1,710.84 | 2,636.87 |
| Spend per 1,000 FAO arable hectares (USD) | 9,640 to 9,920 | 10,140 to 10,430 | 16,750 to 17,220 |
Table 4: Packhouse & Agrochemical Facility Spending Indicators for the Agriculture Packaging Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 14.2 billion | FMI 2026 baseline estimate |
| Commercial packhouses & input blenders worldwide | 285,000 facilities | 2025 industry census synthesis |
| Average annual packaging spend per facility | USD 49,825 | Modeled facility ratio |
| Food & Beverage end-use revenue, 2026 | USD 5.3 billion | 37.6% segment share |
Analyst Perspective
"Co-extruded barrier jerrycans and moisture-resistant corrugated trays give agrochemical and produce packers lower spoilage across humid export routes. Recycled resin decontamination costs still force extended drop-test qualification before blenders approve post-consumer drums."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the agriculture packaging market segmented?
The agriculture packaging market is segmented by packaging format, material substrate, and end-use sector. In 2026, Rigid Containers & Bottles are projected at 43.1%, Recycled Paperboard at 31.2%, and Food & Beverage at 37.6%.
By packaging format: Rigid Containers & Bottles, Flexible Wraps & Bags, and Secondary Bulk Packaging.
By material substrate: Recycled Paperboard, Thermoplastic Polymers, Sustainable Plant Fibers, and Specialty Alloys.
By end-use sector: Food & Beverage, Pharmaceuticals & Healthcare, Personal Care & Homecare, and Industrial Manufacturing.
Why Do Rigid Containers & Bottles Lead the Agriculture Packaging Market by Packaging Format?
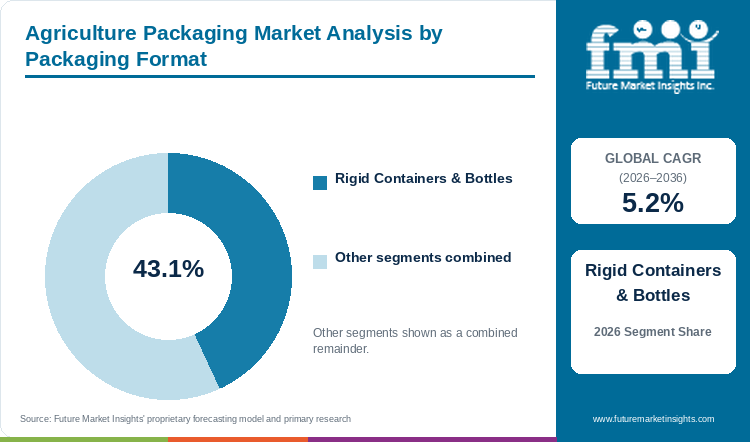
Rigid Containers & Bottles are expected to account for 43.1% of packaging format revenue in 2026, supported by chemical containment standards.
Table 5: Packaging Format Share for the Agriculture Packaging Market (percentage share), 2026
| Packaging Format | Share (2026) |
|---|---|
| Rigid Containers & Bottles | 43.1% |
| Other Segments Combined | 56.9%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Packaging Format Leadership and Market Growth for the Agriculture Packaging Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.2% |
| Leading Segment | Rigid Containers & Bottles |
Blow-molded high-density polyethylene jerrycans and intermediate bulk totes anchor the packaging format category because solvent-based crop protection chemicals require UN hazardous-goods drop resistance. Flexible Wraps & Bags and Secondary Bulk Packaging serve silage bales and dry fertilizer granules, yet flexible pouches cannot match the closed-transfer valve threading of rigid industrial drums when farm operators connect jugs directly to sprayer induction hoppers. Multi-layer co-extrusion with polyamide barrier cores also prevents hydrocarbon solvent paneling during summer warehouse storage. Agrochemical formulators fit induction-sealed foil liners onto container necks to stop counterfeit dilution across rural dealerships.
- Closed-transfer agrochemical dosing and UN drop-test rules keep Rigid Containers & Bottles at 43.1% of packaging format demand in 2026.
- Amcor plc finalized its USD 8.4 billion combination with Berry Global in April 2025 to unite blow-molded agricultural chemical drums with stretch silage film extrusion [3].
What Makes Recycled Paperboard Central to the Material Substrate Category?
Recycled Paperboard is estimated to represent 31.2% of the material substrate category in 2026, reflecting ventilated field-to-retail produce carton demand.
Recycled Paperboard captures the largest revenue share across material substrates because horticultural packhouses use double-wall corrugated trays to move fresh tomatoes and orchard fruit straight onto supermarket displays. Thermoplastic Polymers and Sustainable Plant Fibers alongside Specialty Alloys serve silage films and fumigant flasks, whereas ventilated corrugated boxes enter municipal old-corrugated-container recovery streams after a single export trip. Converters blend long virgin kraft fibers into recycled testliner furnishes and apply hydrophobic starch sizing so trays retain vertical compression strength inside hydro-cooling tunnels.
- Supermarket replacement of expanded polystyrene produce crates with recyclable fiber trays gives Recycled Paperboard 31.2% of material substrate revenue in 2026.
- Mondi plc introduced its expanded Grow&Go ventilated fresh-produce tray and bulk octabin range in November 2025 following the Schumacher Packaging integration [4].
How Does Food & Beverage Anchor the End-Use Sector Category?
Food & Beverage is projected to capture 37.6% of end-use sector demand in 2026, driven by packhouse fruit and grain handling.
Edible horticultural crops and milled grains place the Food & Beverage sector at the front of end-use demand ahead of veterinary Pharmaceuticals & Healthcare inputs and Industrial Manufacturing agro-fibers. Fresh berry and table-grape exporters pair corrugated master cartons with perforated food contact films that slow fruit respiration and delay fungal botrytis during ocean shipping. Bulk grain and oilseed processors also rely on food-grade woven polypropylene totes and multi-wall kraft valve sacks to shield stored harvests from rodent and aflatoxin damage.
- Year-round fruit and grain packing across domestic and export cold chains secures 37.6% of end-use sector revenue for Food & Beverage in 2026.
- Smurfit Westrock plc signed a definitive agreement in April 2026 to acquire CMPC's Chilean containerboard and corrugated operations for South American fruit export boxes [5].
What are the drivers, restraints, and opportunities in the agriculture packaging market?
High-value fruit and grain export volumes elevate demand for ventilated cartons and barrier drums, whereas food-contact decontamination rules on recycled plastics restrain margin expansion, and paper-based protective cushioning creates new revenue streams.
- Driver: Expanding counter-seasonal fruit trade and mechanized grain handling push cooperatives toward standardized corrugated trays and UN-certified chemical drums.
- Restraint: Strict decontamination rules on post-consumer agricultural plastics and volatile virgin polyolefin resin prices elevate compliance costs for converters.
- Opportunity: Replacing plastic foam dividers with recyclable paper cushioning and bag-in-box liquid biologicals opens higher-margin packhouse contracts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Supermarket chains and agricultural export boards enforce strict bruise-tolerance standards that compel farm cooperatives to upgrade from loose bulk bins to unitized retail-ready trays. Standardized footprint cartons lock onto Euro and ISO pallets without overhang, which cuts forklift damage and maximizes reefer container cube utilization. Eurostat data released in October 2025 showed that the European Union generated 79.7 million tonnes of packaging waste or 177.8 kilograms per resident with paper and cardboard representing 40.4% of all materials [6]. That established fiber collection network encourages grocery buyers to specify corrugated produce trays paired with protective transit cushioning over mixed-polymer crates when awarding annual tenders.
Risk Assessment of the Agriculture Packaging Market: Operational and Supply Friction
Collecting and decontaminating used farm plastics remains expensive because field mulch films and pesticide jerrycans accumulate up to 50% soil and chemical residue by weight. Mechanical wash lines struggle to strip absorbed organophosphate solvents from post-consumer polyolefins, which blocks closed-loop regrind from entering edible produce containers. Updated safety evaluation rules from the European Food Safety Authority in February 2026 require challenge-test proof that recycling reactors reduce chemical contaminants below food-contact migration limits [7]. Converters supplying multi-trip woven jumbo bags and produce punnets must therefore purchase costly virgin or super-clean resin grades.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Biological crop inputs and delicate greenhouse berries are generating strong demand for low-waste containment formats that eliminate rigid jug disposal and transit bruising. High-value microbial biostimulants degrade under ultraviolet light and oxygen exposure, prompting formulators to adopt metallized bag-in-box liquid liners inside heavy-duty corrugated cases that cut plastic weight by over 75% compared with blow-molded carboys. Packhouse operators gained a compact on-demand paper pad option in August 2026 when Sealed Air Corporation rolled out its ProPad Mini cushioning system [8]. Converters that bundle automated tray erectors with recyclable cushioning pads secure multi-year packhouse service agreements.
Agriculture Packaging Market by Country (2026 to 2036)
National growth rates diverge across the five evaluated countries between 2026 and 2036 according to fresh-produce export intensity and domestic containerboard mill capacity. Future Market Insights projects Mexico at a leading 6.3% CAGR on the strength of greenhouse vegetable and berry shipments to North America, whereas Portugal posts a 4.2% CAGR as olive oil and almond packers operate within a mature Iberian farming base.
Table 7: Country CAGR and Primary Growth Levers for the Agriculture Packaging Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 6.3% | Protected-agriculture berry and avocado export carton demand across USMCA cold chains |
| South Africa | 5.8% | Citrus and maize export volume growth requiring telescopic reefer boxes and woven bulk sacks |
| Chile | 5.4% | Counter-seasonal cherry and table-grape modified-atmosphere liner and corrugated tray shipments |
| Germany | 4.6% | VerpackG recyclability compliance and PAMIRA agrochemical container take-back standardization |
| Portugal | 4.2% | Intensive Alentejo olive oil and almond harvests driving bulk tinplate and bag-in-box demand |
Source: Future Market Insights analysis
Mexico Agriculture Packaging Market Outlook (2026 to 2036)
Year-round shade-house cultivation across Michoacán and Sinaloa links Mexican packaging procurement directly to United States supermarket cold-chain specifications rather than domestic grain storage cycles. Field crop monitoring published by the USDA Foreign Agricultural Service and Mexico's Agrifood and Fisheries Information Service (SIAP) in January 2026 tracked 462 hectares of early winter plantings in Campeche and Michoacán alongside shifting irrigated acreage [9]. Mexican demand for agricultural packaging is projected to climb at a 6.3% CAGR through 2036 as cross-border shipments of avocados and berries expand. However, independent corrugated converters face margin compression from dollar-denominated virgin kraft linerboard imports and regional water shortages. Domestic box plants are countering this pressure by colocating automated tray-erecting depots inside Bajío agro-parks.
Key takeaway: In Mexico, year-round protected-horticulture shipments to United States grocery chains generate recurring packhouse contracts for wet-strength corrugated flats and vented berry clamshells.
South Africa Agriculture Packaging Market Outlook (2026 to 2036)
Export-oriented orchard and dryland grain production across the Western Cape and Limpopo requires packaging engineered for three-week equatorial ocean voyages to European and Asian ports. Trade figures released by Statistics South Africa (Stats SA) and Agbiz in May 2026 showed that national agricultural exports rose 11% year-on-year in the first quarter of 2026 on the back of 1.37 million tonnes of maize shipments [10]. South African agricultural containment revenue is set to advance at a 5.8% CAGR from 2026 to 2036 as packhouses order telescopic citrus cartons and woven polypropylene grain sacks. Yet commercial uptake faces friction from crane delays at Cape Town and Durban terminals, prompting cooperatives to pre-order flat-packed carton buffers before peak harvest.
Key takeaway: In South Africa, rising seaborne citrus and maize export volumes anchor multi-season cooperative procurement of high-compression telescopic reefer boxes and woven bulk bags.
Chile Agriculture Packaging Market Outlook (2026 to 2036)
Southern Hemisphere counter-seasonal harvesting turns Chilean fruit packing into an intensive eight-week sprint where modified-atmosphere preservation decides landed retail value in Chinese and North American markets. Official trade data from Chile's Office of Agricultural Studies and Policies (ODEPA) and Frutas de Chile in September 2026 showed 2025–2026 fresh fruit exports reaching USD 9.95 billion on 569,450 tonnes of cherries worth USD 2.64 billion [11]. Packhouse spending in Chile will expand at a 5.4% CAGR over the ten-year forecast horizon thanks to 5-kilogram laminated cherry boxes and micro-perforated polyethylene liners. Nonetheless, concentrated December packing peaks strain local converting capacity, pushing multinational paperboard groups to acquire domestic Chilean box plants to secure kraft supply.
Key takeaway: In Chile, counter-seasonal cherry and table-grape export shipments sustain packhouse spending on modified-atmosphere vapor-barrier liners and laminated gift cartons.
Germany Agriculture Packaging Market Outlook (2026 to 2036)
Statutory producer-responsibility auditing and industry-wide chemical container take-back schemes govern agricultural packaging design in Germany far more tightly than volume-driven export growth. Waste recovery audits published by the German Federal Environment Agency (Umweltbundesamt) in January 2026 confirmed that dual-system household packaging collection reached roughly 5.5 million tonnes annually under national recycling rules [12]. German agricultural packaging sales are forecast to progress at a 4.6% annual clip through 2036 as blenders adopt mono-material high-density polyethylene canisters and FSC-certified solid-board produce baskets. While strict PAMIRA rinsing and thread-standardization rules lengthen qualification timelines for new chemical jugs, converters supplying water-rinsable barrier drums and recyclable paperboard punnets win multi-year supply agreements with German farm cooperatives.
Key takeaway: In Germany, VerpackG recyclability enforcement and PAMIRA agrochemical container take-back standards compel suppliers to deliver mono-material canisters and certified fiber punnets.
Portugal Agriculture Packaging Market Outlook (2026 to 2036)
High-density hedgerow olive groves and irrigated almond orchards fed by the Alqueva reservoir have shifted Portuguese agricultural packaging demand toward bulk lipid-barrier and nut-storage formats. Crop production data from Statistics Portugal (INE) and AICEP in July 2025 showed national olive oil output reaching 180,000 tonnes while almond harvests hit an all-time record of 91,000 tonnes [13]. Revenue across Portugal's agricultural packaging market is estimated to grow at a 4.2% CAGR between 2026 and 2036 on steady orders for nitrogen-flushed bag-in-box totes and woven jumbo bags. The central commercial obstacle involves fragmented smallholder horticulture in northern districts where small-lot carton freight costs remain high, encouraging regional packers to pool cooperative box purchasing.
Key takeaway: In Portugal, record Alentejo olive oil and almond harvests generate steady mill and huller orders for oxidation-barrier bag-in-box liners and bulk sacks.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the agriculture packaging market?
Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company, and Amcor plc are the notable companies in this market.
Supplier qualification in the agriculture packaging sector hinges on whether a converter controls vertically integrated kraft linerboard mills or UN-certified blow-molding lines near major harvest basins. Amcor plc and Berry Global Group supply fluorinated agrochemical jerrycans and flexible plastic wraps for silage bales, whereas Smurfit Westrock plc and Mondi plc operate containerboard mills that feed regional produce box plants. Sealed Air Corporation and Sonoco Products Company combine automated bagging equipment and rigid paper-metal cans with protective cushioning. Meanwhile, Ball Corporation and Crown Holdings alongside Silgan Holdings and Huhtamaki Oyj provide metal seed cans and molded-fiber punnets.
- Integrated Polymer & Corrugated Leaders: Berry Global Group and Smurfit Westrock plc alongside Sealed Air Corporation supply agrochemical containers and ventilated produce cartons.
- Metal Containment & Precision Closure Specialists: Ball Corporation and Crown Holdings together with Silgan Holdings manufacture hermetic tinplate seed cans and chemical-dosing closures.
- Fiber, Barrier Paper & Multi-Format Converters: Huhtamaki Oyj and Mondi plc alongside Sonoco Products Company and Amcor plc provide molded-fiber fruit trays and heavy-duty sack kraft bags.
Competitive Benchmarking: Agriculture Packaging Market
Table 8: Competitive Benchmarking for the Agriculture Packaging Market (qualitative capability ratings), 2026
| Company | Packaging Format Breadth | Agricultural Basin Reach | UN & Food-Contact Certification | Barrier & Fiber Innovation |
|---|---|---|---|---|
| Berry Global Group, Inc. | High | High | High | High |
| Smurfit Westrock plc | High | High | High | High |
| Sealed Air Corporation | High | High | High | High |
| Ball Corporation | Medium | High | High | Medium |
| Crown Holdings, Inc. | Medium | High | High | Medium |
| Silgan Holdings Inc. | High | Medium | High | Medium |
| Huhtamaki Oyj | High | High | High | High |
| Mondi plc | High | High | High | High |
Scoring basis: Format Breadth earns a High mark when a converter manufactures rigid drums alongside flexible films or corrugated trays across farm-input and harvest channels, whereas a Medium mark reflects specialization in metal cans and closures. Basin Reach measures converting plant proximity to American and European farming corridors alongside African harvest hubs. Certification tracks compliance with UN hazardous-liquid drop tests and direct produce contact standards, while Innovation evaluates commercial rollouts of heavy-duty kraft papers and wet-strength boxboard.
Key Developments in the Agriculture Packaging Market
- Sonoco Products Company completed the operational integration of its metal packaging and rigid paper container units in February 2026 following the Eviosys transaction to expand vegetable and seed can capacity across EMEA and North America [14].
- Commercial containerboard rolls began shipping from Mondi plc's EUR 200 million converted paper machine in Duino during September 2025 for Italian and Central European produce box plants [15].
- Sealed Air Corporation released its AUTOBAG 850HB hybrid bagging machine in September 2025 so packers can run both paper and poly mailers on a single high-speed filling line [16].
Key Players in the Agriculture Packaging Market
Established Market Leaders
- Berry Global Group, Inc.
- Smurfit Westrock plc
- Sealed Air Corporation
Specialized Manufacturers
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
Regional and Emerging Players
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
- Amcor plc
Agriculture Packaging Market - Report Scope
Table 9: Report Scope for the Agriculture Packaging Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Packaging Format; Material Substrate; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes converter and manufacturer revenue from primary, secondary, and bulk agricultural packaging formats across crop-protection containment, seed and fertilizer bags, silage wraps, and field-to-packhouse produce trays. Category Scope Note: Market valuation reflects commercial packaging substrates and containers sold across agricultural Food & Beverage harvest packing, veterinary Pharmaceuticals & Healthcare biologics, Personal Care & Homecare lawn/garden inputs, and Industrial Manufacturing agro-fibers, excluding non-packaging farm machinery. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, South Africa, Chile, Germany, Portugal, and additional countries in the full report |
| Key Companies Covered | Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company, Amcor plc |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Agriculture Packaging Market - Research Methodology
Table 10: Research Methodology for the Agriculture Packaging Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with resin extruders, corrugated converters, agrochemical formulators, horticultural packhouse directors, and packaging procurement leads across the agriculture packaging value chain to validate format shifts, drop-test qualification rules, and seasonal contract structures. |
| Secondary Research | Secondary research included FAO crop production bulletins, Eurostat and national packaging waste registries, USDA and national agricultural ministry trade releases, EFSA food-contact material opinions, and corporate annual filings from leading packaging converters. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined bottom-up converter revenue aggregation with top-down packed crop tonnage and agrochemical volume models across all covered regions. |
| Data Triangulation and Validation | Estimates were triangulated against national containerboard output, agricultural export carton shipments, and polymer resin allocations to eliminate double-counting between raw substrates and converted containers. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's agricultural containment econometric model, calibrating evaluated national growth rates against the 5.2% global baseline through verified horticultural export tonnage growth, national extended producer responsibility (EPR) recycling targets, and domestic containerboard and blow-molding capacity additions. |
| Operational Benchmark Traceability | Operational benchmarks (packed cereal and horticultural tonnage, commercial rigid and bulk container deployment, and packaging spend per arable hectare) represent modeled estimates synthesized from FAOSTAT crop registries, Eurostat packaging waste datasets, national agricultural ministries (SIAP, ODEPA, Stats SA, INE), and converter capacity disclosures. |
Agriculture Packaging Market by Segments
Agriculture Packaging Market segmented by Packaging Format:
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
Agriculture Packaging Market segmented by Material Substrate:
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
Agriculture Packaging Market segmented by End-Use Sector:
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
Agriculture Packaging Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- Portugal
- Eastern Europe
- Poland
- Russia
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- Australia
- New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations (FAO). (2025, June 14). FAO Cereal Supply and Demand Brief. Food and Agriculture Organization of the United Nations.
- [2] European Commission, Directorate-General for Environment. (2026, August 11). New EU rules on packaging enter into application. Official Website of the European Union.
- [3] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global. Amcor Investor Relations.
- [4] Mondi plc. (2025, November 18). Mondi launches extended corrugated and solid board portfolio for the food packaging industry. Mondi Group News and Insight.
- [5] Smurfit Westrock plc. (2026, April 15). Smurfit Westrock Announces Agreement to Acquire CMPC's Chilean Containerboard and Corrugated Business. Smurfit Westrock Newsroom.
- [6] Eurostat. (2025, October 22). Plastic packaging waste in the EU: 35.3 kg per person. Statistical Office of the European Union.
- [7] European Food Safety Authority (EFSA). (2026, February 20). Recycled plastic materials. European Food Safety Authority.
- [8] Sealed Air Corporation. (2026, August 24). Sealed Air Expands Paper Cushioning Portfolio with New ProPad Mini System. Sealed Air Media Center.
- [9] U.S. Department of Agriculture, Foreign Agricultural Service (USDA FAS), & Servicio de Informacion Agroalimentaria y Pesquera (SIAP). (2026, January 29). Grain and Feed Update (Report MX2026-0005). USDA Global Agricultural Information Network.
- [10] Statistics South Africa (Stats SA) & Agricultural Business Chamber (Agbiz). (2026, May 25). South Africa's agricultural exports jumped 11% in Q1, 2026. Statistics South Africa.
- [11] Oficina de Estudios y Politicas Agrarias (ODEPA) & Frutas de Chile. (2026, September 28). Chile's fruit exports reach $9.95 billion in 2025/26. Oficina de Estudios y Politicas Agrarias (ODEPA).
- [12] Umweltbundesamt (German Federal Environment Agency). (2026, January 27). Facts against myths: Packaging waste recycling in Germany is working. Umweltbundesamt.
- [13] Instituto Nacional de Estatistica (INE Portugal) & AICEP Portugal Global. (2025, July 28). Record year for olive oil: Agricultural Statistics 2024. Instituto Nacional de Estatistica (INE Portugal).
- [14] Sonoco Products Company. (2026, February 16). Sonoco Reports Fourth Quarter and Full Year 2025 Results. Sonoco Investor Relations.
- [15] Mondi plc. (2025, September 22). Mondi Duino marks start-up of recycled containerboard mill with international customers in Italy. Mondi Group News and Insight.
- [16] Sealed Air Corporation. (2025, September 16). Sealed Air Launches AUTOBAG Brand 850HB Hybrid Bagging Machine for Paper and Poly Mailers. Sealed Air Media Center.
- [17] Silgan Holdings Inc. (2026, February 4). Silgan Announces Fourth Quarter and Full Year 2025 Results. Silgan Investor Relations.
- [18] Ball Corporation. (2026, March 25). Ball Corporation Releases 2025 Combined Annual and Sustainability Report. Ball Corporation Investor Relations.
- [19] Crown Holdings, Inc. (2026, February 4). Crown Holdings, Inc. Reports Fourth Quarter and Full Year 2025 Results. Crown Holdings Newsroom.
- [20] Huhtamaki Oyj. (2026, July 23). Huhtamaki Oyj's Half-yearly Report January 1-June 30, 2026. Huhtamaki Stock Exchange Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the agriculture packaging market in 2026 and what is forecast for 2036?
- Which harvest and agrochemical containment pressures support demand for agriculture packaging?
- Why do Rigid Containers & Bottles lead the packaging format category?
- Why does Recycled Paperboard lead the material substrate category globally?
- How do growth rates differ across Mexico, South Africa, Chile, Germany, and Portugal?
- Which leading companies supply agricultural containers, cartons, and films today?
- What limits post-consumer polymer adoption or supplier switching in the agriculture packaging market?
- What should packhouses and chemical blenders evaluate before purchasing agriculture packaging?
Frequently Asked Questions
How big is the agriculture packaging market in 2026, and what is forecast for 2036?
The global agriculture packaging market is estimated to reach USD 14.2 billion in 2026. Industry revenue is projected to climb to USD 23.6 billion by 2036 as mechanized packhouses and crop-input suppliers expand bulk and retail-ready containment.
What CAGR is forecast for the Agriculture Packaging Market through 2036?
As per FMI, the agriculture packaging market is projected to grow at a 5.2% CAGR from 2026 to 2036. Expansion is supported by counter-seasonal fruit exports and strict UN chemical containment rules.
Which packaging format holds a notable agriculture packaging demand share in 2026?
Rigid Containers & Bottles are projected to hold 43.1% of packaging format demand in 2026. The segment benefits from fluorinated high-density polyethylene jerrycans and closed-transfer drums used in liquid crop protection.
Which material substrate segment holds a notable agriculture packaging share in 2026?
Recycled Paperboard is estimated to account for 31.2% of material substrate revenue in 2026. Demand is underpinned by supermarket replacement of plastic foam crates with ventilated corrugated produce trays.
Which country has a notable agriculture packaging expansion outlook during the forecast period?
FMI finds that Mexico is projected to expand at a 6.3% CAGR during the 2026 to 2036 assessment period. Growth is driven by protected-agriculture berry and avocado shipments across North American cold chains.
Which companies are active in the Agriculture Packaging Market during 2026?
Notable companies active in the sector include Berry Global Group, Inc., Smurfit Westrock plc, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc., Huhtamaki Oyj, Mondi plc, Sonoco Products Company, and Amcor plc. These manufacturers focus on wet-strength containerboard and fluorinated chemical drums alongside recyclable modified-atmosphere films.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Rigid Containers & Bottles
- Flexible Wraps & Bags
- Secondary Bulk Packaging
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Recycled Paperboard
- Thermoplastic Polymers
- Sustainable Plant Fibers
- Specialty Alloys
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food & Beverage
- Pharmaceuticals & Healthcare
- Personal Care & Homecare
- Industrial Manufacturing
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Spain
- Italy
- Portugal
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Russia
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia
- New Zealand
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Packaging Format
- By Material Substrate
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Berry Global Group, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Smurfit Westrock plc
- Sealed Air Corporation
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
- Huhtamaki Oyj
- Mondi plc
- Sonoco Products Company
- Amcor plc
- Berry Global Group, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


