
- Market Size (2026)
- USD 300.0 Mn
- Forecast (2036)
- USD 474.9 Mn
- CAGR (2026 to 2036)
- 4.7%
How big is BOPP Bag Market in 2026?
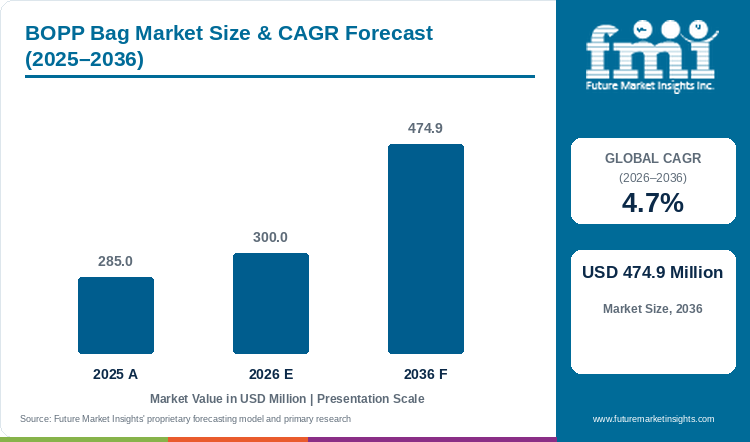
For 2026, global BOPP bag market value is estimated at USD 300.0 million compared with USD 285.0 million in 2025, and a 4.7% annual growth rate brings 2036 industry valuation to USD 474.9 million.
Dry companion-animal kibble and hybrid seed processors rely on reverse-printed biaxially oriented polypropylene (BOPP) films thermally bonded onto circular woven polypropylene fabric to stop oil staining and warehouse bag bursts. Within this category, Pet Food, Animal Feed & Seeds represent an expected 56.3% of end-use sector demand while BOPP Film Laminated Woven PP Sacks account for a projected 53.1% of bag construction in 2026 across mills purchasing polypropylene woven bags and sacks. In June 2026, the European Pet Food Industry Federation (FEDIAF) reported that 140 million European households (49%) own 306 million companion animals consuming 8.6 million tonnes of pet food each year [1]. Supported by this recurring kibble and dry-staple volume, global BOPP bag industry valuation moves from a 2025 level of USD 285.0 million to an estimated USD 300.0 million in 2026 and is forecast to reach USD 474.9 million by 2036 at a 4.7% CAGR, delivering USD 174.9 million in added annual valuation. Nevertheless, limited municipal collection networks for post-consumer woven sacks still complicate closed-loop mechanical recycling.
Key Market Trends & Insights
- By bag construction: BOPP Film Laminated Woven PP Sacks lead with a projected 53.1% share for 2026 because polypropylene homopolymer tie layers bond printed BOPP film to woven tape fabric into a single mono-polyolefin structure.
- By capacity weight: 5 kg to 25 kg Pet Food, Rice & Seed Sacks hold an estimated 54.7% share for 2026 owing to club-store consumer carry handles and automated open-mouth bagging speeds.
- By end-use sector: Pet Food, Animal Feed & Seeds command an expected 56.3% share for 2026 driven by high-fat kibble barrier requirements and photorealistic breed graphics on retail aisles.
- By film finish: High-Gloss Reverse-Printed BOPP secures a forecast 57.9% share for 2026 backed by ten-color rotogravure ink protection beneath an abrasion-resistant crystal-clear outer film.
Regional Highlights
- Southeast Asian and South American agricultural exporters: Vietnam leads all evaluated countries with an anticipated 5.9% compound annual pace to 2036 while Brazil achieves a projected 5.6% trajectory and Mexico records 5.3% due to rice and pet food bagging expansion.
- Mature companion-animal and specialty staple markets: United States valuation advances at a forecast 4.2% yearly clip until 2036 whereas Germany registers 3.9% and Japan expands at 3.7% per annum.
Market Size & Forecast
Table 1: Global BOPP Bag Valuation Progression (2025 Baseline, 2026 Estimate, and 2036 Target in USD Million)
| Metric | Value |
|---|---|
| 2025 Market Size | USD 285.0 million |
| Estimated Market Size in 2026 | USD 300.0 million |
| Projected Market Size by 2036 | USD 474.9 million |
| CAGR, 2026 to 2036 | 4.7% |
| Added Market Value, 2026 to 2036 | USD 174.9 million |
Multiwall paper sacks frequently suffer edge wicking and seam splitting when filled with high-lipid dog kibble or humid agricultural grains. In September 2026, ProAmpac LLC detailed its PRO-DURA woven polypropylene and QUADFLEX recyclable pet food bag platforms engineered to resist kibble grease and drop tears across weights up to 50 pounds [2]. Because of this durability advantage, national pet nutrition and lawn-seed brands are shifting large-format SKUs into laminated woven bags that combine woven tape tensile strength with trapped rotogravure graphics.
Circular Loom Output and Laminated Sack Throughput Sizing
Table 2: Laminated Woven Sack Shipments, BOPP Substrate Tonnage, and Converter Realization (2025 to 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 285.0 | 300.0 | 474.9 |
| Finished BOPP bags & laminated sacks shipped (billion units) | 1.42 to 1.58 | 1.49 to 1.66 | 2.25 to 2.52 |
| BOPP film & woven PP substrate consumed (thousand metric tons) | 118.0 to 132.0 | 124.0 to 139.0 | 188.0 to 212.0 |
| Average converter realization per 1,000 BOPP bags (USD) | 180.0 to 201.0 | 182.0 to 204.0 | 190.0 to 214.0 |
Operational note: Unit and tonnage ranges cross-reference 18-to-25-micron reverse-printed BOPP film lamination runs with circular PP tape weaving output across pet food and mineral sack plants.
Extrusion coaters bond 18-micron reverse-printed BOPP film onto 75-gsm woven polypropylene fabric using molten polypropylene homopolymer resin at speeds exceeding 250 meters per minute. This all-polypropylene construction allows converters producing heavy-duty bags and sacks to avoid adhesive solvent emissions while maintaining unified polymer composition.
Per Capita & High-Speed Bagging Line Sizing
Table 3: Automated Open-Mouth Bagging Line Allocation and Per-Thousand-Inhabitant Benchmarks (2025 to 2036)
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 34.8 | 36.1 | 52.8 |
| Annual BOPP bag valuation per automated bagging line (USD thousand) | 42.0 to 49.0 | 44.0 to 51.5 | 62.0 to 73.0 |
| Mono-material PP recycle-ready sack share (%) | 78.0% to 82.0% | 80.0% to 84.0% | 90.0% to 94.0% |
Table 4: Global Kibble and Grain Bagging Line Base and Primary Segment Allocations in 2026 (USD Million and Share)
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 300.0 million | 2026 global BOPP bag valuation baseline |
| Automated pet food, grain & seed bagging lines worldwide | 6,300 lines | Global dry kibble, rice & seed packaging base |
| BOPP laminated woven PP sack value, 2026 | USD 159.3 million | 53.1% bag construction segment allocation |
| Pet food, animal feed & seeds end-use value, 2026 | USD 168.9 million | 56.3% end-use sector segment allocation |
Micro-perforated laser pinholes along the side gussets let trapped air escape rapidly when 20-kilogram sacks drop onto vibrating conveyor belts, which enables robotic palletizers to build flat, brick-like stacks. Bulk grain and fertilizer mills that also utilize one-tonne industrial bulk bags for inter-plant transfers rely on 25-kilogram BOPP laminated sacks for distributor and retail dealer fulfillment.
Analyst Perspective
"Pet food and specialty rice brands treat the 15-kilogram sack as a primary billboard in warehouse clubs and farm-supply aisles. Converters that pair ten-color reverse-printed BOPP films with pinch-bottom heat seals and post-consumer recycled polypropylene tapes are capturing premium brand conversions from multiwall paper."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the BOPP bag market segmented?
The BOPP bag market is segmented by bag construction, capacity weight, end-use sector, film finish, and region. In 2026, BOPP Film Laminated Woven PP Sacks are projected at 53.1%, 5 kg to 25 kg Pet Food, Rice & Seed Sacks at 54.7%, Pet Food, Animal Feed & Seeds at 56.3%, and High-Gloss Reverse-Printed BOPP at 57.9%.
By bag construction: BOPP Film Laminated Woven PP Sacks, Clear Gusseted & Cello-Style BOPP Bags, and Block-Bottom Pinch-Seal BOPP Bags.
By capacity weight: 5 kg to 25 kg Pet Food, Rice & Seed Sacks, <5 kg Retail Bakery & Confectionery Bags, and >25 kg Industrial Agricultural Sacks.
By end-use sector: Pet Food, Animal Feed & Seeds, Rice, Flour & Dry Staples, and Fertilizers & Building Minerals.
By film finish: High-Gloss Reverse-Printed BOPP, Matte & Soft-Touch Premium BOPP, and Metallized & Pearlized BOPP.
What makes BOPP Film Laminated Woven PP Sacks the primary bag construction?
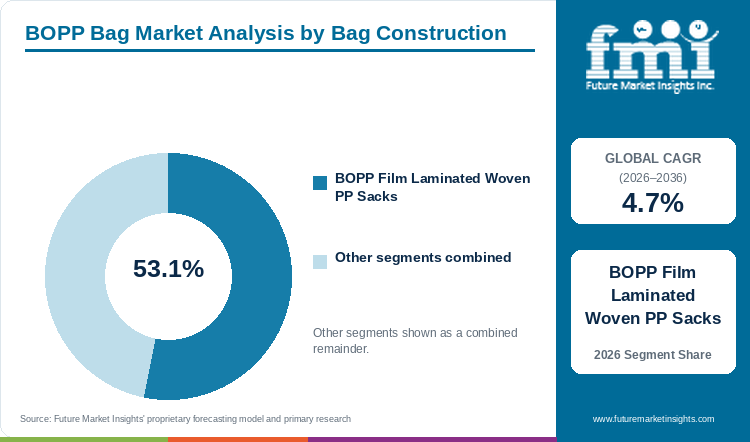
BOPP Film Laminated Woven PP Sacks account for a projected 53.1% portion within bag construction in 2026, attributed to mono-polypropylene puncture resistance.
Table 5: Laminated Woven and Gusseted Construction Breakdown Across Global BOPP Bags in 2026
| Bag Construction | Share (2026) |
|---|---|
| BOPP Film Laminated Woven PP Sacks | 53.1% |
| Other Segments Combined | 46.9%* |
| Total | 100.0% |
*Note: Combined share of remaining bag construction categories totaling 100.0% of 2026 market demand.
Table 6: Ten-Year Compound Expansion Trajectory and Primary Bag Construction Anchor (2026 to 2036)
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.7% |
| Leading Segment | BOPP Film Laminated Woven PP Sacks |
Interlaced polypropylene tapes give woven fabric exceptional tear and drop strength, while the exterior BOPP film layer seals weave gaps against warehouse humidity and insect entry. Since the woven tape fabric and the extrusion-coated tie layer as well as the outer BOPP film are all polypropylene (PP #5), the entire sack is a mono-material structure suitable for polyolefin recycling streams. Agricultural co-ops procuring farming sacks and totes favor BOPP laminated woven sacks because they survive outdoor dock handling without bursting.
- BOPP Film Laminated Woven PP Sacks secure a projected 53.1% share in bag construction for 2026 enabled by high tensile seam strength and all-polypropylene material uniformity.
- On April 30, 2025, Amcor plc completed its all-stock combination with Berry Global Group Inc. to unite global flexible film and woven or nonwoven industrial bag converting networks with USD 650 million in targeted cost and commercial efficiencies by fiscal 2028 [3].
Why do 5 kg to 25 kg Pet Food, Rice & Seed Sacks lead the capacity weight category?
5 kg to 25 kg Pet Food, Rice & Seed Sacks capture an estimated 54.7% share within capacity weight in 2026, owing to retail club-pack ergonomics.
Five-kilogram and ten-kilogram bags fitted with die-cut or injection-molded carry handles dominate supermarket basmati and jasmine rice shelves, whereas fifteen-kilogram to twenty-five-kilogram sacks represent the standard unit size for bulk dog food and certified crop seeds. Packs in this mid-weight bracket run at 20 to 35 bags per minute on automated tubular form-fill-seal and open-mouth bagging lines. Furthermore, converters supplying extrusion-coated polywoven bags equip 10-kilogram to 20-kilogram sacks with easy-open laser tear tapes and press-to-close zippers so pet owners can reseal kibble between feedings.
- 5 kg to 25 kg Pet Food, Rice & Seed Sacks hold an estimated 54.7% share of capacity weight demand for 2026 since mid-weight packs balance consumer lifting comfort with bulk unit economics.
- In 2026, Royal LC Packaging International B.V. published its 2025 Sustainability Report aligned with EU CSRD and ESRS standards detailing its global woven polypropylene (WPP) and BOPP laminated bag operations [4].
How do Pet Food, Animal Feed & Seeds anchor the end-use sector category?
Pet Food, Animal Feed & Seeds represent an expected 56.3% share across end-use sectors in 2026, fueled by lipid-barrier kibble protection.
Extruded dry dog and cat foods contain 12% to 20% animal fats and digest coatings that rapidly oxidize or stain unlined paper bags, while treated hybrid corn and soybean seeds require moisture barriers that preserve germination rates over winter warehouse storage. Laminated BOPP sacks prevent fat migration and moisture uptake without requiring intentionally added fluorochemical grease barriers. Mills buying moisture-barrier feed packaging also value anti-slip embossing on BOPP sack faces so palletized feed bags do not slide during farm truck delivery.
- Pet Food, Animal Feed & Seeds claim an expected 56.3% share of end-use sector valuation for 2026 driven by PFAS-free grease resistance and moisture-vapor protection.
- In June 2026, FEDIAF documented in its 2026 Annual Report that European companion-animal food production reached 8.6 million tonnes valued at EUR 29.4 billion across 41 Council of Europe member countries [5].
Why does High-Gloss Reverse-Printed BOPP lead the film finish category?
High-Gloss Reverse-Printed BOPP secures a forecast 57.9% share within film finish in 2026, backed by locked-in rotogravure shelf graphics.
In reverse-printed BOPP lamination, rotogravure or high-definition flexographic inks are applied to the inside surface of crystal-clear biaxially oriented polypropylene film before the film is laminated onto the woven substrate. Placement of the ink layer between the transparent BOPP film and the extrusion tie layer protects brand photography from scuffing on metal warehouse racks or forklift tines. Consumer goods companies sourcing commercial retail and industrial bags choose high-gloss finishes because mirror-like light reflection makes pet portraits and grain imagery stand out under supermarket LED lighting.
- High-Gloss Reverse-Printed BOPP commands a forecast 57.9% share in film finish for 2026 attributable to scratch-proof sandwiched ink layers and high optical clarity.
- In September 2026, Mondi plc presented its mono-material re/cycle FlexiBag and high-barrier pet food packaging portfolio for North American brands at PACK EXPO International 2026 in Chicago [6].
What are the drivers, restraints, and opportunities in the BOPP bag market?
In the BOPP bag market, PFAS-free pet food conversions and branded rice exports are projected to expand sack orders whereas polypropylene resin swings restrain converter margins and block-bottom pinch-seal sacks create premium opportunities.
- Driver: Pet nutrition and specialty grain brands are replacing fluorochemical-treated paper bags with PFAS-free BOPP laminated woven sacks that prevent oil wicking and bag breakage.
- Restraint: Polypropylene homopolymer resin price fluctuations and limited curbside collection for woven sacks pressure converter margins and circularity claims.
- Opportunity: Rollout of block-bottom pinch-seal BOPP bags with advanced-recycled PCR polypropylene and matte-gloss spot coatings captures specialty pet food accounts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
State and European Union bans on per- and polyfluoroalkyl substances (PFAS) in food-contact paper packaging are accelerating brand migration toward inherently greaseproof polyolefin bag structures. Biaxially oriented polypropylene laminated onto woven PP tape provides natural lipid and moisture resistance without fluorinated chemical additives, while matching the graphic quality of stand-up pouch packaging on 10-kilogram to 25-kilogram club-store sacks. In August 2026, Uflex Limited detailed in its FY2025-26 Annual Report the commissioning of its 80-million-bag-per-year woven polypropylene (WPP) pet food bag plant in Mexico together with its new 54,000 MTPA BOPP film line in Dharwad [7]. Expanded BOPP film casting capacity stabilizes film supply for sack laminators.
Risk Assessment of the BOPP Bag Market: Operational and Formulation Friction
Propylene monomer price volatility and the scarcity of food-contact mechanically recycled polypropylene (PCR-PP) create cost and regulatory challenges for BOPP bag converters. Because virgin polypropylene resin accounts for more than 60% of woven-sack manufacturing cost, crude oil and naphtha price spikes rapidly squeeze converter gross margins on fixed-price agricultural tenders. Furthermore, brands comparing woven BOPP sacks against smaller premade retail pouches or recyclable multiwall paper bags face retailer questions over store drop-off collection infrastructure for heavy woven sacks. In August 2025, Amcor plc filed its fourth-quarter fiscal 2025 SEC Form 8-K detailing the integration of Berry Global's flexible and industrial bag assets amid polymer resin pass-through adjustments [8].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Sack converters are winning high-margin specialty pet food and basmati rice contracts by replacing sewn open-mouth gusset sacks with stitch-free block-bottom pinch-seal BOPP bags and ultrasonic valve ports. Traditional sewn bottom seams leave needle holes that allow grain weevils or warehouse humidity to enter the sack and cause sifting dust on retail shelves. Hot-air pinch-bottom closures and flat brick-style bases allow 15-kilogram sacks to stand upright on store gondolas while displaying five-panel branding across both main panels and side gussets. In April 2026, Starlinger & Co. introduced its pp*starKON X hot-air welding conversion system for PP*STAR pinch-bottom bags made from polypropylene tape fabric laminated with reverse-printed BOPP film, eliminating glue to create a 100% mono-material recyclable pet food sack [9].
BOPP Bag Market by Country (2026 to 2036)
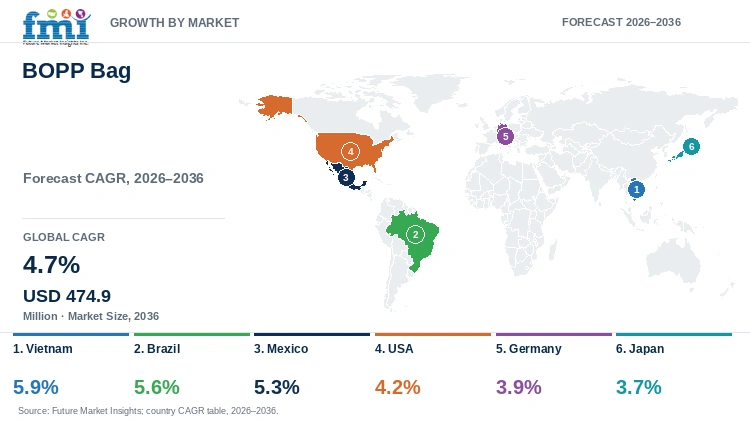
Vietnam is anticipated to lead country-level BOPP bag growth with a 5.9% yearly expansion rate across the 2026 to 2036 decade, followed by Brazil at 5.6% and Mexico at 5.3%.
Mekong Delta fragrant rice and shrimp-feed mills propel Vietnamese BOPP bag demand at a leading 5.9% yearly clip through 2036, while certified soybean seed and pet kibble packers drive Brazil at 5.6% and Mexico at 5.3% annually. Across mature companion-animal and specialty staple economies, PFAS-free club-store kibble sacks support a 4.2% annual pace in the USA, whereas German mono-PP recyclability rules (3.9%) and Japanese handled rice bags (3.7%) sustain steady upgrades.
Table 7: National BOPP Bag Expansion Rates and Agricultural or Pet-Care Demand Levers Across Six Markets (2026 to 2036)
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Vietnam | 5.9% | Mekong Delta export fragrant rice and aquaculture feed mills adopting 5kg-25kg BOPP laminated woven sacks |
| Brazil | 5.6% | Large-scale soybean seed, pet kibble, and specialty fertilizer bagging across Mato Grosso and Parana |
| Mexico | 5.3% | Expanding domestic dry dog food brands, sugar/flour milling, and duty-free BOPP sack exports to the USA |
| USA | 4.2% | PFAS-free pet kibble conversions to pinch-bottom BOPP woven bags across warehouse clubs and farm stores |
| Germany | 3.9% | Mono-material PP recycle-ready pet food and garden seed sacks aligned with German VerpackG and EU PPWR |
| Japan | 3.7% | High-clarity cello-style BOPP bakery/confectionery bags and moisture-barrier 5kg-10kg retail rice packs |
Source: Future Market Insights analysis
USA BOPP Bag Market Outlook (2026 to 2036)
High companion-animal ownership and warehouse-club merchandising of 25-pound to 50-pound kibble and lawn-care sacks anchor the United States as the largest national buyer of BOPP laminated woven bags. Following the April 2025 combination of Amcor plc with Evansville-based Berry Global Group Inc., Amcor expanded its North American AmPrima recycle-ready BOPP and polyethylene pet food and bulk seed bag laminate offerings across domestic converting plants [10]. Across the United States, BOPP bag industry size is anticipated to expand at a 4.2% yearly clip until 2036 as state PFAS restrictions accelerate conversions away from fluorochemical-treated multiwall paper sacks. Easy-open tear strips and press-to-close sliders further differentiate premium club SKUs.
Key takeaway: In the USA, state PFAS phase-outs in food-contact paper and club-store pet food merchandising are forecast to drive a 4.2% annual expansion in BOPP laminated sacks.
Germany BOPP Bag Market Outlook (2026 to 2036)
Strict extended producer responsibility fee modulation under Germany's Verpackungsgesetz (Packaging Act) and the European Union's PPWR pushes German pet food and building-mineral packers toward 100% mono-polypropylene bag designs. In March 2026, Amcor plc demonstrated its European circular polyolefin and post-consumer recycled packaging capabilities at Plastics Recycling Show Europe (PRSE) to help German and EU pet care brands satisfy PPWR recyclability criteria [11]. Within Germany, BOPP bag demand is projected to advance at a 3.9% annual pace until 2036 as dry pet nutrition and garden-fertilizer brands replace multi-material paper-film composites with recyclable BOPP-on-WPP pinch-bottom sacks. Unbleached matte BOPP finishes that mimic natural paper aesthetics also gain German retail shelf space.
Key takeaway: In Germany, eco-modulated VerpackG recycling rules and large domestic pet food output are projected to sustain steady conversion toward mono-material PP BOPP sacks.
Japan BOPP Bag Market Outlook (2026 to 2036)
Rigorous retail appearance standards for 5-kilogram and 10-kilogram milled japonica rice bags together with crystal-clear gusseted BOPP bags for bakery and confectionery gifts distinguish Japan's market structure. In March 2026, the USDA Foreign Agricultural Service Grain and Feed Annual report for Tokyo (JA2026-0011) citing Ministry of Agriculture, Forestry and Fisheries (MAFF) data documented Japan's 7.3-million-tonne milled rice supply and 24-million-tonne compound feed output [12]. Across Japan, BOPP bag market size is slated to climb at a 3.7% annual pace until 2036 as rice wholesalers and pet-care brands adopt anti-slip embossed BOPP laminated bags and laser-perforated easy-open gusset sacks. Older household demographics in urban centers also shift volume toward lighter 5-kilogram handled packs for daily convenience.
Key takeaway: In Japan, handled 5-kilogram japonica rice bags and crystal-clear bakery gusset packs sustain a 3.7% annual pace across urban supermarkets.
Brazil BOPP Bag Market Outlook (2026 to 2036)
Massive certified soybean and corn seed harvests across Mato Grosso and Parana combined with one of the world's largest companion-animal populations propel Brazil's BOPP bag market at a projected 5.6% annual clip until 2036. In April 2026, the USDA Foreign Agricultural Service Grain and Feed Annual report for Brazil documented expanding 2025/26 and 2026/27 national grain and animal feed production requiring moisture-barrier sack packaging across tropical transit lanes [13]. Brazilian seed multipliers and pet food processors specify UV-stabilized BOPP laminated woven PP sacks to prevent solar polymer degradation and tropical humidity clumping during open-truck agricultural distribution. Domestic circular weaving capacity in southern Brazil supports rapid turnaround.
Key takeaway: In Brazil, tropical moisture protection for certified crop seeds and dry pet kibble is projected to fuel a 5.6% compound annual growth trajectory through 2036.
Vietnam BOPP Bag Market Outlook (2026 to 2036)
Rapid growth in branded 5-kilogram to 25-kilogram fragrant jasmine rice exports and shrimp aquaculture feed mills together with low-cost woven-sack converting plants places Vietnam first in national growth with an anticipated 5.9% compound annual pace until 2036. In April 2026, the USDA Foreign Agricultural Service Grain and Feed Annual report for Vietnam tracked Mekong Delta paddy rice cultivation and commercial aquaculture feed production across 2025/26 and 2026/27 [14]. Vietnamese exporters increasingly package ST25 and jasmine rice in reverse-printed BOPP laminated woven sacks with carrying handles for overseas supermarket chains, while domestic circular weaving and extrusion-lamination plants in Ho Chi Minh City ship empty BOPP sacks worldwide.
Key takeaway: In Vietnam, branded retail rice exports and Mekong Delta aquaculture feed production paired with export sack converting are anticipated to sustain a top 5.9% CAGR.
Mexico BOPP Bag Market Outlook (2026 to 2036)
Strong supermarket and specialty pet-shop demand for 10-kilogram to 25-kilogram dry dog food sacks paired with flour and oilseed bagging drives Mexico's BOPP bag valuation at a forecast 5.3% annual pace up to 2036. In March 2026, the USDA Foreign Agricultural Service Grain and Feed Annual report for Mexico City (MX2026-0018) detailed Mexico's expanding 2026/27 livestock feed and wheat flour plus dry grain milling volumes [15]. Mexican pet food processors in Jalisco and Nuevo Leon are upgrading from unlaminated woven sacks to eight-color high-gloss and matte BOPP pinch-bottom bags to compete with imported US brands. Cross-border USMCA trade also enables Mexican woven-bag plants to supply southwestern United States agribusinesses.
Key takeaway: In Mexico, eight-color kibble bag upgrades in Jalisco and Nuevo Leon paired with USMCA woven-sack exports propel a 5.3% yearly clip.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the BOPP bag market?
Amcor plc, Berry Global Group, Inc. (Amcor plc), Mondi plc, ProAmpac LLC, Hood Packaging Corporation, Constantia Flexibles, LC Packaging International B.V., and Uflex Limited are the notable companies in the BOPP bag market.
FMI analysis indicates that vendor participation across the BOPP bag sector covers global BOPP film-and-woven-sack multinationals as well as high-definition pet food flexible packaging converters and agricultural woven polypropylene specialists. Global packaging groups led by Amcor plc (incorporating Berry Global Group Inc. following their April 2025 combination) and Mondi plc operate multi-continent film extrusion and rotogravure bag-converting plants. Meanwhile, ProAmpac LLC and Hood Packaging Corporation together with Constantia Flexibles specialize in pinch-bottom pet food bags and high-clarity retail BOPP packs. At the same time, LC Packaging International B.V. and Uflex Limited combine in-house BOPP film casting and circular PP tape weaving across European and Asian hubs.
- Global Flexible & Laminated Woven Bag Multinationals: Amcor plc and Berry Global Group Inc. (Amcor plc) together with Mondi plc run global BOPP film printing and mono-material pet food and industrial bag networks.
- High-Definition Pet Food & Retail Specialty Bag Converters: ProAmpac LLC and Hood Packaging Corporation along with Constantia Flexibles manufacture PRO-DURA woven PP bags and quad-seal BOPP bags for retail shelves.
- Industrial Agricultural & Woven Polypropylene Sack Producers: LC Packaging International B.V. and Uflex Limited operate circular polypropylene tape looms and high-capacity agricultural BOPP sack plants.
Competitive Benchmarking: BOPP Bag Market
Table 8: Competitive Benchmarking for the BOPP Bag Market (qualitative capability ratings), 2026
| Company | Woven PP & BOPP Lamination | Rotogravure & Flexo Graphics | Pet Food & Agro Sector Reach | Geographic Reach |
|---|---|---|---|---|
| Amcor plc | High | High | High | High |
| Berry Global Group, Inc. (Amcor plc) | High | High | High | High |
| Mondi plc | High | High | High | High |
| ProAmpac LLC | High | High | High | High |
| Hood Packaging Corporation | Medium | High | High | High |
| Constantia Flexibles | Medium | High | High | High |
| LC Packaging International B.V. | High | Medium | High | High |
| Uflex Limited | High | High | High | High |
Evaluation basis: Capability ratings reflect captive circular PP tape weaving and extrusion BOPP lamination together with 10-color rotogravure or HD-flexo reverse printing and pinch-bottom bag conversion. Sector reach and geographic ratings evaluate documented supply contracts with global pet nutrition and agricultural seed or fertilizer producers.
Key Developments in the BOPP Bag Market
- Uflex Limited announced a USD 50 million capital investment in August 2025 to establish an 80-million-bag-per-year woven polypropylene (WPP) laminated pet food bag plant in Mexico serving North and South American pet care brands [16].
- Royal LC Packaging International B.V. expanded its custom eight-color BOPP-laminated woven polypropylene (WPP) open-mouth and block-bottom sack portfolio in 2026 for European animal feed and seed plus food ingredient packers [17].
- Constantia Flexibles presented its decarbonized and mono-polypropylene recyclable packaging laminates for food and pet nutrition converters at CFIA Rennes in February 2026 [18].
Key Players in the BOPP Bag Market
Global Flexible & Laminated Woven Bag Multinationals
- Amcor plc
- Berry Global Group, Inc. (Amcor plc)
- Mondi plc
High-Definition Pet Food & Retail Specialty Bag Converters
- ProAmpac LLC
- Hood Packaging Corporation
- Constantia Flexibles
Industrial Agricultural & Woven Polypropylene Sack Producers
- LC Packaging International B.V.
- Uflex Limited
BOPP Bag Market - Report Scope
Table 9: BOPP Bag Coverage Architecture, Unit Basis, and Category Scope Boundaries (2026 to 2036)
| Coverage field | Report scope |
|---|---|
| Market breakdown | Bag Construction; Capacity Weight; End-Use Sector; Film Finish; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial converter market value from finished biaxially oriented polypropylene (BOPP) bags and sacks, including BOPP film laminated woven polypropylene (WPP) sacks, clear gusseted and cello-style BOPP retail bags, and block-bottom pinch-seal BOPP bags across <5 kg to >25 kg capacities. Category Scope Note: Excludes unprinted/unlaminated 500 kg to 2,000 kg flexible intermediate bulk containers (FIBC jumbo tonic bags), unlaminated multiwall kraft paper sacks, low-density polyethylene (LDPE) trash bags, and raw BOPP rollstock film sold for non-bag labeling or tape applications. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Germany, Japan, Brazil, Vietnam, Mexico, and additional countries in the full report |
| Key Companies Covered | Amcor plc, Berry Global Group, Inc. (Amcor plc), Mondi plc, ProAmpac LLC, Hood Packaging Corporation, Constantia Flexibles, LC Packaging International B.V., Uflex Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
BOPP Bag Market - Research Methodology
Table 10: Primary Validation, Woven-Substrate Triangulation, and Country Modeling Protocol (2026 Edition)
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with circular PP loom and BOPP extrusion-lamination plant managers, pet food packaging engineers, rice and seed mill procurement directors, and rotogravure cylinder prepress specialists. |
| Secondary Research | Analysis of Amcor/Berry Global, Mondi, ProAmpac, LC Packaging, and Uflex corporate disclosures, FEDIAF European pet food production statistics, USDA FAS Grain and Feed Annual reports, and MAFF Japan agricultural bulletins. |
| Market Sizing and Forecasting | Top-down BOPP bag converter valuations reconciled against bottom-up bagged pet food, rice, seed, animal feed, and specialty fertilizer tonnage from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight companion-animal kibble output, milled rice and hybrid seed export volumes, PFAS paper-replacement regulations, and domestic PP weaving capacity across six national markets. |
| Operational Benchmark Traceability | Circular loom output and bagging-line valuation indicators in Tables 2, 3, and 4 trace to FEDIAF pet food tonnage, USDA FAS rice/grain trade datasets, and converter bag-line specifications. |
| Data Triangulation and Validation | Demand estimates are cross-checked against BOPP lamination film consumption and woven PP tape tonnage without double counting 1-tonne FIBC bulk bags or unlaminated paper sacks. |
BOPP Bag Market by Segments
BOPP Bag Market segmented by Bag Construction:
- BOPP Film Laminated Woven PP Sacks
- Clear Gusseted & Cello-Style BOPP Bags
- Block-Bottom Pinch-Seal BOPP Bags
BOPP Bag Market segmented by Capacity Weight:
- 5 kg to 25 kg Pet Food, Rice & Seed Sacks
- <5 kg Retail Bakery & Confectionery Bags
- >25 kg Industrial Agricultural Sacks
BOPP Bag Market segmented by End-Use Sector:
- Pet Food, Animal Feed & Seeds
- Rice, Flour & Dry Staples
- Fertilizers & Building Minerals
BOPP Bag Market segmented by Film Finish:
- High-Gloss Reverse-Printed BOPP
- Matte & Soft-Touch Premium BOPP
- Metallized & Pearlized BOPP
BOPP Bag Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Vietnam
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Pet Food Industry Federation (FEDIAF). (2026, June 15). European Pet Population and Pet Food Production Statistics. FEDIAF EuropeanPetFood.
- [2] ProAmpac LLC. (2026, September 22). Sustainable Pet Food Packaging: PRO-DURA Woven Polypropylene and QUADFLEX Recyclable Bags. ProAmpac Flexible Packaging.
- [3] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global to create global flexible and industrial packaging leader. Amcor Investor Relations.
- [4] Royal LC Packaging International B.V. (2026, March 18). LC Packaging 2025 Sustainability Report (CSRD & ESRS Aligned Woven PP and BOPP Operations). LC Packaging International B.V.
- [5] European Pet Food Industry Federation (FEDIAF). (2026, June 20). FEDIAF Annual Report 2026: European Companion Animal Population and 8.6 Million Tonne Market Data. FEDIAF Brussels.
- [6] Mondi plc. (2026, September 24). Mondi highlights sustainable packaging innovations including mono-material re/cycle FlexiBag at PACK EXPO International 2026. Mondi Group Newsroom.
- [7] Uflex Limited. (2026, August 18). Uflex Limited Annual Report 2025-26: 80-Million-Bag Mexico WPP Pet Food Bag Plant and 54,000 MTPA Dharwad BOPP Film Line. Uflex Limited Investor Relations.
- [8] U.S. Securities and Exchange Commission & Amcor plc. (2025, August 14). Amcor plc Form 8-K Exhibit 99.1: Fourth Quarter and Full Year Fiscal 2025 Results and Berry Global Integration. U.S. Securities and Exchange Commission EDGAR.
- [9] Starlinger & Co. Gesellschaft m.b.H. (2026, April 17). Welding Instead of Gluing: PP*STAR Pinch-Bottom Bags Made from Polypropylene Tape Fabric and Reverse-Printed BOPP Film. Starlinger Newsroom.
- [10] Amcor plc. (2026, March 12). AmPrima Recycle-Ready BOPP and Polyethylene Packaging Solutions for Pet Care and Dry Staples. Amcor Sustainability Products.
- [11] Amcor plc. (2026, March 05). Amcor Demonstrates Circular Polyolefin and PCR Packaging Capabilities at Plastics Recycling Show Europe (PRSE) 2026. Amcor Media Newsroom.
- [12] U.S. Department of Agriculture Foreign Agricultural Service (USDA FAS). (2026, March 18). Report Name: Grain and Feed Annual (Tokyo, Japan JA2026-0011 - Citing MAFF Rice and Compound Feed Data). United States Department of Agriculture.
- [13] U.S. Department of Agriculture Foreign Agricultural Service (USDA FAS). (2026, April 06). Report Name: Grain and Feed Annual (Brasilia, Brazil BR2026-0015). United States Department of Agriculture.
- [14] U.S. Department of Agriculture Foreign Agricultural Service (USDA FAS). (2026, April 15). Report Name: Grain and Feed Annual (Ho Chi Minh City, Vietnam VM2026-0012). United States Department of Agriculture.
- [15] U.S. Department of Agriculture Foreign Agricultural Service (USDA FAS). (2026, March 27). Report Name: Grain and Feed Annual (Mexico City, Mexico MX2026-0018). United States Department of Agriculture.
- [16] Uflex Limited. (2025, August 13). Earnings Release Q1 FY26: USD 50 Million Investment for 80 Million WPP Woven Polypropylene Pet Food Bags in Mexico. Uflex Limited NSE/BSE Filing.
- [17] Royal LC Packaging International B.V. (2026, April 09). Woven PP Bags (WPP) and 8-Color BOPP Laminated Sacks for Agricultural Seed, Feed, and Food Ingredients. LC Packaging Product Categories.
- [18] Constantia Flexibles. (2026, February 23). Constantia Flexibles Highlights Decarbonization and Recyclable Mono-Polypropylene Packaging Advances at CFIA 2026. Constantia Flexibles Press Releases.
- [19] Hood Packaging Corporation. (2026, February 18). Woven Polypropylene (WPP) Laminated to BOPP Pinch-Closure and Sewn Open-Mouth Bags for Dry Pet Food, Flour, and Seed. Hood Packaging Products.
- [20] Constantia Flexibles. (2026, January 20). Constantia Flexibles Wins Two WorldStar 2026 Packaging Awards and Expands Recyclable Flexible Laminates. Constantia Flexibles Newsroom.
- [21] Mondi plc. (2026, April 10). Pet Food & Care Packaging Portfolio: Mono-Material FlexiBag and High-Barrier Dry Kibble Sacks. Mondi Group Products and Solutions.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the BOPP bag market in 2026 and what is forecast for 2036?
- Which pet food lipid-barrier and agricultural export pressures support demand for BOPP bags?
- What makes BOPP Film Laminated Woven PP Sacks the primary bag construction?
- Why do 5 kg to 25 kg Pet Food, Rice & Seed Sacks lead the capacity weight category?
- How do growth rates differ across Vietnam, Brazil, Mexico, the USA, Germany, and Japan?
- Which notable companies manufacture and supply BOPP laminated woven sacks and retail BOPP bags today?
- What restrains post-consumer woven sack recycling or converter margins in the BOPP bag market?
- What should pet food and grain mills evaluate before qualifying a BOPP bag converter?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Bag Construction, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Bag Construction, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Bag Construction, 2026 to 2036
- BOPP Film Laminated Woven PP Sacks
- Clear Gusseted & Cello-Style BOPP Bags
- Block-Bottom Pinch-Seal BOPP Bags
- Y-o-Y Growth Trend Analysis By Bag Construction, 2021 to 2025
- Absolute $ Opportunity Analysis By Bag Construction, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity Weight, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Capacity Weight, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Capacity Weight, 2026 to 2036
- 5 kg to 25 kg Pet Food, Rice & Seed Sacks
- <5 kg Retail Bakery & Confectionery Bags
- >25 kg Industrial Agricultural Sacks
- Y-o-Y Growth Trend Analysis By Capacity Weight, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity Weight, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Pet Food, Animal Feed & Seeds
- Rice, Flour & Dry Staples
- Fertilizers & Building Minerals
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Film Finish, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Film Finish, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Film Finish, 2026 to 2036
- High-Gloss Reverse-Printed BOPP
- Matte & Soft-Touch Premium BOPP
- Metallized & Pearlized BOPP
- Y-o-Y Growth Trend Analysis By Film Finish, 2021 to 2025
- Absolute $ Opportunity Analysis By Film Finish, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Vietnam
- India
- ASEAN
- Australia and New Zealand
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- By Country
- Market Attractiveness Analysis
- By Country
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Vietnam
- Pricing Analysis
- Market Share Analysis, 2025
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Bag Construction
- By Capacity Weight
- By End-Use Sector
- By Film Finish
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Berry Global Group, Inc. (Amcor plc)
- Mondi plc
- ProAmpac LLC
- Hood Packaging Corporation
- Constantia Flexibles
- LC Packaging International B.V.
- Uflex Limited
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 26: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 28: East Asia Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 29: East Asia Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 30: East Asia Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Million) Forecast by Bag Construction, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Million) Forecast by Capacity Weight, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Million) Forecast by Film Finish, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Bag Construction
- Figure 6: Global Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Capacity Weight
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Film Finish
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Bag Construction
- Figure 29: North America Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Capacity Weight
- Figure 32: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End-Use Sector
- Figure 35: North America Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Film Finish
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Bag Construction
- Figure 42: Latin America Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Capacity Weight
- Figure 45: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 48: Latin America Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Film Finish
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Bag Construction
- Figure 55: Western Europe Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Capacity Weight
- Figure 58: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 61: Western Europe Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Film Finish
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Bag Construction
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Capacity Weight
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Film Finish
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Bag Construction
- Figure 81: East Asia Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Capacity Weight
- Figure 84: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 87: East Asia Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Film Finish
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Bag Construction
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Capacity Weight
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Film Finish
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Bag Construction, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Bag Construction, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Bag Construction
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Capacity Weight, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Capacity Weight, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Capacity Weight
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Film Finish, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Film Finish, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Film Finish
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the BOPP bag market in 2026, and what is forecast for 2036?
Global BOPP bag industry valuation moves from USD 285.0 million in 2025 to an estimated USD 300.0 million in 2026 and is forecast to reach USD 474.9 million by 2036 as pet kibble and specialty rice brands adopt puncture-resistant laminated sacks.
What is the CAGR for the BOPP bag market from 2026 to 2036?
A 4.7% annual growth pace governs the global BOPP bag market from 2026 through 2036, generating USD 174.9 million in incremental industry valuation as pet food and seed mills adopt laminated woven sacks.
Which bag construction segment leads the BOPP bag market?
BOPP Film Laminated Woven PP Sacks account for a projected 53.1% portion within bag construction in 2026 because extrusion-bonded polypropylene tape fabric prevents drop bursts while remaining 100% mono-polypropylene.
Which end-use sector segment leads the BOPP bag market?
Pet Food, Animal Feed & Seeds represent an expected 56.3% share across end-use sectors in 2026 driven by PFAS-free kibble fat barriers and high-impact breed photography on retail shelves.
Which country has a notable growth outlook during the assessment period?
Vietnam leads all evaluated countries with an anticipated 5.9% compound annual pace to 2036, supported by Mekong Delta fragrant rice exports and aquaculture feed mills.
Who are the key players in the market?
Amcor plc, Berry Global Group, Inc. (Amcor plc), Mondi plc, ProAmpac LLC, Hood Packaging Corporation, Constantia Flexibles, LC Packaging International B.V., and Uflex Limited anchor commercial supply worldwide.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
