
- Market Size (2026)
- USD 3.3 Bn
- Forecast (2036)
- USD 5.2 Bn
- CAGR (2026 to 2036)
- 4.4%
How big is Compression Garments and Stockings Market in 2026?
The global compression garments and stockings market is estimated at USD 3.2 billion in 2025 and is expected to reach USD 3.34 billion in 2026. Sales of compression garments and stockings are projected to reach USD 5.22 billion by 2036, growing at a CAGR of 4.4% between 2026 and 2036. FMI analysis puts compression garments in the lead, with an expected 92.6% of 2026 product sales.
Key drivers of the compression garments and stockings market include clot prevention and population ageing. Use of stockings for clot prevention is a daily routine in hospitals, after operations and for swollen legs. For instance, up to 900,000 people in the United States are affected by venous thromboembolism each year, according to the Centers for Disease Control and Prevention. As a result, hospitals keep ordering anti-embolism stockings and follow-up garments. Sales of medical compression also gain from ageing, as older adults develop venous disease more often. Evidence of this comes from WHO, which expects 1 in 6 people in the world to be aged 60 years or over by 2030. Device makers are adding to the patient flow, and Stryker completed the acquisition of Inari Medical on 19 February 2025, gaining clot removal products for venous thromboembolism. FMI analysis finds that more of these patients leave hospital with a compression plan, which supports steady garment demand.
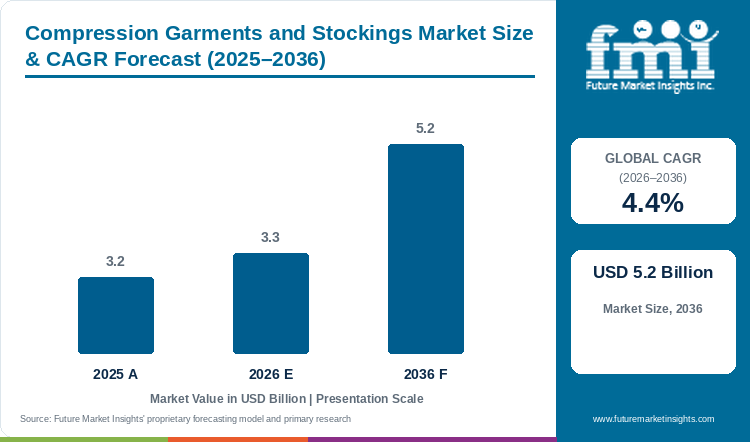
Table 1: Compression Garments and Stockings Market Size and Forecast (USD billion), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 3.2 billion |
| Estimated market size in 2026 | USD 3.34 billion |
| Projected market size by 2036 | USD 5.22 billion |
| CAGR (2026 to 2036) | 4.4% |
| Added sales, 2026 to 2036 | USD 1.88 billion |
Key Market Trends & Insights
- By product: Compression garments will hold 92.6% of 2026 sales, since sleeves, wraps and full garments cover more body areas and conditions than stockings alone.
- By application: With an estimated 46.7% of 2026 sales, varicose veins form the largest application, as long-term wear is the standard conservative treatment for chronic venous disease.
- By distribution channel: Consumption of compression wear through hospitals accounts for about 34.8% of 2026 sales, given that most patients receive a first fitting after an operation or a vascular procedure.
Regional Highlights
- Fastest-growing country: India is expected to grow fastest, at a projected CAGR of 5% between 2026 and 2036, as more surgical patients and diabetics gain access to graduated compression.
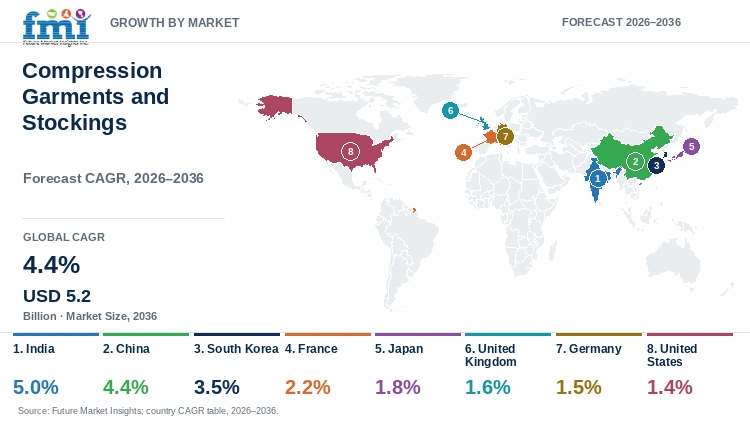
- Growth across other countries: China is projected to grow at 4.4%, level with the global rate, as hospitals expand. South Korea is likely to grow at 3.5% on demand from vein clinics, and France at 2.2%, as reimbursed hosiery keeps use high. Japan, at 1.8%, the United Kingdom, at 1.6%, and Germany, at 1.5%, grow slowly, as most sales there replace worn garments. The United States is slowest at 1.4%, since use of compression there is already high.
Venous clot data show a large, recurring group of patients, and the number of these patients largely sets the level of compression use. Demand for repeat garments is high, as one third of people with venous thromboembolism have a recurrence within 10 years, the CDC says. Recurrent cases need long-term compression and repeat garments, which keeps refill orders steady for suppliers. Prevention gaps add room for growth, as up to 70% of healthcare-associated cases may be preventable, though fewer than half of hospital patients receive recommended prevention. Closing that gap would raise use of anti-embolism stockings in hospitals, which favours suppliers with strong hospital contracts.
Key trends in the compression garments and stockings market point to rising investment in venous care, led by device groups that treat clots. Buyers of venous device makers are paying high prices, as Boston Scientific agreed in January 2026 to acquire Penumbra at USD 374 per share, an enterprise value of about USD 14.5 billion. Large deals in clot treatment raise awareness of venous disease among vascular specialists, which supports referrals for follow-up compression. Device sales keep growing, as Penumbra reported second-quarter 2026 thrombectomy revenue of USD 259.0 million, up 12.5%. More thrombectomy procedures create more patients who need compression after treatment, though garment makers gain only indirectly from device budgets.
New clot-treatment products are widening interventional venous care. Sales of clot-removal devices are rising, as AngioDynamics reported fiscal 2026 Med Tech net sales of USD 150.0 million, up 18.4% on a pro forma basis, with AlphaVac sales up 38.4% in the fourth quarter. Faster growth in clot removal products shows that more venous patients reach specialist care, which raises the number of fitted compression prescriptions. Lifestyle risk is also rising, as WHO counted 940 million adults living with obesity in 2024. Higher body weight increases venous pressure in the legs, so obesity trends add long-term demand for medical compression.
Table 2: Supporting Industry Indicators for the Compression Garments and Stockings Market, 2022 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Venous thromboembolism cases, United States | Up to 900,000 people affected each year. | Clot patients and at-risk cases need compression. | |
| Venous thromboembolism recurrence | About 33% of people with a VTE have a recurrence within 10 years. | Recurrence drives long-term garment use. | |
| Preventable hospital cases | Up to 70% of healthcare-associated VTEs may be preventable. | Better prevention raises stocking use in hospitals. | |
| Population ageing | 1 in 6 people globally expected to be aged 60 or over by 2030. | Venous disease rises with age. | |
| Adult obesity | 940 million adults living with obesity in 2024, 16% of adults. | Excess weight raises venous pressure in the legs. | |
| Cancer incidence | An estimated 20 million new cancer cases in 2022. | Cancer treatment can lead to lymphedema that needs compression. | |
| Venous device deal | Boston Scientific agreed to acquire Penumbra at an enterprise value of about USD 14.5 billion. | Investment in venous care raises clinical attention. | |
| Thrombectomy sales | Penumbra thrombectomy revenue reached USD 259.0 million in the second quarter of 2026, up 12.5%. | More clot procedures lead to more follow-up compression. | |
| Venous device sales | AngioDynamics Med Tech net sales reached USD 150.0 million in fiscal 2026, up 18.4% on a pro forma basis. | Growing specialist venous care raises prescriptions. | |
| Venous device consolidation | Stryker completed the acquisition of Inari Medical in February 2025. | Large groups now sell venous clot products. |
Demand Intensity Analysis
Clot statistics give a clinical benchmark for how much compression demand each patient group supports. The CDC estimates that up to 900,000 people in the United States are affected by venous thromboembolism each year. Dividing the 2025 market estimate of USD 3.2 billion by that case count gives about USD 3,556 per US clot case. Scope differs widely, since the market is global and covers varicose veins, wounds, burns and sports use as well as clot care. The ratio therefore overstates spend per patient, though the result shows that clot care alone is a sizeable part of compression demand.
Population data give a broader benchmark, since venous disease becomes more common with age. WHO expects about 1.4 billion people aged 60 or over by 2030. Compression garments, at 92.6% of 2026 sales or about USD 3.09 billion, equal about USD 2.2 per older person on that 2030 base. Such a small amount per person shows that only a minority of older adults use medical compression, which leaves room for wider prescription.
Demographic change in older age groups offers a fair check on the growth rate. The rise from 1 billion people aged 60 or over in 2020 to 1.4 billion in 2030 implies growth of about 3.4% a year. A 4.4% CAGR is therefore about 1 point above growth in the older population, so the forecast assumes modest gains in prescription rates and product mix. Interventional venous care grows faster, as Penumbra guided to 2025 revenue growth of about 17.3% to 17.5%. Compression sells mostly as follow-up care, so garment makers grow more slowly than device makers but with steadier repeat orders.
Obesity offers a further per-person check, as excess weight raises pressure in the leg veins. WHO counted 940 million adults living with obesity in 2024. The 2025 market estimate equals about USD 3.4 per adult with obesity, which shows how far compression use lags the size of the risk group.
Table 3: Demand Intensity Metrics for the Compression Garments and Stockings Market, 2022 to 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| People affected by VTE each year, United States | Up to 900,000 | Centers for Disease Control and Prevention |
| 2025 market value per US VTE case | About USD 3,556 | Calculated from CDC case estimates and the 2025 market value |
| People aged 60 or over, 2030 | About 1.4 billion | World Health Organization, ageing and health fact sheet |
| Garment segment value per person aged 60 or over | About USD 2.2 | Calculated from WHO population estimates and the 2026 garment segment value |
| Annual growth in people aged 60 or over, 2020 to 2030 | About 3.4% | Calculated from World Health Organization population estimates |
| Penumbra 2025 revenue growth | About 17.3% to 17.5% | Boston Scientific announcement, January 2026 |
| Adults living with obesity, 2024 | 940 million | World Health Organization, obesity and overweight fact sheet |
| 2025 market value per adult with obesity | About USD 3.4 | Calculated from WHO obesity estimates and the 2025 market value |
Analyst Perspective
“Compression wear is a steady, repeat-purchase category that grows with age, weight and operation volumes. Growth now depends on better prevention in hospitals and on comfortable garments that patients will actually wear every day. Suppliers that win hospital formularies and then follow patients into pharmacies and online stores will gain the most.”
Anurag Sharma, Principal Consultant, Future Market Insights.
How is the compression garments and stockings market segmented?
The market is segmented into product, application, distribution channel, and region. Compression garments are expected to lead product with 92.6% share in 2026, and varicose veins lead application with an estimated 46.7%.
By product: compression garments (upper and lower) and compression stockings (anti-embolism and gradient).
By application: varicose veins, wound care, oncology, burns, and others.
By distribution channel: hospitals, online sales, clinics, ambulatory surgical centres, and other healthcare facilities.
By region: compression bought by hospital wards, vein clinics, fitters and home patients living in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do compression garments lead compression wear sales by product?
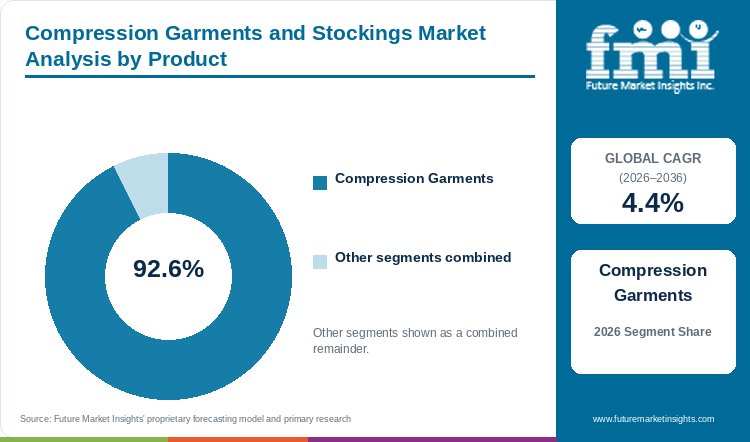
Compression garments are expected to lead product sales with 92.6% share in 2026, ahead of compression stockings at an estimated 7.4%.
Table 4: Product Share for the Compression Garments and Stockings Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Compression Garments | 92.6% |
| Compression Stockings | 7.4% |
| Total | 100.0% |
Table 5: Product Leadership and Market Growth for the Compression Garments and Stockings Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.4% |
| Leading Segment | Compression Garments |
Arms, legs, trunk and face all need garments across lymphedema, burns, post-surgical recovery and sport, so FMI places compression garments at 92.6% of 2026 sales. Use of compression stockings, at an estimated 7.4%, centres on anti-embolism and gradient products bought in bulk by hospitals at low unit prices. Cancer care adds steady demand for upper-body garments, and IARC estimated 20 million new cancer cases and 9.7 million deaths in 2022. Lymph node removal and radiotherapy leave many survivors with arm or leg swelling, and the compression therapy market is forecast to grow at a 5.8% CAGR from 2024 to 2034. Garments will keep the lead through 2036, as made-to-measure products serve more conditions.
- Arm sleeves, leggings, full-body suits, face masks and post-surgical garments make up the garment group.
- WHO expects people aged 80 or older to triple between 2020 and 2050 to 426 million. A larger very old population raises demand for easy-to-don garments, which favours designs with zips and wraps over tight stockings.
Why do varicose veins lead compression wear sales by application?
Varicose veins are expected to lead application sales with 46.7% share in 2026, ahead of wound care at an estimated 17.4% and oncology at 13.2%.
Table 6: Application Share for the Compression Garments and Stockings Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Varicose Veins | 46.7% |
| Wound Care | 17.4% |
| Oncology | 13.2% |
| Others | 12.1% |
| Burns | 10.6% |
| Total | 100.0% |
Chronic venous disease is common in older and overweight adults, and graduated compression is the standard first treatment. Varicose veins therefore take an estimated 46.7% of 2026 application sales in the FMI breakdown. Consumption of wound care garments, at about 17.4%, covers venous leg ulcers, and oncology, near 13.2%, covers lymphedema after cancer treatment. Burns, at 10.6%, need custom pressure garments for scar control. Weight trends strengthen the varicose lead, as WHO said 2.6 billion adults, or 45%, were overweight in 2024. Higher body weight raises venous pressure, and procedures for advanced disease also rise, with the venous stents market projected at an 8.4% CAGR between 2025 and 2035. Varicose veins will remain the largest application, as patients wear garments before and after procedures.
- Mild varicose veins, chronic venous insufficiency and post-sclerotherapy care make up the varicose group.
- Peripheral device groups are expanding venous portfolios, and Boston Scientific said the Penumbra portfolio addresses deep vein thrombosis and pulmonary embolism among other conditions. Wider venous treatment raises the number of patients prescribed compression after procedures.
Why do hospitals lead compression wear sales by distribution channel?
Hospitals are expected to lead distribution channel sales with 34.8% share in 2026, ahead of online sales at an estimated 21.3% and clinics at 18.6%.
Table 7: Distribution Channel Share for the Compression Garments and Stockings Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Hospitals | 34.8% |
| Online Sales | 21.3% |
| Clinics | 18.6% |
| Ambulatory Surgical Centres | 13.9% |
| Other Healthcare Facilities | 11.4% |
| Total | 100.0% |
A first fitting usually happens in hospital after an operation, a clot or a vascular procedure, so hospitals are estimated at 34.8% of 2026 distribution sales. Popularity of online refills is growing, and online sales take about 21.3%, covering repeat purchases and sports compression, and clinics, near 18.6%, serve fittings for venous disease and lymphedema. Hospital prevention protocols drive the channel, since more than a third of yearly clot cases follow a recent hospitalization, the CDC says. Post-discharge risk makes hospital-issued stockings a key prevention tool, and the venous thromboembolism treatment market is expected to grow at a 3.9% CAGR between 2026 and 2036. Hospitals will keep the lead, though online refills will gain share.
- Inpatient wards, surgical units and vascular departments make up the hospital channel.
- Quarterly sales at Penumbra grew to USD 390.0 million in the June 2026 period, 14.9% above a year earlier. Growth in hospital vascular procedures adds patients who leave with a compression prescription.
What are the drivers, restraints, and opportunities in the compression garments and stockings market?
Ageing, obesity and clot prevention keep compression in daily clinical use. Poor patient adherence and price pressure in hospital tenders restrain growth, and comfortable designs and online refills open new demand.
- Driver: Older and heavier populations develop more venous disease, and hospitals use compression to prevent clots after operations.
- Restraint: Many patients stop wearing tight garments, and hospital tenders push prices down for basic stockings.
- Opportunity: Softer, easier-to-wear designs and online refill programmes can keep patients in therapy longer.
Ageing, Obesity and Clot Prevention Drive Demand
Age and body weight push medical compression use higher, and chronic venous disease adds most of the new volume. Demand for long-term compression grows with ageing, as WHO expects the population aged 60 or over to double to 2.1 billion by 2050. Each older cohort brings more varicose veins, leg ulcers and operations, which raises long-term garment use. Clot prevention adds hospital volume, as more than a third of yearly clot cases follow a recent hospitalization. Interventional venous care is widening the patient pool too, with the peripheral vascular devices market projected at a 6.6% CAGR from 2025 to 2035. Demographics will keep compression demand rising steadily through 2036 in every profiled region.
Adherence and Tender Pricing Restrain Growth
Producers of compression wear lose sales when patients stop wearing garments that feel hot or tight. The CDC notes that fewer than half of hospital patients receive recommended clot prevention. Gaps in prevention and adherence limit how many patients enter and stay in compression therapy. Hospital buyers also push for lower prices, and device groups capture more of venous care budgets, as AngioDynamics guided to 12% to 15% Med Tech growth for fiscal 2027. Budget shifts toward devices put pressure on stocking prices, so suppliers need to differentiate on comfort and evidence.
Comfortable Designs and Online Refills Open New Demand
Products that patients choose to keep wearing will increasingly drive growth of the compression garments and stockings market. Adoption of weight-loss drugs may widen, as WHO published a guideline on GLP-1 therapies for adult obesity in December 2025. Weight-loss drugs can change limb shape quickly, which creates repeat fittings and new garment sizes for treated patients. Procedure growth adds further fittings, with the vascular closure devices market expected to grow at a 3.4% CAGR between 2026 and 2036. Brands with soft fabrics and online reorder services will hold patients in therapy longer.
Which country CAGRs are profiled in the compression garments and stockings market?
Table 8: Country CAGR Comparison for the Compression Garments and Stockings Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 5% |
| China | 4.4% |
| South Korea | 3.5% |
| France | 2.2% |
| Japan | 1.8% |
| United Kingdom | 1.6% |
| Germany | 1.5% |
| United States | 1.4% |
How do country-level CAGRs compare in the compression garments and stockings market?
India leads the FMI country table at 5%, 0.6 points above the 4.4% global rate, as access to surgical and chronic care widens. China, at 4.4%, grows in line with the global pace on hospital expansion and an ageing population. Slower but steady gains come from South Korea (3.5%) and France (2.2%), as clinics and reimbursement keep use high. Japan, at 1.8%, the United Kingdom, at 1.6%, Germany, at 1.5%, and the United States, at 1.4%, are mature markets with high existing use. The wide gap between Asia and mature Western markets shows that new patient access drives growth more than higher use per patient.
- Hospital building and rising operation volumes in India bring anti-embolism stockings into more wards, so local and imported brands gain first-time buyers.
- China is expanding hospital capacity for an ageing population, which raises demand for basic stockings and lymphedema garments.
- South Korean clinics treat varicose veins actively, which supports garment sales before and after procedures.
- French reimbursement for medical compression keeps use high, so growth comes mainly from replacement and ageing.
- An older population in Japan already uses compression widely, which limits new demand to replacements and premium fabrics.
- NHS prescribing of compression for leg ulcers and veins is well established, so growth depends on new fabrics and online supply.
- German medical hosiery makers serve a mature home market, which keeps growth low and steers them toward exports.
- Use of compression is already high in the United States, so growth depends on clot prevention protocols and online sports compression.
Full report country CAGRs cover: eight profiled rates from 1.4% in the United States to 5% in India, with the other standard countries listed in the regional tables.
Country-wise Analysis
India Compression Garments and Stockings Market Outlook (2026 to 2036)
India is adding hospital beds and surgical capacity, and more patients receive clot prevention after operations. Diabetes and venous ulcers also create long-term demand for wound compression. With more wards issuing stockings, Indian sales rise at a 5% CAGR, the quickest pace among the eight profiled countries.
Key takeaway: As Indian hospitals add beds and surgical capacity, more patients will receive compression stockings after operations, which makes India the fastest-growing country.
China Compression Garments and Stockings Market Outlook (2026 to 2036)
With a large and ageing population, China is adding vascular and oncology services in hospitals. Sales of stockings and garments rise with each new service line, as more patients need them after treatment. FMI projects China at a 4.4% CAGR, in line with the global rate.
Key takeaway: Chinese hospitals adding vascular and oncology services will issue more stockings and garments, keeping growth in China level with the global rate.
South Korea Compression Garments and Stockings Market Outlook (2026 to 2036)
FMI notes that South Korean clinics perform many varicose vein procedures, and patients wear compression before and after treatment. An ageing population adds chronic venous cases that need long-term compression. With fittings tied to these procedures, South Korea is projected to grow at a CAGR of 3.5% through 2036, under the 4.4% global figure.
Key takeaway: Patients treated for varicose veins at Korean vein clinics will keep buying compression garments before and after each procedure.
France Compression Garments and Stockings Market Outlook (2026 to 2036)
French patients have a long tradition of medical compression, with reimbursed stockings prescribed for venous disease. High existing use limits new patients, so growth comes from ageing and replacement. France is projected to grow at a CAGR of 2.2% through 2036, as reimbursed patients age.
Key takeaway: French patients with venous disease will keep buying reimbursed stockings, but high existing use leaves growth coming mostly from ageing and replacement.
Japan Compression Garments and Stockings Market Outlook (2026 to 2036)
Japan has one of the oldest populations in the world, and compression use there is high. WHO expects 1 in 6 people globally to be 60 or over by 2030, a share Japan passed long ago. In a mature user base, most sales are replacements for worn garments. Japan is likely to grow at a 1.8% CAGR, well below the global pace.
Key takeaway: Older Japanese patients already wear compression widely, so most sales in Japan will come from replacing worn garments, not from new users.
United Kingdom Compression Garments and Stockings Market Outlook (2026 to 2036)
Under the NHS, compression is prescribed widely for leg ulcers and venous disease, and community nurses manage much of that care. Supply of hosiery online is rising, though established prescribing limits new growth. The United Kingdom is projected to grow at a CAGR of 1.6% through 2036, mostly through new fabrics and online refills.
Key takeaway: Community nurses in the NHS will keep prescribing compression for leg ulcers and veins, and online hosiery sales add modest growth.
Germany Compression Garments and Stockings Market Outlook (2026 to 2036)
Germany hosts leading medical hosiery makers such as medi, and use of compression is high. A mature home market leaves little room for new patients. FMI forecasts Germany at a 1.5% CAGR, below most profiled countries.
Key takeaway: German patients already use medical hosiery widely, so local makers such as medi will look to exports for most new growth.
United States Compression Garments and Stockings Market Outlook (2026 to 2036)
Clot prevention is a major hospital focus in the United States. Up to 900,000 people are affected by venous thromboembolism each year in the country. Hospitals already use stockings widely, so growth comes from better prevention and online sports compression. The United States is projected to grow at a CAGR of 1.4% through 2036, the lowest rate among the eight profiled countries.
Key takeaway: American hospitals already use stockings widely, so US sales will grow mainly through better clot prevention and online sports compression.
Who are the notable companies in the compression garments and stockings market?
Eleven companies are profiled across medical hosiery makers, hospital suppliers and consumer brands. The hosiery makers are medi, SIGVARIS, BSN Medical, Therafirm and Medical Z, and the hospital suppliers are 3M, Covidien and Santemol Group Medikal. 2XU, Leonisa and Nouvelle complete the list as consumer brands for sport and shapewear.
Medical hosiery specialists, diversified medical groups and sports and shapewear brands compete for different buyers, and the hosiery specialists hold the deepest clinical range. Venous care is drawing large investment, as Stryker completed the acquisition of Inari Medical in February 2025 to enter the fast-growing VTE segment. Device consolidation raises clinical focus on venous disease, which supports referrals to compression specialists. Among the profiled companies, medi, SIGVARIS and BSN Medical lead medical hosiery, and 3M and Covidien serve hospitals. 2XU, Leonisa and Nouvelle serve sport and shapewear buyers. Hospital contracts and fitting networks are likely to decide share in medical compression through 2036.
- Medical hosiery specialists with fitting networks and made-to-measure ranges: medi, SIGVARIS, BSN Medical, Therafirm and Medical Z.
- Diversified medical groups supplying hospital stockings: 3M, Covidien and Santemol Group Medikal.
- Sports and shapewear brands selling through retail and online channels: 2XU, Leonisa and Nouvelle.
Competitive Benchmarking: Compression Garments and Stockings Market
Table 9: Competitive Benchmarking for the Compression Garments and Stockings Market (qualitative ratings), 2026
| Company | Medical Hosiery Range | Hospital Contracts | Consumer Channels | Recent Activity |
|---|---|---|---|---|
| medi | High | Medium | Medium | Medium |
| SIGVARIS | High | Medium | Medium | Medium |
| BSN Medical | High | High | Medium | Medium |
| 3M | Medium | High | Low | Low |
| Covidien | Medium | High | Low | Low |
| 2XU | Low | Low | High | Medium |
| Therafirm | Medium | Low | Medium | Low |
Ratings compare the companies on medical hosiery range, hospital contracts, consumer channels and recent activity.
Key Developments in the Compression Garments and Stockings Market
- Penumbra reported second-quarter 2026 thrombectomy revenue of USD 259.0 million in July 2026, up 12.5%. More clot procedures lead to more patients needing follow-up compression.
- AngioDynamics reported fiscal 2026 Med Tech net sales of USD 150.0 million, up 18.4% on a pro forma basis, in July 2026. Venous device growth widens the pool of patients in specialist care.
- Boston Scientific agreed to acquire Penumbra at an enterprise value of about USD 14.5 billion in January 2026. Large investment in venous care raises clinical attention to clot disease.
- WHO reported in October 2026 that 940 million adults lived with obesity in 2024. Rising obesity adds long-term demand for leg compression in adult patients.
- In October 2025, WHO projected that 1 in 6 people globally will be aged 60 or over by 2030. Ageing steadily expands the population living with chronic venous disease.
- On 19 February 2025, Stryker completed the acquisition of Inari Medical. A large medtech group now sells venous clot removal products.
Key Players in the Compression Garments and Stockings Market
Medical Hosiery Specialists
- medi
- SIGVARIS
- BSN Medical
- Therafirm
- Medical Z
Diversified Medical Groups
- 3M
- Covidien
- Santemol Group Medikal
Sports and Shapewear Brands
- 2XU
- Leonisa
- Nouvelle
Compression Garments and Stockings Market - Report Scope
Table 10: Report Scope for the Compression Garments and Stockings Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; application; distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Graduated and anti-embolism compression stockings and compression garments for upper and lower body, used for venous disease, wound care, oncology, burns and recovery. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; South Korea; France; Japan; United Kingdom; Germany; United States |
| Key companies profiled | 3M, BSN Medical, Covidien, medi, SIGVARIS, Therafirm, 2XU, Santemol Group Medikal, Leonisa, Nouvelle, Medical Z |
| Forecast period | 2026 to 2036 |
Compression Garments and Stockings Market - Research Methodology
Table 11: Research Methodology for the Compression Garments and Stockings Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Venous disease, clot prevention, lymphedema, ageing and obesity trends, and hospital and online distribution. |
| Market Sizing | Market value is built from patient numbers, garment volumes and prices across products and channels. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Compression Garments and Stockings Market by Segments
Compression Garments and Stockings Market segmented by Product:
- Compression Garments
- Compression Stockings
Compression Garments and Stockings Market segmented by Application:
- Varicose Veins
- Wound Care
- Oncology
- Burns
- Others
Compression Garments and Stockings Market segmented by Distribution Channel:
- Hospitals
- Online Sales
- Clinics
- Ambulatory Surgical Centres
- Other Healthcare Facilities
Compression Garments and Stockings Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Centers for Disease Control and Prevention. (2025, January 27). Data and Statistics on Venous Thromboembolism. https://www.cdc.gov/blood-clots/data-research/facts-stats/index.html
- [2] World Health Organization. (2025, October 1). Ageing and health. https://www.who.int/news-room/fact-sheets/detail/ageing-and-health
- [3] Stryker. (2025, February 19). Stryker completes acquisition of Inari Medical, Inc., providing entry into the high-growth peripheral vascular segment. https://www.stryker.com/us/en/about/news/2025/stryker-completes-acquisition-of-inari-medical-inc.html
- [4] Boston Scientific. (2026, January 15). Boston Scientific announces agreement to acquire Penumbra, Inc. https://news.bostonscientific.com/2026-01-15-Boston-Scientific-announces-agreement-to-acquire-Penumbra,-Inc
- [5] Penumbra. (2026, July 30). Penumbra, Inc. Reports Second Quarter 2026 Financial Results. https://www.sec.gov/Archives/edgar/data/0001321732/000132173226000036/pen-63026xexhibit991.htm
- [6] AngioDynamics. (2026, July 14). AngioDynamics Reports Record Fiscal Year 2026 Fourth Quarter and Full Year Financial Results. https://www.businesswire.com/news/home/20260714974221/en/
- [7] World Health Organization. (2026, October 7). Obesity and overweight. https://www.who.int/news-room/fact-sheets/detail/obesity-and-overweight
- [8] International Agency for Research on Cancer. (2024, February 1). Global cancer burden growing, amidst mounting need for services. https://www.iarc.who.int/news-events/global-cancer-burden-growing-amidst-mounting-need-for-services/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the compression garments and stockings market during 2026?
- What market size is projected by 2036?
- Which product holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Compression Garments
- Compression Stockings
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Varicose Veins
- Wound Care
- Oncology
- Burns
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hospitals
- Online Sales
- Clinics
- Ambulatory Surgical Centres
- Other Healthcare Facilities
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Application
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Application
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- medi
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- SIGVARIS
- BSN Medical
- 3M
- Covidien
- 2XU
- Therafirm
- Medical Z
- Santemol Group Medikal
- Leonisa
- Nouvelle
- medi
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the compression garments and stockings market expected in 2026?
At USD 3.34 billion in 2026, the compression garments and stockings market is up from USD 3.2 billion in 2025, FMI estimates. Ageing and clot prevention keep compression in daily clinical use.
What CAGR is projected for the compression garments and stockings market through 2036?
A 4.4% CAGR is projected for compression wear, taking sales to USD 5.22 billion by 2036, since venous disease rises with age and body weight.
Which product holds a notable market share in 2026?
Compression garments are expected to hold 92.6% of 2026 sales, given that garments serve more body areas and conditions than stockings.
Which application holds a notable market share in 2026?
Varicose veins are likely to account for 46.7% of application sales, as compression is the standard first treatment for chronic venous disease.
Which country has a notable expansion outlook through 2036?
India grows fastest in the FMI view, at a 5% CAGR, as more hospitals issue compression after operations.
Who are the key companies in the compression garments and stockings market?
medi, SIGVARIS and BSN Medical lead medical hosiery, 3M and Covidien serve hospitals, and 2XU, Leonisa and Nouvelle serve sport and shapewear buyers with consumer brands.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
