

- Market Size (2026)
- USD 8.2 Bn
- Forecast (2036)
- USD 13.0 Bn
- CAGR (2026 to 2036)
- 4.7%
How big is Cream Cheese Market in 2026?
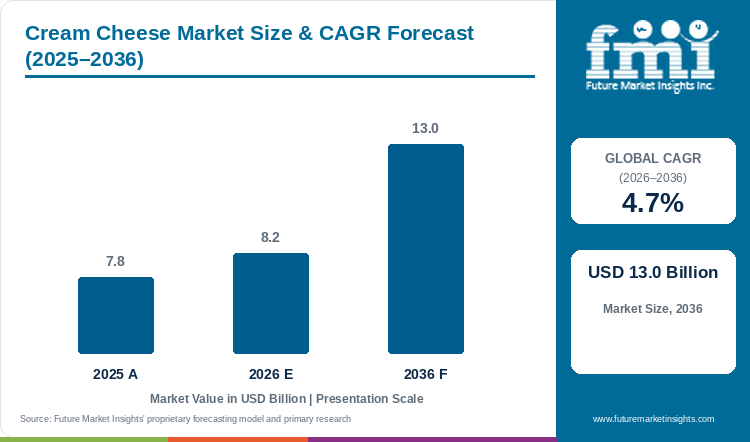
The global cream cheese industry valuation reached USD 7.8 billion in 2025 and is estimated at USD 8.2 billion for 2026 before hitting USD 13.0 billion in 2036 under a 4.7% CAGR.
The global cream cheese industry valuation stood at USD 7.8 billion in 2025 and is estimated to reach a market size of USD 8.2 billion for 2026. Demand continues to build across both grocery dairy aisles and commercial cheesecake bakeries, with a January 2025 study of 1,093 United Kingdom shoppers in Foods showing that 89% chose real dairy cream cheese over plant-based alternatives because of its smooth melt and clean cultured taste [1]. Owing to this steady consumer preference, FMI predicts that worldwide cream cheese market value will climb to USD 13.0 billion by 2036 under a 4.7% CAGR, delivering USD 4.8 billion in net valuation growth. Spreadable Whipped & Soft Tubs are slated to account for 52.1% of 2026 product form market value as households reach for fridge-ready tubs that spread easily onto warm bagels in addition to culinary dairy spreads, while farmgate butterfat price swings still test creamery margins.
Key Market Trends & Insights
- By product form: Spreadable Whipped & Soft Tubs are slated to hold 52.1% in 2026 because whipped nitrogen overrun and reclosable tubs allow easy knife spreading at 4 degrees Celsius.
- By fat content: Regular Full-Fat varieties are predicted to capture 53.9% in 2026 since a minimum 33% milkfat level prevents surface cracks in baked cheesecakes.
- By flavor: Plain Original blocks and tubs are likely to capture 55.3% during 2026 as mild cultured tang works equally well in sweet frostings and savory sushi rolls.
- By end use: Retail Household Breakfast occasions are set to generate 57.1% in 2026 on daily morning bagel and toast habits across urban homes.
- By distribution channel: Supermarkets & Retail Dairy Aisles are slated to generate 58.9% for 2026 through chilled private-label and branded twin-pack promotions.
Regional Highlights
- Fastest national trajectory: South Korea paces evaluated dairy importers at 5.8% CAGR up to 2036 as cafe bakery chains and spicy K-food recipes incorporate mild dairy cream cheese.
- Comparative country pacing: Brazil posts a 5.6% annual growth rate and Saudi Arabia records 5.5% whereas the USA grows at 4.2% ahead of Canada (4.1%) and Germany (3.9%).
Market Size & Forecast
Table 1: Market Size and Forecast for the Cream Cheese Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 7.8 billion |
| Estimated Market Size in 2026 | USD 8.2 billion |
| Projected Market Size by 2036 | USD 13.0 billion |
| CAGR, 2026 to 2036 | 4.7% |
| Absolute Market Growth, 2026 to 2036 | USD 4.8 billion |
Commercial bakeries and dairy processors need curds that resist watery whey separation during high-heat cheesecake baking or chilled bagel counter service. A July 2025 fermentation study in Food Chemistry: X showed that R704 lactic starter co-cultures reached 187.67 million CFU/g at pH 4.16 and built a smooth protein-fat network with zero whey separation [2]. Creameries are applying these starter-culture gains to produce firmer blocks and tubs next to sliced and spreadable processed cheeses in retail and foodservice chillers. Tight cold-chain temperature control and steady winter butterfat supply remain the top day-to-day priorities for dairy co-operatives.
Creamery Curd Output and Milkfat Solids Sizing
Table 2: Creamery Production Volume and Milkfat Utilization Indicators for the Cream Cheese Market (USD billion and physical volume ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 7.8 | 8.2 | 13.0 |
| Commercial cream cheese production (million tonnes) | 1.4 to 1.5 | 1.5 to 1.6 | 2.1 to 2.3 |
| Spreadable tub & whipped output (million tonnes) | 0.7 to 0.8 | 0.8 to 0.8 | 1.1 to 1.2 |
| Average wholesale valuation (USD per kilogram) | 5.2 to 5.6 | 5.3 to 5.7 | 5.7 to 6.2 |
Operational note: Creamery output ranges cover lactic-fermented dairy curds standardized to 33% minimum fat on a wet basis for regular grades and 20% to 32% fat for Neufchatel variants.
Modern creameries have replaced cloth-bag whey draining with high-speed centrifugal separators and ultrafiltration membranes that trap whey proteins inside the curd. Membrane filtration paired with spreadable dairy fats raises cheese yield per 100 kilograms of milk while cutting acid-whey wastewater treatment costs.
Per Capita & Bakery Commissary Sizing
Table 3: Per Capita Market Valuation Indicators for the Cream Cheese Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual market value per capita (USD) | 1.0 | 1.0 | 1.4 |
| Market valuation per 1,000 people (USD) | 951.2 | 988.0 | 1,444.4 |
| Retail supermarket channel share (%) | 58.0% to 59.2% | 58.4% to 59.4% | 56.5% to 58.0% |
Table 4: Retail and Commercial Bakery Segment Valuation Indicators for the Cream Cheese Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 8.2 billion | 2026 global industry valuation baseline |
| Supermarkets & retail dairy aisle valuation, 2026 | USD 4.8 billion | 58.9% distribution channel share |
| Retail household breakfast market value, 2026 | USD 4.7 billion | 57.1% end-use segment allocation |
| Spreadable whipped & soft tub valuation, 2026 | USD 4.3 billion | 52.1% product form allocation |
Bagel shops and commercial cheesecake bakeries order 2-kilogram to 10-kilogram plastic pails and foil loaves built for high-speed planetary mixers. Heat-stable cream cheese blocks used with commercial bakery ingredients stop fat separation inside deck ovens and blast freezers.
Analyst Perspective
"Ultrafiltration curd recovery and lactase-treated dairy recipes let creameries deliver clean-label spreadability without synthetic gums. Processors that pair lactose-free retail bricks and tubs with bake-stable foodservice blocks will win high-margin Asian bakery and Western grocery contracts."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the cream cheese market segmented?
The cream cheese market is segmented by product form, fat content, flavor, end use, distribution channel, and region. In 2026, Spreadable Whipped & Soft Tubs are projected at 52.1%, Regular Full-Fat at 53.9%, Plain Original at 55.3%, Retail Household Breakfast at 57.1%, and Supermarkets & Retail Dairy Aisles at 58.9%.
By product form: Spreadable Whipped & Soft Tubs, Foil-Wrapped Baking Bricks/Blocks, and Bulk Foodservice Pails.
By fat content: Regular Full-Fat, Neufchatel / Reduced-Fat, and Whipped & Lactose-Free.
By flavor: Plain Original, Savory Herb, Chive & Garlic, and Sweet Berry & Honey.
By end use: Retail Household Breakfast, Commercial Cheesecake & Bakery, and Bagel Cafes & Sushi Foodservice.
By distribution channel: Supermarkets & Retail Dairy Aisles, Commercial Foodservice & Bagel Chains, and Industrial Bakery & Cheesecake Processors.
Why do Spreadable Whipped & Soft Tubs lead the product form category?
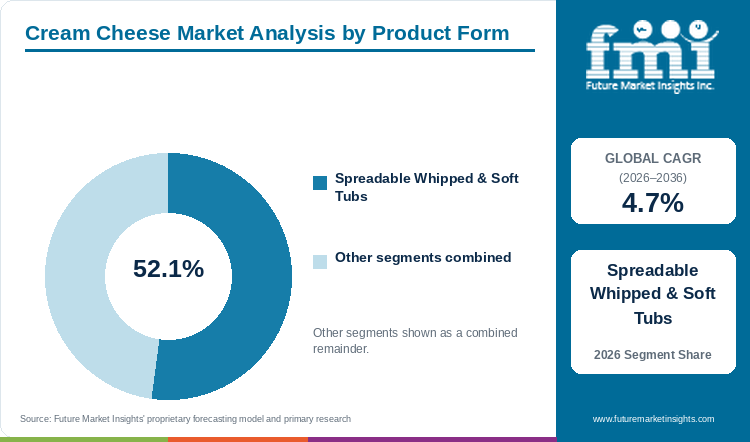
Spreadable Whipped & Soft Tubs are slated to hold 52.1% of product form volume in 2026, enabled by cold-schmear convenience.
Table 5: Product Form Share for the Cream Cheese Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Spreadable Whipped & Soft Tubs | 52.1% |
| Other Segments Combined | 47.9%* |
| Total | 100.0% |
*Note: Remaining product form categories sum to 100.0% of 2026 global cream cheese market value.
Table 6: Product Form Leadership and Market Growth for the Cream Cheese Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.7% |
| Leading Segment | Spreadable Whipped & Soft Tubs |
Food-grade nitrogen whipping or cultured whey-cream blending softens the curd at 4 degrees Celsius so shoppers can spread cream cheese straight from the fridge without waiting for a brick to warm up. Reclosable polypropylene tubs also keep out refrigerator odors and stop surface drying between breakfasts while sitting near whipped dairy cream toppings in dairy cases. Meanwhile, firm foil-wrapped 8-ounce bricks remain the go-to format for holiday cheesecake and frosting bakers.
- Spreadable Whipped & Soft Tubs are slated to capture 52.1% of the product form market valuation in 2026 because reclosable tubs avoid foil mess and torn bread.
- In February 2026, Arla Foods amba reported record 2025 group revenue of EUR 15.1 billion and confirmed a plant expansion at Holstebro Dairy in Denmark to add 16,000 tonnes of annual cream cheese capacity across spreadable and foodservice lines [3].
How does Regular Full-Fat maintain the largest fat content share?
Regular Full-Fat formulations are predicted to capture 53.9% of fat content market value in 2026, sustained by 33% milkfat emulsion stability.
Under United States FDA 21 CFR 133.133 and Codex rules, regular cream cheese must contain at least 33% milkfat with moisture capped at 55% by weight. That rich milkfat network surrounds casein proteins to give a smooth mouthfeel and prevent watery cracks during water-bath cheesecake baking with specialty baking ingredients. While Neufchatel and lactose-free tubs appeal to calorie-conscious and lactose-sensitive shoppers, pastry chefs and bagel counters still prefer full-fat curds.
- Regular Full-Fat grades are predicted to secure 53.9% of the fat content valuation in 2026 because intact milkfat globules give reliable bake stability and rich texture.
- An October 2025 narrative review in Frontiers in Nutrition confirmed that natural dairy cheese matrices containing milk polar lipids and calcium-casein networks support normal lipid digestion without negative cardiometabolic effects [4].
What keeps Plain Original ahead in the flavor category?
Plain Original recipes are likely to command 55.3% of flavor market size in 2026, guided by sweet and savory recipe versatility.
Unflavored cultured cream cheese gets its mild buttery aroma from Lactococcus lactis starter cultures and works as an all-purpose base in both home kitchens and commercial bakeries. A single plain tub or brick can be spread onto morning bagels or whipped with powdered sugar for cake icing with home baking mixes and frostings. Savory chive and roasted garlic tubs as well as sweet strawberry swirls remain popular add-on buys for party platters.
- Plain Original formulations are likely to represent 55.3% of flavor market value in 2026 because unseasoned curds work for both breakfast spreading and dessert baking.
- In October 2025, The Kraft Heinz Company reported that its Philadelphia brand supplies over 50 million pounds of cream cheese each holiday season for nearly 50 million slices of cheesecake while launching Philadelphia Frozen Cheesecake and Cinnamon Cream Cheese Frosting [5].
Why does Retail Household Breakfast lead the end use category?
Retail Household Breakfast occasions are set to represent 57.1% across end-use consumption in 2026, favored for morning toast routines.
Remote and hybrid work routines have kept weekday breakfast at home, where toasted bagels and sourdough slices topped with soft cream cheese make a quick two-minute meal. Families also use soft tubs to pack school lunch wraps and afternoon vegetable dips. At the same time, commercial cheesecake bakeries and sushi restaurants are the fastest-growing foodservice buyers across East Asia and the Middle East.
- Retail Household Breakfast occasions are set to capture 57.1% of the end-use market valuation in 2026 owing to regular daily bagel and bread spreading.
- In May 2026, Bel Group reported in its 2025 Annual Results presentation that core portion and spreadable cheese brands including Kiri and Boursin plus The Laughing Cow posted steady 2025 retail volume growth [6].
What gives Supermarkets & Retail Dairy Aisles the top distribution channel share?
Supermarkets & Retail Dairy Aisles are projected to hold 58.9% within channel market value for 2026, powered by multi-pack promotions.
Supermarkets and hard discounters anchor household cream cheese buying through chilled dairy walls that place soft tubs next to packaged bagels and smoked salmon. Grocers use private-label 200-gram tubs and holiday two-brick packs as high-traffic promotions during fourth-quarter baking weeks. Meanwhile, direct B2B shipments to industrial cheesecake plants and cafe chains continue to grow through dedicated foodservice dairy teams.
- Supermarkets & Retail Dairy Aisles are projected to capture 58.9% across distribution channel market size during 2026 through chilled shelf visibility and holiday baking promotions.
- In June 2026, Saputo Inc. reported fiscal 2026 revenues of CAD 17.551 billion and adjusted EBITDA of CAD 1.659 billion, up 10.4% year-over-year on stronger North American retail and foodservice cheese volumes [7].
What are the drivers, restraints, and opportunities in the cream cheese market?
New Asian and Middle Eastern bakery cafe menus and home bagel habits will likely boost cream cheese industry valuation through 2036, whereas raw milkfat price swings restrain processor margins and lactase-treated real dairy bricks and tubs create premium growth opportunities.
- Driver: Fast growth of Western-style bakery cafes and Basque cheesecakes as well as cheese-foam tea drinks across Asia and the Middle East lifts bulk foodservice cream cheese imports.
- Restraint: Seasonal farmgate butterfat price swings and cold-chain power bills squeeze margins for non-integrated creameries and private-label packers.
- Opportunity: Lactase-treated lactose-free real dairy bricks and tubs made without artificial preservatives attract digestive-wellness shoppers without losing authentic dairy taste.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Foodservice demand for cream cheese is climbing fast as coffee chains and bakeries roll out baked Basque cheesecakes and cream-cheese-filled pretzels plus whipped cheese-foam tea toppings. Pastry chefs need blocks with steady curd firmness that whip smoothly into drink foams while holding their shape in cake fillings next to non-dairy whipping creams. In July 2026, Fonterra Co-operative Group Limited reported that its Anchor Food Professionals foodservice division generated 24% of co-operative earnings across more than 50 countries by tailoring cream cheese texture for Asian and Middle Eastern bakeries and beverage chains [8].
Risk Assessment of the Cream Cheese Market: Operational and Formulation Friction
Because regular cream cheese must contain at least 33% milkfat by weight, creamery profits are closely tied to wholesale butter prices and consumer concerns over saturated fat. When cream prices jump or shoppers look for lower-fat bread spreads, some budget-conscious buyers switch to competing plant-based spreadable alternatives or reduced-fat Neufchatel. In July 2025, a systematic review of 88 studies and 66 patents in Foods noted that saturated fat and lactose concerns have driven new patent filings for hybrid and oil-gel cheese analogues [9]. Dairy processors therefore pair butterfat standardization with membrane protein recovery to protect their margins.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Dairy processors can add lactase enzymes to pasteurized milk and cream curds to make clean-label lactose-free cream cheese bricks and tubs that keep real dairy flavor and one-to-one baking performance. Shoppers with lactose sensitivity strongly prefer real cow-milk cream cheese over starch-thickened vegan spreads, which supports wider shelf space next to lactose-free dairy products in grocery dairy cases. In July 2026, The Kraft Heinz Company announced the nationwide U.S. retail launch of Philadelphia Lactose Free cream cheese formulated with real milk and cream plus lactase enzyme and zero artificial preservatives after two years of R&D [10].
Cream Cheese Market by Country (2026 to 2036)
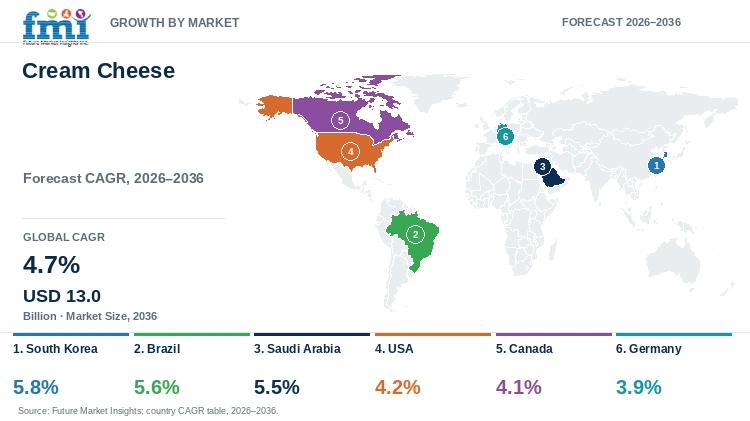
Across evaluated national markets, South Korea leads cream cheese growth at 5.8% annually to 2036 ahead of Brazil (5.6%) and Saudi Arabia (5.5%) while mature dairy sectors in the USA (4.2%) as well as Canada (4.1%) and Germany (3.9%) post steady gains. Growth across East Asian and Latin American foodservice channels in addition to Gulf Cooperation Council retailers is supported by duty-free dairy quotas and cafe cheesecake chains.
Table 7: Country CAGR and Primary Growth Levers for the Cream Cheese Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 5.8% | Duty-free U.S. and EU cheese tariff phase-outs and K-bakery cafe and spicy fusion dish adoption |
| Brazil | 5.6% | Commercial pizza, sushi, and bakery foodservice expansion and domestic soft-curd creameries |
| Saudi Arabia | 5.5% | USD 57 billion food retail expansion and high per-capita consumption of spreadable breakfast cheeses |
| USA | 4.2% | Habitual household bagel consumption, holiday cheesecake baking, and lactose-free brick and tub innovation |
| Canada | 4.1% | Rising fresh specialty cheese imports and capacity modernization across Quebec and Ontario dairies |
| Germany | 3.9% | Record 26.4 kg per-capita cheese intake and strong household preference for herb Frischkase tubs |
Source: Future Market Insights analysis
South Korea Cream Cheese Market Outlook (2026 to 2036)
Specialty coffee-and-bagel cafes in Seoul and restaurant chains that stir mild dairy curds into spicy rice cakes and fried chicken sauces make South Korea a top growth market for imported cream cheese. According to the USDA Foreign Agricultural Service Dairy and Products Annual report for South Korea published in November 2025, total Korean cheese imports are forecast to reach 153,000 metric tons in 2026 as U.S. and European Union cheese tariffs drop to zero under free trade agreements [11]. South Korean cream cheese industry valuation is projected to expand by 5.8% per year through 2036. High local raw-milk farm costs still keep Korean bakeries reliant on imported 2-kilogram blocks.
Key takeaway: In South Korea, zero-tariff U.S. and EU dairy trade access and specialty bagel-cafe demand are projected to drive 5.8% yearly growth.
Brazil Cream Cheese Market Outlook (2026 to 2036)
Heavy foodservice use of firm cream cheese in Japanese-Brazilian temaki sushi rolls and stuffed-crust pizzas as well as bakery desserts sets Brazil apart from breakfast-only markets. In its December 2025 Brazil Dairy and Products Annual report, the USDA Foreign Agricultural Service noted that high 2025 domestic farmgate milk prices compared with Mercosur neighbors continue to encourage competitive dairy imports and local creamery upgrades [12]. Brazilian cream cheese market value is forecast to grow at a 5.6% compound annual rate between 2026 and 2036 across chilled supermarket tubs and 1.2-kilogram foodservice piping bags. Local processors still face inland cold-chain bottlenecks and price competition from starch-extended requeijao spreads.
Key takeaway: In Brazil, high-volume sushi and pizzeria foodservice piping bags and retail tub demand are expected to sustain 5.6% annual growth.
Saudi Arabia Cream Cheese Market Outlook (2026 to 2036)
Daily family consumption of spreadable breakfast cheeses on warm flatbreads and fast growth of international coffee and cheesecake chains make Saudi Arabia the fastest-growing Middle Eastern market. An August 2026 Saudi Arabia Retail Foods Annual report by the USDA Foreign Agricultural Service showed that the Kingdom's grocery retail sector grew to about USD 57 billion in 2025, while local dairies import bulk cheese blocks for repacking into retail jars and tubs [13]. Saudi Arabian cream cheese market valuation is expected to rise by 5.5% annually through 2036. Strict Saudi Food and Drug Authority shelf-life and Arabic nutrition-labeling rules favor global dairy co-operatives with regional GCC repacking plants.
Key takeaway: In Saudi Arabia, USD 57 billion grocery retail expansion and local repacking of imported bulk curds are forecast to power 5.5% annual growth.
USA Cream Cheese Market Outlook (2026 to 2036)
Morning bagel-shop habits and fourth-quarter holiday cheesecake baking keep the United States as the world's largest producer and consumer of cream cheese and Neufchatel. In April 2026, the USDA National Agricultural Statistics Service published its Dairy Products 2025 Summary showing steady 2025 commercial output across U.S. plants making cream cheese and Neufchatel curds after federal milk marketing order price updates [14]. Domestic cream cheese market value in the USA is projected to progress at 4.2% per annum over the ten-year horizon to 2036. Because most U.S. households already buy the category, dairy processors focus on whipped flavored tubs and lactose-free bricks plus thaw-and-serve frozen cheesecakes to lift category valuation.
Key takeaway: In the USA, steady bagel foodservice demand and value-added lactose-free and dessert launches are anticipated to support 4.2% yearly expansion.
Canada Cream Cheese Market Outlook (2026 to 2036)
Canada runs under a federal dairy supply-management system where domestic creameries in Quebec and Ontario supply grocery chains while tariff-rate quotas govern specialty imports. In September 2026, Agriculture and Agri-Food Canada reported in its Cheese Sector Profile that Canadian natural cheese output reached 515,033 metric tonnes in 2025 while fresh cheese imports rose from 2,585 metric tonnes in 2021 to 8,614 metric tonnes in 2025 [15]. Canadian cream cheese market size is slated to advance by 4.1% per year through 2036 as urban households buy whipped herb tubs and bagel spreads. Local dairies offset regulated raw-milk prices by automating tub filling and adding lactose-free SKUs.
Key takeaway: In Canada, rising fresh-cheese intake and automated domestic creamery lines are predicted to anchor a 4.1% annual growth rate.
Germany Cream Cheese Market Outlook (2026 to 2036)
Evening bread meals (Abendbrot) and strong shopper demand for herb and horseradish Frischkase tubs make Germany the largest cream cheese market in Western Europe. In April 2026, the German Dairy Industry Association (Milchindustrie-Verband) reported that per-capita cheese intake in Germany rose by 900 grams during 2025 to reach 26.4 kilograms, with local dairies producing 2.76 million tonnes of cheese and Frischkase ranking among the top four varieties [16]. German cream cheese industry valuation is anticipated to increase by 3.9% per year up to 2036 across discount and full-line supermarkets. Tough private-label price competition at Aldi and Lidl pushes branded dairies toward pasture-milk and high-protein skyr spreads.
Key takeaway: In Germany, 26.4-kilogram per-capita cheese intake paired with evening Abendbrot bread-spread habits anchors a 3.9% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the cream cheese market?
The Kraft Heinz Company, Savencia Fromage & Dairy, Arla Foods amba, Bel Group, Saputo Inc., Fonterra Co-operative Group Limited, Franklin Foods, Inc., Schreiber Foods, Inc., and Groupe Lactalis are the notable companies in the cream cheese market.
Competitive positioning in the global cream cheese industry is split between multinational retail brand owners and export-focused dairy co-operatives as well as private-label and industrial bakery processors. Branded consumer groups lead supermarket dairy walls through whipped tubs and herb portions as well as ready-to-use frosting tubs. Meanwhile, international dairy co-operatives and private-label specialists supply 2-kilogram to 10-kilogram foodservice blocks and pails to bagel chains and cheesecake bakeries.
- Global Branded Retail & Spreadable Cream Cheese Leaders: The Kraft Heinz Company and Bel Group as well as Savencia Fromage & Dairy lead retail dairy aisles through Philadelphia and Kiri plus the Boursin and Elle & Vire brands.
- Integrated Dairy Co-operatives & Multi-Region Cheese Processors: Arla Foods amba and Fonterra Co-operative Group Limited in addition to Saputo Inc. turn cooperative milk pools into retail tubs and Anchor Food Professionals and Arla Pro bakery blocks.
- Private-Label & Industrial Bakery Cultured Dairy Specialists: Schreiber Foods and Franklin Foods plus Groupe Lactalis supply supermarket private-label tubs and industrial cheesecake loaves as well as global consumer dairy brands.
Competitive Benchmarking: Cream Cheese Market
Table 8: Competitive Benchmarking for the Cream Cheese Market (qualitative capability ratings), 2026
| Company | Retail & Flavored Tub Breadth | Bakery & Foodservice Block Scale | Ultrafiltration & Starter R&D | Geographic Reach |
|---|---|---|---|---|
| The Kraft Heinz Company | High | High | High | High |
| Savencia Fromage & Dairy | High | High | High | High |
| Arla Foods amba | High | High | High | High |
| Bel Group | High | Medium | High | High |
| Saputo Inc. | Medium | High | Medium | High |
| Fonterra Co-operative Group Limited | Medium | High | High | High |
| Franklin Foods, Inc. | Medium | Medium | Medium | Medium |
| Schreiber Foods, Inc. | High | High | Medium | High |
| Groupe Lactalis | High | High | High | High |
Scoring basis: Capability ratings reflect product coverage across whipped retail tubs and foil bricks as well as bulk bakery pails and ultrafiltration curd yield. Geographic scores reflect multi-region cold-chain distribution across the Americas and Europe in addition to the Middle East and Asia-Pacific.
Key Developments in the Cream Cheese Market
- The Kraft Heinz Company announced a new global operating structure taking effect in July 2026 across North America, Europe & Pacific Developed Markets, and Emerging Markets to speed up growth in core brands including Philadelphia cream cheese [17].
- Fonterra Co-operative Group Limited reported strong HY26 financial results in March 2026 with NZD 13.9 billion in revenue and a 12.6% return on capital in Foodservice while advancing the NZD 4.22 billion sale of Mainland Group to Groupe Lactalis [18].
- Savencia Fromage & Dairy confirmed the integration of Savencia Gourmet into its premium foodservice division in September 2025 while expanding Elle & Vire Professionnel cream cheese and culinary cream supply across Asian and European bakeries [19].
Key Players in the Cream Cheese Market
Global Branded Retail & Spreadable Cream Cheese Leaders
- The Kraft Heinz Company
- Bel Group
- Savencia Fromage & Dairy
Integrated Dairy Co-operatives & Multi-Region Cheese Processors
- Arla Foods amba
- Fonterra Co-operative Group Limited
- Saputo Inc.
Private-Label, Industrial Bakery & Foodservice Cultured Dairy Specialists
- Schreiber Foods, Inc.
- Franklin Foods, Inc.
- Groupe Lactalis
Cream Cheese Market - Report Scope
Table 9: Report Scope for the Cream Cheese Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Fat Content; Flavor; End Use; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial dairy industry valuation from unripened, lactic-acid-coagulated cream cheese, Neufchatel, whipped cream cheese tubs, foil bricks, and foodservice pails. Category Scope Note: Excludes aged rennet-coagulated hard cheeses, liquid fluid milk and UHT whipping cream sold separately, uncultured butter, and 100% non-dairy vegan spreads. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Brazil, Saudi Arabia, USA, Canada, Germany, and additional countries in the full report |
| Key Companies Covered | The Kraft Heinz Company, Savencia Fromage & Dairy, Arla Foods amba, Bel Group, Saputo Inc., Fonterra Co-operative Group Limited, Franklin Foods, Inc., Schreiber Foods, Inc., Groupe Lactalis |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Cream Cheese Market - Research Methodology
Table 10: Research Methodology for the Cream Cheese Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with cooperative creamery plant directors, dairy rheology formulators, commercial bakery R&D chefs, and supermarket dairy category managers to validate curd yields and channel shares. |
| Secondary Research | Analysis of corporate annual filings, USDA NASS and FAS dairy reports, Agriculture and Agri-Food Canada and German MIV cheese statistics, and peer-reviewed dairy science literature. |
| Market Sizing and Forecasting | Top-down retail and foodservice cultured dairy valuation models reconciled against bottom-up creamery curd tonnage and milkfat allocation from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight bilateral cheese tariff phase-outs, bakery-cafe outlet growth, and per-capita fresh cheese intake across South Korea, Brazil, Saudi Arabia, the USA, Canada, and Germany. |
| Operational Benchmark Traceability | Curd tonnage, milkfat standardization, and channel valuation indicators in Tables 2, 3, and 4 trace to USDA NASS Dairy Products summaries, AAFC Canada profiles, MIV Germany registries, and corporate disclosures. |
| Data Triangulation and Validation | Market value estimates are cross-checked against milk-solids allocation and retail scanner volume without double counting fluid whipping cream or aged natural cheddar and mozzarella. |
Cream Cheese Market by Segments
Cream Cheese Market segmented by Product Form:
- Spreadable Whipped & Soft Tubs
- Foil-Wrapped Baking Bricks/Blocks
- Bulk Foodservice Pails
Cream Cheese Market segmented by Fat Content:
- Regular Full-Fat
- Neufchatel / Reduced-Fat
- Whipped & Lactose-Free
Cream Cheese Market segmented by Flavor:
- Plain Original
- Savory Herb, Chive & Garlic
- Sweet Berry & Honey
Cream Cheese Market segmented by End Use:
- Retail Household Breakfast
- Commercial Cheesecake & Bakery
- Bagel Cafes & Sushi Foodservice
Cream Cheese Market segmented by Distribution Channel:
- Supermarkets & Retail Dairy Aisles
- Commercial Foodservice & Bagel Chains
- Industrial Bakery & Cheesecake Processors
Cream Cheese Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- Saudi Arabia
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Jaeger, S. R., Chheang, S. L., & Schouteten, J. J. (2025, January 29). Consumer Expectations for Cream Cheese: A Category Appraisal Study in the United Kingdom with Dairy and Plant-Based Variants in Various Flavours. Foods, 14(3), 445 (PMC11816490).
- [2] Zhang, F., Gu, Y., Guo, Y., Aaqil, M., Huang, X., Zheng, J., Shi, Z., Tian, Y., Zhuang, L., & Zhao, C. (2025, July 7). Process optimization and flavor characteristics of cream cheese fermented with avocado co-cultures. Food Chemistry: X, 29, 102745 (PMC12275123).
- [3] Arla Foods amba. (2026, February 18). Arla Foods posts strong results in a record year. Arla Foods News & Press.
- [4] Eugenio, A., Ramos, R., Barreto, I. R., Carrico, R., Marcos, J., Camelo, A., Espirito Santo, C., & Brandao, I. (2025, October 3). Cheese: mere indulgence or part of a healthy diet?. Frontiers in Nutrition, 12, 1649432 (PMC12531155).
- [5] The Kraft Heinz Company. (2025, October 7). Philadelphia Makes Holiday Hosting Sweeter With Its First-Ever Frozen Cheesecake and New Cinnamon Cream Cheese Frosting. The Kraft Heinz Company Newsroom.
- [6] Bel Group. (2026, May 6). Bel Group 2025 Annual Results Investor Presentation. Groupe Bel Financial Publications.
- [7] Saputo Inc. (2026, June 4). Saputo Reports Financial Results for the Fourth Quarter and Fiscal 2026. Saputo Newsroom.
- [8] Fonterra Co-operative Group Limited. (2026, July 28). Fonterra's Foodservice business. Fonterra Co-operative Group.
- [9] Leal, I., Correia, P., Lima, M., Machado, B., & de Souza, C. (2025, July 18). Cheese Analogues, an Alternative to Dietary Restrictions and Choices: The Current Scenario and Future. Foods, 14(14), 2522 (PMC12294849).
- [10] The Kraft Heinz Company. (2026, July 22). Philadelphia Brings Its Signature Cream Cheese to Millions More Consumers with New Lactose Free Innovation. The Kraft Heinz Company Newsroom.
- [11] USDA Foreign Agricultural Service. (2025, November 25). Dairy and Products Annual - Seoul ATO Republic of Korea (KS2025-0041). United States Department of Agriculture Foreign Agricultural Service.
- [12] USDA Foreign Agricultural Service. (2025, December 17). Dairy and Products Annual - Brasilia Brazil (BR2025-0042). United States Department of Agriculture Foreign Agricultural Service.
- [13] USDA Foreign Agricultural Service. (2026, August 31). Saudi Arabia: Retail Foods Annual. United States Department of Agriculture Foreign Agricultural Service.
- [14] USDA National Agricultural Statistics Service (NASS). (2026, April 24). Dairy Products 2025 Summary (April 2026). United States Department of Agriculture National Agricultural Statistics Service.
- [15] Agriculture and Agri-Food Canada (AAFC). (2026, September 4). Cheese sector profile. Government of Canada Canadian Dairy Information Centre.
- [16] Milchindustrie-Verband e.V. (MIV). (2026, April 24). Kase kommt gut an - Gouda bleibt auf Platz 1!. Milchindustrie-Verband e.V.
- [17] The Kraft Heinz Company. (2026, June 18). Kraft Heinz Announces New Global Operating Structure to Accelerate Growth. The Kraft Heinz Company Newsroom.
- [18] Fonterra Co-operative Group Limited. (2026, March 23). Fonterra delivers another strong result for HY26. Fonterra Media Releases.
- [19] Savencia SA. (2025, September 18). SAVENCIA SA Press Release: 2025 half-yearly results. Savencia Fromage & Dairy.
- [20] Schreiber Foods, Inc. (2026, April 27). Read Our 2026 Doing Good Through Food Story. Schreiber Foods.
- [21] Groupe Lactalis. (2025, October 15). Lactalis press release - 2025 Annual Results. Groupe Lactalis Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the cream cheese market in 2026 and what is forecast for 2036?
- Which bakery foodservice and breakfast pressures support demand for cream cheese?
- Why do Spreadable Whipped & Soft Tubs lead the product form category?
- Why does Regular Full-Fat lead the fat content category globally?
- How do growth rates differ across South Korea, Brazil, Saudi Arabia, the USA, Canada, and Germany?
- Which leading companies manufacture and distribute cream cheese products today?
- What limits adoption or supplier switching in the cream cheese market?
- What should bakery and retail buyers evaluate before purchasing cream cheese?
Frequently Asked Questions
How big is the cream cheese market in 2026, and what is forecast for 2036?
Worldwide cream cheese industry valuation stands at USD 8.2 billion in 2026 (up from a market size of USD 7.8 billion in 2025) and is predicted to reach USD 13.0 billion by 2036 as household bagel consumption and Asian bakery-cafe menus expand.
What is the CAGR for the cream cheese market from 2026 to 2036?
As per FMI, global cream cheese market value is projected to compound at 4.7% annually from 2026 to 2036, yielding a USD 4.8 billion expansion in overall industry valuation across retail and foodservice channels.
Which product form segment leads the cream cheese market?
Spreadable Whipped & Soft Tubs are slated to hold 52.1% of product form volume in 2026 because nitrogen-whipped curds in reclosable tubs spread immediately at refrigerator temperatures.
Which fat content segment leads the cream cheese market?
Regular Full-Fat formulations are predicted to capture 53.9% of fat content market value in 2026 since minimum 33% milkfat emulsions prevent cracking and whey separation in baked cheesecakes.
Which country has a notable growth outlook during the assessment period?
FMI finds that South Korea paces analyzed countries with a 5.8% CAGR through 2036, supported by duty-free U.S. and EU cheese import quotas and specialty cafe cheesecake demand.
Who are the key players in the market?
The Kraft Heinz Company, Savencia Fromage & Dairy, Arla Foods amba, Bel Group, Saputo Inc., Fonterra Co-operative Group Limited, Franklin Foods, Inc., Schreiber Foods, Inc., and Groupe Lactalis supply retail dairy walls and commercial bakery commissaries.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Spreadable Whipped & Soft Tubs
- Foil-Wrapped Baking Bricks/Blocks
- Bulk Foodservice Pails
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Fat Content, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fat Content, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fat Content, 2026 to 2036
- Regular Full-Fat
- Neufchatel / Reduced-Fat
- Whipped & Lactose-Free
- Y-o-Y Growth Trend Analysis By Fat Content, 2021 to 2025
- Absolute $ Opportunity Analysis By Fat Content, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor, 2026 to 2036
- Plain Original
- Savory Herb, Chive & Garlic
- Sweet Berry & Honey
- Y-o-Y Growth Trend Analysis By Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Retail Household Breakfast
- Commercial Cheesecake & Bakery
- Bagel Cafes & Sushi Foodservice
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Retail Dairy Aisles
- Commercial Foodservice & Bagel Chains
- Industrial Bakery & Cheesecake Processors
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- Saudi Arabia
- South Africa
- Turkiye
- Israel
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Fat Content
- By Flavor
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Kraft Heinz Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Savencia Fromage & Dairy
- Arla Foods amba
- Bel Group
- Saputo Inc.
- Fonterra Co-operative Group Limited
- Franklin Foods, Inc.
- Schreiber Foods, Inc.
- Groupe Lactalis
- The Kraft Heinz Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


