

- Market Size (2026)
- USD 8.4 Bn
- Forecast (2036)
- USD 15.2 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Encapsulated Flavors and Fragrances Market in 2026?
USD 8.4 Billion in 2026 and USD 15.2 Billion by 2036, expanding at 6.2% CAGR.
Demand for encapsulated flavors and fragrances is projected to expand at 6.2% CAGR between 2026 and 2036, growing from USD 7.9 Billion in 2025 to USD 8.4 Billion in 2026 and reaching USD 15.2 Billion by 2036. A Food Chemistry review published in June 2026 identified spray drying as the most widely used and scalable approach for food flavor encapsulation. The commercial value comes from protecting volatile compounds against heat, moisture and oxidation while giving manufacturers greater control over release during processing, storage or consumption.
The growth mechanism differs by country. Germany combines a large processed-food manufacturing base with reformulation requirements in consumer goods, while South Korea adds a substantial export-oriented cosmetics sector. The USA benefits from local flavor-development and application infrastructure, while Japan and the UK place a premium on documentation and formulation compliance. Similar stability and formulation requirements are shaping the broader , particularly where manufacturers need consistent sensory performance across industrial production runs.
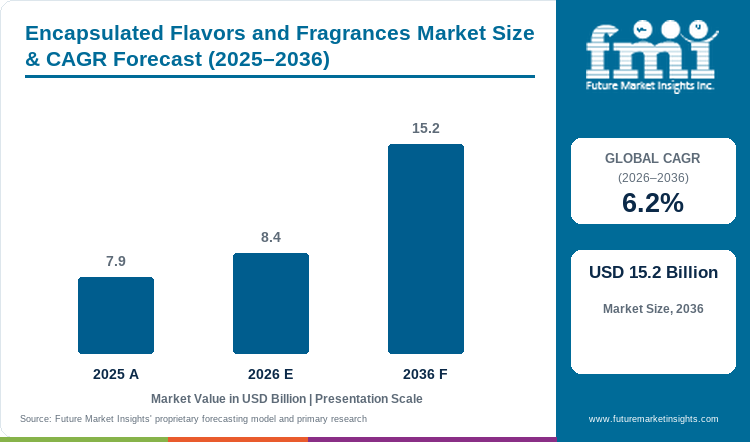
Key Takeaways of Encapsulated Flavors and Fragrances Market
- Demand is driven by the need to protect volatile flavor and fragrance compounds and release them at a controlled point during processing, storage or use.
- Powder leads Encapsulated Form with a 58.9% share in 2026 because it supports dry handling, dosing efficiency and broad compatibility with industrial formulations.
- Micro-encapsulation leads Process with a 71.3% share in 2026 because it combines protective shell design with controlled release and established industrial processing.
- Qualification remains a major purchasing constraint because buyers must test release timing, wall-core compatibility, processing stability and regulatory fit before switching systems.
- Key companies include Givaudan SA, International Flavors & Fragrances, dsm-firmenich, Symrise AG, Sensient Technologies, Takasago International, Balchem Corporation, Kerry Group, T. Hasegawa Co. and Robertet Group.
Analyst Perspective
“Encapsulation creates value when a supplier can reproduce the intended sensory profile inside the customer’s actual process, not only under laboratory conditions. Buyers will increasingly compare release control, processing stability and cost-in-use before moving a formulation into repeat production.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Encapsulated Flavors and Fragrances Market segmented?
Encapsulated Flavors and Fragrances Market is segmented by Encapsulated Form, End Use, Process, Product Type, Technology, Wall Material, and Region.
Encapsulated Form comprises Powder, Granules and Paste. End Use comprises Food and Beverage and Consumer Goods. Process includes Micro-encapsulation, Hybrid-encapsulation, Nano-encapsulation and Macro-encapsulation. Product Type covers Flavor Blends, Fragrance Blends, Essential Oils & Natural Extracts and Aroma Chemicals. Technology is split between Mechanical and Chemical. Wall Material includes Maltodextrin (DE<20), Modified starch, Gelatin, Others, Gum Arabic, Hydrogenated fat, Whey protein and Modified cellulose.
Why does powder lead demand within the encapsulated form category?
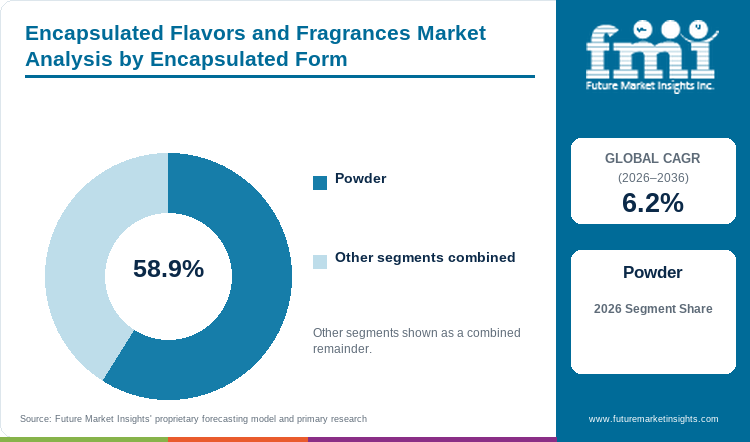
Powder formats fit established dry-blending and dosing operations. Spray drying converts unstable liquid aroma systems into free-flowing particles while reducing direct exposure to oxygen and moisture. Powders are also straightforward to weigh into premixes and dry formulations. These operating advantages extend across the wider , where handling stability is an important part of the buyer's formulation decision.
- Powder represents 58.9% of Encapsulated Form demand in 2026, reflecting its convenient handling, transport efficiency, and compatibility with established industrial processes.
- A June 2026 review in Food Chemistry identified spray drying as the most widely used and scalable food flavor encapsulation technique, highlighting the commercial relevance of free-flowing powder formats.
Why does food and beverage lead demand within the end use category?
Food and beverage processing can expose aroma compounds to heat, oxygen, moisture and extended storage periods. Encapsulation separates the sensitive core from these conditions until the intended release point. Consumer goods also use controlled fragrance delivery, but food applications span a wider set of everyday formulation requirements where aroma stability directly influences product acceptance.
- Food and Beverage captures 66.8% of End Use demand in 2026, with encapsulation helping preserve taste and aroma through manufacturing, storage, and shelf life.
- Germany's Federal Statistical Office reported in January 2026 that 1.7 million tonnes of ready meals were produced in the country during 2024, illustrating the scale of processed-food manufacturing that relies on consistent flavor performance.
Why does micro-encapsulation lead demand within the process category?
Micro-encapsulation surrounds droplets or particles with a functional barrier that can protect the core and release it under selected conditions. The process serves both food-flavor and consumer-fragrance applications without requiring the very small particle structures associated with nano systems. Its balance between protection, release control and production practicality also connects directly with developments in the wider .
- Micro-encapsulation accounts for 71.3% of Process demand in 2026, as established production methods allow manufacturers to tailor shell chemistry and release characteristics.
- Givaudan's July 2026 strategic collaboration with Microcaps AG illustrates continued commercial investment in precision microencapsulation for fragrance delivery applications.
Why do flavor blends lead demand within the product type category?
Flavor blends allow formulators to combine top notes, base notes and supporting sensory components inside one delivery system. Encapsulation then protects the combined profile rather than requiring the manufacturer to manage several aroma components separately. The same development logic is visible across the , where manufacturers increasingly need complex flavor systems that can retain their intended character through processing.
- Flavor Blends account for 55.1% of Product Type demand in 2026, as integrated sensory profiles simplify formulation and facilitate application development.
- Kerry Group's January 2026 Taste Charts initiative combined trend analysis with flavor sampling and technical support, highlighting the role of rapid blend development and application testing.
Why does mechanical lead demand within the technology category?
Mechanical routes such as spray drying and granulation use physical processing to convert a prepared emulsion or matrix into a stable delivery format. These methods can link particle design with high-throughput manufacturing and are already familiar to industrial ingredient producers. Chemical routes remain important where reaction-driven shell formation is needed for specialized delivery requirements.
- Mechanical technology represents 79.2% of Technology demand in 2026, reflecting the established throughput and process integration offered by drying and particle-engineering methods.
- A June 2026 review in Food Chemistry identified spray drying as the most widely used and scalable technique for food flavor encapsulation, reinforcing the commercial role of mechanical processing.
Why does maltodextrin (DE<20) lead demand within the wall material category?
Maltodextrin provides a carbohydrate matrix that can be processed at useful solids levels without imposing excessive viscosity. This makes it suitable for high-throughput spray-drying systems where the wall must protect volatile compounds while remaining economical at scale. Similar carrier functionality shapes purchasing across the wider , particularly in food applications that require bulking, carrier and drying performance.
- Maltodextrin (DE<20) makes up 24.3% of Wall Material demand in 2026, supported by its processing flexibility and cost-performance profile in high-volume flavor encapsulation.
- Wall-material selection remains closely tied to retention and controlled release, keeping maltodextrin relevant for manufacturers seeking a familiar carbohydrate carrier with consistent processing characteristics.
What are the drivers, restraints and opportunities in the Encapsulated Flavors and Fragrances Market?
Protection of volatile sensory compounds drives demand, qualification requirements slow supplier switching, and biodegradable wall systems create opportunities for reformulation.
- Driver: Food and consumer-goods manufacturers need flavor and fragrance systems that retain performance through heat, oxygen exposure, moisture and shelf life.
- Restraint: Buyers must validate release behavior, processing stability and regulatory fit before replacing an established delivery system.
- Opportunity: Biodegradable capsule technologies and fit-for-purpose wall systems can capture reformulation demand in fragrance and other consumer-goods applications.
Why does process stability drive encapsulation demand?
Flavor and fragrance compounds can lose intensity or change character when exposed to heat, oxygen and moisture. The June 2026 Food Chemistry review linked flavor volatility and chemical reactivity with aroma loss and highlighted encapsulation as a route to greater stability and controlled release. Food processors and consumer-goods manufacturers therefore purchase encapsulated systems to protect the intended sensory profile through their production and storage conditions.
Why does qualification slow supplier switching?
An alternative capsule must survive mixing, drying, filling and storage while releasing at the correct stage without creating unwanted changes in texture or sensory intensity. Fragrance customers also face increasing pressure to evaluate wall chemistry as sustainability and chemical requirements evolve. IFF's July 2025 launch of the biodegradable ENVIROCAP scent-delivery system reflects active reformulation around these purchasing requirements.
Where do biodegradable wall systems create opportunity?
Fragrance suppliers can redesign the capsule wall while preserving the commercial benefit of long-lasting scent. Givaudan's 2026 collaboration with Microcaps and IFF's 2025 ENVIROCAP launch show that suppliers are investing in alternative release architectures. The opportunity is strongest where a new system can match the release profile and manufacturing stability of the established formulation while giving customers a clearer route through changing sustainability requirements.
Which country CAGRs are profiled in the Encapsulated Flavors and Fragrances Market?
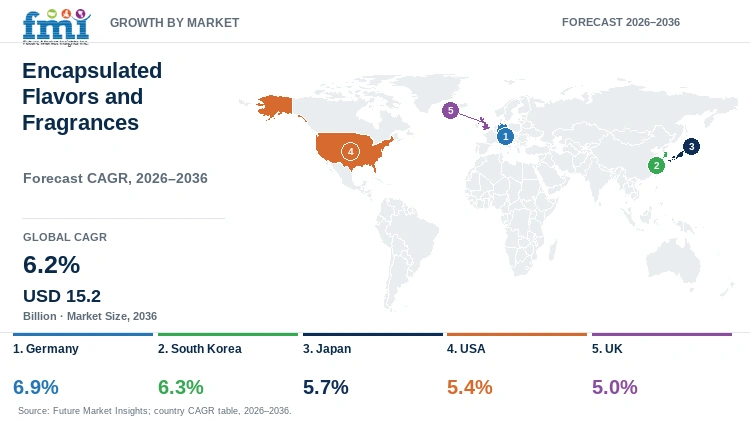
| Country | CAGR |
|---|---|
| Germany | 6.9% |
| South Korea | 6.3% |
| Japan | 5.7% |
| USA | 5.4% |
| UK | 5.0% |
How do country-level CAGRs compare in the Encapsulated Flavors and Fragrances Market?
Germany and South Korea form the faster-growth group at above 6%. Japan and the USA occupy the middle of the profiled range, while the UK records the lowest CAGR at 5.0%. The spread between Germany at 6.9% and the UK at 5.0% is 1.9 percentage points. These figures describe growth pace rather than absolute market size.
- Germany combines a large processed-food manufacturing base with consumer-goods reformulation requirements that support flavor and fragrance delivery systems.
- South Korea adds strong cosmetics manufacturing and export activity to its food formulation base, increasing demand for controlled sensory delivery.
- Japan rewards suppliers that combine local application support with clear documentation and reliable delivery performance.
- The USA combines large-scale food processing with local supplier production, R&D and application-development infrastructure.
- The UK requires food manufacturers to pay close attention to authorized flavorings and conditions of use during formulation and product approval.
Comparable growth rates can lead to different supplier strategies because each country has a different mix of processed foods, cosmetics, regulatory requirements and local technical support.
Country-wise Analysis
- Germany has the fastest profiled CAGR at 6.9% from 2026 to 2036. The Federal Statistical Office reported in January 2026 that Germany produced 1.7 million tonnes of ready meals in 2024, 25.6% more than in 2019. This manufacturing base creates recurring demand for flavor systems that remain stable through industrial processing and shelf life. Consumer-goods formulators create a second demand channel where fragrance capsules are being redesigned around changing material requirements. Suppliers therefore compete on both sensory performance and technical documentation.
- South Korea is profiled at a 6.3% CAGR from 2026 to 2036. The Ministry of Food and Drug Safety reported in May 2026 that cosmetics exports reached USD 11.4 billion during 2025, up 11.8% from the previous year. That export-oriented cosmetics base creates demand for fragrance systems that can maintain release performance while meeting the requirements of several destination markets. Food manufacturers create an additional route for flavor encapsulation, making local application support important across two different customer groups.
- Japan is forecast to expand at a 5.7% CAGR between 2026 and 2036. Supplier activity indicates continued technical interest in protected flavor delivery. At Hi Japan in October 2025, dsm-firmenich presented flavor delivery systems focused on protection and controlled release. Japanese buyers place strong emphasis on formulation detail, so suppliers that combine application testing with clear product documentation can reduce the time needed to move from a formulation concept to repeat production.
- The USA is profiled at a 5.4% CAGR from 2026 to 2036. The country has direct production and application infrastructure from major flavor and encapsulation suppliers. T. Hasegawa U.S.A. listed production and R&D operations in California and Illinois in its June 2025 locations update, while Balchem announced additional food microencapsulation capacity in New York during December 2025. These investments support faster sampling, application testing and scale-up for domestic food customers.
- The UK is forecast to grow at a 5.0% CAGR between 2026 and 2036. From April 2025, the Food Standards Agency and Food Standards Scotland registers became the primary source for flavoring authorizations in Great Britain. The system places permitted flavorings and conditions of use directly into the manufacturer's formulation workflow. Suppliers that can connect encapsulation performance with clear ingredient status and application documentation are better positioned to reduce procurement friction.
Who are the notable companies in the Encapsulated Flavors and Fragrances Market?
Givaudan SA, International Flavors & Fragrances, dsm-firmenich, Symrise AG, Sensient Technologies, Takasago International, Balchem Corporation, Kerry Group, T. Hasegawa Co. and Robertet Group are the notable companies profiled in the market.
Competition separates into three practical models. Integrated flavor and fragrance houses combine sensory creation with delivery technology, allowing them to design the core ingredient and the release system as part of the same customer brief. Food-focused specialists compete through powder systems, process knowledge and application support. Controlled-release specialists compete more directly on capsule engineering and manufacturing capability.
Scale alone does not determine the purchasing decision. Food customers evaluate whether the encapsulated system survives processing without losing aroma or changing texture. Consumer-goods buyers place greater emphasis on release duration, capsule-wall chemistry and sustainability requirements. Application laboratories and regional technical teams therefore influence repeat business alongside production capacity.
- Integrated flavor and fragrance platforms include Givaudan SA, International Flavors & Fragrances, dsm-firmenich, Symrise AG, Takasago International and Robertet Group.
- Food and beverage taste specialists include Sensient Technologies, Kerry Group and T. Hasegawa Co.
- Balchem Corporation competes strongly in controlled-release food microencapsulation.
Competitive Benchmarking: Encapsulated Flavors and Fragrances Market
| Company | Food Flavor Encapsulation | Fragrance Encapsulation | Application & Scale-up Support | Geographic Reach |
|---|---|---|---|---|
| Givaudan SA | High | High | High | Americas, Europe, Asia Pacific, Middle East and Africa |
| International Flavors & Fragrances | High | High | High | Greater Asia, Europe, Middle East and Africa, Latin America and North America |
| dsm-firmenich | High | High | High | Broad network across Europe, the Americas and Asia Pacific |
| Symrise AG | High | High | High | Global network with broad regional coverage |
| Sensient Technologies | Medium | Unscored | Medium | Americas, Europe and Asia Pacific |
| Takasago International | Unscored | High | High | Asia, Americas and Europe |
| Balchem Corporation | High | Unscored | Medium | North America, Europe and selected Asian locations |
| Kerry Group | High | Unscored | High | More than 30 countries across six continents |
| T. Hasegawa Co. | Medium | Medium | Medium | Japan, North America and multiple Asian markets |
| Robertet Group | Medium | Unscored | Medium | Europe, North America, Asia and other international markets |
Key Developments in the Encapsulated Flavors and Fragrances Market
- In July 2026, Givaudan SA announced an equity investment and strategic collaboration with Microcaps AG to strengthen fragrance encapsulation. The collaboration combines Givaudan's formulation expertise with precision microencapsulation and expands the company's range of release architectures for beauty and personal-care applications.
- In July 2025, International Flavors & Fragrances launched ENVIROCAP for fabric care. IFF positioned the biodegradable biopolymer system around long-lasting scent delivery and ECHA-aligned formulation requirements. The launch directly addresses consumer-goods customers that need to maintain fragrance performance while changing capsule materials.
- In December 2025, Balchem Corporation announced a new high-capacity food microencapsulation facility in Orange County, New York. The plant is expected to open in 2027 and expand capacity for BakeShure, ConfecShure and MeatShure products. The investment increases future production capacity for controlled-release food ingredients and gives qualified formulations an additional domestic supply route.
Key Players in the Encapsulated Flavors and Fragrances Market
Integrated Flavor and Fragrance Delivery Platforms
- Givaudan SA
- International Flavors & Fragrances
- dsm-firmenich
- Symrise AG
- Takasago International
- Robertet Group
Food and Beverage Taste Delivery Specialists
- Sensient Technologies
- Kerry Group
- T. Hasegawa Co.
Controlled-Release Encapsulation Specialist
- Balchem Corporation
Encapsulated Flavors and Fragrances Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Encapsulated Form, End Use, Process, Product Type, Technology, Wall Material, and Region |
| Quantitative Units | Revenue in USD Billion and CAGR in %. |
| Market Definition | Includes B2B revenue from encapsulated flavor and fragrance preparations sold within the stated form, end-use, process, product-type, technology and wall-material categories. Downstream finished-product revenue, unencapsulated flavor or fragrance ingredients, standalone encapsulation equipment and unrelated encapsulated actives are outside the market scope. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | USA, UK, Germany, Japan, South Korea |
| Key Companies Profiled | Givaudan SA, International Flavors & Fragrances, dsm-firmenich, Symrise AG, Sensient Technologies, Takasago International, Balchem Corporation, Kerry Group, T. Hasegawa Co., Robertet Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Encapsulated Flavors and Fragrances Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, ingredient suppliers, technology developers, distributors, end users, procurement teams and subject-matter experts. Interviews covered purchasing requirements, application performance, approval criteria, pricing and technical support. |
| Desk Research | Desk research covered government statistics, regulatory publications, technical literature, company filings, product information and corporate announcements relevant to flavor and fragrance encapsulation. |
| Market Sizing and Forecasting | Market sizing considered the baseline market value, segment structure, pricing, adoption levels, company activity and country-level demand conditions. Forecast assumptions incorporated manufacturing activity, formulation trends, regulation, technology adoption and purchasing cycles. |
| Data Validation | Market estimates were compared with independent indicators including company activity, processing trends, regulatory developments and primary research findings before segment and regional values were aligned with the market total. |
Encapsulated Flavors and Fragrances Market by Segments
Encapsulated Flavors and Fragrances Market segmented by Encapsulated Form:
- Powder
- Granules
- Paste
Encapsulated Flavors and Fragrances Market segmented by End Use:
- Food and Beverage
- Consumer Goods
Encapsulated Flavors and Fragrances Market segmented by Process:
- Micro-encapsulation
- Hybrid-encapsulation
- Nano-encapsulation
- Macro-encapsulation
Encapsulated Flavors and Fragrances Market segmented by Product Type:
- Flavor Blends
- Fragrance Blends
- Essential Oils & Natural Extracts
- Aroma Chemicals
Encapsulated Flavors and Fragrances Market segmented by Technology:
- Mechanical
- Chemical
Encapsulated Flavors and Fragrances Market segmented by Wall Material:
- Maltodextrin (DE<20)
- Modified starch
- Gelatin
- Others
- Gum Arabic
- Hydrogenated fat
- Whey protein
- Modified cellulose
Encapsulated Flavors and Fragrances Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Weng, Y., Serrano, T., Magallanes, K., Bekker, M., and Baldelli, A. (2026, June 1). Locking in flavor: Aroma chemistry and spray drying encapsulation strategies for stable food applications. Food Chemistry.
- Federal Statistical Office of Germany (2026, January 14). Convenience food production in Germany: 1.7 million tonnes of ready meals in 2024.
- Ministry of Food and Drug Safety, Republic of Korea (2026, May 28). 2025 cosmetics trade surplus surpasses USD 10 billion and Korea becomes the world's second-largest cosmetics exporter.
- Food Standards Agency and Food Standards Scotland (2025). Register of Flavouring Authorisations for Great Britain.
- dsm-firmenich (2025, October 15). Meet dsm-firmenich at Hi Japan 2025.
- Givaudan SA (2026, July 7). Givaudan announces strategic collaboration with Microcaps.
- International Flavors & Fragrances (2025, July 24). IFF introduces ENVIROCAP, a biodegradable scent delivery technology for fabric care.
- International Flavors & Fragrances (2025, April 1). IFF Introduces Science of Performance: A New Approach to Elevating Scent Design.
- Takasago International (2025, May 1). Takasago Opens Taste Innovation Centre in Bengaluru, India.
- Balchem Corporation (2025, December 10). Balchem Announces New Microencapsulation Manufacturing Facility.
- Kerry Group (2026, January 14). Kerry Releases 2026 Global Taste Charts: Defining the Future of Flavour with Data-Rich Insights.
- T. Hasegawa U.S.A. (2025, June 30). Locations and U.S. production and R&D operations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the Encapsulated Flavors and Fragrances Market in 2026 and what value is forecast for 2036?
- Which commercial pressures support demand for encapsulated flavor and fragrance delivery systems?
- Why does Powder lead the Encapsulated Form category?
- Why does Food and Beverage lead the End Use category?
- Why does Micro-encapsulation lead the Process category?
- How do profiled country growth rates differ from 2026 to 2036?
- Which companies supply flavor and fragrance encapsulation capabilities?
- What should buyers evaluate before selecting an encapsulated flavor or fragrance system?
Frequently Asked Questions
How big is the Encapsulated Flavors and Fragrances Market in 2026, and what is forecast for 2036?
The market is valued at USD 8.4 Billion in 2026 and is forecast to reach USD 15.2 Billion by 2036. Growth reflects continued investment in sensory protection and controlled-release systems across food and consumer-goods applications.
What is the CAGR of the Encapsulated Flavors and Fragrances Market from 2026 to 2036?
The market is forecast to expand at a 6.2% CAGR from 2026 to 2036. Growth depends on the ability of encapsulated systems to retain flavor or fragrance performance under commercial processing and storage conditions.
Which segment leads Encapsulated Form in 2026?
Powder leads Encapsulated Form with a 58.9% share in 2026. Dry handling, storage stability and compatibility with spray-dried systems support its use in high-volume manufacturing.
Which segment leads End Use in 2026?
Food and Beverage leads End Use with a 66.8% share in 2026. Manufacturers use encapsulation to protect aroma through processing, moisture exposure and shelf life.
Which profiled countries record the highest growth rates?
Germany has the highest profiled CAGR at 6.9%, followed by South Korea at 6.3% and Japan at 5.7%. These figures compare growth pace and do not represent absolute market-size rankings.
Which companies are active in the Encapsulated Flavors and Fragrances Market?
Key companies include Givaudan SA, International Flavors & Fragrances, dsm-firmenich, Symrise AG, Sensient Technologies, Takasago International, Balchem Corporation, Kerry Group, T. Hasegawa Co. and Robertet Group. Their commercial positions range from integrated taste and scent delivery to food-focused controlled-release systems.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Encapsulated Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Encapsulated Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Encapsulated Form, 2026 to 2036
- Powder
- Granules
- Paste
- Powder
- Y-o-Y Growth Trend Analysis By Encapsulated Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Encapsulated Form, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Food and Beverage
- Consumer Goods
- Food and Beverage
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Process, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Process, 2026 to 2036
- Micro-encapsulation
- Hybrid-encapsulation
- Nano-encapsulation
- Macro-encapsulation
- Micro-encapsulation
- Y-o-Y Growth Trend Analysis By Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Process, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Mechanical
- Chemical
- Mechanical
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Wall Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wall Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wall Material, 2026 to 2036
- Maltodextrin (DE<20)
- Modified starch
- Gelatin
- Others
- Gum Arabic
- Hydrogenated fat
- Whey protein
- Modified cellulose
- Maltodextrin (DE<20)
- Y-o-Y Growth Trend Analysis By Wall Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Wall Material, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- By Country
- Market Attractiveness Analysis
- By Country
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Encapsulated Form
- By End Use
- By Process
- By Technology
- By Wall Material
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Givaudan SA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- International Flavors & Fragrances
- Symrise AG
- Sensient Technologies
- Takasago International
- Balchem Corporation
- Kerry Group
- T. Hasegawa Co.
- Robertet Group
- Food and Beverage Taste Delivery Specialists
- Givaudan SA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


