

- Market Size (2026)
- USD 46.6 Bn
- Forecast (2036)
- USD 72.3 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Gas Turbine Market in 2026?
Demand is projected to expand at 4.5% CAGR from 2026 to 2036. Market value rises from USD 44.6 billion in 2025 to USD 46.6 billion in 2026 and USD 72.3 billion by 2036.
The global gas turbine market spans equipment for power generation, industrial installations, oil and gas, and aviation, with separate product, capacity, technology and fuel categories. Market value rises from USD 44.6 billion in 2025 to an estimated USD 46.6 billion in 2026 and a projected USD 72.3 billion by 2036, at a CAGR of 4.5% from 2026 to 2036. Heavy Duty Gas Turbines represent 48.0% of product demand in 2026, while natural gas accounts for 72.0% of fuel-type demand, making generating duty and fuel economics central commercial considerations.
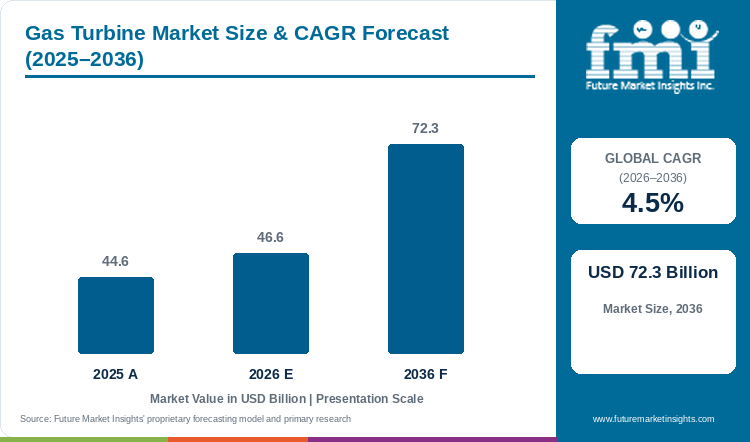
New generating projects and equipment renewal underpin demand, with fuel supply, dispatch requirements and maintenance shaping investment. IEA's Gas 2025 examines supply, infrastructure and affordability through 2030, providing context for the power sector's fuel requirements. [3] Technical and regulatory developments address other parts of the project: NETL's February 2025 modelling investigates environmental barrier-coating damage under thermal cycling, while EPA's January 2026 final-rule analysis sets out equipment-category and timing considerations for stationary turbines. [1][2] Durability research and project-specific emissions requirements consequently inform different parts of the specification, alongside commissioning and the support needed during outages.
The European Union regional aggregate has the highest profiled CAGR at 4.7% for 2026 to 2036, followed by South Korea at 4.6%, the UK at 4.4%, the USA at 4.3% and Japan at 4.2%. Ireland's official 2025 electricity data identify gas as its largest generation fuel, illustrating one national operating base within the EU. [4] The regional forecast covers a broader set of markets and generating conditions.
General Electric Company, Siemens Energy AG, Mitsubishi Power Ltd., Ansaldo Energia S.p.A. and Kawasaki Heavy Industries Ltd. are representative equipment participants. Competition centres on the complete generating proposition: performance under the intended load and fuel conditions, commissioning, emissions equipment and continuing maintenance. Existing plants add replacement interfaces and outage windows to that comparison. Suppliers that define these commitments clearly can help owners assess the equipment alongside the cost and practical requirements of keeping the plant available for its intended dispatch role.
Key Market Trends & Insights
- Hot-section durability remains a research subject; simulation outcomes do not establish commercial service-life gains. [1]
- Stationary-turbine requirements depend on the equipment category and project timing, rather than one emissions limit for all machines. [2]
- Fuel affordability and infrastructure influence the operating case alongside the turbine specification. [3]
Regional Highlights
- The European Union is the leading profiled regional aggregate at 4.7% for 2026 to 2036, followed by South Korea at 4.6%.
- The UK, USA and Japan are profiled at 4.4%, 4.3% and 4.2% respectively over the same period.
- Ireland’s official 2025 electricity data provide one national example of gas-fired generation within the EU; they do not represent the whole region’s turbine-sales mix. [4]
Market Size & Forecast
Table 1: Market Size and Forecast for Gas Turbine Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 44.6 billion |
| 2026 market value | USD 46.6 billion |
| 2036 market value | USD 72.3 billion |
| CAGR 2026 to 2036 | 4.5% |
| Revenue increase 2026 to 2036 | USD 25.7 billion |
| Market expansion 2026 to 2036 | 1.55 times |
New generating projects and equipment replacement create different purchasing programmes. A new plant must coordinate the turbine with fuel supply, grid connection and the rest of the generating installation; a replacement starts with an existing site and its operating constraints. Both need a credible maintenance arrangement and a clear account of the output and emissions conditions behind the offer. Fuel-market changes can alter the commercial case without changing the machine’s nominal rating. That makes the ownership comparison broader than acquisition price, especially where the customer’s revenue depends on when and how the unit is dispatched.
The Micro Gas Turbine Market covers another scale of equipment whose operating and purchasing conditions can differ from larger generating units.
Dispatch, durability and fuel supply shape the equipment decision
The same rated output can serve very different operating programmes. A customer needs to know how the turbine and supporting equipment will perform under the intended load and maintenance schedule. NETL’s February 2025 work uses modelling to study damage in environmental barrier coatings under thermal cycling. [1] It illustrates a durability question without establishing a fleet-wide improvement. The fuel setting is separate: IEA’s medium-term report describes how supply, infrastructure and prices can affect gas demand. [3] Project developers need to bring those operating considerations into an equivalent equipment comparison, while retaining the applicable emissions and installation requirements for the proposed project.
Table 2: Industry evidence relevant to the gas turbine market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Coating research | NETL reported a model of environmental barrier-coating damage in February 2025. | Durability evidence needs to match the component and operating conditions. | [1] |
| Stationary-turbine analysis | EPA’s January 2026 analysis describes final-rule equipment scope and project timing. | An emissions specification needs the applicable category and project basis. | [2] |
| Fuel-market outlook | IEA’s Gas 2025 distinguishes demand scenarios and infrastructure constraints. | Fuel economics belong alongside equipment and maintenance costs. | [3] |
Analyst Perspective
“A gas turbine lifecycle comparison needs the intended dispatch programme and its fuel and maintenance assumptions. Efficiency, generation reliability and compliance requirements can then be assessed against the same operating duty, with equipment and continuing service responsibilities clear in each offer.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Gas Turbine Market segmented?
The market is segmented by Product, Capacity, Application, Technology, Fuel Type, End Use, and Region.
Product, capacity, technology, fuel and application describe separate views of the market. A heavy duty turbine can use natural gas. The report also includes other turbine configurations and uses, whose purchasing conditions may differ from a stationary power-generation project. Buyers need to connect the relevant product with the required duty rather than infer application fit from the broad category name. For stationary installations, project-specific emissions requirements and the fuel arrangement sit alongside output and maintenance in the commercial specification. The published shares describe the 2026 sales mix rather than the selection for every project.
Why do heavy duty turbines lead the product benchmark?
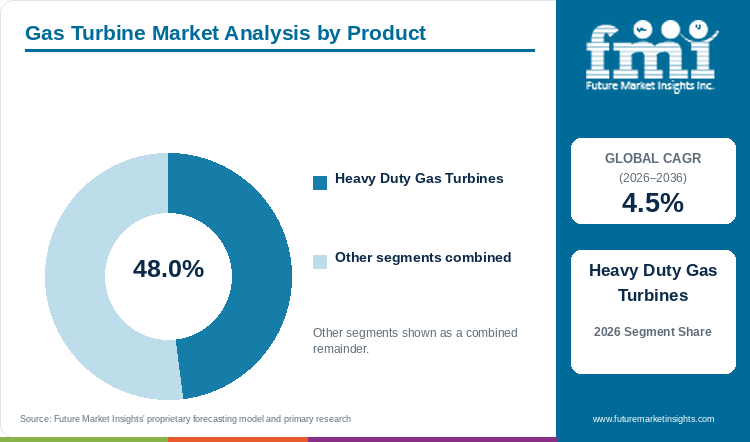
Table 3: Product Share for Gas Turbine Market (percentage share), 2026
| Product | Estimated share (2026) |
|---|---|
| Heavy Duty Gas Turbines | 48.0% |
| Other product segments | 52.0% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Gas Turbine Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.5% |
| Profiled product segment | Heavy Duty Gas Turbines |
Heavy duty gas turbines represent an estimated 48.0% of product demand in 2026. Their commercial assessment needs to connect the machine’s capability with the intended generating installation and dispatch duty. A developer compares the equipment package, commissioning responsibilities and maintenance support alongside the rated output. Hot-section durability is relevant to that ownership decision, but NETL’s 2025 coating research remains a simulation study rather than a commercial life-extension guarantee. [1] Customers therefore need to distinguish research direction from performance evidence for the offered configuration. The product share identifies the category’s market position. It does not establish that every power project requires the same turbine or that a larger frame provides the best operating economics under every load and fuel condition.
The Heavy Duty Gas Turbines segment is estimated to account for 48.0% of product demand in 2026.
- Heavy Duty Gas Turbines account for an estimated 48.0% of product demand in 2026; other product segments together account for 52.0%.
- The machine must be evaluated with its intended dispatch duty, maintenance plan and complete generating installation.
What supports the natural-gas share?
Table 5: Fuel Type Share for Gas Turbine Market (percentage share), 2026
| Fuel Type | Estimated share (2026) |
|---|---|
| Natural Gas | 72.0% |
| Other fuel type segments | 28.0% |
| Total | 100.0% |
Natural gas represents an estimated 72.0% of fuel-type demand in 2026. A customer’s ability to obtain fuel on suitable terms remains distinct from the turbine’s ability to use it. IEA’s Gas 2025 discusses supply changes, demand scenarios and infrastructure constraints, providing context for that operating decision. [3] A project developer needs to assess fuel arrangements alongside the equipment and maintenance offer, rather than translate an aggregate gas-demand forecast directly into turbine orders. The purchase also depends on the unit’s intended role within the generating system. A plant dispatched for different hours or operating conditions can have a different commercial case despite using the same fuel. Clear assumptions make competing offers easier to compare over the expected operating programme.
The Natural Gas segment is estimated to account for 72.0% of fuel type demand in 2026.
- Natural Gas represents an estimated 72.0% of fuel-type demand in 2026; other fuel type segments together represent 28.0%.
- Fuel supply terms and infrastructure need to fit the proposed plant’s operating programme.
- Fuel flexibility has its own equipment requirements. The Multifuel Gas Turbine Market supplies related coverage of that distinct category.
What are the drivers, restraints, and opportunities in the Gas Turbine Market?
Generating projects and equipment renewal support demand; fuel, site and specification dependencies constrain orders; a complete operating and maintenance proposition improves the investment case.
Driver
Electricity requirements and the need to renew generating equipment create turbine purchasing programmes. The investment decision depends on the role the proposed unit will serve, the fuel available and the wider plant configuration. IEA’s Gas 2025 identifies the power sector as an important part of its medium-term gas-demand outlook. [3] That provides a demand setting without measuring turbine sales. An owner may also need equipment that fits an existing installation or a new dispatch requirement. Suppliers can assess the opportunity more clearly when the customer’s operating hours, maintenance expectations and project interfaces are established before an equipment package is priced.
Restraint
A turbine project combines substantial equipment expenditure with site, fuel and operating dependencies. Uncertainty in any of those can delay an order even where generating capacity is needed. IEA’s scenarios identify fuel affordability and infrastructure constraints as separate influences on demand. [3] Buyers also need to establish the applicable emissions basis for the actual stationary-turbine category; EPA’s January 2026 analysis does not describe one common limit for every turbine. [2] These requirements make a broad equipment quotation insufficient. A competitive price can leave a weak investment case if the owner cannot identify the remaining installation work, maintenance burden or fuel exposure.
Opportunity
Suppliers can strengthen the equipment offer through a clear maintenance proposition and a complete statement of project responsibilities. A customer needs to understand which performance conditions, emissions equipment and outage support are included in the price. Durability research can inform future development, while the equipment being offered still needs its own operating basis. [1] There is also room to improve support for owners comparing replacement options within existing plants. A defined installation scope and realistic schedule help the customer connect the machine purchase with fuel, commissioning and the next period of operation, making the ownership comparison more useful than a rating or equipment price alone.
The Industrial Gas Turbine Market provides adjacent coverage for customers comparing turbine duties within an industrial installation.
Which country CAGRs are profiled in the Gas Turbine Market?
Table 6: Country CAGR Comparison for Gas Turbine Market (CAGR percentage), 2026 to 2036
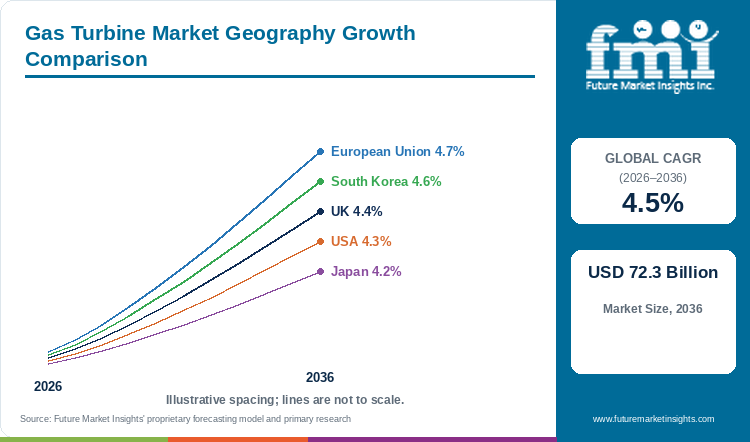
| Country | CAGR |
|---|---|
| European Union | 4.7% |
| South Korea | 4.6% |
| UK | 4.4% |
| USA | 4.3% |
| Japan | 4.2% |
Country-wise Analysis
European Union Gas Turbine Market Outlook (2026 to 2036)
Ireland’s official electricity statistics show gas as the country’s largest generation fuel in 2025, providing one example of the operating base within that wider region. [4] This national mix is not the EU’s turbine-sales distribution. Buyers evaluating new or replacement equipment need to establish the role of the plant, fuel arrangements and its relationship with the wider electricity system. A supplier’s offer becomes more useful when it identifies the maintenance and commissioning responsibilities alongside performance conditions. The regional growth rate covers diverse markets and cannot determine the operating economics of an individual generating project or be relabelled as a single-country estimate.
South Korea Gas Turbine Market Outlook (2026 to 2036)
For a South Korean project, the commercial comparison needs to link turbine capability with the intended operating programme and fuel arrangement. A project that adds new equipment must coordinate commissioning and supporting plant systems, whereas a replacement must fit an established site and work window. Buyers can compare bids coherently only after those responsibilities and assumptions are visible. Fuel supply and the expected dispatch duty can also change the ownership case without changing the machine’s rated output. These considerations describe how a purchaser assesses the investment, rather than assert an unverified national capacity programme. The forecast remains distinct from the growth of every turbine category or a guarantee of a plant’s future utilization.
UK Gas Turbine Market Outlook (2026 to 2036)
Replacement at an existing generating site can require a different equipment and outage plan from a completely new plant. An owner needs to identify which parts of the installation remain in use, how the new configuration will be commissioned and what maintenance support is available. The equipment offer should also state the load and fuel assumptions behind its performance conditions. These details help compare the cost of continued operation with the proposed investment. The national forecast does not establish that every project has the same dispatch role or that a turbine’s catalogue rating settles its economics. A clear operating programme remains necessary for a useful commercial comparison.
USA Gas Turbine Market Outlook (2026 to 2036)
EPA’s January 2026 final-rule analysis describes the scope of stationary-turbine requirements and the project dates relevant to that analysis. [2] A purchaser needs the applicable equipment category and detailed project basis rather than assume one emissions limit across all machines. The commercial offer also needs to connect the turbine with fuel arrangements, emissions equipment, commissioning and maintenance. NETL’s coating research provides a separate component-durability context, without establishing commercial life extension for an offered model. [1] These sources inform different parts of the specification. Neither measures national turbine orders, and the market estimate remains separate from an individual project’s approval or operating performance.
Japan Gas Turbine Market Outlook (2026 to 2036)
Japan’s estimated market CAGR is 4.2% for 2026 to 2036. An equipment owner needs a turbine package that fits its intended generating duty and the support available during maintenance. A new installation can compare alternative plant configurations, while a replacement starts with existing site interfaces and an outage schedule. The buyer can make those differences visible through a common scope that identifies fuel assumptions, commissioning work and continuing service responsibilities. The published growth rate does not determine future fuel costs or dispatch hours for an individual project. Those conditions still need to be assessed in the ownership case behind the equipment order.
Who are the notable companies in the Gas Turbine Market?
General Electric Company; Siemens Energy AG; Mitsubishi Power Ltd.; Ansaldo Energia S.p.A.; Kawasaki Heavy Industries Ltd.
General Electric, Siemens Energy, Mitsubishi Power, Ansaldo Energia and Kawasaki Heavy Industries are representative names in the market coverage. Their offers need to be compared for a defined duty and scope, since equipment supply and a complete generating package leave different work with the customer. A useful purchasing decision brings performance conditions, commissioning and maintenance into the same commercial review, allowing the owner to see the obligations behind the equipment price.
Competitive Benchmarking: Gas Turbine Market
Table 7: Competitive positioning for the gas turbine market
| Company | Positioning | Buyer comparison focus |
|---|---|---|
| General Electric Company | Gas-turbine equipment participant | Compare the proposed duty, package boundary and maintenance support. |
| Siemens Energy AG | Gas-turbine equipment participant | Identify performance conditions and commissioning responsibilities. |
| Mitsubishi Power Ltd. | Gas-turbine equipment participant | Assess the equipment combination and service arrangement for the project. |
| Ansaldo Energia S.p.A. | Gas-turbine equipment participant | Review replacement interfaces and the planned outage scope. |
| Kawasaki Heavy Industries Ltd. | Gas-turbine equipment participant | Compare the offered configuration with the required operating programme. |
Key Developments in the Gas Turbine Market
- NETL reported its barrier-coating damage model in February 2025. [1]
- EPA issued the cited stationary-turbine final-rule analysis in January 2026. [2]
- IEA published Gas 2025 in October 2025, including supply and demand scenarios to 2030. [3]
Key Players in the Gas Turbine Market
Gas-turbine equipment participant
- General Electric Company
- Siemens Energy AG
- Mitsubishi Power Ltd.
- Ansaldo Energia S.p.A.
- Kawasaki Heavy Industries Ltd.
Gas Turbine Market Report Scope
Table 8: Report Scope for Gas Turbine Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market definition | Gas turbines across the report’s product, capacity, technology, fuel and application categories. |
| Quantitative units | USD billion and percentage |
| Forecast period | 2026 to 2036 |
| Segment reference period | 2026 |
| Market breakdown | Product; Capacity; Application; Technology; Fuel Type; End Use |
| Profiled geographies | European Union; South Korea; UK; USA; Japan |
| Representative companies | General Electric Company; Siemens Energy AG; Mitsubishi Power Ltd.; Ansaldo Energia S.p.A.; Kawasaki Heavy Industries Ltd. |
Gas Turbine Market Research Methodology
Table 9: Research Methodology for Gas Turbine Market, 2026 edition
| Method | Approach |
|---|---|
| Market estimates | FMI’s 2025, 2026 and 2036 values and 4.5% CAGR supply the quantitative outlook. |
| Segment comparisons | Product and fuel shares retain separate 2026 denominators. |
| Geographic estimates | Country rates retain 2026 to 2036; the EU remains a regional aggregate. |
| Durability evidence | NETL’s modelling supplies component-specific research context. |
| Project requirements | The EPA analysis provides category and timing context for its stationary-turbine scope. |
| Demand context | IEA scenarios and Irish generation data describe the operating and fuel setting. |
Gas Turbine Market by Segments
Gas Turbine Market segmented by Product:
- Heavy Duty Gas Turbines
- Industrial Gas Turbines
- Aero Derivative Gas Turbines
Gas Turbine Market segmented by Capacity:
- Low Capacity
- Medium Capacity
- High Capacity
- Very High Capacity
Gas Turbine Market segmented by Application:
- Power Generation
- Aviation
- Oil and Gas
- Industrial
Gas Turbine Market segmented by Technology:
- Open Cycle Technology
- Combined Cycle Technology
Gas Turbine Market segmented by Fuel Type:
- Natural Gas
- Liquid Fuels
- Alternative Fuels
Gas Turbine Market segmented by End Use:
- Power Utilities
- Oil and Gas Companies
- Industrial Enterprises
- Aviation Sector
Gas Turbine Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Argentina
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Eastern Europe
- Poland
- Czech Republic
- Romania
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- New Zealand
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
Research Sources and Bibliography
- [1] US National Energy Technology Laboratory. 19 February 2025. NETL Develops Simulation To Study How Corrosion Occurs on Gas Turbines’ Barrier Coatings
- [2] US Environmental Protection Agency. January 2026. Economic Impact Analysis for the New Source Performance Standards Review for Stationary Combustion Turbines: Final Rule
- [3] International Energy Agency. 27 October 2025. Gas 2025—Executive summary
- [4] Ireland Central Statistics Office. 24 August 2026. Electricity Supply by Source 2025—Generation Energy Sources
This Report Answers
- How big is the gas turbine market in 2026?
- What is the 2036 projection?
- Which product category leads?
- What is the natural-gas share?
- Is the EU forecast a single-country estimate?
- Does a fuel-demand forecast measure turbine orders?
Frequently Asked Questions
What is the estimated market size in 2026?
The market is estimated at USD 46.6 billion in 2026, compared with USD 44.6 billion in 2025.
What is the 2036 projection?
FMI projects USD 72.3 billion in 2036 and a CAGR of 4.5% for 2026 to 2036.
Which product category leads?
Heavy Duty Gas Turbines represent an estimated 48.0% of product demand in 2026.
What is the natural-gas share?
Natural Gas represents an estimated 72.0% of fuel-type demand in 2026.
Is the EU forecast a single-country estimate?
No. The European Union is a regional aggregate, profiled at 4.7% for 2026 to 2036.
Does a fuel-demand forecast measure turbine orders?
No. Fuel use and equipment purchases have different units, periods and investment dependencies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Heavy Duty Gas Turbines
- Industrial Gas Turbines
- Aero Derivative Gas Turbines
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Capacity, 2026 to 2036
- Low Capacity
- Medium Capacity
- High Capacity
- Very High Capacity
- Y-o-Y Growth Trend Analysis By Capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By Capacity, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Power Generation
- Aviation
- Oil and Gas
- Industrial
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Open Cycle Technology
- Combined Cycle Technology
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Fuel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Type, 2026 to 2036
- Natural Gas
- Liquid Fuels
- Alternative Fuels
- Y-o-Y Growth Trend Analysis By Fuel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Power Utilities
- Oil and Gas Companies
- Industrial Enterprises
- Aviation Sector
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- New Zealand
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Saudi Arabia
- United Arab Emirates
- South Africa
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Capacity
- By Application
- By Technology
- By Fuel Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- General Electric Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Siemens Energy AG
- Mitsubishi Power Ltd.
- Ansaldo Energia S.p.A.
- Kawasaki Heavy Industries Ltd.
- General Electric Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


