

- Market Size (2026)
- USD 2.9 Bn
- Forecast (2036)
- USD 5.9 Bn
- CAGR (2026 to 2036)
- 7.3%
How big is Gas Separation Membranes Market in 2026?
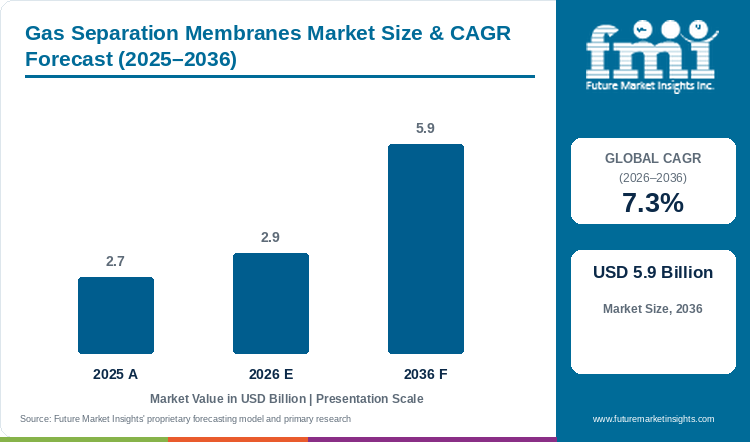
The gas separation membranes market is estimated at USD 2.7 billion in 2025 and is projected to reach USD 2.9 billion in 2026. Demand for gas separation membranes is likely to grow at a 7.3% CAGR between 2026 and 2036 and reach USD 5.9 billion by 2036.
Gas separation membranes market share is concentrated in hollow fiber modules, at 60.2% of 2026 construction type sales, as fibres pack a large membrane area into one vessel. For 2025, FMI estimates gas separation membranes sales at USD 2.7 billion, with USD 2.9 billion expected in 2026 and the gas separation membranes market reaching USD 5.9 billion by 2036 on a 7.3% CAGR. MTR raised USD 27 million in April 2026 to speed deployment of the Polaris capture membrane, after building the largest membrane-based capture system, at Dry Fork Station in Wyoming.[1] Capture projects will add large module orders to the gas processing base.
Gulf Coast projects put the United States at a projected 7.5% CAGR, a full point ahead of 6.5% for Germany. Air Liquide plans a USD 200 million partial oxidation unit for Oxea at Bay City, Texas, supplying syngas and low-carbon hydrogen from early 2029.[2] Syngas and hydrogen plants on the Gulf Coast need hydrogen recovery and ratio control, and hollow fiber units do both with less energy than cryogenic plants. Demand in Germany relies on biogas upgrading and fuel-cell hydrogen, from a smaller base.
Polymeric materials hold 60% of material sales, and plant owners pick modules on selectivity, pressure rating and fouling resistance, so suppliers with long field references keep most tenders.
Key Market Trends & Insights
- Polyimide, polysulfone and cellulose acetate fibres keep polymeric membranes first on material, at an expected 60% of 2026 sales, with inorganic membranes near 27.2%.
- Compact skids keep hollow fiber modules ahead on construction type, at 60.2% of 2026 sales, with spiral wound elements at 26.4%.
- CO2 separation is projected to lead applications with 27.6% in 2026, ahead of nitrogen separation at an estimated 21.3%. Europe had 8.2 bcm a year of installed biomethane capacity by the end of Q2 2026, and upgrading units remove CO2 from every cubic metre.[3]
Regional Highlights
- China is first among the countries covered at an 8.2% CAGR, as new chemical and hydrogen plants specify membrane units.
- India follows China within half a point on refinery and fertiliser expansion, and Germany is lowest in the FMI country table at 6.5% on a mature gas processing base.
- Brazil had 20 ANP-authorised biomethane plants with 1,331,401 m³ a day of capacity in July 2026, and 50 more projects were awaiting authorisation, ABiogás reported.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Gas Separation Membranes Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.7 billion |
| Estimated Market Size in 2026 | USD 2.9 billion |
| Projected Market Size by 2036 | USD 5.9 billion |
| CAGR, 2026 to 2036 | 7.3% |
| Added Revenue, 2026 to 2036 | USD 3.0 billion |
| Market Expansion Multiple | 2.0x |
Membrane orders come in two waves, first as skids for a new gas plant, refinery unit or biomethane site, then as replacement modules every few years as fibres foul or lose selectivity. Air Liquide reported a EUR 6 billion investment backlog and nearly EUR 3 billion of new investment decisions in H1 2026.[5] Syngas plants adjust hydrogen to carbon monoxide ratios with membranes, and the syngas to ethylene glycol catalyst market is predicted to grow at an 8.4% CAGR on new coal and gas based glycol plants. Over the decade, the gas separation membranes market is projected to gain USD 3.0 billion in the FMI outlook, with 2036 sales about twice the 2026 figure. Delays to capture and hydrogen projects are the main risk, since those projects carry the largest new module orders.
Biomethane, Hydrogen and Carbon Capture Projects
Biomethane plants are the steadiest source of new skids. Europe commissioned 327 biomethane plants in a year, bringing the count to 1,975, and installed capacity grew 17% to 8.2 bcm a year by the end of Q2 2026, EBA said.[3] Danish plants average 1,528 Nm³ an hour and French plants 212 Nm³ an hour, so module sizes vary widely by country. Membrane upgrading suits small and mid-sized plants, as the units are modular and need no water or solvent.
Hydrogen and capture add larger, newer orders. Air Liquide, Daimler Truck, Volvo Group, Toyota, Bosch and TotalEnergies agreed in September 2026 to scale hydrogen truck refuelling from Germany, with funding applications for over 70 high-capacity stations and 800 heavy trucks.[6] Fuel-cell trucks need hydrogen at very high purity, and purification steps at production sites use membranes and adsorption. Sales in the membrane chemicals market are forecast to grow at a 6.1% CAGR, and cleaning and conditioning chemicals extend module life in these plants.
Table 2: Project, Capacity and Investment Indicators for the Gas Separation Membranes Market (capacity, plants and investment), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| European biomethane capacity, Q2 2026 | 8.2 bcm a year; 1,975 plants | Each plant needs CO2 removal. | [3] |
| Brazil authorised biomethane plants, July 2026 | 20 plants; 1,331,401 m³ a day | Landfill gas upgrading grows. | [4] |
| MTR equity raise, April 2026 | USD 27 million | Membrane capture scale-up. | [1] |
| Air Liquide Oxea POX unit, Texas | USD 200 million; start-up early 2029 | Syngas and hydrogen separation duty. | [2] |
| Air Liquide investment backlog, H1 2026 | EUR 6 billion | Gas plant pipeline for separation units. | [5] |
| Aramco well construction awards to SLB | Over 450 wells in three years | Saudi gas processing volumes rise. | [7] |
Analyst Perspective
“I see biomethane and hydrogen purification moving membranes from a niche gas processing tool to a standard piece of energy plant, and module replacement turning each installation into a recurring order. Suppliers with field data on fouling and lifetime will hold those plants for the full forecast.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the gas separation membranes market segmented?
The market is segmented into material, construction type, application, and region. Polymeric membranes are expected to lead material with 60% share in 2026, and hollow fiber modules lead construction type with 60.2%.
By material: polymeric, inorganic, and metallic.
By construction type: hollow fiber, spiral wound, and plate and frame.
By application: CO2 separation, nitrogen separation, hydrogen separation, acid gas separation, methane separation, oxygen separation, and olefin paraffin separation.
By region: gas processing, refining, chemical, biogas and industrial gas plants in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do polymeric membranes lead gas separation membranes sales by material?
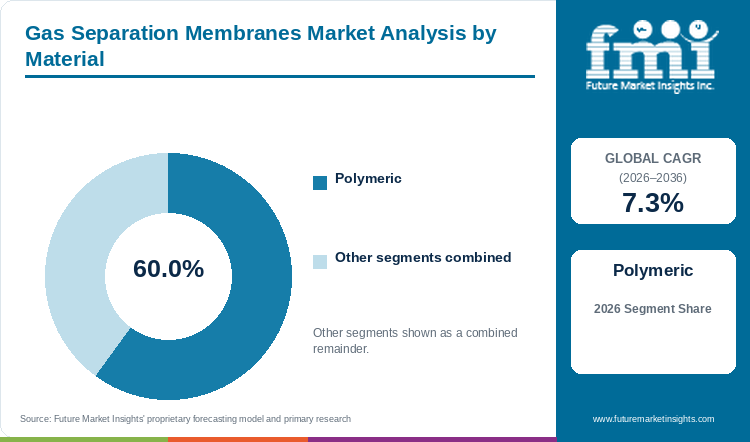
Material sales in 2026 split 60% polymeric, about 27.2% inorganic and roughly 12.8% metallic, with low-cost polymer fibres in the lead.
Table 3: Material Share for the Gas Separation Membranes Market (percentage share), 2026
| Material | Estimated Share (2026) |
|---|---|
| Polymeric | 60% |
| Inorganic | 27.2% |
| Metallic | 12.8% |
| Total | 100.0% |
Table 4: Material Leadership and Market Growth for the Gas Separation Membranes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Leading Segment | Polymeric |
Polyimide and polysulfone can be spun into hollow fibres at low cost and run at the moderate temperatures of most gas plants, so polymeric membranes are expected to lead with 60% share in 2026. Against inorganic membranes, an estimated 27.2%, polymers cost far less per square metre and tolerate pressure cycling, and inorganic zeolite, carbon and ceramic types serve hot or chemically harsh streams. Ceramic membranes are moving into more gas duties, and the ceramic membranes market is projected to grow at an 11.2% CAGR. Against metallic membranes, about 12.8%, polymers trade lower purity for much lower cost, and palladium membranes make ultra-pure hydrogen in small volumes. MTR has deployed over 450 commercial systems for petrochemical, natural gas and refining customers.[1] A gas processor choosing a material will stay with polymer fibres until temperature or purity rules out polymer fibres.
- Polyimide, polysulfone, cellulose acetate and newer polymer blends make up the polymeric group.
- MTR named BTX aromatics recovery and acid gas enrichment for Claus plants as industrial growth areas in April 2026.[1]
Why do hollow fiber modules lead gas separation membranes sales by construction type?
Hollow fiber modules are likely to hold 60.2% of construction type sales in 2026, with spiral wound elements at 26.4% and plate and frame units at 13.4%.
Table 5: Construction Type Share for the Gas Separation Membranes Market (percentage share), 2026
| Construction Type | Estimated Share (2026) |
|---|---|
| Hollow Fiber | 60.2% |
| Spiral Wound | 26.4% |
| Plate and Frame | 13.4% |
| Total | 100.0% |
Hollow fiber modules are projected to lead with 60.2% share in 2026, as a single vessel holds the largest membrane area, which cuts skid size on nitrogen generators, biogas upgraders and hydrogen recovery units. Spiral wound elements, at 26.4%, handle high-pressure natural gas and CO2 removal with good fouling tolerance, and SLB and Honeywell UOP supply that format for gas fields. Plate and frame units, at 13.4%, serve pilot plants, vapour recovery and specialty duties. Brazil had 50 biomethane projects awaiting ANP authorisation in July 2026, each a candidate for compact hollow fiber upgrading.[4] Engineering contractors will choose hollow fiber for most new modular skids and keep spiral wound for large offshore and acid gas trains.
- Nitrogen generators, biogas upgraders and hydrogen recovery skids use most hollow fiber modules.
- Brazil expects about 7 million m³ a day of biomethane capacity and nearly 200 plants by 2030, ABiogás said on 15 July 2026.[4]
Why does CO2 separation lead gas separation membranes sales by application?
CO2 separation is expected to account for 27.6% of application sales in 2026, ahead of nitrogen separation at about 21.3% and hydrogen separation at roughly 18.9%.
Table 6: Application Share for the Gas Separation Membranes Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| CO2 Separation | 27.6% |
| Nitrogen Separation | 21.3% |
| Hydrogen Separation | 18.9% |
| Acid Gas Separation | 10.4% |
| Methane Separation | 9.8% |
| Oxygen Separation | 7.2% |
| Olefin Paraffin Separation | 4.8% |
| Total | 100.0% |
Natural gas sweetening, biomethane upgrading and new capture projects all remove CO2, and with three buyer groups behind the duty, CO2 separation is estimated to lead with 27.6% share in 2026. Nitrogen separation, about 21.3%, comes from on-site generators for food packaging, tyre filling and tank blanketing. Hydrogen separation, near 18.9%, recovers hydrogen in refineries, ammonia and syngas plants. Acid gas separation, an estimated 10.4%, treats sour gas with high hydrogen sulphide. Methane separation, about 9.8%, covers landfill and coal mine gas, oxygen separation, near 7.2%, supplies enriched air, and olefin paraffin separation, around 4.8%, is still early. The same polyimide and polysulfone fibres serve most of these duties, which ties gas separation to growth of the polymeric membrane market. Europe added over 1 bcm a year of biomethane capacity in twelve months to Q2 2026.[3] Plant owners facing carbon rules will buy CO2 separation first, since every tonne removed improves product quality or earns credits.
- Natural gas sweetening, biomethane upgrading and post-combustion capture form the CO2 separation group.
- MTR built the largest membrane-based carbon capture system at the Dry Fork Station coal plant in Wyoming, the company said in April 2026.[1]
What are the drivers, restraints, and opportunities in the gas separation membranes market?
Biomethane, hydrogen and gas processing plants need compact, low-energy separation, which keeps membrane skids in demand. Fouling and high-pressure limits restrict some duties, and carbon capture opens large new projects.
- Driver: Biomethane and hydrogen producers want modular separation with no solvent handling, so membrane skids gain many small and mid-sized plants.
- Restraint: Contaminants and high temperatures shorten membrane life, which pushes some buyers to adsorption or cryogenic units for harsh streams.
- Opportunity: Power and industrial emitters planning carbon capture need large CO2 separation systems, giving membrane suppliers a new class of projects.
Biomethane and Hydrogen Plants Buy Modular Skids
Adoption of membrane upgrading is rising with each new biomethane plant. Brazil added 12 authorised biomethane plants with 714,240 m³ a day of capacity after the Fuel of the Future law was approved, ABiogás said.[4] Germany is the launchpad for a hydrogen truck plan backed by Air Liquide, Daimler Truck and Volvo Group.[6] Skid makers will gain repeat orders as each plant replaces modules every few years.
Fouling and Harsh Streams Limit Some Duties
Producers of gas separation membranes face streams that can damage fibres. Air Liquide reported nearly EUR 3 billion of investment decisions in H1 2026, and many large gas units still use cryogenic or adsorption routes.[5] Saudi Arabia is drilling over 450 wells under new SLB contracts with Aramco, and sour gas from such fields needs pre-treatment before membranes.[7] Suppliers with pre-treatment packages will keep harsh-stream projects that bare modules lose.
Carbon Capture Opens Large Projects
Demand for membrane capture is moving from pilots to commercial plants. MTR said the USD 27 million raise will accelerate global deployment of Polaris for power and industrial capture.[1] Ceramic hollow fibres can handle hot flue gas, and growth of the hollow fiber ceramic membranes market will widen that option for capture plants. Suppliers with proven large units will gain the first wave of capture contracts, a pattern the FMI country table reflects in the 7.5% US rate.
Which country CAGRs are profiled in the gas separation membranes market?
Table 7: Country CAGR Comparison for the Gas Separation Membranes Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 8.2% |
| India | 7.8% |
| United States | 7.5% |
| GCC Countries | 7% |
| Brazil | 6.8% |
| Germany | 6.5% |
How do country-level CAGRs compare in the gas separation membranes market?
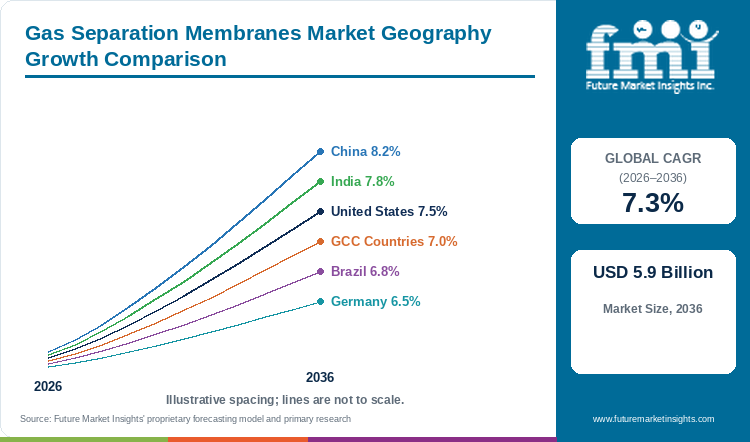
GPIC in Bahrain selected Honeywell UOP in October 2026 for a new aromatics complex producing about 1.2 million tonnes a year of paraxylene.[8] FMI's model shows the GCC Countries at 7%, below the 7.3% CAGR of the gas separation membranes market, as cryogenic and amine units already serve most large gas trains. China leads at 8.2% on new chemical and hydrogen plants, and India follows at 7.8% on refinery and fertiliser expansion. The United States grows at 7.5% on Gulf Coast hydrogen, syngas and capture projects. Brazil, at 6.8%, gains from biomethane upgrading at landfills. Germany, at 6.5%, has the slowest rate, with biomethane and hydrogen purity carrying a mature base.
- New chemical and hydrogen plants carry China.
- Refinery and fertiliser expansion drives India.
- US orders follow Gulf Coast syngas and capture projects.
- Gas field and petrochemical projects support the GCC Countries.
- Landfill biomethane plants add Brazilian orders.
- In Germany, biomethane and truck hydrogen add most new volume.
Full report country CAGRs cover: Chemical and refinery growth in Asia keeps China and India above the 7.3% global rate, the United States is also above that rate, and the GCC Countries, Brazil and Germany are below that rate. Regional figures carry every other listed country.
Country-wise Analysis
China Gas Separation Membranes Market Outlook (2026 to 2036)
Chinese chemical parks are adding coal and gas based syngas, glycol and hydrogen units, and each needs hydrogen recovery and purge gas treatment. China is forecast at an 8.2% CAGR, the top rate in the table, and local polyimide fibre makers compete with imported modules on price.
Key takeaway: New chemical capacity keeps China ahead.
India Gas Separation Membranes Market Outlook (2026 to 2036)
Indian refiners and fertiliser makers are expanding hydrogen and ammonia capacity, and city gas networks are adding compressed biogas plants that need CO2 removal. India is projected at a 7.8% CAGR, with membrane skids favoured for smaller biogas sites.
Key takeaway: Refinery hydrogen and compressed biogas support India.
United States Gas Separation Membranes Market Outlook (2026 to 2036)
Air Liquide's planned partial oxidation unit at Bay City, Texas, will supply syngas and low-carbon hydrogen to Oxea from early 2029.[2] The FMI outlook gives the United States a 7.5% CAGR, above the global rate, as Gulf Coast chemical, hydrogen and capture projects add separation duties. MTR, based in California, is expanding membrane capture with new equity.[1]
Key takeaway: Gulf Coast hydrogen and capture raise US orders.
GCC Countries Gas Separation Membranes Market Outlook (2026 to 2036)
Aramco awarded SLB four integrated well construction contracts covering over 450 wells across Saudi Arabia in September 2026.[7] The GCC Countries are projected at a 7% CAGR, as gas processing and petrochemical plants add hydrogen recovery and CO2 removal, and large trains still use amine and cryogenic units.
Key takeaway: Gas field growth supports the GCC Countries below the global rate.
Brazil Gas Separation Membranes Market Outlook (2026 to 2036)
Eleven of the 20 authorised biomethane plants in Brazil treat landfill gas, and nine treat agricultural, agro-industrial and commercial organic waste, ABiogás said in July 2026.[4] Brazil is forecast at a 6.8% CAGR, as new plants under the Fuel of the Future law install upgrading skids.
Key takeaway: Landfill and farm biomethane carry Brazil.
Germany Gas Separation Membranes Market Outlook (2026 to 2036)
German biomethane plants average 607 Nm³ an hour, larger than plants in France, EBA data show.[3] Germany is projected at a 6.5% CAGR, the slowest in the table. Most gas processing is mature, and new demand comes from biomethane upgrading and hydrogen for trucks.[6]
Key takeaway: Biomethane and truck hydrogen keep Germany growing from a mature base.
Who are the notable companies in the gas separation membranes market?
Air Products, Air Liquide, Honeywell UOP, MTR, UBE, Evonik, Parker Hannifin, Fujifilm, DIC and SLB are the profiled companies.
The FMI company profile covers industrial gas groups, membrane makers and gas processing licensors, ten in all. Air Liquide, owner of the Air Liquide Advanced Separations membrane business, reported H1 2026 revenue of nearly EUR 14 billion.[5] MTR raised USD 27 million and named a new CEO in April 2026.[1] Honeywell UOP secured the GPIC aromatics licence in Bahrain.[8] Air Products, UBE, Evonik, Parker Hannifin, Fujifilm, DIC and SLB complete the group.
- Industrial gas groups: Air Products and Air Liquide.
- Membrane and fibre makers: MTR, UBE, Evonik, Fujifilm and DIC.
- Process and equipment suppliers: Honeywell UOP, Parker Hannifin and SLB.
Competitive Benchmarking: Gas Separation Membranes Market
Table 8: Competitive Benchmarking for the Gas Separation Membranes Market (qualitative documentation ratings), 2026
| Company | Hydrogen and Syngas | CO2 and Biogas | Gas Processing | Recency |
|---|---|---|---|---|
| Air Liquide | High | Medium | Medium | High |
| MTR | Medium | High | High | High |
| Honeywell UOP | Medium | Medium | High | High |
| SLB | Low | Medium | High | High |
| Evonik | Medium | High | Low | Low |
Each capability score in the FMI table follows the number of dated releases on that capability, and the scores carry no share meaning.
Key Developments in the Gas Separation Membranes Market
- On 12 October 2026, GPIC selected Honeywell UOP technology for a new aromatics complex in Bahrain.[8]
- On 24 September 2026, Aramco awarded SLB four well construction contracts for over 450 wells.[7]
- On 15 September 2026, Air Liquide and truck makers announced a plan to scale hydrogen mobility from Germany.[6]
- On 28 July 2026, Air Liquide reported a EUR 6 billion investment backlog in H1 2026 results.[5]
- On 15 July 2026, ABiogás reported 20 authorised biomethane plants in Brazil.[4]
- On 9 July 2026, Air Liquide announced a USD 200 million POX unit for Oxea in Texas.[2]
- On 1 July 2026, EBA put European biomethane capacity at 8.2 bcm a year.[3]
- On 9 April 2026, MTR announced a USD 27 million equity investment.[1]
Key Players in the Gas Separation Membranes Market
Industrial Gas Groups
- Air Products
- Air Liquide
Membrane and Fibre Makers
- MTR
- UBE
- Evonik
- Fujifilm
- DIC
Process and Equipment Suppliers
- Honeywell UOP
- Parker Hannifin
- SLB
Gas Separation Membranes Market - Report Scope
Table 9: Report Scope for the Gas Separation Membranes Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Material; construction type; application; region |
| Quantitative units | USD billion |
| Market definition | Polymeric, inorganic and metallic membranes and modules in hollow fiber, spiral wound and plate and frame formats for CO2, nitrogen, hydrogen, acid gas, methane, oxygen and olefin separation. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Air Products, Air Liquide, Honeywell UOP, MTR, UBE, Evonik, Parker Hannifin, Fujifilm, DIC, SLB |
| Forecast period | 2026 to 2036 |
Gas Separation Membranes Market - Research Methodology
Table 10: Research Methodology for the Gas Separation Membranes Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Industrial gas and membrane company releases, biogas association data, energy service contracts and trade press from May 2025 onward. |
| Desk Research | Desk research covers biomethane plants, hydrogen and syngas projects, carbon capture and gas processing awards. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 2.9 billion and the 7.3% CAGR for the forecast decade. |
| Data Validation | Capacities, investments and contract terms were matched to the company or association that released each one first. |
Gas Separation Membranes Market by Segments
Gas Separation Membranes Market segmented by Material:
- Polymeric
- Inorganic
- Metallic
Gas Separation Membranes Market segmented by Construction Type:
- Hollow Fiber
- Spiral Wound
- Plate and Frame
Gas Separation Membranes Market segmented by Application:
- CO2 Separation
- Hydrogen Separation
- Nitrogen Separation
- Oxygen Separation
- Acid Gas Separation
- Methane Separation
- Olefin Paraffin Separation
Gas Separation Membranes Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Membrane Technology and Research, Inc. (2026, April 9). $27M investment to accelerate global deployment. https://www.mtrinc.com/news/27m-investment-to-accelerate-global-deployment/
- [2] Air Liquide. (2026, July 9). Air Liquide to invest over 200M USD to support chemical manufacturing expansion in Texas. https://www.airliquide.com/group/press-releases-news/2026-07-09/air-liquide-invest-over-200m-usd-support-chemical-manufacturing-expansion-texas
- [3] European Biogas Association. (2026, July 1). Europe adds 1 bcm of biomethane production, but acceleration of its own source of renewable gas can go much faster. https://www.europeanbiogas.eu/news/europe-adds-1-bcm-of-biomethane-production-but-acceleration-of-its-own-source-of-renewable-gas-can-go-much-faster/
- [4] ABiogás. (2026, July 15). Com mercado cinco vezes maior desde 2020, setor de biometano chega a 20 plantas autorizadas e acelera expansão no Brasil. https://abiogas.org.br/com-mercado-cinco-vezes-maior-desde-2020-setor-de-biometano-chega-a-20-plantas-autorizadas-e-acelera-expansao-no-brasil/
- [5] Air Liquide. (2026, July 28). H1 2026 results: acceleration in the second quarter, Air Liquide combines growth and continuous performance. https://www.airliquide.com/group/press-releases-news/2026-07-28/h1-2026-results-acceleration-second-quarter-air-liquide-combines-growth-continuous-performance
- [6] Air Liquide. (2026, September 15). Industry leaders join forces to scale the full value chain of hydrogen mobility across Europe. https://www.airliquide.com/group/press-releases-news/2026-09-15/industry-leaders-scale-full-value-chain-hydrogen-mobility-across-europe
- [7] SLB. (2026, September 24). SLB awarded four multi-year integrated well construction contracts by Aramco. https://www.slb.com/newsroom/press-release/2026/pr-2026-0924-slb-aramco
- [8] Honeywell. (2026, October 12). Honeywell Technologies to help GPIC build new aromatics complex in Bahrain. https://www.honeywell.com/us/en/news/press-releases/2026/10/honeywell-technologies-to-help-gpic-build-new-aromatics-complex-in-bahrain
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the gas separation membranes market during 2026?
- What market size is projected by 2036?
- Which material holds notable share?
- Which construction type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the gas separation membranes market expected in 2026?
FMI's base year of 2026 carries expected gas separation membranes sales of USD 2.9 billion, after about USD 2.7 billion in 2025. The gas separation membranes market is projected to reach USD 5.9 billion by 2036.
What CAGR is projected for the gas separation membranes market through 2036?
Biomethane upgrading, hydrogen purification and carbon capture are expected to carry the gas separation membranes market at a 7.3% CAGR over the decade. Gas processing adds steady replacement orders.
Which material holds a notable market share in 2026?
Polymeric membranes, made mostly from polyimide and polysulfone fibres, are expected to lead with 60% share in 2026. Inorganic membranes follow at an estimated 27.2%.
Which construction type holds a notable market share in 2026?
A 60.2% share in 2026 is likely for hollow fiber modules. Spiral wound elements follow at 26.4%.
Which country has a notable expansion outlook through 2036?
New chemical and hydrogen plants give China an 8.2% CAGR, the top rate in the FMI country table. India follows at 7.8%.
Who are the key companies in the gas separation membranes market?
Air Products and Air Liquide lead the industrial gas group, and MTR, UBE, Evonik, Fujifilm and DIC make membranes and fibres. Honeywell UOP, Parker Hannifin and SLB complete the profiled list.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material, 2026 to 2036
- Polymeric
- Inorganic
- Metallic
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By Construction Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Construction Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Construction Type, 2026 to 2036
- Hollow Fiber
- Spiral Wound
- Plate and Frame
- Y-o-Y Growth Trend Analysis By Construction Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Construction Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- CO2 Separation
- Hydrogen Separation
- Nitrogen Separation
- Oxygen Separation
- Acid Gas Separation
- Methane Separation
- Olefin Paraffin Separation
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Material
- By Construction Type
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Material
- By Construction Type
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- GCC Countries
- Pricing Analysis
- Market Share Analysis, 2025
- By Material
- By Construction Type
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Material
- By Construction Type
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Air Liquide
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- MTR
- Honeywell UOP
- SLB
- Evonik
- Air Products
- UBE
- Fujifilm
- DIC
- Parker Hannifin
- Air Liquide
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


