
- Market Size (2026)
- USD 21.9 Bn
- Forecast (2036)
- USD 54.8 Bn
- CAGR (2026 to 2036)
- 9.6%
How big is Automotive Turbochargers Market in 2026?
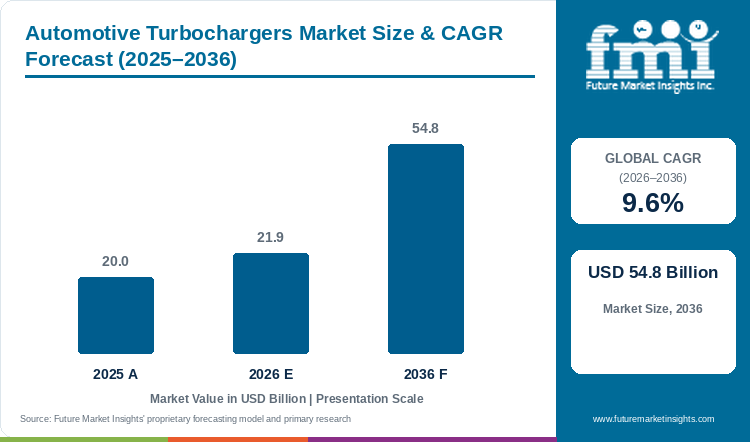
Sales of automotive turbochargers will grow at a CAGR of 9.6% from 2026 to 2036. Market size was USD 20 billion in 2025 and is projected to reach USD 21.9 billion in 2026 and USD 54.8 billion by 2036.
Turbochargers were fitted to 45.1% of US model year 2024 production, the US Environmental Protection Agency reported.[1] Penetration at that level means nearly half of new US vehicles already use boost, so the next stage of growth will come from new engine programmes and from markets with lower fitment. Automotive turbochargers market size stood at USD 20 billion in 2025, is estimated at USD 21.9 billion in 2026 and is projected to reach USD 54.8 billion by 2036. Sales of automotive turbochargers will grow at a CAGR of 9.6% from 2026 to 2036, a strong pace for a product that already has wide fitment.
The EPA repealed all greenhouse gas emission standards for light-duty, medium-duty and heavy-duty vehicles and engines in a final action published on 18 February 2026 and effective on 20 April 2026.[2] Looser federal rules weaken one reason to downsize engines in the USA. US fitment will therefore stay near current levels, and growth in sales will lean on other regions and on engine types that already use turbos.
Variable geometry units hold 55% of product sales and OEM supply holds 70% of end use sales in 2026, as per FMI, so programme awards from vehicle makers carry the market. Engine control content in these programmes ties turbo suppliers to the automotive electronics market, projected to grow from USD 282,989.3 million in 2026 to USD 443,697.4 million by 2036 at a 4.6% CAGR. Investment in variable geometry and electronically controlled units is likely to shape supplier sales through 2036.
Key Market Trends & Insights
- By product, variable geometry turbochargers led with 55% of sales in 2026, ahead of wastegate turbochargers at an estimated 33%. BorgWarner's May 2026 awards cover variable turbine geometry, twin-scroll wastegate and regulated two-stage units.[3]
- By application, passenger vehicles accounted for 65% of sales in 2026, and commercial vehicles held an estimated 35%. Most gasoline turbocharged engines in US model year 2024 were 4-cylinder units.[1]
- By end use, OEM supply held 70% of sales in 2026, and aftermarket supply held the balance at an estimated 30%.
- By distribution channel, direct sales captured 65% of sales in 2026, ahead of distributors at an estimated 18% and authorized dealers at 10%. Garrett Motion's top ten customers accounted for approximately 62% of net sales.[4]
- By fuel type, gasoline engines took 60% of sales in 2026, ahead of diesel engines at an estimated 29%. Garrett Motion's gasoline sales rose 6% on a reported basis in 2025.[5]
Regional Highlights
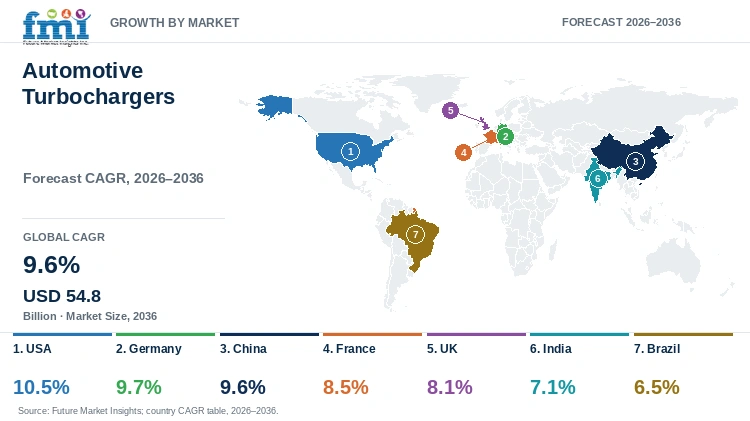
- Fastest-growing profiled country is the USA, projected to grow at a CAGR of 10.5% from 2026 to 2036.
- Germany (9.7%), China (9.6%), France (8.5%), the UK (8.1%) and India (7.1%) follow on the same projected basis, and Brazil records the lowest profiled CAGR at 6.5%.
- India's draft CAFE norms of 16 July 2026 apply to M1 passenger vehicles from 1 April 2027.[6]
Market Size & Forecast
Table 1: Market Size and Forecast for the Automotive Turbochargers Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 20 billion |
| Estimated Market Size in 2026 | USD 21.9 billion |
| Projected Market Size by 2036 | USD 54.8 billion |
| CAGR, 2026 to 2036 | 9.6% |
| Added Revenue, 2026 to 2036 | USD 32.9 billion |
| Market Expansion Multiple | 2.5x |
Orders are placed years before the vehicle reaches a showroom. BorgWarner's July 2025 awards carry production starts in August 2027 for Europe and September 2028 for North America.[7] Garrett Motion's February 2026 results cite continued turbo business across all hybrid types.[5] Hybrid launches add cabling content, so suppliers follow the automotive wiring harness market for ramp-up signals. FMI adds USD 32.9 billion of market size from 2026 to 2036, a 2.5x multiple on the 2026 base. A platform that drops the combustion engine removes the turbo from the bill of materials.
Turbo Fitment and Electrification Readiness
Hybrid drivetrains keep the turbo on the engine. The EPA lists turbos on 75.3% of model year 2024 mild hybrids and 67.7% of plug-in hybrids, against 20.6% of gasoline engines without stop/start.[1] Battery electric vehicles fell from 10% to 7% of all new vehicles in model year 2024 against model year 2023.[1] Garrett Motion directs about 50% of research, development and engineering spending to zero emission technologies, and the annual report lists a shift toward vehicles needing no turbocharger, such as BEVs, as a longer-term risk.[5][4]
Rules in the largest markets now point in different directions. US greenhouse gas standards for vehicles were repealed with effect from 20 April 2026.[2] India published draft CAFE norms on 16 July 2026 for passenger vehicles from 1 April 2027, with the formula constant falling from 3.9960 for 2027-28 to 3.3273 for 2031-32.[6] BorgWarner secured a new eTurbo award with a major European OEM for an advanced hybrid passenger car application in July 2026, with production scheduled to begin in 2029.[7a] Suppliers choose between hybrid and downsized gasoline programmes in the USA and electric turbo content for markets with tighter fuel targets.
Table 2: Turbo Fitment and Electrification Indicators for the Automotive Turbochargers Market (percentages, units and engine data), mixed reporting years from 2024 to 2027
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| US turbo fitment, model year 2024 | Turbos on 45.1% of production; 75.3% of mild hybrids; 67.7% of plug-in hybrids | Hybrid engines keep boost on the bill of materials. | [1] |
| US diesel turbo fitment, model year 2024 | 100% of diesel production | Diesel programmes carry a turbo on every engine. | [1] |
| US battery electric share, model year 2024 | BEVs fell from 10% to 7% of all new vehicles | A slower electric shift protects combustion volume. | [1] |
| Garrett Motion outlook assumption, 2026 | Average light vehicle BEV penetration of 19% | A leading supplier plans around a mixed drivetrain fleet. | [5] |
| Garrett Motion customer mix, 2025 | OEM about 86% of revenues; top ten customers about 62% of net sales | Sales concentrate on a small group of carmakers. | [4] |
| Garrett Motion fourth quarter 2025 demand | Higher demand for commercial vehicle and diesel applications, partially offset by weaker gasoline demand | Gasoline softness was offset by other applications. | [5] |
| US vehicle greenhouse gas standards | All repealed; effective 20 April 2026 | Published 18 February 2026. | [2] |
| India draft CAFE norms | From 1 April 2027; constant 3.9960 for 2027-28 and 3.3273 for 2031-32 | Fuel targets tighten across the period. | [6] |
| BorgWarner eTurbo award, August 2026 | New eTurbo award with a major European OEM for an advanced hybrid passenger car application | Electric turbo content is entering hybrid programmes. | [8] |
| BorgWarner net sales, second quarter 2026 | USD 3,648 million, up about 0.3% on the second quarter of 2025 | Supplier sales are flat as awards build. | [8] |
| BorgWarner awards, July 2025 | 1.0-liter wastegate gasoline turbo in Europe from August 2027; 3.0-liter gasoline hybrid in North America from September 2028 | Awards cover both compact combustion and hybrid applications. | [7] |
Analyst Perspective
“Hybrid and downsized gasoline programmes will hold turbo volume even as battery electric share rises. Suppliers that pair variable geometry units with electric assist products will hold the strongest position in new awards through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Automotive Turbochargers Market segmented?
The automotive turbochargers market is segmented into product, application, end use, distribution channel, and fuel type, and region. In 2026, variable geometry turbochargers hold 55% of product sales, passenger vehicles hold 65% of application sales, OEM supply holds 70% of end use sales, direct sales hold 65% of distribution channel sales and gasoline engines hold 60% of fuel type sales.
By product: variable geometry turbochargers, wastegate turbochargers, and electric turbochargers.
By application: passenger vehicles and commercial vehicles.
By end use: OEM and aftermarket.
By distribution channel: direct sales, distributors, authorized dealers, and online platforms.
By fuel type: gasoline engines, diesel engines, and alternative fuel engines.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do variable geometry turbochargers lead product sales?
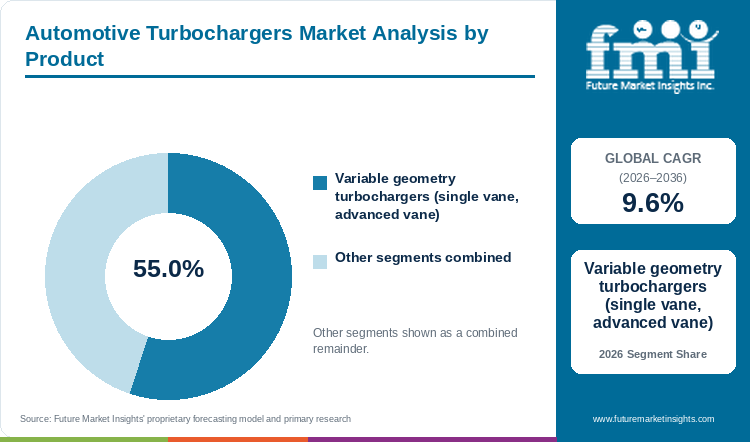
Variable geometry turbochargers account for 55% of product sales in 2026.
Table 3: Product Share for the Automotive Turbochargers Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Variable Geometry Turbochargers | 55% |
| Wastegate Turbochargers | 33% |
| Electric Turbochargers | 12% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Automotive Turbochargers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.6% |
| Leading Segment | Variable Geometry Turbochargers |
Engines that need boost across a wide speed range favour variable geometry units, and FMI finds a 55% share of product sales for them in 2026. Cummins describes the Holset HE300VG 8th generation variable geometry turbocharger as designed specifically for pickup applications, with a 4-percentage-point efficiency improvement over the previous generation.[9] BorgWarner's May 2026 awards list variable turbine geometry beside twin-scroll wastegate and regulated two-stage units.[3] Motors in electric turbochargers link the segment to the magnetic materials market. Engine teams choose between a simpler wastegate unit and a variable geometry unit for each programme.
- Programme choice follows boost range, response time and actuator durability.
- BorgWarner's July 2025 award covers a wastegate gasoline turbocharger for 1.0-liter engines, with production scheduled to begin in August 2027.[7]
Why do passenger vehicles dominate application sales?
Passenger vehicles account for 65% of application sales in 2026, ahead of commercial vehicles.
Table 5: Application Share for the Automotive Turbochargers Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Passenger Vehicles | 65% |
| Commercial Vehicles | 35% |
| Total | 100.0% |
Against commercial vehicles, passenger vehicles take 65% of application sales in 2026. Most gasoline turbocharged engines in US model year 2024 were 4-cylinder units, which the EPA links to turbo downsizing.[1] Lighter body structures serve the same fuel economy goals, a trend followed in the automotive composites market. India's draft CAFE norms of 16 July 2026 apply to M1 category passenger vehicles from 1 April 2027.[6] Fleet buyers of vans and light trucks read a different spec sheet, with duty cycle and service intervals ahead of peak boost.
- Hatchback, sedan and SUV programmes set the volume base.
- BorgWarner's May 2026 awards cover passenger car and van applications with both gasoline and diesel engines.[3]
Why do OEM programmes account for most end use sales?
OEM supply accounts for 70% of end use sales in 2026.
Table 6: End Use Share for the Automotive Turbochargers Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| OEM | 70% |
| Aftermarket | 30% |
| Total | 100.0% |
Garrett Motion drew about 86% of 2025 revenues from OEM sales, and aftermarket and other products supplied about 14%.[4] FMI estimates the OEM share of end use sales at 70% in 2026. That market-wide figure is lower than the Garrett Motion mix, so other suppliers carry a larger aftermarket weight. Carmakers specify the turbo at the engine design stage, which leaves late entrants with the replacement route.
- Replacement units and performance upgrades form the aftermarket group.
- Garrett Motion supplies products to more than 60 OEMs globally.[4]
What gives direct sales the lead in distribution channel sales?
Direct sales account for 65% of distribution channel sales in 2026.
Table 7: Distribution Channel Share for the Automotive Turbochargers Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Direct Sales | 65% |
| Distributors | 18% |
| Authorized Dealers | 10% |
| Online Platforms | 7% |
| Total | 100.0% |
Long contracts between suppliers and carmakers keep direct sales ahead of the other channels, at 65% in 2026. Garrett Motion's top ten customers accounted for approximately 62% of net sales.[4] BorgWarner's May 2026 awards run in phases to the second quarter of 2029.[3] Distributors, authorized dealers and online platforms serve repair demand. Workshops buying through those routes decide on fit data and delivery time, not on programme terms.
- Authorized dealers hold an estimated 10% and online platforms 7%.
- Garrett Motion operates through a network of more than 370 distributors covering 165 countries.[4]
Why does gasoline lead fuel type sales?
Gasoline engines account for 60% of fuel type sales in 2026.
Table 8: Fuel Type Share for the Automotive Turbochargers Market (percentage share), 2026
| Fuel Type | Estimated Share (2026) |
|---|---|
| Gasoline Engines | 60% |
| Diesel Engines | 29% |
| Alternative Fuel Engines | 11% |
| Total | 100.0% |
Sales of turbochargers for gasoline engines account for 60% of fuel type sales in 2026, FMI finds. Garrett Motion reported gasoline sales up 6% and diesel sales up 1% for 2025 on a reported basis.[5] In the fourth quarter, higher demand for commercial vehicle and diesel applications partially offset weaker gasoline demand.[5] Diesel engines keep full fitment, so the gasoline lead is a volume story and not a fitment story.[1]
- Small displacement and high performance engines form the gasoline group.
- The EPA lists turbos on 100% of model year 2024 US diesel production.[1]
What are the drivers, restraints, and opportunities in the Automotive Turbochargers Market?
Hybrid and downsized gasoline programmes support sales, rising battery electric share and looser fuel economy rules restrain them, and electric assist units open the main opportunity.
- Driver: Hybrid and downsized gasoline programmes keep a turbo on the engine, with turbos on 75.3% of US mild hybrids and 67.7% of plug-in hybrids in model year 2024.[1]
- Restraint: Battery electric vehicles need no turbocharger, and Garrett Motion lists that shift among longer-term risks.[4]
- Opportunity: The hybrid setup enables electric turbos and compressors, according to Garrett Motion.[4]
Hybrid Programmes Keep Boost on the Engine
Hybrid engines keep the combustion engine and the turbo. BorgWarner secured a high-performance turbocharger programme for a 3.0-liter gasoline hybrid application in North America in July 2025, with production starting in September 2028.[7] Garrett Motion reported continued turbo business across all hybrid types in February 2026.[5] Supplier order books for hybrid platforms therefore extend well beyond the current model cycle.
Electric Share and Looser Rules Narrow Turbo Content
The EPA reported that BEVs fell from 10% to 7% of all new vehicles in model year 2024.[1] US greenhouse gas standards for vehicles were repealed with effect from 20 April 2026, which removes a federal reason to downsize.[2] Cast housings link turbo makers to the die casting services market for capacity. Suppliers carry the risk that a platform ends without a turbo replacement.
Electric Assist Units and Pickup Programmes Open New Content
In the FMI split, electric assist and fully electric units form the electric turbocharger group of the product segment. Garrett Motion directs about 50% of research, development and engineering spending to zero emission technologies.[5] Cummins described the HE300VG for pickups in June 2026, with a 4-percentage-point efficiency gain over the previous generation.[9] Suppliers with both variable geometry and electric assist products can bid across drivetrain types.
Which country CAGRs are profiled in the Automotive Turbochargers Market?
Table 9: Country CAGR Comparison for the Automotive Turbochargers Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| USA | 10.5% |
| Germany | 9.7% |
| China | 9.6% |
| France | 8.5% |
| UK | 8.1% |
| India | 7.1% |
| Brazil | 6.5% |
How do country-level CAGRs compare in the automotive turbochargers market?
FMI projects the USA at a CAGR of 10.5% from 2026 to 2036, ahead of Germany at 9.7%, China at 9.6%, France at 8.5% and the UK at 8.1%. India is projected at 7.1% and Brazil at 6.5%, the lowest of the seven. Vehicle output, fuel rules and drivetrain mix set the gap between them.
- The USA pairs pickup and light truck engines with fuel economy pressure.
- Germany centres on premium and commercial platforms.
- China links large domestic vehicle output with local sourcing.
- France follows the European engine programme cycle.
- The UK ranks fifth of the seven profiled countries.
- India adds rising vehicle output and replacement demand.
- Brazil combines compact cars with price-sensitive buyers.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
USA Automotive Turbochargers Market Outlook (2026 to 2036)
The EPA repeal of all greenhouse gas emission standards for light-duty, medium-duty and heavy-duty vehicles took effect on 20 April 2026.[2] Turbos were still fitted to 45.1% of US model year 2024 production.[1] Cummins described the 8th generation HE300VG for pickups in June 2026, which suits the pickup and light truck focus that places the USA first, at a projected CAGR of 10.5% from 2026 to 2036.[9] BorgWarner's 3.0-liter gasoline hybrid award for North America starts production in September 2028.[7]
Key takeaway: Pickup and hybrid programmes, not federal fuel rules, now set the pace for US turbo orders.
Germany Automotive Turbochargers Market Outlook (2026 to 2036)
Premium and commercial platforms define German turbo orders, and Euro 7-linked launches are the stated lever behind a projected CAGR of 9.7% from 2026 to 2036. BorgWarner's May 2026 awards from a major European OEM include production at Kirchheimbolanden, Germany, in phases from the second quarter of 2026 through the second quarter of 2029.[3] The awards cover passenger car and van applications on gasoline and diesel engines, a mix that fits premium and light commercial programmes.
Key takeaway: Multi-year awards lock German volume in, so late entrants meet closed platforms until the next sourcing round.
China Automotive Turbochargers Market Outlook (2026 to 2036)
Large domestic vehicle output and local sourcing are the stated levers behind a projected CAGR of 9.6% from 2026 to 2036 in China. Growth in new energy vehicles narrows the pool of boosted engines, so turbo growth comes from hybrid and combustion models. Global suppliers report awards for hybrid applications, such as BorgWarner's new eTurbo award with a major European OEM in July 2026.[7]
Key takeaway: Local sourcing decides which turbo makers hold Chinese volume as new energy vehicles take share.
France Automotive Turbochargers Market Outlook (2026 to 2036)
France is projected to grow at a CAGR of 8.5% from 2026 to 2036, fourth among the seven profiled countries. French turbo orders follow European engine programmes. BorgWarner's July 2025 award for 1.0-liter wastegate gasoline turbochargers in Europe covers compact and light commercial combustion and hybrid vehicles, with production scheduled for August 2027.[7]
Key takeaway: France offers a mid-sized pool of compact and light commercial programmes, awarded on the same European cycle as Germany.
UK Automotive Turbochargers Market Outlook (2026 to 2036)
The UK has a smaller vehicle base than Germany or France, and the country is projected to grow at a CAGR of 8.1% from 2026 to 2036, fifth of the seven. Europe-wide awards, such as BorgWarner's phased programmes from the second quarter of 2026 through the second quarter of 2029, set the timeline that suppliers work to.[3] Hybrid and combustion programmes placed by global carmaker teams reach UK plants through the same award cycle.
Key takeaway: UK turbo volume is smaller, and supply contracts follow decisions taken outside the country.
India Automotive Turbochargers Market Outlook (2026 to 2036)
A draft notification dated 16 July 2026 sets CAFE norms for M1 category passenger vehicles with effect from 1 April 2027, with the formula constant falling from 3.9960 for 2027-28 to 3.3273 for 2031-32.[6] Tighter fuel targets favour boosted small engines and hybrids. India is projected at a CAGR of 7.1% from 2026 to 2036, sixth of the seven, on rising vehicle output and replacement demand.
Key takeaway: Indian carmakers face a regulatory push from April 2027, and the draft stage leaves the final constants open.
Brazil Automotive Turbochargers Market Outlook (2026 to 2036)
Compact cars and price-sensitive buyers shape sales of turbochargers in Brazil, and the projected CAGR of 6.5% from 2026 to 2036 is the lowest of the seven. Small boosted engines suit compact cars, and cost decides supplier choice more than boost range.
Key takeaway: Brazilian turbo orders reward cost-led compact car programmes, and the lower CAGR leaves little room for premium content.
Who are the notable companies in the Automotive Turbochargers Market?
Garrett Motion, BorgWarner, Cummins, Continental AG, Mitsubishi Heavy Industries, IHI Corporation, BMTS Technology and Rotomaster are notable companies profiled in this market.
FMI lists eight key companies, and supply reach and new awards separate them. Garrett Motion supplies more than 60 OEMs globally.[4] BorgWarner announced turbocharger awards in July 2025 and May 2026.[7][3] Cummins Turbo Technologies developed the HE300VG for pickup applications.[9] Continental AG, Mitsubishi Heavy Industries, IHI Corporation, BMTS Technology and Rotomaster complete the roster.
- Dedicated turbocharger makers: Garrett Motion and BorgWarner.
- Engine group and component suppliers: Cummins and Continental AG.
- Japanese industrial groups: Mitsubishi Heavy Industries and IHI Corporation.
- Regional and aftermarket suppliers: BMTS Technology and Rotomaster.
Competitive Benchmarking: Automotive Turbochargers Market
Table 10: Competitive Benchmarking for the Automotive Turbochargers Market (qualitative documentation ratings), 2026
| Company | Turbo range | OEM programmes | Aftermarket | Disclosure |
|---|---|---|---|---|
| Garrett Motion | High | High | High | High |
| BorgWarner | High | High | Low | Medium |
| Cummins | Medium | Medium | Low | Low |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Automotive Turbochargers Market
- On 29 July 2026, BorgWarner announced a new eTurbo award with a major European OEM for an advanced hybrid passenger car application, with production scheduled to begin in 2029. On 5 August 2026, BorgWarner reported second quarter 2026 net sales of USD 3,648 million.[7a][8]
- On 16 July 2026, India published draft CAFE norms for M1 category passenger vehicles, to apply from 1 April 2027.[6]
- On 9 June 2026, Cummins described the Holset HE300VG 8th generation variable geometry turbocharger for pickups.[9]
- In May 2026, BorgWarner announced multiple turbocharger awards with a major European OEM, with production in phases from the second quarter of 2026 through the second quarter of 2029.[3]
- On 19 February 2026, Garrett Motion reported 2025 net sales of USD 3,584 million and a 2026 net sales outlook of USD 3.6 billion to USD 3.8 billion.[5]
- On 18 February 2026, the EPA published the repeal of vehicle greenhouse gas emission standards, effective 20 April 2026.[2]
- In July 2025, BorgWarner announced two turbocharger awards covering Europe and North America.[7]
Key Players in the Automotive Turbochargers Market
Dedicated Turbocharger Makers
- Garrett Motion Inc.
- BorgWarner Inc.
Engine Group and Component Suppliers
- Cummins Inc. (Cummins Turbo Technologies)
- Continental AG
Japanese Industrial Groups
- Mitsubishi Heavy Industries, Ltd.
- IHI Corporation
Regional and Aftermarket Suppliers
- BMTS Technology GmbH & Co. KG
- Rotomaster
Automotive Turbochargers Market - Report Scope
Table 11: Report Scope for the Automotive Turbochargers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; application; end use; distribution channel; fuel type; region |
| Quantitative units | USD billion |
| Market definition | Automotive turbochargers market covering variable geometry, wastegate and electric turbochargers, tracked by application, end use, distribution channel and fuel type. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA; Germany; China; France; UK; India; Brazil |
| Key companies profiled | Garrett Motion, BorgWarner, Cummins, Continental AG, Mitsubishi Heavy Industries, IHI Corporation, BMTS Technology, Rotomaster |
| Forecast period | 2026 to 2036 |
Automotive Turbochargers Market - Research Methodology
Table 12: Research Methodology for the Automotive Turbochargers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Supplier and policy facts come from company filings, press releases and regulator notices dated May 2025 or later. |
| Desk Research | Desk research covers company annual reports, results releases, award announcements and regulator publications on fuel economy and emissions. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market size of USD 20 billion and the 9.6% CAGR. |
| Data Validation | Supplier awards, results and policy facts are confirmed against annual reports, results releases and regulator notices. |
Automotive Turbochargers Market by Segments
Automotive Turbochargers Market segmented by Product:
- Variable geometry turbochargers (single vane, advanced vane)
- Wastegate turbochargers (internal, external)
- Electric turbochargers (electric assist, fully electric)
Automotive Turbochargers Market segmented by Application:
- Passenger vehicles (hatchback, sedan, SUV)
- Commercial vehicles (LCV, HCV)
Automotive Turbochargers Market segmented by End Use:
- OEM (passenger vehicle manufacturers, commercial vehicle manufacturers)
- Aftermarket (replacement, performance upgrades)
Automotive Turbochargers Market segmented by Distribution Channel:
- Direct sales (OE supply, long term contracts)
- Distributors
- Authorized dealers
- Online platforms
Automotive Turbochargers Market segmented by Fuel Type:
- Gasoline engines (small displacement, high performance)
- Diesel engines (light duty, heavy duty)
- Alternative fuel engines
Automotive Turbochargers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] U.S. Environmental Protection Agency. (2026, February). Fuel Economy and Technology since 1975: EPA Automotive Trends Report 2025 (EPA-420-R-26-001). https://www.epa.gov/system/files/documents/2026-02/420r26001.pdf
- [2] U.S. Environmental Protection Agency. (2026, February 18). Rescission of the Greenhouse Gas Endangerment Finding and Motor Vehicle Greenhouse Gas Emission Standards under the Clean Air Act. Federal Register. https://www.federalregister.gov/documents/2026/02/18/2026-03157/rescission-of-the-greenhouse-gas-endangerment-finding-and-motor-vehicle-greenhouse-gas-emission
- [3] BorgWarner Inc. (2026, May 6). BorgWarner Secures Multiple Turbocharger Awards with Major European OEM. https://borgwarner.com/newsroom/press-releases/2026/05/06/borgwarner-secures-multiple-turbocharger-awards-with-major-european-oem
- [4] Garrett Motion Inc. (SEC Form 10-K). (2026). Annual Report on Form 10-K for the fiscal year ended December 31, 2025. https://www.sec.gov/Archives/edgar/data/1735707/000173570726000009/gtx-20251231.htm
- [5] Garrett Motion Inc. (2026, February 19). Garrett Motion Reports Strong 2025 Results and Expansion of Zero-Emission and Industrial Technology Portfolio, Issues 2026 Outlook. https://garrettmotion.gcs-web.com/news-releases/news-release-details/garrett-motion-reports-strong-2025-results-and-expansion-zero
- [6] Ministry of Power, Government of India. (2026, July 16). Draft notification on Corporate Average Fuel Economy (CAFE) 2027 norms for M1 category motor vehicles. https://www.powermin.gov.in/static/uploads/2026/07/ee9eb7febe38828e495f3abbae3da3de.pdf
- [7] BorgWarner Inc. (2025, July 31). BorgWarner Secures Strategic Turbocharger Business for Major Global OEM's Compact and Light Commercial Vehicles. https://www.borgwarner.com/newsroom/press-releases/2025/07/31/borgwarner-secures-strategic-turbocharger-business-for-major-global-oem-s-compact-and-light-commercial-vehicles
- [8] BorgWarner Inc. (2026, August 5). Exhibit 99.1: BorgWarner Reports Second Quarter 2026 Results (press release filed with SEC Form 8-K). https://www.sec.gov/Archives/edgar/data/0000908255/000090825526000049/a20260630ex991pressrelease.htm
- [9] Cummins Inc. (2026, June 9). What powers the 6.7L Cummins Turbo Diesel? https://www.cummins.com/news/2026/06/09/what-powers-67l-cummins-turbo-diesel
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automotive turbochargers market during 2026?
- What market size is projected by 2036?
- Which product holds notable share?
- Which application holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Variable geometry turbochargers (single vane, advanced vane)
- Wastegate turbochargers (internal, external)
- Electric turbochargers (electric assist, fully electric)
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Passenger vehicles (hatchback, sedan, SUV)
- Commercial vehicles (LCV, HCV)
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- OEM (passenger vehicle manufacturers, commercial vehicle manufacturers)
- Aftermarket (replacement, performance upgrades)
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct sales (OE supply, long term contracts)
- Distributors
- Authorized dealers
- Online platforms
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Fuel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Type, 2026 to 2036
- Gasoline engines (small displacement, high performance)
- Diesel engines (light duty, heavy duty)
- Alternative fuel engines
- Y-o-Y Growth Trend Analysis By Fuel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Application
- By End Use
- By Distribution Channel
- By Fuel Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Garrett Motion
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- BorgWarner
- Cummins
- Cummins Inc. (Cummins Turbo Technologies)
- Continental AG
- Mitsubishi Heavy Industries, Ltd.
- IHI Corporation
- BMTS Technology GmbH & Co. KG
- Rotomaster
- Garrett Motion
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End Use, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Fuel Type, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End Use
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Fuel Type
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End Use
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Fuel Type
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End Use
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Fuel Type
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product
- Figure 64: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Application
- Figure 67: Western Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End Use
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Fuel Type
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Application
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End Use
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Fuel Type
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product
- Figure 96: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Application
- Figure 99: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End Use
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Fuel Type
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End Use
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Fuel Type
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End Use
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Fuel Type, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Fuel Type, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Fuel Type
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the automotive turbochargers market expected in 2026?
Market size is projected to reach USD 21.9 billion in 2026 and USD 54.8 billion by 2036, as per Future Market Insights. Market size was USD 20 billion in 2025.
What CAGR is projected for the automotive turbochargers market through 2036?
As per FMI analysis, sales of automotive turbochargers will grow at a CAGR of 9.6% from 2026 to 2036. Hybrid and downsized gasoline programmes support the outlook.
Which product holds a notable market share in 2026?
Product sales are led by variable geometry turbochargers at 55% in 2026. Wastegate and electric turbochargers complete the product split.
Which application holds a notable market share in 2026?
Passenger vehicles take 65% of application sales in 2026, ahead of commercial vehicles. Hatchback, sedan and SUV programmes form the passenger group.
Which country has a notable expansion outlook through 2036?
The USA is projected to grow fastest, at a CAGR of 10.5% from 2026 to 2036, according to FMI. Pickup and light truck engines are the stated lever.
Who are the key companies in the automotive turbochargers market?
Notable companies include Garrett Motion, BorgWarner, Cummins, Continental AG, Mitsubishi Heavy Industries, IHI Corporation, BMTS Technology and Rotomaster.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
