

- Market Size (2026)
- USD 4.2 Bn
- Forecast (2036)
- USD 6.5 Bn
- CAGR (2026 to 2036)
- 4.5%
How Big is the Idler Wheels Market in 2026?
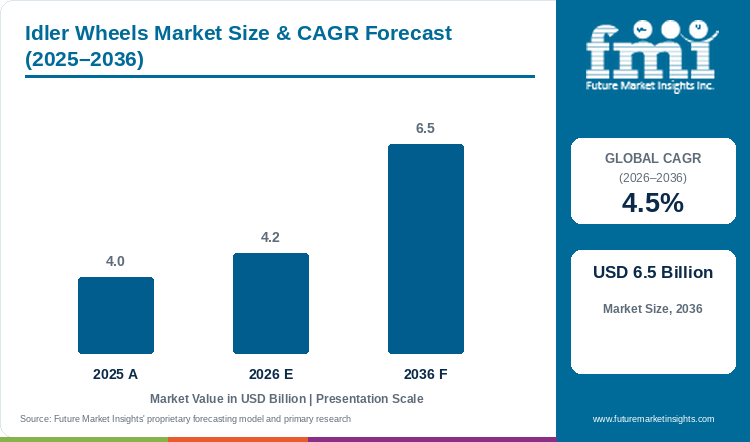
Idler wheel revenue is projected to grow from USD 4.2 Billion in 2026 to USD 6.5 Billion by 2036 at 4.5% CAGR, from a 2025 base of USD 4.0 Billion.
Valued at USD 4.2 Billion in 2026, the idler wheels market is on course for USD 6.5 Billion by 2036, expanding at 4.5% CAGR, according to FMI. Sales stood at USD 4.0 Billion in 2025, and the 2036 column on the market size chart reflects USD 2.3 Billion of new value gained after 2026.
Machine sales to end users picked up sharply in 2026, enlarging the tracked fleet that will need replacement idlers later in the decade. Caterpillar reported second-quarter 2026 Construction Industries sales of USD 8.3 billion, up 35%, on higher equipment sales to end users [1]. Machines already in the field are logging more hours as well. Komatsu's Komtrax data for August 2026 showed average monthly use of 69.9 hours per unit in North America, up 2.3%, and 212.7 hours in Indonesia, up 3.3% [2]. Machines in Japan averaged 49.3 hours over the same month, down 1.3%. Idler wear follows operating hours, so the 2025 and 2026 delivery wave is expected to turn into replacement orders before 2036. Tracked excavators hold 31% of idler demand in 2026, and replacement on this growing fleet will carry sales toward USD 6.5 Billion by 2036.
Key Takeaways
- Key players operating in the idler wheels market include Caterpillar, Komatsu, John Deere, Hitachi Construction Machinery, Berco (thyssenkrupp), Topy Industries, ITR America and VemaTrack.
- Track idler wheels take 28% of demand by wheel type in 2026, supported by steel-track excavators, dozers and crawler loaders.
- Tracked excavators make up 31% of demand by equipment type in 2026. Quarry and construction fleets add hours to these machines on every working shift.
- Chile is set for the fastest growth at 6.3% CAGR through 2036. South Africa follows at 5.9% as mining and public works keep heavy tracked machines busy.
Analyst Perspective
“Fleet owners will start booking undercarriage inspections at fixed hour intervals and ordering idlers ahead of failure, since machines bought in the 2025 and 2026 sales wave are now logging more monthly hours. Owners of tracked excavators, which make up 31% of idler demand in 2026, are likely to lock in stocked replacement parts with a dealer or multi-brand supplier near each site.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Idler Wheels Market Segmented?
The idler wheels market is divided into wheel type, equipment type, material, end use, sales channel and region.
As per FMI, the market is split by wheel type into track idler wheels, conveyor idlers, excavator idlers, dozer idlers and rubber track idlers. Equipment coverage spans tracked excavators, dozers, crawler loaders, conveyor systems and agricultural track systems. Materials are divided into cast steel, forged steel, rubber-coated, polyurethane and ductile iron idlers. Construction, mining, agriculture, material handling and forestry make up the end-use split, and sales are tracked across equipment OEMs, aftermarket replacement, dealer service and MRO distributors. Country estimates cover more than 30 countries grouped under seven regions.
Why Do Track Idler Wheels Lead the Idler Wheels Market by Wheel Type?
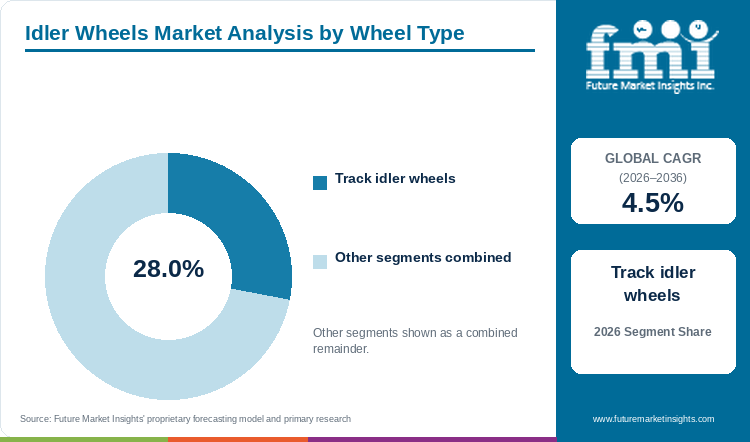
Track idler wheels take 28% of wheel type demand in 2026, led by steel-track crawler fleets.
Track idler wheels lead the wheel type split with 28% of demand in 2026, as every steel-track excavator, dozer and crawler loader runs front idlers that wear with each hour of travel. Conveyor idlers come next by volume, yet belt idlers are bought on conveyor maintenance budgets tied to belt replacement at mines and ports. Excavator, dozer and rubber track idlers each serve a narrower set of machine models, so order volumes per catalogue line stay smaller.
- Rental and contractor fleets are expected to keep track idlers on planned replacement lists through 2036, timed to undercarriage inspections.
- JCEMA reported in May 2026 that domestic service-parts shipment value in Japan increased 4% year over year in April 2026 [3].
Why Do Tracked Excavators Lead the Idler Wheels Market by Equipment Type?
With 31% of equipment-type demand in 2026, tracked excavators form the largest machine group.
Tracked excavators account for 31% of demand by equipment type in 2026, since quarry, mining and construction fleets run excavators on abrasive ground for long shifts. In May 2025, BGC Quarries in Western Australia switched the PC1250-8 excavator fleet to Komatsu Genuine Undercarriage and began using free inspections to time replacement [4]. Dozers carry heavy duty too, but contractors own fewer dozers than excavators, and agricultural track systems use lighter rubber-track platforms.
- Excavator owners are expected to order replacement idlers on hour-based inspection schedules, giving dealers earlier sight of each order.
- Komatsu's Komtrax data showed machines in Indonesia averaging 212.7 hours of use in August 2026, up 3.3% from a year earlier [2].
Why Does Cast Steel Lead the Idler Wheels Market by Material?
Cast steel remains the material of choice, holding 39% of 2026 demand by material.
Cast steel is the largest material group at 39% of demand in 2026, as one casting can be hardened on the running surface and priced in line with service life. Forged steel goes mainly to the heaviest strength duty, and rubber-coated, polyurethane and ductile iron idlers serve damping, contact or low-cost needs on smaller machines.
- Large fleets are expected to approve cast steel foundries with consistent hardening results and keep them on contract for years.
- In October 2025, Topy Industries reported the highest Excellent rating in Caterpillar's Supplier Excellence Recognition program for construction machinery undercarriage parts [5].
Why Does Construction Lead the Idler Wheels Market by End Use?
Construction buyers account for 35% of end-use demand for idler wheels in 2026.
Construction is the largest end-use buyer group at 35% of demand in 2026, as contractors move excavators, dozers and compact machines between sites with changing ground. Parts budgets on construction fleets follow job margins, and OEM dealers use timed discounts to pull wear-part spending forward. From May to July 2026, John Deere offered 15% off selected undercarriage components for compact track loaders and compact excavators at participating US and Canadian dealers [6]. Mining runs heavier duty per machine, but mining fleets are smaller in machine count, and agriculture, material handling and forestry use narrower ranges of tracked equipment.
- Contractors are expected to batch idler purchases between projects, when machines return to the yard for scheduled service.
- CECE reported in February 2026 that European construction equipment sales grew 4.6% in 2025, with 2% to 2.5% growth expected for 2026 [7].
Why Do Equipment OEMs Lead the Idler Wheels Market by Sales Channel?
Equipment OEMs control 42% of sales by sales channel in 2026 through first-fit supply.
Because machine makers fix idler geometry, sealing and material on each new model, first-fit volume flows through OEM supply chains, giving equipment OEMs 42% of demand by sales channel in 2026. Warranty terms then keep early replacement inside dealer networks. Aftermarket replacement suppliers gain orders once warranties expire, and dealer service and MRO distributors handle inspection-linked and stocked orders.
- OEMs are expected to bundle genuine idlers with inspection programs to hold owners through the second and third undercarriage change.
- Caterpillar reported in August 2026 that higher equipment sales to end users drove second-quarter Resource Industries sales up 20% to USD 4.6 billion [1].
What are the Drivers, Restraints, and Opportunities in the Idler Wheels Market?
More operating hours on tracked fleets are creating steady replacement orders for idler wheels, according to FMI. Fitment checks slow supplier switching, and inspection programs tied to local stock will open the largest new revenue pool through 2036.
- Driver: Rising machine hours in mining and construction turn into recurring idler replacement, as wear parts appear in every fleet maintenance budget.
- Restraint: Each idler has to match machine geometry, track pitch, tension and sealing, so qualification risk delays purchases from new suppliers.
- Opportunity: Wear inspections and stocked multi-brand catalogues can turn emergency failures into planned replacement orders for suppliers near each site.
Mine development in Latin America and Africa is adding tracked machines and operating hours. In April 2026, the Brazilian Mining Institute projected mining investment of US$76.9 billion for 2026 to 2030 [8]. New pits will add excavators and dozers across the surface mining equipment market, and the crawler excavator market is projected to rise from USD 54.5 Billion in 2026 to USD 71.1 Billion by 2036. Smaller machines add volume as well, with the compact construction equipment market projected to grow from USD 36.7 Billion in 2026 to USD 49.8 Billion by 2036. Every new machine joins the replacement pool once the first undercarriage wears out.
Supplier approval slows switching in the idler wheels market, as a cheaper part loses value once dimensional variation causes track misalignment. Weak heat treatment shortens wear life in abrasive duty, and procurement teams avoid brand changes during critical projects. Rebuilt components from the mining remanufacturing component market compete with new cast parts on large machines. Belt-driven operations follow a separate replacement cycle set by the conveyor belt market, which limits cross-selling from track idler lines.
Which Country CAGRs are Profiled in the Idler Wheels Market?
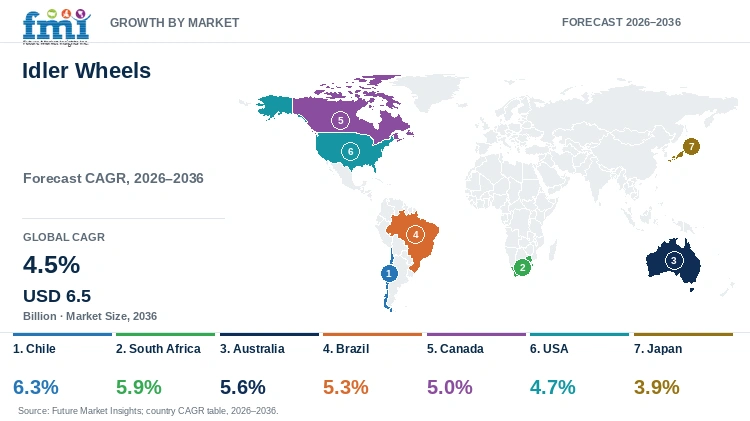
| Country | CAGR, 2026 to 2036 |
|---|---|
| Chile | 6.3% |
| South Africa | 5.9% |
| Australia | 5.6% |
| Brazil | 5.3% |
| Canada | 5% |
| USA | 4.7% |
| Japan | 3.9% |
How do Country-level CAGRs Compare in the Idler Wheels Market?
Mining-led economies form the faster group, with Chile at 6.3%, South Africa at 5.9% and Australia at 5.6% CAGR through 2036, as per FMI. Brazil and Canada are expected to grow at 5.3% and 5%, backed by new mine capital spending. The mature group of the USA at 4.7% and Japan at 3.9% is projected to grow on replacement across large installed fleets. Japan closes the country CAGR chart at the lower end, reflecting a 1.3% drop in average machine hours in August 2026 [2]. Rental fleets in the mining equipment rental market, projected to grow from USD 8.7 Billion in 2026 to USD 15.7 Billion by 2036, are expected to add hours in the faster group.
- Chile is projected to post the fastest growth at 6.3% CAGR through 2036. A record mining project pipeline will add machine hours on large excavators.
- Public infrastructure spending and busy mining fleets carry South Africa to 5.9% CAGR by 2036.
- Australia is expected to grow at 5.6% CAGR during the forecast period, supported by remote quarry and mining sites.
- Demand for idler wheels in Brazil will rise at 5.3% CAGR through 2036. Mining investment planned up to 2030 adds new tracked fleets.
- Higher mining capital spending sets Canada on a 5% CAGR by 2036 across remote mine sites.
- Growth of 4.7% CAGR in the USA during the forecast period will follow dealer programs that pull planned replacement forward.
- Japan is set for 3.9% CAGR through 2036, the lowest rate among the seven, with OEM specifications guiding service-parts supply.
The full report adds CAGR estimates for seven regions and more than 30 countries outside these seven profiles.
Country Outlook
- Cochilco put the 2025 to 2034 mining investment portfolio in Chile at a record of more than US$104 billion in December 2025 [9]. New mine projects will put large excavators to work in abrasive pits far from service hubs, and demand in Chile is projected at 6.3% CAGR through 2036.
- The government of South Africa stated in February 2026 that more than R1 trillion in public infrastructure investment had been committed over three years [10]. Public works will keep tracked fleets busy alongside mining, supporting 5.9% CAGR by 2036. Distributors serving both mining and construction fleets are expected to gain steady volume.
- Long transport distances to remote quarries push Australian buyers to plan undercarriage changes ahead of failure. BGC Quarries uses free Komatsu inspections to monitor wear and time replacement [4]. Australia is projected to grow at 5.6% CAGR during the forecast period.
- Brazil is set to grow at 5.3% CAGR through 2036, as the US$76.9 billion of mining investment projected for 2026 to 2030 adds new tracked fleets [8]. Mining, construction and farm machines across a wide territory need broad make-and-model coverage, favouring multi-brand suppliers with national distribution.
- Natural Resources Canada expects mining and quarrying capital spending to increase by 7% to C$18.5 billion in 2026, according to a May 2026 release [11]. More capital spending puts more machines to work at remote sites, and demand in Canada will rise at 5% CAGR by 2036.
- Komatsu's Komtrax data showed North American machines averaging 69.9 hours of use in August 2026, up 2.3% from a year earlier [2]. More hours bring earlier undercarriage wear, and John Deere offered 15% off selected undercarriage components at participating dealers from May 1 to July 31, 2026 [6]. The USA is projected at 4.7% CAGR through 2036.
- JCEMA reported in May 2026 that domestic service-parts shipment value rose 4% year over year in April 2026 [3]. Buyers in Japan follow equipment-maker specifications, so genuine OEM suppliers keep most replacement orders, and the country is projected at 3.9% CAGR through 2036.
Who are the Notable Companies in the Idler Wheels Market?
Caterpillar, Komatsu, John Deere, Hitachi Construction Machinery, Berco (thyssenkrupp) and Topy Industries are among the leading companies profiled by FMI across OEM, specialist and aftermarket idler supply.
Quarry fleet managers are tying undercarriage purchases to inspection programs, as BGC Quarries did in Western Australia when moving the PC1250-8 excavators to Komatsu Genuine Undercarriage with free wear checks [4]. Topy Industries received the highest Excellent rating for undercarriage parts in Caterpillar's 2025 supplier program, strengthening first-fit access [5]. John Deere used a 2026 dealer discount on undercarriage components to pull planned purchases forward [6]. OEMs hold pricing power on machines under warranty, and multi-brand suppliers compete on catalogue depth and local stock once warranties expire. Specialist makers also supply complete track groups covered in the earthmoving equipment undercarriage market. According to FMI, suppliers holding fitment-proven idlers in stock near remote fleets are set to gain the larger share of replacement orders through 2036.
- Integrated OEM Undercarriage Platforms: Caterpillar, Komatsu, John Deere and Hitachi Construction Machinery pair machine engineering with genuine parts, dealer inspections and service programs.
- Specialist Undercarriage Manufacturers: Berco (thyssenkrupp), Topy Industries and ITR America make idlers and track components for OEM programs and heavy-duty replacement fitments.
- Aftermarket and Distribution Specialists: VemaTrack, Trek Direct and Astrak Group hold model-specific idlers in stock for multi-brand fleets needing fast replacement.
Competitive Benchmarking
| Company | Idler and Undercarriage Breadth | OEM Engineering Integration | Aftermarket and Service Access | Geographic Reach |
|---|---|---|---|---|
| Berco (thyssenkrupp) | High | High | High | Global manufacturing and dealer coverage across tracked-equipment classes |
| Caterpillar | High | High | High | Global Cat equipment and dealer network |
| Komatsu | High | High | High | Global OEM reach with strong Asia-Pacific parts and service coverage |
| ITR America | High | Medium | High | North American distribution with wider ITR group reach |
| VemaTrack | Medium | Medium | High | International dealer-led aftermarket coverage |
| Topy Industries | Medium | High | Medium | Japan with supply operations in North America, China and Indonesia |
| Trek Direct | Medium | Low | High | North American replacement-parts supply |
| Astrak Group | Medium | Low | High | UK and European base with broader reseller support |
| John Deere | Medium | High | High | North America and other construction markets through dealer channels |
| Hitachi Construction Machinery | Medium | High | High | Global construction-equipment and selected-parts network |
Scoring basis: Idler and Undercarriage Breadth rates documented coverage of idlers and related track components, OEM Engineering Integration rates evidence of first-fit design or qualified OEM supply, and Aftermarket and Service Access rates dealer, distributor, inspection or online replacement channels. High reflects broad documented capability, Medium a narrower proven range, and Low limited public documentation or an adjacent role.
Key Developments
- In May 2025, Komatsu reported that BGC Quarries in Western Australia had moved the PC1250-8 excavators to Komatsu Genuine Undercarriage, using free inspections to plan replacement [4].
- Topy Industries announced the Caterpillar Supplier Excellence Award 2025 in October 2025, with the highest Excellent rating for construction machinery undercarriage parts and mining equipment wheels [5].
- John Deere opened a promotion in May 2026 offering 15% off selected undercarriage components for compact track loaders and compact excavators at participating US and Canadian dealers through July 31 [6].
Key Players
Integrated OEM Undercarriage Platforms
- Caterpillar
- Komatsu
- John Deere
- Hitachi Construction Machinery
Specialist Undercarriage Manufacturers
- Berco (thyssenkrupp)
- Topy Industries
- ITR America
Aftermarket and Distribution Specialists
- VemaTrack
- Trek Direct
- Astrak Group
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | 5 categories plus region: Wheel Type (Track idler wheels, Conveyor idlers, Excavator idlers, Dozer idlers, Rubber track idlers), Equipment Type (Tracked excavators, Dozers, Crawler loaders, Conveyor systems, Agricultural track systems), Material (Cast steel, Forged steel, Rubber-coated, Polyurethane, Ductile iron), End Use (Construction, Mining, Agriculture, Material handling, Forestry), Sales Channel (Equipment OEMs, Aftermarket replacement, Dealer service, MRO distributors), and Region |
| Quantitative units | USD Billion |
| Market definition | Revenue from idler wheels and idler assemblies sold within the stated wheel type, equipment type, material, end-use and sales channel segments. The definition excludes finished equipment revenue and adjacent components such as track chains, sprockets, non-idler rollers, complete rubber tracks and final drives, except for the idler component value. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | More than 30 countries, including Chile, the USA, Japan, Australia, Canada, Brazil and South Africa |
| Key companies profiled | A few of the leading companies out of many players covered in the study: Caterpillar, Komatsu, John Deere, Hitachi Construction Machinery, Berco (thyssenkrupp), Topy Industries, ITR America, VemaTrack, Trek Direct and Astrak Group |
| Forecast period | 2026 to 2036 |
| Approach | A hybrid bottom-up and top-down model built by FMI reconciles OEM first-fit demand, replacement activity, equipment exposure, channel checks and country operating conditions within the defined revenue boundary. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | Interviews with manufacturers, equipment OEMs, dealers, distributors and fleet maintenance teams test replacement triggers, fitment criteria, channel behavior, price sensitivity and service expectations. |
| Desk research | The analysis reviews official mining and infrastructure statistics, construction equipment shipment data, product documentation, supplier qualification notices and public parts programs, retaining sources specific to idlers and undercarriage demand. |
| Market sizing and forecasting | The sizing framework relates idler demand to new tracked-equipment output, installed fleet exposure, replacement cycles, application intensity, material and channel mix and country operating conditions. |
| Data validation | Estimates are cross-checked across OEM, specialist supplier, official and country sources. Finished-machine revenue, adjacent undercarriage components and double-counted replacement events are excluded. |
Idler Wheels Market by Segments
Idler Wheels Market Segmented by Wheel Type
- Track idler wheels
- Conveyor idlers
- Excavator idlers
- Dozer idlers
- Rubber track idlers
Idler Wheels Market Segmented by Equipment Type
- Tracked excavators
- Dozers
- Crawler loaders
- Conveyor systems
- Agricultural track systems
Idler Wheels Market Segmented by Material
- Cast steel
- Forged steel
- Rubber-coated
- Polyurethane
- Ductile iron
Idler Wheels Market Segmented by End Use
- Construction
- Mining
- Agriculture
- Material handling
- Forestry
Idler Wheels Market Segmented by Sales Channel
- Equipment OEMs
- Aftermarket replacement
- Dealer service
- MRO distributors
Idler Wheels Market Segmented by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] Caterpillar Inc. (2026, August 4). Second-quarter 2026 results, Form 8-K Exhibit 99.1.
- [2] Komatsu Ltd. (2026). Hours of machine use by region from Komtrax, data through August 2026.
- [3] Japan Construction Equipment Manufacturers Association (2026, May 27). Shipment Value Statistics for April 2026.
- [4] Komatsu Australia (2025, May 28). BGC Quarries makes the switch to a Komatsu Genuine Undercarriage.
- [5] Topy Industries (2025, October 20). Topy Industries receives the Caterpillar Supplier Excellence Award 2025.
- [6] John Deere (2026, May 1). 15% Off Select John Deere Undercarriage Components promotion.
- [7] CECE (2026, February 26). European construction equipment sector sees moderate recovery in 2025 with 4.6% growth in sales.
- [8] Brazilian Mining Institute (2026, April 15). Mining accounts for 66% of Brazil's trade surplus in the first quarter and projects US$76.9 billion in investments by 2030.
- [9] ProActivo (2025, December 11). Chile: Cartera de inversiones mineras alcanza récord con más de US$ 104 mil millones.
- [10] Parliament of South Africa (2026, February 12). State of the Nation Address by President Cyril Ramaphosa.
- [11] Natural Resources Canada (2026, May 22). Capital Expenditures.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will the Idler Wheels Market size be in 2026, and what value will the market reach by 2036?
- Which equipment-use and maintenance pressures will support demand for idler wheels through 2036?
- Why will track idler wheels hold the leading position within the Wheel Type category in 2026?
- What role will tracked excavators play in first-fit and replacement idler orders?
- Why will cast steel, construction and equipment OEMs anchor demand across the other categories?
- Which growth rates will Chile, South Africa, Australia, Brazil, Canada, the USA and Japan post till 2036?
- Which fitment, qualification and logistics checks will slow switching between idler suppliers?
- What will fleet and procurement teams need to verify before qualifying a new idler supplier?
Frequently Asked Questions
How Big Is the Idler Wheels Market Expected to Be in 2026?
Idler wheel sales will reach USD 4.2 Billion in 2026, up from USD 4.0 Billion in 2025, according to FMI. Revenue will rise to USD 6.5 Billion by 2036 as tracked fleets in mining and construction keep wearing undercarriage parts.
What Is the CAGR of the Idler Wheels Market from 2026 to 2036?
The market will grow at a 4.5% CAGR from 2026 to 2036. Replacement orders tied to machine hours will add most of the new value, and first-fit demand will follow new machine output.
Which Wheel Type Holds the Largest Share of the Idler Wheels Market?
Track idler wheels will lead with 28% of market share by wheel type in 2026. Track guidance and tension duty on steel-track excavators, dozers and loaders will support the position.
Which Material Leads the Idler Wheels Market?
Cast steel will account for 39% of market share by material in 2026. A practical balance of strength, hardened running surfaces and replacement cost will support the lead.
Which Country Is Expected to Grow Fastest in the Idler Wheels Market?
Chile will grow fastest at a 6.3% CAGR till 2036, followed by South Africa at 5.9% and Australia at 5.6%. Japan will post the slowest rate of the seven profiled countries at 3.9%.
What Notable Restraint Affects the Idler Wheels Market?
Key challenges will come from fitment and qualification, since an idler will need to match machine geometry, track pitch, tension and sealing. Buyers will delay a switch when a cheaper part lacks documented compatibility.
Which Are the Key Companies in the Idler Wheels Market?
Caterpillar, Komatsu, John Deere, Hitachi Construction Machinery, Berco (thyssenkrupp), Topy Industries, ITR America, VemaTrack, Trek Direct and Astrak Group rank among the leading companies covered by FMI. The report will place each company in one of three supplier groups.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Wheel Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wheel Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wheel Type, 2026 to 2036
- Track idler wheels
- Conveyor idlers
- Excavator idlers
- Dozer idlers
- Rubber track idlers
- Y-o-Y Growth Trend Analysis By Wheel Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Wheel Type, 2026 to 2036
- Global Market Analysis and Forecast, By Equipment Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Equipment Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Equipment Type, 2026 to 2036
- Tracked excavators
- Dozers
- Crawler loaders
- Conveyor systems
- Agricultural track systems
- Y-o-Y Growth Trend Analysis By Equipment Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Equipment Type, 2026 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material, 2026 to 2036
- Cast steel
- Forged steel
- Rubber-coated
- Polyurethane
- Ductile iron
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Construction
- Mining
- Agriculture
- Material handling
- Forestry
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Equipment OEMs
- Aftermarket replacement
- Dealer service
- MRO distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Market Attractiveness Analysis
- By Country
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Chile
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Wheel Type
- By Equipment Type
- By Material
- By End Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Berco (thyssenkrupp)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Caterpillar
- Komatsu
- ITR America
- VemaTrack
- Topy Industries
- Trek Direct
- Astrak Group
- John Deere
- Hitachi Construction Machinery
- Berco (thyssenkrupp)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


