
- Market Size (2026)
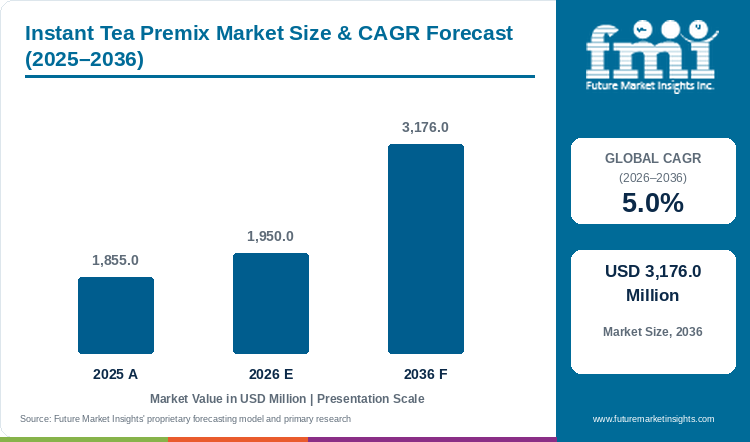
- USD 1950.0 Mn
- Forecast (2036)
- USD 3176.0 Mn
- CAGR (2026 to 2036)
- 5.0%
How big is the Instant Tea Premix Market in 2026?
The Instant Tea Premix Market is projected to reach USD 3,176 million by 2036, growing at a 5.0% CAGR from 2026 to 2036. FMI estimates the market at USD 1,950 million in 2026, after it was valued at USD 1,855 million in 2025. Mature tea markets add little volume, so growth comes mainly from India, where brands are adding sachet capacity [1]. Revenue therefore depends on flavor range, pack price and distribution in Asia, not on more tea drinkers in the West.
Tea leaf supply is concentrated, which limits where premix makers can buy. China, India and Kenya produced 53.0%, 18.2% and 8.5% of the 2024 world crop of over 7 million tonnes [8]. Producing countries keep more than 70% of their leaf and export 26.6% [8]. Kenya alone holds 31.6% of world tea exports, so importing markets buy from a narrow pool [8]. India supplied 21.8% of German tea imports in 2024, so one origin can move input costs there [8]. FMI expects leaf cost, more than drinker numbers, to decide premix margins in import-dependent markets.
Key Market Trends & Insights
- Large tea brands are extending loose-tea lines into ready-mix formats. Tata Consumer Products launched iced tea and matcha latte premixes in its summer 2026 range [2]. Matcha is the flavor most visible in the Japanese green tea export trade. Powdered green tea made up about 70.0% of fiscal 2025 export volume [3]. Matcha is ground tea leaf with particles of 1 to 100 micrometres that settle out of water [21]. Premix sachets differ: instant chai mixes tea and spice extracts with dehydrated milk [4].
- Manufacturing capacity is being built for sachet tea. Wagh Bakri Tea Group committed more than INR 100 crore to a plant at Dakor in Gujarat [1]. The plant lifts instant tea output from about 3,000 to 4,000 packets a day to roughly 20,000 [1]. The company website lists the Dakor factory as established in 2025 [25].
- Brands now sell reduced-sugar premixes beside the sweetened core. Girnar lists low-sugar premix chai in four flavors and stevia-sweetened chai in three [22][23]. Chai Point sells an instant chai with no added sugar in packs of 10 sachets [4].
Regional Highlights
- In Asia Pacific, India drives volume. The Tea Board data reported by Business Standard show India exported a record volume of tea in 2025, up 9.5%, with domestic production about 5.0% higher [5], and a large local leaf supply keeps premix input costs stable for Indian brands.
- In Europe, tea drinking is stable and not growing: Germans drank 67.2 litres of tea per person in 2024, of which 27.1 litres was black and green tea [6]. Premix suppliers there compete on herbal and functional blends, not on volume.
Instant Tea Premix Market Size and Forecast
Table 1: Instant Tea Premix Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 1,855.0 million |
| Estimated market size in 2026 | USD 1,950.0 million |
| Projected market size by 2036 | USD 3,176.0 million |
| CAGR from 2026 to 2036 | 5.0% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
Analyst Perspective
“Premix tea is bought for speed and a consistent cup, so buyers compare price per sachet and the number of flavors a brand can keep on shelf. Indian producers with their own tea blending capacity can hold prices while global brands pay more for imported leaf and freight. The main commercial risk is sugar: sweetened 3-in-1 sachets carry most of the revenue, yet health campaigns and retailer reformulation targets push brands toward reduced-sugar versions that cost more to make.”
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
How is the Instant Tea Premix Market segmented?
- By sugar content: Sweetened, No sugar or reduced sugar.
- By flavor: Cardamom, Ginger, Masala, Lemon, Lemongrass, Plain, Others.
- By sales channel: Supermarkets and hypermarkets, Convenience stores, Drug stores, Specialty stores, Traditional grocery stores, Online stores.
- By nature: Conventional, Organic.
- By region: North America, Latin America, Western Europe, Eastern Europe, South Asia and Pacific, East Asia, Middle East and Africa.
Why do Sweetened premixes lead by Sugar Content in the Instant Tea Premix Market in 2026?
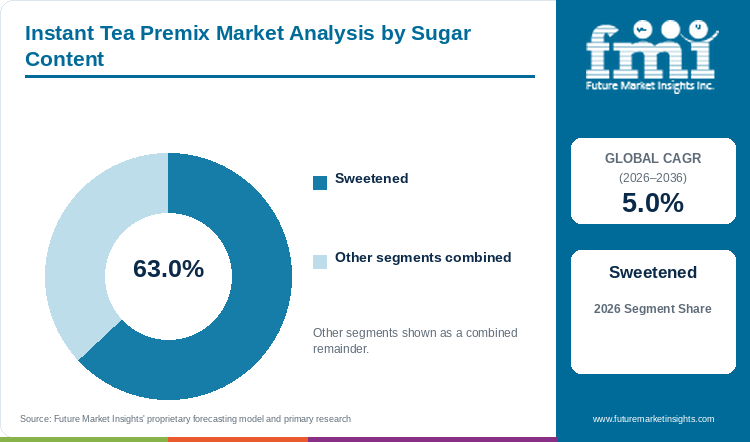
Sweetened premixes hold 63.0% of the Instant Tea Premix Market by sugar content in 2026.
Mass-market 3-in-1 sachets combine tea, milk powder and sugar so that the buyer only adds hot water. Nestle India's Everyday Chai Life range lists sugar as an ingredient in its Desi Masala sachet [7]. No-sugar and reduced-sugar premixes hold the remaining 37.0%.
Table 2: Sugar Content, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Sweetened | 63.0% |
| All Other Segments Combined Share | 37.0% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
Why does Cardamom lead by Flavor in the Instant Tea Premix Market in 2026?
Cardamom holds 22.5% of the Instant Tea Premix Market by flavor in 2026.
Cardamom is the flavor Girnar sells in the most premix formats [24]. Its cardamom versions include standard, 1 kg vending, jaggery and saffron blends [24]. Nestle India launched its sachet range around saffron and cardamom, desi masala, and ginger and lemongrass flavors [7]. The other six flavor groups share the remaining 77.5%.
Table 3: Flavor, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Cardamom | 22.5% |
| All Other Segments Combined Share | 77.5% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
Why do Supermarkets and hypermarkets lead by Sales Channel in the Instant Tea Premix Market in 2026?
Supermarkets and hypermarkets hold 29.0% of the Instant Tea Premix Market by sales channel in 2026.
FMI expects boxed multi-flavor packs to sell best where shelf space allows several flavors side by side. Other channels share the remaining 71.0% and include online stores, where Chai Point launched its instant chai [4]. The launch covered its own website and five online platforms, with 170 stores also stocking the range [4].
Table 4: Sales Channel, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Supermarkets and hypermarkets | 29.0% |
| All Other Segments Combined Share | 71.0% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
Why does Conventional lead by Nature in the Instant Tea Premix Market in 2026?
Conventional premixes hold 94.0% of the Instant Tea Premix Market by nature in 2026.
Mass brands buy conventional leaf at scale from India [5], while organic leaf costs more and supports only small premium ranges. Organic premixes hold the remaining 6.0%. Growth depends on retailers giving organic sachets shelf space, because they cost more per cup than mass-market brands.
Table 5: Nature, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Conventional | 94.0% |
| All Other Segments Combined Share | 6.0% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
What are the key drivers, restraints and opportunities?
Driver
Convenience tea demand in India. India produced about 1,370 million kg of tea in 2025 [5]. That domestic leaf supports local brands that convert loose tea into sachets. The chief executive of one Indian tea producer says convenience drives demand for its instant tea [1].
Capacity investment by regional brands. Capacity additions by regional brands reduce unit cost and let brands enter smaller towns [1].
Restraint
Flat tea demand in mature markets. German per-capita tea consumption eased slightly from 68.2 litres in 2023 [8], and US black tea imports fell by about 11.7% in 2025 while total US tea imports were down 7.1% in the first five months of 2026 [9]. Premix brands in these countries must win share from loose tea, since the category itself is not growing.
Sugar concerns. Most sachets still contain sugar [7], so brands must reformulate toward low-sugar versions, which raises production cost.
Opportunity
Matcha and iced premixes. Japan's green tea exports reached JPY 84.7 billion in fiscal 2025, about 2.2 times the previous year [3]. Matcha and iced tea formats were the focus of the summer 2026 premix launches [2]. Fine matcha with a particle diameter of 3.2 micrometres settles more slowly than normal matcha at 11.5 micrometres [21].
Export and specialty lines from Indian producers. Exports are 12 to 15% of Wagh Bakri sales, according to its chief executive [1]. Specialty blends such as jaggery and saffron already sit beside standard premixes in one Indian range [24].
Instant Tea Premix Market by Country (2026 to 2036)
Table 6: Instant Tea Premix Market Country Growth Forecast
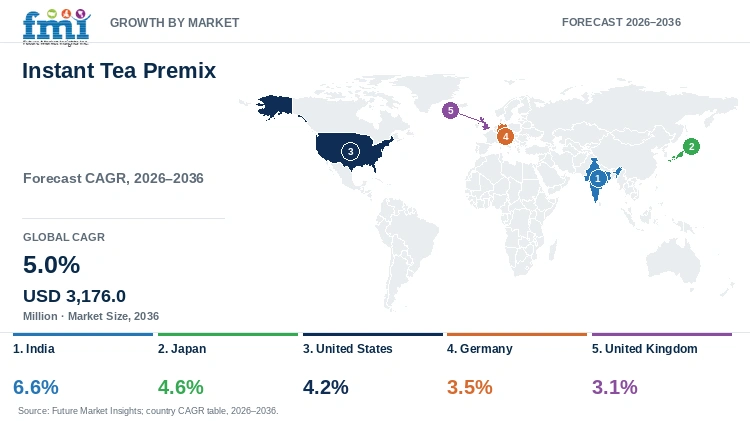
| Country | CAGR, 2026 to 2036 |
|---|---|
| India | 6.6% |
| Japan | 4.6% |
| United States | 4.2% |
| Germany | 3.5% |
| United Kingdom | 3.1% |
Source: Future Market Insights analysis of the instant tea premix market, 2026.
India
India is the production base and the fastest-growing demand centre. Tata Consumer reported India tea volume growth of 4.0% in the fourth quarter of fiscal 2026 [2]. Regional brands are adding sachet capacity [1]. These factors support a 6.6% CAGR for 2026 to 2036, the highest among the five profiled countries.
India's lead rests on a leaf supply that domestic blenders largely control. India produced 1,369.98 million kg of tea in 2025, and imports equal only 2 to 3% of output [15]. Assam and West Bengal supplied 50.20% and 30.01% of that crop [15]. Producers must sell 50% of their produce through licensed public auctions, which gives sachet makers a visible leaf price [15]. Auction prices rose in 2024 and moderated in 2025 [15], which eased leaf costs as the tax change arrived.
Tax added a second push, with GST on tea preparations cut from 18% to 5% on 22 September 2025 [13][14]. The cut covers preparations with a basis of tea, tariff heading 2101 20 [14]. At a fixed pre-tax price, the cut lowers the shelf price of a sachet in that heading by 11.0% [13]. FMI expects makers to hold pre-tax prices, which keeps margins intact. Sachets then reach more buyers while auction-priced leaf remains a visible cost [15]. Assam and West Bengal supplied 80.2% of the crop, so most leaf cost exposure sits in two states [15].
Japan
Japan's green tea exports reached JPY 84.7 billion in fiscal 2025 and anchor the matcha trade [3]. Ito En lists Oi Ocha Instant Green Tea with Matcha, a 40 g container that dissolves in cold water as well [26]. Premix growth is steady and not fast, at a 4.6% CAGR for 2026 to 2036.
Leaf cost, more than demand, explains why Japanese premix growth stays modest next to India. Tencha, the matcha leaf, was 8.6% of Japan's 75,100 tonnes of crude tea in 2025 [16]. It sold at JPY 8,562 per kg against JPY 1,746 for sencha, which is 4.9 times the price [16]. Tencha output has risen about 3.2 times since 2014, so matcha now pulls leaf away from other uses [16]. First-crop leaf tea fell from 40,682 tonnes in 2008 to 25,213 tonnes in 2025 [16]. Prices for the 2026 first crop were about double 2025 levels in Kagoshima and 70% higher in Shizuoka [16].
Japan shipped 12,612 tonnes of green tea abroad in 2025, and 69% of the volume was powder [16]. Powder earned JPY 6,927 per kg against JPY 3,007 for other forms, or 2.3 times as much [16]. FMI expects domestic premix makers to compete with export buyers for matcha-grade leaf, which limits margins. Cheap fourth-crop and autumn-winter leaf aimed at drinks rose from 18,475 tonnes in 2008 to 22,614 tonnes in 2025 [16]. FMI expects bottlers to hold the leaf cost advantage, so premix stays a complement to bottled tea. Premix makers can limit exposure by contracting fourth-crop leaf and leaving matcha-grade leaf to exporters.
United States
The US tea market is shifting toward ready-to-drink and functional products, with sales up and volume down according to Beverage Industry's 2025 review [10]. With imports also weak [9], premix growth is forecast at a 4.2% CAGR for 2026 to 2036, below the global rate.
Adult intake of coffee and tea in the United States is broad but flat [17]. The national health survey recorded a 20.1% share of adult nonalcoholic beverage grams from August 2021 to August 2023 [17]. That share shows no significant trend since the 2013 to 2014 survey [17]. It rises with age, from 13.2% at ages 20 to 39 to 26.8% at age 60 and older [17]. FMI expects premix growth to depend on adults aged 20 to 39, who show the lowest coffee and tea share. Sweetened beverages fell from 14.9% to 11.2% of adult intake between those surveys [17]. Sweetened premix therefore competes inside a shrinking category, which raises the cost of gaining new users.
Japanese export data show powder as the US growth format [16]. Japan shipped 4,431 tonnes of green tea to the United States in 2025, against 2,852 tonnes in 2024 [16]. That is a 55.4% rise, and 85% of the 2025 volume was powder [16]. The brewed base shows no trend, so US growth must come from format change and not from more drinkers. Powder can be mixed without steeping, but ground matcha settles while premixes use soluble tea extract [21][4]. Powder export growth therefore signals matcha demand and not direct premix demand. FMI expects US premix makers to treat matcha as a separate blend line because its settling behavior differs from soluble extract [21].
Germany
Germany is a stable, herbal-led tea market, with 40.1 litres of herbal and fruit tea per person and nearly 47 billion cups drunk [6]. Small volumes of premix are sold as functional and spiced blends, and the forecast is a 3.5% CAGR for 2026 to 2036 [8].
Germany grows slowly because its tea market is mature and already bag-based. Per-person consumption was 67.2 litres in 2024, down 1.5% on the year [8]. Bags hold 49% of black and green tea and 85% of herbal and fruit tea [8]. Cold brew tea bags have settled at about 1% of the market [8]. FMI expects new formats such as premix to gain share slowly in a market this settled. Supply is import-led, with India providing 10,443 tonnes, or 21.8% of 2024 imports [8]. Sri Lanka ranked second at 9,524 tonnes and China third at 8,837 tonnes [8]. These three origins supplied about 60% of German imports in 2024 [8].
EU packaging rules apply directly in Germany and weigh on sachet formats. Packaging must be at least 70% recyclable from 1 January 2030 and 80% from 1 January 2038 [18]. Tea bags and other packaging used and discarded with the product must be compostable from 12 February 2028 [18]. Japan's agriculture ministry notes that multilayer film with aluminium foil, used for tea packaging, is not recyclable [18]. FMI expects premix sachets built that way to need redesign, and small volumes spread that cost over few units. Packaging therefore becomes a nearer cost than leaf for German premix launches as the 2030 recyclability threshold approaches [18].
United Kingdom
Tea is a daily habit in Britain, with an estimated 60 billion cups drunk a year [11], so premix is a small niche next to the established brewed tea habit. The forecast is a 3.1% CAGR for 2026 to 2036, the lowest among the five countries.
Tea bags account for 97.5% of tea purchased in the UK, so convenience is already standard [19]. Germany buys 49% of black and green tea in bags [8], so the UK has less room for new formats. Among UK tea drinkers, 57% add dairy milk and 27% add sugar [19]. A sweetened premix therefore suits only the drinkers who add sugar. The other 73% do not add sugar, so unsweetened blends have the wider base [19]. Another 10% of drinkers add plant milk, which gives dairy-free blends a smaller second niche [19].
Concern over microplastics in tea bags is the other variable in UK premix demand. The industry body reports that plastic is about 1% of a filled tea bag by weight [20]. Producers are increasingly replacing polypropylene and nylon heat-seals with polylactic acid, a plant-derived bioplastic [20]. The Food Standards Agency advised in March 2025 that microplastics in food are unlikely to harm consumers [20]. A powder sachet is opened and not steeped, so FMI expects this debate to add little to UK premix demand. Unsweetened and dairy-free blends therefore offer UK suppliers a wider base than the sweetened 3-in-1 core [19].
Who are the notable companies in the Instant Tea Premix Market?
Notable companies in the Instant Tea Premix Market include Tata Consumer, Nestle India, Wagh Bakri, Girnar and Ito En.
Instant tea premix suppliers differ by their control of blended tea supply, sachet filling lines and shelf distribution. Tata Consumer reported tea volume growth of 4.0% in the fourth quarter of fiscal 2026 [2]. It added iced tea and matcha latte premixes to its summer 2026 range [2]. Wagh Bakri invested more than INR 100 crore in a Dakor plant [1]. The plant targets instant tea output of roughly 20,000 packets a day [1]. Girnar sells low-sugar premixes in four flavors and stevia-sweetened premixes in three [22][23]. Chai Point entered the category with instant chai in masala, ginger and cardamom [4]. Retailers should review shelf allocation between masala chai and the new formats [2].
Nestle India sells its Everyday Chai Life range in desi masala, saffron and cardamom, and ginger and lemongrass flavors [7]. The Desi Masala sachet lists sugar as an ingredient, and the company also sells sachet-in-a-cup formats [7]. Lipton Teas and Infusions separated from Unilever on 1 July 2022 and is owned by CVC Capital Partners Fund VIII [12].
Ito En lists instant matcha products, including Oi Ocha Instant Green Tea with Matcha and Oishi Matcha Latte Powder [26]. The instant green tea comes in a 40 g container and dissolves in cold water as well [26]. Powdered green tea made up about 70.0% of Japan's fiscal 2025 export volume [3]. Premix makers should secure matcha supply contracts before launching new lines [3].
Key Developments in the Instant Tea Premix Market
- On 8 May 2026 Tata Consumer reported summer premix launches: Tata Tea Gold Iced Tea and Tetley Matcha Latte [2].
Key Players in the Instant Tea Premix Market
- Tata Consumer Products Ltd.
- Nestle India Ltd.
- Wagh Bakri Tea Group
- Girnar Food & Beverages Pvt. Ltd.
- Lipton Teas and Infusions
- Ito En Ltd.
- Chai Point
Instant Tea Premix Market Report Scope
Table 7: Instant Tea Premix Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Powdered, granulated or paste tea mixes sold in sachets or cups that are prepared by adding hot water or milk, valued at manufacturer selling prices. Ready-to-drink tea, tea bags and loose-leaf tea are excluded. |
| Sugar Content | Sweetened; No sugar or reduced sugar |
| Flavor | Cardamom; Ginger; Masala; Lemon; Lemongrass; Plain; Others |
| Sales Channel | Supermarkets and hypermarkets; Convenience stores; Drug stores; Specialty stores; Traditional grocery stores; Online stores |
| Nature | Conventional; Organic |
| Regions and profiled countries | North America, Latin America, Western Europe, Eastern Europe, South Asia and Pacific, East Asia, Middle East and Africa. Profiled countries: India, Japan, United States, Germany, United Kingdom |
| Companies covered | Tata Consumer Products Ltd.; Nestle India Ltd.; Wagh Bakri Tea Group; Girnar Food & Beverages Pvt. Ltd.; Lipton Teas and Infusions; Ito En Ltd.; Chai Point |
| Quantitative Units | USD million |
Instant Tea Premix Market by Segments
Instant Tea Premix Market segmented by Sugar Content:
- Sweetened
- No sugar or reduced sugar
Instant Tea Premix Market segmented by Flavor:
- Cardamom
- Ginger
- Masala
- Lemon
- Lemongrass
- Plain
- Others
Instant Tea Premix Market segmented by Sales Channel:
- Supermarkets and hypermarkets
- Convenience stores
- Drug stores
- Specialty stores
- Traditional grocery stores
- Online stores
Instant Tea Premix Market segmented by Nature:
- Conventional
- Organic
Instant Tea Premix Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- South Asia
- Pacific
- East Asia
- Middle East
- Africa
- India
- Japan
- United States
- Germany
- United Kingdom
Research Sources and Bibliography
- [1] Agron Food Processing. (2025, January 8). Wagh Bakri Tea to Invest Rs. 100 Crore in New Manufacturing Unit in Gujarat. https://agronfoodprocessing.com/wagh-bakri-tea-to-invest-rs-100-crore-in-new-manufacturing-unit-in-gujarat/
- [2] Tata Consumer Products Ltd. (2026, May 8). Results for the Quarter and Year ended 31st March 2026. https://www.tataconsumer.com/news/results-quarter-and-year-ended-31st-march-2026
- [3] Adnkronos, citing Jiji Press. (2026, May 1). Japan Green Tea Exports Jump in FY 2025 amid Global Matcha Boom. https://english.adnkronos.com/2026/05/01/japan-green-tea-exports-jump-in-fy-2025-amid-global-matcha-boom/
- [4] Mediabrief. (2021, February 19). Chai Point announces its foray into instant chai category. https://mediabrief.com/chai-point-foray-into-instant-chai-category/
- [5] Business Standard. (2026, February 9). Tea exports spike 9.5% in 2025, output gains 5%. https://www.business-standard.com/markets/capital-market-news/tea-exports-spike-9-5-in-2025-output-gains-5-126020900800_1.html
- [6] Lebensmittelpraxis. (2025, June 25). Getraenkemarkt-Analyse: Teekonsum in Deutschland bleibt stabil. https://lebensmittelpraxis.de/industrie-aktuell/44840-getraenkemarkt-analyse-teekonsum-in-deutschland-bleibt-stabil.html
- [7] Nestle India. Introducing Nestle Everyday Chai Life. https://www.nestle.in/media/pressreleases/introducing-nestle-everyday-chai-life
- [8] Deutscher Teeverband. TeeReport 2025. https://www.teeverband.de/files/bilder/C-Tee-Report/Report2025/Tee-Report2025/Downloads/Report/TeeReport_2025_DS.pdf
- [9] Forbes Tea. (2026, May). U.S. Tea Imports - May 2026. https://www.forbestea.com/news/39
- [10] Beverage Industry. (2025). 2025 State of the Beverage Industry: Tea market sees sales up, volume declines. https://www.bevindustry.com/articles/97646-2025-state-of-the-beverage-industry-tea-market-sees-sales-up-volume-declines
- [11] GB News. Britons celebrate National Tea Day with 60 billion cups drunk every year in the UK. https://www.gbnews.com/news/national-tea-day-britons-celebrate-60billion-cups-drunk-per-year-uk
- [12] Unilever. (2022, July 1). Unilever announces completion of the sale of its tea business, ekaterra. https://www.unilever.com/news/press-and-media/press-releases/2022/unilever-announces-completion-of-the-sale-of-its-tea-business-ekaterra/
- [13] Press Information Bureau, Ministry of Finance. (2025, September 3). Recommendations of the 56th Meeting of the GST Council held at New Delhi. https://gstcouncil.gov.in/sites/default/files/2025-09/press_release_press_information_bureau_0.pdf
- [14] Central Board of Indirect Taxes and Customs. (2025, September 17). Notification No. 9/2025-Integrated Tax (Rate). https://courier.cbic.gov.in/ECCS/advisory/2025/NOTIFICATION%20NO.%209_2025-INTEGRATED%20TAX%20(RATE)%20-1759486719.pdf
- [15] Press Information Bureau, Ministry of Commerce and Industry. (2026, May 5). Indian Tea Sector: Production, Trade, Welfare and Sustainability. https://www.pib.gov.in/PressNoteDetails.aspx?id=158446&NoteId=158446&ModuleId=3
- [16] Ministry of Agriculture, Forestry and Fisheries of Japan. (2026, October). Cha o meguru josei (Situation of Tea, in Japanese). https://www.maff.go.jp/j/seisan/tokusan/cha/attach/pdf/ocha-201.pdf
- [17] National Center for Health Statistics. (2026, September 2). Nonalcoholic Beverage Consumption Among Youth and Adults: United States, August 2021 to August 2023 (NCHS Data Brief 568). https://www.cdc.gov/nchs/data/databriefs/db568.pdf
- [18] Ministry of Agriculture, Forestry and Fisheries of Japan, Export and International Affairs Bureau. (2026, September 10). EU Packaging and Packaging Waste Regulation (PPWR) from the Viewpoint of Food Exports (in Japanese). https://www.maff.go.jp/j/seisan/tokusan/cha/attach/pdf/ocha-199.pdf
- [19] UK Tea & Infusions Association. (2026). Tea Facts and Stats. https://www.tea.co.uk/tea-facts
- [20] UK Tea & Infusions Association. (2026). Frequently Asked Questions About Tea. https://www.tea.co.uk/tea-faqs
- [21] Haraguchi, Y., Imada, Y. and Sawamura, S. (2003, October 15). Production and Characterization of Fine Matcha for Processed Food. Nippon Shokuhin Kagaku Kogaku Kaishi, 50(10), 468-473. https://www.jstage.jst.go.jp/article/nskkk1995/50/10/50_10_468/_article/-char/en
- [22] Girnar Tea. Low Sugar Tea Premix Collection. https://girnar.com/collections/instant-premix-chais-low-sugar
- [23] Girnar Tea. Stevia Tea Premix Collection. https://girnar.com/collections/instant-premix-chais-with-stevia
- [24] Girnar Tea. Instant Premix Collection. https://girnar.com/collections/instant-premix
- [25] Wagh Bakri Tea Group. Manufacturing Facilities. https://www.waghbakritea.com/our-presence/manufacturing-facilities
- [26] ITO EN, Ltd. ITO EN Matcha. https://www.itoen-global.com/products/travelers_product/matcha/en.html
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Sugar Content, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sugar Content, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sugar Content, 2026 to 2036
- Sweetened
- No sugar or reduced sugar
- Y-o-Y Growth Trend Analysis By Sugar Content, 2021 to 2025
- Absolute $ Opportunity Analysis By Sugar Content, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Flavor, 2026 to 2036
- Cardamom
- Ginger
- Masala
- Lemon
- Lemongrass
- Plain
- Others
- Y-o-Y Growth Trend Analysis By Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets and hypermarkets
- Convenience stores
- Drug stores
- Specialty stores
- Traditional grocery stores
- Online stores
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- South Asia
- East Asia
- Middle East
- Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- South Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Pacific
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Middle East Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Japan
- United States
- Germany
- United Kingdom
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Sugar Content
- By Flavor
- By Sales Channel
- By Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tata Consumer Products Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nestle India Ltd.
- Wagh Bakri Tea Group
- Girnar Food & Beverages Pvt. Ltd.
- Lipton Teas and Infusions
- Ito En Ltd.
- Chai Point
- Tata Consumer Products Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 18: Western Europe Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 19: Western Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 20: Western Europe Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 26: South Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: South Asia Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 28: South Asia Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 29: South Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 30: South Asia Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 31: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 33: East Asia Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 34: East Asia Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 35: East Asia Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 36: Middle East Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 38: Middle East Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 39: Middle East Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 40: Middle East Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 41: Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 42: Africa Market Value (USD Million) Forecast by Sugar Content, 2021 to 2036
- Table 43: Africa Market Value (USD Million) Forecast by Flavor, 2021 to 2036
- Table 44: Africa Market Value (USD Million) Forecast by Sales Channel, 2021 to 2036
- Table 45: Africa Market Value (USD Million) Forecast by Nature, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Sugar Content
- Figure 6: Global Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Flavor
- Figure 9: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Sales Channel
- Figure 12: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Nature
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: South Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: North America Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 28: North America Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 29: North America Market Attractiveness Analysis by Sugar Content
- Figure 30: North America Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 31: North America Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 32: North America Market Attractiveness Analysis by Flavor
- Figure 33: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 34: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 35: North America Market Attractiveness Analysis by Sales Channel
- Figure 36: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 37: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 38: North America Market Attractiveness Analysis by Nature
- Figure 39: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 40: Latin America Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 41: Latin America Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 42: Latin America Market Attractiveness Analysis by Sugar Content
- Figure 43: Latin America Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 44: Latin America Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 45: Latin America Market Attractiveness Analysis by Flavor
- Figure 46: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 47: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 48: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 49: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 50: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 51: Latin America Market Attractiveness Analysis by Nature
- Figure 52: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Western Europe Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 54: Western Europe Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 55: Western Europe Market Attractiveness Analysis by Sugar Content
- Figure 56: Western Europe Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 57: Western Europe Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 58: Western Europe Market Attractiveness Analysis by Flavor
- Figure 59: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 60: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 61: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 62: Western Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 63: Western Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 64: Western Europe Market Attractiveness Analysis by Nature
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 66: Eastern Europe Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 67: Eastern Europe Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 68: Eastern Europe Market Attractiveness Analysis by Sugar Content
- Figure 69: Eastern Europe Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 70: Eastern Europe Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 71: Eastern Europe Market Attractiveness Analysis by Flavor
- Figure 72: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 73: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 74: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 75: Eastern Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 76: Eastern Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 77: Eastern Europe Market Attractiveness Analysis by Nature
- Figure 78: South Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 79: South Asia Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 80: South Asia Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 81: South Asia Market Attractiveness Analysis by Sugar Content
- Figure 82: South Asia Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 83: South Asia Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 84: South Asia Market Attractiveness Analysis by Flavor
- Figure 85: South Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 86: South Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 87: South Asia Market Attractiveness Analysis by Sales Channel
- Figure 88: South Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 89: South Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 90: South Asia Market Attractiveness Analysis by Nature
- Figure 91: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 92: East Asia Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 93: East Asia Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 94: East Asia Market Attractiveness Analysis by Sugar Content
- Figure 95: East Asia Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 96: East Asia Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 97: East Asia Market Attractiveness Analysis by Flavor
- Figure 98: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 99: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 100: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 101: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 102: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 103: East Asia Market Attractiveness Analysis by Nature
- Figure 104: Middle East Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 105: Middle East Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 106: Middle East Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 107: Middle East Market Attractiveness Analysis by Sugar Content
- Figure 108: Middle East Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 109: Middle East Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 110: Middle East Market Attractiveness Analysis by Flavor
- Figure 111: Middle East Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 112: Middle East Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 113: Middle East Market Attractiveness Analysis by Sales Channel
- Figure 114: Middle East Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 115: Middle East Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 116: Middle East Market Attractiveness Analysis by Nature
- Figure 117: Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 118: Africa Market Value Share and BPS Analysis by Sugar Content, 2026 and 2036
- Figure 119: Africa Market Y-o-Y Growth Comparison by Sugar Content, 2026-2036
- Figure 120: Africa Market Attractiveness Analysis by Sugar Content
- Figure 121: Africa Market Value Share and BPS Analysis by Flavor, 2026 and 2036
- Figure 122: Africa Market Y-o-Y Growth Comparison by Flavor, 2026-2036
- Figure 123: Africa Market Attractiveness Analysis by Flavor
- Figure 124: Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 125: Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 126: Africa Market Attractiveness Analysis by Sales Channel
- Figure 127: Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 128: Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 129: Africa Market Attractiveness Analysis by Nature
- Figure 130: Global Market - Tier Structure Analysis
- Figure 131: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the instant tea premix market in 2026?
FMI estimates the market at USD 1,950 million in 2026, up from USD 1,855 million in 2025. It is forecast to reach USD 3,176 million by 2036 at a 5.0% CAGR.
Which sugar content segment leads in 2026?
Sweetened premixes lead with 63.0% in 2026. No-sugar and reduced-sugar premixes hold 37.0%.
Which flavor leads in 2026?
Cardamom leads with 22.5% of 2026 revenue, while ginger, masala, lemon, lemongrass, plain and other flavors hold the remaining 77.5%.
Which country is forecast to grow fastest through 2036?
India has the highest forecast CAGR among the profiled countries at 6.6% during 2026 to 2036, followed by Japan at 4.6%.
Which channel sells the most instant tea premix?
Supermarkets and hypermarkets lead with 29.0% of 2026 revenue by sales channel.
Why is growth slower in Germany and the United Kingdom?
Tea drinking is stable in both countries, with Germany at 67.2 litres per person in 2024 [6].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
