

- Market Size (2026)
- USD 67.7 Bn
- Forecast (2036)
- USD 105.2 Bn
- CAGR (2026 to 2036)
- 4.5%
How big is Packaging Machinery Market in 2026?
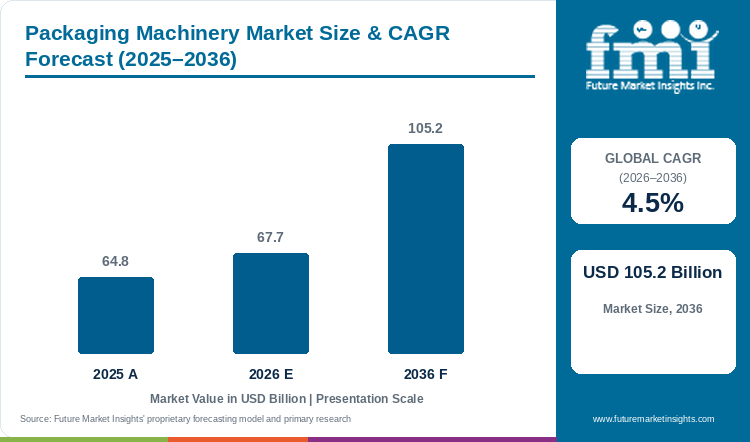
Sales in the packaging machinery market are projected to grow at 4.5% CAGR, with market size rising from USD 64.8 billion in 2025 to USD 67.7 billion in 2026 and reaching USD 105.2 billion by 2036.
Rising SKU turnover across consumer packaging facilities is compelling manufacturing plants to replace discrete manual packaging stations with integrated forming, filling, sealing, and inspection platforms. A packaging line running bottles, pouches, and cartons in short production runs loses valuable operating hours during mechanical changeovers, which is steering plant engineers toward machinery that maintains continuous line synchronization. According to Future Market Insights analysis, global packaging machinery valuation stood at USD 64.8 billion in 2025 and rises to USD 67.7 billion in 2026. The sector is projected to reach USD 105.2 billion by 2036, progressing at a 4.5% CAGR over the assessment period and generating USD 37.5 billion in added revenue. In August 2025, PMMI reported that factory automation investments are driven by severe manufacturing labor constraints, with 68% of consumer packaged goods plants deploying operator-independent machinery [1]. Form, fill and seal machines lead the machine type category with 12.0% share in 2026, as integrated dosing minimizes intermediate handling. This supports the hypothesis that capital allocation remains anchored to overall equipment effectiveness (OEE); however, heavy installation expenses and commissioning stoppages continue to delay full line replacement across mid-sized contract packagers.
Key Market Trends & Insights
- By machine type: Form, fill and seal machines hold 12.0% share in 2026, supported by continuous forming and smaller floor space requirements.
- By packaging technology: Automatic systems account for 35.0% in 2026, driven by the need to synchronize filling, capping, and inspection speeds.
- By end user: Homecare and personal care represents 45.0% in 2026, reflecting high bottle and pouch SKU rotation across retail brands.
- Lifecycle service is gaining prominence, as installed packaging assets deliver value only when original replacement parts and local diagnostic technicians remain accessible.
- Modular line architectures are witnessing rising adoption, allowing plant engineers to upgrade cartoning or sealing sections without decommissioning productive fillers.
Regional Highlights
- Fastest-growing evaluated country: Germany, at 4.1% CAGR from 2026 to 2036.
- By country: Japan at 4.0%, the USA at 3.4%, and the UK at 3.1% follow through the forecast period.
Market Size & Forecast
Table 1: Market Size and Forecast for the Packaging Machinery Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 64.8 billion |
| Estimated Market Size in 2026 | USD 67.7 billion |
| Projected Market Size by 2036 | USD 105.2 billion |
| CAGR, 2026 to 2036 | 4.5% |
| Added Revenue, 2026 to 2036 | USD 37.5 billion |
Commercial conditions differ across the profiled countries owing to divergent plant automation standards and regional machinery supply ecosystems. Plant managers no longer compare packaging lines solely by rated output per minute, as excessive changeover duration or intermediate stoppage erodes total output. In April 2026, Syntegon reported fiscal 2025 order intake of EUR 1.86 billion and revenue of EUR 1.75 billion, driven by pharmaceutical and food processing machinery demand [2]. This expansion confirms that procurement is concentrating around suppliers that combine mechanical platforms with lifecycle service, standardized software interfaces, and rapid field maintenance. Full line integration advantages established equipment conglomerates, whereas specialized builders must demonstrate rapid changeover tooling or superior dosing precision to secure capital allocations.
Installed-Line Productivity and Investment Sizing
Table 2: Installed-Line Productivity and Investment Sizing for the Packaging Machinery Market, 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 64.8 | 67.7 | 105.2 |
| Illustrative active packaging lines (million) | 0.82 to 0.92 | 0.85 to 0.96 | 1.18 to 1.34 |
| Average annual machinery spend per line (USD) | 70,400 to 79,000 | 70,500 to 79,600 | 78,500 to 89,200 |
| Automated line share indicator | 32% to 34% | 35% | 45% to 50% |
Throughput and Downtime Economics
Packaging machinery investment is increasingly being recovered through the time not lost during cleaning, setup and stoppage. This becomes more visible in food and personal care plants where a line may change from one pack size to another several times in a week. Connected controls make alarms visible at line level, while machine vision systems can stop an off-spec pack before it travels through secondary packaging. However, connected machinery can also transfer one fault across the full line when interfaces are not tested properly. Modular equipment is therefore likely to gain attention as capacity can be inserted in stages and the plant is not required to disturb every installed machine at one time.
Table 3: Illustrative Throughput and Downtime Indicators for Packaging Lines
| Metric | Conventional Line | Connected Automatic Line | Commercial Effect |
|---|---|---|---|
| Format change duration | 45 to 120 minutes | 10 to 45 minutes | More saleable production time |
| Unplanned downtime indicator | 6% to 10% | 3% to 6% | Higher scheduled output |
| Operator positions per line | 4 to 8 | 2 to 5 | Lower repetitive handling |
| Data capture | Machine-level | Line-level | Faster root-cause analysis |
Table 4: Segment Revenue Indicators for the Packaging Machinery Market, 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 67.7 billion | Source report value |
| Automatic technology revenue, 2026 | USD 23.7 billion | 35.0% share |
| Form, fill and seal revenue, 2026 | USD 8.1 billion | 12.0% share |
| Homecare and personal care revenue, 2026 | USD 30.5 billion | 45.0% share |
Analyst Perspective
“Packaging machinery demand will remain connected with the production time recovered between one batch and the next. Suppliers able to reduce change parts, simplify operation and keep service close to the plant are likely to secure a longer position on the line.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the packaging machinery market segmented?
The packaging machinery market is segmented by machine type, packaging technology, and end user. In 2026, form, fill and seal machines are projected at 12.0%, automatic systems at 35.0%, and homecare and personal care at 45.0%.
By machine type: Form, fill and seal; filling and dosing; labeling, decorating and coding; cartoning machines; case handling; closing; wrapping and bundling; palletizing and depalletizing; bottling line; conveying machines.
By packaging technology: Automatic, semi-automatic, and manual.
By end user: Beverages, food, chemicals, homecare and personal care, pharmaceuticals, and others.
Why do Form, Fill and Seal Machines lead the machine type category?
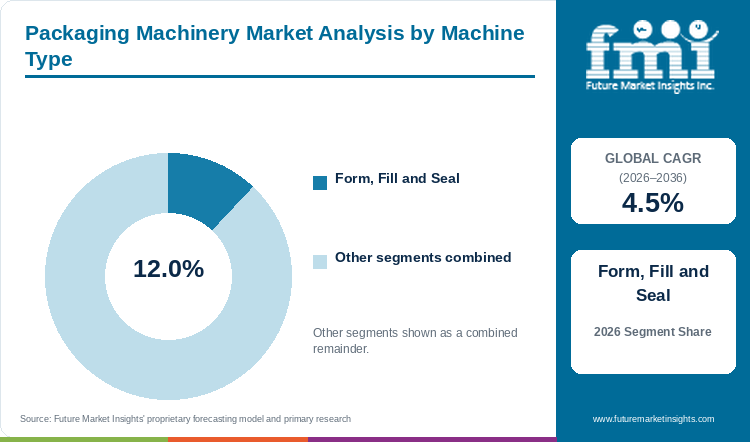
Form, fill and seal machines are projected to command 12.0% of machine type revenue in 2026, supported by continuous forming and reduced transfer handling.
Table 5: Machine Type Share for the Packaging Machinery Market (percentage share), 2026
| Machine Type | Share (2026) |
|---|---|
| Form, Fill and Seal | 12.0% |
| Other Segments Combined | 88.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Machine Type Leadership and Market Growth for the Packaging Machinery Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.5% |
| Leading Segment | Form, Fill and Seal |
Form, fill and seal equipment is gaining preference where flexible packs are produced continuously, as the package is formed from rollstock and is closed soon after dosing. This reduces transfers and also limits the floor area required for separate machines. The 12.0% share in 2026 is therefore supported by operating convenience rather than one application alone. Demand may improve further as cup filling machines and sealing controls are adjusted for recyclable structures, although weak seal windows on newer films can increase rejection if temperature and dwell time are not maintained.
- Continuous forming, dosing, and sealing supports the 12.0% share where production volume justifies an integrated single-chassis platform.
- In March 2026, Syntegon introduced HFX flow-wrapping and TRX topload cartoning as core modules of its neXt architecture for automated lines [3].
What supports Automatic Systems as the preferred packaging technology?
Automatic systems are estimated to represent 35.0% of packaging technology demand in 2026, reflecting synchronized multi-station line control and reduced manual supervision.
Automatic systems are preferred when the delay created at one station starts affecting every pack moving after it. Servo control, recipe storage and automatic reject functions reduce the dependence on an operator repeating the same adjustment through a long production run. This helps explain the 35.0% share in 2026. Also, integration of case packing machines and palletizers is moving automation towards the end of line, where manual lifting remains high. Adoption can still remain slow in short runs because engineering, guarding and validation costs do not reduce only because fewer packs are produced.
- Automatic systems hold 35.0% in 2026 as consistent line timing becomes necessary to eliminate upstream bottlenecks during peak shifts.
- In June 2025, the International Federation of Robotics reported that global installations of industrial robots and automated packaging cells in consumer goods manufacturing expanded by 9% year-on-year [4].
How does Homecare and Personal Care maintain end-user dominance?
Homecare and personal care is anticipated to contribute 45.0% of end-user revenue in 2026, driven by high container variety and frequent brand-driven packaging changeovers.
Homecare and personal care demand is shaped by product variety more than one uniform package. Pumps, trigger sprays, bottles and refill pouches require different handling, while the branded finish must remain close across every size placed on a retail shelf. This gives the end user a 45.0% share in 2026 because recipe control and fast change parts can be used repeatedly across the same product family. Growth in personal care wipes also puts pressure on flow wrapping and secondary packing capacity. The share could face some limitation where contract manufacturers continue to use semi-automatic lines for smaller brand volumes, as flexibility can be more valuable than maximum speed.
- The 45.0% share is underpinned by high retail volume and routine shifts between trigger sprays, flexible pouches, and rigid bottles.
- In May 2025, Cosmetics Europe documented that European personal care manufacturing reached EUR 96 billion, requiring high-speed automated packaging lines for continuous multi-SKU filling [5].
What are the drivers, restraints, and opportunities in the packaging machinery market?
In the packaging machinery market, high SKU turnover and labor shortages drive automated line investment, extensive capital outlay and validation shutdowns restrain adoption, and modular retrofit platforms create significant lifecycle service opportunities through 2036.
- Driver: SKU multiplication across retail brands forces packaging plants to replace dedicated manual stations with recipe-controlled automated systems through 2036.
- Restraint: High upfront capital requirements and line validation shutdowns delay equipment commissioning among contract packaging facilities through 2036.
- Opportunity: Modular mechanical platforms and standardized PLC architectures allow plant engineers to modernize selected packaging cells without decommissioning installed lines through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Manufacturers are trying to remove manual transfers first from the points where an error can stop the full line. Filling accuracy, label verification and case formation are receiving attention because a fault at these points either wastes product or delays dispatch. In January 2025, the U.S. Census Bureau reported that shipments of food and beverage packaging machinery grew 4.2% year-over-year, reflecting sustained factory automation investment [6]. Automatic technology reaching 35.0% in 2026 shows that this movement is established, but it has not removed the requirement for lower-cost machinery. Demand for label solutions and inspection-linked coding can strengthen as traceability becomes attached with the package itself. The opportunity will be higher for suppliers that can connect a new machine with older fillers and conveyors, since complete line replacement is not practical for every plant.
Risk Assessment of the Packaging Machinery Market: Integration and Capital Friction
A packaging line can appear productive during a factory test and still lose output after installation when upstream and downstream machines do not exchange signals at the same speed. In October 2025, European mechanical engineering association VDMA warned that machine delivery lead times and interface integration challenges added 12 to 16 weeks to line commissioning schedules [7]. Remote access can shorten service time; however, cybersecurity rules may prevent an outside engineer from reaching the machine when the fault occurs. Increasing use of screw capping machines and vision checks also adds more interfaces which need to be validated. Suppliers that do not define acceptance speed, product loss and changeover conditions before shipment may face delayed payment and repeated site work.
Commercial Opportunity Analysis: Modular Platforms and Lifecycle Services
Modular machinery gives an established plant a path to automate one constraint at a time. A cartoner can be replaced before the filler, or a new control and vision layer can be added while mechanical equipment remains in use. In August 2025, Syntegon presented its Amplified Heat Sealing technology, enabling hermetic sealing of mono-material recyclable films across horizontal flow-wrappers [8]. Such development gains commercial value when recyclable films run without increasing leakage or scrap. Growth in biodegradable packaging will similarly favour machines having a wider sealing window. At the same time, adoption of next-generation packaging technology and automated packaging solutions creates recurring aftermarket engineering agreements for modular line builders.
Packaging Machinery Market by Country (2026 to 2036)
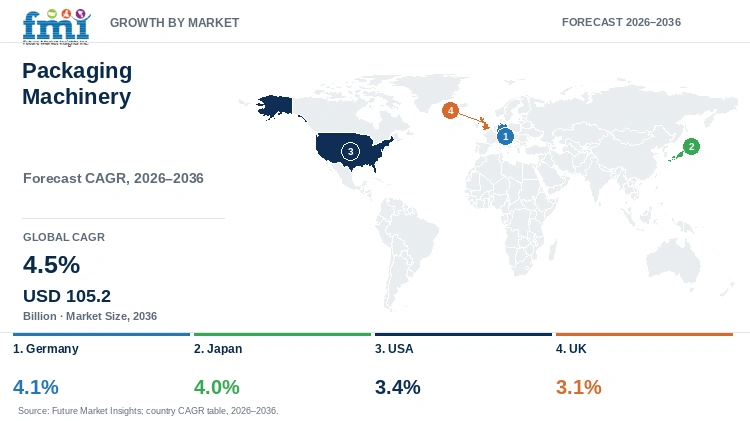
As per Future Market Insights, Germany records the highest growth rate among the four evaluated countries at a 4.1% CAGR from 2026 to 2036, followed closely by Japan at 4.0%, the USA at 3.4%, and the UK at 3.1%. Across these advanced industrial markets, commercial success depends on engineering precision, regulatory line validation, local field engineering coverage, and the ability to integrate flexible changeover kits into existing factory layouts.
Table 7: Country CAGR and Primary Growth Levers for the Packaging Machinery Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 4.1% | Engineering exports and pharmaceutical packaging automation |
| Japan | 4.0% | Precision engineering and compact automated systems |
| USA | 3.4% | E-commerce fulfillment and automation upgrades |
| UK | 3.1% | Regulated pharmaceutical and food production |
Source: Future Market Insights analysis
Germany Packaging Machinery Market Outlook (2026 to 2036)
Germany's packaging machinery market is projected to expand at a 4.1% CAGR from 2026 to 2036, supported by an advanced mechanical engineering export base and demanding domestic pharmaceutical packaging standards. German manufacturers both construct and operate high-speed automated packaging machinery, creating a sophisticated domestic testbed for servo-driven cartoning and sterile blister packaging lines. In September 2025, the Federal Statistical Office of Germany (Destatis) reported that domestic production of specialized industrial machinery rose 2.8% year-over-year [9]. However, elevated electrical power costs and skilled engineering labor shortages impose severe cost pressures on mid-tier machinery fabricators. Equipment buyers increasingly favor modular packaging architectures that incorporate remote diagnostic interfaces, enabling German OEMs to maintain machine uptime across international customer facilities without dispatching on-site engineers.
Key takeaway: In Germany, advanced machinery exports and strict pharmaceutical validation protocols establish a highly resilient commercial market for servo-driven automated packaging lines.
Japan Packaging Machinery Market Outlook (2026 to 2036)
In Japan, packaging machinery demand is forecast to advance at a 4.0% CAGR through 2036, driven by extreme factory footprint constraints and an acute shortage of factory floor operators. Japanese food and personal care manufacturers require exceptionally compact, high-precision packaging cells that execute filling, capping, and optical verification within restricted floor footprints. In July 2025, the Ministry of Economy, Trade and Industry (METI) documented that Japan's production index for automated packaging machinery increased by 3.4% [10]. The primary operational hurdle stems from conservative capital replacement cycles, as Japanese plant managers routinely maintain legacy mechanical equipment for decades. Equipment vendors successfully stimulate procurement by offering modular robotic drop-in stations and computerized changeover tooling that integrate seamlessly into existing conveyor networks without triggering structural factory modifications.
Key takeaway: In Japan, severe physical plant footprint limitations and demographic labor declines drive steady demand for high-precision, ultra-compact automated packaging machines.
USA Packaging Machinery Market Outlook (2026 to 2036)
United States packaging machinery revenue is estimated to grow at a 3.4% CAGR between 2026 to 2036, underpinned by rapid warehouse fulfillment automation and nationwide plant modernization initiatives. Consumer packaged goods producers across North America face persistent technical labor shortages, compelling facilities to automate repetitive end-of-line operations including case packing, palletizing, and stretch wrapping. In November 2025, the U.S. Bureau of Labor Statistics reported that packaging and filling machine operator vacancies remained elevated across manufacturing hubs [11]. Nonetheless, fragmented plant legacy systems and divergent communication protocols between older fillers and newer cartoners often escalate integration costs. Suppliers that provide comprehensive turnkey integration, pre-shipment factory acceptance testing (FAT), and rapid regional technical support capture preferred vendor status across tier-one food and beverage corporations.
Key takeaway: In the USA, persistent factory labor deficits and high-volume e-commerce fulfillment operations make turnkey packaging line modernization a primary capital expenditure priority.
UK Packaging Machinery Market Outlook (2026 to 2036)
The United Kingdom packaging machinery sector is projected to register a 3.1% CAGR over the assessment period, propelled by stringent food hygiene standards and compliance with extended producer responsibility (EPR) packaging directives. British food processors and contract packaging houses operate under tight retail delivery schedules, requiring automated inspection, metal detection, and coding machinery that eliminates mislabeling penalties. In June 2025, the UK Office for National Statistics (ONS) recorded that food and beverage manufacturing turnover reached GBP 112 billion, sustaining steady capital allocations for automated packaging equipment [12]. However, industrial electricity tariffs and cautious corporate borrowing create friction against large greenfield installations. Consequently, procurement activity concentrates heavily on brownfield retrofits, automated case erectors, and compact flow-wrappers that deliver visible capital payback within 18 months.
Key takeaway: In the UK, rigorous retail food safety compliance and regulatory packaging waste mandates direct capital expenditure toward high-speed coding and modular packaging retrofits.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the packaging machinery market?
Syntegon Technology GmbH, Krones AG, IMA Group, Coesia S.p.A., MULTIVAC Group, Tetra Pak, ProMach, and GEA Group are notable companies operating in this market.
Future Market Insights analysis indicates that the competitive landscape divides between full-line turnkey engineering conglomerates and specialized single-stage machinery manufacturers. Full-line integrators provide unified controls from bulk product infeed down to end-of-line palletizing, reducing integration liabilities for plant owners. Conversely, specialist builders focus on proprietary dosing valves, hermetic sealing jaws, or high-resolution machine vision inspection systems. Procurement directors evaluate vendors based on certified line efficiency, guaranteed changeover speed, Mean Time to Repair (MTTR), and local availability of factory-trained service engineers.
- Turnkey line platforms: Syntegon Technology GmbH, IMA Group, Coesia S.p.A., and ProMach integrate multiple machine modules into unified plant control systems.
- Liquid food and beverage platforms: Krones AG, Tetra Pak, and GEA Group connect aseptic processing with high-speed bottling, cartoning, and secondary packaging.
- Flexible food packaging specialists: MULTIVAC Group competes through specialized thermoforming, vacuum packaging, tray sealing, and automated robotic infeed solutions.
Competitive Benchmarking: Packaging Machinery Market
Table 8: Competitive Benchmarking for the Packaging Machinery Market (qualitative capability ratings), 2026
| Company | Machine Breadth | Automation Depth | Lifecycle Access | Geographic Reach |
|---|---|---|---|---|
| Syntegon Technology GmbH | High | High | High | High |
| Krones AG | High | High | High | High |
| IMA Group | High | High | High | High |
| Coesia S.p.A. | High | High | High | High |
| MULTIVAC Group | High | High | High | High |
| Tetra Pak | High | High | High | High |
| ProMach | High | High | High | Medium |
| GEA Group | Medium | High | High | High |
Scoring basis: High indicates public evidence across several relevant machine categories or service regions. Medium indicates a more concentrated capability.
Key Developments in the Packaging Machinery Market
- In April 2026, Syntegon reported fiscal 2025 financial results with 10% revenue expansion to EUR 1.75 billion and total order intake reaching EUR 1.86 billion [2].
- In March 2026, Syntegon unveiled its neXt system architecture, integrating HFX flow-wrapping and TRX topload cartoning platforms for automated food plants [3].
- In August 2025, Syntegon introduced Amplified Heat Sealing technology, enabling high-speed processing of mono-material recyclable films across horizontal flow-wrappers [8].
Key Players in the Packaging Machinery Market
Full-Line Turnkey Platform Providers
- Syntegon Technology GmbH
- IMA Group
- Coesia S.p.A.
- ProMach
Liquid Food and Beverage Packaging Specialists
- Krones AG
- Tetra Pak
- GEA Group
Flexible Packaging and Thermoforming Platforms
- MULTIVAC Group
Packaging Machinery Market - Report Scope
Table 9: Report Scope for the Packaging Machinery Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Machine Type; Packaging Technology; End User |
| Quantitative Units | USD Billion |
| Market Definition | Revenue from filling, sealing, labeling, wrapping, cartoning, palletizing, and inspection machinery. Packaging materials and standalone non-packaging robots are excluded. |
| Regions Covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, UK, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Syntegon, Krones, IMA Group, Coesia, MULTIVAC, Tetra Pak, ProMach, GEA Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Packaging Machinery Market - Research Methodology
Table 10: Research Methodology for the Packaging Machinery Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with machinery manufacturers, packaging engineers, line operators, system integrators, component suppliers, and plant procurement managers across the value chain to validate equipment reliability, changeover protocols, and purchasing decisions. |
| Secondary Research | Secondary research included analysis of corporate financial filings, equipment patent databases, trade publications, packaging machinery association reports, technical engineering papers, and government industrial production statistics. |
| Market Sizing and Forecasting | Market sizing and projections for 2026 to 2036 were established through integrated top-down and bottom-up models evaluating machine unit volumes, average selling prices, plant replacement cycles, and end-user capital expenditures. |
| Data Triangulation and Validation | Market estimates were validated against manufacturing capital expenditure trends, factory automation benchmarks, industrial robot shipments, and historical machinery delivery data to prevent double-counting adjacent processing categories. |
Packaging Machinery Market by Segments
Packaging Machinery Market segmented by Machine Type:
- Form, Fill and Seal
- Filling and Dosing
- Labeling, Decorating and Coding
- Cartoning Machines
- Case Handling
- Closing
- Wrapping and Bundling
- Palletizing and Depalletizing
- Bottling Line
- Conveying Machines
Packaging Machinery Market segmented by Packaging Technology:
- Automatic
- Semi-Automatic
- Manual
Packaging Machinery Market segmented by End User:
- Beverages
- Food
- Chemicals
- Homecare and Personal Care
- Pharmaceuticals
- Others
Packaging Machinery Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] PMMI. (2025, August 20). State of the Industry 2025. PMMI Reports.
- [2] Syntegon. (2026, April 16). Syntegon posts record year in 2025 and aims for further growth. Syntegon Press Releases.
- [3] Syntegon. (2026, March 31). neXt system architecture for the Factory of the Future. Corporate Technical Announcements.
- [4] International Federation of Robotics. (2025, June 25). World robotics industrial automation and packaging applications report. IFR Statistical Division.
- [5] Cosmetics Europe. (2025, May 14). European personal care manufacturing and packaging market overview. Industry Economic Reports.
- [6] U.S. Census Bureau. (2025, January 28). Manufacturers' shipments, inventories, and orders: Food and industrial machinery. United States Department of Commerce.
- [7] Verband Deutscher Maschinen- und Anlagenbau (VDMA). (2025, October 15). Packaging machinery economic survey and lead-time report. VDMA Industry Publications.
- [8] Syntegon. (2025, August 7). Scalable automated packaging solutions and Amplified Heat Sealing at PACK EXPO. Commercial Product Bulletins.
- [9] Federal Statistical Office of Germany (Destatis). (2025, September 18). Production and export indices in specialized mechanical engineering. Statistisches Bundesamt.
- [10] Ministry of Economy, Trade and Industry (METI). (2025, July 22). Indices of industrial production and machinery manufacturing in Japan. Government of Japan.
- [11] U.S. Bureau of Labor Statistics. (2025, November 19). Occupational employment and wages for packaging machine operators. U.S. Department of Labor.
- [12] Office for National Statistics. (2025, June 26). UK manufacturer sales by product: Food, beverage, and packaging lines. UK National Statistics Reports.
This bibliography is provided for reader reference and is not exhaustive. The full report contains supporting source review.
This Report Answers
- How large is the packaging machinery market in 2026 and what is forecast for 2036?
- Which automation and workforce pressures support machinery investment?
- Why do form, fill and seal machines lead machine type demand?
- Why do automatic systems hold the largest technology share?
- How do country growth rates differ across Germany, Japan, the USA, and the UK?
- Which companies supply integrated packaging lines and lifecycle service?
- What capital and integration risks limit equipment adoption?
- What should buyers test before approving a packaging machinery supplier?
Frequently Asked Questions
How big is the packaging machinery market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global packaging machinery market will reach USD 67.7 billion in 2026 and USD 105.2 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at a 4.5% CAGR over the assessment period.
Which machine type leads the market?
Form, fill and seal machines are projected to hold 12.0% share in 2026, supported by continuous forming and minimal product transfer.
Which packaging technology leads demand?
Automatic packaging technology is expected to account for 35.0% share in 2026, driven by high-speed line synchronization and labor substitution.
Which end user holds the largest share?
Homecare and personal care applications are projected to represent 45.0% of demand in 2026, owing to diverse container geometries and branded SKU rotation.
Who are the key players?
Notable companies operating in the global packaging machinery market include Syntegon Technology GmbH, Krones AG, IMA Group, Coesia S.p.A., MULTIVAC Group, Tetra Pak, ProMach, and GEA Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Machine Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Machine Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Machine Type, 2026 to 2036
- Form, Fill and Seal
- Filling and Dosing
- Labeling, Decorating and Coding
- Cartoning Machines
- Case Handling
- Closing
- Wrapping and Bundling
- Palletizing and Depalletizing
- Bottling Line
- Conveying Machines
- Y-o-Y Growth Trend Analysis By Machine Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Machine Type, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Technology, 2026 to 2036
- Automatic
- Semi-Automatic
- Manual
- Y-o-Y Growth Trend Analysis By Packaging Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Technology, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Beverages
- Food
- Chemicals
- Homecare and Personal Care
- Pharmaceuticals
- Others
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Machine Type
- By Packaging Technology
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Machine Type
- By Packaging Technology
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Machine Type
- By Packaging Technology
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Machine Type
- By Packaging Technology
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Syntegon Technology GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Krones AG
- IMA Group
- Coesia S.p.A.
- MULTIVAC Group
- Tetra Pak
- ProMach
- GEA Group
- Syntegon Technology GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


