
- Market Size (2026)
- USD 1029.0 Mn
- Forecast (2036)
- USD 1613.4 Mn
- CAGR (2026 to 2036)
- 4.6%
How big is Pectin Market in 2026?
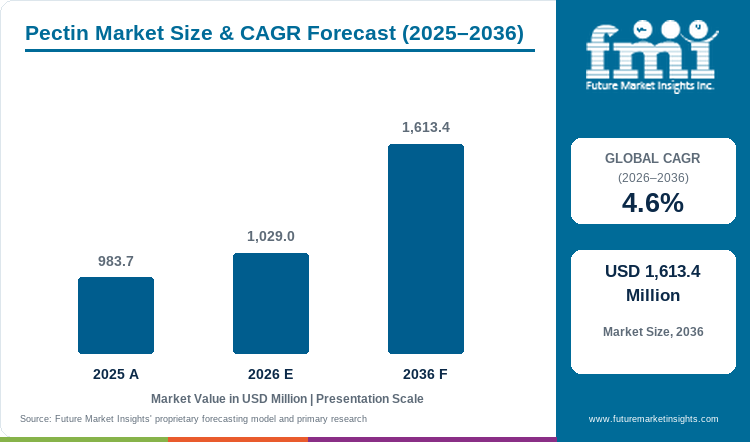
The pectin market is valued at USD 1,029.0 million in 2026 and is projected to reach USD 1,613.4 million by 2036, growing at a 4.6% CAGR.
Sales of pectin are estimated to rise at 4.6% CAGR through 2036. Market valuation increases from USD 983.7 million in 2025 to USD 1029.0 million in 2026 and is estimated to reach USD 1613.4 million by 2036. Food makers are using pectin to control gel strength, thickness, and stability in jams, dairy foods, drinks, and fillings. Recipe teams are adjusting pectin as sugar, acid, calcium, heat, or storage conditions change. Lower-sugar recipes are creating demand for specialized pectin grades, while plant teams are checking texture before changing an approved grade. In May 2025, Tate & Lyle's full-year results confirmed that CP Kelco achieved 8% volume growth, with strong pectin performance identified as the primary driver of that growth. CP Kelco's reported growth matches the current need for grades that keep texture stable from laboratory trials through full production.
Food additives such as pectin are part of food systems with different rules, plant sizes, and export requirements. UK food makers are using E 440 pectin, while German processors are running several recipes on shared production lines. Japanese and South Korean exporters are keeping detailed ingredient records because finished foods must pass destination-market checks. US plants are following federal pectin definitions and are testing each recipe before changing grades. In March 2026, the U.S. Census Bureau reported USD 88.4 billion in US food-product shipments for January 2026. The large US production base is creating many pectin uses, while national rules and export needs are changing how buyers approve each grade.
Key Takeaways
- Food makers are using pectin to form gels, control thickness, keep particles suspended, and maintain stable texture.
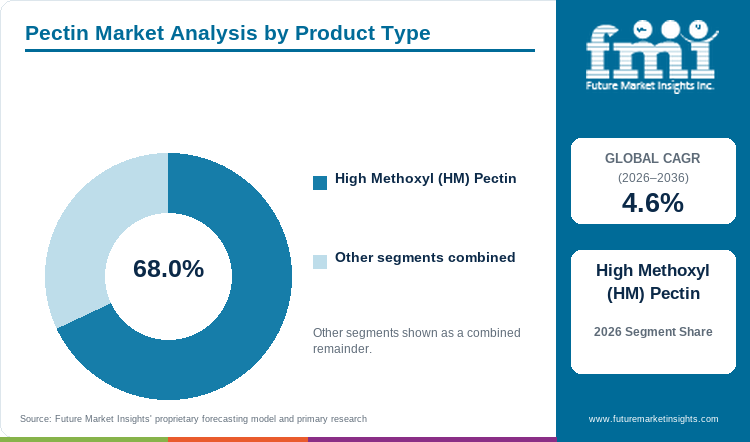
- In 2026, high methoxyl (HM) pectin is expected to lead the product type category with 68.0% share, owing to its fit with acidic high-solids recipes. Food makers are choosing it for recipes with more sugar or dissolved solids.
- By application, the food & beverages category is estimated to hold 71.0% in 2026, reinforced by use across everyday food formats. Fruit products, dairy foods, drinks, confectionery, and bakery fillings keep pectin in regular use.
- Lower-sugar foods and functional gummies are increasing demand for specialized pectin grades because less sugar changes how stable texture forms.
- Pectin performance is sensitive to fruit source and extraction steps from batch to batch. Changes in pectin chemistry alter gel behavior and increase approval testing for buyers.
- Notable companies include CP Kelco (Tate & Lyle), DuPont de Nemours, Inc. (IFF), Cargill, Incorporated, Herbstreith & Fox GmbH & Co KG, Silvateam S.p.A., Compañía Española de Algas Marinas (CEAMSA), and Yantai Andre Pectin Co. Ltd.
Analyst Perspective
"Lower-sugar foods are opening a clear pectin opportunity because less sugar changes how a stable gel forms. Producers need plant-scale texture and heat-stability data so buyers can approve one grade across bakery, dairy, or fortified gummy lines."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the pectin market segmented?
The pectin market is segmented by Product Type, Application, Source, and Region.
The pectin market uses three segment axes with region as the geographic split.
Product type covers high methoxyl (HM) pectin and low methoxyl (LM) pectin.
Application covers food and beverages, pharmaceuticals, and cosmetics.
Source covers citrus fruits (oranges, tangerines and mandarins, grapefruit, lemon and lime), pears, apples, plums, banana, and others such as peach and berries.
Why does high methoxyl (HM) pectin anchor the product type category?
High methoxyl (HM) pectin forms gels in acidic recipes with more sugar or other dissolved solids. HM pectin contains more methyl ester groups than LM pectin. Food scientists call this chemical difference the degree of esterification. The degree of esterification changes how pectin chains join and form a gel. HM and LM pectin are gelling agents that respond differently as sugar, acid, and calcium levels change. Low methoxyl (LM) pectin relies more on calcium and works well in lower-sugar recipes. Recipe teams choose HM or LM pectin based on the recipe's sugar, acid, and calcium levels. A poor match creates weak gels, uneven texture, or more plant testing.
- By product type, high methoxyl (HM) pectin is forecast to represent 68.0% in 2026, attributable to its fit with acidic high-solids recipes. Food makers use HM pectin where sugar and acid help form the required gel.
- Food teams are choosing pectin grades that match established processing conditions. Clear test records are helping buyers keep the same texture across production runs.
Why does food & beverages dominate the application category?
Pectin is useful across food and beverage production because it can thicken, stabilize, firm, and form gels. FDA lists pectin as a thickener, stabilizer, texturizer, emulsifier, and firming agent. Food manufacturers are using these functions to keep products thick, smooth, mixed, or firm during production and storage. Food stabilizers such as pectin are helping fruit and dairy products keep a consistent texture. Drink and confectionery teams are using pectin to suspend particles and form gels. Bakery teams are using selected grades in fillings and lower-sugar recipes. Pharmaceutical and cosmetic uses are important but follow narrower approval paths. Food makers can use one approved grade across several lines if recipes and process conditions are similar. Plant teams are testing each line to confirm the grade gives the same result during production.
- The food & beverages category is set to lead the application category with 71.0% share in 2026, supported by broad food use. Fruit products, dairy foods, drinks, confectionery, and bakery fillings keep this application in regular demand.
- Bakery ingredients such as pectin need to keep texture stable during mixing, heating, and storage. Buyers are testing bake stability and finished texture before approving a grade for production. Plant trials show whether the same pectin grade keeps structure as a recipe scales from laboratory work to full bakery production.
What are the drivers, restraints and opportunities in the pectin market?
In the pectin market, the key driver is the recurring need across food and beverage production to control gel strength, thickness, particle suspension, and texture stability from recipe development through factory-scale production, since sugar reduction, shelf-life changes, and new flavor systems keep recipe teams adjusting pectin grades and each recipe must be tested before a grade change is approved, the key restraint is the natural variation in fruit raw material and extraction conditions that changes pectin yield, gel strength, and batch-to-batch consistency, since differences in peel quality, extraction heat, and process control can alter gel behavior enough to require new recipe testing before a buyer accepts a grade, and the key opportunity is growing demand from lower-sugar foods and fortified gummies for specialized pectin grades that form stable gels with less sugar or tolerate heat-sensitive active ingredients, as reduced solids change the gel-forming conditions that high methoxyl pectin normally relies on and plant-scale texture and heat-stability data are helping buyers approve suitable grades with fewer trial runs.
- Driver: Food processors are using pectin to control texture and stability across routine commercial production.
- Restraint: Fruit source and extraction conditions change pectin performance and increase buyer approval work.
- Opportunity: Lower-sugar foods and functional gummies are increasing demand for pectin grades that work within tighter recipe limits.
Recipe changes keep pectin tied to routine texture work
Food makers are using pectin in routine recipe work because texture needs to stay consistent from trial batches to factory runs. Sugar reduction, shelf-life changes, and new flavor systems are changing how a pectin grade sets. In September 2025, IFF announced DANISCO GRINDSTED Pectin FB 420, a bake-stable citrus-peel pectin positioned as a label-friendly starch alternative for reduced-sugar bakery applications. The grade supports stable texture and glossy finish in recipes with less sugar. Recipe teams are testing each grade under the same heat, acid, and storage conditions the plant uses in production. Clear grade data helps plant teams reach approval with fewer trial runs. Plant teams can then use the same grade across several product lines with similar process conditions.
Source and extraction variation raise buyer approval work
Raw fruit source and extraction steps change pectin yield, gel strength, and consistency between batches. Citrus pectin is a common commercial source, so peel quality and extraction control affect final pectin performance. Hot acid extraction uses heat and creates acidic wastewater. Plants must manage higher energy use, corrosion risk, and tighter process control. In April 2025, Tate & Lyle completed an evaporator upgrade at Lille Skensved that cut energy use 6% and carbon emissions 7%. The upgrade now lowers energy demand and gives plant teams tighter control over extraction. Batch changes can force new recipe tests before buyers accept a grade. Stable raw materials and controlled extraction settings help suppliers protect gel behavior and avoid another approval cycle.
Lower-sugar recipes open more specialized pectin uses
Lower-sugar foods and functional gummies are increasing demand for pectin grades that still form stable gels with less sugar. Less sugar changes the solids balance that helps pectin form a stable gel. Fortified gummies contain vitamins, minerals, or proteins that can change texture during heating. In August 2026, Herbstreith & Fox GmbH & Co KG highlighted H&F Pectin systems for fortified gummies. The company reported heat stability and tolerance for active ingredients in gummy lines that do not use starch molds. CEAMSA lists pectin for capsules and medical syrups in health products. Food teams are testing confectionery ingredients with alternative sweeteners and heat-sensitive compounds before full production. Clear plant results help buyers approve recipes that combine lower sugar with heat-sensitive active ingredients.
What are the country CAGRs in the pectin market?
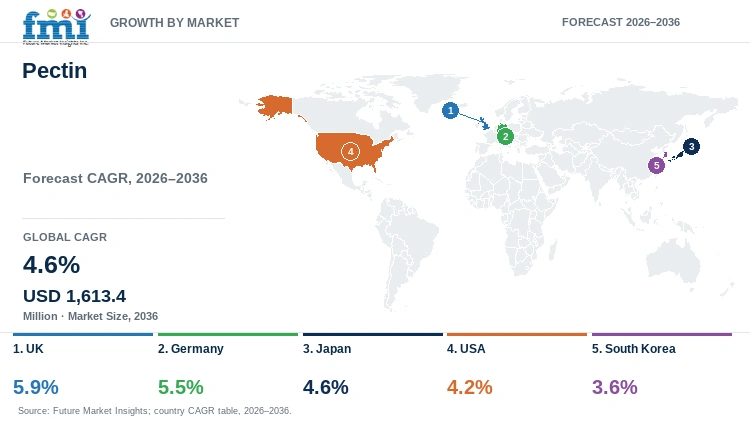
| Country | CAGR |
|---|---|
| UK | 5.9% |
| Germany | 5.5% |
| Japan | 4.6% |
| USA | 4.2% |
| South Korea | 3.6% |
How do country-level CAGRs compare in the pectin market?
Pectin buying conditions are different across countries because food rules, plant size, export activity, and supplier support change approval work. Export-focused buyers are asking for stronger ingredient records, while large domestic plants are focusing on consistent performance across many recipes.
- UK food manufacturers are using pectin across bakery, dairy, and fruit recipes that need stable texture during recipe changes.
- German food plants are favoring pectin grades that give the same result across several recipes and production lines.
- Japanese processed-food exporters need stable texture and are keeping clear ingredient records for domestic and export shipments.
- Across the USA, large food plants are using supplier testing as they change pectin grades.
- South Korean confectionery and beverage makers are keeping clear pectin records for local approval and export checks.
Across other regions, processors are matching pectin grades with local food rules, plant conditions, and export requirements before approval.
Country-wise Analysis
- Pectin demand in the UK is forecast to rise at 5.9% CAGR over the forecast period, supported by diverse food manufacturing needs. UK food makers are using E 440 pectin in dairy, bakery, confectionery, and fruit products. In July 2026, the Office for National Statistics reported that food manufacturing represented 22.9% of UK manufacturers' product sales in 2025. The UK's large food industry gives suppliers many recipes to support, but each recipe needs its own texture and process checks. Lower-sugar products need extra work because less sugar changes the conditions that form a firm gel. Buyers are asking for test records that link each grade to the intended recipe and plant conditions. Clear supplier support is helping buyers change grades without losing texture consistency.
- Germany's pectin sector is projected to record 5.5% CAGR during the assessment period, shaped by prepared-food production and multi-recipe plants. German food plants are running several recipes on shared production lines, so they value grades that give the same result. In January 2026, Destatis reported ready-meal output worth EUR 4.5 billion during the first three quarters of 2025. Germany's prepared-food industry keeps demand steady for texture control across several recipes. Lower-sugar recipes need more testing because reduced solids change pectin gel conditions. Technical teams are helping buyers match each grade with the recipe and production conditions. Supplier changes can trigger new plant trials, so clear test records make comparison easier and reduce approval work.
- Pectin sales in Japan are forecast to expand at 4.6% CAGR by 2036, reinforced by processed-food export activity. Processed-food exporters need stable texture and are keeping clear ingredient records for domestic products and export shipments. In February 2026, MAFF reported that Japan's agricultural, forestry, fishery, and food exports increased 12.8% during 2025. MAFF identified processed foods as a prominent export group for the same year. Export activity makes consistent gel performance and complete ingredient records more important to processors. Suppliers are matching grades with local recipes and plant limits. Natural-origin claims do not replace texture and shelf-life tests. Qualified grades help manufacturers keep the same result across domestic and export channels while meeting local quality checks.
- Adoption of pectin in the USA is estimated to expand at 4.2% CAGR through 2036, supported by a large food-production base. Federal rules define pectin made from edible plant materials such as citrus peel and apple pomace. In March 2026, the Census Bureau reported USD 88.4 billion in US food-product shipments for January 2026. The scale of US food production is creating many recipes that need stable thickness, gel strength, and texture. Large food plants are testing process stability before changing a pectin grade. Supplier labs are matching each pectin grade to the customer's sugar, acid, and heat conditions. Federal definitions guide identity checks, but recipe tests decide whether a grade works on the line. Clear test records are reducing switching work across large food programs.
- In South Korea, pectin demand is predicted to advance at 3.6% CAGR through 2036, influenced by export-focused processed-food production. MFDS additive rules and export-focused food production are shaping how processors review each grade. In January 2026, MAFRA reported South Korean agri-food and food exports reached USD 10.41 billion during 2025, part of a record USD 13.62 billion in total K-Food Plus exports for the year. Export channels include confectionery, drinks, bakery products, and other processed foods that need consistent texture. Suppliers are matching pectin records with local rules during plant approval. Product teams are testing how sugar level and plant conditions affect the grade. Imported ingredients face extra review if records do not match the declared product. Clear documentation is helping buyers approve new sources while keeping the same recipe performance for domestic and export sales.
Who are the notable companies in the pectin market?
Notable companies in the Pectin market include CP Kelco (Tate & Lyle), DuPont de Nemours, Inc. (IFF), Cargill, Incorporated, Herbstreith & Fox GmbH & Co KG, Silvateam S.p.A., Compañía Española de Algas Marinas (CEAMSA), and Yantai Andre Pectin Co. Ltd.
CP Kelco (Tate & Lyle), IFF, and Cargill sell pectin within wider food-ingredient businesses and support customers with recipe testing. Herbstreith & Fox, Silvateam, and CEAMSA specialize in pectin and related hydrocolloids that control texture and thickness. Yantai Andre Pectin manufactures in China under dsm-firmenich control. Naturex is a legacy name because Givaudan no longer runs the former pectin business. Buyers are comparing each supplier's grades, production locations, and recipe support before choosing a source.
- CP Kelco (Tate & Lyle), DuPont de Nemours, Inc. (IFF), and Cargill, Incorporated combine pectin with wider food-ingredient ranges and recipe support.
- Herbstreith & Fox GmbH & Co KG and Silvateam S.p.A. specialize in pectin and related food hydrocolloids that control texture and thickness. CEAMSA supplies pectin for food and health applications, while Yantai Andre supplies
Competitive Benchmarking: Pectin Market
| Company | Methoxyl Grade Coverage | Food Formulation Breadth | Health & Nutrition Pectin Evidence | Geographic Reach |
|---|---|---|---|---|
| CP Kelco (Tate & Lyle) | High | High | Medium | Americas and Europe; global application network |
| DuPont de Nemours, Inc. (IFF) | Medium | High | High | Manufacturing on two continents with global food-ingredient coverage |
| Cargill, Incorporated | High | High | Medium | Americas, Europe, and Asia-Pacific pectin coverage |
| Herbstreith & Fox GmbH & Co KG | High | High | High | Europe and North America with international pectin support |
| Silvateam S.p.A. | High | High | Medium | Europe-based pectin production with international distribution |
| Compañía Española de Algas Marinas (CEAMSA) | Medium | High | High | Spain and Philippines production with worldwide distribution |
| Yantai Andre Pectin Co. Ltd. | Medium | High | Medium | China-based manufacturing with dsm-firmenich ownership |
High means current company materials show both HM and LM pectin or another broad range of pectin grades. Medium means the public range is narrower. Low means public evidence shows limited current pectin coverage or an exit from the category. A High food-use rating means current materials show pectin across several food or beverage applications. Health and nutrition ratings look for pectin in supplements, capsules, syrups, or health-focused gummies. The table compares current published pectin evidence and does not rank overall company size.
Key Developments in the Pectin Market
- In December 2025, CEAMSA reported an AI digital twin project for pectin extraction. A digital twin uses plant data to model the extraction process in software. Production teams are using the model to spot process changes earlier and protect batch consistency before pectin leaves the plant.
- In November 2025, Herbstreith & Fox GmbH & Co KG presented H&F Pectin with fruit fibers for savory sauces and dressings. The system targets thickness and texture in ketchup, barbecue sauce, and similar products. Application teams are using trials to adjust sauce thickness while keeping pectin and fruit fiber as the main texture ingredients.
- In April 2025, dsm-firmenich raised its stake in Yantai DSM Andre Pectin Company Limited to 90.5%. The deal gave dsm-firmenich more control over a China-based pectin manufacturer. Current ownership now links Andre's production with dsm-firmenich ingredient development and sales network.
Key Players in the Pectin Market
Global ingredient and application suppliers
- CP Kelco (Tate & Lyle)
- DuPont de Nemours, Inc. (IFF)
- Cargill, Incorporated
Pectin and hydrocolloid specialists
- Herbstreith & Fox GmbH & Co KG
- Silvateam S.p.A.
- Compañía Española de Algas Marinas (CEAMSA)
- Yantai Andre Pectin Co. Ltd.
Pectin Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Application; Source |
| Quantitative Units | USD million |
| Market Definition | Revenue from pectin sold within the Product Type, Application and Source universe is included. Downstream finished-product revenue and adjacent or substitute product revenue are excluded. Bundled formulation systems are included only to the extent revenue is attributable to pectin itself; services and unrelated components are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Japan; South Korea |
| Key Companies | CP Kelco (Tate & Lyle); DuPont de Nemours, Inc. (IFF); Cargill, Incorporated; Herbstreith & Fox GmbH & Co KG; Silvateam S.p.A.; Compañía Española de Algas Marinas (CEAMSA); Yantai Andre Pectin Co. Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Pectin Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Pectin Market by Segments
Pectin Market segmented by Product Type:
- High Methoxyl (HM) Pectin
- Low Methoxyl (LM) Pectin
Pectin Market segmented by Application:
- Food & Beverages
- Pharmaceuticals
- Cosmetics
Pectin Market segmented by Source:
- Citrus Fruits
- Oranges
- Tangerines/Mandarins
- Grapefruit
- Lemon and Lime
- Pears
- Apples
- Plums
- Banana
- Others (Peach, Berries)
Pectin Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- U.S. Government Publishing Office. (2025). Code of Federal Regulations, Title 21, §184.1588 Pectins.
- U.S. Food and Drug Administration. (n.d.). Substances Added to Food: Pectin. Retrieved September 24, 2026.
- Food Standards Agency. (2025, April 1). Pectins (E 440).
- Ministry of Food and Drug Safety, Republic of Korea. (2025, March 18). Food Additives Code (Notice No. 2025-15).
- Dixit, S. S., Muruganandam, L., & Moorthy, I. G. (2025). Pectin from fruit peel: A comprehensive review on various extraction approaches and their potential applications in pharmaceutical and food industries. Carbohydrate Polymer Technologies and Applications, 9, 100708.
- Arumuganainar, D. G., Ramesh, D. L., Pandurangan, P., Sunkar, S., Abraham, S., Samrot, A. V., Sainandhini, R., Thirumurugan, A., & Moovendhan, M. (2025). Sustainable pectin extraction: Navigating industrial challenges and opportunities with fruit by-products - A review. Process Biochemistry, 154, 234-245.
- World Health Organization. (2025). Compendium of Food Additive Specifications.
- Kalita, P., Bhattacharjee, B., Pachuau, L., & Roy, S. (2025). Recent trends in pectin sources, extraction, and active-edible coating applications. Food Control, 171, 111105.
- Tate & Lyle. (2025, April 1). Tate & Lyle welcomes government officials to Lille Skensved to celebrate completion of carbon reduction and energy efficiency project.
- Tate & Lyle. (2026, March 30). Tate & Lyle and Van Triest CirQlar extend partnership to advance circular food systems.
- Tate & Lyle. (n.d.). Our locations. Retrieved September 24, 2026.
- CP Kelco. (n.d.). Products. Retrieved September 24, 2026.
- IFF. (n.d.). GRINDSTED Pectin. Retrieved September 24, 2026.
- IFF. (2025, September 2). IFF tackles top challenges in baking at IBIE 2025.
- Cargill, Incorporated. (n.d.). Pectin. Retrieved September 24, 2026.
- Cargill, Incorporated. (n.d.). Our new Brazilian pectin plant. Retrieved September 24, 2026.
- Herbstreith & Fox GmbH & Co KG. (n.d.). Pectins. Retrieved September 24, 2026.
- Herbstreith & Fox GmbH & Co KG. (n.d.). The challenge of sugar reduction in product development. Retrieved September 24, 2026.
- Herbstreith & Fox GmbH & Co KG. (2026, August 19). News & Events: Fortified gummies with specialized H&F Pectin.
- Herbstreith & Fox GmbH & Co KG. (n.d.). Fortified gummies with specialized H&F Pectin. Retrieved September 24, 2026.
- Silvateam S.p.A. (n.d.). Pectin. Retrieved September 24, 2026.
- Silvateam S.p.A. (n.d.). Aglupectin. Retrieved September 24, 2026.
- Compañía Española de Algas Marinas. (n.d.). Products. Retrieved September 24, 2026.
- Compañía Española de Algas Marinas. (n.d.). Health & Nutrition. Retrieved September 24, 2026.
- Compañía Española de Algas Marinas. (2026, March 18). CEAMSA advances in the development of its new intelligent and sustainable pilot line within the FABRINTYSO project.
- Compañía Española de Algas Marinas. (n.d.). About us. Retrieved September 24, 2026.
- Codex Alimentarius Commission. (2025). Codex General Standard for Food Additives (GSFA) Online Database.
- Givaudan. (2020, September 29). Givaudan divests pectin business to Herbstreith & Fox.
- dsm-firmenich. (2025, April 3). dsm-firmenich completes shareholding increase in Andre Pectin to 90.5%.
- dsm-firmenich. (n.d.). Confectionery Pectin Solutions. Retrieved September 24, 2026.
- Office for National Statistics. (2026, July 24). UK manufacturers' sales by product: 2025.
- Federal Statistical Office of Germany (Destatis). (2026, January 14). Production of ready meals increased by 25.6% in volume within five years.
- Ministry of Agriculture, Forestry and Fisheries, Japan. (2026, February 3). 2025 export results for agricultural, forestry and fishery products and food.
- U.S. Census Bureau. (2026, March 18). Monthly Full Report on Manufacturers’ Shipments, Inventories and Orders: January 2026.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, January 20). Exports of K-Food Plus reached USD 13.6 billion in 2025, up 5.1% year-over-year.
- Tate & Lyle. (2025, May 22). Tate & Lyle PLC 2025 full year results statement.
- Herbstreith & Fox GmbH & Co KG. (2025, November 20). Spicy savory applications - Combination of H&F Pectin with functional fruit fibers.
- Herbstreith & Fox GmbH & Co KG. (2025, September 17). Chocolate topping, cream or filling with H&F Pectin.
- Herbstreith & Fox GmbH & Co KG. (2025, February 13). Dairy desserts with a maximum of creaminess - Perfect gelling with H&F Pectin.
- CEAMSA. (2025, June 27). CEAMSA showcases progress in innovation and sustainable technologies at the Atlantic Bioprocessing Summit 2025.
- CEAMSA. (2025, July 18). CEAMSA at IFT FIRST 2025: Innovation with Texturizing Solutions.
- CEAMSA. (2025, December 3). CEAMSA advances in the development of AI-driven digital twins through the PlatGDIA project.
- Tate & Lyle. (2026, May 21). Tate & Lyle PLC: Results for the Year Ended 31 March 2026.
The bibliography lists the sources used for this article. The full report keeps the complete reference set and detailed citations.
This Report Answers
- How large is the Pectin Market in 2026, and what value is forecast for 2036?
- Which industry pressures support recurring demand for pectin in processed-food formulation?
- Why does high methoxyl (HM) pectin hold a prominent product type position?
- Why does food & beverages hold a prominent application position?
- How do country growth rates differ across the UK, Germany, Japan, USA, and South Korea?
- Which companies sell pectin or provide direct pectin formulation support?
- What limits pectin use, approval, or switching between suppliers?
- What should buyers evaluate during pectin-grade selection for a specific formulation?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- High Methoxyl (HM) Pectin
- Low Methoxyl (LM) Pectin
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Food & Beverages
- Pharmaceuticals
- Cosmetics
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Citrus Fruits
- Oranges
- Tangerines/Mandarins
- Grapefruit
- Lemon and Lime
- Pears
- Apples
- Plums
- Banana
- Others (Peach, Berries)
- Citrus Fruits
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- CP Kelco (Tate & Lyle)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- DuPont de Nemours, Inc. (IFF)
- Cargill, Incorporated
- Herbstreith & Fox GmbH & Co KG
- Silvateam S.p.A.
- Compañía Española de Algas Marinas (CEAMSA)
- Yantai Andre Pectin Co. Ltd.
- CP Kelco (Tate & Lyle)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 13: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 15: Western Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 16: Western Europe Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Million) Forecast by Source, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Product Type, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Application, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by Source, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Source
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type
- Figure 26: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Application
- Figure 29: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Source
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type
- Figure 36: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Application
- Figure 39: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Source
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type
- Figure 46: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Application
- Figure 49: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Source
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Application
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Source
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type
- Figure 66: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Application
- Figure 69: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Source
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Pectin Market in 2026, and what is forecast for 2036?
The pectin market is valued at USD 1,029.0 million in 2026 and projected to reach USD 1,613.4 million by 2036. Recipe teams are using pectin to control gel strength, thickness, and stability across food and other products.
What is the CAGR for the pectin market from 2026 to 2036?
The forecast places pectin growth at 4.6% CAGR from 2026 to 2036. Food processors are using pectin because recipe changes need reliable texture and stability.
Which product type leads the pectin market?
High methoxyl (HM) pectin is likely to capture 68.0% share in 2026, influenced by its fit with acidic high-solids recipes. Food makers are choosing HM pectin for recipes with more sugar or other dissolved solids.
Which application leads the pectin market?
By application, the food & beverages category is forecast to represent 71.0% in 2026, supported by use across several food formats. Fruit products, dairy foods, drinks, confectionery, and bakery are creating recurring pectin use.
What are the country CAGRs for the pectin market through 2036?
The UK and Germany is expected to rise at 5.9% and 5.5% CAGR respectively through 2036. Japan is poised to follow at 4.6%, the USA at 4.2%, and South Korea at 3.6% CAGR by 2036.
Which companies are active in the pectin market?
CP Kelco (Tate & Lyle), IFF, and Cargill, Incorporated are current pectin suppliers. Herbstreith & Fox, Silvateam, CEAMSA, and Yantai Andre are supplying pectin across several regions. Naturex (Givaudan) is a legacy name and does not operate as a current standalone pectin business.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
