

- Market Size (2026)
- USD 170.1 Mn
- Forecast (2036)
- USD 336.4 Mn
- CAGR (2026 to 2036)
- 7.1%
How big is Clean Label Pectin Market in 2026?
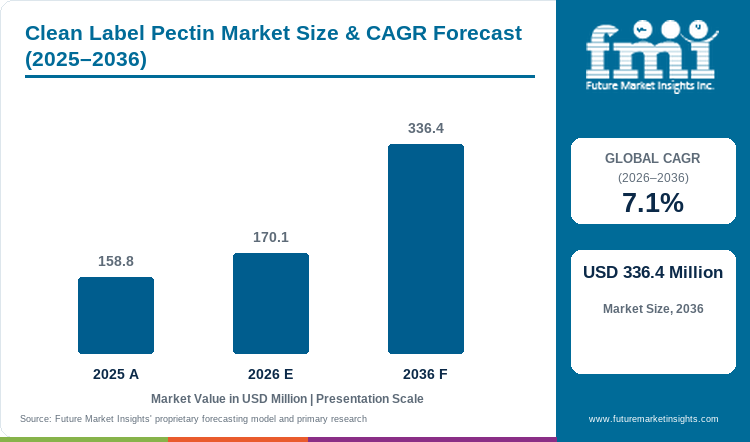
The clean label pectin market is valued at USD 170.1 million in 2026 and is projected to reach USD 336.4 million by 2036, growing at a 7.1% CAGR.
Sales of clean label pectin are forecast to grow at 7.1% from USD 170.1 Million in 2026 to USD 336.4 Million by 2036. The market stood at USD 158.8 Million in 2025. Pectin gives manufacturers a plant-derived way to manage texture and stability while keeping a familiar ingredient declaration.
Regulatory pressure around sugar is particularly visible in the UK, while the United States continues to examine more prominent added-sugar information on packaged foods. At the same time, citrus-processing economics influence the supply side in Brazil and Mexico. The UK government confirmed in July 2026 that the Soft Drinks Industry Levy threshold will fall from 5 g to 4.5 g of sugar per 100 ml from January 2028.
Key Takeaways of Clean Label Pectin Market
- Sugar reduction and simpler ingredient declarations are increasing the commercial value of pectin that can rebuild texture and stability after formulation changes.
- High-Methoxyl Pectin leads Product Type in 2026, supported by its established use in fruit systems and other acidified formulations.
- Bakery Fillings lead End Use Application because processors need controlled viscosity, bake stability and low syneresis.
- Citrus Fruits lead Source, supported by large peel streams from commercial citrus processing.
- Qualification remains an important purchasing constraint because pH, soluble solids, calcium conditions and fruit variability can materially change pectin performance.
- Key suppliers include Tate & Lyle through CP Kelco, Cargill, dsm-firmenich; Herbstreith & Fox; Ingredion; IFF; CEAMSA and JRS Silvateam Ingredients.
Analyst Perspective
Sugar reduction can change how a fruit product sets and feels. A pectin grade that works in a conventional recipe may behave differently when sugar, acidity or calcium changes. Suppliers need to show how their grades perform in the customer’s formulation and process.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Clean Label Pectin Market segmented?
The market is segmented by Product Type, End Use Application and Source.
The clean label pectin market uses three segment axes with region as the geographic split.
Product type covers high-methoxyl pectin and low-methoxyl pectin.
End use application covers bakery fillings, jams, fermented dairy products including yoghurt, sugar confectionary, jellies, reduced-sugar beverages, juices, and fruit spreads.
Source covers citrus fruits, apples, pears, plums, others (peach, berries), and banana.
Why does High-Methoxyl Pectin lead demand within the Product Type category?
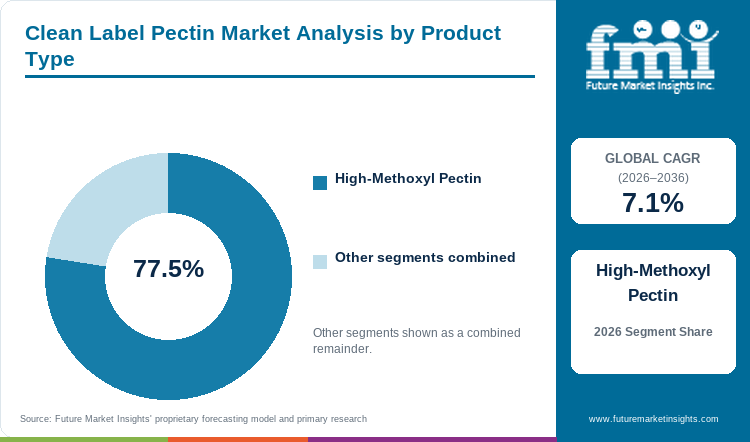
High-Methoxyl Pectin remains widely used where formulators work with acidic, higher-soluble-solids systems and need predictable gel formation. Cargill markets HM alongside low-methoxyl amidated and conventional grades, while Herbstreith & Fox offers high-; medium- and low-ester pectin families. This breadth helps explain why HM continues to anchor purchasing in the wider market even as lower-sugar recipes increase the importance of LM systems.
- High-Methoxyl Pectin holds 77.5% of Product Type demand in 2026.
- HM grades remain commercially important in conventional fruit applications, while LM grades become more relevant as sugar levels fall or calcium-mediated gelation is required.
Why do Bakery Fillings lead demand within the End Use Application category?
Bakery fillings need to remain pumpable during processing and retain structure after heat exposure. Pectin can help control water migration, spread and syneresis while preserving a clear fruit appearance. IFF’s current GRINDSTED pectin portfolio includes grades designed for bake stability and pumpability in fruit fillings, while Cargill identifies conventional LM pectin for bake-stable fruit fillings. These requirements also connect pectin demand with the food texturing agents market.
- Bakery Fillings hold 16.7% of End Use Application demand in 2026.
- Supplier differentiation depends on whether a grade can control texture under the actual fruit solids, sugar level, calcium content and baking conditions used by the processor.
Why do Citrus Fruits lead demand within the Source category?
Citrus peel combines suitable pectin chemistry with a large industrial byproduct stream from juice processing. Brazil alone was forecast by USDA Foreign Agricultural Service to produce 13.5 million metric tons of oranges in MY 2025/26. CEAMSA and JRS Silvateam Ingredients both market citrus-derived pectin platforms, showing the continuing commercial importance of citrus pectin.
- Citrus Fruits account for 39.2% of Source demand in 2026.
- Apple pomace provides an important alternative feedstock, but citrus retains an advantage where processors can connect pectin extraction with large juice-processing streams.
What are the drivers, restraints and opportunities in the Clean Label Pectin Market?
In the clean label pectin market, the key driver is reformulation activity that increases the value of pectin able to restore body, gel strength, or stability as sugar content is reduced, as regulatory and labeling pressure around sugar pushes manufacturers toward lower-sugar recipes that still need familiar texture, the key restraint is that functional performance varies with acidity, soluble solids, calcium, and processing conditions, turning grade substitution into a technical qualification exercise rather than a simple purchasing switch, and the key opportunity lies in high-fruit and lower-sugar formulations that create room for pectins engineered around controlled calcium response, bake stability, and stronger sensory performance, letting suppliers differentiate through tailored grades rather than compete on commodity terms.
- Driver: Reformulation increases the value of pectin that can restore body, gel strength or stability as sugar content changes.
- Restraint: Functional performance varies with acidity, soluble solids, calcium and processing conditions; making grade substitution a technical exercise rather than a simple purchasing change.
- Opportunity: High-fruit and lower-sugar formulations create room for pectins designed around controlled calcium response, bake stability and stronger sensory performance.
Sugar reduction is moving from a broad consumer theme into specific formulation work. In January 2025, the U.S. Food and Drug Administration proposed a front-of-package nutrition box that would characterize added sugars, sodium and saturated fat as Low; Med or High. FDA’s economic analysis also recognizes that some manufacturers could choose to reformulate products in response. In the UK; the Soft Drinks Industry Levy threshold is scheduled to tighten in January 2028.
High- and low-methoxyl pectins behave differently as soluble solids, acidity and calcium change. Herbstreith & Fox notes that low-sugar fruit spreads create specific challenges around liquid binding, firmness and mouthfeel while Cargill distinguishes HM; LMA and LMC systems by sugar level; calcium response and end use.
The opportunity lies in products that remove sugar but still need familiar texture. Cargill markets LMCPlus pectins specifically for high-fruit and low-sugar jams, jellies, fruit spreads and bakery fillings. Herbstreith & Fox also offers pectin solutions for sugar-reduced confectionery and fruit spreads. The same formulation challenge supports adjacent demand in sugar-reduction formulations where replacing sucrose requires attention to structure as well as sweetness.
Which country CAGRs are profiled in the Clean Label Pectin Market?
| Country | CAGR |
|---|---|
| Mexico | 13.8% |
| UK | 8.7% |
| Brazil | 7.5% |
| Germany | 6.1% |
| Italy | 5.0% |
| USA | 4.7% |
| Canada | 3.5% |
| Russia | 3.2% |
How do country-level CAGRs compare in the Clean Label Pectin Market?
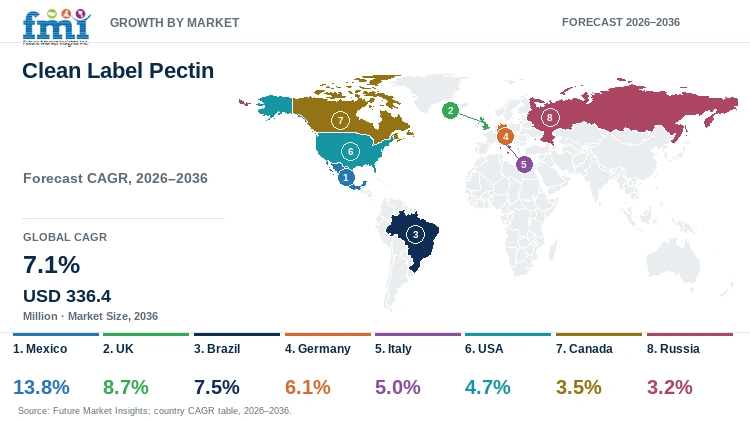
Mexico records the highest CAGR at 13.8%, followed by the UK at 8.7% and Brazil at 7.5%. Germany and Italy occupy the middle of the country set, while the USA; Canada and Russia show more measured growth. These rates describe forecast growth pace rather than absolute market size.
- Mexico: Citrus-processing scale creates a strong raw-material connection, while variable growing conditions increase the value of consistent sourcing and grade standardization.
- UK: The planned tightening of the Soft Drinks Industry Levy provides manufacturers with a defined future reformulation deadline.
- Brazil: A large orange-processing base supports citrus-pectin economics and gives suppliers proximity to substantial peel volumes.
- Germany: National policy continues to encourage lower sugar, fat and salt in processed foods, sustaining formulation work across packaged-food categories.
- Italy: A large apple and pear industry provides a relevant fruit-processing base alongside demand from European food manufacturers.
- USA: Greater attention to added-sugar labeling keeps texture-preserving reformulation on the development agenda.
- Canada: Clear additive permissions create an established regulatory setting for pectin use, while growth depends on formulation economics and supplier support.
- Russia: A large domestic confectionery industry provides an application base, but the profiled growth rate indicates a more gradual expansion path.
Country-wise Analysis
- Mexico is forecast to expand at a 13.8% CAGR from 2026 to 2036. USDA Foreign Agricultural Service reported in January 2025 that orange output was being affected by prolonged drought, high temperatures and erratic rainfall in major producing regions. Food manufacturers create demand for pectin in fruit and packaged-food systems, while citrus processors influence the availability and consistency of one of the industry’s main raw materials.
- The UK is profiled at an 8.7% CAGR from 2026 to 2036. From January 2028, the lower Soft Drinks Industry Levy threshold is scheduled to fall from 5 g to 4.5 g of sugar per 100 ml and exemptions for milk-based and milk-substitute drinks will be removed. Lower-sugar formulation can alter mouthfeel and stability, giving pectin suppliers a clear technical role where their grades perform under the revised product design.
- Brazil is forecast to grow at a 7.5% CAGR. Its importance extends beyond end-product demand because the country is one of the world’s major citrus-processing locations. USDA Foreign Agricultural Service forecast the Brazilian orange crop at 13.5 million metric tons in MY 2025/26, 3.7% above its previous estimate. The scale of that processing base supports access to citrus peel and makes Brazil strategically relevant to pectin sourcing as well as consumption.
- Germany carries a 6.1% CAGR through 2036. The Federal Ministry of Food and Agriculture continues to position its National Reduction and Innovation Strategy around lowering sugar, fats and salt in processed foods. For pectin suppliers, the commercial opening is strongest where manufacturers must preserve texture after changing a recipe. Dairy preparations; beverages and fruit systems can require different pectin specifications so application support remains central to conversion.
- Italy is profiled at a 5.0% CAGR from 2026 to 2036. Eurostat reported that Italy produced 21% of the EU’s apples and 24% of its pears in 2024. This fruit-processing base supports pectin demand and alternative feedstock supply.
- The USA is forecast to grow at a 4.7% CAGR. The FDA’s 2025 front-of-package proposal would give consumers an at-a-glance indication of added sugars on most packaged foods if finalized. FDA also recognizes that the proposed framework could encourage some voluntary reformulation. Pectin suppliers can benefit where changing sugar content creates a need to rebuild viscosity, gel structure or mouthfeel without complicating the ingredient declaration.
- Canada is profiled at a 3.5% CAGR. In September 2025, Health Canada announced an extension permitting pectin as a stabilizing and thickening agent in human milk fortifier and infant formula at specified conditions, effective 20 October 2025. The extension confirms a clearly defined regulatory framework for pectin use in Canada.
- Russia records a 3.2% CAGR, the slowest rate among the profiled countries. Rosstat reported 4.1 million tonnes of confectionery production for 2025, indicating a substantial domestic application base for texturizers and related ingredients. Growth will come from pectin gaining share in existing confectionery formulations.
Who are the notable companies in the Clean Label Pectin Market?
Tate & Lyle through CP Kelco, Cargill Incorporated, dsm-firmenich; Herbstreith & Fox; Ingredion Incorporated; IFF; CEAMSA and JRS Silvateam Ingredients are key companies serving the market.
Competition spans large specialty-ingredient platforms and focused pectin manufacturers. Tate & Lyle’s CP Kelco business combines pectin with other specialty gums. Cargill markets HM, LMA and LMC pectin families for fruit systems. dsm-firmenich controls 90.5% of Andre Pectin following its April 2025 investment increase. IFF markets GRINDSTED pectin across bakery, beverage and other food applications.
Herbstreith & Fox maintains a specialist apple- and citrus-pectin portfolio, while Ingredion lists both high-methoxyl and low-methoxyl amidated pectin within its hydrocolloid range. CEAMSA’s CEAMPECTIN platform is derived from citrus peel and JRS Silvateam Ingredients markets Aglupectin citrus pectins across bakery, beverages; confectionery and fruit preparations.
Competitive Benchmarking: Clean Label Pectin Market
| Company | HM/LM Pectin Breadth | Application Support | Fruit-Source / Production Depth | Geographic Reach |
|---|---|---|---|---|
| Tate & Lyle (CP Kelco) | High | High | High | Global specialty-ingredient platform with CP Kelco pectin capabilities. |
| Cargill Incorporated | High | High | High | Broad food-ingredient network with HM, LMA and LMC pectin systems. |
| dsm-firmenich (Andre Pectin) | High | High | High | Global ingredient network linked to the Andre Pectin manufacturing platform in China. |
| Herbstreith & Fox | High | High | High | Specialist apple- and citrus-pectin supplier serving multiple food applications. |
| Ingredion Incorporated | Medium | High | Medium | Global ingredient network offering HM and LMA pectins alongside broader hydrocolloids. |
| IFF | High | High | High | GRINDSTED pectin platform covering bakery, beverages and other texture applications. |
| CEAMSA | High | High | Medium | Citrus-derived CEAMPECTIN platform with fruit, confectionery and dairy applications. |
| JRS Silvateam Ingredients | High | High | High | Citrus-pectin platform supporting bakery, beverages, confectionery; dairy and fruit preparations. |
Scoring reflects breadth of pectin families, application capability, production or fruit-source depth and commercial reach. High indicates broad capability across the criterion while Medium indicates a more concentrated offering.
Key Developments in the Clean Label Pectin Market
- In April 2025, dsm-firmenich increased its shareholding in Yantai DSM Andre Pectin Company Limited from 75% to 90.5%. The company described Andre Pectin as a specialty food ingredient producer, The move strengthened dsm-firmenich’s control of a major texturizing asset in China.
- In May 2025, Tate & Lyle reported that CP Kelco’s pro forma volume for the year ended March 2025 increased 8%, with strong pectin performance contributing to the result. The update showed commercial momentum in pectin as the enlarged specialty-ingredients platform advanced integration and cross-selling activity.In November 2025, CEAMSA reported progress on an AI-driven digital twin associated with its industrial pectin-extraction process. The project applies artificial intelligence and machine learning to industrial digitalization, showing how established hydrocolloid producers are investing in process control and manufacturing efficiency.
Key Players in the Clean Label Pectin Market
Integrated global pectin and hydrocolloid platforms
- Tate & Lyle (CP Kelco)
- Cargill Incorporated
- dsm-firmenich
- Ingredion Incorporated
- IFF
Pectin-focused and plant-derived texturizer specialists
- Herbstreith & Fox
- CEAMSA
- JRS Silvateam Ingredients
Clean Label Pectin Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; End Use Application; Source |
| Quantitative Units | USD Million |
| Market Definition | Revenue includes clean label pectin sold as an ingredient within the stated Product Type, End Use Application and Source universe. Finished-product revenue, substitute hydrocolloids and unrelated ingredient revenue are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Russia; Brazil; Mexico; Canada; Italy |
| Key Companies Profiled | Tate & Lyle (CP Kelco); Cargill Incorporated; dsm-firmenich; Herbstreith & Fox; Ingredion Incorporated; IFF; CEAMSA; JRS Silvateam Ingredients |
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Approach | Primary and secondary research with market triangulation |
Clean Label Pectin Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts engage manufacturers, ingredient suppliers, distributors; processors; procurement teams and subject-matter specialists to understand purchasing behavior; product evaluation; technical requirements and adoption barriers. |
| Desk Research | Research covers official statistics, regulatory publications, trade information; technical literature; standards; company filings; product documentation and corporate announcements. |
| Market Sizing and Forecasting | Market sizing incorporates the baseline market value, segment structure, pricing and volume indicators; adoption patterns; company activity and country-level demand conditions. |
| Data Validation | Market estimates are compared across independent demand, supply and company indicators before segment and regional totals are finalized. |
Clean Label Pectin Market by Segments
Clean Label Pectin Market segmented by Product Type:
- High-Methoxyl Pectin
- Low-Methoxyl Pectin
Clean Label Pectin Market segmented by End Use Application:
- Bakery Fillings
- Jams
- Fermented dairy products, including yoghurt
- Sugar Confectionary
- Jellies
- Reduced-Sugar beverages
- Juices
- Fruit Spreads
Clean Label Pectin Market segmented by Source:
- Citrus Fruits
- Apples
- Pears
- Plums
- Others (Peach, Berries)
- Banana
Clean Label Pectin Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- U.S. Food and Drug Administration, January 14, 2025. FDA Proposes Requiring At-a-Glance Nutrition Information on the Front of Packaged Foods.
- U.S. Food and Drug Administration, 2025. Food Labeling: Front-of-Package Nutrition Information, Proposed Rule.
- HM Revenue & Customs, July 13, 2026. Changes to the Soft Drinks Industry Levy.
- Federal Ministry of Food and Agriculture, Germany. The National Reduction and Innovation Strategy for Sugar, Fats and Salt in Processed Foods.
- USDA Foreign Agricultural Service, January 2025. Mexico: Citrus Annual.
- USDA Foreign Agricultural Service, January 2026. Brazil: Citrus Annual.
- Eurostat, August 25, 2025. How much fruit and vegetables does the EU harvest?
- Health Canada, 15 September 2025. Modification to the List of Permitted Emulsifying, Gelling; Stabilizing or Thickening Agents to extend the use of pectin.
- Rosstat, 2026. Industrial production in 2025.
- Tate & Lyle, May 22, 2025. 2025 Full Year Results Statement.
- dsm-firmenich, April 3, 2025. dsm-firmenich completes shareholding increase in Andre Pectin to 90.5%.
- CEAMSA, 28 November 2025. CEAMSA advances in the development of AI-driven digital twins through the PlatGDIA project.
- Cargill. UniPECTINE Pectin and Pectin for Fruit.
- Herbstreith & Fox. Pectins and Pectin Applications.
- Ingredion. Gums and Hydrocolloids.
- IFF. GRINDSTED Pectin.
- JRS Silvateam Ingredients. Plant-Based Ingredients and Aglupectin Solutions.
- CEAMSA. Pectin, Citrus Texturizer.
This Report Answers
- How large is the Clean Label Pectin Market in 2026 and what value is forecast for 2036?
- Which reformulation pressures support demand for clean label pectin?
- Why does High-Methoxyl Pectin lead the Product Type category?
- Why do Bakery Fillings lead the End Use Application category?
- Why do Citrus Fruits lead the Source category?
- How do country growth rates differ from 2026 to 2036?
- Which companies participate in the current pectin and hydrocolloid supply landscape?
- What should buyers evaluate before qualifying a pectin grade for regular purchasing?
Frequently Asked Questions
How big is the Clean Label Pectin Market in 2026, and what is forecast for 2036?
The Clean Label Pectin Market is valued at USD 170.1 Million in 2026 and is forecast to reach USD 336.4 Million by 2036. The market was valued at USD 158.8 Million in 2025.
What is the Clean Label Pectin Market CAGR from 2026 to 2036?
The market is forecast to grow at a 7.1% CAGR from 2026 to 2036, supported by food reformulation and demand for plant-derived texturizing systems.
Which segment leads Product Type in the Clean Label Pectin Market?
High-Methoxyl Pectin leads Product Type in 2026. Its established performance in acidic fruit systems and other traditional pectin applications supports continued purchasing.
Which source leads the Clean Label Pectin Market?
Citrus Fruits lead Source in 2026. Citrus peel provides a commercially established feedstock connected to large juice-processing streams.
Which companies are active in the Clean Label Pectin Market?
Key companies include Tate & Lyle through CP Kelco, Cargill Incorporated, dsm-firmenich; Herbstreith & Fox; Ingredion Incorporated; IFF; CEAMSA and JRS Silvateam Ingredients.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- High-Methoxyl Pectin
- Low-Methoxyl Pectin
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use Application, 2026 to 2036
- Bakery Fillings
- Jams
- Fermented dairy products, including yoghurt
- Sugar Confectionary
- Jellies
- Reduced-Sugar beverages
- Juices
- Fruit Spreads
- Y-o-Y Growth Trend Analysis By End Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Citrus Fruits
- Apples
- Pears
- Plums
- Others (Peach, Berries)
- Banana
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use Application
- By Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- By Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- By Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use Application
- By Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Tate & Lyle (CP Kelco)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill Incorporated
- dsm-firmenich (Andre Pectin)
- Herbstreith & Fox
- Ingredion Incorporated
- IFF
- CEAMSA
- JRS Silvateam Ingredients
- dsm-firmenich
- Tate & Lyle (CP Kelco)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


