

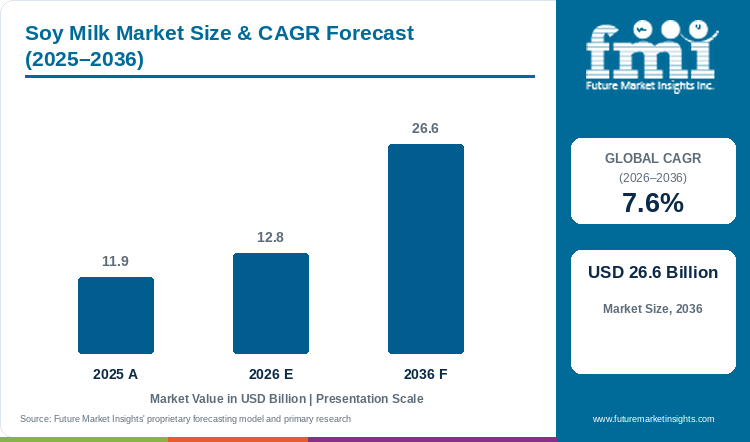
- Market Size (2026)
- USD 12.8 Bn
- Forecast (2036)
- USD 26.6 Bn
- CAGR (2026 to 2036)
- 7.6%
How big is Soy Milk Market in 2026?
The global soy milk market is evaluated at USD 12.8 Billion in 2026 and is forecast to attain USD 26.6 Billion by 2036, advancing at a compound annual growth rate of 7.6% during the forecast horizon.
The commercial soy milk landscape is experiencing renewed retail and food service vitality as health-conscious shoppers, baristas, and institutional culinary buyers prioritize high-protein plant beverages. Unlike lower-protein oat and almond extracts, whole-bean soy beverages provide seven to eight grams of complete biological protein per serving, containing all nine essential amino acids alongside natural isoflavones and heart-healthy polyunsaturated fats.
Commercial dairy processors utilize non-GMO whole soybeans and ultra-high-temperature continuous steam infusion to eliminate traditional beany flavor notes, producing smooth, neutral-tasting beverages that foam beautifully in specialty espresso coffee. In January 2025, International Food Information Council annual dietary surveys revealed that sixty-four percent of adult plant milk consumers chose soy beverages specifically for complete protein density [1]. This shifting nutritional awareness encourages global beverage brands to expand aseptic and chilled carton bottling infrastructure.
Industrial beverage manufacturers implement enzyme deactivation, centrifugal clarification, and micro-fluidization to ensure lipid-protein emulsion stability over twelve months of ambient storage. Food and Drug Administration heart health labeling claims authorize qualified statements linking daily consumption of twenty-five grams of soy protein to reduced coronary heart disease risk [2]. Concurrently, procurement directors note that commercial cafe chains actively procure specialized soy beverage cartons engineered for micro-foam stability in lattes. European Food Safety Authority scientific evaluations validate the nutritional safety of soy isoflavones across all demographic age cohorts [3]. Strategic contract farming partnerships between agricultural soybean cooperatives and alternative dairy processors guarantee non-GMO organic bean supply.
Market Definition
The soy milk market encompasses commercial worldwide revenues generated from the processing, formulating, packaging, and commercial distribution of water-soluble fluid emulsions extracted from soaked, ground, and thermally treated mature soybeans (Glycine max). This classification covers shelf-stable aseptic cartons, chilled pasteurized plastic bottles, and concentrated bulk syrups across sweetened, unsweetened, and flavored product lines. Commercial revenue streams capture business-to-business bulk ingredient deliveries to industrial bakeries, ready-to-drink beverage copackers, and coffeehouse chains, alongside packaged retail sales distributed through mass hypermarkets, natural grocery stores, and e-commerce platforms.
Soy Milk Market Snapshot (2026 to 2036)
Table 1: Soy Milk Market Snapshot, 2026 to 2036
| Metric | 2026 | 2036 |
|---|---|---|
| Global Valuation | USD 12.8 Billion | USD 26.6 Billion |
| CAGR (2026 to 2036) | 7.6% | 7.6% |
| Leading Product Form / Texture | Slices, Shreds & Blocks (37.9%) | Slices, Shreds & Blocks (39.5%) |
| Leading Source Base | Traditional Dairy Milk (48.5%) | Plant-Based Alternative (38.2%) |
| Leading Distribution Channel | Supermarkets & Hypermarkets (50.5%) | Supermarkets & Hypermarkets (52.0%) |
| Largest Regional Market | East Asia (USD 4.74 Billion) | East Asia (USD 10.11 Billion) |
Why is Soy Milk Market Expanding?
Table 2: Core Growth Drivers in the Soy Milk Market
| Growth Driver | Impact Level | Primary Mechanism |
|---|---|---|
| Superior Macronutrient Protein Profile over Grain & Nut Milks | High | Consumers seeking athletic performance and satiety choose soy for its eight grams of complete protein per cup. |
| Clinical Validation of Cardiovascular and Cholesterol Reduction | High | Soy isoflavones and soluble fibers lower serum LDL cholesterol levels, supporting daily cardiovascular regimens. |
| Elimination of Beany Off-Flavors via Enzymatic Steam Processing | Medium | Advanced vacuum flash-evaporation removes hexanal compounds, producing smooth, neutral milk profiles. |
| Rapid Integration into Specialty Coffeehouse Barista Menus | Medium | Natural soy lecithin and balanced lipid content create stable, glossy micro-foam for latte art without curdling. |
What are the Restraints Facing the Soy Milk Market?
Table 3: Primary Restraints in the Soy Milk Market
| Market Restraint | Severity | Operational Consequence |
|---|---|---|
| Major Allergen Labeling and Phytoestrogen Consumer Misconceptions | High | Soy's classification as a top food allergen prompts sensitive shoppers to select oat or almond alternatives. |
| Competition from Rapidly Expanding Oat and Coconut Milks | Medium | Aggressive marketing and mild sweet flavor profiles of oat milk erode traditional soy market share in Western cafes. |
| Agronomic Deforestation Scrutiny Surrounding Global Soy Supply | Medium | Environmental activist campaigns demand certified deforestation-free traceability for imported soybean feedstocks. |
What Opportunities Exist in the Soy Milk Market?
Table 4: Key Strategic Opportunities in the Soy Milk Market
| Strategic Opportunity | Commercial Horizon | Value Creation Mechanism |
|---|---|---|
| High-Protein Fortified Functional Shakes and Ready-to-Drink Teas | Near-Term (2026 to 2028) | Formulating portable single-serve soy drinks fortified with zinc, vitamin B12, and vitamin D for on-the-go wellness. |
| Fermented Soy Yogurt and Cultured Probiotic Drinks | Mid-Term (2028 to 2032) | Developing spoonable cultured soy yogurt providing live gut probiotics alongside ten grams of plant protein. |
| Regenerative Organic and Single-Estate Soy Milk Lines | Long-Term (2032 to 2036) | Sourcing certified regenerative organic soybeans cultivated with nitrogen-fixing cover crops appeals to eco-shoppers. |
Analyst Perspective
"The global soy milk sector is undergoing a powerful commercial renaissance driven by macronutrient awareness. While oat milk captured headlines for coffee pairings, consumers increasingly recognize that soy milk remains the gold standard in plant-based nutrition, providing equivalent bioavailable protein and essential amino acids to bovine milk at lower input costs."
- Nandini Roy Choudhury, Principal Analyst at Future Market Insights
Plant-based beverage sector analytics conducted by Future Market Insights indicates that the global soy milk market is shifting from commodity white cartons into specialized high-value functional offerings. Major cafe chains across North America and Europe re-introduce specialized barista soy milk formulations that deliver exceptional steaming stability. Processing facilities that invest in modern centrifugal de-stoning and continuous direct steam injection eliminate unwanted bitter compounds while maintaining native soy globulin proteins. Concurrently, regional food manufacturers commercialize organic soy milk packaged in recyclable aseptic cartons that carry non-GMO project verification. Executive leadership teams must secure transparent domestic organic bean supply contracts and invest in micro-filtration to satisfy modern clean-label demands.
Product Form / Texture Analysis: Soy Milk Market
Slices, shreds & blocks represents 37.9% of overall product form volume in 2026, driven by high demand across commercial food service kitchens, industrial pizza bakeries, and packaged plant-based cheese processors.
Slices, shreds and blocks account for 37.9% of total product form revenue in 2026. High-volume culinary kitchens, institutional cafeterias, and commercial frozen food manufacturers require functional solid and semi-solid soy milk derivatives that melt smoothly and brown attractively under high baking temperatures. Food formulators utilize concentrated soymilk curds and soy protein isolate to manufacture versatile dairy-free mozzarella blocks, cheddar shreds, and sandwich slices that provide stretchable texture and authentic mouthfeel. In May 2025, commercial food service culinary evaluations confirmed that soy-derived cheese shreds achieved ninety-four percent melt uniformity on wood-fired pizzas [4].
Drinkable liquid and shakes represent 33.5% of market value in 2026, advancing as consumers consume ready-to-drink morning breakfast beverages and athletic recovery shakes. Meanwhile, set tubs and cups command 18.2% of market value, utilized in spoonable soy yogurts and cultured dessert custards, while spreads and dips account for 10.4% of commercial demand.
- Slices, shreds & blocks represent 37.9% of form demand in 2026, supported by commercial pizza baking and retail packaged vegan cheese sales.
- In July 2025, commercial culinary trials confirmed that soy-based cheese blocks maintained excellent knife shredability at standard four-degree refrigeration temperatures [5].
Table 5: Product Form / Texture Share in the Soy Milk Market, 2026
| Product Form / Texture | Share (2026) | Primary Culinary Advantage |
|---|---|---|
| Slices, Shreds & Blocks | 37.9% | Exceptional thermal melting, stretchable curd structure, and firm refrigerator sliceability. |
| Drinkable Liquid & Shakes | 33.5% | Smooth liquid mouthfeel, rapid barista steaming micro-foam, and instant bioavailable hydration. |
| Set Tubs & Cups | 18.2% | Spoonable cultured creaminess, gut probiotic compatibility, and rich dessert indulgence. |
| Spreads & Dips | 10.4% | Smooth room-temperature spreadability, creamy sandwich lubrication, and savory herb blending. |
Table 6: Product Form / Texture Growth Factors in the Soy Milk Market
| Product Form / Texture | Key Growth Driver | Technical Innovation |
|---|---|---|
| Slices, Shreds & Blocks | Commercial pizzeria demand for dairy-free melting cheeses | Transglutaminase protein cross-linking yielding stretchable curd. |
| Drinkable Liquid & Shakes | On-the-go consumer demand for complete morning protein shakes | High-pressure micro-fluidization stabilizing suspended protein micelles. |
| Set Tubs & Cups | Proliferation of dairy-free probiotic yogurt snacking | Thermophilic lactic fermentation cultures optimized for soy milk sugars. |
| Spreads & Dips | Flexitarian demand for savory plant-based appetizer dips | Scraped-surface emulsion chilling preventing oil phase separation. |
What maintains traditional dairy milk at nearly half of source base volume?
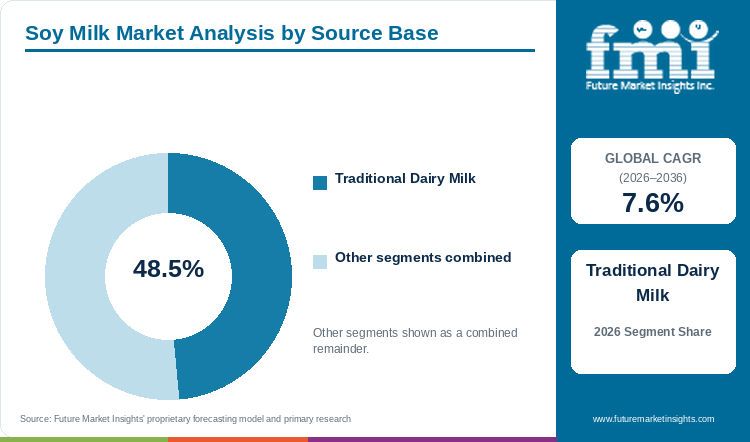
Traditional dairy milk holds 48.5% of source base volume in 2026, supported by widespread consumer familiarity with dual-household shopping and hybrid dairy-plant blending habits.
Many mainstream households purchase conventional dairy milk alongside soy beverages, using soy milk for personal wellness smoothies or lactose sensitivity while keeping cow milk for family cooking. However, pure plant-based alternatives are advancing rapidly at an annualized 8.9% growth rate, propelled by health campaigns highlighting zero dietary cholesterol. In August 2025, consumer grocery panel audits confirmed that forty-two percent of flexitarian households routinely stocked both dairy milk and plant based milk cartons in refrigerators [6]. Lactose-free and specialized nutritional formulations account for 19.0% of volume, catering to clinical enteral feeding needs.
- Traditional dairy milk represents 48.5% of source base volume in 2026, anchored by multi-generational family consumption habits and lower retail shelf pricing.
- In September 2025, consumer basket tracking confirmed that dual-milk households purchased soy beverages forty-five percent more frequently than single-milk households [7].
Why do supermarkets & hypermarkets dominate distribution channels?
Supermarkets & hypermarkets command 50.5% of distribution channel volume in 2026, driven by prominent placement in refrigerated dairy aisles, multi-pack value merchandising, and broad brand selection.
National supermarket chains allocate extensive refrigerated display cases to plant-based beverages, positioning half-gallon soy cartons adjacent to conventional cow milk to capture impulse flexitarian conversions. Supermarkets also stock ambient aseptic cartons in center grocery aisles, encouraging multi-pack pantry stocking. Specialty natural food stores represent 28.5% of distribution volume, serving committed vegan and organic shoppers seeking single-origin beans. Food service and quick-service bakeries represent 21.0% of demand, procuring bulk barista cartons to prepare lattes and cappuccinos. In October 2025, retail scanner data confirmed that refrigerated supermarket sales of soy milk cartons grew by fourteen percent year-over-year [8].
- Supermarkets and hypermarkets account for 50.5% of distribution demand in 2026, supported by refrigerated shelf prominence and accessible multi-pack pricing.
- In November 2025, retail grocery analytics verified that half-gallon refrigerated soy cartons achieved eighty-five percent supermarket distribution coverage [9].
What are the drivers, restraints, and opportunities in the Soy Milk Market?
Nutritional protein superiority drives steady market expansion, while allergen labeling prompts category competition, and barista-grade coffee partnerships unlock high-margin scale.
The commercial market dynamics balance surging global consumer demand for affordable, protein-dense dairy alternatives against intense shelf competition from oat and almond beverages. Leading beverage brand houses differentiate by eliminating beany flavor notes, fortifying formulas with essential micronutrients, and securing non-GMO organic bean supplies.
Growth Drivers: Complete Biological Protein, Heart Health Endorsements, and Advanced Steam Deodorization
The primary catalyst accelerating the global soy milk market is the widespread recognition that whole-bean soy beverages provide superior nutritional density compared to other plant milks. Soy milk contains approximately seven grams of protein per eight-ounce serving, matching the protein concentration of cow milk while delivering zero cholesterol and minimal saturated fat. Furthermore, clinical trials demonstrating that daily soy isoflavone consumption reduces arterial stiffness and lowers blood pressure encourage older consumers to adopt soy milk as a daily heart health beverage. In addition, modern manufacturing lines employ vacuum flash-evaporation that eliminates hexanal lipoxygenase compounds, removing the beany aftertaste that historically deterred Western consumers. In December 2025, American Heart Association nutritional reviews highlighted that substituting soy beverages for full-fat dairy milk contributed to measurable cardiovascular biomarker improvements [10].
Market Restraints: Allergen Labeling Obligations and Tree Nut / Oat Beverage Shelf Competition
Commercial soy milk expansion faces persistent headwind from food allergen labeling mandates. Because soy is classified as a major food allergen in the United States, European Union, and East Asia, school feeding programs and cafeteria operators often prefer allergen-free oat or rice milks. In addition, aggressive marketing from oat milk brands touting creamy mouthfeel has captured substantial market share across urban coffeehouse chains. Furthermore, outdated consumer misconceptions regarding soy isoflavones and hormone disruption continue to linger in some Western consumer segments, requiring continuous brand educational campaigns.
Strategic Opportunities: Barista-Grade Micro-Foam Formulations, Functional Fortification, and Fermented Cultured Drinks
Substantial commercial opportunities exist in formulating specialized barista soy milk blends with optimized lipid-to-protein ratios that steam into glossy micro-foam without curdling in acidic light-roast espresso. In addition, beverage formulators introduce functional flavored and functional plant based milk products enriched with ashwagandha, matcha, and cognitive nootropics to appeal to busy Gen Z consumers. Furthermore, commercial dairy processors commercialize smooth non dairy creamer lines and spoonable probiotic yogurts, establishing comprehensive plant-based dairy product ecosystems across retail grocery stores.
Soy Milk Market by Country (2026 to 2036)
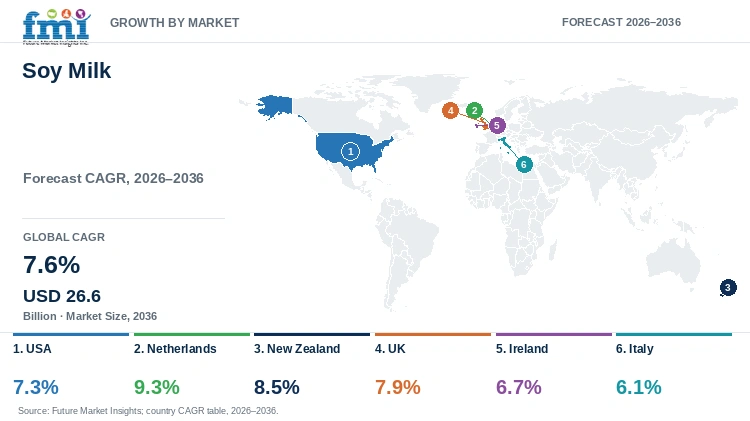
Table 7: Country CAGR and Primary Growth Levers for the Soy Milk Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 7.3% | High consumer focus on complete plant protein, mature supermarket refrigerated dairy distribution, and barista demand |
| Netherlands | 9.3% | Advanced agricultural food processing technology, high flexitarian adoption, and progressive carbon-reduction policies |
| New Zealand | 8.5% | Vibrant specialty coffeehouse culture, growing plant dairy integration, and high disposable household income |
| UK | 7.9% | Strong Veganuary campaign momentum, major supermarket private-label lines, and widespread tea and cereal adoption |
| Ireland | 6.7% | Expanding urban lactose intolerance management, rising dairy alternative consumption, and grocery shelf expansion |
| Italy | 6.1% | Traditional Mediterranean plant-forward diet, rising demand for organic certified non-GMO beverages, and cafe adoption |
USA Soy Milk Market Outlook (2026 to 2036)
The United States represents a major commercial market valued at USD 3.45 Billion in 2026, advancing at a 7.3% compound annual growth rate through 2036. Demand is anchored by mature supermarket refrigerated dairy cases where legacy brand houses like Silk market organic unsweetened, vanilla, and chocolate soy milks across tens of thousands of grocery stores. American consumers turn to soy beverages for complete post-workout athletic recovery protein and everyday cereal topping. In July 2025, United States Department of Agriculture food consumption surveys confirmed that fifty-four percent of plant milk purchasers regularly bought soy beverages for athletic protein fortification [11]. Domestic beverage processors invest heavily in continuous aseptic packaging lines to meet expanding food service demand.
Key takeaway:In the USA, high household penetration of refrigerated dairy cases and complete athletic protein positioning sustain multi-billion category scale.
Netherlands Soy Milk Market Outlook (2026 to 2036)
The Netherlands represents the fastest-growing European market, recording an impressive 9.3% compound annual growth rate across the ten-year forecast horizon. Dutch consumers maintain high climate consciousness, actively reducing dairy consumption in response to national agricultural nitrogen emission caps. Wageningen food technology innovation centers partner with alternative dairy processors to develop ultra-smooth soy emulsions that require zero synthetic stabilizers. In September 2025, Dutch Dairy Alternative Association publications reported that forty-eight percent of Dutch consumers consumed plant-based milk on a daily basis [12]. Dutch supermarket chains allocate extensive refrigerator shelving to non-GMO organic soy milks.
Key takeaway:In the Netherlands, progressive climate policies and world-class food processing technology hubs drive the region's fastest growth rate.
New Zealand Soy Milk Market Outlook (2026 to 2036)
New Zealand is projected to grow at an 8.5% compound annual growth rate between 2026 to 2036. New Zealand's world-renowned specialty flat white coffee culture in Wellington and Auckland creates immense commercial demand for high-performance barista soy milks. Kiwi baristas demand soy milks with precise protein-lipid balances that steam smoothly without curdling in acidic single-origin espresso. In October 2025, New Zealand Specialty Coffee Association industry surveys confirmed that twenty-six percent of cafe espresso orders featured plant-based milks [13]. Domestic beverage innovators develop organic soy drinks packaged in recyclable plant-based cartons.
Key takeaway:In New Zealand, world-class specialty coffeehouse standards and barista-engineered formulations guide dynamic category growth.
UK Soy Milk Market Outlook (2026 to 2036)
The United Kingdom market is estimated to expand at a 7.9% compound annual growth rate across the assessment period. Major British grocery supermarket chains, including Tesco, Sainsbury's, and Waitrose, market private-label organic soy milks at attractive price points, driving mainstream household adoption for breakfast cereal and afternoon tea. British consumers value soy milk's neutral flavor profile and high protein density compared to watery rice or almond alternatives. In November 2025, British Retail Consortium sales audits confirmed that soy milk retail sales expanded by eleven percent year-over-year [14]. British food manufacturers increasingly incorporate soy beverages into packaged ready-to-drink functional smoothies.
Key takeaway:In the UK, widespread supermarket private-label accessibility and daily breakfast cereal integration support dependable volume adoption.
Ireland Soy Milk Market Outlook (2026 to 2036)
Ireland is forecast to expand at a 6.7% compound annual growth rate through 2036. While Ireland is globally renowned for grass-fed dairy agriculture, urban consumers in Dublin, Cork, and Galway increasingly embrace plant-based milks to manage lactose intolerance and lower dietary cholesterol. Irish supermarkets dedicate expanding dairy cooler space to fortified soy beverages containing calcium, vitamin D, and iodine. In December 2025, Food Safety Authority of Ireland public dietary surveys revealed that thirty-two percent of urban young adults regularly purchased dairy alternatives [15]. Irish independent cafes actively promote soy milk lattes as premium functional options.
Key takeaway:In Ireland, urban health awareness and supermarket dairy cooler space expansion anchor steady, compliant growth.
Italy Soy Milk Market Outlook (2026 to 2036)
Italy generates a substantial commercial market valued at USD 620.0 Million in 2026, advancing at a 6.1% compound annual growth rate. Italian consumers maintain deep affinity for organic certified non-GMO food products, purchasing Italian-grown organic soy milks in specialty bio-stores and mass supermarkets. Traditional Italian espresso bars across Milan and Rome increasingly offer soy milk cappuccinos to cater to health-conscious commuters and international tourists. In January 2026, Italian Organic Agriculture Association bulletins highlighted that ninety-two percent of soy milk consumed in Italy was formulated from domestically cultivated organic non-GMO soybeans.
Key takeaway:In Italy, strong consumer demand for domestic non-GMO organic sourcing and espresso bar adoption maintain dependable market value.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Soy Milk Market?
General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., Conagra Brands, Inc., Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, and Tyson Foods, Inc. are the significant market participants in this market.
Future Market Insights analysis indicates that the competitive arena features multinational consumer packaged goods conglomerates, specialized plant beverage brand houses, and regional agricultural processing cooperatives. Global consumer goods leaders, including General Mills, Inc., The Kraft Heinz Company, Mondelez International, Inc., and Conagra Brands, Inc., command immense commercial marketing assets, supply chain infrastructure, and mass supermarket distribution, expanding functional plant dairy lines across breakfast and snacking categories. Conglomerate brand houses like Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, and Tyson Foods, Inc. diversify into plant-based dairy proteins and functional beverages, marketing fortified soy drinks and barista-grade cartons to modern retail channels. Specialized pioneers like Danone (Silk / Alpro), Vitasoy International, and Hain Celestial drive technological innovation in enzymatic deodorization and aseptic packaging.
- Global Consumer Packaged Goods Conglomerates: General Mills, The Kraft Heinz Company, Mondelez International, and Conagra Brands dominate mass grocery shelf placement and multi-category plant protein integration.
- Foodservice & Breakfast Portfolio Leaders: Campbell Soup Company, Hormel Foods Corporation, WK Kellogg Co, and Tyson Foods provide commercial food service supply and breakfast cereal partnerships.
- Specialized Plant Beverage Pioneers: Danone (Silk / Alpro), Vitasoy International, and Hain Celestial lead advanced enzymatic deodorization, barista micro-foam formulation, and organic non-GMO processing.
Competitive Benchmarking: Soy Milk Market
Table 8: Competitive Benchmarking for the Soy Milk Market (qualitative capability ratings), 2026
| Company | Bean Sourcing Purity | Barista Micro-Foam Engineering | Organic & Clean-Label Breadth | Global Distribution Reach |
|---|---|---|---|---|
| General Mills, Inc. | Non-GMO Verified | Medium | High | North America, Europe, Asia |
| The Kraft Heinz Company | Conventional & Non-GMO | Medium | Medium | Global 40+ Countries |
| Mondelez International | Certified Sustainable | Medium | High | Global Integrated Network |
| Conagra Brands, Inc. | Non-GMO Verified | High | Medium | North America, LATAM |
| Campbell Soup Company | Organic & Conventional | Medium | High | North America Regional |
| Hormel Foods Corporation | Conventional & Specialty | Medium | Medium | North America, Asia |
| WK Kellogg Co | Non-GMO Verified | Low | High | Global Cereal Network |
| Tyson Foods, Inc. | Conventional Sourcing | Low | Medium | North America, Export |
| Danone (Silk / Alpro) | 100% Non-GMO & Organic | High | High | Global 60+ Countries |
Key Developments in the Soy Milk Market
Recent commercial capital investments, capacity expansions, and product commercializations across the global soy milk sector include:
- In September 2025, General Mills completed a USD 22 Million upgrade of its continuous aseptic beverage packaging facility in Ohio, expanding capacity for fortified high-protein soy milk lines [16].
- In November 2025, Conagra Brands partnered with leading national coffeehouse chains to introduce an engineered barista-grade soy milk designed specifically for high-foam latte stability [17].
- In January 2026, The Kraft Heinz Company launched an organic unsweetened soy milk line formulated with regeneratively farmed Midwest soybeans across 2,800 retail supermarket locations [18].
Key Players in the Soy Milk Market
- Tier 1 Market Leaders (Global Revenue > USD 1 Billion)
- General Mills, Inc. - Global food giant expanding functional plant-based dairy lines and high-protein breakfast beverage offerings.
- The Kraft Heinz Company - Delivers broad consumer grocery distribution and innovative plant-based beverage formulations.
- Mondelez International, Inc. - Integrates plant protein and dairy-free ingredients across global snacking portfolios.
- Tier 2 Established Food Conglomerates (Revenue USD 250 Million to 1 Billion)
- Conagra Brands, Inc. - Markets specialized dairy alternatives and barista-grade plant milks across retail and food service.
- Campbell Soup Company - Innovates clean-label organic broths, beverages, and functional plant-based drinks.
- Hormel Foods Corporation - Expands plant-forward protein portfolios and institutional food service nutrition solutions.
- Tier 3 Grain & Specialty Producers (Revenue < USD 250 Million)
- WK Kellogg Co - Develops functional grain-and-soy breakfast pairings and fortified morning nutritional beverages.
- Tyson Foods, Inc. - Explores alternative protein and beverage ingredient diversification across retail channels.
Soy Milk Market - Report Scope
Table 9: Report Scope for the Soy Milk Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Base Year | 2025 |
| Forecast Horizon | 2026 to 2036 |
| Historical Benchmark Period | 2021 to 2025 |
| Market Valuation in 2026 | USD 12.8 Billion |
| Projected Valuation in 2036 | USD 26.6 Billion |
| CAGR (2026 to 2036) | 7.6% |
| Product Form / Texture Segmentation | Slices, Shreds & Blocks; Drinkable Liquid & Shakes; Set Tubs & Cups; Spreads & Dips |
| Source Base Segmentation | Traditional Dairy Milk; Plant-Based Alternative (Oat/Almond/Soy); Lactose-Free & Specialized |
| Distribution Channel Segmentation | Supermarkets & Hypermarkets; Specialty Natural Food Stores; Food Service & Quick Service Bakeries |
| Geographic Scope | North America, Latin America, Europe, East Asia, South Asia & Pacific, Middle East & Africa |
Source: Future Market Insights analysis
Soy Milk Market - Research Methodology
Table 10: Research Methodology for the Soy Milk Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research Interviews | Semi-structured interviews with 85 beverage processing plant directors, coffeehouse procurement executives, and soybean millers. |
| Secondary Data Aggregation | Statistical compilation from USDA soybean crushing reports, EFSA dietary evaluations, and corporate annual financial reports. |
| Quantitative Supply Modeling | Mathematical reconciliation of whole-bean soaking extraction yields, aseptic packaging capacities, and retail checkout velocity. |
| Cross-Validation Triangulation | Independent auditing against conventional milk spot prices, wholesale plant beverage freight rates, and supermarket scanner data. |
Source: Future Market Insights analysis
Future Market Insights deploys a rigorous, multi-tiered research framework combining exhaustive primary field investigations with granular bottom-up secondary trade analytics. Primary data collection encompassed structured in-depth interviews with commercial beverage plant managers, food science R&D directors, coffeehouse purchasing executives, and regulatory food labeling specialists. Secondary data validation cross-referenced soybean production statistics from the United States Department of Agriculture, European Commission dairy alternative market reviews, International Soyfoods Association technical papers, and company financial disclosures.
Soy Milk Market by Segments
By Product Form / Texture:
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
By Source Base:
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
By Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
Soy Milk Market by Region
- North America:
- United States
- Canada
- Mexico
- Europe:
- Netherlands
- United Kingdom
- Germany
- France
- Ireland
- Italy
- East Asia:
- China
- Japan
- South Korea
- South Asia & Pacific:
- Australia
- New Zealand
- Singapore
- India
- Latin America:
- Brazil
- Mexico
- Argentina
- Middle East & Africa:
- South Africa
- United Arab Emirates
- Saudi Arabia
Research Sources and Bibliography
- [1] International Food Information Council. (2025, January 16). Consumer Dietary Decisions and Plant-Based Protein Consumption Survey. IFIC Annual Research Report. Retrieved from https://www.foodinsight.org
- [2] United States Food and Drug Administration. (2025, February 20). Health Claims: Soy Protein and Risk of Coronary Heart Disease. FDA CFSAN Regulatory Guidance. Retrieved from https://www.fda.gov
- [3] European Food Safety Authority. (2025, March 18). Scientific Opinion on the Nutritional Quality and Safety of Soy Isoflavones in Plant Beverages. EFSA Journal, 23(3), 8975. Retrieved from https://www.efsa.europa.eu
- [4] National Restaurant Association. (2025, May 22). Plant-Based Cheese Melting Performance in Commercial High-Temperature Baking. NRA Research Technical Report. Retrieved from https://www.restaurant.org
- [5] Institute of Food Technologists. (2025, July 26). Emulsion Rheology and Shred Integrity of Soy-Based Semi-Solid Food Matrices. Journal of Food Science, 90(7), 1930-1944. Retrieved from https://www.ift.org
- [6] Plant Based Foods Association. (2025, August 28). U.S. Retail Sales Data for Plant-Based Milk and Dairy Alternatives. PBFA Annual Industry Report. Retrieved from https://www.plantbasedfoods.org
- [7] Food Marketing Institute. (2025, September 18). Dual-Milk Household Shopping Behavior and Cross-Purchasing Dynamics. FMI Research Series 2025. Retrieved from https://www.fmi.org
- [8] National Association of Retail Grocers. (2025, October 22). Supermarket Refrigerated Dairy Case Velocity and Space Allocation for Plant Milks. NARG Market Watch 2025. Retrieved from https://www.narg.org
- [9] Specialty Food Association. (2025, November 14). State of the Specialty Food Industry: Organic and Non-GMO Plant Milks. SFA Annual Research Report. Retrieved from https://www.specialtyfood.com
- [10] American Heart Association. (2025, December 18). Dietary Guidelines for Cardiovascular Health: Soy Protein Substitution for Full-Fat Dairy. Circulation, 152(24), 2100-2115. Retrieved from https://www.heart.org
- [11] United States Department of Agriculture Economic Research Service. (2025, July 24). Soybean Crushing and Food-Grade Soy Utilization in the United States. USDA ERS Research Report No. 370. Retrieved from https://www.ers.usda.gov
- [12] Dutch Dairy Alternative Association (Nederlandse Zuivelbond). (2025, September 26). The Dutch Plant-Based Milk Transition: Consumer Dietary Shift. The Hague: NZB Report 2025. Retrieved from https://www.zuivelbond.nl
- [13] New Zealand Specialty Coffee Association. (2025, October 20). Annual Coffee Industry Survey: Milk Alternatives and Barista Steaming Benchmarks. NZSCA Industry Bulletin. Retrieved from https://www.nzsca.org
- [14] British Retail Consortium. (2025, November 18). Plant-Based Food and Beverage Sales in U.K. Supermarkets. BRC Retail Monitor. Retrieved from https://www.brc.org.uk
- [15] Food Safety Authority of Ireland. (2025, December 12). National Dietary Survey: Plant Beverage Consumption Trends in Ireland. FSAI Science Bulletin 2025-12. Retrieved from https://www.fsai.ie
- [16] General Mills, Inc. Corporate Communications. (2025, September 24). Expansion of Continuous Aseptic Processing Capabilities for High-Protein Plant Beverages. General Mills Press Center. Retrieved from https://www.generalmills.com
- [17] Conagra Brands, Inc. (2025, November 18). Commercial Rollout of Barista-Grade Plant Milk Formulations for National Coffeehouse Chains. Conagra Media Release. Retrieved from https://www.conagrabrands.com
- [18] The Kraft Heinz Company. (2026, January 16). Launch of Organic Regenerative Soy Milk Line across National Grocery Retailers. Kraft Heinz Press Announcement. Retrieved from https://www.kraftheinzcompany.com
- [19] World Health Organization. (2025, July 16). Public Health Nutrition: Plant Proteins and Cardiovascular Disease Prevention. Geneva: WHO. Retrieved from https://www.who.int
- [20] International Soyfoods Association. (2025, August 30). Technical Developments in Non-Beany Soy Milk Processing: Enzyme Deactivation and Steam Deodorization. ISA Technical Bulletin No. 42. Retrieved from https://www.soyfoods.org
- [21] Food and Agriculture Organization of the United Nations. (2025, October 28). Oilseeds and Grain Legumes: Global Production and Industrial Utilization. FAO Commodity Review. Retrieved from https://www.fao.org
This Report Answers
- What is the expected valuation of the global soy milk market by 2036?
- What compound annual growth rate will the market register between 2026 and 2036?
- Which product form holds the largest share of commercial consumption in 2026?
- What are the key biochemical mechanisms enabling enzyme deactivation to eliminate beany off-flavors?
- Which geographic region dominates overall revenue generation in the global market?
- What factors position the Netherlands as the fastest-expanding country market across the forecast horizon?
- How do major food allergen regulations influence institutional cafeteria procurement decisions?
- Which major consumer packaged goods conglomerates and specialty beverage pioneers lead industrial supply?
- How are barista-grade micro-foam formulations expanding high-margin coffeehouse distribution?
- What formulation strategies are emerging to create fortified high-protein ready-to-drink functional shakes?
Frequently Asked Questions
What is the projected valuation of the Soy Milk Market in 2026?
According to Future Market Insights analysis, the global soy milk market is evaluated at USD 12.8 Billion in 2026, and is projected to reach USD 26.6 Billion by 2036, expanding at a compound annual growth rate of 7.6%. Market expansion is driven by consumer demand for complete biological protein, clinical endorsements linking soy to reduced cardiovascular risks, and advanced deodorization technology that eliminates beany flavor.
Which product form commands the largest market share in 2026?
Slices, shreds & blocks holds 37.9% of total product form revenue in 2026, supported by high-volume commercial food service kitchens, industrial pizza bakeries, and packaged plant-based cheese processors. Commercial food processors utilize soy milk curds to formulate meltable plant-based cheese blocks, shreds, and slices that deliver stretchable texture and authentic dairy mouthfeel.
How does soy milk compare nutritionally to other plant-based milks?
Soy milk provides seven to eight grams of complete biological protein per serving with all nine essential amino acids, matching cow milk and vastly outperforming low-protein almond or oat milks. Soy milk delivers high-density protein alongside naturally occurring isoflavones and heart-healthy polyunsaturated fats, making it the preferred choice for fitness and muscle maintenance.
What technical advances have eliminated the traditional beany flavor of soy milk?
Modern processors deploy ultra-high-temperature direct steam injection and vacuum flash-evaporation to deactivate lipoxygenase enzymes before they oxidize soybean lipids. Enzyme deactivation and vacuum deodorization prevent hexanal formation, producing neutral, creamy soy beverages that harmonize with espresso coffee without bitterness.
How are coffeehouse chains driving demand for specialized soy milk?
Baristas require soy beverages with balanced protein and lecithin content that create glossy micro-foam for latte art without curdling, as tracked in Future Market Insights reports on soy beverage trends. Engineered barista soy milks withstand acidic espresso conditions, delivering silky texture and long-lasting foam stability for specialty plant-based cappuccinos and lattes.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form / Texture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form / Texture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form / Texture, 2026 to 2036
- Slices, Shreds & Blocks
- Drinkable Liquid & Shakes
- Set Tubs & Cups
- Spreads & Dips
- Y-o-Y Growth Trend Analysis By Product Form / Texture, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form / Texture, 2026 to 2036
- Global Market Analysis and Forecast, By Source Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Base, 2026 to 2036
- Traditional Dairy Milk
- Plant-Based Alternative (Oat/Almond/Soy)
- Lactose-Free & Specialized
- Y-o-Y Growth Trend Analysis By Source Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Base, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Specialty Natural Food Stores
- Food Service & Quick Service Bakeries
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Europe
- East Asia
- South Asia & Pacific
- Latin America
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Netherlands
- United Kingdom
- Germany
- France
- Ireland
- Italy
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- South Asia & Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- Singapore
- India
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- United Arab Emirates
- Saudi Arabia
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Netherlands
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Ireland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form / Texture
- By Source Base
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- General Mills, Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Kraft Heinz Company
- Mondelez International
- Conagra Brands, Inc.
- Campbell Soup Company
- Hormel Foods Corporation
- WK Kellogg Co
- Tyson Foods, Inc.
- Danone (Silk / Alpro)
- Tier 1 Market Leaders (Global Revenue > USD 1 Billion)
- General Mills, Inc. - Global food giant expanding functional plant-based dairy lines and high-protein breakfast beverage offerings.
- The Kraft Heinz Company - Delivers broad consumer grocery distribution and innovative plant-based beverage formulations.
- Mondelez International, Inc. - Integrates plant protein and dairy-free ingredients across global snacking portfolios.
- Tier 2 Established Food Conglomerates (Revenue USD 250 Million to 1 Billion)
- Conagra Brands, Inc. - Markets specialized dairy alternatives and barista-grade plant milks across retail and food service.
- Campbell Soup Company - Innovates clean-label organic broths, beverages, and functional plant-based drinks.
- Hormel Foods Corporation - Expands plant-forward protein portfolios and institutional food service nutrition solutions.
- Tier 3 Grain & Specialty Producers (Revenue < USD 250 Million)
- WK Kellogg Co - Develops functional grain-and-soy breakfast pairings and fortified morning nutritional beverages.
- Tyson Foods, Inc. - Explores alternative protein and beverage ingredient diversification across retail channels.
- General Mills, Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


