
- Market Size (2026)
- USD 46.8 Bn
- Forecast (2036)
- USD 85.4 Bn
- CAGR (2026 to 2036)
- 6.2%
How big is Soy Food Products Market in 2026?
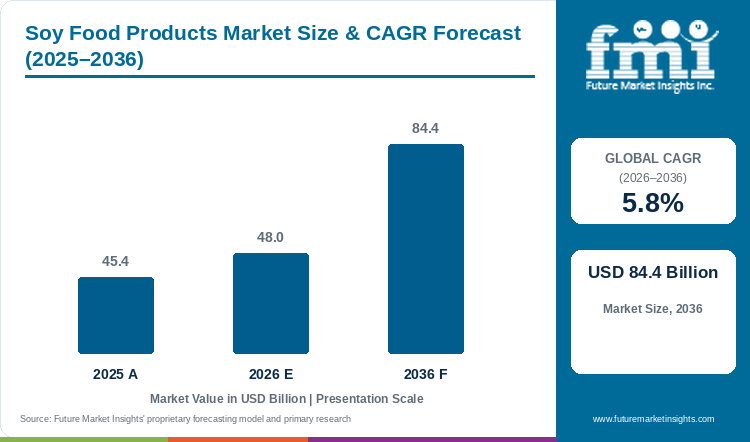
The soy food products market demonstrated steady progress from USD 44.0 billion in 2025 to USD 46.8 billion in 2026, building toward a targeted valuation of USD 85.4 billion by 2036 at a CAGR of 6.2%.
Table 1: Market Size and Forecast for the Soy Food Products Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 44.0 billion |
| Estimated Market Size in 2026 | USD 46.8 billion |
| Projected Market Size by 2036 | USD 85.4 billion |
| CAGR, 2026 to 2036 | 6.2% |
| Added Revenue, 2026 to 2036 | USD 38.6 billion |
The global soy food products market was valued at USD 44.0 billion in 2025 and is estimated to reach USD 46.8 billion in 2026. The market is projected to reach USD 85.4 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.2% between 2026 and 2036. Soy Milk and Ready Drinks command 39.0% of 2026 category demand, since vacuum steam-infusion deodorization preserves 7 to 9 grams of complete protein per serving without beany off-notes. Demand for whole-bean and fermented soy foods is reinforced by complete amino-acid nutrition and clean-label umami seasoning across retail and foodservice kitchens. FMI foodservice and grocery tracking reflects a structural divergence from the commodity textured vegetable protein ingredient trade under conditions where branded soy beverages, chilled tofu, and brewed shoyu command higher retail margins per kilogram. Major producers are expanding global brand platforms and vegan certifications to capture that shift, as Kikkoman launched its dedicated Soymilk Global Site in February 2025 and obtained North American Vegetarian Society vegan certification across nine core soy sauces in January 2025. Supermarkets and institutional buyers lock in multi-year contracts with processors that guarantee identity-preserved non-GMO soybean traceability through 2036.
Key Market Trends & Insights
- By product category: Soy Milk and Ready Drinks leads the product category segment with a 39.0% share in 2026 given that whole-bean extraction delivers 7 to 9 grams of complete protein per serving.
- By processing type: Fermented Soy Foods captures 64.0% of the processing type segment in 2026 as consumers demand naturally brewed shoyu, aged miso, and natto in grocery aisles.
- By source certification: Non-GMO Certified Organic Soybeans command a 72.0% share in 2026 owing to strict European, Japanese, and North American food-grade identity-preservation mandates.
- By distribution channel: Retail Supermarkets and Asian Specialty Grocers account for 56.0% of total distribution in 2026 through dedicated chilled plant-based doors and pan-Asian condiment sections.
- By packaging format: Aseptic Cartons and Vacuum Pouches represent 52.0% of packaging format sales in 2026 by enabling ambient shelf stability for UHT soy beverages and silken tofu without refrigeration.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at a 7.4% CAGR through 2036 as food processors incorporate textured soy protein into retail meat extensions and lactose-free soy drinks.
- Broader country progression: Brazil tracks at a 6.7% CAGR ahead of the United States at 6.5% and Canada at 6.3%, whereas Spain advances at a 5.5% CAGR.
Market Size & Forecast
Commercial tofu and soy beverage plants confront curd syneresis and okara byproduct disposal costs when processing whole food-grade soybeans. In September 2025, food engineers reporting in Foods demonstrated that optimizing soy milk solid concentrations at 9% to 10% Brix during coagulation while valorizing okara side streams containing 17% to 29% dry-weight protein substantially improves plant yield economics. Accordingly, operations directors pair high-yield whole-bean grinding with plant-based protein extraction systems to eliminate wet-curd waste.
Food-Grade Soybean Harvest, Tofu Coagulation, and Brewing Sizing
Table 2: Food-Grade Soybean and Processing Sizing for the Soy Food Products Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 44.0 | 46.8 | 85.4 |
| Food-grade identity-preserved soybean usage (million metric tons) | 14.8 to 16.2 | 15.7 to 17.2 | 27.5 to 30.2 |
| Packaged soy milk & ready beverage volume (billion liters) | 8.4 to 9.2 | 8.9 to 9.8 | 15.8 to 17.4 |
| Average retail price across tofu & soy beverages (USD per kg/L) | 2.45 to 3.10 | 2.52 to 3.20 | 2.75 to 3.55 |
Operational note: Food-grade soybean ranges isolate identity-preserved human food processing beans and exclude bulk solvent-extracted animal feed meal and biodiesel crush.
Continuous tofu coagulation lines require precise control of soy milk solid concentration and calibrated calcium sulfate or magnesium chloride nigari dosing to maximize curd water-holding capacity. Specialty processors also expand fermented tempeh fermentation lines to serve flexitarian center-of-plate protein demand.
Per Capita & Commercial Tofu and Soy Beverage Line Sizing
Table 3: Per Capita and Processing Line Spending Indicators for the Soy Food Products Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per 1,000 people (USD) | 5,365.9 | 5,638.6 | 9,488.9 |
| Annual revenue per commercial tofu & UHT soy line (USD million) | 22.0 to 26.5 | 23.4 to 28.0 | 40.5 to 48.0 |
| Non-GMO certified organic & IP share (%) | 70.0% to 71.5% | 71.5% to 72.5% | 76.0% to 79.0% |
Table 4: Retail & Channel Spending Indicators for the Soy Food Products Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 46.8 billion | 2026 global revenue baseline |
| Commercial tofu, soymilk & shoyu plants global | 1,850 facilities | Industrial coagulation, UHT soy beverage & Koji brewing plants |
| Annual output value per facility | USD 25.3 million | Annualized soy food processing value |
| Retail Supermarkets and Asian Specialty Grocers, 2026 | USD 26.2 billion | 56.0% distribution channel allocation |
High-salt liquid-state fermentation of naturally brewed soy sauce and traditional miso relies on selected Aspergillus oryzae starter cultures to achieve premium umami grading. In November 2025, fermentation scientists publishing in Foods documented that controlled Koji proteolysis under updated GB/T 18186-2025 brewing standards elevates amino acid nitrogen levels to 1.37 grams per 100 milliliters without chemical acid hydrolysis.
Analyst Perspective
"Food-grade soy processors are winning back plant-based beverage doors and center-store grocery shelves since whole soybeans offer unbeatable complete protein economics, clean-label fermentation heritage, and zero-cholesterol versatility."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the soy food products market segmented?
The soy food products market is segmented by product category, processing type, source certification, distribution channel, and packaging format. In 2026, Soy Milk and Ready Drinks is projected at 39.0%, Fermented Soy Foods at 64.0%, Non-GMO Certified Organic Soybeans at 72.0%, Retail Supermarkets and Asian Specialty Grocers at 56.0%, and Aseptic Cartons and Vacuum Pouches at 52.0%.
By product category: Soy Milk and Ready Drinks, Tofu Silken Firm and Extra Firm, Soy Sauce and Fermented Pastes Miso, Textured Soy Protein TSP and Chunks, and Edamame and Roasted Soybeans.
By processing type: Fermented Soy Foods, Non-Fermented Soy Foods, Sprouted and Germinated Soy Products, and Enzyme-Modified Soy Preparations.
By source certification: Non-GMO Certified Organic Soybeans, Conventional Commercial Soybeans, Identity-Preserved Non-GMO Soybeans, and Regenerative Certified Soybeans.
By distribution channel: Retail Supermarkets and Asian Specialty Grocers, Foodservice Institutional and Commercial Kitchens, Online Grocery and Direct-to-Consumer Channels, and Industrial Food Processing B2B Supply.
By packaging format: Aseptic Cartons and Vacuum Pouches, Chilled Water-Pack Plastic Tubs, Glass Bottles and Brewing Jars, and Bulk Multi-Wall Industrial Sacks.
Why do Soy Milk and Ready Drinks lead the product category?
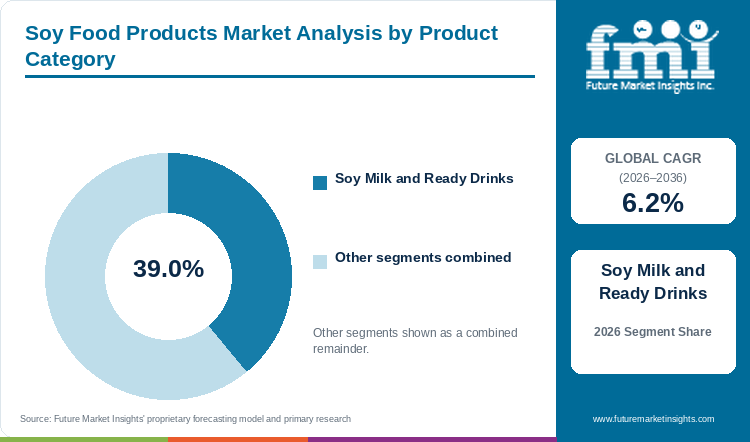
Soy Milk and Ready Drinks hold an estimated 39.0% of product category demand in 2026, anchored by complete plant protein nutrition and barista coffee compatibility.
Table 5: Product Category Share for the Soy Food Products Market (percentage share), 2026
| Product Category | Share (2026) |
|---|---|
| Soy Milk and Ready Drinks | 39.0% |
| Other Segments Combined | 61.0%* |
| Total | 100.0% |
*Note: Remaining product category segments account for the balance of 2026 global soy food products demand.
Table 6: Product Category Leadership and Market Growth for the Soy Food Products Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.2% |
| Leading Segment | Soy Milk and Ready Drinks |
Soy Milk and Ready Drinks processed via vacuum steam-infusion deodorization lead global product category revenue as whole-bean extraction preserves native protein and calcium fortification near miso paste culinary staples. Coffee-shop chains and household breakfast buyers favor soy beverages under conditions where soy lecithin and globulins form stable micro-foam under steam.
- Soy Milk and Ready Drinks hold 39.0% of product category value in 2026 given that high protein density and neutral espresso micro-foam performance drive repeat grocery and coffee-chain purchases.
- Vitasoy International Holdings Limited reported FY2025/2026 annual business results in June 2026 confirming sustained profitability across its core Vitasoy soy milk and ready-to-drink plant beverage operations in China, Hong Kong, and Australia.
What sustains Fermented Soy Foods leadership in the processing type segment?
Fermented Soy Foods represent 64.0% of the processing type category in 2026, supported by global demand for naturally brewed soy sauce, miso, tempeh, and natto.
Microbial fermentation using Aspergillus oryzae, Rhizopus oligosporus, and Bacillus subtilis converts soy isoflavone glycosides into bioavailable aglycones and umami-rich free amino acids. Consumers pair fermented soy condiments with soy beverage cartons across Asian and Western grocery baskets.
- Fermented Soy Foods represent 64.0% of the processing type segment in 2026 as naturally brewed soy sauce, aged miso, and natto anchor daily culinary preparation across Asia and Western markets.
- A December 2024 review in Nutrients (PMC11647071) documented how bioactive peptides and isoflavone aglycones generated during miso, tempeh, and natto fermentation improve gut microbiome diversity and protein digestibility.
How do Non-GMO Certified Organic Soybeans lead the source certification category?
Non-GMO Certified Organic Soybeans account for 72.0% of source certification volume in 2026, driven by strict human food identity-preservation mandates.
Food-grade soy processors contract clear-hilum non-GMO organic soybeans from Ontario, Quebec, the U.S. Midwest, and Heilongjiang with segregated farm-to-plant storage for Japanese soy drinks and tofu manufacturing. Dedicated container sealing and PCR testing prevent cross-contact with commodity biotech crush beans.
- Non-GMO Certified Organic Soybeans account for 72.0% of source certification demand in 2026 since European, Japanese, and North American grocery buyers require verified non-GMO clean labels on human soy foods.
- The Nisshin OilliO Group reported an 82.9% verified sustainable and identity-preserved soybean supply rate in July 2025 under its FY2025 Soybean Action Plan for food-grade soy operations.
Why do Retail Supermarkets and Asian Specialty Grocers lead the distribution channel category?
Retail Supermarkets and Asian Specialty Grocers secure 56.0% of distribution channel value in 2026, supported by chilled plant-based doors and pan-Asian grocery growth.
Mainstream supermarket chains allocate wider multi-deck refrigerated doors to organic tofu, edamame, and plant-based milk while pan-Asian specialty grocers expand across North American and European metropolitan suburbs. Direct store delivery networks keep chilled water-pack tofu tubs fresh.
- Retail Supermarkets and Asian Specialty Grocers secure 56.0% of distribution channel demand in 2026 as mainstream grocers widen chilled plant-protein planograms and Asian specialty chains expand.
- House Foods Group Inc. detailed in its October 2025 Integrated Report how expanded U.S. tofu manufacturing capacity in California, New Jersey, and Ohio supports rising retail supermarket distribution.
What gives Aseptic Cartons and Vacuum Pouches the leading position in packaging format?
Aseptic Cartons and Vacuum Pouches command 52.0% of packaging format share in 2026, anchored by 9-to-12-month ambient shelf stability without refrigeration.
Six-layer laminated paperboard-aluminum aseptic bricks and retort vacuum pouches protect soy beverages and silken tofu from oxygen and light for 9 to 12 months without refrigeration. Ambient pallet stacking reduces warehouse energy consumption and parcel shipping weight.
- Aseptic Cartons and Vacuum Pouches command 52.0% of packaging format value in 2026 as ambient shelf stability eliminates cold-chain freight costs and prevents glass breakage in e-commerce.
- Eden Foods introduced one-year and two-year cypress-barrel aged organic shoyu soy sauces and shelf-stable organic soy food packages in September 2024 to serve specialty retail channels.
What are the drivers, restraints, and opportunities in the soy food products market?
In the soy food products market, clinically validated cardiometabolic health benefits and bakery egg-replacement savings are projected to drive adoption while soy allergen labeling and non-GMO identity-preservation premiums restrain margins and okara upcycling creates new value.
- Driver: Clinical validation of soy isoflavone cholesterol reduction and commercial bakery egg replacement with functional soy proteins propel retail and B2B adoption.
- Restraint: Strict allergen labeling for Gly m 5 and Gly m 6 storage globulins and 25% to 40% price premiums for identity-preserved non-GMO soybeans constrain margins.
- Opportunity: Upcycling soybean okara pulp into high-fiber snacks and nitrogen-protected clean-label soy protein gels create high-margin product tiers.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Health-conscious consumers are rotating back from low-protein nut waters toward whole-bean soy-based food items that deliver complete amino acid profiles and cardiometabolic benefits. In March 2026, an umbrella review in Frontiers in Nutrition confirmed that soy isoflavone and soy protein intake significantly reduces total cholesterol (mean difference minus 0.12 mmol/L) while unfermented soy intake raises HDL cholesterol by 0.06 mmol/L.
Risk Assessment of the Soy Food Products Market: Operational and Formulation Friction
Strict allergen labeling requirements for Gly m 5 and Gly m 6 storage globulins across North America, the European Union, and Japan restrict soy adoption in allergen-free school and hospital menus. In October 2026, food safety researchers in Foods analyzed 216.0 million hectares of global biotech crops and demonstrated that Gly m 5 and Gly m 6 soy allergens retain high thermal stability during industrial food processing, requiring rigorous line sanitation in commercial soy milk plants.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Processors capture higher margins by engineering clean-label soy protein gel matrices for non-dairy yogurt and plant-based meat analogs without synthetic hydrocolloids. In February 2026, biopolymer researchers in PLOS One demonstrated that nitrogen-protected thermal induction paired with microbial transglutaminase cross-linking produces high-elasticity soy protein isolate gels for clean-label foods.
Soy Food Products Market by Country (2026 to 2036)
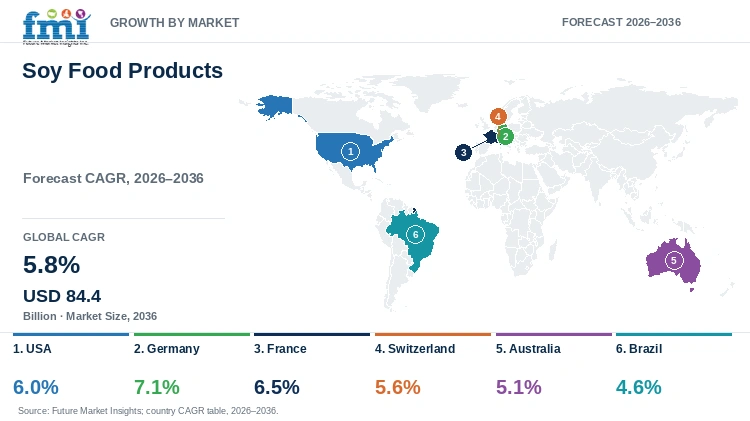
FMI country modeling indicates that Mexico leads soy food products expansion at a 7.4% CAGR through 2036, while Brazil follows at 6.7% ahead of the United States at 6.5% and Spain at 5.5%.
Table 7: Country CAGR and Primary Growth Levers for the Soy Food Products Market (CAGR percentage and operational driver), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 7.4% | Textured soy protein in retail meat extensions and lactose-free soy drinks |
| Brazil | 6.7% | Domestic value-added processing of aseptic soy beverages and TSP |
| United States | 6.5% | Chilled tofu plant expansions, brewed shoyu, and Silk plant-based drinks |
| Canada | 6.3% | Record 7.5M tonne soybean crop in Ontario and Quebec supporting IP food soy |
| China | 6.1% | GB/T 18186-2025 zero-additive brewed soy sauce and packaged chilled tofu |
| Japan | 5.9% | High per-capita natto, silken tofu, miso, and functional soymilk consumption |
| United Kingdom | 5.7% | Supermarket smoked and marinated tofu blocks and barista soy beverages |
| Spain | 5.5% | 244 new supermarket openings in early 2025 and ambient UHT soy drinks |
Source: Future Market Insights analysis
Mexico Soy Food Products Market Outlook (2026 to 2036)
Soy food products demand in Mexico is projected to lead global growth at a 7.4% CAGR between 2026 and 2036. In April 2026, the USDA Foreign Agricultural Service Mexico City office reported in its Mexico Food Processing Ingredients Annual (MX2026-0018) that Mexican agricultural and food ingredient imports reached a record 30.6 billion in 2025, led by soybeans and food preparations. Widespread incorporation of textured soy protein into affordable retail chorizo and taco fillings combines with rising urban demand for lactose-free soy beverages.
Key takeaway: In Mexico, textured soy protein meat extensions and lactose-free retail soy drinks are projected to drive a leading 7.4% CAGR through 2036.
Brazil Soy Food Products Market Outlook (2026 to 2036)
Based on FMI's South American agribusiness assessment, Brazil is forecast to climb at a 6.7% CAGR through 2036. Brasilia agricultural trade data published in March 2026 (BR2026-0008) documented how record domestic soybean harvesting and crushing capacity support expansion into value-added food-grade soy protein and beverage processing. Domestic processors scale aseptic soy drinks, textured soy protein, and chilled tofu for metropolitan supermarkets.
Key takeaway: In Brazil, domestic value-added processing of aseptic soy beverages and textured soy chunks is forecast to sustain a 6.7% CAGR.
United States Soy Food Products Market Outlook (2026 to 2036)
FMI's North American grocery scanner audit indicates that the United States soy food products market will grow at a 6.5% CAGR through 2036. In February 2026, the USDA Economic Research Service reported in its Oil Crops Outlook (OCS-26b) that global soybean output reached 428.2 million metric tons with strong U.S. domestic food and crush utilization. Dedicated investments in U.S. tofu manufacturing plants in California, New Jersey, and Ohio combine with steady foodservice demand for brewed soy sauce and edamame.
Key takeaway: In the United States, domestic tofu capacity expansion and high-protein plant beverage demand are estimated to support a 6.5% CAGR through 2036.
Canada Soy Food Products Market Outlook (2026 to 2036)
Per FMI's Canadian agricultural and retail model, Canada will register a 6.3% CAGR over the 2026 to 2036 forecast window. In September 2026, Statistics Canada reported that Canadian soybean production rose 7.8% in 2026 to 7.5 million tonnes, led by 4.0 million tonnes in Ontario (+11.8%) and 1.4 million tonnes in Quebec (+14.0%). Identity-preserved non-GMO harvests in Ontario and Quebec supply both domestic tofu and soy milk plants and premium food-soy export containers.
Key takeaway: In Canada, a 7.8% increase in soybean output to 7.5 million tonnes across Ontario and Quebec underpins a 6.3% CAGR.
China Soy Food Products Market Outlook (2026 to 2036)
In FMI's East Asian staple food analysis, China is slated to expand at a 6.1% CAGR over the 2026 to 2036 horizon. March 2026 Beijing agricultural reporting (CH2026-0032) confirmed that domestic non-genetically engineered food soybeans in Northeast China anchor local tofu and soymilk production as well as food-soy exports to Japan and Korea. Packaged chilled tofu and zero-additive brewed soy sauces steadily replace unbranded wet-market curds.
Key takeaway: In China, non-GE food-grade soybean cultivation and packaged chilled tofu modernization are slated to generate a 6.1% CAGR through 2036.
Japan Soy Food Products Market Outlook (2026 to 2036)
FMI's Japanese food industry tracking places Japan at a 5.9% CAGR through 2036 as consumers maintain high per-capita intake of natto, silken tofu, and functional soy milk beverages. In May 2026, Morinaga Milk Industry Co. Ltd. outlined its FY2026 international tofu and nutritional beverage capital investment program in its Corporate Overview. Japanese manufacturers actively export long-life aseptic silken tofu and naturally brewed shoyu to North American and European grocers.
Key takeaway: Functional soy milk beverages, high-protein tofu bars, and aseptic tofu exports in Japan are projected to lift demand at a 5.9% CAGR.
United Kingdom Soy Food Products Market Outlook (2026 to 2036)
From FMI's UK retail grocery model, the United Kingdom is projected to progress at a 5.7% CAGR from 2026 to 2036. In December 2025, the UK Department for Environment, Food and Rural Affairs reported in its United Kingdom Food Security Digest 2025 that resilient global soybean supply (428 million metric tons) and a 21% first-quarter moderation in wholesale soy meal prices stabilized UK plant-protein supply chains. Mainstream supermarket adoption of smoked and pre-marinated tofu blocks and barista soy milk drives weekly basket penetration.
Key takeaway: In the United Kingdom, pre-marinated chilled tofu blocks and coffee-shop barista soy milk adoption are forecast to sustain a 5.7% CAGR.
Spain Soy Food Products Market Outlook (2026 to 2036)
FMI's Iberian retail audit forecasts a 5.5% CAGR for Spain between 2026 and 2036. In November 2025, the USDA Foreign Agricultural Service Madrid office reported in its Spain Retail Foods Annual (SP2025-0022) that Spanish grocery retailers opened 244 new supermarkets between January and April 2025 (+25% year-on-year), expanding shelf space for plant-based beverages and convenience foods. High household penetration of ambient UHT soy drinks across Mercadona and Carrefour anchors steady volume growth.
Key takeaway: In Spain, a 25% surge in new supermarket openings and ambient UHT soy beverage penetration are predicted to support a 5.5% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the soy food products market?
Kikkoman Corporation, Danone SA, The Hain Celestial Group Inc., House Foods Group Inc., Vitasoy International Holdings Ltd, The Nisshin OilliO Group Ltd, Eden Foods Inc., Pulmuone Co., Ltd., Archer Daniels Midland Company, and Morinaga Milk Industry Co., Ltd. are the notable companies in the soy food products market.
Competitive positioning in the soy food products industry separates global fermented condiment and beverage leaders, packaged tofu and Asian soy specialists, and functional soy protein ingredient processors.
- Global Fermented Soy & Plant Beverage Leaders: Kikkoman Corporation and Danone SA operate multi-continent soy sauce breweries and aseptic soy milk plants. Vitasoy International Holdings Ltd and The Hain Celestial Group Inc. also anchor retail beverage doors.
- Packaged Tofu & Craft Organic Specialists: House Foods Group Inc. and Pulmuone Co., Ltd. lead chilled and baked tofu manufacturing. Morinaga Milk Industry Co., Ltd. and Eden Foods Inc. supply aseptic silken tofu and barrel-aged organic shoyu.
- Functional Soy Protein & IP Bean Processors: Archer Daniels Midland Company and The Nisshin OilliO Group Ltd supply identity-preserved food-grade soy proteins, textured soy chunks, and functional bakery egg-replacement systems.
Competitive Benchmarking: Soy Food Products Market
Table 8: Competitive Benchmarking for the Soy Food Products Market (qualitative capability ratings), 2026
| Company | Fermentation & Coagulation Mastery | Non-GMO IP Supply Traceability | Clean-Label & Nutrition Fit | Geographic Reach |
|---|---|---|---|---|
| Kikkoman Corporation | High | High | High | Global brewed soy sauce and Japan #1 soy milk brand across 100+ countries |
| Danone SA | Medium | High | High | North America (Silk) and Europe (Alpro) soy beverages and plant yogurts |
| The Hain Celestial Group Inc. | Medium | High | High | Europe (Joya, Natumi) and North America organic soy drinks and condiments |
| House Foods Group Inc. | High | High | High | Japan, United States, and China chilled, organic, and pre-baked tofu |
| Vitasoy International Holdings Ltd | High | High | High | Hong Kong, Mainland China, Australia, and ASEAN soy milk and tofu |
| The Nisshin OilliO Group Ltd | Medium | High | High | Japan and East Asia identity-preserved soy proteins (82.9% verified supply) |
| Eden Foods Inc. | High | High | High | North America organic Edensoy, cypress-barrel shoyu, tamari, and miso |
| Pulmuone Co., Ltd. | High | High | High | South Korea, U.S. (Nasoya, Wildwood), China, and Japan tofu and natto |
| Archer Daniels Midland Company | Medium | High | High | Global Arcon SFP functional soy proteins, isolates, and textured soy |
| Morinaga Milk Industry Co., Ltd. | High | High | High | Japan and global export of Mori-Nu aseptic shelf-stable silken tofu |
Benchmark basis: Fermentation & Coagulation Mastery evaluates Koji brewing and continuous tofu coagulation; Non-GMO IP Supply Traceability measures segregated food-grade soybean contracting.
Key Developments in the Soy Food Products Market
- Pulmuone Co. Ltd. reported a 25.5% first-half 2026 revenue increase in its Sustainable Foods division in September 2026. Growth was led by Whole Soybean Soy Milk, Soybean Tofu Chips, and fermented natto.
- Danone SA reported first-half 2026 revenue of EUR 13,936 million in July 2026, supported by sustained volume-mix growth across its Alpro and Silk plant-based soy beverage and yogurt lines.
- Kikkoman Corporation launched its Soymilk Global Site in February 2025 and secured North American Vegetarian Society vegan certification across nine core soy sauce products in January 2025.
Key Players in the Soy Food Products Market
Global Fermented Soy & Plant Beverage Leaders
- Kikkoman Corporation
- Danone SA
- Vitasoy International Holdings Ltd
- The Hain Celestial Group Inc.
Packaged Tofu & Craft Organic Specialists
- House Foods Group Inc.
- Pulmuone Co., Ltd.
- Morinaga Milk Industry Co., Ltd.
- Eden Foods Inc.
Functional Soy Protein & IP Bean Processors
- Archer Daniels Midland Company
- The Nisshin OilliO Group Ltd
Soy Food Products Market - Report Scope
Table 9: Report Scope for the Soy Food Products Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Category; Processing Type; Source Certification; Distribution Channel; Packaging Format |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from packaged and B2B human-consumption soy food products including soy milk and ready drinks, silken/firm/extra-firm tofu, naturally brewed soy sauce, miso, natto, tempeh, textured soy protein (TSP), functional food soy isolates/concentrates, and edamame. Category Scope Note: Excludes bulk commodity soybean oil for biodiesel/industrial frying and solvent-extracted soybean meal used for livestock and aquaculture feed. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, Brazil, United States, Canada, China, Japan, United Kingdom, Spain, and additional countries in the full report |
| Key Companies Covered | Kikkoman Corporation, Danone SA, The Hain Celestial Group Inc., House Foods Group Inc., Vitasoy International Holdings Ltd, The Nisshin OilliO Group Ltd, Eden Foods Inc., Pulmuone Co., Ltd., Archer Daniels Midland Company, Morinaga Milk Industry Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Soy Food Products Market - Research Methodology
Table 10: Research Methodology for the Soy Food Products Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with commercial tofu and soymilk plant directors, Koji fermentation Brewmasters, identity-preserved grain exporters, and supermarket plant-based category buyers. |
| Secondary Research | Analysis of USDA FAS Oilseeds and Retail Foods Annual reports, USDA ERS Oil Crops Outlook, Statistics Canada field crop surveys, GOV.UK Food Security Digest, and corporate filings. |
| Market Sizing and Forecasting | Top-down global plant-based food and fermented condiment baselines reconciled against bottom-up food-grade IP soybean tonnage (15.7M to 17.2M MT in 2026) and retail unit pricing from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight lactose-intolerance prevalence, food-grade non-GMO harvest capacity, and supermarket plant-beverage slotting across eight national markets. |
| Operational Benchmark Traceability | Food-grade bean and line indicators in Tables 2, 3, and 4 trace to Statistics Canada soybean harvest logs, MDPI tofu coagulation and GB/T 18186-2025 fermentation studies, and USDA FAS reports. |
| Data Triangulation and Validation | Revenue estimates isolate human-grade whole, fermented, and textured soy foods while strictly excluding bulk livestock feed meal and industrial crude soybean oil. |
Soy Food Products Market by Segments
Soy Food Products Market segmented by Product Category:
- Soy Milk and Ready Drinks
- Tofu Silken Firm and Extra Firm
- Soy Sauce and Fermented Pastes Miso
- Textured Soy Protein TSP and Chunks
Soy Food Products Market segmented by Processing Type:
- Fermented Soy Foods
- Non-Fermented Soy Foods
- Sprouted and Germinated Soy Products
- Enzyme-Modified Soy Preparations
Soy Food Products Market segmented by Source Certification:
- Non-GMO Certified Organic Soybeans
- Conventional Commercial Soybeans
- Identity-Preserved Non-GMO Soybeans
- Regenerative Certified Soybeans
- Edamame and Roasted Soybeans
Soy Food Products Market segmented by Distribution Channel:
- Retail Supermarkets and Asian Specialty Grocers
- Foodservice Institutional and Commercial Kitchens
- Online Grocery and Direct-to-Consumer Channels
- Industrial Food Processing B2B Supply
Soy Food Products Market segmented by Packaging Format:
- Aseptic Cartons and Vacuum Pouches
- Chilled Water-Pack Plastic Tubs
- Glass Bottles and Brewing Jars
- Bulk Multi-Wall Industrial Sacks
Soy Food Products Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Kikkoman Corporation. (2025, February 28). Kikkoman Launches Soymilk Global Site to Expand Plant-Based Soy Beverage Awareness. Kikkoman Corporation Newsroom. https://www.kikkoman.com/en/news/2025/20250228_766.html
- [2] Kikkoman Corporation. (2025, January 8). Nine Kikkoman Soy Sauce Products Obtain North American Vegetarian Society Vegan Certification. Kikkoman Corporation Newsroom. https://www.kikkoman.com/en/news/2025/20250108_738.html
- [3] MDPI Foods. (2025, September 15). Processing Optimization of Tofu Coagulation and Nutritional Valorization of Soybean Okara Side Streams. Foods, 14(18), 3206. https://www.mdpi.com/2304-8158/14/18/3206
- [4] MDPI Foods. (2025, November 25). Amino Acid Nitrogen Evolution and Flavor Compound Formation during High-Salt Liquid-State Soy Sauce Fermentation under GB/T 18186-2025. Foods, 14(23), 4049. https://www.mdpi.com/2304-8158/14/23/4049
- [5] Vitasoy International Holdings Limited. (2026, June 25). Vitasoy Announces Annual Business Results for FY2025/2026 and Soy Milk Portfolio Performance. Vitasoy Investor Relations. https://www.vitasoy.com/wp-content/uploads/2026/06/Press-Release-Vitasoy-Announces-Business-Results-for-FY20252026_0625-EN.pdf
- [6] PubMed Central (PMC). (2024, December 15). Bioactive Peptides, Isoflavone Aglycones, and Gut Microbiome Modulation in Fermented Soy Foods Including Miso, Tempeh, and Natto. Nutrients (PMC11647071). https://pmc.ncbi.nlm.nih.gov/articles/PMC11647071/
- [7] The Nisshin OilliO Group, Ltd. (2025, July 18). Sustainability Report and FY2025 Soybean Action Plan Achieving 82.9% Verified Sustainable and Identity-Preserved Soy Supply. Nisshin OilliO Sustainability. https://www.nisshin-oillio.com/english/sustainability/sustain/soy_action_plan.html
- [8] House Foods Group Inc. (2025, October 14). Integrated Report 2025: Expansion of North American Tofu Production and Plant-Based Soy Operations. House Foods Group Investor Library. https://housefoods-group.com/en/ir/ir_library/e_guide/pdf/integrated_report2025.pdf
- [9] Eden Foods, Inc. (2024, September 18). Eden Foods Introduces One-Year and Two-Year Cypress-Barrel Aged Organic Shoyu Soy Sauces. Eden Foods News Articles. https://www.edenfoods.com/articles/view.php?articles_id=524&rtn=1
- [10] Frontiers in Nutrition. (2026, March 12). Umbrella Review of Soy Isoflavones and Soy Protein Intake on Lipid Profiles and Cardiometabolic Biomarkers. Frontiers in Nutrition, 13, 1949200. https://www.frontiersin.org/journals/nutrition/articles/10.3389/fnut.2026.1949200/full
- [11] MDPI Foods. (2026, October 8). Traceability of Genetically Modified Soybean DNA and Thermal Stability of Gly m 5 and Gly m 6 Soy Allergens in Processed Foods. Foods, 15(20), 3718. https://www.mdpi.com/2304-8158/15/20/3718
- [12] PLOS One. (2026, February 23). Nitrogen-Protected Thermal Induction and Transglutaminase Cross-Linking of Soy Protein Isolate for Clean-Label Gel Matrices. PLOS One, 21(2), e0343526. https://journals.plos.org/plosone/article?id=10.1371/journal.pone.0343526
- [13] USDA Foreign Agricultural Service. (2026, April 6). Mexico: Food Processing Ingredients Annual. U.S. Department of Agriculture GAIN Report MX2026-0018. https://www.fas.usda.gov/data/gain/2026/04/mexico-food-processing-ingredients-annual
- [14] USDA Foreign Agricultural Service. (2026, March 18). Brazil: Oilseeds and Products Annual. U.S. Department of Agriculture GAIN Report BR2026-0008. https://www.fas.usda.gov/data/gain/2026/03/brazil-oilseeds-and-products-annual
- [15] USDA Economic Research Service (ERS). (2026, February 12). Oil Crops Outlook February 2026: Global Soybean Production Reaching 428.2 Million Metric Tons and Domestic Crush Trends. USDA ERS Report OCS-26b. https://www.ers.usda.gov/media/20853/ocs-26b.pdf?v=29588
- [16] Statistics Canada. (2026, September 16). Principal Field Crop Areas and Production September 2026: Canadian Soybean Output Rising 7.8% to 7.5 Million Tonnes in Ontario and Quebec. The Daily, Statistics Canada. https://www150.statcan.gc.ca/n1/daily-quotidien/260916/dq260916b-eng.htm
- [17] USDA Foreign Agricultural Service. (2026, March 19). People's Republic of China: Oilseeds and Products Annual. U.S. Department of Agriculture GAIN Report CH2026-0032. https://apps.fas.usda.gov/newgainapi/api/Report/DownloadReportByFileName?fileName=Oilseeds%20and%20Products%20Annual_Beijing_China%20-%20People%27s%20Republic%20of_CH2026-0032.pdf
- [18] Morinaga Milk Industry Co., Ltd. (2026, May 13). Corporate Overview 2026: International Tofu and Nutritional Beverage Investment Program. Morinaga Milk Investor Relations. https://www.morinagamilk.co.jp/english/ir/pdf/company_overview2026_9.pdf
- [19] GOV.UK Department for Environment, Food & Rural Affairs. (2025, December 11). United Kingdom Food Security Digest 2025: Global Soybean Supply and Plant Protein Import Dynamics. DEFRA Official Statistics. https://www.gov.uk/government/statistics/united-kingdom-food-security-digest-2025/united-kingdom-food-security-digest-2025
- [20] USDA Foreign Agricultural Service. (2025, November 19). Spain: Retail Foods Annual. U.S. Department of Agriculture GAIN Report SP2025-0022. https://www.fas.usda.gov/data/gain/2025/11/spain-retail-foods-annual
- [21] Pulmuone Co., Ltd. (2026, September 2). Pulmuone Sustainable Foods Division Posts 25.5% H1 2026 Growth Led by Soy Milk, Tofu Chips, and Natto. Pulmuone Newsroom. https://www.pulmuone.co.kr/en/newsroom/viewPulmuoneNews.do?id=1107
- [22] Danone SA. (2026, July 28). First-Half 2026 Financial Results: EUR 13,936 Million Revenue and Sustained Volume-Mix Growth Across Plant-Based Alpro and Silk Portfolios. Danone Press Releases. https://www.danone.com/newsroom/press-releases/h1-results-2026.html
- [23] Archer Daniels Midland Company (ADM). (2025, May 19). ADM Launches New Arcon SFP Specialty Soy Protein Line That Replaces Eggs and Reduces Costs by up to 45% in the Food Industry. ADM News Stories. https://www.adm.com/en-us/news/adm-stories/adm-launches-new-arcon-sfp-line-that-replaces-eggs-and-reduces-costs-in-the-food-industry/
- [24] The Hain Celestial Group, Inc. (2026, September 14). Hain Celestial Reports Fiscal Fourth Quarter and Fiscal Year 2026 Financial Results. Hain Celestial Investor Relations. https://ir.hain.com/news-releases/news-release-details/hain-celestial-reports-fiscal-fourth-quarter-and-fiscal-year-0
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete list of sources and detailed citations.
This Report Answers
- How large is the soy food products market in 2026 and what is forecast for 2036?
- Which complete plant-protein nutrition and egg-replacement trends support demand for soy foods?
- Why do Soy Milk and Ready Drinks lead the product category?
- Why do Fermented Soy Foods lead the processing type category globally?
- How do national growth rates differ across Mexico, Brazil, and the United States?
- Which leading companies supply brewed soy condiments and tofu versus functional soy proteins?
- What soy allergen labeling rules and non-GMO price premiums restrain the soy food products market?
- What should food processors evaluate when sourcing identity-preserved non-GMO organic soybeans?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Category, 2026 to 2036
- Soy Milk and Ready Drinks
- Tofu Silken Firm and Extra Firm
- Soy Sauce and Fermented Pastes Miso
- Textured Soy Protein TSP and Chunks
- Y-o-Y Growth Trend Analysis By Product Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Category, 2026 to 2036
- Global Market Analysis and Forecast, By Processing Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing Type, 2026 to 2036
- Fermented Soy Foods
- Non-Fermented Soy Foods
- Sprouted and Germinated Soy Products
- Enzyme-Modified Soy Preparations
- Y-o-Y Growth Trend Analysis By Processing Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing Type, 2026 to 2036
- Global Market Analysis and Forecast, By Source Certification, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source Certification, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source Certification, 2026 to 2036
- Non-GMO Certified Organic Soybeans
- Conventional Commercial Soybeans
- Identity-Preserved Non-GMO Soybeans
- Regenerative Certified Soybeans
- Edamame and Roasted Soybeans
- Y-o-Y Growth Trend Analysis By Source Certification, 2021 to 2025
- Absolute $ Opportunity Analysis By Source Certification, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail Supermarkets and Asian Specialty Grocers
- Foodservice Institutional and Commercial Kitchens
- Online Grocery and Direct-to-Consumer Channels
- Industrial Food Processing B2B Supply
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Aseptic Cartons and Vacuum Pouches
- Chilled Water-Pack Plastic Tubs
- Glass Bottles and Brewing Jars
- Bulk Multi-Wall Industrial Sacks
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Category
- By Processing Type
- By Source Certification
- By Distribution Channel
- By Packaging Format
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kikkoman Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone SA
- The Hain Celestial Group Inc.
- House Foods Group Inc.
- Vitasoy International Holdings Ltd
- The Nisshin OilliO Group Ltd
- Eden Foods Inc.
- Pulmuone Co., Ltd.
- Archer Daniels Midland Company
- Morinaga Milk Industry Co., Ltd.
- Kikkoman Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Category, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Processing Type, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Source Certification, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Category
- Figure 6: Global Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing Type
- Figure 9: Global Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Source Certification
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Packaging Format
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Category
- Figure 32: North America Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Processing Type
- Figure 35: North America Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Source Certification
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Packaging Format
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Category
- Figure 48: Latin America Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Processing Type
- Figure 51: Latin America Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Source Certification
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Category
- Figure 64: Western Europe Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Processing Type
- Figure 67: Western Europe Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Source Certification
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Category
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Processing Type
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Source Certification
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Category
- Figure 96: East Asia Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Processing Type
- Figure 99: East Asia Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Source Certification
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Category
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Processing Type
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Source Certification
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Category, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Category, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Category
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Processing Type, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Processing Type, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Processing Type
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Source Certification, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Source Certification, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Source Certification
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the soy food products market in 2026, and what is forecast for 2036?
FMI estimates that the global soy food products market size stood at USD 44.0 billion in 2025 and reaches USD 46.8 billion in 2026, with projections reaching USD 85.4 billion by 2036.
What is the CAGR for the soy food products market from 2026 to 2036?
The soy food products sector is projected to expand at a 6.2% CAGR over the 2026 to 2036 window, adding USD 38.6 billion in incremental revenue.
Which product category segment leads the soy food products market?
Soy Milk and Ready Drinks hold 39.0% of product category demand in 2026 under conditions where whole-bean extraction provides 7 to 9 grams of complete protein per serving.
Which processing type segment leads the soy food products market?
Fermented Soy Foods represent 64.0% of the processing type category in 2026 as global consumers purchase naturally brewed soy sauce, aged miso, and natto.
Which country has a notable growth outlook during the assessment period?
Mexico leads national expansion projections at a 7.4% CAGR through 2036, driven by textured soy protein adoption in retail meat extensions and lactose-free soy drinks.
Who are the key players in the market?
Kikkoman Corporation, Danone SA, The Hain Celestial Group Inc., House Foods Group Inc., Vitasoy International Holdings Ltd, The Nisshin OilliO Group Ltd, Eden Foods Inc., Pulmuone Co., Ltd., Archer Daniels Midland Company, and Morinaga Milk Industry Co., Ltd. lead the global market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
