

- Market Size (2026)
- USD 14.4 Bn
- Forecast (2036)
- USD 19.5 Bn
- CAGR (2026 to 2036)
- 3.1%
How big is Potassium Chloride Market in 2026?
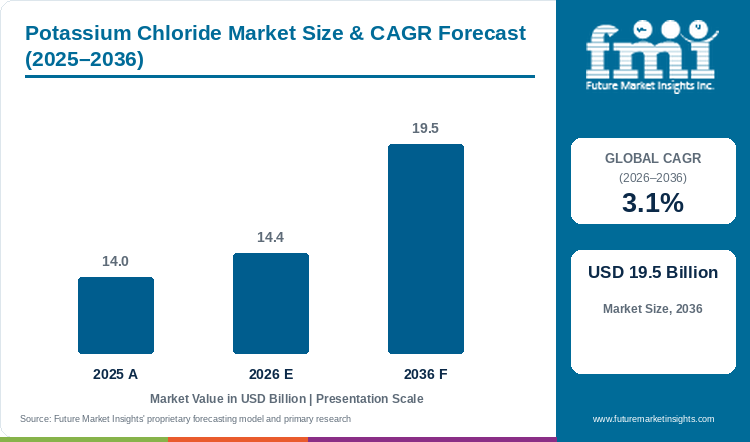
The potassium chloride market is estimated at USD 14.0 billion in 2025 and is expected to reach USD 14.4 billion in 2026. A 3.1% CAGR is projected to carry the market to USD 19.5 billion by 2036.
Growth of the potassium chloride market is tied to farm affordability, with an estimated USD 14.0 billion of sales for 2025 and USD 14.4 billion expected for 2026. On a 3.1% CAGR, FMI's model shows sales of USD 19.5 billion by 2036. Growers are holding potash application rates because muriate of potash still prices well against nitrogen and phosphate. Nutrien sold 3,943 thousand tonnes of potash in April to June 2026 and raised the low end of full-year volume guidance to 14.2 million tonnes, citing strong demand in key offshore markets.[1] Large exporters with spare mine capacity are serving offshore buyers first, so tonnage growth will come mainly from import markets.
Buyers are paying firmer prices after the second-quarter results. The mine-gate MOP price at Mosaic rose to US$275 per tonne in Q2 2026 from US$261, and the company guided to US$270 to US$290 for the third quarter.[2] Nutrien reported a net selling price of US$295 per tonne in North America against US$259 offshore in the same quarter.[1] Farm dealers in the United States are paying more per tonne than overseas importers, so dealers will commit to summer fill programmes earlier to lock in price. Importers on annual contracts keep the strongest bargaining position, and small distributors buying spot cargoes absorb the full increase.
Key Market Trends & Insights
- Agricultural grade, sold as standard and high-purity granules, is expected to hold 61% of product sales in 2026, and chemical and industrial grade is estimated at 39%.
- Cereals are projected to account for the largest crop share in 2026, about 36%, with oilseeds close behind near 27.5%. Nutrien expects Brazilian soybean acreage to rise moderately, with purchases shaped by credit and affordability.[1]
- Agriculture is projected to absorb 52% of application sales in 2026, with industrial uses near 26.5% by estimate.
- Granules are likely to supply 48% of form sales in 2026, as blenders and spreaders need a sized, dust-free product. Powder is estimated at 37.5%.
- Direct sales from producers to importers and large dealers form an estimated 58.3% of channel sales in 2026, and distributors at about 36.9%. Canpotex was fully committed on potash sales through 30 June 2026.[3]
Regional Highlights
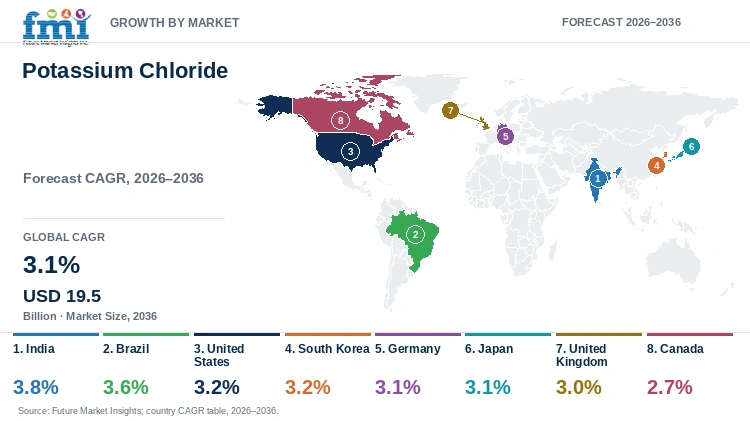
- Potash imports put India at the top of the table, and FMI's forecast puts the country at a 3.8% CAGR from 2026 to 2036, ahead of the 3.1% global CAGR.
- Brazil ranks second with 3.6%. The United States and South Korea are level at 3.2%. Germany and Japan grow in line with the market, the United Kingdom grows at 3%, and Canada has the slowest pace in the table at 2.7%.
- Potash was added to the U.S. Critical Minerals List on 7 November 2025, and the United States imported 92% of apparent potash consumption in 2025, the U.S. Geological Survey reported.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Potassium Chloride Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 14.0 billion |
| Estimated Market Size in 2026 | USD 14.4 billion |
| Projected Market Size by 2036 | USD 19.5 billion |
| CAGR, 2026 to 2036 | 3.1% |
| Added Revenue, 2026 to 2036 | USD 5.1 billion |
| Market Expansion Multiple | 1.4x |
Potash moves on quarterly export programmes and on the two main application windows of the farm year. Canpotex said in April 2026 that the company was fully committed on potash sales through 30 June 2026, on strong buyer participation and healthy farm conditions.[3] Nutrien expects global potash shipments of 74 to 77 million tonnes in 2026, consistent with expected consumption.[1] Growers adding microbial products keep mineral potash in the crop plan, so dealers will stock biological products next to potash blends as the biofertilizers market grows at an 8.5% CAGR over 2026 to 2036. Potash sales in 2036 are expected to be about 1.4 times the 2026 figure, with roughly USD 5.1 billion added over ten years, FMI data indicate. A fall in crop prices is the main risk, since lower farm income pushes growers to skip a season of potash.
New Mine Capacity, Export Logistics and Price Discipline
Canada is building the next large block of potash supply. BHP said in June 2026 that Jansen Stage 1 was about 80% complete and due for first production in mid-calendar 2027, and that the Stage 2 investment estimate rose from US$4.9 billion to US$6.9 billion.[5] Creamer Media reported in January 2026 that the Stage 1 estimate had risen to US$8.4 billion, from US$5.7 billion approved in August 2021.[6] Canpotex will invest CA$500 million at Neptune Bulk Terminals in Vancouver, with construction expected to finish in 2028.[7] New tonnes from Jansen and a larger Vancouver export capacity will add Canadian supply to Asian and Latin American buyers from 2027.
Mine sales and closures are tightening supply discipline at the same time. Indian Chemical News reported that Mosaic closed the sale of the Carlsbad potash mine in New Mexico in the June quarter of 2026.[8] The USGS expects world potash capacity to rise from 66.1 million tons of K2O in 2025 to 77.4 million tons by 2029, mostly from Laos and Russia.[4] K+S expects high capacity utilization in the global potash market for the remainder of 2026.[9] Higher-cost mines will keep price support near current levels until Jansen ramps up.
Table 2: Supply, Price and Logistics Indicators for the Potassium Chloride Market (tonnes, prices and dates), 2025 to 2029
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Mosaic MOP mine-gate price, Q2 2026 | US$275 per tonne; from US$261 | Prices firmed for buyers. | [2] |
| Nutrien potash volume guidance, 2026 | 14.2 to 14.8 million tonnes | Offshore buyers keep ordering. | [1] |
| Jansen Stage 2 investment estimate | US$6.9 billion; from US$4.9 billion | New supply costs more to build. | [5] |
| Canpotex Neptune terminal upgrade | CA$500 million; finish in 2028 | More export capacity from Vancouver. | [7] |
| World potash capacity, 2025 to 2029 | 66.1 to 77.4 million tons K2O | Supply growth from Laos and Russia. | [4] |
| U.S. net import reliance, 2025 | 92% of apparent consumption | American buyers rely on Canadian mines. | [4] |
Analyst Perspective
“My money is on Brazil and the 3.6% CAGR we see there for the decade to 2036, because Canpotex already sends nearly half of offshore volume to Latin America and soybean acreage keeps rising. Suppliers who secure Brazilian port storage before Jansen tonnes arrive in 2027 will set the terms for the next decade of contracts.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the potassium chloride market segmented?
The market is segmented into product, crop, application, form, sales channel, and region. Agricultural grade is expected to lead product sales with 61% share in 2026, and granules are projected to hold 48% of form sales.
By product: agricultural grade and chemical and industrial grade.
By crop: cereals, fruits and vegetables, oilseeds, and fiber and sugar.
By application: agriculture, industrial, water softeners, and de-icer.
By form: granules, powder, and liquid.
By sales channel: direct sales, distributors, and online sales.
By region: Latin America with Brazil, North America, Western Europe, East Asia, South Asia and Pacific, Eastern Europe, and Middle East and Africa.
Why does agricultural grade lead potassium chloride sales by product?
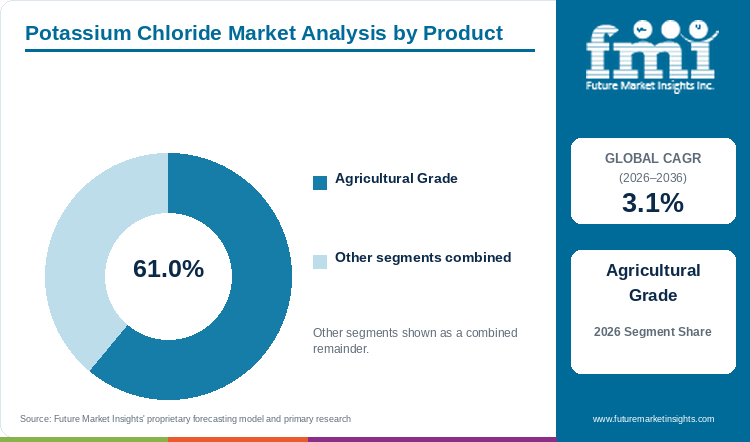
Agricultural grade is expected to lead product sales with 61% share in 2026, and chemical and industrial grade is estimated at 39%.
Table 3: Product Share for the Potassium Chloride Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Agricultural Grade | 61% |
| Chemical and Industrial Grade | 39% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Potassium Chloride Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.1% |
| Leading Segment | Agricultural Grade |
Agricultural grade is expected to lead with 61% share in 2026, because most mined potash leaves the plant as a 60% K2O fertilizer that needs little more than sizing. Chemical and industrial grade, an estimated 39%, needs extra purification for caustic potash, food salt blends and drug production, and those buyers order smaller lots. Infusion makers buy both pharmaceutical potassium chloride and saline, and with a 5.7% CAGR expected for the pharmaceutical grade sodium chloride market, hospital electrolyte lines will keep a premium outlet for purified grades. Some standard agricultural granules also go into de-icing and softener blends, so the 61% product share runs above the 52% agriculture application share. A fertilizer importer buys standard granules by the shipload, and that volume keeps agricultural grade ahead.
- Standard and high-purity agricultural grades are both sold mainly as granules.
- Fertilizer accounted for about 85% of U.S. potash sales in 2025, with chemical and industrial uses making the remainder, the U.S. Geological Survey reported in February 2026.[4]
Why do cereals lead potassium chloride use by crop?
Cereals are projected to lead crop sales with 36% share in 2026, with oilseeds at about 27.5%.
Table 5: Crop Share for the Potassium Chloride Market (percentage share), 2026
| Crop | Estimated Share (2026) |
|---|---|
| Cereals | 36% |
| Oilseeds | 27.5% |
| Fruits and Vegetables | 21.8% |
| Fiber and Sugar | 14.7% |
| Total | 100.0% |
Cereals are projected to lead with 36% share in 2026, as wheat and rice cover the largest planted area and growers apply potash every season. Oilseeds, an estimated 27.5%, are close behind on soybean area in Brazil and the United States. Fruits and vegetables, about 21.8%, use less chloride because many fruit crops are chloride sensitive. Growers of grapes, citrus and tobacco will keep switching to sulfate, and the potassium sulfate market has a forecast CAGR of 4.9%. Fiber and sugar crops are estimated near 14.7%, with cotton and sugarcane buying potash in large volumes but on fewer hectares. A wheat or rice grower uses the cheapest potassium source, and that habit keeps cereals in front.
- Wheat and rice account for nearly all cereal tonnage.
- Nutrien said in August 2026 that Brazilian soybean acreage is expected to rise moderately and that credit and affordability shape purchases.[1]
What keeps agriculture ahead in potassium chloride applications?
Agriculture is expected to lead application sales with 52% share in 2026, ahead of industrial uses at an estimated 26.5%.
Table 6: Application Share for the Potassium Chloride Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Agriculture | 52% |
| Industrial | 26.5% |
| Water Softeners | 12.4% |
| De-Icer | 9.1% |
| Total | 100.0% |
Agriculture is expected to lead with 52% share in 2026, since potash is one of the three main crop nutrients and has no synthetic replacement. Industrial uses, an estimated 26.5%, include caustic potash, drilling fluids and food processing, and each plant buys on a fixed schedule. Water softeners are estimated at 12.4%, as households on low-sodium diets refill softeners with potassium chloride pellets in place of salt. De-icers hold about 9.1%, and road agencies use potassium chloride mainly near trees and lawns, as the price per tonne runs well above rock salt. Calcium brines will keep the coldest de-icing jobs, backed by a calcium chloride market that is forecast to rise at 4.2% CAGR between 2026 and 2036. A farmer pays for yield, and that reason keeps agriculture ahead of every other use.
- Most farm potash is blended with nitrogen and phosphate before spreading, and some is applied straight or through drip lines.
- Mosaic said in August 2026 that growers see potash as good value against other nutrients, which supports application rates.[2]
Why do granules lead potassium chloride sales by form?
Granules are likely to lead form sales with 48% share in 2026, with powder at about 37.5%.
Table 7: Form Share for the Potassium Chloride Market (percentage share), 2026
| Form | Estimated Share (2026) |
|---|---|
| Granules | 48% |
| Powder | 37.5% |
| Liquid | 14.5% |
| Total | 100.0% |
Granules are likely to lead with 48% share in 2026, because bulk blenders mix potash with nitrogen and phosphate granules of the same size before spreading. Powder, an estimated 37.5%, is the standard grade for NPK fertilizer plants in Asia and for chemical buyers who dissolve the product. Liquid forms are estimated at 14.5% and serve fertigation and greenhouse growers who inject nutrients through drip lines. A dealer selling blended fertilizer to many farms stocks granules first.
- Compacted coarse granules suit bulk blending and broadcast spreaders.
- Canpotex announced on 25 September 2026 a CA$500 million upgrade of shiploaders, conveyors and the railcar dumper pit at Neptune Bulk Terminals in Vancouver.[7]
Why do direct sales lead potassium chloride sales by channel?
Direct sales are estimated to lead channel sales with 58.3% share in 2026, ahead of distributors at about 36.9%.
Table 8: Sales Channel Share for the Potassium Chloride Market (percentage share), 2026
| Sales Channel | Estimated Share (2026) |
|---|---|
| Direct Sales | 58.3% |
| Distributors | 36.9% |
| Online Sales | 4.8% |
| Total | 100.0% |
Producer-to-importer deals give direct sales the lead in 2026, at an estimated 58.3%, as producers and export agencies sell whole vessels to national importers and large blenders under annual or quarterly contracts. Distributors, an estimated 36.9%, serve smaller dealers and industrial users who buy truckloads. Online sales, about 4.8%, cover bagged potash and softener pellets sold to households and small farms. An importer buying 50,000 tonnes at a time negotiates with the producer directly, and that keeps direct sales on top.
- Export agencies sell to national importers and large blenders under contract.
- Canpotex announced on 14 April 2026 that the company was fully committed on potash sales volumes through 30 June 2026.[3]
What are the drivers, restraints, and opportunities in the potassium chloride market?
Crop nutrition needs and good affordability against other nutrients keep potash in every season of planting. Rising mine construction costs and substitute de-icers hold back supply and non-farm use, and new low-cost capacity opens room for importers to diversify suppliers.
- Driver: Growers treat potash as a cheap nutrient next to nitrogen and phosphate, so application rates hold even when crop prices soften.
- Restraint: New potash mines take many years and large capital to build, so supply cannot respond quickly, and other chloride de-icers compete for road budgets.
- Opportunity: Low-cost new mines in Canada give importers in Brazil and Asia a second supplier choice, which improves contract terms for buyers.
Affordability Keeps Potash in the Crop Plan
Fertilizer buyers judge potash on cost per unit of yield, and potash is passing that test in 2026. Mosaic described potash fundamentals as balanced with strong demand across major consuming regions.[2] Nutrien called global potash markets constructive due to favorable affordability and reported healthy demand in all major global markets.[1] Canpotex sends more than 15 million tonnes of potash to customers in more than 40 countries each year.[7] Steady application rates will keep potash volume close to crop area growth through 2036.
Mine Costs and Substitute De-Icers Limit Growth
Building a new potash mine has become more expensive and slower. BHP expects an impairment of about US$2.3 billion on the investment in Jansen to date after raising the Stage 2 estimate to US$6.9 billion.[5] Mine costs hold back new supply, and FMI estimates global growth at a 3.1% CAGR across the forecast period. Road agencies choose among several chloride de-icers, and with the magnesium chloride market growing faster, at 5.1% CAGR, potassium chloride will stay a small, specialist de-icer. Producers will delay further expansions until prices justify the capital.
New Low-Cost Supply Gives Importers More Choice
Importers in Brazil and Asia will gain a new supply option when Jansen starts. BHP expects combined Jansen output of about 8.5 million tonnes a year after Stage 2, about 10% of global potash production, at a unit cost of US$114 to 130 per tonne.[5] The USGS lists new MOP mines planned in Belarus, Brazil, Canada, Ethiopia, Morocco and Spain after 2029.[4] More suppliers will give national importers better bargaining power in annual contract talks.
Which country CAGRs are profiled in the potassium chloride market?
Table 9: Country CAGR Comparison for the Potassium Chloride Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 3.8% |
| Brazil | 3.6% |
| United States | 3.2% |
| South Korea | 3.2% |
| Germany | 3.1% |
| Japan | 3.1% |
| United Kingdom | 3% |
| Canada | 2.7% |
How do country-level CAGRs compare in the potassium chloride market?
Brazil and Latin America accounted for 47% of Canpotex sales in Q2 2026, five points more than in the same quarter of 2025, Nutrien reported.[1] In FMI's estimate, India and Brazil grow fastest, at 3.8% and 3.6%, as large importers with growing crop area. The United States and South Korea share a 3.2% CAGR, and Germany and Japan grow level with the 3.1% global rate. The United Kingdom, at 3%, sits just under the overall 3.1% CAGR, and Canada is last in the country ranking at 2.7%. Canada mines more potash than any other country and uses little at home, so domestic sales there grow slowest.
- Indian importers returned to Canadian potash in 2026.
- Brazilian soybean growers rebuild potash stocks before each planting.
- American dealers buy most potash from Canadian mines.
- Buyers in South Korea use potash for modern farming and pharmaceutical electrolytes.
- German farms buy from K+S mines close to home.
- Japan imports all potash and watches freight costs.
- British growers follow soil health goals in farm policy.
- Canada exports most of the potash mined in Saskatchewan.
Full report country CAGRs cover: eight national tables, for Brazil, Canada, Germany, India, Japan, South Korea, the United Kingdom and the United States, plus regional tables for Eastern Europe and Middle East and Africa.
Country-wise Analysis
India Potassium Chloride Market Outlook (2026 to 2036)
India received 4% of Canpotex volume in the June quarter of 2026, after no sales there in the same quarter of 2025, Nutrien reported.[1] BHP lists India among the five importing regions that take roughly three-quarters of global potash imports.[5] Demand for potassium chloride in India is projected to rise at a 3.8% CAGR, 0.7 points over the market rate of 3.1%. Rice and wheat farms with low soil potassium will drive the extra imports.
Key takeaway: Restarted import contracts and potassium-poor soils put India first.
Brazil Potassium Chloride Market Outlook (2026 to 2036)
Brazil is replenishing potash inventories, Mosaic said in August 2026.[2] Fertilizer sales at Mosaic Fertilizantes were 1.5 million tonnes for the three months to June 2026.[8] Brazil mined only about 300 thousand tons of K2O in 2025, and a new MOP mine is planned after 2029.[4] For Brazil, a 3.6% CAGR through 2036 is likely. Soybean and sugarcane growers will keep Brazil the largest destination for Canadian potash.
Key takeaway: Imports carry almost all growth in Brazil until a domestic mine opens.
United States Potassium Chloride Market Outlook (2026 to 2036)
American buyers imported 5.6 million tons of potash in 2025, with Canada supplying 79% of imports between 2021 and 2024.[4] The Carlsbad mine in New Mexico changed hands when Mosaic sold the site in mid-2026.[8] Nutrien reported a North American net selling price of US$295 per tonne in that quarter.[1] Growth in the United States is expected at 3.2% CAGR over 2026 to 2036, a little faster than the market average of 3.1%. Corn belt dealers will lean even more on Canadian rail supply.
Key takeaway: Canadian supply and corn belt planting set the U.S. outlook.
South Korea Potassium Chloride Market Outlook (2026 to 2036)
Asian markets outside China and India, the group that covers South Korea, received 23% of Canpotex volume in the second quarter of 2026, Nutrien reported.[1] Korean growers and drug makers give the country a 3.2% CAGR for the decade to 2036, and FMI analysts expect government farm modernization, hydroponic and vertical farming and pharmaceutical electrolyte use to support that rate. Korean buyers import all potash and will pay for higher-purity grades used in hydroponic nutrient solutions and drug production.
Key takeaway: Purified grades for hydroponics and medicine raise the value of each tonne sold in South Korea.
Germany Potassium Chloride Market Outlook (2026 to 2036)
Germany mined about 3 million tons of K2O in 2025, the fifth-largest output, according to the USGS.[4] K+S raised 2026 operating EBITDA guidance to €680 to 760 million and expects high capacity utilization in the global potash market for the remainder of the year.[9] German growth is projected to match the 3.1% CAGR of the market as a whole. Fertilizer runoff rules will push German farms toward precise doses of potash.
Key takeaway: Domestic mines and runoff rules keep German growth at the global rate.
Japan Potassium Chloride Market Outlook (2026 to 2036)
Japanese importers buy from the same Canpotex pool, which shipped 23% of volume to Asian markets other than China and India during the June quarter.[1] Japan imports all of the potash used in the country, and FMI flags that import dependence as a source of exposure to supply disruptions and freight costs. Precision farming and pharmaceutical manufacturing support a CAGR of 3.1% for Japan. Japanese buyers will spread contracts across Canadian, Israeli and Jordanian suppliers to limit freight risk.
Key takeaway: Freight risk shapes potash buying in Japan.
United Kingdom Potassium Chloride Market Outlook (2026 to 2036)
FMI links potash use in the United Kingdom to farm policy after Brexit and soil health goals, with water treatment as a stable industrial outlet. Defra set the first application window for SFI26, the 2026 Sustainable Farming Incentive, to open on 30 June 2026, with an action paying for precision equipment that applies all major nutrients.[10] British growers are expected to raise potash use at a 3% CAGR across the forecast period, short of the 3.1% rate for the market as a whole. Arable farms joining the scheme will apply potash by variable rate, field by field.
Key takeaway: Precision application under SFI26 sets British potash rates field by field.
Canada Potassium Chloride Market Outlook (2026 to 2036)
Canada mined about 15 million tons of K2O in 2025, the largest national output.[4] Canpotex moves more than 15 million tonnes of potash each year to customers in more than 40 countries and will upgrade Neptune Bulk Terminals by 2028.[7] BHP expects first Jansen Stage 1 output in mid-calendar 2027.[5] Prairie farms already apply potash at mature rates, so domestic sales in Canada are likely to grow at a 2.7% CAGR, the slowest pace in the table.
Key takeaway: Canada supplies the world, and home use grows slowest of the profiled countries.
Who are the notable companies in the potassium chloride market?
Nutrien, Mosaic, K+S, Uralkali, ICL, BHP and Canpotex are the profiled companies.
Importers buy traded potash from a handful of miners and judge each one on price, reliability and freight. Nutrien guides to 14.2 to 14.8 million tonnes of potash sales in 2026.[1] Mosaic expects about 9 million tonnes of potash production in 2026, weighted to the second half.[2] Industry+ at K+S brought in €278 million during the June quarter of 2026.[9] BHP's revised Jansen numbers set out the business case for market expansion in Canada, with an 11% after-tax IRR for Stage 2 at consensus prices.[5] Uralkali and ICL complete the profiled producers, and Canpotex markets potash overseas.
- North American miners: Nutrien, Mosaic and BHP.
- Export marketer: Canpotex.
- European and Middle East producers: K+S and ICL.
- Russian producer: Uralkali.
Competitive Benchmarking: Potassium Chloride Market
Table 10: Competitive Benchmarking for the Potassium Chloride Market (qualitative documentation ratings), 2026
| Company | Mine Capacity | Export Reach | New Supply Projects | Recency |
|---|---|---|---|---|
| Nutrien | High | High | Medium | High |
| Mosaic | High | Medium | Medium | High |
| K+S | Medium | Medium | Low | High |
| BHP | Medium | Low | High | High |
| Canpotex | Low | High | Medium | High |
Each producer rating shows how fully dated filings and company announcements document that miner, and no rating measures market share.
Key Developments in the Potassium Chloride Market
- On 25 September 2026, Canpotex announced a CA$500 million investment in Neptune Bulk Terminals in Vancouver.[7]
- On 12 August 2026, K+S raised 2026 operating EBITDA guidance to €680 to 760 million.[9]
- On 7 August 2026, Indian Chemical News reported that Mosaic completed the sale of the Carlsbad potash mine.[8]
- On 5 August 2026, Nutrien raised the low end of 2026 potash sales guidance to 14.2 million tonnes.[1]
- On 4 August 2026, Mosaic reported a second-quarter MOP price of US$275 per tonne.[2]
- On 18 June 2026, BHP raised the Jansen Stage 2 investment estimate to US$6.9 billion.[5]
- On 14 April 2026, Canpotex reported full commitment on potash sales through 30 June 2026.[3]
- On 20 January 2026, Creamer Media reported the Jansen Stage 1 estimate at US$8.4 billion.[6]
Key Players in the Potassium Chloride Market
North American Miners
- Nutrien
- Mosaic
- BHP
Export Marketer
- Canpotex
European and Middle East Producers
- K+S
- ICL
Russian Producer
- Uralkali
Potassium Chloride Market - Report Scope
Table 11: Report Scope for the Potassium Chloride Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; crop; application; form; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Potassium chloride (muriate of potash) sold as agricultural, chemical and industrial grades in granular, powder and liquid form for fertilizer, industrial, water softener and de-icing use. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Nutrien, Mosaic, K+S, Uralkali, ICL, BHP, Canpotex |
| Forecast period | 2026 to 2036 |
Potassium Chloride Market - Research Methodology
Table 12: Research Methodology for the Potassium Chloride Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Producer quarterly results, export agency notices, mine project updates, geological survey data and trade press from May 2025 onward. |
| Desk Research | Prices per tonne, volume guidance, mine costs, terminal investment and import reliance. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 14.0 billion and the 3.1% CAGR for 2026 to 2036. |
| Data Validation | Prices, volumes and project costs were matched to the producer or agency release that carried them. |
Potassium Chloride Market by Segments
Potassium Chloride Market segmented by Product:
- Agricultural Grade
- Chemical and Industrial Grade
Potassium Chloride Market segmented by Crop:
- Cereals
- Fruits and Vegetables
- Oilseeds
- Fiber and Sugar
Potassium Chloride Market segmented by Application:
- Agriculture
- Industrial
- Water Softeners
- De-Icer
Potassium Chloride Market segmented by Form:
- Granules
- Powder
- Liquid
Potassium Chloride Market segmented by Sales Channel:
- Direct Sales
- Distributors
- Online Sales
Potassium Chloride Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Nutrien Ltd. (2026, August 5). Nutrien Reports Second Quarter 2026 Results. https://www.sec.gov/Archives/edgar/data/0001725964/000119312526335517/d129364dex991.htm
- [2] The Mosaic Company. (2026, August 4). The Mosaic Company Reports Second Quarter 2026 Results. https://www.sec.gov/Archives/edgar/data/0001285785/000128578526000109/pressreleaseq22026-ex991.htm
- [3] Canpotex. (2026, April 14). Canpotex Fully Committed on Potash Sales Through June 30, 2026. https://www.canpotex.com/news/canpotex-fully-committed-on-potash-sales-through-june-30-2026/
- [4] U.S. Geological Survey. (2026, February). Mineral Commodity Summaries 2026: Potash. https://pubs.usgs.gov/periodicals/mcs2026/mcs2026-potash.pdf
- [5] BHP Group Limited. (2026, June 18). Update - Jansen Stage 2 Potash Project. https://www.sec.gov/Archives/edgar/data/0000811809/000119312526275167/d124011d6k.htm
- [6] Creamer Media. (2026, January 20). Jansen Stage 1 price tag swells as BHP completes cost reassessment. https://newsletter.en.creamermedia.com/article/jansen-stage-1-price-tag-swells-as-bhp-completes-cost-reassessment-2026-01-20
- [7] Canpotex. (2026, September 25). Canpotex announces $500 million investment in Neptune Bulk Terminals. https://www.canpotex.com/news/canpotex-announces-500-million-investment-in-neptune-bulk-terminals/
- [8] Indian Chemical News. (2026, August 7). Mosaic posts $273 million second-quarter loss as market pressures weigh on fertilizer giant. https://www.indianchemicalnews.com/fertilizer/mosaic-posts-273-million-second-quarter-loss-as-market-pressures-weigh-on-fertilizer-giant-31424
- [9] K+S Aktiengesellschaft. (2026, August 12). K+S raises 2026 guidance and is in line with the full-year market expectation. https://www.kpluss.com/.downloads/pr/2026/kpluss-20260812-press-q2-figures-en.pdf
- [10] Department for Environment, Food and Rural Affairs, Defra Farming blog. (2026, June 2). SFI26: scheme information now available. https://defrafarming.blog.gov.uk/2026/06/02/sfi26-scheme-information-now-available/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the potassium chloride market during 2026?
- What market size is projected by 2036?
- Which product holds notable share?
- Which crop holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the potassium chloride market expected in 2026?
Potassium chloride is expected to reach USD 14.4 billion in 2026, from USD 14.0 billion in 2025. By 2036, FMI projects USD 19.5 billion.
What CAGR is projected for the potassium chloride market through 2036?
The outlook calls for a 3.1% CAGR between 2026 and 2036. Crop nutrition needs and good affordability against other nutrients support that rate.
Which product holds a notable market share in 2026?
Farm buyers give agricultural grade a projected 61% share in 2026. Chemical and industrial grade is estimated at 39%.
Which crop holds a notable market share in 2026?
Cereals are expected to lead crop use with 36% share in 2026. Oilseeds follow at an estimated 27.5%.
Which country has a notable expansion outlook through 2036?
India is the fastest profiled country on a 3.8% CAGR from 2026 to 2036, as per FMI. Canada is the slowest at 2.7%.
Who are the key companies in the potassium chloride market?
Nutrien, Mosaic, K+S, Uralkali and ICL are the main producers in the profiled group. BHP is building the Jansen mine, and Canpotex markets Canadian potash overseas.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Agricultural Grade
- Chemical and Industrial Grade
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Crop, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Crop, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Crop, 2026 to 2036
- Cereals
- Fruits and Vegetables
- Oilseeds
- Fiber and Sugar
- Y-o-Y Growth Trend Analysis By Crop, 2021 to 2025
- Absolute $ Opportunity Analysis By Crop, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Agriculture
- Industrial
- Water Softeners
- De-Icer
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Granules
- Powder
- Liquid
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct Sales
- Distributors
- Online Sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Crop
- By Application
- By Form
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nutrien
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mosaic
- K+S
- BHP
- Canpotex
- ICL
- Uralkali
- Nutrien
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


