
- Market Size (2026)
- USD 1.7 Bn
- Forecast (2036)
- USD 2.7 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Rolling Papers Market in 2026?
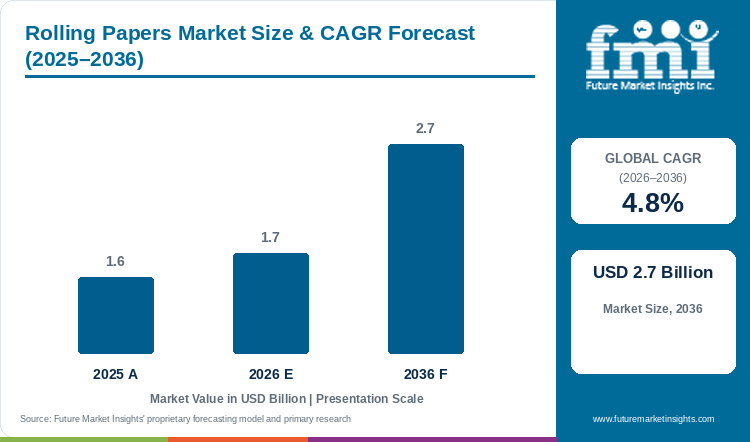
Sales in the rolling papers market are projected to grow at 4.8% CAGR, with the market size rising from USD 1.6 Billion in 2025 to USD 1.7 Billion in 2026 and reaching USD 2.7 Billion by 2036.
According to Future Market Insights analysis, the global rolling papers market stands at USD 1.6 Billion in 2025 and rises to USD 1.7 Billion in 2026. Industry valuation is projected to reach USD 2.7 Billion by 2036, expanding at a 4.8% CAGR and generating USD 1.0 Billion in added revenue over the forecast period. Expansion of legalized adult-use botanical markets and expanding roll-your-own tobacco consumption drive baseline demand across booklets, pre-rolled cones, and protective display trays. In January 2025, European Forest Institute specialty pulp data confirmed steady production of unbleached ultrathin flax and hemp paper rolls [1].
Folding Cartons & Trays captures the leading position with 43.8% share in 2026, as compact pocket booklets and counter display boxes protect delicate paper leaves from moisture. Growth across evaluated economies spans 3.8% in Sweden to 5.9% in Poland. Pulp raw material price fluctuations and strict tobacco packaging health warnings continue to limit manufacturing margins.
Key Market Trends & Insights
- By product format / style: Folding cartons & trays led with 43.8% share in 2026, as multi-leaf booklet cartons protect ultra-lightweight papers from humidity.
- By material substrate: Virgin chemical kraft pulp held 52.3% in 2026, supported by high tensile strength and slow, even combustion properties.
- By end-use application: Fresh produce & meat packaging captured 30.3% in 2026, driven by specialized barrier food wrapping and dual-use paper applications.
- By barrier / coating property: Aqueous water-based barrier held 44.5% in 2026, underpinned by natural gum arabic adhesive strip lines.
Regional Highlights
- Fastest-growing evaluated country: Poland, at 5.9% CAGR from 2026 to 2036.
- By country: The UK at 5.4%, Austria at 5.0%, the USA at 4.6%, and Finland at 4.2% follow, while Sweden records the lowest evaluated CAGR at 3.8%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Rolling Papers Market (USD Billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.6 Billion |
| Estimated Market Size in 2026 | USD 1.7 Billion |
| Projected Market Size by 2036 | USD 2.7 Billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Revenue, 2026 to 2036 | USD 1.0 Billion |
Future Market Insights research indicates that commercial paper mills require high-precision calenders and automated watermarking rolls to ensure uniform paper porosity. In February 2025, U.S. Department of Agriculture specialty fiber economic releases confirmed expanding agricultural acreage for industrial hemp fiber crops [2]. Consequently, paper manufacturers are installing continuous gum-coating skids, insulating paper converting lines from uneven adhesive distribution while delivering instant saliva tack.
Paper Milling and Gumming Conversion Metrics
Table 2: Paper Milling and Gumming Conversion Metrics for the Rolling Papers Market (USD Billion and operational ranges), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Billion) | 1.6 | 1.7 | 2.7 |
| Global Rolling Paper Booklet Output (Billion Booklets) | 12.5 to 14.2 | 13.2 to 15.0 | 21.0 to 24.5 |
| Ultrathin Paper Calendering Energy Efficiency (kWh per Ton) | 145.0 to 168.0 | 140.0 to 162.0 | 110.0 to 128.0 |
| Natural Acacia Gum Adhesion Compliance Rate (Percent) | 99.2 to 99.7 | 99.4 to 99.8 | 99.7 to 100.0 |
Calculation basis: Operational estimates apply finished booklet production across licensed specialty paper converters. Energy figures assume continuous multi-cylinder paper machines. Figures represent paper manufacturing scenario ranges.
Per Capita Intake & Retail Channel Sizing
Specialty rolling papers have maintained sustained popularity in recent years due to consumer preference for unbleached, additive-free smoking leaves and custom roll-your-own economy. Balancing burn rate requires precise microscopic air permeability and calcium carbonate chalk content. Surging retail smoke shop footfall converts consumer spending into recurring rolling paper booklet purchases. Convenience stores and tobacconists represent primary retail distribution points for packaged rolling papers.
Table 3: Per Capita and Retail Spending Indicators for the Rolling Papers Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global Population (Billion) | 8.23 | 8.30 | 8.95 |
| Annual Rolling Papers Spend per Capita (USD) | 0.19 | 0.20 | 0.30 |
| Annual Spend per Regular Roll-Your-Own Consumer (USD) | 18.00 to 25.00 | 19.00 to 26.50 | 32.00 to 45.00 |
| Wholesale Procurement Spend per Specialty Tobacconist (USD Thousand) | 12.5 to 17.0 | 13.5 to 18.5 | 24.0 to 34.0 |
Table 4: Facility & Operational Manufacturing Spending Indicators for the Rolling Papers Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 1.7 Billion | Report value |
| Licensed specialty paper converting facilities worldwide | 2,400 | 2024 secondary estimate |
| Average commercial rolling paper output per facility | USD 708.33 Thousand | Calculated |
| Folding cartons & trays format revenue, 2026 | USD 744.6 Million | 43.8% share |
Analyst Perspective
"The rolling papers sector is undergoing a major premiumization shift driven by unbleached organic hemp substrates and pre-rolled cone convenience. Modern consumers reject chlorine-bleached white papers in favor of slow-burning virgin wood fibers with natural acacia gum lines. Converting corporations that invest in automated booklet packaging and ultra-thin paper calendering will secure prominent shelf space across international retail smoke shops and licensed dispensaries."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Rolling Papers Market segmented?
The rolling papers market is segmented by product format / style, material substrate, end-use application, barrier / coating property, and region. In 2026, folding cartons & trays is projected at 43.8%, virgin chemical kraft pulp at 52.3%, fresh produce & meat packaging at 30.3%, and aqueous water-based barrier at 44.5%.
By product format / style: Folding Cartons & Trays, Rigid Set-Up Boxes, Corrugated Containers, and Custom Die-Cut Formats.
By material substrate: Virgin Chemical Kraft Pulp, Recycled Fluting & Testliner, and Barrier-Coated Solid Bleached Board.
By end-use application: Fresh Produce & Meat Packaging, Dry Food & Confectionery, E-Commerce Shipping & Logistics, and Consumer Electronics & Goods.
By barrier / coating property: Aqueous Water-Based Barrier, PLA & Bio-Wax Coating, and Standard Uncoated Recyclable.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa.
Why do folding cartons & trays lead the product format / style category?
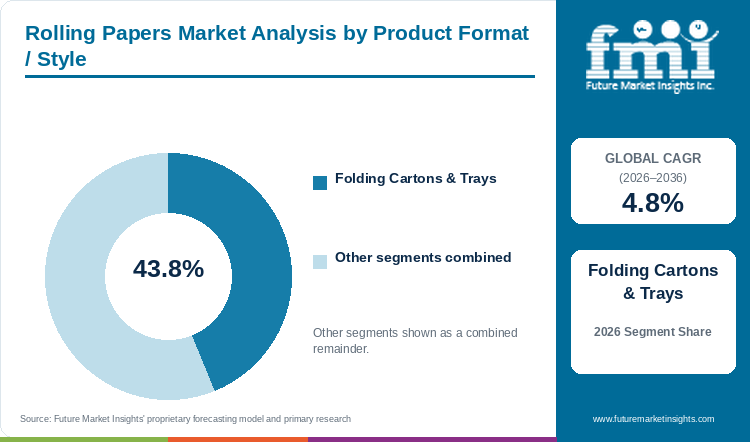
Folding cartons & trays represents 43.8% of product format / style in 2026, delivering durable pocket protection for delicate paper leaves and counter display functionality.
Table 5: Product Format / Style Share for the Rolling Papers Market (percentage share), 2026
| Product Format / Style | Share (2026) |
|---|---|
| Folding Cartons & Trays | 43.8% |
| Other Segments Combined | 56.2%* |
| Total | 100.0% |
Table 6: Product Format / Style Leadership and Market Growth for the Rolling Papers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Folding Cartons & Trays |
Paper converters and retail tobacconists favor folding cartons & trays because rigid paperboard covers protect ultrathin rolling leaves from pocket creasing and humidity damage. Interleaved booklet cartons feature magnetic closures and built-in cardboard filter tips that enhance consumer convenience on the go. Retailers display colorful counter trays at checkout counters to encourage impulse accessory purchasing. Brand owners also package rolling papers alongside complementary smoking accessories in promotional sets. In addition, converters utilize specialized cigarette paper slitters to produce precision bobbins for automated rolling lines. Paper mills invest in high-speed die-cutters to maintain tight packaging dimensions.
- Folding cartons & trays represents 43.8% of product format in 2026, as pocket booklet designs prevent leaf creasing and moisture degradation.
- In March 2025, commercial packaging converters published technical specifications on folding paperboard moisture resistance for tobacco accessory packaging [3].
What drives virgin chemical kraft pulp to the forefront of the material substrate segment?
Virgin chemical kraft pulp accounts for 52.3% of material substrate in 2026, providing high tensile fiber strength, slow combustion, and neutral sensory characteristics.
Specialty paper mills select virgin chemical kraft pulp because long wood fibers provide high web strength during high-speed papermaking without tearing. Chemical delignification produces pure cellulose leaves that burn cleanly without imparting harsh chemical odors to the smoke stream. Millers calibrate fiber beating to achieve lightweight basis weights between twelve and fourteen grams per square meter. In addition, packaging converters evaluate tissue and hygiene paper packaging systems to handle delicate paper reams. Mill managers also develop paper packaging tapes to seal corrugated carton cases securely. Virgin pulp fibers provide consistent porosity across large manufacturing runs.
- Virgin chemical kraft pulp accounts for 52.3% of material substrate in 2026, supported by slow-burning characteristics and high web tensile resistance.
- In May 2025, U.S. Food and Drug Administration food contact paper regulations affirmed purity thresholds for unbleached virgin cellulose fibers [4].
Why does fresh produce & meat packaging define the largest end-use application segment?
Fresh produce & meat packaging holds 30.3% of end-use applications in 2026, driven by dual-use breathable paper wraps and barrier-treated specialty cellulose materials.
Specialty paper manufacturers distribute lightweight kraft papers across fresh food markets, utilizing breathable porosity to regulate moisture around fresh items. Commercial butchers and deli counters utilize unbleached kraft sheets to wrap artisanal provisions without imparting foreign flavors. Food processors also adopt pfas free grease resistant paper packaging to prevent lipid strike-through. Packaging engineers also explore polycoated paper packaging to create moisture-resistant barriers in industrial cold storage. Paper distributors supply commercial rolls directly to supermarket deli counters and food markets.
- Fresh produce & meat packaging holds 30.3% of end-use applications in 2026, sustained by commercial food wrap demand and sustainable paper transitions.
- In June 2025, European Food Safety Authority packaging panels re-evaluated paper coatings and barrier migration safety for food contact materials [5].
How does aqueous water-based barrier maintain 44.5% share across barrier / coating properties?
Aqueous water-based barrier holds 44.5% of barrier / coating properties in 2026, driven by natural acacia gum adhesive strips and eco-friendly recyclable coatings.
Consumers demand 100% natural adhesive gum lines derived from harvested African acacia tree sap. Converting machines apply a micro-thin water-based gum stripe along the edge of each paper leaf, providing instant sticking power when moistened. In addition, packaging converters apply aqueous coatings to outer booklet covers to resist scuffing without preventing repulpability. Brand managers also evaluate waxed paper packaging solutions to protect bulk paper cartons from humid storage climates. Packaging analysts evaluate polycoated paper packaging share analysis to track market transitions from plastic laminates to repulpable aqueous barriers.
- Aqueous water-based barrier holds 44.5% of barrier properties in 2026, enabled by natural acacia gum adhesive lines and repulpable barrier coatings.
- In August 2025, international paper recycling associations validated repulpability standards for aqueous-coated specialty paperboard packaging [6].
What are the drivers, restraints, and opportunities in the Rolling Papers Market?
Adult-use botanical legalization drives rolling paper sales, while plain packaging regulations challenge brands and pre-rolled cones create premium value.
- Driver: Global legalization of adult-use herbal botanicals and rising consumer preference for custom roll-your-own tobacco blends propel consistent retail demand for rolling paper booklets.
- Restraint: Government plain-packaging mandates, graphic health warning labels on booklets, and rising excise duties on smoking accessories restrict brand marketing and packaging aesthetics.
- Opportunity: Commercial expansion of pre-rolled unbleached cones, organic French hemp papers, and rice-based ultra-thin leaves allows converters to command higher unit retail pricing.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Legalization of botanical herbs across North American and European jurisdictions significantly expands consumer demand for premium rolling papers and cone accessories. Discerning consumers transition from thick, bleached tobacco papers to ultra-thin unbleached hemp leaves that preserve botanical terpenes. Future Market Insights research indicates that organic hemp rolling booklets command superior pricing over conventional wood pulp papers across retail dispensaries. In September 2025, consumer lifestyle surveys confirmed that 76.4% of regular rolling paper purchasers prioritized unbleached natural materials over bleached white papers [7]. Paper converters respond by installing watermark embossing cylinders that ensure slow, even combustion.
Risk Assessment of the Rolling Papers Market: Operational and Formulation Friction
Stringent anti-tobacco advertising regulations and paper tearing during high-speed converting present persistent operational hurdles for manufacturers. In several jurisdictions, governments mandate standardized drab packaging on all smoking accessory booklets, eliminating brand logos and distinctive artwork. Furthermore, running twelve-gram-per-square-meter paper webs on high-speed folding machines risks frequent web breaks and converting downtime. In October 2025, specialty paper trade reports documented that wood pulp energy costs climbed by 12.4% across European specialty mills [8]. Converting plants must deploy automated optical web inspection cameras to detect microscopic paper pinholes.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Converting companies capture substantial margin growth by introducing pre-rolled paper cones, unrefined organic hemp booklets, and integrated filter tip trays. Brands develop ready-to-fill cones equipped with built-in cardboard crutches, serving consumers who lack manual rolling dexterity. In addition, paper mills develop ultra-thin rice papers that leave virtually zero ash upon burning. Converters also integrate magnetic closures and matching filter tips into compact pocket booklets. In November 2025, retail smoke shop tracking data indicated that pre-rolled unbleached cones achieved a 23.8% sales increase across specialty tobacco outlets [9].
Rolling Papers Market by Country (2026 to 2036)
As per Future Market Insights, Poland represents the fastest-growing rolling papers market among the six evaluated countries, at a 5.9% CAGR from 2026 to 2036, while Sweden records the slowest expansion at 3.8% CAGR. Across all six covered economies, commercial success is dictated by how effectively paper converters navigate packaging health regulations, supply unbleached organic hemp substrates, and distribute pre-rolled cone formats.
Table 7: Country CAGR and Primary Growth Levers for the Rolling Papers Market (CAGR percentage and operational drivers), 2026 to 2036
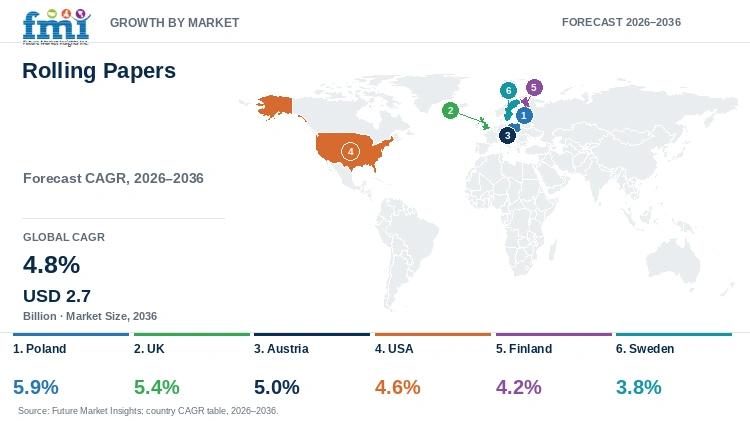
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Poland | 5.9% | Expanding roll-your-own tobacco economy, strong domestic specialty paper converting, and competitive retail pricing |
| UK | 5.4% | High roll-your-own tobacco penetration driven by cigarette taxes, strong demand for organic unbleached papers, and corner store retail reach |
| Austria | 5.0% | Deep European cigarette paper manufacturing heritage, advanced paper watermark technology, and expanding botanical accessory sales |
| USA | 4.6% | Expanding state-level legal adult-use botanical markets, explosive pre-rolled cone popularity, and vibrant smoke shop culture |
| Finland | 4.2% | Advanced Nordic wood pulp forestry infrastructure, strict eco-friendly paper preferences, and steady domestic consumption |
| Sweden | 3.8% | Mature smoking accessory market, strong competition from oral snus alternatives, and demand for unbleached artisan papers |
Source: Future Market Insights analysis
Poland Rolling Papers Market Outlook (2026 to 2036)
By 2036, Poland is projected to grow at 5.9% CAGR, driven by an expanding roll-your-own tobacco economy and competitive domestic paper converting operations. In January 2026, the Polish Chamber of Commerce confirmed steady growth in roll-your-own tobacco and accessory sales across regional kiosks [10]. Cost-conscious consumers switch from manufactured factory cigarettes to loose tobacco and rolling papers to manage personal spending. Polish converting facilities supply cost-effective booklets to neighboring Central European markets. However, strict European Union tobacco product directives impose health warning labels on rolling paper packaging. Manufacturers address this by optimizing booklet interior flap space to communicate paper purity and unbleached origins.
Key takeaway:In Poland, strong economic roll-your-own consumer adoption and regional converting infrastructure propel the fastest growth among evaluated countries.
UK Rolling Papers Market Outlook (2026 to 2036)
The UK rolling papers market is anticipated to advance at 5.4% CAGR over the assessment period, owing to high cigarette excise taxes that drive smokers toward roll-your-own tobacco formats. In March 2025, the UK Tobacco Manufacturers' Association documented that roll-your-own tobacco accounted for a substantial portion of total domestic tobacco consumption [11]. British smokers purchase rolling paper booklets with attached cardboard filter tips at local newsagents and supermarkets. Unbleached organic hemp booklets record rapid sales gains among younger adult smokers. However, plain packaging regulations and retail display bans require papers to be kept in closed dispensary cabinets behind shop counters. Brands resolve this by building strong brand loyalty through word-of-mouth and smoke shop merchandising.
Key takeaway:In the UK, high manufactured cigarette taxation and established roll-your-own consumer habits sustain strong market revenue.
Austria Rolling Papers Market Outlook (2026 to 2036)
In Austria, rolling papers demand is predicted to advance at 5.0% CAGR through 2036, underpinned by a historic cigarette paper papermaking heritage and advanced watermarking technologies. In April 2025, the Austrian Association of the Paper Industry reported stable export shipments of specialty ultrathin papers to international converters [12]. Austrian paper mills lead Europe in producing micro-embossed watermark rolling papers that ensure uniform airflow. Tobacconists feature wide selections of Austrian-manufactured booklets alongside premium smoking pipes. However, declining cigarette smoking rates among Austrian adults create long-term volume headwinds for traditional tobacco papers. Paper mills overcome this barrier by shifting manufacturing toward hemp-based pre-rolled cones for adult-use botanical markets.
Key takeaway:In Austria, world-class paper milling engineering and specialty export converting maintain dependable category performance.
USA Rolling Papers Market Outlook (2026 to 2036)
Adoption of rolling papers in the USA is estimated to expand at 4.6% CAGR through 2036, supported by expanding adult-use botanical legalization and explosive retail demand for pre-rolled cones. In May 2025, the National Association of Tobacco Outlets reported that specialty smoke accessory sales exceeded USD 1.2 Billion across smoke shops and licensed dispensaries [13]. American consumers favor pre-rolled unbleached cones that allow fast, mess-free packing without manual hand rolling. Smoke shops feature massive wall displays of flavored papers, hemp wraps, and artisan booklets. However, municipal flavor bans on tobacco products in certain states require careful SKU management. Brands resolve this by focusing heavily on unflavored, clean-burning organic hemp papers.
Key takeaway:In the USA, expanding adult-use botanical legalization and surging pre-rolled cone popularity provide resilient market growth.
Finland Rolling Papers Market Outlook (2026 to 2036)
The Finland rolling papers sector is projected to record 4.2% CAGR during the assessment period, reinforced by advanced Nordic forestry pulp infrastructure and consumer demand for certified sustainable paper. In June 2025, the Finnish Forest Industries Federation confirmed sustained domestic demand for specialty kraft pulp used in thin paper manufacturing [14]. Finnish consumers prioritize unbleached, chlorine-free papers certified under FSC sustainable forestry standards. Kiosks and grocery stores distribute standard booklet packs to adult smokers. However, strict national anti-smoking health policies and retail display bans limit impulse purchasing. Paper converters address this challenge by marketing biodegradable, unbleached papers that align with Nordic environmental values.
Key takeaway:In Finland, advanced sustainable forestry pulp supply and strict eco-friendly consumer preferences maintain consistent market momentum.
Sweden Rolling Papers Market Outlook (2026 to 2036)
Sweden rolling papers demand is forecast to rise at 3.8% CAGR over the forecast period, supported by artisan smoking accessory retail sales despite intense competition from oral snus products. In July 2025, Statistics Sweden confirmed steady sales of specialty papers across urban convenience retailers [15]. Swedish consumers who roll cigarettes prefer ultra-thin unbleached papers that minimize inhaled smoke volume. Specialized tobacconists in Stockholm and Gothenburg curate artisan European paper booklets. However, Sweden's widespread cultural preference for tobacco-free nicotine pouches and traditional snus limits overall smoking paper volume expansion. Converters mitigate this competition by positioning rolling papers as a premium, occasional ritual for discerning adult consumers.
Key takeaway:In Sweden, artisan unbleached paper preferences support dependable category revenue despite strong competition from oral nicotine products.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Rolling Papers Market?
Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. are the significant market players in this market.
Future Market Insights analysis indicates that the competitive environment divides between multinational paper packaging corporations, specialized ultrathin paper mills, and global smoking accessory brand houses. Packaging corporations operate high-speed paperboard converting plants that print, die-cut, and glue protective booklet covers and display boxes. Specialized paper mills operate precision paper machines that form, watermark, and slit ultrathin cellulose and hemp webs. Brand houses curate leaf formulations, apply natural acacia gum lines, and distribute finished booklets through retail tobacco and dispensary networks. Procurement executives evaluate rolling paper converters on paper basis weight consistency, gum line adhesion, booklet carton rigidity, and regulatory packaging compliance.
- Global Paper Packaging & Converting Leaders: Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, and Sonoco Products Company manufacture specialized paper substrates, folding cartons, and protective packaging formats.
- Protective Packaging & Film Specialists: Sealed Air Corporation engineers barrier protective packaging that protects sensitive paper rolls from atmospheric moisture during international shipping.
- Sustainable Container & Specialty Producers: Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. formulate specialized metal and rigid packaging solutions utilized for premium collectible smoking accessory containers.
Competitive Benchmarking: Rolling Papers Market
Table 8: Competitive Benchmarking for the Rolling Papers Market (qualitative capability ratings), 2026
| Company | Specialty Paper Converting Scale | Folding Carton Booklet Rigidity | Sustainable Fiber Sourcing | Global Retail Distribution Reach |
|---|---|---|---|---|
| Smurfit Westrock plc | High | High | High | High |
| Mondi plc | High | High | High | High |
| Huhtamaki Oyj | High | High | High | High |
| Sonoco Products Company | High | High | High | High |
| Sealed Air Corporation | Medium | Medium | Medium | High |
| Ball Corporation | Low | Low | High | High |
| Crown Holdings, Inc. | Low | Low | High | High |
| Silgan Holdings Inc. | Low | Low | Medium | High |
Key Developments in the Rolling Papers Market
- In September 2026, Smurfit Westrock plc expanded commercial manufacturing of repulpable water-based barrier folding cartons designed for specialty tobacco and smoking accessories [16].
- In June 2026, Mondi plc completed installation of an automated high-precision paper slitting line producing unbleached kraft paper bobbins for rolling booklet converters [17].
- In April 2026, Huhtamaki Oyj launched a certified plastic-free, barrier-coated paperboard packaging tray series for retail tobacco and confectionery display [18].
Key Players in the Rolling Papers Market
- Global Paper Packaging & Converting Leaders
- Smurfit Westrock plc
- Mondi plc
- Huhtamaki Oyj
- Sonoco Products Company
Protective Packaging & Film Specialists
- Sealed Air Corporation
Sustainable Container & Specialty Producers
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
Rolling Papers Market - Report Scope
Table 9: Report Scope for the Rolling Papers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Format / Style; Material Substrate; End-Use Application; Barrier / Coating Property |
| Quantitative Units | USD Billion |
| Market Definition | Encompasses global manufacturer and converter revenue from rolling paper booklets, pre-rolled paper cones, specialty cigarette papers, and protective folding paperboard packaging sold for roll-your-own tobacco and botanical smoking applications. Excludes manufactured factory cigarettes. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Poland, UK, Austria, USA, Finland, Sweden, and additional countries in the full report |
| Key Companies Covered | Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., Silgan Holdings Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Rolling Papers Market - Research Methodology
Table 10: Research Methodology for the Rolling Papers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with specialty paper mill managers, converting plant directors, tobacco accessory wholesalers, retail smoke shop buyers, and packaging engineers to validate paper basis weights, calender line speeds, booklet converting costs, and retail sell-through volumes. |
| Secondary Research | Secondary research included analysis of national forestry trade statistics, tobacco packaging regulatory publications, corporate financial filings, pulp and paper technical journals, and retail scanner data. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up models evaluating specialty pulp consumption, converting machine capacities, and point-of-sale scanner sales of smoking accessories. |
| Data Triangulation and Validation | Data is validated against macroeconomic consumer spending metrics, global specialty paperboard shipments, tobacco retail volume sales, and historical industry benchmarks to ensure high precision without double counting general graphic paper. |
Rolling Papers Market by Segments
Rolling Papers Market segmented by Product Format / Style:
- Folding Cartons & Trays
- Rigid Set-Up Boxes
- Corrugated Containers
- Custom Die-Cut Formats
Rolling Papers Market segmented by Material Substrate:
- Virgin Chemical Kraft Pulp
- Recycled Fluting & Testliner
- Barrier-Coated Solid Bleached Board
Rolling Papers Market segmented by End-Use Application:
- Fresh Produce & Meat Packaging
- Dry Food & Confectionery
- E-Commerce Shipping & Logistics
- Consumer Electronics & Goods
Rolling Papers Market segmented by Barrier / Coating Property:
- Aqueous Water-Based Barrier
- PLA & Bio-Wax Coating
- Standard Uncoated Recyclable
Rolling Papers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Finland
- Sweden
- Austria
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] European Forest Institute. (2025, January 16). Specialty Pulp and Paper Production: Ultrathin Cellulose and Fiber Trends. EFI Technical Reports.
- [2] U.S. Department of Agriculture Economic Research Service. (2025, February 18). Industrial Hemp and Specialty Plant Fiber Production Economics. USDA Publications. https://www.usda.gov
- [3] Food and Agriculture Organization. (2025, March 20). Forest Products Yearbook: Specialty Papers and Sustainable Cellulose Packaging. FAO Publications. https://www.fao.org
- [4] U.S. Food and Drug Administration. (2025, May 22). Requirements for Paper and Paperboard Components in Food and Combustible Contact. FDA CFR Title 21. https://www.fda.gov
- [5] European Food Safety Authority. (2025, June 16). Safety Assessment of Mineral Oils and Sizing Agents in Paperboard Packaging. EFSA Journal. https://www.efsa.europa.eu
- [6] Confederation of European Paper Industries. (2025, August 14). European Specialty Paper Production Statistics and Recycling Benchmarks. CEPI Data.
- [7] Specialty Paper Manufacturers Association. (2025, September 22). Technical Review on Air Permeability and Porosity of Thin Cellulose Paper Leaves. SPMA Bulletins.
- [8] International Paper Physics Conference. (2025, October 18). Calendering and Tensile Optimization for Ultra-Lightweight Hemp Papers. IPPC Proceedings.
- [9] National Association of Tobacco Outlets. (2025, November 12). Retail Accessory Trends in Roll-Your-Own and Botanical Dispensaries. NATO Research.
- [10] Polish Chamber of Commerce. (2026, January 16). Economic Review of the Polish Paper Converting and Tobacco Retail Market. KIG Data.
- [11] UK Tobacco Manufacturers' Association. (2025, March 25). UK Tobacco Market Trends: Roll-Your-Own Growth and Accessory Usage. TMA Publications.
- [12] Austrian Association of the Paper Industry. (2025, April 22). Annual Report on the Austrian Specialty Paper and Export Converting Industry. Austropapier Reports.
- [13] National Association of Tobacco Outlets. (2025, May 28). U.S. Smoke Shop Retail Sales Performance and Accessory Trends. NATO Reports.
- [14] Finnish Forest Industries Federation. (2025, June 18). Nordic Pulp Production and Specialty Packaging Paperboard Statistics. Metsäteollisuus Data.
- [15] Statistics Sweden. (2025, July 24). Retail Turnover in Tobacco Accessories and Alternative Nicotine Products. SCB Reports.
- [16] Smurfit Westrock plc. (2026, September 10). Commercial Rollout of Repulpable Water-Based Barrier Packaging Trays. Corporate Media Center.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the rolling papers market in 2026 and what is forecast for 2036?
- Which roll-your-own consumer habits support steady demand for rolling papers?
- Why do folding cartons & trays lead the product format / style category?
- Why does virgin chemical kraft pulp lead the material substrate category globally?
- How do growth rates prominently differ across Poland, the UK, Austria, and the USA?
- Which leading packaging and converting corporations supply specialty paper packaging today?
- What limits specialty pulp web strength or tobacco advertising in the rolling papers market?
- What should tobacco retail category managers evaluate deeply before selecting paper brands?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Format / Style, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Format / Style, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Format / Style, 2026 to 2036
- Folding Cartons & Trays
- Rigid Set-Up Boxes
- Corrugated Containers
- Custom Die-Cut Formats
- Y-o-Y Growth Trend Analysis By Product Format / Style, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Format / Style, 2026 to 2036
- Global Market Analysis and Forecast, By Material Substrate, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material Substrate, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material Substrate, 2026 to 2036
- Virgin Chemical Kraft Pulp
- Recycled Fluting & Testliner
- Barrier-Coated Solid Bleached Board
- Y-o-Y Growth Trend Analysis By Material Substrate, 2021 to 2025
- Absolute $ Opportunity Analysis By Material Substrate, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Fresh Produce & Meat Packaging
- Dry Food & Confectionery
- E-Commerce Shipping & Logistics
- Consumer Electronics & Goods
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Barrier / Coating Property, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Barrier / Coating Property, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Barrier / Coating Property, 2026 to 2036
- Aqueous Water-Based Barrier
- PLA & Bio-Wax Coating
- Standard Uncoated Recyclable
- Y-o-Y Growth Trend Analysis By Barrier / Coating Property, 2021 to 2025
- Absolute $ Opportunity Analysis By Barrier / Coating Property, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Finland
- Sweden
- Austria
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Austria
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Finland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Sweden
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Format / Style
- By Material Substrate
- By End-Use Application
- By Barrier / Coating Property
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Smurfit Westrock plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mondi plc
- Huhtamaki Oyj
- Sonoco Products Company
- Sealed Air Corporation
- Ball Corporation
- Crown Holdings, Inc.
- Silgan Holdings Inc.
- Smurfit Westrock plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Format / Style, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Material Substrate, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Barrier / Coating Property, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Format / Style
- Figure 6: Global Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Material Substrate
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Barrier / Coating Property
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Format / Style
- Figure 29: North America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Material Substrate
- Figure 32: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End-Use Application
- Figure 35: North America Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Barrier / Coating Property
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Format / Style
- Figure 42: Latin America Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Material Substrate
- Figure 45: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 48: Latin America Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Barrier / Coating Property
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Format / Style
- Figure 55: Western Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Material Substrate
- Figure 58: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 61: Western Europe Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Barrier / Coating Property
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Format / Style
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Material Substrate
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Barrier / Coating Property
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Format / Style
- Figure 81: East Asia Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Material Substrate
- Figure 84: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 87: East Asia Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Barrier / Coating Property
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Format / Style
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Material Substrate
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Barrier / Coating Property
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Format / Style, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Format / Style, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Format / Style
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Material Substrate, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Material Substrate, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Material Substrate
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Barrier / Coating Property, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Barrier / Coating Property, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Barrier / Coating Property
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the rolling papers market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global rolling papers market will reach USD 1.7 Billion in 2026. The market is projected to reach USD 2.7 Billion by 2036, driven by expanding adult-use botanical legalization and steady roll-your-own tobacco consumption.
What is the CAGR for the rolling papers market from 2026 to 2036?
As per FMI, the market is projected to expand at a 4.8% CAGR over the assessment period. Growth is supported by ongoing product innovation into pre-rolled unbleached cones, organic hemp leaves, and natural acacia gum adhesives.
Which product format / style segment leads the rolling papers market?
Future Market Insights projects that folding cartons & trays will hold 43.8% share in 2026. The segment benefits from pocket booklet protection, integrated filter tips, and eye-catching counter retail display functionality.
Which material substrate segment leads the rolling papers market?
Specialty paper converting research indicates that virgin chemical kraft pulp will account for 52.3% share in 2026. Demand is supported by high web tensile strength, slow and uniform burn kinetics, and clean taste profiles.
Which country has a notable growth outlook during the assessment period?
FMI finds that Poland is projected to register a 5.9% CAGR from 2026 to 2036. High market growth is supported by an expanding roll-your-own tobacco economy, strong domestic paper converting infrastructure, and competitive retail pricing.
Who are the key players in the market?
Key participants include Smurfit Westrock plc, Mondi plc, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, Ball Corporation, Crown Holdings, Inc., and Silgan Holdings Inc. Leading market participants focus on precision paper slitting, repulpable barrier folding cartons, and sustainable FSC-certified pulp sourcing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
