

- Market Size (2026)
- USD 178.8 Mn
- Forecast (2036)
- USD 264.6 Mn
- CAGR (2026 to 2036)
- 4.0%
How big is Tennis Shoes Market in 2026?
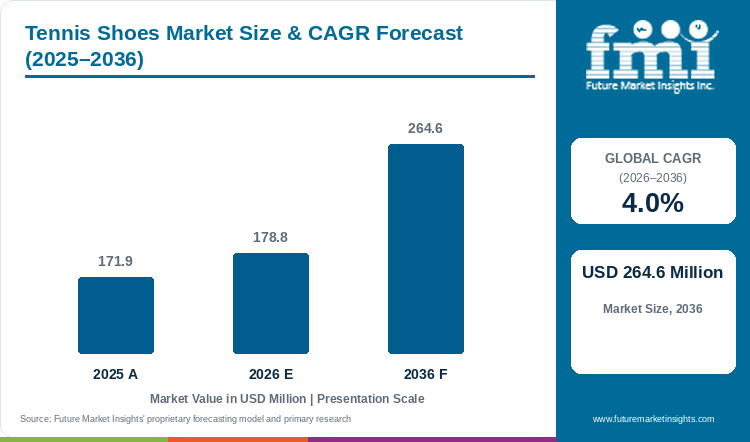
Tennis shoes market size stood at USD 171.9 million in 2025, reaches USD 178.8 million in 2026 and is projected at USD 264.6 million by 2036. Demand for tennis shoes is set to expand at a 4% CAGR from 2026 to 2036, as club and recreational players replace worn pairs more often.
Participation data points to higher wear intensity among frequent players than among casual athleisure buyers. The United States Tennis Association, citing National Golf Foundation PAC and PLAY survey data, reported 27.3 million tennis players in 2025, up 1.6 million from 2024 and up 54% since 2019, with core players completing 10 or more sessions a year reaching 14.5 million [1]. Due to this, outsole wear climbs faster among frequent players, since court surfaces grind soles down quicker than casual wear. Apart from that, first-time players reached 4.9 million in 2025, adding buyers who need a first pair of court shoes [1]. FMI finds hard court shoes holding a 49% share of playing surface sales in 2026, as hard courts are the most widely available surface at public and club facilities. Growth in core and first-time player counts is anticipated to keep replacement and first-pair purchases rising through 2036.
Key Market Trends & Insights
- By playing surface, hard court shoes lead 2026 sales, as hard courts are the most widely available and most commonly played surface for recreational and club players.
- By consumer orientation, men account for 58% of 2026 sales, reflecting higher participation rates among male players across profiled countries.
- By sales channel, specialty stores hold the largest estimated share of 2026 sales, as players prefer fitting and surface-specific advice before a purchase.
- By country, South Korea shows the fastest profiled CAGR at 4.2% from 2026 to 2036 among the limited set of countries with comparable data, supported by growing racquet sport participation among younger players.
- Sustainable materials and AI foot scanning for personalized fit are gaining ground, and online retailers now support product discovery ahead of an in-store or online purchase.
Regional Highlights
- South Korea ranks first among the profiled countries at 4.2% CAGR over the 2026 to 2036 period.
- Japan (4.1%) and France (4.0%) rank just behind, with United States closing the profiled set at 3.8% through 2036.
- Tennis participation in the United States reached 27.3 million players in 2025, a record level reported by the United States Tennis Association, and this growth is supporting demand for tennis shoes across the profiled countries [1].
Market Size & Forecast
Table 1: Market Size and Forecast for the Tennis Shoes Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 171.9 million |
| Estimated Market Size in 2026 | USD 178.8 million |
| Projected Market Size by 2036 | USD 264.6 million |
| CAGR, 2026 to 2036 | 4% |
| Added Sales, 2026 to 2036 | USD 85.8 million |
| Market Expansion Multiple | 1.5x |
Most tennis shoe demand now comes from recreational and club players buying a first or replacement pair. Better traction and surface-specific cushioning are the main reasons players choose a particular pair. Participation among women grew by 1.1 million players in 2025, a 10% increase, broadening the buyer base for tennis shoes [1]. At the top end, professional-grade models keep premium pricing in place, as elite players and endorsers favor the newest cushioning builds. High prices for premium technical models can still delay purchases among price-sensitive recreational players. Growing participation across age groups is anticipated to drive most purchases through 2036.
Player Participation and Footwear Replacement Readiness
Sales of tennis shoes are rising alongside player counts, since frequent play wears down outsoles faster than casual use. Retained players in the United States reached 20.7 million in 2025, up 10% from 2024, and 4.9 million first-time players picked up a racquet for the first time [1]. First-time and returning players both need a first pair of court shoes, widening the entry-level buyer base. More than 25 million non-players describe strong enthusiasm for starting, a pool FMI expects to convert gradually into new footwear buyers [1]. Grass court shoes are set to keep leading initial purchases, as beginner coaching programs commonly start players on grass or hard courts with similar traction needs.
Large sporting goods brands are reporting broad growth across performance categories that include tennis footwear. adidas reported currency-neutral revenues for the adidas brand rising 12% in the third quarter of 2025, with gains across markets, product divisions, categories, and channels, on October 21, 2025 [2]. Consumer orientation sales stay tilted toward men, who hold 58% share in 2026, though participation data shows play among women growing faster, up 10% in 2025 [1]. South Korea leads profiled country growth at a 4.2% CAGR through 2036, followed by Japan at 4.1%, and growth in the United States stays comparatively modest at 3.8% despite record domestic participation, pointing to a replacement cycle among already-established players [1].
Table 2: Participation and Brand Growth Indicators for the Tennis Shoes Market (percentage changes and player counts), mixed reporting years from 2024 to 2025
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| US tennis participation, 2025 | 27.3 million players, up 1.6 million from 2024 | Rising participation widens the buyer base for tennis shoes. | [1] |
| US core players, 2025 | 14.5 million, 53% of all players | Frequent players wear down outsoles faster, lifting replacement demand. | [1] |
| US first-time players, 2025 | 4.9 million, up 9% from 2024 | New players need a first pair of court shoes. | [1] |
| US women's participation, 2025 | Up 1.1 million, a 10% increase | Faster growth in women's play widens sizing and style demand. | [1] |
| US retained players, 2025 | 20.7 million, up 10% from 2024 | Retained players drive mostly replacement purchases. | [1] |
| adidas brand sales, Q3 2025 | Currency-neutral growth of 12% | Gains across categories and regions support performance footwear sales. | [2] |
| South Korea tennis shoes CAGR | 4.2%, 2026 to 2036 | Fastest-growing profiled country. | Future Market Insights |
| Japan tennis shoes CAGR | 4.1%, 2026 to 2036 | Second-fastest profiled country. | Future Market Insights |
| Grass court shoes share, 2026 | 49% of playing surface sales | Leading playing surface segment. | Future Market Insights |
| Men's consumer orientation share, 2026 | 58% of consumer orientation sales | Leading consumer orientation segment. | Future Market Insights |
Table 3: Participation, Brand and Segment Benchmarks for the Tennis Shoes Market (CAGR percentage and player participation), 2025 to 2036
| Indicator | Reported value | Related figure | Source |
|---|---|---|---|
| Tennis shoes market, 2025 to 2026 | USD 171.9 million to USD 178.8 million | 4% CAGR, 2026 to 2036 | Future Market Insights |
| US tennis participation, 2025 | 27.3 million players | Up 1.6 million from 2024 | [1] |
| US tennis participation growth since 2019 | Up 54% | Nearly 10 million more players added | [1] |
| US first-time players, 2025 | 4.9 million | Up 9% from 2024 | [1] |
| US women's participation, 2025 | Up 1.1 million players | A 10% increase | [1] |
| adidas brand sales growth, Q3 2025 | Currency-neutral growth of 12% | Reported October 21, 2025 | [2] |
| South Korea tennis shoes CAGR | 4.2%, 2026 to 2036 | Fastest among profiled countries with comparable data | Future Market Insights |
| Hard court shoes share, 2026 | Leading share | Leading playing surface segment | Future Market Insights |
Analyst Perspective
“Tennis shoe brands that match grass, clay and hard court traction patterns to local playing surfaces, and that reach first-time players through specialty retail and club programs, will take most replacement and entry-level orders through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Tennis Shoes Market segmented?
The tennis shoes market is studied across three commercial segments plus region, namely playing surface, consumer orientation and sales channel. In 2026, grass court shoes hold 49% of playing surface sales, men hold 58% of consumer orientation sales, and specialty stores lead sales channel demand.
By playing surface: grass court shoes, clay court shoes, and hard court shoes.
By consumer orientation: men and women.
By sales channel: hypermarket/supermarket, wholesalers/distributors, specialty stores, multi-brand stores, independent small stores, online retailers, and other channels.
North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do hard court shoes lead playing surface sales?
Hard court shoes hold the leading share of playing surface sales in 2026, as hard courts are the most widely available playing surface for recreational and club players.
Table 4: Playing Surface Share for the Tennis Shoes Market (percentage share), 2026
| Playing Surface | Share (2026) |
|---|---|
| Hard Court Shoes | 49% |
| Grass and Clay Court Shoes Combined | 51% |
| Total | 100% |
Table 5: Playing Surface Leadership and Market Growth for the Tennis Shoes Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4% |
| Leading Segment | Grass Court Shoes |
Demand for hard court shoes stays ahead of clay and grass court models, as hard courts are the most widely available playing surface at public and club facilities. FMI finds that hard court shoes hold the leading share of playing surface sales in 2026, with grass and clay court shoes serving tournament-linked and regional demand.
- Hard court shoes hold the leading share of playing surface sales in 2026, since most public and club facilities offer hard courts, giving this category the broadest everyday wear base.
- Players comparing playing-surface shoes should check outsole pattern and cushioning, as these factors set grip and comfort on a given court type.
Why do men lead consumer orientation sales?
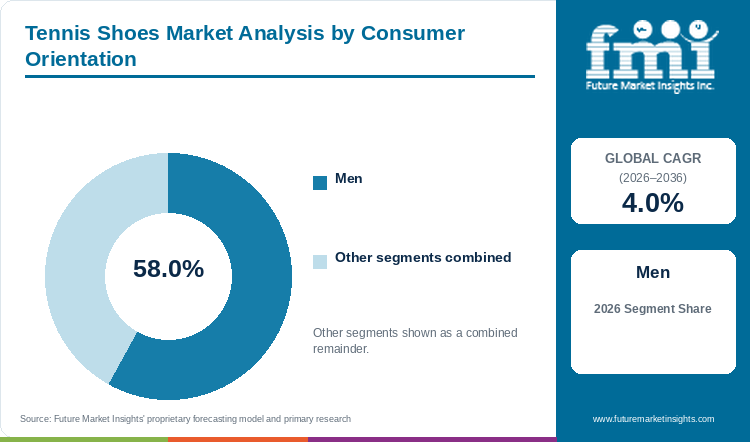
Men account for 58% of consumer orientation sales in 2026, reflecting higher long-standing participation rates among male players.
Sales of men's tennis shoes follow higher participation rates among male players across most profiled countries. As per FMI estimates, men hold 58% of consumer orientation sales in 2026. Participation among women is growing faster, up 10% in 2025 to add 1.1 million more women players in the United States alone [1]. Brands are widening women's lines and sizing ranges in response. Faster growth in women's participation is expected to narrow the consumer orientation gap gradually through 2036.
- Men hold 58% of consumer orientation sales in 2026, reflecting longer-standing participation rates among male players.
- Growth in women's participation, up 10% in 2025, is widening sizing and style ranges across tennis shoe lines.
Why do specialty stores lead sales channel demand?
Specialty stores hold the largest estimated share of sales channel demand in 2026, as players prefer fitting advice before a purchase.
Demand for tennis shoes through specialty stores stays ahead of other channels, as players want fitting advice and surface-specific recommendations before a purchase. FMI estimates that specialty stores hold the largest share of sales channel demand in 2026. Multi-brand stores and independent small stores also sell fitted pairs, and hypermarkets, supermarkets and wholesalers serve price-led, lower-engagement buyers. Online retailers are expanding the role of digital discovery, letting buyers compare models before an in-store or online purchase. Growth of online discovery alongside specialty fitting is expected to keep both channels relevant through 2036.
- Specialty stores lead sales channel demand in 2026, and fitting advice remains the main reason players choose this channel over general retail.
- Players comparing sales channels should weigh in-person fitting against online price and selection before choosing a channel for the purchase.
South Korea leads profiled country growth at a 4.2% CAGR through 2036, supported by rising youth racquet sport participation.
United States posts the slowest profiled CAGR at 3.8% through 2036, even with record domestic participation of 27.3 million players in 2025.
What are the drivers, restraints, and opportunities in the Tennis Shoes Market?
Rising tennis participation lifts replacement and first-pair demand, price-sensitive markets slow premium adoption, and growth among first-time and returning players opens the main opportunity for entry-level specialty retail lines.
- Driver: Key drivers of the tennis shoes market include rising tennis participation, with United States players reaching a record 27.3 million in 2025, up 54% since 2019, as per FMI [1].
- Restraint: Intense competition and pricing pressure in price-sensitive emerging markets slow sales of premium tennis shoes, and counterfeit products add further pressure.
- Opportunity: Rising participation among first-time and returning players opens growth for entry-level tennis shoe lines sold through specialty retail.
Record Participation Lifts Replacement Demand
Tennis participation keeps setting new highs, and this lifts the pool of players who need a replacement pair. The United States Tennis Association reported 27.3 million players in 2025, up 1.6 million from 2024, with 20.7 million retained players and 4.9 million first-time players [1]. Due to this, specialty retailers are stocking deeper ranges of surface-specific shoes. Sales of tennis shoes are anticipated to grow fastest in markets that keep adding first-time buyers through 2036.
Price-Sensitive Markets Slow Premium Adoption
Price-sensitive buyers in emerging markets remain slower to adopt premium technical models. Intense competition among established brands keeps margins tight on mid-range pairs. Counterfeit products add further pressure on brand pricing in several regions. High prices for premium technical models may slow orders from price-sensitive recreational players in the early forecast years.
Entry-Level Demand Opens Specialty Retail Growth
Rising numbers of first-time and returning players are opening growth for entry-level tennis shoe lines. The United States Tennis Association recorded 4.9 million first-time players and 1.7 million returning players in 2025 [1]. Specialty stores offering fitting advice and starter ranges stand to gain from this entry-level buyer pool. Brands building starter lines sold through specialty retail stand to gain new orders through 2036.
Which country CAGRs are profiled in the Tennis Shoes Market?
Sales of tennis shoes in South Korea grow fastest among the five profiled countries for which comparable data is available, at a 4.2% CAGR between 2026 and 2036, as per FMI. United States posts the slowest rate among this profiled set, at 3.8% CAGR, even with directly reported record domestic participation.
Table 6: Country CAGRs and Primary Growth Levers for the Tennis Shoes Market (CAGR percentage), 2026 to 2036
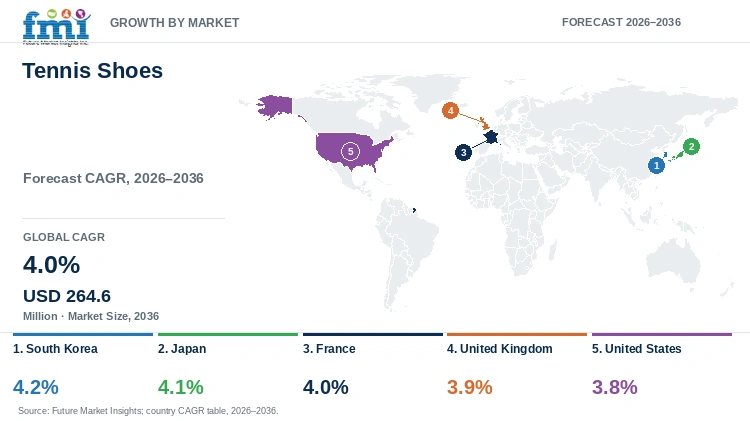
| Country | CAGR (2026–2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 4.2% | Growing youth racquet sport participation |
| Japan | 4.1% | Steady club participation and replacement buying |
| France | 4% | Broad recreational player base |
| United Kingdom | 3.9% | Tournament-linked grass and hard court demand |
| United States | 3.8% | Replacement buying among an already-large player base |
Source: Future Market Insights
South Korea Tennis Shoes Market Outlook (2026–2036)
South Korea leads profiled country growth with a 4.2% CAGR for 2026 to 2036, the fastest among the five profiled countries. Rising racquet sport participation among younger players is widening the buyer base for tennis shoes in the country. Specialty sporting goods retailers are expanding tennis-specific ranges to meet this demand. Growth in youth participation is expected to keep South Korea ahead of the other profiled countries through 2036.
Key takeaway: Growing youth participation in racquet sports will keep South Korea as the fastest-growing profiled market.
Japan Tennis Shoes Market Outlook (2026–2036)
Japan is projected to add tennis shoe sales at a 4.1% CAGR through 2036, the second-fastest among the five profiled countries. Established club and school tennis programs keep a steady base of players needing surface-specific shoes. Replacement purchases from existing club players form the main source of demand. Steady club participation is expected to keep Japan ahead of the United States and France through 2036.
Key takeaway: Replacement purchases from established club players will drive most Japanese demand.
France Tennis Shoes Market Outlook (2026–2036)
France is projected to add tennis shoe sales at a 4.0% CAGR through 2036. A broad base of recreational and club players, supported by the country's strong domestic tournament culture, supports steady demand across playing surfaces.
Key takeaway: A broad recreational player base will keep French demand steady and slower than the fastest-growing profiled countries.
United Kingdom Tennis Shoes Market Outlook (2026–2036)
United Kingdom tennis shoe sales are projected to grow at a 3.9% CAGR through 2036. Grass court tradition, reinforced by major domestic tournaments, keeps grass and hard court shoes as the main purchase. Club and recreational players form the core buyer base for replacement pairs. Tournament-linked attention is expected to support steady, if modest, growth through 2036.
Key takeaway: Tournament-linked demand will keep grass and hard court shoes as the main United Kingdom purchase.
United States Tennis Shoes Market Outlook (2026–2036)
United States tennis shoe sales are projected to grow at a 3.8% CAGR through 2036, the slowest among the five profiled countries, even as domestic participation hit a record 27.3 million players in 2025 [1]. Most of this growth, a 54% rise since 2019, has already fed through to current footwear purchases, leaving a smaller incremental base for the forecast period. Retained players, at 20.7 million in 2025, are buying mainly replacement pairs instead of first pairs [1]. Replacement buying among an already-large player base is expected to keep United States growth comparatively modest through 2036.
Key takeaway: A large, already-converted player base will keep United States growth modest relative to faster-growing profiled countries.
Who are the notable companies in the Tennis Shoes Market?
Adidas Group, Nike Inc., New Balance, ASICS, PUMA SE, Under Armour, Li Ning, ECCO, China Dongxiang, and 361 Degrees are the leading companies profiled in this market.
Tennis shoe makers come from the United States, Germany, Japan and China and differ in surface-specific range, endorsement reach and price positioning. FMI data shows Adidas Group, Nike Inc., New Balance and ASICS concentrating on performance court footwear with professional endorsements. PUMA SE, Under Armour and Li Ning supply mid-range performance and lifestyle-crossover models. ECCO, China Dongxiang and 361 Degrees complete the supplier set with regional and comfort-focused ranges. Leading brands are widening surface-specific ranges and sizing to gain replacement and first-pair orders from players.
- Performance court specialists: Adidas Group, Nike Inc., New Balance, and ASICS supply professional-endorsed, surface-specific tennis shoes.
- Mid-range and crossover suppliers: PUMA SE and Under Armour cover performance and training crossover models, and Li Ning adds regional mid-range ranges.
- Specialist tennis brands: Wilson, Head, Babolat, Yonex, Mizuno, K-Swiss, and Diadora supply dedicated court-tennis footwear alongside racquet and apparel lines.
Competitive Benchmarking: Tennis Shoes Market
Table 7: Competitive Benchmarking for the Tennis Shoes Market (qualitative capability ratings), 2026
| Company | Performance Tech | Endorsement Reach | Specialty Retail | Regional Reach |
|---|---|---|---|---|
| Adidas Group | High | High | High | High |
| Nike Inc. | High | High | High | High |
| New Balance | High | Medium | High | Medium |
| ASICS | High | Medium | Medium | Medium |
| PUMA SE | Medium | Medium | Medium | Medium |
| Dolphin Pack | Low | Medium | Medium | High |
| Mert Makina | Low | Low | Low | Medium |
| AMT Engineering | Low | Low | Low | Low |
| Sima Machinery | Low | Low | Low | Low |
| BekaertDeslee Machinery | Low | Low | Low | Low |
Key Developments in the Tennis Shoes Market
- In October 2025, adidas reported currency-neutral revenues for the adidas brand rising 12% in the third quarter, with gains across markets, product divisions, categories, and channels [2].
- In February 2026, the United States Tennis Association reported record national participation of 27.3 million players for 2025, up 1.6 million from 2024 [1].
- In 2025, the United States Tennis Association recorded 4.9 million first-time tennis players, up 9% from 2024 [1].
- In 2025, the United States Tennis Association recorded a 10% rise in women's tennis participation, adding 1.1 million more women players [1].
Key Players in the Tennis Shoes Market
Performance Court Specialists
- Adidas Group
- Nike Inc.
- New Balance
- ASICS
Mid-range and Crossover Suppliers
- PUMA SE
- Under Armour
- Li Ning
Specialist Tennis Brands
- Wilson
- Head
- Babolat, Yonex, Mizuno, K-Swiss, and Diadora
Tennis Shoes Market - Report Scope
Table 8: Report Scope for the Tennis Shoes Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Playing surface; consumer orientation; sales channel; region |
| Quantitative units | USD million |
| Market definition | Revenue from first sales of tennis-specific footwear designed for grass, clay, and hard court surfaces, sold across specialty stores, multi-brand stores, online retailers, hypermarkets/supermarkets, wholesalers/distributors, independent small stores, and other channels. General athletic footwear and multi-sport shoes without court-specific outsole design are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; France; United Kingdom; Japan; South Korea |
| Key companies profiled | Adidas Group, Nike Inc., New Balance, ASICS, PUMA SE, Under Armour, Li Ning, ECCO, China Dongxiang, 361 Degrees |
| Forecast period | 2026 to 2036 |
| Approach | Sizing combines bottom-up and top-down approaches that reconcile player participation data, replacement cycle estimates, average selling prices by surface type, segment splits, and country-level demand, checked against brand disclosures and primary interviews. |
Tennis Shoes Market - Research Methodology
Table 9: Research Methodology for the Tennis Shoes Market (research methods and approach), 2026 edition
| Coverage field | Report scope |
|---|---|
| Primary Research | Primary research includes interviews with tennis shoe brand managers, specialty retailers, club and facility operators, and recreational players. Interviews cover purchasing frequency, surface preferences, sizing needs, and willingness to pay across price tiers. |
| Desk Research | Desk research draws on brand filings, product launch releases, sports participation reports, trade body data, and country-level retail statistics. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and applies player participation growth rates, replacement cycle estimates, average selling prices by surface and channel, and segment splits for each country. |
| Data Validation | Each estimate is tested against brand disclosures, player participation data, and primary interviews. Multi-sport shoes and general athletic footwear stay outside market value, so no revenue is counted twice. |
Tennis Shoes Market by Segments
Tennis Shoes Market segmented by Playing Surface:
- Grass court shoes
- Clay court shoes
- Hard court shoes
Tennis Shoes Market segmented by Consumer Orientation:
- Men
- Women
Tennis Shoes Market segmented by Sales Channel:
- Specialty stores
- Multi-brand stores
- Online retailers
- Hypermarket/supermarket, wholesalers/distributors, independent small stores, and other channels
Tennis Shoes Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] United States Tennis Association, citing National Golf Foundation PAC and PLAY study data. (2026, February 18). Tennis Participation Continues to Surge with Six Consecutive Years of Growth, Reaching 27.3 Million Players in 2025.https://www.usta.com/en/home/stay-current/national/tennis-participation-continues-to-surge-with-six-consecutive-yea.html
- [2] adidas AG. (2025, October 21). adidas Reports Strong Third Quarter Results and Increases its Full-Year Outlook.https://www.adidas-group.com/en/media/press-releases/adidas-reports-strong-third-quarter-results-and-increases-its-full-year-outlook
This Report Answers
- What value will tennis shoe sales reach in 2026?
- By 2036, what market value will tennis shoes reach?
- Which playing surface takes the largest share of sales?
- What consumer orientation and sales channel do players favor?
- Which profiled countries show the fastest growth in tennis shoe sales?
- Which companies lead the supply of tennis shoes to players?
Frequently Asked Questions
What is the Tennis Shoes Market worth in 2026?
Tennis shoe sales are valued at USD 178.8 million in 2026, according to FMI. The market will reach USD 264.6 million by 2036 as participation keeps adding first-time and returning buyers.
What CAGR is projected for the Tennis Shoes Market through 2036?
FMI projects a 4% CAGR for the tennis shoes market from 2026 to 2036. Rising tennis participation and replacement buying will support much of this growth.
Which playing surface holds a leading share in 2026?
Hard court shoes hold the leading share of playing surface sales in 2026. Players favor this surface type because hard courts are the most widely available for everyday and club play.
Which consumer orientation holds a leading share in 2026?
Men will account for 58% of consumer orientation sales in 2026. Higher long-standing participation rates among male players support this share.
Which country has a leading growth outlook through 2036?
South Korea leads the profiled countries with a 4.2% CAGR for tennis shoe sales over 2026 to 2036. Growing racquet sport participation among younger players supports this outlook.
Who are the key companies in the Tennis Shoes Market?
Key companies include Adidas Group, Nike Inc., New Balance, ASICS, PUMA SE, Under Armour, Li Ning, ECCO, China Dongxiang, and 361 Degrees. These brands compete on surface-specific range, endorsement reach and price positioning.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Playing Surface, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Playing Surface, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Playing Surface, 2026 to 2036
- Grass court shoes
- Clay court shoes
- Hard court shoes
- Y-o-Y Growth Trend Analysis By Playing Surface, 2021 to 2025
- Absolute $ Opportunity Analysis By Playing Surface, 2026 to 2036
- Global Market Analysis and Forecast, By Consumer Orientation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Consumer Orientation, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Consumer Orientation, 2026 to 2036
- Men
- Women
- Y-o-Y Growth Trend Analysis By Consumer Orientation, 2021 to 2025
- Absolute $ Opportunity Analysis By Consumer Orientation, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- Specialty stores
- Multi-brand stores
- Online retailers
- Hypermarket/supermarket, wholesalers/distributors, independent small stores, and other channels
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Playing Surface
- By Consumer Orientation
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Adidas Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nike Inc.
- New Balance
- ASICS
- PUMA SE
- Dolphin Pack
- Mert Makina
- AMT Engineering
- Sima Machinery
- BekaertDeslee Machinery
- Under Armour
- Li Ning
- Wilson
- Head
- Babolat, Yonex, Mizuno, K-Swiss, and Diadora
- Adidas Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


