

- Market Size (2026)
- USD 27.4 Bn
- Forecast (2036)
- USD 39.4 Bn
- CAGR (2026 to 2036)
- 3.7%
How big is Veneer Sheets Market in 2026?
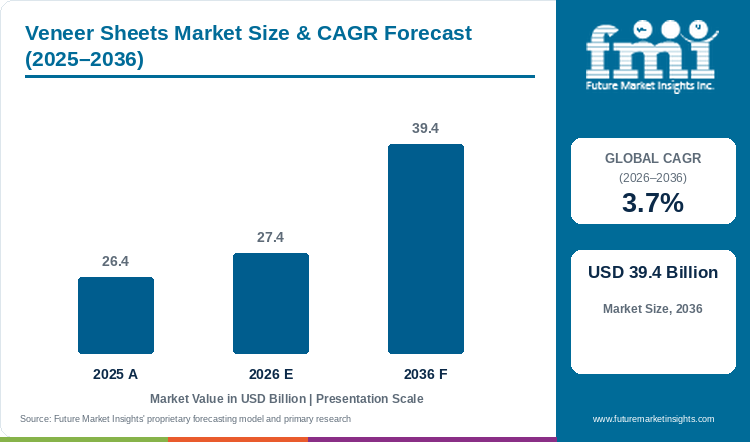
The veneer sheets market is estimated at USD 26.4 billion in 2025 and is expected to reach USD 27.4 billion in 2026. Sales are forecast to grow at a 3.7% CAGR and reach USD 39.4 billion by 2036.
Veneer sheets market size, an estimated USD 26.4 billion for 2025, is projected to rise to USD 27.4 billion in 2026. Sales are then forecast to expand on a 3.7% CAGR, to an expected USD 39.4 billion by 2036. Traceable, legally sourced face veneer will set the outlook through 2036, because European furniture and shopfit buyers now check the origin of every log behind a panel. The EU deforestation regulation will apply to medium and large operators from 30 December 2026, after the European Parliament adopted a targeted revision on 17 December 2025.[1] Slicing mills holding geolocation data for each hardwood log will keep European orders, and mills lacking such data will lose those buyers. The FMI outlook points veneer producers toward securing documented hardwood supply and certifying paper-backed lines first, since paper-backed sheets are expected to carry close to half of product type demand in 2026, at 47%.
Key Market Trends & Insights
- Paper-backed sheets, at an expected 47% in 2026, lead product type sales by a wide margin over wood-backed sheets at an estimated 18.5%.
- Office, hospitality, retail and institutional fit-outs give commercial use a projected 58% share of the end use split in 2026. German furniture industry associations reported a 3.5% drop in office and shop furniture sales for January to June 2026.[2]
- Hardwood faces are projected to cover 56% of wood source sales in 2026, against 20% for engineered or reconstituted veneer.
Regional Highlights
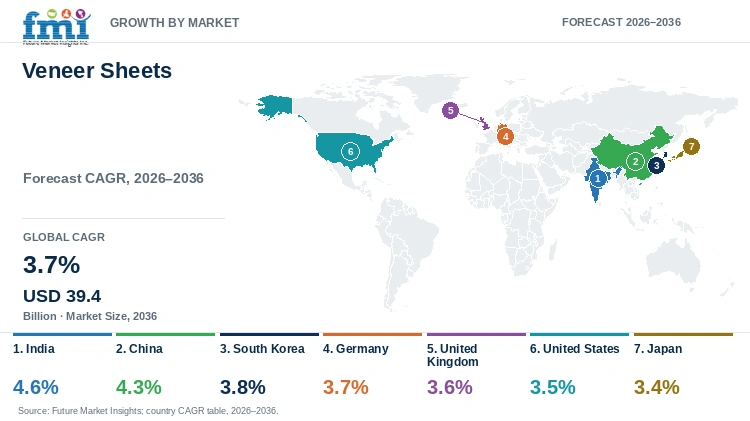
- Commercial fit-outs put India first among the countries covered, with an expected 4.6% CAGR between 2026 and 2036 in the FMI outlook.
- China and South Korea, at 4.3% and 3.8%, run ahead of the market, and Germany matches the 3.7% overall pace. Mature interior markets in the United Kingdom, the United States and Japan range from 3.4% to 3.6%, short of the 3.7% rate for the market as a whole.
- US duties of 25% on imported kitchen cabinets and vanities applied from 14 October 2025, and a rise to 50% was scheduled from 1 January 2026 for countries without an agreement.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Veneer Sheets Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 26.4 billion |
| Estimated Market Size in 2026 | USD 27.4 billion |
| Projected Market Size by 2036 | USD 39.4 billion |
| CAGR, 2026 to 2036 | 3.7% |
| Added Revenue, 2026 to 2036 | USD 12.0 billion |
| Market Expansion Multiple | 1.4x |
Veneer orders follow furniture, cabinet and fit-out schedules, so housing permits and office refurbishment set the timing of sales. US building permits for August 2026 ran at a seasonally adjusted annual rate of 1,394,000, a 3.5% gain on the August 2025 figure.[4] Plywood mills peel softwood logs for structural panels, and growth of the softwood veneer and plywood market competes with decorative slicing for the same log supply. FMI's model shows USD 12.0 billion of new veneer sales arriving over the decade, which puts the 2036 market at roughly 1.4 times the 2026 size. Weak housing in Japan is a regional risk, as housing starts fell 6.5% to 740,667 units in 2025, the lowest in 62 years.[5]
Traceability Rules, Tariffs and Housing Cycles
Traceability rules are changing supplier choice in Europe. The revised EU deforestation regulation applies to micro and small operators from 30 June 2027, and only the first downstream operator still needs to collect a reference number.[1] Veneer importers will favour slicers who can supply geolocation and due diligence files with each shipment.
US tariffs are moving cabinet and furniture assembly toward domestic plants. The September 2025 proclamation set 25% duties on kitchen cabinets, vanities and cabinet parts, and 25% on upholstered wooden products.[3] Ethan Allen said about 75% of the company's custom furniture is made in North American plants and reported new Section 301 tariffs between 10% and 12.5% from 24 July 2026.[6] Domestic cabinet and casegood makers will buy more face veneer from local slicers.
Table 2: Traceability, Tariff and Housing Indicators for the Veneer Sheets Market (dates, rates and units), 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| EUDR application, medium and large operators | 30 December 2026 | Log origin data for veneer imports. | [1] |
| US duty on kitchen cabinets and vanities | 25% from 14 October 2025 | Domestic cabinet assembly. | [3] |
| US building permits, August 2026 | 1,394,000 SAAR; up 3.5% | Cabinet and furniture demand. | [4] |
| German kitchen furniture sales, H1 2026 | About EUR 2.9 billion; up 1% | Kitchen fronts and panels. | [2] |
| Greenply plywood and allied sales, Q1 FY27 | INR 526.6 crore; up 16% | Decorative veneer demand in India. | [7] |
| Japan housing starts, 2025 | 740,667; down 6.5% | Weak interior demand. | [5] |
| Hanssem Rehaus sales, Q2 2026 | Up 13%; premium kitchens up 40% | Kitchen and storage orders in Korea. | [8] |
Analyst Perspective
“The EU traceability deadline will sort veneer suppliers into two groups by 2027, in my view. Slicers with documented logs and paper-backed lines ready for European furniture plants will take the new orders, and I would put capital into log-origin systems before adding slicing capacity.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the veneer sheets market segmented?
The market is segmented into product type, end use, wood source, and region. Paper-backed veneer is expected to lead product type with 47% share in 2026, commercial use is likely to lead end use with 58%, and hardwood is projected at 56% of wood source.
By product type: paper-backed, wood-backed, laid-up, phenolic-backed, and others.
By end use: commercial (office, hospitality, retail and institutional) and residential.
By wood source: hardwood, engineered or reconstituted, softwood, and bamboo and others.
By region: seven regions spanning North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does paper-backed veneer lead veneer sheets sales by product type?
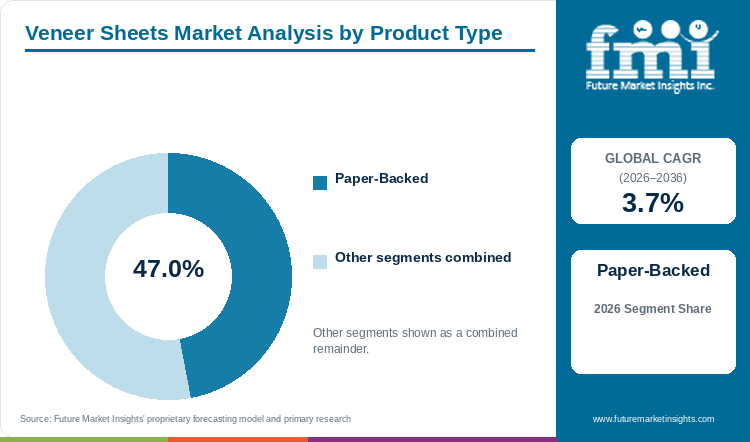
Paper-backed veneer is expected to lead product type sales with 47% share in 2026, ahead of wood-backed sheets at an estimated 18.5% and laid-up faces at about 14.2%.
Table 3: Product Type Share for the Veneer Sheets Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Paper-Backed | 47% |
| Wood-Backed | 18.5% |
| Laid-Up | 14.2% |
| Phenolic-Backed | 12.4% |
| Others | 7.9% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Veneer Sheets Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.7% |
| Leading Segment | Paper-Backed |
Paper-backed veneer is expected to lead with 47% share in 2026, because the flexible sheet bends around columns, curved desks and door edges without cracking. Wood-backed sheets, an estimated 18.5%, are stiffer and suit flat panels that need a two-ply build. Laid-up faces, near 14.2%, arrive spliced and ready to press, which saves time for small joinery shops. Phenolic-backed sheets, about 12.4%, resist moisture in hotel bathrooms and laboratories but cost more. Others, roughly 7.9%, include peel-and-stick and edge-banding rolls. Thin stone faces compete on feature walls, and the thin stone veneers market is forecast to expand at a CAGR of 6.7%, so wood veneer suppliers will keep pricing tight on lobby and retail walls. A fit-out contractor picks paper-backed veneer for curves and phenolic-backed sheets for wet areas.
- Architectural millwork, curved reception desks, columns and door skins use most paper-backed sheets.
- In April 2026, Salone del Mobile.Milano reported 316,342 visitors from 167 countries.[9]
What gives commercial use the larger end use share for veneer sheets?
Commercial use is likely to lead end use sales with 58% share in 2026, against 42% for residential.
Table 5: End Use Share for the Veneer Sheets Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Commercial | 58% |
| Residential | 42% |
| Total | 100.0% |
Commercial use is projected to lead with 58% share in 2026, carried by office and hotel refurbishment. Offices take about 24% of sales, hospitality 18%, retail 12% and institutions 4%, and each refurbishment replaces wall panels, reception desks and doors at once. Residential use, at 42%, follows kitchen and furniture purchases, which move with housing permits. A hotel group renovating a floor orders veneer by the container, so commercial projects keep the larger share.
- Offices, hotels, shops and institutions are the four commercial buyer groups.
- Hanssem reported in August 2026 that apartment purchases and renovations raised Rehaus kitchen, bath and storage sales by 13%.[8]
Why does hardwood lead veneer sheets sales by wood source?
Hardwood is projected at 56% of wood source sales in 2026, ahead of engineered or reconstituted veneer at 20% and softwood at 19%.
Table 6: Wood Source Share for the Veneer Sheets Market (percentage share), 2026
| Wood Source | Estimated Share (2026) |
|---|---|
| Hardwood | 56% |
| Engineered or Reconstituted | 20% |
| Softwood | 19% |
| Bamboo and Others | 5% |
| Total | 100.0% |
Hardwood will lead wood source sales in 2026, at 56%. Oak, walnut and ash faces carry the grain that architects specify for premium interiors. Engineered or reconstituted veneer, at 20%, repeats the same pattern across a whole project and avoids grain mismatch. Softwood, at 19%, serves lower-cost panels and rustic designs. Bamboo and others, at 5%, remain a niche for eco-labelled fit-outs. Hardwood logs face the strictest origin checks under the EU regulation from December 2026, so reconstituted veneer will gain some specification work.[1]
- Oak, walnut, ash, maple and cherry are the main hardwood faces.
- In September 2025, the US set duties on cabinets and upholstered wooden products under Section 232.[3]
What are the drivers, restraints, and opportunities in the veneer sheets market?
Office, hotel and kitchen refurbishment brings repeat orders for real wood surfaces. Traceability rules and tariffs raise compliance and supply costs, and domestic cabinet assembly in the United States opens orders for local slicers.
- Driver: Refurbishment cycles in offices, hotels and kitchens replace wall panels, doors and fronts together, which keeps orders for real wood surfaces flowing.
- Restraint: Log-origin checks and import duties raise the cost of each sheet, and small importers struggle to carry the paperwork.
- Opportunity: Cabinet and furniture makers moving assembly into the United States need local face veneer, which opens contracts for domestic slicers.
Refurbishment Cycles Bring Repeat Orders
Interior refurbishment creates veneer demand even when new building is flat. Kitchen furniture held up better in Germany, with first-half 2026 sales up 1% at about EUR 2.9 billion, against a 2.7% fall for the furniture industry as a whole.[2] Hanssem reported 13% growth in Rehaus kitchen, bath and storage sales for April to June 2026 and linked the gain to apartment purchases and renovations.[8] Kitchen and joinery firms working on these homes will order more veneered fronts and panels from 2027.
Traceability Rules and Duties Raise Supply Costs
FMI's model shows compliance costs rising for veneer importers. Medium and large operators face the EU deforestation regulation from 30 December 2026.[1] US duties on cabinets and upholstered wooden products came into force in October 2025.[3] Japan housing starts fell to a 62-year low in 2025, which cuts demand for interior veneer there.[5] Small importers will consolidate or leave the trade as paperwork per shipment grows.
Domestic Cabinet Assembly Opens Orders for Local Slicers
US cabinet and furniture makers are buying more from local suppliers. Ethan Allen said about 75% of the company's custom furniture is made in North American plants.[6] August 2026 brought a 7.6% gain in single-family housing starts in the United States, to an annual rate of 918,000.[4] Furniture makers are a large veneer buyer group, and growth of the wooden furniture market will add case goods that use face veneer. Acrylic panels compete on high-gloss cabinet doors, and growth of the cast acrylic sheets market keeps pressure on veneer pricing in kitchens.
Which country CAGRs are profiled in the veneer sheets market?
Table 7: Country CAGR Comparison for the Veneer Sheets Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 4.6% |
| China | 4.3% |
| South Korea | 3.8% |
| Germany | 3.7% |
| United Kingdom | 3.6% |
| United States | 3.5% |
| Japan | 3.4% |
How do country-level CAGRs compare in the veneer sheets market?
Japan's 740,667 housing starts in 2025 were the lowest in 62 years.[5] In FMI's projection, office work in India gives the quickest country rate, 4.6%, and China follows at 4.3%. South Korea and Germany stay close to the overall pace, at 3.8% and 3.7%. Japan, at 3.4%, has the smallest gain of the group, a little behind the United States and the United Kingdom, as interior markets in all three are mature. Commercial fit-outs in India, hotels in China, luxury towers in South Korea, kitchens in Germany, office refurbishment in the United Kingdom, remodelling in the United States and compact housing in Japan set the order.
- Indian buyers ask for certified, low-VOC veneer.
- Hotel projects and reconstituted veneer plants support sales in China.
- Luxury residential towers in South Korea specify fire-rated veneer.
- Premium kitchens and shopfitting keep German demand close to the global pace.
- British office refurbishment uses veneer to earn green building credits.
- American remodellers buy engineered veneer for panels and casegoods.
- Prefabricated interiors in compact Japanese homes use high-grade hardwood faces.
Full report country CAGRs cover: Exactly three of the seven profiled countries beat the 3.7% global rate, namely India, China and South Korea. Germany matches the global figure, the United Kingdom, the United States and Japan are below, and Latin America, Eastern Europe, and Middle East and Africa have regional tables.
Country-wise Analysis
India Veneer Sheets Market Outlook (2026 to 2036)
In FMI's numbers, demand for veneer sheets in India is expected to grow at a 4.6% CAGR, 0.9 points faster than the market. Office fit-outs and organized furniture manufacturing are adding volume, and buyers ask for FSC-certified and low-VOC materials. Plywood and allied product sales at Greenply, a range that includes decorative veneers, rose 16% in the June quarter of 2026, with volumes up 13.8%.[7] Indian veneer and laminate makers such as Greenlam and Greenply will add pressing capacity for these office and residential projects.
Key takeaway: Organized furniture and office fit-outs keep India at the head of the country table.
China Veneer Sheets Market Outlook (2026 to 2036)
Hotel construction and new reconstituted veneer plants give China an expected 4.3% CAGR. Export cabinetry is recovering, but US duties of 25% on cabinets and vanities from October 2025 limit shipments to the United States.[3] Chinese producers will sell more reconstituted veneer to domestic hotel and residential projects.
Key takeaway: Domestic hotel work offsets export duties for Chinese veneer makers.
South Korea Veneer Sheets Market Outlook (2026 to 2036)
Luxury residential towers in South Korea specify antimicrobial and fire-rated veneers for lobbies and apartments. Hanssem, a leading Korean kitchen and furniture brand, reported 40% growth in the premium Kitchen Bach and Euro Kitchen lines for April to June 2026.[8] Korean kitchen makers will order more veneered fronts as apartment renovations continue, and the country is expected to expand at a 3.8% CAGR.
Key takeaway: Luxury towers keep South Korea just above the global rate.
Germany Veneer Sheets Market Outlook (2026 to 2036)
First-half 2026 sales of German furniture makers fell 2.7% to about EUR 7.7 billion, and kitchen furniture, up 1%, held up best of the segments.[2] Premium kitchens, shopfitting and modular furniture with EN and CE compliance carry most veneer orders. FMI ranks Germany level with the market at a 3.7% CAGR, and German slicers such as Fritz Kohl will need EUDR-ready log data from December 2026.[1]
Key takeaway: Kitchen furniture demand holds Germany at the market's own pace.
United Kingdom Veneer Sheets Market Outlook (2026 to 2036)
Office refurbishment and bespoke joinery drive veneer use in the United Kingdom. Green building credits there reward certified timber. German furniture makers shipped less to British buyers between January and June 2026, the German furniture industry associations reported.[2] British shopfitters and joinery firms are filling more fit-out orders with veneered panels pressed at home. A 3.6% CAGR is projected for the United Kingdom, short of the 3.7% rate for the market as a whole. Joinery firms press these sheets onto boards, and growth of the United Kingdom veneered panels market will carry more veneer into British fit-outs.
Key takeaway: Refurbishment work keeps UK demand steady below the global rate.
United States Veneer Sheets Market Outlook (2026 to 2036)
Remodellers in the United States buy engineered veneers for panels and casegoods, and FMI's table gives the country a 3.5% CAGR. Housing starts ran at an annual rate of 1,275,000 in August 2026.[4] Duties on imported cabinets will move more veneer pressing to domestic plants.[3]
Key takeaway: Tariffs on imported cabinets support domestic veneer buying in the United States.
Japan Veneer Sheets Market Outlook (2026 to 2036)
Compact housing holds Japan to a forecast 3.4% CAGR, the weakest of the profiled set. Housing starts fell 6.5% in 2025, with owner-occupied homes down 7.7%.[5] Compact homes and prefabricated interiors still use high-grade hardwood faces, so value per square metre stays high.
Key takeaway: Falling housing starts leave Japan at the bottom of the country table.
Who are the notable companies in the veneer sheets market?
Decospan, ALPI, Tabu, Fritz Kohl, Columbia Forest Products, Timber Products, Oakwood Veneer, Flexible Materials, Greenlam, Greenply, Turakhia Overseas and Samko Timber are the profiled companies.
Natural and reconstituted veneer brands from Europe face North American and Asian slicers for furniture and fit-out orders. Decospan and Fritz Kohl slice natural hardwood faces, and ALPI and Tabu specialise in reconstituted and dyed veneer. Columbia Forest Products, Timber Products, Oakwood Veneer and Flexible Materials serve North American cabinet and millwork shops. Greenlam, Greenply, Turakhia Overseas and Samko Timber supply Asian furniture and interior buyers. European slicers will need EUDR-ready log data from 30 December 2026.[1]
- European veneer makers: Decospan, ALPI, Tabu and Fritz Kohl.
- North American veneer makers: Columbia Forest Products, Timber Products, Oakwood Veneer and Flexible Materials.
- Asian veneer makers: Greenlam, Greenply, Turakhia Overseas and Samko Timber.
Competitive Benchmarking: Veneer Sheets Market
Table 8: Competitive Benchmarking for the Veneer Sheets Market (qualitative documentation ratings), 2026
| Company | Natural Veneer | Reconstituted Veneer | Paper-Backed Range | Recency |
|---|---|---|---|---|
| Decospan | High | Low | Medium | Low |
| ALPI | Low | High | Medium | Low |
| Columbia Forest Products | High | Low | Medium | Low |
| Greenlam | Medium | Medium | Medium | Low |
| Flexible Materials | Medium | Low | High | Low |
Product detail published by each company sets the rating, which does not measure market share.
Key Developments in the Veneer Sheets Market
- On 17 September 2026, the US Census Bureau reported August housing starts at an annual rate of 1,275,000.[4]
- In September 2026, the German furniture industry associations reported first-half furniture sales of about EUR 7.7 billion, 2.7% below January to June 2025.[2]
- On 10 August 2026, Hanssem reported KRW 11.3 billion of operating profit for the June quarter, with Rehaus sales up 13%.[8]
- On 29 July 2026, Ethan Allen put full-year fiscal 2026 net sales at USD 579.5 million.[6]
- On 24 July 2026, Greenply reported a 20.7% gain in Q1 FY27 consolidated sales, to INR 724.9 crore.[7]
- On 26 April 2026, Salone del Mobile.Milano reported 316,342 visitors to the 2026 fair.[9]
- On 30 January 2026, Japan reported 2025 housing starts of 740,667 units.[5]
- On 17 December 2025, the European Parliament adopted the targeted revision of the EU deforestation regulation.[1]
- On 29 September 2025, the US set Section 232 duties on timber, lumber, cabinets and vanities.[3]
Key Players in the Veneer Sheets Market
European Veneer Makers
- Decospan
- ALPI
- Tabu
- Fritz Kohl
North American Veneer Makers
- Columbia Forest Products
- Timber Products
- Oakwood Veneer
- Flexible Materials
Asian Veneer Makers
- Greenlam
- Greenply
- Turakhia Overseas
- Samko Timber
Veneer Sheets Market - Report Scope
Table 9: Report Scope for the Veneer Sheets Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; end use; wood source; region |
| Quantitative units | USD billion |
| Market definition | Thin decorative sheets of sliced, peeled or reconstituted wood, sold plain or backed with paper, wood or phenolic layers, for furniture, cabinets and interiors. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Decospan, ALPI, Tabu, Fritz Kohl, Columbia Forest Products, Timber Products, Oakwood Veneer, Flexible Materials, Greenlam, Greenply, Turakhia Overseas, Samko Timber |
| Forecast period | 2026 to 2036 |
Veneer Sheets Market - Research Methodology
Table 10: Research Methodology for the Veneer Sheets Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Government statistics, trade rules, company results and furniture trade sources from May 2025 onward. |
| Desk Research | Desk research covers deforestation rules, tariffs, housing permits, refurbishment output and furniture fairs. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 26.4 billion and the 3.7% CAGR from 2026 to 2036. |
| Data Validation | Rule dates, permits and housing data were matched to the authority that published them. |
Veneer Sheets Market by Segments
Veneer Sheets Market segmented by Product Type:
- Paper-Backed
- Wood-Backed
- Laid-Up
- Phenolic-Backed
- Others
Veneer Sheets Market segmented by End Use:
- Commercial
- Residential
Veneer Sheets Market segmented by Wood Source:
- Hardwood
- Engineered or Reconstituted
- Softwood
- Bamboo and Others
Veneer Sheets Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Timber Trade Portal (ATIBT). (2025, December 18). EUDR: the European Parliament adopts the targeted revision of the Regulation and launches a stakeholder consultation. https://www.timbertradeportal.com/en/news/20/eudr-the-european-parliament-adopts-the-targeted-revision-of-the-regulation-and-launches-a-stakeholder-consultation
- [2] Interior Daily. (2026, September 2). German furniture industry records 2.7% sales decline in first half of 2026. https://www.interiordaily.com/article/9868727/german-furniture-industry-records-2-7-sales-decline-in-first-half-of-2026/
- [3] The White House. (2025, September 29). Adjusting Imports of Timber, Lumber, and Their Derivative Products into the United States. https://www.whitehouse.gov/presidential-actions/2025/09/adjusting-imports-of-timber-lumber-and-their-derivative-products-into-the-united-states/
- [4] U.S. Census Bureau. (2026, September 17). Monthly New Residential Construction, August 2026. https://www.census.gov/construction/nrc/pdf/newresconst_202608.pdf
- [5] Nippon.com (Jiji Press). (2026, January 30). Japan Housing Starts Fall to 62-Year Low in 2025. https://www.nippon.com/en/news/yjj2026013001015
- [6] Ethan Allen Interiors Inc. (2026, July 29). Ethan Allen Reports Fiscal 2026 Full Year and Fourth Quarter Results. https://ir.ethanallen.com/news-events/press-releases/detail/318/ethan-allen-reports-fiscal-2026-full-year-and-fourth/
- [7] Greenply Industries Limited. (2026, July 24). Greenply achieves a consolidated revenue of Rs 724.9 crs in Q1 FY27, a 20.7% YoY increase. https://nsearchives.nseindia.com/corporate/GREEN_24072026135950_PRESS_RELEASE_Q1_FY2027.pdf
- [8] Asia Economy. (2026, August 10). Hanssem Posts Q2 Operating Profit of 11.3 Billion Won...13 Consecutive Quarters in the Black. https://view.asiae.co.kr/en/article/2026081020040464514
- [9] Salone del Mobile.Milano. (2026, April 26). Salone del Mobile.Milano 2026: this is how it went. https://www.salonemilano.it/en/articles/salone-del-mobilemilano-2026-how-it-went
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the veneer sheets market during 2026?
- What market size is projected by 2036?
- Which product type holds notable share?
- Which end use holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the veneer sheets market expected in 2026?
Expected 2026 market size is USD 27.4 billion for veneer sheets, up from USD 26.4 billion in 2025. FMI's forecast puts the 2036 size at USD 39.4 billion.
What CAGR is projected for the veneer sheets market through 2036?
Growth of 3.7% CAGR is projected from 2026 to 2036. Office, hotel and kitchen refurbishment supplies most new veneer orders.
Which product type holds a notable market share in 2026?
At 47% share in 2026, paper-backed veneer is expected to lead product type sales. Wood-backed sheets follow at an estimated 18.5%.
Which end use holds a notable market share in 2026?
With 58% share in 2026, commercial use is likely to lead end use sales. Residential use holds 42%.
Which country has a notable expansion outlook through 2036?
India heads the FMI country table on a 4.6% CAGR to 2036. Japan is the slowest at 3.4%.
Who are the key companies in the veneer sheets market?
European makers Decospan, ALPI, Tabu and Fritz Kohl are key suppliers. Columbia Forest Products, Timber Products, Oakwood Veneer, Flexible Materials, Greenlam, Greenply, Turakhia Overseas and Samko Timber complete the group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Paper-Backed
- Wood-Backed
- Laid-Up
- Phenolic-Backed
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Commercial
- Residential
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Wood Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wood Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wood Source, 2026 to 2036
- Hardwood
- Engineered or Reconstituted
- Softwood
- Bamboo and Others
- Y-o-Y Growth Trend Analysis By Wood Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Wood Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use
- By Wood Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use
- By Wood Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use
- By Wood Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use
- By Wood Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Decospan
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ALPI
- Columbia Forest Products
- Greenlam
- Flexible Materials
- Tabu
- Fritz Kohl
- Timber Products
- Oakwood Veneer
- Greenply
- Turakhia Overseas
- Samko Timber
- Decospan
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


