

- Market Size (2026)
- USD 1314.1 Mn
- Forecast (2036)
- USD 2837.2 Mn
- CAGR (2026 to 2036)
- 8.0%
How big is Automated Guided Vehicles (AGV) Market in 2026?
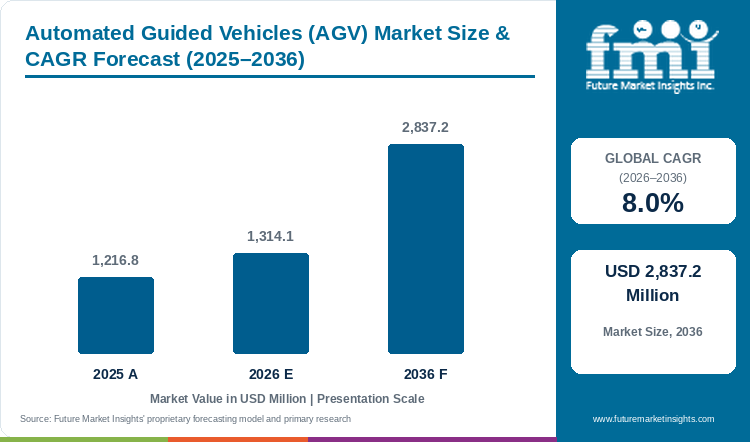
The automated guided vehicles (AGV) market is estimated at USD 1,216.8 million in 2025 and is expected to reach USD 1,314.1 million in 2026. Demand for automated guided vehicles is forecast to grow at an 8% CAGR and reach USD 2,837.2 million by 2036.
Key trends in the automated guided vehicles (AGV) market point to wider use of laser and natural-feature guidance in warehouses, and sales of automated guided vehicles are estimated at USD 1,216.8 million in 2025. FMI analysis shows the automated guided vehicles (AGV) market reaching USD 1,314.1 million in 2026 and USD 2,837.2 million by 2036, at an 8% CAGR between 2026 and 2036. Warehouse operators are now buying driverless transport faster than car plants. In the wider robot field, transport and logistics robots accounted for 117,500 of the almost 250,000 professional service robots sold in 2025, up 21%, the International Federation of Robotics said in September 2026.[1] This growth reflects how warehouse operators now order driverless transport as fleets, which carries AGV use beyond car plants into parcel and retail sites.
Porter's five forces analysis points to a high threat of substitutes and sharper rivalry from forklift makers. Above all, free-roaming mobile robots and automated forklifts compete for the same pallet and tote moves, and truck suppliers are adding autonomy to fleets already on site. For instance, KION acquired 70% of Smart Innovation, a Colruyt subsidiary, to develop autonomous pallet trucks, and the Intelligent Automation Solutions segment reported 17.6% higher sales for January to June 2026.[2] As a result, buyers can now compare fixed-path AGVs with free-roaming options from the truck brand already in the building, which pushes AGV makers to cut commissioning time and price fleet software lower.
Key Market Trends & Insights
- Laser guidance is expected to account for 41.3% of technology type sales in 2026, more than double magnetic guidance at an estimated 19.6%, as reflectors and scanners allow route changes without new floor tape.
- Transportation moves between docks, lines and storage are estimated at 46.8% of application type sales in 2026, with distribution near 31.5%. Faster setup is widening the pool of transport projects. Alongside this, KION cut autonomous vehicle commissioning from weeks to a few days with AI digital twins, the company said in October 2026.[3] Shorter commissioning lowers the cost of each new route, so mid-sized sites can now justify a transport fleet.
- Within vehicle type, unit load carriers are likely to hold 27.9% of 2026 sales, ahead of tow vehicles at about 19.4% and pallet trucks near 18.6%.
- Automotive plants, at an estimated 24.6% of end use sales in 2026, lead logistics at 22.8% on tow trains and line feeding. Even so, US automotive robot installations fell 1% to 13,500 units in 2025, and non-automotive users drove growth.[4] New fleet orders are therefore shifting toward warehouses and food plants, which puts logistics on the faster growth path.
Regional Highlights
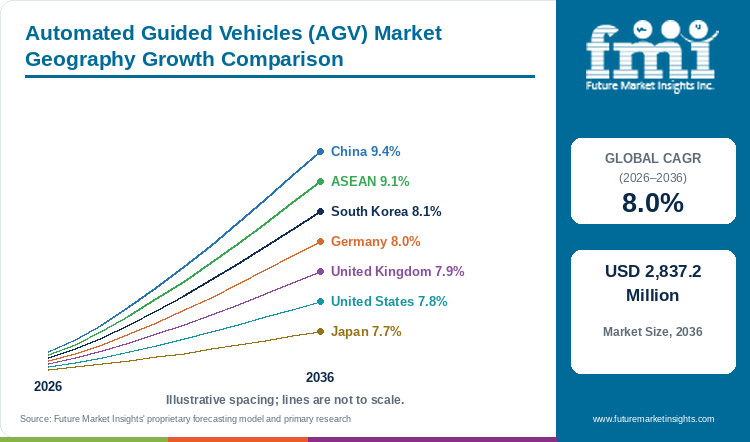
- The 15th Five-Year Plan places robotics at the centre of industrial policy in China, which leads the FMI outlook at 9.4% against the 8% global CAGR.
- ASEAN is forecast to expand at 9.1% as new electronics plants open, South Korea at 8.1% on battery lines, and Germany in line with the global 8%. Growth in three mature markets is projected just under that rate, at 7.9% for the United Kingdom, 7.8% for the United States and 7.7% for Japan.
- Factory automation in the United States is gathering pace again. US industrial robot installations rose 11% to 38,000 units in 2025, the International Federation of Robotics reported in June 2026.[4] Each new robot cell needs a steady parts feed, which adds driverless cart orders at US plants into 2027.
Market Size & Forecast
Table 1: Market Size and Forecast for the Automated Guided Vehicles (AGV) Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1,216.8 million |
| Estimated Market Size in 2026 | USD 1,314.1 million |
| Projected Market Size by 2036 | USD 2,837.2 million |
| CAGR, 2026 to 2036 | 8% |
| Added Revenue, 2026 to 2036 | USD 1,523.1 million |
| Market Expansion Multiple | 2.2x |
Demand for automated guided vehicles is moving toward large multi-site warehouse programmes, which makes order intake uneven from one quarter to the next. For example, KION Intelligent Automation Solutions order intake fell 17.1% to EUR 1.824 billion in January to June 2026 after an exceptional project quarter a year earlier, though segment sales rose 17.6%.[2] Rising sales against lower orders show earlier projects now being delivered, which supports AGV shipments into 2027 even as new tenders slow. Supply is consolidating at the same time. Meanwhile, Toyota Industries agreed on 8 May 2026 to buy 80% of IHI Logistics & Machinery, citing e-commerce growth and the labour shortage in Japan.[5] The deal joins automated storage with a large truck network, giving Japanese buyers one supplier for storage and driverless transport. Behind these deals, parcel and online retail volumes keep rising, and the e-commerce logistics market will expand at an 18.9% CAGR, adding fulfilment sites that need driverless transport. By 2036, FMI estimates that the automated guided vehicles (AGV) market will be USD 1,523.1 million larger than in 2026, more than double the 2026 base. Even so, large up-front costs for smaller plants are the main restraint on near-term orders.
Fleet Software, Physical AI and Robot Density
Software now decides fleet performance. For instance, Amazon said the DeepFleet AI model will improve robot fleet travel time by 10% across a network of more than 300 facilities.[6] A 10% gain in travel time across that many sites shows the return on a fleet now coming as much from routing software as from the vehicles. Likewise, KION reported that a GXO autonomous vehicle fleet at Épinoy in France moved into daily operation after a pilot in early 2026, with on-site deployment time cut by over 60%.[3] Consequently, buyers are asking AGV suppliers for simulation, traffic control and safety software along with the vehicles.
Robot density in factories is rising fast in Asia. In particular, China has about 2 million operational industrial robots and accounts for 54% of global installations, the International Federation of Robotics said in May 2026.[7] Factories with dense robot cells in turn need driverless carts to feed parts between cells. With an 18.1% CAGR forecast for the industrial robotics market, more plants will reach the point of automating internal transport.
Table 2: Fleet, Robot and Deal Indicators for the Automated Guided Vehicles (AGV) Market (units, orders and deals), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Transport and logistics robots sold, 2025 | 117,500 units; up 21% | Driverless logistics demand | [1] |
| KION Intelligent Automation Solutions, H1 2026 | Sales up 17.6%; orders down 17.1% | Warehouse automation project flow | [2] |
| GXO Épinoy autonomous fleet, 2026 | Deployment time cut by over 60% | Faster AGV commissioning | [3] |
| Toyota Industries and IHI Logistics & Machinery | 80% stake; completion April 2027 | Logistics automation in Japan | [5] |
| US industrial robot installations, 2025 | 38,000 units; up 11% | Factory automation in the United States | [4] |
| China operational industrial robots | About 2 million; 54% of global installations | Factory transport demand in China | [7] |
| Amazon robot fleet, July 2025 | 1 million robots; DeepFleet 10% faster travel | Fleet software benchmark | [6] |
Analyst Perspective
“The AGV business is turning from hardware into fleet software, and I believe commissioning speed will matter more to buyers than vehicle price within five years. Forklift groups adding autonomy to existing trucks are the main threat to specialist AGV makers. Specialists that keep a clear lead in positioning accuracy and integration will still secure the complex factory jobs.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the automated guided vehicles (AGV) market segmented?
The market is segmented into technology type, application type, vehicle type, end use, and region. Laser guidance is expected to lead technology type with 41.3% share in 2026, and transportation leads application type with an estimated 46.8%.
By technology type: laser guidance, magnetic guidance, infrared guidance, wire guidance, inertial guided, and optical guided.
By application type: transportation, distribution, and storage.
By vehicle type: unit load carrier, pallet truck, assembly line vehicle, tow vehicle, forklift truck, and light load transporters.
By end use: logistics, healthcare, automotive, manufacturing, food and beverages, and aerospace.
By region: factories, warehouses and hospitals in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does laser guidance lead AGV sales by technology type?
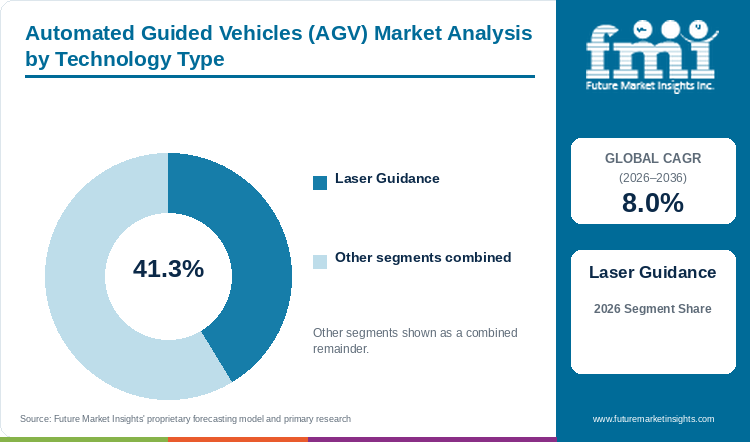
Laser guidance is expected to lead technology type sales with 41.3% share in 2026, ahead of magnetic guidance at an estimated 19.6% and optical guided systems near 14.2%.
Table 3: Technology Type Share for the Automated Guided Vehicles (AGV) Market (percentage share), 2026
| Technology Type | Estimated Share (2026) |
|---|---|
| Laser Guidance | 41.3% |
| Magnetic Guidance | 19.6% |
| Optical Guided | 14.2% |
| Inertial Guided | 11.4% |
| Wire Guidance | 8.1% |
| Infrared Guidance | 5.4% |
| Total | 100.0% |
Table 4: Technology Type Leadership and Market Growth for the Automated Guided Vehicles (AGV) Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8% |
| Leading Segment | Laser Guidance |
Laser scanners let a vehicle find a position to within millimetres and change routes in software, so laser guidance is expected to keep the technology lead in 2026 with 41.3% share. By comparison, magnetic guidance, at an estimated 19.6%, costs less but needs tape or magnets laid in the floor, which slows layout changes. Optical guided systems, near 14.2%, use cameras and printed markers and are gaining in mixed warehouses. Inertial guided units at 11.4% suit outdoor yards and long fixed runs. Wire guidance, about 8.1%, survives in older plants, and infrared guidance at 5.4% serves small indoor fleets. Setup speed now counts as much as positioning accuracy. On the software side, KION is using AI digital twins to set up autonomous fleets in days.[3] Digital setup of this kind favours laser and camera guidance, as routes can be redrawn in software without floor work, so both will keep gaining over the forecast period.
- Reflector-based laser, natural-feature laser and hybrid laser-camera systems make up the laser segment.
- Safety software is the next hurdle for laser-guided fleets in shared aisles. KION is building an AI safety concept with NVIDIA, using the NVIDIA Halos blueprint, for vehicles working alongside people.[3] Certified safety logic would let laser-guided vehicles run faster beside pickers, which opens mixed manual and automated zones to AGV fleets.
Why does transportation lead AGV sales by application type?
Transportation is estimated to lead application type sales with 46.8% share in 2026, with distribution near 31.5% and storage at about 21.7%.
Table 5: Application Type Share for the Automated Guided Vehicles (AGV) Market (percentage share), 2026
| Application Type | Estimated Share (2026) |
|---|---|
| Transportation | 46.8% |
| Distribution | 31.5% |
| Storage | 21.7% |
| Total | 100.0% |
Moving loads between receiving docks, production lines and storage is the core AGV task, and transportation is estimated at 46.8% of application sales in 2026, the largest task group. Behind transportation, distribution, near 31.5%, covers order picking support, sorting and outbound staging in fulfilment centres. Storage, about 21.7%, covers put-away and retrieval runs to racks, and automated storage systems often do that job without vehicles. Suppliers are also regrouping to sell transport and storage as one package. At the same time, Toyota Industries is considering merging the warehouse automation units of Vanderlande and viastore in Europe under Toyota Automated Logistics.[8] A combined European unit could bid for whole warehouse flows, which favours transport fleets linked to storage and conveyor systems. Transport will therefore stay the largest task, as every plant and warehouse moves goods between zones.
- Dock-to-stock moves, line feeding and finished goods transfer make up transportation.
- Fulfilment operators run the largest transport fleets. Amazon delivered the company's 1 millionth robot to a fulfilment centre in Japan in July 2025.[6] A fleet of that size sets the traffic-control standard that other parcel operators now expect from AGV suppliers.
Why do unit load carriers lead AGV sales by vehicle type?
Unit load carriers are likely to lead vehicle type sales with 27.9% share in 2026, ahead of tow vehicles at about 19.4% and pallet trucks near 18.6%.
Table 6: Vehicle Type Share for the Automated Guided Vehicles (AGV) Market (percentage share), 2026
| Vehicle Type | Estimated Share (2026) |
|---|---|
| Unit Load Carrier | 27.9% |
| Tow Vehicle | 19.4% |
| Pallet Truck | 18.6% |
| Forklift Truck | 15.3% |
| Assembly Line Vehicle | 11.2% |
| Light Load Transporters | 7.6% |
| Total | 100.0% |
Point-to-point moves of a single pallet, rack or bin suit most plant and warehouse tasks, so unit load carriers are likely to lead the vehicle mix in 2026 at 27.9%. Behind them, tow vehicles, about 19.4%, pull trains of carts along fixed routes in car and parts plants. Pallet trucks, near 18.6%, are the fastest-changing group, as forklift makers add autonomy to existing models, and KION bought 70% of Smart Innovation to develop autonomous pallet trucks.[2] Autonomous pallet trucks from incumbent forklift brands are likely to take some pallet moves from specialist AGV makers. Forklift trucks at 15.3% handle high racking, and assembly line vehicles at 11.2% carry car bodies and engines through build stations. Light load transporters, an estimated 7.6%, move totes in hospitals and electronics plants. Material handling fleets as a whole, on the other hand, grow more slowly, at a 4.2% CAGR forecast for the material handling equipment market. Even so, unit load carriers will keep the lead as buyers start with simple point-to-point routes.
- Roller-top, scissor-deck and conveyor-top carriers make up the unit load group.
- Consolidation is adding unit load and storage capacity in Japan. Toyota Industries expects the IHI Logistics & Machinery deal to complete on 1 April 2027.[5] Once the deal closes, IHI storage systems and Toyota carriers can be offered as one package to cold-store operators.
Why do automotive plants lead AGV sales by end use?
Automotive plants are estimated to lead end use sales with 24.6% share in 2026, ahead of logistics at about 22.8% and manufacturing near 18.3%.
Table 7: End Use Share for the Automated Guided Vehicles (AGV) Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Automotive | 24.6% |
| Logistics | 22.8% |
| Manufacturing | 18.3% |
| Food and Beverages | 14.1% |
| Healthcare | 10.7% |
| Aerospace | 9.5% |
| Total | 100.0% |
Car plants were the first large AGV users, with tow trains and assembly carriers built into body and final assembly halls, so automotive plants are estimated to hold the largest end use share in 2026, 24.6%. Logistics, about 22.8%, is closing the gap as parcel and retail warehouses automate, and US robot installations outside automotive grew faster than in car plants in 2025.[4] That growth gap points to logistics as the main source of new fleet orders. Manufacturing, near 18.3%, covers electronics, machinery and metal plants. Food and beverages at 14.1% use AGVs in cold stores and bottling halls, healthcare at 10.7% moves meals, linen and drugs in hospitals, and aerospace at 9.5% moves large assemblies. In addition, plant controls tie the vehicles to production systems, and control upgrades will stay frequent with a 6.9% CAGR projected for the industrial automation market. Given that pace, logistics will close in on automotive by the early 2030s.
- Body shop carriers, engine and battery transfer and parts tow trains make up automotive demand.
- Food plants are a fast-growing new outlet. The International Federation of Robotics said robot installations in the US food industry rose 30% in 2025.[4] Bottling and packing halls with more robots will also need carts to move ingredients and finished cases, adding AGV demand outside car plants.
What are the drivers, restraints, and opportunities in the automated guided vehicles (AGV) market?
Labour shortages and growing parcel volumes push plants and warehouses toward driverless transport. High up-front costs hold back smaller buyers, and AI fleet software and autonomous trucks open new orders.
- Driver: Warehouses and factories struggle to hire drivers for repetitive transport tasks, so operators replace manual tugs and pallet jacks with driverless vehicles.
- Restraint: Smaller plants find the cost of vehicles, software and integration hard to justify, and links to existing warehouse systems add risk to each project.
- Opportunity: AI fleet control and simulation cut setup time and let fleets mix vehicle types, which opens new projects in mid-sized warehouses.
Labour Shortages Push Driverless Transport
Demand for automated guided vehicles grows fastest at sites short of drivers. For example, Toyota Industries cited the labour shortage in Japan as a reason for buying IHI Logistics & Machinery.[5] When a forklift group buys an automation maker to address staff gaps, the shortage is shaping supply as well as demand. Sales data confirm the trend. Across the industry, transport and logistics robot sales rose 21% in 2025.[1] In turn, each site that automates one transport route usually adds more routes within a few years.
Up-front Costs Hold Back Smaller Buyers
Producers of AGV fleets face slower orders from buyers with tight budgets. As an example, KION Intelligent Automation Solutions order intake fell 39.6% in the June 2026 quarter against an exceptional project quarter a year earlier.[2] A drop of that size shows how heavily AGV orders rest on a few large projects, and small buyers cannot fill the gap quickly. Payment models are starting to ease that barrier. At the same time, the International Federation of Robotics said traditional sales remain the main channel, though robots-as-a-service is gaining popularity.[1] In time, rental and service models will therefore bring more small plants into the market.
AI Fleet Software Opens New Projects
Growth of the automated guided vehicles (AGV) market will come from software that makes fleets easier to deploy. For instance, KION said ROSSMANN ordered more Robotic Case Picker vehicles after a pilot in October 2026.[3] A repeat order after a pilot shows software-led setup turning trials into fleet orders faster. Similarly, Amazon's DeepFleet model coordinates robot movement across the company's network.[6] As a result, suppliers with simulation and AI traffic control will gain mid-sized warehouse projects first, bringing driverless fleets within reach of regional distributors.
Which country CAGRs are profiled in the automated guided vehicles (AGV) market?
Table 8: Country CAGR Comparison for the Automated Guided Vehicles (AGV) Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 9.4% |
| ASEAN | 9.1% |
| South Korea | 8.1% |
| Germany | 8% |
| United Kingdom | 7.9% |
| United States | 7.8% |
| Japan | 7.7% |
How do country-level CAGRs compare in the automated guided vehicles (AGV) market?
Local supply is cutting automation costs in China. Chinese suppliers provided 57% of industrial robots installed in China in 2024, up from 30% in 2020, which lowers the cost of automating plant transport.[7] On that basis, growth in China is projected by FMI at 9.4%, the fastest rate and 1.4 points clear of the global CAGR. ASEAN follows at 9.1% as electronics and parts plants move into the region. South Korea, at 8.1%, gains from battery and car plant automation. Meanwhile, Germany is in line with the global rate at 8%. The United Kingdom (7.9%) and the United States (7.8%) fall a fraction below the 8% AGV average, and Japan is lowest at 7.7% on a large installed base.
- Chinese robot makers now supply most new installations at home, bringing down the price of a full transport fleet. Lower system cost favours local AGV brands in price-led tenders.
- Electronics and parts makers relocating to Vietnam, Thailand and Malaysia design plants with automated transport from day one, so fleets are bought whole. Suppliers with regional integration teams are set to gain these greenfield contracts.
- Long battery and car lines in South Korea need constant material feeding, which tilts demand toward tow and unit load vehicles. Vendors that meet battery plant safety rules stand to gain.
- In Germany, home market of KION and Jungheinrich, car plants keep buying as retailers move from pilots to fleets. Domestic intralogistics groups hold the advantage, as many buyers already run trucks from these groups.
- British online grocers concentrate new orders on dispatch and storage transfers in large fulfilment centres. That concentration rewards suppliers with fast commissioning in brownfield warehouses.
- Parcel growth and a rebound in factory robots both add US transport routes. With demand split between fulfilment centres and food plants, suppliers that serve both settings will gain.
- A large installed base means most Japanese orders replace ageing fleets in car and electronics plants. Labour shortages keep that replacement steady and favour suppliers with national service networks.
Full report country CAGRs cover: seven rates within a narrow 1.7-point band, China highest and Japan lowest, with regional tables listing every other standard country.
Country-wise Analysis
China Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
Industrial policy is pushing Chinese factories toward full automation. China's 15th Five-Year Plan for 2026 to 2030 puts robotics at the centre of the modern industrial system, the International Federation of Robotics said in May 2026.[7] That policy builds on scale, as China has about 2 million operational industrial robots, roughly 4.5 times the stock in Japan. Over the next decade, sales of automated guided vehicles in China will grow at a 9.4% CAGR, the quickest of the seven countries, as plants link robot cells with driverless transport.
Key takeaway: Policy and robot density put China first.
ASEAN Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
Electronics and car parts makers are opening plants in Vietnam, Thailand and Malaysia, and new plants are designed with automated transport from the start. As greenfield sites buy full fleets, ASEAN will grow at a 9.1% CAGR, above the global rate.
Key takeaway: New plants in ASEAN buy whole fleets at the start.
South Korea Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
Korean battery, chip and car plants run long production lines that need regular material feeding. For this reason, FMI estimates South Korea at an 8.1% CAGR, slightly above the global rate, as new battery lines add tow and unit load vehicles.
Key takeaway: Long battery and car lines in South Korea need constant feeding.
Germany Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
German retailers are moving from pilots to fleets. KION delivered a Robotic Case Picker to a ROSSMANN regional warehouse in October 2026, and the customer ordered more vehicles after the pilot.[3] A repeat order from a large drugstore chain shows retail warehouses joining car plants as AGV buyers. Beyond this, Germany is home to KION and Jungheinrich, and car plants remain large buyers. Taken together, demand for automated guided vehicles in Germany will grow in line with the global rate, an 8% CAGR.
Key takeaway: German growth matches the global rate on car plant and retail orders.
United Kingdom Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
British online grocers and retailers run large automated fulfilment centres, and driverless vehicles move goods between storage and dispatch. FMI expects retail warehouses to carry most new orders in the United Kingdom, which is likely to grow at a 7.9% CAGR.
Key takeaway: Retail fulfilment shapes the United Kingdom.
United States Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
American factories and fulfilment networks are both automating again. US industrial robot installations rose 11% to 38,000 units in 2025, and food industry installations grew 30%.[4] Food plants adding robots at that pace will also need carts and tuggers to move ingredients and cases. In addition, Amazon runs more than 300 facilities and opened a next-generation fulfilment centre in Shreveport, Louisiana.[6] Parcel and retail operators keep adding fleets, so demand for automated guided vehicles in the United States will grow at a 7.8% CAGR.
Key takeaway: US fleet orders come mostly from fulfilment centres.
Japan Automated Guided Vehicles (AGV) Market Outlook (2026 to 2036)
Japanese demand is moving toward cold-chain and storage automation. Toyota Industries signed on 8 May 2026 to buy 80% of IHI Logistics & Machinery, known for automated storage systems built for refrigerated and freezer sites.[5] Domestic consolidation of this kind favours upgrade work in food and freezer warehouses. Japan already has a large AGV base in car and electronics plants, so FMI forecasts the slowest growth in the table for Japan, a 7.7% CAGR.
Key takeaway: Replacement of ageing fleets matters more than new sites in Japan.
Who are the notable companies in the automated guided vehicles (AGV) market?
KUKA, Daifuku, Toyota Industries, Jungheinrich, Hyster-Yale, KION Group, Seegrid, E&K Automation, Swisslog, Omron, AGILOX, Balyo, Murata Machinery, MiR, SSI Schaefer and Transbotics are the profiled companies.
Forklift and intralogistics groups, robotics companies and AGV specialists compete in the market, FMI analysis shows. Among these, KION Group reported H1 2026 sales of EUR 5.687 billion, up 3.5%, and narrowed the 2026 Intelligent Automation Solutions sales outlook to EUR 3,325 million to EUR 3,525 million.[2] Sales growth at the largest intralogistics group, with a firm automation outlook, shows fleet buyers favouring suppliers that also service trucks. Rivals are reorganising to match that reach. Meanwhile, Toyota Industries plans to run warehouse automation in Europe and the United States under the Toyota Automated Logistics name from April 2026.[8] A single brand across Europe and the United States lets Toyota bid for multi-country warehouse programmes against KION. KUKA, Daifuku, Jungheinrich, Hyster-Yale, Seegrid, E&K Automation, Swisslog, Omron, AGILOX, Balyo, Murata Machinery, MiR, SSI Schaefer and Transbotics complete the group.
- Forklift and intralogistics groups: KION Group, Toyota Industries, Jungheinrich, Hyster-Yale, Daifuku and Murata Machinery.
- Robotics and automation companies: KUKA, Swisslog, Omron, MiR and SSI Schaefer.
- AGV specialists: Seegrid, E&K Automation, AGILOX, Balyo and Transbotics.
Competitive Benchmarking: Automated Guided Vehicles (AGV) Market
Table 9: Competitive Benchmarking for the Automated Guided Vehicles (AGV) Market (qualitative ratings), 2026
| Company | Autonomous Trucks | Fleet Software | Warehouse Projects | Recent Activity |
|---|---|---|---|---|
| KION Group | High | High | High | High |
| Toyota Industries | Medium | Low | High | High |
| KUKA | Low | Medium | Medium | Low |
| Daifuku | Low | Low | Medium | Low |
| Jungheinrich | Medium | Low | Medium | Low |
Ratings compare the companies on autonomous trucks, fleet software, warehouse projects and recent activity.
Key Developments in the Automated Guided Vehicles (AGV) Market
- KION showed Physical AI projects with GXO and ROSSMANN at NVIDIA GTC Berlin on 21 October 2026, a sign that AI setup tools are moving from pilots into live warehouses.[3]
- Sales of 117,500 transport and logistics robots in 2025 were reported by the International Federation of Robotics on 30 September 2026; for AGV makers this confirms logistics as the fastest-growing outlet.[1]
- In the half-year report of 30 July 2026, KION set a range of EUR 3,325 million to EUR 3,525 million for 2026 Intelligent Automation Solutions sales, which points to steady fleet deliveries in the second half.[2]
- On 18 June 2026, the International Federation of Robotics reported 38,000 US robot installations for 2025, adding factory sites that will need driverless parts transport.[4]
- Toyota Industries agreed on 8 May 2026 to acquire 80% of IHI Logistics & Machinery, widening the storage and transport range offered to Japanese buyers.[5]
- The place of robotics in the 15th Five-Year Plan of China was set out by the International Federation of Robotics on 5 May 2026, so policy support for plant automation runs through 2030.[7]
- On 11 November 2025, Toyota Industries announced plans to regroup warehouse automation under Toyota Automated Logistics, giving buyers in Europe and the United States one contact for large projects.[8]
- Amazon's announcement of 1 July 2025 covered the company's 1 millionth robot and the launch of the DeepFleet model; for other operators this raises the bar for fleet software.[6]
Key Players in the Automated Guided Vehicles (AGV) Market
Forklift and Intralogistics Groups
- KION Group
- Toyota Industries
- Jungheinrich
- Hyster-Yale
- Daifuku
- Murata Machinery
Robotics and Automation Companies
- KUKA
- Swisslog
- Omron
- MiR
- SSI Schaefer
AGV Specialists
- Seegrid
- E&K Automation
- AGILOX
- Balyo
- Transbotics
Automated Guided Vehicles (AGV) Market - Report Scope
Table 10: Report Scope for the Automated Guided Vehicles (AGV) Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Technology type; application type; vehicle type; end use; region |
| Quantitative units | USD million |
| Market definition | Self-guided material transport vehicles for factories, warehouses and hospitals, including laser, magnetic, optical, inertial, wire and infrared guided units, with fleet management software sold with the vehicles. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | KUKA, Daifuku, Toyota Industries, Jungheinrich, Hyster-Yale, KION Group, Seegrid, E&K Automation, Swisslog, Omron, AGILOX, Balyo, Murata Machinery, MiR, SSI Schaefer, Transbotics |
| Forecast period | 2026 to 2036 |
Automated Guided Vehicles (AGV) Market - Research Methodology
Table 11: Research Methodology for the Automated Guided Vehicles (AGV) Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers guidance technology, fleet software, autonomous trucks, robot density and warehouse projects. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 1,314.1 million and the 8% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Automated Guided Vehicles (AGV) Market by Segments
Automated Guided Vehicles (AGV) Market segmented by Technology Type:
- Laser Guidance
- Magnetic Guidance
- Infrared Guidance
- Wire Guidance
- Inertial Guided
- Optical Guided
Automated Guided Vehicles (AGV) Market segmented by Application Type:
- Transportation
- Distribution
- Storage
Automated Guided Vehicles (AGV) Market segmented by Vehicle Type:
- Unit Load Carrier
- Pallet Truck
- Assembly Line Vehicle
- Tow Vehicle
- Forklift Truck
- Light Load Transporters
Automated Guided Vehicles (AGV) Market segmented by End Use:
- Logistics
- Healthcare
- Automotive
- Manufacturing
- Food and Beverages
- Aerospace
Automated Guided Vehicles (AGV) Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Federation of Robotics. (2026, September 30). Global Sales of Professional Service Robots Surge 24%. https://ifr.org/ifr-press-releases/news/global-sales-of-professional-service-robots-surge-24-percent
- [2] KION GROUP AG. (2026, July 30). KION with positive first half of 2026. https://www.kiongroup.com/en/Press/Press-Releases/Press-Releases-Detail.html?id=358652711
- [3] KION GROUP AG. (2026, October 21). KION showcases how Physical AI delivers measurable customer value at NVIDIA GTC Berlin 2026. https://www.kiongroup.com/en/Press/Press-Releases/Press-Releases-Detail.html?id=312356311
- [4] International Federation of Robotics. (2026, June 18). US Robot Industry Returns to Double Digit Growth. https://ifr.org/ifr-press-releases/news/us-robot-industry-returns-to-double-digit-growth
- [5] Toyota Industries Corporation. (2026, May 8). Notice Concerning Acquisition of Shares of IHI Logistics & Machinery Corporation. https://www.toyota-industries.com/news/2026/05/08/009001/index.html
- [6] Amazon. (2025, July 1). Amazon launches a new AI foundation model to power its robotic fleet and deploys its 1 millionth robot. https://www.aboutamazon.com/news/operations/amazon-million-robots-ai-foundation-model
- [7] International Federation of Robotics. (2026, May 5). China Makes AI-powered Robots Core of National Strategy. https://ifr.org/ifr-press-releases/news/china-makes-ai-powered-robots-core-of-national-strategy
- [8] Toyota Industries Corporation. (2025, November 11). Toyota Industries Corporation to Reorganize its Warehouse Automation Business in Europe and the United States. https://www.toyota-industries.com/news/2025/11/11/008891/index.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the automated guided vehicles (AGV) market during 2026?
- What market size is projected by 2036?
- Which technology type holds notable share?
- Which application type holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the automated guided vehicles (AGV) market expected in 2026?
The automated guided vehicles (AGV) market is expected to reach USD 1,314.1 million in 2026, up from an estimated USD 1,216.8 million in 2025, FMI's analysis shows. Sales of automated guided vehicles are projected to reach USD 2,837.2 million by 2036.
What CAGR is projected for the automated guided vehicles (AGV) market through 2036?
Demand for automated guided vehicles is projected to grow at an 8% CAGR through 2036. Labour shortages, parcel growth and AI fleet software carry that growth.
Which technology type holds a notable market share in 2026?
Laser guidance is expected to lead with 41.3% share in 2026. Magnetic guidance follows at an estimated 19.6%.
Which application type holds a notable market share in 2026?
Transportation will lead with an estimated 46.8% share. Distribution holds about 31.5%.
Which country has a notable expansion outlook through 2036?
FMI projects China to grow fastest, at a 9.4% CAGR. ASEAN is next at 9.1%.
Who are the key companies in the automated guided vehicles (AGV) market?
KION Group, Toyota Industries, Jungheinrich, Hyster-Yale, Daifuku and Murata Machinery lead the forklift and intralogistics groups, and KUKA, Swisslog, Omron, MiR and SSI Schaefer lead the robotics companies. Seegrid, E&K Automation, AGILOX, Balyo and Transbotics make up the AGV specialist group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Technology Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Technology Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Technology Type, 2026 to 2036
- Laser Guidance
- Magnetic Guidance
- Infrared Guidance
- Wire Guidance
- Inertial Guided
- Optical Guided
- Y-o-Y Growth Trend Analysis By Technology Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application Type, 2026 to 2036
- Transportation
- Distribution
- Storage
- Y-o-Y Growth Trend Analysis By Application Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Type, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vehicle Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vehicle Type, 2026 to 2036
- Unit Load Carrier
- Pallet Truck
- Assembly Line Vehicle
- Tow Vehicle
- Forklift Truck
- Light Load Transporters
- Y-o-Y Growth Trend Analysis By Vehicle Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Logistics
- Healthcare
- Automotive
- Manufacturing
- Food and Beverages
- Aerospace
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Technology Type
- By Application Type
- By Vehicle Type
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- KION Group
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Toyota Industries
- KUKA
- Daifuku
- Jungheinrich
- Hyster-Yale
- Murata Machinery
- Swisslog
- Omron
- MiR
- SSI Schaefer
- Seegrid
- E&K Automation
- AGILOX
- Balyo
- Transbotics
- KION Group
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


