

- Market Size (2026)
- USD 48.8 Bn
- Forecast (2036)
- USD 304.4 Bn
- CAGR (2026 to 2036)
- 20.1%
How big is the 3D printing market in 2026?
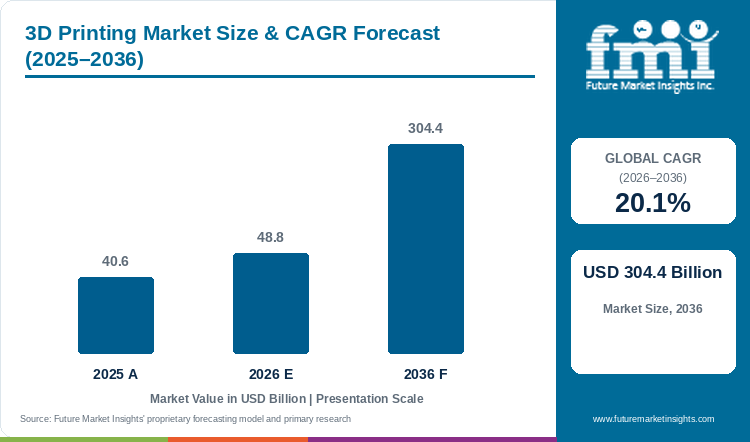
Demand is projected to expand at 20.1% CAGR from 2026 to 2036. Market value rises from USD 40.6 billion in 2025 to USD 48.76 billion in 2026 and USD 304.44 billion by 2036. [1]
Demand is estimated at USD 48.76 billion in 2026 and projected to reach USD 304.44 billion by 2036, at a CAGR of 20.1% from 2026 to 2036. [1] 3D printing gives manufacturers another route to producing geometry that may be difficult or uneconomic through a conventional process, but the commercial decision concerns the complete part rather than the printed shape alone. Build preparation, material behavior, finishing and inspection determine whether a design can move into repeat production. [2][3][4][5] The relationship with manufacturing execution systems becomes relevant when additive work needs to sit within a wider production record, while service providers offer an alternative to owning equipment for every application. Medical-device examples show how patient-specific and complex designs can use additive methods, although product requirements continue to govern the manufacturing route. [3] Printer demand therefore develops alongside software and support that make the process repeatable, with production parts reflecting an opportunity beyond early prototyping. Buyers compare production quantity, geometry and the finished component's requirements before selecting a technology. Over the forecast period, measurement and application knowledge are likely to remain important conditions for scaling use from an initial build to dependable manufacturing. [1][4][5]
Key Market Trends and Insights
- Production adoption places more emphasis on build preparation, finishing and inspection, because the printed geometry must become a component suitable for its intended use. [3][4][5]
- Measurement and monitoring remain relevant to additive manufacturing, helping teams examine how process conditions relate to the quality of a completed build. [4]
- Service and software offerings develop alongside printer demand, giving users options for preparing builds and obtaining parts without owning every required manufacturing system. [1]
Regional Highlights
- China and India have the strongest published growth profiles, with manufacturing modernization and application development supporting the use of additive methods across industrial tasks. [1]
- Germany's industrial environment supports demand for application-specific equipment and repeatable processes, making standards terminology and measurement relevant to supplier comparison. [1][2][4]
- US medical-device applications illustrate the relationship between design flexibility and manufacturing requirements, with additive production serving several different types of regulated products. [3]
Market Size and Forecast
Table 1: Value outlook for the 3D printing market
| Metric | Value |
|---|---|
| 2025 market value | USD 40.6 billion [1] |
| 2026 market value | USD 48.76 billion [1] |
| 2036 market value | USD 304.44 billion [1] |
| CAGR 2026 to 2036 | 20.1% [1] |
| Revenue increase 2026 to 2036 | USD 255.68 billion [1] |
| Market expansion 2026 to 2036 | 6.24 times [1] |
The projected 20.1% CAGR from 2026 to 2036 depends on extending additive capability into a repeatable application route. Manufacturers need to select materials and finishing methods that suit the component, while inspection confirms that the build meets its intended requirement. Computer-aided engineering can support the design assessment before printing, and service suppliers can help users evaluate a process without purchasing equipment for every project, making software and application support relevant alongside the hardware outlook. [1][2][3][4][5]
What does production readiness require beyond a completed 3D print?
Additive manufacturing standards establish a common process vocabulary, while FDA documentation illustrates the use of digital designs for complex and patient-specific devices. NIST examines measurement and real-time monitoring, and the Department of Energy explains different printing processes. These references place printer selection within a broader application route, where material, process control and the finished part's requirement remain necessary to evaluate production readiness. [2][3][4][5]
Table 2: Industry evidence relevant to the 3D printing market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Process terminology | ISO/ASTM 52900 defines additive manufacturing terms | Comparable descriptions support process selection | [2] |
| Medical applications | FDA describes complex and patient-specific device designs | Geometry must meet the product requirement | [3] |
| Process measurement | NIST studies real-time monitoring of additive manufacturing | Build information supports quality assessment | [4] |
Analyst Perspective
"3D printing has moved beyond prototype use and is becoming part of production planning. Manufacturers need to assess equipment alongside material selection and the requirements of the finished part, so that the production process can be repeated consistently for the intended application." [1]
— Sudip Saha, Principal Consultant for Technology, FMI
How is the 3D printing market segmented?
The market is segmented by Component, Technology, Application, Industry, and Region.
By component, coverage includes 3D Printers, 3D Printing Services, 3D Printing Software, Consulting Services, Support Services, Others. By technology, coverage includes Digital Light Processing (DLP), Direct Metal Laser Sintering (DMLS), Electron Beam Melting (EBM), Fused Deposition Modelling (FDM), Selective Laser Sintering (SLS), Stereolithography, Others. By application, coverage includes Production Parts, Prototypes, Tools & Fixtures. By industry, coverage includes Aerospace & Aeronautics, Automotive, Consumer Goods, Healthcare & Medical Devices, Industrial, Others. Regional coverage follows the report's defined geographic markets. [1]
Why does the 3D printers segment lead demand within the component category?
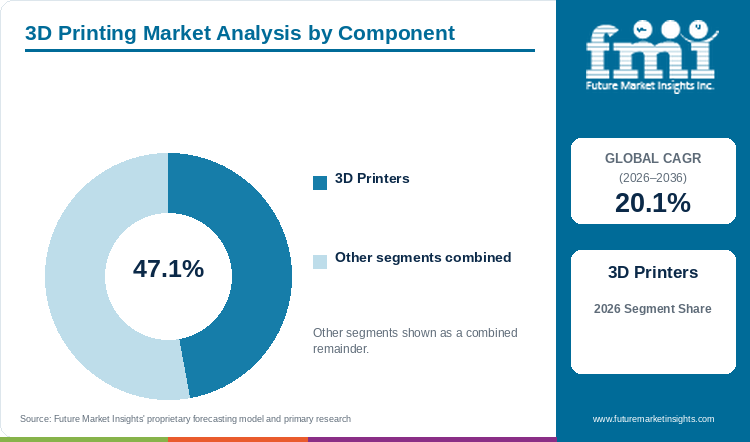
The 3D printers segment accounts for 47.1% of component demand in 2026. [1]
Printers provide the physical production capability within the additive manufacturing ecosystem, making them a central purchase when an organization brings a defined process in-house. The system needs to suit the selected material and geometry, while preparation and finishing remain part of the application route rather than optional additions after a machine has been chosen. [2][3][5] Industrial users can compare throughput and build size with the intended production task, although a system's usefulness also depends on the support needed to make repeat work dependable. Design tasks may require a professional workstation environment, connecting hardware investment with preparation software and operator capability. The segment's position therefore reflects the need for a functioning production system rather than printer ownership alone. [1][4]
- The 3D printers segment is estimated to account for 47.1% of component demand in 2026, reflecting the equipment needed to establish a defined additive manufacturing process within the user's own operation. [1]
- Printer selection should follow material and part requirements, while preparation, finishing and process support remain relevant to a repeatable manufacturing route. [2][3][4][5]
Table 3: Leading component share in 2026
| Segment | Share of demand |
|---|---|
| 3D printers | 47.1% [1] |
| Other component segments | 52.9% [1] |
| Total | 100.0% |
Why does the Production parts segment lead demand within the application category?
The Production parts segment accounts for 47.8% of application demand in 2026. [1]
Production parts require additive output to perform a defined role beyond showing the appearance of a proposed design, bringing material properties, dimensions and inspection into the purchasing decision. The category's strong position reflects the opportunity to use additive methods for a finished component, although qualification and the route to a repeatable build remain application-specific. [1][2][3][4] Medical-device examples demonstrate how complex and patient-specific geometry can create useful applications, while industrial users assess the economics of the complete process against conventional alternatives. Software, finishing and measurement can influence that comparison as much as build speed, making the supplier's ability to support a reliable part-production route central to adoption rather than the novelty of the manufacturing method. [3][4][5]
- The Production parts segment is estimated to account for 47.8% of application demand in 2026, as additive methods extend beyond design demonstration into components intended to perform a defined practical function. [1]
- The finished part needs suitable inspection and process control, with application requirements determining how a printed build can enter dependable production. [3][4]
What are the drivers, restraints, and opportunities in the 3D printing market?
Driver
Complex geometry and changing design requirements can make additive methods useful where a conventional production setup would be difficult or costly to modify. Manufacturers can evaluate that flexibility against the particular part's quantity, material and performance requirement, while software prepares the geometry for the selected process. Demand grows when the complete route delivers an application benefit, connecting design freedom with a finished component that the user can produce, inspect and use consistently. [1][2][3][4][5]
Restraint
The route from a successful demonstration to repeat production can require substantial work on material control, finishing and inspection, limiting adoption when a buyer considers only the printer's headline capability. Different processes also carry different operating requirements, so a system selected for one application may not suit another. These conditions raise the need for application support and practical process knowledge, particularly when the finished component must meet demanding quality or performance requirements. [2][3][4][5]
Opportunity
Application support can help users identify parts that benefit from additive methods and develop a workable route from design to finishing and inspection. Suppliers that connect preparation software, process knowledge and services can broaden access without requiring every buyer to establish the same equipment base. Industrial robotics may support selected handling tasks around the process, while the commercial opportunity remains tied to delivering repeatable parts that meet the user's actual manufacturing requirement. [1][2][3][4][5]
Which country CAGRs are profiled in the 3D printing market?
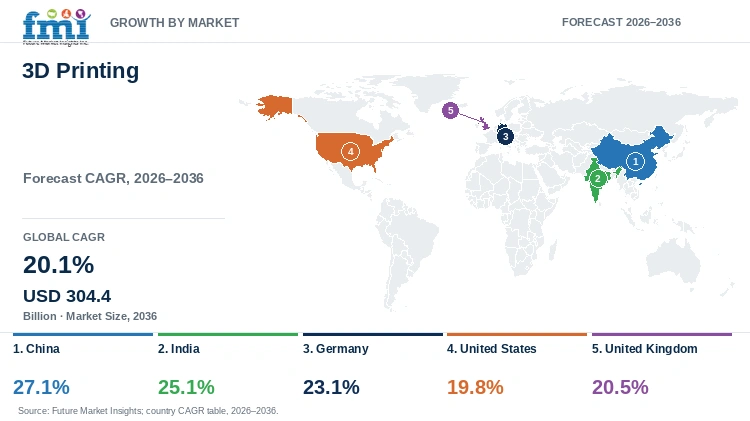
Table 4: Country CAGR comparison for the 3D printing market
| Country or market | CAGR 2026 to 2036 |
|---|---|
| China | 27.1% [1] |
| India | 25.1% [1] |
| Germany | 23.1% [1] |
| United States | 19.8% [1] |
| United Kingdom | 20.5% [1] |
Country-wise Analysis
China
China's large manufacturing base creates opportunities to use additive methods for complex components, tooling and development work, although production adoption requires more than installing a printer. Manufacturers need to connect material handling, build preparation and inspection with a repeatable process, particularly when the finished part must perform consistently beyond the initial demonstration. [1][3][4] Demand is projected at a CAGR of 27.1% from 2026 to 2036, with manufacturing modernization supporting the outlook. Suppliers can address this requirement through application-specific systems and support, while buyers compare additive production with the conventional route for the particular part, assessing geometry, production quantity and finishing requirements before deciding where a layered manufacturing method offers a useful commercial advantage. [2][5]
India
Indian manufacturers and engineering teams can use 3D printing to develop tooling and components without committing immediately to a conventional production setup, giving the technology a practical role in product development and smaller production runs. The decision still needs to account for material behavior and the work required after printing, since a completed build is only one stage in delivering a usable part. [1][4][5] The market is projected to grow at a CAGR of 25.1% from 2026 to 2036, supported by manufacturing modernization and wider application knowledge. Buyers can begin with a defined part requirement and compare printer, software and service options, while training and process control determine how effectively an initial project can extend into repeat production. [2]
Germany
Germany's industrial equipment and automotive development environment supports demand for additive systems that fit a disciplined engineering and production workflow. Buyers need to connect design freedom with practical material and inspection requirements, because a complex shape only creates value when the resulting component meets its intended operating conditions. [1][3][4] A 23.1% CAGR from 2026 to 2036 is projected for the market, with industrial applications supporting the outlook. Standards terminology can help organizations compare processes consistently, while measurement and monitoring provide the information needed to examine build quality. Suppliers therefore compete through the complete application route, including preparation and finishing, rather than presenting printer speed alone as sufficient evidence that a production requirement can be met. [2][5]
United States
Medical devices provide a clear US example of how additive manufacturing can serve complex or patient-specific designs while remaining subject to product and process requirements. FDA documentation describes patient-matched design, material controls and device-testing considerations, making the link between digital geometry and an appropriate manufacturing route relevant to adoption. [3] The broader market is projected at a CAGR of 19.8% from 2026 to 2036, with demand extending across development, tooling and production. NIST's monitoring work also shows the importance of measurement within a build, while industrial users compare the finished part's requirement with material, post-processing and inspection capabilities before deciding whether to purchase equipment or use an external additive manufacturing service. [1][4][5]
United Kingdom
UK engineering and manufacturing users can evaluate additive methods through the particular design problem they need to solve, whether that concerns a complex component, a tool or an early prototype. A printer's flexibility can make design changes easier, but the procurement decision still needs a clear route from the digital file to the finished and inspected part. [1][3][5] Demand is forecast at a CAGR of 20.5% from 2026 to 2036, with application knowledge and service support influencing adoption. Buyers can compare an internal system with outsourced printing when production volumes or material requirements vary, while common process terminology helps the engineering and purchasing teams discuss the same manufacturing method rather than treating every form of 3D printing as interchangeable. [2][4]
Who are the notable companies in the 3D printing market?
Stratasys; 3D Systems; Materialise; Voxeljet; Autodesk
Competitive Benchmarking
Stratasys, 3D Systems and Voxeljet provide additive equipment and related production offerings, while Materialise and Autodesk add software or service roles within the same ecosystem. Those activities address different purchasing decisions, from establishing an internal process to preparing a build or obtaining an externally produced part. Buyers can compare the supplier's technology and application support with the intended material and geometry, retaining the complete finished-part requirement as the basis for choosing equipment, software and services. [1][2][3][4][5]
Table 5: Competitive positioning for the 3D printing market
| Company | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Stratasys | Additive manufacturing systems | Printer systems and related production offerings. [1] |
| 3D Systems | Additive equipment and solutions | Printing systems and application-oriented additive services. [1] |
| Materialise | Additive software and services | Build preparation and additive manufacturing service roles. [1] |
| Voxeljet | Industrial 3D printing | Industrial printing systems and associated production services. [1] |
| Autodesk | Design and manufacturing software | Software supports digital preparation within the additive ecosystem. [1] |
Key Developments in the 3D Printing Market
- ISO confirmed ISO/ASTM 52900:2021 in 2025, retaining a common vocabulary for additive manufacturing processes and providing an established reference for technology descriptions. [2]
- NIST's current real-time monitoring program examines additive manufacturing measurement, reflecting the continuing importance of linking build information with part-quality assessment. [4]
- FDA's additive-manufacturing guidance addresses patient-matched design, manufacturing controls and device testing, illustrating the role of complex and patient-specific design within an appropriate manufacturing route. [3]
Key Players in the 3D Printing Market
- Stratasys
- 3D Systems
- Materialise
- Voxeljet
- Autodesk
3D Printing Market Report Scope
Table 6: Report coverage for the 3D printing market
| Attribute | Coverage |
|---|---|
| Market | 3D Printing Market |
| Currency and unit | USD billion; market revenue |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Segmentation | Component, Technology, Application, Industry |
| Country profiles | China; India; Germany; United States; United Kingdom |
| Competitive coverage | Stratasys; 3D Systems; Materialise; Voxeljet; Autodesk |
| Geographic coverage | North America, Latin America, Europe, East Asia, South Asia and Pacific, Middle East and Africa |
3D Printing Market Research Methodology
Table 7: Research methods for the 3D printing market
| Method | Approach |
|---|---|
| Market definition | Revenue coverage is defined around 3D printing offerings and their related commercial services, with adjacent markets retained as context. |
| Desk research | Public FMI outlooks, direct product documentation, institutional publications and official guidance provide the source base. |
| Segment assessment | Categories are assessed against their functional role, purchasing decisions and reported market structure, with shares kept within their own segmentation axes. |
| Country assessment | Country demand is examined through local customer requirements, industry composition and implementation conditions, with a consistent 2026 to 2036 forecast period. |
| Competitive comparison | Participants are compared through documented offerings and business roles; product features and service models are distinguished from market-share rankings. |
| Forecast assessment | The outlook considers adoption, replacement, integration effort and commercial constraints, expressing monetary forecasts and segment estimates in consistent units. |
3D Printing Market by Segments
3D Printing Market segmented by Component:
- 3D Printers
- 3D Printing Services
- 3D Printing Software
- Consulting Services
- Support Services
- Others
3D Printing Market segmented by Technology:
- Digital Light Processing (DLP)
- Direct Metal Laser Sintering (DMLS)
- Electron Beam Melting (EBM)
- Fused Deposition Modelling (FDM)
- Selective Laser Sintering (SLS)
- Stereolithography
- Others
3D Printing Market segmented by Application:
- Production Parts
- Prototypes
- Tools & Fixtures
3D Printing Market segmented by Industry:
- Aerospace & Aeronautics
- Automotive
- Consumer Goods
- Healthcare & Medical Devices
- Industrial
- Others
3D Printing Market by Region
North America
- United States
- Canada
- Mexico
Latin America
- Brazil
- Chile
- Rest of Latin America
Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
Eastern Europe
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
East Asia
- China
- Japan
- South Korea
South Asia and Pacific
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
Middle East & Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
Research Sources and Bibliography
[1] Future Market Insights. Accessed 14 October 2026. 3D Printing Market
[2] International Organization for Standardization. Accessed 14 October 2026. ISO/ASTM 52900: additive manufacturing terminology
[3] US Food and Drug Administration. Accessed 14 October 2026. Technical considerations for additive manufactured medical devices
[4] National Institute of Standards and Technology. Accessed 14 October 2026. Metrology for real-time additive manufacturing monitoring
[5] US Department of Energy. Accessed 14 October 2026. How 3D printers work
This Report Answers
- How big is the 3D printing market in 2026?
- What is the outlook for the 3D printing market through 2036?
- Which component segment is highlighted?
- Which markets are included in the growth comparison?
- Which participants are included in the competitive assessment?
Frequently Asked Questions
How big is the 3D printing market in 2026?
The market is estimated at USD 48.76 billion in 2026, compared with USD 40.6 billion in 2025. [1]
What is the outlook for the 3D printing market through 2036?
Revenue is projected to reach USD 304.44 billion by 2036, with a CAGR of 20.1% from 2026 to 2036. [1]
Which component segment is highlighted?
The 3D printers segment accounts for an estimated 47.1% share in 2026, reflecting the purchasing conditions described in the segment analysis. [1]
Which markets are included in the growth comparison?
The comparison profiles China, India, Germany, United States, United Kingdom and presents their demand outlooks for 2026 to 2036. [1]
Which participants are included in the competitive assessment?
The assessment includes Stratasys, 3D Systems, Materialise, Voxeljet, Autodesk, with positioning based on each participant's documented business role. [1]
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Component, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Component, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Component, 2026 to 2036
- 3D Printers
- 3D Printing Services
- 3D Printing Software
- Consulting Services
- Support Services
- Others
- Y-o-Y Growth Trend Analysis By Component, 2021 to 2025
- Absolute $ Opportunity Analysis By Component, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Digital Light Processing (DLP)
- Direct Metal Laser Sintering (DMLS)
- Electron Beam Melting (EBM)
- Fused Deposition Modelling (FDM)
- Selective Laser Sintering (SLS)
- Stereolithography
- Others
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Production Parts
- Prototypes
- Tools & Fixtures
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Industry, 2026 to 2036
- Aerospace & Aeronautics
- Automotive
- Consumer Goods
- Healthcare & Medical Devices
- Industrial
- Others
- Y-o-Y Growth Trend Analysis By Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Component
- By Technology
- By Application
- By Industry
- By Country
- Market Attractiveness Analysis
- By Country
- By Component
- By Technology
- By Application
- By Industry
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Component
- By Technology
- By Application
- By Industry
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Component
- By Technology
- By Application
- By Industry
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Stratasys
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- 3D Systems
- Materialise
- Voxeljet
- Autodesk
- Stratasys
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


