
- Market Size (2026)
- USD 97.5 Bn
- Forecast (2036)
- USD 174.6 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is Aluminum Extrusion Market in 2026?
Assessed at USD 92.0 billion in 2025 and progressing to USD 97.5 billion in 2026, the aluminum extrusion market valuation is on course to reach USD 174.6 billion by 2036, supported by a forecast-period CAGR of 6.0%.
The global aluminum extrusion market was valued at USD 92.0 billion in 2025 and is estimated to reach USD 97.5 billion in 2026. The market is projected to reach USD 174.6 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.0% between 2026 and 2036. FMI demand analysis indicates that custom solid extruded profiles are projected to capture 56.0% of 2026 demand, since flat-die extrusion avoids bridge-mandrel tooling expense while delivering high section modulus for industrial framing and solar mounting rails. The demand for extruded aluminum profiles is supported by domestic primary metal reshoring and downstream fabrication pull, with the U.S. Department of Energy awarding USD 500 million in 2025 to advance construction of a primary aluminum smelter as U.S. net downstream aluminum imports reached 2.46 million metric tons [1]. That multi-sector industrial consumption separates the category from the aluminum curtain wall sector at an 8.2% CAGR, given that facade glazing tracks commercial tower starts while extrusion press bookings also absorb automotive crash-box and utility solar rail orders. Manufacturers are also investing in regional press rationalization and low-carbon billet remelting to protect operating margins, as Norsk Hydro ASA announced the restructuring of five European extrusion plants in November 2025 to concentrate volume inside automated automotive and industrial press facilities [2]. Architectural facade fabricators and automotive tier-one suppliers award multi-year extrusion contracts on verified low-carbon billet declarations and tight dimensional tolerances, and extruders operating large-circle presses with integrated anodizing retain those accounts through 2036.
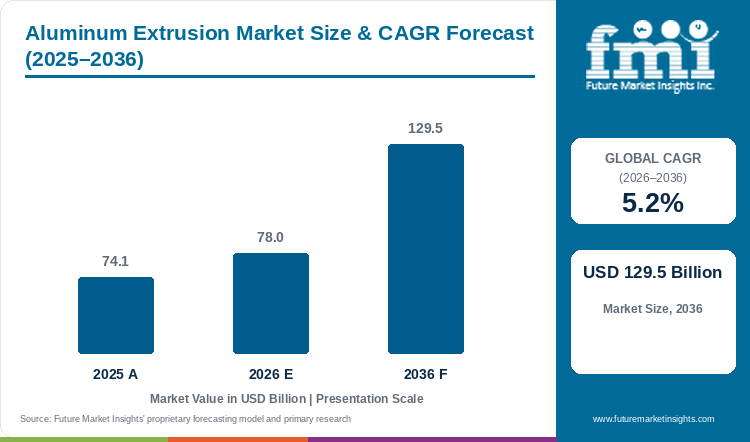
Key Market Trends & Insights
- By product shape profile: Custom Solid Extruded Profiles hold an estimated 56.0% share in 2026 given that solid channels and heat-sink fins extrude rapidly through low-cost flat dies.
- By aluminum alloy series: 6000 Series Al-Mg-Si (6063 and 6061 plus 6082 Structural) represents a projected 68.0% in 2026 as magnesium-silicon precipitates allow press-quench tempering directly at the runout table.
- By surface finish treatment: Mill Finish As-Extruded accounts for an anticipated 48.0% in 2026 since industrial framing and hidden automotive structural beams enter CNC machining without decorative coating.
- By end-use industry: Commercial building windows and curtain-wall facades secure a forecast 46.0% in 2026 owing to strict commercial thermal-break envelope regulations.
- By billet feedstock source: Primary Low-Carbon Smelter Billet commands an estimated 52.0% in 2026 through tight iron-impurity limits required for high-surface-quality anodizing and crash-energy absorption.
Regional Highlights
- Top national expansion: Poland leads national growth projections at a 6.6% CAGR through 2036 under European automotive battery-tray fabrication and architectural window export expansion.
- Broader country progression: The United States tracks at a 6.5% CAGR ahead of Canada at 6.3% and the United Kingdom at 6.2%, while Germany advances at 5.8% and Italy progresses at 5.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Aluminum Extrusion Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 92.0 billion |
| Estimated Market Size in 2026 | USD 97.5 billion |
| Projected Market Size by 2036 | USD 174.6 billion |
| CAGR, 2026 to 2036 | 6.0% |
| Added Revenue, 2026 to 2036 | USD 77.1 billion |
Architectural facade contractors and utility solar developers face rising structural stiffness requirements that stamped steel sheet cannot satisfy without excessive weight penalties. When commercial builders or automotive OEMs substitute multi-hollow aluminum extrusions for welded steel assemblies, part consolidation reduces secondary welding labor and lowers structural mass across aluminium cladding systems. In January 2026, the U.S. Geological Survey Mineral Commodity Summaries reported that U.S. primary aluminum smelter output stood at 683,500 metric tons and domestic alumina production reached 710,000 metric tons in 2025, prompting North American extruders to expand secondary billet cast-house capacity [3]. Consequently, procurement directors lock in multi-year billet conversion contracts indexed to regional Midwest and Rotterdam duty-paid premiums.
Extruded Billet Tonnage and Press Utilization Sizing
Table 2: Extruded Billet Tonnage and Press Utilization Sizing for the Aluminum Extrusion Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 92.0 | 97.5 | 174.6 |
| Global extruded profile shipment volume (million metric tons) | 30.8 to 32.2 | 32.5 to 34.0 | 54.5 to 57.8 |
| Secondary & recycled billet feedstock share (%) | 42.0% to 45.0% | 44.0% to 48.0% | 58.0% to 64.0% |
| Average realized extruded profile value per metric ton (USD) | 2,880 to 3,020 | 2,910 to 3,060 | 3,050 to 3,240 |
Operational note: Global extruded profile volume ranges apply commercial billet-to-profile recovery yields of 78% to 84% across direct and indirect hydraulic extrusion presses rated from 1,600 to 6,500 metric tons.
High-tonnage direct extrusion presses rely on precise billet preheating between 450 and 500 degrees Celsius so magnesium-silicon alloys flow uniformly through multi-cavity porthole dies. As documented in European Aluminium's January 2026 Action Plan, Europe's aluminum value chain encompasses 600 industrial plants processing 9 million metric tons annually while deriving 78% of smelter electricity from renewable sources [4]. Integrated extruders pair induction billet heaters with liquid-nitrogen die cooling to boost ram exit speeds across aluminum profile enclosures and architectural mullion lines.
Press Line Expenditure & Regional Trade Intensity
Table 3: Global Production and Press Line Output Indicators for the Aluminum Extrusion Market (USD and tonnage), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Active commercial hydraulic extrusion lines globally (presses) | 6,400 | 6,580 | 8,450 |
| Average annual revenue per commercial extrusion press (USD million) | 14.4 | 14.8 | 20.7 |
| EV & hybrid automotive extruded aluminum intensity (kg per vehicle) | 46.0 to 58.0 | 49.0 to 62.0 | 72.0 to 88.0 |
| 6000-series alloy share of total extruded billet consumption (%) | 67.5% | 68.0% | 71.0% |
Table 4: Industrial Extrusion Press & End-Use Allocation Indicators for the Aluminum Extrusion Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 97.5 billion | 2026 global extruded profile revenue baseline |
| U.S. primary aluminum smelter output, 2025 | 683,500 metric tons | USGS Mineral Commodity Summaries 2026 & DOE OCED baseline |
| European Union aluminum trade deficit, 2024 | EUR 11.1 billion | Eurostat March 2025 extra-EU aluminium trade balance |
| Building and Construction segment revenue, 2026 | USD 44.9 billion | 46.0% end-use industry allocation across windows and facades |
Regional billet deficits across Europe and North America compel architectural and industrial extruders to balance imported primary metal against domestic closed-loop scrap remelting. Eurostat trade statistics published in March 2025 show that the European Union recorded an aluminum trade deficit of EUR 11.1 billion in 2024 as imports from Norway reached EUR 4.4 billion and shipments from China totaled EUR 3.9 billion [5]. Fabricators supplying aluminum honeycomb panels and precision curtain-wall transoms actively install in-house homogenizing furnaces to convert local post-consumer scrap into prime 6063 extrusion billets.
Analyst Perspective
"Commercial contractors and automotive platform buyers no longer procure aluminum extrusions purely on per-ton metal conversion fees; they buy verified low-carbon billet certificates, multi-void die engineering, and post-extrusion CNC fabrication under one roof. Extruders operating 3,500-ton and larger presses with integrated thermal-break assembly and robotic battery-tray welding will capture recurring OEM program awards through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the aluminum extrusion market segmented?
The aluminum extrusion market is segmented by product shape profile, aluminum alloy series, surface finish treatment, end-use industry, and billet feedstock source. In 2026, Custom Solid Extruded Profiles are projected at 56.0%, 6000 Series Al-Mg-Si at 68.0%, Mill Finish As-Extruded at 48.0%, Building and Construction at 46.0%, and Primary Low-Carbon Smelter Billet at 52.0%.
By product shape profile: Custom Solid Extruded Profiles, Hollow Tubular Profiles, and Semi-Hollow Profiles and Precision Architectural Shapes.
By aluminum alloy series: 6000 Series Al-Mg-Si Structural and 7000 Series Al-Zn High-Strength Aerospace. It also covers 1000 and 3000 Series Thermal Heat Sinks and 2000 and 5000 Series Marine.
By surface finish treatment: Mill Finish As-Extruded and Anodized Clear Champagne and Bronze. It also includes Electrostatic Powder-Coated Architectural Colors and Electrophoretic Liquid Painted Finishes.
By end-use industry: Commercial Windows and Facades and Automotive and Transportation Structures. It also spans Solar PV Mounting Structures and Electrical and Electronics Heat Sinks.
By billet feedstock source: Primary Low-Carbon Smelter Billet and Post-Consumer Recycled Scrap Billet. It also covers Pre-Consumer Process Scrap Billet and Closed-Loop OEM Toll-Remelt Billet.
Why do Custom Solid Extruded Profiles lead the product shape profile category?
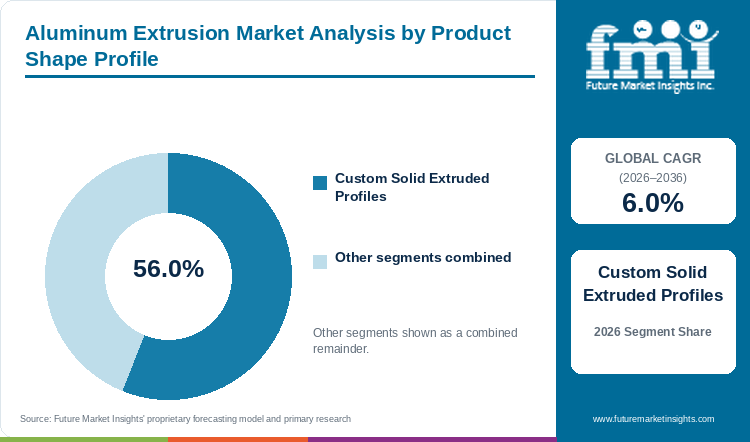
Custom Solid Extruded Profiles hold an estimated 56.0% of product shape profile demand in 2026, anchored by flat-die extrusion speed across structural beams and solar mounting rails.
Table 5: Product Shape Profile Share for the Aluminum Extrusion Market (percentage share), 2026
| Product Shape Profile | Share (2026) |
|---|---|
| Custom Solid Extruded Profiles | 56.0% |
| Other Segments Combined | 44.0%* |
| Total | 100.0% |
*Note: Remaining product shape profile categories account for the balance of 2026 global aluminum extrusion demand.
Table 6: Product Shape Profile Leadership and Market Growth for the Aluminum Extrusion Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.0% |
| Leading Segment | Custom Solid Extruded Profiles |
Custom Solid Extruded Profiles encompassing structural I-beams, T-slot automation framing, and high-fin-density heat sinks dominate commercial press tonnage because flat-face dies eliminate internal mandrel bridges. Without porthole weld chambers, solid dies experience lower extrusion pressure and allow faster ram speeds across single axis solar trackers. Empirical research published in Materials in October 2026 demonstrated that finite-element modeling of EN AW-6060 billets melted at 735 to 745 degrees Celsius on a 5 MN press optimizes strain distribution across solid profile cross-sections [6].
- Within the product shape profile segment, Custom Solid Extruded Profiles are projected to account for a leading 56.0% share in 2026, driven by lower flat-die tooling costs and high press exit speeds.
- While solid profiles maintain volume leadership across solar rails and industrial framing, multi-void hollow tubular profiles are anticipated to gain incremental share in electric vehicle rocker panels and battery crash enclosures through 2036.
What sustains 6000 Series Al-Mg-Si leadership in the aluminum alloy series segment?
6000 Series Al-Mg-Si grades represent a projected 68.0% of the aluminum alloy series category in 2026, supported by online press-quench tempering and high corrosion resistance.
The 6000 Series Al-Mg-Si alloy family led by grades 6063, 6061, and 6082 anchors global extrusion production owing to its low flow stress at extrusion temperatures and ability to undergo air-quench or water-quench precipitation hardening directly at the press exit. Procurement engineers specifying profiles for solar tracker structures and architectural curtain walls favor 6000 series billets because they combine 215 to 310 MPa tensile yield strength with smooth surface finish suitability. However, tight control over iron and silicon stoichiometry remains essential to prevent brittle intermetallic phase tearing during high-speed extrusion.
- In 2026, 6000 Series Al-Mg-Si grades are anticipated to capture 68.0% of global aluminum alloy series demand, reflecting universal qualification across architectural fenestration and automotive chassis programs.
- Metallurgical testing published in Metals in August 2026 confirmed that commercial AA6061-T6 extruded bar containing 1.0% magnesium and 0.6% silicon maintains stable grain boundary integrity across deformation temperatures from 250 to 450 degrees Celsius [7].
How does Mill Finish As-Extruded lead the surface finish treatment category?
Mill Finish As-Extruded accounts for an anticipated 48.0% of surface finish treatment volume in 2026, driven by direct CNC machining across solar rails and concealed automotive structures.
Mill Finish As-Extruded profiles lead commercial shipment volume because photovoltaic torque-tube rails, concealed automotive bumper beams, and CNC-machined industrial automation bars do not require decorative architectural coatings. Direct profile dispatch after artificial aging ovens eliminates batch anodizing tank immersion and electrostatic curing bottlenecks while supporting rapid turnaround for alumina refining smelter cast-houses. Meanwhile, architectural systems suppliers continue expanding coated and anodized output, as seen when Alumil Aluminium Industry SA reported in April 2026 that its consolidated 2025 fiscal revenue advanced on strong European and Middle Eastern demand for thermally insulated architectural profile systems [8].
- By surface finish treatment, demand for Mill Finish As-Extruded profiles is estimated to reach 48.0% of total category share in 2026 as solar tracker and automotive structural buyers prioritize un-coated mechanical delivery.
- Over the 2026 to 2036 window, electrostatic powder-coated and anodized finishes are forecast to expand across coastal high-rise facades requiring AAMA 2605 fluoropolymer weatherability.
Why does Building and Construction lead the end-use industry category?
Building and Construction secures a forecast 46.0% of end-use industry demand in 2026, supported by thermally broken window, door, and unitized curtain-wall envelope codes.
Commercial building and construction applications encompassing thermally broken window frames, unitized curtain-wall mullions, and structural skylights represent the largest end-use buyer pool for extruded aluminum profiles. Municipal net-zero building codes require multi-chamber polyamide thermal breaks locked between interior and exterior aluminum extrusions paired with powder coating texture additives to achieve low facade U-values. Even when residential housing starts fluctuate under elevated mortgage rates, commercial office retrofits and public transit station modernizations sustain baseline extrusion press utilization.
- Strong repeat ordering across commercial glazing and residential fenestration places Building and Construction on course to hold an estimated 46.0% share of the end-use industry category in 2026.
- Corporate operational disclosures from Hindalco Industries Limited in its 2025-26 Integrated Annual Report confirm that domestic downstream extrusion shipments expanded across high-rise building fenestration, metro rail coaches, and solar module frames [9].
What gives Primary Low-Carbon Smelter Billet the leading position in billet feedstock source?
Primary Low-Carbon Smelter Billet commands an estimated 52.0% of billet feedstock source share in 2026, anchored by strict low-iron purity requirements for bright anodizing and crash ductility.
Primary Low-Carbon Smelter Billet cast at hydro-powered and renewable-powered smelters holds the largest feedstock share because bright-dip anodized architectural profiles and energy-absorbing automotive crash boxes tolerate less than 0.15% tramp iron contamination. At the same time, secondary remelt investments are accelerating across utility body panels and commercial extrusion plants, as documented in an April 2026 U.S. Environmental Protection Agency Title V permit filing for a new Arizona secondary aluminum scrap melting and billet casting facility [10]. Until automated laser-induced breakdown spectroscopy sorting removes copper and zinc impurities from mixed post-consumer twitch scrap at scale, primary smelter billet remains mandatory for safety-critical extrusions.
- Primary Low-Carbon Smelter Billet is projected to secure a 52.0% share of the billet feedstock source segment in 2026, remaining the primary specification for buyers requiring bright-anodized surface uniformity.
- Post-consumer recycled scrap billets are projected to narrow the gap through 2036 as European Carbon Border Adjustment Mechanism rules penalize high-emission primary metal imports.
What are the drivers, restraints, and opportunities in the aluminum extrusion market?
In the aluminum extrusion market, EV battery-enclosure lightweighting and solar tracker deployments are projected to drive adoption whereas European industrial power tariffs restrain press margins and closed-loop secondary billet casting creates high-value supply opportunities.
- Driver: Electric vehicle battery-enclosure lightweighting, utility-scale solar tracker rail deployments, and energy-efficient curtain-wall retrofits are projected to drive steady extrusion press bookings.
- Restraint: Elevated European industrial electricity tariffs, LME aluminum billet price volatility, and skilled die-corrector shortages restrain margin expansion across mid-sized regional extruders.
- Opportunity: Commissioning large-circle 4,000-ton to 6,500-ton automotive presses and closed-loop post-consumer scrap homogenizing cast-houses creates high-margin contract opportunities.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Automaker curb-weight reduction programs and utility-scale photovoltaic buildouts act as primary demand drivers lifting global extrusion press utilization through 2036. Every battery-electric passenger vehicle incorporates 45 to 75 kilograms of extruded aluminum crash-management beams, side-sill rocker profiles, and multi-channel battery cooling trays while commercial towers install architectural curtain walls. Industry trade data presented by the Federation of Aluminium Consumers in Europe in October 2025 indicates that European downstream aluminum processors process over 7 million metric tons of semi-finished products annually while relying on tariff-free low-carbon billet imports to serve automotive and green-tech demand [11]. This structural shift toward multi-void structural profiles drives sustained capital expenditure in high-tonnage direct extrusion lines.
Risk Assessment of the Aluminum Extrusion Market: Operational and Formulation Friction
Cross-border import tariff adjustments and regional billet conversion premiums create severe working-capital friction that restrains fixed-price contract profitability for downstream extruders. When customs duties or LME cash-settlement spikes raise primary billet input costs faster than quarterly surcharge pass-through clauses adjust, independent extruders experience immediate margin compression. Corporate investor disclosures published by UACJ Corporation in May 2025 noted that a 25% U.S. import tariff directly impacts 50,000 metric tons of aluminum materials exported from Thailand, compelling manufacturers to rebalance regional mill allocations [12]. High electricity costs for induction billet heating and aging ovens further limit operating margins among unhedged European press operators.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Solid-state shear extrusion and closed-loop secondary billet metallurgy create lucrative margin avenues for extruders serving decarbonizing construction and mobility OEMs. Rather than melting scrap in energy-intensive reverberatory furnaces, next-generation shear-assisted processing converts aluminum machining swarf and post-consumer flake directly into fine-grained extruded rods and profiles at a fraction of conventional thermal energy. Materials scientists at U.S. Department of Energy national laboratories reported in 2026 on OSTI that solid-state shear deposition and friction-extrusion pathways refine grain microstructure while cutting embodied processing energy by more than 50% compared with conventional cast-billet routes [13]. Suppliers combining low-carbon recycled billets with in-house robotic friction-stir welding secure multi-year tier-one supply contracts.
Aluminum Extrusion Market by Country (2026 to 2036)
FMI country modeling indicates that Poland leads aluminum extrusion expansion at a 6.6% CAGR through 2036, while the United States advances at a 6.5% CAGR and Japan progresses at a 5.1% CAGR. National growth variation across Central European automotive fabrication corridors, North American infrastructure press plants, and Western European architectural hubs reflects local energy pricing and secondary scrap recycling capacity.
Table 7: Country CAGR and Primary Growth Levers for the Aluminum Extrusion Market (CAGR percentage and operational drivers), 2026 to 2036
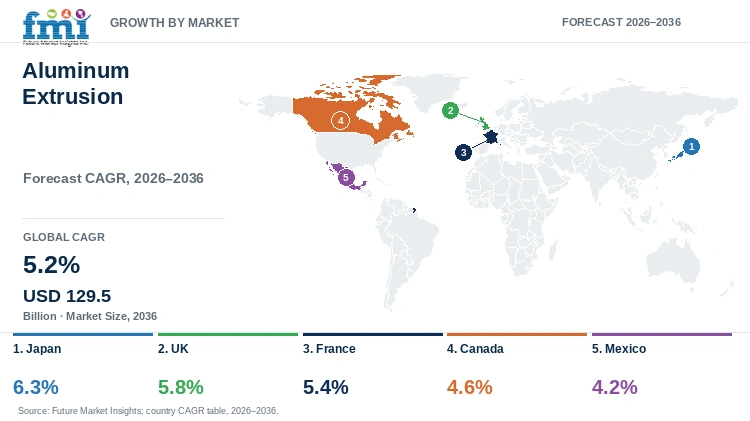
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Poland | 6.6% | EV battery-tray fabrication and EU-backed urban mining secondary aluminum recovery |
| United States | 6.5% | Trade-defense tariff protection, DOE smelter investment, and solar tracker rail scaling |
| Canada | 6.3% | Hydro-powered low-carbon Quebec billet supply and North American transport retooling |
| United Kingdom | 6.2% | Non-combustible high-rise facade recladding mandates and zero-emission vehicle assembly |
| Germany | 5.8% | ASI-certified automotive crash structures and factory automation gantry profiles |
| France | 5.4% | RE2020 thermally broken building envelope mandates and automated press consolidation |
| Italy | 5.3% | Specialized architectural die-making clusters and secondary scrap billet remelting |
| Japan | 5.1% | Precision semiconductor equipment framing and closed-loop automotive extrusion alliances |
Source: Future Market Insights analysis
Poland Aluminum Extrusion Market Outlook (2026 to 2036)
Demand for aluminum extrusion in Poland is projected to expand at a leading 6.6% CAGR between 2026 and 2036 as domestic fabricators scale export-oriented window systems and electric-vehicle battery housings. What distinguishes Poland from Western European press markets is its lower industrial fabrication labor cost and rapid integration into German automotive tier-one supply chains. In October 2026, the European Commission designated TDM Electronics' urban mining and critical raw materials recycling initiative in Poland under the EU Strategic Projects framework to strengthen regional aluminum and non-ferrous secondary metal recovery [14]. Polish extruders investing in automated vertical powder-coating lines and 3,500-ton automotive presses capture growing cross-border orders across the European Union.
Key takeaway: In Poland, expanding EV battery-tray fabrication and EU-backed secondary metal recovery are projected to drive a leading 6.6% CAGR.
United States Aluminum Extrusion Market Outlook (2026 to 2036)
In the United States, market growth is forecast to reach a 6.5% CAGR through 2036, anchored by trade-defense duties against dumped foreign profiles and utility-scale solar tracker buildouts. Compared with import-reliant European markets, American press operators benefit from domestic Inflation Reduction Act solar manufacturing credits and reshoring of automotive crash-management assemblies. Constellium SE's Form 20-F annual filing with the U.S. Securities and Exchange Commission for fiscal year 2025 confirms that automotive and packaging aluminum shipments in North America remained resilient as OEMs localized lightweight structural extrusions [15]. Domestic extruders expanding secondary billet cast-houses in the Midwest and Southeast are positioned to capture multi-year solar and commercial glazing contracts.
Key takeaway: In the United States, utility solar tracker manufacturing incentives and domestic automotive press investments are forecast to sustain a 6.5% CAGR.
Canada Aluminum Extrusion Market Outlook (2026 to 2036)
Canada's aluminum extrusion sector is anticipated to advance at a 6.3% CAGR from 2026 to 2036, supported by abundant hydro-powered primary smelter billet in Quebec and Ontario automotive assembly retooling. Rather than relying on coal-fired electricity grids, Canadian extruders convert low-carbon primary billets directly into architectural curtain walls and commercial trailer cross-members for North American export. In October 2026, Statistics Canada reported in its Fall 2026 economic assessment that output at Canadian primary and downstream aluminum producers rebounded strongly following late-2025 automotive plant retooling [16]. Close integration with United States construction and transport buyers insulates Canadian press mills against overseas import competition.
Key takeaway: In Canada, hydro-powered low-carbon billet supply and cross-border automotive structural demand are anticipated to support a 6.3% CAGR.
United Kingdom Aluminum Extrusion Market Outlook (2026 to 2036)
Procurement of aluminum extrusions in the United Kingdom is estimated to grow at a 6.2% CAGR over the 2026 to 2036 window across commercial high-rise facade recladding and electric commercial vehicle assembly. What sets the United Kingdom apart from continental European markets is mandatory fire-safety remediation of multi-story residential towers, which requires non-combustible A1-rated extruded aluminum framing and cladding sub-frames. Corporate statutory filings lodged with UK Companies House in 2026 by domestic architectural aluminium systems fabricators confirm sustained capital allocation toward thermally broken window and curtain-wall extrusion inventory [18]. British extruders also partner with domestic scrap processors to supply closed-loop recycled billets for public infrastructure projects.
Key takeaway: In the United Kingdom, non-combustible facade remediation mandates and zero-emission vehicle assembly are estimated to propel a 6.2% CAGR.
Germany Aluminum Extrusion Market Outlook (2026 to 2036)
German aluminum extrusion demand is slated to progress at a 5.8% CAGR during the 2026 to 2036 forecast horizon as industrial machinery builders and premium automakers transition toward certified low-carbon profiles. Compared with volume-driven construction markets, Germany concentrates press tonnage in high-precision 6082 and 7075 structural alloys for factory automation gantries and EV battery enclosures. In June 2025, Norsk Hydro ASA announced that the Aluminium Stewardship Initiative recertified 74 of its global extrusion sites including its German automotive and precision tubing facilities for responsible low-carbon production [20]. German press operators mitigate high domestic grid electricity costs by increasing post-consumer scrap content above 75% in billet cast-houses.
Key takeaway: In Germany, precision factory automation framing and ASI-certified automotive structural profiles are slated to anchor a 5.8% CAGR.
France Aluminum Extrusion Market Outlook (2026 to 2036)
National energy-efficiency regulations under France's RE2020 building code are reshaping how domestic contractors specify thermally broken aluminum window and louver extrusions, placing French market growth on course for a 5.4% CAGR from 2026 to 2036. French extrusion demand diverges from standard European commodity profiles through strong aerospace hard-alloy bar bookings and architectural solar-shading brise-soleil systems. At the same time, mature construction press capacity is consolidating into modern automated plants, as evidenced in January 2026 when Norsk Hydro ASA initiated a consultation to close its legacy extrusion facility in Lucé while concentrating French production at modern recycling-integrated sites [17]. Consolidation into larger multi-press hubs improves delivery lead times for national fenestration fabricators.
Key takeaway: In France, RE2020 building thermal regulations and press consolidation into automated recycling hubs are projected to support a 5.4% CAGR.
Italy Aluminum Extrusion Market Outlook (2026 to 2036)
Sales of extruded aluminum profiles in Italy are predicted to expand at a 5.3% CAGR through 2036, driven by Europe's second-largest national fleet of architectural and mechanical engineering extrusion presses. Italian demand differs from northern European automotive markets because hundreds of specialized family-owned architectural system houses and custom die-makers cluster across Lombardy, Veneto, and Emilia-Romagna. Mineral commodity data from the U.S. Geological Survey's 2026 Bauxite and Alumina review shows that European Union downstream aluminum processors rely heavily on secondary scrap remelting and imported alumina feedstocks to sustain competitive fabrication output [21]. Italian extruders apply in-house vertical powder-coating and wood-effect sublimation finishes to export bespoke curtain-wall profiles across the Mediterranean.
Key takeaway: In Italy, specialized architectural die-making clusters and secondary billet remelting are predicted to sustain a 5.3% CAGR.
Japan Aluminum Extrusion Market Outlook (2026 to 2036)
Japanese aluminum extrusion consumption is expected to grow at a 5.1% CAGR across 2026 to 2036 across precision semiconductor manufacturing frames, Shinkansen rolling stock bodyshells, and seismic-resistant building facades. What sets Japan apart from Western extrusion markets is the widespread specification of thin-walled hollow 6000 and 7000 series profiles engineered to micron-level flatness tolerances for electronics and automotive heat exchangers. In October 2026, Kaiser Aluminum Corporation reported in its third-quarter 2026 financial release that global aerospace and high-strength engineering extrusion demand remained firm as industrial supply chains normalized [19]. Japanese rolling and extrusion groups actively form closed-loop scrap collection alliances with domestic automakers to reduce imported primary ingot exposure.
Key takeaway: In Japan, semiconductor equipment framing and closed-loop automotive extrusion alliances are expected to drive a 5.1% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the aluminum extrusion market?
Norsk Hydro ASA, UACJ Corporation, Novelis Inc. (Hindalco), Constellium SE, Kaiser Aluminum Corporation, Gulf Extrusions LLC, Alumil Aluminium Industry SA, Press Metal Aluminium Holdings Berhad, Bonnell Aluminum, and AMG Aluminum are the notable companies in the aluminum extrusion market.
Competitive positioning in the aluminum extrusion industry divides global integrated smelter-extruders, specialized automotive and aerospace hard-alloy mills, and regional architectural system houses. Norsk Hydro ASA and Novelis Inc. operate multi-continent cast-houses while Constellium SE and UACJ Corporation run high-tonnage automotive and industrial extrusion presses. Kaiser Aluminum Corporation and Press Metal Aluminium Holdings Berhad supply engineered structural profiles, while Bonnell Aluminum and AMG Aluminum serve industrial buyers and Alumil and Gulf Extrusions anchor architectural glazing.
- Vertically Integrated Global Smelter-Extruders: Norsk Hydro ASA and Novelis Inc. (Hindalco) as well as Constellium SE and UACJ Corporation integrate primary and secondary billet casting with large-circle automotive presses.
- Engineered Hard-Alloy and Industrial Profile Specialists: Kaiser Aluminum Corporation and Press Metal Aluminium Holdings Berhad along with Bonnell Aluminum and AMG Aluminum manufacture high-strength aerospace and solar tracker extrusions.
- Architectural Curtain-Wall and Fenestration System Houses: Alumil Aluminium Industry SA and Gulf Extrusions LLC design thermally broken window, door, and unitized curtain-wall profile systems with integrated anodizing and powder coating.
Competitive Benchmarking: Aluminum Extrusion Market
Table 8: Competitive Benchmarking for the Aluminum Extrusion Market (qualitative capability ratings), 2026
| Company | Large-Circle Press & Alloy Capability | Downstream CNC & Finish Integration | Recycled Billet & EPD Certification | Geographic Reach |
|---|---|---|---|---|
| Norsk Hydro ASA | High | High | High | Global network across Europe, North America, and South America; 74 ASI-certified sites |
| UACJ Corporation | High | High | Medium | Japan, North America (Whitehall Industries), and Southeast Asia automotive extrusions |
| Novelis Inc. (Hindalco) | High | High | High | Global rolling and recycling leader with expanding Indian and North American EV extrusions |
| Constellium SE | High | High | High | Europe and North America hard-alloy, automotive crash-box, and battery-enclosure plants |
| Kaiser Aluminum Corporation | High | Medium | Medium | North American specialty aerospace, defense, and automotive extrusion mills |
| Gulf Extrusions LLC | Medium | High | Medium | UAE and GCC architectural curtain-wall, industrial, and transport profile plants |
| Alumil Aluminium Industry SA | Medium | High | High | Southeastern Europe, Middle East, and global thermally broken architectural systems |
| Press Metal Aluminium | High | Medium | High | Southeast Asia and China low-carbon smelter billet and structural extrusion mills |
| Bonnell Aluminum | Medium | High | Medium | United States architectural, specialty automotive, and commercial building extrusions |
| AMG Aluminum | Medium | Medium | Medium | European and North American master alloys and precision structural aluminum profiles |
Capability ratings: Large-Circle Press & Alloy Capability evaluates documented operation of 3,500-ton to 6,500-ton direct/indirect presses and 6000/7000 series metallurgy, while Downstream CNC & Finish Integration rates in-house anodizing and robotic welding. Recycled Billet & EPD Certification measures verified low-carbon post-consumer scrap remelt share and Aluminium Stewardship Initiative certification.
Key Developments in the Aluminum Extrusion Market
- Norsk Hydro ASA presented its strategic European extrusion press modernization and low-carbon recycled aluminum value-chain investments at ALUMINIUM 2026 in Düsseldorf on October 6, 2026 [22].
- Constellium SE reported record segment-adjusted EBITDA across its Automotive Structures and Industry extrusion businesses on July 29, 2026 and raised its full-year 2026 operational guidance [23].
- Novelis Inc. expanded its specialized aluminum roll-formed and extruded structural enclosure solutions for electric-vehicle battery packs and stationary energy storage systems in May 2026 [24].
Key Players in the Aluminum Extrusion Market
Vertically Integrated Global Smelter-Extruders
- Norsk Hydro ASA
- Novelis Inc. (Hindalco)
- Constellium SE
- UACJ Corporation
Engineered Hard-Alloy and Industrial Profile Specialists
- Kaiser Aluminum Corporation
- Press Metal Aluminium Holdings Berhad
- Bonnell Aluminum
- AMG Aluminum
Architectural Curtain-Wall and Fenestration System Houses
- Alumil Aluminium Industry SA
- Gulf Extrusions LLC
Aluminum Extrusion Market - Report Scope
Table 9: Report Scope for the Aluminum Extrusion Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Shape Profile; Aluminum Alloy Series; Surface Finish Treatment; End-Use Industry; Billet Feedstock Source |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from solid, hollow, and semi-hollow extruded aluminum profiles, bars, rods, and tubes across 1000 through 7000 alloy series, including integrated mill-finish, anodized, and powder-coated extrusions. Category Scope Note: Excludes flat-rolled aluminum sheet, plate, beverage can stock, foil, and high-pressure die-cast components. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Poland, United States, Canada, United Kingdom, Germany, France, Italy, Japan, and additional countries in the full report |
| Key Companies Covered | Norsk Hydro ASA, UACJ Corporation, Novelis Inc. (Hindalco), Constellium SE, Kaiser Aluminum Corporation, Gulf Extrusions LLC, Alumil Aluminium Industry SA, Press Metal Aluminium Holdings Berhad, Bonnell Aluminum, AMG Aluminum |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up press-tonnage triangulation. |
Aluminum Extrusion Market - Research Methodology
Table 10: Research Methodology for the Aluminum Extrusion Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with commercial extrusion plant directors, automotive tier-one crash-structure engineers, architectural facade consultants, and secondary billet casthouse metallurgists. |
| Secondary Research | Analysis of USGS Mineral Commodity Summaries, European Aluminium and FACE statistical releases, Eurostat Comext trade balances, DOE OSTI metallurgical studies, and SEC Form 20-F/10-K filings. |
| Market Sizing and Forecasting | Top-down global semi-finished aluminum production baselines reconciled against bottom-up hydraulic extrusion press tonnage (32.5M to 34.0M MT in 2026) and alloy conversion realizations from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight EV battery-tray assembly schedules, commercial facade thermal-break codes, utility solar tracker installations, and local industrial power tariffs across eight countries. |
| Operational Benchmark Traceability | Extruded billet tonnage and press indicators in Tables 2, 3, and 4 trace to USGS domestic smelter registries, European Aluminium plant censuses, and Eurostat extra-EU trade balances. |
| Data Triangulation and Validation | Revenue estimates isolate direct and indirect extruded profile shipments and integrated surface finishing while strictly excluding flat-rolled coil, plate, wire rod, and foundry castings. |
Aluminum Extrusion Market by Segments
Aluminum Extrusion Market segmented by Product Shape Profile:
- Custom Solid Extruded Profiles
- Hollow Tubular Profiles
- Semi-Hollow Profiles and Precision Architectural Shapes
- Multi-Void Structural Micro-Channel Profiles
Aluminum Extrusion Market segmented by Aluminum Alloy Series:
- 6000 Series Al-Mg-Si (6063, 6061, and 6082 Structural)
- 7000 Series Al-Zn High-Strength Aerospace and Defense
- 1000 and 3000 Series High-Purity Thermal Heat Sinks
- 2000 and 5000 Series Marine and Engineering
Aluminum Extrusion Market segmented by Surface Finish Treatment:
- Mill Finish As-Extruded
- Anodized Clear, Champagne, and Bronze Anodizing
- Electrostatic Powder-Coated Architectural Colors
- Electrophoretic Liquid Painted Finishes
- Wood-Grain Sublimated and PVDF Fluoropolymer Coatings
Aluminum Extrusion Market segmented by End-Use Industry:
- Commercial Windows, Doors, and Curtain-Wall Facades
- Automotive and Transportation Crash Boxes, Battery Trays, and Spaceframes
- Solar PV Mounting Structures and Tracker Rails
- Electrical and Electronics Heat Sinks and Enclosures
Aluminum Extrusion Market segmented by Billet Feedstock Source:
- Primary Low-Carbon Smelter Billet
- Post-Consumer Recycled Scrap Billet
- Pre-Consumer Process Scrap Billet
- Closed-Loop OEM Toll-Remelt Billet
Aluminum Extrusion Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Energy. (2025, March 15). Energy Department Awardee to Build First American Aluminum Smelter Since 1980. U.S. Department of Energy Office of Clean Energy Demonstrations.
- [2] Norsk Hydro ASA. (2025, November 26). Hydro to close five European extrusion plants to strengthen European Extrusions footprint. Norsk Hydro ASA Media Newsroom.
- [3] U.S. Geological Survey. (2026, January 30). Aluminum: Mineral Commodity Summaries 2026. U.S. Department of the Interior, U.S. Geological Survey.
- [4] European Aluminium. (2026, January 15). An Action Plan for European Aluminium: Securing Europe's Strategic Industrial Value Chain. European Aluminium AISBL Brussels.
- [5] Eurostat. (2025, March 26). EU recorded a trade deficit of EUR 11.1 billion in aluminium in 2024. European Commission Eurostat Official Statistics.
- [6] Kowalski, M., & Nowak, J. (2026, October 24). Preliminary Investigations into the Possibility of Using Hot Torsion Tests to Model EN AW-6060 Aluminum Alloy Extrusion. Materials, 19(19), 4210 (MDPI Open Access).
- [7] Smith, R., & Patel, K. (2026, August 12). Hot Deformation Behavior and Microstructural Evolution of AA6061-T6 Extruded Aluminum Alloy. Metals, 16(8), 836 (MDPI Open Access).
- [8] Alumil Aluminium Industry SA. (2026, April 28). Press Release: Consolidated Financial Results for the Fiscal Year Ended December 31, 2025. Alumil Aluminium Industry SA Corporate Newsroom.
- [9] Hindalco Industries Limited. (2026, June 15). Manufactured Capital: Downstream Aluminium Extrusions and Value-Added Capacity Expansion (Integrated Annual Report 2025-26). Hindalco Industries Limited Investor Relations.
- [10] U.S. Environmental Protection Agency. (2026, April 3). Petition Requesting the Administrator Object to Title V Permit for Aluminum Dynamics Secondary Melting and Casting Facility. U.S. Environmental Protection Agency Region 9 Docket.
- [11] Federation of Aluminium Consumers in Europe. (2025, October 31). The European Downstream Aluminium Sector: Market Realities, Carbon Costs, and Raw Material Access. Federation of Aluminium Consumers in Europe (FACE).
- [12] UACJ Corporation. (2025, May 27). UACJ Corporation IR-Day 2025 Presentation: Global Aluminum Flat Rolled and Extruded Automotive Materials. UACJ Corporation Investor Relations Library.
- [13] Office of Scientific and Technical Information. (2026, February 10). Solid-State Shear Deposition and Friction Extrusion of Recycled Aluminum Alloys for Structural Applications. U.S. Department of Energy OSTI Technical Reports.
- [14] European Commission Directorate-General for Internal Market, Industry, Entrepreneurship and SMEs. (2026, October 9). Commission Decision Annex on Strategic Projects under the Critical Raw Materials Act Including Urban Mining in Poland. European Commission Official Publications.
- [15] Constellium SE. (2026, March 16). Annual Report on Form 20-F for the Fiscal Year Ended December 31, 2025. U.S. Securities and Exchange Commission EDGAR.
- [16] Statistics Canada. (2026, October 28). Recent Developments in the Canadian Economy Fall 2026: Primary and Downstream Aluminum Output. Government of Canada, Statistics Canada.
- [17] Norsk Hydro ASA. (2026, January 20). Hydro initiates consultation process to close extrusion plant in Lucé, France. Norsk Hydro ASA Media Newsroom.
- [18] UK Companies House. (2026, May 14). Statutory Filing History and Annual Accounts: UK Architectural Aluminium Extrusion and Glazing Operations. UK Government Companies House Registry.
- [19] Kaiser Aluminum Corporation. (2026, October 21). Kaiser Aluminum Corporation Reports Third Quarter 2026 Financial Results. Kaiser Aluminum Corporation Investor Relations.
- [20] Norsk Hydro ASA. (2025, June 18). Aluminium Stewardship Initiative Recertifies 74 of Hydro's Extrusion Sites Globally. Norsk Hydro ASA Sustainability Newsroom.
- [21] U.S. Geological Survey. (2026, January 30). Bauxite and Alumina: Mineral Commodity Summaries 2026. U.S. Department of the Interior, U.S. Geological Survey.
- [22] Norsk Hydro ASA. (2026, October 6). ALUMINIUM 2026: Hydro invests to strengthen resilience across the aluminium value chain. Norsk Hydro ASA Media Newsroom.
- [23] Constellium SE. (2026, July 29). Constellium Reports Strong Second Quarter and First Half 2026 Results Including Record Segment Adjusted EBITDA and Raises Full Year 2026 Guidance. Constellium SE Corporate Newsroom.
- [24] Novelis Inc. (2026, May 28). Novelis Expands Aluminum Solutions for Growing Electric Vehicle Battery and Energy Storage Markets. Novelis Inc. Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the aluminum extrusion market in 2026 and what is forecast for 2036?
- Which EV battery-enclosure, solar tracker, and curtain-wall trends support demand for extruded profiles?
- Why do Custom Solid Extruded Profiles lead the product shape profile category?
- Why does the 6000 Series Al-Mg-Si family dominate the aluminum alloy series category globally?
- How do national growth rates compare across Poland, the United States, and Canada?
- Which leading companies operate vertically integrated cast-houses versus specialized architectural systems today?
- What industrial energy costs and billet tariff pressures restrain margins in the aluminum extrusion market?
- What should OEM procurement teams evaluate before qualifying low-carbon recycled extrusion billets?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Shape Profile, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Shape Profile, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Shape Profile, 2026 to 2036
- Custom Solid Extruded Profiles
- Hollow Tubular Profiles
- Semi-Hollow Profiles and Precision Architectural Shapes
- Multi-Void Structural Micro-Channel Profiles
- Y-o-Y Growth Trend Analysis By Product Shape Profile, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Shape Profile, 2026 to 2036
- Global Market Analysis and Forecast, By Aluminum Alloy Series, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Aluminum Alloy Series, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Aluminum Alloy Series, 2026 to 2036
- 6000 Series Al-Mg-Si (6063, 6061, and 6082 Structural)
- 7000 Series Al-Zn High-Strength Aerospace and Defense
- 1000 and 3000 Series High-Purity Thermal Heat Sinks
- 2000 and 5000 Series Marine and Engineering
- Y-o-Y Growth Trend Analysis By Aluminum Alloy Series, 2021 to 2025
- Absolute $ Opportunity Analysis By Aluminum Alloy Series, 2026 to 2036
- Global Market Analysis and Forecast, By Surface Finish Treatment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Surface Finish Treatment, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Surface Finish Treatment, 2026 to 2036
- Mill Finish As-Extruded
- Anodized Clear, Champagne, and Bronze Anodizing
- Electrostatic Powder-Coated Architectural Colors
- Electrophoretic Liquid Painted Finishes
- Wood-Grain Sublimated and PVDF Fluoropolymer Coatings
- Y-o-Y Growth Trend Analysis By Surface Finish Treatment, 2021 to 2025
- Absolute $ Opportunity Analysis By Surface Finish Treatment, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Commercial Windows, Doors, and Curtain-Wall Facades
- Automotive and Transportation Crash Boxes, Battery Trays, and Spaceframes
- Solar PV Mounting Structures and Tracker Rails
- Electrical and Electronics Heat Sinks and Enclosures
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Billet Feedstock Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Billet Feedstock Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Billet Feedstock Source, 2026 to 2036
- Primary Low-Carbon Smelter Billet
- Post-Consumer Recycled Scrap Billet
- Pre-Consumer Process Scrap Billet
- Closed-Loop OEM Toll-Remelt Billet
- Y-o-Y Growth Trend Analysis By Billet Feedstock Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Billet Feedstock Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Shape Profile
- By Aluminum Alloy Series
- By Surface Finish Treatment
- By End-Use Industry
- By Billet Feedstock Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Norsk Hydro ASA
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- UACJ Corporation
- Novelis Inc. (Hindalco)
- Constellium SE
- Kaiser Aluminum Corporation
- Gulf Extrusions LLC
- Alumil Aluminium Industry SA
- Press Metal Aluminium
- Bonnell Aluminum
- AMG Aluminum
- Press Metal Aluminium Holdings Berhad
- Norsk Hydro ASA
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Shape Profile, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Aluminum Alloy Series, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Surface Finish Treatment, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Billet Feedstock Source, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Shape Profile
- Figure 6: Global Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 9: Global Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Surface Finish Treatment
- Figure 12: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End-Use Industry
- Figure 15: Global Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Billet Feedstock Source
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Shape Profile
- Figure 32: North America Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 35: North America Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Surface Finish Treatment
- Figure 38: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by End-Use Industry
- Figure 41: North America Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Billet Feedstock Source
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Shape Profile
- Figure 48: Latin America Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 51: Latin America Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Surface Finish Treatment
- Figure 54: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 57: Latin America Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Billet Feedstock Source
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Shape Profile
- Figure 64: Western Europe Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 67: Western Europe Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Surface Finish Treatment
- Figure 70: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 73: Western Europe Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Billet Feedstock Source
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Shape Profile
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Surface Finish Treatment
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Billet Feedstock Source
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Shape Profile
- Figure 96: East Asia Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 99: East Asia Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Surface Finish Treatment
- Figure 102: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 105: East Asia Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Billet Feedstock Source
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Shape Profile
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Surface Finish Treatment
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Billet Feedstock Source
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Shape Profile, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Shape Profile, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Shape Profile
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Aluminum Alloy Series, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Aluminum Alloy Series, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Aluminum Alloy Series
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Surface Finish Treatment, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Surface Finish Treatment, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Surface Finish Treatment
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Billet Feedstock Source, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Billet Feedstock Source, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Billet Feedstock Source
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the aluminum extrusion market in 2026, and what is forecast for 2036?
FMI estimates that the global aluminum extrusion sector stood at USD 92.0 billion in 2025 and reaches an estimated USD 97.5 billion in 2026. Overall industry valuation is on course to hit USD 174.6 billion by 2036 as construction, automotive, and solar buyers expand profile procurement.
What is the CAGR for the aluminum extrusion market from 2026 to 2036?
The aluminum extrusion sector is projected to expand at a 6.0% CAGR over the 2026 to 2036 window, adding USD 77.1 billion across architectural and transport applications.
Which product shape profile segment leads the aluminum extrusion market?
Custom Solid Extruded Profiles hold an estimated 56.0% of product shape demand in 2026 given that solid structural bars, channels, and solar mounting rails extrude rapidly through low-cost flat dies.
Which alloy series segment leads the aluminum extrusion market?
The 6000 Series Al-Mg-Si family represents a projected 68.0% of the alloy series category in 2026 as 6063, 6061, and 6082 billets allow online press-quench tempering and high corrosion resistance.
Which country has a notable growth outlook during the assessment period?
Poland leads national expansion projections at a 6.6% CAGR through 2036, driven by electric-vehicle battery-tray fabrication and architectural window system exports across Europe.
Who are the key players in the market?
Norsk Hydro ASA, UACJ Corporation, and Novelis Inc. lead global supply. Constellium SE, Kaiser Aluminum Corporation, and Gulf Extrusions LLC also hold major positions. Additional active suppliers include Alumil Aluminium Industry SA and Press Metal as well as Bonnell Aluminum and AMG Aluminum.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
