

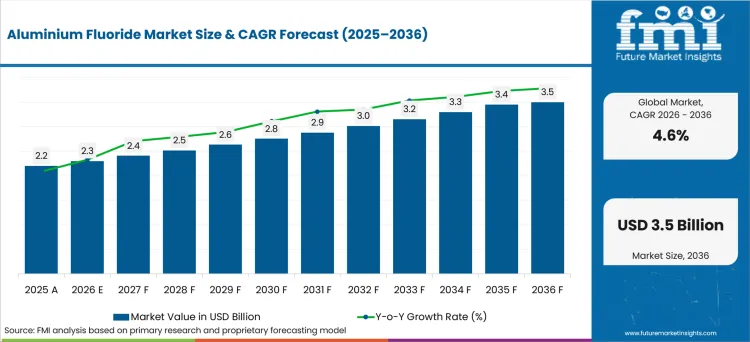
- Market Size (2026)
- USD 2.3 Bn
- Forecast (2036)
- USD 3.5 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Aluminium Fluoride Market in 2026?
USD 2.3 billion in 2026 and USD 3.5 billion by 2036 at a 4.6% CAGR.
Demand for aluminium fluoride is projected to expand at 4.6% CAGR between 2026 and 2036, increasing valuation from USD 2.3 billion in 2026 to USD 3.5 billion by 2036. Primary aluminium smelters replenish aluminium fluoride during continuous electrolyte control, so operating potlines provide the repeat demand base. Hydro’s February 2026 annual report records 448,000 tonnes of primary aluminium production at Albras during 2025 from four prebake lines. Albras’s operating scale converts into repeat fluoride replenishment after producers qualify chemistry and secure hydrofluoric acid feedstock for contracted supply.
Country demand diverges with operating smelter scale and upstream alumina availability, not downstream aluminium interest alone. The USA Geological Survey estimated 2025 primary aluminium output at about 3.3 million tonnes in Canada versus 660,000 tonnes in the United States. Canada therefore carries a broader installed replenishment base, while USA growth depends more heavily on greenfield commissioning and subsequent material qualification.
Key Takeaways of Aluminium Fluoride Market
- Primary aluminium potlines require repeated aluminium fluoride purchases because bath chemistry is adjusted during continuous electrolysis campaigns.
- By grade, metallurgical is estimated to hold 91.6% in 2026 owing to large qualified volumes consumed during primary aluminium electrolysis.
- In 2026, aluminium for primary smelting is expected to lead application with 91.8% share because potline operation renews electrolyte requirements.
- Other industrial applications remain smaller because fluorocarbon, ceramic and chemical-intermediate users purchase aluminium fluoride through less concentrated demand channels.
- Feedstock price exposure and planned furnace maintenance can interrupt producer economics even while underlying smelter consumption stays intact.
- Key players in the aluminium fluoride market include Fluorsid S.p.A., Industries Chimiques du Fluor (ICF), Derivados del Fluor S.A.U. (DDF), Do-Fluoride New Materials Co., Ltd., Alufluor AB, Alufluoride Limited, PhosAgro, and Tanfac Industries Limited.
Analyst Perspective
"Smelters should qualify aluminium fluoride on impurity control and delivery continuity before comparing nominal price because a supply interruption affects active pots immediately. Producers protect contract margins by securing fluorine feedstocks and scheduling bulk deliveries against each customer’s potline replenishment plan."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights
How is the Aluminium Fluoride Market segmented?
The aluminium fluoride market is segmented by grade and application.
The aluminium fluoride market is segmented by grade and application. Grade covers metallurgical and other industrial material, while application includes aluminium for primary smelting, fluorocarbon applications, ceramic, chemical intermediate and other uses.
Why does Aluminium for primary smelting lead the Application category?
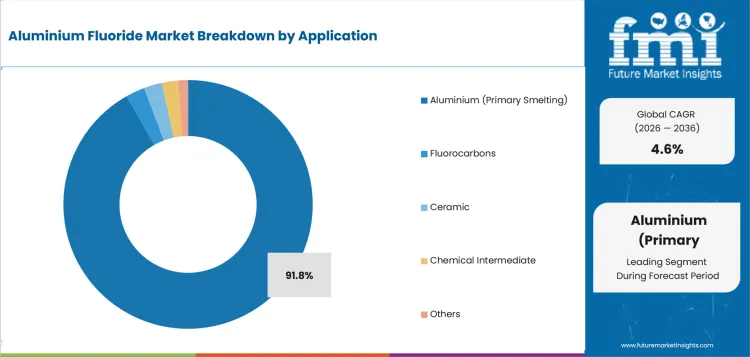
Primary smelting dominates applications because aluminium fluoride adjusts the cryolite bath used to dissolve alumina during Hall-Héroult electrolysis. Operating demand scales with potline activity, so additional dedicated production broadens the pool of qualified supply. Alufluoride Limited’s May 2025 annual report states that its capacity was being raised from 16,000 to 18,000 tonnes annually.
- In 2026, aluminium for primary smelting is expected to lead application with 91.8% share because potline operation renews electrolyte input requirements.
- The expansion gives smelters another dedicated source while aluminum hydroxide supply and qualification records shape the producer’s ability to sustain contracted output.
Why does Metallurgical lead the Grade category?
Metallurgical grade serves smelters that adjust electrolyte chemistry continuously and require consistent bulk material over long production campaigns. Supply continuity forms part of technical qualification because Alufluoride Limited disclosed in May 2026 that hydrofluosilicic acid shortages would temporarily reduce Visakhapatnam aluminium fluoride output. The disruption showed how upstream feed availability can constrain qualified tonnage while smelter demand does not change.
- By grade, metallurgical is estimated to hold 91.6% in 2026 owing to repeated qualified tonnage consumed during primary aluminium electrolysis.
- Smelters also review fluorite feedstock and sulfuric acid exposure because both inputs affect the upstream fluorine chain before aluminium fluoride reaches potline stores.
What are the drivers, restraints and opportunities in the Aluminium Fluoride Market?
Primary aluminium output sustains repeat consumption, while feedstock exposure and plant reliability restrict supply economics and recovered fluorine routes broaden sourcing options.
- Driver: Smelter operation and new potline capacity sustain repeated aluminium fluoride purchases after each material specification receives technical approval.
- Restraint: Raw-material costs and production outages weaken supply economics because smelters require qualified aluminium fluoride without interruptions.
- Opportunity: Fluorine recovery from phosphatic by-products can broaden feedstock options where producers prove impurity control and commercial continuity.
New primary aluminium capacity raises addressable aluminium fluoride demand once each potline reaches commissioning and approved material enters operating schedules. In February 2026 the USA Department of Energy said Century Aluminum’s planned Oklahoma smelter could produce more than 500,000 tonnes annually. The project would enlarge electrolyte input requirements after engineering and procurement convert announced capacity into operating cells.
Aluminium fluoride producers carry feedstock exposure and furnace risk while fulfilling contracted volumes for primary smelters. Tunisia’s Financial Market Council disclosed in April 2026 that ICF’s 2025 aluminium fluoride production fell 16.5% after a planned fourth-quarter furnace shutdown. Higher raw-material costs also weakened margins in the filing, which means maintenance timing can tighten qualified supply without reducing underlying smelter demand.
Recovered fluorine can reduce dependence on mined feedstock once alternative streams meet the same impurity limits as conventional inputs. Alufluor’s June 2025 sustainability report states that fluorosilicic acid from phosphoric-acid production is its primary raw material for aluminium fluoride. The route can improve fluorochemical intermediates sourcing while lowering raw-material exposure, provided recovered fluorine preserves the product quality required by smelters.
Which country CAGRs are profiled in the Aluminium Fluoride Market?
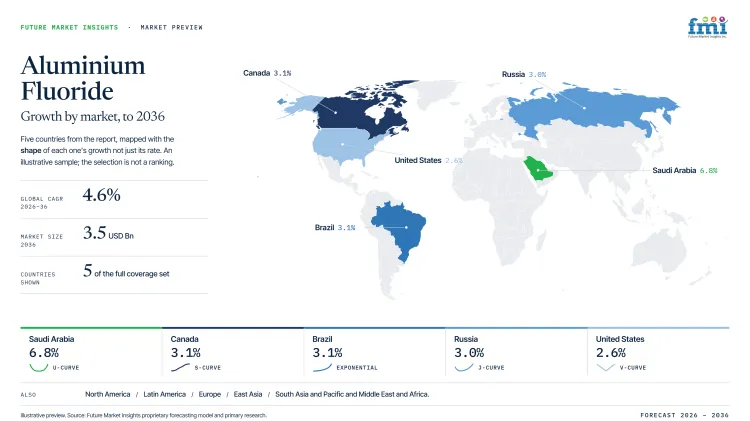
| Country | CAGR |
|---|---|
| Saudi Arabia | 6.8% |
| Canada | 3.1% |
| Russia | 3.0% |
| United States | 2.6% |
| Brazil | 3.1% |
How do country-level CAGRs compare in the Aluminium Fluoride Market?
The five profiled rates span 7.2 percentage points from Saudi Arabia at 6.8% to Brazil at 3.1%. Saudi Arabia forms the expansion case, while Canada and Russia occupy a narrow middle band. The United States and Brazil remain near flat or contracting because existing operating smelter capacity outweighs announced projects.
- Saudi Arabia’s coastal corridor shortens delivery routes between fluorochemical imports and smelters.
- Quebec hydropower supports steady smelter utilization and predictable electrolyte-input purchasing under contracts.
- Domestic phosphate chemistry gives Russian smelters additional fluorine feedstock options without imports.
- Few USA smelter accounts concentrate qualification decisions among a small group of plants.
- Brazil’s Pará smelter geography makes port access and inland freight central to contracts.
Comparable CAGRs require different entry plans because capacity and account concentration differ. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Maaden’s integrated bauxite-to-aluminium system concentrates aluminium fluoride buying within a small number of operating assets and central technical teams. Saudi Arabia is projected to grow at 6.8% CAGR through 2036 attributable to coordinated alumina and smelting investment that can raise potline input needs despite concentrated purchasing power and demanding material qualification. Maaden’s June 2025 announcement to acquire Alcoa’s remaining 25.1% interests in the aluminium and bauxite-alumina ventures would tighten ownership of the operating chain, giving qualified producers clearer plant-level coordination while leaving fewer independent accounts for new aluminium fluoride entrants to pursue during the forecast period.
- Quebec’s mature smelter cluster gives aluminium fluoride producers a large operating base with established bulk routes and long customer qualification records. In May 2026 the Government of Canada announced support for Rio Tinto’s ELYSIS demonstration plant, which is intended to validate inert-anode smelting at industrial scale and could alter qualification routines for electrolyte inputs at future commercial sites. Canada is forecast to expand at 3.1% CAGR through 2036 aided by its installed smelter base, yet producers must document material compatibility carefully while conventional Hall-Héroult lines and ELYSIS trials coexist and purchasing teams protect process stability during any transition.
- Long distances between major smelting assets make reliable bulk delivery and plant-level technical support central to aluminium fluoride qualification for producers without established local accounts. Russia is estimated to post 3.0% CAGR from 2026 to 2036 given its substantial operating aluminium base, while concentrated purchasing and limited switching restrict new entrants even after chemistry meets customer specification. RUSAL reported in July 2025 that an AI system at Taishet monitored as many as 20 melt-preparation operations, which means upstream material producers face a plant culture built around tighter process control before a new source receives wider commercial acceptance at scale.
- United States’ existing primary aluminium capacity is small, which means routine aluminium fluoride demand is driven by a narrow operating base while greenfield projects can alter future qualification volumes. The Department of Energy awarded Century Aluminum USD 10 million for Phase 1 in January 2025, leaving site selection and engineering as practical gates before commercial fluoride sourcing begins. Aluminium fluoride demand is forecast to contract at 2.6% CAGR through 2036 because current consumption lacks broad capacity growth, while a completed greenfield smelter would start a separate qualification cycle instead of immediately generating repeat orders for established or newly approved producers during operation.
- In Brazil, Albras and Alumar account for most primary-smelter demand, so aluminium fluoride contracts depend heavily on plant utilization and power availability at a small number of accounts. Brazil is forecast to contract at 3.1% CAGR through 2036, owing to mature capacity and limited account expansion, making retention of qualified contracts more important than speculative new-entry plans. The Brazilian Aluminium Association reported in July 2026 that 2025 primary aluminium output reached 1.18 million tonnes after an 8.5% increase, which confirms stronger plant activity without widening the pool of smelter customers available to new aluminium fluoride producers seeking sustained commercial volumes locally.
Who are the notable companies in the Aluminium Fluoride Market?
Fluorsid S.p.A., Industries Chimiques du Fluor (ICF), Derivados del Fluor S.A.U. (DDF), Do-Fluoride New Materials Co., Ltd., Alufluor AB, Alufluoride Limited, PhosAgro, and Tanfac Industries Limited serve this market.
Competition is concentrated among producers that can qualify aluminium fluoride for continuous smelter service and deliver bulk tonnage without chemistry drift. Do-Fluoride operates aluminium fluoride inside a wider fluorine-materials portfolio whose anhydrous hydrogen fluoride also feeds fluoropolymers and other downstream chemicals. Smelters therefore compare impurity limits and shipment reliability before approving a second source.
- Integrated fluorochemical platforms include Fluorsid S.p.A., Do-Fluoride New Materials Co., Ltd., PhosAgro and Tanfac Industries Limited with several fluorine-conversion steps.
- European and Mediterranean specialists include Industries Chimiques du Fluor (ICF), Derivados del Fluor S.A.U. (DDF) and Alufluor AB with documented regional production.
- India-focused Alufluoride Limited operates dedicated aluminium fluoride capacity with long-term fluorosilicic acid sourcing from fertilizer producers.
Competitive Benchmarking: Aluminium Fluoride Market
| Company | AlF3 Production Depth | Fluorine Feedstock Control | Supply and Qualification Support | Geographic Reach |
|---|---|---|---|---|
| Fluorsid S.p.A. | High | High | High | Global |
| Industries Chimiques du Fluor (ICF) | Medium | Medium | Medium | Tunisia and exports |
| Derivados del Fluor S.A.U. (DDF) | Medium | High | High | Global |
| Do-Fluoride New Materials Co., Ltd. | High | High | High | China and exports |
| Alufluor AB | Medium | High | High | Global |
| Alufluoride Limited | Medium | Medium | High | India and exports |
| PhosAgro | High | High | High | Russia |
| Tanfac Industries Limited | Medium | Medium | Medium | India and Asia-Pacific |
Scoring basis: High production depth requires verified aluminium fluoride capacity above 50,000 tonnes annually, while Medium covers smaller commercial output and Low covers pilot-scale evidence. High feedstock control requires captive or circular fluorine, while Medium indicates partial integration and Low indicates documented external dependence. High supply support requires bulk logistics plus qualification records, while Medium indicates narrower support and Low indicates limited verified coverage.
Key Developments in the Aluminium Fluoride Market
- In July 2026, Alufluoride Limited began restoring normal Visakhapatnam operations after its hydrofluosilicic acid supplier confirmed resolution of the raw-material disruption.
- In April 2026, Do-Fluoride New Materials Co., Ltd. filed its 2025 annual report showing a 30,000-tonne-per-year anhydrous aluminium fluoride project under construction alongside its existing commercial production base.
- In March 2025, PhosAgro completed another expansion stage at its Cherepovets aluminium fluoride shop and raised annual output by 4.5 thousand tonnes to 79 thousand tonnes.
Key Players in the Aluminium Fluoride Market
European and Mediterranean Producers
- Fluorsid S.p.A.
- Industries Chimiques du Fluor (ICF)
- Derivados del Fluor S.A.U. (DDF)
Dedicated Aluminium Fluoride Producers
- Do-Fluoride New Materials Co., Ltd.
- Alufluor AB
- Alufluoride Limited
Integrated Chemical Producers
- PhosAgro
- Tanfac Industries Limited
Aluminium Fluoride Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By grade, application and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial aluminium fluoride supplied for primary aluminium smelting and other industrial applications within the defined grade and application taxonomy. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | Saudi Arabia, Canada, Russia, United States, Brazil, and 20+ countries included in the full report. |
| Key Companies Profiled | Fluorsid S.p.A., Industries Chimiques du Fluor (ICF), Derivados del Fluor S.A.U. (DDF), Do-Fluoride New Materials Co., Ltd., Alufluor AB, Alufluoride Limited, PhosAgro, Tanfac Industries Limited. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Aluminium Fluoride Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Aluminium Fluoride Market by Segments
Aluminium Fluoride Market segmented by Grade:
- Metallurgical
- Other Industrial
Aluminium Fluoride Market segmented by Application:
- Aluminium (Primary Smelting)
- Fluorocarbons
- Ceramic
- Chemical Intermediate
- Others
Aluminium Fluoride Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- Norsk Hydro ASA. (2026, February 13). Integrated Annual Report 2025: Increasing resilience to reach 2030 ambitions.
- USA Geological Survey. (2026, February 6). Mineral Commodity Summaries 2026.
- Alufluoride Limited. (2026, May 23). Intimation of disruption in operations.
- Alufluoride Limited. (2025, May 31). Annual Report 2024-25.
- USA Department of Energy. (2026, February 10). Energy Department Awardee to Build First American Aluminum Smelter Since 1980.
- Conseil du Marché Financier. (2026, April 23). Bulletin officiel no. 7597: Société Industries Chimiques du Fluor communiqué.
- Alufluor AB. (2025, June). Alufluor Sustainability Report 2024.
- Maaden. (2025, June 3). Maaden to acquire full ownership of aluminium and bauxite assets in major strategic move.
- Innovation, Science and Economic Development Canada. (2026, May 29). Minister Joly announces $100 million investment to transform Canada’s aluminum sector.
- RUSAL. (2025, July 1). RUSAL implements AI to monitor alloy production.
- USA Department of Energy. (2025, January 15). Award Wednesday | January 15, 2025.
- Brazilian Aluminium Association. (2026, July 15). Indústria do alumínio resiste ao cenário global adverso, mas importados avançam no mercado nacional.
- Alufluoride Limited. (2026, July 15). Resumption of normal operations at Visakhapatnam plant.
- Do-Fluoride New Materials Co., Ltd. (2026, April 16). 2025 Annual Report.
- PhosAgro. (2025, November 20). PhosAgro Board of Directors Reviews Progress on Key Investment Projects.
- FLUORSID S.p.A. (2025, November). Sustainability Report 2024.
- Derivados del Flúor S.A.U. (2025, May). Informe de Seguridad, Medio Ambiente y Energía 2024.
- PhosAgro. (2025, June 2). Integrated Report 2024.
- Tanfac Industries Limited. (2026, February 12). Institutional Investor Presentation.
- Ministry of Environment and Energy Security, Italy. (2025, April 1). Stabilimento di Macchiareddu - Assemini.
- United Company RUSAL. (2026, April 29). Consolidated Report 2025.
- ABx Group Limited. (2026, March 27). Hydrogen Fluoride Pilot Plant Enters Construction Phase.
- Falcon Energy Materials plc. (2025, May 20). Falcon Announces Strategic Partnership with Fluoralpha to Advance Anode Plant Development in Morocco.
- Alufluoride Limited. (2025, March 20). Notice of Postal Ballot of Alufluoride Limited.
- Tanfac Industries Limited. (2025, September 3). Annual Report 2024-2025.
- Hubei Yihua Chemical Industry Co., Ltd. (2025, August 23). 2025 Half-Year Report.
- Conseil du Marché Financier. (2026, May 8). États financiers: Société Les Industries Chimiques du Fluor - ICF.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the aluminium fluoride market in 2026 and what value is forecast for 2036?
- Which operating conditions sustain recurring aluminium fluoride demand inside primary smelters?
- Why does metallurgical grade hold the leading position within the grade category?
- Why does aluminium for primary smelting account for most aluminium fluoride application demand?
- How do forecast growth rates differ among Saudi Arabia, Canada, Russia, the United States and Brazil?
- Which companies supply aluminium fluoride through integrated, regional and dedicated production positions?
- Which feedstock and plant-reliability constraints can weaken profitable aluminium fluoride supply?
- What should smelter process teams evaluate before approving an aluminium fluoride supplier?
Frequently Asked Questions
How big is the Aluminium Fluoride Market in 2026?
The aluminium fluoride market is valued at USD 2.3 billion in 2026 and is projected to reach USD 3.5 billion by 2036. Primary aluminium smelters sustain the forecast through repeated fluoride replenishment during continuous electrolyte control.
What is the CAGR of the Aluminium Fluoride Market from 2026 to 2036?
The aluminium fluoride market is projected to grow at a CAGR of 4.6% between 2026 and 2036. Expansion follows repeat smelter consumption and selected capacity additions that require newly qualified electrolyte inputs for operation.
Which grade leads the Aluminium Fluoride Market?
The metallurgical segment is expected to hold 91.6% of the aluminium fluoride market in 2026, driven by large qualified smelter volumes used in electrolysis. Continuous electrolyte control ties metallurgical material directly to scheduled potline replenishment and qualification cycles.
Which application leads the Aluminium Fluoride Market?
The aluminium for primary smelting segment is expected to hold 91.8% of the aluminium fluoride market in 2026, attributable to potline operation renewing electrolyte requirements. Other industrial applications purchase smaller volumes through less concentrated and more fragmented demand channels.
Which companies are active in the Aluminium Fluoride Market?
The aluminium fluoride market includes Fluorsid S.p.A., Industries Chimiques du Fluor (ICF), Derivados del Fluor S.A.U. (DDF), Do-Fluoride New Materials Co., Ltd., Alufluor AB, Alufluoride Limited, PhosAgro, and Tanfac Industries Limited. These companies compete through feedstock control and qualification support for contracted bulk deliveries.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Grade, 2026 to 2036
- Metallurgical
- Other Industrial
- Metallurgical
- Y-o-Y Growth Trend Analysis By Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Aluminium (Primary Smelting)
- Fluorocarbons
- Ceramic
- Chemical Intermediate
- Others
- Aluminium (Primary Smelting)
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Grade
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Grade
- By Application
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Grade
- By Application
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Grade
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Fluorsid S.p.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Industries Chimiques du Fluor (ICF)
- Derivados del Fluor S.A.U. (DDF)
- Do-Fluoride New Materials Co., Ltd.
- Alufluor AB
- Alufluoride Limited
- Morita Chemical Industries Co., Ltd.
- PhosAgro
- Shandong Zhenbo New Materials
- Fluorsid S.p.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


