

- Market Size (2026)
- USD 148.5 Bn
- Forecast (2036)
- USD 215.6 Bn
- CAGR (2026 to 2036)
- 3.8%
How big is Beer Market in 2026?
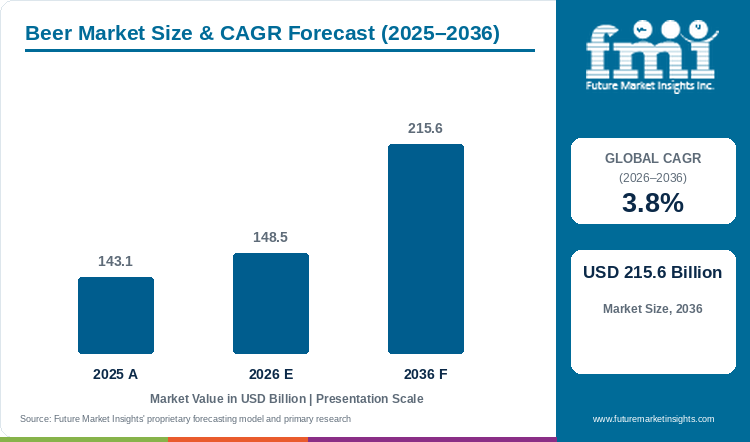
Sales in the beer market are projected to grow at 3.8% CAGR, with the market size rising from USD 143.1 billion in 2025 to USD 148.5 billion in 2026 and reaching USD 215.6 billion by 2036.
Managing mashing thermal profiles and dissolved oxygen levels across high-speed packaging lines has become essential for commercial breweries seeking shelf-stable flavor consistency. In April 2026, the Brewers Association reported that independent and regional brewers prioritized cold-fermented lagers and packaged draught quality to stabilize commercial barrel volumes [1]. Hospitality buyers and supermarket chains demand crisp malt brews that resist papery oxidation during ambient warehouse storage. As per FMI, global beer sales rise from USD 143.1 billion in 2025 to USD 148.5 billion in 2026 and reach USD 215.6 billion by 2036 at a 3.8% CAGR, generating USD 67.1 billion in added revenue with Standard Classic Formulation holding 39.5% share in 2026.
Key Market Trends & Insights
- By type / formulation: With a 39.5% share in 2026, standard classic formulation led the category because crisp bottom-fermented lagers pair across diverse dining occasions.
- By packaging format: Glass bottles (750ml) held the leading share of 41.4% in 2026, underpinned by amber ultraviolet light protection and table-sharing presentation.
- By distribution channel: Off-trade retail supermarkets and liquor stores accounted for 52.0% of demand in 2026, driven by chilled beer-cave variety packs and home consumption.
Regional Highlights
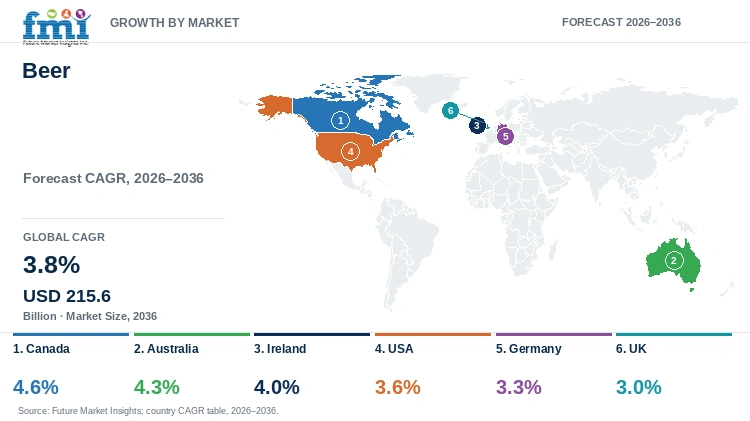
- Fastest-growing evaluated country: Canada, at 4.6% CAGR from 2026 to 2036.
- By country: Australia at 4.3%, Ireland at 4.0%, the USA at 3.6%, and Germany at 3.3% follow, while the UK records the lowest evaluated CAGR at 3.0%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Beer Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 143.1 billion |
| Estimated Market Size in 2026 | USD 148.5 billion |
| Projected Market Size by 2036 | USD 215.6 billion |
| CAGR, 2026 to 2036 | 3.8% |
| Added Revenue, 2026 to 2036 | USD 67.1 billion |
Bi-annual alcohol excise indexation in Australia and ABV-banded Draught Relief duties in the United Kingdom contrast with newly liberalized grocery and convenience beer licensing across Canadian provinces, reshaping how brewers allocate packaging formats. Brewhouse procurement teams also contend with shifting protein and moisture levels in two-row spring barley harvests across temperate grain belts. October 2026 updates to the Food and Agriculture Organization global cereal supply and demand brief tracked coarse grain and malting barley balances across major exporting regions [2]. Brewing groups are therefore locking in forward contracts for malted cereal grains and installing membrane wort filters to protect brewhouse extract yields.
Brewhouse Capacity and Fermentation Efficiency Operating Metrics
Table 2: Brewhouse Capacity and Fermentation Efficiency Operating Metrics for the Beer Market (USD billion and operational parameters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 143.1 | 148.5 | 215.6 |
| Global commercial beer production volume (billion hectoliters) | 1.88 | 1.94 | 2.52 |
| Average brewhouse extract efficiency percentage (dry basis) | 88.0 to 92.0 | 89.0 to 93.0 | 91.0 to 95.0 |
| Fermentation attenuation cycle duration (days) | 7 to 14 | 6 to 12 | 5 to 10 |
Brewhouse scope: Extract efficiency and cellar attenuation durations reflect commercial mash-filter conversion and cylindroconical fermentation benchmarks.
Facility Capital Expenditure & Packaging Yardstick Metrics
Keeping dissolved oxygen below 50 parts per billion from bright-beer tanks through crown capping requires automated deaerated water blending and double-pre-evacuation rotary fillers. Mechanical vapor recompression on wort kettles cuts brewhouse steam consumption by thirty percent while CO2 recovery scrubbers capture fermentation gas for packaging purge cycles. Strong off-trade grocery demand for craft variety twelve-packs and commercial drink cans is also prompting regional brewers to add flash pasteurizers and automated multi-pack cartoning lines.
Table 3: Facility Capital Expenditure and Processing Yardstick Metrics for the Beer Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Operational commercial breweries globally (units) | 12400 | 12900 | 17500 |
| Automated five-vessel brewhouse installation (USD million) | 4.5 to 7.2 | 4.8 to 7.8 | 6.8 to 11.2 |
| Rotary glass bottling and crown capping line spend (USD million) | 5.2 to 8.5 | 5.5 to 9.0 | 7.8 to 12.5 |
| Fermentation cellar yeast propagation and assay outlay (USD) | 850 to 1400 | 900 to 1500 | 1300 to 2100 |
Table 4: Facility & Operational Cost Benchmark Metrics for the Beer Market (USD and unit parameters), mixed reporting years from 2024 to 2026
| Operational Cost Indicator | 2024 | 2025 | 2026 |
|---|---|---|---|
| Two-row brewing barley malt cost per metric ton (USD) | 480 to 620 | 460 to 590 | 450 to 580 |
| Aroma hop pellets procurement expense per kilogram (USD) | 28 to 44 | 30 to 48 | 32 to 52 |
| Thermal energy expense for wort boiling per hectoliter (USD) | 3.2 to 4.8 | 3.4 to 5.1 | 3.6 to 5.4 |
| Glass bottle packaging and cardboard carton cost per case (USD) | 1.85 to 2.60 | 1.92 to 2.75 | 2.00 to 2.90 |
Analyst Perspective
"Low-temperature vacuum dealcoholization lets brewers strip ethanol below 35 degrees Celsius without cooking off delicate hop aromatics. Inflation-indexed alcohol excise duties and glass furnace energy costs still squeeze regional pub and microbrewery margins."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the beer market segmented?
The beer market is segmented by type / formulation, packaging format, distribution channel, and region. In 2026, standard classic formulation is projected at 39.5%, glass bottles (750ml) at 41.4%, and off-trade supermarkets & liquor stores at 52.0%.
By type / formulation: Standard Classic Formulation, flavored & specialty craft beer, and low & non-alcoholic beer.
By packaging format: Glass Bottles (750ml), aluminum cans, and draught kegs.
By distribution channel: Off-Trade (Retail Supermarkets & Liquor Stores), on-trade (bars, pubs, restaurants & hotels), and direct-to-consumer & brewery taprooms.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does Standard Classic Formulation lead the type and formulation category?
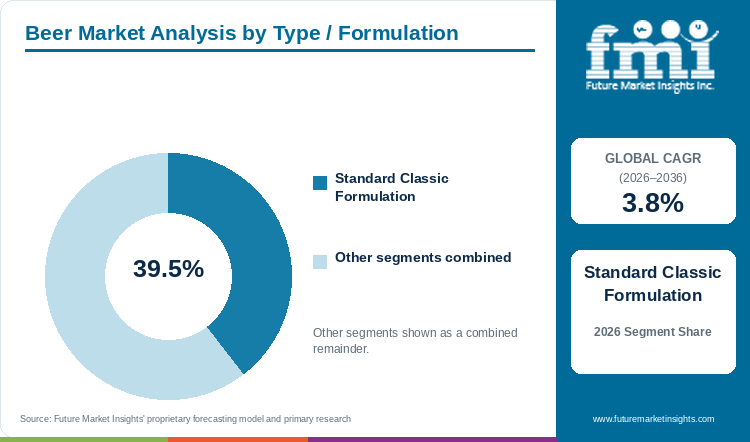
Standard classic formulation is estimated to represent 39.5% of type formulation demand in 2026, enabled by balanced malt drinkability.
Table 5: Type / Formulation Share for the Beer Market (percentage share), 2026
| Type / Formulation | Share (2026) |
|---|---|
| Standard Classic Formulation | 39.5% |
| Other Segments Combined | 60.5%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Type / Formulation Leadership and Market Growth for the Beer Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 3.8% |
| Leading Segment | Standard Classic Formulation |
Crisp, bottom-fermented pilsners and golden lagers keep standard classic formulations at the top of commercial brewhouse schedules because moderate bitterness units and clean malt attenuation appeal to the widest adult demographic. Pitching pure Saccharomyces pastorianus yeast across premium lager styles at 8 to 12 degrees Celsius ferments wort without heavy isoamyl acetate esters, delivering the snappy finish expected in stadiums, restaurants, and family gatherings. High-gravity brewing of classic lagers also maximizes fermenter turnover compared with multi-month barrel-aged sours. Pale golden beer leaves zero cover for diacetyl or papery trans-2-nonenal notes, so cellars monitor lagering temperatures strictly.
- Standard classic formulation accounts for 39.5% of type and formulation revenue in 2026, enabled by clean lager drinkability and high-volume hospitality turnover.
- European Brewery Convention proceedings in May 2025 published fermentation kinetics findings showing that hybridized lager yeast strains shortened cold-maturation diacetyl rest cycles [3].
What keeps Glass Bottles (750ml) ahead by packaging format?
Glass bottles (750ml) are expected to retain 41.4% of packaging format revenue in 2026, linked to ultraviolet hop protection.
Light wavelengths below 450 nanometers cleave hop iso-alpha acids in the presence of riboflavin, creating light-struck skunky thiols within minutes if beer sits in clear glass or sunlit coolers. Thick 750-milliliter amber bottles filter out those ultraviolet rays while holding high volumes of carbonation for bottle-conditioned abbey ales, stouts, and sharing lagers brewed with specialty malt ingredients. Hospitality sommeliers and off-trade gift buyers also prefer cork-and-cage or crown-capped 750-milliliter bottles for tabletop service. Because heavy glass raises freight fuel burn, European and Latin American brewers circulate standardized returnable bottles through caustic bottle-washing pools.
- Glass bottles (750ml) represent 41.4% of packaging format demand in 2026, linked to ultraviolet hop protection, zero oxygen permeability, and dining presentation.
- Master Brewers Association of the Americas studies in July 2025 documented that double-pre-evacuation rotary crown fillers cut bottleneck headspace oxygen pickup across 750ml packaging lines [4].
Why does Off-Trade lead the distribution channel category?
Off-trade supermarkets and liquor stores are projected to hold 52.0% of distribution channel sales in 2026, stemming from multipack promotions.
Wide price gaps between on-premise pub pints and grocery multi-packs continue to shift weekend beer occasions into home refrigerators and backyard gatherings. Supermarkets and licensed liquor stores dedicate walk-in cold rooms to craft variety twelve-packs, imported Mexican and European lagers, and low-carb brews attenuated with industrial brewing enzymes that hydrolyze residual dextrins. Tying loyalty-card beer discounts to televised football and cricket fixtures further lifts off-trade case volume. Regional microbreweries seeking national grocery listings must still absorb slotting fees and guarantee uninterrupted summer replenishment.
- Off-trade supermarkets and liquor stores hold 52.0% of distribution channel revenue in 2026, stemming from chilled multi-pack value pricing and home consumption habits.
- In July 2026, the Brewers Association Midyear Report noted that off-premise supermarket scan velocity remained the primary volume anchor for packaged craft and import beers [5].
What are the drivers, restraints, and opportunities in the beer market?
Artisanal hop-forward brewing and premium cold-filtered lagers support revenue expansion, whereas alcohol excise indexation and glass and aluminum packaging costs restrain volume growth, and vacuum-dealcoholized zero-proof beers unlock new daytime and wellness occasions.
- Driver: Consumer trade-up toward flavourful craft ales, regional aroma-hop varieties, and crisp imported lagers sustains value growth across retail and dining channels.
- Restraint: Recurring government excise duty increases, public health moderation policies, and high glass and aluminum packaging costs compress brewer margins.
- Opportunity: Membrane and vacuum dealcoholization technologies preserve authentic malt and hop esters in 0.0% ABV beers, opening daytime and athletic retail occasions.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Value growth in mature beer markets rests on drinkers trading up from economy domestic cans to dry-hopped pale ales, unfiltered Kellerbiers, and imported dry lagers. Brewmasters increasingly bypass heavy kettle bitterness and dose late-whirlpool T90 pellets alongside volatile hops essential oils on the cold side of the cellar to lock in mango, grapefruit, and pine aromatics without vegetative polyphenol bite. International Hop Growers Convention acreage reports in August 2025 confirmed an increased commercial share for high-alpha and proprietary aroma hop cultivars [6]. Flowable hop oil extracts also cut beer loss trapped in spent hop trub by up to twenty percent.
Risk Assessment of the Beer Market: Operational and Formulation Friction
Inflation-linked alcohol excise hikes and energy surcharges on container glass and aluminum sheet put steady pressure on brewery operating margins. Whenever finance ministries raise per-hectoliter beer duties, pub pint prices and supermarket case tags climb, encouraging younger legal-drinking-age cohorts to drink less frequently or switch to smaller packs. Glass furnaces and aluminum rolling mills also pass natural-gas and electricity tariffs directly onto buyers of amber glass bottles and cans. In June 2025, World Health Organization alcohol monitoring frameworks documented expanding national fiscal excise measures and marketing restrictions across European and Asia-Pacific jurisdictions [7]. Independent brewpubs lacking commodity hedges absorb the sharpest margin compression.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Stripping ethanol under deep vacuum at 30 to 35 degrees Celsius combined with aroma-recovery condensers has solved the worty, cooked flavor that once held back non-alcoholic craft beers. By capturing volatile hop and yeast esters before dealcoholization and dosing them back into 0.0% bright beer, brewers now match the body and head retention of full-strength pilsners and stouts. In March 2025, Anheuser-Busch InBev committed EUR 30 million to expand zero-alcohol brewing and dealcoholization capabilities across its European production network [8]. Zero-proof draught taps and isotonic 0.0% six-packs let brewers capture weekday business lunches, corporate events, and post-run occasions.
Beer Market by Country (2026 to 2036)
According to FMI, Canada posts the strongest growth among the six evaluated beer markets at a 4.6% CAGR from 2026 to 2036, while the United Kingdom expands at 3.0% CAGR. Country-level performance is shaped by provincial and national retail licensing reforms, ABV-tiered excise duty brackets, and consumer adoption of 0.0% draught and craft variety packs.
Table 7: Country CAGR and Primary Growth Levers for the Beer Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Canada | 4.6% | Expanded grocery and convenience retail access alongside provincial craft variety packs |
| Australia | 4.3% | Strong outdoor demand for tropical pale ales and tax-advantaged mid-strength beers |
| Ireland | 4.0% | Global dry stout export momentum and surging domestic 0.0% draught pub tap installations |
| USA | 3.6% | Large regional craft taproom base and rapid supermarket adoption of non-alcoholic brews |
| Germany | 3.3% | Reinheitsgebot brewing heritage paired with isotonic alcohol-free wheat beer growth |
| UK | 3.0% | Draught Relief duty differentials for pub kegs and off-trade premium world lager sales |
Source: Future Market Insights analysis
Canada Beer Market Outlook (2026 to 2036)
Opening thousands of convenience stores, supermarkets, and big-box grocers to beer and ready-to-drink multi-packs in Ontario has widened chilled retail access across Canada, propelling a 4.6% CAGR from 2026 to 2036. Domestic brewhouses draw on high-diastatic Prairie two-row barley to craft cold-filtered lagers and seasonal hazy IPAs. In October 2025, Beer Canada reported that domestic brewers expanded packaged variety-pack and non-alcoholic beer distribution across newly licensed grocery and convenience outlets [9]. Interprovincial trade markups and graduated federal excise duties still challenge small microbreweries, which rely on high-margin taproom pints and local twelve-packs.
Key takeaway: In Canada, convenience-store beer deregulation and Prairie malting barley supply underpin a leading 4.6% CAGR.
Australia Beer Market Outlook (2026 to 2036)
Twice-yearly federal excise indexation tied to the consumer price index makes full-strength pub pints expensive in Sydney and Melbourne, steering Australian drinkers toward tax-advantaged mid-strength (3.0% to 3.5% ABV) pale ales and crisp lagers. Australia's beer sector is projected to expand at a 4.3% CAGR through 2036 as coastal brewpubs and off-trade bottle shops champion tropical Galaxy and Enigma hop profiles. Independent Brewers Association scan data in August 2025 confirmed that mid-strength and tropical hop-forward craft beers captured growing off-premise scan share [10]. Brewers mash at higher dextrin temperatures so 3.5% ABV beers retain full-bodied mouthfeel.
Key takeaway: In Australia, steep ABV excise brackets make full-flavored 3.5% mid-strength pale ales and lagers the core growth engine.
Ireland Beer Market Outlook (2026 to 2036)
Global export demand for nitrogenated dry stouts and rapid domestic pub rollout of 0.0% draught keg taps place Ireland on a 4.0% CAGR trajectory from 2026 to 2036. Rather than confining alcohol-free beer to bottled singles, Irish publicans now pour nitrogenated 0.0% stout directly from dedicated bar fonts alongside traditional full-strength taps. In September 2025, Drinks Ireland's Irish Brewers Association reported that national beer exports rose 7.0% while zero-alcohol beer market share continued to climb across domestic pubs [11]. Statutory minimum unit pricing blocks deep supermarket price cuts, keeping competition focused on roast-barley heritage and pour quality.
Key takeaway: In Ireland, booming international stout exports and dedicated 0.0% pub draught taps sustain a 4.0% annual expansion.
USA Beer Market Outlook (2026 to 2036)
Over nine thousand independent craft brewhouses, regional taprooms, and large domestic lagering plants anchor the United States market, where beer revenue is forecast to advance at a 3.6% CAGR between 2026 and 2036. In August 2026, the U.S. Alcohol and Tobacco Tax and Trade Bureau updated its national beer production and taxable removals statistical reporting across domestic brewing tiers [12]. Intense cold-box competition from canned spirit cocktails and hard iced teas has pressured legacy economy light lagers. U.S. brewers are offsetting that volume shift by scaling crisp Mexican-style import lagers, juicy hazy IPAs, and dedicated athletic non-alcoholic craft six-packs.
Key takeaway: In the USA, strong supermarket rotation into Mexican-style import lagers, hazy IPAs, and non-alcoholic craft cans supports revenue growth.
Germany Beer Market Outlook (2026 to 2036)
Brewing strictly with water, malted barley, hops, and yeast under the Reinheitsgebot while marketing 0.0% wheat beers (Alkoholfreies Weissbier) as isotonic sports recovery drinks defines the Germany market, which is projected to grow at a 3.3% CAGR through 2036. Finish-line tents at German marathons and cycling tours routinely serve vitamin-B-rich alcohol-free wheat beers and pilsners. German Brewers Association production releases in November 2025 reported that over 800 alcohol-free and organic beer brands are now produced domestically as non-alcoholic output rose 8.0% [13]. Aging demographics still temper traditional full-strength volume, prompting Bavarian and northern breweries to expand Hellbier and zero-proof exports.
Key takeaway: In Germany, isotonic 0.0% wheat beers and regional Hellbier lagers offset gradual demographic moderation in full-strength styles.
UK Beer Market Outlook (2026 to 2036)
Tax cuts on pub kegs under the UK Draught Relief scheme and a lower excise band for beers at or below 3.4% ABV are reshaping recipe design across the United Kingdom, supporting a 3.0% CAGR from 2026 to 2036. British Beer and Pub Association statistical handbooks in December 2025 confirmed that low-alcohol and zero-alcohol beer volumes rose 12.0% across licensed pubs and off-trade supermarkets [14]. Steep commercial energy tariffs, business rates, and Extended Producer Responsibility packaging fees still strain community pubs. British brewers protect pub accounts by re-engineering session ales to 3.4% ABV while expanding off-trade world-lager multipacks.
Key takeaway: In the UK, 3.4% ABV tax thresholds and Draught Relief keg discounts guide brewer reformulation and pub tap allocation.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the beer market?
Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Asahi Group Holdings, Molson Coors Beverage Company, Boston Beer Company, Constellation Brands, Kirin Holdings Company, Tsingtao Brewery, and Diageo plc (Guinness) are the notable companies in this market.
Controlling captive malting barley supply, returnable glass bottle pools, and national wholesaling networks gives Anheuser-Busch InBev, Heineken, and Carlsberg a decisive scale advantage across off-trade supermarkets and hospitality venues. All three mega-brewers are also installing vacuum dealcoholization columns to scale low-alcohol malt beverages and 0.0% draught kegs. In North America and Europe, Constellation Brands, Molson Coors, Boston Beer Company, and Diageo capture high unit margins through Mexican import lagers, regional craft ales, and nitrogenated stouts, while Asahi, Kirin, and Tsingtao lead East Asian dry lagers.
- Global Mega-Brewing & Zero-Proof Platforms: Anheuser-Busch InBev, Heineken N.V., and Carlsberg Group operate multi-continent brewhouses, malting plants, and vacuum dealcoholization lines.
- North American & European Premium Import, Stout & Craft Leaders: Constellation Brands, Molson Coors Beverage Company, Boston Beer Company, and Diageo plc (Guinness) lead specialty ale, stout, and Mexican import categories.
- Asia-Pacific Precision Fermentation & Dry Lager Champions: Asahi Group Holdings, Kirin Holdings Company, and Tsingtao Brewery supply cold-filtered dry lagers and functional non-alcoholic malt brews.
Competitive Benchmarking: Beer Market
Table 8: Competitive Benchmarking for the Beer Market (qualitative capability ratings), 2026
| Company | Lager & Craft Portfolio Breadth | Non-Alcoholic & Low-ABV Depth | Off-Trade & On-Trade Access | Geographic Reach |
|---|---|---|---|---|
| Anheuser-Busch InBev | High | High | High | High |
| Heineken N.V. | High | High | High | High |
| Carlsberg Group | High | High | High | High |
| Asahi Group Holdings | High | High | High | High |
| Molson Coors Beverage Company | High | Medium | High | High |
| Boston Beer Company | High | Medium | High | Medium |
| Constellation Brands | Medium | Medium | High | Medium |
| Kirin Holdings Company | High | High | High | High |
| Tsingtao Brewery | High | Medium | High | High |
| Diageo plc (Guinness) | Medium | High | High | High |
Scoring basis: Brewers achieve a High rating in Lager & Craft Portfolio Breadth when they brew core pilsners, regional craft IPAs, and seasonal dark ales across multiple price tiers. Non-Alcoholic & Low-ABV Depth is rated High where vacuum distillation or arrested fermentation with commercial brewer's yeast supports 0.0% draught and canned flagships. Off-Trade & On-Trade Access reflects supermarket beer-cave space and pub keg distribution, whereas Geographic Reach contrasts multi-continent brewing groups with North American import and craft specialists.
Key Developments in the Beer Market
- In April 2026, the Brewers Association hosted the 2026 World Beer Cup, recognizing commercial innovation across cold-fermented lagers, hazy IPAs, and non-alcoholic craft styles [15].
- In October 2025, Asahi Group Holdings expanded European retail and hospitality distribution for its Asahi Super Dry and 0.0% dry lager lines across Western European markets [16].
- In June 2025, Heineken N.V. upgraded its automated high-speed canning and returnable glass bottling lines across the Americas to improve dissolved-oxygen control and packaging efficiency [17].
Key Players in the Beer Market
Global Mega-Brewing & Zero-Proof Platforms
- Anheuser-Busch InBev
- Heineken N.V.
- Carlsberg Group
North American & European Premium Import, Stout & Craft Leaders
- Molson Coors Beverage Company
- Boston Beer Company
- Constellation Brands
- Diageo plc (Guinness)
Asia-Pacific Precision Fermentation & Dry Lager Champions
- Asahi Group Holdings
- Kirin Holdings Company
- Tsingtao Brewery
Beer Market - Report Scope
Table 9: Report Scope for the Beer Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type / Formulation; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial brewer revenue from standard lagers, specialty craft ales, stouts, wheat beers, and low/non-alcoholic malt beers sold in glass bottles, aluminum cans, and draught kegs within the listed segmentation. Excludes distilled spirits, wine, hard cider, and spirit-based ready-to-drink cocktails. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Canada, Australia, Ireland, USA, Germany, UK, and additional countries in the full report |
| Key Companies Covered | Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Asahi Group Holdings, Molson Coors Beverage Company, Boston Beer Company, Constellation Brands, Kirin Holdings Company, Tsingtao Brewery, Diageo plc (Guinness) |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Beer Market - Research Methodology
Table 10: Research Methodology for the Beer Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with master brewers, fermentation scientists, packaging plant directors, and retail off-trade beverage buyers across the value chain to validate brewhouse extract yields, dealcoholization costs, and shelf velocity trends. |
| Secondary Research | Secondary research included company annual reports, TTB taxable removals releases, Brewers Association statistical surveys, FAO malting barley briefs, European Brewery Convention proceedings, and national brewers association handbooks. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models pairing commercial brewhouse hectoliter output with off-trade and on-trade pricing tiers. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, malted barley and aroma hop trade balances, glass bottle and aluminum can shipments, and national alcohol excise tax receipts to ensure accuracy without double counting adjacent beverage categories. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's beverage econometric model, calibrating evaluated national growth rates against the 3.8% global baseline through verified adult per-capita consumption shifts, craft brewery licensing density, and on-trade versus off-trade channel dynamics. |
| Operational Benchmark Traceability | Operational benchmarks (commercial beer production volume, brewery hectoliter capacities, and packaging line fill speeds) represent modeled estimates synthesized from Brewers Association data, FAO agricultural briefs, TTB filings, and corporate brewer disclosures. |
Beer Market by Segments
Beer Market segmented by Type / Formulation:
- Standard Classic Formulation
- Flavored & Specialty Craft Beer
- Low & Non-Alcoholic Beer
Beer Market segmented by Packaging Format:
- Glass Bottles (750ml)
- Aluminum Cans
- Draught Kegs
Beer Market segmented by Distribution Channel:
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs, Restaurants & Hotels)
- Direct-to-Consumer & Brewery Taprooms
Beer Market by Region
- North America
- Canada
- United States
- Mexico
- Latin America
- Brazil
- Argentina
- Colombia
- Western Europe
- Germany
- United Kingdom
- Ireland
- Belgium
- Netherlands
- Eastern Europe
- Poland
- Czech Republic
- East Asia
- Japan
- China
- South Korea
- South Asia and Pacific
- Australia
- New Zealand
- India
- Middle East and Africa
- South Africa
- Nigeria
- Kenya
Research Sources and Bibliography
- [1] Brewers Association. (2026, April 14). National beer sales and production data: Annual craft and regional brewing industry review. Brewers Association Statistics and Data.
- [2] Food and Agriculture Organization. (2026, October 02). Global cereal supply and demand brief: Coarse grains and malting barley balances. FAO World Food Situation.
- [3] European Brewery Convention. (2025, May 19). Technical report on novel yeast hybridization and fermentation kinetics in lager brewing. EBC Proceedings No. 89.
- [4] Master Brewers Association of the Americas. (2025, July 11). Practical brewing science: Wort clarification and dissolved oxygen control in 750ml glass bottling. MBAA Technical Quarterly, 62(2), 115-130.
- [5] Brewers Association. (2026, July 22). 2026 midyear report: Off-premise retail scan performance and craft brewing stability. BA Economic Insights, 43, 18-32.
- [6] International Hop Growers Convention. (2025, August 14). World hop acreage, alpha-acid yield, and proprietary aroma compound indices. IHGC Annual Overview, 34, 18-35.
- [7] World Health Organization. (2025, June 28). Global alcohol consumption monitoring report, excise duty structures, and public health policy frameworks. WHO Fact Sheets on Alcohol.
- [8] Anheuser-Busch InBev. (2025, March 18). Investment in low-temperature vacuum dealcoholization facilities for zero-proof lagers in Western Europe. AB InBev Corporate Releases.
- [9] Beer Canada. (2025, October 21). Canadian brewing industry annual statistical bulletin: Provincial grocery and convenience sales trends. Beer Canada Report, 28, 40-56.
- [10] Independent Brewers Association. (2025, August 19). Australian craft beer survey: Excise indexation impact and mid-strength pale ale preferences. IBA Industry Data, 17, 30-46.
- [11] Irish Brewers Association. (2025, September 24). Annual report on Irish brewing performance: Global stout exports and domestic 0.0% draught sales. Drinks Ireland Publication, 23, 22-38.
- [12] Alcohol and Tobacco Tax and Trade Bureau. (2026, August 31). Monthly beer production and taxable removals statistical reports in the United States. U.S. Department of the Treasury TTB Beer Statistics.
- [13] German Brewers Association. (2025, November 14). Deutscher Brauer-Bund Jahresbericht: Market trends in Reinheitsgebot and isotonic alcohol-free beers. DBB Annual Review, 35, 45-62.
- [14] British Beer and Pub Association. (2025, December 10). Statistical handbook of the UK beer and pub industry: Draught relief and low-ABV shifts. BBPA Document No. 54.
- [15] Brewers Association. (2026, April 22). Brewing excellence shines at the 2026 World Beer Cup, marking 30 years of global competition. BA Association News.
- [16] Asahi Group Holdings, Ltd. (2025, October 15). International retail and hospitality expansion for Asahi Super Dry and 0.0% premium lager lines. Asahi Corporate Releases.
- [17] Heineken N.V. (2025, June 20). Upgrade of automated canning and returnable glass packaging infrastructure across the Americas. Heineken Corporate Filings.
- [18] Diageo plc. (2025, October 08). Doubling of Guinness 0.0% nitrogenated draught and can production capacity at St. James's Gate in Dublin. Diageo Investor News.
- [19] Carlsberg Group. (2025, September 12). Rollout of regenerative malting barley contracts and snap-pack low-carbon multipackaging across Europe. Carlsberg Sustainability Releases.
- [20] Constellation Brands, Inc. (2026, January 16). Expansion of high-capacity glass bottling and cold-filtered lager brewing capacity in Mexico for North American import channels. Constellation Corporate Reports.
- [21] Kirin Holdings Company, Limited. (2025, July 25). Commercial expansion of functional non-alcoholic malt beverages and precision fermentation lines in Japan. Kirin Group Newsroom.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the beer market in 2026 and what is forecast for 2036?
- Why does standard classic formulation lead the type and formulation category?
- What keeps 750ml glass bottles ahead across the packaging format category?
- Why do off-trade supermarkets and liquor stores command the largest distribution share?
- How do growth rates differ across Canada, Australia, Ireland, and the USA?
- Which notable companies supply commercial lagers, craft ales, and 0.0% beers today?
- What alcohol excise duty and packaging cost pressures restrain brewery margins?
- What should hospitality and off-trade buyers evaluate before approving a brewing supplier?
Frequently Asked Questions
How big is the beer market in 2026, and what is forecast for 2036?
The global beer market is projected to reach USD 148.5 billion in 2026 and expand to USD 215.6 billion by 2036, supported by craft beer premiumization and vacuum-dealcoholized non-alcoholic beer demand.
What is the CAGR for the beer market from 2026 to 2036?
FMI projections show that the beer market will advance at a 3.8% CAGR through 2036 as drinkers trade up to aroma-hop craft ales, imported lagers, and 0.0% draught and canned brews.
Which type and formulation segment leads the beer market in 2026?
Standard classic formulation is projected to hold 39.5% of type and formulation demand in 2026. Balanced malt sweetness, clean cold-fermented lager drinkability, and broad dining appeal sustain its leading position.
Which packaging format holds the largest beer share in 2026?
Glass bottles (750ml) are estimated to account for 41.4% of packaging format revenue in 2026. Amber glass ultraviolet hop protection, high carbonation retention, and tabletop presentation sustain bottle demand.
Which country has the fastest beer growth outlook through 2036?
As per FMI analysis, Canada leads with a 4.6% CAGR from 2026 to 2036, aided by widened grocery and convenience store beer licensing and provincial microbreweries.
Who are the notable companies active in the beer market?
Leading commercial brewers include Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Asahi Group Holdings, Molson Coors Beverage Company, Boston Beer Company, Constellation Brands, Kirin Holdings Company, Tsingtao Brewery, and Diageo plc (Guinness).
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type / Formulation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type / Formulation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type / Formulation, 2026 to 2036
- Standard Classic Formulation
- Flavored & Specialty Craft Beer
- Low & Non-Alcoholic Beer
- Y-o-Y Growth Trend Analysis By Type / Formulation, 2021 to 2025
- Absolute $ Opportunity Analysis By Type / Formulation, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles (750ml)
- Aluminum Cans
- Draught Kegs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs, Restaurants & Hotels)
- Direct-to-Consumer & Brewery Taprooms
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Canada
- United States
- Mexico
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Argentina
- Colombia
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Ireland
- Belgium
- Netherlands
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- China
- South Korea
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- South Africa
- Nigeria
- Kenya
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Ireland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type / Formulation
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Anheuser-Busch InBev
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Heineken N.V.
- Carlsberg Group
- Asahi Group Holdings
- Molson Coors Beverage Company
- Boston Beer Company
- Constellation Brands
- Kirin Holdings Company
- Tsingtao Brewery
- Diageo plc (Guinness)
- Anheuser-Busch InBev
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


