
- Market Size (2026)
- USD 2.2 Bn
- Forecast (2036)
- USD 4.5 Bn
- CAGR (2026 to 2036)
- 7.4%
How big is Bio-Plasticizers Market in 2026?
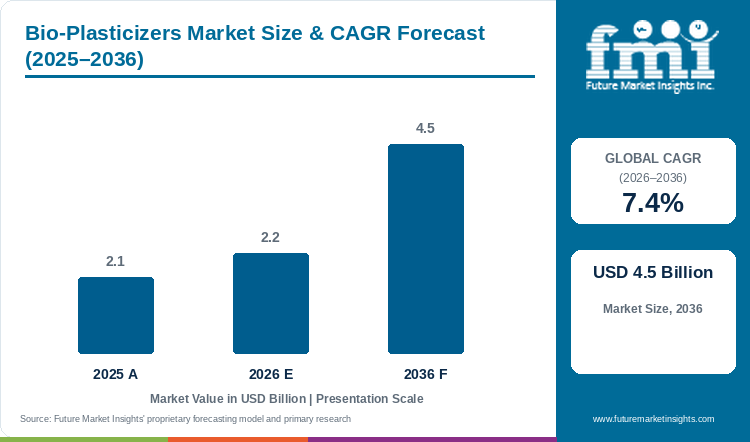
Assessed at USD 2.1 billion in 2025 and progressing to USD 2.2 billion in 2026, the bio-plasticizers market valuation is on course to reach USD 4.5 billion by 2036, supported by a forecast-period CAGR of 7.4%.
The global bio-plasticizers market was valued at USD 2.1 billion in 2025 and is estimated to reach USD 2.2 billion in 2026. Total market valuation is projected to reach USD 4.5 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.4% between 2026 and 2036. Formulation trend analysis by FMI indicates that epoxidized soybean oil holds an estimated 48.0% share of 2026 feedstock demand, given that flexible vinyl compounders rely on its oxirane rings to replace restricted ortho-phthalates while stabilizing polymer heat resistance. Demand for plant-derived plasticizers is accelerating as regulatory phase-outs of low-molecular-weight phthalates convert optional green reformulation into mandatory compliance across food wraps, medical blood bags, and indoor flooring.
In December 2025, the U.S. Environmental Protection Agency released its final Toxic Substances Control Act risk evaluation for diisobutyl phthalate following peer review of five restricted ortho-phthalates, compelling polymer processors to qualify non-toxic bio-esters. That PVC-dominated compliance volume differs from polylactic acid resins expanding at an 11.8% CAGR, since rigid biopolymer toughening grows from a smaller specialty base than bulk vinyl calendering. Oleochemical producers are introducing hazard-free esters to capture this substitution wave, illustrated in May 2026 when Emery Oleochemicals commercialized a 100% biobased EDENOL plasticizer to replace N-butylbenzene sulfonamide without safety hazard labeling. Compounders lock in multi-year bio-plasticizer contracts when renewable esters match petrochemical Shore A softness efficiency and pass migration testing through 2036.
Key Market Trends & Insights
- By chemical feedstock base: Epoxidized Soybean Oil ESBO holds an estimated 48.0% share in 2026 since integrated oilseed crushing chains supply cost-competitive epoxidized triglycerides for bulk vinyl compounding.
- By plastic compatibility: Polyvinyl Chloride PVC Flexible Compounds represent 74.0% in 2026 given that flexible PVC films, cables, and medical tubing require 20% to 50% plasticizer loading by weight.
- By end-use industry: Food Contact Packaging Films Tubing and Jar Gaskets account for 46.0% in 2026 owing to strict migration limits on synthetic phthalates in cling wraps and metal lid plastisols.
- By formulation function: Primary Monomeric Plasticizers secure 58.0% in 2026 through direct glass-transition temperature reduction in high-speed extrusion and calendering lines.
- By sales channel: Direct to Polymer Compounders and Calendering Plants commands 62.0% in 2026 via bulk heated-tanker deliveries and plant-specific migration qualification.
Regional Highlights
- Top national expansion: Brazil leads profiled national growth projections at an 8.4% CAGR through 2036 under abundant domestic soybean oil epoxidation feedstock and expanding food-packaging film production.
- Broader country progression: Mexico tracks at an 8.3% CAGR ahead of South Korea at 8.2% and the United States at 7.8%, while the United Kingdom advances at 7.6% and Japan progresses at 6.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Bio-Plasticizers Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 2.1 billion |
| Estimated Market Size in 2026 | USD 2.2 billion |
| Projected Market Size by 2036 | USD 4.5 billion |
| CAGR, 2026 to 2036 | 7.4% |
| Added Revenue, 2026 to 2036 | USD 2.3 billion |
Flexible polymer processors face mounting regulatory and brand-owner pressure to eliminate reproductive toxicants and endocrine-disrupting ortho-phthalates from consumer and medical plastics. When compounders substitute conventional di(2-ethylhexyl) phthalate with vegetable-oil epoxides or citrate esters, they also gain secondary thermal stabilization and improved polymer chain recovery during melt extrusion. Laboratory research published in ACS Omega in December 2025 demonstrated that incorporating 2.0 weight percent epoxidized soybean oil during reactive single-screw extrusion restores intrinsic viscosity, molecular weight, and tensile strength in recycled polyester matrices. Consequently, vinyl and biopolymer formulators are pairing epoxidized soybean oil with primary citrates to maintain film elasticity across high-speed packaging lines.
Bio-Plasticizer Tonnage & Polymer Loading Sizing
Table 2: Bio-Plasticizer Tonnage and Polymer Loading Sizing for the Bio-Plasticizers Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 2.1 | 2.2 | 4.5 |
| Global bio-plasticizer shipment volume (thousand metric tons) | 860 to 940 | 910 to 995 | 1,780 to 1,950 |
| Average bio-ester selling price range (USD per metric ton) | 2,180 to 2,420 | 2,210 to 2,460 | 2,310 to 2,580 |
| Active plasticizer loading in flexible PVC & PLA (phr / wt%) | 15 to 50 phr (PVC) / 10-20% (PLA) | 15 to 50 phr (PVC) / 10-20% (PLA) | 18 to 55 phr (PVC) / 12-22% (PLA) |
Food-contact cling films, closure gaskets, and beverage transfer hoses must comply with stringent European Union and North American overall migration limits when contacting fatty or acidic foods. As documented by the European Food Safety Authority in September 2026, regulatory assessors implemented new evaluation protocols for Substances of Very High Concern in plastic food contact materials under Commission Regulation (EU) 2025/351 purity amendments. Film converters in the food sector are therefore replacing legacy petrochemical additives with phthalate-free polymer plasticizers derived from acetylated citrates and high-oxirane soybean oil.
Feedstock Crushing & Compounder Line Indicators
Table 3: Global Bio-Plasticizer Feedstock and Compounding Indicators for the Bio-Plasticizers Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global soybean & canola oilseed crush supply (million MT) | 412.0 | 424.5 | 510.0 |
| Bio-plasticizer share of total global plasticizer volume (%) | 10.5% to 11.8% | 11.2% to 12.6% | 19.5% to 22.0% |
| Food-contact & medical phthalate-free compound share (%) | 64.0% to 68.0% | 67.0% to 71.0% | 86.0% to 91.0% |
| Average oxirane oxygen specification in premium ESBO (%) | 6.4% to 6.8% | 6.5% to 6.9% | 6.8% to 7.2% |
Table 4: Industrial Compounder & Channel Expenditure Indicators for the Bio-Plasticizers Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 2.2 billion | 2026 global bio-plasticizers revenue baseline |
| Epoxidized Soybean Oil (ESBO) revenue, 2026 | USD 1.06 billion | 48.0% chemical feedstock base allocation (USDA FAS soy crush base) |
| Flexible PVC compounds bio-plasticizer spend, 2026 | USD 1.63 billion | 74.0% plastic compatibility allocation (calendering & extrusion lines) |
| Direct to Polymer Compounders revenue, 2026 | USD 1.36 billion | 62.0% sales channel allocation (bulk heated-tanker contracts) |
Reduction of the natural brittleness of biopolymers such as polylactic acid and cellulose acetate requires low-volatility bio-esters that lower glass-transition temperatures without exudation during shelf storage. Technical application trials published by Jungbunzlauer in April 2025 confirmed that CITROFOL tributyl O-acetylcitrate esters effectively plasticize polylactic acid and biodegradable agricultural mulch films while preserving soil compostability. Masterbatch blenders combine these citrate esters with succinic acid ester derivatives to achieve tear-resistant blown films on conventional polyethylene extrusion equipment.
Analyst Perspective
"Polymer compounders do not pay a green premium for bio-plasticizers out of charity; they switch when regulatory bans remove ortho-phthalates from food, medical, and toy specifications and when high-oxirane epoxides or acetylated citrates run cleanly on existing calendering rolls without plasticizer exudation."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Bio-Plasticizers Market segmented?
The bio-plasticizers market is segmented by chemical feedstock base, plastic compatibility, end-use industry, formulation function, and sales channel. In 2026, Epoxidized Soybean Oil ESBO is projected at 48.0%, Polyvinyl Chloride PVC Flexible Compounds at 74.0%, Food Contact Packaging Films Tubing and Jar Gaskets at 46.0%, Primary Monomeric Plasticizers at 58.0%, and Direct to Polymer Compounders and Calendering Plants at 62.0%.
By chemical feedstock base: Epoxidized Soybean Oil ESBO, Citrate Esters Triethyl and Tributyl Citrate, and Sebacates and Castor Oil Ricinoleates. Additional feedstocks include Succinic Acid and Levulinic Acid Bio-Esters along with Adipates and Vegetable Oil Fatty Acid Methyl Esters.
By plastic compatibility: Polyvinyl Chloride PVC Flexible Compounds and Polylactic Acid PLA and Biopolymer Blends. Additional polymer systems cover Polyurethane PU and Synthetic Rubber Formulations along with Cellulose Esters and Acrylic Polymer Systems.
By end-use industry: Food Contact Packaging Films Tubing and Jar Gaskets and Medical Devices Blood Bags Infusion Lines and Catheters. Other end uses include Children Toys Childcare Articles and Teethers as well as Consumer Wire Cable Insulation and Vinyl Flooring.
By formulation function: Primary Monomeric Plasticizers and Secondary Heat-Stabilizing Co-Plasticizers. Further functions include Polymeric Low-Migration Bio-Plasticizers and Reactive Chain-Extending Modifiers.
By sales channel: Direct to Polymer Compounders and Calendering Plants and Specialty Chemical and Masterbatch Distributors. Other channels cover Contract Medical and Food-Grade Extruders and B2B Industrial Chemical Procurement Portals.
Why does Epoxidized Soybean Oil ESBO lead the chemical feedstock base category?
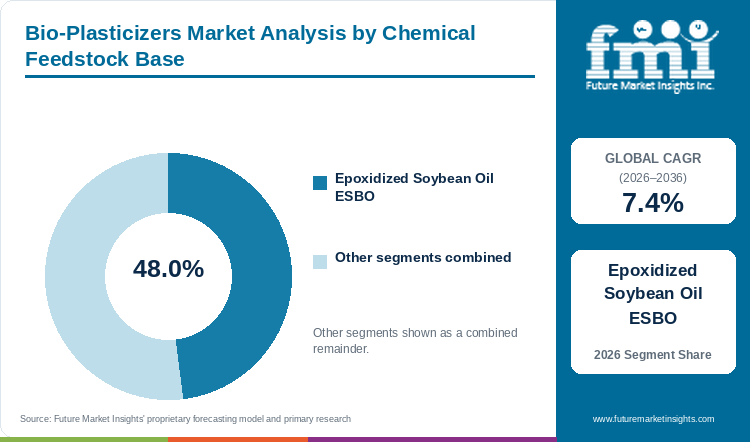
Epoxidized Soybean Oil ESBO holds an estimated 48.0% of chemical feedstock base demand in 2026, anchored by dual plasticizing and thermal HCl-scavenging performance in PVC.
Table 5: Chemical Feedstock Base Share for the Bio-Plasticizers Market (percentage share), 2026
| Chemical Feedstock Base | Share (2026) |
|---|---|
| Epoxidized Soybean Oil ESBO | 48.0% |
| Other Segments Combined | 52.0%* |
| Total | 100.0% |
*Note: Remaining chemical feedstock base categories account for the balance of 2026 global bio-plasticizers demand.
Table 6: Chemical Feedstock Base Leadership and Market Growth for the Bio-Plasticizers Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.4% |
| Leading Segment | Epoxidized Soybean Oil ESBO |
Epoxidized Soybean Oil ESBO anchors the chemical feedstock base category because large-scale soybean crushing and hydrogen peroxide epoxidation provide the lowest per-ton production cost among commercial renewable plasticizers. Beyond imparting flexibility to vinyl sheets and flexible vinyl packaging films, ESBO scavenges free hydrochloric acid liberated during high-temperature PVC extrusion, preventing polymer discoloration and thermal degradation. Limited compatibility at primary loadings above 15 parts per hundred resin in unmodified PVC can cause surface exudation, prompting compounders to blend ESBO with acetylated citrates or bio-succinates.
- Within the chemical feedstock base category, Epoxidized Soybean Oil ESBO is projected to account for a leading 48.0% share in 2026, supported by dual plasticizer-stabilizer functionality and global oilseed crushing scale.
- Major agricultural processors are upgrading epoxidation specifications, as documented in January 2026 by Cargill Incorporated, whose high-oxirane Vikoflex bio-based plasticizers deliver enhanced heat stability and low-temperature flexibility in custom PVC formulations.
What sustains Polyvinyl Chloride PVC Flexible Compounds leadership in the plastic compatibility segment?
Polyvinyl Chloride PVC Flexible Compounds represent 74.0% of the plastic compatibility category in 2026, supported by high liquid plasticizer loading across films, cables, and tubing.
Polyvinyl Chloride PVC Flexible Compounds consume nearly three-quarters of global bio-plasticizer tonnage because unplasticized PVC is a rigid polymer that requires 20% to 50% liquid ester incorporation to manufacture flexible medical tubing and calendered flooring. Unlike polyolefins that achieve flexibility through copolymerization, PVC relies on polar ester carbonyl groups to form dipole interactions with carbon-chlorine bonds, paired with emerging demand in castor-derived biopolymer compounds. Peer-reviewed polymer research published in Polymers in April 2026 confirmed that non-phthalate polyol and bio-based ester systems in PVC compounds satisfy European Regulation (EU) 2025/351 migration thresholds while maintaining tensile elongation. Volatile vegetable oil feedstock pricing still challenges margin stability for commodity vinyl extruders.
- In 2026, Polyvinyl Chloride PVC Flexible Compounds are anticipated to capture 74.0% of global plastic compatibility demand, reflecting high plasticizer weight fractions across flexible vinyl goods.
- While flexible PVC retains volume dominance through 2036, polylactic acid and biopolymer blends are forecast to post faster percentage growth as compostable film converters scale production.
How do Food Contact Packaging Films Tubing and Jar Gaskets lead the end-use industry category?
Food Contact Packaging Films Tubing and Jar Gaskets account for 46.0% of end-use industry demand in 2026, driven by FDA and EFSA EU 2025/351 non-phthalate migration rules.
Food-grade packaging wraps, dairy transfer tubing, and metal lug-cap plastisol gaskets represent the largest end-use sector because supermarket meat and produce wraps undergo direct contact with lipid-rich foods that extract conventional ortho-phthalates. Food processors and retail grocers mandate FDA 21 CFR and EU 10/2011 compliant epoxidized oils and citrates across both virgin wraps and recycled flexible packaging films to prevent chemical taint and regulatory recalls. Simultaneous control of low lipid-extraction migration rates and high-speed stretch-film cling performance remains the central formulation challenge for food-film extruders.
- By end-use industry, demand from Food Contact Packaging Films Tubing and Jar Gaskets is estimated to reach 46.0% of total category share in 2026 as food brands enforce phthalate-free packaging specifications.
- Academic formulation trials published in Polysaccharides in May 2025 demonstrated that modifying epoxidized soybean oil with cinnamic acid yields flexible food-packaging films with superior mechanical barrier stability.
Why do Primary Monomeric Plasticizers lead the formulation function category?
Primary Monomeric Plasticizers secure 58.0% of formulation function value in 2026, supported by rapid resin fusion and glass-transition temperature reduction.
Primary Monomeric Plasticizers lead formulation function revenue because low-viscosity monomeric esters such as acetyl tributyl citrate, dioctyl sebacate, and ring-opened fatty acid esters diffuse rapidly between polymer chains during dry-blending and melt compounding. Rapid gelation and fusion lower extruder torque and enable high line speeds across medical catheter tubing, toy plastisols, and flexible film calendering. In August 2026, polymer chemists reporting in Polymers synthesized and evaluated eleven novel renewable plasticizers, demonstrating that 15 to 20 weight percent bio-plasticizer loading sharply lowers glass-transition temperatures and elevates elongation at break up to 99% before phase separation occurs at 30 weight percent. Higher volatility compared with polymeric esters requires careful molecular-weight selection for high-temperature cables.
- With a projected 58.0% share of the formulation function segment in 2026, Primary Monomeric Plasticizers remain the core specification for compounders prioritizing rapid resin fusion and low Shore A hardness.
- Polymeric low-migration and reactive chain-extending bio-plasticizers are expected to gain incremental share in permanent automotive interior and under-hood wire harness applications through 2036.
What gives Direct to Polymer Compounders and Calendering Plants the leading position in sales channel?
Direct to Polymer Compounders and Calendering Plants commands 62.0% of sales channel share in 2026, anchored by bulk ISO-tanker supply and custom oxirane/migration qualification.
Direct to Polymer Compounders and Calendering Plants dominates sales channel distribution because vinyl calendering mills, wire-and-cable compounders, and medical plastisol formulators purchase liquid plasticizers in heated bulk road tankers and ISO tank containers. Direct technical supply agreements allow oleochemical manufacturers to tailor oxirane oxygen percentages, acid values, and APHA color stability to each customer's specific Banbury mixer or twin-screw extruder profile. Full line qualification of a replacement bio-plasticizer across medical or food-contact extrusion lines requires six to twelve months of accelerated aging and migration certification, locking in direct producer-to-compounder contracts.
- Direct to Polymer Compounders and Calendering Plants is predicted to secure 62.0% of sales channel demand in 2026, anchored by bulk liquid logistics and plant-level formulation audits.
- Specialty chemical producers are certifying mass-balance and bio-attributed supply chains for direct industrial accounts, as highlighted by LANXESS in November 2025 when it transitioned its Mesamoll plasticizer line to over 30% sustainable raw materials with a 20% lower product carbon footprint.
What are the drivers, restraints, and opportunities in the Bio-Plasticizers Market?
In the bio-plasticizers market, EPA TSCA and European REACH ortho-phthalate restrictions are projected to drive adoption whereas phase separation above 20 to 30 wt% loading restrains uncalibrated dosing and high-purity citrates, succinates, and isosorbide unlock medical and food-film upgrades.
- Driver: Tightening federal and international chemical restrictions on ortho-phthalates force PVC, rubber, and biopolymer processors to switch to epoxidized vegetable oils and citrate esters.
- Restraint: Excess dosing of epoxidized oils above compatibility thresholds triggers phase separation, surface exudation, and drop-offs in tensile strength unless reaction parameters are tightly controlled.
- Opportunity: High-purity fermented succinic acid, isosorbide, and castor sebacate esters open high-margin applications in medical blood bags and zero-migration electronics cables.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Federal chemical risk evaluations and mandatory retail phase-outs of ortho-phthalates are compelling flexible polymer manufacturers to reformulate vinyl and elastomer compounds with bio-based plasticizers, directly driving global volume expansion. When regulatory agencies classify legacy phthalates as high-priority hazards in food wraps and hospital tubing, compounders accelerate qualification of epoxidized soybean oil and bio-based levulinic esters. In June 2025, the U.S. EPA convened its Science Advisory Committee on Chemicals under Docket EPA-HQ-OPPT-2024-0551 to review risk evaluations for five regulated phthalates including DEHP, DBP, and DIBP. Consequently, North American and European vinyl processors are locking in long-term bio-ester supply contracts to eliminate regulatory compliance risk across consumer and institutional product lines.
Risk Assessment of the Bio-Plasticizers Market: Operational and Formulation Friction
Narrow compatibility windows and mechanical property trade-offs at elevated bio-plasticizer loadings restrain uncalibrated substitution in structural and recycled polymer compounds. While adding low concentrations of epoxidized vegetable oil improves impact toughness and melt flow, exceeding the polymer's solubility threshold causes plasticizer exudation and compromises seal strength in sterile blood bag assemblies. Experimental composite testing published in Materials in May 2025 demonstrated that introducing 0.5 weight percent epoxidized soybean oil raised Charpy notched impact strength from 7.5 to 20.0 kilojoules per square meter and bending strength from 31.6 to 50.8 megapascals, whereas higher loadings degraded mechanical strength. Formulators must therefore run rigorous Brabender torque and migration curves before scaling bio-plasticizer dosages.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Industrial scale-up of high-purity fermented succinates and bicyclic diol esters creates lucrative demand avenues in medical devices, optical packaging films, and bio-based packaging adhesives. Medical tubing extruders and premium food-packaging converters seek 100% bio-based monomers that deliver optical clarity, ultraviolet stability, and zero endocrine-disrupting activity. Technical product disclosures published by Roquette Frères in February 2026 confirmed that its USDA-certified 100% bio-based POLYSORB isosorbide and BIOSUCCINIUM succinic acid platform exceeds 99.5% purity while enhancing thermal and chemical resistance in performance polymers. Producers that supply pharmacopoeia-grade citrate, succinate, and isosorbide esters capture substantial margin premiums over commodity vegetable-oil epoxides.
Bio-Plasticizers Market by Country (2026 to 2036)
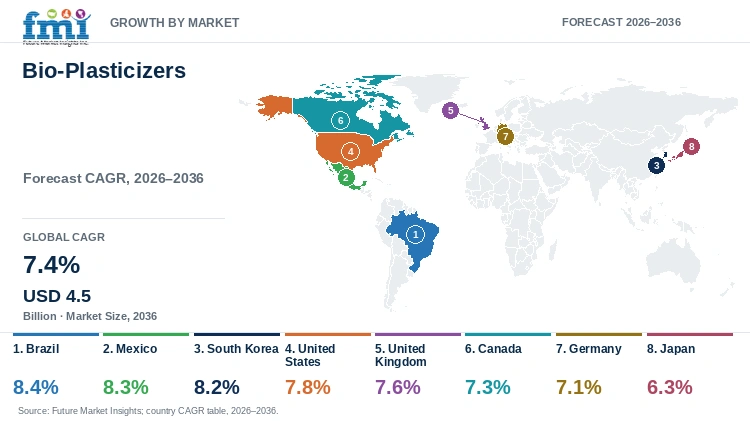
FMI country modeling indicates that Brazil leads profiled bio-plasticizers expansion at an 8.4% CAGR through 2036, closely followed by Mexico at 8.3% and South Korea at 8.2%, while Japan advances at 6.3%. National growth variations reflect domestic oilseed crushing availability, export food-packaging film conversion, and phthalate restriction enforcement.
Table 7: Country CAGR and Primary Growth Levers for the Bio-Plasticizers Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.4% | 178M-192M MT domestic soybean harvest and integrated ESBO packaging and footwear compounding |
| Mexico | 8.3% | 5.49M MT oilseed crush base and USMCA export medical tubing and automotive cable extrusion |
| South Korea | 8.2% | Phthalate-free heated Ondol residential vinyl flooring and cleanroom tubing conversion |
| United States | 7.8% | EPA TSCA phthalate risk evaluations, Midwest soy epoxidation, and DEHP-free hospital IV lines |
| United Kingdom | 7.6% | Supermarket phthalate-free food wrap charters and low-energy fast-fusing vinyl compounding |
| Canada | 7.3% | Record 21.8M MT canola harvest and cold-resistant sub-zero flexible PVC cable jacketing |
| Germany | 7.1% | 62% separate packaging recycling purity rules and mass-balance specialty ester biorefineries |
| Japan | 6.3% | Positive List food-contact purity standards and non-toxic medical and electronics wire esters |
Source: Future Market Insights analysis
Brazil Bio-Plasticizers Market Outlook (2026 to 2036)
Demand for bio-plasticizers in Brazil is projected to expand at a leading 8.4% CAGR between 2026 and 2036 as domestic oleochemical crushers convert abundant local soybean oil into epoxidized plasticizers for South American packaging and footwear compounders. What distinguishes Brazil from import-dependent chemical markets is its position as the world's largest soybean producer, providing integrated domestic feedstock for epoxidized soybean oil reactors in São Paulo and Mato Grosso. Field estimates from USDA FAS in March 2026 showed that Brazilian soybean production reached 178 million metric tons across 49.1 million hectares in marketing year 2025/26 and is forecast to hit 192 million metric tons in 2026/27. Domestic industrial output data from IBGE also confirmed 5.8% growth in Brazilian motor vehicle and auto-parts production through August 2026, supporting vinyl interior and cable compounding.
Key takeaway: In Brazil, record 178-to-192 million metric ton domestic soybean harvests and expanding food-film and automotive vinyl compounding are projected to drive a leading 8.4% CAGR.
Mexico Bio-Plasticizers Market Outlook (2026 to 2036)
In Mexico, bio-plasticizers procurement is anticipated to advance at an 8.3% CAGR from 2026 to 2036, fueled by export-oriented automotive wire-harness extrusion and medical device tubing manufacturing across Nuevo León and Baja California. Compared with domestic-focused Latin American markets, Mexican polymer compounders formulate to meet strict United States FDA food-contact and TSCA phthalate-free specifications for duty-free USMCA export. Official June 2026 agricultural records from the U.S. Department of Agriculture documented that Mexico accounted for 5.49 million metric tons of oilseed meal and associated vegetable oil crushing in marketing year 2025/26. Cross-border medical catheter and appliance cable plants rely heavily on imported and locally epoxidized soybean and citrate esters.
Key takeaway: In Mexico, USMCA-compliant medical tubing and automotive wire-harness export manufacturing are anticipated to sustain an 8.3% CAGR.
South Korea Bio-Plasticizers Market Outlook (2026 to 2036)
Projected to expand at an 8.2% CAGR through 2036, the South Korean bio-plasticizers market reflects rapid conversion toward non-phthalate vinyl flooring and semiconductor cleanroom tubing across Ulsan and Yeosu chemical complexes. South Korean demand diverges from commodity packaging averages because domestic residential construction standards mandate ultra-low volatile organic compound emissions and phthalate-free cushion vinyl flooring for heated Ondol subfloors. Seoul post updates from the Foreign Agricultural Service in March 2026 confirmed that South Korean industrial oilseed crushers maintain steady domestic soybean processing and specialized vegetable oil refining for industrial chemical derivatives. Korean petrochemical houses are actively retrofitting batch esterification reactors to produce bio-citrate and epoxidized oil plasticizers.
Key takeaway: In South Korea, phthalate-free heated residential vinyl flooring standards and electronics cable compounding are forecast to propel an 8.2% CAGR.
United States Bio-Plasticizers Market Outlook (2026 to 2036)
Bio-plasticizers sales in the United States are estimated to progress at a 7.8% CAGR between 2026 and 2036 across Midwest soy-epoxidation biorefineries, medical blood-bag and IV-tubing plants, and foodservice cling-film extruders. What sets the United States apart from European markets is the combination of massive domestic soybean oil feedstock availability and federal USDA BioPreferred procurement incentives paired with EPA TSCA phthalate risk evaluations. Policy analysis published by the American Chemistry Council in July 2026 emphasized that harmonized science-based federal standards and regulatory clarity under TSCA are accelerating commercial investment in renewable and bio-based polymer additives across American plastics processors. Hospital group purchasing organizations continue to mandate DEHP-free citrate and adipate tubing across neonatal and intensive care units.
Key takeaway: In the United States, domestic soy-epoxidation capacity and hospital DEHP-free tubing mandates are estimated to support a 7.8% CAGR.
United Kingdom Bio-Plasticizers Market Outlook (2026 to 2036)
Procurement of bio-plasticizers in the United Kingdom is slated to grow at a 7.6% CAGR over the 2026 to 2036 horizon, supported by supermarket clean-packaging charters and flame-retardant bio-ester cable compounding. British polymer converters operate under dual UK and European Union regulatory compliance when exporting packaged foods and medical disposables across the English Channel, accelerating the removal of restricted ortho-phthalates. Findings from the Circular Economy for Plastics 2026 analysis published by Plastics Europe in May 2026 show rising converter reliance on bio-based and bio-attributed feedstocks across the United Kingdom and continental Europe to offset declining fossil resin output. High industrial electricity tariffs in the United Kingdom favor fast-fusing citrate and sulfonate esters that reduce extruder cycle energy.
Key takeaway: In the United Kingdom, supermarket phthalate-free packaging charters and fast-fusing low-energy vinyl compounding are slated to drive a 7.6% CAGR.
Canada Bio-Plasticizers Market Outlook (2026 to 2036)
Canadian bio-plasticizers demand is projected to rise at a 7.3% CAGR from 2026 to 2036, anchored by record domestic canola and soybean oilseed crushing and cold-resistant flexible PVC wire and food-packaging manufacturing. Canadian vinyl compounders differ from warm-climate processors by requiring epoxidized fatty acid esters and sebacates that prevent cable jacketing and exterior construction membranes from cracking at sub-zero winter temperatures. Official agricultural statistics published by the Ottawa post of USDA FAS in April 2026 confirmed that Canadian canola production hit a record 21.8 million metric tons in marketing year 2025/26 on average yields of 2.507 metric tons per hectare. Abundant domestic vegetable oil supply supports local epoxidation for North American polymer compounders.
Key takeaway: In Canada, record 21.8 million metric ton oilseed harvests and sub-zero flexible cable and film specifications are projected to sustain a 7.3% CAGR.
Germany Bio-Plasticizers Market Outlook (2026 to 2036)
Sales of bio-plasticizers in Germany are predicted to advance at a 7.1% CAGR between 2026 and 2036, driven by world-scale specialty ester plants in Ludwigshafen and Marl supplying medical devices and automotive interior skins. German chemical producers lead Europe in mass-balance bio-attributed plasticizers and high-purity acetyl tributyl citrate and sulfonic acid esters that drop directly into existing PVC processing lines. In May 2026, the full Circular Economy for Plastics 2026 report from Plastics Europe documented that separate packaging waste collection in Germany achieves a 62% recycling rate compared with 2% in mixed streams, reinforcing demand for non-toxic bio-plasticizers that do not contaminate mechanical PVC and biopolymer recycling loops. Elevated European natural gas and petrochemical feedstock costs further narrow the price gap for bio-based esters.
Key takeaway: In Germany, mass-balance specialty ester manufacturing and strict circular-plastics recycling purity standards are predicted to underpin a 7.1% CAGR.
Japan Bio-Plasticizers Market Outlook (2026 to 2036)
In Japan, the bio-plasticizers market is likely to expand at a 6.3% CAGR through 2036 as domestic food-wrap extruders and precision electronics wire coaters prioritize ultra-pure renewable esters. Japanese compounders enforce the world's strictest odor and extraction specifications under Positive List food-contact regulations, favoring purified citrate and polyglycerine fatty acid esters over crude vegetable oils. Toxicological research published by Japanese investigators in the Journal of Applied Toxicology in May 2025 demonstrated that certain synthetic non-phthalate sebacates still induce aquatic reproductive disruption in Japanese medaka models, accelerating formulator migration toward verified nontoxic plant citrates and epoxidized oils. Demographic shifts toward older hospital patient populations also sustain steady domestic consumption of non-phthalate medical infusion tubing.
Key takeaway: In Japan, Positive List food-contact purity rules and non-toxic medical and electronics tubing standards are likely to support a 6.3% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Bio-Plasticizers Market?
Dow Inc., Evonik Industries AG, BASF SE, LANXESS AG, Cargill Incorporated, Emery Oleochemicals Group, Roquette Frères, Jungbunzlauer Suisse AG, and Matrìca S.p.A. are the notable companies in the bio-plasticizers market.
Competitive positioning in the bio-plasticizers industry brings together global chemical and polymer additive leaders, integrated agricultural oleochemical processors, and fermentation bio-monomer specialists. Dow Inc., Evonik Industries AG, and BASF SE along with LANXESS AG supply non-phthalate and mass-balance plasticizer portfolios for flexible PVC and elastomers. Cargill Incorporated and Emery Oleochemicals Group lead in vegetable-oil epoxides and polymeric bio-esters. LCY Biosciences Inc., Roquette Frères, and Jungbunzlauer Suisse AG plus Matrìca S.p.A. specialize in fermented citrates, succinates, and cardoon-oil plasticizers.
- Integrated Chemical and Mass-Balance Polymer Additive Leaders: Dow Inc., Evonik Industries AG, and BASF SE along with LANXESS AG produce high-purity non-phthalate and sulfonic or cyclohexane ester plasticizers for medical and technical vinyl.
- Oleochemical Epoxide and Sebacate Ester Producers: Cargill Incorporated, Emery Oleochemicals Group, and Matrìca S.p.A. manufacture epoxidized soybean oil, castor-oil sebacates, and azelaic or pelargonic bio-plasticizers from integrated plant-oil refineries.
- Fermentation Citrate and Isosorbide Specialists: Jungbunzlauer Suisse AG, Roquette Frères ferment carbohydrate feedstocks into citric acid esters and high-purity isosorbide plasticizers.
Competitive Benchmarking: Bio-Plasticizers Market
Table 8: Competitive Benchmarking for the Bio-Plasticizers Market (qualitative capability ratings), 2026
| Company | Renewable Carbon & Feedstock Integration | PVC & Biopolymer Compatibility Breadth | Food-Contact & Medical Regulatory Clearance | Geographic Reach |
|---|---|---|---|---|
| Dow Inc. | Medium | High | High | 31 manufacturing countries; bio-based NORDEL REN elastomers and barrier packaging modifiers |
| Evonik Industries AG | Medium | High | High | Global specialty additives network; ELATUR non-phthalate PVC plasticizers and EUR 1.87B EBITDA |
| BASF SE | High | High | High | Global Verbund sites; Hexamoll DINCH biomass-balanced plasticizers for medical and food contact |
| LANXESS AG | Medium | High | Medium | Global Polymer Additives network; Mesamoll plasticizer with >30% sustainable feedstock |
| Cargill Incorporated | High | High | High | Global oilseed crushing and bioindustrial hubs; Vikoflex high-oxirane ESBO and Priplast polyols |
| Emery Oleochemicals Group | High | High | High | North America, Europe, and Asia; EDENOL 100% biobased BBSA replacement and polymeric esters |
| Roquette Frères | High | High | High | Global plant-based biorefineries; USDA-certified >99.5% pure POLYSORB isosorbide and BIOSUCCINIUM |
| Jungbunzlauer Suisse AG | High | High | High | Europe and North America fermentation plants; CITROFOL tributyl citrate esters for PVC and PLA |
| Matrìca S.p.A. | High | Medium | Medium | Porto Torres, Italy biorefinery; Matrilox azelaic and pelargonic bio-esters from cardoon oil |
Key Players in the Bio-Plasticizers Market
Integrated Chemical and Mass-Balance Polymer Additive Leaders
- Dow Inc.
- Evonik Industries AG
- BASF SE
- LANXESS AG
Oleochemical Epoxide and Vegetable-Ester Producers
- Cargill Incorporated
- Emery Oleochemicals Group
- Matrìca S.p.A.
Fermentation Citrate and Isosorbide Specialists
- Jungbunzlauer Suisse AG
- Roquette Frères
Bio-Plasticizers Market - Report Scope
Table 9: Report Scope for the Bio-Plasticizers Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Chemical Feedstock Base; Plastic Compatibility; End-Use Industry; Formulation Function; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from renewable, plant-oil-derived, and carbohydrate-fermented plasticizers (epoxidized soybean and linseed oils, triethyl and acetyl tributyl citrates, castor sebacates and ricinoleates, succinic and levulinic acid esters, isosorbide diesters, and bio-attributed sulfonic/adipic esters) used to impart flexibility and processability to polymers. Category Scope Note: Excludes crude unepoxidized vegetable oils, fossil ortho-phthalates (DEHP, DINP, DIDP), and rigid impact modifiers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, South Korea, United States, United Kingdom, Canada, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Dow Inc., Evonik Industries AG, BASF SE, LANXESS AG, Cargill Incorporated, Emery Oleochemicals Group, Roquette Frères, Jungbunzlauer Suisse AG, Matrìca S.p.A. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up polymer compounding triangulation. |
Bio-Plasticizers Market - Research Methodology
Table 10: Research Methodology for the Bio-Plasticizers Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with flexible PVC calendering directors, medical tubing formulation chemists, agricultural oilseed epoxidation managers, and fermented citrate/succinate product directors to validate phr dosing and price-per-ton spreads. |
| Secondary Research | Analysis of U.S. EPA TSCA phthalate risk evaluations, EFSA Food Contact Materials opinions, USDA FAS Oilseeds and Products Annual GAIN reports, Plastics Europe Circular Economy 2026 datasets, ACS and MDPI polymer studies, and corporate filings. |
| Market Sizing and Forecasting | Top-down global non-phthalate plasticizer baselines reconciled against bottom-up bio-plasticizer shipment tonnage (910K to 995K MT in 2026) and weighted average selling prices across epoxides, citrates, sebacates, and succinates from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight domestic soybean, canola, and castor crushing volumes, food-contact and medical PVC extrusion output, and national ortho-phthalate bans across eight profiled countries. |
| Operational Benchmark Traceability | Polymer loading ranges, oxirane oxygen specifications, and channel allocations in Tables 2, 3, and 4 trace to ASTM D1652 epoxide titration benchmarks, USDA FAS oilseed crush tables, and Plastics Europe circular converter surveys. |
| Data Triangulation and Validation | Revenue estimates isolate functional bio-based and biomass-balanced plasticizing esters while excluding unepoxidized commodity cooking oils, metallic stabilizers, and petrochemical terephthalates. |
Bio-Plasticizers Market by Segments
Bio-Plasticizers Market segmented by Chemical Feedstock Base:
- Epoxidized Soybean Oil ESBO
- Citrate Esters Triethyl and Tributyl Citrate
- Sebacates and Castor Oil Ricinoleates
- Succinic Acid and Levulinic Acid Bio-Esters
Bio-Plasticizers Market segmented by Plastic Compatibility:
- Polyvinyl Chloride PVC Flexible Compounds
- Polylactic Acid PLA and Biopolymer Blends
- Polyurethane PU and Synthetic Rubber Formulations
- Cellulose Esters and Acrylic Polymer Systems
Bio-Plasticizers Market segmented by End-Use Industry:
- Food Contact Packaging Films Tubing and Jar Gaskets
- Medical Devices Blood Bags Infusion Lines and Catheters
- Children Toys Childcare Articles and Teethers
- Consumer Wire Cable Insulation and Vinyl Flooring
- Adipates and Vegetable Oil Fatty Acid Methyl Esters (Feedstock Cross-Split)
Bio-Plasticizers Market segmented by Formulation Function:
- Primary Monomeric Plasticizers
- Secondary Heat-Stabilizing Co-Plasticizers
- Polymeric Low-Migration Bio-Plasticizers
- Reactive Chain-Extending Modifiers
Bio-Plasticizers Market segmented by Sales Channel:
- Direct to Polymer Compounders and Calendering Plants
- Specialty Chemical and Masterbatch Distributors
- Contract Medical and Food-Grade Extruders
- B2B Industrial Chemical Procurement Portals
Bio-Plasticizers Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
x
- [1] U.S. Environmental Protection Agency. Final TSCA Risk Evaluation for Diisobutyl Phthalate and Science Advisory Review on Ortho-Phthalates. U.S. Environmental Protection Agency TSCA Dockets (2025, December 15).
- [2] Emery Oleochemicals GmbH. Emery Oleochemicals Advances Development of a 100% Biobased EDENOL Plasticizer Alternative to BBSA. Emery Oleochemicals Corporate Newsroom (2026, May 12).
- [3] American Chemical Society. Synthesis of Epoxidized Soybean Oil as a Bio-Based Chain Extender and Modifier for Recycled Polymers. ACS Omega, 11(1), 1041-1052 (2025, December 26).
- [4] European Food Safety Authority. Substances of Very High Concern and Plasticizer Re-Evaluations in Plastic Food Contact Materials under EU Regulation 2025/351. EFSA Food Contact Materials Scientific Dossiers (2026, September 18).
- [5] Jungbunzlauer Suisse AG. CITROFOL Citrate Esters as Bio-Based Non-Phthalate Plasticisers for Polylactic Acid and Biodegradable Film Applications. Jungbunzlauer Technical Bulletins (2025, April 30).
- [6] Cargill Incorporated. Vikoflex Epoxidized Vegetable Oil Plasticizers for High-Oxirane PVC Stabilization and Low-Temperature Flexibility. Cargill Bioindustrial Polymer Additives (2026, January 14).
- [7] Kowalski, A., & Nowak, M. Sustainable Bio-Based Plasticizers: Advances in Polyols and Non-Phthalate Poly(vinyl chloride) Compounds. Polymers, 18(8), 985 (2026, April 18).
- [8] Berezina, E., & Volkov, D. Modification of Epoxidized Soybean Oil with Cinnamic Acid for Flexible Food Packaging Films. Polysaccharides, 6(2), 40 (2025, May 7).
- [9] Chen, L., & Zhang, W. Synthesis and Evaluation of Eleven Novel Renewable Plasticizers for PVC and Polylactic Acid Formulations. Polymers, 18(17), 2070 (2026, August 29).
- [10] LANXESS AG. Mesamoll General-Purpose Plasticizer for PVC, Polyurethane, and Rubber Formulations from Sustainable Raw Materials. LANXESS Polymer Additives Sustainability Portal (2025, November 10).
- [11] U.S. Environmental Protection Agency. Science Advisory Committee on Chemicals Peer Review of Five High-Priority Phthalates under TSCA Docket EPA-HQ-OPPT-2024-0551. U.S. EPA Chemical Risk Evaluations (2025, June 10).
- [12] Sokolova, T., & Ivanova, N. Study of the Impact of Epoxidized Soybean Oil on the Mechanical and Thermal Characteristics of Recycled Polymer Composites. Materials, 18(11), 2455 (2025, May 23).
- [13] Roquette Frères. POLYSORB High-Purity USDA-Certified Bio-Based Isosorbide Monomer and BIOSUCCINIUM for Performance Polymers. Roquette Bioindustry Technical Dossiers (2026, February 19).
- [14] USDA Foreign Agricultural Service. Brazil: Oilseeds and Products Annual: Soybean Production Forecast at 178 MMT in MY 2025/26 and 192 MMT in MY 2026/27. U.S. Department of Agriculture GAIN Report BR2026-0014 (2026, March 18).
- [15] USDA Foreign Agricultural Service. Global Oilseed Crushing and Mexico Soybean Meal and Oil Production Series MY 2025/2026. U.S. Department of Agriculture Production Database (2026, June 12).
- [16] USDA Foreign Agricultural Service. Republic of Korea: Oilseeds and Products Annual: Industrial Soybean Crushing and Oil Supply Outlook. U.S. Department of Agriculture GAIN Report KS2026-0006 (2026, March 4).
- [17] American Chemistry Council. Bio-Based Plastics Policy, Sustainability Standards, and Regulatory Innovation in the United States. American Chemistry Council Plastics Division (2026, July 1).
- [18] Plastics Europe. The Circular Economy for Plastics: A European Analysis 2026: Bio-Based and Circular Converter Demand. Plastics Europe Knowledge Hub (2026, May 18).
- [19] USDA Foreign Agricultural Service. Canada: Oilseeds and Products Annual: Record 21.8 Million Metric Ton Canola Harvest in MY 2025/26. U.S. Department of Agriculture GAIN Report CA2026-0008 (2026, April 23).
- [20] Plastics Europe. Circular Economy for Plastics 2026 Full Analytical Report: German and EU Bio-Attributed Polymer Conversion. Plastics Europe Official Publication PDF (2026, May 18).
- [21] Watanabe, H., & Sato, K. Reproductive Toxicity Assessment of Non-Phthalate Plasticizers in Aquatic Models Supporting Citrate and Bio-Ester Substitution. Journal of Applied Toxicology, 45(9), 1761-1769 (2025, May 8).
- [22] BASF SE. BASF Group Releases Third-Quarter 2026 Results and Showcases Sustainable Polymer Additives and Circular Materials. BASF Media Releases (2026, October 28).
- [23] BASF SE. BASF at Fakuma 2026: Resilient, Bio-Attributed, and Circular Plastic Solutions for Medical, Food Packaging, and Cable Applications. BASF Media Releases (2026, September 17).
- [24] Evonik Industries AG. Evonik Meets 2025 Profit Guidance with EUR 1.87 Billion Adjusted EBITDA and Reaffirms 2026 Specialty Additives Outlook. Evonik Corporate Press Releases (2026, March 4).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the bio-plasticizers market in 2026 and what is forecast for 2036?
- Which phthalate regulatory bans and food-contact migration rules support demand for bio-plasticizers?
- Why does Epoxidized Soybean Oil ESBO lead the chemical feedstock base category?
- Why do Polyvinyl Chloride PVC Flexible Compounds lead the plastic compatibility category globally?
- How do national growth rates differ across Brazil, Mexico, and South Korea?
- Which leading companies supply integrated vegetable-oil epoxides versus fermented citrate and succinate esters?
- What compatibility limits or phase-separation risks restrain high dosing in the bio-plasticizers market?
- What should vinyl and biopolymer compounders evaluate before switching from ortho-phthalates to bio-esters?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Chemical Feedstock Base, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Chemical Feedstock Base, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Chemical Feedstock Base, 2026 to 2036
- Epoxidized Soybean Oil ESBO
- Citrate Esters Triethyl and Tributyl Citrate
- Sebacates and Castor Oil Ricinoleates
- Succinic Acid and Levulinic Acid Bio-Esters
- Y-o-Y Growth Trend Analysis By Chemical Feedstock Base, 2021 to 2025
- Absolute $ Opportunity Analysis By Chemical Feedstock Base, 2026 to 2036
- Global Market Analysis and Forecast, By Plastic Compatibility, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Plastic Compatibility, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Plastic Compatibility, 2026 to 2036
- Polyvinyl Chloride PVC Flexible Compounds
- Polylactic Acid PLA and Biopolymer Blends
- Polyurethane PU and Synthetic Rubber Formulations
- Cellulose Esters and Acrylic Polymer Systems
- Y-o-Y Growth Trend Analysis By Plastic Compatibility, 2021 to 2025
- Absolute $ Opportunity Analysis By Plastic Compatibility, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Food Contact Packaging Films Tubing and Jar Gaskets
- Medical Devices Blood Bags Infusion Lines and Catheters
- Children Toys Childcare Articles and Teethers
- Consumer Wire Cable Insulation and Vinyl Flooring
- Adipates and Vegetable Oil Fatty Acid Methyl Esters (Feedstock Cross-Split)
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Formulation Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Formulation Function, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Formulation Function, 2026 to 2036
- Primary Monomeric Plasticizers
- Secondary Heat-Stabilizing Co-Plasticizers
- Polymeric Low-Migration Bio-Plasticizers
- Reactive Chain-Extending Modifiers
- Y-o-Y Growth Trend Analysis By Formulation Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Formulation Function, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct to Polymer Compounders and Calendering Plants
- Specialty Chemical and Masterbatch Distributors
- Contract Medical and Food-Grade Extruders
- B2B Industrial Chemical Procurement Portals
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Chemical Feedstock Base
- By Plastic Compatibility
- By End-Use Industry
- By Formulation Function
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Dow Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Evonik Industries AG
- BASF SE
- LANXESS AG
- Cargill Incorporated
- Emery Oleochemicals Group
- Roquette Frères
- Jungbunzlauer Suisse AG
- Matrìca S.p.A.
- Dow Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Chemical Feedstock Base, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Plastic Compatibility, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Formulation Function, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 6: Global Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Plastic Compatibility
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Industry
- Figure 12: Global Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Formulation Function
- Figure 15: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Sales Channel
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 32: North America Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Plastic Compatibility
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Industry
- Figure 38: North America Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Formulation Function
- Figure 41: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Sales Channel
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 48: Latin America Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Plastic Compatibility
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 54: Latin America Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Formulation Function
- Figure 57: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 64: Western Europe Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Plastic Compatibility
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 70: Western Europe Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Formulation Function
- Figure 73: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Plastic Compatibility
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Formulation Function
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 96: East Asia Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Plastic Compatibility
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 102: East Asia Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Formulation Function
- Figure 105: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Plastic Compatibility
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Formulation Function
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Chemical Feedstock Base, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Chemical Feedstock Base, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Chemical Feedstock Base
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Plastic Compatibility, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Plastic Compatibility, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Plastic Compatibility
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Formulation Function, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Formulation Function, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Formulation Function
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Bio-Plasticizers Market in 2026, and what is forecast for 2036?
FMI estimates that the global bio-plasticizers market size stood at USD 2.1 billion in 2025 and reached USD 2.2 billion in 2026. Total global revenue is on course to hit USD 4.5 billion by 2036 as polymer compounders replace restricted ortho-phthalates across food packaging and medical devices.
What is the CAGR for the Bio-Plasticizers Market from 2026 to 2036?
The bio-plasticizers sector is projected to expand at a 7.4% CAGR over the 2026 to 2036 window, adding USD 2.3 billion in incremental revenue across flexible vinyl and biopolymer formulations.
Which chemical feedstock base segment leads the Bio-Plasticizers Market?
Epoxidized Soybean Oil ESBO holds an estimated 48.0% share of chemical feedstock base demand in 2026 since high oxirane oxygen content provides both plasticization and thermal stabilization in PVC.
Which plastic compatibility segment leads the Bio-Plasticizers Market?
Polyvinyl Chloride PVC Flexible Compounds represent 74.0% of the plastic compatibility category in 2026 as flexible films, cables, and medical tubing require high liquid plasticizer loadings.
Which country has a notable growth outlook during the assessment period?
Brazil leads profiled national expansion projections at an 8.4% CAGR through 2036, driven by record domestic soybean oil feedstock supply and growing flexible packaging output.
Who are the key players in the market?
Dow, Evonik, and BASF plus Lanxess lead global polymer additive and mass-balance ester supply. Cargill and Emery Oleochemicals join LCY Biosciences, Roquette, and Jungbunzlauer plus Matrìca in anchoring oleochemical epoxide and fermented bio-ester production.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
