

- Market Size (2026)
- USD 3.6 Bn
- Forecast (2036)
- USD 7.6 Bn
- CAGR (2026 to 2036)
- 7.9%
How big is Bio Plasticizer Market in 2026?
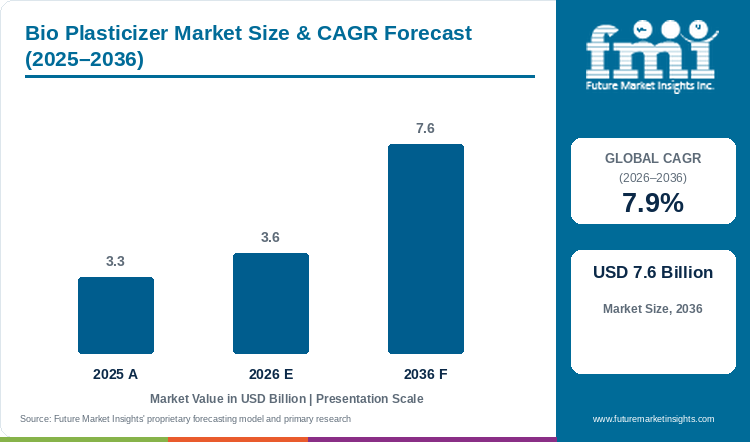
Over the 2026 to 2036 decade, bio plasticizer sales record a 7.9% CAGR. Bio plasticizer sales open the forecast at USD 3.30 billion for 2025. For 2026 the figure moves up to an estimated USD 3.56 billion. Looking to 2036, the projection reaches USD 7.62 billion.
Bio plasticizer sales open 2026 at an estimated USD 3.56 billion, up from USD 3.30 billion in 2025. The market will post a 7.9% CAGR from 2026 to 2036 and close the decade at USD 7.62 billion.
ESBO is the top bio plasticizer product, and the epoxidized soybean oil market is projected to grow at a 5.6% CAGR from 2026 to 2036, below the 7.9% rate for bio plasticizers. Due to this, compounders will turn to citrates and other non-soy grades for part of the added volume. Castor grade makers crush the same seed as castor resin and biopolymer makers, and FMI tracks the castor oil derivatives market at a 4.5% CAGR for the same decade. Castor grade makers will therefore bid against biopolymer makers for each seed crop.
Castor seed demand from biopolymer makers keeps feedstock cost at the centre of the price gap with phthalates. The International Castor Oil Association, for one, wrote on 6 February 2026 that 2025 brought a 20% reduction in castor crop output.[1] The ICOA newsletter expected stabilizing seed prices to make 2026 pricing easier to predict.[1] Steadier castor costs in 2026 will narrow the premium on castor grades for vinyl compounders, unlocking the next wave of market growth. Vinyl compounders will switch only as fast as the castor premium allows, so ESBO keeps 34% of 2026 product sales on the cheaper soybean base.
Medical tubing and food film, the uses with the tightest rules, will switch first. Commodity cable and hose compounds will stay with phthalates until the bio premium shrinks.
Key Market Trends & Insights
- Product: epoxidized soybean oil leads with 34% in 2026, and citrates follow at an estimated 21.6%.
- Application: packaging materials take 29%, and consumer goods hold about 19.4% (estimated).
- Raw material source: plant-based sources supply 61%. ICOA reported a 3.5% fall in castor oil exports for 2025 against 2024.[1]
Regional Highlights
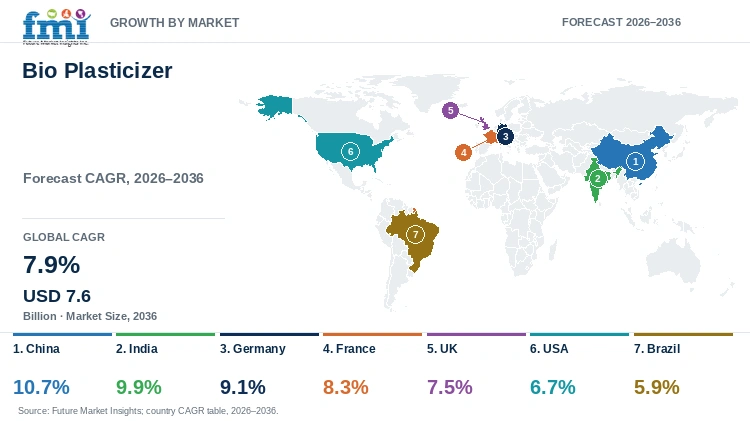
- China is the top profiled country with a 10.7% CAGR, and India is second at 9.9%, both for 2026 to 2036.
- Germany is third on 9.1%. France reaches 8.3%. Britain registers 7.5%. The USA posts 6.7%, and Brazil records the lowest rate, 5.9%. FMI singles out China and India as the fastest-growing countries.
- Final castor sowing in India reached 0.95 million hectares in 2025, ICOA reported in November 2025.[2]
Market Size & Forecast
Table 1: Market Size and Forecast for the Bio Plasticizer Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.30 billion |
| Estimated Market Size in 2026 | USD 3.56 billion |
| Projected Market Size by 2036 | USD 7.62 billion |
| CAGR, 2026 to 2036 | 7.9% |
| Added Revenue, 2026 to 2036 | USD 4.06 billion |
| Market Expansion Multiple | 2.1x |
ESBO and castor derivatives, the two main feedstock families, grow slower than bio plasticizers. The epoxidized soybean oil market grows at a 5.6% CAGR to 2036, so soy-based supply expands more slowly than bio plasticizer orders. Castor chemistry moves slower still, as the castor oil derivatives market gains at a 4.5% CAGR through 2036. FMI figures place bio plasticizers at a 7.9% CAGR over 2026 to 2036. New grades from succinic acid and glycol esters will add volume beyond ESBO and castor grades.
Vegetable Oil and Castor Feedstock Behind the Price Premium
Castor seed supply fell sharply in 2025. ICOA reported a 20% fall in castor crop output and a decline of about 3.5% in castor oil exports against 2024.[1] A historically weak Indian rupee in 2025 might now be recovering, the February 2026 newsletter added.[1] The November 2025 newsletter said castor seed prices had held firm despite softer demand.[2] Castor meal prices rose by over 30% in recent months, and most trade participants predicted a 10% drop in castor oil demand during 2025.[2] Firm seed prices on weak demand will keep castor-based plasticizer costs high into 2026. Buyers will see the castor-grade premium ease only as the 2026 crop arrives at steadier prices.
Vegetable oils will set the cost floor for ESBO. USDA ERS said on 18 September 2026 that strong demand for vegetable oils was supporting global rapeseed and sunflowerseed crush.[3] Higher rapeseed and sunflowerseed oil supplies for 2026/27 outweighed a lower Indonesian palm oil forecast, the same outlook said.[3] Jungbunzlauer and Emery point to the next wave of investment opportunities, one through a new US plant and one through a new bio grade. Jungbunzlauer closed the purchase of a site in Thomson, Illinois, in November 2025, the first US manufacturing facility for the company, to support a portfolio of natural-origin ingredients.[4] Emery Oleochemicals said in May 2026 that initial results show a new EDENOL grade with 100% biobased carbon content can substitute BBSA in targeted applications.[5] Local plants like the Thomson site and drop-in grades like EDENOL will cut freight and qualification cost, the two parts of the premium that buyers control.
Table 2: Feedstock and Producer Indicators for the Bio Plasticizer Market (percentage, hectares and dates), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Castor crop output, 2025 | Down 20% | Supply shock for castor-based grades. | [1] |
| Castor oil exports, 2025 against 2024 | Down about 3.5% | Tighter castor flows to plasticizer makers. | [1] |
| Castor seed prices, November 2025 | Held firm despite softer demand | Feedstock cost held up on weak demand. | [2] |
| Castor meal prices, late 2025 | Up over 30% in recent months | By-product value shapes crushing margins. | [2] |
| Indian castor sowing, 2025 | 0.95 million hectares against 0.87 million | Larger area supports 2026 supply. | [2] |
| Vegetable oil demand, September 2026 | Supporting global rapeseed and sunflowerseed crush | Oil supply backdrop for epoxidized grades. | [3] |
| Jungbunzlauer US site, November 2025 | First US manufacturing facility, Thomson, Illinois | Producer capacity closer to North American buyers. | [4] |
| Emery EDENOL BBSA alternative, May 2026 | 100% biobased carbon content | Bio grades replace hazard-labelled plasticizers. | [5] |
| US EPA final risk evaluations, January 2026 | Five phthalates, including DEHP and DBP, found to present unreasonable risk to human health under certain conditions of use | TSCA risk management rules will follow for PVC plasticizers. | [6] |
| China RoHS phthalate limit, from 1 January 2026 | DEHP, BBP, DBP and DIBP at 0.1% or less | Electrical and electronic products need phthalate-free compounds. | [7] |
| ECHA consultation on C4-C6 ortho-phthalates | Launched 28 January 2026 on a French dossier | Further EU hazard classification of legacy phthalates. | [8] |
Analyst Perspective
“I expect the cost gap between bio plasticizers and phthalates to narrow most in medical, food-contact and flooring compounds, as hazard labelling and buyer specifications make the cheaper option harder to use. Suppliers that lock in castor and soybean oil contracts and qualify drop-in grades with large vinyl compounders will hold the best margins through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the bio plasticizer market segmented?
Product, application and raw material source make up the three product axes, plus region. ESBO leads products at 34% in 2026, packaging materials lead applications at 29%, and plant-based sources lead raw material at 61%.
By product: epoxidized soybean oil (ESBO), citrates, castor oil-based plasticizers, succinic acid, glycol esters, and others.
By application: packaging materials, building and construction, consumer goods, automotive, medical devices, and others.
By raw material source: plant-based sources, bio-waste materials, and other sources.
By region: the Americas (North America, Latin America), Europe (Western Europe, Eastern Europe), East Asia, South Asia and Pacific, and Middle East & Africa.
Why does epoxidized soybean oil lead product sales?
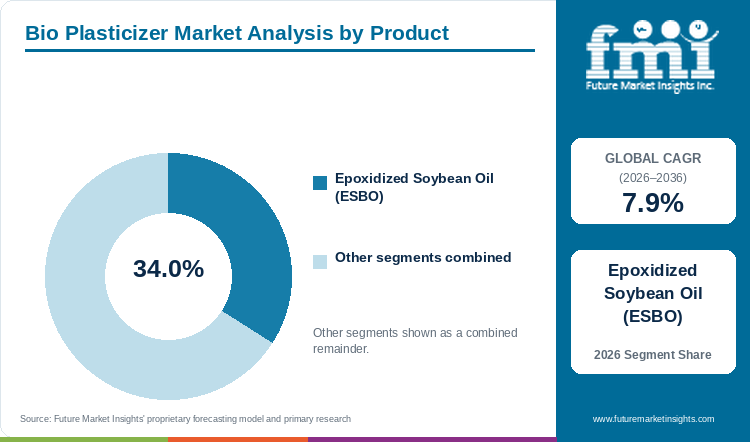
ESBO holds 34% of 2026 product sales, against an estimated 21.6% for citrates and 15.8% for castor oil-based plasticizers.
Table 3: Product Share for the Bio Plasticizer Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Epoxidized Soybean Oil (ESBO) | 34% |
| Citrates | 21.6% |
| Castor Oil-based Plasticizers | 15.8% |
| Glycol Esters | 11.3% |
| Succinic Acid | 8.7% |
| Others | 8.6% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Bio Plasticizer Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.9% |
| Leading Segment | Epoxidized Soybean Oil (ESBO) |
FMI credits ESBO with 34% of product sales. Citrates hold an estimated 21.6%, and castor oil-based plasticizers take about 15.8%. Glycol esters hold an estimated 11.3%, succinic acid 8.7% and others 8.6%. ESBO makers buy soybean oil from large crushing chains, and soybean oil market growth sets the volume those crushers can offer. Strong vegetable oil demand supported global rapeseed and sunflowerseed crush in 2026, USDA ERS noted.[3] Broad oilseed supply will keep ESBO the cheapest bio option per tonne. Citrates will gain in medical and toy compounds, and castor grades will stay with cable and specialty film.
- Medical tubing and food-contact film makers specify citrates for phthalate-free grades.
- Succinic acid grades will expand as fermentation capacity rises.
Why do packaging materials lead application sales?
Packaging materials are the top application in 2026 at 29%, with consumer goods next at about 19.4% (estimated).
Table 5: Application Share for the Bio Plasticizer Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Packaging Materials | 29% |
| Consumer Goods | 19.4% |
| Building and Construction | 17.2% |
| Medical Devices | 13.1% |
| Automotive | 12.6% |
| Others | 8.7% |
| Total | 100.0% |
Food wrap, cap liners and flexible film will need plasticizers that pass food-contact rules, and food-contact rules will favour bio grades. Packaging takes 29% of application sales, per FMI. Consumer goods hold an estimated 19.4%, building and construction about 17.2%, medical devices 13.1% (estimated), automotive 12.6% and others 8.7%. Emery said the EDENOL alternative requires no chemical hazard labeling.[5] Packaging brands will favour hazard-free labels like the EDENOL label. Hospitals are replacing phthalate tubing and bags, so medical devices, at 13.1% (estimated), will add bio grade volume as biomaterial market growth brings more polymer devices.
- Building and construction takes about 17.2% (estimated), mostly in flooring and wall coverings.
- Automotive buyers, at about 12.6% (estimated), use bio plasticizers in seat and dashboard skins.
Why do plant-based sources lead raw material supply?
Plant-based sources supply 61% of raw material in 2026, compared with an estimated 27.3% for bio-waste materials and 11.7% for other sources.
Table 6: Raw Material Source Share for the Bio Plasticizer Market (percentage share), 2026
| Raw Material Source | Estimated Share (2026) |
|---|---|
| Plant-based Sources | 61% |
| Bio-waste Materials | 27.3% |
| Other | 11.7% |
| Total | 100.0% |
Soybean, castor and other crop oils will keep arriving in bulk through established crushers. FMI sizes plant-based sources at 61% of raw material. Bio-waste materials take about 27.3% (estimated), and other sources 11.7%. The Indian castor area rose to 0.95 million hectares in 2025 from 0.87 million hectares, ICOA noted.[2] Crop-based supply will keep the 61% lead, and waste oils will gain with buyers that ask for lower carbon footprints.
- Bio-waste feedstocks will grow with used cooking oil collection.
- Gujarat castor area rose to 0.68 million hectares from 0.64 million hectares in 2025.[2]
What are the drivers, restraints, and opportunities in the bio plasticizer market?
Demand for bio plasticizers rises with hazard rules on legacy plasticizers, food-contact standards and brand carbon targets. Key challenges faced by manufacturers include volatile castor and vegetable oil prices and a steady cost premium over phthalates.
- Driver: Hazard classification of legacy plasticizers pushes buyers to bio grades.
- Restraint: Castor and vegetable oil swings keep a cost premium in place.
- Opportunity: Local plants and drop-in grades for North American and European buyers.
Hazard Labels Push Formulators Toward Bio Grades
Hazard labels on BBSA are moving formulators toward bio grades. ECHA states that BBSA may cause organ damage through prolonged or repeated exposure, Emery noted in May 2026.[5] BBSA is also classified as harmful to aquatic life with long-lasting effects.[5] Polyamide and coating formulators will replace labelled plasticizers with bio grades that carry no hazard statements. US EPA published final risk evaluations on 6 January 2026 for BBP, DBP, DCHP, DEHP and DIBP, the SBA Office of Advocacy reported.[6] EPA determined that the five phthalates present an unreasonable risk of injury to human health under certain conditions of use.[6] TSCA risk management rulemakings for each chemical come next.[6] PVC compounders will qualify bio grades ahead of the TSCA rules.
Feedstock Swings Keep a Cost Premium
Sales of castor-based plasticizers will carry the most feedstock risk. ICOA said in November 2025 that the 2025 crop was about 20% lower than in 2024.[2] Indian castor oil shipments for the first ten months of 2025 came to around 585 kt, down from 621 kt.[2] Compounders that buy on spot terms will pass castor seed swings into price. Phthalates will keep a cost edge in cable and hose compounds.
Local Plants Bring Bio Grades Closer to Buyers
Jungbunzlauer is bringing bio grade capacity to North America. Sales potential is expected to emerge from plants built close to compounders. Jungbunzlauer plans to invest in advanced manufacturing at the Thomson, Illinois site.[4] Castor plasticizer makers will bid for the same castor oil as biopolymer resin makers, and castor oil-based biopolymer market growth will tighten that oil supply. Shorter freight routes will trim part of the bio premium for US and Canadian buyers.
Which country CAGRs are profiled in the bio plasticizer market?
Table 7: Country CAGR Comparison for the Bio Plasticizer Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| China | 10.7% |
| India | 9.9% |
| Germany | 9.1% |
| France | 8.3% |
| UK | 7.5% |
| USA | 6.7% |
| Brazil | 5.9% |
How do country-level CAGRs compare in the bio plasticizer market?
With China and India above 9.5% and Brazil under 6%, regional growth is following different paths. In FMI country data, China leads on a 10.7% CAGR for 2026 to 2036, with India on 9.9%. Germany (9.1%) and France (8.3%) lead Europe, ahead of the UK at 7.5%. The USA posts 6.7%, and Brazil, the slowest, grows at 5.9%.
- China will add bio plasticizer capacity next to large PVC and packaging output.
- Indian makers draw on 0.95 million hectares of domestic castor sowing.
- Germany will push bio grades through chemical safety rules and flooring demand.
- France submitted the ECHA dossier on C4-C6 ortho-phthalates.
- The UK will follow EU-style chemical rules in packaging and toys.
- The USA will build local supply for compounders.
- Brazil will use soybean oil supply for ESBO.
Full report country CAGRs cover: Asia (East Asia, South Asia and Pacific), Europe (Western Europe, Eastern Europe), the Americas (North America, Latin America), and Middle East & Africa.
Country-wise Analysis
China Bio Plasticizer Market Outlook (2026 to 2036)
With a 10.7% CAGR, China heads the profiled group. Chinese PVC film, cable and flooring plants form a broad buyer base for bio grades. China RoHS added DEHP, BBP, DBP and DIBP to the restricted list, which grew from six substances to ten, CIRS reported in January 2026.[7] Amendment 1 to GB/T 26572-2011 took effect on 1 January 2026, with each phthalate capped at 0.1% or less.[7] The mandatory GB 26572-2025 is set to take effect on 1 August 2027.[7] Cable and appliance compounders will need phthalate-free plasticizers for electrical goods. Export-oriented toy and packaging makers will adopt bio grades to meet buyer specifications in Europe and the United States.
Key takeaway: Export compliance and local capacity will make China the main growth source for bio grades.
India Bio Plasticizer Market Outlook (2026 to 2036)
Castor meal prices rose by over 30% in recent months, ICOA reported in November 2025.[2] Higher meal value will help Indian crushers carry castor oil prices. The Indian CAGR is 9.9%. Domestic seed will give Indian plasticizer makers a cost edge in castor-based grades.
Key takeaway: India will turn domestic castor seed into an export-ready bio plasticizer base.
Germany Bio Plasticizer Market Outlook (2026 to 2036)
Germany posts a 9.1% CAGR, ahead of every other European country in the table. The ECHA dossier covers a group of C4-C6 ortho-phthalates, with France as Dossier Submitter.[8] German compounders will keep phthalate rules under review for every EU export grade. Flooring, cable and automotive interior makers will test bio grades for drop-in use. German chemical groups will qualify citrates and ESBO for medical and toy uses.
Key takeaway: Germany will lead European adoption, with hazard labelling as the main trigger.
France Bio Plasticizer Market Outlook (2026 to 2036)
At an 8.3% CAGR, France grows ahead of the UK and the USA. Food packaging and medical device makers will form the core of French buying. ECHA launched a public consultation on 28 January 2026 on a French dossier covering C4-C6 ortho-phthalates, European Plasticisers reported.[8] European Plasticisers argued that the dossier largely targets substances already heavily regulated or no longer commercial.[8] ICOA expected trade shifts to have a positive impact on European consumption of castor oil and derivatives.[1] Castor-based grades will gain a firmer supply route into France.
Key takeaway: French growth will come from packaging and medical uses, helped by steadier castor flows into Europe.
UK Bio Plasticizer Market Outlook (2026 to 2036)
British sales rise at a 7.5% CAGR over the decade. British buyers will import most bio grades from European and Asian producers. Packaging and toy makers will align with EU chemical standards to keep export access. Food retailers will press packaging suppliers on phthalate-free film.
Key takeaway: Retailer demands for phthalate-free packaging will set British growth, with supply mostly imported.
USA Bio Plasticizer Market Outlook (2026 to 2036)
Jungbunzlauer described the Thomson, Illinois site as the first US manufacturing facility of the company.[4] Emery Oleochemicals planned further updates on the EDENOL BBSA alternative in the third quarter of 2026.[5] EPA named PVC and non-PVC plastics among the plasticizer uses of the five evaluated phthalates.[6] Sales grow at a 6.7% CAGR, and local plants will shorten lead times for vinyl and polyamide compounders.
Key takeaway: The 6.7% US CAGR will reward producers with local plants that capture switching demand.
Brazil Bio Plasticizer Market Outlook (2026 to 2036)
Of the seven, Brazil grows slowest at 5.9%. Brazilian soybean output will give local ESBO makers a ready feedstock. Cost-sensitive cable and footwear makers will keep phthalates in cable and footwear compounds. Packaging exporters will adopt bio grades first.
Key takeaway: ESBO feedstock is plentiful in Brazil, and price-led buying will hold Brazil to a 5.9% CAGR.
Who are the notable companies in the bio plasticizer market?
BASF SE, Avient Corporation, Cargill, Incorporated, DIC Corporation, Dow, Inc., Emery Oleochemicals, Evonik Industries AG, Goldstab Organics Pvt. Ltd., GRUPO PRINCZ IPASA and JUNGBUNZLAUER SUISSE AG make up the main supplier group for bio plasticizers.
FMI names BASF, Dow, Avient and Evonik as leaders, with Emery Oleochemicals and Jungbunzlauer as well-recognized names. Goldstab Organics, GRUPO PRINCZ IPASA and Cargill work as smaller or regional suppliers. Emery advanced a 100% biobased BBSA alternative in May 2026.[5] Jungbunzlauer added a US manufacturing site in November 2025.[4] Production economics are changing the competitive equation, as a 20% drop in the 2025 castor crop raised feedstock risk for castor-grade makers.[1] Vertical integration into feedstock, product certifications and procurement relationships will separate BASF, Dow, Avient and Evonik from smaller suppliers.
- Leaders: BASF SE, Dow, Inc., Avient Corporation and Evonik Industries AG.
- Well-recognized suppliers: Emery Oleochemicals and JUNGBUNZLAUER SUISSE AG.
- Smaller or regional suppliers: Goldstab Organics Pvt. Ltd., GRUPO PRINCZ IPASA and Cargill, Incorporated.
- Other key player: DIC Corporation.
Competitive Benchmarking: Bio Plasticizer Market
Table 8: Competitive Benchmarking for the Bio Plasticizer Market (qualitative documentation ratings), 2026
| Company | Bio Grade Launches | Capacity Moves | Feedstock Exposure Data | Disclosure |
|---|---|---|---|---|
| Emery Oleochemicals | High | Low | Low | Medium |
| JUNGBUNZLAUER SUISSE AG | Low | High | Low | Medium |
| BASF SE | Low | Low | Low | Low |
| Dow, Inc. | Low | Low | Low | Low |
| Cargill, Incorporated | Low | Low | Low | Low |
High signals several dated company items on the column topic, and Low signals few.
Key Developments in the Bio Plasticizer Market
- In September 2026, USDA ERS reported strong vegetable oil demand supporting rapeseed and sunflowerseed crush.[3]
- In May 2026, Emery Oleochemicals advanced an EDENOL alternative to BBSA with 100% biobased carbon content.[5]
- In May 2026, European Plasticisers published comments on the ECHA consultation on C4-C6 ortho-phthalates.[8]
- In February 2026, ICOA reported a 20% fall in 2025 castor crop output and said seed prices were expected to stabilize.[1]
- In January 2026, US EPA published final risk evaluations for five phthalate plasticizers.[6]
- In January 2026, China RoHS limits on four phthalates took effect for electrical and electronic products.[7]
- In November 2025, Jungbunzlauer closed the purchase of a site in Thomson, Illinois.[4]
- In November 2025, ICOA put final Indian castor sowing at 0.95 million hectares.[2]
Key Players in the Bio Plasticizer Market
Leaders
- BASF SE
- Dow, Inc.
- Avient Corporation
- Evonik Industries AG
Well-recognized Suppliers
- Emery Oleochemicals
- JUNGBUNZLAUER SUISSE AG
Smaller or Regional Suppliers
- Goldstab Organics Pvt. Ltd.
- GRUPO PRINCZ IPASA
- Cargill, Incorporated
Other Key Player
- DIC Corporation
Bio Plasticizer Market - Report Scope
Table 9: Report Scope for the Bio Plasticizer Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; application; raw material source; region |
| Quantitative units | USD billion |
| Market definition | Bio plasticizers covering ESBO, citrates, castor oil-based plasticizers, succinic acid, glycol esters and related grades used in packaging, construction, consumer goods, automotive and medical devices. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East & Africa |
| Countries covered | China; India; Germany; France; UK; USA; Brazil |
| Key companies profiled | BASF SE, Avient Corporation, Cargill, Incorporated, DIC Corporation, Dow, Inc., Emery Oleochemicals, Evonik Industries AG, Goldstab Organics Pvt. Ltd., GRUPO PRINCZ IPASA, JUNGBUNZLAUER SUISSE AG |
| Forecast period | 2026 to 2036 |
Bio Plasticizer Market - Research Methodology
Table 10: Research Methodology for the Bio Plasticizer Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Feedstock, producer and regulatory facts come from trade association newsletters, USDA outlooks, government notices, regulatory trade press and producer releases dated May 2025 or later. |
| Desk Research | Desk work followed castor crop and export data, vegetable oil supply, producer site moves and new bio grades. |
| Market Sizing and Forecasting | The forecast starts from the 2025 base of USD 3.30 billion and applies the 7.9% CAGR. |
| Data Validation | Feedstock figures were compared across association newsletters of different months. |
Bio Plasticizer Market by Segments
Bio Plasticizer Market segmented by Product:
- Epoxidized Soybean Oil (ESBO)
- Citrates
- Castor Oil-based Plasticizers
- Succinic Acid
- Glycol Esters
- Others
Bio Plasticizer Market segmented by Application:
- Packaging Materials
- Building and Construction
- Consumer Goods
- Automotive
- Medical Devices
- Others
Bio Plasticizer Market segmented by Raw Material Source:
- Plant-based Sources
- Bio-waste Materials
- Other
Bio Plasticizer Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
Research Sources and Bibliography
- [1] International Castor Oil Association. (2026, February 6). ICOA February 2026 Newsletter. https://www.icoa.org/icoa-february-2026-newsletter/
- [2] International Castor Oil Association. (2025, November 28). ICOA November 2025 Newsletter. https://www.icoa.org/icoa-november-2025-newsletter/
- [3] USDA Economic Research Service. (2026, September 18). Soybeans and Oil Crops, Market Outlook. https://www.ers.usda.gov/topics/crops/soybeans-and-oil-crops/market-outlook
- [4] Jungbunzlauer. (2025, November 6). Jungbunzlauer closes acquisition of Illinois facility to launch U.S. manufacturing operations. https://www.jungbunzlauer.com/news/jungbunzlauer-closes-acquisition-of-illinois-facility-to-launch-u-s-manufacturing-operations/
- [5] Emery Oleochemicals. (2026, May). Emery Oleochemicals Advances Development of a Next-Generation Alternative to BBSA. https://www.emeryoleo.com/news/emery-oleochemicals-advances-development-next-generation-alternative-bbsa
- [6] U.S. Small Business Administration, Office of Advocacy. (2026, January 8). EPA Issues Final Risk Evaluations for Five Plasticizer Chemicals. https://advocacy.sba.gov/2026/01/08/epa-issues-final-risk-evaluations-for-five-plasticizer-chemicals/
- [7] CIRS Group. (2026, January 9). Official Upgrade! China RoHS Launches Full Control over New List of 10 Hazardous Substances. https://www.cirs-group.com/en/chemicals/official-upgrade-china-rohs-launches-full-control-over-new-list-of-10-hazardous-substances
- [8] European Plasticisers. (2026, May 7). ECHA public consultation: CLH proposal for C4-C6 ortho-phthalates. https://www.plasticisers.org/news/echa-public-consoltation-clh-proposal-for-c4-c6-ortho-phthalates/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will bio plasticizer sales be in 2026 and in 2036?
- At what CAGR will the market expand over 2026 to 2036?
- Which product will hold the largest share?
- Which application will use the most bio plasticizers?
- How will castor and vegetable oil supply shape the cost premium over phthalates?
- Which countries and suppliers will lead growth through 2036?
Frequently Asked Questions
What is the size of the bio plasticizer market in 2026?
A total of USD 3.56 billion (estimated) will arrive in 2026. By 2036, the FMI projection will be USD 7.62 billion. At what rate will the bio plasticizer market grow? A steady 7.9% CAGR will hold between 2026 and 2036, with packaging and medical uses adding the most volume.
Which product will lead the market?
ESBO will lead with 34% of 2026 product sales. Citrates and castor-based grades will follow.
Which application will buy the most bio plasticizers?
Packaging materials will take 29% of 2026 application sales.
Which country will grow fastest?
China will set the fastest pace with a 10.7% CAGR, FMI data indicate, and India will follow on 9.9%. Will bio plasticizers stay more expensive than phthalates? A cost premium will remain through the decade. Steadier castor prices, broad vegetable oil supply and local plants will narrow the premium over phthalates in medical, food-contact and flooring uses.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Epoxidized Soybean Oil (ESBO)
- Citrates
- Castor Oil-based Plasticizers
- Succinic Acid
- Glycol Esters
- Others
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Packaging Materials
- Building and Construction
- Consumer Goods
- Automotive
- Medical Devices
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Raw Material Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Raw Material Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Raw Material Source, 2026 to 2036
- Plant-based Sources
- Bio-waste Materials
- Other
- Y-o-Y Growth Trend Analysis By Raw Material Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Material Source, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Application
- By Raw Material Source
- Market Attractiveness Analysis
- By Country
- By Product
- By Application
- By Raw Material Source
- Key Takeaways
- Key Countries Market Analysis
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Application
- By Raw Material Source
- China
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Application
- By Raw Material Source
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Emery Oleochemicals
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- JUNGBUNZLAUER SUISSE AG
- BASF SE
- Dow, Inc.
- Cargill, Incorporated
- Avient Corporation
- Evonik Industries AG
- Goldstab Organics Pvt. Ltd.
- GRUPO PRINCZ IPASA
- DIC Corporation
- Emery Oleochemicals
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


