

- Market Size (2026)
- USD 78.0 Bn
- Forecast (2036)
- USD 124.7 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is Bottles Market in 2026?
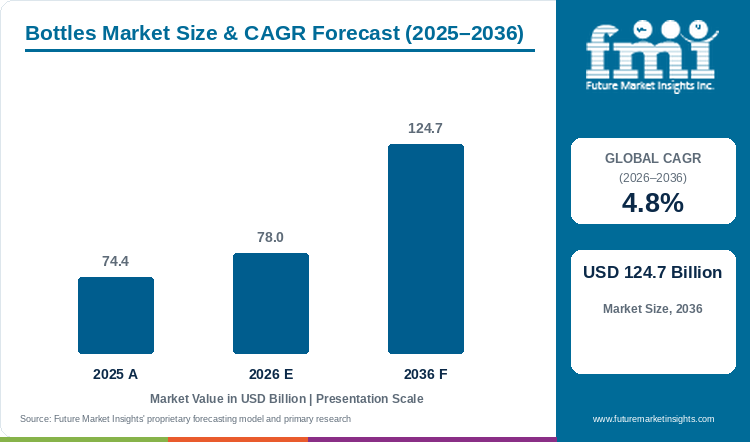
Demand for bottles is projected to expand at 4.8% CAGR between 2026 and 2036. Industry value grows from USD 74.4 billion in 2025 to USD 78.0 billion in 2026 and is projected to reach USD 124.7 billion by 2036.
According to Future Market Insights analysis, the bottles market stands at USD 74.4 billion in 2025 and reaches an estimated USD 78.0 billion in 2026. Revenue is projected at USD 124.7 billion by 2036 with 4.8% CAGR and USD 46.7 billion in added revenue. Beverage filling keeps bottle demand tied to repeat unit production. In July 2026, Oregon’s first-year packaging EPR report recorded nearly 410,000 tons of covered products sold into the state. Rigid plastic represented 57,000 tons and glass represented 39,000 tons. The same program collected 18,888 tons of glass through its curbside incentive route.
FMI research indicates that the USA and UK follow different compliance routes. Oregon required covered producers to report 2024 supply data by March 31, 2025. UK Plastic Packaging Tax statistics retain a 30% recycled-content threshold for plastic packaging. These rules increase demand for traceable rPET while food-contact quality and bottle color still limit rapid resin substitution. [2]The adjacent plastic bottles provides a closer view of lightweight formats and recycled-content purchasing.
Key Market Trends & Insights
- By product: Plastic bottles are projected to account for 51.0% in 2026, driven by low weight and shatter resistance.
- By material: PET is estimated to hold 42.0% in 2026, supported by beverage clarity and bottle-to-bottle recycling routes.
- By closure type: Screw cap bottles are expected to lead with 58.0% share in 2026, enabled by resealability and automated capping.
- By end use: Beverages are forecast to represent 34.0% in 2026, owing to high unit throughput for water and functional drinks.
- By distribution channel: Direct sales are projected to hold 61.0% in 2026, linked to tooling and filling-line qualification.
Regional Highlights
- The USA records 5.9% CAGR from 2026 to 2036 among the evaluated countries.
- The UK follows at 5.4%, while France, Canada, Mexico, and Italy retain separate regulatory and collection routes.
Market Size & Forecast
Table 1: Market Size and Forecast for the Bottles Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 74.4 billion |
| Estimated Market Size in 2026 | USD 78.0 billion |
| Projected Market Size by 2036 | USD 124.7 billion |
| CAGR, 2026 to 2036 | 4.8% |
| Added Revenue, 2026 to 2036 | USD 46.7 billion |
Material and Container Volume Sizing
Table 2: Material and Container Volume Sizing for the Bottles Market (USD billion and percentages), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 74.4 | 78.0 | 124.7 |
| Plastic bottles revenue (USD billion) | 37.9 | 39.8 | 63.6 |
| PET material revenue (USD billion) | 31.2 | 32.8 | 52.4 |
| Beverages end-use revenue (USD billion) | 25.3 | 26.5 | 42.4 |
Per Capita & Beverage Filling Sizing
Rigid bottles represent essential packaging across consumer beverage, food, and personal care sectors. High filling throughput and transport efficiency make bottle design central to supply chains. Converters maintain strict wall-thickness tolerances to minimize tare weight while preserving top-load strength during high-speed palletization.
Table 3: Per Capita Revenue Indicators for the Bottles Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Market revenue (USD billion) | 74.4 | 78.0 | 124.7 |
| Revenue per capita (USD) | 9.04 | 9.40 | 13.93 |
| Added revenue per 1,000 people (USD) | - | - | 5,217.88 |
Table 4: End-Use and Closure Spending Indicators for the Bottles Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 78.0 billion | Report value |
| Beverages revenue, 2026 | USD 26.5 billion | 34.0% share |
| Screw cap bottles revenue, 2026 | USD 45.2 billion | 58.0% share |
| Remaining end-use revenue | USD 51.5 billion | 66.0% balance |
Analyst Perspective
"Bottle production is shifting from isolated container supply toward traceable material systems. Suppliers linking design, molding, and recovery data can reduce filling-line qualification friction."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Bottles Market segmented?
The bottles market is segmented by product, material, capacity, closure type, application, end use, and distribution channel. In 2026, plastic bottles are projected at 51.0%, PET at 42.0%, screw cap bottles at 58.0%, beverages at 34.0%, and direct sales at 61.0%.
By product: glass bottles, plastic bottles, metal bottles, paper bottles.
By material: glass, polyethylene terephthalate, high-density polyethylene, polypropylene, metal, paper-based materials.
By capacity: up to 200 ml, 201 to 500 ml, 501 to 1,000 ml, above 1,000 ml.
By closure type: screw cap bottles, flip top bottles, pump bottles, dropper bottles, other closures.
By application: packaging and storage, dispensing applications.
By end use: food, beverages, pharmaceuticals, personal care and cosmetics, home care.
By distribution channel: direct sales, distributor sales, online sales.
Why do plastic bottles account for a notable product share?
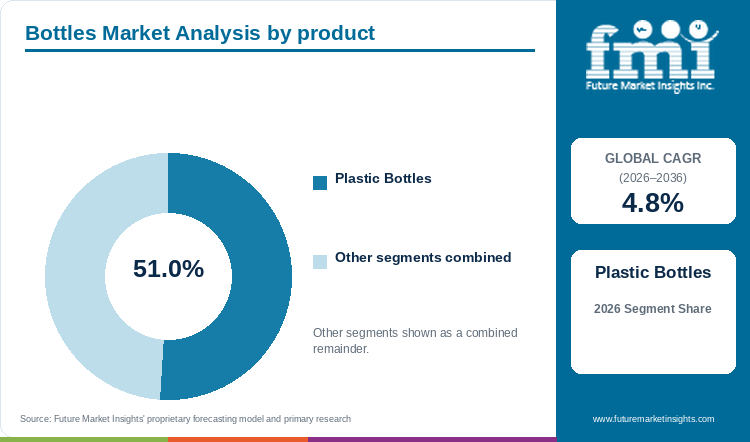
Plastic bottles are projected to hold 51.0% share in 2026, driven by lightweight transport and shatter-resistant beverage use.
Table 5: Product Share for the Bottles Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Plastic bottles | 51.0% |
| Other segments combined | 49.0%* |
| Total | 100.0% |
Table 6: Product Leadership and Market Growth for the Bottles Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.8% |
| Leading Segment | Plastic bottles |
PET and HDPE cover different bottle jobs. PET supplies clarity and carbonation resistance, while HDPE supports chemical resistance for home and personal care. Lower empty-container freight keeps both formats relevant. The related PET material packaging sets the nearest reference for resin and barrier choice.
- Plastic bottles account for 51.0% of product demand in 2026 as fillers balance weight, strength, and line speed.
In May 2026, the Federal Plastics Registry required Canadian producers to report resin type and packaging quantities, increasing demand for traceable bottle specifications.[3]
What supports PET as a preferred choice in the material category?
By material, PET is estimated to hold 42.0% in 2026, supported by clarity and established bottle recycling systems.
PET is used for water, carbonated drinks, edible oils, and personal care bottles. Bottle-to-bottle recycling gives large fillers a route to recycled content without changing neck finishes or filling equipment. The related polyethylene terephthalate offers the nearest reference for food-grade resin use.
- PET holds 42.0% of material demand in 2026 as bottle-grade resin combines clarity, strength, and recovery value.
France requires at least 25% recycled plastic in PET beverage bottles from 2025, which moves food-grade rPET into purchasing specifications.[4]
How are screw cap bottles gaining use across closure applications?
In 2026, screw cap bottles are expected to lead closure type with 58.0% share, enabled by resealing and torque control.
Screw caps use standard neck finishes and established capping equipment. Beverage and household product lines can therefore protect seal consistency without adding a separate dispensing system. The related caps and closures frames the nearest reference for torque and seal design.
- Screw cap bottles represent 58.0% of closure type demand in 2026 as resealing and automated capping support repeat production.
Why are buyers selecting beverages within the end-use segment?
By end use, beverages are forecast to represent 34.0% in 2026, owing to recurring water and functional drink output.
Beverage plants purchase bottles through continuous filling schedules. Water and soft drinks use lightweight PET at scale, while glass retains a role where shelf identity and product protection justify higher freight. The related bottled water packaging provides the nearest reference for high-speed water filling.
- Beverages hold 34.0% of end-use demand in 2026 as high unit output creates recurring bottle orders.
- In November 2025, Plastipak announced a USD 53.8 million expansion of its Pineville, Louisiana manufacturing facility, adding new production lines and increasing recycled plastics capacity. [6]
Which market conditions keep direct sales relevant by distribution channel?
Direct sales are set to lead distribution channel with 61.0% share in 2026, reinforced by tooling and line qualification.
Large fillers qualify wall weight, neck finish, barrier performance, and capping together. Direct supplier programs place technical support near filling plants and align tooling changes with annual demand plans. The related personal care packaging gives the closest adjacent demand context.
- Direct sales account for 61.0% in 2026 as long supply agreements connect bottle design with filling-line acceptance.
- Amcor completed its Berry Global combination in April 2025, broadening the rigid packaging capabilities available to multinational customer programs.[7]
What are the drivers, restraints, and opportunities in the Bottles Market?
Beverage output expands recurring unit demand, whereas recycled-resin qualification limits substitution, and premium refillable formats create design value.
- Driver: Beverage and personal care filling ties bottle orders to repeat consumer unit output.
- Restraint: Food-contact approval and inconsistent bottle-grade recycled resin increase testing time and conversion risk.
- Opportunity: Lightweight glass, high-rPET bottles, and refillable dispensing systems support premium value and compliance.
Growth Analysis and Future Potential
Beverage plants replenish bottles through daily filling plans rather than occasional projects. Water and functional drinks multiply specifications while large lines still require stable neck finish and wall weight. Future Market Insights data suggests that suppliers with beverage, resin, and closure expertise can shorten qualification cycles. High unit volume rewards downgauging only when bottles retain top-load strength during pallet movement. Converters therefore sell a tested bottle system rather than an isolated molded part. This route supports recurring contracts since every new flavor or pack size must still pass filling, capping, and distribution trials.
Risk Assessment and Material Friction
Recycled resin changes bottle performance before it changes brand claims. Food-contact bottles need controlled contamination, odor, color, and intrinsic viscosity. Country rules also define recycled-content evidence differently. In the FMI report, qualification delay is identified as the main commercial restraint since one failed resin lot can interrupt high-speed filling. Bottle makers respond with tighter incoming inspection and longer blending windows. The added controls increase manufacturing cost and can narrow the savings expected from lightweighting. Buyers therefore approve recycled resin through repeat plant trials rather than accepting a certificate without line evidence.
Commercial Opportunity and Value-Add Formats
Premium beverage, beauty, and healthcare products give bottles a visible role after purchase. Embossing, decoration, pumps, droppers, and refill systems can justify higher packaging spend when the format protects dosing or brand identity. An FMI analyst notes that opportunity moves toward containers designed with the closure and recovery route from the start. Lightweight glass can reduce freight while retaining presentation. PET can add recycled content without changing the filling platform. Suppliers gain the clearest advantage when decorative work, line trials, and material documentation arrive as one commercial program. The glass packaging provides the closest comparison for lightweight premium bottle formats.
Bottles Market by Country (2026 to 2036)
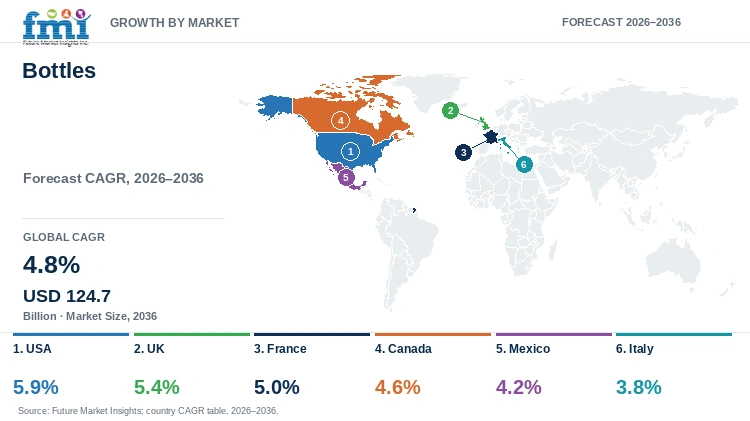
As per Future Market Insights, the USA records the strongest expansion among the six evaluated countries at 5.9% CAGR, while Italy records 3.8%. Commercial outcomes depend on beverage scale, collection performance, recycled-content rules, and the cost of qualifying bottle-grade resin.
Table 7: Country CAGR and Primary Growth Levers for the Bottles Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.9% | State packaging EPR and beverage filling volume |
| UK | 5.4% | Plastic Packaging Tax and recycled-content records |
| France | 5.0% | 25% rPET requirement for PET beverage bottles |
| Canada | 4.6% | Federal Plastics Registry reporting |
| Mexico | 4.2% | Bottle-to-bottle recycling capacity |
| Italy | 3.8% | High national packaging recycling and glass recovery |
Source: Future Market Insights analysis
USA Bottles Market Outlook (2026 to 2036)
By 2036, the USA is projected to grow at 5.9% CAGR, driven by beverage scale and state packaging EPR. Oregon launched its approved producer-responsibility program on July 1, 2025. Producers must report packaging supply by material and pay fees linked to that supply. Bottle buyers consequently need component weights and resin records before annual reporting closes. Yet the state-by-state structure raises administrative friction for national brands. Converters respond with common lightweight bottle platforms and plant-level material declarations. Those records help beverage and personal care companies use one bottle design while adapting reports for each active state program. [8]
Key takeaway: In the USA, state EPR adds packaging data and fee exposure to large-volume bottle purchasing.
UK Bottles Market Outlook (2026 to 2036)
The UK's bottles outlook is anticipated to advance at 5.4% CAGR over the assessment period, influenced by the Plastic Packaging Tax. Official statistics updated in August 2026 kept the tax threshold at less than 30% recycled plastic. The 2025 to 2026 rate applied to manufacturers and importers handling at least 10 tonnes. Bottle buyers therefore need recycled-content evidence even when no tax is payable. Food-contact approval and color consistency still slow substitutions. Suppliers answer with certified rPET grades, lighter preforms, and records that follow each component through production. The commercial gain comes from avoiding tax exposure without reducing filling speed. [9]
Key takeaway: In the UK, recycled-content evidence governs both cost exposure and supplier qualification.
France Bottles Market Outlook (2026 to 2036)
Bottles demand in France is forecast to rise at 5.0% CAGR over the forecast period, supported by direct recycled-content regulation. France requires PET beverage bottles to contain at least 25% recycled plastic from 2025. The rule covers bottles up to three litres and includes caps and lids in the defined format. Clear food-grade feedstock therefore carries more procurement value than mixed-color PET. Yet sleeves, opaque colors, and complex closures can reduce sorting yield. Converters are simplifying labels and increasing rPET while glass suppliers preserve premium beverage demand. The strongest offers combine distinctive presentation with a recovery-compatible material set. [10]
Key takeaway: In France, the 25% rPET rule directs beverage bottle design toward clear and simpler material combinations.
Canada Bottles Market Outlook (2026 to 2036)
Adoption of bottles in Canada is estimated to expand at 4.6% CAGR through 2036, supported by national plastics reporting. The Federal Plastics Registry collects annual data on resin type, source, market placement, collection, reuse, and recycling. Phase 1 reporting covers the 2024, 2025, and 2026 calendar years. Bottle suppliers must therefore provide weights and material details that customers can carry into federal submissions. Provincial recovery systems still use different definitions and routes. Regional molding reduces empty-container transport across long distances. Standard resin declarations also let national brands reconcile federal records with provincial obligations. [11]
Key takeaway: In Canada, federal reporting makes resin and component data part of the bottle supply agreement.
Mexico Bottles Market Outlook (2026 to 2036)
The Mexico bottles sector is projected to record 4.2% CAGR during the assessment period, underpinned by beverage use and food-grade PET recycling. In November 2025, PetStar commissioned an expansion that raised annual recycled-resin capacity from 50,000 to 86,000 tons. The plant processes more than 123,000 tons of PET each year, equal to about 5.5 billion bottles. This scale gives beverage fillers a domestic rPET route. Collection quality and traceability remain the central friction since food-contact resin needs controlled feedstock. Producers are improving inspection, washing, and preform design before material returns to filling plants. [12]
Key takeaway: In Mexico, expanded bottle-to-bottle capacity links beverage volume with domestic food-grade rPET supply.
Italy Bottles Market Outlook (2026 to 2036)
In Italy, bottle demand is predicted to advance at 3.8% CAGR through 2036, reinforced by a mature packaging recovery system. CONAI reported in June 2025 that Italy recycled 76.7% of packaging placed on the market during 2024. The total reached about 10.7 million tonnes, while almost 7,400 municipalities participated in the national system. Glass bottle suppliers benefit from established collection and cullet channels. Energy use in glass melting remains a cost obstacle. PET converters also face EU recycled-content requirements. Suppliers are reducing glass weight and improving rPET acceptance without forcing fillers to replace proven lines. [13]
Key takeaway: In Italy, strong recovery infrastructure supports bottles while furnace energy and material qualification constrain costs.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Bottles Market?
Amcor plc, O-I Glass, Gerresheimer AG, ALPLA, Plastipak Holdings, Ardagh Group, Silgan Holdings, and Berlin Packaging are significant market participants.
As per the analysis from FMI, the competitive environment is moderately fragmented since global packaging platforms operate beside material specialists and regional plants. Plastic bottle producers compete through preform design, molding scale, recycling access, and customer-side plants. Glass groups compete through furnace networks, decoration, and cullet use. Healthcare suppliers add regulated molding and documentation. Distributors connect smaller brands with stock and custom formats. Procurement teams compare line compatibility, material traceability, regional supply, and current investment rather than relying on one unsupported share ranking. The pharmaceutical packaging adds context for regulated bottles and documentation requirements.
- Plastic bottle platforms: Amcor plc, ALPLA, and Plastipak Holdings combine molding with recycled-material programs.
- Glass bottle platforms: O-I Glass and Ardagh Group operate regional furnace and beverage-container networks.
- Healthcare and closure-linked suppliers: Gerresheimer AG and Silgan Holdings support regulated or application-specific bottle systems.
- Distribution and design network: Berlin Packaging connects stock and custom containers with logistics support.
Competitive Benchmarking: Bottles Market
Table 8: Competitive Benchmarking for the Bottles Market (qualitative capability ratings), 2026
| Company | Bottle Breadth | Material Depth | Customer Access | Geographic Reach |
|---|---|---|---|---|
| Amcor plc | High | High | High | High |
| O-I Glass | High | High | High | High |
| Gerresheimer AG | Medium | High | High | High |
| ALPLA | High | High | High | High |
| Plastipak Holdings | High | High | High | High |
| Ardagh Group | High | High | High | High |
| Silgan Holdings | High | Medium | High | High |
| Berlin Packaging | High | Medium | High | High |
Scoring basis: High indicates broad documented bottle capability or geographic reach. Medium indicates a narrower material, product, or regional role. Low is reserved for documented limitations. Ratings are not market-share or quality rankings.
Key Developments in the Bottles Market
In October 2026, ALPLA announced a new North Las Vegas, Nevada facility scheduled to begin operations in spring 2027. The 13,000-square-metre site will manufacture plastic bottles using extrusion blow moulding technology, serving food and beverage, health and beauty, and home care customers. [14]
In April 2025, Amcor completed its combination with Berry Global in a transaction valued at about USD 10.4 billion. The combined platform broadened rigid packaging and customer access. [15]
In February 2025, O-I Glass announced a Gas-Oxy furnace technology upgrade at its Holzminden, Germany plant, with the conversion expected to reduce fuel consumption by up to 30% and lower CO2 emissions by approximately 4,000 tons annually. [16]
Key Players in the Bottles Market
Plastic Bottle Manufacturers
- Amcor plc
- ALPLA
- Plastipak Holdings
Glass Bottle Manufacturers
- O-I Glass
- Ardagh Group
Healthcare, Closure, and Distribution Platforms
- Gerresheimer AG
- Silgan Holdings
- Berlin Packaging
Bottles Market - Report Scope
Table 9: Report Scope for the Bottles Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; Material; Capacity; Closure Type; Application; End Use; Distribution Channel |
| Quantitative units | USD Billion |
| Market definition | Supplier revenue from rigid bottles made from glass, plastic, metal, and paper-based materials. Flexible pouches, cartons, and cans are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | USA, UK, France, Canada, Mexico, Italy, and additional countries in the full report |
| Key companies covered | Amcor plc; O-I Glass; Gerresheimer AG; ALPLA; Plastipak Holdings; Ardagh Group; Silgan Holdings; Berlin Packaging |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation |
Bottles Market - Research Methodology
Table 10: Research Methodology for the Bottles Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with bottle manufacturers, resin suppliers, converters, distributors, fillers, procurement teams, and industry experts to validate demand, qualification, pricing, and purchasing decisions. |
| Secondary Research | Secondary research included annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 used top-down and bottom-up approaches to assess bottle volume, price points, material mix, and end-use adoption. |
| Data Triangulation and Validation | Data was validated against macroeconomic indicators, beverage and healthcare demand, regulation, company activity, and historical trends without double counting adjacent packaging categories. |
Bottles Market by Segments
Bottles Market segmented by product:
- Glass Bottles
- Plastic Bottles
- Metal Bottles
- Paper Bottles
Bottles Market segmented by material:
- Glass
- Polyethylene Terephthalate
- High-Density Polyethylene
- Polypropylene
- Metal
- Paper-Based Materials
Bottles Market segmented by capacity:
- Up To 200 Ml
- 201 To 500 Ml
- 501 To 1,000 Ml
- Above 1,000 Ml
Bottles Market segmented by closure type:
- Screw Cap Bottles
- Flip Top Bottles
- Pump Bottles
- Dropper Bottles
- Other Closures
Bottles Market segmented by application:
- Packaging And Storage
- Dispensing Applications
Bottles Market segmented by end use:
- Food
- Beverages
- Pharmaceuticals
- Personal Care And Cosmetics
- Home Care
Bottles Market segmented by distribution channel:
- Direct Sales
- Distributor Sales
- Online Sales
Bottles Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Circular Action Alliance. (2026, July 1). Oregon 2025 annual report: Packaging extended producer responsibility implementation. Circular Action Alliance Publications.
- [2] HM Revenue & Customs. (2026, August 27). Plastic Packaging Tax statistics: Background and references. GOV.UK Official Statistics.
- [3] Environment and Climate Change Canada. (2026). Federal Plastics Registry: Reporting requirements for resin type and packaging quantities. Government of Canada Publications.
- [4] République française. (2025). Décret no. 2021-1610: Recycled plastic incorporation in beverage bottles. Légifrance.
- [5] European Commission. (2025). Packaging and packaging waste regulation: Design for recyclability and recycled-content provisions. Official Journal of the European Union.
- [6] Plastipak Packaging, Inc. (2025, November). Plastipak announces expansion at Pineville, Louisiana facility. Plastipak Corporate News.
- [7] Amcor plc. (2025, April 30). Amcor completes combination with Berry Global. Amcor Press Releases.
- [8] Oregon Department of Environmental Quality. (2025). Producers of covered products under the Recycling Modernization Act. State of Oregon DEQ.
- [9] HM Revenue & Customs. (2026). Plastic Packaging Tax collection guidance: Rates and thresholds for manufacturers and importers. GOV.UK.
- [10] République française. (2025). Recycled-content requirements for PET beverage bottles (Decree No. 2021-1610, effective 2025). Légifrance.
- [11] Environment and Climate Change Canada. (2025, August 14). Regulatory Services Platform for the Federal Plastics Registry. Government of Canada.
- [12] Arca Continental. (2025, November 26). PetStar food-grade PET recycling plant expansion: Capacity from 50,000 to 86,000 tons. PetStar Operations Releases.
- [13] CONAI. (2025, June 25). Packaging recycling: Italy reaches 76.7% recovery. Italian National Packaging Consortium.
- [14] ALPLA Group. (2026, October). ALPLA expands United States operations with new North Las Vegas facility. ALPLA Corporate News.
- [15] Amcor plc. (2025). Annual report 2025: Rigid packaging performance and Berry Global integration. Amcor Investor Relations.
- [16] O-I Glass, Inc. (2025, February 6). O-I Glass seeks to position Holzminden for strong future. O-I Glass Newsroom.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the bottles market in 2026 and 2036?
- Which operating conditions support bottle demand through the forecast period?
- Why do plastic bottles lead the product category in 2026?
- Why does PET retain a notable material position in 2026?
- How do screw cap bottles support automated packaging operations?
- Which countries show notable bottle market expansion through 2036?
- Which companies operate across plastic and glass bottle supply?
- What limits recycled-material substitution in bottle manufacturing programs?
Frequently Asked Questions
How big is the bottles market in 2026, and what is forecast for 2036?
Future Market Insights estimates the bottles market at USD 78.0 billion in 2026 and USD 124.7 billion by 2036.
What is the CAGR for the bottles market from 2026 to 2036?
As per FMI, the bottles market is projected to expand at 4.8% CAGR over the assessment period.
Which product segment leads the bottles market?
Plastic bottles are projected to hold 51.0% of product demand in 2026.
Which material segment has a notable position?
PET is estimated to hold 42.0% of material demand in 2026.
Which country has a notable growth outlook?
The USA is projected to record 5.9% CAGR from 2026 to 2036 within the evaluated country set.
Who are the key players in the market?
Key participants include Amcor plc, O-I Glass, Gerresheimer AG, ALPLA, Plastipak Holdings, Ardagh Group, Silgan Holdings, and Berlin Packaging.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By product, 2026 to 2036
- Glass Bottles
- Plastic Bottles
- Metal Bottles
- Paper Bottles
- Y-o-Y Growth Trend Analysis By product, 2021 to 2025
- Absolute $ Opportunity Analysis By product, 2026 to 2036
- Global Market Analysis and Forecast, By material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By material, 2026 to 2036
- Glass
- Polyethylene Terephthalate
- High-Density Polyethylene
- Polypropylene
- Metal
- Paper-Based Materials
- Y-o-Y Growth Trend Analysis By material, 2021 to 2025
- Absolute $ Opportunity Analysis By material, 2026 to 2036
- Global Market Analysis and Forecast, By capacity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By capacity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By capacity, 2026 to 2036
- Up To 200 Ml
- 201 To 500 Ml
- 501 To 1,000 Ml
- Above 1,000 Ml
- Y-o-Y Growth Trend Analysis By capacity, 2021 to 2025
- Absolute $ Opportunity Analysis By capacity, 2026 to 2036
- Global Market Analysis and Forecast, By closure type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By closure type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By closure type, 2026 to 2036
- Screw Cap Bottles
- Flip Top Bottles
- Pump Bottles
- Dropper Bottles
- Other Closures
- Y-o-Y Growth Trend Analysis By closure type, 2021 to 2025
- Absolute $ Opportunity Analysis By closure type, 2026 to 2036
- Global Market Analysis and Forecast, By application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By application, 2026 to 2036
- Packaging And Storage
- Dispensing Applications
- Y-o-Y Growth Trend Analysis By application, 2021 to 2025
- Absolute $ Opportunity Analysis By application, 2026 to 2036
- Global Market Analysis and Forecast, By end use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By end use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By end use, 2026 to 2036
- Food
- Beverages
- Pharmaceuticals
- Personal Care And Cosmetics
- Home Care
- Y-o-Y Growth Trend Analysis By end use, 2021 to 2025
- Absolute $ Opportunity Analysis By end use, 2026 to 2036
- Global Market Analysis and Forecast, By distribution channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By distribution channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By distribution channel, 2026 to 2036
- Direct Sales
- Distributor Sales
- Online Sales
- Y-o-Y Growth Trend Analysis By distribution channel, 2021 to 2025
- Absolute $ Opportunity Analysis By distribution channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- By Country
- Market Attractiveness Analysis
- By Country
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By product
- By material
- By capacity
- By closure type
- By application
- By end use
- By distribution channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Amcor plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- O-I Glass
- Gerresheimer AG
- ALPLA
- Plastipak Holdings
- Ardagh Group
- Silgan Holdings
- Berlin Packaging
- Amcor plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


