
- Market Size (2026)
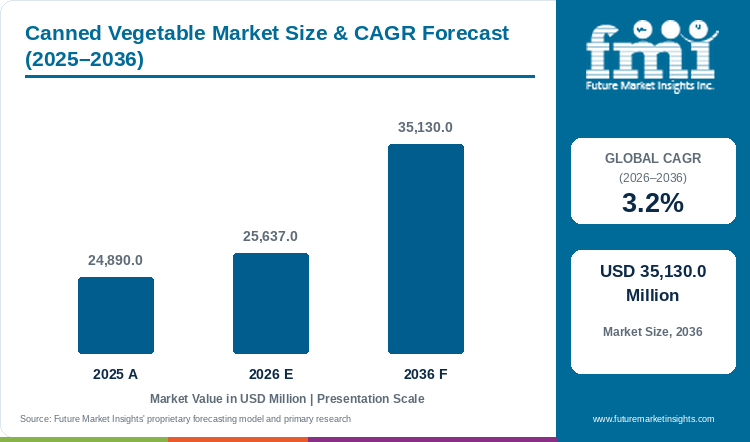
- USD 25637.0 Mn
- Forecast (2036)
- USD 35130.0 Mn
- CAGR (2026 to 2036)
- 3.2%
How big is the Canned Vegetable Market in 2026?
The Canned Vegetable Market is projected to reach USD 35,130.0 million by 2036, growing at a 3.2% CAGR from 2026 to 2036.
FMI estimates the market at USD 25,637.0 million in 2026, up from USD 24,890.0 million in 2025. Seneca Foods grew net sales by 5.1% in the year to 31 March 2026 on higher unit volume. Growth stays moderate because consumers are moving toward healthier fresh and frozen alternatives. Fresh Del Monte completed its purchase of the Del Monte vegetable and tomato brands on 19 March 2026.
Tomatoes are the leading vegetable type, and raw material supply sets their cost base. WPTC estimates 2026 world processing at 39.1 million tonnes as of 9 October, below 40.4 million tonnes in 2025. California is at 9.34 million tonnes and Italy at 6.3 million tonnes, together 40.0% of that volume. Raw tomatoes cost about USD 123.0 per tonne in Europe, USD 115.0 in California and USD 70.0 in China. Canners in Europe start with a raw material cost 75.7% above Chinese processors. Italian processors faced seasonal gas prices 103.0% above 2025 and electricity prices 78.0% higher in the 2026 campaign.
Key Market Trends & Insights
- On 19 March 2026 Fresh Del Monte completed its purchase of select Del Monte Foods assets for about USD 285.0 million. The deal moved the Del Monte and S&W vegetable brands and four US facilities to one owner. Retail buyers therefore deal with a new owner and a restructured supply base.
- Seneca Foods raised gross margin to 13.9% in fiscal 2026 from 9.5% on more normalised pack costs in calendar 2025. Its facilities include can manufacturing, seed production and a farming operation.
- Canned tomato trade is concentrated, as Italy supplied 91,108 of the 99,075 tonnes that Japan imported in 2025.
Regional Highlights
- In North America, lenders committed USD 912.5 million to keep Del Monte operating through the sale that closed in March 2026. Fourth-quarter net sales at Seneca Foods rose to USD 393.8 million from USD 345.8 million on higher volume.
- In Europe, the Commission imposed definitive anti-dumping duties of 31.0% to 54.3% on Chinese sweetcorn in February 2026. One French producer reports that private-label volumes are normalising after those tariffs.
Canned Vegetable Market Size and Forecast
Table 1: Canned Vegetable Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 24,890.0 million |
| Estimated market size in 2026 | USD 25,637.0 million |
| Projected market size by 2036 | USD 35,130.0 million |
| CAGR from 2026 to 2036 | 3.2% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
Analyst Perspective
“Households buy canned vegetables for price, storage life and convenience, while foodservice and industrial users buy by the tonne against fixed specifications. Processors with their own farms, cans and plants hold the strongest cost position when crops and steel prices move, and consumer preference for fresh and frozen products is the main risk to volume, as the Del Monte restructuring showed.”
- Nandini Roy Choudhury, Principal Consultant, FMI
How is the Canned Vegetable Market segmented?
- By vegetable type: Tomatoes, Corn, Peas, Beans, Carrots, Potatoes, Mushrooms, Others.
- By nature: Conventional, Organic.
- By packing medium: Water and Brine, Oil, Juice and Sauce.
- By end use: Household Retail, Foodservice, Food Processing.
- By region: North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa.
Why do Tomatoes lead by Vegetable Type in the Canned Vegetable Market in 2026?
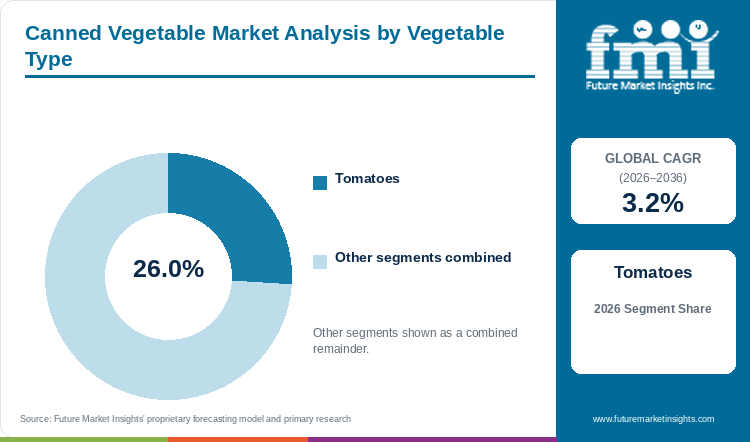
Tomatoes hold 26.0% of the Canned Vegetable Market by vegetable type in 2026.
Tomatoes are processed on a very large scale, with WPTC putting 2026 world processing at 39.1 million tonnes. The Contadina tomato brand moved to Fresh Del Monte in the March 2026 completion. Corn, peas, beans, carrots, potatoes, mushrooms and others hold the remaining 74.0%. Corn and peas and beans are core canned lines. Seneca Foods lists sweet corn, peas and green beans as its major vegetable varieties.
Table 2: Vegetable Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Tomatoes | 26.0% |
| All Other Segments Combined Share | 74.0% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
Why does Conventional lead by Nature in the Canned Vegetable Market in 2026?
Conventional products hold 92.0% of the Canned Vegetable Market by nature in 2026.
Canned vegetables are bought on price, and Seneca Foods buys most of its vegetables from farmers under contract. Its products are sourced primarily from more than 1,100 American farms. It sells private label, foodservice and branded products. Organic holds the remaining 8.0%. The Take Root Organics tomato range was included in the sale agreement announced in January 2026.
Table 3: Nature, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Conventional | 92.0% |
| All Other Segments Combined Share | 8.0% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
Why does Water and Brine lead by Packing Medium in the Canned Vegetable Market in 2026?
Water and brine hold 78.0% of the Canned Vegetable Market by packing medium in 2026.
Plain vegetables in water or brine are the simplest pack, which suits shelf-stable staples for households and foodservice. Seneca Foods reported higher unit volume in fiscal 2026, and canned vegetables were 82.0% of its food packaging net sales. Oil, juice and sauce packs hold the remaining 22.0% and serve prepared dishes and tomato-based products.
Table 4: Packing Medium, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Water and Brine | 78.0% |
| All Other Segments Combined Share | 22.0% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
Why does Household Retail lead by End Use in the Canned Vegetable Market in 2026?
Household retail holds 68.0% of the Canned Vegetable Market by end use in 2026.
Household retail is served by private label and branded cans sold through supermarkets, mass merchandisers, club stores and dollar stores. Seneca Foods also supplies foodservice and industrial customers and exports to about 55 countries. Foodservice and food processing hold the remaining 32.0%.
Table 5: End Use, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Household Retail | 68.0% |
| All Other Segments Combined Share | 32.0% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
What are the key drivers, restraints and opportunities?
Driver
Unit volume growth at large processors. Seneca Foods completed fiscal 2026 with higher unit volume and net sales of USD 1,659.7 million, up from USD 1,578.9 million. Fourth-quarter sales rose mainly on volume to USD 393.8 million from USD 345.8 million.
Export demand for tomato products. Importing markets continue to rely on canned and paste tomato supply, as Japan imported 146,451 tonnes of tomato paste in 2025 and its canned tomato imports were roughly flat on 2024.
Restraint
Consumer shift away from canned products. Del Monte Foods attributed its July 2025 Chapter 11 filing to declining consumer demand and costly surplus inventory, and a restructuring analyst said consumers moved toward healthier alternatives to canned food. Even after a stronger year for one large processor, the category has to defend itself against fresh vegetables and frozen alternatives.
Cost and ingredient volatility. Raw material and packaging costs vary from year to year, as the recovery in Seneca's gross margin shows. Section 232 tariffs on steel imports rose to 50% in June 2025. Nearly 80% of the tinplate that US can makers use is imported.
Opportunity
Integration after the Del Monte sale. Fresh Del Monte completed the purchase on 19 March 2026 and owns the Del Monte brand globally, subject to existing licensing arrangements. The new owner also took four US facilities in Texas, Illinois, Wisconsin and Washington. That lets it sell fresh and packaged lines under one name.
Export markets for tomato products. Tomato processors can supply markets that depend on imports, and Italy reported a larger 2026 campaign than the year before, which adds supply for those buyers.
Canned Vegetable Market by Country (2026 to 2036)
Table 6: Canned Vegetable Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
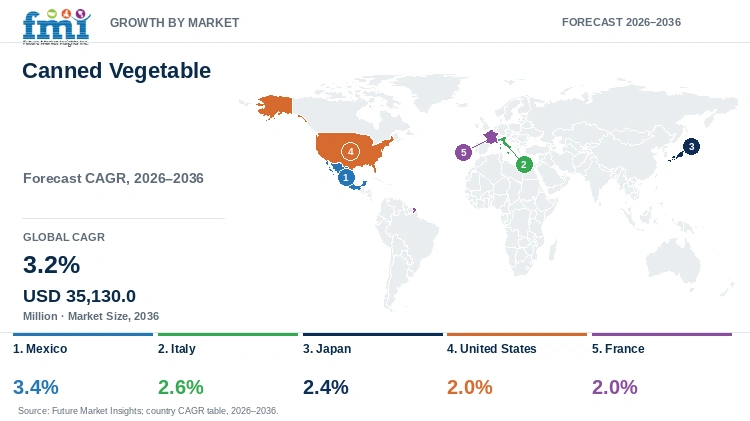
| Mexico | 3.4% |
| Italy | 2.6% |
| Japan | 2.4% |
| United States | 2.0% |
| France | 2.0% |
Source: Future Market Insights analysis of the canned vegetable market, 2026.
Mexico
Mexico hosts two facilities that moved to Fresh Del Monte in the March 2026 completion. Canned and shelf-stable fruit in Mexico was excluded from that sale and sits outside this report. Processing capacity close to US demand supports a projected 3.4% CAGR for 2026 to 2036.
United States import dependence explains the lead. USDA reports that imports supplied 36.3% of US processed vegetable availability in 2025. For chili peppers the import share reaches 95%, and 97% of that volume originates in Mexico. Imports of canned snap beans from Canada and Mexico also rose in 2025. The snap bean import share is about 20%, roughly double the level a decade earlier. Volumes of canned whole tomatoes from Mexico fell in 2025, so the gain is not uniform across products.
Trade with the United States runs in both directions. US processed vegetable exports to Mexico fell 20.0% to USD 513.0 million in 2025. That made Mexico the third-largest market, after Canada at USD 736.0 million and Japan at USD 623.0 million. Mexico also lost canned whole tomato volume in the US market in 2025. At the July 2026 review, the United States declined to extend USMCA in its current form. Plants that supply US buyers therefore depend on the USMCA outcome, the main uncertainty for this growth rate.
Italy
ANICAV reported 6.3 million tonnes of tomatoes processed in the 2026 campaign, and export strength supports a 2.6% CAGR for 2026 to 2036, limited by a mature home market.
Italy ranks second among processors, and export orders set its growth more than home demand does. ISMEA reports 2025 output above 5.8 million tonnes, an 11.0% rise on 2024. Shipments in the 2024/25 campaign reached 4.7 million tonnes in raw-tomato equivalent and EUR 2.8 billion in value. That produced a trade surplus above EUR 2.5 billion. Retail volumes at home rose only 2.0%, so incremental volume depends on foreign buyers. Area rose to 86,382 hectares in 2026, and northern yields were the weakest in five years.
Italian output feeds import-dependent markets. It supplied 83.0% of US tomato sauce import volume in 2025 and about 92.0% of Japan's canned tomato imports. Cost is the main brake on that position. ANICAV states that Italian raw tomato prices remain the highest in the world. Gas prices rose 103.0% and electricity 78.0% during the 2026 campaign. A long Centre and South campaign also cut economies of scale because plants were not always able to run at full capacity. Italy sent less canned whole tomato volume to the US in 2025. Its exporters face California and China, where raw tomatoes cost USD 115.0 and USD 70.0 per tonne.
Japan
Canned tomato imports were flat and paste imports fell 5.7% in 2025, and a mature, import-reliant market grows slowly, so FMI forecasts a 2.4% CAGR for 2026 to 2036.
Japan buys what it cannot supply at scale, so import prices drive its value growth more than volumes do. The tomato product trade deficit fell 15.4% to USD 389.0 million in 2025 from USD 460.0 million in 2024. Paste accounted for USD 254.3 million of the deficit on 146,451 tonnes of imports. Japan holds 5.7% of global canned tomato imports and ranks fourth among buyers. Italy supplied 91,108 of the 99,075 tonnes of canned tomatoes it imported in 2025. Western Europe supplied 53,388 tonnes of paste in 2025 against 72,737 tonnes in 2020.
Japan has almost no export outlet, as its exports of paste and canned tomatoes are virtually nil. Buyers therefore carry price risk in full. Canned tomatoes added a deficit of USD 124.9 million, down 8.0% on 2024. Sauces account for only USD 10.3 million of the deficit, so paste and canned tomatoes decide the import bill. Japan is also the second-largest market for US processed vegetable exports, at USD 623.0 million in 2025. Paste buyers are diversifying away from Western Europe, with North America at 41,014 tonnes and Chile at 23,304 tonnes in 2025.
United States
US sales are stable, as Seneca's fiscal 2026 volume gains show. A preference for fresh and frozen products limits volume growth. The Del Monte restructuring, which ended with the March 2026 sale of its vegetable business, shows that pressure on the category. This holds the US to a 2.0% CAGR for 2026 to 2036.
Slower per-person use and higher input costs explain the US rate. ERS estimates 2025 processing vegetable availability at 102.7 pounds per person. That is 6% below the 2021 to 2023 average of 109.7 pounds. Imports supplied 36.3% of availability, and the tomato import share reached 16% from 7% a decade ago. Contracted California processing tomato acreage for 2026 is forecast at 185,000 acres, down 10%. That is below 200,000 acres for the first time since the 1970s.
Packaging adds a second cost that affects every shelf-stable line. Section 232 tariffs on steel imports rose to 50% in June 2025. Nearly 80% of tinplate used by US can makers is imported. Nine of 12 US tinplate lines have stopped running since 2018, so domestic supply cannot replace imports quickly. The United States produced 26.0% of world processing tomatoes in 2025 yet is a net importer of tomato sauce. Canners that import tinplate are exposed to changes in Section 232 steel tariffs.
France
Bonduelle sells canned and frozen vegetable ranges. Its 2025-26 sales were EUR 2,186.2 million, with canned products at EUR 1,119.9 million. Its canned sales in Europe grew 1.5% in otherwise sluggish markets. The French market is mature, which gives a 2.0% CAGR for 2026 to 2036.
Farm supply sets the French rate more than retail demand does. UNILET reports that processing vegetable area fell to 62,000 hectares in 2025, 13.0% below the ten-year average, and production fell 9.0%. Dedicated vegetable crops are fully contracted before the campaign, so weaker orders from processors cut acreage directly. Purchases of canned vegetables in France were 4.0% lower in 2024 than in 2019. Households bought 87.0% of the volume, so home demand sets the outlet.
French canned sweet corn output fell from 201,979 tonnes in 2021 to 160,626 tonnes in 2024. In February 2026 the Commission imposed definitive anti-dumping duties of 31.0% to 54.3% on Chinese sweetcorn. It found that these imports were entering the EU at dumped prices after a 14-month investigation. The EU sweetcorn market is worth EUR 642.0 million. The industry employs some 3,500 people in France, Hungary, Italy, Poland and Spain. Bonduelle said that large-scale Chinese sweet corn imports and private-label price pressure hurt its 2025-26 profitability. These duties decide how far Chinese canned sweet corn can undercut French processors.
Who are the notable companies in the Canned Vegetable Market?
Notable companies in the Canned Vegetable Market include Seneca Foods, Fresh Del Monte, Bonduelle and Pacific Coast Producers.
Control of crops, cans and brands separates canned vegetable suppliers. Seneca Foods sources primarily from more than 1,100 American farms and runs can manufacturing, seed production and a farming operation. Canned vegetables were 82.0% of its food packaging net sales in fiscal 2026. Its brands include Libby's, Green Giant and Aunt Nellie's. Net sales were USD 1,659.7 million, up from USD 1,578.9 million. Fourth-quarter sales rose mainly on volume to USD 393.8 million from USD 345.8 million.
Fresh Del Monte completed the purchase of select Del Monte Foods assets for about USD 285.0 million on 19 March 2026. The assets cover Del Monte and S&W vegetable brands, Del Monte and Contadina tomato brands, and four US facilities. It also holds global ownership of the Del Monte brand, subject to existing licensing arrangements. Del Monte Foods filed for Chapter 11 in July 2025 with USD 912.5 million of lender funding. It cited declining consumer demand and costly surplus inventory.
Pacific Coast Producers is a California grower-owned cooperative packing canned fruits, tomatoes and cherries for retail and foodservice customers. It draws on more than 150 family farms across Central and Northern California. Its 2026 Del Monte and S&W licence covers canned fruit, outside this report, so only its tomato lines count here.
Bonduelle reported 2025-26 sales of EUR 2,186.2 million, of which canned products were EUR 1,119.9 million or 51.2%. Canned sales rose 4.6% on reported figures and 3.5% like-for-like. Its Bonduelle, Cassegrain and Globus brands drove growth in Europe and Eurasia. Private-label volumes are normalising after the EU tariffs on Chinese sweet corn.
Key Developments in the Canned Vegetable Market
- On 19 March 2026 Fresh Del Monte completed the purchase of select Del Monte Foods assets for about USD 285.0 million. The assets include the Del Monte and S&W packaged vegetable brands, Contadina tomatoes and four US facilities.
Key Players in the Canned Vegetable Market
- Seneca Foods Corporation
- Fresh Del Monte Produce Inc.
- Bonduelle Group
- Pacific Coast Producers
Canned Vegetable Market Report Scope
Table 7: Canned Vegetable Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Vegetables and tomato products preserved in cans, jars and pouches and sold shelf-stable to households, foodservice operators and food manufacturers, valued at manufacturer selling prices. Fresh, frozen and dried vegetables and canned fruit are excluded. |
| Vegetable Type | Tomatoes; Corn; Peas; Beans; Carrots; Potatoes; Mushrooms; Others |
| Nature | Conventional; Organic |
| Packing Medium | Water and Brine; Oil; Juice and Sauce |
| End Use | Household Retail; Foodservice; Food Processing |
| Regions and profiled countries | North America, Latin America, Europe, East Asia, South Asia, Oceania, Middle East and Africa. Profiled countries: Mexico, Italy, Japan, United States, France |
| Companies covered | Seneca Foods Corporation; Fresh Del Monte Produce Inc.; Bonduelle Group; Pacific Coast Producers |
| Quantitative Units | USD million |
Canned Vegetable Market by Segments
Canned Vegetable Market segmented by Vegetable Type:
- Tomatoes
- Corn
- Peas
- Beans
- Carrots
- Potatoes
- Mushrooms
- Others
Canned Vegetable Market segmented by Nature:
- Conventional
- Organic
Canned Vegetable Market segmented by Packing Medium:
- Water and Brine
- Oil
- Juice and Sauce
Canned Vegetable Market segmented by End Use:
- Household Retail
- Foodservice
- Food Processing
Canned Vegetable Market by Region
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- Mexico
- Italy
- Japan
- United States
- France
Research Sources and Bibliography
- [1] Seneca Foods Corporation. (2026, June 11). Seneca Foods Reports Sales and Earnings for the Quarter and Twelve Months Ended March 31, 2026. https://www.senecafoods.com/wp-content/uploads/drupal/2026-06/PressRel0326.pdf
- [2] CBS News. (2025, July 2). Del Monte files for Chapter 11 bankruptcy. https://www.cbsnews.com/news/del-monte-bankruptcy-chapter-11/
- [3] Just Food. (2026, January 16). Del Monte Foods agrees asset sales to Fresh Del Monte, B&G Foods and Pacific Coast Producers. https://www.just-food.com/news/del-monte-foods-asset-acquisition/
- [4] Fresh Del Monte Produce Inc. (2026, March 19). Fresh Del Monte completes acquisition of select Del Monte Foods assets. https://freshdelmonte.com/news/fresh-del-monte-completes-acquisition-of-select-del-monte-foods-assets/
- [5] Seneca Foods Corporation. (2026, June 11). Annual report on Form 10-K for the fiscal year ended March 31, 2026. https://www.sec.gov/Archives/edgar/data/88948/000143774926020290/senea20260331_10k.htm
- [6] Tomato News, citing Trade Data Monitor. (2026, October 30). Japan: a heavy reliance on imports for tomato products in 2025. https://tomatonews.com/japan-a-heavy-reliance-on-imports-for-tomato-products-in-2025/
- [7] Tomato News, citing ANICAV. (2026, November 3). 2026 campaign: 6.3 million tonnes of tomatoes processed in Italy. https://tomatonews.com/2026-campaign-6-3-million-tonnes-tomatoes-processed-in-italy/
- [8] Bonduelle Group. (2026, August 3). 2025-2026 annual sales: financial notice. https://www.bonduelle.com/app/uploads/2026/08/e40a511c-3148-4e34-aa60-e8190520a964.pdf
- [9] Tomato News, citing WPTC. (2026, October 12). WPTC crop update as of 9 October 2026. https://tomatonews.com/wptc-crop-update-as-of-9-october-2026/
- [10] Tomato News, citing WPTC and AMITOM. (2026, July 1). 2026: Average Global Indicative Price of Raw Processing Tomato. https://tomatonews.com/2026-average-global-indicative-price-of-raw-processing-tomato/
- [11] ISMEA, citing WPTC and ITC data. (2026, April 7). Italy remains the leading exporter of tomato preserves, while ranking second in production. FreshPlaza. https://www.freshplaza.com/north-america/article/9826128/italy-remains-the-leading-exporter-of-tomato-preserves-while-ranking-second-in-production/
- [12] U.S. Department of Agriculture, Economic Research Service. (2026, April 30). Vegetables and Pulses Outlook: April 2026 (VGS-378). https://www-tx.ers.usda.gov/media/20874/vgs-378.pdf?v=79031
- [13] U.S. Department of Agriculture, Foreign Agricultural Service. (2026). Processed Vegetables 2025 Export Highlights. https://www.fas.usda.gov/processed-vegetables-2025-export-highlights
- [14] Congressional Research Service. (2026, September 17). Section 232 Tariffs on Steel and Aluminum. https://www.congress.gov/crs-product/IN12519
- [15] Can Manufacturers Institute. (2025, September 22). Majority of Americans Point to Steel Tariffs for Skyrocketing Grocery Costs. https://www.cancentral.com/majority-of-americans-point-to-steel-tariffs-for-skyrocketing-grocery-costs/
- [16] FranceAgriMer. (2026, January). Panorama statistique des fruits et légumes transformés 2024. https://www.franceagrimer.fr/sites/default/files/2026-01/ETU-FL-2025-PANORAMA-STATISTIQUE-FL-TRANSFORMES-2024.pdf
- [17] La France Agricole, citing UNILET. (2026, June 4). La production de légumes d'industrie a dégringolé en 2025. https://www.lafranceagricole.fr/conjoncture-cultures/article/899467/la-production-de-legumes-d-industrie-a-degringole-en-2025
- [18] European Commission, Directorate-General for Trade and Economic Security. (2026, February 6). Commission acts against unfairly traded imports of sweetcorn from China. https://policy.trade.ec.europa.eu/news/commission-acts-against-unfairly-traded-imports-sweetcorn-china-2026-02-06_en
- [19] Pacific Coast Producers. (2026, May 11). Canned fruits and canned tomatoes for private brands. https://pacificcoastproducers.com/
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Vegetable Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Vegetable Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Vegetable Type, 2026 to 2036
- Tomatoes
- Corn
- Peas
- Beans
- Carrots
- Potatoes
- Mushrooms
- Others
- Y-o-Y Growth Trend Analysis By Vegetable Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Vegetable Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Packing Medium, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Packing Medium, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Packing Medium, 2026 to 2036
- Water and Brine
- Oil
- Juice and Sauce
- Y-o-Y Growth Trend Analysis By Packing Medium, 2021 to 2025
- Absolute $ Opportunity Analysis By Packing Medium, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- Household Retail
- Foodservice
- Food Processing
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia
- Oceania
- Middle East
- Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- South Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Oceania Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Middle East Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Mexico
- Italy
- Japan
- United States
- France
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Vegetable Type
- By Nature
- By Packing Medium
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Seneca Foods Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Fresh Del Monte Produce Inc.
- Bonduelle Group
- Pacific Coast Producers
- Seneca Foods Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 5: Global Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 8: North America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 11: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 13: Latin America Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 14: Latin America Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 15: Latin America Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 16: Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: Europe Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 18: Europe Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 19: Europe Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 20: Europe Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 21: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 23: East Asia Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 24: East Asia Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 25: East Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 26: South Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 27: South Asia Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 28: South Asia Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 29: South Asia Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 30: South Asia Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 31: Oceania Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 32: Oceania Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 33: Oceania Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 34: Oceania Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 35: Oceania Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 36: Middle East Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 37: Middle East Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 38: Middle East Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 39: Middle East Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 40: Middle East Market Value (USD Million) Forecast by End Use, 2021 to 2036
- Table 41: Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 42: Africa Market Value (USD Million) Forecast by Vegetable Type, 2021 to 2036
- Table 43: Africa Market Value (USD Million) Forecast by Nature, 2021 to 2036
- Table 44: Africa Market Value (USD Million) Forecast by Packing Medium, 2021 to 2036
- Table 45: Africa Market Value (USD Million) Forecast by End Use, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Vegetable Type
- Figure 6: Global Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Nature
- Figure 9: Global Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packing Medium
- Figure 12: Global Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by End Use
- Figure 15: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: South Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Oceania Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: North America Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 28: North America Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 29: North America Market Attractiveness Analysis by Vegetable Type
- Figure 30: North America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 31: North America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 32: North America Market Attractiveness Analysis by Nature
- Figure 33: North America Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 34: North America Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 35: North America Market Attractiveness Analysis by Packing Medium
- Figure 36: North America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 37: North America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 38: North America Market Attractiveness Analysis by End Use
- Figure 39: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 40: Latin America Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 41: Latin America Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 42: Latin America Market Attractiveness Analysis by Vegetable Type
- Figure 43: Latin America Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 44: Latin America Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 45: Latin America Market Attractiveness Analysis by Nature
- Figure 46: Latin America Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 47: Latin America Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 48: Latin America Market Attractiveness Analysis by Packing Medium
- Figure 49: Latin America Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 50: Latin America Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 51: Latin America Market Attractiveness Analysis by End Use
- Figure 52: Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Europe Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 54: Europe Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 55: Europe Market Attractiveness Analysis by Vegetable Type
- Figure 56: Europe Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 57: Europe Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 58: Europe Market Attractiveness Analysis by Nature
- Figure 59: Europe Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 60: Europe Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 61: Europe Market Attractiveness Analysis by Packing Medium
- Figure 62: Europe Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 63: Europe Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 64: Europe Market Attractiveness Analysis by End Use
- Figure 65: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 66: East Asia Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Vegetable Type
- Figure 69: East Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Nature
- Figure 72: East Asia Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 73: East Asia Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 74: East Asia Market Attractiveness Analysis by Packing Medium
- Figure 75: East Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 76: East Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 77: East Asia Market Attractiveness Analysis by End Use
- Figure 78: South Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 79: South Asia Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 80: South Asia Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 81: South Asia Market Attractiveness Analysis by Vegetable Type
- Figure 82: South Asia Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 83: South Asia Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 84: South Asia Market Attractiveness Analysis by Nature
- Figure 85: South Asia Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 86: South Asia Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 87: South Asia Market Attractiveness Analysis by Packing Medium
- Figure 88: South Asia Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 89: South Asia Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 90: South Asia Market Attractiveness Analysis by End Use
- Figure 91: Oceania Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 92: Oceania Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 93: Oceania Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 94: Oceania Market Attractiveness Analysis by Vegetable Type
- Figure 95: Oceania Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 96: Oceania Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 97: Oceania Market Attractiveness Analysis by Nature
- Figure 98: Oceania Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 99: Oceania Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 100: Oceania Market Attractiveness Analysis by Packing Medium
- Figure 101: Oceania Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 102: Oceania Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 103: Oceania Market Attractiveness Analysis by End Use
- Figure 104: Middle East Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 105: Middle East Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 106: Middle East Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 107: Middle East Market Attractiveness Analysis by Vegetable Type
- Figure 108: Middle East Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 109: Middle East Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 110: Middle East Market Attractiveness Analysis by Nature
- Figure 111: Middle East Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 112: Middle East Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 113: Middle East Market Attractiveness Analysis by Packing Medium
- Figure 114: Middle East Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 115: Middle East Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 116: Middle East Market Attractiveness Analysis by End Use
- Figure 117: Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 118: Africa Market Value Share and BPS Analysis by Vegetable Type, 2026 and 2036
- Figure 119: Africa Market Y-o-Y Growth Comparison by Vegetable Type, 2026-2036
- Figure 120: Africa Market Attractiveness Analysis by Vegetable Type
- Figure 121: Africa Market Value Share and BPS Analysis by Nature, 2026 and 2036
- Figure 122: Africa Market Y-o-Y Growth Comparison by Nature, 2026-2036
- Figure 123: Africa Market Attractiveness Analysis by Nature
- Figure 124: Africa Market Value Share and BPS Analysis by Packing Medium, 2026 and 2036
- Figure 125: Africa Market Y-o-Y Growth Comparison by Packing Medium, 2026-2036
- Figure 126: Africa Market Attractiveness Analysis by Packing Medium
- Figure 127: Africa Market Value Share and BPS Analysis by End Use, 2026 and 2036
- Figure 128: Africa Market Y-o-Y Growth Comparison by End Use, 2026-2036
- Figure 129: Africa Market Attractiveness Analysis by End Use
- Figure 130: Global Market - Tier Structure Analysis
- Figure 131: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Canned Vegetable Market in 2026?
FMI estimates the market at USD 25,637.0 million in 2026, up from USD 24,890.0 million in 2025. It is forecast to reach USD 35,130.0 million by 2036 at a 3.2% CAGR.
Which vegetable type leads the Canned Vegetable Market in 2026?
Tomatoes lead by vegetable type with 26.0% in 2026. Corn, peas, beans, carrots, potatoes, mushrooms and others hold 74.0%.
Which nature segment leads the market?
Conventional products lead by nature with 92.0% in 2026. Organic products hold 8.0%.
Which country is forecast to grow fastest through 2036?
Mexico has the highest forecast CAGR among the profiled countries at 3.4% during 2026 to 2036, followed by Italy at 2.6%.
What happened to Del Monte Foods?
Del Monte Foods filed for Chapter 11 in July 2025 [2]. Fresh Del Monte completed the purchase of its vegetable and tomato assets on 19 March 2026 [4]. Canned fruit and broth assets went to separate buyers [3].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
