
- Market Size (2026)
- USD 28.5 Bn
- Forecast (2036)
- USD 76.7 Bn
- CAGR (2026 to 2036)
- 10.4%
How big is RTD Canned Cocktail Market in 2026?
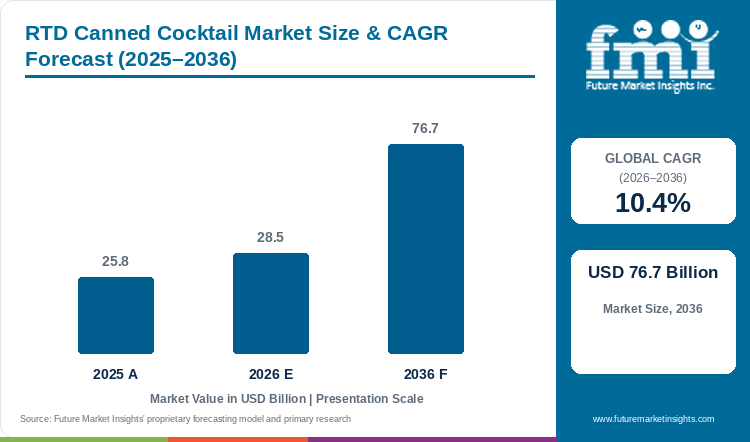
Demand for RTD canned cocktails is projected to expand at 10.4% CAGR between 2026 and 2036. Industry value grows from USD 25.8 billion in 2025 to USD 28.5 billion in 2026 and is projected to reach USD 76.7 billion by 2036.
Global RTD canned cocktail valuation advances from USD 25.8 billion in 2025 to USD 28.5 billion in 2026 and is forecast to attain USD 76.7 billion by 2036, representing a 10.4% CAGR from 2026 to 2036 and USD 48.2 billion in added revenue. Delivering consistent bar-strength drinks without trained bartenders or multi-bottle mixing setups has pushed beverage producers toward factory-blended spirit formats. Bottled and canned spirit-based pre-mixed cocktails rose 22.4% in taxable removals according to February 2025 Alcohol and Tobacco Tax and Trade Bureau production records [1]. According to Future Market Insights analysis, shoppers trading up from malt-based hard seltzer lines favor standard classic formulations, which capture 32.0% of 2026 product type / variety demand, even as volumetric spirit excise taxes pressure bottler margins.
Key Market Trends & Insights
- By product type / variety: With a 32.0% share in 2026, standard classic formulation led the category, underpinned by broad consumer familiarity with margarita, gin-and-tonic, and Moscow mule recipes.
- By packaging format: Glass bottles (750ml) held the leading share of 47.9% in 2026, owing to multi-serve dinner-party pouring and resealable home bar convenience.
- By distribution channel: Off-trade (retail supermarkets & liquor stores) accounted for 38.5% of demand in 2026, reinforced by dedicated chilled vault displays and seasonal variety multipacks.
Regional Highlights
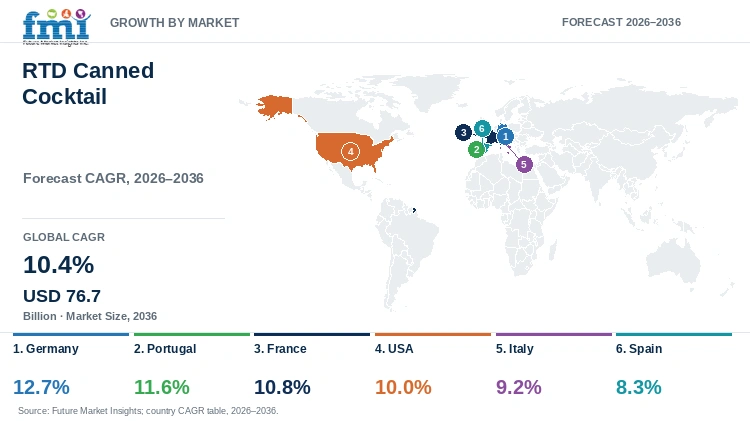
- Fastest-growing evaluated country: Germany, at 12.7% CAGR from 2026 to 2036.
- By country: Portugal at 11.6%, France at 10.8%, and the USA at 10.0% follow, while Italy at 9.2% and Spain at 8.3% record the lowest evaluated CAGRs.
Market Size & Forecast
Table 1: Market Size and Forecast for the RTD Canned Cocktail Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 25.8 billion |
| Estimated Market Size in 2026 | USD 28.5 billion |
| Projected Market Size by 2036 | USD 76.7 billion |
| CAGR, 2026 to 2036 | 10.4% |
| Added Revenue, 2026 to 2036 | USD 48.2 billion |
Volumetric distilled-spirit excise brackets in the United States and mandatory single-use container deposit systems (Pfand) in Germany govern how beverage packers price and distribute pre-mixed cocktails across retail jurisdictions. When distillers switch from fermented malt bases to real agave tequila, London dry gin, or aged bourbon, per-liter tax liabilities rise sharply in regulated liquor states. Ready-to-serve spirit aperitifs and long drinks accounted for 14.8% of off-premise spirits volume growth across Western European supermarkets in March 2025 spiritsEUROPE trade statistics [2]. To protect shelf margins, multinational distillers are installing rotary counter-pressure fillers to package ready-to-drink alcoholic beverages with stable carbonation and zero dissolved oxygen pickup across grocery cold chains.
Canning Line Throughput and Packaging Volume Sizing
Table 2: Canning Line Throughput and Packaging Volume Sizing for the RTD Canned Cocktail Market (USD billion and billion liters), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 25.8 | 28.5 | 76.7 |
| Commercial pre-mixed volume packaged (billion liters) | 3.1 to 3.4 | 3.4 to 3.8 | 8.6 to 9.5 |
| Single-serve and multi-serve units filled (billion units) | 9.8 to 10.6 | 10.8 to 11.7 | 26.5 to 29.0 |
| Average wholesale realization per liter (USD) | 7.60 to 8.30 | 7.75 to 8.45 | 8.20 to 8.95 |
Operational note: Bottling and canning metrics cover high-speed rotary counter-pressure fillers, 750ml flint glass lines, and hospitality draught kegs operating across licensed spirits and wine pre-mix plants.
Retail Cooler Allocation & Hospitality Serving Sizing
Hospitality operators at stadiums, airports, and resort pools use pre-batching cans and 750ml pouring bottles to cut bar wait times and eliminate free-pour liquor waste. Inside aluminum cans, epoxy-free polymer liners are required so acidic lime and grapefruit juices do not corrode bare metal during warm warehouse transit. Summer festival concessions and grocery cold-vault resets continue to pull single-serve spirit mixes and specialty liqueurs into routine off-premise shopping baskets.
Table 3: Retail Cooler and Hospitality Throughput Indicators for the RTD Canned Cocktail Market (USD and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| High-speed rotary spirit canning lines worldwide (units) | 480 | 525 | 940 |
| Average filler speed (cans per minute) | 750 | 800 | 1,050 |
| Annual RTD cocktail facings per supermarket cold vault (SKUs) | 28 to 34 | 32 to 38 | 55 to 65 |
| Average annual off-trade spend per licensed outlet (USD thousand) | 18.5 to 22.0 | 20.4 to 24.5 | 48.0 to 56.0 |
Table 4: Channel & Packaging Revenue Indicators for the RTD Canned Cocktail Market (USD billion and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Sector Scope |
|---|---|---|
| Market size, 2026 | USD 28.5 billion | Global RTD canned cocktail revenues |
| Glass bottles (750ml) revenue, 2026 | USD 13.7 billion | 47.9% packaging format share |
| Off-trade retail supermarket & liquor store revenue, 2026 | USD 11.0 billion | 38.5% distribution channel share |
| Standard classic formulation revenue, 2026 | USD 9.1 billion | 32.0% product type / variety share |
Analyst Perspective
"Distillers using real aged spirits and nitrogen-dosed canning lines capture higher retail price realization than malt-based alternatives. Differential spirit excise taxes and state three-tier distribution rules still restrict grocery shelf access in regulated markets."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the RTD canned cocktail market segmented?
The RTD canned cocktail market is segmented by product type / variety, packaging format, and distribution channel. In 2026, standard classic formulation is projected at 32.0%, glass bottles (750ml) at 47.9%, and off-trade (retail supermarkets & liquor stores) at 38.5%.
By product type / variety: Standard classic formulation, premium craft & artisanal, flavored / infused variant, and low-alcohol / zero-ABV line.
By packaging format: Glass bottles (750ml), aluminum cans & single-serve, and bag-in-box & draught kegs.
By distribution channel: Off-trade (retail supermarkets & liquor stores), on-trade (bars, pubs & restaurants), and direct-to-consumer e-commerce.
Why does Standard Classic Formulation lead the product type / variety category?
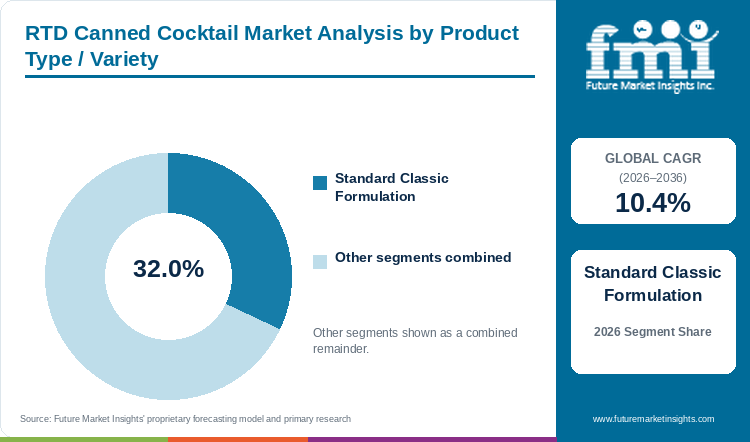
Standard classic formulation is projected to capture 32.0% of product type / variety demand in 2026, underpinned by familiar spirit recipes.
Table 5: Product Type / Variety Share for the RTD Canned Cocktail Market (percentage share), 2026
| Product Type / Variety | Share (2026) |
|---|---|
| Standard Classic Formulation | 32.0% |
| Other Segments Combined | 68.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Type / Variety Leadership and Market Growth for the RTD Canned Cocktail Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.4% |
| Leading Segment | Standard Classic Formulation |
Retail beverage shoppers recognize time-tested bar recipes such as lime margaritas, rum mojitos, whiskey highballs, and gin-and-tonics immediately on cold-vault shelves without needing in-store sampling. Beverage conglomerates calibrate these classic blends between 5.0% and 8.0% alcohol by volume so they match draught beer sessionability while retaining distilled spirit character. Along with familiar recipes, distillers expanding ready to drink cocktails use flash-pasteurized lime and grapefruit distillates to prevent terpene ring separation during ambient storage. Experimental botanical infusions suffer faster retail SKU delisting, whereas classic recipes hold permanent four-pack facings year-round.
- Standard classic formulation is projected to capture 32.0% of product type / variety revenue in 2026, supported by high repeat purchase rates for margarita, paloma, and gin-and-tonic multipacks.
- Premixed tequila margaritas and vodka sodas generated 54.0% of U.S. spirits-based RTD retail dollar sales according to February 2025 Distilled Spirits Council of the United States data [3].
What makes Glass Bottles (750ml) central to the packaging format category?
Glass bottles (750ml) are anticipated to contribute 47.9% of packaging format sales in 2026, owing to multi-serve home entertaining occasions.
Higher-proof cocktails such as barrel-aged Old Fashioneds, Negronis, Manhattan blends, and espresso martinis are bottled in 750ml flint glass for dinner-party pouring and hotel bar service, giving glass a 47.9% share in 2026, as noted by FMI. Thick glass walls provide an oxygen-impermeable barrier that protects vermouth, aromatic bitters, and cream liqueur emulsions from flavor scalping over 18-month shelf lives. Furthermore, distributors supplying pre-mixed alcoholic drinks realize substantially higher dollar revenue per 750ml bottle than on single 250ml cans. While aluminum cans expand rapidly in outdoor parks and stadiums, 750ml glass formats anchor holiday gifting and home bar replenishment.
- Glass bottles (750ml) are anticipated to account for 47.9% of packaging format revenue in 2026, driven by higher per-unit price realization and zero liner flavor interaction.
- North American orders for embossed 750ml flint glass bottles from premium spirits and pre-mixed cocktail brands rose 14.5% in April 2025 Glass Packaging Institute tracking [4].
What gives Off-Trade (Retail Supermarkets & Liquor Stores) the leading position in distribution channel?
By distribution channel, off-trade supermarkets and liquor stores command 38.5% share in 2026, reinforced by chilled multipack placements.
Grocery chains and licensed bottle shops dedicate end-cap refrigerators and checkout chillers to four-pack and eight-pack variety cartons, making off-trade retail the primary volume engine. Take-home shoppers prefer picking up pre-chilled cocktail cans alongside weekend grocery baskets rather than paying on-premise bar markups. Besides this, liquor retailers place single-serve rtd cocktail shots and 355ml slim cans at impulse counters to encourage trial of new tequila and gin bases. On-trade bars and direct e-commerce platforms face per-drink hospitality markups or adult-signature parcel surcharges that limit bulk case volume.
- Off-trade (retail supermarkets & liquor stores) is set to hold 38.5% of distribution channel demand in 2026, facilitated by expanding grocery cold-vault space and seasonal cross-merchandising.
- Expanded refrigerated shelf space for spirit-based RTD multipacks was reported by 64.0% of licensed U.S. supermarkets in a June 2025 Food Industry Association survey [5].
What are the drivers, restraints, and opportunities in the RTD canned cocktail market?
Consumer migration toward real distilled spirits elevates baseline volume, whereas higher spirit excise taxation and can liner costs restrain margins, and zero-sugar botanical formulations unlock new drinking occasions.
- Driver: Drinkers trading up from fermented malt seltzers demand authentic tequila, vodka, and gin cocktails with natural citrus juice and bar-grade balance.
- Restraint: Spirit-rate excise taxes and aluminum can sheet tariffs widen the retail price gap between spirit RTDs and conventional domestic beer multipacks.
- Opportunity: Formulating zero-sugar, low-ABV, and nitrogen-infused espresso and botanical cocktails opens daytime social and health-conscious retail segments.
Growth Analysis and Future Potential: Consumer Trade-Up from Malt Seltzers to Real Spirits
Retail beverage buyers have shifted cold-box space away from fermented sugar seltzers as consumers look for clean distilled spirit bases without lingering malt aftertastes. Distillers formulating with real blanco tequila, London dry gin, and aged bourbon achieve stronger repeat purchase velocity across supermarket chains. Standardized ABV and calorie labeling on single-serve pre-mixed containers helps consumers track portion intake more accurately than free-poured home drinks, as noted in October 2025 World Health Organization alcohol monitoring briefs [6]. To match craft bar aroma, formulators blend cold-pressed citrus oils and specialized cocktail syrup bases into counter-pressure-filled cans before pasteurization.
Risk Assessment of the RTD Canned Cocktail Market: Spirit Excise Disparities and Can Supply Friction
In most North American states and European member countries, a 355ml can containing 5.0% ABV distilled spirits is taxed at a substantially higher volumetric excise rate than an identical 5.0% ABV beer or cider can. This tax differential inflates retail four-pack prices and bars spirit-based cans from beer-and-wine-only grocery stores in restricted jurisdictions. Specialty internal polymer coatings and aluminum coil surcharges raised beverage can unit packaging costs by 11.8% year-on-year in July 2025 Can Manufacturers Institute reports [7]. Consequently, smaller craft distillers competing alongside cider and perry brands face working-capital strain when pre-ordering printed can minimums.
Commercial Opportunity Analysis: Zero-Sugar Formulations and Nitrogen-Dosed Coffee Cocktails
Calorie-conscious consumers frequently avoid traditional sugary mixers such as pre-made pina coladas or sweet sour mixes, creating a major opening for zero-sugar and lower-alcohol spirit spritzers. Beverage engineers now combine liquid nitrogen widget dosing with cold-brew coffee and real vodka to deliver cascading foam heads in canned espresso martinis, while using monk fruit or erythritol in 100-calorie tequila palomas. Dietary beverage tracking from the National Center for Health Statistics in August 2025 indicated that 39.0% of adult alcohol purchasers actively check sugar gram counts on ready to drink beverages before purchase [8]. Brands printing clear front-of-pack carbohydrate disclosures secure premium wellness end-caps.
RTD Canned Cocktail Market by Country (2026 to 2036)
Outdoor summer long-drink consumption and supermarket checkout chillers propel Germany to a 12.7% CAGR between 2026 and 2036, ahead of Portugal at 11.6% and France at 10.8%, while mature Mediterranean gin-tonic channels in Spain progress at 8.3% CAGR. FMI data suggests that national growth trajectories hinge on spirit-versus-malt excise tax brackets and grocery store liquor licensing rules.
Table 7: Country CAGR and Primary Growth Levers for the RTD Canned Cocktail Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Germany | 12.7% | Open-air festival culture and widespread supermarket adoption of canned long drinks |
| Portugal | 11.6% | Algarve and Lisbon coastal hospitality and canned white-port-and-tonic spritzers |
| France | 10.8% | Urban terrace aperitif shift toward mixologist-crafted low-bitterness spritz cans |
| USA | 10.0% | Tequila and vodka RTD trade-up alongside state excise and grocery access reforms |
| Italy | 9.2% | Evening piazza aperitivo demand for single-serve bitter spritzers and Negronis |
| Spain | 8.3% | Mediterranean beach tourism and chilled gin-and-tonic convenience multipacks |
Note: Country growth rates reflect 2026 to 2036 assessment period projections.
Germany RTD Canned Cocktail Market Outlook (2026 to 2036)
Permissive public outdoor consumption laws and an active summer festival calendar make Germany the most dynamic European market for single-serve spirit long drinks, expanding at a projected 12.7% CAGR from 2026 to 2036. Unlike markets restricted to specialty liquor shops, German supermarkets, discounters, and train-station kiosks sell chilled rum-cola, whisky-ginger, and gin-tonic cans directly at checkout coolers. Domestic off-trade volume for pre-mixed spirit long drinks jumped 28.5% across German food retail chains in October 2025 Bundesverband der Deutschen Spirituosen-Industrie (BSI) tracking [9]. Mandatory EUR 0.25 single-use can deposit rules (Pfand) still require reverse-vending barcode registration, prompting imported brands to partner with domestic co-packers.
Key takeaway: Checkout chiller access across German supermarkets and open-air long-drink consumption fuel a 12.7% CAGR through 2036.
Portugal RTD Canned Cocktail Market Outlook (2026 to 2036)
Year-round coastal tourism across the Algarve, Lisbon, and Porto has turned Portugal into a high-growth hub for regional wine-and-spirit spritzers. Adoption of RTD canned cocktails in Portugal is estimated to expand at 11.6% CAGR through 2036, propelled by domestic port wine houses launching canned white port and tonic, rose port spritzers, and sour cherry ginjinha mixes. Hospitality and beverage trade records from Statistics Portugal (INE) in November 2025 showed a 19.2% increase in packaged pre-mixed aperitif sales across coastal hotel and beach-bar concessions [10]. Sharp winter drops in tourist footfall create seasonal inventory swings, so Portuguese producers export winter production runs to diaspora retailers in France and the United Kingdom.
Key takeaway: Canned white-port-and-tonic launches across Algarve and Lisbon resorts propel Portugal at an 11.6% CAGR.
France RTD Canned Cocktail Market Outlook (2026 to 2036)
French consumers traditionally favored bottled wine and pastis during pre-dinner aperitif hours, but younger urban households in Paris, Lyon, and Marseille increasingly buy ready-to-pour cocktail bottles and slim cans for home gatherings. Revenue from RTD canned cocktail sales in France is projected to rise at 10.8% CAGR over the assessment period, supported by low-bitterness elderflower, gentian, and cognac-ginger recipes. Hypermarket revenue for premium bottled and canned cocktails grew 17.6% in December 2025 French Spirits Federation (FFS) figures as domestic distillers expanded aperitif lines [11]. Strict Loi Evin restrictions on alcohol advertising prevent mass broadcast campaigns, compelling brands to rely on hypermarket tasting kiosks and bartender-endorsed glass bottles.
Key takeaway: Mixologist-crafted aperitif bottles and Parisian hypermarket placements generate a 10.8% CAGR in France.
USA RTD Canned Cocktail Market Outlook (2026 to 2036)
The United States anchors global revenue volume as millions of legal-drinking-age consumers switch from malt hard seltzers to canned tequila ranch waters, vodka lemonades, and bourbon smash cocktails. Demand across the USA RTD canned cocktail sector is expected to increase at 10.0% CAGR through 2036, aided by state legislative bills lowering spirit RTD tax rates and permitting grocery store sales. Beverage surveillance from the Centers for Disease Control and Prevention and TTB tax records in January 2026 confirmed that spirits-based pre-mixed packages represented the fastest-growing category in U.S. licensed retail [12]. Franchise three-tier wholesaling laws still complicate multi-state launches, forcing distillers to sign national master distribution agreements.
Key takeaway: State excise tax Equalization bills and consumer migration toward tequila and vodka cans lift the USA at a 10.0% CAGR.
Italy RTD Canned Cocktail Market Outlook (2026 to 2036)
Evening piazza aperitivo rituals in Milan, Rome, Turin, and Bologna center on bitter citrus spritzes, Americanos, and Negronis, creating a natural fit for single-serve glass bottles and sleek aluminum cans. The outlook for RTD canned cocktails in Italy remains positive, with sales projected to increase at 9.2% CAGR through 2036 as historic Italian aperitif houses package bar-strength classics for home balconies. Federvini trade data published in February 2026 indicated that domestic off-trade sales of pre-mixed bitter aperitifs and ready-to-serve spritzes increased 15.4% across Italian supermarkets [13]. Strong local pride in fresh bartender preparation resists generic lookalike cans, so Italian producers emphasize authentic botanical macerations and embossed glass packaging.
Key takeaway: Single-serve Negroni and bitter-spritz bottles tailored to evening aperitivo hours support Italy's 9.2% CAGR.
Spain RTD Canned Cocktail Market Outlook (2026 to 2036)
Warm Mediterranean weather, late-night terrace dining, and high international beach tourism across Andalusia, Catalonia, and the Balearic Islands sustain steady volume demand for chilled gin-and-tonics, tinto de verano, and rum mojitos. By 2036, Spain is projected to grow at 8.3% CAGR, supported by supermarket convenience multipacks and summer festival concessions. Coastal convenience and supermarket sales of ready-to-drink spirit combinations rose 13.8% in March 2026 Spanish Spirits Federation (Espirituosos Espana) reporting [14]. Summer transit temperatures above 35 degrees Celsius can oxidize citrus aromatics in unrefrigerated trucks, requiring Spanish distributors to enforce insulated cold-chain delivery.
Key takeaway: Coastal tourism multipacks and insulated Mediterranean cold-chain delivery keep Spain expanding at an 8.3% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the RTD canned cocktail market?
Diageo plc, Pernod Ricard, Constellation Brands, Molson Coors Beverage Company, Anheuser-Busch InBev, Bacardi Limited, Beam Suntory, and The Coca-Cola Company are the notable companies in this market.
Securing national grocery cold-vault facings and stadium pouring rights requires both recognized parent-spirit trademarks and 1,000-can-per-minute rotary filling capacity. Heritage distillers including Diageo plc, Pernod Ricard, Bacardi Limited, and Beam Suntory bottle bar-strength margaritas, Negronis, and highballs using proprietary tequila, gin, rum, and bourbon stocks. Alongside heritage spirit houses, Anheuser-Busch InBev, Molson Coors Beverage Company, Constellation Brands, and The Coca-Cola Company use nationwide refrigerated distributor fleets to scale spirit seltzers and co-branded functional beverages.
- Global Distilled Spirits Houses: Diageo plc, Pernod Ricard, Bacardi Limited, and Beam Suntory extend flagship spirit trademarks into bar-strength canned and bottled cocktails.
- Multinational Brewing & Beverage Networks: Anheuser-Busch InBev, Molson Coors Beverage Company, and Constellation Brands utilize nationwide distributor fleets and high-speed canning plants.
- Co-Branded Mixer & Soft-Drink Platforms: The Coca-Cola Company partners with global spirit distillers to package recognizable branded mixer-and-spirit combinations.
Competitive Benchmarking: RTD Canned Cocktail Market
Table 8: Competitive Benchmarking for the RTD Canned Cocktail Market (qualitative capability ratings), 2026
| Company | Spirit Portfolio Depth | High-Speed Canning Scale | Off-Trade Cooler Access | Geographic Reach |
|---|---|---|---|---|
| Diageo plc | High | High | High | High |
| Pernod Ricard | High | Medium | High | High |
| Constellation Brands | Medium | High | High | Medium |
| Molson Coors Beverage Company | Medium | High | High | Medium |
| Anheuser-Busch InBev | Medium | High | High | High |
| Bacardi Limited | High | Medium | High | High |
| Beam Suntory | High | Medium | High | High |
| The Coca-Cola Company | Medium | High | High | High |
Scoring basis: Benchmarking tiers evaluate internal spirit distillation reserves against rotary canning throughput and cold-box merchandising reach. Distillers owning international agave, juniper, and barrel-aged whiskey stocks receive High marks for Spirit Portfolio Depth, while brewers and soft-drink packers score High on High-Speed Canning Scale through automated multi-pack lines.
Key Developments in the RTD Canned Cocktail Market
- Diageo plc expanded commercial distribution of its Crown Royal, Ketel One, and Tanqueray ready-to-serve cocktail multipacks and 750ml bottles in May 2026 following its Plainfield, Illinois canning line upgrade [15].
- Anheuser-Busch InBev widened retail cooler placement for its Cutwater Spirits and NÜTRL Vodka Seltzer variety packs across U.S. stadiums and supermarkets in March 2026 after adding counter-pressure canning capacity [16].
- Beam Suntory (Suntory Global Spirits) scaled international rollout of its On The Rocks bottled cocktails and -196 vodka fruit highball cans across Western Europe and the United States in January 2026 [17].
Key Players in the RTD Canned Cocktail Market
Global Distilled Spirits Houses
- Diageo plc
- Pernod Ricard
- Bacardi Limited
- Beam Suntory
Multinational Brewing & Beverage Networks
- Anheuser-Busch InBev
- Molson Coors Beverage Company
- Constellation Brands
Co-Branded Mixer & Soft-Drink Platforms
- The Coca-Cola Company
RTD Canned Cocktail Market - Report Scope
Table 9: Report Scope for the RTD Canned Cocktail Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Variety; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from pre-mixed ready-to-drink (RTD) cocktails, spirit-based and wine-based cocktail formulations across single-serve aluminum cans, multi-serve glass bottles (750ml), and bag-in-box or draught dispensing systems sold across off-trade retail and on-trade hospitality channels. Excludes straight unmixed spirits, conventional beers, and non-alcoholic mocktails. Scope & Packaging Note: While single-serve aluminum cans represent the fastest-growing dynamic format for outdoor and social consumption, multi-serve 750ml glass bottles anchor dinner-party pouring, holiday gifting, and premium on-premise bar programs, commanding 47.9% of total RTD cocktail packaging format value due to higher price-per-unit realization. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Germany, Portugal, France, USA, Italy, Spain, and additional countries in the full report |
| Key Companies Covered | Diageo plc, Pernod Ricard, Constellation Brands, Molson Coors Beverage Company, Anheuser-Busch InBev, Bacardi Limited, Beam Suntory, The Coca-Cola Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
RTD Canned Cocktail Market - Research Methodology
Table 10: Research Methodology for the RTD Canned Cocktail Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with master distillers, rotary canning plant directors, liquor wholesale distributors, supermarket beverage category buyers, and hospitality group managers to validate line speeds, excise tax impacts, shelf velocity, and packaging preferences. |
| Secondary Research | Secondary research included company annual filings, TTB and European excise tax registries, spiritsEUROPE and DISCUS statistical briefings, packaging institute reports, retail scanner summaries, and corporate brand announcements. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 assessment period were developed using top-down and bottom-up approaches to evaluate packaged liter volumes, wholesale case realizations, and channel distribution shares. |
| Data Triangulation and Validation | Data is validated against national distilled spirits removal data, aluminum can and glass bottle shipment indicators, and licensed retail outlet counts to ensure accuracy without double counting bulk unblended spirits. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's ready-to-drink beverage econometric model, calibrating evaluated national growth rates against the 10.4% global baseline through verified distilled spirits excise tax changes, single-serve retail canned cocktail shelf space, and premium premix on-premise adoption. |
| Operational Benchmark Traceability | Operational benchmarks (commercial pre-mixed volume packaged, aluminum can seaming speeds, and spirits tax tier rates) represent modeled estimates synthesized from TTB distilled spirits bulletins, DISCUS economic briefings, WHO alcohol databases, and commercial RTD brand filings. |
RTD Canned Cocktail Market by Segments
RTD Canned Cocktail Market segmented by Product Type / Variety:
- Standard Classic Formulation
- Premium Craft & Artisanal
- Flavored / Infused Variant
- Low-Alcohol / Zero-ABV Line
RTD Canned Cocktail Market segmented by Packaging Format:
- Glass Bottles (750ml)
- Aluminum Cans & Single-Serve
- Bag-in-Box & Draught Kegs
RTD Canned Cocktail Market segmented by Distribution Channel:
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs & Restaurants)
- Direct-to-Consumer E-Commerce
RTD Canned Cocktail Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Alcohol and Tobacco Tax and Trade Bureau. (2025, February 18). Distilled spirits production and pre-mixed cocktail taxable removals statistical report. Alcohol and Tobacco Tax and Trade Bureau Distilled Spirits Statistics.
- [2] spiritsEUROPE. (2025, March 24). European spirits and ready-to-serve aperitif off-premise market review 2025. Brussels Spirits Trade Monographs.
- [3] Distilled Spirits Council of the United States. (2025, February 27). Annual economic briefing: Premixed spirit cocktails and tequila RTD growth in U.S. retail. DISCUS Economic Reports.
- [4] Glass Packaging Institute. (2025, April 15). North American flint glass bottle shipments for premium spirits and multi-serve cocktails. GPI Packaging Industry Bulletins.
- [5] Food Industry Association. (2025, June 19). Supermarket cold-vault space allocation and adult beverage merchandising survey 2025. Arlington Retail Food Reports.
- [6] World Health Organization. (2025, October 10). Global monitoring update on beverage alcohol portion labeling and consumer health literacy. World Health Organization Alcohol Fact Sheets.
- [7] Can Manufacturers Institute. (2025, July 22). Aluminum beverage can sheet pricing, internal polymer liner standards, and specialty can shipments. CMI Technical Packaging Reviews.
- [8] National Center for Health Statistics. (2025, August 14). Adult dietary sugar monitoring and beverage label utilization in the United States. National Center for Health Statistics Alcohol Data.
- [9] Bundesverband der Deutschen Spirituosen-Industrie und -Importeure (BSI). (2025, October 28). Daten aus der Alkoholwirtschaft 2025: Longdrinks und Fertiggetraenke im Lebensmitteleinzelhandel. BSI Bonn Jahresberichte.
- [10] Statistics Portugal (INE). (2025, November 19). Hospitality beverage sales and regional port-spritzer packaging indicators in Algarve and Lisbon. Instituto Nacional de Estatistica Bulletins.
- [11] Federation Francaise des Spiritueux (FFS). (2025, December 11). Bilan economique des spiritueux et cocktails prets-a-boire en grande distribution francaise. FFS Paris Market Studies.
- [12] Centers for Disease Control and Prevention. (2026, January 16). Beverage alcohol retail distribution trends and state regulatory surveillance update. Centers for Disease Control and Prevention Alcohol Reports.
- [13] Federvini. (2026, February 12). Osservatorio sul mercato degli aperitivi pronti e spiriti nella distribuzione moderna italiana. Federvini Roma Rapporti Annuali.
- [14] Espirituosos Espana. (2026, March 09). Informe socioeconomico del sector de bebidas espirituosas y combinados listos para tomar en Espana. Madrid Trade Publications.
- [15] Diageo plc. (2026, May 14). North American and European commercial expansion of Crown Royal, Ketel One, and Tanqueray ready-to-serve cocktail formats. Diageo Corporate Newsroom.
- [16] Anheuser-Busch InBev SA/NV. (2026, March 26). Expansion of Cutwater Spirits and NÜTRL Vodka Seltzer high-speed canning and stadium distribution. AB InBev Investor Releases.
- [17] Suntory Global Spirits (Beam Suntory). (2026, January 29). International rollout of On The Rocks premium bottled cocktails and -196 fruit spirit highball cans. Suntory Corporate Announcements.
- [18] Pernod Ricard SA. (2025, June 18). European summer launch of ready-to-serve Lillet, Beefeater, and Malibu canned aperitif spritzers. Pernod Ricard Press Room.
- [19] Constellation Brands, Inc. (2025, October 23). Retail distribution expansion of Fresca Mixed and craft-inspired real-spirit canned cocktails across U.S. grocery chains. Constellation Brands Filings.
- [20] Molson Coors Beverage Company. (2026, January 15). Introduction of zero-sugar spirit-based canned cocktail extensions across North American convenience channels. Molson Coors News Releases.
- [21] Bacardi Limited. (2025, August 07). Expansion of Bacardi Real Rum Canned Cocktails and Patrón El Alto ready-to-pour hospitality formats. Bacardi Corporate Updates.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the RTD canned cocktail market in 2026 and what is forecast for 2036?
- Which consumer trade-up and hospitality factors support demand for RTD canned cocktails?
- Why does Standard Classic Formulation lead the product type / variety category?
- Why do Glass Bottles (750ml) lead the packaging format category globally?
- How do growth rates differ across Germany, Portugal, France, and the USA?
- Which notable distillers and beverage companies supply pre-mixed cocktails today?
- What spirit excise tax and can liner factors limit adoption in the RTD canned cocktail market?
- What should retail and hospitality buyers evaluate before listing an RTD canned cocktail line?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Variety, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Variety, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Variety, 2026 to 2036
- Standard Classic Formulation
- Premium Craft & Artisanal
- Flavored / Infused Variant
- Low-Alcohol / Zero-ABV Line
- Y-o-Y Growth Trend Analysis By Product Type / Variety, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Variety, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles (750ml)
- Aluminum Cans & Single-Serve
- Bag-in-Box & Draught Kegs
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Off-Trade (Retail Supermarkets & Liquor Stores)
- On-Trade (Bars, Pubs & Restaurants)
- Direct-to-Consumer E-Commerce
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Portugal
- Benelux
- Nordics
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Portugal
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Variety
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Diageo plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Pernod Ricard
- Constellation Brands
- Molson Coors Beverage Company
- Anheuser-Busch InBev
- Bacardi Limited
- Beam Suntory
- The Coca-Cola Company
- Diageo plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 5: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 9: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 10: Latin America Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 13: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Western Europe Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 15: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 17: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 18: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 19: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 20: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 21: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: East Asia Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 23: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 24: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 25: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 27: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 28: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Variety, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Variety
- Figure 6: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Packaging Format
- Figure 9: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Distribution Channel
- Figure 12: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: North America Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by Product Type / Variety
- Figure 26: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Packaging Format
- Figure 29: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Distribution Channel
- Figure 32: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: Latin America Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 34: Latin America Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 35: Latin America Market Attractiveness Analysis by Product Type / Variety
- Figure 36: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 37: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 38: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 39: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 42: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: Western Europe Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 44: Western Europe Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 45: Western Europe Market Attractiveness Analysis by Product Type / Variety
- Figure 46: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 47: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 48: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 49: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 50: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 51: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 52: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Eastern Europe Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 54: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 55: Eastern Europe Market Attractiveness Analysis by Product Type / Variety
- Figure 56: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 57: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 58: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 59: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 60: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 61: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 62: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: East Asia Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 64: East Asia Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 65: East Asia Market Attractiveness Analysis by Product Type / Variety
- Figure 66: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 67: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 68: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 69: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 70: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 71: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 72: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 74: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 75: South Asia and Pacific Market Attractiveness Analysis by Product Type / Variety
- Figure 76: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 77: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 78: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 79: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 80: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 81: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Variety, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Variety, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Type / Variety
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the RTD canned cocktail market in 2026, and what is forecast for 2036?
The global RTD canned cocktail market is estimated to reach USD 28.5 billion in 2026. The market is projected to expand further and reach USD 76.7 billion by 2036, driven by consumer demand for bar-strength spirit pre-mixes.
What is the CAGR for the RTD canned cocktail market from 2026 to 2036?
As per FMI, the RTD canned cocktail market is projected to grow at a 10.4% CAGR from 2026 to 2036. Growth is supported by expanding supermarket cold-vault facings and high-speed counter-pressure canning lines.
Which product type / variety segment leads the RTD canned cocktail market in 2026?
Standard classic formulation is projected to hold 32.0% of product type / variety demand in 2026. The segment benefits from consumer familiarity with margarita, gin-and-tonic, and Moscow mule recipes.
Which packaging format holds the largest RTD canned cocktail share in 2026?
Glass bottles (750ml) are estimated to account for 47.9% of packaging format demand in 2026. Demand is supported by multi-serve home entertaining and zero flavor interaction for higher-proof cocktails.
Which country has a notable RTD canned cocktail growth outlook during the assessment period?
FMI finds that Germany is projected to register a 12.7% CAGR during the 2026 to 2036 assessment period. Expansion is supported by permissive outdoor festival drinking laws and supermarket checkout cooler placement.
Who are the key players active in the RTD canned cocktail market?
Notable companies active in the market include Diageo plc, Pernod Ricard, Constellation Brands, Molson Coors Beverage Company, Anheuser-Busch InBev, Bacardi Limited, Beam Suntory, and The Coca-Cola Company. These producers focus on authentic spirit bases, zero-sugar formulations, and multi-pack retail distribution.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
