

- Market Size (2026)
- USD 34.0 Bn
- Forecast (2036)
- USD 59.7 Bn
- CAGR (2026 to 2036)
- 5.8%
How big is Ready To Drink (RTD) Tea Market in 2026?
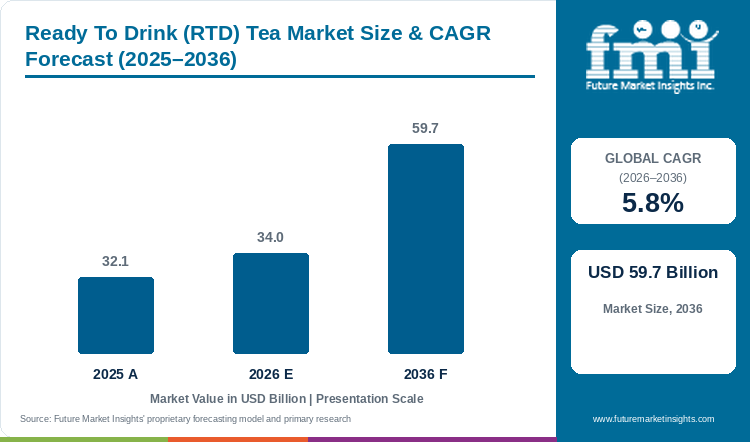
Demand for the ready to drink tea market is projected to expand at 5.8% CAGR between 2026 and 2036. Industry value grows from USD 32.1 billion in 2025 to USD 34.0 billion in 2026 and is projected to reach USD 59.7 billion by 2036.
According to Future Market Insights analysis, the global ready to drink tea market stood at USD 32.1 billion in 2025 and reaches USD 34.0 billion in 2026. Revenue is projected to reach USD 59.7 billion by 2036 at a 5.8% CAGR over the assessment period, adding USD 25.7 billion in incremental opportunity. Portable tea formats are expanding beyond heavily sweetened styles into unsweetened, cold-brewed, and low-sugar formulations. In July 2026, PepsiCo connected four BRISK iced tea flavors with a national Nintendo retail activation, driving trial through interactive displays and recognizable fruit blends[1]. Flavored / botanical infusion RTD tea captures the leading position with 45.9% share in 2026, supported by rapid shelf turnover in modern retail aisles.
Key Market Trends & Insights
- By product variety / flavor: flavored / botanical infusion is projected to hold 45.9% in 2026, driven by fruit and botanical combinations.
- By packaging format: slim aluminum cans are estimated to hold 35.8% in 2026, supported by rapid chilling and compact merchandising.
- By distribution channel: supermarkets and hypermarkets are forecast to represent 32.4% in 2026, enabled by chilled aisles and multipacks.
Regional Highlights
- Fastest-growing evaluated country: South Korea, at 7.1% CAGR from 2026 to 2036.
- By country: the UK reaches 6.5%, Germany 6.0%, the USA 5.6%, Brazil 5.1%, and Italy 4.6% follow through 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ready To Drink Tea Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 32.1 billion |
| Estimated Market Size in 2026 | USD 34.0 billion |
| Projected Market Size by 2036 | USD 59.7 billion |
| CAGR, 2026 to 2036 | 5.8% |
| Added Revenue, 2026 to 2036 | USD 25.7 billion |
Future Market Insights research indicates that lower-sugar reformulation will separate country outcomes across regional distribution channels. The Coca-Cola Company maintains a diversified brand portfolio featuring Gold Peak, FUZE, and Peace Tea while expanding reduced-sugar choice and compact package architectures[2]. Regulatory pressure in Europe compels beverage manufacturers to formulate below statutory sugar levy thresholds, encouraging cross-category development across functional beverages and natural antioxidant iced infusions.
Retail Volume and Purchase-Occasion Sizing
Table 2: Retail Volume and Purchase-Occasion Sizing for the Ready To Drink Tea Market (USD billion and index values), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 32.1 | 34.0 | 59.7 |
| Illustrative retail volume index | 100.0 | 104.0 | 151.0 |
| Value per indexed unit | 0.321 | 0.327 | 0.395 |
| Single-serve purchase index | 100.0 | 105.0 | 158.0 |
Calculation basis: Revenue values are fixed report estimates. Volume and purchase indices are analytical scenarios and not measured global sales totals.
Per Capita & Retail Channel Sizing
RTD tea converts brewed-tea familiarity into immediate consumption across grocery and convenience coolers. Supermarkets provide assortment depth while convenience stores shorten the trip between purchase and consumption. Consumer demand intersects with botanical beverages when botanical extracts or zero-sugar recipes carry clear hydration and functional wellness cues.
Table 3: Per Capita and Retail Indicators for the Ready To Drink Tea Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 3.90 | 4.10 | 6.67 |
| Spend per 1,000 people (USD) | 3,900 | 4,096 | 6,670 |
| Supermarket revenue (USD billion) | 10.4 | 11.0 | 19.3 |
Table 4: Packaging and Channel Spending Indicators for the Ready To Drink Tea Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 34.0 billion | Report value |
| Slim aluminum can revenue | USD 12.2 billion | 35.8% share |
| Supermarket and hypermarket revenue | USD 11.0 billion | 32.4% share |
| Other channel revenue | USD 23.0 billion | 67.6% balance |
Analyst Perspective
“RTD tea is moving beyond one sweet iced-tea formula into controlled-sugar and botanical recipes. In my experience, brands linking those recipes to recyclable single-serve packs can gain broader retail placement.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the ready to drink tea market segmented?
The ready to drink tea market is segmented by product variety / flavor, packaging format, and distribution channel. In 2026, flavored / botanical infusion is projected at 45.9%, slim aluminum cans at 35.8%, and supermarkets and hypermarkets at 32.4%.
The market is segmented across three primary categories and seven geographic regions:
- By product variety / flavor: Flavored / botanical infusion, classic unflavored / traditional, and zero-sugar / sugar-free variant.
- By packaging format: Slim aluminum cans, PET bottles, glass bottles, and aseptic paperboard cartons.
- By distribution channel: Supermarkets & hypermarkets, convenience stores & gas stations, online retail & subscription, and food service & cafes.
Why does flavored / botanical infusion lead product variety demand?
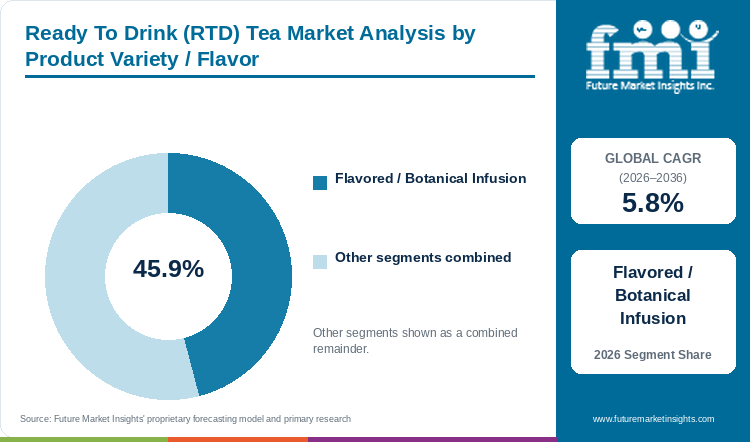
Flavored / botanical infusion is projected to hold 45.9% of product variety revenue in 2026, driven by diversified taste preferences and lower-sugar formulations.
Table 5: Product Variety / Flavor Share for the Ready To Drink Tea Market (percentage share), 2026
| Product Variety / Flavor | Share (2026) |
|---|---|
| Flavored / botanical infusion | 45.9% |
| Other Segments Combined | 54.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Product Variety Leadership and Market Growth for the Ready To Drink Tea Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Flavored / botanical infusion |
Fruit and botanical combinations allow beverage developers to expand flavor variety without departing from authentic brewed-tea profiles. Infusions of peach, lemon, hibiscus, and green tea accommodate reduced-sugar recipes while preserving crisp refreshment cues. This flavor versatility aligns with developments in ready-to-drink beverages where shoppers seek natural alternatives to synthetic carbonated soft drinks.
- Flavored / botanical infusion represents 45.9% of product variety / flavor in 2026 through wider flavor and occasion coverage.
- In May 2026, ITO EN expanded its Oi Ocha botanical portfolio with cold-brewed fruit and jasmine green tea infusions across specialty grocers[11].
What supports slim aluminum cans as a preferred packaging format?
Slim aluminum cans are estimated to capture 35.8% of packaging format revenue in 2026, supported by rapid refrigeration efficiency and modern visual appeal.
Slim cans cool rapidly in commercial retail refrigerators and fit neatly into narrow convenience grab-and-go merchandisers. The full printable surface enables vibrant single-serve branding while hermetically sealing delicate tea polyphenols against light-induced degradation. Commercial growth in aluminum cans ensures that beverage bottlers secure dependable, infinitely recyclable packaging substrates.
- Slim aluminum cans hold 35.8% of packaging format revenue in 2026 through cold-chain speed and visible single-serve branding.
- In September 2026, Crown Holdings broke ground on a high-speed manufacturing plant designed for approximately 2.2 billion beverage cans annually[3].
How are supermarkets gaining use across distribution channels?
Supermarkets and hypermarkets are expected to lead distribution channel sales with 32.4% share in 2026, enabled by chilled multi-tier aisles and multipack merchandising.
Supermarkets merchandise RTD tea adjacent to bottled water and refrigerated soft drinks, facilitating instant comparisons regarding sugar content and unit pricing. Large-format grocery stores leverage multi-pack promotions to convert impulse trials into regular household consumption trips. Expanding reach across food and beverage retail encourages supermarkets to dedicate dedicated endcap coolers to artisanal and organic cold-brewed tea labels.
- Supermarkets and hypermarkets account for 32.4% of distribution revenue in 2026 through assortment depth and multipack economics.
- Retailers compare unsweetened, zero-sugar, botanical, and traditional lines within a unified beverage merchandising aisle.
What are the drivers, restraints, and opportunities in the ready to drink tea market?
Lower-sugar portfolios expand use, whereas packaging compliance limits launches, and botanical recipes create new drinking occasions.
- Driver: Controlled-sugar recipes widen everyday demand beyond traditional sweet iced tea.
- Restraint: Packaging deposits and multi-format procurement raise launch costs across countries.
- Opportunity: Botanical and fruit blends can extend tea into afternoon and alcohol-alternative occasions.
Growth Analysis and Future Potential: Lower-Sugar Demand
FMI research indicates that consumer wellness priorities are compelling brand owners to reformulate legacy sweet tea recipes toward reduced-sugar and zero-calorie alternatives. Coca-Cola expands low- and no-sugar options across its RTD tea portfolio while introducing compact pack sizes. Market dynamics in zero sugar beverages demonstrate that authentic brewed astringency allows beverage makers to reduce sweetening intensity without sacrificing mouthfeel or consumer satisfaction.
Risk Assessment: Packaging and Compliance Friction
Packaging regulations and statutory deposit-return schemes present significant commercial hurdles for multi-country beverage rollouts. In July 2026, the German Environment Agency reported that returnable and reusable containers accounted for 34.5% of deposit-bearing beverage consumption in Germany during 2024[4]. Compliance complexities in beverage packaging elevate production overheads for regional bottlers, requiring dedicated reverse logistics agreements before entering regulated European territories.
Commercial Opportunity Analysis: Botanical Recipe Expansion
Infusing green and black tea bases with botanicals such as mint, chamomile, and citrus peels positions RTD tea as a sophisticated daytime refreshment and alcohol alternative. This botanical approach bridges ready-to-drink tea with the broader non-alcoholic beverages sector, capturing health-conscious adult consumers. Formulations that balance authentic tea polyphenols with functional herbal extracts command premium price points across specialty grocery aisles.
Ready To Drink Tea Market by Country (2026 to 2036)
As per FMI, South Korea represents the fastest-growing ready to drink tea market among the evaluated countries at a 7.1% CAGR, while Italy records measured expansion at 4.6% CAGR. Commercial success across all covered economies depends on dense convenience store access, disciplined sugar reduction, and compliant packaging architectures.
Table 7: Country CAGR and Primary Growth Levers for the Ready To Drink Tea Market (CAGR percentage and operational drivers), 2026 to 2036
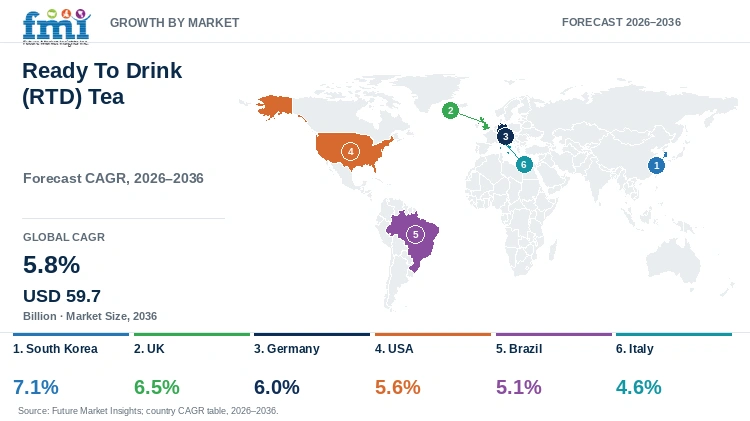
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 7.1% | Dense convenience retail and unsweetened tea habits |
| UK | 6.5% | Sugar reformulation and chilled single-serve ranges |
| Germany | 6.0% | Returnable packaging systems and recyclable packs |
| USA | 5.6% | Established iced-tea demand and national distribution |
| Brazil | 5.1% | Modern grocery growth and warm-weather occasions |
| Italy | 4.6% | Tourism, summer demand, and food-service availability |
Source: Industry analysis
South Korea Ready To Drink Tea Market Outlook (2026 to 2036)
South Korea is projected to grow at 7.1% CAGR through 2036, driven by a deeply ingrained cultural preference for unsweetened barley and green teas sold through high-density urban convenience networks. In 2026, Statistics Korea census and household consumption data highlighted sustained single-person household expansion, accelerating single-serve grab-and-go purchases[5]. Stiff shelf competition from ready-to-drink coffee and energy drinks restricts cooler frontage, requiring suppliers to market ultra-slim cans with distinct functional health attributes.
- Key takeaway: In South Korea, convenience access and familiar unsweetened profiles support repeat single-serve purchasing.
UK Ready To Drink Tea Market Outlook (2026 to 2036)
The UK ready to drink tea outlook is anticipated to advance at 6.5% CAGR over the assessment period, propelled by aggressive sugar reformulation and meal-deal convenience placements. In November 2025, the UK government published consultation responses lowering the Soft Drinks Industry Levy threshold from 5.0g to 4.5g of sugar per 100ml[6]. This fiscal tightening compels tea brand owners to eliminate added sugars. Competing against established hot-brewed tea rituals presents a habitual hurdle, prompting manufacturers to emphasize chilled summer refreshment.
- Key takeaway: In the UK, levy thresholds make controlled sweetness a product qualification issue rather than a marketing option.
Germany Ready To Drink Tea Market Outlook (2026 to 2036)
Ready to drink tea demand in Germany is forecast to rise at 6.0% CAGR over the forecast period, linked to nationwide deposit-return compatibility and organic certifications. In November 2025, the Federal Statistical Office of Germany (Destatis) reported steady domestic turnover in sustainable beverage packaging alongside expanding consumer demand for organic soft drinks[7]. Statutory Pfand deposit compliance creates logistical overheads for foreign brand entrants, requiring standardized barcode registration. Unsweetened herbal teas successfully compete against flavored sparkling waters.
- Key takeaway: In Germany, deposit compatibility and recognizable pack formats determine whether a tea launch can scale.
USA Ready To Drink Tea Market Outlook (2026 to 2036)
Adoption of ready to drink tea in the USA is estimated to expand at 5.6% CAGR through 2036, reinforced by deep historical iced-tea consumption and extensive fountain and grocery distribution. In September 2026, the National Center for Health Statistics reported that coffee and tea constitute 20.1% of adult nonalcoholic beverage intake by weight[8]. Category expansion benefits from mainstream availability across packaged iced tea aisles. Stiff price pressure from value-priced carbonated sodas limits margin expansion, requiring premium cold-brew differentiation.
- Key takeaway: In the USA, existing tea consumption lowers education costs while distribution breadth controls repeat availability.
Brazil Ready To Drink Tea Market Outlook (2026 to 2036)
The Brazil ready to drink tea sector is projected to record 5.1% CAGR during the assessment period, supported by tropical climate conditions and expanding supermarket penetration. In February 2026, the Brazilian Institute of Geography and Statistics (IBGE) reported a 1.6% rise in annual retail sales, with food and beverage volume leading growth[9]. Traditional mate tea consumption provides a strong consumer foundation. High inflation and consumer price sensitivity constrain premium glass-bottled lines, driving producers toward multi-serve PET bottles for home consumption.
- Key takeaway: In Brazil, modern retail supports visibility, but price architecture decides whether trial turns into household volume.
Italy Ready To Drink Tea Market Outlook (2026 to 2036)
In Italy, ready to drink tea demand is predicted to advance at 4.6% CAGR through 2036, aided by warm-weather tourism and café availability. In March 2025, the Italian National Institute of Statistics (Istat) recorded an 11.1% year-over-year rise in tourist nights spent across domestic hospitality venues[10]. Chilled peach and lemon teas achieve high seasonal sales across beachfront bars. Sharply reduced consumption during cooler winter months dampens year-round factory utilization, prompting brands to market functional wellness teas during the off-season.
- Key takeaway: In Italy, tourism supports seasonal throughput while grocery formats are needed to smooth demand beyond summer.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the ready to drink tea market?
The Coca-Cola Company, PepsiCo, Inc., ITO EN, Ltd., Suntory Holdings Limited, Keurig Dr Pepper Inc., AriZona Beverages USA, Asahi Group Holdings, Ltd., and Pokka Sapporo Food & Beverage Ltd. are significant market players in this market.
FMI data suggests that competition divides between multinational beverage corporations, dedicated Asian tea specialists, and prominent North American brand owners. Multinational conglomerates dominate grocery distribution through integrated bottling franchises, while artisanal producers expand through specialty tea sourcing and cold-fill extraction. Competitive advantage centers on shelf presence, sugar profile optimization, and packaging agility.
- Global Beverage Platforms: The Coca-Cola Company and PepsiCo utilize worldwide bottling and direct-store-delivery logistics.
- Tea-Centered Platforms: ITO EN, Suntory, Asahi, and Pokka Sapporo lead in unsweetened authentic green and black tea brewing.
- North American Branded Platforms: Keurig Dr Pepper and AriZona Beverages deploy recognized trademarks and accessible price points.
Competitive Benchmarking: Ready To Drink Tea Market
Table 8: Competitive Benchmarking for the Ready To Drink Tea Market (qualitative capability ratings), 2026
| Company | Tea Portfolio | Packaging Breadth | Channel Access | Geographic Reach |
|---|---|---|---|---|
| The Coca-Cola Company | High | High | High | High |
| PepsiCo, Inc. | High | High | High | High |
| ITO EN, Ltd. | High | High | Medium | High |
| Suntory Holdings Limited | High | High | High | High |
| Keurig Dr Pepper Inc. | Medium | High | High | Medium |
| AriZona Beverages USA | High | Medium | High | Medium |
| Asahi Group Holdings, Ltd. | Medium | High | High | High |
| Pokka Sapporo Food & Beverage Ltd. | High | Medium | Medium | Medium |
Scoring basis: High indicates broad public evidence across the stated capability. Medium indicates narrower or regional presence. Low is reserved for a documented commercial limitation.
Key Developments in the Ready To Drink Tea Market
- In September 2026, Crown Holdings commenced construction of a modern beverage can plant designed for approximately 2.2 billion cans annually.
- In July 2026, PepsiCo and Nintendo launched a nationwide BRISK iced tea promotion featuring four distinct fruit formulations.
- In 2026, The Coca-Cola Company sustained broad retail placement for FUZE, Gold Peak Tea, and Peace Tea across international markets.
Key Players in the Ready To Drink Tea Market
Global Beverage Platforms
- The Coca-Cola Company
- PepsiCo, Inc.
Tea-Centered Asian Platforms
- ITO EN, Ltd.
- Suntory Holdings Limited
- Asahi Group Holdings, Ltd.
- Pokka Sapporo Food & Beverage Ltd.
North American Branded Beverage Platforms
- Keurig Dr Pepper Inc.
- AriZona Beverages USA
Ready To Drink Tea Market - Report Scope
Table 9: Report Scope for the Ready To Drink Tea Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety / Flavor; Packaging Format; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes packaged tea beverages sold ready for immediate consumption. Excludes dry tea, tea bags, and tea brewed at point of sale. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, UK, Germany, USA, Brazil, Italy, and additional countries in the full report |
| Key Companies Covered | The Coca-Cola Company, PepsiCo, Inc., ITO EN, Ltd., Suntory Holdings Limited, Keurig Dr Pepper Inc., AriZona Beverages USA, Asahi Group Holdings, Ltd., Pokka Sapporo Food & Beverage Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
In the FMI report, scope boundaries strictly exclude loose leaf tea, hot dispensary vending tea, and custom café blends brewed fresh at point of sale.
Ready To Drink Tea Market - Research Methodology
Table 10: Research Methodology for the Ready To Drink Tea Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, retailers, foodservice operators, industry experts, and key opinion leaders across the value chain to validate demand dynamics and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other public sources. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 used top-down and bottom-up approaches to assess value demand, price points, distribution, and adoption trends. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, relevant market drivers, regulatory conditions, and historical trends to reduce double counting of adjacent categories. |
Ready To Drink Tea Market by Segments
Ready To Drink Tea Market segmented by Product Variety / Flavor:
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
Ready To Drink Tea Market segmented by Packaging Format:
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
Ready To Drink Tea Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Ready To Drink Tea Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] PepsiCo. (2026, July 21). BRISK iced tea and Nintendo team up to bring Splatoon Raiders fans real-world play and bold flavor. Press Releases.
- [2] The Coca-Cola Company. (2026). Coca-Cola Company coffee and tea brands portfolio review. Corporate Brand Publications.
- [3] Crown Holdings, Inc. (2026, September 11). Crown breaks ground on the company’s first beverage can manufacturing facility in India. Investor News.
- [4] German Environment Agency. (2026, July). Nationwide survey of beverage consumption in reusable beverage packaging, reference year 2024.
- [5] Statistics Korea. (2026). Population and Housing Census data service, 2025 coverage. Korean Statistical Information Service.
- [6] HM Treasury, HM Revenue & Customs, & Department of Health and Social Care. (2025, November 25). Strengthening the Soft Drinks Industry Levy: Summary of responses.
- [7] Federal Statistical Office of Germany (Destatis). (2025, November 18). Retail turnover in beverages and food packaging sustainability report. Statistisches Bundesamt.
- [8] National Center for Health Statistics. (2026, September). Nonalcoholic beverage consumption among youth and adults: United States, August 2021-August 2023.
- [9] Brazilian Institute of Geography and Statistics. (2026, February 13). Retail sales close 2025 with rise of 1.6%. IBGE News Agency.
- [10] Italian National Institute of Statistics. (2025, March 14). Tourist flows: Fourth quarter 2024. Istat Statistical Releases.
- [11] ITO EN, Ltd. (2026, May 15). Introduction of novel cold-brewed botanical jasmine and fruit green tea formulations. Product Releases.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ready to drink tea market in 2026 and what is forecast for 2036?
- Which demand conditions support ready to drink tea purchases?
- Why does flavored / botanical infusion lead product variety / flavor?
- Why do slim aluminum cans lead packaging format revenue?
- How do country growth rates differ across evaluated economies?
- Which companies supply ready to drink tea products today?
Frequently Asked Questions
How big is the ready to drink tea market in 2026, and what is forecast for 2036?
Future Market Insights estimates USD 34.0 billion in 2026 and projects USD 59.7 billion by 2036, advancing at a steady pace across retail channels.
What is the CAGR for the ready to drink tea market from 2026 to 2036?
As per FMI, the market is projected to expand at a 5.8% CAGR over the assessment period, supported by reduced-sugar formulations and portable formats.
Which product variety segment leads the market?
Flavored / botanical infusion is projected to hold 45.9% in 2026 through wider taste choice and functional botanical blending.
Which packaging segment leads the market?
Slim aluminum cans are estimated to hold 35.8% in 2026 through rapid chilling in convenience coolers and compact shelf merchandising.
Which country has a notable growth outlook?
South Korea is projected to register a 7.1% CAGR from 2026 to 2036, propelled by high-density convenience store networks and unsweetened tea consumption.
Who are the key players in the market?
Key participants include The Coca-Cola Company, PepsiCo, ITO EN, Suntory Holdings, Keurig Dr Pepper, AriZona Beverages, Asahi Group, and Pokka Sapporo.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety / Flavor, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Variety / Flavor, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Variety / Flavor, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety / Flavor, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety / Flavor, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety / Flavor
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Coca-Cola Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- PepsiCo, Inc.
- ITO EN, Ltd.
- Suntory Holdings Limited
- Keurig Dr Pepper Inc.
- AriZona Beverages USA
- Asahi Group Holdings, Ltd.
- Pokka Sapporo Food & Beverage Ltd.
- The Coca-Cola Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


