
- Market Size (2026)
- USD 510.0 Mn
- Forecast (2036)
- USD 896.0 Mn
- CAGR (2026 to 2036)
- 5.8%
How big is Ready-to-Use Therapeutic Food Market in 2026?
The global ready-to-use therapeutic food market is estimated at USD 482 million in 2025 and is expected to reach USD 510 million in 2026. Sales of ready-to-use therapeutic food are projected to reach USD 896 million by 2036, growing at a CAGR of 5.8% between 2026 and 2036. FMI analysis puts paste therapeutic food in the lead, with an expected 53.4% of 2026 type sales.
Aid agencies such as UNICEF buy most of these sachets to treat severely wasted children at home. Demand for therapeutic paste is rising as conflict and drought leave more children severely wasted. For instance, some 37.7 million children faced acute malnutrition in 2024 across 26 countries and territories with nutrition crises [1]. Sales of treatment supplies are also gaining from new crises, as over 4 million children in Afghanistan are expected to need treatment for acute malnutrition in 2027 [2]. FMI analysis finds that funding, more than need, will decide how much supply reaches children. Adoption of lower-cost, locally made products is becoming urgent as a result. Haiti shows the scale of the problem, as UNICEF reported on 28 August 2026 a funding gap of more than 64% for nutrition interventions under the 2026 Humanitarian Action for Children appeal [3]. In turn, agencies are likely to favour suppliers that can deliver more treatment per dollar.
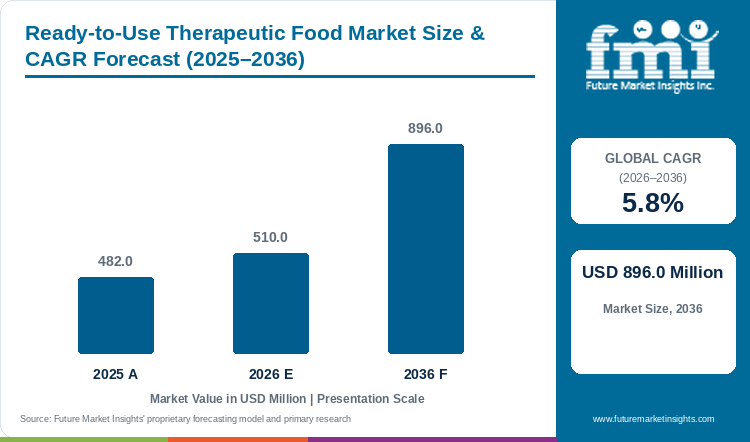
Table 1: Ready-to-Use Therapeutic Food Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 482 million |
| Estimated market size in 2026 | USD 510 million |
| Projected market size by 2036 | USD 896 million |
| CAGR (2026 to 2036) | 5.8% |
| Added sales, 2026 to 2036 | USD 386 million |
Key Market Trends & Insights
- By type: Paste therapeutic food will hold 53.4% of 2026 sales, as peanut-based sachets need no water, preparation or cold storage.
- By end user: UNICEF accounts for 49.7% of 2026 sales, as the agency procures and distributes the bulk of treatment supplies to national programmes.
- By region: The Middle East and Africa form the largest region with an estimated 47.2% share in 2026, as severe wasting is concentrated in conflict and drought zones.
Regional Highlights
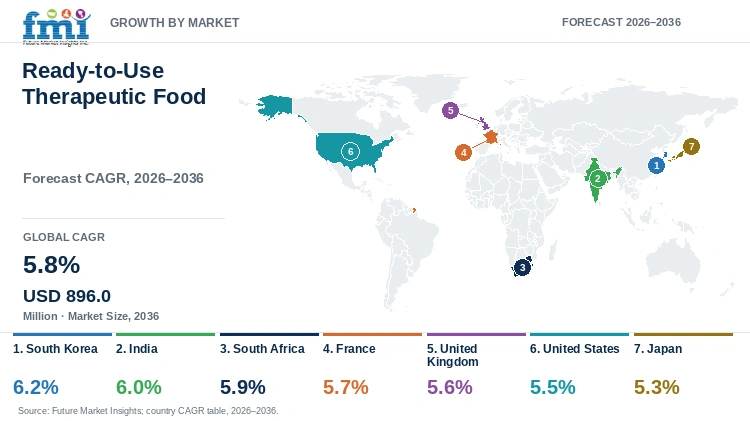
- Fastest-growing country: South Korea is set to expand at a 6.2% CAGR from 2026 to 2036, the top rate among profiled countries, as Korean development aid channels more funds into child nutrition.
- Growth across other countries: India (6%) and South Africa (5.9%) also stay above the 5.8% world figure, as state programmes and regional factories buy more. Donor and producer countries come lower, with France on 5.7%, the United Kingdom on 5.6% and the United States on 5.5%. Japan comes last at a 5.3% CAGR, since almost no therapeutic sachets are made there.
Prices of key ingredients set the cost of every carton, since the standard recipe mixes peanuts, milk powder, vegetable oil and sugar. Skim milk powder quotations were 33.1% above year-earlier levels in September 2026, and the vegetable oil price index was 18.3% higher [4]. Hence, producers face rising ingredient costs at a time of tight donor budgets. Prices of sugar add pressure as well, as the FAO sugar price index reached 114.0 points in September 2026, 14.7% higher than a year earlier [4]. Producers that can replace milk protein or buy oils locally will hold costs down. Lower costs mean more children treated for each donor dollar.
How much agencies buy depends on aid funding and the size of each crisis. In Somalia, about 1.92 million under-five children are projected to need treatment for acute malnutrition between July 2026 and June 2027, including 433,000 with severe acute malnutrition [5]. Consequently, orders for the Horn of Africa stay large even as treatment services face funding shortages. Yemen adds a second large caseload in the Middle East. More than 2.2 million children under five were projected to be acutely malnourished in Yemen in 2026, including over half a million with severe acute malnutrition [6]. Caseloads of this size keep UNICEF the main buyer. Suppliers near these regions save on freight and deliver faster.
New surveys and appeals are changing the flow of supplies. Haiti's 2026 national nutrition survey found global acute malnutrition among children aged 6 to 59 months rose from 5.1% in 2023 to 7.4% in 2026 [3]. As a result, Caribbean demand for treatment supplies is rising after years of smaller orders. Projections point the same way, as nearly 94,000 children in Haiti are expected to suffer severe acute malnutrition between June 2026 and May 2027 [7]. Agencies will therefore need to store stock in advance of the lean season. Regional warehouses near crisis zones will matter more for delivering on time.
Table 2: Supporting Industry Indicators for the Ready-to-Use Therapeutic Food Market, 2022 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Acutely malnourished children | 37.7 million children with acute malnutrition in 26 nutrition-crisis countries and territories (2024) | Core treatment caseload | [1] |
| Acute food insecurity | 295.3 million people facing high acute food insecurity (2024) | Food crises drive wasting | [1] |
| Wasted children | 45 million children under five wasted (2022) | Global pool of potential patients | [8] |
| Afghanistan caseload | Over 4 million children to need treatment in 2027; 1.09 million with severe acute malnutrition, up 16% on 2026 | Largest single-country rise in need | [2] |
| Somalia caseload | 1.92 million under-five children to need treatment between July 2026 and June 2027; 433,000 severe | Horn of Africa procurement stays high | [5] |
| Yemen caseload | More than 2.2 million under-five children projected acutely malnourished in 2026; over half a million severe | Middle East demand for treatment | [6] |
| Haiti prevalence | Global acute malnutrition rose from 5.1% in 2023 to 7.4% in 2026 | New demand in the Caribbean | [3] |
| Haiti funding gap | Funding gap above 64% for nutrition interventions under the 2026 appeal | Funding shortfalls threaten supply | [3] |
| Haiti severe caseload | 93,873 children with severe acute malnutrition expected between June 2026 and May 2027 | Pre-positioning needs ahead of lean season | [7] |
| Milk powder prices | Skim milk powder quotations 33.1% above year-earlier levels (September 2026) | Key ingredient cost rises | [4] |
| Vegetable oil prices | Vegetable oil price index 198.6 points, up 18.3% year on year (September 2026) | Fat ingredient cost rises | [4] |
Demand Intensity Analysis
Consumption of therapeutic food depends on the number of acutely malnourished children, which gives the clearest outside measure for the estimate. The Global Report on Food Crises counted 37.7 million acutely malnourished children in 26 nutrition-crisis countries and territories in 2024 [1]. Dividing the USD 482 million estimated for 2025 by that caseload gives roughly USD 12.8 per acutely malnourished child in crisis settings. The caseload includes moderate cases, which usually receive supplementary food, so the comparison is approximate. Still, the low value per child shows that supply covers only part of the need.
The global count of wasted children gives a broader check on the estimate. WHO estimated that 45 million children under five were wasted in 2022 [8]. Against that figure, the 2025 market equals about USD 10.7 per wasted child. The WHO count covers every country, including many with little treatment on offer, so the figure is only a rough floor. Gaps in treatment of this size leave plenty of room for purchases to grow.
Severe cases in crisis countries give a comparison from the buyer's side. Afghanistan, Somalia, Yemen and Haiti together expect more than 2.1 million children with severe acute malnutrition, based on UNICEF projections for 2026 and 2027 [2] [5] [6] [7]. At a 49.7% share of the USD 510 million estimated for 2026, UNICEF purchases come to about USD 253.5 million. That works out to roughly USD 120 per severe case in these four countries. UNICEF also supplies many other countries, so the ratio overstates the true figure. The comparison still shows that four crises alone could absorb most UNICEF purchases.
The number of children in need is growing much faster than the forecast rate. Severe acute malnutrition in Afghanistan is projected to rise 16% from 2026 to 2027 [2]. Set against the 5.8% CAGR for 2026 to 2036, the gap shows that need can grow far faster than funded supply in a single crisis year. Input costs widen the gap, as skim milk powder quotations rose 33.1% in a year [4]. The forecast therefore assumes steady donor funding and slow cost savings from local production.
Table 3: Demand Intensity Metrics for the Ready-to-Use Therapeutic Food Market, 2022 to 2027 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Acutely malnourished children in nutrition crises, 2024 | 37.7 million | Global Report on Food Crises 2025 |
| Market value per acutely malnourished child | USD 12.8 | Calculated from the Global Report on Food Crises and the 2025 market value |
| Wasted children under five, 2022 | 45 million | World Health Organization |
| Market value per wasted child | USD 10.7 | Calculated from WHO figures and the 2025 market value |
| Severe acute malnutrition caseload in Afghanistan, Somalia, Yemen and Haiti | About 2.12 million | Calculated from UNICEF projections for the four countries |
| UNICEF segment value per severe case in the four countries | USD 120 | Calculated from UNICEF projections and the 2026 UNICEF share |
| Projected rise in severe cases in Afghanistan, 2026 to 2027 | 16% | UNICEF, October 2026 |
| Skim milk powder price change, year on year | 33.1% | Food and Agriculture Organization, September 2026 |
Analyst Perspective
“Crises set the need for therapeutic food, but donor budgets set the supply. Cases in Afghanistan, Somalia, Yemen and Haiti are rising during a period of tight funding and higher ingredient costs. Producers that make sachets close to the children who need them, at lower cost per treatment, will gain the largest share of agency orders.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the ready-to-use therapeutic food market segmented?
The market is segmented into type, end user, and region. Paste therapeutic food is expected to lead type with 53.4% share in 2026, and UNICEF leads end user with an estimated 49.7%.
By type: paste therapeutic food, biscuits or bar form, powder or blend form, drinkable therapeutic food, and other ready-to-use therapeutic foods.
By end user: UNICEF, World Food Programme, non-governmental organizations, government organizations, and other end users.
By region: outpatient clinics, stabilisation centres and sachet factories spread over North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does paste therapeutic food lead by type?
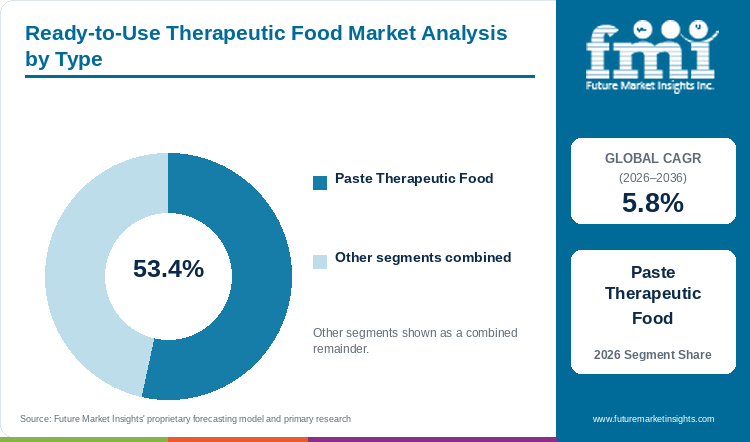
Paste therapeutic food is expected to lead type sales with 53.4% share in 2026, ahead of biscuits or bars at an estimated 17.2% and powder or blend forms near 13.9%.
Table 4: Type Share for the Ready-to-Use Therapeutic Food Market (percentage share), 2026
| Type | Estimated Share (2026) |
|---|---|
| Paste Therapeutic Food | 53.4% |
| Biscuits or Bar Form | 17.2% |
| Powder or Blend Form | 13.9% |
| Drinkable Therapeutic Food | 9.6% |
| Other Ready-to-use Therapeutic Foods | 5.9% |
| Total | 100.0% |
Table 5: Type Leadership and Market Growth for the Ready-to-Use Therapeutic Food Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.8% |
| Leading Segment | Paste Therapeutic Food |
Sales of paste products lead, as peanut-based sachets keep well, need no water and can be eaten straight from the pack at home. FMI puts paste at 53.4% of 2026 sales, with biscuits or bars at 17.2%, powder or blend forms at 13.9%, drinkable forms at 9.6% and others at 5.9%. Use of biscuits and bars is common for older children and in emergencies with limited clean water. Ingredient costs shape the mix, and the FAO vegetable oil price index reached 198.6 points in September 2026 [4]. Costlier oil squeezes margins on paste products, which use a lot of oil. Peanut supply also matters, and the peanut butter market is projected to grow from USD 5.8 billion in 2026 to USD 8.5 billion by 2036. Paste products are likely to keep the lead through 2036, given low cost and easy use.
- Peanut-based pastes, chickpea or soy-based pastes and dairy-reduced recipes make up the paste segment.
- Milk powder is the main protein source in standard recipes, and skim milk powder quotations were 33.1% higher year on year in September 2026 [4]. Costlier milk powder pushes producers to test recipes with other proteins.
Why does UNICEF lead by end user?
UNICEF is expected to lead end user sales with 49.7% share in 2026, ahead of the World Food Programme at an estimated 18.6% and non-governmental organizations near 15.3%.
Table 6: End User Share for the Ready-to-Use Therapeutic Food Market (percentage share), 2026
| End User | Estimated Share (2026) |
|---|---|
| UNICEF | 49.7% |
| World Food Programme | 18.6% |
| Non-governmental Organizations | 15.3% |
| Government Organizations | 11.2% |
| Other End Users | 5.2% |
| Total | 100.0% |
UNICEF holds 49.7% of 2026 sales, as the agency buys treatment supplies for national programmes in most of the worst-hit countries. The World Food Programme, near 18.6%, focuses on supplementary feeding, and non-governmental organizations hold about 15.3%. Government organizations make up 11.2% and other end users 5.2%. UNICEF projections point to the next demand peaks, and in Afghanistan an estimated 1.09 million children are projected to suffer severe acute malnutrition in 2027 [2]. Rising severe cases keep UNICEF at the centre of purchasing. Consumption of fortified foods helps prevent malnutrition, and the food fortifying agents market is projected to reach USD 222.52 billion by 2036. Governments are expected to gain share as national budgets take on more treatment costs.
- Supply Division tenders, country office orders and emergency airlifts make up UNICEF purchasing.
- Funding shortfalls weigh on treatment services, and UNICEF said in September 2026 that services in Somalia face increasing pressure from funding shortages [5]. Tight budgets push agencies to seek the lowest cost per treatment.
Why do the Middle East and Africa lead by region?
Conflict and drought areas in the Middle East and Africa account for an estimated 47.2% of 2026 purchases, against 23.6% for South Asia and Pacific and 9.8% for Western Europe.
Table 7: Region Share for the Ready-to-Use Therapeutic Food Market (percentage share), 2026
| Region | Estimated Share (2026) |
|---|---|
| Middle East and Africa | 47.2% |
| South Asia and Pacific | 23.6% |
| Western Europe | 9.8% |
| North America | 8.4% |
| Latin America | 5.1% |
| East Asia | 3.6% |
| Eastern Europe | 2.3% |
| Total | 100.0% |
The Middle East and Africa hold 47.2% of 2026 sales, as conflict, drought and displacement push severe wasting highest in the Sahel, the Horn of Africa and Yemen. South Asia and Pacific, near 23.6%, covers Afghanistan, Pakistan and India. Western Europe at 9.8% and North America at 8.4% are home to large producers and donors. Latin America holds 5.1%, East Asia 3.6% and Eastern Europe 2.3%. Food crises underpin the regional pattern, and the Global Report on Food Crises counted 295.3 million people facing high acute food insecurity in 2024 [1]. Most of these people live in Africa and the Middle East, which keeps purchases focused there. FMI expects Latin America to gain share as Haiti's needs grow.
- Sudan, Somalia, Ethiopia, Nigeria, Yemen and the Sahel countries form the largest demand centres in the Middle East and Africa.
- Yemen remains a major caseload, with more than 2.2 million children under five projected to be acutely malnourished in 2026 [6]. Lasting need in Yemen keeps purchases for the Middle East high.
What are the drivers, restraints, and opportunities in the ready-to-use therapeutic food market?
Key drivers of the ready-to-use therapeutic food market include food crises, conflict and drought, which push agencies to treat more wasted children at home. Funding gaps and rising ingredient costs limit how much agencies can buy. Local production and new recipes help treat more children per dollar.
- Driver: Conflicts and climate shocks raise the number of severely wasted children, so agencies need ready-made treatment that families can give at home.
- Restraint: Donor funding is uncertain and ingredient prices swing widely, which limits how many cartons agencies can buy.
- Opportunity: Local factories near the children in need and recipes with cheaper proteins can cut the cost per treatment and reach more children.
Food Crises Keep Treatment Needs High
Every major food crisis raises demand for ready-to-use therapeutic food. In Afghanistan, the number of provinces at critical malnutrition levels rose from 7 in 2025 to 10 in 2026 and is projected to reach 14 in 2027 [2]. Wider crisis areas need more treatment sites and more stock. FMI views food crises as the main driver through 2036. Climate shocks such as drought and floods will add to conflict-driven need.
Funding Gaps and Input Costs Limit Purchases
Funding remains the biggest restraint, since agencies can buy only what donors pay for. In Haiti, UNICEF reported a funding gap of more than 64% for nutrition interventions under the 2026 appeal [3]. Gaps of this size force agencies to ration supplies, which delays treatment for some children. Cost per treatment is likely to decide how far budgets stretch. Prices of milk powder remain a key cost, and the milk powder market is projected to reach USD 55.6 billion by 2036 at a 3.9% CAGR.
Local Production and New Recipes Open Room to Grow
Sachets made near feeding centres at lower cost will drive more of the growth of the ready-to-use therapeutic food market. Nearly half of deaths among children under five are linked to undernutrition, according to WHO [8]. A burden of this size justifies building factories close to the children in need. Expertise in medical nutrition supports new recipes, and the clinical nutrition market is projected to grow at a 7.9% CAGR from 2026 to 2036. Producers that combine local ingredients with tested recipes will secure agency tenders.
Which country CAGRs are profiled in the ready-to-use therapeutic food market?
Table 8: Country CAGR Comparison for the Ready-to-Use Therapeutic Food Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| South Korea | 6.2% |
| India | 6% |
| South Africa | 5.9% |
| France | 5.7% |
| United Kingdom | 5.6% |
| United States | 5.5% |
| Japan | 5.3% |
How do country-level CAGRs compare in the ready-to-use therapeutic food market?
South Korea ranks first in the FMI country table with a 6.2% CAGR, 0.4 points clear of the 5.8% global figure, as Korean aid grows. India, on 6%, and South Africa, on 5.9%, gain from local treatment programmes and regional factories. Producer and donor nations hover near the mean, with French demand at 5.7%, British at 5.6% and American at 5.5%. Japan is lowest on 5.3%, as Japanese aid flows mainly through international agencies. The narrow 0.9-point spread shows that global agencies, more than national markets, set most purchasing.
- Korean nutrition aid flows mostly through UN agencies, so purchases rise with each new Korean pledge. Suppliers already on agency lists benefit most from that money.
- Large community programmes for wasted children in India buy from domestic factories, giving local producers steady orders and lower freight.
- South African plants can ship to neighbouring states quickly, which gives regional producers a cost edge in southern African tenders.
- French output is mostly exported, with licensed partner factories supplying African and Middle Eastern programmes.
- British aid budgets fund treatment in crisis states, though budget changes make producer orders less predictable.
- US producers supply agency tenders, so any shift in aid budgets changes factory schedules directly.
- Japanese demand rests on funding through international agencies alone, which keeps growth the slowest.
Full report country CAGRs cover: seven profiled rates between 5.3% in Japan and 6.2% in South Korea, plus regional tables for every other standard country.
Country-wise Analysis
South Korea Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
Sales of therapeutic food linked to Korean aid are rising as South Korea raises development aid for health and nutrition. Funding routed through UN agencies supports therapeutic food purchases for crisis countries. Korean-funded purchases are set to rise at a 6.2% CAGR, the quickest rate in the country table.
Key takeaway: Purchases of therapeutic food funded by South Korea will grow fastest, as Korean aid for child nutrition keeps rising through UN agencies.
India Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
In India, community-based treatment reaches large numbers of wasted children. Buyer preference for local producers is growing, since local factories supply state programmes at lower freight cost than imports. Indian purchases of therapeutic paste are set to expand at a 6% CAGR, ahead of the global figure.
Key takeaway: Indian state programmes will keep buying more therapeutic paste from local factories to treat wasted children through community-based care.
South Africa Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
South Africa has local cases of child wasting and a food processing base that can serve neighbouring countries. Regional crises in southern and eastern Africa create export demand. South African demand is forecast to expand at a 5.9% CAGR as regional relief orders grow.
Key takeaway: South African producers are well placed to sell therapeutic food to neighbouring countries, as regional crises raise relief orders across southern Africa.
France Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
France is home to Nutriset, and the company's peanut-based paste has spread through licensed production at partner factories. Export orders for African and Middle Eastern programmes drive French output. FMI places French demand at a 5.7% CAGR, a touch below the world rate.
Key takeaway: French output of therapeutic paste will depend on export orders from African and Middle Eastern programmes supplied through partner factories licensed by Nutriset.
United Kingdom Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
UK aid funding supports nutrition programmes in crisis countries. Changes in aid budgets make orders less predictable, and British-funded demand is forecast to rise at a 5.6% CAGR over the decade.
Key takeaway: Demand linked to the United Kingdom will move with British aid budgets, which fund treatment programmes in crisis countries and change from year to year.
United States Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
Several US producers supply agency tenders, and US funding supports nutrition surveys in crisis countries. Haiti's 2026 national nutrition survey received funding from the Governments of the United States and Canada [3]. Support for such surveys helps agencies plan the size of orders more accurately. US demand for therapeutic paste is forecast at a 5.5% CAGR, with aid budget decisions setting the pace.
Key takeaway: US producers will keep supplying agency tenders, but changes in US aid funding will decide how much those producers sell each year.
Japan Ready-to-Use Therapeutic Food Market Outlook (2026 to 2036)
Japan contributes to nutrition through aid but has little therapeutic food production. Demand comes from funding given through international agencies, and Japanese demand rises at a 5.3% CAGR, the lowest figure in the table.
Key takeaway: Japan funds therapeutic food mainly through international agencies and makes very little at home, so Japanese demand grows the slowest.
Who are the notable companies in the ready-to-use therapeutic food market?
Sachet and bar producers covered here are Nutriset, Insta Products, MANA Nutrition, Hilina Enriched Foods, Tabatchnik Fine Foods, Edesia Nutrition, Valid Nutrition, Samriddhi Agrotech, Meds & Food for Kids, NutriVita Foods and Project Peanut Butter.
Among ready-to-use therapeutic food suppliers, the leading companies include global producers, regional manufacturers and non-profit factories, and FMI sees cost per treatment as the deciding factor in tenders. Funding pressure is visible across crises, as UNICEF warned of an anticipated funding cliff that could reduce access to preventive nutrition services in Afghanistan [2]. Tight budgets favour producers with the lowest cost once freight is included, which rewards factories close to the children in need. Ingredient prices add pressure, as the FAO Food Price Index averaged 136.0 points in September 2026, 5.8% above a year earlier [4]. Higher food prices raise production costs, which hurts producers on fixed-price contracts. Competition through 2036 will turn on price, local sourcing and delivery speed.
- Large-volume global producers: Nutriset, Edesia Nutrition, MANA Nutrition and Tabatchnik Fine Foods.
- Regional manufacturers near demand centres: Insta Products, Hilina Enriched Foods, Samriddhi Agrotech and NutriVita Foods.
- Non-profit and social enterprise producers: Valid Nutrition, Meds & Food for Kids and Project Peanut Butter.
Competitive Benchmarking: Ready-to-Use Therapeutic Food Market
Table 9: Competitive Benchmarking for the Ready-to-Use Therapeutic Food Market (qualitative ratings), 2026
| Company | Production Scale | Local Footprint | Agency Contracts | Recent Activity |
|---|---|---|---|---|
| Nutriset | High | High | High | Medium |
| Edesia Nutrition | High | Low | High | Medium |
| MANA Nutrition | Medium | Low | High | Low |
| Insta Products | Medium | High | Medium | Low |
| Hilina Enriched Foods | Medium | High | Medium | Low |
| Tabatchnik Fine Foods | Medium | Low | Medium | Low |
Ratings compare the companies on production scale, local footprint, agency contracts and recent activity.
Key Developments in the Ready-to-Use Therapeutic Food Market
- UNICEF and Action Against Hunger warned on 15 October 2026 that over 4 million children in Afghanistan will need treatment in 2027 [2]. Purchases for South Asia are set to rise sharply.
- FAO reported in October 2026 that skim milk powder quotations were 33.1% above year-earlier levels [4]. Producers therefore face higher protein costs on every carton.
- In Yemen, more than 2.2 million children under five were projected to be acutely malnourished in 2026, UNICEF said in September 2026 [6]. Demand from the Middle East is likely to stay high through 2027.
- UNICEF reported in September 2026 that 1.92 million children in Somalia will need treatment between July 2026 and June 2027 [5]. Orders for the Horn of Africa are set to remain large.
- Haiti's 2026 nutrition survey, released on 28 August 2026, showed acute malnutrition at 7.4% among young children [3]. Caribbean demand for treatment supplies is rising as a result.
- The Global Report on Food Crises 2025, released in May 2025, counted 37.7 million acutely malnourished children in nutrition crises [1]. Caseloads of this size keep agency procurement running at scale.
Key Players in the Ready-to-Use Therapeutic Food Market
Global Producers
- Nutriset
- Edesia Nutrition
- MANA Nutrition
- Tabatchnik Fine Foods
Regional Manufacturers
- Insta Products
- Hilina Enriched Foods
- Samriddhi Agrotech
- NutriVita Foods
Non-profit and Social Enterprise Producers
- Valid Nutrition
- Meds & Food for Kids
- Project Peanut Butter
Ready-to-Use Therapeutic Food Market - Report Scope
Table 10: Report Scope for the Ready-to-Use Therapeutic Food Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type; end user; region |
| Quantitative units | USD million |
| Market definition | Energy-dense, micronutrient-enriched foods used to treat severe acute malnutrition, supplied as pastes, biscuits, bars, powders and drinkable forms to agencies, governments and NGOs. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; South Korea; South Africa; France; United Kingdom; United States; Japan |
| Key companies profiled | Nutriset, Insta Products, MANA Nutrition, Hilina Enriched Foods, Tabatchnik Fine Foods, Edesia Nutrition, Valid Nutrition, Samriddhi Agrotech, Meds & Food for Kids, NutriVita Foods, Project Peanut Butter |
| Forecast period | 2026 to 2036 |
Ready-to-Use Therapeutic Food Market - Research Methodology
Table 11: Research Methodology for the Ready-to-Use Therapeutic Food Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Coverage spans malnutrition caseloads, humanitarian funding, ingredient prices and local production. |
| Market Sizing | Market value covers therapeutic food procurement across types, end users and regions. |
| Data Validation | Figures are cross-checked across agency, industry and government sources. |
Ready-to-Use Therapeutic Food Market by Segments
Ready-to-Use Therapeutic Food Market segmented by Type:
- Paste Therapeutic Food
- Biscuits or Bar Form
- Powder or Blend Form
- Drinkable Therapeutic Food
- Other Ready-to-use Therapeutic Foods
Ready-to-Use Therapeutic Food Market segmented by End User:
- UNICEF
- World Food Programme
- Non-governmental Organizations
- Government Organizations
- Other End Users
Ready-to-Use Therapeutic Food Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Global Network Against Food Crises. (2025, May 16). Global Report on Food Crises (GRFC) 2025. https://www.fightfoodcrises.net/report/global-report-food-crises-2025/
- [2] UNICEF. (2026, October 15). Afghanistan to face sharp rise in acute malnutrition in 2027, with over 4 million children projected to be in need of urgent treatment. https://www.unicef.org/press-releases/afghanistan-face-sharp-rise-acute-malnutrition-2027-over-4-million-children
- [3] UNICEF. (2026, August 28). Nearly one in thirteen children under five suffer from acute malnutrition in Haiti. https://www.unicef.org/press-releases/nearly-one-thirteen-children-under-five-suffer-acute-malnutrition-haiti
- [4] Food and Agriculture Organization of the United Nations. (2026, October 2). FAO Food Price Index. https://www.fao.org/worldfoodsituation/foodpricesindex/en
- [5] UNICEF. (2026, September 23). Hunger and malnutrition crises persist in Somalia as projected floods and funding shortfalls threaten vulnerable populations. https://www.unicef.org/press-releases/hunger-and-malnutrition-crises-persist-somalia-projected-floods-and-funding
- [6] UNICEF. (2026, September 25). Hunger and malnutrition stalking Yemen's children as violence escalates. https://www.unicef.org/press-releases/hunger-and-malnutrition-stalking-yemens-children-violence-escalates
- [7] UNICEF. (2026, September 17). Over a quarter of a million children facing acute malnutrition in Haiti amid ongoing violence. https://www.unicef.org/press-releases/over-quarter-million-children-facing-acute-malnutrition-haiti-amid-ongoing-violence
- [8] World Health Organization. (2024, March 1). Malnutrition. https://www.who.int/news-room/fact-sheets/detail/malnutrition
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the ready-to-use therapeutic food market during 2026?
- What market size is projected by 2036?
- Which type holds notable share?
- Which end user holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Type, 2026 to 2036
- Paste Therapeutic Food
- Biscuits or Bar Form
- Powder or Blend Form
- Drinkable Therapeutic Food
- Other Ready-to-use Therapeutic Foods
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End User, 2026 to 2036
- UNICEF
- World Food Programme
- Non-governmental Organizations
- Government Organizations
- Other End Users
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Type
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nutriset
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Edesia Nutrition
- MANA Nutrition
- Insta Products
- Hilina Enriched Foods
- Tabatchnik Fine Foods
- Samriddhi Agrotech
- NutriVita Foods
- Valid Nutrition
- Meds & Food for Kids
- Project Peanut Butter
- Nutriset
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 4: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 5: North America Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 6: North America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 7: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 8: Latin America Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 9: Latin America Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 10: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 11: Western Europe Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 12: Western Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 13: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: Eastern Europe Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 15: Eastern Europe Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 17: East Asia Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 18: East Asia Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 19: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 20: South Asia and Pacific Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by End User, 2021 to 2036
- Table 22: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 23: Middle East and Africa Market Value (USD Million) Forecast by Type, 2021 to 2036
- Table 24: Middle East and Africa Market Value (USD Million) Forecast by End User, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Type
- Figure 6: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End User
- Figure 9: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Region
- Figure 12: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 13: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 14: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 15: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 20: North America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 21: North America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 22: North America Market Attractiveness Analysis by Type
- Figure 23: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 24: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 25: North America Market Attractiveness Analysis by End User
- Figure 26: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 27: Latin America Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 28: Latin America Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 29: Latin America Market Attractiveness Analysis by Type
- Figure 30: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 31: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 32: Latin America Market Attractiveness Analysis by End User
- Figure 33: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 34: Western Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 35: Western Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 36: Western Europe Market Attractiveness Analysis by Type
- Figure 37: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 38: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 39: Western Europe Market Attractiveness Analysis by End User
- Figure 40: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 41: Eastern Europe Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 42: Eastern Europe Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 43: Eastern Europe Market Attractiveness Analysis by Type
- Figure 44: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 45: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 46: Eastern Europe Market Attractiveness Analysis by End User
- Figure 47: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 48: East Asia Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 49: East Asia Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 50: East Asia Market Attractiveness Analysis by Type
- Figure 51: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 52: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 53: East Asia Market Attractiveness Analysis by End User
- Figure 54: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 55: South Asia and Pacific Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 56: South Asia and Pacific Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 57: South Asia and Pacific Market Attractiveness Analysis by Type
- Figure 58: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 59: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 60: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 61: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 62: Middle East and Africa Market Value Share and BPS Analysis by Type, 2026 and 2036
- Figure 63: Middle East and Africa Market Y-o-Y Growth Comparison by Type, 2026-2036
- Figure 64: Middle East and Africa Market Attractiveness Analysis by Type
- Figure 65: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 66: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 67: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 68: Global Market - Tier Structure Analysis
- Figure 69: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the ready-to-use therapeutic food market expected in 2026?
FMI estimates that therapeutic food purchases will reach USD 510 million in 2026, up from USD 482 million a year earlier, as food crises keep severe wasting caseloads high.
What CAGR is projected for the ready-to-use therapeutic food market through 2036?
A 5.8% CAGR is projected through 2036, taking the market to USD 896 million, since conflict and climate shocks keep treatment needs rising.
Which type holds a notable market share in 2026?
Paste therapeutic food is expected to hold 53.4% share in 2026, given easy home use without water. Biscuits or bars follow at about 17.2%.
Which end user holds a notable market share in 2026?
UNICEF is expected to lead with 49.7%, as the agency supplies most national treatment programmes. The World Food Programme holds about 18.6%.
Which country has a notable expansion outlook through 2036?
South Korea leads the FMI outlook with a 6.2% CAGR, as Korean aid for child nutrition keeps growing. India comes next on 6%.
Who are the key companies in the ready-to-use therapeutic food market?
Nutriset, Edesia Nutrition, MANA Nutrition and Tabatchnik Fine Foods lead the global producers, and Insta Products and Hilina Enriched Foods lead regional manufacturing. Valid Nutrition and Meds & Food for Kids run social enterprise factories that focus on local supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
