

- Market Size (2026)
- USD 850.0 Bn
- Forecast (2036)
- USD 1450.0 Bn
- CAGR (2026 to 2036)
- 5.5%
How big is Ready-mix Concrete Market in 2026?
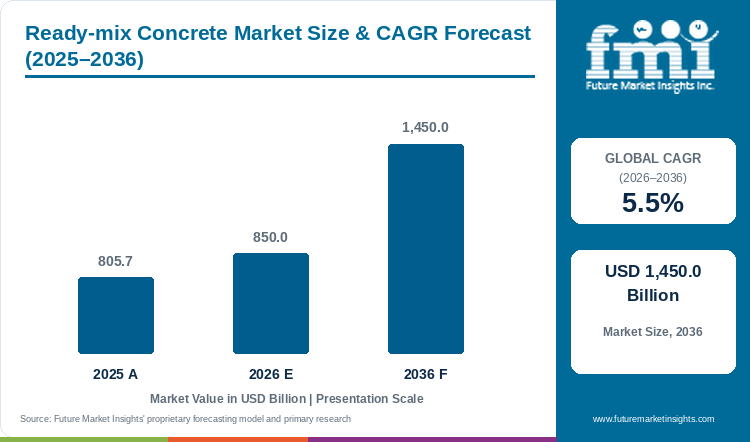
The ready-mix concrete market is estimated at USD 805.7 billion in 2025 and is expected to reach USD 850.0 billion in 2026. Sales of ready-mix concrete are projected to grow at a 5.5% CAGR and reach USD 1,450.0 billion by 2036.
Sales of ready-mix concrete, an estimated USD 805.7 billion for 2025, are forecast to reach USD 850.0 billion in 2026 and USD 1,450.0 billion by 2036, so the ready-mix concrete market will grow at a 5.5% CAGR over 2026 to 2036. Behind that growth, road, bridge and utility owners now buy a growing part of each fleet's loads on budgets fixed years ahead. For instance, Knife River reported second-quarter 2026 ready-mix volume of 1,193 thousand cubic yards, up 14.6%, and said about 85% of a USD 1,216.0 million contracting backlog related to publicly funded street and highway work.[1] As a result, public pours keep drum trucks moving through weak housing quarters, and plants close to funded corridors hold volume best.
Public infrastructure owners are the largest and steadiest buyers of ready-mix loads, as infrastructure makes up an expected 41% of 2026 application sales and pours repeat across multi-year contracts. Residential builders, an estimated 30.5%, order heavily in good years and cut back as soon as mortgage costs rise. Commercial developers near 19.8% order in bursts for warehouses and data halls, and industrial plants at about 8.7% buy for one-off foundations. Given this mix, FMI analysis indicates that producers will protect volume best by reserving truck capacity for public programmes and quoting residential loads on shorter price terms.
Key Market Trends & Insights
- Standard mixes for footings and slabs are expected to lead type sales with 65% share in 2026, and flowable grades for pumped floors follow near 13.5%.
- Transit mixed loads represent a likely 52% of production method sales in 2026, as drum trucks blend the batch on the road and suit long hauls. Producers want more deliveries from each truck, so dispatch systems are drawing fresh investment. On the dispatch front, Titan made a minority investment in dispatch software firm Command Alkon in October 2026.[2] Better routing of this kind raises loads per truck and favours groups running transit fleets across several plants.
- Infrastructure is estimated to hold 41% of application sales, with residential work at about 30.5%, as road, bridge and water owners keep pouring through the housing slowdown. Public backlogs point to further gains next year. In line with this, Knife River guided to a mid-teens percentage rise in 2026 ready-mix volume.[1] Guidance of that size from a producer tied to highway work suggests public pours will grow faster than private ones in 2026.
Regional Highlights
- FMI forecasts demand in India to expand at 7.5%, the fastest among the leading countries, as metro, housing and expressway pours move into smaller Indian cities.
- Canadian demand rises about 6.3% a year as federal housing sites add foundation work, with China close behind at 6.2%. ASEAN and Germany expand near the global pace, at 5.8% and 5.7%, and Italy is likely to be slowest at 3.8%, below the United States at 4.5%.
- Surplus kiln capacity in Indonesia is keeping cement cheap for regional concrete producers. Indonesia reported 122 Mt of installed cement capacity against domestic demand near 64 Mt in April 2026, a surplus that keeps binder plentiful for ASEAN batch plants.[3] Low binder prices let ASEAN producers quote plant-batched concrete close to the cost of site mixing, which speeds the switch.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ready-mix Concrete Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 805.7 billion |
| Estimated Market Size in 2026 | USD 850.0 billion |
| Projected Market Size by 2036 | USD 1,450.0 billion |
| CAGR, 2026 to 2036 | 5.5% |
| Added Revenue, 2026 to 2036 | USD 600.0 billion |
| Market Expansion Multiple | 1.7x |
Volume trends now differ sharply by region, with European housing weak and Asian construction strong. For example, Buzzi reported group ready-mix sales of 4,633 thousand cubic metres for January to June 2026, down 4.2%, with deliveries in Germany 6.9% lower.[4] A fall of that size shows how quickly European pours shrink once housing stalls, and producers there are protecting price on public jobs. Indian builders are moving the other way, with public housing and highway work adding loads. In India, by comparison, UltraTech said domestic cement volume grew 13.1% to 39.2 million tonnes in the June 2026 quarter.[5] Cement growth at that pace feeds straight into batch plant output, so Indian producers are adding plants in tier-2 cities. At the same time, lower-clinker binders now go into a large part of new mixes, and the blended cement market expands more slowly, at a 4.6% CAGR, than demand for the concrete those binders fill. FMI projects sales of ready-mix concrete in 2036 at about 1.7 times the 2026 level, with USD 600.0 billion of new business added over the decade. Even so, clinker, diesel and sand costs that rise inside fixed-price contracts remain the main risk to producer margins.
Public Pours, Plant Deals and Dispatch Software
Public work is holding North American volume together. As a case in point, Knife River's ready-mix sales for the June 2026 quarter grew 14.9% to USD 236.7 million at an average price of USD 198.45 per cubic yard, almost level with a year earlier.[1] Sales rose on volume at an unchanged price, which points to public paving jobs adding loads. Alongside this, Knife River said pull-through demand from Knife River contracting crews, together with acquisitions, gave double-digit volume growth, and Texcrete added volume in the Central segment, so producers in Texas and the upper Midwest are adding trucks before testing higher list prices.
Consolidation is also changing who controls each load. In south-eastern France, Vicat entered exclusive talks on 1 October 2026 to buy 48 Cemex ready-mix plants and 9 quarries along the Marseille to Nice corridor and the Rhône Valley.[6] A purchase on that scale would give one group control of a large part of supply along the busiest building corridor in southern France. Producers elsewhere are investing to get more loads from each truck. In addition, Titan's investment in Command Alkon links workflows and data across ready-mix and aggregates units in Florida, the Mid-Atlantic and South East Europe.[2] With such links in place, producers running large fleets on one system expect fewer empty runs and shorter waits at site.
Table 2: Volume, Price and Ownership Indicators for the Ready-mix Concrete Market (volumes, prices and plant counts), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Knife River ready-mix volume, Q2 2026 | 1,193 thousand cubic yards; up 14.6% | Public and private pours in the US | [1] |
| Knife River ready-mix price, Q2 2026 | USD 198.45 per cubic yard | Pricing per delivered load | [1] |
| Buzzi ready-mix sales, H1 2026 | 4,633 thousand cubic metres; down 4.2% | Volume trend in Europe and the US | [4] |
| Vicat plant purchase, October 2026 | 48 ready-mix plants and 9 quarries | Consolidation in south-eastern France | [6] |
| UltraTech domestic cement volume, June 2026 quarter | 39.2 million tonnes; up 13.1% | Binder supply for Indian batch plants | [5] |
| China cement output, January to September 2026 | 1,131.19 million tons; down 8.6% | Property-led slowdown in pours | [7] |
Analyst Perspective
“I expect producers that own both the binder and the trucks to gain ground in public programmes, as owners want one supplier answerable for strength, carbon and arrival time. Self-compacting and fiber mixes will raise truckload value in dense city work, and plants with good laboratories will set the price for those jobs.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the ready-mix concrete market segmented?
The market is segmented into type, production method, application, and region. Standard mixes are expected to lead type with 65% share in 2026, and transit mixed loads lead production method with 52%.
By type: standard, flowable, self-compacting, and fiber-reinforced.
By production method: transit mixed, central mixed, and shrink mixed.
By application: infrastructure, residential, commercial, and industrial.
By region: batch plants and truck fleets in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do standard mixes lead ready-mix concrete sales by type?
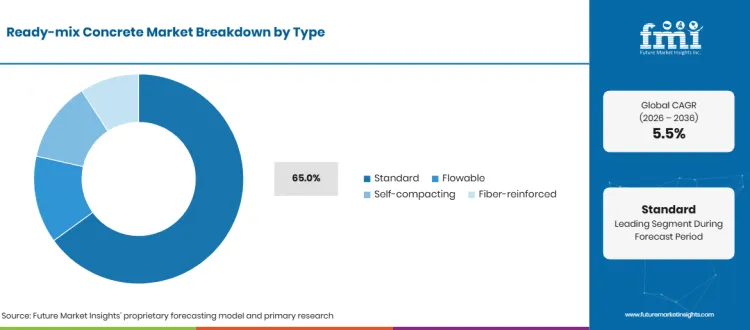
Standard mixes are expected to lead type sales with 65% share in 2026, ahead of flowable grades at about 13.5% and self-compacting concrete at an estimated 12.4%.
Table 3: Type Share for the Ready-mix Concrete Market (percentage share), 2026
| Type | Estimated Share (2026) |
|---|---|
| Standard | 65% |
| Flowable | 13.5% |
| Self-Compacting | 12.4% |
| Fiber-Reinforced | 9.1% |
| Total | 100.0% |
Table 4: Type Leadership and Market Growth for the Ready-mix Concrete Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.5% |
| Leading Segment | Standard |
Standard is expected to lead type sales with 65% in 2026, since footings, ground slabs, kerbs and most pavements need only a specified strength class and slump. On the other hand, flowable grades, about 13.5%, cost more per cubic metre and are ordered for congested reinforcement and pumped upper floors. Self-compacting concrete, near 12.4%, saves vibration labour in tunnels and dense walls, but the plant has to control fines and admixture dosing far more tightly. Fiber-reinforced mixes, an estimated 9.1%, replace steel mesh in warehouse floors and shotcrete linings, and growth of the concrete fibers market will set the speed at which mesh-free floors spread. Public paving, which uses mostly standard classes, is adding the most volume now. In the near term, Knife River expects ready-mix volume to rise by a mid-teens percentage in 2026.[1] Growth of that kind adds mainly standard-class loads, and over the forecast period site engineers will keep ordering standard classes for bulk pours and pay for special mixes only when labour or geometry calls for them.
- C25 to C40 structural classes, pavement grades and lean blinding mixes form the standard base.
- Standard grades are also the first to lose volume when European housing slows. Buzzi reported a 4.2% fall in group ready-mix volume for January to June 2026.[4] Producers selling mostly standard mixes to home builders feel such downturns sooner than suppliers of special grades.
Why do transit mixed loads lead ready-mix concrete sales by production method?
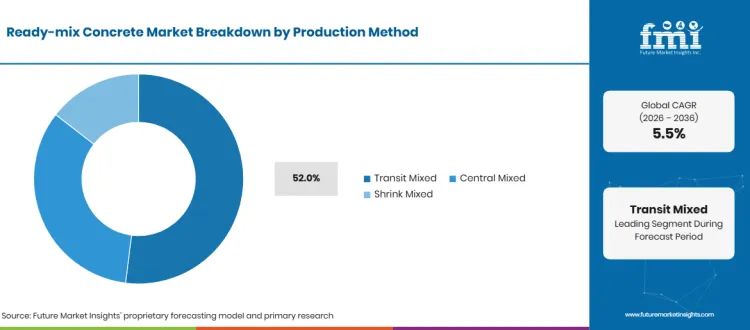
Transit mixed loads are likely to lead production method sales with 52% share in 2026, with central mixed at about 33.5% and shrink mixed at roughly 14.5%.
Table 5: Production Method Share for the Ready-mix Concrete Market (percentage share), 2026
| Production Method | Estimated Share (2026) |
|---|---|
| Transit Mixed | 52% |
| Central Mixed | 33.5% |
| Shrink Mixed | 14.5% |
| Total | 100.0% |
As dry batch plants are cheap to build close to customers, transit mixed concrete is projected to lead production method sales at 52% in 2026. In this method, drum trucks blend cement, aggregate and water on the road, which suits long hauls and small regional producers. Central mixed plants, about 33.5%, give more uniform batches for airfields and highway paving, though the stationary mixer costs more to install. Shrink mixing, near 14.5%, splits the work between plant and truck for producers who want shorter truck cycles without a full central mixer. Fleet operators are now investing in software to cut empty runs and waiting time at site. Meanwhile, Titan tied ready-mix units in Florida, the Mid-Atlantic and South East Europe to the Command Alkon platform through an October 2026 investment.[2] Systems like this raise the number of loads each transit mixer delivers a day, which strengthens the cost case for truck mixing. On balance, fleet owners will stay with transit mixing, and paving contractors will keep paying for central plants.
- Rear- and front-discharge drum trucks of 6 to 12 cubic metres carry most transit mixed volume.
- Regional groups are buying plant networks in dense coastal corridors. Vicat agreed exclusive talks in October 2026 on 48 Cemex ready-mix plants in the Rhône Valley and Provence.[6] Deals of this kind add transit mixed capacity close to city sites, as short hauls favour truck mixing.
Why does infrastructure lead ready-mix concrete sales by application?
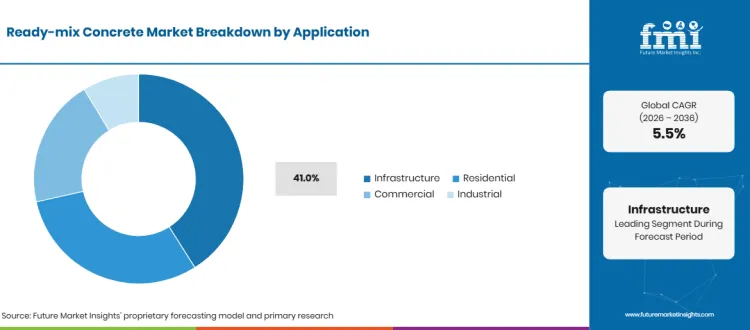
Infrastructure is projected to lead application sales with 41% share in 2026, ahead of residential at an estimated 30.5% and commercial at about 19.8%.
Table 6: Application Share for the Ready-mix Concrete Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Infrastructure | 41% |
| Residential | 30.5% |
| Commercial | 19.8% |
| Industrial | 8.7% |
| Total | 100.0% |
Highways, bridges, metro lines and water works pour in large, scheduled volumes, so infrastructure will lead application sales at 41% in 2026. Residential work, about 30.5%, slows as mortgage costs rise and recovers with housing starts. Commercial projects, near 19.8%, arrive as single large pours for offices, warehouses and data halls, and producers price each one separately. Industrial plants, an estimated 8.7%, buy for machine bases and process floors and seldom repeat an order. Public money is also reaching housing, which steadies part of the residential group. For example, Build Canada Homes listed Direct Build sites for up to 4,000 homes on federal land in January 2026, including 1,055 homes at Pointe-de-Longueil.[8] Federal land and funding give such residential pours the scheduled character of infrastructure work, which evens out orders for city batch plants. Wall and column formwork is ordered for the same public jobs, and the concrete form liners market will rise at a 5.8% CAGR in step with them. By 2036, public owners will keep the largest share, and residential volume will recover with home building.
- Roads, bridges, tunnels, water plants and power stations form the infrastructure group.
- Public backlogs give producers early sight of future pours. Knife River said about 85% of a USD 1,216.0 million contracting backlog at 30 June 2026 related to publicly funded projects.[1] A backlog weighted that heavily to public work protects volume through private building slowdowns.
What are the drivers, restraints, and opportunities in the ready-mix concrete market?
Public works and urban housing keep demand for ready-mix concrete growing. Volatile clinker, fuel and aggregate costs squeeze producers on fixed-price jobs, and low-clinker and special mixes open new contracts.
- Driver: Road, transit and water owners plan pours years ahead, which gives batch plants near those corridors a steady base load.
- Restraint: Producers quote many jobs at fixed prices, so a sudden rise in cement, diesel or sand costs cuts margin before contracts reset.
- Opportunity: Owners asking for lower-carbon and self-compacting mixes reward plants with admixture skills and quality labs, as these mixes sell above standard grades.
Public Programmes Keep Batch Plants Busy
Long public programmes smooth the swings of private building. First, Knife River's ready-mix volume grew 20.9% to 1,917 thousand cubic yards in the six months to June 2026, and the company tied double-digit second-quarter volume to pull-through demand from Knife River contracting crews and to acquisitions.[1] Contracting crews that draw concrete from in-house plants give integrated producers a captive outlet for each new public job. Indian demand rests on a similar public base. Likewise, UltraTech ran domestic grey cement capacity of 200.1 MTPA at 81% utilisation in the June 2026 quarter.[5] Utilisation at that level leaves room to supply more batch plants without new kilns. Consequently, producers with plants along public corridors will see orders hold even as housing slows.
Cost Swings Squeeze Fixed-Price Producers
Margins in ready-mix concrete shrink whenever input costs move faster than contract prices. Buzzi, for instance, expects margins in Germany to contract in 2026 on rising costs and said pricing pressure in Texas will persist.[4] Producers in both markets are absorbing cost increases that fixed-price contracts do not pass on to builders. Weak demand in China adds a different pressure on prices. Further east, China's cement output fell 8.6% to 1,131.19 million tons over January to September 2026.[7] In turn, spare kiln capacity there keeps binder prices low, which helps concrete buyers and squeezes cement producers. Smaller batch plants, therefore, without own cement will feel each swing first.
Low-Clinker and Special Mixes Open New Contracts
Specifications that cap embodied carbon or call for self-compaction will shape the next phase of growth in the ready-mix concrete market. As an example, Indonesia's cement industry cut the clinker factor from 81% to 68% between 2010 and 2025 and raised alternative fuel use from 3% to 13% over the same years.[3] Lower clinker ratios at the kiln let concrete producers offer lower-carbon mixes to public owners at little extra cost. Mixes with less clinker, however, need tighter testing at the batch plant. Since the CO2 reduced concrete market grows at a projected 10.7% CAGR, producers with laboratories and admixture skills will gain the first low-carbon tenders.
Which country CAGRs are profiled in the ready-mix concrete market?
Table 7: Country CAGR Comparison for the Ready-mix Concrete Market (CAGR percentage), 2026 to 2036
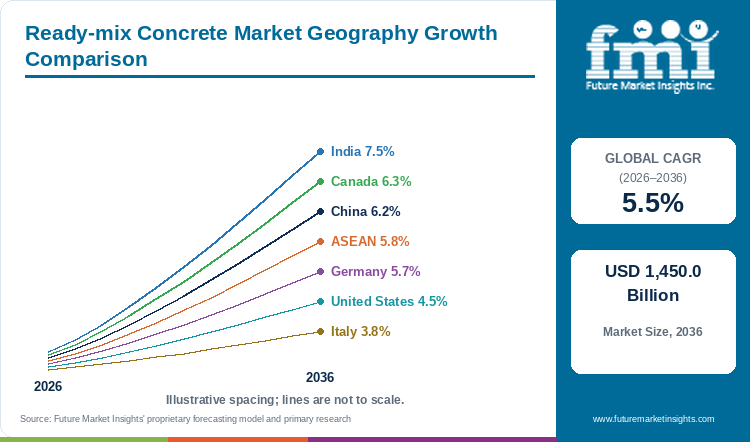
| Country | CAGR (2026 to 2036) |
|---|---|
| India | 7.5% |
| Canada | 6.3% |
| China | 6.2% |
| ASEAN | 5.8% |
| Germany | 5.7% |
| United States | 4.5% |
| Italy | 3.8% |
How do country-level CAGRs compare in the ready-mix concrete market?
Indian builders are moving from site mixing to plant-batched concrete, and cement supply is expanding to meet them. UltraTech crossed 200.1 MTPA of domestic grey cement capacity in April 2026, so Indian batch plants have deep binder supply close at hand.[5] With binder secured, FMI analysis points to India as the fastest-growing country, at 7.5%. Canada, at 6.3%, gains from federal housing sites, and China, at 6.2%, rebuilds volume from a shrunken property base. For ASEAN (5.8%) and Germany (5.7%), cheap Indonesian binder and German renewal work mean growth a few tenths above the 5.5% global figure. Demand in the United States is forecast to rise 4.5% a year on highway and data centre programmes, and Italy slows to 3.8% as recovery-plan works taper.
- Metro and expressway contracts in tier-2 Indian cities specify strength classes that site mixers cannot deliver, so plant-batched volume rises faster than cement use. Cement majors opening RMC plants beside grinding units are best positioned to take those pours.
- Direct Build sites in Ottawa, Toronto and Longueuil call for mid-rise cores and podiums cast in place. That mix raises Canadian demand for pumpable and higher-strength grades, giving urban plants with pump fleets the first call on contracts.
- With property starts falling, Chinese producers are redirecting trucks to rail, water and urban renewal projects. Suppliers tied to housing developers face the slowest rebuild, and those with public contracts recover first.
- Surplus Indonesian kiln capacity has pushed cement prices down across the region. Cheaper binder narrows the cost gap with site mixing, so batch plant operators in Jakarta, Manila and Ho Chi Minh City gain contractors switching over.
- For German plants, rail, bridge and grid renewal now replaces lost housing volume. Carbon limits in those public tenders favour suppliers with certified low-clinker mixes over plants selling only standard grey concrete.
- Two sources add most new US pours, highway backlogs and data centre slabs. Producers integrated with paving crews take the highway work, and large continuous slab pours reward plants with spare truck capacity.
- As PNRR-funded works wind down, Italian deliveries lose the public support of recent years. Producers there are likely to compete harder on price for a smaller pool of residential jobs.
Full report country CAGRs cover: seven named countries with India highest at 7.5% and Italy lowest at 3.8%, followed by regional tables for the remaining standard list.
Country-wise Analysis
India Ready-mix Concrete Market Outlook (2026 to 2036)
In India, builders are moving from site mixing to plant-batched concrete in tier-2 cities, and a 7.5% CAGR through 2036 is forecast for demand for ready-mix concrete in India. A case in point is UltraTech, which reported Q1 FY27 net sales of Rs. 24,465 crores, up 16%, with domestic volume up 13.1%.[5] Cement demand rising at that pace points to more plant-batched pours. Metro corridors, expressways and high-rise housing need consistent strength classes that site mixers cannot match, so cement majors are adding RMC plants beside grinding units.
Key takeaway: Plant-batched concrete replaces site mixing across Indian cities.
Canada Ready-mix Concrete Market Outlook (2026 to 2036)
In FMI's forecast, Canadian demand advances 6.3% a year, 0.8 point faster than the 5.5% global pace, as federal housing money reaches city sites. In particular, the federal government listed six Direct Build sites in January 2026, among them 1,100 homes at Heron in Ottawa and 540 at Arbo in Toronto, and offered up to C$400 million for 3,000 homes with the city of Ottawa.[8] Mid-rise apartments on these sites need cast-in-place cores and podiums, which keeps urban batch plants busy.
Key takeaway: Federal housing sites give Canadian producers a public base load.
China Ready-mix Concrete Market Outlook (2026 to 2036)
Chinese ready-mix volume is still shrinking with the property market. China's cement output was 144.01 million tons in September 2026, 5.3% lower than a year earlier, and 8.6% lower for the first nine months.[7] In response, ready-mix producers are shifting crews to rail, water and urban renewal work as new housing starts fall. As a result, FMI expects a 6.2% CAGR for China as volume recovers from this low base.
Key takeaway: Infrastructure and renewal work rebuild volume after the property slump.
ASEAN Ready-mix Concrete Market Outlook (2026 to 2036)
Across ASEAN, contractors are switching to plant-batched concrete, and the regional rate is projected at 5.8% through 2036. For instance, Indonesia exported USD 443 million of cement in 2025, 18% above 2024, and the sector reported 122 Mt of capacity for domestic demand near 64 Mt.[3] That surplus binder keeps mix prices low for contractors in Jakarta, Manila and Ho Chi Minh City, which speeds the move to plant-batched concrete.
Key takeaway: Cheap binder from surplus kilns supports batch plant growth in ASEAN.
Germany Ready-mix Concrete Market Outlook (2026 to 2036)
German housing remains weak, and producer volumes show the effect. German ready-mix deliveries at Buzzi fell 6.9% in January to June 2026, and prices improved.[4] Firmer prices on lower volume suggest producers are protecting margin on fewer, mainly public, jobs. Looking ahead, rail, bridge and grid renewal will set the pace from 2027 as housing stays soft. German demand for ready-mix concrete is expected to rise about 5.7% a year, a shade above the global figure.
Key takeaway: Rail, bridge and grid renewal offsets weak German housing.
United States Ready-mix Concrete Market Outlook (2026 to 2036)
US volume is growing in the interior states and through acquisitions, though price is under pressure in Texas. Knife River reported higher ready-mix volume in Iowa, Minnesota, the Dakotas and Texas in the June 2026 quarter, partly from the Texcrete purchase, and better pricing in the West segment.[1] Those gains come from public paving and from bought plants, so growth is concentrated in integrated producers. On the other hand, Buzzi expects US volume to stay broadly flat for 2026, with pricing pressure in Texas.[4] Flat volume at a large cement-backed producer shows national gains are uneven by state. Taken together, US growth settles at a mature but steady 4.5% CAGR, supported by highway work, data centre slabs and acquisitions.
Key takeaway: US growth comes from public paving and bought plants.
Italy Ready-mix Concrete Market Outlook (2026 to 2036)
Italian demand is losing the public support of recent years. Buzzi's Italian ready-mix deliveries fell 6.3% in the first half of 2026, and the company expects weak volume as residential work softens and PNRR works scale back.[4] Fewer recovery-plan pours leave producers chasing a smaller residential pool. Accordingly, FMI expects Italy to grow at 3.8%, the slowest pace among the seven major country markets.
Key takeaway: Italy faces the slowest pace once recovery-plan pours end.
Who are the notable companies in the ready-mix concrete market?
Cemex, Holcim, Heidelberg Materials, CRH, Buzzi, Vicat, Titan, Knife River, China National Building Material, UltraTech Cement and ACC are the profiled companies.
FMI analysis shows that global cement groups, regional quarry-and-fleet owners and Asian cement majors with growing RMC arms run most large ready-mix fleets. Integrated cement groups are using own binder to defend concrete volume. Among the cement groups, Buzzi sold 15,674 thousand tonnes of cement in January to June 2026, 5.4% more, with the UAE operations consolidated.[4] Higher cement sales give such groups secure binder for ready-mix arms in weaker housing markets. Regional producers are growing through contracting work. On the regional side, Knife River's aggregates volume rose 13.7% to 10,031 thousand tons in the June 2026 quarter.[1] Own aggregates let regional producers price whole projects firmly. Balance sheets are also being prepared for deals. Vicat, meanwhile, cut financial gearing to 1.5 times at the end of 2025, from 2.8 times at the end of 2022, giving room for plant purchases.[6] Lower debt made the October bid for Cemex plants in France possible. The profiled companies also include Cemex, Holcim, Heidelberg Materials, CRH, Titan, China National Building Material, UltraTech Cement and ACC.
- Global cement and concrete groups: Cemex, Holcim, Heidelberg Materials, CRH and Buzzi.
- Regional integrated producers: Vicat, Titan and Knife River.
- Asian cement majors: China National Building Material, UltraTech Cement and ACC.
Competitive Benchmarking: Ready-mix Concrete Market
Table 8: Competitive Benchmarking for the Ready-mix Concrete Market (qualitative ratings), 2026
| Company | Volume Scale | Public Work Exposure | Plant Network Moves | Recent Activity |
|---|---|---|---|---|
| Knife River | High | High | Medium | High |
| Buzzi | High | Medium | Low | High |
| Vicat | Low | Medium | High | High |
| Titan | Low | Medium | Medium | High |
| UltraTech Cement | Medium | Medium | Medium | High |
Ratings compare the companies on volume scale, public work exposure and plant network moves.
Key Developments in the Ready-mix Concrete Market
- Titan announced a minority investment in Command Alkon on 13 October 2026 to digitise ready-mix and aggregates operations, a sign that large producers now see dispatch software as a route to more loads per truck.[2]
- In exclusive negotiations opened on 1 October 2026, Vicat moved to acquire Cemex ready-mix and aggregates units in south-eastern France; for builders on the coast, this means fewer and larger suppliers.[6]
- Knife River grew June-quarter ready-mix sales to USD 236.7 million and guided to mid-teens volume growth in August 2026, confirming public paving as the main source of new US volume.[1]
- With H1 ready-mix sales of 4,633 thousand cubic metres, Buzzi set a full-year EBITDA range of EUR 1,100 million to EUR 1,200 million on 4 August 2026, suggesting cement margins will cushion weaker European concrete volume.[4]
- On 20 July 2026, UltraTech Cement reported a 17% rise in Q1 FY27 profit after tax on higher domestic volume, evidence that Indian construction is absorbing new cement capacity.[5]
- Indonesian cement producers raised exports 18% to USD 443 million in 2025, figures released in April 2026 show, so more surplus binder is reaching neighbouring ASEAN batch plants.[3]
- The Government of Canada named Build Canada Homes sites for up to 4,000 homes on federal land on 7 January 2026, which adds a federally funded pipeline of foundation and podium pours.[8]
Key Players in the Ready-mix Concrete Market
Global Cement and Concrete Groups
- Cemex
- Holcim
- Heidelberg Materials
- CRH
- Buzzi
Regional Integrated Producers
- Vicat
- Titan
- Knife River
Asian Cement Majors
- China National Building Material
- UltraTech Cement
- ACC
Ready-mix Concrete Market - Report Scope
Table 9: Report Scope for the Ready-mix Concrete Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Type; production method; application; region |
| Quantitative units | USD billion |
| Market definition | Concrete batched at a central plant to a specified mix design and delivered to site in an unhardened state by truck mixer, agitator or volumetric unit, covering standard, flowable, self-compacting and fiber-reinforced grades. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Cemex, Holcim, Heidelberg Materials, CRH, Buzzi, Vicat, Titan, Knife River, China National Building Material, UltraTech Cement, ACC |
| Forecast period | 2026 to 2036 |
Ready-mix Concrete Market - Research Methodology
Table 10: Research Methodology for the Ready-mix Concrete Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Desk research covers delivered volumes, prices per cubic metre or yard, public backlogs, binder supply and plant ownership. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 850.0 billion and the 5.5% CAGR for 2026 to 2036. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Ready-mix Concrete Market by Segments
Ready-mix Concrete Market segmented by Type:
- Standard
- Flowable
- Self-Compacting
- Fiber-Reinforced
Ready-mix Concrete Market segmented by Production Method:
- Transit Mixed
- Central Mixed
- Shrink Mixed
Ready-mix Concrete Market segmented by Application:
- Infrastructure
- Residential
- Commercial
- Industrial
Ready-mix Concrete Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Knife River Corporation. (2026, August 4). Knife River Corporation Reports Second Quarter 2026 Financial Results. https://www.sec.gov/Archives/edgar/data/0001955520/000162828026052184/a2026q2ex99.htm
- [2] Global Cement. (2026, October 13). Titan invests in Command Alkon. https://www.globalcement.com/news/21346-titan-invests-in-command-alkon
- [3] Global Cement. (2026, April 17). Indonesian cement sales rise in 2025. https://www.globalcement.com/news/20663-indonesian-cement-sales-rise-in-2025
- [4] Buzzi SpA. (2026, August 4). Interim results at 30 June 2026. https://www.buzzi.com/w/risultati-al-30-giugno-2026
- [5] UltraTech Cement Limited. (2026, July 20). Financial Results: Q1FY27. https://www.ultratechcement.com/corporate/media/press-releases/financial-results-q1fy27
- [6] Vicat. (2026, October 1). Proposed Acquisition by Vicat Group of Cemex Group's Ready-Mix Concrete and Aggregates Businesses in South-Eastern France. https://www.vicat.com/en/news/proposed-acquisition-vicat-group-cemex-groups-ready-mix-concrete-and-aggregates-businesses
- [7] National Bureau of Statistics of China. (2026, October 20). Industrial Production Operation in September 2026. https://www.stats.gov.cn/english/PressRelease/202610/t20261020_1965665.html
- [8] Housing, Infrastructure and Communities Canada. (2026, January 7). Build Canada Homes: Thousands of Homes in the Pipeline. https://www.canada.ca/en/housing-infrastructure-communities/news/2026/01/build-canada-homes-thousands-of-homes-in-the-pipeline.html
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the ready-mix concrete market during 2026?
- What market size is projected by 2036?
- Which type holds notable share?
- Which production method holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the ready-mix concrete market expected in 2026?
For 2026, FMI estimates the ready-mix concrete market at USD 850.0 billion, up from USD 805.7 billion in 2025. Sales of ready-mix concrete are projected to reach USD 1,450.0 billion by 2036.
What CAGR is projected for the ready-mix concrete market through 2036?
The ready-mix concrete market is expected to grow at a 5.5% CAGR through 2036. Public road, rail and water programmes, urban housing and the move from site mixing to plant-batched concrete carry that growth.
Which type holds a notable market share in 2026?
Standard mixes are expected to lead with 65% share in 2026. Flowable grades follow at an estimated 13.5%.
Which production method holds a notable market share in 2026?
Transit mixed loads are likely to lead with 52% share. Central mixed plants follow at an estimated 33.5%.
Which country has a notable expansion outlook through 2036?
India leads FMI's country outlook with a 7.5% CAGR. Canada follows at 6.3%.
Who are the key companies in the ready-mix concrete market?
Cemex, Holcim, Heidelberg Materials, CRH and Buzzi lead the global group, and Vicat, Titan and Knife River lead the regional producers. China National Building Material, UltraTech Cement and ACC complete the profiled companies.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type, 2026 to 2036
- Standard
- Flowable
- Self-Compacting
- Fiber-Reinforced
- Y-o-Y Growth Trend Analysis By Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Type, 2026 to 2036
- Global Market Analysis and Forecast, By Production Method, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Production Method, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Production Method, 2026 to 2036
- Transit Mixed
- Central Mixed
- Shrink Mixed
- Y-o-Y Growth Trend Analysis By Production Method, 2021 to 2025
- Absolute $ Opportunity Analysis By Production Method, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Infrastructure
- Residential
- Commercial
- Industrial
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Type
- By Production Method
- By Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Type
- By Production Method
- By Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Type
- By Production Method
- By Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Type
- By Production Method
- By Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Knife River
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Buzzi
- Vicat
- Titan
- UltraTech Cement
- Cemex
- Holcim
- Heidelberg Materials
- CRH
- China National Building Material
- ACC
- Knife River
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


