
- Market Size (2026)
- USD 102.5 Bn
- Forecast (2036)
- USD 197.9 Bn
- CAGR (2026 to 2036)
- 6.8%
How big is Modular Construction Market in 2026?
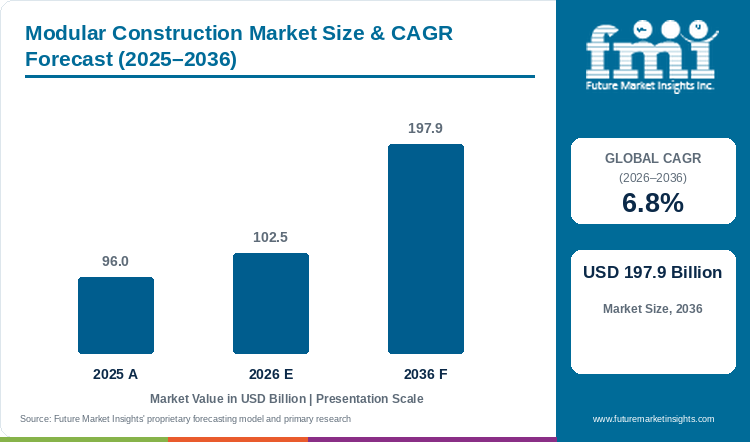
Registering a value of USD 96.0 billion in 2025, the modular construction market expanded to USD 102.5 billion in 2026 and is anticipated to achieve USD 197.9 billion by 2036, driven by a 6.8% CAGR.
The global modular construction market was valued at USD 96.0 billion in 2025 and is estimated to reach USD 102.5 billion in 2026. The industry valuation is projected to reach USD 197.9 billion by 2036, expanding at a compound annual growth rate (CAGR) of 6.8% between 2026 and 2036. FMI demand analysis indicates that Permanent Modular Construction is projected to capture 61.5% of 2026 demand, given that urban apartment builders and hospital networks are replacing sequential site trades with parallel factory assembly to cut loan interest carry. Demand for factory-engineered building modules is supported by schedule-compression economics, since concurrent foundation pouring and indoor module fabrication trim overall project delivery schedules by 20% to 50% according to the Modular Building Institute [1]. That whole-building replacement cycle separates general modular building from specialized modular data center systems expanding at a 13.8% CAGR, where hyperscale server operators purchase pre-wired power skids on accelerated deployment clocks [2]. Leading manufacturers are expanding regional factory capacity and rental fleets to convert that backlog, as Bouygues Construction handed over 42 social apartments in Arras built from 65 three-dimensional timber modules in January 2026 [22], WillScot Holdings raised its 2026 net fleet capital expenditure budget to USD 375 million in August 2026 [18], and Fleetwood Limited generated AUD 323.5 million in modular building solutions during fiscal 2026 [21]. Developers award repeat multi-building contracts when factory modules pass local code inspections without crane-rigging delays, and standardized mechanical wet-cores sustain buyer adoption through 2036 [3].
Key Market Trends & Insights
- By construction type: Permanent Modular Construction (PMC) is projected to hold an estimated 61.5% share in 2026 given that multi-story apartments, hospitals, and schools integrate factory modules onto permanent foundations.
- By module material: Cold-Formed Light Gauge Steel Framing is anticipated to account for 46.8% in 2026 since galvanized steel frames meet strict multi-story fire codes while keeping crane lifting weights manageable.
- By end-use sector: Multi-Family Residential Apartments and Student Housing are estimated to represent 36.8% in 2026 owing to acute municipal affordable housing deficits and university dormitory buildouts.
- By module design: Four-Sided Volumetric Modules are forecast to secure 56.4% in 2026 as fully enclosed room boxes arrive on-site with factory-installed drywall, plumbing, and electrical wiring.
- By delivery model: Turnkey Design-Build Direct Sales are projected to command 54.5% in 2026 through single-contract responsibility covering digital design, factory fabrication, transport, and site craning.
Regional Highlights
- Top national expansion: Saudi Arabia leads national growth projections at a 7.9% CAGR through 2036 driven by hospitality resort villages and remote workforce housing across national giga-projects.
- Broader country progression: The United Kingdom tracks at a 7.4% CAGR ahead of the United States at 7.1% and Australia at 6.9%, while Italy advances at a 5.6% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Modular Construction Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 96.0 billion |
| Estimated Market Size in 2026 | USD 102.5 billion |
| Projected Market Size by 2036 | USD 197.9 billion |
| CAGR, 2026 to 2036 | 6.8% |
| Added Revenue, 2026 to 2036 | USD 95.4 billion |
Commercial real estate developers, school districts, and hospital systems face persistent shortages of licensed site carpenters, electricians, and pipefitters that delay conventional stick-built completions. When general contractors shift structural framing and interior fit-out into climate-controlled plants, weather delays disappear and material scrap drops sharply. According to the Modular Building Institute in July 2026, permanent modular construction in the United States reached USD 20.5 billion in 2025 and accounted for 5.1% of new construction starts across covered building categories [1]. Consequently, institutional project owners combine modular prefabricated construction workflows with multi-year framework tenders to lock in fixed unit pricing and predictable occupancy dates.
Off-Site Floor Area and Volumetric Output Sizing
Table 2: Off-Site Floor Area and Volumetric Module Sizing for the Modular Construction Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 96.0 | 102.5 | 197.9 |
| Factory-fabricated modular floor area (million sq. meters) | 78.5 to 84.0 | 83.8 to 89.6 | 158.0 to 171.0 |
| Commercial volumetric & pod output (thousand units) | 2,150 to 2,320 | 2,290 to 2,480 | 4,350 to 4,720 |
| Average factory realization per sq. meter (USD) | 1,140 to 1,225 | 1,145 to 1,230 | 1,160 to 1,255 |
Operational note: Volumetric module and floor-area ranges reflect commercial permanent and relocatable factory output across steel, precast concrete, and mass-timber assembly lines globally.
According to the U.S. Department of Energy Building Technologies Office, combined European and American modular building activity is on course to reach USD 130 billion by 2030 as developers standardize repeatable room dimensions [5]. Multi-story residential and hotel builders increasingly pair precast concrete components on podium levels with lightweight steel volumetric boxes above to optimize crane hook time and foundation loads.
Construction Put-in-Place & Modular Fleet Indicators
Table 3: Construction Spending and Factory Productivity Indicators for the Modular Construction Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| U.S. permanent modular construction baseline (USD billion) | 20.5 | 21.8 | 41.0 |
| Schedule reduction vs. conventional site build (%) | 20.0% to 50.0% | 22.0% to 50.0% | 30.0% to 55.0% |
| Active global relocatable modular lease fleet (million units) | 1.85 to 1.95 | 1.92 to 2.04 | 2.85 to 3.10 |
| Permanent modular share of total market value (%) | 60.8% to 61.2% | 61.5% | 64.5% to 66.0% |
Table 4: Institutional & Channel Procurement Indicators for the Modular Construction Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 102.5 billion | 2026 global revenue baseline |
| U.S. construction spending SAAR, Sept 2026 | USD 2,186.1 billion | U.S. Census Bureau Release CB26-176 baseline |
| U.S. permanent modular market share | 5.1% of new starts | Modular Building Institute 2026 Industry Report |
| Turnkey Design-Build Direct Sales revenue, 2026 | USD 55.9 billion | 54.5% delivery model allocation |
As per U.S. Census Bureau construction spending data released in November 2026, total American construction put-in-place ran at a seasonally adjusted annual rate of USD 2,186.1 billion in September 2026, including USD 1,639.3 billion in private construction and USD 546.8 billion in public works [2]. Within that capital pool, general contractors and hospitality chains are accelerating purchases of prefabricated bathroom pods and utility wet-cores because factory-tested plumbing manifolds eliminate the highest-defect trade bottleneck on multi-story job sites [3].
Analyst Perspective
"Real estate developers and public infrastructure agencies do not procure modular construction merely to buy factory boxes; they buy guaranteed schedule compression and fixed labor cost certainty. Manufacturers that lock in early design-freeze discipline and combine four-sided volumetric rooms with pre-inspected mechanical wet-cores will capture the largest multi-project framework agreements through 2036."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the modular construction market segmented?
The modular construction market is segmented by construction type, module material, end-use sector, module design, and delivery model. In 2026, Permanent Modular Construction (PMC) is projected at 61.5%, Cold-Formed Light Gauge Steel Framing at 46.8%, Multi-Family Residential Apartments and Student Housing at 36.8%, Four-Sided Volumetric Modules at 56.4%, and Turnkey Design-Build Direct Sales at 54.5%.
By construction type: Permanent Modular Construction (PMC), Relocatable Temporary Modular Buildings, Refurbished and Redeployed Fleet Modules, and Hybrid Site-Built and Modular Structures.
By module material: Cold-Formed Light Gauge Steel Framing, Precast Concrete Modular Units, Structural Timber and Cross-Laminated Timber (CLT), and Hybrid Composite Modular Units.
By end-use sector: Multi-Family Residential Apartments and Student Housing, Commercial Offices and Data Center Modules, Healthcare Emergency Clinics and Hospital Patient Pods, Educational Classrooms and Dormitories, and Hospitality Hotel Rooms and Resort Pods.
By module design: Four-Sided Volumetric Modules, Open-Sided and Panelized Hybrid Modules, Wet-Core Bathroom and MEP Pods, and Skid-Mounted and Containerized Units.
By delivery model: Turnkey Design-Build Direct Sales, Modular Fleet Leasing and Rental, General Contractor Subcontracting, and Government and Institutional Framework Procurement.
Why does Permanent Modular Construction (PMC) lead the construction type category?
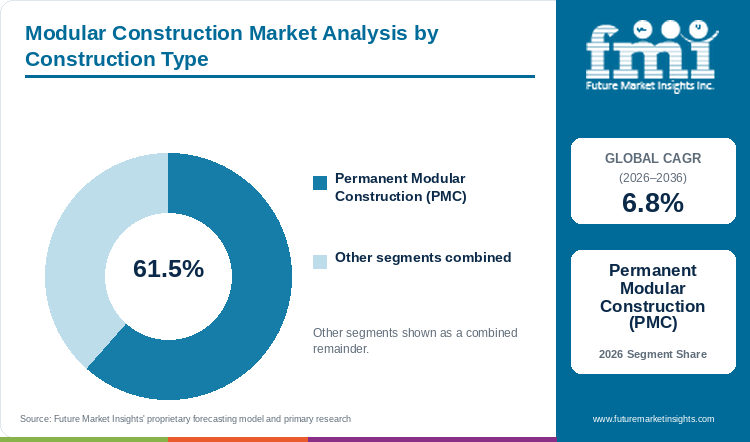
Permanent Modular Construction (PMC) holds an estimated 61.5% of construction type demand in 2026, anchored by multi-story residential, hospitality, and healthcare builds.
Table 5: Construction Type Share for the Modular Construction Market (percentage share), 2026
| Construction Type | Share (2026) |
|---|---|
| Permanent Modular Construction (PMC) | 61.5% |
| Other Segments Combined | 38.5%* |
| Total | 100.0% |
*Note: Remaining construction type categories account for the balance of 2026 global modular construction demand.
Table 6: Construction Type Leadership and Market Growth for the Modular Construction Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.8% |
| Leading Segment | Permanent Modular Construction (PMC) |
Permanent Modular Construction dominates buyer procurement because municipal housing authorities, university systems, and hospital networks require multi-story buildings engineered for fifty-year structural lifespans rather than temporary site cabins. When developers integrate bio-based structural wood adhesives and galvanized steel frames into permanent volumetric boxes, off-site fabrication runs concurrently with site grading, cutting total construction duration by up to half as documented by the Modular Building Institute in July 2026 [1]. However, permanent modular projects face strict design-freeze hurdles prior to factory tooling, since late architectural changes on a running assembly line create costly re-engineering delays.
- By construction type, Permanent Modular Construction (PMC) is projected to account for 61.5% of global share in 2026 as developers favor multi-story permanent structures over temporary site units.
- Relocatable Temporary Modular Buildings are anticipated to retain substantial demand across construction site offices, disaster relief clinics, and swing-space classrooms where lease flexibility outweighs permanent ownership [20].
What sustains Cold-Formed Light Gauge Steel Framing leadership in the module material segment?
Cold-Formed Light Gauge Steel Framing represents 46.8% of the module material category in 2026, supported by non-combustible multi-story stacking and crane weight efficiency.
Cold-Formed Light Gauge Steel Framing forms the primary structural skeleton for multi-story volumetric modules owing to its high strength-to-weight ratio, dimensional precision, and non-combustible fire rating. Unlike heavy concrete boxes that require high-capacity crawler cranes and specialized highway permits, cold-formed steel frames integrate insulated sandwich panel systems to keep individual module weights between fifteen and twenty metric tons for standard flatbed transport. Volatility in hot-dipped galvanized coil tariffs and thermal-bridging insulation requirements remain the primary operational hurdles that fabricators must manage during factory engineering.
- In the module material category, Cold-Formed Light Gauge Steel Framing is estimated to capture a leading 46.8% share in 2026 driven by multi-story residential and hotel stacking standards.
- Research published in PubMed Central in November 2025 confirmed that orthogonal cross-laminated timber and bamboo-timber shear walls deliver competitive lateral stiffness, intensifying material competition across low-rise and mid-rise modular housing [17].
How do Multi-Family Residential Apartments and Student Housing lead the end-use sector category?
Multi-Family Residential Apartments and Student Housing account for 36.8% of end-use sector demand in 2026, driven by repeatable room layouts and municipal housing backlogs.
Multi-Family Residential Apartments and Student Housing anchor global off-site order books because apartment bedrooms, student dormitories, and bathroom layouts repeat identically across dozens of floors. That architectural repetition allows factory assembly lines to standardize wall cassettes, prefabricated composite sandwich panels, and mechanical risers without custom re-tooling between units, as demonstrated when Bouygues Construction delivered 42 modular social apartments in Arras within seven months in January 2026 [22]. Even so, fragmented municipal zoning rules and lender draw schedules designed for conventional site-built milestones continue to slow developer financing across secondary metropolitan areas.
- Within the end-use sector breakdown, Multi-Family Residential Apartments and Student Housing are forecast to represent 36.8% of 2026 demand on the strength of public housing and campus dormitory pipelines.
- A systematic review in MDPI Buildings in August 2026 analyzing 98 modular residential studies showed that academic and commercial research output on flexible modular housing expanded sevenfold over the past decade [15].
Why do Four-Sided Volumetric Modules lead the module design category?
Four-Sided Volumetric Modules secure 56.4% of module design value in 2026, supported by complete factory interior finishes and pre-installed mechanical corridors.
Four-Sided Volumetric Modules lead buyer specifications because completing eighty to ninety percent of interior mechanical, electrical, plumbing, and finish work inside the factory maximizes site labor savings. Developers deploying full volumetric boxes only need to crane modules onto prepared podiums and connect inter-module structural ties and utility corridors on-site. Highway movement of enclosed three-dimensional boxes across highways creates oversized-load escort costs and width restrictions, prompting some high-density urban builders to supplement full boxes with flat-pack panelized cassettes and compact wet-core pods.
- Across module design configurations, Four-Sided Volumetric Modules are slated to secure 56.4% of 2026 demand as turnkey hospitality, student housing, and healthcare buyers prioritize complete factory room finishes.
- The U.S. Department of Housing and Urban Development reported in April 2026 from the International Builders' Show that homebuilders are pairing volumetric rooms with factory-built mechanical wet-cores to eliminate skilled plumbing bottlenecks [3].
What gives Turnkey Design-Build Direct Sales the leading position in delivery model?
Turnkey Design-Build Direct Sales command 54.5% of delivery model share in 2026, anchored by single-contract DfMA engineering, fabrication, and site craning.
Turnkey Design-Build Direct Sales capture the majority of commercial expenditure because property developers and public ministries prefer a single contract covering Design for Manufacture and Assembly engineering, factory fabrication, logistics, and site erection. When a single modular manufacturer controls both architectural tolerances and crane installation, interface disputes between separate architects, factories, and general contractors are eliminated, as evidenced by Laing O'Rourke achieving 40% to 50% schedule reductions through its integrated Centre of Excellence for Modern Construction [23]. High upfront working-capital deposits required to reserve factory line slots remain a notable procurement hurdle for smaller private developers.
- By delivery model, Turnkey Design-Build Direct Sales are anticipated to command 54.5% of 2026 demand because single-point engineering and assembly contracts minimize dimensional tolerance disputes.
- Modular Fleet Leasing and Rental accounts for the second-largest delivery channel as multi-branch operators supply relocatable classrooms, site offices, and temporary healthcare wards on recurring multi-year lease contracts [18].
What are the drivers, restraints, and opportunities in the modular construction market?
In the modular construction market, skilled site labor shortages and schedule-compression economics are projected to drive adoption whereas fragmented local building codes restrain interstate standardization and reusable seismic timber and data center pods unlock new growth.
- Driver: Acute skilled construction trade shortages and high project financing costs compel developers to adopt off-site factory fabrication that compresses build schedules by 20% to 50%.
- Restraint: Fragmented municipal building codes, duplicate on-site inspection mandates, and wide-load highway transport limits restrict cross-border standardization of volumetric modules.
- Opportunity: Circular demountable module engineering, seismic cross-laminated timber systems, and pre-integrated data center and healthcare pods unlock high-margin institutional contracts.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Persistent deficits in skilled site labor and rising urban housing backlogs are driving developers toward industrialized off-site manufacturing across North America, Europe, and Asia-Pacific. When project owners shift eighty percent of construction hours into automated factories using green building materials, parallel site foundation work and indoor module assembly cut project timelines by up to half while reducing construction waste. According to the European Commission BUILD UP portal in July 2025, European Union construction output is projected to expand by 2.1% annually through 2026, with modular prefabrication identified as a primary productivity lever to overcome regional trade shortages [8]. This schedule certainty directly accelerates developer return on invested capital and drives repeat multi-family and healthcare module orders.
Risk Assessment of the Modular Construction Market: Operational and Formulation Friction
Fragmented local building codes, non-uniform state and municipal inspection regimes, and highway dimensional limits represent the primary restraints limiting wider modular adoption. When local building inspectors refuse to recognize third-party factory certification seals, manufacturers must leave drywall and roofing materials open for on-site inspection, eroding the speed advantage of volumetric prefabrication. In August 2026, the U.S. Department of Housing and Urban Development concluded that off-site housing expansion is constrained primarily by fragmented local permitting, inspection protocols, and construction-loan draw rules rather than factory technology [4]. Furthermore, a lifecycle defect study published in MDPI Sustainability in April 2026 documented that hoisting stresses and highway vibration require strict factory dimensional quality gates to prevent water ingress at inter-module joints [16].
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Manufacturers are unlocking lucrative revenue streams by engineering demountable, seismic-resilient mass-timber modules and high-density technical pods that comply with strict embodied-carbon caps. According to the European Commission and UNEP Global Status Report in May 2026, buildings and construction account for 37% of global carbon dioxide emissions and nearly 50% of material extraction, prompting public tenders to mandate low-carbon circular structures [9]. When builders integrate building thermal insulation with reusable structural frames allows owners to relocate and repurpose entire buildings across multiple lifecycles. In March 2026, full-scale seismic testing by the European Commission Joint Research Centre confirmed that a modular building system using rocking cross-laminated timber panels withstood 180% collapse-prevention ground motion with zero panel damage and residual drift below 0.04% [10].
Modular Construction Market by Country (2026 to 2036)
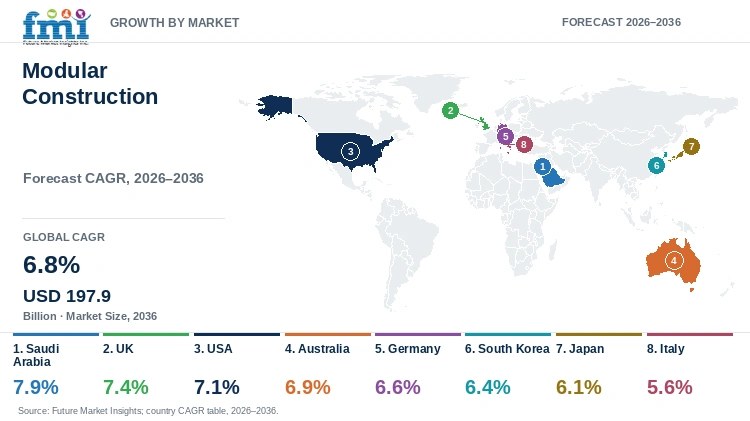
FMI country modeling indicates that Saudi Arabia leads national modular construction expansion at a 7.9% CAGR through 2036, followed by the United Kingdom at 7.4% and the United States at 7.1%, while Italy progresses at a 5.6% CAGR. National adoption patterns reflect differences in public infrastructure procurement, skilled trade availability, and factory certification standards.
Table 7: Country CAGR and Primary Growth Levers for the Modular Construction Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Saudi Arabia | 7.9% | Vision 2030 giga-project hospitality resorts and turnkey remote workforce villages |
| UK | 7.4% | Homes England MMC social housing quotas and public school and hospital rebuilds |
| USA | 7.1% | USD 20.5B permanent modular base, multi-family infill, and data center modules |
| Australia | 6.9% | State modular school upgrade programs and remote mining village expansions |
| Germany | 6.6% | Federal serial housing frameworks and high-efficiency commercial refurbishments |
| South Korea | 6.4% | High-rise steel volumetric public housing and semiconductor fab workforce units |
| Japan | 6.1% | MLIT i-Construction 2.0 labor-saving automation and seismic apartment builds |
| Italy | 5.6% | National Recovery Plan school retrofits and seismic cross-laminated timber systems |
Source: Future Market Insights analysis
Saudi Arabia Modular Construction Market Outlook (2026 to 2036)
Demand for modular construction in Saudi Arabia is projected to expand at a market-leading 7.9% CAGR from 2026 to 2036 as desert giga-projects and hospitality developments require rapid off-site room delivery. National procurement differs from mature Western rental markets because Saudi developers commission entire turnkey workforce cities, utility plants, and luxury resort pods in remote coastal and desert corridors lacking local trade labor. Domestic manufacturers such as Red Sea International Company operate automated factories in Jeddah and Riyadh with integrated mechanical-electrical-plumbing contracting divisions to deliver sixty-minute fire-rated steel modules on compressed schedules [15]. Highway transport of wide volumetric boxes across long desert highway routes remains the primary logistical challenge shaping factory siting across the Kingdom.
Key takeaway: In Saudi Arabia, giga-project hospitality developments and turnkey remote workforce villages are projected to drive leading demand for fire-rated volumetric steel modules.
UK Modular Construction Market Outlook (2026 to 2036)
The United Kingdom modular construction market is anticipated to grow at a 7.4% CAGR between 2026 and 2036, supported by public school rebuilding frameworks, hospital ward expansions, and social housing mandates. British adoption stands apart from continental European markets because central government procurement rules actively require Modern Methods of Construction across publicly funded housing and education tenders. In October 2026, the UK Office for National Statistics reported that total Great Britain construction output dipped 1.0% over the three months to August 2026 as private housing slowed by 3.2%, reinforcing contractor reliance on public off-site building programs [6]. Additionally, the UK government Timber in Construction Roadmap published in March 2025 established national policy pathways to expand volumetric and panelized mass-timber housing [7].
Key takeaway: In the UK, public healthcare and school rebuilding frameworks paired with national mass-timber roadmaps are anticipated to sustain strong off-site procurement.
USA Modular Construction Market Outlook (2026 to 2036)
Modular construction adoption in the United States is forecast to advance at a 7.1% CAGR through 2036 across multi-family apartment infill projects, commercial fleet leasing, and hyperscale data center halls. What distinguishes the American market is the dual scale of permanent volumetric multi-family fabrication with North America's largest relocatable workspace leasing fleets. In July 2026, the Modular Building Institute reported that permanent modular construction captured 5.1% of new American construction starts in 2025 and is projected to grow at 6.5% annually through 2030 [1]. Meanwhile, U.S. Department of Housing and Urban Development researchers noted in August 2026 that harmonizing state-level factory inspection reciprocity remains essential to unlock interstate module shipments [4].
Key takeaway: In the USA, multi-family apartment prefabrication, data center power modules, and large relocatable lease fleets are forecast to anchor long-term expansion.
Australia Modular Construction Market Outlook (2026 to 2036)
Australia is estimated to record a 6.9% CAGR in modular construction demand between 2026 and 2036 as state education departments, mining operators, and suburban housing authorities accelerate off-site procurement. Australian buyer behavior is shaped by vast geographic distances between metropolitan trade pools and remote resource basins in Western Australia and Queensland. In November 2026, the Australian Bureau of Statistics reported that national dwelling approvals rose 5.1% in September 2026, adding pressure on constrained domestic framing crews [12]. Domestic leader Fleetwood Limited demonstrated the commercial shift toward repeatable public designs in August 2026 by reporting high contract volume across its modular school upgrade programs and Searipple workforce village operations [21].
Key takeaway: In Australia, state modular classroom renewal programs and remote resource accommodation villages are estimated to propel steady off-site manufacturing growth.
Germany Modular Construction Market Outlook (2026 to 2036)
German modular construction demand is slated to progress at a 6.6% CAGR from 2026 to 2036, anchored by federal serial housing framework contracts and municipal school and office refurbishments. Germany diverges from North American timber-frame conventions by emphasizing precision steel, precast concrete, and hybrid timber modules engineered to strict national thermal-envelope standards. In July 2025, the federal statistical office Destatis reported that completions of prefabricated residential buildings fell 15.5% in 2024 during the mortgage rate spike, prompting municipal housing corporations to pivot toward serial multi-story apartment tenders [11]. Furthermore, Canada Mortgage and Housing Corporation data from August 2026 showing 373,091 units under construction illustrates the parallel Western policy push toward factory-built multi-unit housing [13].
Key takeaway: In Germany, federal serial housing frameworks and high-efficiency commercial refurbishments are slated to drive recovery and long-term demand for hybrid steel and timber modules.
South Korea Modular Construction Market Outlook (2026 to 2036)
South Korea is predicted to expand at a 6.4% CAGR across the 2026 to 2036 forecast window as public housing agencies and electronics manufacturers deploy high-rise steel modular systems. High urban land density in Seoul and Gyeonggi Province pushes Korean contractors toward thirteen-story and twenty-plus-story fire-resistant steel volumetric towers rather than low-rise suburban modules. A systematic review published in MDPI Buildings in August 2026 ranked South Korea among the top three nations globally in peer-reviewed modular residential engineering research, reflecting intensive domestic investment in inter-module seismic connections and acoustic floor assemblies [15]. Strict high-rise fire-resistance testing and crane setup constraints in congested urban sites remain the primary technical hurdles for Korean builders.
Key takeaway: In South Korea, high-rise public housing programs and semiconductor facility expansions are predicted to accelerate demand for fire-rated steel volumetric modules.
Japan Modular Construction Market Outlook (2026 to 2036)
Sales of modular construction systems in Japan are expected to increase at a 6.1% CAGR between 2026 and 2036, driven by demographic aging among site carpenters and stringent seismic building codes. Japanese residential and commercial buyers have long accepted factory-engineered steel and timber housing from vertically integrated manufacturers such as Daiwa House Industry [24]. In April 2026, the Ministry of Land, Infrastructure, Transport and Tourism published the second-year results of its i-Construction 2.0 initiative, designating fiscal 2026 for full deployment of off-site prefabrication and site automation to achieve a 30% labor reduction by fiscal 2040 [14]. Narrow urban street access in Tokyo and Osaka requires Japanese producers to engineer compact modules and panelized cassettes suited to light mobile cranes.
Key takeaway: In Japan, national i-Construction 2.0 labor-saving mandates and seismic housing replacement are expected to sustain steady factory-built module demand.
Italy Modular Construction Market Outlook (2026 to 2036)
Italy is projected to register a 5.6% CAGR in modular construction from 2026 to 2036 as municipal administrators modernize schools, community healthcare clinics, and seismic-zone housing. Italian procurement is heavily influenced by seismic safety retrofits across historic municipalities and European Union recovery funds targeting net-zero public buildings. In March 2026, experimental testing at the European Commission Joint Research Centre in Ispra validated that a reusable modular building constructed with rocking cross-laminated timber panels survived extreme seismic ground motions without structural damage [10]. Compliance with municipal architectural heritage preservation boards and regional seismic permitting offices remains the primary hurdle governing project timelines across Italian provinces.
Key takeaway: In Italy, seismic-resilient school and healthcare modernizations supported by reusable mass-timber engineering are projected to underpin modular adoption.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the modular construction market?
Laing O'Rourke, Bouygues Construction, Daiwa House Industry Co., Ltd., Guerdon, LLC, WillScot Holdings Corporation, Modulaire Group, ATCO Ltd., Kleusberg GmbH & Co. KG, Red Sea International Company, and Fleetwood Limited are the notable companies in the modular construction market.
Competitive positioning in the modular construction industry divides into permanent volumetric and turnkey modular builders, relocatable modular fleet and hybrid space providers, and regional workforce, institutional, and giga-project specialists. Laing O'Rourke and Bouygues Construction with Daiwa House Industry Co., Ltd. and Guerdon, LLC engineer permanent multi-story residential, hospitality, and healthcare buildings using automated steel, precast concrete, and mass-timber lines. WillScot Holdings Corporation and Modulaire Group and ATCO Ltd. and Kleusberg GmbH & Co. KG operate multi-country relocatable lease fleets and permanent modular manufacturing plants, while Red Sea International Company and Fleetwood Limited anchor turnkey modular delivery across the Middle East and Oceania.
- Permanent Volumetric and Turnkey Modular Builders: Laing O'Rourke, Bouygues Construction, Daiwa House Industry Co., Ltd., and Guerdon, LLC manufacture multi-story steel, concrete, and timber volumetric buildings and mechanical pods.
- Relocatable Modular Fleet and Hybrid Space Providers: WillScot Holdings Corporation, Modulaire Group, ATCO Ltd., and Kleusberg GmbH & Co. KG combine hundreds of thousands of leasable modular cabins with custom permanent modular fabrication.
- Regional Workforce, Institutional, and Giga-Project Specialists: Red Sea International Company and Fleetwood Limited deliver turnkey modular schools, healthcare facilities, mining villages, and hospitality resorts across high-growth regional corridors.
Competitive Benchmarking: Modular Construction Market
Table 8: Competitive Benchmarking for the Modular Construction Market (qualitative capability ratings), 2026
| Company | Volumetric Factory Automation | Turnkey DfMA Engineering | Circular Fleet & Reuse Fit | Geographic Reach |
|---|---|---|---|---|
| Laing O'Rourke | High | High | High | UK, Europe, Australia, and Middle East; GBP 200M CEMC precast and MEP pod plant |
| Bouygues Construction | High | High | High | Europe, UK, and Asia-Pacific; delivered 65-module Arras 3D timber housing in Jan 2026 |
| Daiwa House Industry Co., Ltd. | High | High | High | Japan, USA, Australia, and ASEAN industrialized steel and timber modular housing |
| Guerdon, LLC | High | High | Medium | Western North America multi-story wood and steel volumetric apartments and hotels |
| WillScot Holdings Corporation | Medium | Medium | High | North America relocatable modular fleet leader; USD 2.3B 2026 revenue outlook |
| Modulaire Group | Medium | High | High | Europe and Asia-Pacific (~300,000 modular units across Algeco and regional brands) |
| ATCO Ltd. | High | High | High | Canada, USA, Australia, and Latin America (ATCO Structures and NRB Modular) |
| Kleusberg GmbH & Co. KG | High | High | High | Germany and Western Europe; >50 steel and hybrid modular projects annually |
| Red Sea International Company | High | High | Medium | Saudi Arabia, Middle East, and Africa turnkey giga-project camps and MEP integration |
| Fleetwood Limited | High | High | High | Australia and New Zealand modular schools, housing, and Searipple community villages |
Scoring basis: Volumetric Factory Automation evaluates documented investment in robotic cold-formed steel, precast concrete, or mass-timber assembly lines, while Turnkey DfMA Engineering rates in-house digital twin, structural, and MEP pod integration. Circular Fleet & Reuse Fit measures documented lease-fleet refurbishment or demountable low-carbon building certification.
Key Developments in the Modular Construction Market
- Fleetwood Limited reported fiscal 2026 financial results on August 26, 2026, recording AUD 475.0 million in total revenue including AUD 323.5 million in modular Building Solutions and AUD 93.8 million in Community Solutions across Australia [21].
- WillScot Holdings Corporation announced second-quarter 2026 financial results on August 6, 2026, raising its full-year 2026 revenue outlook to USD 2.3 billion and increasing net fleet capital expenditure guidance to USD 375 million on rising modular project activations [18].
- Bouygues Construction completed final handover of the Madeleine Didier Residence in Arras, France in January 2026, delivering 42 social apartments assembled from 65 factory-finished 3D timber modules in seven months [22].
Key Players in the Modular Construction Market
Permanent Volumetric and Turnkey Modular Builders
- Laing O'Rourke
- Bouygues Construction
- Daiwa House Industry Co., Ltd.
- Guerdon, LLC
Relocatable Modular Fleet and Hybrid Space Providers
- WillScot Holdings Corporation
- Modulaire Group
- ATCO Ltd.
- Kleusberg GmbH & Co. KG
Regional Workforce, Institutional, and Giga-Project Specialists
- Red Sea International Company
- Fleetwood Limited
Modular Construction Market - Report Scope
Table 9: Report Scope for the Modular Construction Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Construction Type; Module Material; End-Use Sector; Module Design; Delivery Model |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial manufacturer and fleet operator revenue from factory-prefabricated three-dimensional volumetric building modules, open-sided panelized hybrid rooms, pre-engineered bathroom and MEP wet-cores, and relocatable modular building leases. Category Scope Note: Excludes conventional site-built stick construction, unfabricated raw steel or lumber, and mobile recreational vehicles. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Saudi Arabia, UK, USA, Australia, Germany, South Korea, Japan, Italy, and additional countries in the full report |
| Key Companies Covered | Laing O'Rourke, Bouygues Construction, Daiwa House Industry Co., Ltd., Guerdon, LLC, WillScot Holdings Corporation, Modulaire Group, ATCO Ltd., Kleusberg GmbH & Co. KG, Red Sea International Company, Fleetwood Limited |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Modular Construction Market - Research Methodology
Table 10: Research Methodology for the Modular Construction Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with volumetric modular plant directors, DfMA structural engineers, public housing procurement officers, and relocatable modular fleet executives to validate factory throughput and per-square-meter pricing. |
| Secondary Research | Analysis of U.S. Census Bureau construction spending releases, Modular Building Institute annual reports, UK ONS construction bulletins, Destatis prefabricated building registries, MLIT i-Construction 2.0 filings, and corporate financial statements. |
| Market Sizing and Forecasting | Top-down global construction put-in-place baselines reconciled against bottom-up factory-fabricated modular floor area (83.8M to 89.6M sq. meters in 2026) and active relocatable lease fleet revenues from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight public social-housing mandates, skilled trade vacancy rates, giga-project capital expenditure, and factory code reciprocity across eight major countries. |
| Operational Benchmark Traceability | Floor-area, schedule-saving, and fleet indicators in Tables 2, 3, and 4 trace to Modular Building Institute industry benchmarks, U.S. DOE industrialized construction studies, and U.S. Census Bureau C30 series data. |
| Data Triangulation and Validation | Revenue estimates isolate factory-manufactured volumetric modules, panelized hybrid systems, and relocatable modular leases while strictly excluding conventional on-site civil works and raw bulk building materials. |
Modular Construction Market by Segments
Modular Construction Market segmented by Construction Type:
- Permanent Modular Construction (PMC)
- Relocatable Temporary Modular Buildings
- Refurbished and Redeployed Fleet Modules
- Hybrid Site-Built and Modular Structures
Modular Construction Market segmented by Module Material:
- Cold-Formed Light Gauge Steel Framing
- Precast Concrete Modular Units
- Structural Timber and Cross-Laminated Timber (CLT)
- Hybrid Composite Modular Units
Modular Construction Market segmented by End-Use Sector:
- Multi-Family Residential Apartments and Student Housing
- Commercial Offices and Data Center Modules
- Healthcare Emergency Clinics and Hospital Patient Pods
- Educational Classrooms and Dormitories
- Hospitality Hotel Rooms and Resort Pods
Modular Construction Market segmented by Module Design:
- Four-Sided Volumetric Modules
- Open-Sided and Panelized Hybrid Modules
- Wet-Core Bathroom and MEP Pods
- Skid-Mounted and Containerized Units
Modular Construction Market segmented by Delivery Model:
- Turnkey Design-Build Direct Sales
- Modular Fleet Leasing and Rental
- General Contractor Subcontracting
- Government and Institutional Framework Procurement
Modular Construction Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Modular Building Institute. (2026, July 14). MBI Reports $20.5 Billion U.S. Permanent Modular Market, Forecasts 6.5% Annual Growth Through 2030. Modular Building Institute Industry Reports.
- [2] U.S. Census Bureau. (2026, November 2). Monthly Construction Spending, September 2026 (Release CB26-176). U.S. Department of Commerce.
- [3] U.S. Department of Housing and Urban Development. (2026, April 30). PD&R Attends the 2026 International Builders' Show. HUD Office of Policy Development and Research.
- [4] U.S. Department of Housing and Urban Development. (2026, August 20). Studying the Impacts of Offsite Construction on Housing Supply. HUD Office of Policy Development and Research.
- [5] U.S. Department of Energy. (2024, February 26). Industrialized Construction: The Case for Modular. DOE Building Technologies Office and NREL.
- [6] UK Office for National Statistics. (2026, October 15). Construction output in Great Britain: August 2026. Office for National Statistics Statistical Bulletins.
- [7] UK Department for Environment, Food and Rural Affairs. (2025, March 3). Timber in construction roadmap 2025. GOV.UK Policy Publications.
- [8] European Commission BUILD UP Portal. (2025, July 11). Construction 2025-2026: Challenges and opportunities. European Commission Directorate-General for Energy.
- [9] European Commission BUILD UP Portal. (2026, May 19). Global Status Report for Buildings and Construction 2025-2026: key messages. European Commission and UNEP.
- [10] Kallioras, S., Bournas, D., & Molina, F. J. (2026, March 27). Modular building system with rocking cross-laminated timber panels for reusable construction: Experimental seismic assessment. European Commission Joint Research Centre (JRC143097).
- [11] Statistisches Bundesamt. (2025, July 28). 2024 wurden 15,5 % weniger Wohngebaude aus Fertigteilen errichtet als 2023 (Press Release PD25_N039_31). Destatis Federal Statistical Office of Germany.
- [12] Australian Bureau of Statistics. (2026, November 2). Total dwelling approvals rise 5.1% in September. Australian Bureau of Statistics Media Releases.
- [13] Canada Mortgage and Housing Corporation. (2026, August 18). Housing starts and construction data for July 2026. CMHC Housing Market Information.
- [14] Ministry of Land, Infrastructure, Transport and Tourism. (2026, April 28). Year 2 (FY2025) Implementation Results of i-Construction 2.0. MLIT Japan Official Press Releases.
- [15] Belkhiri, K., et al. (2026, August 1). Modular and Flexible Residential Architecture: A Systematic Review. Buildings, 16(15), 3052 (MDPI).
- [16] Gurmu, A., et al. (2026, April 17). Defects in Modular Building Construction: A Systematic Lifecycle Review and Implications for Sustainable Delivery. Sustainability, 18(8), 4000 (MDPI).
- [17] National Library of Medicine. (2025, November 12). Sustainable Development Advantages of Cross-Laminated Timber and Bamboo-Timber (CLBT) in Modular Shear Walls. PubMed Central (PMC12608569).
- [18] WillScot Holdings Corporation. (2026, August 6). WillScot Reports Second Quarter 2026 Results and Raises 2026 Outlook. WillScot Investor Relations.
- [19] ATCO Ltd. (2026, May 7). ATCO Reports First Quarter 2026 Earnings. ATCO Corporate Newsroom.
- [20] Modulaire Group. (2025, October 15). Modulaire Group Launches Sixth Annual ESG and Sustainability Report. Modulaire Group Corporate Communications.
- [21] Fleetwood Limited. (2026, August 26). FY26 Full Year Financial Results: Portfolio Simplification and Strong Cash Performance. Fleetwood Australia ASX Filings.
- [22] Bouygues Construction. (2026, January 20). Madeleine Didier Residence, Arras: 42 Modular Timber Homes Delivered in Record Time. Bouygues Construction Project Reference Library.
- [23] Laing O'Rourke. (2025, October 10). DFMA and Offsite Manufacturing at the Centre of Excellence for Modern Construction. Laing O'Rourke Technical Publications.
- [24] Daiwa House Industry Co., Ltd. (2026, September 1). Daiwa House Group Integrated Report 2026. Daiwa House Investor Relations.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the modular construction market in 2026 and what is forecast for 2036?
- Which schedule-compression and trade-shortage pressures support demand for modular construction?
- Why does Permanent Modular Construction (PMC) lead the construction type category?
- Why does Cold-Formed Light Gauge Steel Framing lead the module material category globally?
- How do growth rates differ across Saudi Arabia, the United Kingdom, the United States, and Australia?
- Which leading companies supply permanent volumetric buildings versus relocatable modular lease fleets today?
- What local building code and wide-load transport hurdles restrain adoption in the modular construction market?
- What should real estate developers evaluate before locking in turnkey volumetric design-build contracts?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Construction Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Construction Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Construction Type, 2026 to 2036
- Permanent Modular Construction (PMC)
- Relocatable Temporary Modular Buildings
- Refurbished and Redeployed Fleet Modules
- Hybrid Site-Built and Modular Structures
- Y-o-Y Growth Trend Analysis By Construction Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Construction Type, 2026 to 2036
- Global Market Analysis and Forecast, By Module Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Module Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Module Material, 2026 to 2036
- Cold-Formed Light Gauge Steel Framing
- Precast Concrete Modular Units
- Structural Timber and Cross-Laminated Timber (CLT)
- Hybrid Composite Modular Units
- Y-o-Y Growth Trend Analysis By Module Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Module Material, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Multi-Family Residential Apartments and Student Housing
- Commercial Offices and Data Center Modules
- Healthcare Emergency Clinics and Hospital Patient Pods
- Educational Classrooms and Dormitories
- Hospitality Hotel Rooms and Resort Pods
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Module Design, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Module Design, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Module Design, 2026 to 2036
- Four-Sided Volumetric Modules
- Open-Sided and Panelized Hybrid Modules
- Wet-Core Bathroom and MEP Pods
- Skid-Mounted and Containerized Units
- Y-o-Y Growth Trend Analysis By Module Design, 2021 to 2025
- Absolute $ Opportunity Analysis By Module Design, 2026 to 2036
- Global Market Analysis and Forecast, By Delivery Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Delivery Model, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Delivery Model, 2026 to 2036
- Turnkey Design-Build Direct Sales
- Modular Fleet Leasing and Rental
- General Contractor Subcontracting
- Government and Institutional Framework Procurement
- Y-o-Y Growth Trend Analysis By Delivery Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Delivery Model, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- By Country
- Market Attractiveness Analysis
- By Country
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Construction Type
- By Module Material
- By End-Use Sector
- By Module Design
- By Delivery Model
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Laing O'Rourke
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bouygues Construction
- Daiwa House Industry Co., Ltd.
- Guerdon, LLC
- WillScot Holdings Corporation
- Modulaire Group
- ATCO Ltd.
- Kleusberg GmbH & Co. KG
- Red Sea International Company
- Fleetwood Limited
- Laing O'Rourke
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Construction Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Module Material, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Sector, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Module Design, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Delivery Model, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Construction Type
- Figure 6: Global Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Module Material
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Module Design
- Figure 15: Global Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Delivery Model
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Construction Type
- Figure 32: North America Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Module Material
- Figure 35: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by End-Use Sector
- Figure 38: North America Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Module Design
- Figure 41: North America Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Delivery Model
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Construction Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Module Material
- Figure 51: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 54: Latin America Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Module Design
- Figure 57: Latin America Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Delivery Model
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Construction Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Module Material
- Figure 67: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 70: Western Europe Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Module Design
- Figure 73: Western Europe Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Delivery Model
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Construction Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Module Material
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Module Design
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Delivery Model
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Construction Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Module Material
- Figure 99: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 102: East Asia Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Module Design
- Figure 105: East Asia Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Delivery Model
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Construction Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Module Material
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Module Design
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Delivery Model
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Construction Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Construction Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Construction Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Module Material, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Module Material, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Module Material
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Module Design, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Module Design, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Module Design
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Delivery Model, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Delivery Model, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Delivery Model
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the modular construction market in 2026, and what is forecast for 2036?
FMI estimates that the global modular construction market size stood at USD 96.0 billion in 2025 and is projected to reach USD 102.5 billion in 2026. Overall industry valuation is on track to hit USD 197.9 billion by 2036 as developers standardize off-site room fabrication and pre-tested utility pods.
What is the CAGR for the modular construction market from 2026 to 2036?
The modular construction sector is projected to expand at a 6.8% CAGR over the 2026 to 2036 window, adding USD 95.4 billion across permanent multi-story builds and relocatable workspace fleets.
Which construction type segment leads the modular construction market?
Permanent Modular Construction (PMC) is projected to hold 61.5% of construction type demand in 2026 since multi-family apartment, hospitality, and healthcare developers integrate factory modules into permanent structures.
Which module material segment leads the modular construction market?
Cold-Formed Light Gauge Steel Framing is anticipated to represent 46.8% of the module material category in 2026 owing to its non-combustible fire compliance and favorable crane lifting weight.
Which country has a notable growth outlook during the assessment period?
Saudi Arabia leads national expansion projections at a 7.9% CAGR through 2036, driven by giga-project hospitality villages and turnkey remote workforce housing contracts.
Who are the key players in the market?
Laing O'Rourke, Bouygues Construction, Daiwa House Industry Co., Ltd., Guerdon, LLC, WillScot Holdings Corporation, Modulaire Group, ATCO Ltd., Kleusberg GmbH & Co. KG, Red Sea International Company, and Fleetwood Limited lead commercial supply across permanent volumetric projects and relocatable modular fleets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
