

- Market Size (2026)
- USD 424.5 Mn
- Forecast (2036)
- USD 5522.6 Mn
- CAGR (2026 to 2036)
- 29.2%
How big is Plant-based Fish Market in 2026?
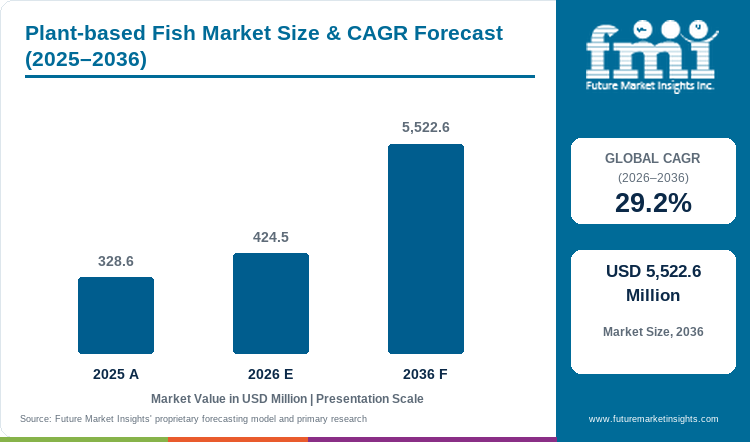
USD 424.5 million in 2026 and USD 5522.6 million by 2036 at a 29.2% CAGR.
Sales of plant-based fish are estimated to rise at 29.2% CAGR through 2036, increasing valuation from USD 328.6 million in 2025 to USD 424.5 million in 2026, and reaching USD 5522.6 million by 2036. Plant-based fish suppliers are competing for repeat purchases by improving texture and value against conventional seafood.
UK plant-based seafood volume increased 13.7% in 2025 and Germany declined 29.4% in the same category. GFI Europe recorded 8.5% UK unit growth and linked German weakness to taste and texture gaps versus animal seafood. UK retailers are testing assortment from a stronger category base. German retailers are addressing a reformulation problem tied to volume losses despite existing shelf access. Suppliers in both markets are working to sustain sensory performance and pricing beyond initial trial.
Key Takeaways of Plant-based Fish Market
- Established seafood meals support plant-based fish demand by giving consumers familiar preparation and serving occasions.
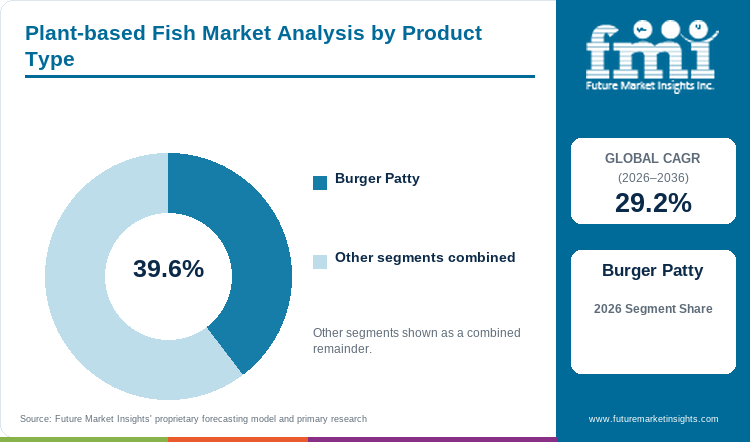
- Burger patty is estimated to hold 39.6% of product type demand in 2026, driven by standardized portions that simplify household cooking and commercial menu costing.
- Plant-based fishless fish is set to lead the nature category with 84.6% share in 2026, attributable to its wider species range and multi-format meal use.
- Refrigerated product is projected to hold 87.6% of merchandising format demand in 2026, influenced by texture-sensitive handling and chilled placement.
- Taste gaps and price premiums are limiting the conversion of initial trial into repeat demand despite adequate retailer shelf access.
- Key players include Revo Foods GmbH and BettaF!sh (Bayou Best Foods). Steakholder Foods Ltd. and Schouten Europe B.V. are also active in the defined market. Oshi Inc. and New School Foods Inc. supply whole-cut fish formats. Save Da Sea Foods Inc. and The Plant Based Seafood Co. serve prepared seafood applications. Fysh Foods (City Roots Hospitality) and IBIDEN Bussan Co., Ltd. complete the profiled company set.
Analyst Perspective
“Plant-based fish earns repeat space by matching the texture and cooking behavior consumers expect from conventional seafood. Suppliers need consistent production and realistic pricing to expand distribution beyond controlled trials.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Plant-based Fish Market segmented?
Plant-based Fish Market is segmented by Product Type, Nature, Merchandising Format, Source, Distribution Channel and Region.
Product type covers burger patty, filets, steaks, fishcakes, crumbles and grounds, slices & strips, cutlet and fingers. Nature includes plant-based fishless fish and plant-based tuna. Merchandising format separates refrigerated product from plant-based ambient foods. Source covers soy, pea, wheat, rice, canola, corn, potato and lentil proteins. Distribution channel includes retail, HoReCa and online retail. Regional analysis follows the listed geography hierarchy.
How do burger patties support familiar seafood preparation within product type?
Burger patties give plant-based fish a standardized portion for household cooking and commercial menu costing. Steakholder Foods moved white-fish kebabs and salmon patties into leading vegan specialty stores across Israel in July 2025 following production scale-up with Bondor Foods. Retail placement in plant-based meat formats makes consistent bite important for repeat purchasing.
- Burger patty is estimated to hold 39.6% of product type demand in 2026, supported by standardized portions that simplify cooking and menu costing.
- Patty formats invite direct comparison with familiar protein products, so retail acceptance depends on consistent sensory performance during repeat purchases.
What gives plant-based fishless fish wider coverage within the nature category?
Plant-based fishless fish is providing developers a wider species range than tuna-only products for familiar seafood meals. Revo Foods returned THE KRAKEN to permanent European sales in July 2025 following its limited release. Its 3D extrusion technology structures fermented mycoprotein into distinct seafood formats, but commercial scale still depends on species-specific texture and cooking behavior.
- Plant-based fishless fish is projected to hold 84.6% of nature demand in 2026, supported by its wider species range beyond tuna.
- Plant-based protein is used across sandwiches and plated meals while separate formats preserve species-specific texture expectations.
How do refrigerated products protect texture during merchandising?
Refrigerated placement protects texture-sensitive fish alternatives and keeps them near familiar chilled proteins during routine shopping. Schouten Europe introduced plant-based tuna in September 2025 with chilled professional packs and a three-month minimum shelf life. Those formats support prepared-food routines but require consistent bite and moisture during cold distribution.
- Refrigerated product is likely to capture 87.6% of merchandising format demand in 2026, influenced by texture protection and chilled placement.
- Cold-chain control increases logistics requirements but gives retailers consistent chilled placement beside familiar proteins during routine shopping.
How does soy protein support structured fish alternatives within the source category?
Formulators are using soy protein ingredients as a concentrated base for structured fish alternatives that need stable bite during cooking. Protein Industries Canada announced a May 2026 project supplying clean-label soy proteins for expanded whole-cut meat and fish production. The project ties soy functionality to scalable structure, but fish-style applications still require controlled flake and moisture.
- Soy-based protein is forecast to represent 34.6% of source demand in 2026, reinforced by established texturization functionality in structured fish alternatives.
- Developers are using pea protein or wheat protein for formulations that require different gelation and bite characteristics in selected seafood formats.
How does retail support trial and repeat purchasing within distribution channels?
Retail places plant-based fish beside products shoppers already compare on price and preparation during ordinary grocery trips. GFI Europe recorded 8.9% retail value growth for UK plant-based seafood during 2025 in grocery channels. Retailers can use the seafood-specific result when reviewing categories and shelf productivity. Suppliers still need dependable quality and stock between shopping trips.
- Retail is anticipated to retain 53.1% of distribution channel demand in 2026, linked to household repurchase and measurable shelf productivity.
- Foodservice supports chef-led trial and retail provides a larger base for testing pack price and household repurchase.
What are the drivers, restraints and opportunities in the Plant-based Fish Market?
Familiar seafood occasions support substitution demand despite price and sensory gaps, and clearer labels can reduce commercial review friction.
- Driver: Familiar seafood meals are increasing demand because consumers already recognize preparation and serving occasions.
- Restraint: Persistent price premiums and sensory gaps are reducing unit velocity despite adequate retailer distribution.
- Opportunity: Clearer naming rules can reduce label ambiguity as manufacturers improve taste and format performance for commercial review.
Established seafood occasions give suppliers a defined substitution target
GFI reported that 11% of USA households bought plant-based meat and seafood in 2025 and 62% purchased more than once. The 62% repeat rate confirms ongoing purchasing within protein products used in everyday meals. Plant-based fish suppliers are using salmon and tuna applications that require no new eating occasion. Fish-specific texture and cooking performance still determine whether household familiarity converts into repeat purchases.
Price and sensory gaps can interrupt the path from trial to repeat purchase
USA plant-based meat and seafood unit sales fell 11% in 2025 according to GFI. The same analysis found most products priced one to three times above conventional equivalents. Retailers are seeing slower velocity in products built around alternative protein ingredients when taste and value do not justify the premium. Fish-style products face an additional texture benchmark because shoppers compare flake and moisture directly with conventional seafood. Cost reduction has commercial value alongside reformulation that protects eating quality.
Label clarity creates a practical route for product naming and retailer review
USA manufacturers are applying the framework to seafood alternatives made with textured vegetable protein or blended sources during retailer review. FDA draft guidance issued in January 2025 covers plant-based alternatives to animal-derived foods including seafood. The guidance recommends clear food names and identification of predominant plant sources for products without a common name. Clearer labels can reduce packaging rework and approval delays. Clearer naming can shorten commercial review without treating regulation as a source of consumer demand.
Which country CAGRs are profiled in the Plant-based Fish Market?
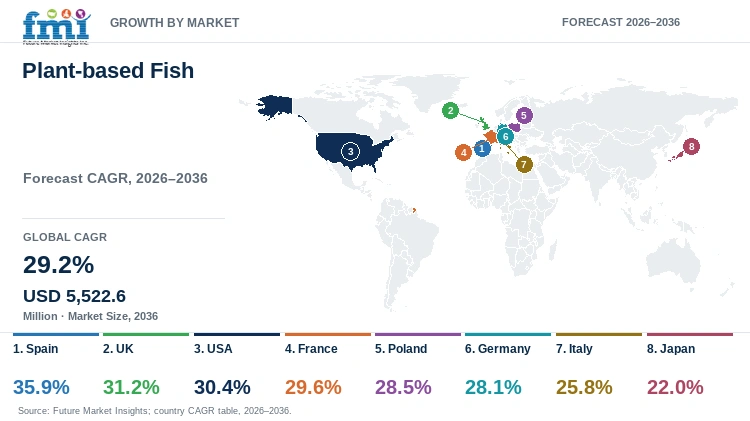
| Country | CAGR |
|---|---|
| Spain | 35.9% |
| UK | 31.2% |
| USA | 30.4% |
| France | 29.6% |
| Poland | 28.5% |
| Germany | 28.1% |
| Italy | 25.8% |
| Japan | 22.0% |
How do country-level CAGRs compare in the Plant-based Fish Market?
The eight profiled CAGRs span 13.9 percentage points from Spain to Japan. Spain and the UK exceed 30%. France and Poland remain near the global 29.2% rate with Germany at 28.1%. These percentages describe growth from each country's own base instead of current market-size rank.
- Spain's alternative-protein familiarity lets retailers test seafood formats without teaching shoppers the plant-based proposition.
- UK plant-based seafood retail value rose 8.9% in 2025, supporting further category tests.
- USA labeling guidance makes product naming and plant-source disclosure part of commercial review before wider retail distribution.
- French private-label growth gives fish alternatives a lower-price route into household trial through familiar plant-based grocery shelves.
- Polish meat-reduction interest supports trial but shelf economics still determine visibility and repeat purchasing.
- German seafood-alternative volume weakness raises the sensory threshold retailers apply before they widen assortment again.
- Italian private-label participation can lower trial prices for fish alternatives that still need convincing texture.
- Japan's national food-tech work gives non-animal protein suppliers a structured domestic commercialization route.
Comparable CAGRs produce different entry conditions because category maturity and pricing pressure vary nationally. The full report provides country-level CAGR analysis across North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa.
Country-wise Analysis
- Spanish grocery buyers are facing strong price sensitivity in a category with established plant-based exposure. Plant-based fish sales in Spain are forecast to expand at 35.9% CAGR by 2036, influenced by familiar plant-based grocery purchasing and persistent price pressure. GFI Europe found plant-based meat volume fell 7.0% in 2025 and cost more than twice conventional meat. The national price gap keeps affordable fish-style packs important during direct comparison with conventional products. Suppliers need familiar formats and lower pack-price exposure to convert household trial into routine repeat purchasing.
- UK retailers are working from measurable plant-based seafood growth recorded in 2025. Plant-based fish demand in the UK is forecast to rise at 31.2% CAGR over the forecast period, supported by category-specific retail progress. GFI Europe measured 8.5% unit growth and 13.7% volume growth for UK plant-based seafood during 2025. Retailers are comparing new formats against an established category baseline.
- USA households are buying plant-based and conventional proteins during the same shopping cycle. Adoption of plant-based fish in the USA is estimated to expand at 30.4% CAGR through 2036, influenced by direct cross-shopping with conventional proteins. GFI reported that 96% of households buying plant-based meat in 2025 also purchased conventional meat. Retailers are testing fish alternatives against immediate taste and price comparisons. Wider distribution depends on repeat velocity from products that perform well in those comparisons.
- French grocery channels are expanding substitute-protein volumes. France's plant-based fish outlook is anticipated to advance at 29.6% CAGR over the assessment period, reinforced by growing private-label participation in plant-based proteins. GFI Europe measured 16.8% plant-based meat volume growth in 2025 and private labels reached 22% of category volume. National retailers are testing lower-priced plant-based proteins through established grocery programs. Fish-style products can use those programs when taste and cooking performance justify shelf space beside conventional seafood.
- Polish retailers are serving a growing flexitarian buyer base but plant-based assortment remains smaller than in western European grocery markets. Poland is estimated to post 28.5% CAGR over the forecast period, shaped by consumer efforts to reduce animal protein. The Polish Plant-Based Food Producers Association reported in 2025 that 44% of consumers were reducing meat intake. Fish alternatives using pea protein are competing for visible placement and accessible prices as meat-reduction interest develops into repeat purchasing.
- German retailers are applying a stricter sensory test following recent plant-based seafood volume losses. In Germany plant-based fish demand is predicted to advance at 28.1% CAGR through 2036. Reformulation needs are constraining the outlook as manufacturers improve eating quality. GFI Europe recorded a 29.4% volume decline in 2025 and linked the weakness to taste and texture gaps. Existing shelf access is not protecting repeat purchasing. Manufacturers are improving sensory performance and pricing to justify wider retailer assortment.
- Italian retailers are expanding plant-based meat volumes as lower prices make substitute proteins more accessible to routine shoppers. By 2036 Italy is projected to grow at 25.8% CAGR. Easing prices and private-label participation are supporting the outlook. GFI Europe recorded 4.1% plant-based meat volume growth in 2025 and a 2.0% decline in average price per kilogram. Retail partnerships are using that affordability pattern to reduce trial barriers. Fish-style products still need convincing texture and simple preparation to convert trial into repeat purchases.
- Japan's national food-tech program is supporting commercialization of non-animal protein products. The Japanese plant-based fish sector is projected to record 22.0% CAGR during the assessment period, enabled by organized testing and commercialization programs. MAFF held a June 2026 tasting event to expand demand for non-animal-derived protein foods and other new-food products. The program provides a domestic testing route for non-animal protein foods.
Who are the notable companies in the Plant-based Fish Market?
Revo Foods GmbH, BettaF!sh (Bayou Best Foods), Steakholder Foods Ltd., Schouten Europe B.V., Oshi Inc., New School Foods Inc., Save Da Sea Foods Inc., The Plant Based Seafood Co., Fysh Foods (City Roots Hospitality), IBIDEN Bussan Co., Ltd. are notable companies active in the defined market.
Competition divides between whole-cut developers and prepared seafood brands serving tuna or shellfish formats. Entry requires a documented fish alternative plus a current retail or foodservice route. Smaller specialists compete through product quality and channel access that sustain repeat orders.
- Revo Foods GmbH and Oshi Inc. commercialize whole-cut fillets, and New School Foods Inc. serves restaurant channels with plant-based salmon.
- BettaF!sh and Schouten Europe B.V. serve tuna formats, and Save Da Sea Foods Inc. plus Fysh Foods focus on salmon applications.
- Steakholder Foods Ltd. serves prepared fish formats, and The Plant Based Seafood Co. plus IBIDEN Bussan Co., Ltd. focus on shellfish alternatives.
Competitive Benchmarking: Plant-based Fish Market
| Company | Seafood Format Breadth | Channel Validation | Texture Process Differentiation | Geographic Reach |
|---|---|---|---|---|
| Revo Foods GmbH | High | High | High | Europe and USA online channels |
| BettaF!sh (Bayou Best Foods) | Medium | High | Medium | Europe with USA distribution under Bayou |
| Steakholder Foods Ltd. | Medium | High | High | Israel and Northeastern USA |
| Schouten Europe B.V. | Medium | High | Medium | Europe with sales to more than 50 countries |
| Oshi Inc. | Medium | High | High | USA retail, online and foodservice |
| New School Foods Inc. | Low | Medium | High | Canada foodservice with distribution partners |
| Save Da Sea Foods Inc. | Medium | High | Medium | Canada and USA foodservice activity |
| The Plant Based Seafood Co. | High | High | Medium | USA retail, e-commerce and foodservice |
| Fysh Foods (City Roots Hospitality) | Medium | Medium | Medium | New York City restaurant channels under City Roots |
| IBIDEN Bussan Co., Ltd. | Low | Medium | Medium | Japan domestic commercial and event channels |
Scoring basis: High seafood-format breadth requires at least three documented formats and Medium requires two. High channel validation requires multiple commercial routes and Medium requires one. High texture differentiation requires a proprietary structuring process and Medium requires a distinct formulation approach. Low applies to one documented format or an undifferentiated process.
Key Developments in the Plant-based Fish Market
- In September 2026, Steakholder Foods Ltd. launched the Perfecta range at Northeastern USA retailers, with the initial assortment including plant-based marbled steak, filet mignon, chicken breast, salmon patties, and white-fish patties distributed through KeHE Distributors.
- In June 2026, IBIDEN Bussan Co., Ltd. reported KIBUN Foods used its Shrimpea product in a three-day event menu.
- In June 2025, Juicy Marbles launched Kinda Cod through its USA online store, a whole-cut plant-based cod fillet developed and supplied by Revo Foods as the first product in the Juicy Marbles and Friends co-branded range.
Key Players in the Plant-based Fish Market
Whole-Cut Fish Platforms
- Revo Foods GmbH
- Oshi Inc.
- New School Foods Inc.
Prepared Fish and Tuna Specialists
- BettaF!sh (Bayou Best Foods)
- Schouten Europe B.V.
- Save Da Sea Foods Inc.
- Fysh Foods (City Roots Hospitality)
Patties and Shellfish Formats
- Steakholder Foods Ltd.
- The Plant Based Seafood Co.
- IBIDEN Bussan Co., Ltd.
Plant-based Fish Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, nature, merchandising format, source, distribution channel and region. |
| Quantitative Units | USD million. |
| Market Definition | Plant-based fish products marketed as substitutes for fish or shellfish using non-animal ingredients and sold through retail or foodservice channels. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Spain, UK, USA, France, Poland, Germany, Italy, Japan, and 20+ countries included in the full report. |
| Key Companies Profiled | Revo Foods GmbH, BettaF!sh (Bayou Best Foods), Steakholder Foods Ltd., Schouten Europe B.V., Oshi Inc., New School Foods Inc., Save Da Sea Foods Inc., The Plant Based Seafood Co., Fysh Foods (City Roots Hospitality), IBIDEN Bussan Co., Ltd. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Plant-based Fish Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained when credible public evidence supported them. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Plant-based Fish Market by Segments
Plant-based Fish Market segmented by Product Type:
- Burger Patty
- Filets
- Steaks
- Fishcakes
- Crumbles and Grounds
- Slices & Strips
- Cutlet
- Fingers
Plant-based Fish Market segmented by Nature:
- Plant-based Fishless Fish
- Plant-based Tuna
Plant-based Fish Market segmented by Merchandising Format:
- Refrigerated Product
- Plant-based Ambient Foods
Plant-based Fish Market segmented by Source:
- Soy-based Protein
- Pea-based Protein
- Wheat-based Protein
- Rice-based Protein
- Canola-based Protein
- Corn-based Protein
- Potato-based Protein
- Lentil-based Protein
Plant-based Fish Market segmented by Distribution Channel:
- Retail
- HoReCa (Food Service Sector)
- Online Retail
Plant-based Fish Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- The Good Food Institute. (2026). State of the Industry: Plant-based meat, seafood, eggs, dairy, and ingredients.
- The Good Food Institute Europe. (2026, June 9). European plant-based sales data.
- Steakholder Foods Ltd. (2025, July 14). First Steakholder Formulated Plant Based Fish Products Rolled Out in Retail Outlets.
- Revo Foods GmbH. (2025, July 9). THE KRAKEN RETURNS.
- Schouten Europe B.V. (2025, September 30). Schouten Europe introduces innovative new plant-based tuna.
- Protein Industries Canada. (2026, May 21). Scaling manufacturing technology that develops whole-cut meat and fish alternatives.
- USA Food and Drug Administration. (2025, January). Draft Guidance for Industry: Labeling of Plant-Based Alternatives to Animal-Derived Foods.
- Polish Plant-Based Food Producers Association. (2025, February). The plant-based food industry in Poland 2024 - data, opportunities and challenges.
- Juicy Marbles. (2025, June 18). Kinda Cod: flaky plant-based fish filet.
- IBIDEN Bussan Co., Ltd. (2026, June 23).
- Steakholder Foods Ltd. (2026, September 3). Steakholder Foods Launches Perfecta™ at Retail Outlets Across the Northeastern USA
- Flag K Kosher. (2025, May 19). Oshi Inc. Flag K Kosher Certificate.
- Steakholder Foods Ltd. (2026, July 6). Steakholder Foods Accelerates USA Market Entry of Perfecta™ Premium Plant-Based Meat.
- Mind Blown. (2025, March 26). Mind Blown! Iconic 85-Year-Old Wintzell's Oyster House Adds Plant Based Seafood To Its Menu.
- Oshi Inc. (2026). Wefunder issuer Q&A: retail launch update. Retrieved September 17, 2026.
- Schouten Europe B.V. (2026, March 19). Visit Schouten at PLMA 2026.
- Steakholder Foods Ltd. (2025, July 28). Steakholder Foods receives positive international search report for patent covering HD144 fish printer.
- Revo Foods GmbH. (2025, April). EL BLANCO - Inspired by Black Cod.
- Food Business News. (2026, July 7). Bayou Best Foods reels in BettaF!sh.
- Steakholder Foods Ltd. (2026, July 14). Steakholder Foods Commences USA Market Entry of Perfecta™ Premium Plant-Based Meat.
- Schouten Europe B.V. (2025, March 18). Schouten Europe launches two innovative plant-based snacks: Power Bites and Sea Bites.
- USA Securities and Exchange Commission. (2026, May 18). Oshi Inc. Form C.
- AgFunderNews. (2025, May 22). New School Foods scales ‘directional freezing’ tech to make next generation of plant-based whole cuts.
- Simon Fraser University. (2026, September 16). Creating Plant-Based Seafood With Save Da Sea.
- Mind Blown. (2025, October 8). Mind Blown Expands Foodservice Lineup with Award-Winning Dusted Scallops on WebstaurantStore.
- City Roots Hospitality. (2026, August 31). City Roots Hospitality Acquires Fysh Foods, Zoya Biglary's Plant-Based Seafood Brand.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the plant-based fish market in 2026 and 2036?
- What commercial conditions support the plant-based fish forecast through 2036?
- Which product type holds 39.6% of the 2026 category demand mix?
- How do nature and merchandising formats change product selection decisions?
- Which source and distribution channel hold the largest 2026 shares?
- Which sensory and pricing conditions limit repeat plant-based fish purchases?
- How do country growth rates differ across the profiled national markets?
- Which companies currently supply documented plant-based fish or shellfish products?
Frequently Asked Questions
How big is the Plant-based Fish Market in 2026?
The plant-based fish market is valued at USD 424.5 million in 2026 and is projected to reach USD 5522.6 million by 2036. Familiar seafood meals provide a substitution route, but taste and pricing determine repeat purchasing.
What is the CAGR of the Plant-based Fish Market from 2026 to 2036?
The plant-based fish market is projected to grow at 29.2% CAGR from 2026 to 2036. Repeat purchasing depends on credible fish-like texture and practical pricing in familiar seafood meals.
Which product type holds the largest estimated share in the Plant-based Fish Market?
The burger patty segment is estimated to hold 39.6% of product type demand in the plant-based fish market during 2026. Standardized portions support household cooking and commercial menu costing by reducing handling variation.
How much value will the Plant-based Fish Market add between 2026 and 2036?
The plant-based fish market is expected to add USD 5098.1 million between 2026 and 2036. The increase depends on stronger sensory performance and stable channels that can sustain repeat purchasing.
Which companies are active in the Plant-based Fish Market?
Active companies include Revo Foods GmbH and BettaF!sh (Bayou Best Foods). Steakholder Foods Ltd. and Schouten Europe B.V. also document active plant-based fish routes. Oshi Inc. and New School Foods Inc. supply whole-cut fish formats. Save Da Sea Foods Inc. and The Plant Based Seafood Co. serve prepared seafood applications. Fysh Foods (City Roots Hospitality) and IBIDEN Bussan Co., Ltd. complete the profiled supplier set.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Burger Patty
- Filets
- Steaks
- Fishcakes
- Crumbles and Grounds
- Slices & Strips
- Cutlet
- Fingers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Plant-based Fishless Fish
- Plant-based Tuna
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Merchandising Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Merchandising Format, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Merchandising Format, 2026 to 2036
- Refrigerated Product
- Plant-based Ambient Foods
- Y-o-Y Growth Trend Analysis By Merchandising Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Merchandising Format, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Source, 2026 to 2036
- Soy-based Protein
- Pea-based Protein
- Wheat-based Protein
- Rice-based Protein
- Canola-based Protein
- Corn-based Protein
- Potato-based Protein
- Lentil-based Protein
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Retail
- HoReCa (Food Service Sector)
- Online Retail
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Nature
- By Merchandising Format
- By Source
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Revo Foods GmbH
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- BettaF!sh (Bayou Best Foods)
- Steakholder Foods Ltd.
- Schouten Europe B.V.
- Oshi Inc.
- New School Foods Inc.
- Save Da Sea Foods Inc.
- The Plant Based Seafood Co.
- Fysh Foods (City Roots Hospitality)
- IBIDEN Bussan Co., Ltd.
- Revo Foods GmbH
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


