

- Market Size (2026)
- USD 886 Mn
- Forecast (2036)
- USD 1510 Mn
- CAGR (2026 to 2036)
- 5.5%
How big is Pharmaceutical Lactose Market in 2026?
USD 886 million in 2026 and USD 1,510 million by 2036 at a 5.5% CAGR.
Demand for pharmaceutical lactose is projected to rise at a 5.5% CAGR from about USD 840 million in 2025 to USD 886 million in 2026. Industry valuation is forecast to reach USD 1510 million by 2036 as oral manufacturers qualify pharmaceutical excipients for recurring tablet and capsule production. FDA recorded 689 generic-drug approvals during FY 2025, keeping formulation and change-control work active across new strengths and commercial line extensions.
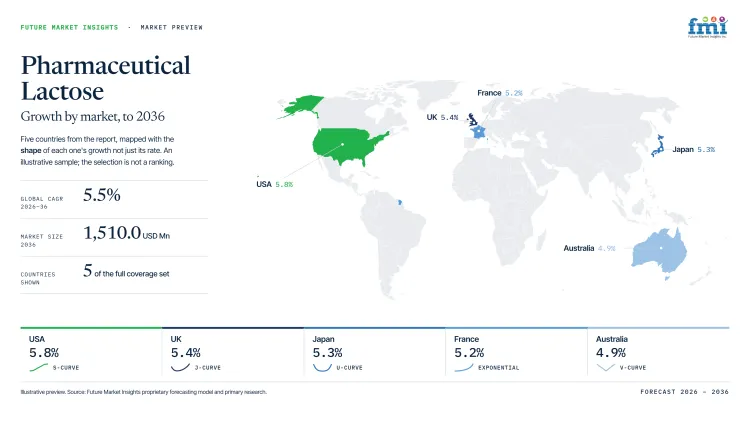
The United States and United Kingdom follow different medicine approval routes despite comparable pharmaceutical lactose growth expectations. The United States is expected to rise at 5.8% CAGR while the United Kingdom is projected at 5.4% through 2036. MHRA approved more than 2,000 medicine licences during 2024-25 as oral solid dosage documentation remained central to commercial changes. Different review routes alter change-control timing for the same qualified lactose grade without changing its pharmaceutical function.
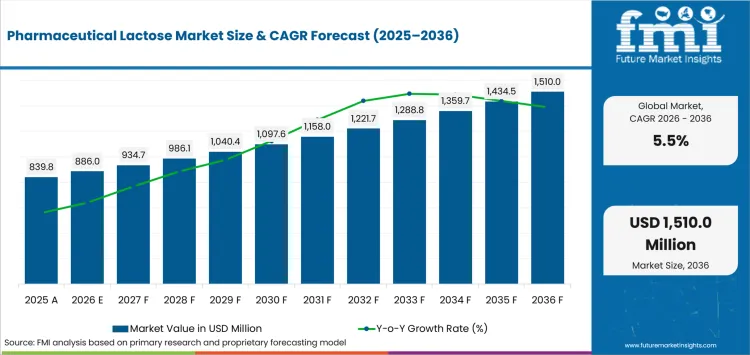
Key Takeaways of Pharmaceutical Lactose Market
- Recurring tablet and capsule production sustains pharmaceutical lactose demand as validated excipients remain embedded across established oral manufacturing routes.
- Based on product type, monohydrate lactose is projected to account for 58.0% in 2026 due to familiar granulation routes and broad pharmacopoeial use.
- In 2026, tablets are expected to lead dosage-form demand with 65.0% share because lactose fits established high-volume compression routes alongside other sugar-based excipients used in oral formulations.
- The diluent and filler segment is likely to capture 52.0% share in 2026 attributable to controlled bulk requirements in low-dose formulations.
- Nitrite control and API compatibility add qualification work as lactose attributes must remain suitable for each drug substance and manufacturing route.
- DFE Pharma, Kerry Group plc, MEGGLE GmbH & Co. KG, Armor Proteines SAS (ARMOR PHARMA), Lactalis Ingredients Pharma, Lactose (India) Limited, Gangwal Healthcare Pvt. Ltd. and International Ingredients & Excipients Pvt. Ltd. serve the market.
Analyst Perspective
"Pharmaceutical teams should compare lactose grades against the exact process that must be reproduced at commercial scale. Particle distribution, nitrite control and API compatibility decide whether a lower-priced grade reduces cost or simply shifts work into qualification and change control."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Pharmaceutical Lactose Market segmented?
The pharmaceutical lactose market is segmented by product type, dosage form, function, manufacturing process and region.
Product types include monohydrate lactose, anhydrous lactose, spray-dried lactose and specialty lactose. Dosage forms cover tablets, capsules, dry powder inhalers, sachets and powders, and other solid dosage forms. Functions include diluent and filler, binder and compression aid, inhalation carrier, and bulking and processing aid. Manufacturing processes cover wet granulation, dry granulation, direct compression, capsule and sachet filling, and inhalation blending.
How do pharmaceutical manufacturers evaluate tablets within the dosage form category?
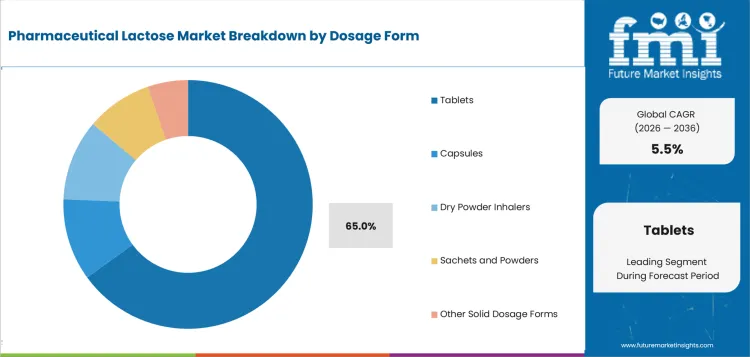
Tablet production concentrates lactose demand because excipient flow and compaction affect die filling, tablet weight and dose uniformity at commercial press speeds.
- Tablets are likely to capture 65.0% share in 2026 attributable to high-volume compression use across established oral formulations.
- Kerry reported in June 2025 that lactose appears in an estimated 60% to 70% of oral medicines. Its direct-compression analysis links grade flow and compressibility with fewer processing stages for moisture-sensitive APIs. Tablet teams therefore qualify lactose against press speed and API loading instead of treating every grade as interchangeable with empty capsules or other filling routes.
What supports demand for monohydrate lactose within the product type category?
Monohydrate lactose gives formulators a familiar crystalline excipient for granulation and filling processes that need controlled particle size. EXCiPACT certified Lactose India’s Gujarat site in May 2025 for manufacturing lactose monohydrate as a pharmaceutical excipient. The certification ties this product form to site-level GMP controls that formulation teams review during pharmaceutical qualification of refined lactose grades.
- By product type, monohydrate lactose is estimated to hold 58.0% in 2026 owing to established wet-granulation and capsule-filling practice.
- Formulation teams compare particle-size grades against flow and compaction targets since manufacturing performance differs across grades despite familiar lactose chemistry.
What role does diluent and filler play within the function category?
Low-dose formulations need sufficient excipient mass to produce a uniform unit without diluting API control during scale-up. Lactalis Ingredients Pharma explained in June 2026 that lactose aids wetting and API dispersion during tablet disintegration in oral solids. The formulation role remains distinct from lactose derivatives used for technical or nutritional purposes.
- Diluent and filler is projected to hold 52.0% share in 2026, reflecting the controlled bulk requirements that low-dose tablets and capsules place on excipient selection.
- Formulation scientists test lactose against each API for compatibility and impurity risk, separating its bulk function from the chemistry that determines whether a grade can enter commercial use.
What drives direct compression within the manufacturing process category?
Direct compression removes granulation stages but places more responsibility on powder flow and compactibility during scale-up. Formulation teams compare grade behavior as they consider replacing an established granulation route. That trade-off becomes most visible on high-speed tablet presses using moisture-sensitive or heat-sensitive APIs.
- By manufacturing process, direct compression is forecast to represent 34.0% in 2026 driven by fewer unit operations and shorter processing sequences.
- Armor Pharma published a September 2024 study comparing granulated lactose with superdisintegrants under direct-compression conditions. Formulators use these compaction comparisons to judge whether high-potent oral dosage formulations can maintain blend uniformity and tablet strength as API loading changes during scale-up.
What are the drivers, restraints and opportunities in the Pharmaceutical Lactose Market?
Generic and novel medicine output supports recurring lactose qualification while nitrite and API compatibility raise testing demands, leaving formulation services as a practical route to faster grade selection.
- Driver: Generic and novel drug pipelines require fresh lactose qualification across new oral solid products and lifecycle changes.
- Restraint: Nitrite limits and API-specific reactions add analytical work during lactose grade qualification for commercial production.
- Opportunity: Application laboratories shorten grade selection by linking particle attributes with compression, inhalation and stability testing.
Medicine Approvals Sustain Recurring Excipient Qualification
Each new oral dosage form adds an excipient decision once the active ingredient is fixed for development. FDA approved 46 novel drugs during 2025, and every program then moves into formulation choices that determine filler performance and manufacturability. Pharmaceutical lactose manufacturers gain recurring work from grades that transfer from development batches into validated tablet or capsule production without forcing unnecessary reformulation.
Nitrite and API Compatibility Increase Qualification Work
Nitrite content matters most in formulations containing an API or another component that contributes amines during nitrosamine formation. Armor Pharma reported in April 2026 that its Eurofins France method quantifies nitrite in lactose down to 30 ppb. Formulation teams therefore need measured impurity data plus API compatibility evidence during lactose substitution in sensitive products and commercial change control.
Application Support Can Shorten Grade Selection
Application laboratories reduce trial work as drug manufacturers choose a lactose grade for commercial scale-up and transfer. DFE Pharma expanded its Hyderabad C2F center in January 2025 with analytical services for dry powder inhalers. Development teams compare particle behavior and aerosol performance earlier, which reduces avoidable repeat testing as projects move into inhalation CDMO transfer and commercial process qualification work.
Which country CAGRs are profiled in the Pharmaceutical Lactose Market?
| Country | CAGR |
|---|---|
| United States | 5.8% |
| United Kingdom | 5.4% |
| Japan | 5.3% |
| France | 5.2% |
| Australia | 4.9% |
How do country-level CAGRs compare in the Pharmaceutical Lactose Market?
The 0.9-point range forms one compact growth band with a modest step between the United States and the remaining markets. The United Kingdom and Japan occupy the middle while France and Australia form a lower pair. These forecasts describe expansion pace rather than current revenue scale while regulatory practice explains spacing.
- United States review volume keeps lifecycle submissions active across established oral-solid portfolios.
- United Kingdom recognition routes reward complete quality packages during medicine licence changes.
- Japan places manufacturing changes inside formal postapproval planning for chemical drug products.
- France combines domestic lactose supply with national and European pharmaceutical quality oversight.
- Australia’s M13A adoption clarifies current bioequivalence expectations for immediate-release oral medicine products.
Comparable CAGRs therefore produce different qualification and commercial entry conditions across these countries.
The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- FDA recorded 250 tentative generic approvals during FY 2025, leaving a visible pipeline of products requiring final commercial formulation and manufacturing controls across sponsor portfolios and commercial manufacturing networks. The United States pharmaceutical lactose outlook is anticipated to advance at 5.8% CAGR over the assessment period as generic portfolios move across domestic plants and contract manufacturers serving multiple strengths and presentation changes. Formulation laboratories shorten grade qualification for established products but multi-site transfers demand matching particle attributes and impurity controls across dossiers so sponsors shift recurring lactose orders without reopening avoidable formulation work during supplier changes and manufacturing site transfers.
- United Kingdom medicine licensing gives formulation teams national and recognition routes for applications and variations that depend on complete quality documentation across registered oral-solid products and commercial manufacturing changes. Pharmaceutical lactose demand in the United Kingdom is forecast to rise at 5.4% CAGR over the forecast period as contract manufacturers handle lifecycle formulation work across local and imported medicine portfolios and established generic product lines. MHRA reported 100% June 2026 performance against its 210-day national-route target, yet lactose producers need rapid technical responses and disciplined change control as grade substitutions enter formal national variation timelines well beyond original formulation approval.
- Japanese drug manufacturers manage lactose substitutions within a lifecycle system that places manufacturing parameters and postapproval changes under formal regulatory planning across registered oral-solid medicines and domestic production sites. Japan is estimated to post 5.3% CAGR over the forecast period as PMDA issued March 2026 early-consideration guidance on pre-specifying change categories for established manufacturing-process conditions in chemical drug products. Strong domestic technical review favors well-documented grades, while overseas lactose producers need repeatable particle behavior and Japanese change-control packages so plant teams switch between granulation or direct-compression routes without adding comparability work to approved formulations during routine supplier and site changes.
- France combines domestic pharmaceutical lactose production with national and European authorization routes that keep qualified material close to oral-solid manufacturers, while ANSM completed 514 inspections during 2025 across regulated health products. France's pharmaceutical lactose sector is projected to record 5.2% CAGR during the assessment period as local production and active quality oversight sustain established medicine portfolios and regional contract manufacturing networks. Local supply improves technical access and inventory visibility, but a lactose grade change requires compatibility evidence and documented particle controls that fit the registered dossier so French plants switch sources without adding avoidable variation work during routine lifecycle changes.
- Australian medicine sponsors work under TGA guidance that adopted 19 international scientific guidelines in May 2025, including ICH M13A for immediate-release oral products and related bioequivalence expectations for national medicine applications and variations. Adoption of pharmaceutical lactose in Australia is estimated to expand at 4.9% CAGR through 2036 as formulation teams align lactose changes with registration requirements across established oral-solid portfolios and imported commercial material routes. TGA guidance gives development teams a clearer evidence path, but deviations require justification and lactose substitutions still need local dossier control before imported grades enter routine production across geographically dispersed manufacturing and distribution networks.
Who are the notable companies in the Pharmaceutical Lactose Market?
DFE Pharma, Kerry Group plc, MEGGLE GmbH & Co. KG, Armor Proteines SAS (ARMOR PHARMA), Lactalis Ingredients Pharma, Lactose (India) Limited, Gangwal Healthcare Pvt. Ltd. and International Ingredients & Excipients Pvt. Ltd. are the notable companies serving this market.
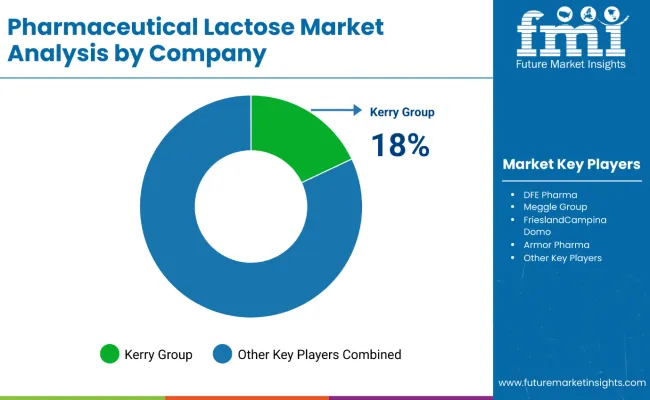
The competitive outlook remains fragmented across global lactose manufacturers and certified regional producers, with competition centered on qualification records. Manufacturers serving adjacent nutraceutical excipients need separate pharmaceutical lactose qualification because drug-product teams assess site quality records and formulation compatibility.
- DFE Pharma, Kerry Group plc and MEGGLE GmbH & Co. KG combine international supply with broad pharmaceutical lactose capabilities.
- Armor Proteines SAS (ARMOR PHARMA) and Lactalis Ingredients Pharma combine European production with application-specific grades and technical support.
- Lactose (India) Limited, Gangwal Healthcare Pvt. Ltd. and International Ingredients & Excipients Pvt. Ltd. compete on certified South Asian manufacturing and regional excipient supply.
Competitive Benchmarking: Pharmaceutical Lactose Market
| Company | Grade Breadth | Qualification Evidence | Formulation Support | Geographic Reach |
|---|---|---|---|---|
| DFE Pharma | High | High | High | Global |
| Kerry Group plc | High | High | High | Global |
| MEGGLE GmbH & Co. KG | High | High | High | Global |
| Armor Proteines SAS (ARMOR PHARMA) | High | High | High | Europe, Americas and international sales |
| Lactalis Ingredients Pharma | Medium | High | Medium | Europe and international sales |
| Lactose (India) Limited | Low | Medium | Low | South Asia and international supply |
| Gangwal Healthcare Pvt. Ltd. | Low | High | Medium | South Asia and international sales |
| International Ingredients & Excipients Pvt. Ltd. | Low | High | Low | South Asia and export markets |
Key Developments in the Pharmaceutical Lactose Market
- In February 2026, DFE Pharma launched a continuous manufacturing platform with Gericke and installed a skid at its Hyderabad C2F center.
- In December 2025, Armor Pharma introduced Lactose Monohydrate 100M as a pharmaceutical grade for capsule and sachet filling.
- In October 2025, MEGGLE introduced a lactose blend prediction tool that predicts blend uniformity and calculates component ratios for DPI formulations.
Key Players in the Pharmaceutical Lactose Market
Global Lactose and Formulation Platforms
- DFE Pharma
- Kerry Group plc
- MEGGLE GmbH & Co. KG
European Pharmaceutical Lactose Specialists
- Armor Proteines SAS (ARMOR PHARMA)
- Lactalis Ingredients Pharma
South Asian Pharmaceutical Excipient Producers
- Lactose (India) Limited
- Gangwal Healthcare Pvt. Ltd.
- International Ingredients & Excipients Pvt. Ltd.
Pharmaceutical Lactose Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, dosage form, function, manufacturing process and region. |
| Quantitative Units | Revenue in USD million and CAGR in %. |
| Market Definition | Pharmaceutical-grade lactose used as a qualified excipient or carrier across oral solid and inhalation dosage-form manufacturing. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | United States, United Kingdom, Japan, France, Australia, and 20+ countries included in the full report. |
| Key Companies Profiled | DFE Pharma, Kerry Group plc, MEGGLE GmbH & Co. KG, Armor Proteines SAS (ARMOR PHARMA), Lactalis Ingredients Pharma, Lactose (India) Limited, Gangwal Healthcare Pvt. Ltd., International Ingredients & Excipients Pvt. Ltd. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Pharmaceutical Lactose Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Pharmaceutical Lactose Market by Segments
Pharmaceutical Lactose Market segmented by Product Type:
- Monohydrate Lactose
- Anhydrous Lactose
- Spray-Dried Lactose
- Specialty Lactose
Pharmaceutical Lactose Market segmented by Dosage Form:
- Tablets
- Capsules
- Dry Powder Inhalers
- Sachets and Powders
- Other Solid Dosage Forms
Pharmaceutical Lactose Market segmented by Function:
- Diluent and Filler
- Binder and Compression Aid
- Inhalation Carrier
- Bulking and Processing Aid
Pharmaceutical Lactose Market segmented by Manufacturing Process:
- Wet Granulation
- Dry Granulation
- Direct Compression
- Capsule and Sachet Filling
- Inhalation Blending
Pharmaceutical Lactose Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- USA Food and Drug Administration. (2025, November 24). Generic Drugs Program Activities Report - FY 2025 Monthly Performance.
- Medicines and Healthcare products Regulatory Agency. (2025, July 21). MHRA's 2024-25 Annual Report and Accounts and Impact Report show progress on safety, innovation and regulatory excellence.
- EXCiPACT. (2025, May 8). Lactose India Ltd site in Gujarat, India RECEIVES EXCiPACT GMP CERTIFICATION AS PHARMACEUTICAL EXCIPIENT SUPPLIER.
- Kerry Group plc. (2025, June 2). How Sheffield™ Anhydrous DT Delivers for Pharma Tablet Manufacturers.
- Lactalis Ingredients Pharma. (2026, June 17). Solubility, Dissolution and Bioavailability.
- Armor Pharma. (2024, September 27). New Armor Pharma study! Comparison of compaction properties of granulated lactose with superdisintegrants by direct compression.
- USA Food and Drug Administration, Center for Drug Evaluation and Research. (2026, January). Advancing Health Through Innovation: New Drug Therapy Approvals 2025.
- Armor Pharma. (2026, April 29). Armor Pharma's Commitment Against Nitrosamines.
- DFE Pharma. (2025, January 13). DFE Pharma expands its C2F Center to advance the development of critical respiratory treatments.
- Medicines and Healthcare products Regulatory Agency. (2026, July 30). MHRA Performance Data.
- Pharmaceuticals and Medical Devices Agency. (2026, March 12). Considerations for Pre-specifying the Change Categories for Manufacturing Process Parameters Identified as Established Conditions for Drug Products (Chemical Products) (Early Consideration).
- Agence nationale de sécurité du médicament et des produits de santé. (2026, July 8). Rapport d'activité 2025: Les temps forts et chiffres clés.
- Therapeutic Goods Administration. (2025, May 29). Adoption of International Scientific Guidelines in Australia.
- DFE Pharma. (2026, February 17). DFE Pharma launches Continuous Manufacturing platform to accelerate and enable formulation development.
- Armor Pharma. (2025, December 10). Discover Armor Pharma's Latest Addition: Lactose Monohydrate 100M.
- MEGGLE GmbH & Co. KG. (2025, October 24). Web Tool: Predict your ideal DPI lactose blend.
- MEGGLE GmbH & Co. KG. (2026, July 9). Simplifying nitrosamine compliance with specified limit!
- Armor Pharma. (2026, June 30). Mastering lactose flowability with the Revolution Powder Analyzer.
- DFE Pharma. (2026, February 4). DFE Pharma introduces EcoLact® 2030, delivering a data-verified CO₂ reduction across its lactose portfolio.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the pharmaceutical lactose market in 2026 and what valuation is projected for 2036?
- Why do recurring oral solid dosage programs create sustained demand for pharmaceutical lactose?
- Which product type and dosage form account for the largest modelled shares in 2026?
- How do particle size and API compatibility influence pharmaceutical lactose grade selection?
- Which manufacturing conditions favor direct compression over granulation routes?
- How do regulatory pathways change lactose qualification requirements across the five profiled countries?
- Which companies combine broad lactose portfolios with current qualification or application-support evidence?
- What do recent supplier developments indicate about nitrite control, continuous manufacturing and capsule filling?
- Where can formulation services reduce qualification time for oral and inhaled pharmaceutical products?
Frequently Asked Questions
How big is the Pharmaceutical Lactose Market in 2026?
The pharmaceutical lactose market is valued at USD 886 million in 2026 and is projected to reach USD 1510 million by 2036. Recurring tablet and capsule production ties qualified lactose grades to validated oral-solid manufacturing records.
What is the CAGR of the Pharmaceutical Lactose Market from 2026 to 2036?
The pharmaceutical lactose market is projected to grow at a 5.5% CAGR between 2026 and 2036. Generic and novel medicine programs sustain recurring excipient qualification across established oral-solid manufacturing routes.
Which product type leads the Pharmaceutical Lactose Market?
Monohydrate lactose is projected to account for 58.0% of the pharmaceutical lactose market by product type in 2026. Its share reflects established wet-granulation and capsule-filling use across qualified oral-solid formulations.
How much value will the Pharmaceutical Lactose Market add between 2026 and 2036?
The pharmaceutical lactose market is expected to add USD 624 million in value between 2026 and 2036. The increase reflects wider recurring use of qualified lactose grades across oral-solid and inhalation formulation programs.
Which companies are active in the Pharmaceutical Lactose Market?
The pharmaceutical lactose market includes DFE Pharma, Kerry Group plc, MEGGLE GmbH & Co. KG, Armor Proteines SAS (ARMOR PHARMA) and Lactalis Ingredients Pharma. Lactose (India) Limited, Gangwal Healthcare Pvt. Ltd. and International Ingredients & Excipients Pvt. Ltd. add certified manufacturing options.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Type, 2026 to 2036
- Monohydrate Lactose
- Anhydrous Lactose
- Spray-Dried Lactose
- Specialty Lactose
- Monohydrate Lactose
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Dosage Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Dosage Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Dosage Form, 2026 to 2036
- Tablets
- Capsules
- Dry Powder Inhalers
- Sachets and Powders
- Other Solid Dosage Forms
- Tablets
- Y-o-Y Growth Trend Analysis By Dosage Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Dosage Form, 2026 to 2036
- Global Market Analysis and Forecast, By Function, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Function, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Function, 2026 to 2036
- Diluent and Filler
- Binder and Compression Aid
- Inhalation Carrier
- Bulking and Processing Aid
- Diluent and Filler
- Y-o-Y Growth Trend Analysis By Function, 2021 to 2025
- Absolute $ Opportunity Analysis By Function, 2026 to 2036
- Global Market Analysis and Forecast, By Manufacturing Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Manufacturing Process, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Manufacturing Process, 2026 to 2036
- Direct Compression
- Wet Granulation
- Dry Granulation
- Capsule and Sachet Filling
- Inhalation Blending
- Direct Compression
- Y-o-Y Growth Trend Analysis By Manufacturing Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Manufacturing Process, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Dosage Form
- By Function
- By Manufacturing Process
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- DFE Pharma
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Kerry Group plc
- MEGGLE GmbH & Co. KG
- Armor Proteines SAS (ARMOR PHARMA)
- Lactalis Ingredients Pharma
- Lactose (India) Limited
- Gangwal Healthcare Pvt. Ltd.
- International Ingredients & Excipients Pvt. Ltd.
- DFE Pharma
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


