
- Market Size (2026)
- USD 5.8 Bn
- Forecast (2036)
- USD 9.4 Bn
- CAGR (2026 to 2036)
- 4.9%
How big is Pharmaceutical Lipids Market in 2026?
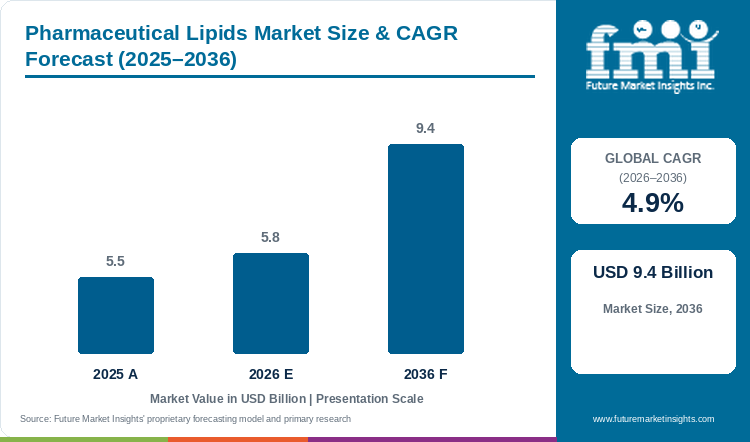
Assessed at USD 5.5 billion in 2025 and progressing to USD 5.8 billion in 2026, the pharmaceutical lipids market valuation is on course to reach USD 9.4 billion by 2036, supported by a forecast-period CAGR of 4.9%.
FMI projects that the global pharmaceutical lipids market value will advance from USD 5.5 billion during 2025 to USD 5.8 billion for 2026 and hit USD 9.4 billion in 2036 with a 4.9% CAGR, with medium- and long-chain triglycerides capturing 44.1% of 2026 chemical class demand. This 4.9% growth rate is steadier than the 8.7% CAGR of wider functional and nutritional lipid ingredients since drugmakers must complete strict purity testing and FDA Drug Master File audits before qualifying a supplier. Higher production of poorly soluble oral pills and RNA vaccines is driving pharmaceutical lipid demand. For instance, in August 2026, Evonik Industries began expanding its Vancouver GMP lipid plant with Canadian federal support to more than triple commercial lipid capacity by 2029. However, multi-step custom synthesis and sub-zero storage costs restrain margins, so growth depends on ready-to-use lipid blends.
Key Market Trends & Insights
- By lipid chemical class: Medium- and long-chain triglycerides are projected to capture 44.1% in 2026, driven by caprylic and capric glyceride solubilization of BCS Class II and IV actives.
- By physical form: Semi-solid waxy matrices and pastes are estimated to command 62.1% in 2026, supported by melt-granulated sustained-release tablets and capsule fills.
- By origin source: Semi-synthetic GMP-purified lipids are expected to concentrate 50.3% in 2026, enabled by transesterified vegetable glycerides that meet narrow compendial limits.
- By drug-delivery application: Oral lipid-based SEDDS and SMEDDS softgels and bioavailability enhancers are forecast to generate 43.1% in 2026 due to commercial oral oncology capsule volume.
- By end user: Pharmaceutical and biopharmaceutical manufacturers are anticipated to account for 65.7% in 2026, reinforced by commercial-scale oral softgel and parenteral liposome production.
Regional Highlights
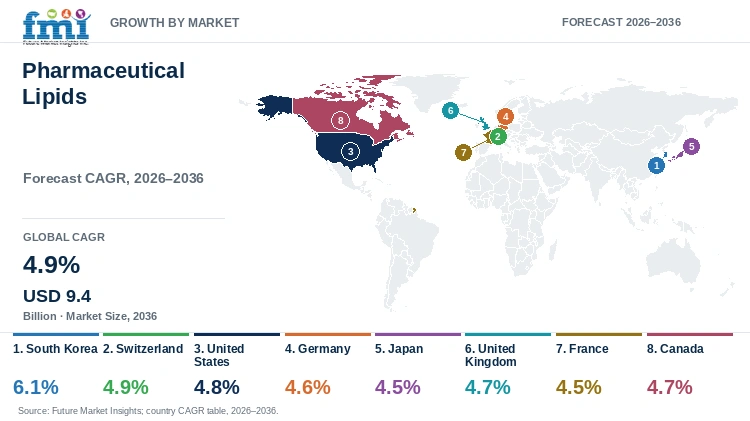
- Top national expansion: South Korea paces major pharmaceutical manufacturing nations with a 6.1% CAGR to 2036 on domestic cGMP lipid synthesis investments and AI-assisted LNP design.
- Broader country progression: Switzerland registers a 4.9% CAGR through 2036 followed by the United States at 4.8% and Germany at 4.6% with Japan at 4.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Pharmaceutical Lipids Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.5 billion |
| Estimated Market Size in 2026 | USD 5.8 billion |
| Projected Market Size by 2036 | USD 9.4 billion |
| CAGR, 2026 to 2036 | 4.9% |
| Added Market Value, 2026 to 2036 | USD 3.6 billion |
Demand for high-purity pharmaceutical lipids is expanding across both fast-growing South Korean contract biologics plants and established Swiss and German oral drug factories. For instance, in March 2026, Croda International Plc reported 7.7% constant-currency Life Sciences sales growth in its 2025 Annual Report after expanding cGMP lipid plants across Western and Asian hubs. Drugmakers now sign multi-year contracts for purified natural and synthetic phospholipids before Phase 3 trials.
Formulation-Batch and Excipient-Tonnage Sizing
Table 2: Formulation-Batch and Excipient-Tonnage Sizing for the Pharmaceutical Lipids Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.5 | 5.8 | 9.4 |
| Commercial & clinical lipid batches (thousand) | 18.5 to 21.0 | 19.5 to 22.2 | 31.0 to 35.5 |
| Oral & topical lipid volume (thousand MT) | 142.0 to 158.0 | 148.0 to 165.0 | 215.0 to 240.0 |
| Parenteral cGMP LNP/liposome lipid share (%) | 36.5% to 38.0% | 37.2% to 38.8% | 42.0% to 44.5% |
Operational note: Tonnage and batch ranges reconcile multi-ton oral triglyceride softgel consumption against high-value gram-to-kilogram cGMP ionizable and pegylated lipid demand in parenteral nanoparticles.
Oral softgel capsule manufacturers require low-peroxide triglyceride and lecithin oils that keep hydrophobic drugs dissolved without making gelatin capsule shells brittle during shelf storage. Contract softgel plants qualify multi-compendial fractionated lecithin and phospholipid carriers to produce stable oral oncology, antiviral, and immunosuppressant capsules.
Per Capita & Pharmaceutical Plant Sizing
Table 3: Per Capita and Formulation Plant Allocation Indicators for the Pharmaceutical Lipids Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Market value per 1,000 people (USD) | 670.7 | 698.8 | 1,044.4 |
| Oral glyceride excipient price range (USD/kg) | 12.0 to 85.0 | 12.5 to 88.0 | 15.0 to 110.0 |
| Parenteral cGMP phospholipid/LNP share (%) | 37.0% to 38.5% | 37.5% to 39.0% | 42.5% to 45.0% |
Table 4: Manufacturing Plant & Application Allocation Indicators for the Pharmaceutical Lipids Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 5.8 billion | 2026 global market value baseline |
| Pharma & CDMO formulation plants | 4,800 facilities | Global cGMP oral softgel, liposome, and LNP plant registry |
| Average lipid allocation per plant | USD 1,208,333 | Annualized pharmaceutical lipid excipient procurement per plant |
| Oral SEDDS/SMEDDS application value, 2026 | USD 2.5 billion | 43.1% drug-delivery application segment allocation |
Higher clinical investment in mRNA vaccines and gene therapies is driving biopharma demand for high-purity cholesterol, helper phospholipids, and ionizable lipids that protect fragile RNA strands. Formulation teams blend these purified lipids into engineered lipid nanoparticle delivery systems for sterile injectable vials.
Analyst Perspective
"Pharmaceutical excipient procurement divides between multi-ton semi-synthetic glyceride matrices for oral BCS Class II solubilization and custom cGMP ionizable lipids for extrahepatic RNA delivery. Lipid manufacturers that pair US FDA Drug Master Files with low-peroxide stability and PEG-free stealth alternatives will win long-term commercial supply locks through 2036."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the pharmaceutical lipids market segmented?
The pharmaceutical lipids market is segmented by five primary commercial axes (lipid chemical class, physical form, origin source, drug-delivery application, and end user) and region. In 2026, medium- and long-chain triglycerides are projected at 44.1%, semi-solid waxy matrices at 62.1%, semi-synthetic GMP-purified lipids at 50.3%, oral lipid-based SEDDS and SMEDDS softgels at 43.1%, and pharmaceutical and biopharmaceutical manufacturers at 65.7%.
By lipid chemical class: medium- and long-chain triglycerides, phospholipids (lecithin, DSPC, HSPC, and DSPE-PEG), ionizable, cationic, and PEGylated lipids for LNP, and cholesterol, sphingolipids, and fatty acid esters.
By physical form: semi-solid waxy matrices and pastes, high-purity liquid oils, and lyophilized and crystalline powders.
By origin source: semi-synthetic GMP-purified lipids, fully synthetic custom lipids, and natural plant and egg-yolk extracted lipids.
By drug-delivery application: oral lipid-based SEDDS and SMEDDS softgels and bioavailability enhancers, mRNA, siRNA, and gene-therapy lipid nanoparticles, liposomal parenteral oncology and amphotericin formulations, and topical, suppository, and ophthalmic emulsions.
By end user: pharmaceutical and biopharmaceutical manufacturers, contract development and manufacturing organizations, and academic and research institutes.
Why do medium- and long-chain triglycerides lead lipid chemical class demand?
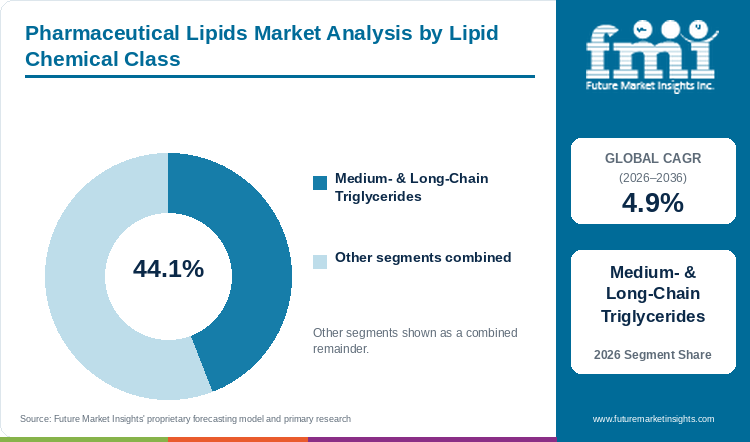
By lipid chemical class, medium- and long-chain triglycerides are estimated to hold 44.1% in 2026, driven by softgel solubilization.
Table 5: Lipid Chemical Class Share for the Pharmaceutical Lipids Market (percentage share), 2026
| Lipid Chemical Class | Share (2026) |
|---|---|
| Medium- & Long-Chain Triglycerides | 44.1% |
| Other Lipid Chemical Classes Combined | 55.9%* |
| Total | 100.0% |
*Note: Remaining lipid chemical class categories sum to 100.0% of 2026 market value.
Table 6: Lipid Chemical Class Leadership and Market Growth for the Pharmaceutical Lipids Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.9% |
| Leading Segment | Medium- & Long-Chain Triglycerides |
Oral drug formulators buy large volumes of medium- and long-chain triglycerides because caprylic and capric oils easily dissolve poorly water-soluble drugs and improve gut absorption. Injectable drugmakers also use purified soy phospholipids in bilayer liposomal drug carriers for hospital cancer and antifungal infusions.
- Medium- and long-chain triglycerides are set to lead the lipid chemical class category with 44.1% share in 2026, supported by high-tonnage consumption across oral softgels and parenteral fat emulsions.
- For instance, an April 2026 study in the International Journal of Pharmaceutics showed that a Capryol 90 self-emulsifying lipid formula (SEDDS F6) boosted intestinal drug absorption 2.51-fold within two hours and raised peak blood levels 1.28-fold.
What supports semi-solid waxy matrices and pastes as the preferred physical form?
In 2026, semi-solid waxy matrices and pastes are expected to lead physical form with 62.1% share, supported by melt extrusion.
Tablet and capsule plants prefer semi-solid waxy lipid matrices and pastes because these excipients melt cleanly between 33 and 70 degrees Celsius without needing hazardous organic solvents. Biologics plants also pair waxy lipid esters with parenteral biologic formulation excipients to keep sensitive proteins stable.
- Within the physical form category, semi-solid waxy matrices and pastes are likely to secure 62.1% share in 2026, associated with solvent-free melt granulation and capsule filling.
- Per technical guidelines published by Gattefossé SAS in November 2025, semi-solid Gelucire and Labrasol ALF with Compritol lipid matrices improve oral drug solubility and mask bitter tablet taste while controlling sustained drug release.
How are semi-synthetic GMP-purified lipids gaining use by origin source?
By origin source, semi-synthetic GMP-purified lipids are forecast to represent 50.3% in 2026, owing to reproducible fatty acid esterification.
Pharmaceutical buyers favor semi-synthetic GMP-purified lipids made from refined plant oils because controlled esterification delivers consistent batch purity and avoids animal virus risks. Formulators combine these purified lipids with high-purity pharmaceutical stabilizer excipients to prevent oil oxidation during multi-year storage.
- Semi-synthetic GMP-purified lipids are forecast to top origin source demand at 50.3% share in 2026, linked to tight USP-NF and Ph. Eur. monograph compliance.
- For instance, a September 2026 formulation study in Biochemical and Biophysical Research Communications achieved 84.95% drug loading in solid lipid nanoparticles and 88.53% in nanostructured lipid carriers over 48-hour controlled release.
Why are buyers selecting oral SEDDS softgels for drug-delivery applications?
Oral lipid-based SEDDS and SMEDDS softgels are likely to capture 43.1% share in 2026, enabled by hydrophobic drug absorption.
More than half of new small-molecule drugs in pharmaceutical pipelines do not dissolve well in water, which drives steady multi-ton demand for self-emulsifying oral lipid oils in softgels and hard capsules. Commercial oral capsule lines consume hundreds of tons of lipid excipients each year compared with smaller kilogram batches in injectable nanomedicines.
- For drug-delivery application, oral lipid-based SEDDS and SMEDDS softgels are anticipated to keep the leading share at 43.1% in 2026 on commercial oral oncology and antiviral volume.
- Per a January 2026 study in Pharmaceutical Research, a sub-200 nm self-emulsifying lipid platform boosted oral sulfasalazine and disulfiram dissolution up to 4.5-fold and increased oral bioavailability 7.9-fold.
Which market conditions keep pharmaceutical and biopharmaceutical manufacturers leading end users?
Pharmaceutical and biopharmaceutical manufacturers are projected to hold 65.7% end user share in 2026, reinforced by commercial softgel lines.
Branded and generic drug manufacturers account for nearly two-thirds of total lipid purchases because they buy bulk drums of triglycerides and phospholipids for commercial softgel and sterile vial lines. Multi-year supply agreements for FDA-approved drugs lock in recurring annual excipient orders.
- Pharmaceutical and biopharmaceutical manufacturers are expected to command 65.7% of end user demand in 2026, influenced by multi-ton commercial manufacturing of approved oral and liposomal drugs.
- For instance, an October 2025 study in the Journal of Controlled Release showed that the novel ionizable lipid FS01 formed 70 nm particles with over 90% mRNA encapsulation and lower liver toxicity than older lipids.
What are the drivers, restraints, and opportunities in the pharmaceutical lipids market?
In the pharmaceutical lipids market, the key driver is BCS Class II/IV oral solubilization, the key restraint is anti-PEG immunogenicity, and the key opportunity is PEG-free extrahepatic LNPs.
- Driver: High proportions of poorly water-soluble BCS Class II/IV oral drugs and expanding mRNA/siRNA clinical pipelines accelerate cGMP lipid procurement.
- Restraint: Anti-PEG antibody clearance, lipid peroxidation impurities, and complex multi-step synthesis of custom ionizable lipids lengthen regulatory qualification.
- Opportunity: Polyglycerol and charge-reversible PEG-free phospholipids with extrahepatic stem-cell and pulmonary LNPs open high-margin specialty segments.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Higher numbers of poorly water-soluble oral drugs and expanding mRNA and siRNA clinical trials are the primary factors driving pharmaceutical companies to buy specialty lipid excipients. An FMI analyst notes that self-emulsifying oil fills inside hermetic softgel oral capsules keep hydrophobic drugs dissolved in the gut while injectable nanomedicine teams test new polyglycerol lipids that avoid immune reactions. For instance, in September 2025, a joint study by Freie Universitat Berlin and Bayer AG in Macromolecular Rapid Communications showed that linear polyglycerol lipids avoided anti-PEG antibody binding while preserving mRNA delivery into human liver cells. Sustained demand across both oral softgels and non-immunogenic RNA carriers supports long-term excipient supply contracts.
Risk Assessment of the Pharmaceutical Lipids Market: Operational and Formulation Friction
Peroxide impurities, crystal changes during storage, and immune reactions to pegylated lipids are the main technical challenges restraining faster adoption of lipid-based drug formulations. Even tiny traces of peroxide in unsaturated phospholipids or pharmaceutical polyethylene glycol polymers can break down fragile mRNA strands or make gelatin softgel shells brittle on pharmacy shelves. Per an October 2026 toxicology study by Seoul National University Hospital and the Korea Disease Control and Prevention Agency in Toxicological Sciences, high-dose mRNA lipid nanoparticles triggered a temporary two-week bone-marrow cell shift via interferon pathways. Drug regulators therefore require strict peroxide testing and nitrogen-sealed cold storage, which raises qualification costs for drugmakers.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Stronger biopharma investment in targeted cancer liposomes and gene-editing nanoparticles is creating high-margin sales opportunities for custom cGMP phospholipid and ionizable lipid producers. Purified phospholipids and cholesterol form the protective shell of advanced pharmaceutical drug delivery platforms used to carry chemotherapy and antifungal drugs directly to tumors with fewer side effects. For instance, in June 2026, a Phase 3 trial across 73 patients with refractory desmoid tumors in Clinical Cancer Research showed that intravenous pegylated liposomal doxorubicin achieved 90.4% two-year progression-free survival versus 19.6% for placebo. Excipient suppliers that offer ready-to-use cGMP lipid mixes and FDA Drug Master Files secure lucrative commercial supply agreements.
Pharmaceutical Lipids Market by Country (2026 to 2036)
As per FMI, South Korea paces pharmaceutical lipids expansion across major biomanufacturing countries with a 6.1% CAGR to 2036, while Japan advances at a 4.5% CAGR over the forecast period. Commercial performance across East Asian and European biopharmaceutical hubs as well as North American CDMO plants depends on domestic cGMP lipid reactor capacity and Drug Master File registrations.
Table 7: Country CAGR and Primary Growth Levers for the Pharmaceutical Lipids Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 6.1% | Songdo/Osong CDMO expansion, localized Croda cGMP lipid plant, and AI LNP design |
| Switzerland | 4.9% | Basel multinational oncology SEDDS pipelines and domestic Lipoid and Merck cGMP supply |
| United States | 4.8% | Extrahepatic CRISPR/mRNA clinical trials and Croda Lamar and Alabama cGMP lipid plants |
| Germany | 4.6% | Lipoid Cologne GMP phospholipid commissioning and Merck KGaA Darmstadt lipid synthesis |
| Japan | 4.5% | PEG-free charge-reversible phospholipid innovation and strict PMDA JPE purity standards |
| United Kingdom | 4.7% | Croda Leek cGMP synthetic lipid expansion and functionalized oncology LNP clinical trials |
| France | 4.5% | Gattefossé oral polyoxylglyceride leadership and academic-industrial phospholipid research |
| Canada | 4.7% | Evonik Vancouver GMP lipid facility expansion and British Columbia nanomedicine CDMO cluster |
Source: Future Market Insights analysis
South Korea Pharmaceutical Lipids Market Outlook (2026 to 2036)
Rapid expansion of contract biologics manufacturing and government-backed mRNA vaccine and softgel plants across Songdo and Osong is driving strong pharmaceutical lipid demand in South Korea. For instance, in January 2026 researchers at MIT and South Korea KIST and MolCube published the Lipid Nanoparticle Database in Nature Communications covering 19,528 lipid nanoparticles to speed up AI-guided lipid selection for RNA drugs. By 2036, South Korea is projected to grow at 6.1% CAGR, supported by Croda International Plc opening its South Korean specialty lipid plant and national bio-supply-chain grants. Reliance on imported raw cholesterol still challenges local producers, so Korean CDMOs sign multi-year supply agreements with global lipid suppliers.
Key takeaway: In South Korea, national CDMO biocluster expansion and localized Croda cGMP lipid production with AI-guided LNP design will sustain a top-ranked 6.1% CAGR.
Switzerland Pharmaceutical Lipids Market Outlook (2026 to 2036)
Strong demand from Basel-based multinational pharmaceutical R&D centers and sterile contract manufacturers for oral bioavailability oils and injectable liposomal phospholipids shapes the market in Switzerland. Per a May 2025 European review in Expert Opinion on Drug Delivery, self-microemulsifying and self-nanoemulsifying lipid matrices remain the primary commercial solution for improving oral absorption of poorly soluble drugs. Adoption of pharmaceutical lipids in Switzerland is estimated to expand at a 4.9% CAGR through 2036, enabled by oncology and immunology oral softgel and liposomal injectable pipelines. High Swiss cleanroom labor and operating costs limit bulk commodity oil production, so domestic plants focus on high-margin purified phospholipids from Lipoid Swiss AG and Merck KGaA.
Key takeaway: In Switzerland, Basel multinational oncology formulation pipelines and domestic Lipoid and Merck KGaA cGMP lipid synthesis will anchor a 4.9% CAGR.
United States Pharmaceutical Lipids Market Outlook (2026 to 2036)
Large-scale clinical trials for mRNA vaccines, CRISPR gene editors, and stem-cell therapies and high-volume oral softgel manufacturing drive pharmaceutical lipid demand across the United States. For instance, in October 2026, Emory University researchers reported in Molecular Therapy that an antibody-free lipid nanoparticle outperformed standard SM-102 LNPs in delivering Cas9 mRNA to human bone-marrow stem cells while reducing liver uptake. The United States pharmaceutical lipids sector is projected to record a 4.8% CAGR across the ten-year horizon, driven by Croda's Lamar and Alabama cGMP lipid plants and Evonik's North American lipid network. Strict FDA Type IV Drug Master File rules protect domestic cGMP lipid suppliers against uncertified imports.
Key takeaway: In the United States, extrahepatic in vivo CRISPR/mRNA LNP clinical trials and expanded domestic cGMP lipid reactor capacity are anticipated to support a 4.8% CAGR.
Germany Pharmaceutical Lipids Market Outlook (2026 to 2036)
Broader production of purified natural and synthetic phospholipids and plant-derived cholesterol across Ludwigshafen, Cologne, and Darmstadt drives market growth in Germany. Per a September 2025 study by LMU Munich and Lipoid GmbH in the European Journal of Pharmaceutical Sciences, balanced ratios of DSPC and DOPE helper phospholipids with PEG-lipids achieved 24% to 42% gene silencing across human lung mucus. In Germany, pharmaceutical lipids demand is predicted to advance at a 4.6% CAGR until 2036, supported by Lipoid GmbH commissioning new GMP phospholipid production and logistics buildings in Cologne. High German energy costs and REACH solvent rules pressure bulk oil margins and direct local producers toward high-purity injectable phospholipids.
Key takeaway: In Germany, Lipoid Cologne GMP phospholipid expansion and Merck KGaA Darmstadt synthesis with pulmonary RNA delivery research are estimated to drive a 4.6% CAGR.
Japan Pharmaceutical Lipids Market Outlook (2026 to 2036)
Strong domestic biopharma investment in liposomal cancer injections and low-inflammatory PEG-free mRNA vaccines is driving demand for ultra-pure synthetic phospholipids across Japan. For instance, in June 2026, researchers at the University of Shizuoka and Nippon Fine Chemical reported in the Journal of Pharmaceutical Sciences that the charge-reversible phospholipid DOP-TMDEDA formed stable PEG-free mRNA nanoparticles with lower inflammatory response. Japan is estimated to post a 4.5% CAGR between 2026 and 2036, reinforced by domestic commercial scale-up of RNA vaccines and liposomal oncology drugs. Strict Japanese Pharmacopoeia Excipients purity standards create high entry hurdles for foreign suppliers, which benefits domestic leaders NOF Corporation and Nippon Fine Chemical.
Key takeaway: In Japan, domestic innovation in PEG-free charge-reversible phospholipids and strict PMDA JPE purity standards are forecast to sustain a 4.5% CAGR.
United Kingdom Pharmaceutical Lipids Market Outlook (2026 to 2036)
Broader domestic cGMP synthetic lipid manufacturing in Staffordshire and growing oncology nanoparticle clinical trials across London, Oxford, and Cambridge support sustained commercial market growth across the United Kingdom. Per a March 2025 study in Molecular Therapy Methods & Clinical Development, folate- and maleimide-functionalized PEG-lipid nanoparticles improved tumor retention in solid cancer models. British pharmaceutical lipids demand is forecast to expand at a 4.7% CAGR by 2036 due to Croda International Plc scaling cGMP synthetic and ionizable lipid production at its Leek manufacturing facility in Staffordshire. Post-Brexit MHRA batch-testing requirements add customs paperwork for imported excipients and encourage UK biopharma companies to buy domestically produced cGMP lipids.
Key takeaway: In the United Kingdom, Croda Leek cGMP synthetic lipid expansion and functionalized oncology LNP clinical pipelines are projected to support a 4.7% CAGR.
France Pharmaceutical Lipids Market Outlook (2026 to 2036)
Strong pharmaceutical demand for oral bioavailability enhancers, sustained-release tablet waxes, and hard-fat suppository bases across Lyon and Paris manufacturing corridors drives the market in France. For instance, in July 2025, proceedings from the 8th International Symposium of the Phospholipid Research Center published in a peer-reviewed European pharmaceutics journal detailed advances in non-spherical lipid nanoparticles and liposomal drug stability. Between 2026 and 2036, the French pharmaceutical lipids market is expected to progress at a 4.5% CAGR, linked to Gattefossé SAS expanding Gelucire and Labrasol ALF oral solid-dosage applications across European contract manufacturers. Strict ANSM impurity audits and generic tablet price caps motivate French formulators to focus on high-value oral peptide and oncology delivery.
Key takeaway: In France, Gattefossé oral polyoxylglyceride leadership and translational phospholipid research across French academic-industrial consortia are slated to guide a 4.5% CAGR.
Canada Pharmaceutical Lipids Market Outlook (2026 to 2036)
Higher investment in parenteral lipid nanoparticle formulation and cGMP specialty lipid manufacturing across Vancouver and Burnaby in British Columbia is driving demand in Canada. Per a January 2025 study in the International Journal of Nanomedicine, a 26% ethyl oleate and 49% Solutol HS15 solid self-microemulsifying lipid system boosted oral relugolix bioavailability 1.9-fold and raised intestinal uptake threefold. Pharmaceutical lipids demand in Canada is forecast to expand at 4.7% CAGR by 2036, linked to Evonik Industries AG building its new Vancouver GMP lipid plant with Canadian Strategic Innovation Fund support to more than triple capacity by 2029. Limited domestic oral tablet volume means Canadian plants export most LNP batches to US biopharma sponsors.
Key takeaway: In Canada, Evonik's Vancouver GMP lipid facility expansion and British Columbia nanomedicine CDMO clusters are likely to drive a 4.7% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the pharmaceutical lipids market?
Evonik Industries AG, Croda International Plc, Merck KGaA, Lipoid GmbH, Gattefossé SAS, NOF Corporation, CordenPharma International, and IOI Oleo GmbH are the notable companies in the pharmaceutical lipids market.
FMI analysis indicates that the pharmaceutical lipids industry is moderately consolidated across cGMP parenteral phospholipids and synthetic ionizable lipids while remaining broader across oral glyceride esters. Parenteral lipid suppliers compete on multi-compendial purity and low peroxide values, whereas oral lipid suppliers differentiate on HLB versatility and melt-extrusion performance.
- Parenteral LNP & Synthetic Lipid Platforms: Evonik Industries AG and Croda International Plc (Avanti Research) with Merck KGaA supply cGMP cholesterol, ionizable lipids, and PEG-lipids with LNP CDMO services.
- Purified Phospholipid & Liposomal Specialists: Lipoid GmbH and NOF Corporation with CordenPharma International manufacture natural and synthetic DSPC, HSPC, and DSPE-PEG excipients.
- Oral Bioavailability & Glyceride Matrix Leaders: Gattefossé SAS and IOI Oleo GmbH formulate functional polyoxylglycerides, medium-chain triglycerides, and hard-fat suppository matrices.
Competitive Benchmarking: Pharmaceutical Lipids Market
Table 8: Competitive Benchmarking for the Pharmaceutical Lipids Market (qualitative capability ratings), 2026
| Company | Oral SEDDS & Glyceride Breadth | Parenteral LNP & Phospholipid Depth | cGMP DMF & CDMO Integration | Geographic Reach |
|---|---|---|---|---|
| Evonik Industries AG | Medium | High | High | High |
| Croda International Plc | High | High | High | High |
| Merck KGaA | Medium | High | High | High |
| Lipoid GmbH | High | High | High | High |
| Gattefossé SAS | High | Medium | High | High |
| NOF Corporation | Medium | High | High | Medium |
| CordenPharma International | Medium | High | High | Medium |
| IOI Oleo GmbH | High | Medium | High | Medium |
Scoring basis: Supplier rankings assess excipient coverage across oral SEDDS glycerides, purified phospholipids, and cGMP synthetic LNP lipids. Regulatory DMF depth and geographic ratings reflect verified US FDA Type IV Drug Master Files and multi-region cGMP plant footprints.
Key Developments in the Pharmaceutical Lipids Market
- In July 2026, Croda International Plc posted 4.6% organic first-half group sales growth, with Pharma Ingredients sales up 7% and ceramide sales up 44% following multi-site cGMP lipid capacity expansion.
- In March 2026, Merck KGaA launched its 2026 Phosphonolipid Challenge and supplied three lead phosphonolipid compounds at 0.5-gram scale to advance enzymatically stable nucleic acid delivery.
- In August 2025, Lipoid GmbH completed new quality control and logistics buildings at its Cologne site ahead of 2026 GMP phospholipid production commissioning.
Key Players in the Pharmaceutical Lipids Market
Parenteral LNP and Synthetic cGMP Lipid Platforms
- Evonik Industries AG
- Croda International Plc
- Merck KGaA
Purified Phospholipid and Liposomal Excipient Specialists
- Lipoid GmbH
- NOF Corporation
- CordenPharma International
Oral Bioavailability and Glyceride Matrix Formulators
- Gattefossé SAS
- IOI Oleo GmbH
Pharmaceutical Lipids Market Report Scope
Table 9: Report Scope for the Pharmaceutical Lipids Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Lipid Chemical Class, Physical Form, Origin Source, Drug-Delivery Application, End User |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier value from pharmaceutical-grade medium- and long-chain triglycerides, polyoxylglycerides, natural and synthetic phospholipids (DSPC, HSPC, DSPE-PEG), plant/synthetic cholesterol, and custom ionizable or cationic lipids used in oral, parenteral, liposomal, LNP, and topical drug products. Category Scope Note: Excludes commodity food cooking oils, unrefined biodiesel tallow, and finished drug product sales. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries Covered | South Korea, Switzerland, United States, Germany, Japan, United Kingdom, France, Canada, and additional countries in the full report |
| Key Companies Covered | Evonik Industries AG, Croda International Plc, Merck KGaA, Lipoid GmbH, Gattefossé SAS, NOF Corporation, CordenPharma International, IOI Oleo GmbH |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Pharmaceutical Lipids Market Research Methodology
Table 10: Research Methodology for the Pharmaceutical Lipids Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with pharmaceutical oral formulation scientists, LNP bioprocessing directors, CDMO excipient procurement heads, and regulatory DMF managers to validate lipid pricing and qualification gates. |
| Secondary Research | Analysis of specialty chemical annual reports, US FDA Drug Master File registries, USP-NF and Ph. Eur. lipid monographs, Phospholipid Research Center proceedings, and peer-reviewed PubMed studies. |
| Market Sizing and Forecasting | Top-down specialty pharma lipid segment revenues reconciled against bottom-up commercial oral softgel tonnage and clinical/commercial LNP and liposome batch consumption from 2026 to 2036. |
| Country Forecasting Model | Econometric national projections weight cGMP lipid reactor capex, domestic CDMO biologics pipelines, and national pharmacopeia compliance frameworks across eight pharmaceutical manufacturing nations. |
| Operational Benchmark Traceability | Batch and plant allocation indicators in Tables 2, 3, and 4 trace to Evonik and Croda capital expenditure disclosures, LNPDB 19,528-nanoparticle benchmarks, and Phase 3 liposomal trials. |
| Data Triangulation and Validation | Excipient value estimates are cross-checked against Evonik, Croda, Merck KGaA, Lipoid, and Gattefossé segment disclosures without double counting downstream contract fill-finish fees. |
Pharmaceutical Lipids Market by Segments
Pharmaceutical Lipids Market segmented by Lipid Chemical Class:
- Medium- & Long-Chain Triglycerides
- Phospholipids Lecithin, DSPC, HSPC & DSPE-PEG
- Ionizable, Cationic & PEGylated Lipids for LNP
- Cholesterol, Sphingolipids & Fatty Acid Esters
Pharmaceutical Lipids Market segmented by Physical Form:
- Semi-Solid Waxy Matrices & Pastes
- High-Purity Liquid Oils
- Lyophilized & Crystalline Powders
Pharmaceutical Lipids Market segmented by Origin Source:
- Semi-Synthetic GMP-Purified Lipids
- Fully Synthetic Custom Lipids
- Natural Plant & Egg-Yolk Extracted Lipids
Pharmaceutical Lipids Market segmented by Drug-Delivery Application:
- Oral Lipid-Based SEDDS/SMEDDS Softgels & Bioavailability Enhancers
- mRNA, siRNA & Gene-Therapy Lipid Nanoparticles
- Liposomal Parenteral Oncology & Amphotericin Formulations
- Topical, Suppository & Ophthalmic Emulsions
Pharmaceutical Lipids Market segmented by End User:
- Pharmaceutical & Biopharmaceutical Manufacturers
- Contract Development & Manufacturing Organizations
- Academic & Research Institutes
- Specialty Compounding & Hospital Parenteral Pharmacies
- Clinical Trial Material Packaging Centers
Pharmaceutical Lipids Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Evonik Industries AG. (2026, August 27). Evonik expands lipid-based drug delivery capabilities with new GMP manufacturing facility in Vancouver. Evonik Industries AG.
- [2] Croda International Plc. (2026, March 10). Life Sciences business review: Annual Report 2025. Croda International Plc.
- [3] Laguna, A., Santos, A. O., Rodrigues, M., Alves, G., Dardonville, C., Torrado-Santiago, S., & Torrado-Salmerón, C. (2026, April 25). Development of self-emulsifying drug delivery systems (SEDDS) to improve the bioavailability of a new antileishmanial drug. International Journal of Pharmaceutics, 695, 126749 (PubMed PMID 41819384).
- [4] Gattefossé SAS. (2025, November 4). Beyond the Capsule: Unlocking the full potential of lipid excipients in oral solid dosage forms. Gattefossé SAS.
- [5] Suriya Prakaash, K. K., & Damodharan, N. (2026, September 17). A comparative QbD-driven optimization of solid lipid nanoparticles and nanostructured lipid carriers for enhanced drug delivery. Biochemical and Biophysical Research Communications, 837, 154599 (PubMed PMID 42759277).
- [6] Desai, P., Bang, K., Chowdhury, M. R. H., Wang, Z. K., Wang, J., Prabhu, S., et al. (2026, January 1). Development, Optimization, and Evaluation of Nano Self-Emulsifying Drug Delivery System Formulation Platform for Oral Bioavailability Enhancement of Sulfasalazine and Disulfiram in Lung Cancer Chemoprevention. Pharmaceutical Research, 43(1), 195-215 (PubMed PMID 41402681).
- [7] Guo, K., Bu, L., Du, J., Zhang, W., Xia, J., Tao, M., et al. (2025, October 10). A novel ionizable lipid with comprehensive improvements in transfection potency, immune profile and safety of lipid nanoparticle. Journal of Controlled Release, 386, 114126 (PubMed PMID 40818720).
- [8] Ensminger, Y., Rashmi, R., Karimov, M., Nölte, G., Hafke, M., Schmitt, A.-C., et al. (2025, September 16). Polyglycerol-Based Lipids: A Next-Generation Alternative to PEG in Lipid Nanoparticles for Advanced Drug Delivery Systems. Macromolecular Rapid Communications, e00428 (PubMed PMID 40955768).
- [9] Ahn, J.-H., Lee, N.-Y., Bae, H.-J., Kim, J., Kwak, J., Roh, G., et al. (2026, October 9). Lipid Nanoparticle-Formulated Synthetic Messenger RNA Induces Reversible Hematopoietic Bias via Type I Interferon Responses Under Upper-Bound Inflammatory Conditions in Preclinical Animal Models. Toxicological Sciences, kfag134 (PubMed PMID 42853072).
- [10] Xu, H., Hu, J., Zhang, Y., Zhuang, A., Zhang, Y., Li, J., et al. (2026, June 1). Phase III Trial of Pegylated Liposomal Doxorubicin for Patients with Advanced and Refractory Desmoid Tumors. Clinical Cancer Research, 32(11), 2198-2205 (PubMed PMID 41504634).
- [11] Collins, E., Ji, J., Kim, S.-G., Witten, J., Kim, S., Zhu, R., et al. (2026, January 28). Lipid Nanoparticle Database towards structure-function modeling and data-driven design for nucleic acid delivery. Nature Communications, 17(1), 2464 (PubMed PMID 41605942).
- [12] Laffleur, F., Millotti, G., & Lagast, J. (2025, May 1). An overview of oral bioavailability enhancement through self-emulsifying drug delivery systems. Expert Opinion on Drug Delivery, 22(5), 659-671 (PubMed PMID 40078056).
- [13] Kim, E., Zenhausern, R., Kapadia, S., Johnson, S., Cho, S., Choi, J., et al. (2026, October 23). A Scalable, Antibody-Free Lipid Nanoparticle Achieves Preferential mRNA Delivery to Human HSPCs In Vivo Without Conditioning. Molecular Therapy, S1525-0016(26)00881-6 (PubMed PMID 42920299).
- [14] Rademacker, S., Carneiro, S. P., Molbay, M., Catapano, F., Forné, I., Imhof, A., et al. (2025, September 1). The impact of lipid compositions on siRNA and mRNA lipid nanoparticle performance for pulmonary delivery. European Journal of Pharmaceutical Sciences, 212, 107182 (PubMed PMID 40571267).
- [15] Sha, P., Maeshima, S., Koide, H., Kanetaka, S., Koge, T., Kurosaki, T., & Asai, T. (2026, June 1). A phospholipid-like charge-reversible lipid for PEG-free, stable, and low-inflammatory mRNA lipid nanoparticles. Journal of Pharmaceutical Sciences, 115(6), 104292 (PubMed PMID 42031024).
- [16] Jester, M., Haley, R. M., Billingsley, M. M., Figueroa-Espada, C., Joseph, R. A., Han, X., & Mitchell, M. J. (2025, March 27). Ionizable lipid nanoparticles with functionalized PEG-lipids increase retention in the tumor microenvironment. Molecular Therapy Methods & Clinical Development, 33(2), 101457 (PubMed PMID 40321415).
- [17] Drescher, S., & Blume, A. (2025, July 1). The 8th International Symposium on Phospholipids in Pharmaceutical Research - An update on current research in phospholipids presented at the biennial symposium of the Phospholipid Research Center Heidelberg. European Journal of Pharmaceutical Sciences, 210, 107126 (PubMed PMID 40374026).
- [18] Li, Z.-L., Deng, G.-X., Fang, C.-Z., Zhao, Y.-Q., Yuan, J., Chen, L., et al. (2025, January 25). Solid Self-Microemulsifying Drug Delivery System for Improved Oral Bioavailability of Relugolix: Preparation and Evaluation. International Journal of Nanomedicine, 20, 1065-1082 (PubMed PMID 39886543).
- [19] Croda International Plc. (2026, July 28). Half Year Results Announcement 2026: Results for the six months ended 30 June 2026. Croda International Plc.
- [20] Merck KGaA. (2026, March 19). Phosphonolipid Challenge - Research | Merck KGaA, Darmstadt, Germany. Merck KGaA.
- [21] Lipoid GmbH. (2025, August 20). 2025 - New milestone reached at the Cologne site: Logistics, administration, and production areas ready for planned commissioning in 2026. Lipoid GmbH.
- [22] Muta, T., Mukhopadhyay, S., Noll, B., Song, Y., & Garg, S. (2026, December 31). Development and in vivo pharmacokinetic evaluation of a phospholipid complex self-nanoemulsifying drug delivery system (PLC-SNEDDS) for enhanced oral bioavailability of cannabidiol. Drug Delivery, 33(1), 2702143 (PubMed PMID 42487275).
- [23] Lu, T., Zhang, J., Liu, D., Gu, B., Yang, X., Lyu, F., et al. (2026, May 27). Real-World Efficacy and Safety of Liposomal Amphotericin B for Invasive Fungal Disease in Patients with Hematologic Malignancies: A Multicenter Retrospective Study. Drug Design, Development and Therapy, 20, 605938 (PubMed PMID 42226752).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the pharmaceutical lipids market in 2026 and 2036?
- Which oral bioavailability and RNA delivery pipelines support pharmaceutical lipids demand?
- Why do medium- and long-chain triglycerides lead lipid chemical class demand?
- Why do semi-solid waxy matrices lead the physical form category?
- How do growth rates differ across South Korea, Switzerland, and Germany?
- Which notable companies supply oral polyoxylglycerides and cGMP LNP lipids?
- What limits custom ionizable lipid synthesis yields in commercial drug products?
- What should formulation scientists evaluate before qualifying a pharmaceutical lipid excipient?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Lipid Chemical Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Lipid Chemical Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Lipid Chemical Class, 2026 to 2036
- Medium- & Long-Chain Triglycerides
- Phospholipids Lecithin, DSPC, HSPC & DSPE-PEG
- Ionizable, Cationic & PEGylated Lipids for LNP
- Cholesterol, Sphingolipids & Fatty Acid Esters
- Y-o-Y Growth Trend Analysis By Lipid Chemical Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Lipid Chemical Class, 2026 to 2036
- Global Market Analysis and Forecast, By Physical Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Physical Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Physical Form, 2026 to 2036
- Semi-Solid Waxy Matrices & Pastes
- High-Purity Liquid Oils
- Lyophilized & Crystalline Powders
- Y-o-Y Growth Trend Analysis By Physical Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Physical Form, 2026 to 2036
- Global Market Analysis and Forecast, By Origin Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Origin Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Origin Source, 2026 to 2036
- Semi-Synthetic GMP-Purified Lipids
- Fully Synthetic Custom Lipids
- Natural Plant & Egg-Yolk Extracted Lipids
- Y-o-Y Growth Trend Analysis By Origin Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Origin Source, 2026 to 2036
- Global Market Analysis and Forecast, By Drug-Delivery Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Drug-Delivery Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Drug-Delivery Application, 2026 to 2036
- Oral Lipid-Based SEDDS/SMEDDS Softgels & Bioavailability Enhancers
- mRNA, siRNA & Gene-Therapy Lipid Nanoparticles
- Liposomal Parenteral Oncology & Amphotericin Formulations
- Topical, Suppository & Ophthalmic Emulsions
- Y-o-Y Growth Trend Analysis By Drug-Delivery Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Drug-Delivery Application, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Pharmaceutical & Biopharmaceutical Manufacturers
- Contract Development & Manufacturing Organizations
- Academic & Research Institutes
- Specialty Compounding & Hospital Parenteral Pharmacies
- Clinical Trial Material Packaging Centers
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- By Country
- Market Attractiveness Analysis
- By Country
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Lipid Chemical Class
- By Physical Form
- By Origin Source
- By Drug-Delivery Application
- By End User
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Evonik Industries AG
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Croda International Plc
- Merck KGaA
- Lipoid GmbH
- Gattefossé SAS
- NOF Corporation
- CordenPharma International
- IOI Oleo GmbH
- Evonik Industries AG
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by End User, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Lipid Chemical Class, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Physical Form, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Origin Source, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Drug-Delivery Application, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by End User, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Lipid Chemical Class
- Figure 6: Global Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Physical Form
- Figure 9: Global Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Origin Source
- Figure 12: Global Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Drug-Delivery Application
- Figure 15: Global Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by End User
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Lipid Chemical Class
- Figure 32: North America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Physical Form
- Figure 35: North America Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Origin Source
- Figure 38: North America Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Drug-Delivery Application
- Figure 41: North America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by End User
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Lipid Chemical Class
- Figure 48: Latin America Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Physical Form
- Figure 51: Latin America Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Origin Source
- Figure 54: Latin America Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Drug-Delivery Application
- Figure 57: Latin America Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by End User
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Lipid Chemical Class
- Figure 64: Western Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Physical Form
- Figure 67: Western Europe Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Origin Source
- Figure 70: Western Europe Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Drug-Delivery Application
- Figure 73: Western Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by End User
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Lipid Chemical Class
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Physical Form
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Origin Source
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Drug-Delivery Application
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by End User
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Lipid Chemical Class
- Figure 96: East Asia Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Physical Form
- Figure 99: East Asia Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Origin Source
- Figure 102: East Asia Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Drug-Delivery Application
- Figure 105: East Asia Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by End User
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Lipid Chemical Class
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Physical Form
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Origin Source
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Drug-Delivery Application
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by End User
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Lipid Chemical Class, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Lipid Chemical Class, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Lipid Chemical Class
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Physical Form, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Physical Form, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Physical Form
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Origin Source, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Origin Source, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Origin Source
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Drug-Delivery Application, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Drug-Delivery Application, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Drug-Delivery Application
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by End User, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by End User, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by End User
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the pharmaceutical lipids market in 2026, and what is forecast for 2036?
FMI estimates show that global pharmaceutical lipids market value will reach USD 5.8 billion in 2026 after standing at USD 5.5 billion in 2025 and advance to USD 9.4 billion by 2036.
What is the CAGR for the pharmaceutical lipids market from 2026 to 2036?
Future Market Insights projects a 4.9% CAGR across the 2026 to 2036 forecast horizon, which delivers USD 3.6 billion in incremental market value across pharmaceutical and CDMO buyers.
Which lipid chemical class segment leads the pharmaceutical lipids market?
Medium- and long-chain triglycerides are projected to capture 44.1% of lipid chemical class demand in 2026 through high-volume solubilization in oral softgels and parenteral lipid emulsions.
Which physical form segment leads the pharmaceutical lipids market?
Semi-solid waxy matrices and pastes are estimated to secure 62.1% of the physical form category in 2026 as oral dosage plants adopt melt-extruded polyoxylglycerides and hard-fat capsule fills.
Which country has a notable growth outlook during the assessment period?
South Korea paces country-level expansion at a 6.1% CAGR through 2036, supported by domestic biocluster CDMO expansion and localized Croda lipid production.
Who are the key players in the market?
Evonik Industries AG and Croda International Plc with Merck KGaA and Lipoid GmbH lead commercial supply with Gattefossé SAS across drug delivery channels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
