

- Market Size (2026)
- USD 34.0 Bn
- Forecast (2036)
- USD 53.3 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Fish Feed Market in 2026?
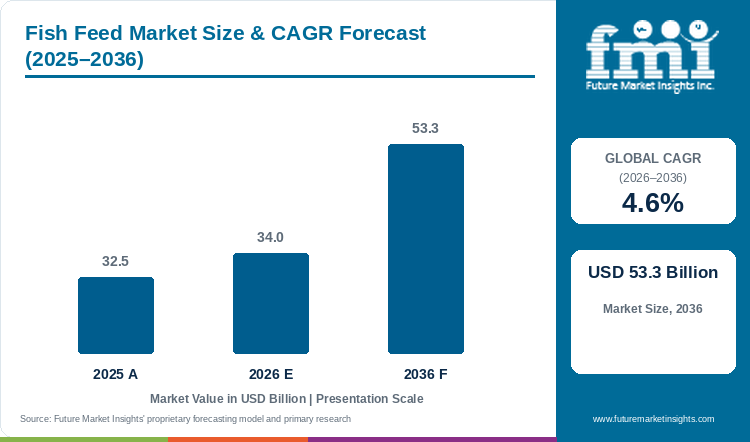
Sales in the fish feed market are projected to grow at 4.6% CAGR, with the market size rising from USD 32.5 billion in 2025 to USD 34.0 billion in 2026 and reaching USD 53.3 billion by 2036.
Intensive sea-cage salmon farming, coastal shrimp pond cultivation, and land-based recirculating hatcheries require high-energy rations that convert into harvestable fish biomass without fouling water quality. According to FMI, the global fish feed market rises from USD 32.5 billion in 2025 to USD 34.0 billion in 2026 and is projected to reach USD 53.3 billion by 2036, expanding at a 4.6% CAGR from 2026 to 2036 and generating USD 19.3 billion in added revenue. Fresh chilled cuts and fillets hold the leading 38.9% share by product form in 2026 because high-moisture marine rations stimulate immediate feeding in carnivorous broodstock and juvenile finfish. In March 2025, the Food and Agriculture Organization documented under its Blue Transformation technical review that precision feed management and byproduct utilization are critical to curbing wild forage fish pressure[1]. Evaluated countries grow between 3.7% in Chile and 5.6% in Iceland, although pelagic fishmeal quota swings continue to test miller margins.
Key Market Trends & Insights
- By product form: Fresh chilled cuts & fillets led the market with a share of 38.9% in 2026, supported by high natural moisture palatability and rapid amino-acid absorption in marine nursery and grow-out cages.
- By species / source: Wild capture marine fishery accounted for 55.5% of demand in 2026, owing to pelagic anchoveta, menhaden, and capelin reduction streams supplying digestible marine proteins and omega-3 lipids.
- By end-use sector: Food service & restaurants represented 43.1% of revenue in 2026, as hospitality chains contract aquaculture farms using commercial aquafeed formulations for uniform fillet fat marbling and color.
Regional Highlights
- Fastest-growing evaluated country: Iceland, at 5.6% CAGR from 2026 to 2036.
- By country: Australia at 5.2%, Norway at 4.8%, and Japan at 4.4% follow, while Chile records the lowest evaluated CAGR at 3.7%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Fish Feed Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 32.5 billion |
| Estimated Market Size in 2026 | USD 34.0 billion |
| Projected Market Size by 2036 | USD 53.3 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 19.3 billion |
Commercial conditions differ across the profiled countries owing to coastal water temperatures, environmental discharge permits, and farmed species mix. FMI research indicates that compound feed mills are investing in twin-screw extruders and vacuum lipid coaters to blend traceable fish feed ingredients that hold pellet integrity in high-current sea cages. In August 2026, the European Food Safety Authority updated its scientific guidance on animal and aquaculture feed additives, tightening trace-element and mycotoxin thresholds across compound rations[2]. Consequently, feed formulators must balance EPA and DHA omega-3 retention against stricter heavy-metal and dioxin screening before shipping bulk bags to coastal farms.
Extruded Aquafeed Production and Bioconversion Sizing
Table 2: Extruded Aquafeed Production and Bioconversion Sizing for the Fish Feed Market (USD billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 32.5 | 34.0 | 53.3 |
| Commercial aquafeed tonnage produced (million metric tons) | 48.0 to 52.0 | 50.5 to 54.5 | 78.0 to 84.5 |
| Plant and microbial alternative protein blend share (percent) | 32.0 to 34.5 | 33.5 to 36.0 | 48.0 to 52.0 |
| Wholesale realization per metric ton equivalent (USD) | 650 to 680 | 655 to 685 | 680 to 715 |
Operational note: Production metrics reflect commercial twin-screw extruded pellets, semi-moist marine rations, and vacuum-coated diets across major global finfish and crustacean farming basins.
Per Capita Commercial Aquaculture Spending Indicators
Commercial salmon, sea bream, yellowtail, and whiteleg shrimp farms purchase specialized rations tailored to each growth stage from hatchery fry to harvest weight. To lower reliance on volatile South American anchoveta harvests, millers are expanding plant-based fish feed formulations fortified with crystalline amino acids, enzyme phytases, and algal DHA oils. Maintaining a feed conversion ratio below 1.2 remains the primary economic benchmark for commercial farm operators.
Table 3: Per Capita and Industrial Spending Indicators for the Fish Feed Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 3.95 | 4.10 | 5.96 |
| Spend per 1,000 people (USD) | 3,949.0 | 4,096.4 | 5,955.3 |
| Commercial recirculating aquaculture facility annual feed spend (USD thousand) | 620.0 to 680.0 | 650.0 to 720.0 | 1,050.0 to 1,180.0 |
Table 4: Facility & Industrial Channel Sizing Indicators for the Fish Feed Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 34.0 billion | Report value |
| Licensed commercial fish farms and hatchery facilities worldwide | 128.0 thousand | 2024 aquaculture census |
| Average annual fish feed spend per commercial farming operation | USD 265.6 thousand | Facility average |
| Wild capture marine fishery input value, 2026 | USD 18.87 billion | 55.5% share |
Analyst Perspective
"Microalgal DHA oils and fermented single-cell proteins allow aquafeed millers to win sustainability-linked salmon and shrimp feed contracts. Pelagic fishmeal quota swings and anti-nutritional factors in plant concentrates still complicate digestibility in carnivorous marine species."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fish feed market segmented?
The fish feed market is segmented by product form, species / source, end-use sector, and region. In 2026, Fresh Chilled Cuts & Fillets represents 38.9%, wild capture marine fishery leads at 55.5%, and food service & restaurants captures 43.1%.
By product form: Fresh chilled cuts & fillets, frozen portions & blocks, canned & shelf-stable, and value-added & breaded.
By species / source: Wild capture marine fishery, commercial aquaculture / farm raised, and livestock pasture raised.
By end-use sector: Food service & restaurants, supermarkets & retail consumers, and industrial food processing plants.
Why do Fresh Chilled Cuts & Fillets lead the product form category?
Fresh chilled cuts and fillets are expected to hold 38.9% of product form revenue in 2026, supported by fingerling palatability.
Table 5: Product Form Share for the Fish Feed Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Fresh Chilled Cuts & Fillets | 38.9% |
| Other Segments Combined | 61.1%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Form Leadership and Market Growth for the Fish Feed Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Fresh Chilled Cuts & Fillets |
Marine finfish hatcheries, bluefin tuna pens, and yellowtail and grouper grow-out farms rely on fresh chilled cuts, moist mash, and semi-moist rations because natural tissue moisture preserves native marine attractants and digestive enzymes. When carnivorous fingerlings transition from live feed or when broodstock prepare for spawning, moist rations combined with high-grade pelagic fish meal trigger a stronger feeding response than dry compressed pellets. However, chilled feed requires refrigerated coastal storage and rapid daily feeding to prevent lipid peroxidation and nutrient leaching in sea cages.
- Fresh chilled cuts & fillets are projected to account for 38.9% of product form revenue in 2026, supported by high moisture digestibility and strong predatory feeding response in marine species.
- In March 2025, the European Aquaculture Society documented that moisture-stabilized nursery and smolt diets reduced early post-transfer mortality by 22% across commercial recirculating and coastal finfish farms[3].
What makes Wild Capture Marine Fishery central to the species and source category?
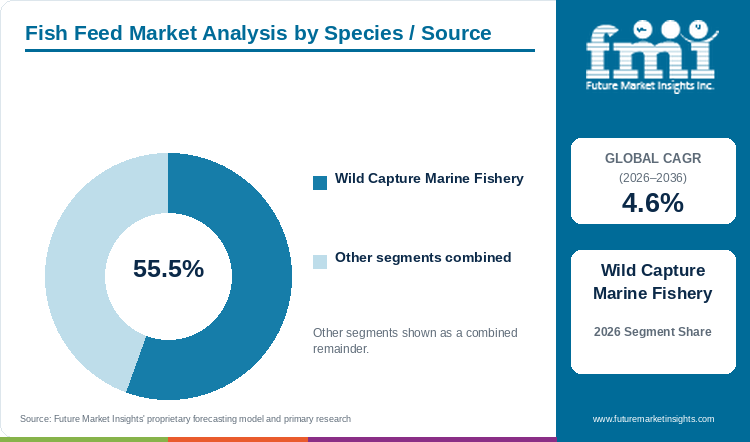
Wild capture marine fishery is projected to capture 55.5% of species and source demand in 2026, driven by amino-acid density.
Wild capture pelagic reduction fisheries in Peru, Chile, and the North Atlantic remain the foundational biological input for high-performance aquaculture feeds because anchoveta, blue whiting, and menhaden supply balanced essential amino acids, phospholipids, and long-chain omega-3 fatty acids. Although soy protein concentrate and wheat gluten supply bulk protein, formulators of salmon feed rations and marine shrimp starter diets still require marine protein fractions and fish oil to prevent intestinal inflammation and maintain immune health. In addition to this, trimmings and byproducts from wild-caught fish filleting plants now supply a growing share of certified marine meal.
- Wild capture marine fishery is estimated to hold 55.5% of species / source demand in 2026, owing to unmatched methionine and lysine bioavailability alongside EPA and DHA lipid density.
- In April 2025, the Marine Ingredients Organisation (IFFO) reported that global fishmeal and fish oil output recovered strongly following normalized Peruvian anchoveta fishing quotas, stabilizing marine protein supply for compound feed mills[4].
What keeps Food Service & Restaurants ahead by end-use sector?
Food service and restaurants are estimated to represent 43.1% of end-use sector demand in 2026, reflecting portioned aquaculture harvest purchasing.
Commercial seafood restaurants, hotel catering groups, and sushi chains drive end-use revenue because hospitality buyers pay premium prices for farmed Atlantic salmon, sea bass, sea bream, and amberjack raised on specialized finishing diets. Restaurant chefs demand year-round harvest consistency, firm fillet texture, controlled intramuscular fat marbling, and deep astaxanthin flesh pigmentation that cannot be guaranteed by seasonal wild catches. To meet these culinary specifications, integrated fish farms implement tailored aquaculture nutrition programs during the final 90 days of grow-out before harvesting and filleting for foodservice distribution.
- Food service & restaurants is forecast to represent 43.1% of end-use sector revenue in 2026, reinforced by hospitality specifications for uniform fillet fat content, firm texture, and carotenoid pigmentation.
- In January 2026, the Aquaculture Stewardship Council implemented its unified Responsible Feed Standard deadlines, requiring certified farms supplying restaurant and retail chains to verify traceable marine and plant feed ingredients[5].
What are the drivers, restraints, and opportunities in the fish feed market?
In the fish feed market, expanding commercial aquaculture biomass and precision feed conversion support demand, pelagic fishmeal quota swings and trace-contaminant rules constrain margins, and microalgal oils and insect proteins create growth opportunities through 2036.
- Driver: Global aquaculture production surpassing wild capture seafood supply will continue to drive compound extruded and moist feed procurement through 2036.
- Restraint: Climatic El Nino disruptions to South American reduction fisheries and strict heavy-metal and ethoxyquin limits will continue to pressure formulation costs through 2036.
- Opportunity: Commercial scaling of heterotrophic microalgal DHA oils, black soldier fly meal, and methanotrophic single-cell proteins is expected to widen sustainable feed margins through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Rising global seafood consumption alongside biological ceilings on wild ocean catches is forcing coastal and inland farms to raise stocking densities and rely on formulated compound feeds. FMI data suggests that commercial shrimp and finfish operators are blending functional animal feed probiotics and organic acids directly into extruded pellets to improve gut villi absorption and keep feed conversion ratios below 1.15. In June 2026, the Food and Agriculture Organization reported in its State of World Fisheries and Aquaculture (SOFIA) 2026 assessment that aquaculture surpassed capture fisheries as the primary source of aquatic animal production, with global aquatic trade reaching USD 184 billion[6]. Feed mills that deliver water-stable pellets with minimal dust fines enable farm operators to expand biomass output without violating coastal nitrogen and phosphorus discharge caps.
Risk Assessment of the Fish Feed Market: Operational and Formulation Friction
Price spikes across marine fishmeal and fish oil combined with anti-nutritional factors in plant protein replacements create persistent margin and formulation friction for aquafeed compounders. Whenever ocean warming or El Nino anomalies reduce Peruvian anchoveta catch quotas, spot prices for high-protein marine meal surge, forcing millers to increase soy, pea, or canola inclusion. However, carnivorous species such as Atlantic salmon and rainbow trout suffer soy-induced enteritis and reduced growth if plant saponins and phytic acid are not enzymatically neutralized. In February 2025, the U.S. Food and Drug Administration Center for Veterinary Medicine reinforced compliance inspections on oxidative rancidity, mycotoxins, and heavy metals across commercial animal and aquaculture feed mills[7]. Qualifying safe fish meal alternatives therefore requires lengthy digestibility trials before commercial farmers risk switching rations across multi-million-dollar sea cages.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Replacing wild forage fish oil and deforestation-exposed soy with fermented microalgae, insect meal, and single-cell bacterial proteins gives feed compounders a clear pathway to win European and North American retail-linked aquaculture accounts. Culturing Schizochytrium microalgae in closed fermentation tanks yields concentrated EPA and DHA omega-3 oils free from marine dioxins or PCBs, allowing millers to formulate algae-based animal feed that lowers the forage fish dependency ratio below 1.0. In January 2026, Cargill Aqua Nutrition highlighted in its 2026 Aquafeed Outlook that combining alternative proteins with AI-assisted acoustic and camera feeding systems significantly reduces uneaten pellet waste in salmon and shrimp operations[8]. Suppliers that bundle novel low-carbon ingredients with real-time cage feeding software secure multi-year supply agreements with certified aquaculture groups.
Fish Feed Market by Country (2026 to 2036)
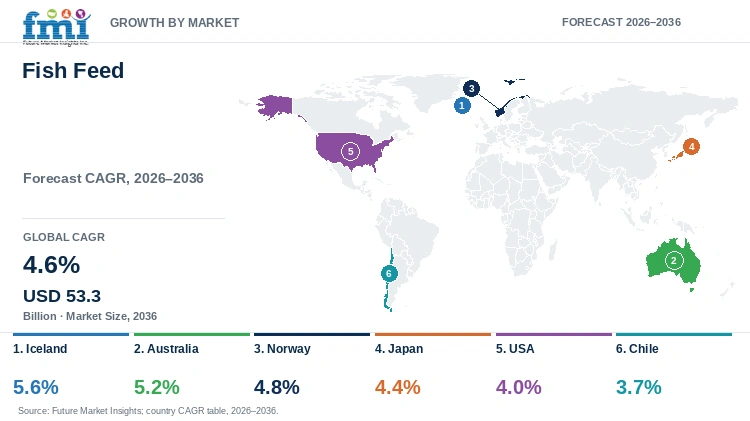
As per FMI, Iceland leads the six profiled countries with a 5.6% CAGR from 2026 to 2036, while Chile records a 3.7% CAGR as a mature salmon-farming producer. Across all covered economies, national growth rates depend on sea-cage versus land-based RAS licensing, domestic pelagic or plant ingredient availability, and environmental feed-conversion regulations.
Table 7: Country CAGR and Primary Growth Levers for the Fish Feed Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Iceland | 5.6% | Geothermal land-based recirculating aquaculture systems (RAS) and Westfjords/Eastfjords salmon biomass expansion |
| Australia | 5.2% | High-value Tasmanian salmon, South Australian bluefin tuna, and Queensland barramundi diets using lupin and canola proteins |
| Norway | 4.8% | Offshore and coastal Atlantic salmon sea cages deploying AI camera feeding and deforestation-free microalgal/insect rations |
| Japan | 4.4% | Transition from raw baitfish to moist extruded pellets in yellowtail, red sea bream, and farmed bluefin tuna mariculture |
| USA | 4.0% | Domestic indoor RAS salmon facilities, Mississippi Delta catfish feed optimization, and NOAA marine aquaculture initiatives |
| Chile | 3.7% | Large-scale Patagonian fjord salmonid farming prioritizing functional immune feeds and low feed conversion ratios |
Source: Future Market Insights analysis
Iceland Fish Feed Market Outlook (2026 to 2036)
Iceland is forecast to emerge as a high-growth market, registering 5.6% CAGR through 2036, propelled by large-scale construction of land-based recirculating aquaculture systems (RAS) on the Reykjanes Peninsula and expanding fjord salmon pens. Unlike traditional open-net salmon farming countries constrained by coastal sea-lice moratoriums, Icelandic operators pump lava-filtered seawater heated with low-cost geothermal energy into onshore smolt and grow-out tanks. In August 2025, the Icelandic Directorate of Fisheries (Fiskistofa) recorded rising farmed Atlantic salmon and Arctic char harvest volumes alongside expanded biomass licenses across the Westfjords and Eastfjords[9]. Because enclosed RAS biofilters clog immediately if pellets crumble or leach oil, Icelandic farms pay premium prices for high-shear extruded RAS diets engineered for fecal cohesion and near-zero fines.
Key takeaway: In Iceland, geothermal land-based RAS salmon expansion and strict biofilter water-clarity requirements drive rapid demand for high-stability extruded RAS feeds.
Australia Fish Feed Market Outlook (2026 to 2036)
Sub-tropical barramundi and prawn pond expansion in Queensland alongside cold-water Atlantic salmon and Southern bluefin tuna mariculture in Tasmania and South Australia support a projected 5.2% CAGR in Australia from 2026 to 2036. Australian aquaculture operates under strict Great Barrier Reef and Tasmanian coastal nutrient-discharge caps, which prevents farms from using low-digestibility feeds. In November 2025, Ridley Corporation Limited commissioned upgraded high-capacity extruded aquafeed milling capacity in Australia, formulating diets with domestic canola, lupin meal, and rendered poultry proteins to cut imported fishmeal freight costs[10]. High summer water temperatures in Tasmanian and South Australian cages create thermal stress for finfish, compelling local millers to fortify summer rations with antioxidant vitamins, betaine, and gut-stabilizing prebiotics.
Key takeaway: In Australia, strict coastal nutrient-discharge limits and summer thermal stress drive demand for locally milled, high-digestibility salmon, tuna, and barramundi feeds.
Norway Fish Feed Market Outlook (2026 to 2036)
Norway's fish feed outlook is anticipated to advance at 4.8% CAGR over the assessment period, anchored by the world's largest Atlantic salmon and rainbow trout sea-cage industry and government targets for sustainable feed raw materials. Norwegian salmon producers operate automated offshore and fjord feeding barges where underwater cameras and hydroacoustic sensors cut feed release the instant fish appetite slows. In May 2025, Skretting Norway published its 2025 Fish Feed Impact Report documenting increased inclusion of deforestation-free certified plant proteins, marine trimmings, and microalgal omega-3 oils under Norway's national raw-material sustainability roadmap[11]. Because Norway's traffic-light licensing system restricts coastal biomass growth in fjords with elevated sea-lice counts, feed compounders compete by selling functional lice-shield and wound-healing diets alongside submerged-cage floating pellets.
Key takeaway: In Norway, traffic-light biomass caps and national raw-material sustainability targets compel salmon farmers to buy functional health diets and zero-deforestation feeds.
Japan Fish Feed Market Outlook (2026 to 2036)
Coastal mariculture modernization across Ehime, Kagoshima, and Nagasaki shapes demand in Japan, where the fish feed market is expected to increase at 4.4% CAGR through 2036. Japanese farms raising yellowtail (buri), red sea bream (madai), and Pacific bluefin tuna historically fed raw thawed sardines and mackerel directly into cages, which caused coastal seabed organic pollution and exposed stocks to wild fish price swings. In July 2025, Japan's Fisheries Agency advanced its aquaculture growth strategy subsidizing mariculture operators that switch from raw baitfish to formulated moist and extruded artificial pellets (EP)[12]. Because domestic sashimi buyers judge farmed fish on pearl-white fat marbling, zero blood spots, and vivid skin coloration, Japanese feed mills add citrus polyphenols, krill meal, and natural carotenoids to finishing rations.
Key takeaway: In Japan, Fisheries Agency subsidies replacing raw baitfish with formulated moist pellets and sashimi flesh-quality standards drive steady mariculture feed upgrades.
USA Fish Feed Market Outlook (2026 to 2036)
Between 2026 and 2036, the USA market is expected to progress at 4.0% CAGR, supported by Mississippi Delta channel catfish ponds, Idaho rainbow trout raceways, and indoor recirculating Atlantic salmon farms in Maine, Florida, and the Midwest. Unlike marine-fishmeal-heavy European diets, American freshwater catfish and trout mills leverage abundant domestic soybean meal, corn gluten, and distillers dried grains to keep feed costs competitive against imported seafood. In September 2026, the National Oceanic and Atmospheric Administration (NOAA) expanded marine spatial planning and alternative-feed initiatives to reduce wild forage fish reliance across U.S. aquaculture operations[13]. Lengthy federal offshore permitting still limits open-ocean net pens in U.S. waters, so domestic feed growth concentrates in soy-optimized pond pellets and specialized zero-fishmeal RAS rations.
Key takeaway: In the USA, abundant domestic soy protein supply and indoor RAS salmon investments support steady demand for low-fishmeal extruded diets.
Chile Fish Feed Market Outlook (2026 to 2036)
As the world's second-largest farmed salmonid producer across Los Lagos, Aysen, and Magallanes, Chile is projected to record 3.7% CAGR during the 2026 to 2036 assessment period. Chilean Atlantic salmon, Coho salmon, and rainbow trout farms operate in remote Patagonian fjords where barge logistics and recurring Piscirickettsia salmonis (SRS) bacterial outbreaks challenge farm profitability. In June 2025, Chile's National Fisheries and Aquaculture Service (SERNAPESCA) enforced updated antimicrobial-reduction and biosecurity reporting rules across southern salmon farming neighborhoods[14]. To help farms cut antibiotic treatments and qualify for North American retail ASC standards, feed mills in Puerto Montt and Coronel formulate high-energy pellets fortified with beta-glucans, nucleotides, and phytogenic immune boosters.
Key takeaway: In Chile, SERNAPESCA antibiotic-reduction rules and Patagonian fjord logistics drive salmonid producers toward immune-fortified, high-energy extruded feeds.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fish feed market?
Nutreco N.V. (Skretting), Cargill Aqua Nutrition, BioMar Group, Alltech (Coppens), Charoen Pokphand Foods (CPF), Tongwei Co., Ltd., Ridley Corporation Limited, and Haid Group are the significant market players in this market.
As per the analysis from FMI, the fish feed industry divides between global cold-water salmonid feed specialists, vertically integrated Asian warmwater and shrimp feed giants, and regional mariculture compounders. Nutreco N.V. (Skretting), Cargill Aqua Nutrition, and BioMar Group lead across Norway, Scotland, Iceland, and Chile with high-energy vacuum-coated salmon feeds and digital cage-feeding platforms. Charoen Pokphand Foods (CPF), Tongwei Co., Ltd., and Haid Group operate massive milling networks across Asia for carp, tilapia, and marine shrimp, while Alltech (Coppens) and Ridley Corporation Limited specialize in RAS diets, gut-health additives, and commercial insect feed formulations.
- Global Salmonid and Marine Extrusion Leaders: Nutreco N.V. (Skretting), Cargill Aqua Nutrition, and BioMar Group operate coastal extrusion plants and R&D centers across Europe and the Americas.
- Asian Warmwater Finfish and Shrimp Feed Giants: Charoen Pokphand Foods (CPF), Tongwei Co., Ltd., and Haid Group combine high-volume feed milling with hatchery and farm technical services across Asia-Pacific.
- Specialty RAS and Regional Mariculture Innovators: Alltech (Coppens) and Ridley Corporation Limited formulate specialized recirculating-system feeds, functional gut-health additives, and Australasian mariculture rations.
Competitive Benchmarking: Fish Feed Market
Table 8: Competitive Benchmarking for the Fish Feed Market (qualitative capability ratings), 2026
| Company | High-Energy Extrusion Capacity | Fishmeal Replacement Research | ASC & GlobalGAP Certification Depth | Global Marine Distribution Reach |
|---|---|---|---|---|
| Nutreco N.V. (Skretting) | High | High | High | High |
| Cargill Aqua Nutrition | High | High | High | High |
| BioMar Group | High | High | High | High |
| Alltech (Coppens) | Medium | High | High | Medium |
| Charoen Pokphand Foods (CPF) | High | Medium | High | High |
| Tongwei Co., Ltd. | High | Medium | Medium | Medium |
| Ridley Corporation Limited | Medium | High | High | Medium |
| Haid Group | High | Medium | Medium | High |
Scoring basis: High-Energy Extrusion Capacity is High when a producer operates multi-line twin-screw extrusion and vacuum coating plants exceeding one million metric tons annually, and Medium when regional. Fishmeal Replacement Research is High when microalgal oil, insect meal, or single-cell protein rations are commercially deployed, and Medium when focused on standard plant proteins. ASC & GlobalGAP Certification Depth and Global Marine Distribution Reach reflect third-party feed certification coverage and multi-basin coastal delivery.
Key Developments in the Fish Feed Market
- In June 2026, Nutreco N.V. and Skretting hosted the 16th biennial AquaVision conference in Stavanger, Norway, advancing commercial partnerships on microalgal DHA oils and AI-driven precision salmon feeding[15].
- In October 2025, BioMar Group expanded commercial deployment of its Blue Impact and deforestation-free Mediterranean sea bass and sea bream diets formulated with circular plant and trimmings proteins[16].
- In May 2025, Alltech Coppens introduced upgraded RAS-specific extruded diets and functional gut-health prebiotic packs designed to stabilize biofilter water quality in European land-based trout and salmon farms[17].
Key Players in the Fish Feed Market
Global Salmonid and Marine Extrusion Leaders
- Nutreco N.V. (Skretting)
- Cargill Aqua Nutrition
- BioMar Group
Asian Warmwater Finfish and Shrimp Feed Giants
- Charoen Pokphand Foods (CPF)
- Tongwei Co., Ltd.
- Haid Group
Specialty RAS and Regional Mariculture Innovators
- Alltech (Coppens)
- Ridley Corporation Limited
Fish Feed Market - Report Scope
Table 9: Report Scope for the Fish Feed Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Species / Source; End-Use Sector; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from formulated aquaculture feeds, moist and fresh chilled marine rations, and compound pelleted feeds sold for finfish and crustacean farming. Excludes ornamental aquarium fish food, recreational fishing bait, and unformulated farm waste. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Iceland, Australia, Norway, Japan, USA, Chile, and additional countries in the full report |
| Key Companies Covered | Nutreco N.V. (Skretting), Cargill Aqua Nutrition, BioMar Group, Alltech (Coppens), Charoen Pokphand Foods (CPF), Tongwei Co., Ltd., Ridley Corporation Limited, Haid Group |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Fish Feed Market - Research Methodology
Table 10: Research Methodology for the Fish Feed Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with commercial aquaculture farm managers, aquafeed extrusion plant directors, fish-health veterinarians, and marine ingredient procurement specialists to validate feed conversion ratios, raw-material blends, and pricing. |
| Secondary Research | Secondary research analyzed FAO State of World Fisheries and Aquaculture (SOFIA) reports, IFFO marine ingredient production bulletins, EFSA and FDA veterinary feed regulations, national fisheries directorate statistics, and corporate annual reports. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined top-down and bottom-up triangulation of farmed species harvest tonnages, species-specific economic feed conversion ratios, and wholesale feed realizations across regions. |
| Data Triangulation and Validation | Estimates were cross-validated against pelagic fishmeal and fish oil trade balances, licensed aquaculture biomass capacities, and corporate aquafeed segment revenues to prevent double-counting raw ingredient sales. |
Fish Feed Market by Segments
Fish Feed Market segmented by Product Form:
- Fresh Chilled Cuts & Fillets
- Frozen Portions & Blocks
- Canned & Shelf-Stable
- Value-Added & Breaded
Fish Feed Market segmented by Species / Source:
- Wild Capture Marine Fishery
- Commercial Aquaculture / Farm Raised
- Livestock Pasture Raised
Fish Feed Market segmented by End-Use Sector:
- Food Service & Restaurants
- Supermarkets & Retail Consumers
- Industrial Food Processing Plants
Fish Feed Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, March 14). Responsible Use of Fishmeal in Aquaculture: FAO Innovation for Blue Transformation. FAO Fisheries and Aquaculture Technical Paper Rome.
- [2] European Food Safety Authority (EFSA). (2026, August 18). Feed Additives in Animal and Aquaculture Nutrition: Safety and Efficacy Evaluation Framework. European Union Food Safety Publications.
- [3] European Aquaculture Society. (2025, March 29). Nutritional management and smolt survival kinetics in land-based recirculating and coastal finfish aquaculture systems. Aquaculture Europe Technical Bulletin, 52, 95-110.
- [4] Marine Ingredients Organisation (IFFO). (2025, April 18). Global Fishmeal and Fish Oil Production Statistics, Pelagic Quota Allocations, and Byproduct Utilization. IFFO Annual Market Monograph.
- [5] Aquaculture Stewardship Council (ASC). (2026, January 10). ASC Feed Standard Implementation and Traceability Requirements for Certified Finfish and Shrimp Farms. ASC Utrecht Technical Publications.
- [6] Food and Agriculture Organization of the United Nations. (2026, June 16). SOFIA 2026: The State of World Fisheries and Aquaculture Global Production and Trade Assessment. FAO Flagship Publications Rome.
- [7] U.S. Food and Drug Administration Center for Veterinary Medicine. (2025, February 20). Compliance Program Guidance: Trace Mineral Thresholds, Mycotoxins, and Oxidative Stability in Commercial Aquaculture Feeds. U.S. Department of Health and Human Services.
- [8] Cargill Aqua Nutrition. (2026, January 15). Aquafeed Outlook 2026: AI-assisted precision feeding, alternative proteins, and salmon and shrimp feed efficiency. Cargill Corporate Aquaculture Reports.
- [9] Icelandic Directorate of Fisheries (Fiskistofa). (2025, August 24). Aquaculture Biomass Statistics, Land-Based RAS Licensing, and Salmonid Harvest Volumes in Iceland. Fiskistofa Analytical Bulletins.
- [10] Ridley Corporation Limited. (2025, November 18). Commissioning of upgraded extruded aquafeed milling capacity and regional protein formulation for Australian mariculture. Ridley Investor Releases.
- [11] Skretting Norway (Nutreco N.V.). (2025, May 15). Impact Report Fish Feed Skretting Norway 2025: Raw Material Contents and Deforestation-Free Ingredient Sourcing. Skretting Sustainability Disclosures.
- [12] Fisheries Agency, Ministry of Agriculture, Forestry and Fisheries (MAFF) Japan. (2025, July 22). Strategy for Sustainable Mariculture: Transitioning Yellowtail, Sea Bream, and Tuna Farming to Formulated Extruded Pellets. Government of Japan Fisheries Reports.
- [13] National Oceanic and Atmospheric Administration (NOAA). (2026, September 24). Feeds for Aquaculture: Alternative Ingredients and Marine Spatial Planning for Responsible Aquaculture. U.S. Department of Commerce NOAA Fisheries.
- [14] National Fisheries and Aquaculture Service (SERNAPESCA). (2025, June 19). Report on Antimicrobial Use and Sanitary Management in Chilean Salmonid Aquaculture. Ministry of Economy, Development, and Tourism Chile.
- [15] Nutreco N.V. (Skretting). (2026, June 10). AquaVision 2026 Stavanger: Scaling microalgal omega-3 inclusion and precision digital feeding across global salmon farms. Skretting Corporate News.
- [16] BioMar Group. (2025, October 8). Commercial rollout of Blue Impact and deforestation-free micro-ingredient diets for Mediterranean and North Atlantic mariculture. BioMar Corporate Releases.
- [17] Alltech Coppens. (2025, May 20). Launch of upgraded RAS-specific extruded feeds and functional gut-health prebiotic packs for commercial finfish hatcheries. Alltech Product Bulletins.
- [18] Charoen Pokphand Foods Public Company Limited (CPF). (2025, August 15). Expansion of biosecure automated shrimp and warmwater fish feed milling capacity across Southeast Asia. CPF Corporate Updates.
- [19] Tongwei Co., Ltd. (2025, September 4). Large-scale freshwater and marine aquafeed extrusion modernization and solar-aquaculture integration. Tongwei Annual Operations Review.
- [20] Haid Group Co., Ltd. (2025, July 26). Commercial expansion of specialized extruded marine finfish feeds and probiotic shrimp starter diets across Asia-Pacific. Haid Corporate Disclosures.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fish feed market in 2026 and what is forecast for 2036?
- Which commercial aquaculture and feed-conversion pressures support demand for fish feed?
- Why do Fresh Chilled Cuts & Fillets lead the product form category?
- Why does wild capture marine fishery lead the species and source category globally?
- How do growth rates differ across Iceland, Australia, Norway, and Japan?
- Which leading companies supply extruded salmonid, shrimp, and warmwater fish feeds today?
- What limits alternative-protein substitution or miller margins in the fish feed market?
- What should aquaculture farm managers evaluate before qualifying a commercial fish feed ration?
Frequently Asked Questions
How large is the Fish Feed Market expected to be in 2026, and what is forecast for 2036?
The global fish feed market is estimated to reach USD 34.0 billion in 2026. The market is projected to expand further and reach USD 53.3 billion by 2036.
What CAGR is forecast for the Fish Feed Market through 2036?
As per FMI, the fish feed market is projected to grow at a 4.6% CAGR from 2026 to 2036. Growth is supported by expanding commercial finfish and shrimp farming and rising adoption of high-energy extruded feeds.
Which product form holds a notable fish feed demand share in 2026?
Fresh Chilled Cuts & Fillets is projected to hold 38.9% of product form demand in 2026. The segment benefits from high moisture palatability, rapid amino-acid digestion, and strong feeding response in marine hatcheries and broodstock cages.
Which species and source segment leads the fish feed market in 2026?
Wild capture marine fishery is estimated to account for 55.5% of species and source demand in 2026. Demand is supported by pelagic anchoveta and menhaden reduction streams supplying digestible marine protein and long-chain omega-3 oils.
Which country has a notable fish feed expansion outlook during the forecast period?
FMI finds that Iceland is projected to expand at a 5.6% CAGR during the 2026 to 2036 assessment period. Growth is supported by geothermal land-based recirculating salmon farms and expanding fjord aquaculture biomass.
Which companies are active in the Fish Feed Market during 2026?
Notable companies include Nutreco N.V. (Skretting), Cargill Aqua Nutrition, BioMar Group, Alltech (Coppens), Charoen Pokphand Foods (CPF), Tongwei Co., Ltd., Ridley Corporation Limited, and Haid Group. These compounders focus on vacuum lipid coating, microalgal DHA inclusion, and low-FCR extruded pellets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Fresh Chilled Cuts & Fillets
- Frozen Portions & Blocks
- Canned & Shelf-Stable
- Value-Added & Breaded
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Species / Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Species / Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Species / Source, 2026 to 2036
- Wild Capture Marine Fishery
- Commercial Aquaculture / Farm Raised
- Livestock Pasture Raised
- Y-o-Y Growth Trend Analysis By Species / Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Species / Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Food Service & Restaurants
- Supermarkets & Retail Consumers
- Industrial Food Processing Plants
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Iceland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Norway
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Species / Source
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nutreco N.V. (Skretting)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Cargill Aqua Nutrition
- BioMar Group
- Alltech (Coppens)
- Charoen Pokphand Foods (CPF)
- Tongwei Co., Ltd.
- Ridley Corporation Limited
- Haid Group
- Nutreco N.V. (Skretting)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


