
- Market Size (2026)
- USD 550.0 Mn
- Forecast (2036)
- USD 1102.3 Mn
- CAGR (2026 to 2036)
- 7.2%
How big is Fish Gelatin Market in 2026?
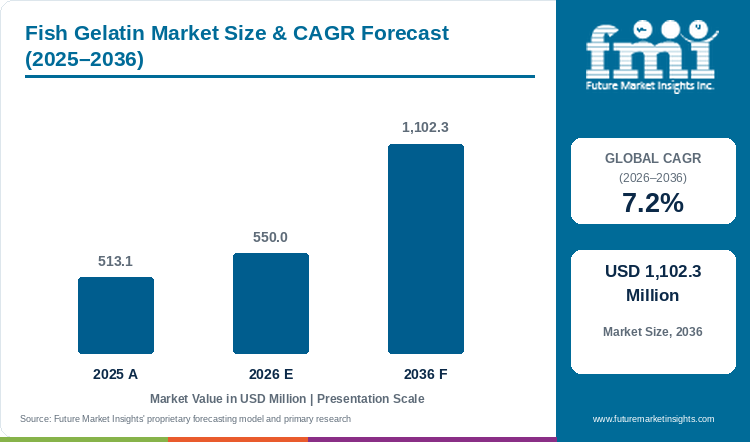
Demand for fish gelatin is projected to rise at 7.2% CAGR through 2036. Sector valuation increases from USD 513.1 million in 2025 to USD 550.0 million in 2026 and is predicted to reach USD 1,102.3 million by 2036.
Pharmaceutical softgel molders, Halal confectionery plants, and fine-pastry kitchens increasingly specify marine-derived gelatin to avoid porcine religious restrictions and mammalian bovine spongiform encephalopathy (BSE) certification hurdles. Extracting Type A gelatin from cold-water cod and warm-water tilapia skins gives formulators reversible hydrocolloid gels with tailored melting points between 21°C and 35°C. According to Future Market Insights analysis, global fish gelatin revenue rises from USD 513.1 million in 2025 to USD 550.0 million in 2026 and is projected to reach USD 1,102.3 million by 2036, advancing at a 7.2% CAGR and adding USD 552.3 million in new revenue. In October 2024, the Gelatin Manufacturers of Europe published Version 13 of its Standardised Methods for the Testing of Edible Gelatine, harmonizing Bloom gel strength, viscosity, and heavy-metal assay protocols across acid-extracted and alkaline-extracted edible gelatins [1]. Chilled-Skin Extracted High-Bloom Granules & Powders hold 41.6% of product form revenue in 2026 alongside hydrolyzed marine collagen co-product streams.
Key Market Trends & Insights
- By product form: Chilled-Skin Extracted High-Bloom Granules & Powders led the category with a 41.6% share in 2026, because processing fresh un-frozen fish skins within 24 hours of filleting prevents collagenase breakdown and yields 220 to 280 Bloom granules.
- By species / source: Wild Capture Marine Fishery accounted for 42.2% of demand in 2026, as Marine Stewardship Council certified cod, haddock, and pollock skins provide low-viscosity gelatin ideal for fast-melt oral dosage films and micro-encapsulation.
- By end-use sector: With a 49.8% share in 2026, Culinary Foodservice, Patisserie & Confectionery Manufacturing held the leading position, owing to rapid aroma release at sub-body melting temperatures and universal Halal and Kosher acceptance.
Regional Highlights
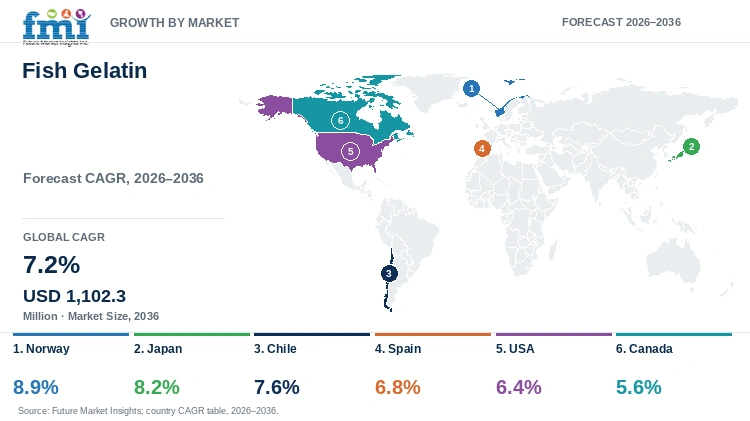
- Fastest-growing evaluated country: Norway, at 8.9% CAGR from 2026 to 2036.
- By country: Japan at 8.2%, Chile at 7.6%, Spain at 6.8%, and the USA at 6.4% follow, while Canada records the lowest evaluated CAGR at 5.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Fish Gelatin Market (USD million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 513.1 million |
| Estimated Market Size in 2026 | USD 550.0 million |
| Projected Market Size by 2036 | USD 1,102.3 million |
| CAGR, 2026 to 2036 | 7.2% |
| Added Revenue, 2026 to 2036 | USD 552.3 million |
Pharmacopeial purity rules and allergen disclosure laws across the United States, the European Union, and East Asia govern how marine gelatin is qualified for oral capsules and retail confectionery. In the U.S. Food and Drug Administration's Substances Added to Food (formerly EAFUS) registry updated through July 2026, edible gelatin (CAS Reg. No. 9000-70-8) is listed for technical food-grade and encapsulation uses subject to good manufacturing practice and mandatory major food allergen labeling when derived from finfish species [2]. Because nutraceutical formulators increasingly specify marine hydrocolloids for two-piece hard gelatin capsules and pastry chefs rely on transparent culinary gelatin sheets, extraction refineries must deploy multi-stage ion-exchange de-ionization and activated-carbon filtration to strip trimethylamine odors and keep heavy metals below 1.0 ppm.
Extraction Refinery Yield and Tonnage Sizing
Table 2: Extraction Tonnage and Feedstock Recovery Indicators for the Fish Gelatin Market (USD million, thousand tonnes, and USD per kilogram), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD million) | 513.1 | 550.0 | 1,102.3 |
| Refined fish gelatin volume (thousand tonnes) | 31.5 to 34.2 | 33.6 to 36.5 | 62.5 to 68.0 |
| Upcycled raw fish skin & scale feedstock (thousand tonnes) | 210 to 245 | 224 to 260 | 415 to 475 |
| Average realized price per kilogram (USD/kg) | 15.00 to 16.30 | 15.10 to 16.40 | 16.20 to 17.65 |
Operational note: Refined volume and raw skin feedstock estimates reflect dry-weight Type A and Type B fish gelatin extracted at 14% to 16% collagen recovery yield across commercial acid and enzymatic biorefineries.
Per Capita & Biorefinery Line Sizing
Co-locating acid extraction skids adjacent to industrial whitefish and salmon filleting plants reduces refrigerated skin transport costs and prevents bacterial histamine formation. Warm-water tilapia and pangasius skins sourced from tropical aquaculture contain higher hydroxyproline and proline amino-acid ratios than cold-water cod, lifting gel melting points to 32°C to 35°C for shelf-stable gummies. Meanwhile, cold-water skins routed to enzymatic gelatin hydrolysates and low-temperature gelatin lines serve oil-in-water vitamin emulsions and cryogenic biological coatings.
Table 3: Per Capita and Refinery Plant Spending Indicators for the Fish Gelatin Market (USD and cents metrics), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.06 | 0.07 | 0.12 |
| Spend per 1,000 people (USD) | 62.3 | 66.3 | 123.2 |
| Annual revenue per commercial marine gelatin extraction line (USD million) | 6.8 to 7.9 | 7.2 to 8.4 | 11.8 to 13.6 |
Table 4: Segment and Source Revenue Indicators for the Fish Gelatin Market (USD million and percentages), mixed reporting years from 2025 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 550.0 million | Report value |
| Chilled-skin extracted high-Bloom granules & powders, 2026 | USD 228.8 million | 41.6% product form share |
| Wild capture marine fishery source revenue, 2026 | USD 232.1 million | 42.2% species / source share |
| Culinary foodservice, patisserie & confectionery revenue, 2026 | USD 273.9 million | 49.8% end-use sector share |
Operational note: Historical 2025 and base-year 2026 indicators in Tables 2, 3, and 4 are derived from Gelatin Manufacturers of Europe (GME) production benchmarks, FAO fishery byproduct yield coefficients, and FDA GRAS specifications, while 2036 figures represent FMI econometric model projections.
Analyst Perspective
"Warm-water tilapia and upcycled salmon skin biorefining allow fish gelatin to match mammalian Bloom strength across Halal softgels and confectionery. Processors must still manage cold-water melting thresholds and mandatory finfish allergen declarations on consumer labels."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the fish gelatin market segmented?
The fish gelatin market is segmented by product form, species / source, end-use sector, and region. In 2026, Chilled-Skin Extracted High-Bloom Granules & Powders is projected at 41.6%, Wild Capture Marine Fishery at 42.2%, and Culinary Foodservice, Patisserie & Confectionery Manufacturing at 49.8%.
By product form: Chilled-Skin Extracted High-Bloom Granules & Powders, Frozen-Skin Extracted Standard Gelatin Blocks & Sheets, Shelf-Stable Liquid Gelatin & Culinary Glazes, and Enzymatically Hydrolyzed Collagen & Micro-Encapsulation Grades.
By species / source: Wild Capture Marine Fishery (Cod, Pollock & Haddock), Commercial Aquaculture / Farm Raised (Tilapia, Pangasius & Salmon), and Pelagic & Mixed Marine Byproduct Streams.
By end-use sector: Culinary Foodservice, Patisserie & Confectionery Manufacturing, Pharmaceutical Softgels & Nutraceutical Capsules, and Industrial Food Processing, Emulsions & Biomedical Coatings.
Why Do Chilled-Skin Extracted High-Bloom Granules & Powders Lead the Fish Gelatin Market by Product Form?
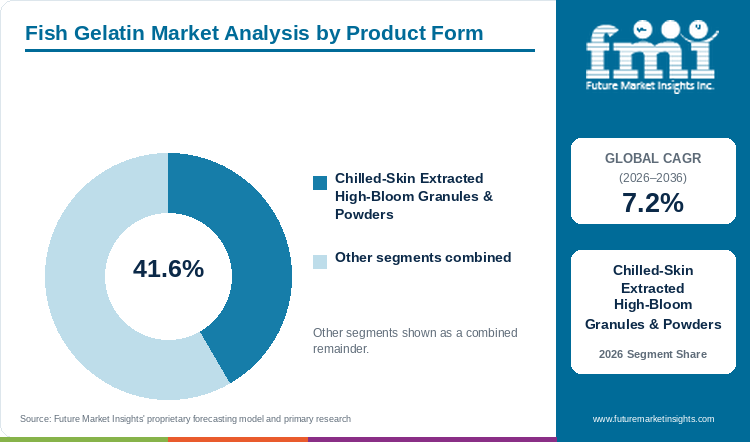
Chilled-Skin Extracted High-Bloom Granules & Powders is projected to hold 41.6% of product form demand in 2026, supported by triple-helix preservation.
Table 5: Product Form Share for the Fish Gelatin Market (percentage share), 2026
| Product Form | Share (2026) |
|---|---|
| Chilled-Skin Extracted High-Bloom Granules & Powders | 41.6% |
| Frozen-Skin Extracted Standard Gelatin Blocks & Sheets | 30.5% |
| Shelf-Stable Liquid Gelatin & Culinary Glazes | 15.4% |
| Enzymatically Hydrolyzed Collagen & Micro-Encapsulation Grades | 12.5% |
| Total | 100.0% |
*Calculated across mutually exclusive extracted fish gelatin product forms totaling 100.0% of 2026 demand.
Table 6: Product Form Leadership and Market Growth for the Fish Gelatin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.2% |
| Leading Segment | Chilled-Skin Extracted High-Bloom Granules & Powders |
Chilled-Skin Extracted High-Bloom Granules & Powders command the largest form share because routing freshly deskinned filleting side-streams directly into chilled dilute organic-acid baths preserves native alpha-chain molecular weight before endogenous proteases cleave the collagen helix. Resulting 200 to 280 Bloom crystalline granules dissolve rapidly on rotary softgel encapsulation lines and in marine collagen based products without fishy off-notes. Frozen-skin extracted standard blocks and leaf sheets hold 30.5% of demand for cross-border skin shipping, while liquid culinary glazes (15.4%) and enzymatic micro-encapsulation grades (12.5%) serve specialized spray-glazing and oil-beadlet lines.
- Chilled-Skin Extracted High-Bloom Granules & Powders are projected to account for 41.6% of product form revenue in 2026, supported by high gel strength and zero-odor membrane filtration.
- In April 2025, Rousselot, the health brand of Darling Ingredients Inc., earned Upcycled Certified status from the Upcycled Food Association and Where Food Comes From for its Peptan marine and mammalian collagen and gelatin raw-material valorization chain [3].
What Makes Wild Capture Marine Fishery Central to the Species / Source Category?
Wild Capture Marine Fishery is estimated to represent 42.2% of species / source demand in 2026, reflecting cold-water whitefish skin purity.
Wild Capture Marine Fishery leads supply source revenue in 2026 because North Atlantic and Bering Sea whitefish filleting plants generate large volumes of lean, low-lipid cod, haddock, and Alaska pollock skins certified under Marine Stewardship Council (MSC) chain-of-custody standards. Cold-water wild fish gelatin stays liquid at 10°C to 15°C due to lower hydroxyproline content, making it indispensable for heat-sensitive oil micro-encapsulation, rapid-melt sublingual drug strips, and clean-label gelatin substitutes in chilled dairy. Commercial warm-water aquaculture sources (tilapia and pangasius) are projected to overtake wild capture by 2036 as processors expand high-melting-point softgel lines.
- Wild Capture Marine Fishery is estimated to hold 42.2% of species / source demand in 2026, reflecting lean cold-water cod skin purity and MSC chain-of-custody verification.
- In September 2025, Nitta Gelatin NA Inc. updated its Wellnex and Vyse technical portfolios highlighting both wild-caught North Atlantic marine gelatin and fresh-water fish collagen grades tailored for rapid-dissolution dosage forms [4].
Why Does Culinary Foodservice, Patisserie & Confectionery Manufacturing Anchor the End-Use Sector Category?
Culinary Foodservice, Patisserie & Confectionery Manufacturing is forecast to capture 49.8% of end-use sector sales in 2026, driven by Halal confectionery.
Culinary Foodservice, Patisserie & Confectionery Manufacturing generates nearly half of category revenue because multinational gummy makers, commercial bakeries, and hotel patisseries require a single hydrocolloid that satisfies both Islamic Halal and Jewish Kosher pareve certifications without altering traditional gelatin bounce. Because marine gelatin melts 5°C to 10°C below mammalian gelatin, fruit mousses, mirror glazes, and soft chews release volatile citrus and berry aromatics immediately upon oral contact. Pharmaceutical softgels and nutraceutical capsules capture 31.2% of demand, while industrial emulsions, biodegradable gelatin films, and biomedical matrices account for 19.0%.
- Culinary Foodservice, Patisserie & Confectionery Manufacturing is anticipated to represent 49.8% of end-use sector sales in 2026, driven by Halal gummy manufacturing and fine-pastry mirror glazes.
- In July 2024, PB Leiner (Tessenderlo Group) expanded technical application support for its SOLUGEL and TEXTURA fish gelatin and collagen lines featuring near-water organoleptics for confectionery, beverages, and patisserie glazes [5].
What are the drivers, restraints, and opportunities in the fish gelatin market?
In the Fish Gelatin Market, universal Halal and Kosher compliance and seafood byproduct valorization drive pharmaceutical and confectionery adoption, whereas cold-water thermal softening and wild whitefish quotas restrain supply, and warm-water tilapia cross-linking plus hemostatic medical matrices unlock high-margin growth through 2036.
- Driver:Universal Islamic Halal and Jewish Kosher eligibility combined with zero mammalian prion (BSE/TSE) risk accelerates pharmaceutical softgel and gummy reformulation.
- Restraint:Low melting points (21°C to 25°C) in cold-water fish gelatin and seasonal North Atlantic cod catch quotas create tropical shipping and raw-skin cost pressures.
- Opportunity:Scaling warm-water aquaculture tilapia gelatin (32°C to 35°C melting point) alongside endotoxin-free biomedical sponges and edible barrier films opens premium revenue streams.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Pharmaceutical capsule molders and multinational confectionery brands are adopting fish gelatin to unify global SKUs across Halal, Kosher, and pescatarian consumer markets while lowering corporate scope-3 environmental footprints. In March 2026, the Gelatin Manufacturers of Europe published its updated Water Footprint of Gelatine and Collagen Peptides assessment (covering member production through 2024), documenting continuous reductions in processing water intensity across European upcycled collagen refineries [6]. By converting discarded salmon, cod, and tilapia skins into high-Bloom pharmaceutical granules and medical gelatin filters, processors eliminate the ritual slaughter documentation required for bovine hides and completely bypass porcine religious prohibitions across Southeast Asia and the Middle East.
Risk Assessment of the Fish Gelatin Market: Operational and Supply Friction
Thermal softening in cold-water marine grades and biological catch limits on wild North Atlantic whitefish stocks constrain uninterrupted raw-material sourcing. According to the Food and Agriculture Organization of the United Nations (FAO) Fisheries and Aquaculture Country Profile for Norway, wild marine capture landings remain tightly regulated by bilateral Barents Sea and North Atlantic quota agreements to preserve spawning biomass [7]. Because cold-water cod and haddock skins contain fewer imino acids (proline and hydroxyproline) than mammalian hides, unblended cold-water fish gelatin gels melt between 21°C and 25°C, causing unrefrigerated pharmaceutical softgel capsules or gummies to agglomerate in tropical distribution corridors unless stabilized with warm-water tilapia gelatin or pectin.
Commercial Opportunity Analysis: Differentiation and Value-Add Formats
Gelatin refiners are expanding margins by pairing certified warm-water aquaculture tilapia extraction with ultra-pure biomedical hydrogels, surgical hemostats, and fast-dissolving oral delivery matrices. In July 2024, PB Leiner secured dual Friend of the Sea (FOS) and Best Aquaculture Practices (BAP) sustainability certifications across its SOLUGEL marine collagen and gelatin portfolio, giving nutraceutical brands verifiable aquaculture traceability [8]. Furthermore, in November 2025, Darling Ingredients' Rousselot unit unveiled specialized ultra-low-endotoxin gelatin prototypes for medical device scaffolds, hemostatic sponges, and drug-delivery applications at the COMPAMED 2025 exhibition in Düsseldorf [9]. Refiners that co-produce high-Bloom warm-water softgel gelatin alongside low-molecular-weight fish collagen peptides maximize revenue per tonne of incoming fish skin.
Fish Gelatin Market by Country (2026 to 2036)
In the FMI report, Norway posts the fastest growth among the six evaluated countries at an 8.9% CAGR from 2026 to 2036, followed by Japan at 8.2%, Chile at 7.6%, Spain at 6.8%, and the USA at 6.4%, while Canada records a 5.6% CAGR. Across these national markets, expansion trajectories depend on domestic salmon and whitefish filleting volumes, coastal biorefinery integration, Halal softgel contract manufacturing, and nutricosmetic consumption.
Table 7: Country CAGR and Primary Growth Levers for the Fish Gelatin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Norway | 8.9% | 1.5 million tonnes of aquaculture exports and automated zero-waste salmon skin biorefining |
| Japan | 8.2% | Foods with Function Claims (FFC) marine collagen jellies and precision enzymatic peptide refining |
| Chile | 7.6% | 1.52 million tonnes of aquaculture harvests in Los Lagos and Aysén supplying export skin blocks |
| Spain | 6.8% | Southern Europe's largest marine aquaculture and tuna/hake canning base supplying Catalan softgel molders |
| USA | 6.4% | Halal and Kosher nutraceutical softgel encapsulation and FDA-compliant marine gummy manufacturing |
| Canada | 5.6% | North Atlantic cold-water cod and haddock skin extraction for technical and photographic coatings |
Source: Future Market Insights analysis
Norway Fish Gelatin Market Outlook (2026 to 2036)
Automated coastal salmon slaughterhouses and mandatory marine rest-raw-material utilization laws position Norway as Europe's primary feedstock engine for cold-water fish gelatin. In January 2026, the Norwegian Seafood Council reported that Norway exported 1.5 million tonnes of aquaculture seafood in 2025, including 1.415 million tonnes of farmed Atlantic salmon, generating massive chilled skin volumes at coastal filleting terminals [10]. Sales of fish gelatin in Norway are forecast to expand at an 8.9% CAGR through 2036 as processors pipe deskinned salmon trimmings directly into enzymatic extraction reactors. While high lipid content in salmon skins requires intensive multi-stage degreasing to prevent rancidity, Norwegian biorefineries are deploying membrane ultrafiltration to export odorless pharmaceutical gelatin across Europe.
Key takeaway: In Norway, record 1.415-million-tonne salmon export processing and co-located coastal biorefineries drive the fastest national fish gelatin expansion globally through 2036.
Japan Fish Gelatin Market Outlook (2026 to 2036)
Deeply ingrained consumer consumption of ingestible beauty jellies and precision biomedical hydrogel engineering set Japan's fish gelatin market apart from bulk Western food-gelling sectors. By 2036, Japan is projected to grow at an 8.2% CAGR, supported by domestic pharmaceutical capsule molders and clinical nutricosmetic formulators. Following the Consumer Affairs Agency's October 1, 2025 regulatory update tightening PRISMA-2020 systematic review and GMP manufacturing compliance for Foods with Function Claims (FFC), Japanese supplement brands increasingly specify traceable low-molecular-weight marine gelatin and tripeptides [11]. Yet commercial uptake faces friction from declining domestic wild pelagic catches and yen-denominated import costs on frozen tilapia scales. Japanese refiners consequently focus on ultra-pure biomedical hemostats and sublingual film excipients.
Key takeaway: In Japan, tightened Consumer Affairs Agency functional-food standards and pharmaceutical oral-film innovation sustain high-margin demand for purified marine gelatin.
Chile Fish Gelatin Market Outlook (2026 to 2036)
Industrial-scale salmonid filleting clusters across the Los Lagos and Aysén regions make Chile the Southern Hemisphere's largest reservoir of cold-water marine collagen skins. According to the National Fisheries and Aquaculture Service (Sernapesca) 2025 Statistical Yearbook released in June 2026, Chilean aquaculture harvests rose 4% in 2025 to reach 1,525,400 tonnes, led by 810,892 tonnes of Atlantic salmon and expanding Coho salmon output [12]. The Chile fish gelatin sector is projected to record a 7.6% CAGR from 2026 to 2036 as Puerto Montt processors monetize filleting side-streams. However, limited domestic pharmaceutical spray-drying capacity and long maritime freight routes to Northern Hemisphere buyers constrain local value capture, prompting joint-venture extraction investments.
Key takeaway: In Chile, 1.52-million-tonne aquaculture harvests provide abundant salmonid skin feedstock to support expanding domestic crude and refined gelatin exports.
Spain Fish Gelatin Market Outlook (2026 to 2036)
Integration between Galician and Andalusian seafood canneries and Catalonia's contract pharmaceutical softgel cluster defines Spain's commercial fish gelatin trajectory. In November 2025, the Spanish Aquaculture Business Association (APROMAR) and the Ministry of Agriculture, Fisheries and Food (MAPA) published their annual national report confirming Spain's leadership in European Union aquaculture volume alongside extensive sea bream, sea bass, and turbot processing [13]. Demand across the Spain fish gelatin sector is expected to increase at a 6.8% CAGR through 2036 as Mediterranean patisserie and omega-3 softgel plants expand. Nonetheless, rising industrial water-treatment tariffs and summer ambient warehouse temperatures challenge low-Bloom cold-water gels. Spanish converters are blending warm-water fish gelatin to stabilize confectionery textures.
Key takeaway: In Spain, domestic fish-processing byproduct streams and Catalan pharmaceutical softgel manufacturing anchor steady 6.8% annual category expansion through 2036.
USA Fish Gelatin Market Outlook (2026 to 2036)
Contract nutraceutical gummy manufacturing and religiously inclusive Halal and Kosher supplement branding drive commercial fish gelatin procurement across the United States. In the USA, demand for fish gelatin is predicted to advance at a 6.4% CAGR through 2036 as coastal supplement co-packers reformulate marine omega-3 and multivitamin softgels. Under the U.S. Food and Drug Administration's Substances Added to Food inventory and Food Allergen Labeling requirements (21 U.S.C. 343(w)), food and supplement brands utilizing marine gelatin must declare the specific finfish species, such as cod, pollock, or tilapia, on retail packaging [14]. The central commercial obstacle involves segregated allergen washdown cycles on shared confectionery lines, encouraging dedicated marine-only encapsulation suites.
Key takeaway: In the USA, Kosher and Halal supplement encapsulation growth outweighs species-specific FDA allergen labeling hurdles to sustain a 6.4% CAGR through 2036.
Canada Fish Gelatin Market Outlook (2026 to 2036)
Cold-water Atlantic groundfish processing and federal ocean-bioeconomy commercialization grants shape Canada's specialized marine gelatin extraction industry. In March 2026, Fisheries and Oceans Canada (DFO) published its Canada's Fisheries Fast Facts 2025 compendium, documenting multi-billion-dollar commercial sea-fishery and aquaculture landings across Nova Scotia, Newfoundland and Labrador, and British Columbia that supply high-purity whitefish and salmonid skins [15]. Canada's fish gelatin outlook is anticipated to advance at a 5.6% CAGR over the assessment period, supported by exports of non-gelling cold-water gelatin for photoresists, micro-encapsulated vitamin beadlets, and diagnostic reagent coatings. Nevertheless, seasonal North Atlantic ice coverage and dispersed Maritime landing ports elevate raw-skin collection logistics, favoring long-term frozen skin supply contracts.
Key takeaway: In Canada, Atlantic cold-water whitefish byproduct valorization and specialty technical and diagnostic coating exports support a steady 5.6% growth rate through 2036.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the fish gelatin market?
Darling Ingredients Inc. (Rousselot), Nitta Gelatin Inc., PB Leiner (Tessenderlo Group), Weishardt Holding SA, Lapi Gelatine SpA, GELITA AG, Seagarden AS, and Nippi, Incorporated are the notable companies in the fish gelatin market.
Supplier qualification in the fish gelatin sector depends on raw-skin species traceability, multi-stage de-odorizing ion-exchange filtration, Bloom gel-strength consistency, and dual Halal and Kosher certification. Multinational hydrocolloid leaders Darling Ingredients Inc. (via Rousselot), PB Leiner (Tessenderlo Group), and GELITA AG operate multi-continental extraction and enzymatic hydrolysis plants supplying both high-Bloom warm-water tilapia gelatin and biomedical-grade excipients. Japanese and European marine specialists Nitta Gelatin Inc., Weishardt Holding SA (maker of Naticol), Lapi Gelatine SpA, and Nippi, Incorporated engineer ultra-low-odor fish gelatins and clinically studied marine collagen peptides for pharmaceutical softgels, oral dissolve films, and nutricosmetic jellies. Meanwhile, Scandinavian processor Seagarden AS focuses on 100% wild-caught North Atlantic cod skin extraction.
- Global Multi-Origin Gelatin & Biomedical Leaders: Darling Ingredients Inc. (Rousselot), PB Leiner (Tessenderlo Group), and GELITA AG supply pharmaceutical-grade warm-water and cold-water fish gelatins alongside low-endotoxin medical matrices.
- European & Japanese Marine Gelatin & Peptide Specialists: Nitta Gelatin Inc., Weishardt Holding SA, Lapi Gelatine SpA, and Nippi, Incorporated specialize in high-Bloom confectionery and softgel fish gelatin and low-molecular-weight marine peptides.
- Nordic Wild-Capture Marine Byproduct Refiners: Seagarden AS upcycles MSC-certified wild North Atlantic whitefish skins into cold-water marine collagen and gelatin powders.
Competitive Benchmarking: Fish Gelatin Market
Table 8: Competitive Benchmarking for the Fish Gelatin Market (qualitative capability ratings), 2026
| Company | Marine Skin Traceability | De-Odorizing & Bloom Control | Halal & Kosher Accreditations | Global Pharma & Food Reach |
|---|---|---|---|---|
| Darling Ingredients Inc. (Rousselot) | High | High | High | High |
| Nitta Gelatin Inc. | High | High | High | High |
| PB Leiner (Tessenderlo Group) | High | High | High | High |
| Weishardt Holding SA | High | High | High | High |
| Lapi Gelatine SpA | High | High | High | Medium |
| GELITA AG | Medium | High | High | High |
| Seagarden AS | High | Medium | High | Medium |
| Nippi, Incorporated | High | High | Medium | Medium |
Scoring basis: Marine Skin Traceability is rated High for documented MSC, Friend of the Sea (FOS), or Best Aquaculture Practices (BAP) chain-of-custody verification. De-Odorizing & Bloom Control evaluates commercial production of sensory-neutral 200 to 280 Bloom warm-water and cold-water grades meeting USP/EP pharmacopeial limits. Halal & Kosher Accreditations and Global Pharma & Food Reach reflect international religious authority certifications and multi-regional warehousing.
Key Developments in the Fish Gelatin Market
- In October 2026, Weishardt Holding SA highlighted expanded European production of its fish gelatines, texturizing solutions, and Naticol marine collagen tripeptide and peptide grades for nutricosmetic and functional food formulations [16].
- In October 2026, Statistics Norway (SSB) documented sustained weekly export volumes exceeding 32,000 tonnes of fresh or chilled farmed salmon, reinforcing year-round raw skin availability for Scandinavian marine collagen and gelatin extractors [17].
- In January 2026, Chile's Undersecretariat for Fisheries and Aquaculture (Subpesca) published its December 2025 sectoral report confirming consolidated salmonid and marine harvest volumes supporting export-grade fish skin byproduct recovery [18].
Key Players in the Fish Gelatin Market
Global Multi-Origin Gelatin & Biomedical Leaders
- Darling Ingredients Inc. (Rousselot)
- PB Leiner (Tessenderlo Group)
- GELITA AG
European & Japanese Marine Gelatin & Peptide Specialists
- Nitta Gelatin Inc.
- Weishardt Holding SA
- Lapi Gelatine SpA
- Nippi, Incorporated
Nordic Wild-Capture Marine Byproduct Refiners
- Seagarden AS
Fish Gelatin Market - Report Scope
Table 9: Report Scope for the Fish Gelatin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Form; Species / Source; End-Use Sector; Region |
| Quantitative Units | USD Million |
| Market Definition | Encompasses global business-to-business manufacturer revenues from commercial food-grade, pharmaceutical-grade, and technical-grade gelatin extracted through thermal, acid (Type A), or alkaline/enzymatic (Type B) hydrolysis of collagen from finfish skins, scales, and bones. Supply & Format Scope Note: Market valuation captures refined B2B fish gelatin and functionalized marine hydrocolloid grades categorized by extraction pathway and physical delivery state (specifically Chilled-Skin Extracted High-Bloom Granules & Powders at 41.6%, Frozen-Skin Extracted Standard Gelatin Blocks & Sheets at 30.5%, Shelf-Stable Liquid Gelatin & Culinary Glazes at 15.4%, and Enzymatically Hydrolyzed Collagen & Micro-Encapsulation Grades at 12.5%) rather than downstream retail seafood fillets or mammalian bovine/porcine gelatins. |
| Regions Covered | Western Europe; North America; East Asia; Latin America; South Asia and Pacific; Eastern Europe; Middle East and Africa |
| Countries Covered | Norway, Japan, Chile, Spain, USA, Canada, and additional countries in the full report |
| Key Companies Covered | Darling Ingredients Inc. (Rousselot), Nitta Gelatin Inc., PB Leiner (Tessenderlo Group), Weishardt Holding SA, Lapi Gelatine SpA, GELITA AG, Seagarden AS, Nippi, Incorporated |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Fish Gelatin Market - Research Methodology
Table 10: Research Methodology for the Fish Gelatin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with marine biorefinery extraction engineers, aquaculture byproduct procurement directors, pharmaceutical softgel formulation scientists, Halal and Kosher certification auditors, and industrial confectionery technologists to validate skin-to-gelatin yield ratios, Bloom gel strength tolerances, and contract pricing. |
| Secondary Research | Secondary research included analysis of Gelatin Manufacturers of Europe (GME) testing monographs and sustainability reports, U.S. FDA GRAS and allergen registries, FAO and national fishery landing databases (Norwegian Seafood Council, Sernapesca, MAPA/APROMAR, DFO Canada), and corporate disclosures. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were constructed using bottom-up marine skin byproduct extraction capacity modeling reconciled with top-down pharmaceutical capsule, Halal confectionery, and culinary hydrocolloid demand. |
| Data Triangulation and Validation | Data points were cross-verified against commercial aquaculture filleting side-stream tonnage, dry gelatin recovery yields (14% to 16% by raw skin weight), international customs HS 3503.00 trade records, and pharmacopeial excipient filings. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's marine biomaterial econometric model, calibrating national trajectories against the 7.2% global baseline using national aquaculture skin supply growth (Norway, Chile, Spain), functional-food clinical claim velocity (Japan CAA), and Halal/Kosher softgel contract manufacturing scale (USA, Canada). |
| Operational Benchmark Traceability | Operational benchmarks (refined fish gelatin tonnage, upcycled raw skin feedstock volume, and average realized price per kilogram in Tables 2, 3, and 4) are synthesized from GME Standardised Methods (Version 13), GME Water Footprint statements, and FAO fishery byproduct conversion ratios. |
Fish Gelatin Market by Segments
Fish Gelatin Market segmented by Product Form:
- Chilled-Skin Extracted High-Bloom Granules & Powders
- Frozen-Skin Extracted Standard Gelatin Blocks & Sheets
- Shelf-Stable Liquid Gelatin & Culinary Glazes
- Enzymatically Hydrolyzed Collagen & Micro-Encapsulation Grades
Fish Gelatin Market segmented by Species / Source:
- Wild Capture Marine Fishery (Cod, Pollock & Haddock)
- Commercial Aquaculture / Farm Raised (Tilapia, Pangasius & Salmon)
- Pelagic & Mixed Marine Byproduct Streams
Fish Gelatin Market segmented by End-Use Sector:
- Culinary Foodservice, Patisserie & Confectionery Manufacturing
- Pharmaceutical Softgels & Nutraceutical Capsules
- Industrial Food Processing, Emulsions & Biomedical Coatings
Fish Gelatin Market by Region
- Western Europe
- Norway
- Spain
- France
- Germany
- UK
- Netherlands
- Italy
- North America
- USA
- Canada
- East Asia
- Japan
- South Korea
- China
- Latin America
- Chile
- Brazil
- Peru
- South Asia and Pacific
- Australia
- New Zealand
- Vietnam
- Eastern Europe
- Poland
- Czechia
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Gelatin Manufacturers of Europe (GME). (2024, October 19). standardised methods for the testing of edible gelatine. Gelatin Manufacturers of Europe (Gelatine Monograph Version 13).
- [2] U.S. Food and Drug Administration (FDA). (2026, July 28). Gelatin. U.S. Food and Drug Administration Substances Added to Food (formerly EAFUS).
- [3] Darling Ingredients Inc. (Rousselot). (2025, April 24). Rousselot granted Upcycled Certified® status for Peptan. Darling Ingredients / Rousselot Newsroom.
- [4] Nitta Gelatin NA Inc. (2025, September 29). Brochures | Nitta Gelatin. Nitta Gelatin NA Inc.
- [5] PB Leiner (Tessenderlo Group). (2024, July 15). SOLUGEL® premium fish collagen peptides - PB Leiner. PB Leiner.
- [6] Gelatin Manufacturers of Europe (GME). (2026, March 12). Water Footprint of gelatine and collagen peptides. Gelatin Manufacturers of Europe.
- [7] Food and Agriculture Organization of the United Nations (FAO). (2024, October 10). Norway - Fisheries and Aquaculture. Food and Agriculture Organization of the United Nations.
- [8] PB Leiner (Tessenderlo Group). (2024, July 18). SOLUGEL®: certificates & co-branding - PB Leiner. PB Leiner.
- [9] Darling Ingredients Inc. (Rousselot). (2025, November 10). Rousselot collagen and gelatin | Darling Ingredients. Darling Ingredients.
- [10] Norwegian Seafood Council (Norges sjømatråd). (2026, January 06). Price growth for wild fish and increased salmon volume resulted in record value for Norwegian seafood exports in 2025. Norwegian Seafood Council.
- [11] Consumer Affairs Agency, Government of Japan (CAA). (2025, November 07). A Complete Overview of the Latest Notices on Foods with Function Claims in Japan. ChemLinked Regulatory Database / Consumer Affairs Agency (CAA).
- [12] Servicio Nacional de Pesca y Acuicultura (Sernapesca). (2026, June 03). Acuicultura chilena aumentó 4% sus cosechas durante 2025 y superó los 1,5 millones de toneladas. Mundo Acuícola / Sernapesca.
- [13] Asociación Empresarial de Acuicultura de España (APROMAR) & Ministerio de Agricultura, Pesca y Alimentación (MAPA). (2025, November 16). LA ACUICULTURA EN ESPAÑA - Apromar. APROMAR / Ministerio de Agricultura, Pesca y Alimentación.
- [14] U.S. Food and Drug Administration (FDA). (2025, May 20). Substances Added to Food (formerly EAFUS). U.S. Food and Drug Administration.
- [15] Fisheries and Oceans Canada (DFO). (2026, March 17). Canada's fisheries fast facts 2025. Government of Canada / Fisheries and Oceans Canada.
- [16] Weishardt Holding SA. (2026, October 13). About Weishardt. Weishardt Group.
- [17] Statistics Norway (Statistisk sentralbyrå - SSB). (2026, October 14). Export of salmon - SSB. Statistics Norway.
- [18] Subsecretaría de Pesca y Acuicultura (Subpesca). (2026, January 30). Informe Sectorial de Pesca y Acuicultura: producción pesquera y acuícola de Chile (diciembre 2025). Gobierno de Chile / Subpesca.
- [19] PB Leiner (Tessenderlo Group). (2025, October 29). PB Leiner @ SupplySide Global. PB Leiner News.
- [20] Norwegian Directorate of Fisheries (Fiskeridirektoratet). (2024, October 10). About Statistics for Aquaculture - English. Norwegian Directorate of Fisheries.
- [21] Nitta Gelatin NA Inc. (2025, October 15). Collagen Peptides | Nitta Gelatin. Nitta Gelatin NA Inc.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the fish gelatin market in 2026 and what is forecast for 2036?
- Which religious compliance and circular aquaculture drivers support demand for fish gelatin?
- Why do Chilled-Skin Extracted High-Bloom Granules & Powders lead the product form category?
- Why does Wild Capture Marine Fishery lead the species / source category in 2026?
- How do growth rates differ across Norway, Japan, Chile, Spain, the USA, and Canada?
- Which leading marine biorefineries and hydrocolloid companies produce fish gelatin today?
- What thermal melting and allergen labeling factors limit adoption in the fish gelatin market?
- What should pharmaceutical and confectionery buyers evaluate before qualifying a fish gelatin supplier?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Product Form, 2026 to 2036
- Chilled-Skin Extracted High-Bloom Granules & Powders
- Frozen-Skin Extracted Standard Gelatin Blocks & Sheets
- Shelf-Stable Liquid Gelatin & Culinary Glazes
- Enzymatically Hydrolyzed Collagen & Micro-Encapsulation Grades
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Species / Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Species / Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Species / Source, 2026 to 2036
- Wild Capture Marine Fishery (Cod, Pollock & Haddock)
- Commercial Aquaculture / Farm Raised (Tilapia, Pangasius & Salmon)
- Pelagic & Mixed Marine Byproduct Streams
- Y-o-Y Growth Trend Analysis By Species / Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Species / Source, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End-Use Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End-Use Sector, 2026 to 2036
- Culinary Foodservice, Patisserie & Confectionery Manufacturing
- Pharmaceutical Softgels & Nutraceutical Capsules
- Industrial Food Processing, Emulsions & Biomedical Coatings
- Y-o-Y Growth Trend Analysis By End-Use Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- Western Europe
- North America
- East Asia
- Latin America
- South Asia and Pacific
- Eastern Europe
- Middle East and Africa
- Market Attractiveness Analysis By Region
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Norway
- Spain
- France
- Germany
- UK
- Netherlands
- Italy
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Chile
- Brazil
- Peru
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- Vietnam
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czechia
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Form
- By Species / Source
- By End-Use Sector
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Form
- By Species / Source
- By End-Use Sector
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- Norway
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Form
- By Species / Source
- By End-Use Sector
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Form
- By Species / Source
- By End-Use Sector
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Darling Ingredients Inc. (Rousselot)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nitta Gelatin Inc.
- PB Leiner (Tessenderlo Group)
- Weishardt Holding SA
- Lapi Gelatine SpA
- GELITA AG
- Seagarden AS
- Nippi, Incorporated
- Darling Ingredients Inc. (Rousselot)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Million) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 3: Global Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 4: Global Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 5: Western Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 6: Western Europe Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 7: Western Europe Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 8: Western Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 9: North America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 10: North America Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 11: North America Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 12: North America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 13: East Asia Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 14: East Asia Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 15: East Asia Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 16: East Asia Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 17: Latin America Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 18: Latin America Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 19: Latin America Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 20: Latin America Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 21: South Asia and Pacific Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 22: South Asia and Pacific Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 23: South Asia and Pacific Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 24: South Asia and Pacific Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
- Table 29: Middle East and Africa Market Value (USD Million) Forecast by Country, 2021 to 2036
- Table 30: Middle East and Africa Market Value (USD Million) Forecast by Product Form, 2021 to 2036
- Table 31: Middle East and Africa Market Value (USD Million) Forecast by Species / Source, 2021 to 2036
- Table 32: Middle East and Africa Market Value (USD Million) Forecast by End-Use Sector, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Million) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Form
- Figure 6: Global Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Species / Source
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Sector
- Figure 12: Global Market Value (USD Million) Share and BPS Analysis by Region, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Region
- Figure 15: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 16: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 17: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 18: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 23: Western Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 24: Western Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 25: Western Europe Market Attractiveness Analysis by Product Form
- Figure 26: Western Europe Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 27: Western Europe Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 28: Western Europe Market Attractiveness Analysis by Species / Source
- Figure 29: Western Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 30: Western Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 31: Western Europe Market Attractiveness Analysis by End-Use Sector
- Figure 32: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 33: North America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 34: North America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 35: North America Market Attractiveness Analysis by Product Form
- Figure 36: North America Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 37: North America Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 38: North America Market Attractiveness Analysis by Species / Source
- Figure 39: North America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 40: North America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 41: North America Market Attractiveness Analysis by End-Use Sector
- Figure 42: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 43: East Asia Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 44: East Asia Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 45: East Asia Market Attractiveness Analysis by Product Form
- Figure 46: East Asia Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 47: East Asia Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 48: East Asia Market Attractiveness Analysis by Species / Source
- Figure 49: East Asia Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 50: East Asia Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 51: East Asia Market Attractiveness Analysis by End-Use Sector
- Figure 52: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 53: Latin America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 54: Latin America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 55: Latin America Market Attractiveness Analysis by Product Form
- Figure 56: Latin America Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 57: Latin America Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 58: Latin America Market Attractiveness Analysis by Species / Source
- Figure 59: Latin America Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 60: Latin America Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 61: Latin America Market Attractiveness Analysis by End-Use Sector
- Figure 62: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 63: South Asia and Pacific Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 64: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 65: South Asia and Pacific Market Attractiveness Analysis by Product Form
- Figure 66: South Asia and Pacific Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 67: South Asia and Pacific Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 68: South Asia and Pacific Market Attractiveness Analysis by Species / Source
- Figure 69: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 70: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 71: South Asia and Pacific Market Attractiveness Analysis by End-Use Sector
- Figure 72: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 73: Eastern Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 74: Eastern Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 75: Eastern Europe Market Attractiveness Analysis by Product Form
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 77: Eastern Europe Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 78: Eastern Europe Market Attractiveness Analysis by Species / Source
- Figure 79: Eastern Europe Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 80: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 81: Eastern Europe Market Attractiveness Analysis by End-Use Sector
- Figure 82: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 83: Middle East and Africa Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 84: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 85: Middle East and Africa Market Attractiveness Analysis by Product Form
- Figure 86: Middle East and Africa Market Value Share and BPS Analysis by Species / Source, 2026 and 2036
- Figure 87: Middle East and Africa Market Y-o-Y Growth Comparison by Species / Source, 2026-2036
- Figure 88: Middle East and Africa Market Attractiveness Analysis by Species / Source
- Figure 89: Middle East and Africa Market Value Share and BPS Analysis by End-Use Sector, 2026 and 2036
- Figure 90: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Sector, 2026-2036
- Figure 91: Middle East and Africa Market Attractiveness Analysis by End-Use Sector
- Figure 92: Global Market - Tier Structure Analysis
- Figure 93: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the fish gelatin market in 2026, and what is forecast for 2036?
Global fish gelatin sales are estimated to reach USD 550.0 million in 2026, rising from USD 513.1 million in 2025. The sector is projected to expand further and attain USD 1,102.3 million by 2036 as pharmaceutical softgel and Halal confectionery manufacturers scale non-mammalian hydrocolloid procurement.
What CAGR is forecast for the Fish Gelatin Market through 2036?
As per FMI, the fish gelatin market is projected to grow at a 7.2% CAGR from 2026 to 2036. Expansion is supported by universal Islamic Halal and Jewish Kosher compliance, zero bovine prion transmission risk, and circular upcycling of aquaculture filleting skins.
Which product form holds a notable fish gelatin demand share in 2026?
Chilled-Skin Extracted High-Bloom Granules & Powders are projected to hold 41.6% of product form demand in 2026. The segment benefits from immediate acid extraction of fresh un-frozen skins that preserves triple-helix collagen chains for 200 to 280 Bloom strength.
Which species / source segment holds a notable fish gelatin share in 2026?
Wild Capture Marine Fishery is estimated to account for 42.2% of species / source revenue in 2026. Demand is supported by MSC-certified North Atlantic and Pacific cod, pollock, and haddock skin streams offering rapid oral dissolution.
Which country has a notable fish gelatin expansion outlook during the forecast period?
FMI finds that Norway is forecast to expand at an 8.9% CAGR during the 2026 to 2036 assessment period. Growth is supported by 1.5 million tonnes of annual aquaculture seafood exports and co-located coastal salmon skin biorefineries.
Which companies are active in the Fish Gelatin Market during 2026?
Notable market participants include Darling Ingredients Inc. (Rousselot), Nitta Gelatin Inc., PB Leiner (Tessenderlo Group), Weishardt Holding SA, Lapi Gelatine SpA, GELITA AG, Seagarden AS, and Nippi, Incorporated. These refiners focus on de-odorized high-Bloom warm-water and cold-water fish gelatins, certified sustainable skin sourcing, and biomedical hydrogels.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
