

- Market Size (2026)
- USD 28.0 Bn
- Forecast (2036)
- USD 58.1 Bn
- CAGR (2026 to 2036)
- 7.6%
How big is the CMO/CDMO Market in 2026?
The CMO/CDMO Market is projected to expand at a CAGR of 7.6% between 2026 and 2036. Market value rises from USD 27.3 billion in 2025 to USD 28.0 billion in 2026 and USD 58.1 billion by 2036. [1]
The global CMO/CDMO market was valued at USD 27.3 billion in 2025 and is estimated at USD 28.0 billion in 2026. According to Future Market Insights, the market is projected to reach USD 58.1 billion by 2036 at a CAGR of 7.6%. Pharmaceutical companies are increasingly working with contract manufacturers to access specialized production facilities and technical expertise. Outsourcing also allows sponsors to expand manufacturing capacity without making large investments in their own facilities. Demand is expected to remain strong for providers that can support drug development and manage the transition from clinical production to commercial supply.
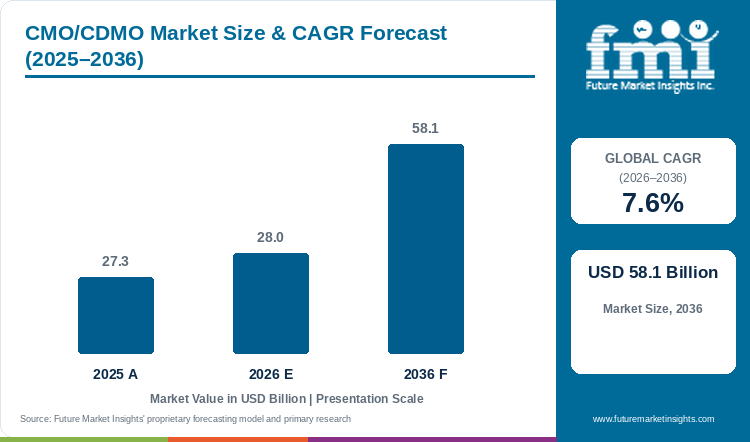
Demand for biologics manufacturing and specialized drug production is encouraging suppliers to expand their technical capabilities. Pharmaceutical sponsors are also looking for manufacturing partners that can provide development services and commercial production within the same network. This is expected to create additional opportunities for CDMOs with integrated manufacturing capabilities. However, manufacturing capacity alone does not guarantee contract awards. Pharmaceutical sponsors must evaluate production quality and regulatory compliance before transferring a process to an external facility. Technical transfer requirements and lengthy qualification procedures can delay manufacturing programs. These factors are expected to influence supplier selection throughout the forecast period. India and China are projected to record the highest country growth rates at 9.5% and 8.7% respectively. Suppliers that expand specialist capabilities while maintaining reliable production schedules are expected to strengthen their competitive positions through 2036. [1, 9]
Key Market Trends & Insights
- Manufacturing Services accounts for 41.5% of services revenue in 2026, reflecting production work across clinical and commercial programs. [1]
- Small Molecules holds 38.0% of modality revenue, while Commercial Launch represents 37.0% by stage of engagement in 2026. [1]
- Simple APIs holds 44.0% by molecule complexity; Oncology accounts for 21.3% by therapeutic area and Large Pharma for 34.0% by client type. [1]
- Supplier selection depends on process fit, quality responsibilities, capacity availability and transfer into routine production.
Regional Highlights
- India has the fastest profiled CAGR at 9.5%, followed by China at 8.7%, over 2026 to 2036. [1]
- The United Kingdom and Japan each record 6.1% CAGR; Germany records 5.9% and the United States 5.5%. [1]
- The U.S. manufacturing context includes large-scale biologics infrastructure at Vacaville and Holly Springs. [3, 4]
Market Size & Forecast
Table 1: Market Size and Forecast for the CMO/CDMO Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 27.3 billion |
| Estimated Market Size in 2026 | USD 28.0 billion |
| Projected Market Size by 2036 | USD 58.1 billion |
| CAGR, 2026 to 2036 | 7.6% |
| Added Revenue, 2026 to 2036 | USD 30.1 billion |
| Market Expansion Multiple | 2.1x |
Pharmaceutical sponsors need a manufacturing process that can move from development into repeat commercial production. Supplier portfolios span chemistry, biologics and specialist modalities, with technical transfer and quality responsibilities shaping the proposed delivery arrangement. The facility, production schedule and testing capabilities need to fit the sponsor’s program. [4, 6, 9]
Manufacturing Capacity and Program Development
Site investments and the progression of customer programs show the operational work addressed by contract manufacturers.
Table 2: Industry Indicators for the CMO/CDMO Market, 2025 to 2026
| Indicator | Data Point | Why It Matters | Source |
|---|---|---|---|
| Vacaville integration | Lonza completed Vacaville integration and reported a fifth significant commercial contract in January 2026. | Connects acquired capacity with contracted commercial work. | [2] |
| Biologics project portfolio | WuXi Biologics reported 1,064 integrated client projects at June 30, 2026, including 78 Phase III and 28 commercial programs. | Shows the mix of development and supply requirements. | [11] |
| Mammalian capacity | Lonza’s Vacaville site holds approximately 330,000 liters of mammalian bioreactor capacity. | Provides an example of infrastructure available for larger programs. | [4] |
| Specialist chemistry investment | Lupin Manufacturing Solutions described integrated CDMO and peptide building-block infrastructure investment in March 2026. | Shows supplier development in technically demanding chemistry. | [14] |
Analyst Perspective
An installed production line creates an opportunity; a qualified process and a repeatable delivery schedule create a contract. Providers that resolve transfer problems early and keep commercial batches on schedule are better placed to retain programs as their volumes grow.
- Anurag Sharma, Principal Consultant, FMI
How is the CMO/CDMO market segmented?
The market is segmented by Services, Modality, Stage of Engagement, Molecule Complexity, Therapeutic Area and Client Type. [1]
By Services: Drug Development Services, Manufacturing Services, Fill-Finish Services, Advanced Therapy Services, Commercial Manufacturing Services, Technology Transfer Services, Quality and Compliance Services.
By Modality: Small Molecules, Classical Biologics, Microbial Biologics, Cell and Gene Therapies, Oligonucleotides, Vaccines.
By Stage of Engagement: Preclinical / Phase I, Phase II / III Clinical, Commercial Launch, Lifecycle Management.
By Molecule Complexity: Simple APIs, Complex APIs (NBCDs), Highly Hazardous APIs.
By Therapeutic Area: Oncology, Cardiovascular Diseases, Infectious Diseases, Metabolic Disorders, Neurology, Immunology, Respiratory Disorders, Urology, Dermatology, Ophthalmology, General Health, Others.
By Client Type: Large Pharma, Mid-Size Pharma, Biotech / Virtual Pharma, Generic Companies, Specialty Pharma.
By Region: North America, Latin America, Western Europe, East Asia, South Asia and Pacific.
Services range from drug development and manufacturing to fill-finish services, advanced therapy support, commercial manufacturing, technology transfer, and quality and compliance. Modalities cover small molecules, classical and microbial biologics, cell and gene therapies, oligonucleotides, and vaccines. Engagement spans early development through commercial launch and lifecycle management. Molecule complexity, therapeutic area and client type provide additional views of the work being outsourced. [1]
Why does Manufacturing Services lead the services category?
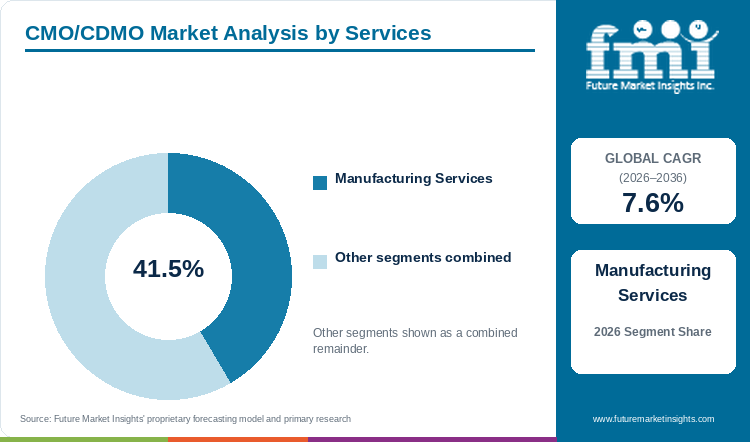
Manufacturing Services holds 41.5% of services revenue in 2026. Production involves facility time, trained operators, materials management and testing, with process validation supporting the transition to commercial supply. [1, 4]
Table 3: Services Share for the CMO/CDMO Market (percentage share), 2026
| Services | Share (2026) |
|---|---|
| Manufacturing Services | 41.5% |
| Other Segments Combined | 58.5% |
| Total | 100.0% |
Table 4: Services Focus and Market Growth for the CMO/CDMO Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.6% |
| Leading Segment | Manufacturing Services |
Production involves facility time, trained operators, materials management and testing for each batch. As a product advances, the provider must also manage a process at the scale required for supply. Lonza’s Vacaville operation illustrates this commercial focus: the site supports late-stage clinical and commercial mammalian manufacturing, with both process validation and GMP testing capabilities. For sponsors, the attraction is access to an operating production system that can support the required process and quality controls. [4]
- Manufacturing Services holds 41.5% of the services category in 2026. [1]
- In January 2026, Lonza reported completion of Vacaville integration and continued commercial contract wins for the site. [2]
What keeps Small Molecules central to modality demand?
Small Molecules accounts for 38.0% of modality revenue in 2026. API portfolios cover process optimization, scale-up and clinical and commercial supply across chemistry and dosage-form requirements. [1, 6]
Small-molecule outsourcing combines process chemistry with product development. A workable synthesis route must deliver material of the required purity, while formulation teams address how the medicine will be manufactured and administered. Patheon offers API development and manufacturing alongside drug-product services, giving sponsors an integrated route through these decisions. This creates demand for both established manufacturing platforms and teams capable of resolving process or formulation problems before scale-up. [5, 6]
- Small Molecules accounts for 38.0% of the modality category in 2026. [1]
- Patheon’s current API service portfolio covers early process optimization, scale-up, and clinical and commercial supply. [6]
What are the drivers, restraints and opportunities in the CMO/CDMO market?
Specialist manufacturing needs support outsourcing, transfer and quality requirements constrain adoption, and integrated supply capabilities create opportunities through 2036.
- Driver: Sponsors need access to process expertise and manufacturing capacity as medicines move through development and into supply.
- Restraint: Qualification, transfer and quality responsibilities add time and cost before a provider can become a dependable production partner.
- Opportunity: Providers can extend contracts by connecting development, drug-substance production and finished-product capability around the same program.
Driver. A sponsor’s requirement changes as the molecule advances. Early work can focus on finding a usable process; later activity requires a process that holds up at the intended scale. External providers give sponsors access to equipment and technical teams suited to that transition. The breadth of Patheon’s services, from development through commercial supply, illustrates the range of tasks available through an integrated partner. Specialist platforms can also attract programs whose technical requirements exceed the sponsor’s own facilities. [5]
Restraint. Outsourcing adds a relationship that must be managed through clear technical and quality responsibilities. Equipment differences, analytical transfer and the treatment of deviations can all become sources of delay if they are unresolved when production begins. FDA’s quality-agreement guidance sets out the importance of documenting manufacturing activities between parties. For buyers, this makes the quality system part of the purchasing decision. A lower quoted price provides limited value if the chosen site cannot meet the process, testing or release requirements of the program. [9]
Opportunity. Co-located or coordinated production steps can reduce the number of separate handoffs a sponsor must manage. FUJIFILM’s Holly Springs facility combines drug-substance and drug-product capability, while Pfizer CentreOne offers a sequence of ADC services from payloads and linkers to final assembly and drug product. These models address different product types, but both can widen the work awarded to a qualified partner. Contract expansion depends on the next service meeting the program’s technical requirements and delivery commitments. [3, 7]
Which country CAGRs are profiled in the CMO/CDMO market?
The country outlook covers the forecast period 2026 to 2036. [1]
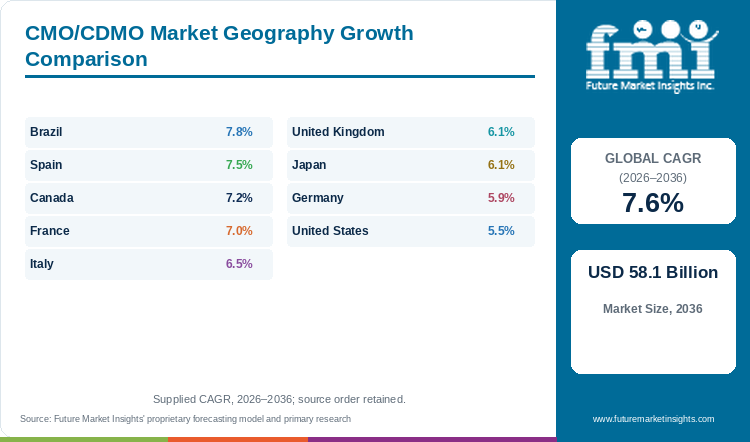
| Country | CAGR 2026 to 2036 |
|---|---|
| Brazil | 7.8% |
| Spain | 7.5% |
| Canada | 7.2% |
| France | 7.0% |
| Italy | 6.5% |
| United Kingdom | 6.1% |
| Japan | 6.1% |
| Germany | 5.9% |
| United States | 5.5% |
Country-wise Analysis
China
The opportunity in China includes the progression of biologics projects into later development and commercial manufacturing. WuXi Biologics reported 1,064 integrated client projects at June 30, 2026, including 78 in Phase III and 28 in commercial manufacturing. This company-level activity illustrates the workload associated with moving a program through successive stages. China’s forecast CAGR is 8.7% over 2026 to 2036. Buyers choosing an external site must consider the requirements of the intended destination market as well as the provider’s process experience and ability to support repeat supply. [1, 11]
United States
The U.S. country outlook records a 5.5% CAGR for 2026 to 2036. Its competitive significance is visible in large-scale biologics infrastructure: Lonza’s Vacaville site lists 332,000 liters of mammalian capacity, while FUJIFILM’s Holly Springs facility combines large-scale drug-substance production with drug-product operations. Such assets give sponsors options for late-stage and commercial work. Available capacity is only one part of the decision, however. A site’s suitability for the process, timing of qualification and release capability influence how quickly an investment can support a contracted program. [1, 3, 4]
Germany
Boehringer Ingelheim BioXcellence operates a biologics manufacturing network that includes Germany alongside the United States and Austria. Its mammalian and microbial capabilities give sponsors distinct production routes within a specialist platform. Germany’s country forecast is 5.9% CAGR over 2026 to 2036. Competition in this setting rests on technical performance, continuity and the fit of the site to a particular molecule. Providers can protect established relationships by resolving process changes and supplying the documentation required when products move through development or lifecycle updates. [1, 10]
Japan
Japanese participation extends beyond domestic plant locations. FUJIFILM’s international CDMO network includes the Holly Springs site in North Carolina, connecting a Japanese corporate platform with large-scale U.S. manufacturing. Japan is forecast to grow at 6.1% CAGR from 2026 to 2036. This international structure makes network coordination relevant to sponsor selection: technical knowledge and production arrangements need to move across sites without disrupting the program. For providers, the opportunity is to offer a coherent development-to-supply proposition while maintaining clear responsibility at the site performing each activity. [1, 3]
Who are the notable companies in the CMO/CDMO market?
Notable providers include Lonza, Thermo Fisher Scientific, FUJIFILM Biotechnologies, Samsung Biologics, Catalent, Pfizer CentreOne and Boehringer Ingelheim BioXcellence.
The competitive set includes independent CDMOs and contract manufacturing businesses within larger pharmaceutical groups. Their portfolios differ by modality, dosage form and the stages they support. Lonza and Samsung Biologics provide large-scale biologics options; Thermo Fisher’s Patheon spans several modalities and development stages. Pfizer CentreOne combines contract work with access to Pfizer manufacturing capabilities, while BioXcellence specializes in mammalian and microbial biologicsCatalent, operating as a private company under Novo Holdings’ ownership since December 2024, covers small molecules, biologics, cell and gene therapies, and clinical supply across its remaining global network. [4, 5, 7, 10, 12, 13]
- Integrated service networks: Lonza, Thermo Fisher Scientific and Catalent support multiple stages or modalities.
- Biologics manufacturing platforms: FUJIFILM Biotechnologies, Samsung Biologics and BioXcellence compete through process expertise and production assets.
- Specialized manufacturing capability: Pfizer CentreOne addresses sterile injectables, ADCs, oral solids and microbial fermentation.
Competitive Benchmarking: CMO/CDMO Market
| Company | Core Offering | Program Coverage | Production Capability | Network Position |
|---|---|---|---|---|
| Lonza | Mammalian biologics | Late clinical and commercial | Vacaville ~330,000 L | United States within wider network |
| Thermo Fisher Scientific | Small molecules, biologics, advanced therapies | Development to commercial supply | Drug substance and drug product | International Patheon network |
| FUJIFILM Biotechnologies | Cell-culture biologics | Large-scale manufacture | Holly Springs 8 x 20,000 L | United States within international network |
| Samsung Biologics | Biologics manufacturing | Scalable production | Plant 5 operational; total capacity 784,000 L | Incheon manufacturing campus |
| Catalent | Small molecules, biologics and CGT | Development, clinical supply and commercial | Multiple specialist platforms | Global CDMO network |
| Pfizer CentreOne | Steriles, ADCs and oral solids | Clinical through commercial | Fill-finish and specialized chemistry | Pfizer manufacturing network |
| BioXcellence | Mammalian and microbial biologics | Contract biologics manufacture | Specialist biologics sites | United States, Germany and Austria |
Manufacturing portfolios vary by process, production scale and site network. Sponsors assess the proposed facility against their product and supply requirements. [3, 4, 5, 7, 10, 12, 13]
Key Developments in the CMO/CDMO Market
- In January 2026, Lonza reported completion of the Vacaville site integration alongside a fifth significant commercial contract for the facility, confirmed in its full-year 2025 results released on January 28, 2026. The development connects capacity acquisition with the task of securing recurring customer programs. [2]
- In March 2026, Lupin Manufacturing Solutions announced a strategic expansion of its Dabhasa manufacturing facility, scaling its peptide building-blocks platform and integrated CDMO capabilities for complex therapies. The focus illustrates supplier movement into technically demanding chemistry and specialist manufacturing. [14]
- In August 2026, WuXi Biologics reported 123 new organic integrated projects in the first half of the year. Its June project portfolio included Phase III and commercial programs, showing the mix of development and supply work addressed by an integrated biologics provider. [11]
Key Players in the CMO/CDMO Market
Integrated Development and Manufacturing
- Lonza
- Thermo Fisher Scientific (Patheon)
- Catalent
Biologics Manufacturing
- FUJIFILM Biotechnologies
- Samsung Biologics
- Boehringer Ingelheim BioXcellence
- KBI Biopharma
Specialized and Diversified Manufacturing
- Pfizer CentreOne
- Emergent BioSolutions
- AbbVie Contract Manufacturing
- Lupin Manufacturing Solutions
CMO/CDMO Market - Report Scope
| Coverage Field | Report Scope |
|---|---|
| Market Breakdown | Services; Modality; Stage of Engagement; Molecule Complexity; Therapeutic Area; Client Type |
| Quantitative Units | Revenue in USD billion |
| Market Definition | Third-party pharmaceutical development and manufacturing services, including production, fill-finish, technology transfer and quality-related work. Excludes captive manufacturing without third-party services, standalone distribution and non-pharmaceutical contract production. |
| Regions Covered | North America; Latin America; East Asia; South Asia and Pacific; Western Europe |
| Countries Profiled | India; China; Brazil; Spain; Canada; France; Italy; United Kingdom; Japan; Germany; United States |
| Companies Compared | Lonza; Thermo Fisher Scientific; FUJIFILM Biotechnologies; Samsung Biologics; Catalent; Pfizer CentreOne; BioXcellence |
| Historical Reference | 2025 |
| Forecast Period | 2026 to 2036 |
CMO/CDMO Market - Research Methodology
| Research Area | Coverage |
|---|---|
| Market Coverage | Pharmaceutical outsourcing across services, modalities, program stages, molecule complexity, therapeutic areas and client types. |
| Industry Evidence | Regulatory guidance, official company disclosures, manufacturing-site information and current service portfolios. |
| Competitive Analysis | Product and process scope, development-stage coverage, manufacturing assets and geographic presence. |
| Demand Assessment | Sponsor qualification needs, transfer requirements, specialist manufacturing capability and continuity of commercial supply. |
CMO/CDMO Market by Segments
CMO/CDMO Market segmented by Services:
- Drug Development Services
- Manufacturing Services
- Fill-Finish Services
- Advanced Therapy Services
- Commercial Manufacturing Services
- Technology Transfer Services
- Quality and Compliance Services
CMO/CDMO Market segmented by Modality:
- Small Molecules
- Classical Biologics
- Microbial Biologics
- Cell and Gene Therapies
- Oligonucleotides
- Vaccines
CMO/CDMO Market segmented by Stage of Engagement:
- Preclinical / Phase I
- Phase II / III Clinical
- Commercial Launch
- Lifecycle Management
CMO/CDMO Market segmented by Molecule Complexity:
- Simple APIs
- Complex APIs (NBCDs)
- Highly Hazardous APIs
CMO/CDMO Market segmented by Therapeutic Area:
- Oncology
- Cardiovascular Diseases
- Infectious Diseases
- Metabolic Disorders
- Neurology
- Immunology
- Respiratory Disorders
- Urology
- Dermatology
- Ophthalmology
- General Health
- Others
CMO/CDMO Market segmented by Client Type:
- Large Pharma
- Mid-Size Pharma
- Biotech / Virtual Pharma
- Generic Companies
- Specialty Pharma
CMO/CDMO Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Western Europe
- United Kingdom
- Germany
- Italy
- France
- Spain
- East Asia
- China
- Japan
- South Asia and Pacific
- India
Research Sources and Bibliography
- [1] Future Market Insights. CMO/CDMO Market.
- [2] Lonza (2026, January 28). Full-Year 2025 results and completion of Vacaville integration.
- [3] FUJIFILM Biotechnologies. Holly Springs, North Carolina manufacturing facility.
- [4] Lonza. Vacaville, California manufacturing site.
- [5] Thermo Fisher Scientific, Patheon. CDMO services for end-to-end drug development and manufacturing.
- [6] Thermo Fisher Scientific, Patheon. API drug development and manufacturing services.
- [7] Pfizer. Pfizer CentreOne contract pharmaceutical manufacturing.
- [8] Lupin. Integrated Report 2025-2026: Business Review.
- [9] U.S. Food and Drug Administration (2016, November). Contract Manufacturing Arrangements for Drugs: Quality Agreements.
- [10] Boehringer Ingelheim. BioXcellence global manufacturing network.
- [11] WuXi Biologics (2026, August 25). First-half 2026 results.
- [12] Samsung Biologics (2025, May 16). Plant 5: Re-shaping biopharma operations.
- [13] Catalent. Global CDMO services and capabilities.
- [14] Lupin Manufacturing Solutions (2026, March 19). Lupin Manufacturing Solutions Announces Expansion of Manufacturing Facility at Dabhasa, India. NSE Filing.
This Report Answers
- How large is the CMO/CDMO market in 2026 and what is forecast for 2036?
- Which services and modalities lead demand in 2026?
- How do launch programs influence outsourcing revenue?
- What are the principal qualification and transfer constraints?
- Which countries have the highest forecast growth rates?
- How do integrated networks and specialist providers compete?
- Which 2026 developments are changing manufacturing options?
- What should sponsors assess before awarding a manufacturing contract?
Frequently Asked Questions
How big is the CMO/CDMO market in 2026, and what is forecast for 2036?
The market is valued at USD 28.0 billion in 2026 and is forecast to reach USD 58.1 billion by 2036. [1]
What is the CMO/CDMO market CAGR from 2026 to 2036?
The market is forecast to expand at a 7.6% CAGR over 2026 to 2036. [1]
Which services segment leads the CMO/CDMO market?
Manufacturing Services leads with 41.5% of services revenue in 2026. [1]
Which modality has the largest 2026 share?
Small Molecules holds 38.0% of modality revenue in 2026. [1]
Which countries have the highest forecast growth rates?
India leads at 9.5% CAGR, followed by China at 8.7%, over 2026 to 2036. [1]
What matters most when choosing a manufacturing partner?
Sponsors assess process and modality fit, quality responsibilities, available production capacity, technical transfer and the ability to support the required supply schedule.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Services, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Services, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Services, 2026 to 2036
- Drug Development Services
- Manufacturing Services
- Fill-Finish Services
- Advanced Therapy Services
- Commercial Manufacturing Services
- Technology Transfer Services
- Quality and Compliance Services
- Y-o-Y Growth Trend Analysis By Services, 2021 to 2025
- Absolute $ Opportunity Analysis By Services, 2026 to 2036
- Global Market Analysis and Forecast, By Modality, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Modality, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Modality, 2026 to 2036
- Small Molecules
- Classical Biologics
- Microbial Biologics
- Cell and Gene Therapies
- Oligonucleotides
- Vaccines
- Y-o-Y Growth Trend Analysis By Modality, 2021 to 2025
- Absolute $ Opportunity Analysis By Modality, 2026 to 2036
- Global Market Analysis and Forecast, By Stage of Engagement, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Stage of Engagement, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Stage of Engagement, 2026 to 2036
- Preclinical / Phase I
- Phase II / III Clinical
- Commercial Launch
- Lifecycle Management
- Y-o-Y Growth Trend Analysis By Stage of Engagement, 2021 to 2025
- Absolute $ Opportunity Analysis By Stage of Engagement, 2026 to 2036
- Global Market Analysis and Forecast, By Molecule Complexity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Molecule Complexity, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Molecule Complexity, 2026 to 2036
- Simple APIs
- Complex APIs (NBCDs)
- Highly Hazardous APIs
- Y-o-Y Growth Trend Analysis By Molecule Complexity, 2021 to 2025
- Absolute $ Opportunity Analysis By Molecule Complexity, 2026 to 2036
- Global Market Analysis and Forecast, By Therapeutic Area, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Therapeutic Area, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Therapeutic Area, 2026 to 2036
- Oncology
- Cardiovascular Diseases
- Infectious Diseases
- Metabolic Disorders
- Neurology
- Immunology
- Respiratory Disorders
- Urology
- Dermatology
- Ophthalmology
- General Health
- Others
- Y-o-Y Growth Trend Analysis By Therapeutic Area, 2021 to 2025
- Absolute $ Opportunity Analysis By Therapeutic Area, 2026 to 2036
- Global Market Analysis and Forecast, By Client Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Client Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Client Type, 2026 to 2036
- Large Pharma
- Mid-Size Pharma
- Biotech / Virtual Pharma
- Generic Companies
- Specialty Pharma
- Y-o-Y Growth Trend Analysis By Client Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Client Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- East Asia
- South Asia and Pacific
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United Kingdom
- Germany
- Italy
- France
- Spain
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Services
- By Modality
- By Stage of Engagement
- By Molecule Complexity
- By Therapeutic Area
- By Client Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lonza
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Thermo Fisher Scientific
- FUJIFILM Biotechnologies
- Samsung Biologics
- Catalent
- Pfizer CentreOne
- BioXcellence
- Thermo Fisher Scientific (Patheon)
- Boehringer Ingelheim BioXcellence
- KBI Biopharma
- Emergent BioSolutions
- AbbVie Contract Manufacturing
- Lupin Manufacturing Solutions
- Lonza
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


