

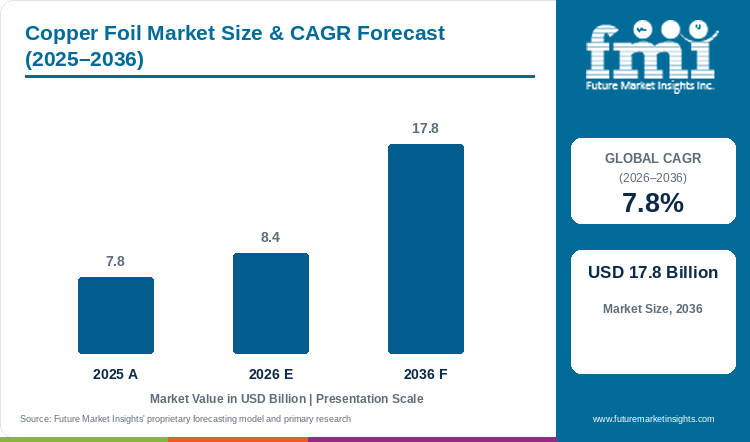
- Market Size (2026)
- USD 8.4 Bn
- Forecast (2036)
- USD 17.8 Bn
- CAGR (2026 to 2036)
- 7.8%
How big is Copper Foil Market in 2026?
Copper foil market size stood at USD 7.8 billion in 2025, reaches USD 8.41 billion in 2026 and is projected at USD 17.79 billion by 2036. Demand for copper foil is set to expand at a 7.8% CAGR from 2026 to 2036, as battery makers and electronics assemblers add thinner, higher-purity foil lines.
Sales of copper foil are tracking the pace of electric vehicle adoption worldwide. Global electric car sales surpassed 20 million in 2025, more than one in four cars sold worldwide, the International Energy Agency reported in May 2025 [1]. Due to this, battery makers are ordering more anode-grade foil to keep pace with cell output. Global battery storage additions reached 108 GW in 2025, a jump of about 40% from 2024, the IEA data showed in June 2026 [2]. Apart from that, global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, up 41.7% from 2024, with China delivering 82.9% of the total, Metalnomist reported in July 2026, citing EV Tank data [3]; this is a global upstream volume benchmark specific to battery-grade foil and is not directly reconcilable with this report's narrower market-value scope.
A clear demand-intensity shift toward thinner foil is forming inside that volume. The 6 micron grade stayed the mainstream product at more than 70% of 2025 shipments. The combined share of 5 micron and 4.5 micron ultra-thin foil rose to 24% in 2025, up from a smaller base a year earlier, as cell makers cut copper input per battery and raise energy density [3]. This thinning trend is expected to deepen as EV Tank projects global lithium-ion battery copper foil shipments to reach 2.615 million tonnes by 2030, nearly double the 2025 total [3]. Foil producers that qualify sub-6 micron grades ahead of competitors are positioned to capture share as battery makers standardize on thinner current collectors through 2036. FMI finds batteries leading application sales in 2026, as EV and grid-storage cell makers add anode-grade foil capacity faster than other end uses. Battery makers chasing lower copper mass per cell and PCB fabricators adding layer density are anticipated to keep sales of copper foil rising over the forecast period.
Key Market Trends & Insights
- By foil type, ED copper foil leads with 68% of 2026 sales, as electrodeposition scales more readily to the thin, wide rolls that battery and PCB current-carrying layers require.
- By application, batteries lead 2026 sales, as EV and grid-storage cell makers add anode-grade foil capacity faster than other end uses. Printed circuit boards and other applications, including heat exchangers, busbars and switchgears, radiators, and electrical equipment, make up the remainder.
- By thickness, the under-6-micron band holds 34% in 2026, owing to battery makers cutting foil thickness toward 4.5 to 6 microns to raise cell energy density [3].
- By sales channel, direct sales account for 56% of 2026 sales, and long-term supply contracts with battery and PCB makers will keep direct sales as the main channel through 2036.
- By region, East Asia leads 2026 sales by a wide margin, as battery and PCB fabrication capacity concentrates in China, South Korea, Japan and Taiwan, with China alone supplying 82.9% of global battery-grade foil shipments [3].
Regional Highlights
- Germany is projected to record the fastest growth of the profiled countries, at 8.1% CAGR through 2036.
- South Korea (7.9%) and Japan (7.7%) come after the leader, with the UK the slowest of the profiled countries at 7.5% through 2036.
- South Korea's Ministry of Trade, Industry and Energy committed about KRW 21 trillion to green vehicle and battery industries in 2025, with the battery-industry allocation of about KRW 7.9 trillion rising 31.7% from the prior year, the ministry announced in January 2025.
Market Size & Forecast
Table 1: Market Size and Forecast for the Copper Foil Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 7.8 billion |
| Estimated Market Size in 2026 | USD 8.41 billion |
| Projected Market Size by 2036 | USD 17.79 billion |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 9.38 billion |
| Market Expansion Multiple | 2.1x |
Most copper foil orders now come from battery makers and PCB fabricators adding capacity for electric vehicles and electronics. Lower copper mass per cell and higher conductivity per layer are the main reasons buyers approve an order. Trade costs are adding pressure in the United States, as the Section 232 tariff set a 50% rate on semi-finished copper products and copper-intensive derivatives such as cables and connectors, effective August 1, 2025. At the top end, battery makers chasing ultra-thin foil still pay a premium for sub-6 micron grades, which keeps specialty foil lines on order books [3]. High production costs for ultra-thin foil and volatile raw copper prices can still delay approvals at smaller fabricators. Replacement of thicker legacy foil lines with thin, high-purity capacity is anticipated to drive most orders through 2036.
Battery and Electronics Capacity Readiness
Sales of copper foil are rising alongside battery and electric vehicle capacity additions across major markets. Global battery storage additions reached 108 GW in 2025, up about 40% from 2024 [2]. The UK government and partners committed about £1 billion to an AESC battery cell gigafactory in Sunderland, with capacity to supply 100,000 electric vehicles a year, reported in May 2025. South Korea is moving in the same direction on battery capacity. The country's trade ministry raised battery-industry support to about KRW 7.9 trillion in 2025, a 31.7% increase from 2024, alongside expanded EV subsidies and about 4,400 new fast-charging units. FMI expects foil producers that qualify thinner, higher-purity grades early to take most new orders in the early forecast years, as cell makers and PCB fabricators look for less copper mass per unit.
Trade and sourcing rules are giving foil buyers a second reason to diversify supply. In August 2025, the United States applied a 50% Section 232 tariff on semi-finished copper products and copper-intensive derivatives, excluding copper ore, cathode and scrap inputs. Global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, with China supplying 82.9% of the total, Metalnomist reported, citing EV Tank [3]. Foil producers outside China are responding by expanding thin-foil capacity to serve buyers seeking supply outside that concentration. Furukawa Electric continues to expand its rolled-annealed and established-grade copper foil lines, while Mitsui Mining & Smelting expands electrolytic copper foil capacity for high-frequency substrates and semiconductor applications. SK Nexilis, Lotte Energy Materials and Solus Advanced Materials add anode-grade battery foil lines. Global electric car sales surpassed 20 million units in 2025, more than one in four cars sold worldwide, the IEA said in May 2025 [1], and FMI sees continued EV output as the main driver of foil demand through the remainder of the decade. Germany and South Korea lead profiled growth, with CAGRs of 8.1% and 7.9% through 2036. The UK grows slowest at a 7.5% CAGR by 2036, even as the AESC Sunderland gigafactory adds downstream battery demand.
Table 2: Battery and Electronics Capacity Indicators for the Copper Foil Market (percentage changes, units, USD and GW values), mixed reporting years from 2025 to 2026
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| Global EV sales, 2025 | On track to surpass 20 million units; over one in four cars sold worldwide | Rising EV output drives anode-grade copper foil demand. | [1] |
| Global battery storage additions, 2025 | 108 GW, up about 40% from 2024 | Grid storage growth is adding a battery foil demand base. | [2] |
| Global lithium-ion battery copper foil shipments, 2025 | 1.302 million tonnes, up 41.7%; China 82.9% share | Battery foil demand concentrates heavily in East Asia. | [3] |
| Ultra-thin foil share, 2025 | 5 micron and 4.5 micron combined share rose to 24% | Thinner foil grades are gaining share inside battery output. | [3] |
| US Section 232 copper tariff | 50% rate effective August 1, 2025 on semi-finished copper products and derivatives | Trade cost is pushing buyers to review foil sourcing. | — |
| South Korea battery-industry support, 2025 | About KRW 7.9 trillion, up 31.7% from 2024 | Government-backed capacity growth lifts foil demand. | — |
| UK AESC Sunderland gigafactory | About £1 billion; capacity for 100,000 EVs a year | A single large battery project sets UK foil demand. | — |
| 6 micron foil share, 2025 | More than 70% of battery copper foil shipments | 6 micron foil stays the mainstream battery grade. | [3] |
| Projected battery copper foil shipments, 2030 | 2.615 million tonnes | Battery foil volume is set to nearly double by 2030. | [3] |
Table 3: Trade Policy and Shipment Benchmarks for the Copper Foil Market (mixed units and currencies), mixed reporting years from 2025 to 2026
| Indicator | Reported value | Related figure | Source |
|---|---|---|---|
| Copper foil market, 2025 to 2026 | USD 7.8 billion to USD 8.41 billion | 7.8% CAGR, 2026 to 2036 | Future Market Insights |
| Global lithium-ion battery copper foil shipments, 2025 | 1.302 million tonnes | Up 41.7% from 2024 | [3] |
| China share of global battery foil shipments, 2025 | 82.9% | Up from a similarly concentrated base in 2024 | [3] |
| US Section 232 copper tariff | 50% rate | Effective August 1, 2025 | — |
| South Korea battery-industry support, 2025 | About KRW 7.9 trillion | Up 31.7% from 2024 | — |
| Global battery storage additions, 2025 | 108 GW | Up about 40% from 2024 | [2] |
| UK AESC Sunderland gigafactory | About £1 billion investment | Capacity for 100,000 EVs a year | — |
| Ultra-thin battery foil share, 2025 | 5 micron and 4.5 micron combined at 24% | 6 micron foil remains mainstream at more than 70% | [3] |
Analyst Perspective
“Copper foil producers will favour thinner, higher-purity grades that cut copper mass per battery cell without losing conductivity. Foil makers offering qualified sub-6 micron supply and diversified sourcing outside a single region will take most new battery and PCB orders through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Copper Foil Market segmented?
The copper foil market is studied across four commercial segments plus region, namely foil type, application, thickness and sales channel.
By foil type: ED (electrodeposited) copper foil and RA (rolled-annealed) copper foil.
By application: batteries lead sales, followed by printed circuit boards and other applications such as heat exchangers, busbars and switchgears, radiators, and electrical equipment.
By thickness: under 6 microns, 6 to 8 microns, 8 to 12 microns, 12 to 18 microns, 18 to 35 microns, and above 35 microns.
By sales channel: direct sales and distributor sales.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia Pacific, and Middle East and Africa.
Why does ED copper foil lead the foil-type segment?
ED copper foil will hold 68% of foil-type sales in 2026, as battery and PCB makers need the thin, wide-format rolls that electrodeposition can scale.
Table 4: Foil Type Share for the Copper Foil Market (percentage share), 2026
| Foil Type | Share (2026) |
|---|---|
| ED Copper Foil | 68% |
| RA Copper Foil | 32% |
| Total | 100% |
Table 5: Foil Type Leadership and Market Growth for the Copper Foil Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | ED Copper Foil |
Demand for ED copper foil leads the foil-type segment, as electrodeposition scales more readily to the thin, wide rolls battery current collectors and PCB conductive layers need. FMI finds that ED accounts for 68% of foil-type sales in 2026. RA copper foil keeps a smaller base in applications needing higher ductility and fold resistance. Global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, with 6 micron foil as the mainstream grade at more than 70% share [3]. Thinner ED grades qualified for battery current collectors are anticipated to keep this segment ahead through 2036.
- ED copper foil holds 68% of foil-type sales in 2026, since battery and PCB makers need the thin, wide-format rolls that electrodeposition can scale.
- Buyers comparing foil types should check conductivity, purity and thickness tolerance, as these factors set the cost of each battery cell or circuit layer.
Why do batteries dominate application sales?
Batteries lead application sales in 2026, as EV and grid-storage cell makers add anode-grade current-collector capacity.
Sales of copper foil for batteries follow EV and grid-storage cell output, as cell makers add anode-grade current-collector capacity. As per FMI estimates, batteries lead application sales in 2026. Printed circuit boards keep gaining share as electronics assemblers add layers, while heat exchangers, busbars and switchgears, radiators, and electrical equipment make up the remaining application demand. Continued battery and PCB capacity additions are expected to keep batteries ahead of other applications through 2036.
- Batteries lead application sales in 2026, as EV and grid-storage cell makers add anode-grade current-collector capacity.
- Buyers adding battery cell capacity should test foil thickness, tensile strength and conductivity before qualifying a new supply order.
Why is battery demand reshaping the thickness segment?
The under-6-micron thickness band makes up 34% of thickness sales in 2026, owing to battery cells moving toward 4.5 to 6 micron foil.
Demand for ultra-thin copper foil is rising, as battery makers cut copper mass per cell to raise energy density. FMI data shows the under-6-micron thickness band making up 34% of thickness sales in 2026. Thicker bands above 35 microns remain the choice for busbars and heavier electrical equipment. The combined share of 5 micron and 4.5 micron ultra-thin foil rose to 24% of lithium-ion battery copper foil shipments in 2025, up from a smaller base, as the 6 micron grade stayed mainstream at more than 70% [3]. Foil producers that qualify sub-6 micron grades are expected to gain orders from battery makers chasing lighter cells.
- The under-6-micron thickness band makes up 34% of thickness sales in 2026, and battery cell thinning will keep this band in front through 2036.
- Battery makers adding thinner foil should test tensile strength and tear resistance before qualifying a new thickness grade.
Why does direct sales lead the sales channel segment?
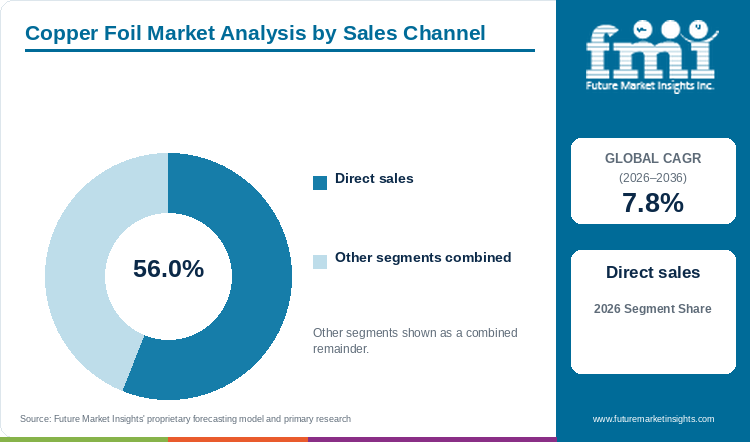
Direct sales capture 56% of sales channel sales in 2026, owing to long-term supply contracts with battery and PCB makers.
Battery and PCB makers buy most copper foil straight from the producer, as long-term supply contracts secure consistent thickness and purity. FMI estimates that direct sales capture 56% of sales channel sales in 2026. Distributor sales serve smaller fabricators and repair shops with shorter order cycles. Global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, with China supplying 82.9% of the total through producer-direct contracts [3]. Large battery and PCB output in countries such as China will keep direct sales as the main channel through 2036.
- Direct sales capture 56% of sales channel sales in 2026, supported by long-term supply contracts with battery and PCB makers.
- Distributor-channel buyers often prefer smaller order lots, since order sizes change more often than at large battery plants.
What gives East Asia the lead in regional demand?
East Asia leads regional sales by a wide margin in 2026, as buyers want capacity close to battery and PCB fabrication clusters.
Battery and PCB fabricators cluster in East Asia, as upstream copper refining and cell assembly sit close together. East Asia leads regional sales by a wide margin in 2026, as per FMI. North America and Western Europe cover smaller bases tied to local gigafactory and electronics capacity. Global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, with China alone supplying 82.9% of global deliveries, Metalnomist reported [3]. Sales of copper foil outside East Asia are anticipated to grow as buyers diversify sourcing away from a single region.
- East Asia leads regional sales by a wide margin in 2026, as battery and PCB fabrication capacity, led by China's 82.9% share of global battery-grade foil shipments, concentrates in the region.
- Buyers outside East Asia should check qualified alternate foil sources, as regional concentration raises supply risk.
What are the drivers, restraints, and opportunities in the Copper Foil Market?
Rising battery and electronics output pushes plants toward thinner, higher-purity foil, volatile raw copper prices and tariffs slow approvals, and grid battery storage growth opens the main opportunity for thin, high-conductivity copper foil.
- Driver: Key drivers of the copper foil market include electric vehicle and battery production, and copper foil serves as an anode current collector.
- Restraint: Volatile raw copper prices and high production costs for ultra-thin foil slow sales of copper foil. Stricter environmental and e-waste rules add further cost.
- Opportunity: Renewable energy and grid storage capacity additions open growth for thin, high-conductivity copper foil in the copper foil market.
Electric Vehicle Growth Lifts Battery Foil Demand
Output of electric vehicle battery packs keeps rising, pulling more anode-grade copper foil into battery cells. Global electric car sales surpassed 20 million in 2025, more than one in four cars sold worldwide, the IEA reported in May 2025 [1]. Due to this, battery makers are qualifying thinner foil to raise cell energy density without adding cost. Sales of battery-grade copper foil are anticipated to grow fastest among applications through 2036.
Raw Copper Price Volatility Slows Orders
Swings in raw copper prices make foil buyers slower to lock in new supply contracts. The United States applied a 50% Section 232 tariff on semi-finished copper products and copper-intensive derivatives, effective August 1, 2025. Copper ore, cathode and scrap inputs stayed exempt. Every new foil order also needs to clear qualification testing for conductivity and thickness tolerance, adding time before full output. High raw material costs and these qualification steps may slow orders from smaller fabricators in the early forecast years.
Grid Storage Growth Opens New Demand
Grid-scale battery energy storage is opening a new demand base for copper foil beyond electric vehicles. Global battery storage additions reached 108 GW in 2025, up about 40% from 2024, IEA data showed in June 2026 [2]. South Korea's trade ministry raised battery-industry support to about KRW 7.9 trillion in 2025, a 31.7% rise from 2024. Foil producers serving grid storage cell makers stand to gain new orders through 2036.
Which country CAGRs are profiled in the Copper Foil Market?
Sales of copper foil in Germany grow fastest among the five profiled countries, at an 8.1% CAGR between 2026 and 2036. The UK posts the slowest rate, a 7.5% CAGR over the same period. Across all five, battery and electronics makers buy copper foil mainly to raise cell energy density and PCB layer density.
Table 6: Country CAGRs and Primary Growth Levers for the Copper Foil Market (CAGR percentage), 2026 to 2036
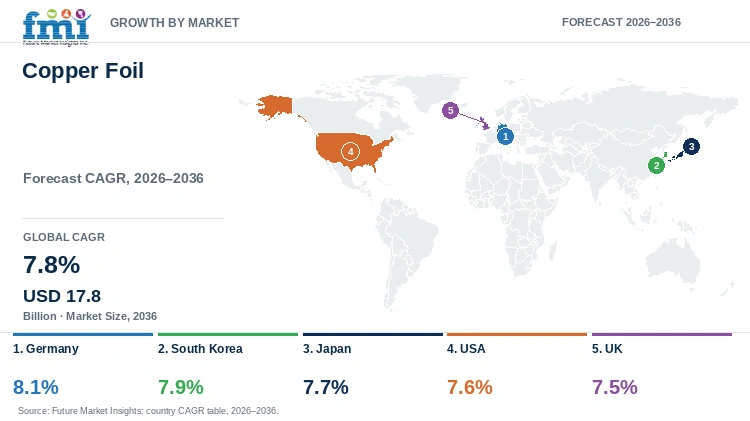
| Country | CAGR (2026–2036) | Primary Growth Lever |
|---|---|---|
| Germany | 8.1% | Battery cell capacity additions across the region |
| South Korea | 7.9% | Government-backed battery and EV support |
| Japan | 7.7% | Digital process tools on existing foil lines |
| USA | 7.6% | Tariff-driven sourcing reviews by battery makers |
| UK | 7.5% | AESC Sunderland gigafactory battery demand |
Source: Future Market Insights
Germany Copper Foil Market Outlook (2026–2036)
German battery and electronics makers are adding capacity alongside rising electric vehicle sales, with global EV sales surpassing 20 million units in 2025, more than one in four cars sold worldwide, the IEA reported in May 2025 [1]. Due to this, German foil buyers are placing the country first with an 8.1% CAGR for 2026 to 2036. With global battery storage additions reaching 108 GW in 2025, up about 40% from 2024, German cell makers are adding storage capacity alongside vehicle battery lines [2]. The UK's AESC Sunderland gigafactory investment of about £1 billion, reported in May 2025, points to continued battery cell capacity building across the wider European market. This buildout is creating room for foil producers qualifying thin, high-conductivity grades.
Key takeaway: Battery cell capacity additions across Germany will draw most new copper foil orders.
South Korea Copper Foil Market Outlook (2026–2036)
South Korea's Ministry of Trade, Industry and Energy committed about KRW 21 trillion, near USD 14.4 billion, to green vehicle and battery industries in 2025, with battery-industry support of about KRW 7.9 trillion, up 31.7% from 2024. The plan also expands EV subsidies and adds about 4,400 new fast-charging units nationwide. Cell makers need qualified thin foil to meet these capacity targets, which favours producers such as SK Nexilis with established battery-grade lines. South Korea is set for the second-fastest rate, a 7.9% CAGR through 2036.
Key takeaway: Government-backed battery capacity targets will keep South Korean foil demand ahead of most profiled markets.
Japan Copper Foil Market Outlook (2026–2036)
Japan remains one of the established foil-grade producer bases outside China's 82.9% share of global battery-grade copper foil shipments in 2025 [3]. Japanese PCB fabricators and electronics assemblers continue to source both ED and RA grades from long-standing domestic suppliers such as Furukawa Electric. Japan is projected to add copper foil sales at a 7.7% CAGR through 2036.
Key takeaway: Digital process tools on existing lines will shape Japanese foil output before new capacity is added.
USA Copper Foil Market Outlook (2026–2036)
The United States applied a 50% Section 232 tariff on semi-finished copper products and copper-intensive derivatives, effective August 1, 2025. Copper ore, cathode, anode and scrap inputs stayed exempt. Due to this, U.S. foil buyers and battery makers are reviewing domestic sourcing options. Global electric car sales surpassed 20 million units in 2025, more than one in four cars sold worldwide [1]. U.S. sales of copper foil are set for a 7.6% CAGR over 2026 to 2036, led by battery cell capacity additions.
Key takeaway: Tariff-driven sourcing reviews will favour domestic and allied foil suppliers over the forecast period.
UK Copper Foil Market Outlook (2026–2036)
The UK government and partners committed about £1 billion to an AESC battery cell gigafactory in Sunderland, with capacity to supply 100,000 electric vehicles a year, reported in May 2025. Due to this, UK copper foil demand is tied closely to this single large battery project. UK sales of copper foil are set for just a 7.5% CAGR from 2026 to 2036, the lowest in this study, as the market base stays smaller than the other four profiled countries.
Key takeaway: The AESC Sunderland gigafactory will set the pace of UK copper foil orders through 2036.
Who are the notable companies in the Copper Foil Market?
Defu Technology, Nuode Investment, Jiayuan Technology, Longdian Huaxin, SK Nexilis, Lotte Energy Materials, Solus Advanced Materials, Furukawa Electric Co. Ltd., Kingboard Holdings, and Shandong Jinbao Electronics are the leading companies profiled in this market.
Copper foil producers profiled here come mainly from China, South Korea and Japan, with one Luxembourg-origin operation now part of a South Korean group, and differ in foil-type coverage, thickness range and application focus. Defu Technology, Nuode Investment, Jiayuan Technology and Longdian Huaxin lead large-scale electrodeposited (ED) foil production for Chinese battery makers. SK Nexilis, Lotte Energy Materials and Solus Advanced Materials, the producer that Circuit Foil Luxembourg became, supply battery-grade ultra-thin foil to cell makers outside China. Furukawa Electric Co. Ltd., Kingboard Holdings and Shandong Jinbao Electronics complete the supplier set with established grade and PCB-grade foil capacity.
- Battery-grade ED foil leaders: Defu Technology, Nuode Investment, Jiayuan Technology, and Longdian Huaxin supply electrodeposited copper foil at scale to Chinese battery makers.
- Established foil and battery-grade specialists: SK Nexilis, Lotte Energy Materials and Solus Advanced Materials supply battery-grade ultra-thin foil to cell makers across Asia and Europe.
- Regional and PCB foil suppliers: Furukawa Electric, Kingboard Holdings, and Shandong Jinbao Electronics supply established-grade and PCB-grade copper foil.
Competitive Benchmarking: Copper Foil Market
Table 7: Competitive Benchmarking for the Copper Foil Market (qualitative capability ratings), 2026
| Company | Foil-Type Range | Thin Foil | Capacity | Reach |
|---|---|---|---|---|
| Defu Technology | High | High | High | Medium |
| Nuode Investment | High | High | High | Medium |
| Jiayuan Technology | Medium | High | Medium | Low |
| Longdian Huaxin | Medium | Medium | Medium | Low |
| SK Nexilis | Medium | High | Medium | Medium |
| Lotte Energy Materials | Medium | High | Medium | Medium |
| Solus Advanced Materials | Medium | Medium | Low | Low |
| Furukawa Electric | High | Medium | High | Medium |
| Kingboard Holdings | Medium | Low | Medium | Low |
| Shandong Jinbao Electronics | Low | Low | Low | Low |
A broad, publicly documented copper foil production range earns High; a partial record earns Medium; a thin public record earns Low. Defu Technology and SK Nexilis are rated on foil-type coverage and battery-grade thin foil, and Furukawa Electric on established grade production.
Key Developments in the Copper Foil Market
- In July 2026, Metalnomist reported that global lithium-ion battery copper foil shipments reached 1.302 million tonnes in 2025, up 41.7% from 2024, citing EV Tank data [3].
- In June 2026, the IEA reported that global battery storage additions reached 108 GW in 2025, up about 40% from 2024 [2].
- In May 2025, the UK government and partners committed about £1 billion to an AESC battery cell gigafactory in Sunderland, with capacity for 100,000 electric vehicles a year.
- In January 2025, South Korea's Ministry of Trade, Industry and Energy raised battery-industry support to about KRW 7.9 trillion for 2025, a 31.7% increase from 2024.
Key Players in the Copper Foil Market
Grade and Conductor Foil Producers
- Defu Technology
- Nuode Investment
- Jiayuan Technology
- Longdian Huaxin
Established Foil and Battery-Grade Specialists
- SK Nexilis
- Lotte Energy Materials
- SK Nexilis
Regional and PCB Foil Suppliers
- Furukawa Electric Co. Ltd.
- Kingboard Holdings
- Shandong Jinbao Electronics
Copper Foil Market - Report Scope
Table 8: Report Scope for the Copper Foil Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Foil type; application; thickness; sales channel; region |
| Quantitative units | USD billion |
| Market definition | Revenue from first sale of copper foil across ED and RA foil types, used in batteries, printed circuit boards, heat exchangers, busbars and switchgears, radiators and electrical equipment. Finished batteries, circuit boards and equipment sold as end products are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia Pacific; Middle East and Africa |
| Countries covered | Germany; South Korea; Japan; USA; UK |
| Key companies profiled | Defu Technology, Nuode Investment, Jiayuan Technology, Longdian Huaxin, SK Nexilis, Lotte Energy Materials, Solus Advanced Materials, Furukawa Electric, Kingboard Holdings, Shandong Jinbao Electronics |
| Forecast period | 2026 to 2036 |
| Approach | Bottom-up volume data and top-down estimates were cross-checked to reconcile foil shipment volumes, grade and thickness mix, battery and electronics capacity additions and country battery-policy conditions, checked against producer filings and primary interviews. |
Copper Foil Market - Research Methodology
Table 9: Research Methodology for the Copper Foil Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary research includes interviews with copper foil producers, battery and PCB makers, and procurement teams. Interviews cover thickness qualification, conductivity needs, supply contracts and foil prices. |
| Desk Research | Desk research draws on producer filings, shipment and capacity reports, government battery-policy announcements and trade-tariff notices. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and adds grade and thickness mix, battery and electronics capacity additions and demand for copper foil in each country. |
| Data Validation | Each estimate is tested against producer disclosures, shipment data and primary interviews. Finished batteries and circuit boards stay outside market value, so no revenue is counted twice. |
Copper Foil Market by Segments
Copper Foil Market segmented by Foil Type:
- ED (electrodeposited) copper foil
- RA (rolled-annealed) copper foil
Copper Foil Market segmented by Application:
- Batteries
- Printed circuit boards
- Heat exchangers
- Busbars and switchgears
Copper Foil Market segmented by Thickness:
- Under 6 microns
- 6 to 8 microns
- 8 to 12 microns
- 12 to 18 microns, 18 to 35 microns, and above 35 microns
Copper Foil Market segmented by Sales Channel:
- Direct sales
- Distributor sales
Copper Foil Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] International Energy Agency. (2025, May 14). More than one in four cars sold worldwide this year is set to be electric, as EV sales continue to grow.https://www.iea.org/news/more-than-one-in-four-cars-sold-worldwide-this-year-is-set-to-be-electric-as-ev-sales-continue-to-grow
- [2] ESS News / International Energy Agency. (2026, June 2). Global battery additions reached 108 GW in 2025, according to IEA.https://www.ess-news.com/2026/06/02/global-battery-additions-reached-108-gw-in-2025-according-to-iea/
- [3] Metalnomist, citing EV Tank. (2026, July 21). Lithium-Ion Battery Copper Foil Shipments Surge as Ultra-Thin Products Gain Share.https://www.metalnomist.com/2026/07/lithium-ion-battery-copper-foil.html
This Report Answers
- What value will copper foil sales reach in 2026?
- By 2036, what market value will copper foil reach?
- Which grade takes the largest share of sales?
- What application and thickness band do battery and electronics makers favour?
- Which profiled countries show the fastest growth in copper foil sales?
- Which producers lead the supply of copper foil to battery and electronics makers?
Frequently Asked Questions
What is the copper foil market worth in 2026?
Copper foil sales are valued at USD 8.41 billion in 2026, according to FMI. The market will reach USD 17.79 billion by 2036 as battery and electronics makers add thinner, higher-purity foil capacity.
What CAGR is projected for the copper foil market through 2036?
FMI projects a 7.8% CAGR for the copper foil market from 2026 to 2036. Electric vehicle output and grid battery storage additions will support much of this growth.
Which foil type holds a leading share in 2026?
ED copper foil will hold 68% of foil-type sales in 2026. Battery and PCB makers favour this foil type because electrodeposition scales more readily to the thin, wide rolls they need.
Which application holds a leading share in 2026?
Batteries will lead application sales in 2026. Rising EV and grid-storage cell output drives this share.
Which country has a leading growth outlook through 2036?
Germany leads the profiled countries with an 8.1% CAGR for copper foil sales over 2026 to 2036. Rising battery cell capacity across the country supports this rate.
Who are the key companies in the copper foil market?
Key companies include Defu Technology, Nuode Investment, Jiayuan Technology, Longdian Huaxin, SK Nexilis, Lotte Energy Materials, Solus Advanced Materials, Furukawa Electric, Kingboard Holdings, and Shandong Jinbao Electronics. These producers compete on foil-type coverage, thickness range and application focus.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Foil Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Foil Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Foil Type, 2026 to 2036
- ED (electrodeposited) copper foil
- RA (rolled-annealed) copper foil
- Y-o-Y Growth Trend Analysis By Foil Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Foil Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Batteries
- Printed circuit boards
- Heat exchangers
- Busbars and switchgears
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Thickness, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Thickness, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Thickness, 2026 to 2036
- Under 6 microns
- 6 to 8 microns
- 8 to 12 microns
- 12 to 18 microns, 18 to 35 microns, and above 35 microns
- Y-o-Y Growth Trend Analysis By Thickness, 2021 to 2025
- Absolute $ Opportunity Analysis By Thickness, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct sales
- Distributor sales
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Foil Type
- By Application
- By Thickness
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Defu Technology
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Nuode Investment
- Jiayuan Technology
- Longdian Huaxin
- SK Nexilis
- Lotte Energy Materials
- Solus Advanced Materials
- Furukawa Electric
- Kingboard Holdings
- Shandong Jinbao Electronics
- Furukawa Electric Co. Ltd.
- Defu Technology
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


