
- Market Size (2026)
- USD 4.2 Bn
- Forecast (2036)
- USD 6.3 Bn
- CAGR (2026 to 2036)
- 4.2%
How big is Dried Soup Market in 2026?
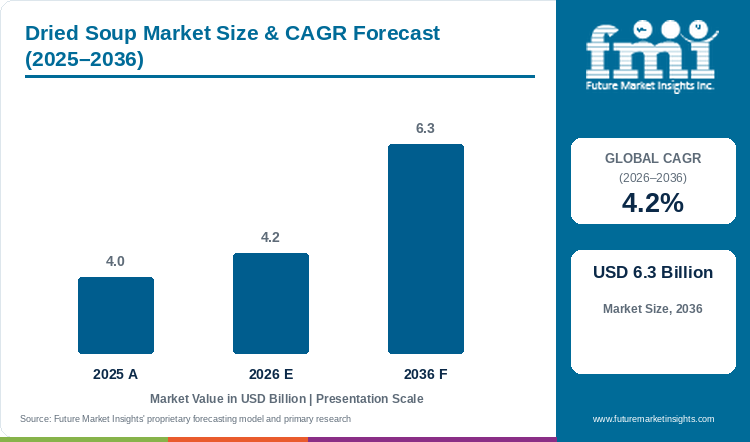
Sales in the dried soup market are projected to grow at 4.2% CAGR, with the market size rising from USD 4.0 billion in 2025 to USD 4.2 billion in 2026 and reaching USD 6.3 billion by 2036.
Increasing need for shelf-stable hot meals that prepare in under five minutes without refrigeration is pushing household grocery shoppers and institutional kitchens toward commercial dried soups. According to FMI, the global dried soup market rises from USD 4.0 billion in 2025 to USD 4.2 billion in 2026 and is projected to reach USD 6.3 billion by 2036, expanding at a 4.2% CAGR from 2026 to 2036 and adding USD 2.1 billion in revenue. Dehydrated noodle and vegetable soup leads product type demand with a 54.1% share in 2026 because pre-portioned noodle blocks and vegetable particulates deliver a full meal in a single pouch.
In January 2025, the U.S. Food and Drug Administration proposed mandatory front-of-package nutrition boxes highlighting sodium per serving on packaged foods[1]. Consequently, soup brands are reformulating seasoning sachets with fermented yeast extracts while managing fluctuating dehydrated vegetable input costs across evaluated countries growing between 3.4% and 5.1% CAGR.
Key Market Trends & Insights
- By product type / grade: Dehydrated noodle and vegetable soup led the market with a share of 54.1% in 2026, driven by fast hot-water rehydration and broad household acceptance as a complete meal.
- By processing state: Ambient packaged dehydrated mix accounted for 40.5% of demand in 2026, owing to room-temperature warehouse stability and lower shipping weight than canned liquids.
- By end-use application: Direct retail consumer consumption held 45.1% of revenue in 2026, as single-person households and commuters stock pantry packets for quick weekday meals.
- By sales channel: Supermarkets and hypermarkets represented 42.5% of sales in 2026, underpinned by multi-pack aisle promotions and private-label lines using freeze-dried food ingredients.
Regional Highlights
- Fastest-growing evaluated country: South Korea, at 5.1% CAGR from 2026 to 2036.
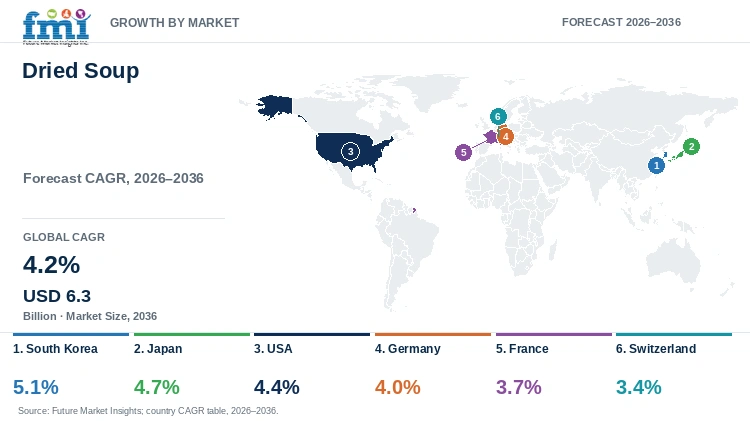
- By country: Japan at 4.7%, the USA at 4.4%, and Germany at 4.0% follow, while Switzerland records the lowest evaluated CAGR at 3.4%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Dried Soup Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.0 billion |
| Estimated Market Size in 2026 | USD 4.2 billion |
| Projected Market Size by 2036 | USD 6.3 billion |
| CAGR, 2026 to 2036 | 4.2% |
| Added Revenue, 2026 to 2036 | USD 2.1 billion |
Adoption develops differently across countries because household cooking routines, convenience-store density, and sodium-labeling rules vary by region. FMI research indicates that commercial soup packers are replacing high-salt monosodium glutamate blends with clean-label culinary broth concentrates and natural umami peptides to retain retail shelf space. In January 2026, the U.S. Food and Drug Administration released its 2026 Human Foods Program deliverables emphasizing Phase II voluntary sodium reduction targets across commercial soups and dry meal mixes[2]. In addition to this, East Asian manufacturers are scaling vacuum freeze-drying lines for single-serve soup blocks, whereas European processors focus on organic vegetable powders packed in recyclable paper sachets.
Dehydration Method Efficiency and Reconstitution Performance Sizing
Table 2: Dehydration Method Efficiency and Reconstitution Performance Sizing for the Dried Soup Market (USD billion and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.0 | 4.2 | 6.3 |
| Commercial dried soup mixes produced (thousand metric tons) | 910 to 960 | 945 to 1,005 | 1,420 to 1,510 |
| Vacuum freeze-dried and clean-label variant share (percent) | 26.5 to 28.0 | 27.8 to 29.5 | 40.0 to 43.5 |
| Wholesale realization per metric ton (USD) | 4,320 to 4,450 | 4,340 to 4,480 | 4,460 to 4,620 |
Per Capita Packaged Soup Consumption Indicators
Urban grocery shoppers are buying larger volumes of shelf-stable noodle cups, vegetable broths, and dehydrated chowders that rehydrate cleanly without stove-top simmering. Dry-mix processors work with dehydration specialists to keep residual moisture below 5% so powders do not cake inside barrier pouches without synthetic flow agents. Furthermore, incorporating natural yeast extracts allows formulators to cut sodium by up to 30% while keeping a full savory mouthfeel.
Table 3: Per Capita and Industrial Spending Indicators for the Dried Soup Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.49 | 0.51 | 0.70 |
| Spend per 1,000 people (USD) | 486.0 | 506.0 | 703.9 |
| Commercial soup processing plant annual seasoning spend (USD thousand) | 92.0 to 102.0 | 95.5 to 106.0 | 148.0 to 165.0 |
Table 4: Facility & Industrial Channel Sizing Indicators for the Dried Soup Market (USD and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 4.2 billion | Report value |
| Licensed commercial soup and dry grocery packing facilities worldwide | 48.0 thousand | 2024 industrial census |
| Average annual revenue per manufacturing facility | USD 87.5 thousand | Facility average |
| Direct retail consumer consumption revenue, 2026 | USD 1.89 billion | 45.1% share |
Analyst Perspective
"Freeze-dried vegetable garnishes and fermented umami bases let soup brands command premium prices in single-serve retail formats. Higher sublimation energy costs and strict front-of-pack sodium thresholds still complicate recipe reformulation for mass-market pouches."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Dried Soup Market segmented?
The dried soup market is segmented by product type / grade, processing state, end-use application, sales channel, and region. In 2026, Dehydrated Noodle & Vegetable Soup is projected at 54.1%, ambient packaged dehydrated mix at 40.5%, direct retail consumer consumption at 45.1%, and supermarkets and hypermarkets at 42.5%.
By product type / grade: Dehydrated noodle and vegetable soup, bouillon and clear broth base, thickened cream and chowder soup, and functional wellness soup.
By processing state: Ambient packaged dehydrated mix, instant single-serve cups, institutional bulk powders, and freeze-dried culinary blocks.
By end-use application: Direct retail consumer consumption, quick-service restaurants and foodservice, institutional catering, and industrial meal kit assembly.
By sales channel: Supermarkets and hypermarkets, convenience grocery stores, online e-commerce channels, and wholesale food distributors.
Why does Dehydrated Noodle & Vegetable Soup lead the product type category?
Dehydrated noodle and vegetable soup is expected to hold 54.1% of product type revenue in 2026, supported by rapid rehydration.
Table 5: Product Type / Grade Share for the Dried Soup Market (percentage share), 2026
| Product Type / Grade | Share (2026) |
|---|---|
| Dehydrated Noodle & Vegetable Soup | 54.1% |
| Other Segments Combined | 45.9%* |
| Total | 100.0% |
Table 6: Product Type / Grade Leadership and Market Growth for the Dried Soup Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.2% |
| Leading Segment | Dehydrated Noodle & Vegetable Soup |
Dehydrated noodle and vegetable soups capture the largest share of category spending because combining par-steamed wheat or rice noodles with freeze-dried vegetable pieces turns a light broth into a filling lunch or dinner entree. Unlike clear bouillon bases that serve mainly as cooking stocks, noodle and vegetable soup packets provide carbohydrates, dietary fiber, and savory seasoning in one shelf-stable unit. Food plants control noodle porosity and vegetable cut thickness so both components rehydrate within three minutes of adding boiling water, although starch leaching must be controlled to prevent cloudy broth.
- Dehydrated noodle and vegetable soup is projected to account for 54.1% of product type revenue in 2026, supported by complete meal satiety and fast three-minute hot-water preparation.
- In January 2025, Unilever reported that its Knorr brand expanded its quick-prep noodle and vegetable mini-meal soup pots across European and North American grocery channels to capture at-home lunch demand[3].
What makes Ambient Packaged Dehydrated Mix central to the processing state category?
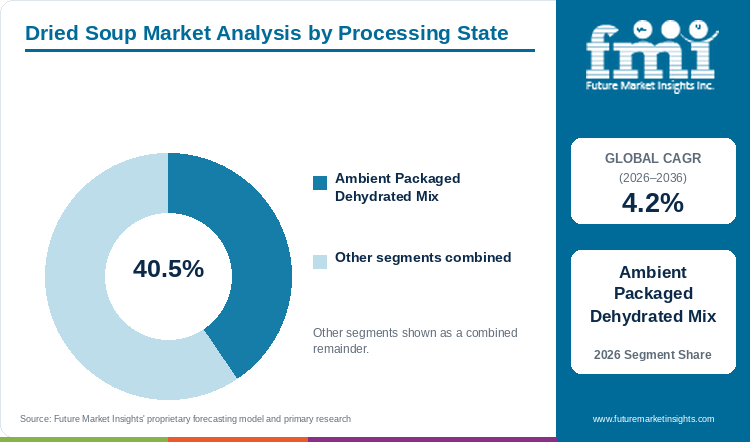
Ambient packaged dehydrated mix is projected to capture 40.5% of processing state demand in 2026, driven by room-temperature storage stability.
Ambient packaged dehydrated mixes lead processing state volume because multi-serve foil-laminated and paper-barrier pouches cost far less to ship and store than rigid single-serve cups or chilled liquid soups. Processors blend air-dried vegetables, herbs, and modified food starch under low-humidity conditions and flush pouches with nitrogen to prevent lipid oxidation over a 18-to-24 month shelf life. Because family shoppers can portion out multiple bowls from a single flat packet, ambient pouches remain the core format in supermarket dry-grocery aisles despite competition from instant cups.
- Ambient packaged dehydrated mix is estimated to hold 40.5% of processing state demand in 2026, owing to low packaging weight per serving and two-year ambient pantry stability.
- In January 2026, the World Health Organization updated its global healthy diet fact sheets urging food processors to lower sodium concentrations across shelf-stable packaged dry soup mixes and bouillon powders[4].
What keeps Direct Retail Consumer Consumption ahead by end-use application?
Direct retail consumer consumption is estimated to represent 45.1% of end-use application sales in 2026, reflecting quick household meal preparation.
Household retail buyers generate the largest share of dried soup revenue as single-person residences, students, and remote workers keep dry soup packets and compressed bouillon cubes on hand for fast home meals. Whereas foodservice kitchens buy bulk 10-kilogram seasoning tubs at wholesale discounts, retail consumers purchase branded single-serve cups and four-pack family cartons at higher per-gram realizations. Retailers also see counter-cyclical demand for ambient dry soups when restaurant menu inflation prompts households to prepare more weekday lunches and dinners at home.
- Direct retail consumer consumption is forecast to represent 45.1% of end-use application revenue in 2026, underpinned by rising single-person household formation and home lunch preparation.
- In October 2026, the Food and Agriculture Organization highlighted through its FAOSTAT food balance releases that household consumption of shelf-stable cereal and pulse-based convenience foods rose steadily across urban centers[5].
What gives Supermarkets and Hypermarkets the leading position in sales channel?
Supermarkets and hypermarkets are anticipated to contribute 42.5% of sales channel revenue in 2026, underpinned by multi-pack grocery aisle promotions.
Supermarkets and hypermarkets anchor dried soup distribution because weekly grocery shoppers compare national brands against private-label family multipacks in dedicated ambient soup aisles. Large retail chains use end-cap winter promotions and bundle discounts to move high volumes of noodle soups, chowder mixes, and broth bases during peak autumn and winter months. In addition to this, supermarket category managers increasingly allocate eye-level shelf space to organic and reduced-sodium lines formulated with clean-label savory ingredients, requiring suppliers to back up health claims with clear ingredient panels.
- Supermarkets and hypermarkets are projected to capture 42.5% of sales channel revenue in 2026, reinforced by private-label tiering and seasonal multi-pack promotional displays.
- In May 2025, the European Food Safety Authority published updated safety evaluations on glutamates and yeast-derived flavor enhancers used across retail supermarket soup and seasoning categories[6].
What are the drivers, restraints, and opportunities in the Dried Soup Market?
In the dried soup market, time-saving household meal preparation and clean-label dehydration support demand, sodium reduction rules and vegetable crop volatility constrain margins, and protein-fortified freeze-dried soups create growth opportunities through 2036.
- Driver: Urban single-person household growth and demand for shelf-stable five-minute meals will continue to support retail and foodservice dried soup volume through 2036.
- Restraint: Front-of-package sodium warnings, clean-label additive scrutiny, and fluctuating dehydrated onion, garlic, and carrot costs will continue to challenge formulators through 2036.
- Opportunity: Vacuum freeze-dried vegetable medleys and plant-protein fortified soup cups are expected to open premium retail and e-commerce margins through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Shrinking household sizes and longer urban commuting hours are pulling shelf-stable soup mixes from occasional emergency pantry stock into regular weekday lunch and dinner rotation. FMI data suggests that food manufacturers are pairing rapid-rehydrating noodles and legumes with textured vegetable protein granules so a dry soup packet delivers 12 to 18 grams of protein per bowl. In July 2026, The Campbell's Company expanded its high-protein soup portfolio in North America, addressing consumer demand for savory bowls delivering 20 grams of protein and added dietary fiber[7]. Suppliers that achieve fast three-minute rehydration without gritty protein sedimentation win wider shelf space across both supermarkets and urban convenience chains.
Risk Assessment of the Dried Soup Market: Operational and Formulation Friction
Public health mandates targeting dietary salt intake and consumer rejection of artificial flavor enhancers create persistent formulation cost friction for dried soup manufacturers. Standard dehydrated bouillon and noodle soup bases historically relied on table salt and monosodium glutamate to mask metallic off-notes from air-dried vegetables and hydrolysed vegetable protein powders. In March 2025, the U.S. Department of Agriculture Economic Research Service reported that erratic weather and higher farm input costs elevated wholesale processing vegetable prices across North American dehydration plants[8]. When soup brands replace inexpensive salt with potassium chloride, natural yeast autolysates, and culinary herb extracts while absorbing higher dehydrated vegetable prices, gross margins tighten across budget retail tiers.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Upgrading from hot-air drying to gentle vacuum freeze-drying and adding targeted wellness nutrients allows soup processors to capture convenience-store and direct-to-consumer price premiums. Freeze-dried soup blocks retain open cellular pores that rehydrate almost instantly in hot water while preserving the natural color, aroma, and vitamin content of spinach, mushrooms, miso, and seafood garnishes. In October 2025, Ajinomoto Co., Inc. commercialized fermented amino-acid and kokumi taste-modulation bases that restore rich mouthfeel in reduced-sodium dehydrated soups[9]. Combining these clean-label flavor systems with functional food ingredients such as prebiotic chicory inulin and collagen peptides helps brands attract health-conscious commuters willing to pay double the price of conventional noodle packets.
Dried Soup Market by Country (2026 to 2036)
As per FMI, South Korea leads the six profiled countries with a 5.1% CAGR from 2026 to 2036, whereas Switzerland expands at a mature 3.4% CAGR. Across these markets, national growth trajectories reflect differences in single-person household share, convenience-store hot-water dispenser infrastructure, and organic and low-sodium labeling standards.
Table 7: Country CAGR and Primary Growth Levers for the Dried Soup Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 5.1% | High single-person household share and convenience-store uptake of freeze-dried pollack, seaweed, and beef soup blocks |
| Japan | 4.7% | Daily miso and dashi broth consumption paired with senior-friendly low-sodium vacuum freeze-dried soup cubes |
| USA | 4.4% | High-protein pantry soup reformulation, private-label supermarket multipacks, and FDA front-of-pack sodium compliance |
| Germany | 4.0% | Strong organic Bio-certified dry vegetable soup demand and transition to recyclable paper barrier sachets |
| France | 3.7% | Culinary demand for dehydrated vegetable veloutes, herb-infused cooking stocks, and Nutri-Score salt reductions |
| Switzerland | 3.4% | High per-capita spend on organic alpine herb bouillon cubes and clean-label yeast-extract seasoning bases |
Source: Future Market Insights analysis
South Korea Dried Soup Market Outlook (2026 to 2036)
By 2036, South Korea is projected to grow at 5.1% CAGR, propelled by the rapid rise of one-person urban households and 24-hour convenience store dining habits across Seoul, Busan, and Incheon. Unlike western markets where dried soup is primarily a winter pantry item, Korean office workers and students year-round buy single-serve vacuum freeze-dried blocks of Hwangtae-guk (dried pollack soup), Miyeok-guk (seaweed soup), and spicy beef broth to accompany microwave rice bowls. In August 2025, South Korea's Ministry of Food and Drug Safety updated sodium-reduction and nutritional labeling standards for convenience meal replacements and dehydrated soup products[10]. High industrial electricity costs for sublimation freeze-dryers remain a local margin hurdle, prompting Korean processors to automate tray loading and sell multi-block value pouches online.
Key takeaway: In South Korea, single-person urban dining and convenience-store pairing of freeze-dried traditional soup blocks with instant rice drive the highest growth rate among profiled countries.
Japan Dried Soup Market Outlook (2026 to 2036)
Cultural integration of savory soup into breakfast, lunch, and dinner underpins demand in Japan, where the dried soup market is anticipated to grow at 4.7% CAGR between 2026 and 2036. Japanese consumers increasingly choose individually wrapped freeze-dried miso, clam, and egg-drop soup blocks because vacuum sublimation keeps whole tofu cubes, negi scallions, and wakame intact when hot water is poured. In November 2025, Japan's Ministry of Health, Labour and Welfare highlighted under its Health Japan 21 nutrition survey that household salt intake targets are driving food makers to expand reduced-sodium dashi and miso products[11]. Because domestic seniors and solo diners expect restaurant-grade dashi aroma with 25% to 30% less salt, Japanese manufacturers blend bonito and kelp extracts with fermented amino acids to protect flavor.
Key takeaway: In Japan, daily household miso and dashi consumption combined with senior demand for low-sodium freeze-dried soup blocks sustains steady premium retail turnover.
USA Dried Soup Market Outlook (2026 to 2036)
In the United States, demand for dried soup is predicted to advance at 4.4% CAGR through 2036, supported by supermarket private-label expansion and consumer interest in high-protein, quick-prep pantry meals. American households use dehydrated ramen cups, chicken noodle packets, and onion dip and soup mixes as affordable weekday staples, while outdoor and wellness shoppers buy bone-broth powder sticks and legume soup pouches. In April 2025, the U.S. Department of Agriculture Food Safety and Inspection Service issued updated compliance alerts reinforcing allergen and ingredient verification across commercial soup and meal-mix plants[12]. Proposed FDA front-of-package sodium disclosures pressure legacy high-salt noodle cups, compelling U.S. conglomerates to reformulate seasoning packets with yeast extracts, potassium salts, and roasted vegetable powders.
Key takeaway: In the USA, high supermarket multipack volume and active reformulation toward higher protein and lower sodium keep domestic revenue on a steady growth path.
Germany Dried Soup Market Outlook (2026 to 2036)
German grocery shoppers scrutinize additive E-numbers and packaging recyclability more closely than almost any other consumer market, guiding Germany to a projected 4.0% CAGR from 2026 to 2036. Major German retail banners including Edeka, Rewe, Aldi, and Lidl demand dried vegetable soups, clear broths, and Spatzle and dumpling soup mixes free from monosodium glutamate, palm oil, and artificial colorings. In September 2025, Germany's Federal Statistical Office (Destatis) recorded stable domestic production value across industrial soups, broths, and homogenized culinary preparations despite elevated energy and agricultural input costs[13]. To win private-label tenders and avoid dual-system plastic packaging surcharges, German soup packers are replacing foil-lined sachets with high-barrier recyclable paper pouches and organic Bio-certified vegetable granulates.
Key takeaway: In Germany, strict retailer clean-label standards and VerpackG packaging rules reward soup manufacturers offering palm-oil-free organic mixes in recyclable paper pouches.
France Dried Soup Market Outlook (2026 to 2036)
Culinary preference for velvety vegetable potages and scratch-cooking bouillon aids shapes the market in France, where dried soup sales are forecast to expand at 3.7% CAGR through 2036. While aseptic liquid carton soups compete strongly in French hypermarkets during winter, dehydrated vegetable veloutes, fish soup mixes, and bouquet-garni bouillon tablets retain loyal household and bistro kitchen usage for sauce and stew preparation. In May 2025, France's Ministry of Agriculture and Food Sovereignty implemented the updated Nutri-Score algorithm across packaged foods, tightening nutritional grading penalties on high-salt dehydrated soups and broths[14]. Because a poor Nutri-Score D or E rating reduces hypermarket promotional eligibility, French manufacturers are increasing dehydrated vegetable solids above 35% and cutting sodium across flagship pouch lines.
Key takeaway: In France, updated Nutri-Score salt penalties and culinary demand for rich vegetable potages are driving brands to raise vegetable content and lower sodium.
Switzerland Dried Soup Market Outlook (2026 to 2036)
Switzerland represents a mature, high-margin market projected to expand at 3.4% CAGR from 2026 to 2036, anchored by strong domestic loyalty to heritage culinary bouillon pastes, cubes, and alpine herb soup mixes. Swiss households and mountain hospitality kitchens pay premium retail prices for organic yeast-based vegetable bouillons, barley soup mixes, and gluten-free clear broths sold through Coop and Migros supermarkets. In November 2025, Switzerland's Federal Food Safety and Veterinary Office advanced national agreements with food processors under the Swiss Nutrition Strategy to reduce salt levels in soups and savory convenience foods through 2028[15]. High domestic labor and raw-material costs limit low-price bulk manufacturing in Switzerland, so local producers focus on concentrated clean-label paste and powder formulations with certified Swiss and European organic herbs.
Key takeaway: In Switzerland, high consumer purchasing power and voluntary federal salt-reduction agreements support premium demand for organic alpine bouillon and clean-label vegetable soups.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Dried Soup Market?
The Campbell’s Company, Unilever PLC (Knorr), Ajinomoto Co., Inc., Toyo Suisan Kaisha, Ltd., Nissin Foods Holdings Co., Ltd., General Mills Inc., Premier Foods plc, and B&G Foods, Inc. are the significant market players in this market.
As per the analysis from FMI, the dried soup competitive arena divides between global ambient grocery conglomerates, Asian instant noodle and freeze-dried soup specialists, and regional savory brand owners. Unilever PLC (through Knorr) and The Campbell’s Company command broad supermarket shelf space across North America and Europe with multi-serve soup pouches and bouillon bases. Ajinomoto Co., Inc., Toyo Suisan Kaisha, Ltd., and Nissin Foods Holdings Co., Ltd. lead in fermented umami flavor science, rapid-rehydrating noodle cups, and vacuum freeze-dried soup blocks, while General Mills Inc., Premier Foods plc, and B&G Foods, Inc. focus on regional family pantry staples. Retailers evaluate suppliers on sodium-reduction capability, rehydration speed, and recyclable packaging.
- Global Savory and Pantry Soup Leaders: Unilever PLC (Knorr), The Campbell’s Company, and General Mills Inc. supply mass-retail dehydrated soup pouches, bouillon bases, and dry meal mixes.
- Umami Fermentation and Freeze-Dried Soup Specialists: Ajinomoto Co., Inc., Toyo Suisan Kaisha, Ltd., and Nissin Foods Holdings Co., Ltd. combine amino-acid flavor engineering with instant noodle and vacuum freeze-dried soup lines.
- Regional Grocery and Specialty Seasoning Producers: Premier Foods plc and B&G Foods, Inc. market heritage British and North American dry soup packets, bouillon cubes, and kosher seasoning mixes.
Competitive Benchmarking: Dried Soup Market
Table 8: Competitive Benchmarking for the Dried Soup Market (qualitative capability ratings), 2026
| Company | Dehydration & Freeze-Drying Breadth | Clean-Label & Sodium-Reduction Depth | Retail & Foodservice Channel Access | Geographic Reach |
|---|---|---|---|---|
| The Campbell’s Company | High | High | High | Medium |
| Unilever PLC (Knorr) | High | High | High | High |
| Ajinomoto Co., Inc. | High | High | High | High |
| Toyo Suisan Kaisha, Ltd. | High | Medium | High | Medium |
| Nissin Foods Holdings Co., Ltd. | High | Medium | High | High |
| General Mills Inc. | Medium | High | High | Medium |
| Premier Foods plc | Medium | Medium | High | Medium |
| B&G Foods, Inc. | Medium | Medium | Medium | Medium |
Key Developments in the Dried Soup Market
- Unilever agreed on March 31, 2026, to combine its Foods business with McCormick in a deal creating a $20 billion-revenue global flavour powerhouse, bringing together brands including Hellmann’s and Knorr. The transaction values Unilever Foods at $44.8 billion and is expected to close by mid-2027.
- On March 27, 2025, Nestlé expanded its Maggi Air Fryer Range into the United Kingdom and Malaysia, supporting the brand’s push into the convenience cooking segment across two key markets.
- In July 2024, Ajinomoto introduced Soup & Go, its first instant soup product in the Philippine market, available at 7-Eleven and supermarkets across the Philippines, featuring one-minute preparation and positioning the product as a nutritious morning meal solution.
Key Players in the Dried Soup Market
Global Savory and Pantry Soup Leaders
- The Campbell’s Company
- Unilever PLC (Knorr)
- General Mills Inc.
Umami Science and Freeze-Dried Soup Specialists
- Ajinomoto Co., Inc.
- Toyo Suisan Kaisha, Ltd.
- Nissin Foods Holdings Co., Ltd.
Regional Grocery and Culinary Mix Producers
- Premier Foods plc
- B&G Foods, Inc.
Dried Soup Market - Report Scope
Table 9: Report Scope for the Dried Soup Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type / Grade; Processing State; End-Use Application; Sales Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes manufacturer revenue from ambient dehydrated soup packets, instant soup cups, freeze-dried soup blocks, and dry bouillon and broth soup bases. Excludes ready-to-serve wet canned soups, chilled liquid soups, and frozen soups. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, Japan, USA, Germany, France, Switzerland, and additional countries in the full report |
| Key Companies Covered | The Campbell’s Company, Unilever PLC (Knorr), Ajinomoto Co., Inc., Toyo Suisan Kaisha, Ltd., Nissin Foods Holdings Co., Ltd., General Mills Inc., Premier Foods plc, B&G Foods, Inc. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Dried Soup Market - Research Methodology
Table 10: Research Methodology for the Dried Soup Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with industrial food dehydration engineers, savory flavor technologists, packaged soup brand managers, and supermarket grocery category buyers to validate rehydration standards, sodium-reduction costs, and channel shares. |
| Secondary Research | Secondary research synthesized corporate annual reports, investor presentations, FDA and EFSA food labeling and additive publications, USDA and FAO agricultural commodity bulletins, and national statistical office production registries. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 combined top-down and bottom-up triangulation of dry soup blending plant output, supermarket scanner sales, and foodservice dry-base procurement across covered regions. |
| Data Triangulation and Validation | Estimates were cross-checked against dehydrated vegetable supply volumes, retail dry-grocery category turnover, and corporate savory segment disclosures to ensure accuracy without double-counting wet soup categories. |
Dried Soup Market by Segments
Dried Soup Market segmented by Product Type / Grade:
- Dehydrated Noodle & Vegetable Soup
- Bouillon & Clear Broth Base
- Thickened Cream & Chowder Soup
- Functional Wellness Soup
Dried Soup Market segmented by Processing State:
- Ambient Packaged Dehydrated Mix
- Instant Single-Serve Cups
- Institutional Bulk Powders
- Freeze-Dried Culinary Blocks
Dried Soup Market segmented by End-Use Application:
- Direct Retail Consumer Consumption
- Quick-Service Restaurants & Foodservice
- Institutional Catering
- Industrial Meal Kit Assembly
Dried Soup Market segmented by Sales Channel:
- Supermarkets & Hypermarkets
- Convenience Grocery Stores
- Online E-Commerce Channels
- Wholesale Food Distributors
Dried Soup Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Food and Drug Administration. (2025, January 14). FDA Proposes Requiring At-a-Glance Nutrition Information on the Front of Packaged Foods. U.S. Department of Health and Human Services.
- [2] U.S. Food and Drug Administration. (2026, January 23). FDA Releases 2026 Deliverables for Human Foods Program: Sodium Reduction and Nutrition Labeling. Center for Food Safety and Applied Nutrition.
- [3] Unilever PLC. (2025, January 29). The growing mini meals trend: Knorr's winning formula in quick-prep dehydrated pots and bouillon. Unilever Corporate Newsroom.
- [4] World Health Organization. (2026, January 26). Healthy Diet Fact Sheet: Global Guidelines on Sodium Reduction and Processed Ambient Foods. WHO Department of Nutrition and Food Safety.
- [5] Food and Agriculture Organization of the United Nations. (2026, October 8). FAOSTAT Food Balances and Dehydrated Commodity Utilization Database. FAO Statistics Division Rome.
- [6] European Food Safety Authority (EFSA). (2025, May 19). Scientific evaluation of clean-label savory flavor enhancers and yeast extracts in prepared ambient foods. EFSA Journal, 23(5), e08544.
- [7] The Campbell's Company. (2026, July 14). Campbell's cooks up new soup lineup with 20g of protein per serving to meet consumer nutrition demand. Corporate Media Releases.
- [8] Economic Research Service, U.S. Department of Agriculture. (2025, March 20). Vegetables and Pulses Outlook: Processing and Dehydrated Vegetable Supply and Farm Price Trends. USDA ERS Situation and Outlook Reports.
- [9] Ajinomoto Co., Inc. (2025, October 24). Commercialization of fermented amino-acid and kokumi seasoning complexes for reduced-sodium dehydrated soup matrices. Corporate R&D Bulletins.
- [10] Ministry of Food and Drug Safety (MFDS). (2025, August 28). Updated nutritional labeling and sodium-reduction standards for ambient convenience foods and freeze-dried soups. Government of South Korea Regulatory Reports.
- [11] Ministry of Health, Labour and Welfare (MHLW). (2025, November 18). National Health and Nutrition Survey: Household Salt Reduction Progress and Instant Soup Consumption in Japan. Government of Japan Health Bureau.
- [12] Food Safety and Inspection Service, U.S. Department of Agriculture. (2025, April 13). Public health compliance and allergen verification standards for commercial soup and meal-mix establishments. USDA FSIS Directives.
- [13] Federal Statistical Office (Destatis). (2025, September 14). Industrial production statistics: Manufacturing of soups, broths, and dehydrated culinary preparations in Germany. Statistisches Bundesamt Wiesbaden.
- [14] Ministry of Agriculture and Food Sovereignty, Government of France. (2025, May 12). Implementation of the updated Nutri-Score calculation algorithm for packaged soups and broths. Official Bulletin of Agriculture France.
- [15] Federal Food Safety and Veterinary Office (BLV). (2025, November 10). Swiss Nutrition Strategy 2025-2028: Voluntary Salt Reduction Milan Declaration Targets for Soups and Dressings. Swiss Confederation Bern.
- [16] Nissin Foods Holdings Co., Ltd. (2026, September 15). Expansion of Cup Noodles Protein instant ramen soup line with doubled protein content in North America. Nissin Foods Corporate Disclosures.
- [17] Toyo Suisan Kaisha, Ltd. (2026, February 14). Expansion of continuous vacuum freeze-drying production lines for single-serve soup blocks in Japan. Corporate Operations Review.
- [18] Premier Foods plc. (2025, November 12). Modernization of automated sachet packaging lines for Batchelors Cup a Soup and ambient savory mixes. Premier Foods Interim Report.
- [19] General Mills Inc. (2025, September 18). Ambient pantry dry mix and clean-label vegetable soup portfolio update across North American retail. Corporate Investor Presentation.
- [20] B&G Foods, Inc. (2025, August 22). Specialty dry grocery, bouillon, and institutional soup seasoning blend portfolio realignment. Corporate Financial Disclosures.
- [21] Unilever PLC. (2025, June 18). Implementation of recyclable paper barrier laminates for Knorr dehydrated bouillon sachets and soup pouches in Europe. Corporate Sustainability Publications.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the dried soup market in 2026 and what is forecast for 2036?
- Which urban household and workplace meal pressures support demand for dried soups?
- Why does dehydrated noodle and vegetable soup lead the product type category?
- Why does ambient packaged dehydrated mix lead the processing state category globally?
- How do growth rates differ across South Korea, Japan, the USA, and Germany?
- Which leading companies supply dehydrated, instant-cup, and freeze-dried soup lines today?
- What limits consumer acceptance or margin expansion in the dried soup market?
- What should grocery category managers evaluate before expanding a dried soup shelf set?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type / Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type / Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type / Grade, 2026 to 2036
- Dehydrated Noodle & Vegetable Soup
- Bouillon & Clear Broth Base
- Thickened Cream & Chowder Soup
- Functional Wellness Soup
- Y-o-Y Growth Trend Analysis By Product Type / Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type / Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Processing State, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Processing State, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Processing State, 2026 to 2036
- Ambient Packaged Dehydrated Mix
- Instant Single-Serve Cups
- Institutional Bulk Powders
- Freeze-Dried Culinary Blocks
- Y-o-Y Growth Trend Analysis By Processing State, 2021 to 2025
- Absolute $ Opportunity Analysis By Processing State, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Application, 2026 to 2036
- Direct Retail Consumer Consumption
- Quick-Service Restaurants & Foodservice
- Institutional Catering
- Industrial Meal Kit Assembly
- Y-o-Y Growth Trend Analysis By End-Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Grocery Stores
- Online E-Commerce Channels
- Wholesale Food Distributors
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- Israel
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type / Grade
- By Processing State
- By End-Use Application
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Campbell’s Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Unilever PLC (Knorr)
- Ajinomoto Co., Inc.
- Toyo Suisan Kaisha, Ltd.
- Nissin Foods Holdings Co., Ltd.
- General Mills Inc.
- Premier Foods plc
- B&G Foods, Inc.
- The Campbell’s Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 6: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 11: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 12: Latin America Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 16: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 17: Western Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 18: Western Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 21: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 22: Eastern Europe Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 23: Eastern Europe Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 24: Eastern Europe Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 26: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 27: East Asia Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 28: East Asia Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 29: East Asia Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 30: East Asia Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 31: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 33: South Asia and Pacific Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 34: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 35: South Asia and Pacific Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
- Table 36: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 37: Middle East and Africa Market Value (USD Billion) Forecast by Product Type / Grade, 2021 to 2036
- Table 38: Middle East and Africa Market Value (USD Billion) Forecast by Processing State, 2021 to 2036
- Table 39: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Application, 2021 to 2036
- Table 40: Middle East and Africa Market Value (USD Billion) Forecast by Sales Channel, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type / Grade
- Figure 6: Global Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Processing State
- Figure 9: Global Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by End-Use Application
- Figure 12: Global Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Sales Channel
- Figure 15: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Region
- Figure 18: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 19: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 20: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 21: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 26: North America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 27: North America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 28: North America Market Attractiveness Analysis by Product Type / Grade
- Figure 29: North America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Processing State
- Figure 32: North America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End-Use Application
- Figure 35: North America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Sales Channel
- Figure 38: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 39: Latin America Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 40: Latin America Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 41: Latin America Market Attractiveness Analysis by Product Type / Grade
- Figure 42: Latin America Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 43: Latin America Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 44: Latin America Market Attractiveness Analysis by Processing State
- Figure 45: Latin America Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by End-Use Application
- Figure 48: Latin America Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Sales Channel
- Figure 51: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 52: Western Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 53: Western Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 54: Western Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 55: Western Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 56: Western Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 57: Western Europe Market Attractiveness Analysis by Processing State
- Figure 58: Western Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 59: Western Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 60: Western Europe Market Attractiveness Analysis by End-Use Application
- Figure 61: Western Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Sales Channel
- Figure 64: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 65: Eastern Europe Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 66: Eastern Europe Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 67: Eastern Europe Market Attractiveness Analysis by Product Type / Grade
- Figure 68: Eastern Europe Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 69: Eastern Europe Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 70: Eastern Europe Market Attractiveness Analysis by Processing State
- Figure 71: Eastern Europe Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 72: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 73: Eastern Europe Market Attractiveness Analysis by End-Use Application
- Figure 74: Eastern Europe Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 75: Eastern Europe Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 76: Eastern Europe Market Attractiveness Analysis by Sales Channel
- Figure 77: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 78: East Asia Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 79: East Asia Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 80: East Asia Market Attractiveness Analysis by Product Type / Grade
- Figure 81: East Asia Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 82: East Asia Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 83: East Asia Market Attractiveness Analysis by Processing State
- Figure 84: East Asia Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 85: East Asia Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 86: East Asia Market Attractiveness Analysis by End-Use Application
- Figure 87: East Asia Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 88: East Asia Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 89: East Asia Market Attractiveness Analysis by Sales Channel
- Figure 90: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 91: South Asia and Pacific Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 92: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 93: South Asia and Pacific Market Attractiveness Analysis by Product Type / Grade
- Figure 94: South Asia and Pacific Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 95: South Asia and Pacific Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 96: South Asia and Pacific Market Attractiveness Analysis by Processing State
- Figure 97: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 98: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 99: South Asia and Pacific Market Attractiveness Analysis by End-Use Application
- Figure 100: South Asia and Pacific Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 101: South Asia and Pacific Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 102: South Asia and Pacific Market Attractiveness Analysis by Sales Channel
- Figure 103: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 104: Middle East and Africa Market Value Share and BPS Analysis by Product Type / Grade, 2026 and 2036
- Figure 105: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type / Grade, 2026-2036
- Figure 106: Middle East and Africa Market Attractiveness Analysis by Product Type / Grade
- Figure 107: Middle East and Africa Market Value Share and BPS Analysis by Processing State, 2026 and 2036
- Figure 108: Middle East and Africa Market Y-o-Y Growth Comparison by Processing State, 2026-2036
- Figure 109: Middle East and Africa Market Attractiveness Analysis by Processing State
- Figure 110: Middle East and Africa Market Value Share and BPS Analysis by End-Use Application, 2026 and 2036
- Figure 111: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Application, 2026-2036
- Figure 112: Middle East and Africa Market Attractiveness Analysis by End-Use Application
- Figure 113: Middle East and Africa Market Value Share and BPS Analysis by Sales Channel, 2026 and 2036
- Figure 114: Middle East and Africa Market Y-o-Y Growth Comparison by Sales Channel, 2026-2036
- Figure 115: Middle East and Africa Market Attractiveness Analysis by Sales Channel
- Figure 116: Global Market - Tier Structure Analysis
- Figure 117: Global Market - Company Share Analysis
Frequently Asked Questions
How large is the Dried Soup Market expected to be in 2026, and what is forecast for 2036?
The global dried soup market is estimated to reach USD 4.2 billion in 2026. The market is projected to expand further and reach USD 6.3 billion by 2036.
What CAGR is forecast for the Dried Soup Market through 2036?
As per FMI, the dried soup market is projected to grow at a 4.2% CAGR from 2026 to 2036. Growth is supported by expanding single-person households and rising adoption of clean-label freeze-dried soup mixes.
Which product type holds a notable dried soup demand share in 2026?
Dehydrated Noodle & Vegetable Soup is projected to hold 54.1% of product type demand in 2026. The segment benefits from fast three-minute hot-water rehydration and complete meal satiety at an affordable retail price.
Which processing state segment leads the Dried Soup Market in 2026?
Ambient packaged dehydrated mix is estimated to account for 40.5% of processing state demand in 2026. Demand is supported by low freight weight, zero refrigeration costs, and two-year pantry shelf life.
Which country has a notable dried soup expansion outlook during the forecast period?
FMI finds that South Korea is projected to expand at a 5.1% CAGR during the 2026 to 2036 assessment period. Growth is supported by dense convenience-store networks and consumer demand for freeze-dried traditional soup blocks.
Which companies are active in the Dried Soup Market during 2026?
Notable companies include Campbell Soup Company, Unilever PLC (Knorr), Ajinomoto Co., Inc., Toyo Suisan Kaisha, Ltd., Nissin Foods Holdings Co., Ltd., General Mills Inc., Premier Foods plc, and B&G Foods, Inc. These producers focus on sodium reduction, vacuum freeze-drying, and recyclable barrier sachets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
