

- Market Size (2026)
- USD 12.4 Bn
- Forecast (2036)
- USD 19.5 Bn
- CAGR (2026 to 2036)
- 4.6%
How big is Fiber Cement Board Market in 2026?
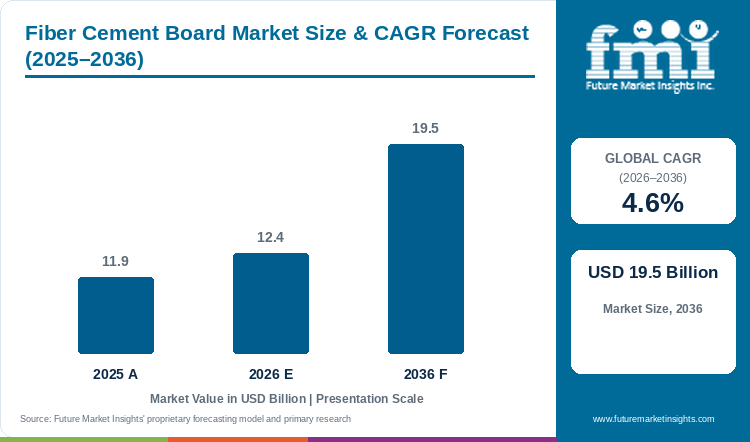
Fiber cement board sales carry a 4.6% CAGR from 2026 to 2036. Sales stood at USD 11.9 billion in 2025, are estimated at USD 12.4 billion in 2026 and are projected at USD 19.5 billion for 2036.
Key trends in the fiber cement board market point to production moving toward regions with housing growth and toward coated, ready-to-fit cladding. Sales of fiber cement boards stood at USD 11.9 billion in 2025 and are estimated at USD 12.4 billion in 2026, and the updated report by FMI finds that sales are projected to reach USD 19.5 billion by 2036 at a 4.6% CAGR from 2026 to 2036. Board lines share autoclaves with pipe and sheet lines at the same plants. The fiber cement market is projected to grow at a 4.5% CAGR from 2026 to 2036, and producers are moving plant hours toward siding, the largest product type. James Hardie reported a low-double-digit rise in North American fiber cement volume in the June 2026 quarter.[1] Siding already holds 39.1% of 2026 product sales, and the North American volume rise at James Hardie is igniting the next phase of business growth for siding lines. Roofing boards hold an estimated 14.6% of product sales, and the roofing materials market is expected to grow at a 5.3% CAGR between 2026 and 2036, so re-roofing jobs will add board volume. Increasing green certification is supporting the demand for recycled-content boards, and the green building materials market is estimated to grow at an 11.3% CAGR for 2026 to 2036. A curing energy constraint is slowing margin gains at older autoclave plants, so producers are adding heat recovery before new lines. Brazil records the fastest profiled CAGR at 5.7%, and the USA the slowest at 3.7%.
Key Market Trends & Insights
- Siding boards outsold roofing, flooring and partition boards in 2026, at 39.1% of product type sales.
- Etex reported Fibre Cement revenue up 5.4% like-for-like over January to June 2026.[2] Homebuilders stay the largest buyer group, with residential construction at 35.6% of 2026 application demand.
- Adoption of 6 mm to 12 mm boards is widest among cladding and partition installers, at about 52.3% (estimated) of 2026 thickness sales.
Regional Highlights
- Light construction growth puts Brazil first among profiled countries, at a 5.7% CAGR from 2026 to 2036.
- Germany follows at 5.4%, India at 5% and China at 4.3%, with the USA lowest at 3.7%.
- Saint-Gobain reported double-digit growth in India for the first half of 2026.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Fiber Cement Board Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 11.9 billion |
| Estimated Market Size in 2026 | USD 12.4 billion |
| Projected Market Size by 2036 | USD 19.5 billion |
| CAGR, 2026 to 2036 | 4.6% |
| Added Revenue, 2026 to 2036 | USD 7.1 billion |
| Market Expansion Multiple | 1.6x |
FMI estimates a 4.6% CAGR for demand for boards from 2026 to 2036, from USD 11.9 billion in 2025. Cladding, flooring, ceiling and partition boards draw on one plant process, so makers shift output toward the board with the best margin. Installers finish many boards on site with primers and sealers, so board volume also feeds growth of the construction chemicals market.
Plant Investment Moves Toward Growth Regions
Board and plasterboard makers are adding capacity in Latin America and trimming exposure to weak European segments. Saint-Gobain is building a fourth plasterboard line at the Bahia plant in Brazil, the August 2026 release said.[4] Etex reported strong first-half 2026 performance in Asia-Pacific, Latin America, and Southern and Eastern Europe.[2] Etex named France and the UK as the more challenging regions.[2] James Hardie reported Australia and New Zealand sales up 26% in the June 2026 quarter.[1] Fiber cement orders will follow toward Etex lines in Asia-Pacific and Latin America and James Hardie plants in Australia and New Zealand.
Table 2: Plant and Regional Indicators for the Fiber Cement Board Market (USD, euros, percentage and units), mixed reporting periods from 2025 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| James Hardie Siding and Trim net sales, quarter to 30 June 2026 | $859.8 million, up 34% | North American cladding demand. | [1] |
| Etex Fibre Cement revenue, H1 2026 | EUR 286 million, up 5.4% like-for-like | Board demand at a Tier 1 maker. | [2] |
| Saint-Gobain Bahia plant, August 2026 | Fourth plasterboard line under construction | Light construction capacity in Brazil. | [4] |
| Saint-Gobain Asia-Pacific organic growth, H1 2026 | 7% | Building material demand in India and China. | [3] |
| US housing completions, August 2026 | 1,128,000 annual rate | New-home pool for siding in the USA. | [5] |
| German dwelling permits, 2025 | 238,500, up 10.8% | Future new-build demand in Germany. | [6] |
| China residential floor space newly started, January to August 2026 | 218.40 million sq m, down 25.4% | Fewer new Chinese housing starts. | [7] |
Analyst Perspective
“Boards with recycled content and certified fire ratings will carry a price premium in green-certified projects, and I expect that premium to protect margins as curing energy costs stay high. Makers selling coated, ready-to-fit siding systems will earn better margins than producers selling plain sheets into commodity roofing.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the fiber cement board market segmented?
The fiber cement board split covers product type, application, thickness and region. Siding boards lead product type at 39.1%, residential construction leads application at 35.6% and 6 mm to 12 mm boards lead thickness at an estimated 52.3% in 2026.
Product types: siding, flooring, roofing, ceiling, partition, decorative, insulation.
By application: residential, commercial and industrial construction, agricultural buildings, interior applications, walls, ceilings, partitions and exterior applications.
By thickness: below 6 mm, 6 mm to 12 mm, above 12 mm.
By region: seven blocks, listed below.
Why do siding boards lead product type sales?
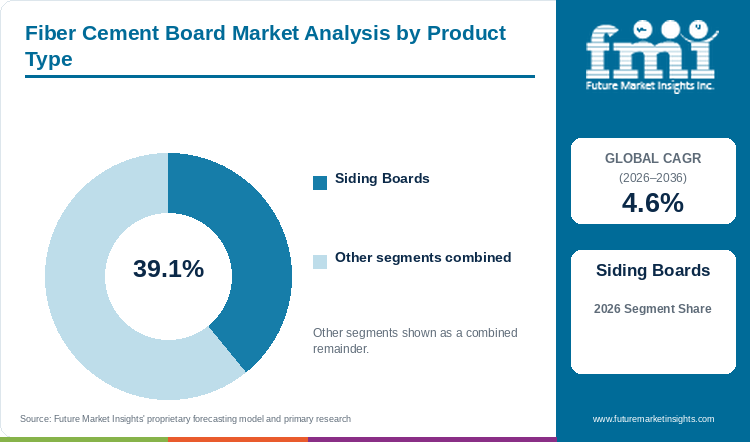
Siding boards stay first in 2026 on 39.1% of product type sales, and roofing and flooring boards come next.
Table 3: Product Type Share for the Fiber Cement Board Market (percentage share), 2026
| Product Type | Estimated Share (2026) |
|---|---|
| Siding Boards | 39.1% |
| Roofing Boards | 14.6% |
| Flooring Boards | 11.2% |
| Partition Boards | 10.4% |
| Ceiling Boards | 9.8% |
| Decorative Boards | 8.3% |
| Insulation Boards | 6.6% |
| Total | 100.0% |
Table 4: Product Type Leadership and Market Growth for the Fiber Cement Board Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.6% |
| Leading Segment | Siding Boards |
Sales of siding boards come in house-lot orders from homebuilders and cladding contractors, so siding boards take 39.1% of 2026 product type sales, FMI's report shows. Roofing boards, at an estimated 14.6%, lose many jobs to metal sheet and tile on price. James Hardie siding and trim sales rose 20% organically in the June 2026 quarter, led by a return to volume growth in North American fiber cement.[1] Flooring boards, about 11.2% (estimated), need a dry, level base and serve mainly mezzanines and wet rooms. Partition boards near 10.4% (estimated) and ceiling boards at roughly 9.8% (estimated) compete with plasterboard, which is lighter and cheaper for dry interiors. Decorative boards, an estimated 8.3%, serve feature walls and soffits only, and insulation boards at about 6.6% (estimated) are a newer retrofit product. Etex said fibre cement growth over January to June 2026 came from most product categories except sidings, so the siding lead will narrow in Europe.[2]
- Insulation boards will gain in cold-climate retrofits that combine cladding and thermal upgrades.
Why does residential construction lead application demand?
Residential construction takes 35.6% of application demand in 2026, ahead of commercial construction and exterior applications.
Table 5: Application Share for the Fiber Cement Board Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Residential Construction | 35.6% |
| Commercial Construction | 21.4% |
| Exterior Applications | 9.6% |
| Industrial Construction | 8.7% |
| Walls | 7.2% |
| Interior Applications | 5.8% |
| Ceilings | 4.3% |
| Agricultural Buildings | 3.9% |
| Partitions | 3.5% |
| Total | 100.0% |
At 35.6% of 2026 application demand, residential construction is the largest buyer, because homebuilders use boards for cladding, soffits, wet-room linings and roofing on the same house. Commercial construction, an estimated 21.4%, builds fewer projects and often specifies glass, metal panels or stone on facades. Exterior applications at about 9.6% (estimated) and walls at an estimated 7.2% are mostly repair jobs on single elevations. Industrial construction, roughly 8.7% (estimated), favours metal cladding on large sheds. Interior applications at about 5.8% (estimated), ceilings at 4.3% (estimated) and partitions at an estimated 3.5% lose on price to plasterboard. Agricultural buildings take about 3.9% (estimated), as barns and storage sheds order corrugated sheets in small lots. Single-family completions in the USA ran at 816,000 on an annual basis in August 2026, the Census Bureau reported.[5]
Why do 6 mm to 12 mm boards lead thickness sales?
Boards of 6 mm to 12 mm hold an estimated 52.3% of thickness sales in 2026, ahead of thinner and thicker boards.
Table 6: Thickness Share for the Fiber Cement Board Market (percentage share), 2026
| Thickness | Estimated Share (2026) |
|---|---|
| Below 6 mm | 27.4% |
| 6 mm to 12 mm | 52.3% |
| Above 12 mm | 20.3% |
| Total | 100.0% |
Demand for 6 mm to 12 mm boards comes from cladding planks and partition panels, and the band holds an estimated 52.3% of 2026 thickness sales. Boards below 6 mm, about 27.4% (estimated), are too thin for exterior walls and serve ceilings and interior linings. Boards above 12 mm, roughly 20.3% (estimated), weigh more and cost more per square metre, so buyers keep them for floors and fire-rated walls.
- Lighter, higher-strength mid-band boards will gain as installers seek faster fitting with fewer crew hours.
What are the drivers, restraints, and opportunities in the fiber cement board market?
Demand for fiber cement boards rises with PMAY-Urban housing in India, light construction in Brazil and a 10.8% rise in German dwelling permits. Installation skill needs, labour shortages and energy-intensive curing hold back growth, and recycled-content boards open a new route to certified projects.
- Driver: Over 1.25 crore PMAY-Urban houses sanctioned in India by August 2026.
- Restraint: Skilled installation, labour shortages and energy-intensive autoclave curing.
- Opportunity: Thin, light boards and recycled-content grades for green-certified buildings.
Urban Housing Programs Add Board Orders in India
Affordable urban homes are the main Indian outlet for boards, analysts at FMI see. PMAY-Urban sanctions passed 1.25 crore houses by August 2026, the housing secretary said.[8] Low-cost homes use boards for roofing, partitions and ceilings. Indian board sales will grow with each sanctioned housing round.
Labour Shortages and Curing Energy Raise Costs
Producers of fiber cement boards face two cost lines at once, skilled installation and high energy use in autoclave curing. German completions fell 18% in 2025 as permits rose 10.8%, VDIV reported, so finished building work is lagging approvals.[6] Plants with heat recovery and lower-emission curing will hold costs better through 2036.
Recycled-Content Boards Gain Certified Projects
Specifiers on green-certified projects ask for recycled content, so thinner, recycled-content boards from lower-emission plants fit those tenders. In Germany, Saint-Gobain saw a return to growth in H1 2026, carried by insulation and light construction solutions.[3] Light construction systems pair boards with frames and insulation batts in one wall build-up, and growth of the insulation market will add board orders in the same projects.
Which country CAGRs are profiled in the fiber cement board market?
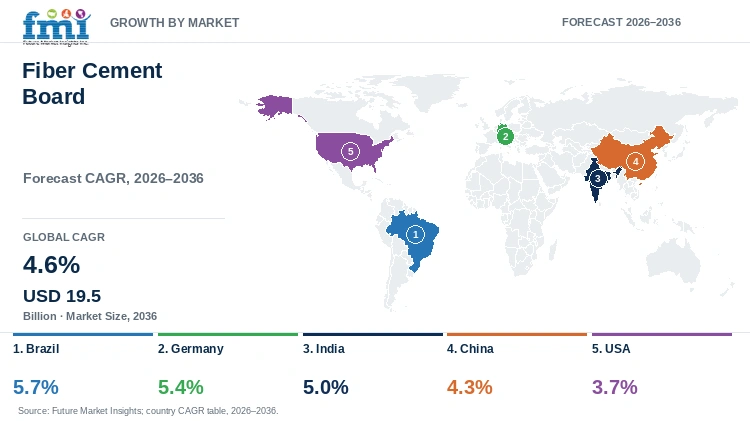
Table 7: Country CAGR Comparison for the Fiber Cement Board Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| Brazil | 5.7% |
| Germany | 5.4% |
| India | 5% |
| China | 4.3% |
| USA | 3.7% |
How do country-level CAGRs compare in the fiber cement board market?
Saint-Gobain gained share in Brazilian light construction in H1 2026, and Brazilian demand for boards leads profiled countries on a 5.7% CAGR from 2026 to 2036, FMI reports.[3] A 10.8% rise in 2025 dwelling permits carries Germany to 5.4%, and PMAY-Urban housing carries India to 5%. China records 4.3% as new housing starts fall, and the USA 3.7% on a mature siding base.
- Brazilian builders are turning to light construction, the segment Saint-Gobain grew in H1 2026.
- German dwelling permits rose 10.8% in 2025, and board orders follow at the cladding stage.
- PMAY-Urban sanctions passed 1.25 crore houses by August 2026.
- Residential starts in China fell 25.4% in January to August 2026.
- James Hardie cited resilient US repair and remodel work in August 2026.
Full report country CAGRs cover: Mexico, Canada, Chile, the UK, France, Italy, Spain, the Nordics, Poland, Russia, Japan, South Korea, ASEAN, Australia, the GCC and South Africa across the seven regional blocks.
Country-wise Analysis
Brazil Fiber Cement Board Market Outlook (2026 to 2036)
Brazilian builders are turning to light construction, and Brazil captured further market share in light construction and construction chemicals during January to June 2026, Saint-Gobain said.[3] A fourth plasterboard line at Bahia will compete with fiber cement for interior partitions.[4] Brazil records the top profiled CAGR at 5.7% from 2026 to 2036, with fiber cement holding exterior and wet-area uses.
Key takeaway: Brazilian board makers will hold exterior walls and wet rooms as plasterboard takes more dry interiors.
Germany Fiber Cement Board Market Outlook (2026 to 2036)
Permits for German dwellings rose 10.8% to 238,500 in 2025, VDIV reported, and completions dropped 18%, so board orders lag the permit rise.[6] German demand for boards carries a 5.4% CAGR from 2026 to 2036, the second-highest profiled rate.
Key takeaway: Orders in Germany will pick up as 2025 permits reach the cladding stage.
India Fiber Cement Board Market Outlook (2026 to 2036)
India holds 12.3% of South Asia and Pacific demand in FMI's analysis. Over one crore PMAY-Urban homes reached beneficiaries by August 2026.[8] Roofing sheets and partition boards suit low-cost urban homes, and board sales grow at a 5% CAGR from 2026 to 2036.
Key takeaway: Roofing and partition boards for PMAY-Urban homes will carry Indian orders.
China Fiber Cement Board Market Outlook (2026 to 2036)
Chinese developers started 218.40 million sq m of residential floor space in January to August 2026, 25.4% below the same months of 2025.[7] Fewer housing starts are slowing board orders for new flats, and infrastructure and urban renewal will carry more of the volume. FMI estimates China at 21.5% of East Asia demand, with growth at a 4.3% CAGR from 2026 to 2036.
Key takeaway: Infrastructure and renewal projects will replace new flats as the main Chinese outlet for boards.
USA Fiber Cement Board Market Outlook (2026 to 2036)
The USA holds 37.3% of North American demand, though the country has the slowest profiled CAGR, 3.7% from 2026 to 2036. James Hardie cited greater resilience in higher-end repair and remodel and multifamily markets in August 2026.[1] Single-family completions held up better than starts, the company said.[1] Repair and remodel jobs on older homes will keep US siding sales growing.
Key takeaway: Repair and remodel work and multifamily projects will carry US board makers until single-family starts recover.
Who are the notable companies in the fiber cement board market?
James Hardie Industries, Etex Group, Cembrit, Saint-Gobain, Mahaphant Fibre Cement, Elementia, Everest Industries, Hume Cemboard Industries and Nichiha Corporation are the key suppliers.
Tier 1 companies earn revenue above USD 4,400 million and hold 35 to 45% of global sales, FMI's tier analysis shows. James Hardie, Etex, Cembrit and Saint-Gobain form Tier 1. Mahaphant, Elementia and Everest Industries compete as regional Tier 2 players.
Etex and Saint-Gobain are expanding market boundaries through new applications in insulation and light construction. James Hardie raised the FY27 outlook in August 2026, targeting pro forma sales growth of 5.9% to 9%.[1] Etex entered exclusive talks with Austrotherm on URSA extruded polystyrene activities in August 2026.[2] Saint-Gobain expanded plasterboard capacity in Brazil.[4]
- Tier 1 groups: James Hardie Industries PLC, Etex Group NV, Cembrit, and Saint-Gobain.
- Regional producers: Mahaphant Fibre Cement Co., Ltd., Elementia S.A.B. de C.V., Everest Industries, Hume Cemboard Industries, and Nichiha Corporation.
Competitive Benchmarking: Fiber Cement Board Market
Table 8: Competitive Benchmarking for the Fiber Cement Board Market (qualitative documentation ratings), 2026
| Company | Siding Focus | Regional Reach | Capacity Moves | Results Disclosure |
|---|---|---|---|---|
| James Hardie Industries | High | High | Medium | High |
| Etex Group | Medium | High | High | High |
| Saint-Gobain | Low | High | High | High |
| Everest Industries | Low | Medium | Low | Medium |
| Nichiha Corporation | High | Medium | Low | Medium |
A rating of High, Medium or Low tracks the dated company releases behind each item.
Key Developments in the Fiber Cement Board Market
- In September 2026, Etex reported first-half Fibre Cement revenue of EUR 286 million.[2]
- In September 2026, China reported a 25.4% fall in residential floor space newly started for January to August.[7]
- In September 2026, the Census Bureau put August single-family completions at 816,000 on an annual basis.[5]
- In August 2026, Saint-Gobain announced a fourth plasterboard line at the Bahia plant in Brazil.[4]
- In August 2026, James Hardie posted quarterly net sales of $1,474.6 million, 64% higher than a year earlier.[1]
- In August 2026, India reported over 1.25 crore houses sanctioned under PMAY-Urban.[8]
- In July 2026, Saint-Gobain reported 7% organic growth in Asia-Pacific for the first half.[3]
- In July 2026, VDIV reported a 10.8% rise in German dwelling permits for 2025.[6]
Key Players in the Fiber Cement Board Market
Tier 1 Groups
- James Hardie Industries PLC
- Etex Group NV
- Cembrit
- Saint-Gobain
Regional Producers
- Mahaphant Fibre Cement Co., Ltd.
- Elementia, S.A.B. de C.V.
- Everest Industries
- Hume Cemboard Industries
- Nichiha Corporation
Fiber Cement Board Market - Report Scope
Table 9: Report Scope for the Fiber Cement Board Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; application; thickness; region |
| Quantitative units | USD billion |
| Market definition | Fiber cement board market covering siding, flooring, roofing, ceiling, partition, decorative and insulation boards for residential, commercial, industrial and agricultural buildings. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | Brazil; Germany; India; China; USA |
| Key companies profiled | James Hardie Industries PLC, Etex Group NV, Cembrit, Mahaphant Fibre Cement Co., Ltd., Elementia S.A.B. de C.V., Everest Industries, Saint-Gobain, Hume Cemboard Industries, Nichiha Corporation |
| Forecast period | 2026 to 2036 |
Fiber Cement Board Market - Research Methodology
Table 10: Research Methodology for the Fiber Cement Board Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Building material company results, housing statistics, government housing programs and trade association data dated May 2025 or later. |
| Desk Research | Desk work covers siding volumes, plant investments, housing starts and completions, and housing programs. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base of USD 11.9 billion and the 4.6% CAGR. |
| Data Validation | Company results were matched to the quarter or half-year in each release. |
Fiber Cement Board Market by Segments
Fiber Cement Board Market segmented by Product Type:
- Siding Boards
- Flooring Boards
- Roofing Boards
- Ceiling Boards
- Partition Boards
- Decorative Boards
- Insulation Boards
Fiber Cement Board Market segmented by Application:
- Residential Construction
- Commercial Construction
- Industrial Construction
- Agricultural Buildings
- Interior Applications
- Walls
- Ceilings
- Partitions
- Exterior Applications
Fiber Cement Board Market segmented by Thickness:
- Below 6 mm
- 6 mm to 12 mm
- Above 12 mm
Fiber Cement Board Market by Region
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] James Hardie Industries plc. (2026, August 6). Earnings Release, First Quarter Fiscal Year 2027. https://s21.q4cdn.com/242028226/files/doc_earnings/2027/q1/earnings-result/PR-Q127.pdf
- [2] Etex. (2026, September 1). Etex delivers strong first-half performance in volatile market. https://www.etexgroup.com/en/news/3450619/
- [3] Saint-Gobain. (2026, July 30). First-Half 2026 Results. https://www.saint-gobain.com/sites/saint-gobain.com/files/media/document/CP_S1_2026_VA_t.pdf
- [4] Saint-Gobain. (2026, August 24). Saint-Gobain strengthens its positioning in construction chemicals and light construction in Latin America. https://www.saint-gobain.com/sites/saint-gobain.com/files/media/document/20260824_Construction_Chemicals_Light_Construction_Latam_VA.pdf
- [5] U.S. Census Bureau. (2026, September 17). Monthly New Residential Construction, August 2026. https://www.census.gov/construction/nrc/current/index.html
- [6] VDIV Deutschland. (2026, July 21). Baufertigstellungen brechen weiter ein - Genehmigungen ziehen an. https://vdiv.de/news-details/baufertigstellungen-brechen-weiter-ein-genehmigungen-ziehen-an
- [7] National Bureau of Statistics of China. (2026, September 16). Investment in Real Estate Development from January to August 2026. https://www.stats.gov.cn/english/PressRelease/202609/t20260916_1965342.html
- [8] News On AIR. (2026, August 9). Over 1.25 Crore Houses Sanctioned Under PMAY-Urban So Far: Govt. https://newsonair.gov.in/over-1-25-crore-houses-sanctioned-under-pmay-urban-so-far-govt/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will fiber cement board sales total in 2026 and 2036?
- What CAGR will board sales record from 2026 to 2036?
- Which product type will hold the largest share?
- Will residential construction stay the top application?
- Which countries will grow fastest?
- Which suppliers will shape competition through 2036?
Frequently Asked Questions
What is the size of the fiber cement board market in 2026?
In 2026, board sales will reach an estimated USD 12.4 billion, and FMI sees USD 19.5 billion by 2036.
What will drive fiber cement board growth?
Demand for boards will rise through 2036 on PMAY-Urban housing in India, light construction in Brazil and green-certified projects.
Which product type will lead in 2026?
Siding boards will keep 39.1% of product type sales, with roofing boards next at an estimated 14.6%. Will residential construction stay the top application? Yes. Homebuilders take 35.6% in 2026, and commercial construction comes next near an estimated 21.4%.
Which country will post the fastest growth?
Brazil will post the quickest growth among profiled countries, a 5.7% CAGR from 2026 to 2036, as FMI projects.
Which companies will matter most in this market?
James Hardie, Etex, Cembrit and Saint-Gobain will lead the Tier 1 group, and Mahaphant, Elementia and Everest Industries will compete regionally.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Siding Boards
- Flooring Boards
- Roofing Boards
- Ceiling Boards
- Partition Boards
- Decorative Boards
- Insulation Boards
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Residential Construction
- Commercial Construction
- Industrial Construction
- Agricultural Buildings
- Interior Applications
- Walls
- Ceilings
- Partitions
- Exterior Applications
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Thickness, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Thickness, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Thickness, 2026 to 2036
- Below 6 mm
- 6 mm to 12 mm
- Above 12 mm
- Y-o-Y Growth Trend Analysis By Thickness, 2021 to 2025
- Absolute $ Opportunity Analysis By Thickness, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product Type
- By Application
- By Thickness
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Application
- By Thickness
- Key Takeaways
- Key Countries Market Analysis
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Application
- By Thickness
- Brazil
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Application
- By Thickness
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- James Hardie Industries
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Etex Group
- Saint-Gobain
- Everest Industries
- Nichiha Corporation
- James Hardie Industries PLC
- Etex Group NV
- Cembrit
- Mahaphant Fibre Cement Co., Ltd.
- Elementia, S.A.B. de C.V.
- Hume Cemboard Industries
- James Hardie Industries
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


