
- Market Size (2026)
- USD 5.6 Bn
- Forecast (2036)
- USD 11.1 Bn
- CAGR (2026 to 2036)
- 7.1%
How big is Ginger Beer Market in 2026?
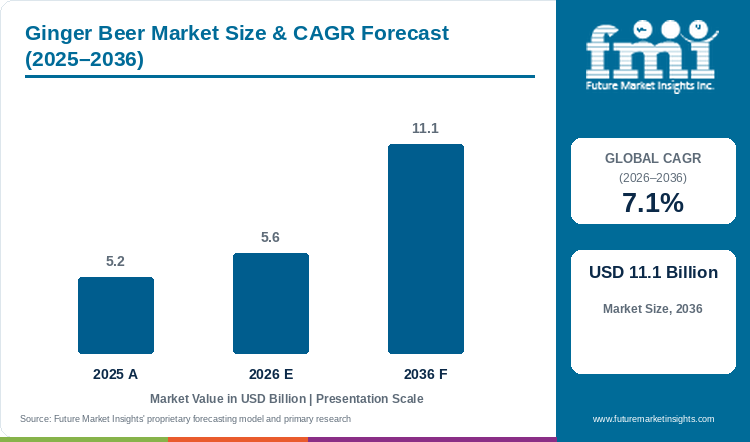
Starting from USD 5.2 billion in 2025, the ginger beer market valuation advanced to USD 5.6 billion in 2026, with projections pointing toward USD 11.1 billion by 2036 at a CAGR of 7.1%.
Table 1: Market Size and Forecast for the Ginger Beer Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 5.2 billion |
| Estimated Market Size in 2026 | USD 5.6 billion |
| Projected Market Size by 2036 | USD 11.1 billion |
| CAGR, 2026 to 2036 | 7.1% |
| Added Revenue, 2026 to 2036 | USD 5.5 billion |
The global ginger beer market was valued at USD 5.2 billion in 2025 and is estimated to reach USD 5.6 billion in 2026. The market valuation is projected to reach USD 11.1 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.1% between 2026 and 2036. FMI survey reflects that Non-Alcoholic Brewed Ginger Beer captures an estimated 74.5% share of 2026 product type demand, since hospitality bars and household shoppers use the same fiery root brew for Moscow Mules and standalone zero-proof sipping. Category demand is accelerating through occasion expansion, where fermented ginger root pungency gives abstaining adults a complex bite that standard sugary sodas lack. Public health data from the UK Department of Health and Social Care in November 2025 confirmed that soft drinks subject to sugar-levy reformulation recorded a 13.5% rise in volume sales between 2015 and 2024 as shoppers embraced lower-sugar adult beverages. That dual mixer-and-mocktail utility separates ginger beer from the slower carbonated ginger ale category at 3.6% CAGR, given that brewed rhizome solids command premium craft pricing over clear flavor-essence sodas. Beverage groups are locking in national distribution to convert that demand, evidenced when Molson Coors Beverage Company signed an exclusive U.S. partnership with Fever-Tree in January 2025 to scale onshore production and grocery delivery. Supermarket category buyers and bar operators renew ginger beer contracts on natural gingerol heat stability and sugar-tax compliance through 2036.
Key Market Trends & Insights
- By product type: Non-Alcoholic Brewed Ginger Beer holds an estimated 74.5% share in 2026 since zero-ABV root brews bridge family grocery aisles and on-premise cocktail bars.
- By flavor formulation: Original Traditional Fiery Ginger represents an expected 68.0% share in 2026 driven by bartender demand for authentic 6-gingerol spice against vodka, rum, and bourbon.
- By packaging format: Glass Bottles account for a projected 52.5% in 2026 supported by high dissolved-CO2 retention and crown-capped craft table presentation.
- By distribution channel: Supermarkets and Hypermarkets secure an anticipated 44.0% in 2026 owing to dedicated cocktail mixer endcaps and chilled multipack promotions.
- By price tier: Mainstream and Mass-Market Brands command an estimated 54.0% in 2026 through high-speed inline carbonation and nationwide direct-store-delivery truck reach.
Regional Highlights
- Top national expansion: Brazil leads national growth projections at an 8.3% CAGR through 2036 under rapid food-processing expansion and tropical fruit-ginger soda adoption.
- Broader country progression: Mexico tracks at an 8.1% CAGR ahead of the United States at 7.4% and the United Kingdom at 7.1%, while Japan advances at a 6.3% CAGR.
Market Size & Forecast
Commercial beverage formulators confront consumer rejection of artificial capsaicin heat and high-fructose corn syrup as shoppers scrutinize ingredient labels for authentic botanical fermentation. When bottlers substitute real Zingiber officinale rhizome extracts with synthetic flavoring, the drink loses the lingering palate warmth and digestive positioning that justify a craft price premium. An umbrella review indexed in PubMed in May 2026 demonstrated that clinical ginger supplementation significantly improves glycemic, lipid, and antioxidant markers across adult cohorts . Consequently, beverage R&D teams pair cold-pressed rhizome juice with steam-distilled ginger oil to standardize natural pungency and cloudy visual authenticity across high-speed bottling lines.
Brewed Liter Volume and Rhizome Input Sizing
Table 2: Brewed Liter Volume and Rhizome Input Sizing for the Ginger Beer Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 5.2 | 5.6 | 11.1 |
| Commercial brewed & carbonated volume (billion liters) | 1.72 to 1.88 | 1.85 to 2.02 | 3.45 to 3.78 |
| Dried & fresh ginger rhizome input (thousand MT) | 68.0 to 75.0 | 73.5 to 81.0 | 142.0 to 156.0 |
| Average wholesale price per liter (USD) | 2.76 to 3.02 | 2.78 to 3.05 | 2.94 to 3.22 |
Operational note: Rhizome input ranges reflect traditional 3-day to 7-day botanical steeping and yeast-lactobacilli fermentation using split dried or fresh crushed ginger root.
Botanical fermentation alters the ratio of non-volatile 6-gingerol to dehydrated 6-shogaol, which directly governs the perceived throat heat and shelf stability of finished ginger beer. Chromatographic research published in the International Journal of Molecular Sciences in March 2025 verified that controlled fermentation of Zingiber officinale modifies 6-gingerol and 6-shogaol concentrations while enhancing bioactive stability . Craft brewers scaling prebiotic sodas and fermented ginger beers monitor pH drop and organic acid profiles during tank steeping so bottled batches maintain consistent spice intensity without secondary yeast refermentation in grocery channels.
Urban Consumer & Sugar-Levy Channel Sizing
Table 3: Urban Consumer and Reformulation Indicators for the Ginger Beer Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global urban beverage consumer base (billion) | 4.6 | 4.7 | 5.3 |
| Annual ginger beer spend per 1,000 urban consumers (USD) | 1,130.4 | 1,191.5 | 2,094.3 |
| Low-sugar & levy-exempt formulation share (%) | 34.0% to 38.0% | 37.0% to 41.0% | 54.0% to 59.0% |
| Hospitality cocktail & mocktail mixer share (%) | 39.0% to 43.0% | 40.5% to 44.5% | 45.0% to 49.0% |
Table 4: Retail Beverage & Channel Spending Indicators for the Ginger Beer Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 5.6 billion | 2026 global valuation baseline |
| UK reformulated soft drink volume growth (2015-2024) | 13.5% volume rise | UK Department of Health and Social Care SDIL audit |
| Active 6-gingerol & shogaol pungency dosing range | 150 to 450 mg/L | Chromatographic fermented ginger beverage benchmarks |
| Supermarkets and Hypermarkets channel revenue, 2026 | USD 2.5 billion | 44.0% distribution channel allocation |
Household expenditure on premium non-alcoholic mixers and botanical soft drinks remains resilient as consumers shift high-margin cocktail occasions from nightclubs to home entertaining. Retail market analysis published by the USDA Foreign Agricultural Service in October 2026 documented that the United Kingdom retail grocery sector reached USD 343 billion in 2026 and is forecast to reach USD 404 billion by 2031, with strong demand for low-sugar and premium functional beverages . Producers of artisanal craft sodas and brewed ginger beers package four-pack glass bottles and sleek eight-pack aluminum cans to capture weekly supermarket basket spend while keeping per-serve costs far below bar menu prices.
Analyst Perspective
"Beverage buyers do not stock ginger beer to duplicate sweet ginger ale; they buy unmistakable gingerol root heat that stands up to dark rum, vodka, or lime juice in a zero-proof mule. Brewers that keep natural rhizome cloudiness while formulating below national sugar-tax thresholds will win both supermarket cold vaults and hospitality bar guns through 2036."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the ginger beer market segmented?
The ginger beer market is segmented by product type, flavor formulation, packaging format, distribution channel, and price tier. In 2026, Non-Alcoholic Brewed Ginger Beer is projected at 74.5%, Original Traditional Fiery Ginger at 68.0%, Glass Bottles at 52.5%, Supermarkets and Hypermarkets at 44.0%, and Mainstream and Mass-Market Brands at 54.0%.
By product type: Non-Alcoholic Brewed Ginger Beer, Alcoholic and Hard Fermented Ginger Beer, Prebiotic and Functional Ginger Beer, and Zero-Proof Botanical Cocktail Mixers.
By flavor formulation: Original Traditional Fiery Ginger, Fruit-Infused Mango and Passionfruit Blends, Spiced Citrus and Yuzu Formulations, and Low-Sugar and Diet Stevia Formulations.
By packaging format: Glass Bottles, Metal Beverage Cans, Polyethylene Terephthalate PET Bottles, Hospitality Post-Mix and Draught Kegs, and Multi-Pack Retail Cartons.
By distribution channel: Supermarkets and Hypermarkets, On-Premise Bars and Cocktail Lounges, Convenience Stores and Corner Grocers, and E-Commerce and Subscription Platforms.
By price tier: Mainstream and Mass-Market Brands, Premium Craft and Botanically Brewed, Super-Premium Hospitality Mixers, and Private-Label Supermarket Lines.
Why does Non-Alcoholic Brewed Ginger Beer lead the product type category?
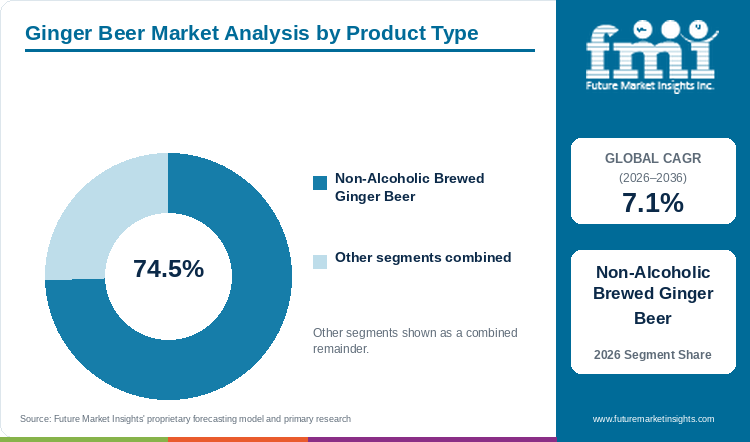
Non-Alcoholic Brewed Ginger Beer holds an estimated 74.5% of product type demand in 2026, anchored by dual consumption as a standalone adult soft drink and a spicy spirit mixer.
Table 5: Product Type Share for the Ginger Beer Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Non-Alcoholic Brewed Ginger Beer | 74.5% |
| Other Segments Combined | 25.5%* |
| Total | 100.0% |
*Note: Remaining product type categories account for the balance of 2026 global ginger beer market demand.
Table 6: Product Type Leadership and Market Growth for the Ginger Beer Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.1% |
| Leading Segment | Non-Alcoholic Brewed Ginger Beer |
Non-Alcoholic Brewed Ginger Beer fermented to remain below the statutory 0.5% alcohol-by-volume threshold avoids liquor licensing restrictions, age-gated retail aisles, and spirits excise duties. This regulatory freedom allows brand owners to merchandise the exact same spicy brew in family supermarket soft-drink aisles, workplace cafeterias, and licensed cocktail bars next to fermented kombucha drinks. Brewers must still pasteurize or micro-filter bottled batches carefully so residual yeast does not generate excess alcohol or bottle over-pressurization during warm warehouse transit.
- Within the product type segment, Non-Alcoholic Brewed Ginger Beer is projected to account for a leading 74.5% share in 2026, driven by unrestricted grocery distribution and dual mocktail-and-mixer versatility.
- Experimental fermentation research published in MDPI Fermentation in March 2025 demonstrated how controlled red ginger consortium fermentation preserves volatile aromatics while stabilizing organic acid and ethanol ceilings.
What sustains Original Traditional Fiery Ginger leadership in the flavor formulation segment?
Original Traditional Fiery Ginger represents an expected 68.0% of the flavor formulation category in 2026, supported by authentic 6-gingerol throat bite required in Moscow Mule and Dark 'n' Stormy serves.
Original Traditional Fiery Ginger formulations rely on multi-origin ginger root extracts to deliver an immediate peppery attack and clean citrus finish without competing fruit esters. Bartenders pouring copper-mug Moscow Mules and Dark 'n' Stormy highballs require an unflavored fiery base that does not clash with aged rum or bourbon next to ready-to-drink botanical teas. Regulatory preliminary results filed by Fevertree Drinks plc in March 2026 confirmed that Adjusted Fever-Tree brand revenue rose 4% at constant currency in FY25, with 45% of group revenue now generated from non-tonic mixers led by Ginger Beer.
- In 2026, Original Traditional Fiery Ginger is anticipated to capture 68.0% of global flavor formulation demand, reflecting universal cocktail recipe compatibility and repeat household purchasing.
- While tropical mango and passionfruit variants attract younger trial shoppers in summer convenience channels, classic fiery ginger retains the highest year-round velocity per supermarket SKU.
How do Glass Bottles lead the packaging format category?
Glass Bottles account for a projected 52.5% of packaging format demand in 2026, driven by high carbonation retention and crown-capped craft presentation across bars and grocery multipacks.
Heavy flint and amber crown-capped glass bottles prevent carbon dioxide permeation and protect oxygen-sensitive ginger essential oils from light-induced off-flavors across twelve-month ambient shelf lives. Across upscale bars and hotel lounges, serving a chilled 200-milliliter or 275-milliliter embossed glass bottle with a spirit glass justifies premium single-serve pricing compared with fountain gun dispensing or recyclable PET beverage bottles. Elevated glass furnace energy costs and heavy interstate trucking weights nevertheless push brewers to add sleek aluminum cans for outdoor and multipack grocery occasions.
- By packaging format, Glass Bottles are estimated to reach 52.5% of total category share in 2026 as hospitality table service and craft four-pack carriers prioritize visual authenticity.
- Technical brewing documentation published by Fentimans Ltd. in September 2025 confirmed how traditional botanical brewing and single-serve glass bottling preserve carbonation bite for premium cocktail pairings.
Why do Supermarkets and Hypermarkets lead the distribution channel category?
Supermarkets and Hypermarkets secure an anticipated 44.0% of distribution channel share in 2026, supported by dedicated craft mixer endcaps and chilled four-pack or six-pack household stocking.
Supermarkets and Hypermarkets allocate dedicated mixer bays adjacent to beer and spirits aisles as well as chilled grab-and-go coolers near checkout lanes to capture planned party stocking and impulse purchases. Retail category managers run joint promotional endcaps that pair ginger beer four-packs with vodka or dark rum bottles during holiday and summer grilling seasons. In September 2025, a USDA Foreign Agricultural Service soft drinks market report documented that supermarkets and convenience stores drive steady packaged carbonated drink growth as consumers seek added-nutrient and low-calorie options.
- Supermarkets and Hypermarkets are predicted to secure 44.0% of distribution channel demand in 2026, supported by multi-pack price promotions and integrated liquor-aisle cross-merchandising.
- Independent craft ginger beer brands must still pay slotting allowances and maintain high case-fill rates to defend eye-level supermarket shelf facings against multinational beverage bottlers.
What gives Mainstream and Mass-Market Brands the leading position in price tier?
Mainstream and Mass-Market Brands command an estimated 54.0% of price tier share in 2026, anchored by high-speed inline bottling and direct-store-delivery grocery truck networks.
Mainstream and Mass-Market Brands leverage high-speed rotary canning and bottling lines, bulk ginger oleoresin procurement, and nationwide direct-store-delivery truck fleets to hit everyday grocery price points. Accessible six-pack and twelve-pack pricing allows middle-income households to stock ginger beer as a daily refrigerator staple rather than reserving it strictly for special-occasion cocktails.
- With a projected 54.0% share of the price tier segment in 2026, Mainstream and Mass-Market Brands anchor high-volume retail and convenience store turnover.
- In May 2026, Keurig Dr Pepper Inc. released its 2026 State of Beverages Trend Report showing that 71% of Gen Z consumers seek function-forward beverages and 64% prioritize bold flavor profiles.
What are the drivers, restraints, and opportunities in the ginger beer market?
In the ginger beer market, zero-proof adult social occasions and cocktail mixer premiumization are projected to drive adoption, whereas sugar-tax reformulation thresholds and ginger rhizome price swings restrain margins and prebiotic or yuzu-infused variants create new demand avenues.
- Driver: Rising adult moderation habits and global popularity of mule and highball cocktails expand demand for fiery brewed ginger beer across bars and supermarkets.
- Restraint: National sugar-sweetened beverage excise taxes and weather-driven swings in dried ginger rhizome prices pressure bottler formulation costs.
- Opportunity: Formulating low-sugar stevia or prebiotic fiber ginger beers unlocks sugar-levy exemptions and daytime functional refreshment occasions.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Adult beverage consumers reducing weekly alcohol consumption are rejecting flat water and overly sweet colas in favor of non-alcoholic drinks that deliver adult sensory complexity and throat warmth. Brewed ginger beer satisfies this demand through natural 6-gingerol, 8-gingerol, and zingerone compounds that replicate the palate bite of distilled spirits without intoxicating effects, outperforming conventional powdered soft drinks in hospitality and social settings. In November 2026, analytical mass-spectrometry research indexed in PubMed characterized 27 chemical constituents across Zingiber officinale origins and quantified 6-gingerol and 8-gingerol markers that govern sensory heat and quality authentication. Hospitality operators consequently feature dedicated zero-proof ginger mule sections on bar menus that generate full cocktail gross margins.
Risk Assessment of the Ginger Beer Market: Operational and Formulation Friction
Traditional brewed ginger beer recipes require 9 to 11 grams of cane sugar per 100 milliliters to balance intense ginger root sharpness and feed yeast fermentation, placing unreformulated brands directly into the highest sugar-tax brackets. When governments expand per-liter sugar levies, bottlers face either steep retail price increases or complex sweetener reformulation that risks leaving a metallic aftertaste unless balanced with stevia leaf sweeteners. Tax impact documentation published by HM Revenue & Customs in October 2026 confirmed that the UK Soft Drinks Industry Levy sugar threshold will drop from 5.0 grams to 4.5 grams per 100 milliliters from January 2028. At the same time, monsoon variability across Indian and Nigerian ginger-growing regions creates raw rhizome cost spikes for independent craft brewers.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Beverage formulators are engineering next-generation ginger beers that combine cold-pressed ginger root juice with soluble chicory inulin fiber, botanical adaptogens, and natural high-intensity sweeteners to hold total sugars below 4.5 grams per 100 milliliters. These functional low-sugar variants qualify for exemption from sugar-sweetened beverage taxes while capturing health-conscious grocery shoppers seeking digestive and metabolic wellness benefits. A GRADE-assessed meta-analysis of 12 randomized controlled trials indexed in PubMed in November 2026 confirmed that ginger interventions significantly reduced body mass index and body fat percentage across 692 adult participants. Distribution of these low-calorie functional brews in slim 250-milliliter aluminum containers opens incremental accounts across fitness studios, natural grocers, and workplace micro-markets.
Ginger Beer Market by Country (2026 to 2036)
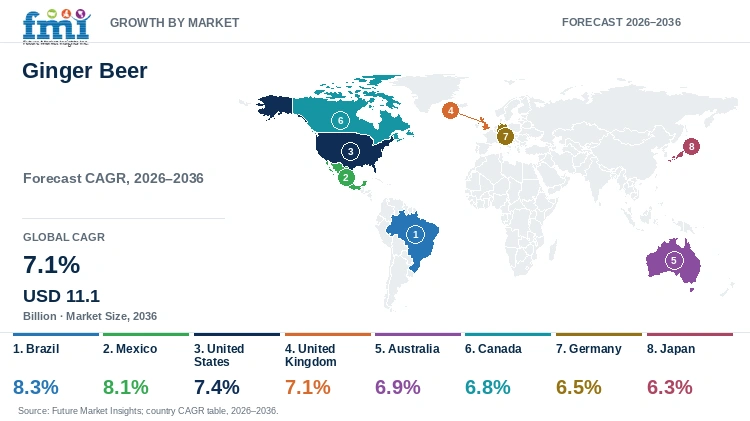
FMI country modeling indicates that Brazil leads ginger beer market expansion at an 8.3% CAGR through 2036, while Mexico advances at an 8.1% CAGR and the United States records a 7.4% CAGR. National growth trajectories depend on warm-weather cocktail culture, domestic cane-sugar and sweetener economics, and supermarket cold-vault expansion.
Table 7: Country CAGR and Primary Growth Levers for the Ginger Beer Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 8.3% | USD 248B food processing sector expansion and tropical craft mixer adoption |
| Mexico | 8.1% | Tequila and mezcal paloma-mule cocktail pairing and modern supermarket growth |
| United States | 7.4% | Entrenched Moscow Mule bar culture and national DSD can and bottle distribution |
| United Kingdom | 7.1% | Botanical brewing heritage and Soft Drinks Industry Levy low-sugar reformulation |
| Australia | 6.9% | Multi-day fermented ginger root brewing tradition and high per-capita consumption |
| Canada | 6.8% | Grocery craft mixer aisle expansion and zero-proof adult social refreshment |
| Germany | 6.5% | Munich Mule hospitality bar popularity and returnable glass bottle retail systems |
| Japan | 6.3% | Domestic spicy dry ginger highball innovation and premium hotel bar mixology |
Source: Future Market Insights analysis
Brazil Ginger Beer Market Outlook (2026 to 2036)
Demand for ginger beer in Brazil is projected to expand at a leading 8.3% CAGR between 2026 and 2036 as urban hospitality bars and cash-and-carry atacarejo supermarkets scale premium cocktail mixers and spiced tropical soft drinks. Domestic commercial demand is driven by the widespread local popularity of the Moscow Mule topped with ginger foam across São Paulo and Rio de Janeiro bar districts. Brazil food processing data released by USDA FAS Brasilia attachés in March 2026 showed that sector revenue grew 8% in 2025 as processors expanded value-added beverage output. High interstate logistics taxes still compel international mixer brands to partner with local Brazilian bottlers rather than relying on imported glass cases.
Key takeaway: In Brazil, active urban mule cocktail culture and expanding domestic beverage processing are projected to drive a leading 8.3% CAGR.
Mexico Ginger Beer Market Outlook (2026 to 2036)
In Mexico, ginger beer adoption is anticipated to advance at an 8.1% CAGR from 2026 to 2036, fueled by resort hotel mixology and tequila-ginger or mezcal-mule cocktail serves across tourist and metropolitan hubs. Mexican bartenders blend spicy brewed ginger beer with blanco tequila and fresh lime or mango infusions. Trade analysis published by U.S. agricultural attachés in Mexico in July 2026 documented rapid modernization across Mexico's convenience store, supermarket, and hospitality foodservice supply chains. Front-of-pack octagonal excess-sugar warning labels in Mexico push domestic and imported bottlers to accelerate low-sugar stevia-blend ginger beer formulations.
Key takeaway: In Mexico, agave-ginger cocktail pairings and front-of-pack calorie reformulation are anticipated to sustain an 8.1% CAGR through 2036.
United States Ginger Beer Market Outlook (2026 to 2036)
Sales of ginger beer in the United States are expected to climb at a 7.4% CAGR over the 2026 to 2036 forecast period across national grocery chains, club stores, and on-premise bar accounts. The United States represents the largest single-country volume pool globally since the Moscow Mule and Kentucky Buck are standard menu staples in casual dining and neighborhood bars nationwide. Corporate financial disclosures from Keurig Dr Pepper Inc. in February 2026 confirmed resilient North American refreshment beverage demand supported by direct-store-delivery distribution investments. Independent craft ginger brewers counter long-haul refrigerated freight costs by transitioning from heavy glass bottles to sleek 12-ounce aluminum can multipacks.
Key takeaway: In the United States, nationwide direct-store-delivery partnerships and aluminum can multipacks are expected to support a 7.4% CAGR.
United Kingdom Ginger Beer Market Outlook (2026 to 2036)
Projected to expand at a 7.1% CAGR between 2026 and 2036, the United Kingdom ginger beer market builds on a two-century heritage of traditional botanical brewing and pub mixer service. British shoppers purchase both fiery non-alcoholic botanical brews and 4.0% ABV alcoholic ginger beers across supermarkets and pubs. Policy paper documentation released by HM Treasury and HM Revenue & Customs in July 2026 detailed updated Soft Drinks Industry Levy consultation stages designed to incentivize continued sugar reduction across pre-packaged beverages. British brewers consequently lead global innovation in half-sugar and Refreshingly Light ginger beer formulations that avoid the levy without losing root heat.
Key takeaway: In the United Kingdom, botanical brewing heritage and sugar-levy-exempt light formulations are projected to maintain a 7.1% CAGR.
Australia Ginger Beer Market Outlook (2026 to 2036)
Consumption of ginger beer in Australia is forecast to progress at a 6.9% CAGR from 2026 to 2036, anchored by some of the highest per-capita non-alcoholic and hard ginger beer drinking rates in the world. What sets Australia apart from Northern Hemisphere markets is the entrenched status of cloudy, multi-day fermented Queensland ginger beer as an everyday daytime cold-vault beverage next to cola. Beverage manufacturing analysis published by the USDA Foreign Agricultural Service in March 2026 noted that Australian food and beverage processors prioritize domestic cane sugar and natural ginger rhizome extracts in premium craft soda production . Australian brewers are also rapidly scaling 3.5% to 4.5% ABV hard alcoholic ginger beer on draught taps in coastal pubs and sports stadiums.
Key takeaway: In Australia, domestic Queensland ginger brewing traditions and surging draught hard ginger beer demand are forecast to drive a 6.9% CAGR.
Canada Ginger Beer Market Outlook (2026 to 2036)
Ginger beer demand in Canada is estimated to grow at a 6.8% CAGR across the 2026 to 2036 horizon as grocery chains and provincial liquor stores expand zero-proof mocktail and craft mixer sections. Canadian households steadily stock spicy brewed ginger beer for alcohol-free social hosting and rye-whisky highballs. Annual food processing analysis published by the USDA Foreign Agricultural Service in August 2026 confirmed that Health Canada's front-of-package nutrition labeling rules effective January 1, 2026 are accelerating low-sugar beverage reformulation across Canada's largest manufacturing sector. Bilingual packaging mandates and long trans-continental rail distribution distances encourage international brands to utilize regional Canadian co-packers.
Key takeaway: In Canada, supermarket zero-proof mixer bays and rye-ginger cocktail popularity are estimated to support a 6.8% CAGR.
Germany Ginger Beer Market Outlook (2026 to 2036)
In Germany, ginger beer sales are predicted to advance at a 6.5% CAGR between 2026 and 2036, driven by widespread hospitality adoption of the cucumber-garnished Munich Mule and Berlin highball culture. German beverage distribution operates through its mandatory Pfand deposit-return system and consumer preference for returnable glass crates in specialty Getrankemarkt beverage stores. Retail export documentation from the U.S. agricultural mission in Germany in July 2026 confirmed that beverage suppliers entering German retail must comply with strict packaging deposit and sustainability standard. Domestic and imported ginger beer brands that offer 200-milliliter returnable glass bottles and organic bio-certified recipes capture strong urban listings.
Key takeaway: In Germany, Munich Mule bar demand and returnable Pfand glass bottle distribution are predicted to underpin a 6.5% CAGR.
Japan Ginger Beer Market Outlook (2026 to 2036)
Japanese ginger beer market valuation is slated to expand at a 6.3% CAGR through 2036 across upscale Tokyo and Osaka cocktail bars, department store food halls, and specialty convenience chains. Japan diverges from sweet Western soda profiles through its traditional appreciation for pungent domestic Kochi ginger and dry, spicy Karaguchi ginger highballs infused with yuzu or sansho pepper. Annual food ingredient reporting from Tokyo agricultural attachés in April 2026 confirmed that soft drinks and functional beverages remained a bright growth spot within Japan's food processing industry. Local beverage formulators focus on compact 200-milliliter glass bottles and low-calorie spicy formulations tailored to adult evening refreshment.
Key takeaway: In Japan, dry Karaguchi Kochi-ginger formulations and upscale highball bar service are slated to sustain a 6.3% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the ginger beer market?
Fever-Tree Drinks plc, Bundaberg Brewed Drinks Pty Ltd, Fentimans Ltd., Maine Root Handcrafted Beverages LLC, Keurig Dr Pepper Inc., The Coca-Cola Company, Molson Coors Beverage Company, Reed's Inc., Brookfield Drinks Ltd., and Old Jamaica Beverage Company are the notable companies in the ginger beer market.
Global ginger beer competition spans botanical craft brewers, multinational direct-store-delivery bottlers, and regional alcoholic ginger beer specialists, led by Fever-Tree Drinks plc, Bundaberg Brewed Drinks Pty Ltd, Fentimans Ltd., Maine Root Handcrafted Beverages LLC, Keurig Dr Pepper Inc., The Coca-Cola Company, Molson Coors Beverage Company, Reed's Inc., Brookfield Drinks Ltd., and Old Jamaica Beverage Company.
- Dedicated Botanical and Craft Ginger Brewers: Fever-Tree Drinks plc, Bundaberg Brewed Drinks Pty Ltd, Fentimans Ltd., and Maine Root Handcrafted Beverages LLC specialize in multi-day ginger root brewing and botanical fermentation.
- Multinational Soft Drink and DSD Mixer Groups: Keurig Dr Pepper Inc., The Coca-Cola Company, Molson Coors Beverage Company, and Reed's Inc. operate high-speed canning lines and national grocery delivery networks.
- Alcoholic and Heritage Regional Specialists: Brookfield Drinks Ltd. (owner of Crabbie's Alcoholic Ginger Beer) and Old Jamaica Beverage Company supply steeped alcoholic ginger beer and fiery Jamaican-style sodas.
Competitive Benchmarking: Ginger Beer Market
Table 8: Competitive Benchmarking for the Ginger Beer Market (qualitative capability ratings), 2026
| Company | Botanical Ginger Brewing | Hospitality & DSD Reach | Low-Sugar Reformulation Fit | Geographic Reach |
|---|---|---|---|---|
| Fever-Tree Drinks plc | High | High | High | 85+ countries; U.S. distribution scaled via Molson Coors partnership |
| Bundaberg Brewed Drinks Pty Ltd | High | High | High | Australia, U.S., UK, and 60+ export markets; family-owned craft brewer |
| Fentimans Ltd. | High | High | Medium | UK, Europe, and North America; botanically brewed 7-day ginger process |
| Maine Root Handcrafted Beverages LLC | High | Medium | Medium | U.S. natural grocery and restaurant chains; organic fair-trade cane sugar |
| Keurig Dr Pepper Inc. | Medium | High | High | North America DSD powerhouse; beverage trend leader and mixer distributor |
| The Coca-Cola Company | Medium | High | High | 200+ countries; Schweppes Ginger Beer and reduced-sugar bar mixers |
| Molson Coors Beverage Company | High | High | High | North America and Europe; exclusive U.S. Fever-Tree commercialization |
| Reed's Inc. | High | Medium | High | U.S. natural and mainstream supermarkets; fresh ginger root zero-sugar lines |
| Brookfield Drinks Ltd. | High | High | Medium | UK and international export markets; acquired Crabbie's Alcoholic Ginger Beer |
| Old Jamaica Beverage Company | Medium | High | High | UK, Caribbean, and European ethnic and mainstream convenience retail |
Evaluation basis: Botanical Ginger Brewing evaluates authentic multi-day rhizome fermentation or multi-origin ginger root extraction, while Hospitality & DSD Reach rates bar placement and direct-store-delivery grocery truck access. Low-Sugar Reformulation Fit measures documented capability to deliver <5g/100ml sugar-levy-exempt or zero-sugar recipes while preserving natural gingerol bite.
Key Developments in the Ginger Beer Market
- Molson Coors Beverage Company released its 2026 Third Quarter financial results on November 5, 2026, reporting USD 2,926.5 million in Q3 net sales and USD 272.2 million in underlying net income while scaling its exclusive U.S. Fever-Tree mixer partnership.
- The Coca-Cola Company reported its Third Quarter 2026 financial results on October 27, 2026, delivering 7% net revenue growth to USD 13.4 billion and 5% global unit case volume growth while raising full-year organic revenue guidance.
- Fevertree Drinks plc published its FY26 Interim Results for the six months ended June 30, 2026 on September 9, 2026, maintaining market leadership across every mixer sub-category while advancing its GBP 60 million share buyback program and U.S. Molson Coors transition.
Key Players in the Ginger Beer Market
Dedicated Botanical and Craft Ginger Brewers
- Fever-Tree Drinks plc
- Bundaberg Brewed Drinks Pty Ltd
- Fentimans Ltd.
- Maine Root Handcrafted Beverages LLC
Multinational Soft Drink and DSD Mixer Groups
- Keurig Dr Pepper Inc.
- The Coca-Cola Company
- Molson Coors Beverage Company
- Reed's Inc.
Alcoholic and Heritage Regional Specialists
- Brookfield Drinks Ltd.
- Old Jamaica Beverage Company
Ginger Beer Market - Report Scope
Table 9: Report Scope for the Ginger Beer Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Flavor Formulation; Packaging Format; Distribution Channel; Price Tier |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial brand-owner and bottler revenue from non-alcoholic brewed and carbonated ginger beer soft drinks, alcoholic hard fermented ginger beers, and botanical ginger beer cocktail mixers using real ginger root extracts or fermented rhizome bases. Category Scope Note: Excludes clear flavor-essence ginger ale, uncarbonated ginger shots, and dry powdered ginger spices. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Brazil, Mexico, United States, United Kingdom, Australia, Canada, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | Fever-Tree Drinks plc, Bundaberg Brewed Drinks Pty Ltd, Fentimans Ltd., Maine Root Handcrafted Beverages LLC, Keurig Dr Pepper Inc., The Coca-Cola Company, Molson Coors Beverage Company, Reed's Inc., Brookfield Drinks Ltd., Old Jamaica Beverage Company |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Ginger Beer Market - Research Methodology
Table 10: Research Methodology for the Ginger Beer Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with botanical beverage fermentation technologists, hospitality bar procurement managers, supermarket soft-drink category directors, and ginger oleoresin suppliers to validate liter realizations and sugar-levy compliance. |
| Secondary Research | Analysis of UK Department of Health and Social Care SDIL datasets, HM Revenue & Customs SDIL impact notes, USDA FAS GAIN food processing reports, PubMed and PMC gingerol fermentation studies, and corporate earnings filings. |
| Market Sizing and Forecasting | Top-down global carbonated soft drinks and craft mixer baselines reconciled against bottom-up commercial ginger beer volume (1.85B to 2.02B liters in 2026) and wholesale per-liter pricing from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight spirit-mixer cocktail adoption, sugar-sweetened beverage tax thresholds, direct-store-delivery bottling reach, and zero-proof adult refreshment trends across eight national markets. |
| Operational Benchmark Traceability | Liter volume, ginger rhizome tonnage, and sugar-levy indicators in Tables 2, 3, and 4 trace to UK DHSC volume audits, USDA FAS retail food reports, and PMC chromatographic 6-gingerol assays. |
| Data Triangulation and Validation | Revenue estimates isolate cloudy brewed and root-extracted ginger beers across non-alcoholic and alcoholic formats while strictly excluding clear ginger-flavored ales and medicinal ginger capsules. |
Ginger Beer Market by Segments
Ginger Beer Market segmented by Product Type:
- Non-Alcoholic Brewed Ginger Beer
- Alcoholic and Hard Fermented Ginger Beer
- Prebiotic and Functional Ginger Beer
- Zero-Proof Botanical Cocktail Mixers
Ginger Beer Market segmented by Flavor Formulation:
- Original Traditional Fiery Ginger
- Fruit-Infused Mango and Passionfruit Blends
- Spiced Citrus and Yuzu Formulations
- Low-Sugar and Diet Stevia Formulations
Ginger Beer Market segmented by Packaging Format:
- Glass Bottles
- Metal Beverage Cans
- Polyethylene Terephthalate PET Bottles
- Hospitality Post-Mix and Draught Kegs
- Multi-Pack Retail Cartons
Ginger Beer Market segmented by Distribution Channel:
- Supermarkets and Hypermarkets
- On-Premise Bars and Cocktail Lounges
- Convenience Stores and Corner Grocers
- E-Commerce and Subscription Platforms
Ginger Beer Market segmented by Price Tier:
- Mainstream and Mass-Market Brands
- Premium Craft and Botanically Brewed
- Super-Premium Hospitality Mixers
- Private-Label Supermarket Lines
Ginger Beer Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Fentimans Ltd. (2025, September 15). The Extraordinary History of Fentimans Ginger Beer and the Best Ginger Beer Cocktail Recipes. Fentimans Official Blog.
- Fevertree Drinks plc. (2026, March 23). FY25 Preliminary Results to 31 December 2025. London Stock Exchange RNS / Investegate Company Announcements.
- Fevertree Drinks plc. (2026, September 9). FY26 Interim Results to 30 June 2026. London Stock Exchange RNS / Investegate Company Announcements.
- HM Revenue & Customs. (2026, October 28). Soft Drink Industry Levy changes. GOV.UK Tax Information and Impact Notes.
- HM Treasury and HM Revenue & Customs. (2026, July 13). Changes to the Soft Drinks Industry Levy - policy paper. GOV.UK Official Publications.
- Keurig Dr Pepper Inc. (2026, February 24). Keurig Dr Pepper Reports Q4 and Full Year 2025 Results and Provides 2026 Outlook. Keurig Dr Pepper Investor Relations.
- Keurig Dr Pepper Inc. (2026, May 6). Keurig Dr Pepper's 2026 State of Beverages Trend Report Reveals Gen Z's Drink Choice Is Now a Form of Self-Expression. Keurig Dr Pepper Corporate Newsroom.
- MDPI Fermentation Open Access. (2025, March 6). Scaling Up Red Ginger Kombucha Fermentation: Insights into Its Bioactive Retention. Fermentation, 11(3), 128.
- Molson Coors Beverage Company. (2025, January 30). Molson Coors Beverage Company Announces Strategic Partnership With Fever-Tree in U.S.. Molson Coors Investor Relations.
- Molson Coors Beverage Company. (2026, November 5). Molson Coors Beverage Company Reports 2026 Third Quarter Results. Molson Coors Investor Relations.
- National Library of Medicine. (2026, May 24). Ginger supplementation and metabolic health: an umbrella review of meta-analyses of randomized trials. Journal of Diabetes & Metabolic Disorders (PubMed PMID 42178586).
- National Library of Medicine. (2026, November 5). Determination of the key characteristic components in ginger from different origins. PubMed PMID 42865278.
- National Library of Medicine. (2026, November 5). Effects of ginger intervention on anthropometric and body composition indices in patients with type 2 diabetes: a GRADE-assessed systematic review and meta-analysis of randomized controlled trials. BMC Complementary Medicine and Therapies, 26(1), 331 (PubMed PMID 42968062).
- PubMed Central Open Access Archive. (2025, February 27). Immunomodulatory Potential of 6-Gingerol and 6-Shogaol in Fermented Zingiber officinale. International Journal of Molecular Sciences, 26(5), 2159 (PMC11900057).
- The Coca-Cola Company. (2026, October 27). Coca-Cola Reports Third Quarter 2026 Results and Raises Full Year Guidance. The Coca-Cola Company Media Center.
- UK Department of Health and Social Care and HM Treasury. (2025, November 25). Soft drinks levy extended to protect children and improve health. GOV.UK Official News Releases.
- USDA Foreign Agricultural Service. (2025, September 18). Taiwan Soft Drinks Market Overview. USDA GAIN Report TW2025-0023.
- USDA Foreign Agricultural Service. (2026, March 18). Australia: Food Processing Ingredients Annual. USDA GAIN Report AS2026-0004.
- USDA Foreign Agricultural Service. (2026, March 31). Brazil: Food Processing Ingredients Annual. USDA GAIN Report BR2026-0011.
- USDA Foreign Agricultural Service. (2026, April 1). Japan: Food Processing Ingredients Annual. USDA GAIN Report JA2026-0012.
- USDA Foreign Agricultural Service. (2026, July 1). Germany: Exporter Guide Annual. USDA GAIN Report GM2026-0012.
- USDA Foreign Agricultural Service. (2026, July 7). Mexico: Exporter Guide Annual. USDA GAIN Report MX2026.
- USDA Foreign Agricultural Service. (2026, August 27). Canada: Food Processing Ingredients Annual. USDA GAIN Report CA2026.
- USDA Foreign Agricultural Service. (2026, October 1). United Kingdom: Retail Foods Annual. USDA GAIN Report UK2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ginger beer market in 2026 and what is forecast for 2036?
- Which zero-proof refreshment and cocktail mixer trends support demand for ginger beer?
- Why does Non-Alcoholic Brewed Ginger Beer lead the product type category?
- Why does Original Traditional Fiery Ginger lead the flavor formulation category globally?
- How do growth rates differ across Brazil, Mexico, and the United States?
- Which leading companies supply botanically brewed ginger beers versus mainstream DSD mixers?
- What sugar-levy thresholds and ginger rhizome cost swings affect bottler margins?
- What should beverage buyers evaluate when selecting low-sugar and canned ginger beers?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Non-Alcoholic Brewed Ginger Beer
- Alcoholic and Hard Fermented Ginger Beer
- Prebiotic and Functional Ginger Beer
- Zero-Proof Botanical Cocktail Mixers
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Flavor Formulation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavor Formulation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavor Formulation, 2026 to 2036
- Original Traditional Fiery Ginger
- Fruit-Infused Mango and Passionfruit Blends
- Spiced Citrus and Yuzu Formulations
- Low-Sugar and Diet Stevia Formulations
- Y-o-Y Growth Trend Analysis By Flavor Formulation, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavor Formulation, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Glass Bottles
- Metal Beverage Cans
- Polyethylene Terephthalate PET Bottles
- Hospitality Post-Mix and Draught Kegs
- Multi-Pack Retail Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and Hypermarkets
- On-Premise Bars and Cocktail Lounges
- Convenience Stores and Corner Grocers
- E-Commerce and Subscription Platforms
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Price Tier, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Price Tier, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Price Tier, 2026 to 2036
- Mainstream and Mass-Market Brands
- Premium Craft and Botanically Brewed
- Super-Premium Hospitality Mixers
- Private-Label Supermarket Lines
- Y-o-Y Growth Trend Analysis By Price Tier, 2021 to 2025
- Absolute $ Opportunity Analysis By Price Tier, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Flavor Formulation
- By Packaging Format
- By Distribution Channel
- By Price Tier
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Fever-Tree Drinks plc
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bundaberg Brewed Drinks Pty Ltd
- Fentimans Ltd.
- Maine Root Handcrafted Beverages LLC
- Keurig Dr Pepper Inc.
- The Coca-Cola Company
- Molson Coors Beverage Company
- Reed's Inc.
- Brookfield Drinks Ltd.
- Old Jamaica Beverage Company
- Fever-Tree Drinks plc
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Flavor Formulation, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Packaging Format, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Price Tier, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Flavor Formulation
- Figure 9: Global Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Packaging Format
- Figure 12: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Distribution Channel
- Figure 15: Global Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Price Tier
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Flavor Formulation
- Figure 35: North America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Packaging Format
- Figure 38: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Distribution Channel
- Figure 41: North America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Price Tier
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Flavor Formulation
- Figure 51: Latin America Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Packaging Format
- Figure 54: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 57: Latin America Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Price Tier
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Flavor Formulation
- Figure 67: Western Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Packaging Format
- Figure 70: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 73: Western Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Price Tier
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Flavor Formulation
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Packaging Format
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Price Tier
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Flavor Formulation
- Figure 99: East Asia Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Packaging Format
- Figure 102: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 105: East Asia Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Price Tier
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Flavor Formulation
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Packaging Format
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Price Tier
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Flavor Formulation, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Flavor Formulation, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Flavor Formulation
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Packaging Format, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Packaging Format, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Packaging Format
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Price Tier, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Price Tier, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Price Tier
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the ginger beer market in 2026, and what is forecast for 2036?
FMI valuation estimates place the ginger beer market at USD 5.2 billion in 2025 and USD 5.6 billion in 2026. Total valuation is forecast to hit USD 11.1 billion by 2036.
What is the CAGR for the ginger beer market from 2026 to 2036?
The ginger beer sector is projected to expand at a 7.1% CAGR over the 2026 to 2036 window, adding USD 5.5 billion in cumulative new revenue across retail and hospitality channels.
Which product type segment leads the ginger beer market?
Non-Alcoholic Brewed Ginger Beer is projected to hold 74.5% of product type demand in 2026 since alcohol-free root brews face zero liquor-licensing barriers and serve both mocktails and spirit highballs.
Which flavor formulation segment leads the ginger beer market?
Original Traditional Fiery Ginger is anticipated to represent 68.0% of the flavor formulation category in 2026 supported by bartender preference for authentic 6-gingerol spice in Moscow Mules and Dark 'n' Stormy cocktails.
Which country has a notable growth outlook during the assessment period?
Brazil leads national expansion projections at an 8.3% CAGR through 2036, driven by urban hospitality mule cocktail culture and domestic beverage processing growth.
Who are the key players in the market?
Fever-Tree Drinks plc, Bundaberg Brewed Drinks Pty Ltd, Fentimans Ltd., Maine Root Handcrafted Beverages LLC, Keurig Dr Pepper Inc., The Coca-Cola Company, Molson Coors Beverage Company, Reed's Inc., Brookfield Drinks Ltd., and Old Jamaica Beverage Company lead commercial supply across botanically brewed and mass-market ginger beer tiers.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
