

- Market Size (2026)
- USD 41.6 Bn
- Forecast (2036)
- USD 97.6 Bn
- CAGR (2026 to 2036)
- 8.9%
How big is Green Tires Market in 2026?
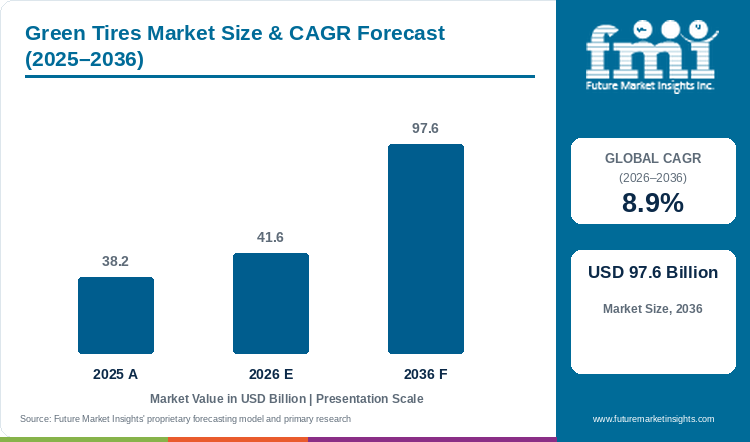
From 2026 to 2036 the green tires market posts an 8.9% CAGR. Green tires opened the base year 2025 at USD 38.2 billion. Estimated 2026 sales of USD 41.6 billion are on course for USD 97.58 billion in 2036 (projected).
Market size for green tires is estimated at USD 41.6 billion in 2026, up from USD 38.2 billion in 2025. Sales will rise at an 8.9% CAGR over the next decade to USD 97.58 billion by 2036, as per FMI.
Each new electric car rolls out on low-loss tyres, so the EV tires market reaches a 26.4% CAGR from 2026 to 2036. EV tyres pair low rolling resistance with high load capacity, so the estimated 17.8% EV share of 2026 application sales will rise. UN Regulation 186 abrasion tests also cover the advanced tires market, on an 8.8% CAGR over the same years. Tyre makers will therefore share low-abrasion compounds across green and advanced lines. Passenger car green tires hold 64.1% of 2026 product sales, and low-loss compounds will replace standard ones at each tyre change.
California voted to cap rolling resistance from 2029, with a tighter limit in 2033, The Next Web reported in August 2026.[1] Noncompliant tyres will leave dealer shelves, and growth is shifting across product categories toward low-loss lines. Budget importers, however, will face higher compound costs for silica blends and new polymers. Those importers will choose between new moulds and exit from regulated states before 2033.
EU tyres have carried a label grading rolling resistance, wet grip and noise since 2012.[1] Counter shoppers compare efficiency with price, and the European Union leads profiled countries on a 9.1% CAGR.
Key Market Trends & Insights
- Product: passenger car green tires carry 64.1% of 2026 sales, with commercial vehicle tires and specialty tires behind.
- Material: natural rubber accounts for 28%, ahead of synthetic rubber alternatives at an estimated 26.3%.
- Technology: tire technology leads with about 41.2% (estimated). Hankook put 18-inch and larger sizes at 49.5% of passenger car and light truck sales for Q2 2026.[2]
- Application: passenger vehicles hold an estimated 57.3%, and electric vehicles about 17.8% (estimated).
- End use: automotive manufacturers lead at an estimated 44.8%, ahead of the aftermarket and fleet operators.
- Distribution channel: the aftermarket takes about 55.2% (estimated), and original equipment manufacturers the balance.
Regional Highlights
- The European Union posts the quickest profiled rate, a 9.1% CAGR from 2026 to 2036.
- South Korea runs at an 8.8% CAGR. The UK (8.7%) and USA (8.6%) come next. Japan grows slowest, at an 8.4% CAGR.
- UN Regulation 186 requires abrasion compliance for new C1 tyre type approvals from 30 June 2028, European Rubber Journal reported.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Green Tires Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 38.2 billion |
| Estimated Market Size in 2026 | USD 41.6 billion |
| Projected Market Size by 2036 | USD 97.58 billion |
| CAGR, 2026 to 2036 | 8.9% |
| Added Revenue, 2026 to 2036 | USD 55.98 billion |
| Market Expansion Multiple | 2.3x |
EV tyres are built for low rolling resistance to protect battery range, so EV fitments overlap with green tyre demand. The EV tires market posts a 26.4% CAGR from 2026 to 2036, about three times the 8.9% green tire CAGR in the FMI base case. EV fitments will therefore raise the estimated 17.8% EV share of green tyre sales. Each UN Regulation 186 abrasion stage, in 2028 and 2033, will move more replacement tyres from the passenger tire market into the green tier.
Rolling-Resistance Caps and Abrasion Limits by Jurisdiction
Regulators in Geneva and Sacramento tightened tyre rules in 2026. Abrasion limits for C1 tyres were adopted by the UNECE WP.29 forum in June 2026, Pew reported on 7 July 2026.[4] UNECE estimates put the cut in overall tyre abrasion at more than 10% and the share of higher-abrasion tyres to be replaced at about 30% in Europe and Japan.[4] Stage 2 of UN Regulation 186 brings tighter abrasion limits for new type approvals from 30 June 2033.[3] The California cap is set at about 9 N/kN in the first phase and about 7 N/kN in the second, against 10.5 N/kN under UN R117 for passenger car tyres.[1] Goodyear and Yokohama told the commission that compliant tyres cost $6 to $10 more each.[1] FMI ties green tire growth to regulatory pressure on safety and emission compliance, and the 2029 and 2033 California caps will push compound upgrades into the next product cycle.
Table 2: Tyre Label, Rolling-Resistance and Abrasion Indicators for the Green Tires Market (N/kN, dates, percentage and USD), mixed reporting years with compliance dates from 2028 onward
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| EU tyre label grades | Rolling resistance, wet grip and noise since 2012 | Buyers see efficiency class at the point of sale. | [1] |
| UN R117 passenger tyre ceiling | 10.5 N/kN | Baseline rolling-resistance limit in Europe. | [1] |
| California rolling-resistance cap, first and second phase | About 9 N/kN from 2029, about 7 N/kN in 2033 | Replacement tyres in a large US state face efficiency caps. | [1] |
| California replacement tyres failing the second threshold | 82% to 91% (state analysis) | Scale of range redesign needed by 2033. | [1] |
| Added cost of compliant tyres | $6 to $10 each (Goodyear and Yokohama) | Price pressure on budget lines. | [1] |
| UN Regulation 186 Stage 1, C1 tyres | New type approvals from 30 June 2028, all approvals from 30 June 2030 | Abrasion testing becomes part of type approval. | [3] |
| UN Regulation 186 Stage 2 | New type approvals from 30 June 2033, all approvals from 30 June 2035 | Tighter limits extend the compound upgrade cycle. | [3] |
| UNECE estimate of tyres replaced under initial limits | About 30% of higher-abrasion tyres in Europe and Japan | Range churn for tyre makers selling in both regions. | [4] |
| UK battery electric share of new car registrations, September 2026 | 28.3% | A growing EV base for low-loss original equipment tyres. | [5] |
| North American passenger and light truck replacement demand, first half 2026 | Down 5% | Weak replacement volume ahead of the California caps. | [6] |
Analyst Perspective
“California's 2029 and 2033 caps hand the clearest opening to tyre makers that already sell low-rolling-resistance lines under the EU label, because those compounds can move to US shelves with little redesign. I expect abrasion testing under UN Regulation 186 to become the next point of difference, and makers with proven low-wear treads will gain original equipment awards.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the green tires market segmented?
Green tire sales are split along six product and buyer axes plus region. Passenger car tires lead product on 64.1% for 2026. Natural rubber leads material with 28%.
By product: specialty green tires, commercial vehicle green tires, and passenger car green tires.
By material: natural rubber, synthetic rubber alternatives, fillers, and reinforcement materials.
By technology: tire technology, manufacturing technology, recycling technology, and smart tire technology.
By application: passenger vehicles, commercial vehicles, and electric vehicles.
By end use: automotive manufacturers, aftermarket, and fleet operators.
By distribution channel: original equipment manufacturers and aftermarket.
By region: green tire sales are split across North America, Middle East and Africa, Europe, South Asia and Pacific, Latin America, and East Asia.
Why do passenger car green tires lead product sales?
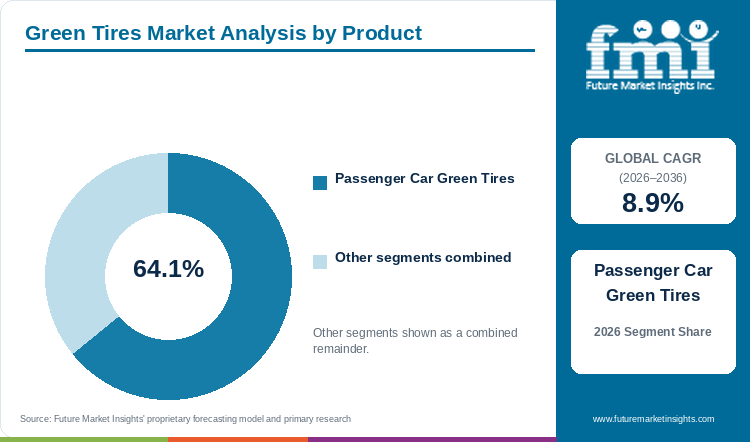
Passenger car green tires own a 64.1% product share for 2026, with commercial vehicle and specialty tires behind.
Table 3: Product Share for the Green Tires Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Passenger Car Green Tires | 64.1% |
| Commercial Vehicle Green Tires | 24.7% |
| Specialty Green Tires | 11.2% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Green Tires Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.9% |
| Leading Segment | Passenger Car Green Tires |
Michelin credited the new MICHELIN Primacy 5 Energy and Pilot Sport 5 Energy ranges for brand momentum in replacement, the group said on 27 July 2026.[7] Car buyers will compare EU label grades for rolling resistance and wet grip first. FMI places passenger car green tires at 64.1% of product sales. Commercial vehicle tires follow at an estimated 24.7%, and specialty tires take about 11.2% (estimated). Car ranges will stay in front as abrasion stages for C2 and C3 tyres arrive later.
- Truck and bus tyres will gain once heavier categories receive abrasion limits.
- Michelin said MICHELIN-brand replacement volumes grew 5% in H1 2026.[7]
Why does natural rubber lead the green tires material mix?
Natural rubber leads materials with 28% in 2026. Synthetic rubber alternatives follow close, near 26.3% (estimated).
Table 5: Material Share for the Green Tires Market (percentage share), 2026
| Material | Estimated Share (2026) |
|---|---|
| Natural Rubber | 28% |
| Synthetic Rubber Alternatives | 26.3% |
| Fillers | 25.2% |
| Reinforcement Materials | 20.5% |
| Total | 100.0% |
Natural rubber leads the material split ahead of synthetic rubber alternatives, fillers and reinforcement materials. In FMI figures the natural rubber slice comes to 28%. Synthetic rubber alternatives stand at an estimated 26.3%, fillers near 25.2% (estimated) and reinforcement materials at about 20.5%. Silica fillers will gain ground with each rolling-resistance cap, and the silica market will gain from each cap. Bio-based polymers will compete with natural rubber in premium lines, and the tire materials market will absorb the move to bio-based polymers.
- Filler share, near 25.2%, will rise as makers chase lower rolling resistance without losing wet grip.
- Reinforcement materials will gain from lighter casings in large rim sizes.
Why does tire technology lead green tire technology sales?
An estimated 41.2% of 2026 technology sales goes to tire technology, with manufacturing, recycling and smart tire technology behind.
Table 6: Technology Share for the Green Tires Market (percentage share), 2026
| Technology | Estimated Share (2026) |
|---|---|
| Tire Technology | 41.2% |
| Manufacturing Technology | 27.5% |
| Recycling Technology | 18.6% |
| Smart Tire Technology | 12.7% |
| Total | 100.0% |
Tread compound and casing design will decide the label class, and tire technology holds the top place at an estimated 41.2%. Manufacturing technology follows on about 27.5% (estimated). Recycling technology accounts for an estimated 18.6%, and smart tire technology about 12.7%. Hankook said 18-inch and larger sizes reached 49.5% of passenger car and light truck sales in Q2 2026.[2] Large rims will raise the value of each low-loss compound. Recycling methods will gain once abrasion and end-of-life rules tighten together.
- Smart tire sensors will gain in fleets that track pressure and wear.
- Hankook set an annual target of 51% for 18-inch and larger sizes.[2]
Why do passenger vehicles lead green tire applications?
Passenger vehicles form the largest application group at an estimated 57.3% in 2026. Commercial vehicles hold about 24.9%, and electric vehicles about 17.8%.
Table 7: Application Share for the Green Tires Market (percentage share), 2026
| Application | Estimated Share (2026) |
|---|---|
| Passenger Vehicles | 57.3% |
| Commercial Vehicles | 24.9% |
| Electric Vehicles | 17.8% |
| Total | 100.0% |
Combustion and hybrid passenger cars lead the application split because far more of those cars are on the road. Passenger vehicles hold an estimated 57.3%. Commercial vehicles account for about 24.9% (estimated), and electric vehicles for an estimated 17.8%. EV tyres made up 31.8% of Hankook passenger car and light truck original equipment sales in Q2 2026.[2] Electric vehicles, now 17.8% of applications, will gain as the first EV fleets reach replacement age.
- Demand for commercial vehicle tyres will follow freight volumes and fuel prices.
- Hankook reported notable replacement sales growth in China as EVs entered tyre replacement cycles.[2]
Why do automotive manufacturers lead green tire end use?
Automotive manufacturers hold the top end-use position at an estimated 44.8% for 2026. The aftermarket takes near 39.7%, and fleet operators 15.5% (estimated).
Table 8: End Use Share for the Green Tires Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| Automotive Manufacturers | 44.8% |
| Aftermarket | 39.7% |
| Fleet Operators | 15.5% |
| Total | 100.0% |
Carmakers buy low-loss tyres to meet range and emission targets at launch. Automotive manufacturers lead end use on an estimated 44.8%. The aftermarket follows near 39.7% (estimated), and fleet operators hold about 15.5%. Hankook named original equipment fitments for the Porsche 911 Carrera, Audi Q7 and Infiniti QX65 in August 2026.[2] Premium fitments will keep carmakers ahead, and fleet operators, at 15.5%, will gain as total-cost buying spreads.
- Fleet operators will weigh tyre price against fuel and tread life.
- Aftermarket buyers will follow the label grade on the original fitment.
Why does the aftermarket lead green tire distribution?
The aftermarket carries about 55.2% (estimated) of channel sales in 2026, and original equipment manufacturers an estimated 44.8%.
Table 9: Distribution Channel Share for the Green Tires Market (percentage share), 2026
| Distribution Channel | Estimated Share (2026) |
|---|---|
| Aftermarket | 55.2% |
| Original Equipment Manufacturers | 44.8% |
| Total | 100.0% |
Each car on the road needs several tyre sets over a life, and that cycle puts the aftermarket ahead with an estimated 55.2%. Original equipment manufacturers take about 44.8% (estimated). The European replacement market for passenger car and light commercial tyres rose 3% in Q2 2026, Continental reported on 4 August 2026.[8] Replacement volume will keep the aftermarket in front, and California caps will add a regulated replacement pool from 2029.
- Original equipment volume will follow global vehicle production, which fell about 1% year on year in Q2 2026, Continental said.[8]
- Dealers will stock more labelled low-loss sizes as the California caps tighten in 2029 and 2033.
What are the drivers, restraints, and opportunities in the green tires market?
Sales of green tires rise with label grading, rolling-resistance caps and abrasion limits. Adoption of green tires slows in price-sensitive segments, and electric vehicle fleets offer the clearest opening.
- Driver: Abrasion limits and rolling-resistance caps in Europe, the USA and UNECE markets.
- Restraint: Cost-performance trade-offs and $6 to $10 of added cost per tyre.
- Opportunity: Electric vehicle tyres in original equipment and first replacement.
Abrasion Rules Enter Type Approval
FMI identifies regulatory pressure on vehicle safety and emission compliance as a main force in demand. Compliance with UN Regulation 186 becomes mandatory for all C1 tyre type approvals from 30 June 2030, European Rubber Journal reported on 9 September 2026.[3] UNECE work on abrasion limits for C2 and C3 tyres continues.[3] Tyre makers will rework tread compounds for every new type approval. The advanced tires market will gain from UN Regulation 186 abrasion testing.
Price Gaps Hold Back Budget Buyers
California analysis found that between 82% and 91% of replacement tyres would not comply at the second threshold, The Next Web reported.[1] Key challenges faced by manufacturers include cost-performance trade-offs and limited reach in price-sensitive segments. Tyre makers estimate that about 70% of the current market would fail.[1] Budget brands will pay for new moulds and compounds across whole ranges.
Electric Fleets Need Low-Loss Tyres
Hankook put EV tyres at 31.8% of passenger car and light truck original equipment sales for Q2 2026, near a 33% annual target.[2] Sales potential is expected to emerge from electric vehicle tyres that pair low rolling resistance with high load capacity. Hankook described iON as the first full-lineup EV-specialised tyre brand.[2] iON and other EV tyre lines are moving from production capacity to commercial scale, and owners will return to the same low-loss lines at replacement.
Which country CAGRs are profiled in the green tires market?
Table 10: Country CAGR Comparison for the Green Tires Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| European Union | 9.1% |
| South Korea | 8.8% |
| UK | 8.7% |
| USA | 8.6% |
| Japan | 8.4% |
How do country-level CAGRs compare in the green tires market?
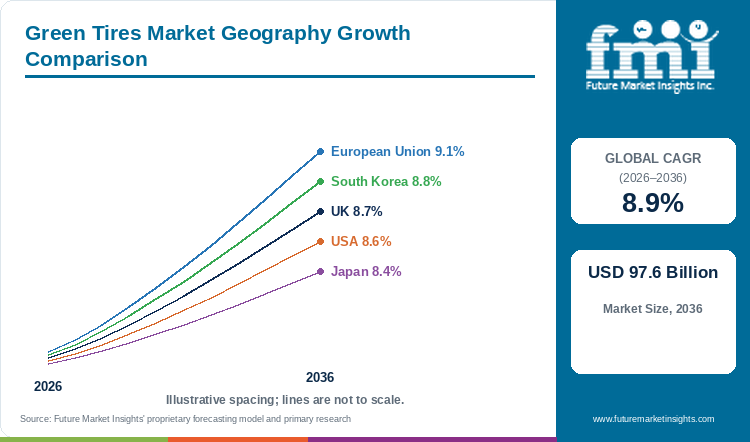
The countries setting the growth agenda cluster within an 8.4% to 9.1% CAGR band across five profiled markets. FMI ranks the European Union first at a 9.1% CAGR from 2026 to 2036, the only profiled market above the 8.9% global CAGR. South Korea, the UK and the USA follow on CAGRs of 8.8%, 8.7% and 8.6% in that order. Japan has the lowest CAGR, 8.4%.
- The European Union combines the tyre label with Euro 7 abrasion limits.
- South Korea pairs large rim sizes with EV original equipment fitments.
- The UK will see label-led replacement buying and lease fleet specification.
- The USA adds a state cap on replacement tyre rolling resistance.
- Japan faces replacement of higher-abrasion tyres under UNECE limits.
Full report country CAGRs cover: a wider country set across six regions, with Middle East and Africa, South Asia and Pacific, Europe, East Asia and the Americas.
Country-wise Analysis
European Union Green Tires Market Outlook (2026 to 2036)
Euro 7, adopted in 2024, is the first legal framework to restrict microplastic releases from tyres, Pew reported.[4] The EU label already shows rolling resistance, wet grip and noise at the point of sale. An EU CAGR of 9.1% from 2026 to 2036 tops the five profiled markets. Demand for replacement passenger car and light commercial tyres in Europe grew 3% in Q2 2026.[8] Abrasion and label grades together will narrow the shelf to low-loss, low-wear products.
Key takeaway: EU buyers will face two grades on one tyre, efficiency and wear, and makers will need both.
South Korea Green Tires Market Outlook (2026 to 2036)
Premium and electric car tyres will carry a Korean CAGR of 8.8% from 2026 to 2036. Hankook reported tyre division sales of KRW 2.8073 trillion for Q2 2026, up 11.8%.[2] Hankook cited continued expansion of OE supply to global premium automakers.[2] Korean makers will push EV ranges into replacement as early EV fleets age.
Key takeaway: Korean tyre makers will grow with premium and EV fitments abroad.
UK Green Tires Market Outlook (2026 to 2036)
UK sales grow at an 8.7% CAGR over the forecast period. Battery electric cars reached 28.3% of UK new registrations in September 2026, on 99,199 units, electrive reported from SMMT data on 2 October 2026.[5] The year-to-date BEV share stood at 26.2%.[5] Each new EV will arrive on low-loss original equipment tyres and return for the same class at replacement. Retail buyers will compare label grades online before a fitting. UK fleet and leasing firms will set tyre specifications on new company cars. Abrasion limits under UNECE rules will shape the UK replacement range as type approvals follow.
Key takeaway: UK lease fleet tyre specifications will drive low-loss tyre adoption toward the 8.7% CAGR.
USA Green Tires Market Outlook (2026 to 2036)
The North American replacement market declined 1% in Q2 2026, Continental said.[8] Bridgestone put the first-half 2026 drop in North American passenger and light truck replacement demand at 5%, using USTMA and TRAC data, Modern Tire Dealer reported on 13 August 2026.[6] US tariffs cost Bridgestone about $158 million over the same half.[6] The 5% replacement drop and $158 million tariff bill will slow Bridgestone price pass-through for compliant tyres. The California rolling-resistance cap will reshape the US replacement range from 2029. The California Energy Commission estimates nearly $1bn a year in statewide fuel savings, The Next Web reported.[1] American tyre sales hold an 8.6% CAGR from 2026 to 2036. Hankook cited ongoing expansion of the Tennessee plant.[2]
Key takeaway: California caps will make low-rolling-resistance tyres the default replacement choice in California.
Japan Green Tires Market Outlook (2026 to 2036)
Japan posts an 8.4% CAGR from 2026 to 2036, the lowest of the five profiled markets. UNECE limits will drive replacement of about 30% of higher-abrasion tyres sold in Europe and Japan, per UNECE estimates cited by Pew.[4] Japanese makers will refresh tread compounds to keep European and Japanese sales open. JATMA revised the 2025 forecast for Japanese summer replacement passenger car tyres to 31,138,000 units, flat on the prior year, Logistics Today reported on 17 July 2025.[9] Flat replacement volume will slow the switch to low-loss treads in the Japanese aftermarket.
Key takeaway: Japan will see a tread range refresh under UNECE abrasion limits, slowed by flat summer replacement volume.
Who are the notable companies in the green tires market?
Michelin, Bridgestone Corporation, Continental AG, Goodyear Tire & Rubber Co., Pirelli & C. S.p.A., Hankook Tire & Technology, Kumho Tire Co., Inc., Apollo Tyres Ltd., Toyo Tire Corporation, Nokian Tyres, JK Tyre & Industries Ltd., MRF Ltd., Sumitomo Rubber Industries Ltd. and CEAT Ltd. compete in green tires.
Michelin holds the leading position with around 18% share, FMI credits. The group advanced green tire launches in 2025, including the Primacy 5 and e.Primacy ranges. Bridgestone Corporation focused on the ENLITEN technology platform across multiple tire lines in 2025. CEAT Ltd. counts among the emerging players.
Half-year results in 2026 show margins rising at Continental and Hankook. Continental reported a 15.3% adjusted EBIT margin for the tires group sector in Q2 2026, helped by a higher share of 18-inch and larger tyres.[8] Michelin posted first-half revenue of €12.7 billion and segment operating income of €1.45 billion.[7] Hankook raised Q2 operating profit 58.1%.[2]
- Share leader: Michelin.
- Other profiled tyre makers: Bridgestone Corporation, Continental AG, Goodyear Tire & Rubber Co., Pirelli & C. S.p.A., Hankook Tire & Technology, Kumho Tire Co., Inc., Apollo Tyres Ltd., Toyo Tire Corporation, Nokian Tyres, JK Tyre & Industries Ltd., MRF Ltd., and Sumitomo Rubber Industries Ltd.
- Emerging player: CEAT Ltd.
Competitive Benchmarking: Green Tires Market
Table 11: Competitive Benchmarking for the Green Tires Market (qualitative documentation ratings), 2026
| Company | Low-Loss Ranges | EV Tyre Focus | Large Rim Mix | Disclosure |
|---|---|---|---|---|
| Michelin | High | Low | Low | High |
| Bridgestone Corporation | High | Low | Low | Medium |
| Hankook Tire & Technology | Medium | High | High | High |
| Continental AG | Low | Low | High | High |
Each score reflects the dated company detail found for that column, on a High, Medium or Low scale.
Key Developments in the Green Tires Market
- In October 2026, electrive reported a record month for UK battery electric car registrations in September.[5]
- In September 2026, UNECE work on UN Regulation 186 for C1 tyres was reported complete by European Rubber Journal.[3]
- In August 2026, The Next Web reported California approval of rolling-resistance caps from 2029.[1]
- In August 2026, Hankook posted KRW 5.6824 trillion in Q2 consolidated revenue, 5.8% above a year earlier.[2]
- In August 2026, Continental reported Q2 tires sales of €3.3 billion.[8]
- In August 2026, Modern Tire Dealer reported an 11% rise in Bridgestone Americas revenue for the first half.[6]
- In July 2026, Michelin reported a 5% rise in MICHELIN-brand replacement volumes for the first half.[7]
- In July 2026, Pew reported UNECE WP.29 adoption of abrasion limits for C1 tyres.[4]
- In July 2025, JATMA revised the 2025 Japanese forecast for winter replacement passenger car tyres to 14,522,000 units, flat on the prior year.[9]
Key Players in the Green Tires Market
Share Leader
- Michelin
Other Profiled Tyre Makers
- Bridgestone Corporation
- Continental AG
- Goodyear Tire & Rubber Co.
- Pirelli & C. S.p.A.
- Hankook Tire & Technology
- Kumho Tire Co., Inc.
- Apollo Tyres Ltd.
- Toyo Tire Corporation
- Nokian Tyres
- JK Tyre & Industries Ltd.
- MRF Ltd.
- Sumitomo Rubber Industries Ltd.
Emerging Player
- CEAT Ltd.
Green Tires Market - Report Scope
Table 12: Report Scope for the Green Tires Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; material; technology; application; end use; distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Green tires market covering passenger car, commercial vehicle and specialty tires built for low rolling resistance and lower environmental impact, sold to carmakers, fleets and the aftermarket. |
| Regions covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | European Union; South Korea; UK; USA; Japan |
| Key companies profiled | Michelin, Bridgestone Corporation, Continental AG, Goodyear Tire & Rubber Co., Pirelli & C. S.p.A., Hankook Tire & Technology, Kumho Tire Co., Inc., Apollo Tyres Ltd., Toyo Tire Corporation, Nokian Tyres, JK Tyre & Industries Ltd., MRF Ltd., Sumitomo Rubber Industries Ltd., CEAT Ltd. |
| Forecast period | 2026 to 2036 |
Green Tires Market - Research Methodology
Table 13: Research Methodology for the Green Tires Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Regulatory and company facts are drawn from tyre maker results, UNECE rule reports and automotive trade press dated May 2025 or later. |
| Desk Research | Desk work follows label grades, rolling-resistance caps, abrasion stages, rim-size mix and EV fitments. |
| Market Sizing and Forecasting | The model starts from USD 38.2 billion in 2025 and an 8.9% CAGR from 2026 to 2036. |
| Data Validation | Rule dates were matched across two independent reports of each decision. |
Green Tires Market by Segments
Green Tires Market segmented by Product:
- Passenger Car Green Tires
- Commercial Vehicle Green Tires
- Specialty Green Tires
Green Tires Market segmented by Material:
- Natural Rubber
- Synthetic Rubber Alternatives
- Fillers
- Reinforcement Materials
Green Tires Market segmented by Technology:
- Tire Technology
- Manufacturing Technology
- Recycling Technology
- Smart Tire Technology
Green Tires Market segmented by Application:
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
Green Tires Market segmented by End Use:
- Automotive Manufacturers
- Aftermarket
- Fleet Operators
Green Tires Market segmented by Distribution Channel:
- Original Equipment Manufacturers
- Aftermarket
Green Tires Market by Region
- North America
- Latin America
- Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
Research Sources and Bibliography
- [1] The Next Web. (2026, August 19). California's new tyre standard is stricter than Europe's, which has had one since 2012. https://thenextweb.com/news/california-replacement-tire-efficiency-standard-europe
- [2] Hankook Tire & Technology. (2026, August 11). Hankook reports 2026 Q2 revenue of EUR 3,254.9 million and operating profit of EUR 320.2 million. https://www.hankooktire-mediacenter.com/press-release/news/hankook-reports-2026-q2-revenue-of-eur-32549-million-and-operating-profit-of-eur-3202-million
- [3] European Rubber Journal. (2026, September 9). UNECE completes work on new car tire abrasion regulation. https://www.european-rubber-journal.com/article/2099651/unece-completes-work-on-new-car-tire-abrasion-regulation
- [4] The Pew Charitable Trusts. (2026, July 7). The long road to a tyre wear policy breakthrough. https://www.pew.org/en/research-and-analysis/articles/2026/07/07/the-long-road-to-a-tyre-wear-policy-breakthrough
- [5] electrive. (2026, October 2). UK posts strongest-ever month for BEV registrations in September. https://www.electrive.com/2026/10/02/uk-posts-strongest-ever-month-for-bev-registrations-in-september/
- [6] Modern Tire Dealer. (2026, August 13). Bridgestone Americas Sales Rise 11% as North American Share Grows. https://www.moderntiredealer.com/suppliers/news/55397897/bridgestone-americas-sales-rise-11-as-north-american-tire-share-grows
- [7] Michelin. (2026, July 27). Financial information at June 30, 2026. https://www.michelin.com/en/publications/group/financial-information-at-june-30-2026
- [8] Continental AG. (2026, August 4). Results first half 2026. https://www.continental.com/en/press/press-releases/results-first-half-2026/
- [9] Logistics Today. (2025, July 17). JATMA、25. https://www.logi-today.com/815083
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- What will green tire sales reach in 2026 and 2036?
- What CAGR will the green tires market post from 2026 to 2036?
- Which product will hold the largest share?
- Which material will lead the mix?
- Which profiled country will grow fastest?
- Which tyre makers will shape competition through 2036?
Frequently Asked Questions
What is the size of the green tires market in 2026?
In 2026, green tire sales will reach about USD 41.6 billion (estimated). FMI forecasts USD 97.58 billion for 2036. At what rate will the green tires market grow? Label grades, rolling-resistance caps and abrasion limits will carry an 8.9% CAGR from 2026 to 2036.
Which product will lead in 2026?
A 64.1% product share will place passenger car green tires first.
Which material will hold the largest share?
Natural rubber will hold the largest material share at 28%, with synthetic alternatives and fillers close behind.
Which country will grow fastest?
The European Union will post the top profiled CAGR of 9.1%, per the FMI outlook, ahead of South Korea at 8.8%.
Which company will lead the market?
Michelin will keep the leading position, with around 18% share in 2026.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Passenger Car Green Tires
- Commercial Vehicle Green Tires
- Specialty Green Tires
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By Material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Material, 2026 to 2036
- Natural Rubber
- Synthetic Rubber Alternatives
- Fillers
- Reinforcement Materials
- Y-o-Y Growth Trend Analysis By Material, 2021 to 2025
- Absolute $ Opportunity Analysis By Material, 2026 to 2036
- Global Market Analysis and Forecast, By Technology, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Technology, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Technology, 2026 to 2036
- Tire Technology
- Manufacturing Technology
- Recycling Technology
- Smart Tire Technology
- Y-o-Y Growth Trend Analysis By Technology, 2021 to 2025
- Absolute $ Opportunity Analysis By Technology, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Automotive Manufacturers
- Aftermarket
- Fleet Operators
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Original Equipment Manufacturers
- Aftermarket
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Market Attractiveness Analysis
- By Country
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- European Union
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By Material
- By Technology
- By Application
- By End Use
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Michelin
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bridgestone Corporation
- Hankook Tire & Technology
- Continental AG
- Goodyear Tire & Rubber Co.
- Pirelli & C. S.p.A.
- Kumho Tire Co., Inc.
- Apollo Tyres Ltd.
- Toyo Tire Corporation
- Nokian Tyres
- JK Tyre & Industries Ltd.
- MRF Ltd.
- Sumitomo Rubber Industries Ltd.
- CEAT Ltd.
- Michelin
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


