

- Market Size (2026)
- USD 43.8 Bn
- Forecast (2036)
- USD 75.7 Bn
- CAGR (2026 to 2036)
- 5.6%
How big is Herbs and Spices Market in 2026?
USD 43.8 billion in 2026 and USD 75.7 billion by 2036 at a 5.6% CAGR.
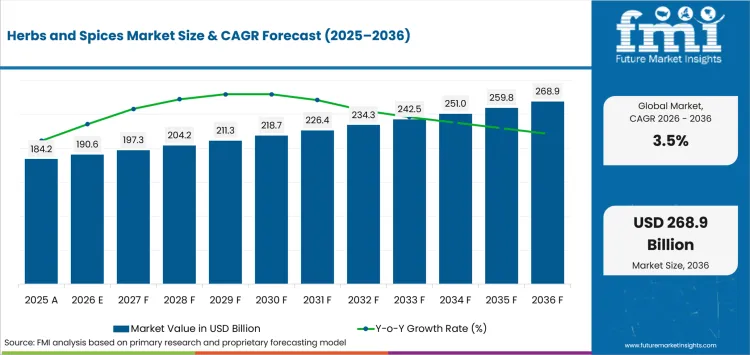
Demand for herbs and spices is projected to expand at 5.6% CAGR between 2026 and 2036, increasing valuation from USD 43.8 billion in 2026 to USD 75.7 billion by 2036. Growth is supported by broader consumer acceptance of international cuisines and more diverse food formulations across retail and foodservice channels. USDA Economic Research Service reported in April 2026 that a more diverse USA food basket has been accompanied by greater consumption of spices and imported gourmet products. The trend increases demand for reliable ingredient sourcing and consistent flavor performance across commercial food production.
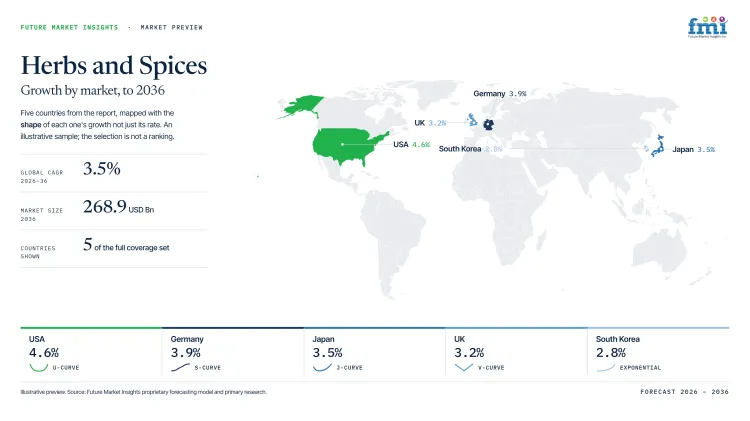
Country forecasts diverge even where import activity remains commercially strong in established consuming markets. USA is projected at 4.6% CAGR and the United Kingdom at 3.2% through 2036. Defra reported in April 2026 that real UK imports of coffee, tea, cocoa and spices rose 18% during 2025. The slower UK CAGR therefore reflects the modeled market path instead of weak ingredient inflows, with qualification and channel economics still shaping value capture.
Key Takeaways of Herbs and Spices Market
- Food manufacturers purchase herbs and spices for repeatable flavor profiles in sauces, snacks, bakery products, beverages, and prepared meals where recipe consistency protects finished-product quality.
- Based on product type, spices are projected to account for 94.3% in 2026 due to broad use of pepper, paprika, cumin, and related seasonings.
- Food is set to lead the end-use category with 32.7% share in 2026 due to repeated seasoning demand in high-volume food manufacturing.
- In 2026, powder & granules are expected to lead form with 52.1% share because dry formats simplify dosing, storage, and industrial blending.
- Residue limits, microbial hazards, adulteration, and destination testing can lengthen qualification or reject an otherwise usable spice lot before production begins.
- Some of the key players in this market include McCormick & Company, Incorporated, ofi, International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Kerry Group plc, dsm-firmenich AG, and Kalsec, Inc.
Analyst Perspective
"Herbs and spices earn margin once processors turn crop variation into a specification a food plant can repeat for heat, particle size, residues, and microbial status. A low crop price loses its advantage quickly if treatment records or sensory consistency force a manufacturer to retest the lot or reformulate the recipe."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Herbs and Spices Market segmented?
The herbs and spices market is segmented by product type, end-use, form, sales channel, nature, and region.
Market taxonomy covers product type, end-use, form, sales channel, nature, and region. Product type includes spices, herbs, cumin, and paprika (hot pepper). End-use covers food, food service, retail, processed food, snacks and savory products, beverages, bakery and confectionery, and flavored or infused oils. Forms include powder & granules, flakes, paste, and whole or fresh. Sales channels include direct, indirect, store-based retailing, and online retail. Nature includes conventional, natural, vegan, non-GMO, and organic.
Why does Food lead the End-use category?
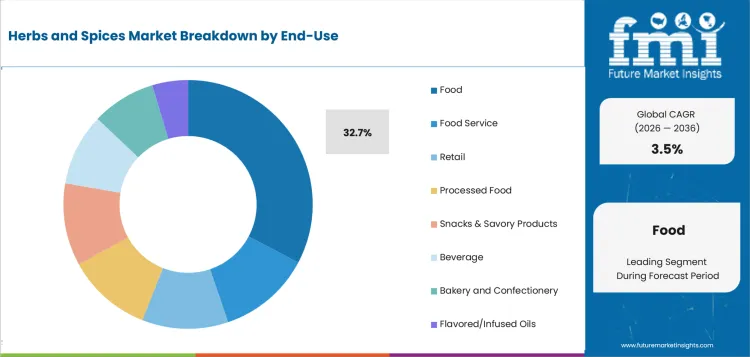
Food manufacturers use herbs and spices as direct formulation inputs in sauces and prepared foods, so seasoning decisions enter product-development work before plant trials. Repeat production turns sensory targets into purchasing specifications tied to each recipe.
- By end-use, the food segment is forecast to represent 32.7% in 2026 driven by repeated recipe demand from food manufacturers.
- Technical teams test food flavor systems and food botanicals at bench scale before plant trials once microbial and sensory specifications are agreed. Kerry released its 2026 Global Taste Charts in January 2026 with eight application categories and a sample-ordering workflow for initial evaluation.
What makes Spices central to the Product type category?
Spice processors standardize heat and aroma for recipes that need the same sensory result despite crop variation. In December 2025 dsm-firmenich named Frosted Star Anise its Flavor of the Year 2026, placing a traditional spice profile into both sweet and savory applications.
- By product type, the spices segment is estimated to hold 94.3% in 2026 owing to its broad culinary reach and compatibility with dried processing.
- Pepper products and seasoning systems extend the same standardization requirement into industrial kitchens and large food plants. Processors secure repeat orders by holding pungency and particle specifications within agreed commercial limits.
How do Powder & Granules lead the Form category?
Dry formats fit automated weighing and blending lines once processors control moisture and particle size at shipment. In June 2025 dsm-firmenich broke ground in Parma for a facility covering concentrated powder flavors and culinary blends, with completion scheduled for the first quarter of 2027.
- Powder & granules are projected to hold 52.1% share in 2026 owing to low moisture and defined particle profiles that simplify industrial handling.
- Herb and spice extracts and spice oils and oleoresins require release profiles matched to specific processing conditions. Powdered ingredients also need dust control and validated hygiene treatment before food plants approve high-volume production.
What supports Direct sales within the Sales channel category?
Large food accounts place origin and treatment status inside the same specification as sensory limits and delivery timing. Direct agreements give technical teams one commercial route for reviewing deviations and approving volume changes.
- Based on sales channel, direct sales are projected to account for 37.8% in 2026 due to specification-heavy orders that benefit from accountable technical contact.
- Application work on botanical extracts and natural food preservatives often needs direct technical contact before scale-up. Kalsec's corporate history records that it opened a Jakarta Applications Lab in 2025, placing application support closer to Southeast Asian food manufacturers.
Why does Conventional lead the Nature category?
Conventional sourcing gives spice processors the broadest crop pool when recipes prioritize sensory consistency and residue compliance over certification claims. Organic programs require separate farm and handling controls before processors can carry the claim into retail or industrial specifications.
- By nature, conventional is estimated to hold 41.7% in 2026 because processors can source commercial volumes without adding organic chain-of-custody requirements.
- USDA began its 2025 Organic Survey in December 2025 to measure certified production and marketing across known organic farms. Organic spice programs therefore remain a separately documented route while conventional suppliers compete mainly on treatment records and repeatable crop specifications.
What are the drivers, restraints and opportunities in the Herbs and Spices Market?
Broader flavor use supports demand, safety failures slow qualification, and application-ready processing gives manufacturers a route to higher-value orders.
- Driver: Food manufacturers expand seasoning programs as new flavor profiles enter established sauces, snacks, beverages, bakery products, and prepared foods.
- Restraint: Contaminants and residue failures can trigger retesting, recalls, rejected imports, or sudden changes in approved spice origin.
- Opportunity: Processors can earn more by pairing treated dry ingredients with traceability records and formulation work that reduces scale-up risk.
New flavor programs widen formulation demand
Seasoning programs expand once manufacturers can place a new flavor profile into an existing sauce, snack, or prepared-food platform without changing the base process. In March 2026 McCormick launched two black-currant products for savory applications under its Flavor of the Year program. Flexible blending lines give spice processors another route into supporting herbs or peppers without forcing the customer's core recipe to change.
Food-safety failures raise the cost of qualification
Weak contaminant control can erase the savings from a low-cost spice lot before a food plant accepts it. In December 2025 the FDA added another ground cinnamon product to its elevated-lead public health alert after agency and state testing. Retesting, rejected entry, or recall work can interrupt production and remove the price advantage of an origin with weaker control records.
Application support shifts processors beyond crop trading
Processors earn more once they solve formulation problems before plant trials instead of selling untreated crop material alone. Symrise opened its Northwest Arkansas Food Studio in May 2026 with rapid-prototyping facilities for customer product development. Local application work can reduce reformulation during scale-up and give botanical ingredients programs a clearer route from test batch to commercial order for food manufacturers.
Which country CAGRs are profiled in the Herbs and Spices Market?
| Country | CAGR |
|---|---|
| USA | 4.6% |
| Thailand | 4.2% |
| Germany | 3.9% |
| Japan | 3.5% |
| United Kingdom | 3.2% |
| South Korea | 2.8% |
| Vietnam | 2.5% |
How do country-level CAGRs compare in the Herbs and Spices Market?
The country range spans 2.1 percentage points from the USA at 4.6% to Vietnam at 2.5%. The USA and Thailand remain the faster pair while Germany through the United Kingdom occupy the middle. South Korea and Vietnam grow more slowly because import controls and crop-export economics add qualification or sourcing friction.
- USA couples retail seasoning demand with food manufacturing that absorbs multiple imported origins.
- Thailand converts regional crops near Southeast Asian food plants and export routes.
- Germany's private-label production replenishes standardized dry spices through continental ingredient distribution networks.
- Japan's convenience foods require controlled dosing and narrow sensory variation between batches.
- United Kingdom retail and foodservice give imported spices outlets beyond packaged-food manufacturing.
- South Korean import inspection keeps residue documentation central when spice origins change between commercial lots.
- Vietnam’s pepper export scale strengthens local processing supply while competing with domestic processors for qualified crop.
Comparable rates produce different economics because processing location and qualification costs shape orders. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- United States spice importers manage broad origin portfolios under FDA's March 2026 Import Alert 28-02, which requires an Indian EIC certificate with lot and test details for affected black pepper shipments detained without physical examination. The USA is estimated to post 4.6% CAGR over the forecast period because retail seasoning demand for sauces, snacks, and prepared foods keeps several origins commercially relevant and gives documented processors room to change supply without abandoning approved recipes. Certification keeps a major pepper route available but Salmonella findings or incomplete records can stop entry before price becomes relevant and leave weakly documented processors with fewer practical sourcing options during routine import qualification.
- Near Thailand's food-manufacturing hubs processors keep sorting and milling close to factories that purchase regional pepper and chilli for domestic recipes or export programs serving nearby Asian markets and large contract seasoning runs. The April 2025 ACFS standard TAS 9002-2568 set maximum residue limits for agricultural food so processors have a current reference for farm records before new origins enter regulated channels during commercial sourcing reviews. Thailand's herbs and spices outlook is anticipated to advance at 4.2% CAGR over the assessment period owing to local processing depth despite farm-level pesticide variation that keeps residue documentation central to qualification for major food manufacturers and export contracts.
- Batch specifications in German private-label and seasoning plants cover moisture, particle size, authenticity, and destination treatment records before dry spices enter routine production for large food programs and regional retail lines. Herbs and spices demand in Germany is forecast to rise at 3.9% CAGR over the forecast period supported by nearby food production and treatment capacity for destination-specific specifications used by contract manufacturers. BVL's 2025 irradiation report documented 49.44 tonnes of herbs and spices treated in Germany during 2024 for third-country destinations, so processors already work under different treatment rules and authenticity files still narrow which lots are commercially interchangeable.
- New-source approval in Japan starts with shipment records and inspection readiness because importers must clear national monitoring controls before a crop origin becomes routine inventory for prepared-food and seasoning programs. MHLW's December 2025 interim report documented 108,862 import inspections from April through September and 359 Food Sanitation Act violations, so importers have a recent measure of how often noncompliant food reaches border review. Adoption of herbs and spices in Japan is estimated to expand at 3.5% CAGR through 2036 given steady prepared-food demand, but higher-risk origins face longer testing cycles until repeated consignments establish a reliable compliance history for regular purchasing.
- Border testing shapes United Kingdom spice imports before lots reach domestic blenders, so pre-shipment contaminant files form part of supplier approval for dried pepper and paprika used in routine food manufacturing. Herbs and spices sales in the United Kingdom are forecast to expand at 3.2% CAGR by 2036 aided by established distribution and broad food applications despite recurring border-control costs. The Food Standards Agency's July 2026 monitoring priorities placed pepper, paprika powder, and chilli powder among higher-priority imported foods, so processors that test before shipment can protect delivery schedules more effectively than origins waiting for border sampling to expose a serious material problem.
- South Korea's spice market grows more slowly because import inspection can interrupt supply before seasonings enter high-volume food production. MFDS issued separate inspection alerts for Malaysian natural spices in September 2025 and Indonesian spices in October 2025. The two notices show how origin-specific control can reopen testing work even when a spice already fits a manufacturer's sensory specification. South Korean herbs and spices demand is expected to rise at 2.8% CAGR during the forecast period, as processors retain imported flavor diversity. Suppliers gain repeat orders by holding residue records and treatment documentation stable enough to avoid requalification after origin changes between commercial lots.
- Vietnam combines deep pepper production with export dependence, so domestic processors compete for raw material against established overseas contracts. Ministry of Agriculture and Environment data showed 166.5 thousand tonnes of pepper exported during the first eight months of 2025. That volume proves commercial scale but also exposes local ingredient buyers to inventory pressure when export orders absorb available crop. Vietnamese herbs and spices demand is projected to rise at 2.5% CAGR through 2036 as processing moves toward treated and standardized formats. Domestic growth remains measured because suppliers must secure traceable crop volumes before adding value through grinding or extraction consistently.
Who are the notable companies in the Herbs and Spices Market?
McCormick & Company, Incorporated, ofi, International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Kerry Group plc, dsm-firmenich AG, and Kalsec, Inc. are notable companies serving this market.

The competitive outlook includes crop-integrated processors, branded seasoning groups, global taste houses and a specialist spice processor. Food manufacturers raise the entry bar by asking for treated ingredients, multi-origin continuity, and application work in the same commercial relationship. The companies differ mainly in how much direct crop control they pair with formulation expertise and regional customer access. Certified organic spices add another sourcing requirement because crop segregation and certification must remain intact through processing.
- McCormick & Company, Incorporated and ofi have direct exposure to branded seasonings or crop-integrated spice sourcing and processing.
- International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Kerry Group plc, and dsm-firmenich AG provide taste systems, seasonings, natural extracts, and application support.
- Kalsec, Inc. specializes in natural taste and direct spice processing for customers that require treated raw spice ingredients.
Competitive Benchmarking: Herbs and Spices Market
| Company | Direct herb and spice exposure | Processing and format depth | Application support | Geographic Reach |
|---|---|---|---|---|
| McCormick & Company, Incorporated | High | High | High | Global |
| ofi | High | High | High | Global |
| International Flavors & Fragrances Inc. | Medium | Medium | High | Global |
| Givaudan SA | Medium | Medium | High | Global |
| Symrise AG | Medium | High | High | Global |
| Kerry Group plc | Medium | Medium | High | Global |
| dsm-firmenich AG | Medium | High | High | Global |
| Kalsec, Inc. | High | Medium | Medium | North America, Europe and Asia |
Scoring basis: High direct exposure requires broad verified herb or spice activity in at least three documented product families. Medium identifies two documented routes, and Low applies to one documented herb or spice route. High processing depth requires at least three documented stages, with Medium covering two stages and Low covering one. High application support requires at least three documented food or beverage application families, with Medium covering two groups and Low covering one.
Key Developments in the Herbs and Spices Market
- In January 2026, McCormick & Company, Incorporated completed the purchase of another 25% interest in McCormick de Mexico and increased ownership to a 75% controlling interest.
- In July 2025, International Flavors & Fragrances Inc. opened an Immersive Experience Hub inside its Singapore Innovation Center for customer product development and testing.
- In October 2025, Givaudan SA broke ground on a 24,000-square-metre liquids production facility in Reading, Ohio for additional North American Taste & Wellbeing capacity.
Key Players in the Herbs and Spices Market
Crop-integrated and branded spice platforms
- McCormick & Company, Incorporated
- ofi
Global taste and application platforms
- International Flavors & Fragrances Inc.
- Givaudan SA
- Symrise AG
- Kerry Group plc
- dsm-firmenich AG
Specialist spice processing and natural taste
- Kalsec, Inc.
Herbs and Spices Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By product type, end-use, form, sales channel, nature and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial culinary herbs, spices, seasoning ingredients, and processed spice forms sold into food manufacturing, foodservice, retail, and related applications. |
| Regions Covered | North America, Latin America, Europe, East Asia, South Asia and Pacific and Middle East and Africa. |
| Countries Covered | USA, Thailand, Germany, Japan, United Kingdom, South Korea, and Vietnam, and 20+ countries included in the full report. |
| Key Companies Profiled | McCormick & Company, Incorporated, ofi, International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Kerry Group plc, dsm-firmenich AG, Kalsec, Inc. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Herbs and Spices Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Herbs and Spices Market by Segments
Herbs and Spices Market segmented by Product Type:
- Spices
- Herbs
- Cumin
- Paprika (Hot Pepper)
Herbs and Spices Market segmented by End-Use:
- Food
- Food Service
- Retail
- Processed Food
- Snacks & Savory Products
- Beverage
- Bakery and Confectionery
- Flavored/Infused Oils
Herbs and Spices Market segmented by Form:
- Powder & Granules
- Flakes
- Paste
- Whole/Fresh
Herbs and Spices Market segmented by Sales Channel:
- Direct
- Indirect
- Store-based Retailing
- Hypermarket/Supermarket
- Traditional Grocery Retailers
- Convenience Stores
- Online Retail
- Food & Drink Specialty Stores
Herbs and Spices Market segmented by Nature:
- Conventional
- Natural
- Vegan
- Non-GMO
- Organic
Herbs and Spices Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- USA Department of Agriculture, Economic Research Service. (2026, April 8). USA Food Imports
- Department for Environment, Food & Rural Affairs. (2026, April 30). UK trade in Food, Feed and Drink, 2025 provisional
- dsm-firmenich. (2025, December 5). dsm-firmenich names "Frosted Star Anise" as Flavor of the Year 2026, capturing a global desire for warmth and freshness
- Kerry Group plc. (2026, January 14). Kerry Releases 2026 Global Taste Charts: Defining the Future of Flavour with Data-Rich Insights
- dsm-firmenich. (2025, June 4). dsm-firmenich breaks ground on new state-of-the-art production facility for the development of flavors and functional blends in Parma, Italy
- Kalsec, Inc. (2026). About Us | Kalsec
- McCormick & Company, Incorporated. (2026, March 24). Black Currant Moves from Trend to Table as McCormick® Launches 2026 Flavor of the Year Products and an Immersive Flavor Experience
- USA Food and Drug Administration. (2025, December 10). More Ground Cinnamon Products Added to FDA Public Health Alert Due to Presence of Elevated Levels of Lead
- Symrise AG. (2026, May 13). Symrise opens Northwest Arkansas Food Studio: expanding customer collaboration & culinary innovation in North America
- USA Food and Drug Administration. (2026, March 5). Import Alert 28-02
- National Bureau of Agricultural Commodity and Food Standards, Thailand. (2025, April 22). Pesticide Residues: Maximum Residue Limits (TAS 9002-2568)
- Federal Office of Consumer Protection and Food Safety, Germany. (2025). Jahresbericht Lebensmittelbestrahlung 2024
- Ministry of Health, Labour and Welfare, Japan. (2025, December 22).
- Food Standards Agency. (2026, July 23). UK National Monitoring Plan (NMP) sampling priorities for imported foods: 2026/2027
- McCormick & Company, Incorporated. (2026, January 22). Form 10-K for the fiscal year ended November 30, 2025
- International Flavors & Fragrances Inc. (2025, July 10). IFF Expands Innovation Center in Singapore with New Immersive Experience Hub
- Givaudan SA. (2025, October 8). Givaudan Taste & Wellbeing breaks ground on new production facility near Cincinnati, Ohio
- ofi. (2025, December 16). ofi launches first spices sustainability strategy as demand for plant-based ingredients accelerates
- dsm-firmenich. (2025, August 26). dsm-firmenich unveils major plant investments, emphasizing commitment to shaping the future of flavor in India
- Symrise AG. (2026, April 30). Building Bridges: Symrise strengthens Food & Beverage capabilities in Barcelona and shortens distances
- Kalsec, Inc. (2026, July 27). Kalsec Celebrates Opening of New Spice Processing Center
- McCormick & Company, Incorporated. (2026, July 16). From Herbs to Hot Sauce: McCormick & Company Scales Post-Consumer Recycled Packaging Worldwide
- International Flavors & Fragrances Inc. (2026, May 11). IFF opens Vanilla Innovation Center in Madagascar
- Givaudan SA. (2026, July 3). Givaudan inaugurates new production facility in Indonesia
- Kerry Group plc. (2025, December 10). Kerry Signs Strategic Agreement with Expo City Dubai to Establish New Regional Customer Co-Creation Centre to Drive Food & Beverage Innovation
- International Flavors & Fragrances Inc. (2026, February 27). 2025 Annual Report
- Kerry Group plc. (2026). Annual Report 2025
- dsm-firmenich. (2026). The year in review - dsm-firmenich Integrated Annual Report 2025
- ofi. (2026). Learn About Our Food Safety Certifications | ofi
- Ministry of Food and Drug Safety, Republic of Korea. (2025, October 13). Import food information alert: Inspection notice for Indonesian spices.
- Ministry of Agriculture and Environment, Vietnam. (2025, September 9). Vietnam pepper breaks through, exports surpass 1 billion USD.
- USA Department of Agriculture, National Agricultural Statistics Service. (2025, December 10). USDA to Conduct 2025 Organic Survey.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- How large is the herbs and spices market in 2026 and 2036?
- Which operating conditions support commercial herb and spice demand?
- Why do spices account for 94.3% of product type revenue in 2026?
- Why does food hold 32.7% of end-use revenue in 2026?
- Why do powder & granules represent 52.1% of form revenue in 2026?
- How do profiled country growth rates compare through 2036?
- Which companies have direct spice-processing or seasoning exposure?
- What contamination and residue issues slow supplier qualification?
- Where can processors capture more value beyond undifferentiated crop supply?
Frequently Asked Questions
How big is the herbs and spices market in 2026?
The herbs and spices market is valued at USD 43.8 billion in 2026 and is projected to reach USD 75.7 billion by 2036. Broad food use and higher-value processing support expansion during the forecast period.
What is the CAGR of the herbs and spices market from 2026 to 2036?
The herbs and spices market is projected to grow at a CAGR of 5.6% between 2026 and 2036. Repeat food-manufacturing demand and qualified ingredients with stable sensory specifications support expansion during the ten-year forecast period.
Which product type leads the herbs and spices market?
The spices segment is expected to hold 94.3% of the herbs and spices market in 2026, attributable to broad use of pepper, paprika, cumin, and related seasonings. Dried processing gives food manufacturers repeatable handling and specifications for high-volume recipes.
Which form leads the herbs and spices market?
The powder & granules segment is projected to represent 52.1% of the herbs and spices market in 2026, driven by controlled dosing and easier storage. Dry formats also fit high-throughput blending lines used for standardized seasoning recipes.
How much value will the herbs and spices market add between 2026 and 2036?
The herbs and spices market is expected to add USD 78.3 billion in value between 2026 and 2036. Higher-value processing and broader food applications account for much of the modeled expansion during this ten-year period.
Which countries are projected to record the highest growth in the herbs and spices market?
USA is projected to grow at 4.6% CAGR, followed by Thailand at 4.2% and Germany at 3.9% through 2036. Food-processing depth and qualification costs account for part of the difference between the profiled country rates.
Which companies are active in the herbs and spices market?
Key companies operating in the herbs and spices market include McCormick & Company, Incorporated, ofi, International Flavors & Fragrances Inc., Givaudan SA, Symrise AG, Kerry Group plc, dsm-firmenich AG, and Kalsec, Inc. They differ in crop access, processing depth, regional application support, and direct spice-processing control.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Spices
- Herbs
- Cumin
- Paprila (Hot Pepper)
- Spices
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use, 2026 to 2036
- Food
- Food Service
- Retail
- Processed Food
- Snacks & Savory Products
- Beverage
- Bakery and Confectionery
- Flavored/Infused Oils
- Food
- Y-o-Y Growth Trend Analysis By End-Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Powder & Granules
- Flakes
- Paste
- Whole/Fresh
- Powder & Granules
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Direct
- Indirect
- Store-based Retailing
- Hypermarket/Supermarket
- Traditional Grocery Retailers
- Convenience Stores
- Online Retail
- Food & Drink Specilaty Stores
- Direct
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Natural
- Vegan
- Non-GMO
- Organic
- Conventional
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End-Use
- By Form
- By Sales Channel
- By Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Corbion N.V.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Balchem Corporation
- Sensient Technologies Corporation
- International Flavors & Fragrances Inc.
- Novozymes A/S
- FrieslandCampina Ingredients
- Ingredion Incorporated
- Symrise AG
- Corbion N.V.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


