
- Market Size (2026)
- USD 20.7 Bn
- Forecast (2036)
- USD 40.3 Bn
- CAGR (2026 to 2036)
- 6.9%
How big is Intercity Bus Travel Market in 2026?
Starting from USD 19.4 billion in 2025, the intercity bus travel market valuation advanced to USD 20.7 billion in 2026, with projections pointing toward USD 40.3 billion by 2036 at a CAGR of 6.9%.
Short-haul airfare inflation and highway toll expenses are pushing regional commuters and leisure travelers to substitute private car trips with app-dispatched luxury coaches, lifting global intercity bus travel market value from USD 19.4 billion in 2025 to USD 20.7 billion in 2026. Future Market Insights estimates that category valuation will climb to USD 40.3 billion by 2036 at a 6.9% CAGR across trunk highway corridors. Dynamic yield pricing and reserved reclining berths now beat regional rail and budget airfares on 150-to-500-kilometer corridors. Sleeper and semi-sleeper luxury coaches hold 34.7% of coach configuration demand in 2026 because wide 2+1 reclining cabins let operators charge higher fares while integrating transit ticketing systems for priority boarding. Per a September 2026 Flix SE operational disclosure, global network ridership reached 99 million passengers across more than 40 countries in 2025 as its fleet in India approached 400 buses across 330 cities [1]. At the same time, fleet operators are adopting mobile battery scheduling because a January 2026 PLoS One study proved that mobile battery pack deployment cuts electric bus vehicle usage costs by 8.11% and battery degradation expenses by 21.06% [2]. FMI sector analysis indicates that category expansion nevertheless faces strict operational gates from highway depot megawatt charger queues and commercial coach driver hour caps.
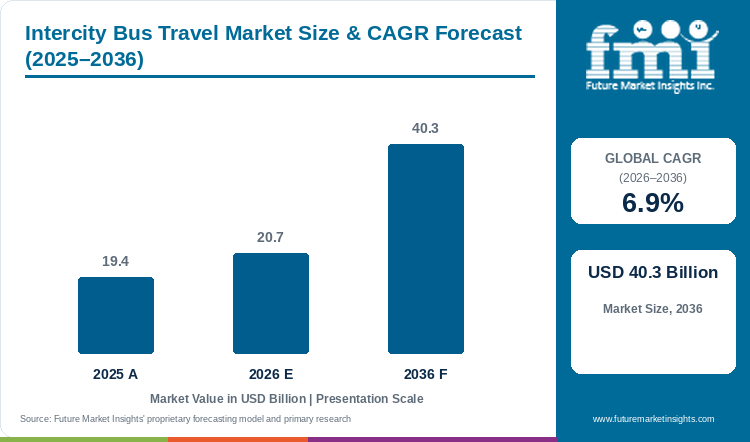
Key Market Trends & Insights
- By coach configuration: Sleeper and semi-sleeper luxury coaches hold an estimated 34.7% share in 2026 because 140-to-180-degree reclining cabins let operators charge premium overnight fares on 400-to-900-kilometer trunk routes.
- By booking channel: Online aggregator apps and digital portals represent 58.2% in 2026 as real-time load-factor algorithms and mobile QR boarding passes replace physical station ticket windows.
- By service model: Scheduled intercity line-haul accounts for 71.4% in 2026 because fixed-timetable city-center and suburban park-and-ride connections anchor year-round commuter and student ridership.
- By powertrain: Clean Euro-VI diesel and RNG coaches secure 78.6% in 2026 owing to 800-to-1,100-kilometer single-fill highway range and rapid refueling across interstate turnpikes.
- By party size: Couples and dual-traveler bookings command 45.9% in 2026 through bundled companion seating discounts and weekend leisure city-pair promotions.
Regional Highlights
- Top national expansion: India tops national coach growth at an 8.2% CAGR through 2036 while Brazil tracks at 7.8% under asset-light aggregator expansion and overnight sleeper coach upgrades.
- Broader country progression: Mexico advances at a 7.4% CAGR ahead of Germany at 7.2% and Spain at 7.0%. France records 6.8% while the United Kingdom posts 6.6% and the United States reaches 6.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Intercity Bus Travel Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 19.4 billion |
| Estimated Market Size in 2026 | USD 20.7 billion |
| Projected Market Size by 2036 | USD 40.3 billion |
| CAGR, 2026 to 2036 | 6.9% |
| Added Market Value, 2026 to 2036 | USD 19.6 billion |
Route profit per coach departure depends heavily on keeping seat load factors above 70% while curbing highway diesel burn across secondary city pairs. When operators run half-empty 50-seat buses on fixed timetables, fuel and terminal gate fees quickly erode route margins. To solve this utilization gap, carriers deploy open-loop contactless ticketing and automated fare buckets that discount off-peak seats early and raise walk-up prices as departure nears. Fuel procurement math also favors near-term hybrid and renewable-fuel coaches over unsubsidized all-electric chassis on long highway runs. According to a September 2025 iScience lifecycle assessment, conventional diesel buses emit 0.12 kilograms of carbon dioxide per passenger-kilometer while combining hybrid and electric fleets cuts diesel consumption by 59% and lifecycle emissions by 45% [3].
Fleet Seat-Kilometer and Route Yield Sizing
Table 2: Fleet Seat-Kilometer and Route Yield Sizing for the Intercity Bus Travel Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 19.4 | 20.7 | 40.3 |
| Scheduled intercity passenger volume (billion trips) | 1.42 to 1.56 | 1.50 to 1.65 | 2.65 to 2.92 |
| Active intercity line-haul motorcoaches (thousand units) | 168.0 to 182.0 | 176.0 to 191.0 | 285.0 to 312.0 |
| Average ticket yield per passenger trip (USD) | 12.4 to 13.7 | 12.6 to 13.8 | 13.8 to 15.2 |
Operational note: Seat-kilometer ranges reflect scheduled intercity line-haul and airport express motorcoaches operating routes exceeding 80 kilometers with 36 to 78 seats per vehicle.
High chassis acquisition costs and maintenance garage overhead have historically restricted how fast traditional bus companies can enter new intercity corridors. Asset-light mobility platforms overcome this capital barrier by handling consumer app marketing and dynamic route scheduling while contracting bus operations to regional family-owned fleet partners. Under revenue-sharing agreements, local fleet owners focus on driver retention and vehicle uptime while deploying battery-electric bus fleets on high-frequency 150-to-250-kilometer shuttle corridors where overnight depot charging is assured.
Per Capita & Commercial Coach Fleet Sizing
Table 3: Per Capita and Active Motorcoach Yield Indicators for the Intercity Bus Travel Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual market value per capita (USD) | 2.37 | 2.49 | 4.48 |
| Annual ticket value per active coach (USD thousand) | 106.6 to 115.5 | 108.4 to 117.6 | 129.2 to 141.4 |
| Digital app & portal booking share (%) | 55.8% to 57.4% | 57.5% to 59.0% | 71.0% to 74.5% |
Table 4: Operator Fleet & Channel Allocation Indicators for the Intercity Bus Travel Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 20.7 billion | 2026 global market valuation baseline |
| Scheduled Intercity Line-Haul allocation, 2026 | USD 14.8 billion | 71.4% service model share |
| Online Aggregator Apps & Portals allocation, 2026 | USD 12.0 billion | 58.2% booking channel share |
| Sleeper & Semi-Sleeper Luxury Coaches value, 2026 | USD 7.2 billion | 34.7% coach configuration share |
Solo highway motorists and budget rail passengers switch to repeat coach travel once operators eliminate downtown terminal congestion and slow curb-side baggage loading. Travelers frequently abandon intercity buses when inner-city traffic adds forty minutes to scheduled arrival times. To speed up turnarounds, regional transit authorities now co-locate coach bays with suburban rail stations and deploy electric low-entry buses so intercity passengers step directly onto metropolitan feeder lines.
Analyst Perspective
"Intercity coach operators no longer compete merely as the cheapest fallback for travelers without cars. By pairing airline-style dynamic fare buckets with 2+1 reclining sleeper cabins and suburban park-and-ride stops, asset-light platforms capture high-margin leisure and bleisure riders directly from short-haul rail and domestic airlines."
- Ronak Shah, Principal Consultant, Future Market Insights.
How is the intercity bus travel market segmented?
The intercity bus travel market is segmented by coach configuration, booking channel, service model, powertrain, and party size. In 2026, Sleeper and Semi-Sleeper Luxury Coaches reach 34.7%, Online Aggregator Apps and Digital Portals 58.2%, Scheduled Intercity Line-Haul 71.4%, Clean Euro-VI Diesel and RNG Coaches 78.6%, and Couples and Dual-Traveler Bookings 45.9%.
By coach configuration: Sleeper and Semi-Sleeper Luxury Coaches, Standard Express Single-Deck Coaches, and High-Capacity Double-Deck Intercity Coaches.
By booking channel: Online Aggregator Apps and Digital Portals, and Terminal Ticket Counters and Kiosks.
By service model: Scheduled Intercity Line-Haul, and Airport Shuttle and University Express Corridors.
By powertrain: Clean Euro-VI Diesel and RNG Coaches, and Battery-Electric and Fuel-Cell Intercity Coaches.
By party size: Couples and Dual-Traveler Bookings, Multi-Person Families and Private Groups, and Solo Independent Consumers.
Why do Sleeper and Semi-Sleeper Luxury Coaches lead the coach configuration category?
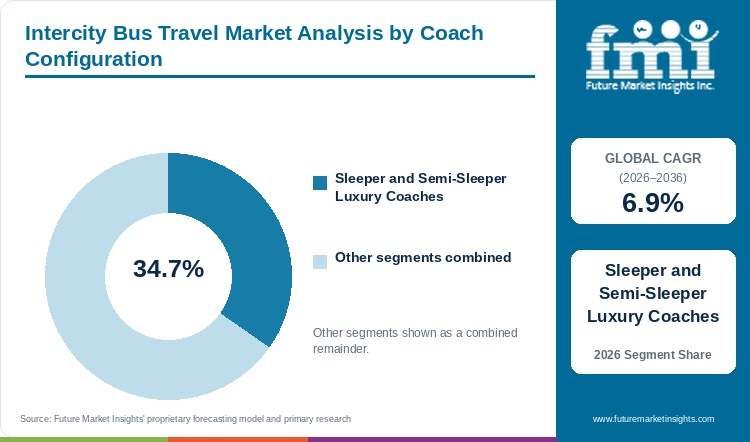
Sleeper and Semi-Sleeper Luxury Coaches hold 34.7% of coach configuration demand in 2026 through premium overnight berth yields.
Table 5: Coach Configuration Share for the Intercity Bus Travel Market (percentage share), 2026
| Coach Configuration | Share (2026) |
|---|---|
| Sleeper and Semi-Sleeper Luxury Coaches | 34.7% |
| Other Segments Combined | 65.3%* |
| Total | 100.0% |
*Note: Remaining coach configuration categories account for the balance of 2026 global intercity bus travel demand.
Table 6: Coach Configuration Leadership and Market Growth for the Intercity Bus Travel Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 6.9% |
| Leading Segment | Sleeper and Semi-Sleeper Luxury Coaches |
Sleeper and semi-sleeper luxury coaches equipped with 2+1 wide leather recliners and enclosed lie-flat berths allow operators to command 35% to 60% ticket premiums over standard 49-seat coaches while linking with autonomous transit shuttles at terminal hubs.
- Sleeper and Semi-Sleeper Luxury Coaches hold 34.7% of coach configuration value in 2026 because overnight departures save travelers one hotel night on 500-to-1,000-kilometer journeys.
- A March 2026 Scientific Reports study of 1,318 bus passengers found that seated riders estimate cabin crowding at a median 25% versus 45% among standing riders, explaining why guaranteed berth reservations command higher ticket yields [4].
What sustains Online Aggregator Apps and Digital Portals leadership in the booking channel segment?
Online Aggregator Apps and Digital Portals represent 58.2% of booking channel demand in 2026 through dynamic mobile pricing.
Mobile ticketing apps and multi-carrier web portals consolidate fragmented regional bus operators into unified search engines with live GPS coach tracking and instant seat selection with airport ground shuttle services.
- Online Aggregator Apps and Digital Portals represent 58.2% of the booking channel segment in 2026 as dynamic early-bird fare tiers and mobile wallet checkouts shift travelers away from cash station booths.
- BlaBlaCar reported in September 2025 that monthly passenger volume in India reached 2 million riders in August 2025 with 95% of intercity bookings completed on mobile devices [5].
How does Scheduled Intercity Line-Haul lead the service model category?
Scheduled Intercity Line-Haul accounts for 71.4% of service model volume in 2026 through fixed-timetable trunk highway connections.
Fixed-route scheduled line-haul networks connect primary metropolitan terminals and secondary highway towns on clock-face departures, requiring heavy-duty coach suspension bearing components to sustain 180,000-kilometer annual chassis utilization.
- Scheduled Intercity Line-Haul accounts for 71.4% of service model demand in 2026 because multi-stop trunk corridors pool point-to-point and intermediate town passengers into high-load-factor departures.
- A June 2026 PLoS One hub-routing optimization study demonstrated that coordinating multi-station passenger demand across trunk transit hubs reduces combined passenger and operator travel costs by 2.7% [6].
Why do Clean Euro-VI Diesel and RNG Coaches lead the powertrain category?
Clean Euro-VI Diesel and RNG Coaches secure 78.6% of powertrain value in 2026 through long single-fill highway range.
High-torque Euro-VI diesel and compressed biomethane engines dominate long-distance highway rosters because intercity coaches require 800-kilometer continuous range with heavy under-floor baggage loads and full cabin air conditioning.
- Clean Euro-VI Diesel and RNG Coaches secure 78.6% of powertrain demand in 2026 as hydrotreated vegetable oil and renewable natural gas drop-in fuels let fleets cut emissions without waiting for highway megawatt chargers.
- Busworld Europe reported in October 2025 that Solaris is developing 10.8-meter to 13.1-meter intercity buses with 260 to 620 kilowatt-hour battery packs for 2026 launch, while diesel and RNG coaches still carry the bulk of routes over 600 kilometers [7].
What gives Couples and Dual-Traveler Bookings the leading position in party size?
Couples and Dual-Traveler Bookings command 45.9% of party size value in 2026 through companion leisure seat bundles.
Weekend city-break couples and two-person travel companions represent the highest-yielding passenger cohort for intercity coach platforms because dual bookings pre-select adjacent panoramic or twin-recliner seats weeks before departure.
- Couples and Dual-Traveler Bookings command 45.9% of party size value in 2026 because companion fare bundles and reserved two-seat lounge rows convert price-sensitive leisure pairs from domestic rail.
- Mobico Group plc reported in February 2026 that its ALSA coach division achieved record double-digit full-year 2025 top-line growth in Spain through leisure companion passes and high-occupancy holiday corridors [8].
What are the drivers, restraints, and opportunities in the intercity bus travel market?
In the intercity bus travel market, short-haul rail and airfare inflation and mobile aggregator apps drive adoption whereas commercial driver shortages and sparse highway megawatt chargers restrain peak capacity and 2+1 sleeper cabins create yield opportunities.
- Driver: Higher domestic rail ticket prices and short-haul aviation carbon taxes push cost-conscious leisure and student travelers onto scheduled express coaches.
- Restraint: Severe commercial coach driver shortages across North America and Europe with sparse highway megawatt charging infrastructure constrain peak-season departure frequencies.
- Opportunity: Executive 2+1 sleeper coaches and suburban park-and-ride express stops with depot electric charging hubs unlock higher per-seat yields and B2B fleet monetization.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Short-haul airfare increases and congested intercity rail networks are compelling leisure travelers and university students to adopt app-booked express coaches across 150-to-600-kilometer corridors. Digital mobility platforms integrate intercity motorcoaches with intercity passenger railway systems through unified multimodal ticketing so passengers book single-itinerary connections to underserved towns. Per the European Commission Alternative Fuels Observatory in February 2026, the Netherlands allocated USD 0.011 billion in 2026 under its STour subsidy scheme for battery-electric M3 touring coaches and USD 0.003 billion for transit concession holders [9]. Operators that pair subsidized zero-emission coaches with dynamic mobile yield management capture sustained volume growth.
Risk Assessment of the Intercity Bus Travel Market: Operational and Fleet Friction
Chronic commercial D-license coach driver shortages and strict statutory driving-time limits represent the primary operational bottlenecks restraining capacity expansion across North United States and European trunk networks. Long-distance battery-electric coaches also face severe payload weight penalties and mid-route charging delays until highway rest areas deploy dedicated commercial fleet charging services for heavy M3 vehicles. A January 2025 PLoS One real-driving-cycle analysis across 570 kilometers showed that driving aggressiveness and highway gradient swings alter fuel and energy consumption by up to 39% across powertrain types [10]. Fleet directors mitigate range anxiety and driver overtime costs by staging driver relay swaps at intermediate highway hubs.
Commercial Opportunity Analysis: Fleet Differentiation and Value-Add Formats
Motorcoach operators unlock high-margin ancillary value by reconfiguring standard 55-seat coaches into 32-to-38-seat executive lounges with paid panoramic front-row seats and onboard Wi-Fi tiers. Long-haul carriers also test hydrogen fuel-cell commercial vehicles and shared B2B depot chargers to monetize off-peak electrical capacity across regional terminals. Stagecoach Group Limited showcased its Chargd B2B electric vehicle charging platform in July 2026 across 6 live UK bus depots including Cambridge and Oxford, with 9 additional depot hubs scheduled in 2026 [11]. Third-party commercial fleet charging paired with premium sleeper seat reservations insulates coach operators from base ticket fare wars.
Intercity Bus Travel Market by Country (2026 to 2036)
FMI country projections show India pacing intercity coach expansion at an 8.2% CAGR through 2036 ahead of Brazil at 7.8% and Mexico at 7.4%. Germany follows at 7.2% and Spain at 7.0%, while France registers 6.8% and the United Kingdom and United States record 6.6% and 6.5%.
Table 7: Country CAGR and Primary Growth Levers for the Intercity Bus Travel Market (CAGR percentage and operational drivers), 2026 to 2036
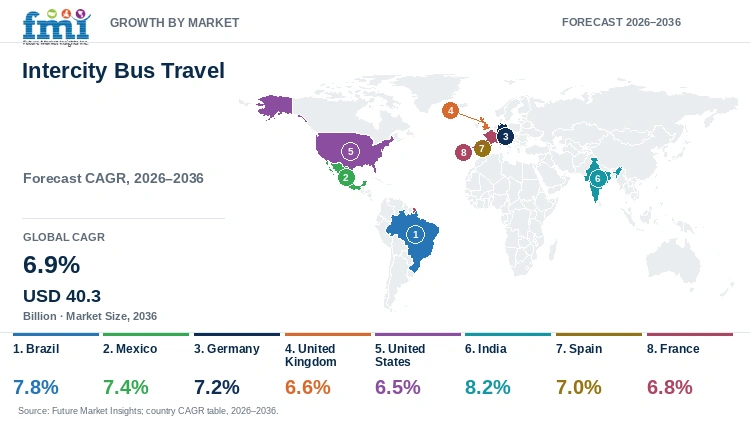
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Brazil | 7.8% | 180-degree double-deck Leito Cama sleeper fleets and ANTT digital app charter integration |
| Mexico | 7.4% | Nearshoring industrial corridor travel and luxury dedicated terminal lounges |
| Germany | 7.2% | Cross-border Schengen coach hubs and dynamic fare competition against delayed ICE rail |
| United Kingdom | 6.6% | High-frequency Heathrow, Gatwick, and university express corridors |
| United States | 6.5% | Curbside multimodal stop relocation and 2+1 business-class cabin upgrades |
| India | 8.2% | Access-controlled national expressways and organized AC sleeper fleet aggregation |
| Spain | 7.0% | Ministry corridor concessions and Supra-class coastal tourist coach services |
| France | 6.8% | Transverse non-Paris city pairs under Loi Macron and BioGNV coach deployments |
Source: Future Market Insights analysis
Brazil Intercity Bus Travel Market Outlook (2026 to 2036)
Continental highway distances and limited passenger rail coverage make Brazil the largest heavy double-deck sleeper coach market in Latin America. Regulatory authorization of open-charter and app-intermediated ticketing under ANTT rules allows digital platforms to challenge incumbent state road concessions across Sao Paulo and Rio de Janeiro as well as Minas Gerais. Per Transdev Group half-year operational disclosures in September 2026, South United States and global multi-modal networks carried 14 million daily passenger trips while generating USD 11.2 billion in group receipts [12]. Intercity bus travel market value in Brazil climbs at a 7.8% CAGR over 2026 to 2036 while operators deploy 180-degree Leito Cama sleeper decks to counter domestic airline fare inflation.
Key takeaway: In Brazil, 180-degree double-deck Leito Cama sleeper upgrades and digital app aggregation across ANTT interstate corridors drive sustained passenger yield expansion.
Mexico Intercity Bus Travel Market Outlook (2026 to 2036)
Whereas Brazil relies heavily on third-party digital charter apps, Mexico is anchored by vertically integrated terminal-owning motorcoach groups operating dedicated executive and luxury highway fleets. Industrial assembly plants across Monterrey and Queretaro as well as Guadalajara generate recurring bi-weekly workforce travel with strong domestic VFR and tourist corridors linking Mexico City to Cancun and Oaxaca. Mobico Group plc noted in its September 2026 trading update that long-distance coach demand remains resilient across core Hispanic and North United States corridors under disciplined fare indexing [13]. Intercity bus travel market valuation in Mexico rises at a 7.4% CAGR through 2036 as ADO Mobility Group and regional carriers expand digital wallet kiosks and loyalty tiers.
Key takeaway: In Mexico, industrial corridor workforce mobility and first-class terminal lounge differentiation sustain high load factors across private luxury motorcoach fleets.
Germany Intercity Bus Travel Market Outlook (2026 to 2036)
Since the liberalization of intercity coach routes beyond 50 kilometers, Germany has evolved into the central hub of asset-light European coach network scheduling. Price-sensitive leisure riders and cross-border travelers use long-distance coaches to bypass Deutsche Bahn engineering delays and high walk-up ICE rail fares even with the subsidized Deutschlandticket regional pass. According to Federal Statistical Office Destatis passenger transport records in April 2026, long-distance scheduled coach services remain a core pillar of intercity collective mobility across Germany-based federal states [14]. Intercity bus travel market size in Germany grows at a 7.2% CAGR between 2026 and 2036 while Flix SE upgrades cross-border hubs in Munich and Berlin as well as Frankfurt.
Key takeaway: In Germany, cross-border Schengen hub scheduling and dynamic yield management against delayed intercity rail services anchor steady long-distance coach expansion.
United Kingdom Intercity Bus Travel Market Outlook (2026 to 2036)
Unlike continental markets dominated by a single aggregator, the United Kingdom features intense corridor competition among National Express and FlixBus UK with Megabus and Scottish Citylink across airport and university routes. High walk-up rail fares and periodic rail industrial actions push Heathrow and Gatwick as well as Stansted airport transfers onto high-frequency scheduled coaches. On October 28, 2026, the Confederation of Passenger Transport UK warned that rising driver wage and fuel cost pressures require targeted fiscal support across scheduled bus and coach networks [15]. Scheduled coach market valuation in the United Kingdom advances at a 6.6% CAGR through 2036 as operators partner with regional fleets to add executive reclining seats.
Key takeaway: In the United Kingdom, dedicated airport transfer corridors and university express routes insulate scheduled coach operators from domestic rail volatility.
United States Intercity Bus Travel Market Outlook (2026 to 2036)
Downtown bus terminal closures in major metropolitan areas have forced United States intercity coach carriers to pivot toward curbside pickup zones and suburban park-and-ride lots with multimodal rail stations. Simultaneously, luxury single-deck cabin startups and FlixBus-integrated Greyhound schedules are recapturing Northeast Corridor and Texas Triangle intercity travelers from congested interstate highways. The U.S. Bureau of Transportation Statistics updated its national Intercity Bus Atlas in October 2026, mapping expanded scheduled intercity route stops and rural feeder connections across all 50 states [16]. Scheduled intercity motorcoach market value across the United States advances at a 6.5% CAGR through 2036 under unified Greyhound and Trailways mobile booking and interline route integration.
Key takeaway: In the United States, curbside multimodal stop relocation and executive 2+1 business-class coach cabins revitalize corridor ridership across major city pairs.
India Intercity Bus Travel Market Outlook (2026 to 2036)
Rapid construction of access-controlled national expressways and widespread UPI mobile ticketing make India the fastest-growing intercity bus market globally. Private fleet operators and global asset-light platforms are replacing unorganized non-AC buses with multi-axle Volvo and Scania AC sleeper coaches across Delhi-Lucknow and Bengaluru-Hyderabad as well as Mumbai-Pune trunk corridors. An October 2026 BMJ Open stakeholder study on Indian public transportation documented that accessible boarding and reserved seating remain decisive facilitators for family and long-distance bus adoption [17]. Scheduled intercity motorcoach market valuation across India expands at a table-topping 8.2% CAGR over the ten-year period to 2036 while woman-only berth reservations and clean highway lounge stops boost middle-class ridership.
Key takeaway: In India, national expressway expansion and organized AC sleeper fleet aggregation drive rapid conversion from waitlisted overnight rail.
Spain Intercity Bus Travel Market Outlook (2026 to 2036)
Spain operates on a regulated national and regional corridor concession model under Ministerio de Transportes tenders that grant exclusive multi-year operating rights across radial and coastal routes. High tourism arrivals and mountainous northern and coastal geography where high-speed AVE rail does not reach sustain year-round demand for premium Supra-class coaches with wide leather seating. Flix SE documented in its April 2026 ESG Report that collective long-distance coach networks now connect more than 8,700 destinations across Iberian and European corridors with low per-passenger carbon intensity [18]. Scheduled coach industry valuation in Spain rises at a 7.0% ten-year CAGR to 2036 while national ministry concession renewals mandate biomethane and zero-emission touring coaches.
Key takeaway: In Spain, long-term ministry route concessions and Supra-class tourist coach cabins support high fleet utilization across non-rail coastal corridors.
France Intercity Bus Travel Market Outlook (2026 to 2036)
Following the Loi Macron liberalization of intercity coach routes over 100 kilometers, France consolidated around two primary digital coach networks in FlixBus and BlaBlaCar Bus operating with regional Car Express lines. Transverse routes connecting Lyon, Bordeaux and Toulouse as well as Nantes bypass the Paris-centric TGV high-speed rail star network and save passengers costly train station transfers. FirstGroup plc highlighted in its June 2026 Annual Report that contracted intercity coach operations and European partner fleet allocations provide stable multi-year returns under fixed-fee service agreements [19]. Intercity bus travel market size in France increases at a 6.8% CAGR through 2036 as operators add BioGNV renewable gas coaches to meet low-emission zone rules.
Key takeaway: In France, direct transverse city-pair routing that bypasses Paris rail terminals and BioGNV fleet upgrades sustain intercity coach demand.
Full report country CAGRs cover North America and Latin America with Western Europe and Eastern Europe. Coverage also spans East Asia and South Asia and Pacific with Middle East and Africa.
Who are the notable companies in the intercity bus travel market?
Flix SE (FlixBus and Greyhound), Mobico Group plc (ALSA and National Express), Stagecoach Group Limited (Megabus), Transdev Group, FirstGroup plc, ADO Mobility Group, BlaBlaCar Bus, Trailways Transportation System, Keolis Group, and Irizar S. Coop. are the notable companies in the intercity bus travel market.
Commercial competition in the intercity bus travel sector separates asset-light digital network orchestrators and vertically integrated multi-country fleet operators from specialized regional motorcoach and chassis platforms. Asset-light aggregators control brand marketing and dynamic pricing with mobile ticketing while contracting bus operations to local SME fleet partners. Integrated transit groups own terminal real estate and maintenance depots with large motorcoach fleets across regulated and deregulated national corridors.
- Asset-Light Network Aggregators: Flix SE (FlixBus and Greyhound) and BlaBlaCar Bus as well as Trailways Transportation System orchestrate intercity route networks and dynamic mobile ticketing as well as cross-carrier revenue management.
- Integrated Multi-Modal Coach Operators: Mobico Group plc (ALSA and National Express), Stagecoach Group Limited (Megabus) and Transdev Group as well as FirstGroup plc operate scheduled line-haul and airport express as well as contracted fleet services.
- Regional Corridor & Coach Platforms: ADO Mobility Group and Keolis Group as well as Irizar S. Coop. anchor Latin United States luxury terminal networks and interurban concessions as well as electric/Euro-VI coach supply.
Competitive Benchmarking: Intercity Bus Travel Market
Table 8: Competitive Benchmarking for the Intercity Bus Travel Market (qualitative capability ratings), 2026
| Company | Network Route Density | Digital Yield & Ticketing | Fleet Decarbonization Fit | Geographic Reach |
|---|---|---|---|---|
| Flix SE (FlixBus & Greyhound) | High | High | High | 40+ countries across Europe, North America, Latin America, and India; 99M riders in 2025 |
| Mobico Group plc (ALSA & National Express) | High | High | High | Spain, UK, Morocco, and North America; record ALSA long-haul coach performance |
| Stagecoach Group Limited (Megabus) | High | High | High | UK intercity Megabus and Scottish Citylink corridors; launched Chargd EV depots in July 2026 |
| Transdev Group | High | Medium | High | 19 countries across Europe, Americas, and Oceania; 14M daily multi-modal passenger trips |
| FirstGroup plc | Medium | Medium | High | UK regional coach, airport express, and contracted FlixBus partner fleet operations |
| ADO Mobility Group | High | High | Medium | Mexico, Central America, and Iberia terminal-anchored luxury and executive coach networks |
| BlaBlaCar Bus | High | High | Medium | Western and Eastern Europe express coach network integrated with carpooling app |
| Trailways Transportation System | Medium | High | Medium | North American network of independent motorcoach carriers on unified digital ticketing |
| Keolis Group | High | Medium | High | France, North America, Australia, and European interurban coach and rail-bridge operations |
| Irizar S. Coop. | Medium | Medium | High | Global intercity luxury i6S/i8 coach OEM and zero-emission electric/hydrogen transit platforms |
Scoring basis: Network Route Density evaluates cross-border and multi-state city-pair coverage. Digital Yield & Ticketing assesses proprietary mobile app share and dynamic seat pricing, while Fleet Decarbonization Fit reflects verified electric, hybrid and RNG as well as B2B depot charger deployments.
Key Developments in the Intercity Bus Travel Market
- The U.S. Surface Transportation Board published a Federal Register notice on October 29, 2026 regarding TBL Group Inc. acquiring control of interstate passenger carrier Horizon Motor Coach Inc. to expand North United States motorcoach operations [20].
- Coach UK and the Confederation of Passenger Transport issued an industry policy assessment on October 28, 2026 calling for targeted coach terminal and fuel-duty support across United Kingdom intercity and touring fleets [21].
- The Transportation Choices Coalition published its 2026 Washington State intercity bus expansion review on January 6, 2026 detailing new rural-to-urban feeder coach connections across Pacific Northwest corridors [22].
Key Players in the Intercity Bus Travel Market
Asset-Light Network Aggregators
- Flix SE (FlixBus & Greyhound)
- BlaBlaCar Bus
- Trailways Transportation System
- ADO Mobility Group
Integrated Multi-Modal Coach Operators
- Mobico Group plc (ALSA & National Express)
- Stagecoach Group Limited (Megabus)
- Transdev Group
- FirstGroup plc
Regional Corridor & Coach Platforms
- Keolis Group
- Irizar S. Coop.
Intercity Bus Travel Market - Report Scope
Table 9: Report Scope for the Intercity Bus Travel Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Coach Configuration, Booking Channel, Service Model, Powertrain, and Party Size |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial passenger ticket value and ancillary seat/baggage fees from scheduled intercity line-haul motorcoaches, airport express shuttles, and university corridor buses operating routes exceeding 80 kilometers. Excludes intracity municipal transit buses, school buses, and private corporate employee shuttles. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Brazil, Mexico, Germany, United Kingdom, United States, India, Spain, France, and additional countries in the full report |
| Key Companies Covered | Flix SE, Mobico Group plc, Stagecoach Group Limited, Transdev Group, FirstGroup plc, ADO Mobility Group, BlaBlaCar Bus, Trailways Transportation System, Keolis Group, and Irizar S. Coop. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Intercity Bus Travel Market - Research Methodology
Table 10: Research Methodology for the Intercity Bus Travel Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with intercity coach network planners, asset-light aggregator revenue managers, terminal operations directors, and motorcoach fleet procurement officers across North America, Europe, Latin America, and India. |
| Secondary Research | Analysis of U.S. DOT Bureau of Transportation Statistics Intercity Bus Atlas records, UK Department for Transport bus statistics, Destatis Germany passenger registries, European Commission Alternative Fuels Observatory releases, and corporate filings. |
| Market Sizing and Forecasting | Top-down collective passenger transport baselines reconciled against bottom-up active intercity motorcoach fleets (176,000 to 191,000 units in 2026), annual seat-kilometers, and average fare yields from 2026 to 2036. |
| Country Forecasting Model | Econometric country projections weight expressway additions, rail fare spread, airport shuttle volume, and digital aggregator penetration across eight core national markets. |
| Operational Benchmark Traceability | Seat-kilometer and fleet yield indicators in Tables 2, 3, and 4 trace to Flix SE and Mobico Group plc ridership disclosures, PLoS One and iScience fleet cost studies, and American Bus Association census records. |
| Data Triangulation and Validation | Market value estimates isolate scheduled intercity and corridor express coach ticketing while strictly excluding urban municipal bus networks, private tour charters, and rail operations. |
Intercity Bus Travel Market by Segments
Intercity Bus Travel Market segmented by Coach Configuration:
- Sleeper and Semi-Sleeper Luxury Coaches
- Standard Express Single-Deck Coaches
- High-Capacity Double-Deck Intercity Coaches
- Executive 2+1 Business-Class Lounge Coaches
- Accessible Lift-Equipped Intercity Coaches
Intercity Bus Travel Market segmented by Booking Channel:
- Online Aggregator Apps and Digital Portals
- Terminal Ticket Counters and Kiosks
- Corporate Travel Portals and GDS Integrations
- Onboard Contactless and Curbside QR Ticketing
Intercity Bus Travel Market segmented by Service Model:
- Scheduled Intercity Line-Haul
- Airport Shuttle and University Express Corridors
- Cross-Border International Trunk Routes
- Rural Feeder and Rail-Bridge Coach Connections
Intercity Bus Travel Market segmented by Powertrain:
- Clean Euro-VI Diesel and RNG Coaches
- Battery-Electric and Fuel-Cell Intercity Coaches
- Series and Parallel Hybrid Express Coaches
- Hydrotreated Vegetable Oil (HVO) Biofuel Coaches
Intercity Bus Travel Market segmented by Party Size:
- Couples and Dual-Traveler Bookings
- Multi-Person Families and Private Groups
- Solo Independent Consumers
- Student and Senior Concessionary Travelers
Intercity Bus Travel Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Flix SE. (2026, September 28). FlixBus India Approaches 400-Bus Fleet as Network Spans 330+ Cities Across 14 States. Flix SE Corporate Newsroom.
- [2] Chen, S., Chang, A., & Cong, Y. (2026, January 2). Optimization of urban and rural electric bus scheduling considering mobile battery pack deployment. PLoS One, 21(1), e0339387 (PubMed PMID 41481563).
- [3] Arabi, M., Oke, T., Baker, E., & Oke, J. (2025, September 13). Harnessing hybrid buses in the near term leads to faster transit decarbonization. iScience, 28(10), 113567 (PubMed PMID 41079631).
- [4] Kovacevic, T., Pitka, P., Ivetic, J., Dedeic, J., Milicic, M., & Majstorovic, M. (2026, March 13). Passenger perception of vehicle occupancy in public transport and factors that shape crowding estimations. Scientific Reports, 16, 13437 (PubMed PMID 41826619).
- [5] BlaBlaCar. (2025, September 4). Carpooling: India Becomes BlaBlaCar's Largest Market as Shared Mobility Accelerates. BlaBlaCar Newsroom.
- [6] Wang, Y. (2026, June 15). Research on optimization of train routing problem for railway hubs considering passenger demand. PLoS One, 21(6), e0351229 (PubMed PMID 42296155).
- [7] Busworld Europe. (2025, October 8). Solaris Has Plans for an Intercity Bus Platform Equipped With 260 to 620 kWh Battery Packs for 2026 Launch. Busworld Europe Foundation.
- [8] Mobico Group plc. (2026, February 25). Mobico Group plc Full Year Results for the Twelve Months Ended 31 December 2025. Mobico Group plc Investor Relations.
- [9] European Commission Alternative Fuels Observatory. (2026, February 3). Dutch Subsidies for Heavy EV Charging, Zero-Emission Trucks and Touring Coaches. European Commission Directorate-General for Mobility and Transport.
- [10] Bagheri, E., Masih Tehrani, M., Azadi, M., & Moosavian, A. (2025, January 13). Impact of driving characteristic parameters and vehicle type on fuel consumption and emissions performance over real driving cycles. PLoS One, 20(1), e0317098 (PubMed PMID 39804898).
- [11] Stagecoach Group Limited. (2026, July 15). Stagecoach Showcases Chargd in Action at Launch Event as Nationwide Rollout Accelerates. Stagecoach Group Media Centre.
- [12] Transdev Group. (2026, September 18). Transdev Group 2026 Half-Year Financial and Operational Results Across Global Mobility Networks. Transdev Group Press Room.
- [13] Mobico Group plc. (2026, September 8). Mobico Group plc Q2 2026 Trading Update and North America and ALSA Coach Operations Review. Mobico Group plc Media Releases.
- [14] Statistisches Bundesamt (Destatis). (2026, April 14). Passenger Transport by Regular Short-Distance and Long-Distance Bus and Coach Services in Germany. Federal Statistical Office of Germany (Destatis).
- [15] Confederation of Passenger Transport UK. (2026, October 28). Budget Fails to Ease Mounting Pressure on Bus and Coach Services, Warns CPT. Confederation of Passenger Transport UK.
- [16] U.S. Department of Transportation, Bureau of Transportation Statistics. (2026, October 27). Intercity Bus Atlas: Scheduled Intercity Bus Service Routes, Stops, and Frequencies in the United States. U.S. Bureau of Transportation Statistics.
- [17] Samuel, R., et al. (2026, October 5). Navigating the ride: stakeholder perspectives on public transportation challenges and accessibility in India. BMJ Open, 16(10), e094112 (PubMed PMID 42833718).
- [18] Flix SE. (2026, April 22). Flix SE 2025 ESG Report: Decarbonizing Long-Distance Collective Coach Mobility Across 8,700 Destinations. Flix SE Sustainability Publications.
- [19] FirstGroup plc. (2026, June 17). FirstGroup plc Annual Report and Accounts 2026: Regional Coach, Open-Access Rail, and FlixBus Partnerships. FirstGroup plc Investor Relations.
- [20] U.S. Surface Transportation Board. (2026, October 29). TBL Group, Inc. Acquisition of Control of Interstate Motor Passenger Carrier Horizon Motor Coach, Inc.. Federal Register, 91(209), 2026-22035.
- [21] Coach UK, Confederation of Passenger Transport. (2026, October 28). Coach UK Analysis of Scheduled and Touring Motorcoach Infrastructure and Fiscal Policy Requirements. Confederation of Passenger Transport UK.
- [22] Transportation Choices Coalition. (2026, January 6). Intercity Bus Service for a More Connected Washington: 2026 Feeder Network Expansion. Transportation Choices Coalition.
- [23] Transport Scotland. (2025, April 1). National Concessionary Travel Scheme Operator Reimbursement Rates and Scheduled Coach Eligibility 2025-2026. Scottish Government Transport Scotland.
- [24] International Road Transport Union (IRU). (2025, November 6). European Coach Driver Shortage Report and Long-Distance Passenger Transport Driving-Time Rules. International Road Transport Union.
- [25] FirstGroup plc. (2025, June 10). FirstGroup plc Full Year Results for the 52 Weeks Ended 29 March 2025. FirstGroup plc Regulatory News.
- [26] Transport Research Board, National Academies. (2025, May 19). Rural and Intercity Bus Transit Network Connectivity and Federal Section 5311(f) Feeder Program Performance. National Academies Press.
- [27] Federal Transit Administration. (2025, August 12). Formula Grants for Rural Areas and Intercity Bus Consultation Requirements Under 49 U.S.C. 5311(f). U.S. Department of Transportation Federal Transit Administration.
- [28] Iowa Department of Transportation. (2025, November 12). CY26 InterCity Bus Program Assistance and Regional Feeder Route Restructuring Guidelines. Iowa Department of Transportation.
- [29] Kim, H., & Lee, S. (2026, January 20). When less travel means more carbon: How rainfall-induced shifts from public transit to cars increase transport emissions. Science of the Total Environment, 1013, 181269 (PubMed PMID 41456516).
- [30] Tadesse, M., et al. (2026, January 15). Assessment of airborne infection risk and ventilation air exchange rates in high-occupancy bus and rail transport. Science of the Total Environment, 1012, 181254 (PubMed PMID 41435582).
- [31] Schwanen, T., et al. (2025, October 31). Cognitive co-ageing with inequitable political ecologies: Deconditioning and collective public transport access. Social Science & Medicine, 388, 118727 (PubMed PMID 41192217).
- [32] Al-garadi, M. A., et al. (2026, June 4). Quantum federated learning for autonomous and connected commercial vehicle cybersecurity. MethodsX, 13, 103412 (PubMed PMID 42292860).
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the intercity bus travel market in 2026 and what is forecast for 2036?
- Which modal substitution and dynamic ticketing catalysts support demand for intercity bus travel?
- Why do Sleeper and Semi-Sleeper Luxury Coaches lead the coach configuration category?
- Why do Online Aggregator Apps and Digital Portals lead the booking channel category?
- How do growth rates differ across India, Brazil, Mexico, Germany, the UK, and the USA?
- Which leading companies operate asset-light digital coach networks versus integrated fleets today?
- What limits battery-electric coach deployment and peak-season frequency in the intercity bus travel market?
- What should fleet operators evaluate before upgrading corridors to 2+1 sleeper cabins or depot EV charging?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Coach Configuration, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Coach Configuration, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Coach Configuration, 2026 to 2036
- Sleeper and Semi-Sleeper Luxury Coaches
- Standard Express Single-Deck Coaches
- High-Capacity Double-Deck Intercity Coaches
- Executive 2+1 Business-Class Lounge Coaches
- Accessible Lift-Equipped Intercity Coaches
- Y-o-Y Growth Trend Analysis By Coach Configuration, 2021 to 2025
- Absolute $ Opportunity Analysis By Coach Configuration, 2026 to 2036
- Global Market Analysis and Forecast, By Booking Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Booking Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Booking Channel, 2026 to 2036
- Online Aggregator Apps and Digital Portals
- Terminal Ticket Counters and Kiosks
- Corporate Travel Portals and GDS Integrations
- Onboard Contactless and Curbside QR Ticketing
- Y-o-Y Growth Trend Analysis By Booking Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Booking Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Service Model, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Model, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Model, 2026 to 2036
- Scheduled Intercity Line-Haul
- Airport Shuttle and University Express Corridors
- Cross-Border International Trunk Routes
- Rural Feeder and Rail-Bridge Coach Connections
- Y-o-Y Growth Trend Analysis By Service Model, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Model, 2026 to 2036
- Global Market Analysis and Forecast, By Powertrain, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Powertrain, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Powertrain, 2026 to 2036
- Clean Euro-VI Diesel and RNG Coaches
- Battery-Electric and Fuel-Cell Intercity Coaches
- Series and Parallel Hybrid Express Coaches
- Hydrotreated Vegetable Oil (HVO) Biofuel Coaches
- Y-o-Y Growth Trend Analysis By Powertrain, 2021 to 2025
- Absolute $ Opportunity Analysis By Powertrain, 2026 to 2036
- Global Market Analysis and Forecast, By Party Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Party Size, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Party Size, 2026 to 2036
- Couples and Dual-Traveler Bookings
- Multi-Person Families and Private Groups
- Solo Independent Consumers
- Student and Senior Concessionary Travelers
- Y-o-Y Growth Trend Analysis By Party Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Party Size, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- By Country
- Market Attractiveness Analysis
- By Country
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Coach Configuration
- By Booking Channel
- By Service Model
- By Powertrain
- By Party Size
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Flix SE (FlixBus & Greyhound)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mobico Group plc (ALSA & National Express)
- Stagecoach Group Limited (Megabus)
- Transdev Group
- FirstGroup plc
- ADO Mobility Group
- BlaBlaCar Bus
- Trailways Transportation System
- Keolis Group
- Irizar S. Coop.
- Flix SE (FlixBus & Greyhound)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Coach Configuration, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Booking Channel, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Service Model, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Powertrain, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Party Size, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Coach Configuration
- Figure 6: Global Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Booking Channel
- Figure 9: Global Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Service Model
- Figure 12: Global Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Powertrain
- Figure 15: Global Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Party Size
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Coach Configuration
- Figure 32: North America Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Booking Channel
- Figure 35: North America Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Service Model
- Figure 38: North America Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Powertrain
- Figure 41: North America Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Party Size
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Coach Configuration
- Figure 48: Latin America Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Booking Channel
- Figure 51: Latin America Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Service Model
- Figure 54: Latin America Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Powertrain
- Figure 57: Latin America Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Party Size
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Coach Configuration
- Figure 64: Western Europe Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Booking Channel
- Figure 67: Western Europe Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Service Model
- Figure 70: Western Europe Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Powertrain
- Figure 73: Western Europe Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Party Size
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Coach Configuration
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Booking Channel
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Service Model
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Powertrain
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Party Size
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Coach Configuration
- Figure 96: East Asia Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Booking Channel
- Figure 99: East Asia Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Service Model
- Figure 102: East Asia Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Powertrain
- Figure 105: East Asia Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Party Size
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Coach Configuration
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Booking Channel
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Service Model
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Powertrain
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Party Size
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Coach Configuration, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Coach Configuration, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Coach Configuration
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Booking Channel, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Booking Channel, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Booking Channel
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Service Model, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Service Model, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Service Model
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Powertrain, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Powertrain, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Powertrain
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Party Size, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Party Size, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Party Size
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the intercity bus travel market in 2026, and what is forecast for 2036?
Global intercity bus travel market valuation stood at USD 19.4 billion in 2025 and moved to USD 20.7 billion in 2026 per FMI modeling. Scheduled line-haul and express coach corridors are forecast to lift category size to USD 40.3 billion by 2036.
What is the CAGR for the intercity bus travel market from 2026 to 2036?
Intercity bus travel demand is forecast to progress at a 6.9% CAGR from 2026 through 2036, adding USD 19.6 billion in ten-year incremental value across passenger corridors.
Which coach configuration segment leads the intercity bus travel market?
Sleeper and Semi-Sleeper Luxury Coaches hold 34.7% of coach configuration demand in 2026 because wide reclining seats and lie-flat berths enable premium overnight ticket yields on long highway routes.
Which booking channel segment leads the intercity bus travel market?
Online Aggregator Apps and Digital Portals represent 58.2% of the booking channel category in 2026 as mobile QR boarding passes and dynamic early-bird fare tiers replace station ticket counters.
Which country has a notable growth outlook during the assessment period?
India paces national coach growth at an 8.2% CAGR through 2036 ahead of Brazil at 7.8% and Mexico at 7.4% through organized AC sleeper fleets and mobile ticketing.
Who are the key players in the market?
Flix SE (FlixBus and Greyhound) and Mobico Group plc (ALSA and National Express) lead commercial operations with Stagecoach Group Limited (Megabus) and Transdev Group. FirstGroup plc and ADO Mobility Group also compete with BlaBlaCar Bus and Trailways Transportation System as well as Keolis Group and Irizar S. Coop.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
