

- Market Size (2026)
- USD 78.0 Bn
- Forecast (2036)
- USD 168.3 Bn
- CAGR (2026 to 2036)
- 8.0%
How big is Kid Snacks Market in 2026?
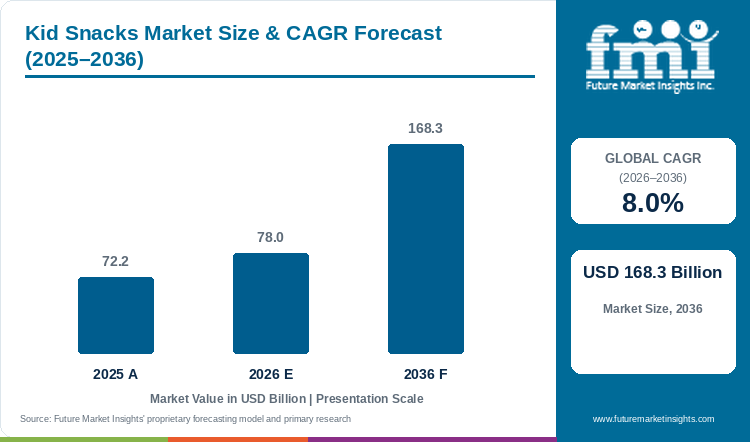
Sales in the kid snacks market are projected to grow at 8.0% CAGR, with the market size rising from USD 72.2 billion in 2025 to USD 78.0 billion in 2026 and reaching USD 168.3 billion by 2036.
FMI research indicates the global kid snacks market stands at USD 72.2 billion in 2025 and rises to USD 78.0 billion in 2026. Industry valuation is projected to reach USD 168.3 billion by 2036, expanding at an 8.0% CAGR and generating USD 90.3 billion in added revenue across the forecast period. Working parents are increasingly looking for portion-controlled packaged foods that fit into school lunchboxes and withstand transit without spoiling or crushing. In September 2025, a UNICEF report documented that 391 million children aged 5 to 19 were overweight globally, including 188 million living with obesity [1]. This shifting health reality compels food manufacturers to reformulate recipes with reduced added sugars and whole grains while preserving familiar taste profiles. Conventional kid snacks captures the leading position with a 68.4% share in 2026, as household familiarity and shelf availability dictate weekly grocery purchasing. Growth across evaluated countries ranges from 4.6% in the USA to 8.4% in China, though unit price ceilings and strict school nutrition rules continue to limit unproven premium launches.
Key Market Trends & Insights
- By source: Conventional kid snacks are projected to account for 68.4% in 2026, supported by established retail availability and broad household acceptance.
- By product type: Bakery is estimated to hold 36.7% in 2026, driven by lunchbox suitability and familiar portion-controlled formats.
- By distribution channel: Supermarkets or hypermarkets are forecast to represent 41.0% in 2026, underpinned by assortment depth and regular family shopping trips.
- By packaging type: Single-serve and multi-pack formats gain relevance as parents seek portion visibility, freshness, and school-bag convenience.
Regional Highlights
- Fastest-growing evaluated country: China, at 8.4% CAGR from 2026 to 2036.
- India follows at 7.8%, then Japan at 6.1% and Germany at 5.7%, while the USA records 4.6%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Kid Snacks Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 72.2 billion |
| Estimated Market Size in 2026 | USD 78.0 billion |
| Projected Market Size by 2036 | USD 168.3 billion |
| CAGR, 2026 to 2036 | 8.0% |
| Added Revenue, 2026 to 2036 | USD 90.3 billion |
Retail grocery shelves and school cafeteria guidelines are creating demanding qualification hurdles for processed snack brands. In September 2025, UNICEF published its Child Nutrition Report emphasizing the exposure of school-age children to aggressively marketed ultra-processed foods [2]. Healthcare authorities are scrutinizing excessive sodium and artificial additives in lunchbox items. Food manufacturers are therefore replacing refined flours with legume starches and whole grains, protecting crumb structure and preventing shelf staling. Formulating healthier snacks without dry texture or bitter off-notes requires precise baking trials. Brand owners must balance clean-label certifications against household grocery budgets to defend recurring basket placement across supermarket aisles.
Child-Population and Annual Spend Sizing
Table 2: Child-Population and Kid-Snack Spending Indicators (USD billion and scenario ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 72.2 | 78.0 | 168.3 |
| Addressable children aged 5-19 (billion) | 1.30 to 1.36 | 1.31 to 1.37 | 1.36 to 1.43 |
| Annual market spend per child (USD) | 53 to 56 | 57 to 60 | 118 to 124 |
| Weekly branded snack occasions | 2.4 to 2.8 | 2.5 to 2.9 | 3.1 to 3.6 |
Per Household & Retail Channel Sizing
Lunchbox, travel and after-school eating keep the category in regular household buying rather than occasional buying. Multipacks work because one outer pack can cover several school days, but the inner pack has to show a portion that parents can see and children can carry. This is also increasing the use of flexible packaging, as freshness and low pack weight matter more when a product is divided into smaller servings. The opportunity is favorable, although too much packaging can bring cost and waste pressure, which may limit how far brands can reduce each serving.
Table 3: Per Household Spending Indicators for the Kid Snacks Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global households with children (million) | 610 to 650 | 615 to 655 | 640 to 690 |
| Annual spend per household (USD) | 111 to 118 | 119 to 127 | 244 to 263 |
| Monthly spend per household (USD) | 9.3 to 9.8 | 9.9 to 10.6 | 20.3 to 21.9 |
| Single-serve share of occasions | 45% to 50% | 47% to 52% | 54% to 60% |
Table 4: Retail and Product Revenue Indicators for the Kid Snacks Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 78.0 billion | Report value |
| Supermarket / hypermarket revenue | USD 32.0 billion | 41.0% share |
| Bakery product revenue | USD 28.6 billion | 36.7% share |
| Conventional source revenue | USD 53.4 billion | 68.4% share |
Analyst Perspective
“Parents still prioritize taste and value, but nutrition signals now shape repeat purchase. Suppliers that reformulate familiar formats without compromising texture can strengthen retailer acceptance and household loyalty.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Kid Snacks Market segmented?
The kid snacks market is segmented by source, product type, distribution channel, and packaging type.
By source: Conventional kid snacks and organic kid snacks.
By product type: Bakery, salty, refrigerated or frozen, and confectionery.
By distribution channel: Supermarkets or hypermarkets, online stores, specialty stores, and grocery stores.
By packaging type: Flexible packaging, rigid packaging, single-serve packs, and multi-packs.
Why does Conventional Kid Snacks lead the source category?
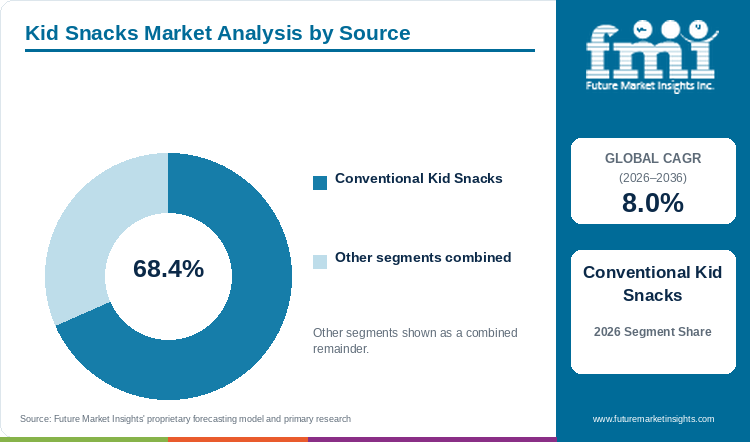
Conventional kid snacks represent 68.4% of source demand in 2026, balancing broad affordability with established household familiarity.
Table 5: Source Share for the Kid Snacks Market (percentage share), 2026
| Source | Share (2026) |
|---|---|
| Conventional Kid Snacks | 68.4% |
| Other Segments Combined | 31.6% |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Source Leadership and Market Growth for the Kid Snacks Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.0% |
| Leading Segment | Conventional Kid Snacks |
Conventional snacks keep the lead because availability and price are still stronger buying conditions than certification for most households. A 68.4% share in 2026 means the segment is not depending on one health claim; it is benefiting from products already present across supermarkets, grocery stores and value shelves. Organic products can gain where ingredient confidence is worth a higher price, but the gap can remain wide when the same household is buying several packs for a week. Conventional suppliers may therefore hold volume, provided cleaner recipes are introduced without moving the product outside the price range that built the demand. Related demand is also visible across organic snacks where the same purchase conditions are being tested.
- Conventional Kid Snacks is projected to hold 68.4% share in 2026, supported by the purchasing mechanism described above.
- In March 2025, Mondelēz International identified cleaner-label bakery and protein evolution among priority snacking themes [3].
What supports Bakery as the preferred product type?
Bakery accounts for 36.7% of product type demand in 2026, supported by portable portions and lunchbox familiarity.
Bakery holds 36.7% in 2026 because the format solves more than hunger. Cookies, crackers and small cakes can be portioned, packed and placed in a lunchbox without preparation, which gives bakery an advantage over refrigerated products. The share can also be protected by recipe flexibility, as grains, protein or reduced sugar can be introduced inside a product already known to the child. However, an improvement on the label will not be enough if sweetness, bite or shelf life changes sharply. This is where bakery growth may slow even when the nutrition direction is correct. Related demand is also visible across bakery products where the same purchase conditions are being tested.
- Bakery is projected to hold 36.7% share in 2026, supported by the purchasing mechanism described above.
- In January 2025, the OREO brand introduced new cookie and frozen snack formats for the year [4].
How do Supermarkets or Hypermarkets maintain channel leadership?
Supermarkets or hypermarkets hold 41.0% of distribution demand in 2026, underpinned by assortment depth and family shopping frequency.
Supermarkets and hypermarkets reach 41.0% share in 2026 because families can compare price, serving count and ingredients in the same visit. The channel also converts multipacks better than smaller stores, particularly near school reopening and other periods when households purchase for several days. Its lead is not protected from online retail. Digital grocery can take planned repeat orders, although supermarkets may keep the first purchase because shelf visibility and promotion make a new product easier to notice. Brands that miss both the physical shelf and the digital search result can lose demand even when the product itself is suitable. Related demand is also visible across online grocery where the same purchase conditions are being tested.
- Supermarkets or Hypermarkets is projected to hold 41.0% share in 2026, supported by the purchasing mechanism described above.
- Retail concentration supports broad displays alongside adjacent healthy snacks.
Why are Single-Serve Packs gaining relevance within packaging?
Single-serve packs gain relevance across packaging demand as parents standardize portions and protect freshness for school use.
Single-serve packs are gaining because they remove one decision from the morning routine. The serving is already separated, freshness is protected and allergen or calorie information can be shown for the amount actually eaten. This could work in favour of school use and variety packs. It can also turn against the supplier when packaging cost rises faster than the value parents see in the smaller unit. The format is therefore likely to expand first where convenience and portion control can justify the pack premium.
- Single-serve packs are gaining relevance in 2026, although the source does not publish a separate share for this packaging format.
- Packaging development increasingly connects portion control with the wider food packaging.
What are the drivers, restraints, and opportunities in the Kid Snacks Market?
Health-oriented reformulation supports demand, while price pressure and nutrition regulation limit execution, and portion-led product design creates new value.
- Driver: Parents seek convenient snacks with recognizable ingredients, controlled portions, and formats suitable for school and travel.
- Restraint: Added-sugar scrutiny, school rules, allergen management, and private-label pricing compress branded product flexibility.
- Opportunity: Protein, whole grains, fruit ingredients, and transparent portion labeling can extend familiar bakery and savory formats.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Portable snacking remains tied with school and family routines, but repeat purchase is becoming selective. The 2025 count of 391 million overweight children and adolescents gives regulators and parents a reason to look beyond a front-pack promise. Smaller portions, lower added sugar and whole-grain recipes can support demand when these changes remain inside a familiar format. The same changes may fail when texture becomes dry or the unit price rises sharply. Growth is therefore likely to come from products that improve one visible part of the offer without asking the household to change taste, routine and budget at the same time. Related demand is also visible across healthy snacks where the same purchase conditions are being tested.
Risk Assessment of the Kid Snacks Market: Formulation and Commercial Friction
Reformulation can fix one problem and create another. Less sugar may weaken browning, softness and flavour release in bakery products, while a natural colour can look less familiar than the product children already recognise. The commercial risk is equally direct. Better ingredients raise the cost, but private labels keep a low-price reference on the shelf. A claim that sounds stronger than the recipe can also bring retailer or regulatory challenge. Suppliers will need to validate serving size, allergens and each nutrient statement before the pack changes, because a quick launch followed by correction can damage trust more than a slower launch. Related demand is also visible across clean label ingredients where the same purchase conditions are being tested.
Commercial Opportunity Analysis: Nutrition Differentiation and Value-Add Formats
The stronger opportunity lies in improving a snack that already fits the occasion. Whole grains, fruit pieces, nuts, dairy protein and legume flour can raise the value of bakery and savoury products, but each ingredient brings its own cost, allergen or texture question. PepsiCo’s 2025 Doritos Simply NKD and Quaker whole-grain snack innovations show why large brands are testing cleaner formulations inside familiar shapes and flavours [5]. This approach may bring trial without forcing a new eating habit. Smaller brands can compete through a clearer ingredient story, although production scale and retail promotion can decide whether the product remains visible after the first listing. Related demand is also visible across protein snacks where the same purchase conditions are being tested.
Kid Snacks Market by Country (2026 to 2036)
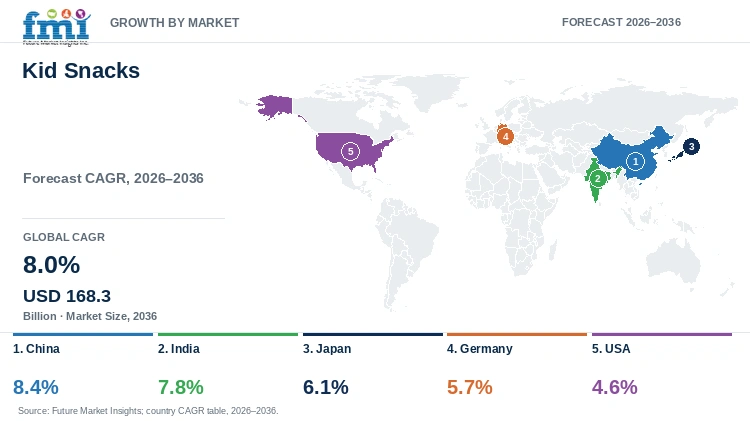
As per Future Market Insights, China represents the fastest-growing kid snacks market among five evaluated countries at 8.4% CAGR, while the USA records 4.6%. Across these economies, success depends on retail access, nutrition positioning, and pack-price discipline.
Table 7: Country CAGR and Primary Growth Levers for the Kid Snacks Market, 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| China | 8.4% | Urban retail expansion and digital grocery reach |
| India | 7.8% | Large child cohort and widening packaged-food access |
| Japan | 6.1% | Portion discipline and convenience-store innovation |
| Germany | 5.7% | Ingredient transparency and organic retail demand |
| USA | 4.6% | Better-for-you reformulation and large snack aisles |
Source: Future Market Insights analysis
China Kid Snacks Market Outlook (2026 to 2036)
China can grow at 8.4% through 2036 because digital grocery shortens the distance between product launch and household trial. A local or imported snack can appear in a promotion, collect reviews and move into repeat purchase faster than in a market led only by store shelves. This speed is also the hurdle. Price comparison is immediate and a weak product can disappear as quickly as it arrived. Smaller packs, local flavours and domestic production may work in favour by controlling delivery time and unit price. Nutrition claims will need real support, as decorative premium positioning alone is unlikely to hold repeat demand when parents can compare several alternatives in one screen.
Key takeaway: In China, Digital retail scale and localized pack-price architecture support fast product testing and repeat family purchase.
India Kid Snacks Market Outlook (2026 to 2036)
India’s 7.8% CAGR is connected with distribution moving deeper into tier-two and tier-three cities, but the market cannot be read only through population size. A large child base creates occasions, while the sale is decided by the money required for one pack. Low-unit-price packs and local sourcing can open demand where a large multipack may not move. Millets, nuts and reduced refined sugar give suppliers a local nutrition angle, although these ingredients must stay close to known taste. UNICEF India reported in September 2025 that overweight and obesity are rising across age groups, giving clearer portions more relevance [6]. The hurdle remains that a nutrition premium can lose volume if it moves beyond the weekly cash budget. Related demand is also visible across millet snacks where the same purchase conditions are being tested.
Key takeaway: In India, Low-unit-price packaging and locally relevant ingredients convert distribution growth into repeat demand.
Japan Kid Snacks Market Outlook (2026 to 2036)
Japan is projected at 6.1% CAGR without depending on a rapidly expanding child population. Value is more likely to come through precise portions, seasonal formats and convenience-store rotation. Compact multipacks can support freshness and give households variety without leaving an open pack. The same market can be hard for a supplier that cannot maintain packaging accuracy and product consistency, as a small defect becomes visible in a format sold on detail. Novelty may bring the first sale, but restrained sweetness, clear allergen information and reliable texture are more likely to hold the repeat sale.
Key takeaway: In Japan, Precise portions and high packaging quality sustain value growth in a mature demographic environment.
Germany Kid Snacks Market Outlook (2026 to 2036)
Germany’s 5.7% CAGR is likely to be shaped by ingredient scrutiny rather than simple flavour expansion. Organic retail, whole-grain bakery and strong private labels give parents several reference points for price and recipe quality. A shorter ingredient list or recyclable pack can support acceptance, but a claim without evidence can slow a listing instead of helping it. Organic certification may create trust and may also raise ingredient and audit cost. Suppliers that build one recipe for both mainstream and specialist channels can improve scale; those depending only on a premium niche may face slower volume when household spending tightens.
Key takeaway: In Germany, Transparent recipes and disciplined claims determine retailer acceptance across mainstream and organic channels.
USA Kid Snacks Market Outlook (2026 to 2036)
The USA grows at 4.6% through 2036 from an already large snack base, therefore shelf defence matters more than market entry alone. Protein, whole grains and controlled servings can protect branded products when the improvement is visible and taste remains familiar. Private labels place a ceiling on price, while large snack aisles make it easy for a weak proposition to be replaced. Portion-led variety packs may work in favour because households can cover different preferences in one purchase. Higher ingredient cost and scrutiny of child-directed marketing can work against a fast reformulation claim, especially when the benefit is difficult to measure on the pack. Related demand is also visible across better-for-you snacks where the same purchase conditions are being tested.
Key takeaway: In USA, Measurable reformulation and clear serving information help branded products defend space against private labels.
Full report country coverage includes North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the kid snacks market?
Mars, Incorporated, Mondelēz International, Inc., Nestlé S.A., The Kraft Heinz Company, PepsiCo, Inc., General Mills, Inc., and The Campbell’s Company are notable companies operating in this market.
Competition is not limited to the company with the largest number of brands. The stronger supplier is the one that can keep taste steady, change a recipe without stopping supply and give retailers a pack price that works across normal and promotional weeks. Global groups hold an advantage in manufacturing and shelf access, while smaller brands can move faster in organic, allergen-aware or lower-sugar niches. The gap can narrow when a specialist proves repeat sales, but it can widen again when raw-material cost, audits and national distribution put pressure on working capital.
- Global Snack Platforms: Mars, Mondelēz International, and PepsiCo combine broad brands with extensive distribution. Mars completed the acquisition of Kellanova in December 2025, integrating its snack portfolio under Mars Snacking.
- Diversified Food Groups: Nestlé, General Mills, Kraft Heinz, and The Campbell’s Company connect snacks with wider family food portfolios.
Competitive Benchmarking: Kid Snacks Market
Table 8: Competitive Benchmarking for the Kid Snacks Market (qualitative capability ratings), 2026
| Company | Kid-Focused Portfolio | Nutrition Reformulation | Retail Access | Geographic Reach |
|---|---|---|---|---|
| Mars, Incorporated | High | High | High | High |
| Mondelēz International, Inc. | High | High | High | High |
| Nestlé S.A. | Medium | High | High | High |
| The Kraft Heinz Company | Medium | Medium | High | High |
| PepsiCo, Inc. | High | Medium | High | High |
| General Mills, Inc. | High | High | High | High |
| The Campbell’s Company | Medium | Medium | High | Medium |
Scoring basis: High indicates broad public evidence across the named capability. Medium indicates a narrower or more regionally concentrated offering. Low is reserved for documented limitations.
Key Developments in the Kid Snacks Market
- In December 2025, Mars completed its acquisition of Kellanova, bringing major global snack brands into a broader combined platform [7].
- In July 2025, PepsiCo unveiled new summer flavour innovations including Doritos Tangy Golden Sriracha and expanded Gatorade flavour mashups within its seasonal food and drinks portfolio [5].
- In March 2025, Mondelēz International identified cleaner-label bakery and protein evolution among SnackFutures Ventures priorities [3].
- In January 2025, OREO introduced new cookie and frozen snack formats for the year [4].
Key Players in the Kid Snacks Market
Global Snack Platforms
- Mars, Incorporated
- Mondelēz International, Inc.
- PepsiCo, Inc.
Diversified Family Food Companies
- Nestlé S.A.
- The Kraft Heinz Company
- General Mills, Inc.
- The Campbell’s Company
Kid Snacks Market - Report Scope
Table 9: Report Scope for the Kid Snacks Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Source; Product Type; Distribution Channel; Packaging Type |
| Quantitative units | USD Billion |
| Market definition | Commercially traded kid-oriented snacks sold through retail and direct channels within the listed taxonomy. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries highlighted | China; India; Japan; Germany; USA |
| Key companies covered | Mars, Incorporated; Mondelēz International, Inc.; Nestlé S.A.; The Kraft Heinz Company; PepsiCo, Inc.; Kellanova; General Mills, Inc.; The Campbell’s Company |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with data triangulation. |
Kid Snacks Market - Research Methodology
Table 10: Research Methodology for the Kid Snacks Market, 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with manufacturers, suppliers, distributors, retailers, nutrition professionals, industry experts, and key opinion leaders validate demand and purchasing patterns. |
| Secondary Research | Company annual reports, investor presentations, regulatory publications, associations, technical papers, trade journals, company websites, product literature, and public sources support the assessment. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess product revenue, channel mix, price points, and regional adoption from 2026 to 2036. |
| Data Triangulation and Validation | Data is validated against child-population indicators, nutrition trends, regulatory conditions, company activity, and historical demand patterns. |
Kid Snacks Market by Segments
Kid Snacks Market segmented by Source:
- Conventional Kid Snacks
- Organic Kid Snacks
Kid Snacks Market segmented by Product Type:
- Bakery
- Salty
- Refrigerated or Frozen
- Confectionery
Kid Snacks Market segmented by Distribution Channel:
- Supermarkets or Hypermarkets
- Online Stores
- Specialty Stores
- Grocery Stores
Kid Snacks Market segmented by Packaging Type:
- Flexible Packaging
- Rigid Packaging
- Single-Serve Packs
- Multi-Packs
Kid Snacks Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] UNICEF. (2025, September 10). Obesity exceeds underweight for the first time among school-age children and adolescents globally. UNICEF Press Release.
- [2] UNICEF. (2025, September). Feeding profit: How food environments are failing children. Child Nutrition Report 2025.
- [3] Mondelēz International, Inc. (2025, March 4). SnackFutures Ventures to unveil top trends shaping the future of snacking. Corporate News.
- [4] Mondelēz International, Inc. (2025, January 10). OREO unveils new flavor innovations to kickstart 2025. Product Announcements.
- [5] PepsiCo, Inc. (2025, July 1). From smoky to bold and fruity flavors: New foods and drinks for summer. Corporate Stories.
- [6] Ministry of Statistics and Programme Implementation, Government of India. (2025, September 25). Children in India 2025. Government of India Publications.
- [7] Mars, Incorporated. (2025, December 11). Mars completes acquisition of Kellanova. Corporate Announcements.
- [8] Future Market Insights. (2026, May 8). Kid Snacks Market: Global industry analysis and opportunity assessment, 2026 to 2036. FMI Reports.
- [9] World Obesity Federation. (2025). World Obesity Atlas 2025. Policy Reports.
- [10] Sweets and Snacks Expo. (2026). Most Innovative New Product Awards Showcase. Industry Highlights.
- [11] Nestlé S.A. (2026). Nestlé for Healthier Kids program overview. Global Nutrition Portfolios.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the kid snacks market in 2026 and what is forecast for 2036?
- Which nutrition and convenience pressures support kid snack demand?
- Why do conventional kid snacks lead the source category?
- Why does bakery lead product type demand?
- How do growth rates differ across China, India, Japan, Germany, and the USA?
- Which companies supply major kid snack categories today?
- What limits reformulation and supplier switching?
- What should retail buyers assess before listing kid snacks?
Frequently Asked Questions
How big is the kid snacks market in 2026, and what is forecast for 2036?
Future Market Insights estimates USD 78.0 billion in 2026 and USD 168.3 billion by 2036.
What is the CAGR from 2026 to 2036?
FMI projects an 8.0% CAGR during the assessment period.
Which source segment leads?
Conventional kid snacks are projected to hold 68.4% share in 2026.
Which product type leads?
Bakery products account for 36.7% of demand in 2026.
Which country records the fastest evaluated growth?
China is projected at 8.4% CAGR through 2036.
Who are the key players?
Key participants include Mars, Mondelēz International, Nestlé, Kraft Heinz, PepsiCo, Kellanova, General Mills, and The Campbell’s Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Conventional Kid Snacks
- Organic Kid Snacks
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Bakery
- Salty
- Refrigerated or Frozen
- Confectionery
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets or Hypermarkets
- Online Stores
- Specialty Stores
- Grocery Stores
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Type, 2026 to 2036
- Flexible Packaging
- Rigid Packaging
- Single-Serve Packs
- Multi-Packs
- Y-o-Y Growth Trend Analysis By Packaging Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Type, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- By Country
- Market Attractiveness Analysis
- By Country
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Source
- By Product Type
- By Distribution Channel
- By Packaging Type
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Mars, Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Mondelēz International, Inc.
- Nestlé S.A.
- The Kraft Heinz Company
- PepsiCo, Inc.
- Kellanova
- General Mills, Inc.
- The Campbell’s Company
- Mars, Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


