

- Market Size (2026)
- USD 36.0 Bn
- Forecast (2036)
- USD 96.8 Bn
- CAGR (2026 to 2036)
- 10.4%
How big is Kids’ Food and Beverages Market in 2026?
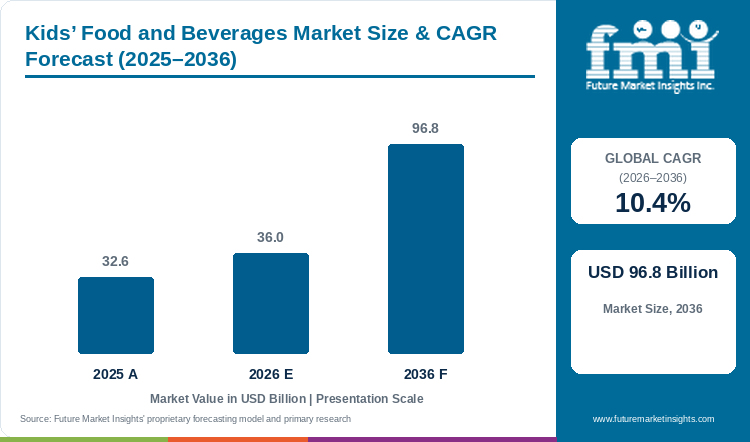
Demand for kids’ food and beverages is projected to expand at 10.4% CAGR between 2026 and 2036. Industry value grows from USD 32.6 billion in 2025 to USD 36.0 billion in 2026 and is projected to reach USD 96.8 billion by 2036.
According to FMI, global revenue expands from USD 32.6 billion in 2025 to USD 36.0 billion in 2026 and reaches USD 96.8 billion by 2036, advancing at a 10.4% CAGR and creating USD 60.8 billion in incremental expansion. Parents increasingly scrutinize front-of-pack nutrition, checking sugar thresholds, sodium levels, and allergen disclosures before adding items to weekly household replenishment. In September 2025, UNICEF documented that childhood obesity prevalence surpassed underweight metrics among school-age cohorts globally [1]. This shift compels manufacturers to reformulate recipes with reduced added sugar while preserving familiar flavor profiles. Snacks represent the primary commercial anchor, commanding 36.4% of product type revenue in 2026 as portable formats accommodate dense school and activity routines.
Key Market Trends & Insights
- By product type: Snacks are projected to account for 36.4% in 2026, driven by portable school-day eating occasions.
- By age group: School-aged children are estimated to hold 38.6% in 2026, supported by frequent independent snack choices.
- By packaging format: Single-serve pouches and packs are expected to lead with 41.2% share, owing to visible portion control.
- By distribution channel: Supermarkets and hypermarkets are forecast to represent 44.8% in 2026, enabled by basket-based comparison.
- Notable companies include Nestlé, Danone, General Mills, Kellanova, PepsiCo, The Campbell’s Company, Hain Celestial, and Once Upon a Farm.
Regional Highlights
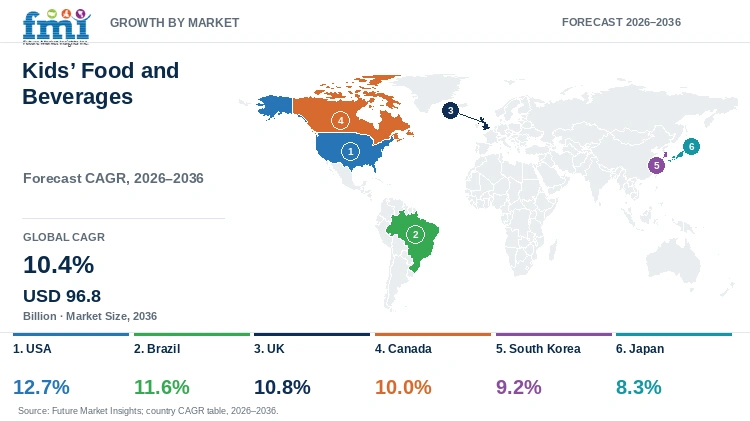
- Fastest-growing profiled country: The USA is projected at 12.7% CAGR, while Brazil advances at 11.6% CAGR through 2036.
- By country: The UK (10.8%), Canada (10.0%), South Korea (9.2%), and Japan follow, while Japan records the lowest profiled CAGR at 8.3%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Kids’ Food and Beverages Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 32.6 billion |
| Estimated Market Size in 2026 | USD 36.0 billion |
| Projected Market Size by 2036 | USD 96.8 billion |
| CAGR, 2026 to 2036 | 10.4% |
| Added Revenue, 2026 to 2036 | USD 60.8 billion |
Growth conditions vary between the profiled countries as regulatory frameworks diverge across major consumer markets. The U.S. FDA finalized its updated healthy nutrient content claim criteria with an effective date of April 28, 2025, establishing strict limits on added sugars, saturated fats, and sodium while requiring qualifying food-group contributions [2]. The rule provides food processors with a clear shelf advantage for certified products. Concurrently, UK advertising controls restrict child-facing marketing for less healthy foods across broadcast and digital channels. Food processors are compelled to reformulate product lines before marketing expenditures can generate equivalent brand reach. Expanding availability across organic baby food further illustrates how clean-label validation anchors household trust across early childhood categories.
Child Population and Eating-Occasion Sizing
Table 2: Child Population and Eating-Occasion Sizing for the Kids’ Food and Beverages Market (USD billion and scenario ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 32.6 | 36.0 | 96.8 |
| Addressable children (billion) | 2.02 | 2.03 | 2.06 |
| Packaged occasions (billion) | 48–54 | 52–58 | 91–102 |
| Spend per child (USD) | 16.14 | 17.73 | 46.99 |
Calculation basis: Addressable population and occasion ranges are scenario inputs. They are not measured global consumption totals.
Channel and Packaging Sizing
Parents combine routine grocery shopping with planned replenishment across healthy snacks categories. Supermarkets maintain the widest assortment visible on main aisles, while digital channels support subscription reordering for approved household brands.
Table 3: Channel and Packaging Indicators for the Kids’ Food and Beverages Market (USD billion), 2026 and 2036
| Metric | 2026 | 2036 |
|---|---|---|
| Single-serve pouches and packs revenue | 14.8 | 39.9 |
| Supermarkets and hypermarkets revenue | 16.1 | 43.4 |
| Snacks revenue | 13.1 | 35.2 |
Table 4: Commercial Purchase Indicators for the Kids’ Food and Beverages Market (USD and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market value | USD 36.0 billion | Report value |
| Average spend per child | USD 17.73 | Scenario calculation |
| Single-serve share | 41.2% | Segment share analysis |
| Supermarket share | 44.8% | Segment share analysis |
Analyst Perspective
“Parents now expect convenience to carry a visible nutrition benefit without compromising on familiar taste profiles. Brands that reformulate established recipes to lower added sugar and sodium will protect recurring retail demand as school nutrition and marketing standards tighten.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the kids’ food and beverages market segmented?
The kids’ food and beverages market is segmented by product type, age group, packaging format, and distribution channel. In 2026, snacks are projected at 36.4%, school-aged children at 38.6%, single-serve pouches and packs at 41.2%, and supermarkets and hypermarkets at 44.8%.
By product type: snacks, dairy and cultured products, breakfast cereals, beverages, bakery products, prepared meals, confectionery, and others.
By age group: infants, toddlers, preschool children, school-aged children, and early teens.
By packaging format: single-serve pouches and packs, cartons, cups and tubs, bottles, multipacks, and others.
By distribution channel: supermarkets and hypermarkets, convenience stores, online retail, pharmacy and specialty nutrition stores, foodservice and schools, and others.
Why do snacks account for a notable share of product type demand?
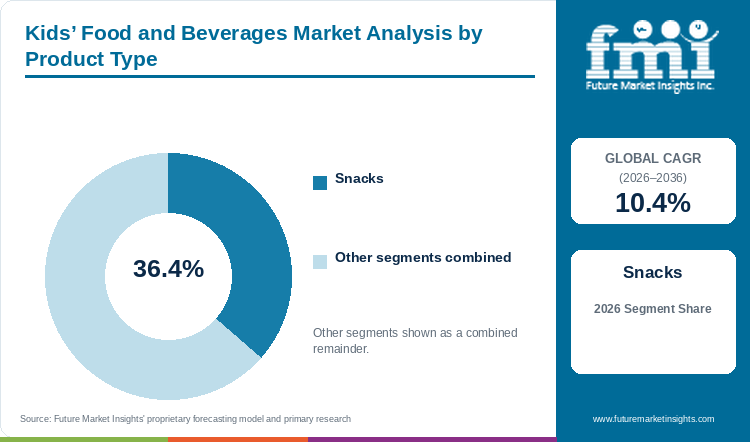
Snacks are projected to hold 36.4% of product type revenue in 2026, driven by recurring school-day convenience and portion-controlled portability.
Table 5: Product Type Share for the Kids’ Food and Beverages Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Snacks | 36.4% |
| Other segments combined | 63.6%* |
| Total | 100.0% |
*Calculated as the balance after deducting the leading segment share from 100.0%.
Table 6: Product Type Leadership and Market Growth for the Kids’ Food and Beverages Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 10.4% |
| Leading segment | Snacks |
Snack products bridge nutritional gaps between formal meals, travel, and extracurricular activities. Single-serve portions allow parents to manage caloric and sugar intake without manual repackaging. Brand growth is closely tied to kid snacks where certified allergen claims and clear nutritional callouts drive selection.
- Snacks represent 36.4% of product type revenue as portable packaging supports recurring weekday consumption.
- In September 2026, USDA Food and Nutrition Service updated child nutrition meal tables documenting participation across 29 million daily school lunches [3].
What supports school-aged children as a preferred age group choice?
School-aged children are estimated to represent 38.6% of age group demand in 2026, reflecting independent snacking choices and structured school schedules.
School-aged children exhibit greater autonomy in taste selection while attending primary education and sports activities. Caregivers continue to control household purchase budgets, reviewing nutritional panels and sugar levels prior to repeat grocery replenishment. This dynamic mirrors broader developments in pediatric nutrition where age-appropriate fortification informs parental trust. Further specialized demand intersects with pediatric high-calorie snacks when clinical dietary requirements arise.
- School-aged children account for 38.6% of age-group sales as family dietary priorities align with child flavor preferences.
- In July 2026, UNICEF reported reaching 158 million school-age children across 71 countries with malnutrition-prevention programs during 2025 [4].
How are single-serve packs gaining use across packaging formats?
Single-serve pouches and packs are expected to capture 41.2% of packaging format sales in 2026, supported by convenient handling and measured portions.
Single-serve packaging eliminates prep time and provides clear visibility into single-sitting portion sizes. Resealable pouches and cartons also prevent spillage during commutes and sports practices. The commercial adoption of these formats shares operational parallels with baby snacks where package ergonomics and barrier preservation remain decisive purchasing factors.
- Single-serve pouches and packs command 41.2% of packaging format revenue as pre-measured portions prevent overconsumption.
- In April 2024, USDA Food and Nutrition Service established updated nutrition standards phasing in dietary limits on added sugars in school breakfast items through 2025 and 2026 [5].
Why are buyers selecting supermarkets within the distribution channel?
Supermarkets and hypermarkets are anticipated to command 44.8% of distribution channel revenue in 2026, owing to comprehensive assortment and direct price comparison.
Modern grocery stores provide multi-category displays that allow parents to compare organic options, chilled dairy cups, and multipacks side by side. Retail buyers actively curate health-forward children's food aisles to capture weekly family basket spend. This retail concentration mirrors ongoing shelf-space reallocation in children’s breakfast cereal reformulation where cleaner ingredient declarations secure premium placement.
- Supermarkets and hypermarkets generate 44.8% of channel turnover as comprehensive merchandising enables immediate nutritional comparison.
- In June 2026, Employment and Social Development Canada reported expanding the National School Food Program to over 10,000 participating schools nationwide [6].
What are the drivers, restraints, and opportunities in the kids’ food and beverages market?
In the kids' food and beverages market, school routines expand demand for convenient nutrition, regulatory sugar limits raise reformulation expenses, and clean-label functional formulations unlock premium retail growth through 2036.
- Driver: Increasing extracurricular participation and dual-income households accelerate demand for nutrient-dense, pre-portioned foods that simplify school lunches.
- Restraint: Stringent governmental restrictions on front-of-pack marketing, sodium thresholds, and added sugar elevate sensory formulation costs for food processors.
- Opportunity: Introducing recognizable whole-grain ingredients, legume proteins, and functional probiotics in kid-friendly formats captures premium retail shelf space.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
School schedules and organized sports create recurring daily eating occasions outside traditional family mealtimes. In September 2025, USDA Economic Research Service documented that child nutrition programs provided 9.3 billion meals during fiscal 2024, representing an expenditure of USD 28.2 billion [7]. This massive volume highlights how structured institutional settings reinforce child eating routines. Processors that formulate shelf-stable snack bars and chilled dairy cups with recognizable fruit and grain ingredients secure recurring grocery placement. Food brands that communicate portion balance and allergen transparency establish enduring parental brand loyalty.
Risk Assessment of the Kids’ Food and Beverages Market: Operational and Formulation Friction
Statutory restrictions on advertising foods high in fat, sugar, and salt directly constrain child-directed promotional campaigns. In June 2025, the UK Department of Health and Social Care issued updated compliance guidance confirming a 9 p.m. broadcast watershed and comprehensive ban on paid online advertising for less healthy foods taking effect on January 5, 2026 [8]. Complying with these thresholds requires extensive recipe reformulations, including sweetening with real fruit purees and optimizing natural flavor masking. These technical adjustments elevate raw material costs and necessitate extensive sensory testing before commercial release. Smaller brand owners with limited manufacturing scale face significant cost hurdles when competing against multinational food conglomerates.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Heightened parental scrutiny regarding ingredient purity creates substantial commercial room for clean-label formulation innovation. Caregivers routinely examine nutrition panels, comparing fiber and protein content against added sugars before selecting snack packs. Processors are increasingly reformulating classic staples by incorporating oats, ancient grains, and cultured dairy. Industry developments in prepared baby food demonstrate how clear developmental age-stage labeling fosters long-term consumer trust. Products that deliver certified nutritional density without compromising familiar taste profiles achieve superior gross margins and preferential supermarket shelf space. Specialized dietary management also connects with pediatric ketogenic snacks formulated under clinical medical guidance.
Kids’ Food and Beverages Market by Country (2026 to 2036)
As noted by FMI, the USA represents the strongest expansion outlook among six evaluated countries at 12.7% CAGR, while Japan records 8.3% CAGR. Commercial success depends on reformulation, school-food compatibility, retail access, and price discipline.
Table 7: Country CAGR and Primary Growth Levers for the Kids’ Food and Beverages Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 12.7% | Healthy-claim reformulation and national retail scale |
| Brazil | 11.6% | School nutrition education and local procurement |
| UK | 10.8% | Less healthy food advertising restrictions |
| Canada | 10.0% | National School Food Program expansion |
| South Korea | 9.2% | National child dietary surveillance and dense retail access |
| Japan | 8.3% | School lunch and shokuiku food education |
Source: Future Market Insights analysis
USA Kids’ Food and Beverages Market Outlook (2026 to 2036)
In the United States, children's food and beverage sales are projected to advance at 12.7% CAGR through 2036, driven by massive grocery retail scale and clear front-of-pack nutritional labeling. The U.S. Food and Drug Administration finalized its updated criteria for the voluntary healthy nutrient content claim with an effective date of April 28, 2025, establishing strict nutrient ceilings for added sugars, sodium, and saturated fats [9]. This statutory guideline gives packaged food processors a measurable competitive advantage in mass retail aisles. However, reformulating established snack recipes with real fruit, legume flours, and whole milk solids increases input costs. Large consumer packaged goods manufacturers leverage national production facilities to absorb ingredient price swings, while emerging clean-label challenger brands focus on premium refrigerated channels to build recurring direct-to-consumer subscriber volumes.
Key takeaway: In the USA, healthy-claim reformulation turns national retail scale into repeat purchasing.
Brazil Kids’ Food and Beverages Market Outlook (2026 to 2036)
Brazil exhibits rapid commercial momentum, with market revenues forecast to expand at 11.6% CAGR over the assessment period, underpinned by institutional feeding guidelines and municipal dietary education programs. In 2025, the National Fund for Educational Development (FNDE) issued Technical Note No. 4816230/2025 mandating enhanced food and nutrition curriculum integration across public school networks [10]. This regulatory focus creates heightened consumer awareness regarding processed food ingredients among urban households. Nonetheless, commercial manufacturers must contend with municipal procurement policies that legally prioritize locally grown agricultural commodities over shelf-stable packaged foods. Food processors are responding by formulating fruit-based snacks and cassava-derived baked items that align with national dietary recommendations while remaining affordable for middle-income working families.
Key takeaway: In Brazil, school nutrition education links local procurement to household replenishment.
UK Kids’ Food and Beverages Market Outlook (2026 to 2036)
Tighter marketing constraints define commercial competition across the United Kingdom, where children's packaged food demand is forecast to rise at 10.8% CAGR between 2026 and 2036. Government statutory instruments confirmed strict marketing bans on identifiable less healthy products across television before the 9 p.m. watershed and comprehensive prohibitions on paid online advertising taking effect in January 2026 [11]. These promotional barriers compel food manufacturers to reformulate legacy confectionery, bakery, and sugary cereal lines to avoid broadcast advertising bans. While recipe modification requires substantial capital expenditure on natural sweetening alternatives, compliant brands gain preferred listing status across major UK grocery multiples. Retailers are actively expanding dedicated healthy family snack fixtures to capture caregiver demand without relying on traditional cartoon-character promotion.
Key takeaway: In the UK, advertising restrictions reward reformulation with sustained family-audience reach.
Canada Kids’ Food and Beverages Market Outlook (2026 to 2036)
Expansion of nationwide public school nutrition infrastructure is reshaping the addressable market landscape in Canada, supporting a projected 10.0% CAGR through 2036. In June 2026, Employment and Social Development Canada announced that over 10,000 schools had implemented subsidized meal programs, providing nutritious daily food access to an estimated 400,000 students [12]. This federal funding initiative creates predictable institutional procurement volumes for portion-controlled, allergen-aware packaged dairy and fruit snacks. However, commercial suppliers must navigate stringent provincial nutritional guidelines that strictly restrict synthetic preservatives, added sugars, and artificial flavorings. Brand owners that achieve certified nut-free facility standards and ambient shelf stability are securing preferred multi-district institutional delivery contracts.
Key takeaway: In Canada, school food expansion opens institutional volume alongside retail demand.
South Korea Kids’ Food and Beverages Market Outlook (2026 to 2036)
In South Korea, dense convenience retail networks and rigorous dietary health standards drive children's food and beverage revenue at an estimated 9.2% CAGR through 2036. The Korea Disease Control and Prevention Agency (KDCA) maintains comprehensive youth dietary and health surveillance monitoring adolescent nutritional balance and processed food consumption [13]. High parental educational involvement translates into intense retail scrutiny of product ingredient lists, particularly concerning sodium and chemical stabilizers. Manufacturers cater to compact urban living by developing single-serve refrigerated yogurt smoothies and portion-controlled freeze-dried fruit cubes. Convenience store operators frequently rotate novel flavor profiles, requiring processors to balance continuous formulation innovation with proven nutritional efficacy to sustain household repeat purchases.
Key takeaway: In South Korea, dietary surveillance and dense retail reward practical nutrition over novelty.
Japan Kids’ Food and Beverages Market Outlook (2026 to 2036)
Japan’s market environment is structured around the cultural and legal doctrine of shokuiku (food and nutrition education), underpinning an 8.3% CAGR from 2026 to 2036. In December 2025, the Cabinet Office and Ministry of Education highlighted the continued evolution of national school lunch programs under the School Lunch Program Act, reinforcing daily dietary balance and mindful eating [14]. Although demographic aging constrains total child population headcount, average parental spending per child on premium organic foods continues to rise. Food processors overcome volume constraints by formulating nutrient-dense calcium and iron fortified milk drinks in compact, easily recyclable cartons. Strict Japanese quality standards necessitate clean-label formulations with minimal additive counts, creating a premium market niche for certified domestic producers.
Key takeaway: In Japan, school lunch culture supports nutrient-dense formats in smaller portions.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the kids’ food and beverages market?
Nestlé S.A., Danone S.A., General Mills, Inc., Kellanova, PepsiCo, Inc., The Campbell’s Company, The Hain Celestial Group, Inc., and Once Upon a Farm are significant market players in this market.
FMI research indicates that commercial competition divides between diversified global food corporations and specialized child-nutrition brands. Major multinational conglomerates utilize extensive supermarket distribution networks and large-scale manufacturing to supply breakfast cereals, snack multipacks, and cultured dairy lines. In contrast, emerging clean-label specialists establish direct parental trust by formulating organic fruit purees, cold-pressed smoothies, and refrigerated snack bars with zero added cane sugar. In addition, procurement decisions among institutional foodservice buyers and mass retailers prioritize verified allergen certifications, clean-label compliance, and dependable cold-chain distribution.
- Multi-category food groups: Nestlé, General Mills, Kellanova, PepsiCo, and The Campbell’s Company leverage international grocery scale and extensive manufacturing footprints.
- Nutrition and dairy platforms: Danone applies specialized cultured dairy capabilities and child-targeted probiotic formulations.
- Organic and child-focused platforms: Hain Celestial and Once Upon a Farm focus on certified organic ingredients, cold-pressure processing, and recognizable whole foods.
Competitive Benchmarking: Kids’ Food and Beverages Market
Table 8: Competitive Benchmarking for the Kids’ Food and Beverages Market (qualitative capability ratings), 2026
| Company | Portfolio Breadth | Nutrition Depth | Retail Access | Geographic Reach |
|---|---|---|---|---|
| Nestlé S.A. | High | High | High | High |
| Danone S.A. | Medium | High | High | High |
| General Mills, Inc. | High | Medium | High | High |
| Kellanova | High | Medium | High | High |
| PepsiCo, Inc. | High | Medium | High | High |
| The Campbell’s Company | Medium | Medium | High | Medium |
| The Hain Celestial Group, Inc. | Medium | High | Medium | Medium |
| Once Upon a Farm | Medium | High | Medium | Low |
Scoring basis: High indicates broad documented category activity, current commercial access, or international reach. Medium indicates a narrower range or regional strength. Low indicates limited geographic breadth. Ratings describe capability coverage rather than quality or market share. Related category breadth can be reviewed through baby food activity.
Key Developments in the Kids’ Food and Beverages Market
- In March 2026, Once Upon a Farm expanded its retail footprint by launching protein-rich organic refrigerated smoothies and whole-grain snack bars for children [15].
- In September 2025, UNICEF published its global child nutrition report highlighting critical shifts in childhood dietary patterns and food environments worldwide [16].
- In April 2025, the U.S. Food and Drug Administration finalized updated regulatory benchmarks governing the use of the voluntary healthy claim on packaged food labels [9].
Key Players in the Kids’ Food and Beverages Market
Multi-Category Food and Snack Groups
- Nestlé S.A.
- General Mills, Inc.
- Kellanova
- PepsiCo, Inc.
- The Campbell’s Company
Nutrition and Dairy Platforms
- Danone S.A.
Organic and Child-Focused Platforms
- The Hain Celestial Group, Inc.
- Once Upon a Farm
Kids’ Food and Beverages Market - Report Scope
Table 9: Report Scope for the Kids’ Food and Beverages Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Age Group; Packaging Format; Distribution Channel |
| Quantitative Units | USD Billion |
| Market Definition | Supplier revenue from foods and non-alcoholic beverages formulated, portioned, packaged, or marketed primarily for children. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Brazil, UK, Canada, South Korea, Japan, and additional countries in the full report |
| Key Companies Covered | Nestlé S.A., Danone S.A., General Mills, Inc., Kellanova, PepsiCo, Inc., The Campbell’s Company, The Hain Celestial Group, Inc., Once Upon a Farm |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Kids’ Food and Beverages Market - Research Methodology
Table 10: Research Methodology for the Kids’ Food and Beverages Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, nutrition professionals, industry experts, and key opinion leaders across the value chain to validate demand patterns and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public data. |
| Market Sizing and Forecasting | Market sizing and forecasts for 2026 to 2036 were developed using top-down and bottom-up approaches to assess revenue, price points, channel demand, and adoption. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, child nutrition conditions, regulation, and historical trends to reduce double counting of adjacent categories. |
Kids’ Food and Beverages Market by Segments
Kids’ Food and Beverages Market segmented by Product Type:
- Snacks
- Dairy and cultured products
- Breakfast cereals
- Beverages
- Bakery products
- Prepared meals
- Confectionery
- Others
Kids’ Food and Beverages Market segmented by Age Group:
- Infants
- Toddlers
- Preschool children
- School-aged children
- Early teens
Kids’ Food and Beverages Market segmented by Packaging Format:
- Single-serve pouches and packs
- Cartons
- Cups and tubs
- Bottles
- Multipacks
- Others
Kids’ Food and Beverages Market segmented by Distribution Channel:
- Supermarkets and hypermarkets
- Convenience stores
- Online retail
- Pharmacy and specialty nutrition stores
- Foodservice and schools
- Others
Kids’ Food and Beverages Market by Region
- North America
- United States
- Canada.
- Latin America
- Brazil
- Mexico
- Argentina
- Chile.
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics.
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary.
- East Asia
- China
- Japan
- South Korea.
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand.
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel.
Research Sources and Bibliography
- [1] United Nations Children’s Fund. (2025, September). Feeding profit: How food environments are failing children. Child Nutrition Report 2025.
- [2] U.S. Food and Drug Administration. (2025, February 24). FDA finalizes updated “Healthy” nutrient content claim. Constituent Updates.
- [3] U.S. Department of Agriculture, Food and Nutrition Service. (2026, September 18). Child Nutrition Tables: FY 1969–2025.
- [4] United Nations Children’s Fund. (2026, July). Global Annual Results Report 2025: Goal Area 1, Nutrition.
- [5] U.S. Department of Agriculture, Food and Nutrition Service. (2024, April 24). Child Nutrition Programs: Revisions to meal patterns consistent with the 2020-2025 Dietary Guidelines for Americans. Federal Register, 89(81), 31962-32057.
- [6] Employment and Social Development Canada. (2026, June 16). National School Food Program takes shape across Canada.
- [7] U.S. Department of Agriculture, Economic Research Service. (2025, September 23). Child Nutrition Programs. Data Products.
- [8] Department of Health and Social Care. (2025, June 4). Restricting advertising of less healthy food or drink on TV and online: Products in scope.
- [9] U.S. Food and Drug Administration. (2025). Use of the term healthy on food labeling. Guidance for Industry.
- [10] Fundo Nacional de Desenvolvimento da Educação. (2025). Nota Técnica No. 4816230/2025: Educação alimentar e nutricional no currículo escolar.
- [11] Office of Communications (Ofcom). (2026, January). Statutory guidance on the implementation of advertising restrictions for less healthy food and drink.
- [12] Employment and Social Development Canada. (2026). Delivering healthy meals for Canadian students: Progress update 2026.
- [13] Korea Disease Control and Prevention Agency. (2025). 2024 KDCA White Paper and national health survey program.
- [14] Government of Japan. (2025, December). The significance and evolution of Japan’s school lunch program.
- [15] Once Upon a Farm, PBC. (2026, March 12). Once Upon a Farm introduces organic refrigerated protein smoothies and snack bars for active kids.
- [16] United Nations Children’s Fund. (2025). State of the World’s Children: Child nutrition and evolving food environments.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the kids’ food and beverages market in 2026 and 2036?
- Which nutrition and convenience pressures support market demand through 2036?
- Why do snacks lead the product type category in 2026?
- Why do single-serve packs lead the packaging format category?
- How do country growth rates differ across the evaluated economies?
- Which companies supply relevant food and beverage categories today?
- What limits adoption or supplier switching in this market?
- What should buyers evaluate before purchasing child-focused foods?
Frequently Asked Questions
How big is the kids’ food and beverages market in 2026?
Future Market Insights estimates the market at USD 36.0 billion in 2026 and projects USD 96.8 billion by 2036.
What is the market CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at 10.4% CAGR between 2026 and 2036.
Which product type leads the market?
Snacks are forecast to account for 36.4% of product type revenue in 2026, driven by portable school-day eating occasions.
Which packaging format leads the market?
Single-serve pouches and packs are projected to hold 41.2% of packaging format revenue in 2026, supported by convenient handling and portion clarity.
Which country has a notable growth outlook?
The USA is projected to register 12.7% CAGR through 2036, supported by retail scale and reformulation incentives under updated healthy labeling criteria.
Who are the notable companies?
Notable participants include Nestlé, Danone, General Mills, Kellanova, PepsiCo, The Campbell’s Company, Hain Celestial, and Once Upon a Farm.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Snacks
- Dairy and cultured products
- Breakfast cereals
- Beverages
- Bakery products
- Prepared meals
- Confectionery
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Age Group, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Age Group, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Age Group, 2026 to 2036
- Infants
- Toddlers
- Preschool children
- School-aged children
- Early teens
- Y-o-Y Growth Trend Analysis By Age Group, 2021 to 2025
- Absolute $ Opportunity Analysis By Age Group, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Single-serve pouches and packs
- Cartons
- Cups and tubs
- Bottles
- Multipacks
- Others
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets and hypermarkets
- Convenience stores
- Online retail
- Pharmacy and specialty nutrition stores
- Foodservice and schools
- Others
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel.
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Age Group
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Nestlé S.A.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Danone S.A.
- General Mills, Inc.
- Kellanova
- PepsiCo, Inc.
- The Campbell’s Company
- The Hain Celestial Group, Inc.
- Once Upon a Farm
- Nestlé S.A.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


