

- Market Size (2026)
- USD 54.9 Bn
- Forecast (2036)
- USD 98.4 Bn
- CAGR (2026 to 2036)
- 6.0%
How big is the luxury fine jewellery market in 2026?
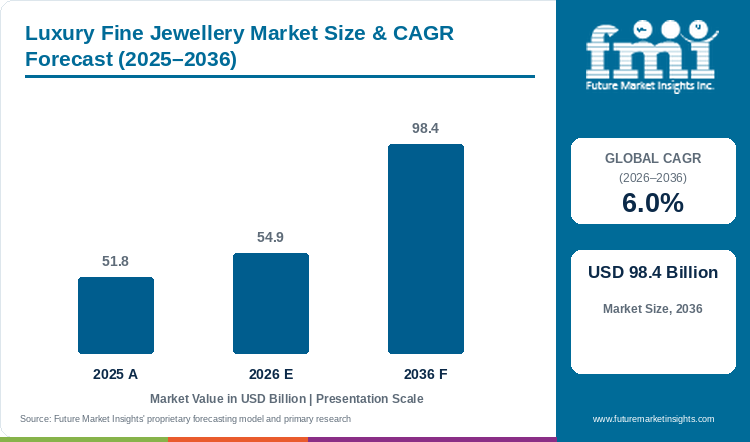
Demand is projected to expand at 6.0% CAGR from 2026 to 2036. Market value rises from USD 51.83 billion in 2025 to USD 54.94 billion in 2026 and USD 98.39 billion by 2036. [1]
FMI values the luxury fine jewellery market at USD 54.94 billion in 2026, compared with USD 51.83 billion in 2025, and projects USD 98.39 billion by 2036 at a 6.0% CAGR. [1] Gold accounts for 46.0% by raw material and necklaces represent 27.0% by product in 2026, leading the respective classifications of the finished luxury jewellery offer. [1] Buyers compare precious material, design and workmanship, while metal fineness and gemstone identity describe separate attributes that need to remain clear within the item's product record. UK hallmarking guidance establishes a one-gram minimum weight threshold for gold and different thresholds for other precious metals, with relevant exemptions applying to the stated requirement. [2] Qualifying items sold online and in shops fall within that framework, making the item's actual material and weight relevant to the assessment of a precious-metal description. [2] FTC jewellery guidance addresses mined, laboratory-created and simulated products, with relevant origin and treatment disclosures helping a customer understand the stone contained in the finished item. [3] A necklace also brings practical construction details into the purchase, including chain length, clasp design and access to repair when an owner needs the item maintained. Japan has the fastest profiled growth rate at 6.2% CAGR from 2026 to 2036, within a country outlook covering established and developing jewellery purchasing markets. [1] Suppliers can support consistent item descriptions across store and online channels through clear material and stone records, while separating changes in ticket price from units sold and upstream precious-metal trading.
Key Market Trends and Insights
- Gold carries 46.0% of the forecast material mix. [1]
- Necklaces carry 27.0% of product revenue. [1]
- Precious-metal and gemstone descriptions require separate verification. [2][3]
Regional Highlights
- Fastest-growing profiled market: Japan at 6.2% CAGR from 2026 to 2036. [1]
- Qualifying precious-metal items sold in the UK require hallmarking across shop and online channels, and product records connect this verification with the material, weight and description of the item. [2]
Market Size and Forecast
Table 1: Market size and forecast for the luxury fine jewellery market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 51.83 billion |
| Estimated market size in 2026 | USD 54.94 billion |
| Projected market size by 2036 | USD 98.39 billion |
| CAGR 2026 to 2036 | 6.0% |
| Added revenue 2026 to 2036 | USD 43.45 billion |
| Market expansion multiple | 1.8x |
Product value and unit purchases both affect the market. Higher metal costs can influence ticket prices, while the gemstone market supplies stones for finished jewellery. Design, workmanship and aftercare contribute further product distinctions.
Precious-Metal Verification and Gemstone Disclosure
Hallmarking guidance addresses precious-metal verification. FTC jewellery guidance sets out descriptions and disclosures for diamonds, gemstones and pearls, supporting clear material and origin information. [2][3]
Table 2: Evidence and adoption indicators for the luxury fine jewellery market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| UK gold threshold | 1 gram, subject to applicable exemptions | Qualifying items need hallmark assessment | [2] |
| Online and shop sales | Guidance applies across both channels | Channel choice does not remove verification | [2] |
| Gemstone nature | Mined, laboratory-created and simulated descriptions differ | Product identity needs clear disclosure | [3] |
Analyst Perspective
"A luxury jewellery purchase combines design and workmanship with materials that need to be described precisely at item level. Metal fineness and the nature of a gemstone answer different questions, while treatment and origin disclosures remain relevant when a stone is included. Coloured gemstones extend the range of stone choices within that purchase. Clear records also help with repair or resizing, giving the owner a usable description of the item beyond the brand name and the original retail presentation."
- Rahul Pandita, Principal Consultant, FMI
How is the luxury fine jewellery market segmented?
The market covers 4 commercial axes and region: raw material; product type; consumer orientation; sales channel.
By raw material: Gold; Platinum; Diamond; Precious pearls; Gemstones; Other materials. By product type: Necklaces; Rings; Earrings; Bracelets; Pendants; Anklets; Brooches; Other products. By consumer orientation: Women; Men; Children. By sales channel: Individual jewellery stores; Specialty stores; Online retailers; Other channels.
Why does gold lead demand within the raw material category?
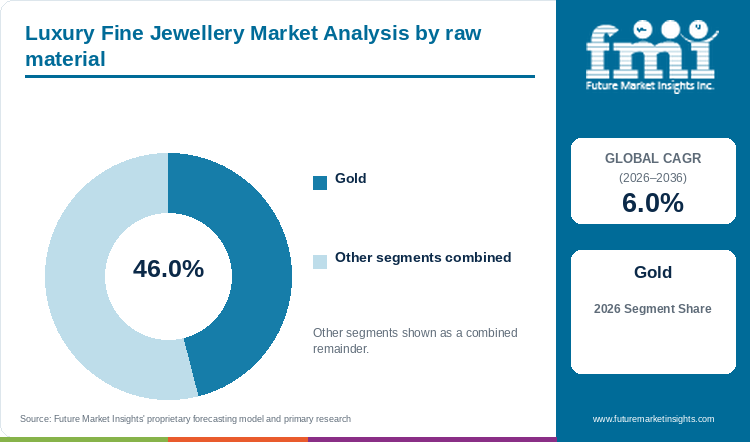
The gold segment accounts for 46.0% of raw material demand in 2026. [1]
Gold provides a precious-metal foundation for luxury jewellery, with the finished item bringing together fineness, weight and workmanship alongside its design and any stones. Applicable hallmark information supports the metal description, helping buyers interpret the actual material used in a ring, necklace or other product. The item's price also reflects more than the metal alone because construction and retail service form part of the offer. Demi-fine jewellery occupies another positioning within the wider purchase landscape, while luxury fine jewellery retains its own finished-product and material boundaries.
- Gold accounts for 46.0% of raw-material demand in 2026, leading the material classification that also includes platinum, diamond, precious pearls, gemstones and other materials used within luxury fine jewellery. [1]
- Buyers can assess gold fineness and weight alongside workmanship, design and any included stones, with applicable hallmark information supporting the precious-metal description of the finished item supplied through store or online channels.
Table 3: Leading raw material share for the luxury fine jewellery market
| Raw material | Share in 2026 |
|---|---|
| Gold | 46.0% |
| Other segments combined | 54.0% |
| Total | 100.0% |
Table 4: Segment leadership and market growth for the luxury fine jewellery market
| Metric | Value |
|---|---|
| Global CAGR 2026 to 2036 | 6.0% |
| Leading segment | Gold |
Why do necklaces lead demand within the product type category?
The necklaces segment accounts for 27.0% of product type demand in 2026. [1]
Necklaces can combine precious metal, gemstones and detailed construction within an item that also needs to function comfortably during wear. Chain length and clasp design give the customer practical distinctions alongside the visual design, while a clear repair route helps an owner maintain the piece. If CVD lab-grown diamonds are included, origin and relevant treatment disclosures form part of the stone description. These linked material and construction choices support necklaces' leading place within the product mix without making gemstone identity interchangeable with the metal description.
- Necklaces account for 27.0% of product demand in 2026, holding the leading share within a classification that also includes rings, earrings, bracelets, pendants, anklets, brooches and other finished jewellery products. [1]
- Chain length, clasp construction and repair access help distinguish necklace offers, while the metal record and any gemstone-origin or treatment disclosures describe separate attributes of the actual item presented to the buyer.
What are the drivers restraints and opportunities in the luxury fine jewellery market?
- Driver: Luxury jewellery purchases bring a finished physical item together with design and retail service, supporting demand across different products while value assessment keeps higher ticket prices, additional units sold and upstream precious-metal transactions distinct within the commercial outlook.
- Restraint: Inconsistent metal or gemstone descriptions make an item harder to assess across channels, while FTC guidance distinguishes mined, laboratory-created and simulated products and keeps relevant disclosures material to the customer's understanding of the finished jewellery offer. [3]
- Opportunity: Suppliers can maintain a clear record of metals, stones and relevant disclosures across stores and online listings, supporting consistent item descriptions and giving owners useful information when the jewellery needs repair, resizing or subsequent description after purchase.
Material and design combinations support finished-product value
Jewellery purchases combine a finished physical item with design and retail service, requiring value assessment to distinguish higher ticket prices from additional units sold and the upstream precious-metal transactions that have a different commercial purpose.
Unclear product descriptions weaken comparability
Consistent metal and gemstone descriptions allow buyers to assess the same item across channels, while FTC guidance distinguishes mined, laboratory-created and simulated products and makes those relevant disclosures part of the luxury jewellery description. [3]
Durable product identity supports aftercare
A clear record of materials, stones and relevant disclosures can support repair, resizing and future item descriptions, with sellers carrying that information across stores and online listings to preserve the identity of the piece supplied to the customer.
Which country CAGRs are profiled in the luxury fine jewellery market?
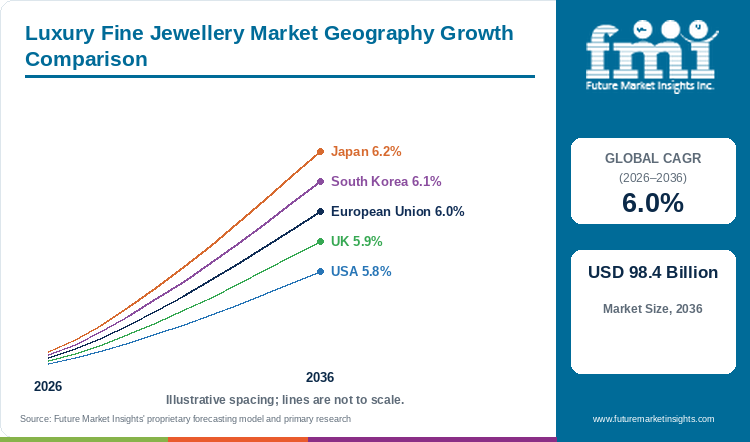
Table 5: Country CAGR comparison for the luxury fine jewellery market
| Country or regional market | CAGR 2026 to 2036 |
|---|---|
| USA | 5.8% |
| UK | 5.9% |
| European Union | 6.0% |
| Japan | 6.2% |
| South Korea | 6.1% |
Country and Regional Analysis
USA
Established luxury retail and purchases linked with personal milestones provide a commercial setting for fine jewellery in the USA. [1] Within that offer, FTC guidance distinguishes mined, laboratory-created and simulated stones and addresses treatment disclosures where durability, care or value is affected. [3] A retailer therefore needs item descriptions that connect the gemstone with the precious metal, design and price being presented, including when a customer researches online before viewing the piece. The USA outlook records 5.8% CAGR from 2026 to 2036 within this established retail setting. [1] Practical purchase decisions concern fit, clasp construction, repair access and the record accompanying the sale, since continued ownership may require work on a particular setting or chain. Clear descriptions help the buyer compare finished items without assuming that a familiar stone name explains every aspect of the piece.
UK
Hallmarking gives UK buyers an independent check on the precious-metal content of qualifying jewellery, with the government's guidance setting different weight thresholds for gold, silver, platinum and palladium. Gold has a one-gram threshold, while relevant exemptions and recognised marks need to be considered for the item sold. [2] Retailers use that material information alongside design, gemstone identity and workmanship when presenting a luxury necklace, ring or other piece in a shop or online. UK demand is projected to expand at 5.9% CAGR from 2026 to 2036, with the purchasing discussion extending from material identity to how the owner will wear and maintain the item, including length, fastening and access to repairs. [1] A clear item record allows those practical details to remain connected with the material description when the same piece appears across different sales channels.
European Union
Jewellery houses and specialist workshops across the European Union give the regional offer a range of design traditions, materials and production capabilities. [1] A customer comparing finished pieces needs to distinguish the metal specification and gemstone identity from the brand's design and service offer, particularly when an item combines several components. With the combined regional forecast at 6.0% CAGR from 2026 to 2036, retailers handling purchases across different countries can support comparison through consistent descriptions, care information and a clear route to aftercare, while keeping the requirements applying to the actual destination in view. [1] Commercial performance also depends on which collections are stocked and how customers discover them through boutiques or digital listings. Those choices connect an established craftsmanship offer with the availability and service arrangements surrounding ownership of the finished item.
Japan
Precision workmanship and restrained design provide part of the commercial context for luxury fine jewellery in Japan, where customers compare an item's proportions and finish alongside its material content. [1] Pearl necklaces illustrate why the individual components matter: Mikimoto's collection presents pearl jewellery whose appearance, length and setting form part of the finished offer. [5] Retailers can use those details to explain how a piece will be worn and maintained, rather than leaving the customer to infer its construction from a broad luxury description. Japan has the highest profiled growth rate at 6.2% CAGR from 2026 to 2036, with assortment and aftercare capacity remaining practical considerations as a collection expands, since a purchase intended for continued ownership can require cleaning advice, inspection or repair appropriate to the actual item. [1]
South Korea
Social-media discovery and celebrity styling influence how jewellery reaches customers in South Korea, with statement pieces and flexible styling described in the country outlook. [1] An image can introduce a design, while the subsequent purchase requires information about the metal, stone, dimensions and construction of the piece actually offered. The South Korea forecast records 6.1% CAGR from 2026 to 2036 as customers discover designs across digital and store channels. [1] Someone moving from online research to a store visit needs those descriptions to remain consistent, especially when a collection includes different sizes or material combinations under similar names. Retailers can connect the visual presentation with practical fit and aftercare information, helping the buyer understand the item chosen for continuing use. Availability also matters when discovery creates interest in a particular design that must be located or ordered through the sales network.
Who are the notable companies in the luxury fine jewellery market?
Richemont; Tiffany & Co.; Graff; Chopard; Mikimoto
Competitive Benchmarking
Table 6: Competitive positioning for the luxury fine jewellery market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| Richemont | Luxury jewellery houses | Luxury jewellery brand portfolio [1] |
| Tiffany & Co. | Fine jewellery | Material, gemstone identity and aftercare [1] |
| Graff | Fine jewellery | Item-level gemstone and product records [1] |
| Chopard | Luxury fine jewellery | Official collections include diamond and gold necklaces and rings. [4] |
| Mikimoto | Cultured-pearl jewellery | Official necklace range identifies cultured-pearl and precious-metal combinations. [5] |
Key Developments in the Luxury Fine Jewellery Market
- UK hallmarking guidance applies a one-gram minimum weight threshold to gold, subject to relevant exemptions, with different thresholds for other precious metals and qualifying items sold online and in shops falling within the stated requirement. [2]
- FTC jewellery guidance distinguishes mined, laboratory-created and simulated gemstones and addresses relevant descriptions and disclosures, providing a framework for explaining stone identity separately from the precious-metal composition and workmanship of a finished jewellery item. [3]
Key Players in the Luxury Fine Jewellery Market
Richemont; Tiffany & Co.; Graff; Chopard; Mikimoto; Gucci; Signet Jewelers; Pandora.
Luxury Fine Jewellery Market Report Scope
Coverage includes finished luxury jewellery by raw material, product, consumer orientation and sales channel. Metal fineness, gemstone nature, treatment disclosures and workmanship are separate item attributes; upstream material sales describe different transactions.
Table 7: Report coverage for the luxury fine jewellery market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Raw material; Product type; Consumer orientation; Sales channel; region |
| Quantitative units | USD billion |
| Market definition | Finished luxury fine jewellery by material, product and channel. Bullion trading, loose-stone transactions and watches are excluded unless expressly included in a finished-jewellery item. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | USA; UK; European Union; Japan; South Korea |
| Key companies profiled | Richemont; Tiffany & Co.; Graff; Chopard; Mikimoto; Gucci; Signet Jewelers; Pandora |
| Forecast period | 2026 to 2036 |
Luxury Fine Jewellery Market Research Methodology
Table 8: Research methods for the luxury fine jewellery market
| Method | Approach |
|---|---|
| Market definition | The study examines the luxury fine jewellery market through raw material, product type, consumer orientation and sales channel, identifying the products or services and purchasing transactions covered. |
| Public documentary research | FMI market research, UK hallmarking guidance, FTC jewellery information and official product catalogs inform the analysis of product characteristics, operating conditions and market context. |
| Company portfolio research | Official product pages and company disclosures describe relevant offerings, intended customers and participation within wider business portfolios. |
| Segment assessment | The raw material, product type, consumer orientation and sales channel categories are examined through product or service characteristics, practical use and purchase conditions. |
| Country research | Local distribution, purchasing arrangements and applicable public requirements inform country analysis alongside the reported market outlook. |
| Regulatory and technical assessment | Metal fineness, gemstone identity and treatment disclosures inform item assessment, with workmanship and aftercare considered as additional features of the finished jewellery offer. |
| Forecast coverage | The forecast considers the demand drivers, purchasing constraints and supplier opportunities affecting the market across the study period. |
Luxury Fine Jewellery Market by Segments
By raw material
- Gold
- Platinum
- Diamond
- Precious pearls
- Gemstones
- Other materials
By product type
- Necklaces
- Rings
- Earrings
- Bracelets
- Pendants
- Anklets
- Brooches
- Other products
By consumer orientation
- Women
- Men
- Children
By sales channel
- Individual jewellery stores
- Specialty stores
- Online retailers
- Other channels
Luxury Fine Jewellery Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. Luxury Fine Jewellery Market.
- [2] UK government. Accessed October 2026. Hallmarking: practical guidance summary.
- [3] US Federal Trade Commission. Accessed October 2026. In the Loupe: Advertising Diamond Gemstones and Pearls.
- [4] Chopard. Accessed October 2026. Jewellery Collections.
- [5] Mikimoto. Accessed October 2026. Pearl Necklaces.
This Report Answers
- How big is the luxury fine jewellery market in 2026?
- What market value is projected by 2036?
- Which raw material segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Frequently Asked Questions
How large is the luxury fine jewellery market in 2026?
FMI estimates market value at USD 54.94 billion in 2026. The estimated 2025 value is USD 51.83 billion. [1]
What value and CAGR are projected through 2036?
Market value is projected to reach USD 98.39 billion by 2036 at a 6.0% CAGR from 2026 to 2036. [1]
Which raw material segment leads in 2026?
Gold accounts for 46.0% of this category. [1]
What is the report segmentation?
Raw material; Product type; Consumer orientation; Sales channel, and region.
Which profiled market records the highest CAGR?
Japan has the highest profiled rate at 6.2% from 2026 to 2036. [1]
Who are the key participants?
Richemont; Tiffany & Co.; Graff; Chopard; Mikimoto; Gucci; Signet Jewelers; Pandora.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By raw material, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By raw material, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By raw material, 2026 to 2036
- Gold
- Platinum
- Diamond
- Precious pearls
- Gemstones
- Other materials
- Y-o-Y Growth Trend Analysis By raw material, 2021 to 2025
- Absolute $ Opportunity Analysis By raw material, 2026 to 2036
- Global Market Analysis and Forecast, By product type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By product type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By product type, 2026 to 2036
- Necklaces
- Rings
- Earrings
- Bracelets
- Pendants
- Anklets
- Brooches
- Other products
- Y-o-Y Growth Trend Analysis By product type, 2021 to 2025
- Absolute $ Opportunity Analysis By product type, 2026 to 2036
- Global Market Analysis and Forecast, By consumer orientation, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By consumer orientation, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By consumer orientation, 2026 to 2036
- Women
- Men
- Children
- Y-o-Y Growth Trend Analysis By consumer orientation, 2021 to 2025
- Absolute $ Opportunity Analysis By consumer orientation, 2026 to 2036
- Global Market Analysis and Forecast, By sales channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By sales channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By sales channel, 2026 to 2036
- Individual jewellery stores
- Specialty stores
- Online retailers
- Other channels
- Y-o-Y Growth Trend Analysis By sales channel, 2021 to 2025
- Absolute $ Opportunity Analysis By sales channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By raw material
- By product type
- By consumer orientation
- By sales channel
- By Country
- Market Attractiveness Analysis
- By Country
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- European Union
- Pricing Analysis
- Market Share Analysis, 2025
- By raw material
- By product type
- By consumer orientation
- By sales channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By raw material
- By product type
- By consumer orientation
- By sales channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Richemont
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Tiffany & Co.
- Graff
- Chopard
- Mikimoto
- Richemont
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


